
Protein Market Analysis by Mordor Intelligence
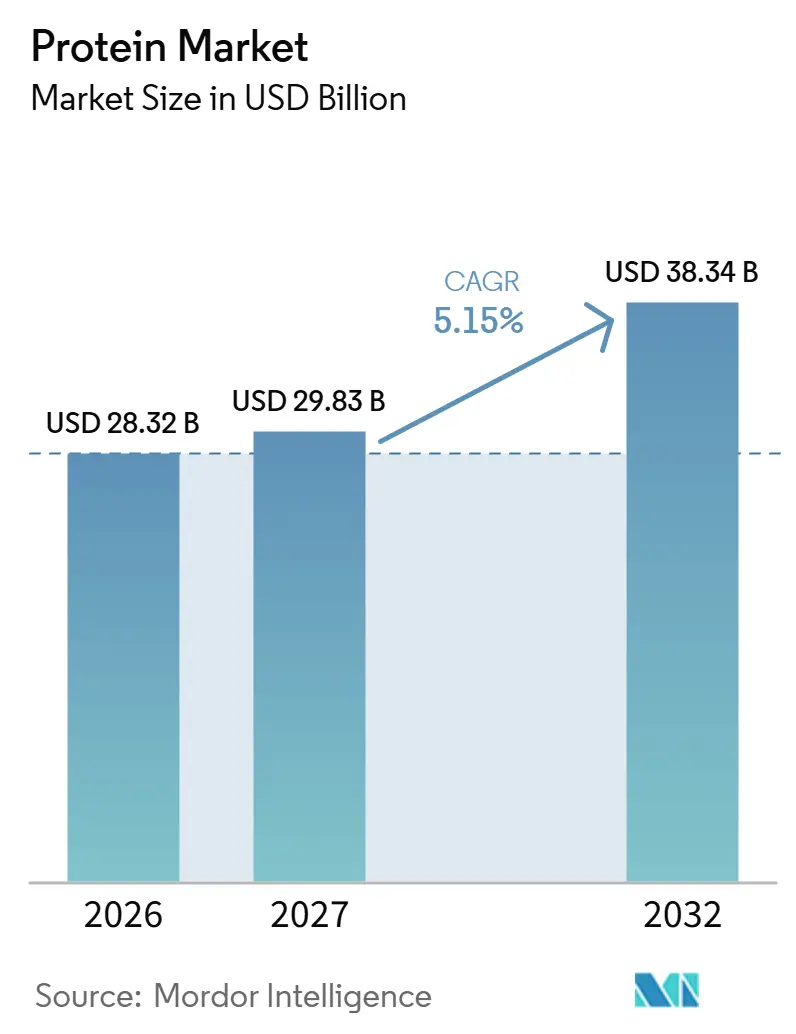
The protein market size is projected to expand from USD 28.32 billion in 2026 and USD 29.83 billion in 2027 to USD 38.34 billion by 2032, registering a CAGR of 5.15% between 2027 and 2032.
Growth opportunities in the United States span high-protein diets, ready-to-drink beverages, and plant-protein formulations suited to soda-like drinks. These uses favor ingredients whose functionality matches the finished product, while distribution reach offers beverage manufacturers another route to expansion. Whey supply interruptions can raise replacement costs for food manufacturers dependent on dairy proteins. Producers are responding through soy-concentrate capacity additions, planned whey upgrades, and contract manufacturing arrangements, although food-customer qualification can delay commercialization. Because food-customer qualification can delay new supply while whey interruptions raise replacement costs, suppliers with capacity already qualified for food manufacturers hold the nearer-term advantage.
Key Report Takeaways
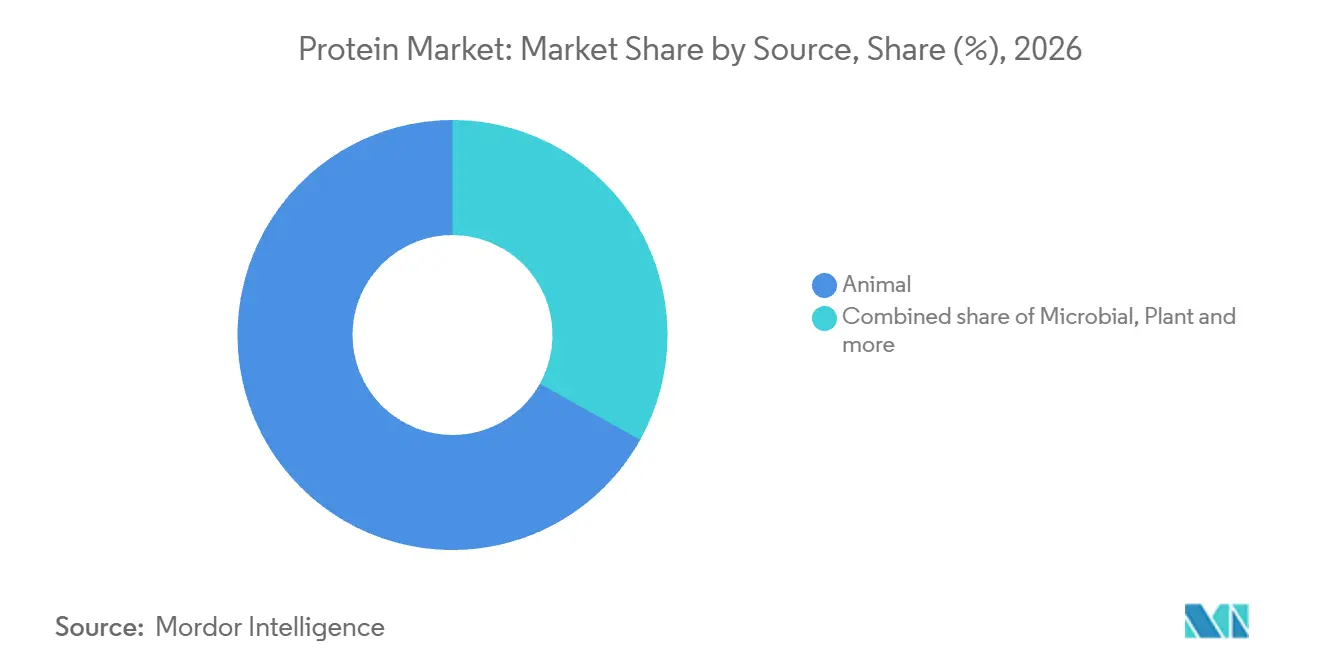
- By source, animal proteins held a 66.89% protein market share in 2026, while plant proteins are forecast to be the fastest-growing segment with a CAGR of 7.6% between 2027 and 2032.
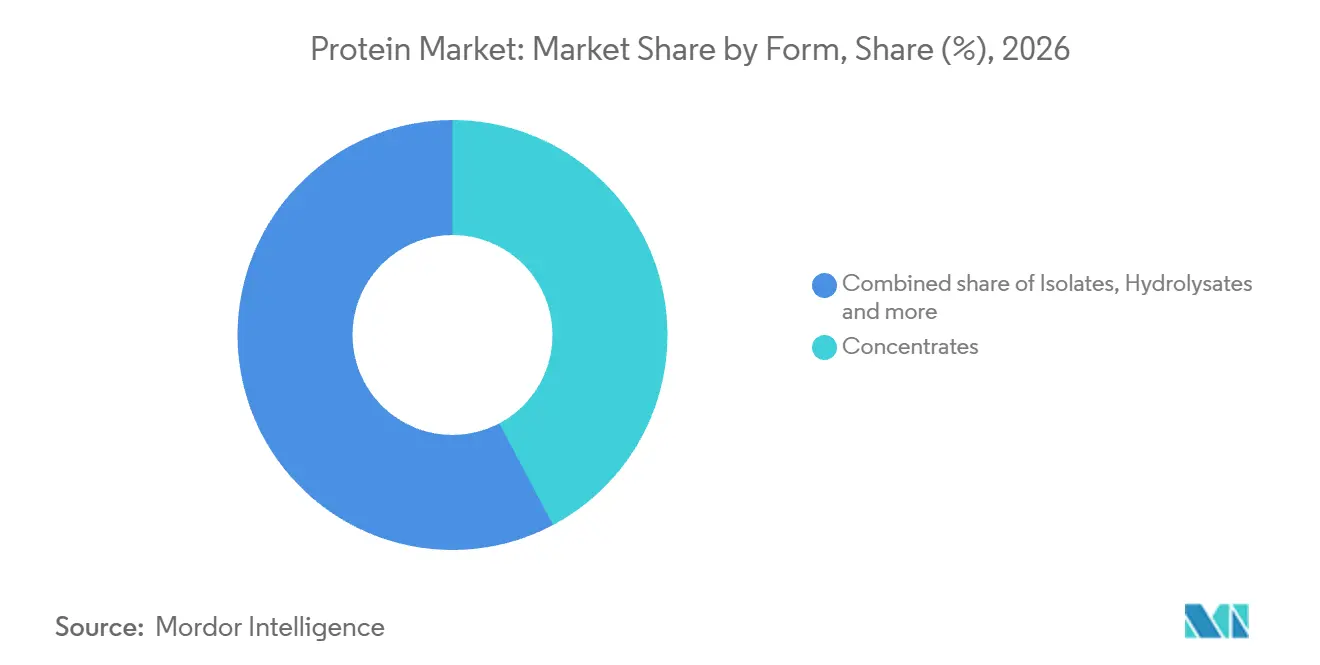
- Across forms, concentrates accounted for a 42.25% share of the protein market size in 2026, and hydrolysates are projected to lead growth with a CAGR of 7.7% between 2027 and 2032.
- For applications, food and beverages led with a 59.61% share in 2026, while the dietary supplements and sports nutrition segment is forecast to expand fastest with a CAGR of 6.55% between 2027 and 2032.
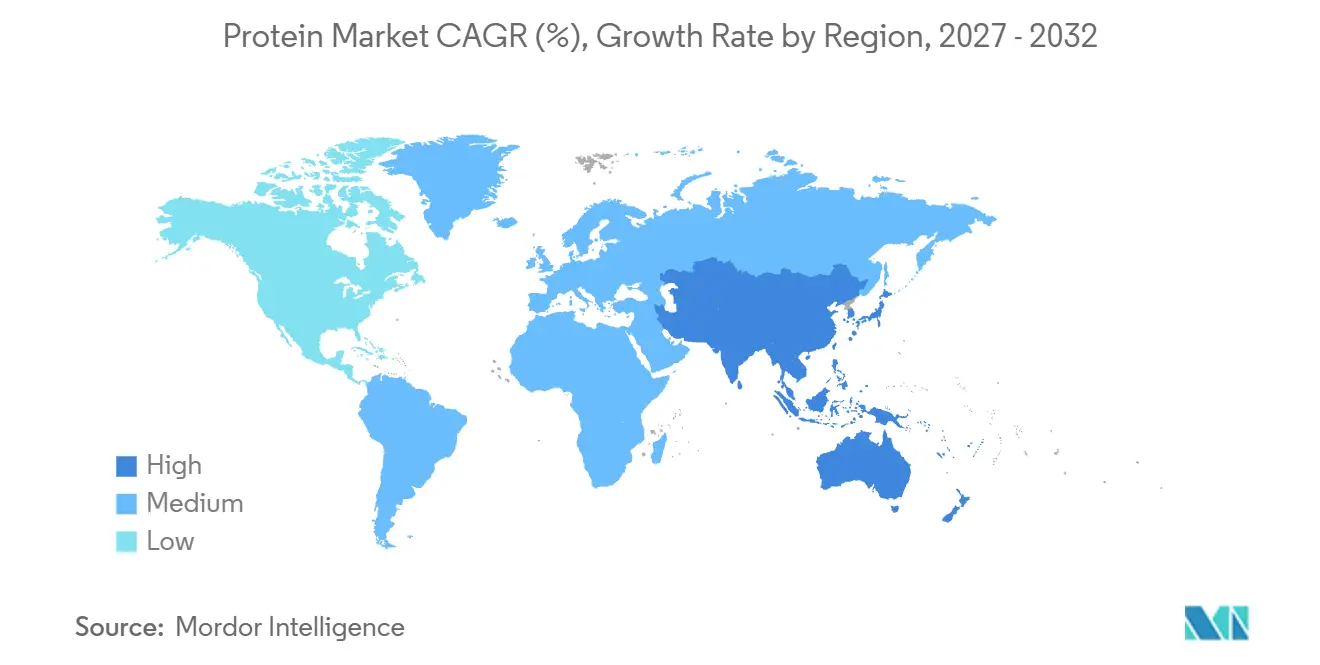
- Geographically, North America held a 35.01% share in 2026, while Asia-Pacific is projected to be the fastest-growing geography with a CAGR of 7.3% between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Protein Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Mainstream high-protein diets and sports nutrition adoption | +2.4% | North America, especially the United States | Short term (≤ 2 years) |
| Rapid penetration of plant-based and alternative proteins in food and beverages | +1.4% | Europe, especially Spain | Medium term (2-4 years) |
| Protein fortification across functional foods and beverages | +1.1% | North America, especially the United States | Medium term (2-4 years) |
| Expansion of protein supplements and RTD formats | +1% | North America, especially the United States | Short term (≤ 2 years) |
| Precision fermentation scale-up for animal-free dairy proteins | +0.5% | North America, especially the United States | Long term (≥ 4 years) |
| Premium pet food and aquafeed demand for novel proteins | +0.3% | South America, particularly Ecuador | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Mainstream high-protein diets and sports nutrition adoption
Mainstream adoption can enlarge the consumer base available to protein-using manufacturers. In the International Food Information Council’s 2026 survey, 27% of U.S. adults ages 18 to 80 reported following a high-protein diet in the prior year, up from 23% in 2025. Glanbia plc also reported 16.4% volume growth for Optimum Nutrition in the first half of 2026, driven by category growth, increased distribution, and innovation. The survey identifies a widening dietary audience in the United States, while the Optimum Nutrition result shows physical volume expansion within an established sports-nutrition brand. Glanbia separately reported 23.5% growth in Optimum Nutrition’s U.S. measured-channel consumption in the 13 weeks to July 4, 2026, linking the brand’s expansion to shopper uptake across measured U.S. channels.
Rapid penetration of plant-based and alternative proteins in food and beverages
Spain shows plant-based demand rising while 2 of its 4 replacement categories shrink. In Spain, retail sales volume across plant-based meat, milk and drinks, cheese, and yogurt rose 6.6% in 2025 from 2024. Plant-based meat and cheese volumes nevertheless declined in Spain during 2025. The combined volume gain represents additional finished-product throughput across those categories, creating a potential route to greater ingredient use for manufacturers participating in the expansion. Milk, drink, and yogurt applications collectively offer the clearer route to ingredient demand in Spain, because they sustain the combined volume gain despite declines in meat and cheese alternatives.
Protein fortification across functional foods and beverages
U.S. retail sales of high-protein soft drinks, covering carbonates, juice, ready-to-drink coffee, energy and sports drinks, rose 17.8% in 2025 from 2024. This finished-drink sales growth gives fortification suppliers a downstream commercial signal across several beverage applications. Koia introduced Protein Pop through TikTok Shop in January 2026, calling it the first clear plant-based protein soda in the U.S. market. The product combines clear pea protein and prebiotic fiber in a fizzy, soda-like format. A pea-protein supplier pursuing this type of formulation needs to deliver clarity in a carbonated drink alongside protein content, making application performance central to the ingredient opportunity.
Expansion of protein supplements and RTD formats
U.S. Premier Protein ready-to-drink (RTD) dollar consumption sales grew 6% year over year in the 13 weeks ended June 28, 2026, including BellRing’s estimates for untracked channels. BellRing attributed the increase primarily to distribution growth. Growth was 5% excluding the timing shift of an e-commerce promotion and 16% excluding both club channels and that promotional shift. The adjusted results preserve a positive sales signal after removing the promotion’s timing effect, with stronger growth when club channels are also excluded. Outside club channels, growth of 16% after excluding the promotion’s timing shift identifies the more distinct sales opening for ingredient suppliers serving this RTD brand.
Restraints Impact Analysis of Protein Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Allergenicity/clean label and GMO concerns in soy/legume proteins | -0.6% | North America, especially the United States | Long term (≥ 4 years) |
| Commodity price and supply volatility for dairy and soy inputs | -0.7% | United States and Canada | Short term (≤ 2 years) |
| Flavor off-notes/processing challenges driving higher costs | -0.3% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Regulatory approvals slowing insect/microbial protein adoption | -0.2% | Europe, especially EU countries | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Allergenicity/clean label and GMO concerns in soy/legume proteins
Under U.S. law, covered foods containing soy protein ingredients that are not raw agricultural commodities must identify soy as a major food allergen. The label may name soy in parentheses within the ingredient list or in an adjacent “Contains” statement. Soy-derived highly refined oils and ingredients qualifying for statutory exemptions fall outside the relevant allergen definition. The duty attaches to the finished food sold to consumers rather than the bulk ingredient sale. Using nonexempt soy protein therefore requires soy identification on the finished label, a step that pea or potato protein does not trigger because neither appears on the statutory list of major food allergens.
Commodity price and supply volatility for dairy and soy inputs
In early May 2026, a supplier ran out of whey protein for Canadian food brand HelloAmino.[1] Bunge Global SA, an integrated agribusiness producing soy protein concentrate, disclosed in February 2026 that higher agricultural commodity prices generally increase borrowing needs across its operations. Such exposure can burden suppliers’ working capital even when the immediate problem for food manufacturers is access to an ingredient. By June 2026, Calgary-based HelloAmino had turned to U.S.-sourced whey isolate after Canadian supply dried up, although the substitute cost 50% more. Restoring availability at that premium leaves less room to absorb protein inclusion costs within an affordable finished-food proposition.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Protein Market Segment Analysis
By Source:
Whey Value and Plant Capacity Shape Different Growth RoutesAnimal proteins accounted for a 66.89% share of the protein market size in 2026. Arla Foods Ingredients Group P/S reported 29.3% growth in sales of value-added whey protein ingredients in 2025. In the first half of 2026, Arla Foods said higher whey protein prices mainly drove its ingredients business’s performance, reflecting demand linked to health and nutrition trends. Higher whey prices separate the seller’s value gain from the buyer’s cost exposure, making strong ingredient-business performance compatible with pressure on manufacturers’ input costs.
Plant proteins are the fastest-growing segment, with a projected CAGR of 7.6% between 2027 and 2032. Bunge reported 60,000 metric tons of installed soy protein concentrate capacity at Morristown during commissioning in 2026, and the Indiana plant opened in May 2026. Microbial protein has a feed channel at Beijing Shougang LanzaTech, which reported in 2025 that its product was mainly supplied to aquaculture-feed and piglet-feed manufacturers in China.



By Form:
Concentrate Scale Meets Peptide Capacity DevelopmentConcentrates represented a 42.25% protein market share in 2026. USDA NASS reported 42.8 million pounds of total whey protein concentrate production in the United States in August 2026, up 4.6% from August 2025.[2] Its whey protein concentrate category covered ingredients with 25% to 89.9% protein and both human and animal uses. USDA NASS also reported 502 million pounds of total whey protein concentrate production in 2025, up 2.1% from 2024, so the August increase followed a year of expanding U.S. output in this ingredient category.
Hydrolysates are the fastest-growing segment, with a projected CAGR of 7.7% between 2027 and 2032. In October 2025, GELITA Brasil announced plans to double collagen-peptide manufacturing capacity at Mococa, Brazil, with completion expected in 2027. GELITA linked the expansion to growing global collagen-peptide demand associated with healthy aging, sports nutrition, and beauty applications. At Soldiers Nutrition in Brazil, sales volume of powdered hydrolyzed collagen supplements rose 44.3% in the first half of 2026 from the first half of 2025. Mococa’s planned doubling, expected in 2027, would add collagen-peptide supply after a first half in which powdered collagen volumes at Soldiers Nutrition were already rising.

By Application:
Food Manufacturing Anchors Demand as Nutrition Sales ExpandFood and beverages represented the largest application segment, with a 59.61% share in 2026. In winter 2025-26, Valley Queen began producing Arla Foods Ingredients’ microparticulated whey protein concentrate under a contract manufacturing agreement. The ingredient was formulated for high-protein food and beverage applications, with South Dakota-based Valley Queen acting as the contract manufacturer. In July 2025, Fonterra said Meiji used its proteins in Japanese medical foods and beverages, including a high-protein drink it described as having the highest market share in its category. These examples connect food and beverage demand to application-specific ingredients, with a manufacturing partner extending supply and a medical-food buyer providing a defined outlet.
The dietary supplements and sports nutrition segment is the fastest-growing segment, with a projected CAGR of 6.55% between 2027 and 2032. BellRing Brands reported that its sports-nutrition brand Dymatize’s net sales rose 26.7% in the fiscal third quarter ended June 30, 2026, from the prior-year quarter. The increase comprised 6% volume growth and 20.7% price/mix growth. Price/mix supplied most of Dymatize’s sales gain, so ingredient suppliers have a narrower physical-demand signal in the brand’s 6% volume increase.
Geography Analysis
North America Protein Market
North America accounted for a 35.01% share of the protein market size in 2026, making it the largest geography. Bunge’s soy protein concentrate business is primarily located in North America, giving the region an established production base for that ingredient. In September 2026, Bunge reported ongoing customer business at Morristown, Indiana, in the United States, while food-customer approvals, qualification, and capacity-utilization ramp-up continued.[3] At Morristown, converting installed capacity into food-grade supply depends on customer qualification, so a completed facility does not by itself remove the commercial lead time.
Asia-Pacific Protein Market
Asia-Pacific is the fastest-growing geography, with a projected CAGR of 7.3% between 2027 and 2032. China’s 2025-2030 Food and Nutrition Development Outline targets annual per-capita legume consumption of 14 kilograms and a high-quality-protein share above 50% of daily protein intake by 2030. In June 2026, USDA’s Foreign Agricultural Service in Beijing expected China’s whey demand to remain robust during 2026, supported by food and feed applications. China’s whey import volumes nevertheless declined in January through March 2026 from the same period in 2025. Food and feed uses broaden the regional demand base beyond China’s whey-import channel, where early-2026 volumes declined.
In Europe, the EU sourced 25% of the protein from oilseeds and protein crops used there internally in 2025, with livestock feed the main use of plant protein. In South America, ProTerra’s 2026 outlook identified Caramuru and CJ Selecta as Brazilian exporters of non-GMO soy protein concentrate focused on supplying Europe. Within the Middle East and Africa, USDA forecast expanded South African oilseed meal production and regional exports in 2026/27, while biosecurity and economic challenges were likely to limit feed-consumption growth. Europe’s feed-oriented import dependence connects its plant-protein supply needs with the processed soy protein concentrate channel served by Brazilian exporters. South Africa’s forecast makes regional exports the outlet for meal supply that constrained domestic feed growth may not absorb.
Regional Editions
All regions
Regulatory Framework and Outlook
Selected jurisdictions differ in the entry and labeling duties affecting protein-ingredient suppliers serving human-food manufacturers. The comparison assesses these suppliers’ regulatory burden, including customer-facing labeling duties for foods made with their ingredients. U.S. notification of qualifying generally recognized as safe (GRAS) uses is voluntary, while the FDA’s August 2026 proposal would require notices for covered uses. South Africa’s April 2023 Draft R3337 proposed claim restrictions for foods required to carry front-of-pack labels and was described as under consultation and negotiation in October 2026.
Regulatory Table of Protein Market
| Decision factor | United States | Germany | Singapore | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | European Commission | Singapore Food Agency | Anvisa | Municipal Health Services through Environmental Health Practitioners; national Food Control Directorate support |
| Key instruments or direction | GRAS notification framework; August 2026 mandatory-notice proposal | Regulation (EU) 2015/2283; Union-list conditions | Food Safety and Security Act; novel-food authorization regulations | RDC 839/2023; planned 2026-2027 authorized-ingredient lists | R146; proposed Draft R3337 |
| Commercial effect | Voluntary notices for qualifying GRAS uses; potential new filing duty | Premarket authorization for qualifying novel foods and specified uses | Premarket approval and advance-application requirements for novel foods | Safety assessment and authorization for qualifying new ingredients | Food-manufacturer, importer, and seller labeling and allergen-disclosure duties |
| Current policy attractiveness | High | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Hardening | No change | No change | No change | Hardening |
| Source: Mordor Intelligence | |||||
U.S. flexibility supports its current rating, while the August 2026 notice proposal supports a hardening direction. Germany’s Union-list conditions and Brazil’s safety-authorization duties anchor their entry burdens, while Brazil’s Anvisa 2026-2027 agenda topic on authorized-ingredient lists supports continuity alongside the central approval obligation. Singapore’s rule, unchanged since November 28, 2025, requires applications at least 9 months before proposed supply unless the Singapore Food Agency reasonably finds earlier filing impossible and accepts less time, supporting continuity. South Africa’s customer-labeling burden explains its current assessment, while the proposed front-of-pack claim restrictions point toward hardening for relevant finished-food applications.
Value Chain Stages
Value capture changes across crop sourcing, protein-ingredient manufacturing, and distribution as suppliers turn agricultural inputs into ingredients for commercial buyers. In 2026, more than 80% of soybeans processed at Bunge’s Morristown complex came from Indiana farms, according to company figures. Geographic sourcing concentration makes additional farm-supply relationships a distinct resilience decision before protein manufacturing begins.
Value Chain Analysis Table of Protein Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Agricultural sourcing and primary processing | Integrated soybean processors such as Bunge Global SA | Crop-processing sales | Crop-market volatility | Diversify crop-supply contracts |
| Protein-ingredient manufacturing | Soy-protein suppliers such as Archer-Daniels-Midland Company; whey-ingredient suppliers such as Arla Foods Ingredients Group P/S | Protein-ingredient sales | Different crop and whey processing requirements | Maintain dedicated crop and dairy processing expertise |
| Ingredient distribution | Specialty ingredient distributors such as Brenntag Specialties | Ingredient resale revenue | Dependence on supplier distribution agreements | Maintain alternative authorized supplier relationships |
| Source: Mordor Intelligence | ||||
In July 2025, Brenntag announced an expanded U.S. distribution agreement with Royal Avebe covering potato-based functional proteins, starches, and fibers. Under the announced arrangement, Royal Avebe would supply the ingredients and Brenntag would distribute them to U.S. food and nutrition customers. Territorial distribution rights place part of the commercial value in access to U.S. food and nutrition customers, alongside the supplier’s ingredient-manufacturing capability.
Competitive Landscape
Market Concentration
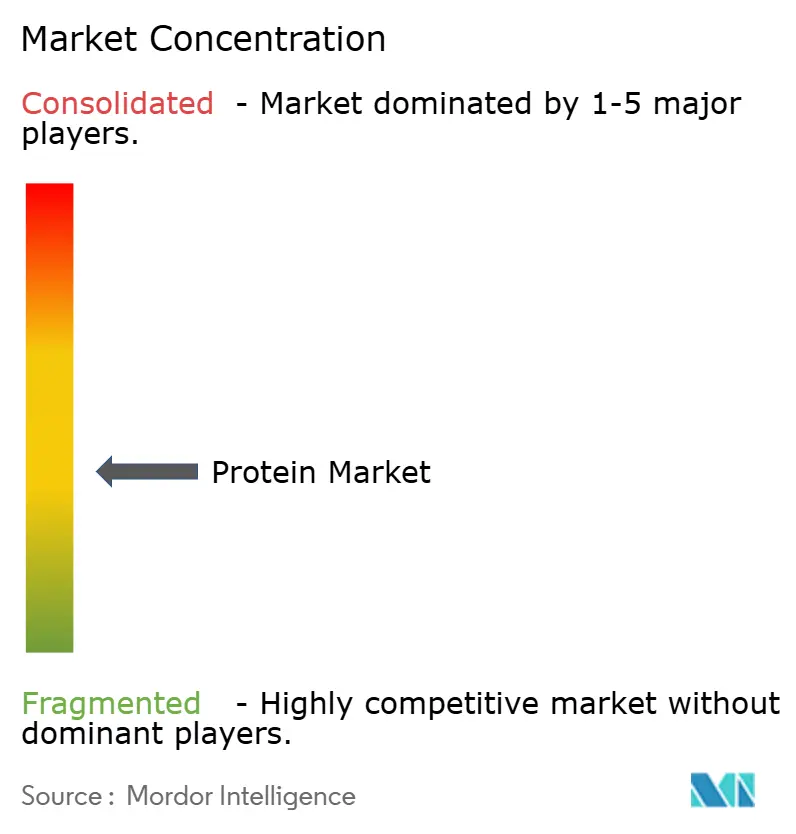
Competition is moderately fragmented among Archer-Daniels-Midland Company, Fonterra Co-operative Group Limited, the former soy protein concentrate business of International Flavors & Fragrances Inc., now part of Bunge Global SA, Kerry Group plc, and Cargill, Incorporated. On March 2, 2026, Bunge announced it had closed its acquisition of IFF’s soy protein concentrate, lecithin, and soy crush businesses. Fonterra’s Studholme advanced protein hub in New Zealand reached construction completion, with first trial products coming off the line in February 2026. The completed hub gives Fonterra a New Zealand manufacturing base for advanced proteins. The named players span distinct protein chains, with soy at ADM and Bunge, dairy at Fonterra, and hydrolysates at Kerry, so the 2026 moves reshape specific production capabilities rather than establish a common competitive position.
On July 14, 2026, Archer-Daniels-Midland Company (ADM) and The EVERY Company announced a collaboration to begin commercial-scale production of EVERY’s OvoPro egg-white protein ingredient at ADM’s Clinton, Iowa facility. The arrangement combines EVERY’s ingredient with ADM’s manufacturing site, offering a challenger a production route through an established operator. Kerry Group plc supplies dairy and plant protein hydrolysates for clinical nutrition, infant formula, and texture-led applications such as aerated confectionery, ice cream, and sponge cakes. The July announcement positioned EVERY’s egg-white supply as prospective, so ADM’s manufacturing partnership addresses a different competitive hurdle from Kerry’s application-specific hydrolysate range.
In May 2026, FrieslandCampina announced phased upgrades at Bedum, Veghel, and Workum in the Netherlands to expand conversion of internally sourced whey into protein ingredients, with full operational capacity expected in 2028. The announced program specified more than EUR 90 million (USD 105.1 million) and targeted performance and active nutrition, early life nutrition, and medical nutrition. On September 24, 2026, Fonterra announced an incremental investment over the next 3 years in its South Island protein manufacturing network and environmental performance, with operations expected in 2029. FDA recorded no questions for EVERY’s egg-white protein from Komagataella phaffii ATCC GSD-1235 on October 17, 2023, for the notice’s specified uses under applicable manufacturing-practice conditions. FrieslandCampina’s 2028 and Fonterra’s 2029 operating targets imply multiyear dairy expansion, whereas EVERY’s planned ADM production pairs manufacturing access with an FDA no-questions record limited to specified uses.
Protein Industry Leaders
-
Archer-Daniels-Midland Company
-
Fonterra Co-operative Group Limited
-
International Flavors & Fragrances Inc.
-
Kerry Group plc
-
Cargill, Incorporated
- *Disclaimer: Major Players sorted in no particular order
Protein Market Companies Covered in this Report
- Archer-Daniels-Midland Company
- Cargill, Incorporated
- Arla Foods Ingredients Group P/S
- Fonterra Co-operative Group Limited
- Glanbia plc
- Kerry Group plc
- Roquette Frères S.A.
- Ingredion Incorporated
- dsm-firmenich AG
- International Flavors & Fragrances Inc.
- Bunge Global SA
- CHS Inc.
- PURIS Proteins, LLC
- Axiom Foods, Inc.
- COSUCRA Groupe Warcoing SA
- Emsland-Stärke GmbH
- FrieslandCampina Ingredients
- Lactalis Ingredients
- GELITA AG
- Rousselot B.V.
- Hilmar Ingredients
- Wilmar International Limited
- The Scoular Company
Recent Industry Developments in Protein Market
- Sep 2026: Fonterra Co-operative Group Limited announced an incremental investment over the next 3 years to expand its protein manufacturing network and improve environmental performance in New Zealand’s South Island, with operations expected in 2029.
- Jul 2026: Archer-Daniels-Midland Company and The EVERY Company announced a collaboration to begin commercial-scale production of EVERY’s OvoPro egg-white protein ingredient at Archer-Daniels-Midland Company’s Clinton, Iowa facility.
- May 2026: Bunge Global SA opened its soy protein concentrate plant near Morristown, Indiana, on May 7, 2026.
Scope and Methodology
Segmentation Overview
By Source
| Animal | Casein and Caseinates |
| Collagen | |
| Egg Protein | |
| Gelatin | |
| Insect Protein | |
| Milk Protein | |
| Whey Protein | |
| Other Animal Proteins | |
| Microbial | Algae Protein |
| Mycoprotein | |
| Plant | Hemp Protein |
| Pea Protein | |
| Potato Protein | |
| Rice Protein | |
| Soy Protein | |
| Wheat Protein | |
| Other Plant Proteins |
By Form
| Concentrates |
| Isolates |
| Hydrolysates |
| Other Forms |
By Application
| Food and Beverages | Bakery |
| Beverages | |
| Breakfast Cereals | |
| Condiments/Sauces | |
| Confectionery | |
| Dairy and Dairy Alternative Products | |
| Meat/Poultry/Seafood and Meat Alternative Products | |
| RTE/RTC Food Products | |
| Snacks | |
| Infant Nutrition | |
| Other Food and Beverage Applications | |
| Personal Care and Cosmetics | |
| Animal Feed | |
| Dietary Supplements and Sports Nutrition |
By Geography
| North America | United States |
| Canada | |
| Mexico | |
| Rest of North America | |
| Europe | United Kingdom |
| Germany | |
| France | |
| Italy | |
| Spain | |
| Sweden | |
| Belgium | |
| Poland | |
| Netherlands | |
| Rest of Europe | |
| Asia-Pacific | China |
| Japan | |
| India | |
| Thailand | |
| Singapore | |
| Indonesia | |
| South Korea | |
| Australia | |
| New Zealand | |
| Rest of Asia-Pacific | |
| South America | Brazil |
| Argentina | |
| Peru | |
| Colombia | |
| Chile | |
| Rest of South America | |
| Middle East and Africa | South Africa |
| Nigeria | |
| Egypt | |
| Morocco | |
| Turkey | |
| Rest of Middle East and Africa |
| By Source | Animal | Casein and Caseinates |
| Collagen | ||
| Egg Protein | ||
| Gelatin | ||
| Insect Protein | ||
| Milk Protein | ||
| Whey Protein | ||
| Other Animal Proteins | ||
| Microbial | Algae Protein | |
| Mycoprotein | ||
| Plant | Hemp Protein | |
| Pea Protein | ||
| Potato Protein | ||
| Rice Protein | ||
| Soy Protein | ||
| Wheat Protein | ||
| Other Plant Proteins | ||
| By Form | Concentrates | |
| Isolates | ||
| Hydrolysates | ||
| Other Forms | ||
| By Application | Food and Beverages | Bakery |
| Beverages | ||
| Breakfast Cereals | ||
| Condiments/Sauces | ||
| Confectionery | ||
| Dairy and Dairy Alternative Products | ||
| Meat/Poultry/Seafood and Meat Alternative Products | ||
| RTE/RTC Food Products | ||
| Snacks | ||
| Infant Nutrition | ||
| Other Food and Beverage Applications | ||
| Personal Care and Cosmetics | ||
| Animal Feed | ||
| Dietary Supplements and Sports Nutrition | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Rest of North America | ||
| Europe | United Kingdom | |
| Germany | ||
| France | ||
| Italy | ||
| Spain | ||
| Sweden | ||
| Belgium | ||
| Poland | ||
| Netherlands | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| Japan | ||
| India | ||
| Thailand | ||
| Singapore | ||
| Indonesia | ||
| South Korea | ||
| Australia | ||
| New Zealand | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Argentina | ||
| Peru | ||
| Colombia | ||
| Chile | ||
| Rest of South America | ||
| Middle East and Africa | South Africa | |
| Nigeria | ||
| Egypt | ||
| Morocco | ||
| Turkey | ||
| Rest of Middle East and Africa | ||
Market Definition
- End User - The Protein Ingredients Market operates on a B2B basis. Food, Beverages, Supplements, Animal Feed, and Personal Care & Cosmetic manufacturers are considered to be end-consumers in the market studied. The scope excludes manufacturers buying liquid/dry whey to be used for application as a binding agent or thickener or other non-protein applications.
- Penetration Rate - Penetration Rate is defined as the percentage of Protein-Fortified End User Market Volume in the Overall End User Market Volume.
- Average Protein Content - Average protein content is the average protein content present per 100 g of product manufactured by all end-user companies considered under the scope of this report.
- End User Market Volume - End-user market volume is the consolidated volume of all types and forms of end-user products in the country or region.
| Keyword | Definition |
|---|---|
| Alpha-lactalbumin (α-Lactalbumin) | It is a protein that regulates the production of lactose in the milk of almost all mammalian species. |
| Amino acid | It is an organic compound that contains both amino and carboxylic acid functional groups, which are required for the synthesis of body protein and other important nitrogen-containing compounds, such as creatine, peptide hormones, and some neurotransmitters. |
| Blanching | It is the process of briefly heating vegetables with steam or boiling water. |
| BRC | British Retail Consortium |
| Bread improver | It is a flour-based blend of several components with specific functional properties designed to modify dough characteristics and give quality attributes to bread. |
| BSF | Black Soldier Fly |
| Caseinate | It is a substance produced by adding an alkali to acid casein, a derivative of casein. |
| Celiac disease | Celiac disease is an immune reaction to eating gluten, a protein found in wheat, barley, and rye. |
| Colostrum | It is a milky fluid that’s released by mammals that have recently given birth before breast milk production begins. |
| Concentrate | It is the least processed form of protein and has a protein content ranging from 40-90% by weight. |
| Dry protein basis | It refers to the percentage of "pure protein" present in a supplement after the water in it is completely removed through heat. |
| Dry whey | It is the product resulting from drying fresh whey which has been pasteurized and to which nothing has been added as a preservative. |
| Egg protein | It is a mixture of individual proteins, including ovalbumin, ovomucoid, ovoglobulin, conalbumin, vitellin, and vitellenin. |
| Emulsifier | It is a food additive that facilitates the blending of foods that are immiscible with one another, such as oil and water. |
| Enrichment | It is the process of addition of micronutrients that are lost during the processing of the product. |
| ERS | Economic Research Service of the USDA |
| Extrusion | It is the process of forcing soft mixed ingredients through an opening in a perforated plate or die designed to produce the required shape. The extruded food is then cut to a specific size by blades. |
| Fava | Also known as Faba, it is another word for yellow split beans. |
| FDA | Food and Drug Administration |
| Flaking | It is a process in which typically a cereal grain (like corn, wheat, or rice) is broken down into grits, cooked with flavors and syrups, and then pressed into flakes between cooled rollers. |
| Foaming agent | It is a food ingredient that makes it possible to form or maintain a uniform dispersion of a gaseous phase in a liquid or solid food. |
| Foodservice | It refers to the part of the food industry which includes businesses, institutions, and companies which prepare meals outside the home. It includes restaurants, school and hospital cafeterias, catering operations, and many other formats. |
| Fortification | It is the deliberate addition of micronutrients that are not found in them naturally or which are lost during processing, to improve a food product's nutritional value. |
| FSANZ | Food Standards Australia New Zealand |
| FSIS | Food Safety and Inspection Service |
| FSSAI | Food Safety and Standards Authority of India |
| Gelling agent | It is an ingredient that functions as a stabilizer and thickener to provide thickening without stiffness through the formation of gel. |
| GHG | Greenhouse Gas |
| Gluten | It is a family of proteins found in grains, including wheat, rye, spelt, and barley. |
| Hemp | It is a botanical class of Cannabis sativa cultivars grown specifically for industrial or medicinal use. |
| Hydrolysate | It is a form of protein manufactured by exposing the protein to enzymes that can partially break the bonds between the protein's amino acids and break down large, complicated proteins into smaller pieces. Its processing makes it easier and quicker to digest. |
| Hypoallergenic | It refers to a substance that causes fewer allergic reactions. |
| Isolate | It is the purest and most processed form of protein which has undergone separation to obtain a pure protein fraction. It typically contains ≥ 90% of protein by weight. |
| Keratin | It is a protein that helps form hair, nails, and the outer layer of skin. |
| Lactalbumin | It is the albumin contained in milk and obtained from whey. |
| Lactoferrin | It is an iron‑binding glycoprotein that is present in the milk of most mammals. |
| Lupin | It is the yellow legume seeds of the genus Lupinus. |
| Millenial | Also known as Generation Y or Gen Y, it refers to the people born from 1981 to 1996. |
| Monogastric | It refers to an animal with a single-compartmented stomach. Examples of monogastric include humans, poultry, pigs, horses, rabbits, dogs, and cats. Most monogastric are generally unable to digest much cellulose food materials such as grasses. |
| MPC | Milk protein concentrate |
| MPI | Milk protein isolate |
| MSPI | Methylated soy protein isolate |
| Mycoprotein | Mycoprotein is a form of single-cell protein, also known as fungal protein, derived from fungi for human consumption. |
| Nutricosmetics | It is a category of products and ingredients that act as nutritional supplements to care for skin, nails, and hair natural beauty. |
| Osteoporosis | It is a medical condition in which the bones become brittle and fragile from loss of tissue, typically as a result of hormonal changes, or deficiency of calcium or vitamin D. |
| PDCAAS | Protein digestibility-corrected amino acid score (PDCAAS) is a method of evaluating the quality of a protein based on both the amino acid requirements of humans and their ability to digest it. |
| Per-capita consumption of animal protein | It is the average amount of animal protein (such as milk, whey, gelatin, collagen, and egg proteins) that is readily available for consumption by each person in an actual population. |
| Per-capita consumption of plant protein | It is the average amount of plant protein (such as soy, wheat, pea, oat, and hemp proteins) that is readily available for consumption by each person in an actual population. |
| Quorn | It is a microbial protein manufactured using mycoprotein as an ingredient, in which the fungus culture is dried and mixed with egg albumen or potato protein, which acts as a binder, and then is adjusted in texture and pressed into various forms. |
| Ready-to-Cook (RTC) | It refers to food products that include all of the ingredients, where some preparation or cooking is required through a process that is given on the package. |
| Ready-to-Eat (RTE) | It refers to a food product prepared or cooked in advance, with no further cooking or preparation required before being eaten. |
| RTD | Ready-to-Drink |
| RTS | Ready-to-Serve |
| Saturated fat | It is a type of fat in which the fatty acid chains have all single bonds. It is generally considered unhealthy. |
| Sausage | It is a meat product made of finely chopped and seasoned meat, which may be fresh, smoked, or pickled and which is then usually stuffed into a casing. |
| Seitan | It is a plant-based meat substitute made out of wheat gluten. |
| Softgel | It is a gelatin-based capsule with a liquid fill. |
| SPC | Soy protein concentrate |
| SPI | Soy protein isolate |
| Spirulina | It is a biomass of cyanobacteria that can be consumed by humans and animals. |
| Stabilizer | It is an ingredient added to food products to help maintain or enhance their original texture, and physical and chemical characteristics. |
| Supplementation | It is the consumption or provision of concentrated sources of nutrients or other substances that are intended to supplement nutrients in the diet and is intended to correct nutritional deficiencies. |
| Texturant | It is a specific type of food ingredient that is used to control and alter the mouthfeel and texture of food and beverage products. |
| Thickener | It is an ingredient that is used to increase the viscosity of a liquid or dough and make it thicker, without substantially changing its other properties. |
| Trans fat | Also called trans-unsaturated fatty acids or trans fatty acids, it is a type of unsaturated fat that naturally occurs in small amounts in meat. |
| TSP | Textured soy protein |
| TVP | Textured vegetable protein |
| WPC | Whey protein concentrate |
| WPI | Whey protein isolate |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: The quantifiable key variables (industry and extraneous) pertaining to the specific product segment and country are selected from a group of relevant variables & factors based on desk research & literature review; along with primary expert inputs. These variables are further confirmed through regression modeling (wherever required).
- Step-2: Build a Market Model: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


