
Hospitality Market Size and Share
Hospitality Market Analysis by Mordor Intelligence
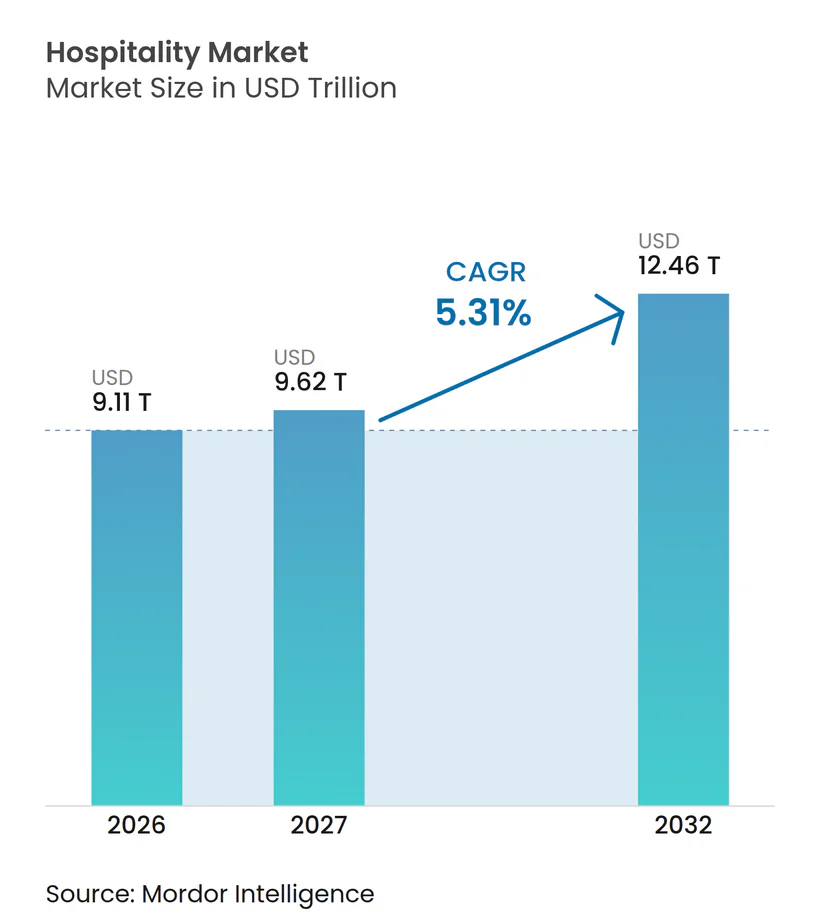
The hospitality market size is expected to increase from USD 9.11 trillion in 2026 to USD 9.62 trillion in 2027 and reach USD 12.46 trillion by 2032, growing at a CAGR of 5.31% over 2027-2032.
Mixed-purpose trips and wellness-focused stays broaden demand for accommodation supporting activities beyond sleeping, encouraging operators to develop services around the stay. In Cambodia, a wellness hotel can combine rooms with on-property wellness programs and dedicated relaxation and recovery spaces, while flexible-work trips require accommodation usable for work and leisure. Digital guest support and direct reservations can connect specialized offers to room sales within an existing hotel network. Yet labor costs and cautious discretionary spending in the United States put pressure on income retained from rooms and optional services. The expansion of specialized stays therefore creates a revenue opportunity whose value depends on service spending and the labor required to deliver it.
Key Report Takeaways
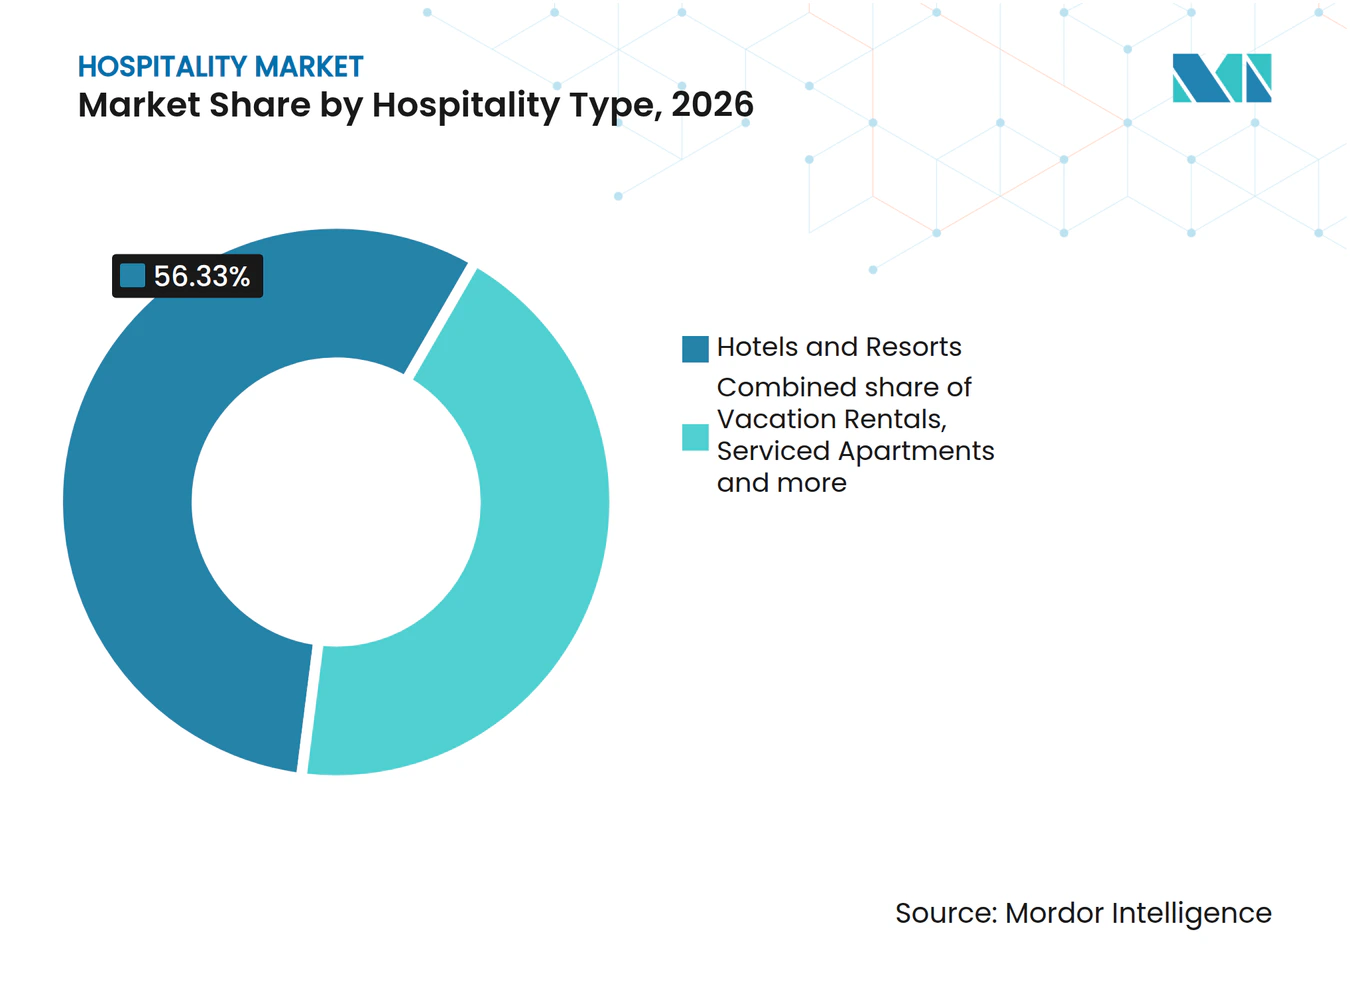
- By hospitality type, hotels and resorts held a 56.33% hospitality market share in 2026, while vacation rentals are forecast to grow fastest at a CAGR of 6.58% over 2027-2032.
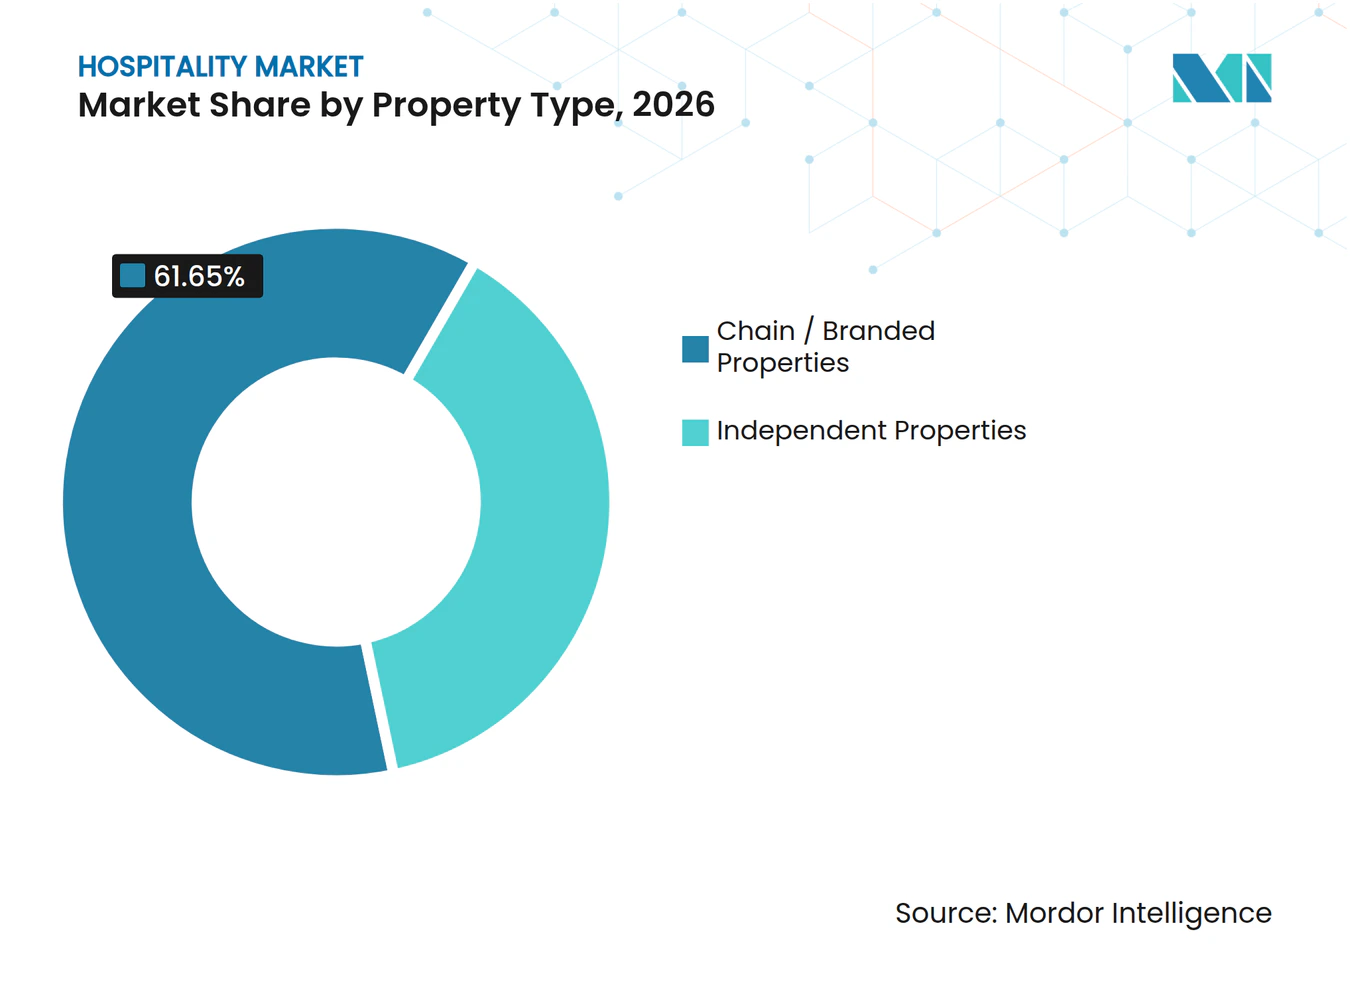
- Within property types, chain and branded properties accounted for a 61.65% share of the hospitality market size in 2026, and independent properties are projected to grow fastest at a CAGR of 6.1% over 2027-2032.
- Direct booking channels generated the largest channel share at 42.87% of property revenue in 2026 and are also forecast to grow fastest at a CAGR of 6.2% over 2027-2032.
- Across revenue streams, room revenue led with 56.49% of property revenue in 2026, while wellness and recreation revenue is projected to grow fastest at a CAGR of 6.65% over 2027-2032.
- Leisure travelers led the traveler-type breakdown with 52.64% of property revenue in 2026, whereas long-stay and digital nomad travelers are forecast to grow fastest at a CAGR of 6.55% over 2027-2032.
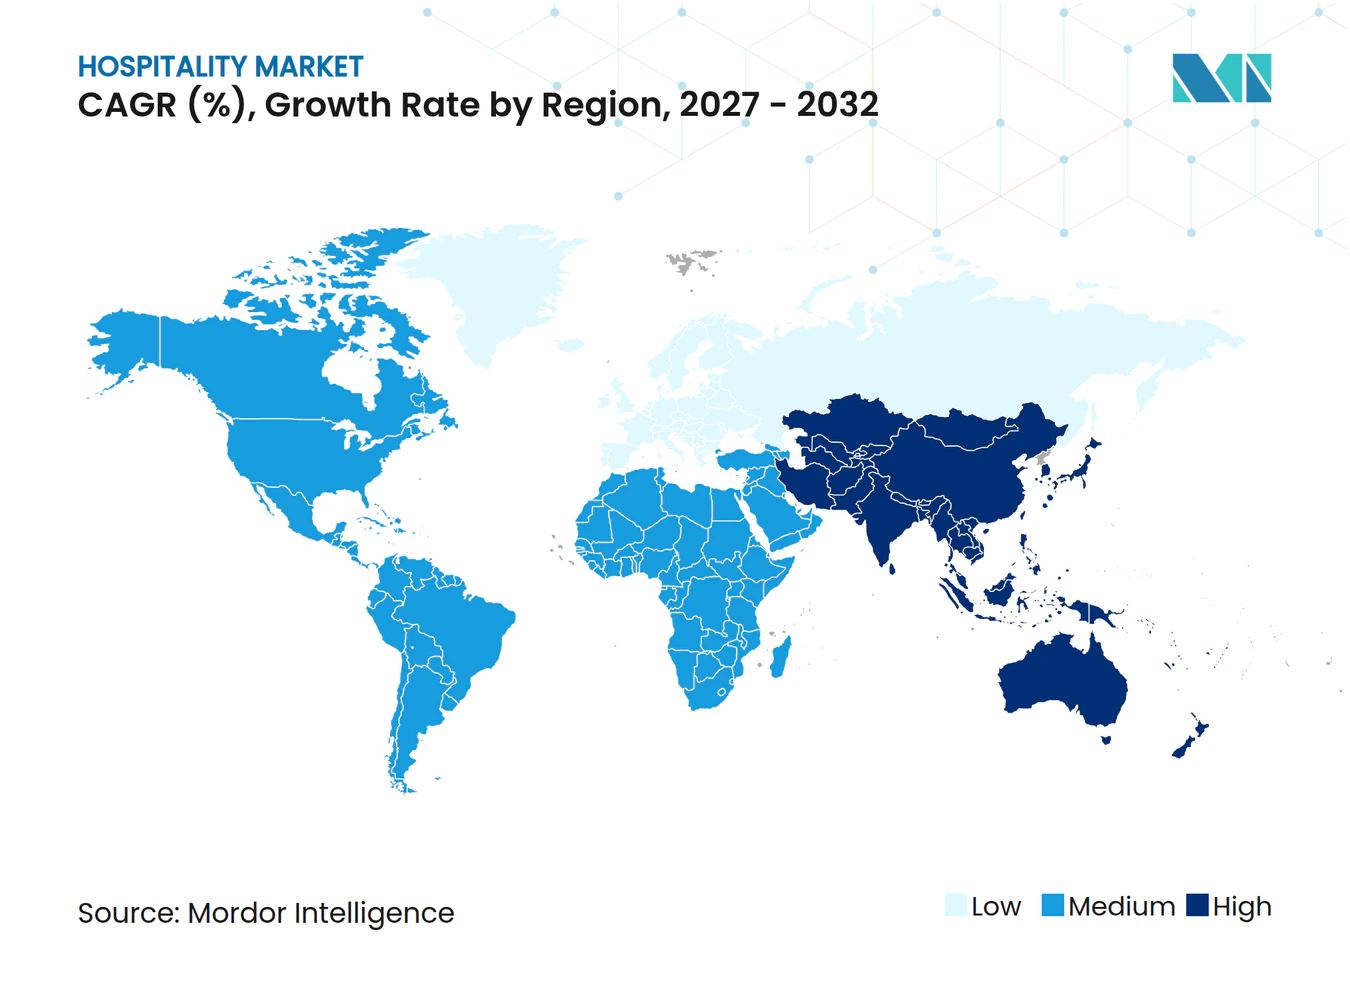
- Across geographies, Europe held 30.72% of property revenue in 2026, while Asia-Pacific is projected to grow fastest in the hospitality industry at a CAGR of 7.3% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Hospitality Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expansion of Experiential and Lifestyle-Led Hospitality Concepts | +2% | Australia, Europe and Southeast Asia | Medium term (2-4 years) |
| Rising Bleisure and Flexible Work-Driven Travel Demand | +1.6% | North America, Europe, Asia-Pacific and Brazil | Short term (≤ 2 years) |
| Growth in Wellness, Medical, and Regenerative Tourism Stays | +1.5% | Asia-Pacific, particularly Cambodia | Medium term (2-4 years) |
| Digital Transformation Through AI-Based Revenue & Guest Management | +1.35% | Europe, North America and Asia-Pacific | Short term (≤ 2 years) |
| Rapid Expansion of Alternative Accommodation and Hybrid Stay Models | +0.95% | Europe, United States and Canada | Medium term (2-4 years) |
| Increasing Middle-Class International Travel from Emerging Economies | +0.65% | Asia-Pacific, particularly India | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expansion of Experiential and Lifestyle-Led Hospitality Concepts
Ennismore's 2025 openings brought its lifestyle brands to Australia, Barcelona, Singapore and Dublin, including first entries for several brands or the group. These openings broaden the destinations offering lifestyle-led stays, showing how hospitality concepts can extend beyond a single location. Hilton's Curio Collection had more than 200 open hotels worldwide in 2026.[1] The collection spanned nearly 50 countries and territories. For property operators, this international scale makes lifestyle positioning a potential route into a larger collection, with the commercial task shifting from establishing an isolated concept to differentiating a property within a widely available format.
Rising Bleisure and Flexible Work-Driven Travel Demand
Flexible work creates 2 routes to mixed-purpose stays, with work shaping holidays and leisure extending business trips. Expedia Group's 2025 survey found 42% of adults across 11 markets planned a bleisure trip in the following 12 months, up from 29% in 2022.[2] The same survey found 44% planned leisure trips incorporating remote work, compared with 28% in 2022. One pattern adds leisure around a work trip, while the other requires a holiday stay to accommodate remote work. Expedia's guidance to prioritize midweek availability, reliable Wi-Fi and working spaces identifies practical accommodation requirements behind these mixed-purpose stays.
Growth in Wellness, Medical, and Regenerative Tourism Stays
Wellness programs give accommodation providers a way to sell a stay around activities delivered within the property. In August 2025, TUI announced the 151-room wellness-focused TUI BLUE Angkor Grace hotel in Siem Reap, Cambodia. By September 2026, the property offered guests yoga, sound healing and traditional wellness practices, with dedicated relaxation and recovery spaces. That combination makes time spent at the hotel part of the accommodation offer, giving the operator a reason to coordinate rooms and activities within one guest itinerary. A coordinated wellness program can therefore support both the reason to book and the on-property services purchased during the stay.
Digital Transformation Through AI-Based Revenue & Guest Management
Conversational guest services can help properties turn travel interest into a more informed accommodation choice. Accor launched its ALL Concierge AI travel companion on September 24, 2026, with availability varying by platform, language and point of sale.[3] Accor described it as the first large-scale rollout of a fully conversational AI companion by a hospitality group. At launch, the ALL Accor app covered 4 languages across 5 points of sale, while ALL.com covered 11 languages. For an accommodation operator, the demand mechanism is a shorter path from uncertainty about a property to a decision to stay. Channel-specific availability makes rollout design part of the commercial proposition, since assistance must be accessible where a guest tries to book.
Restraints Impact Analysis of Hospitality Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Operating and Labor Costs Across Hospitality Properties | -1.15% | United States of America | Short term (≤ 2 years) |
| Economic Slowdowns Impacting Discretionary Travel Spending | -0.85% | United States of America | Short term (≤ 2 years) |
| Regulatory and Licensing Challenges in Short-Term Accommodation Markets | -0.45% | Spain, France and Italy | Medium term (2-4 years) |
| Seasonal Demand Volatility and Occupancy Fluctuations | -0.3% | European Union member states | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Operating and Labor Costs Across Hospitality Properties
Higher labor expenditure raises the revenue a hotel needs to recover the cost of delivering each stay. The American Hotel & Lodging Association reported that total United States hotel labor costs rose 15% cumulatively from 2019 to 2025. In its late-February 2026 survey of 246 United States hoteliers, 65% identified labor costs as a financial pressure. For accommodation operators, absorbing that pressure reduces the earnings available from a given level of room sales. Passing it through to guests instead raises the price at which the property must compete for discretionary stays. This tradeoff constrains expansion because additional occupied rooms must generate enough revenue to support the service labor they require.
Economic Slowdowns Impacting Discretionary Travel Spending
Pressure on essential household spending reduces the funds available for optional accommodation and services during a trip. In June 2026, EY reported that United States consumers were reducing discretionary spending to offset rising essential costs. More than 30% of respondents were reevaluating leisure and entertainment spending ahead of that summer. For lodging operators, this creates exposure at the decision to travel and at the choice of services purchased during a stay. Properties relying on optional spa and dining purchases face an additional revenue exposure when guests retain the room reservation but trim those services.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Hospitality Market Segment Analysis
By Hospitality Type:
Established Hotel Demand and Distinct Stay PropositionsHotels and resorts accounted for a 56.33% share of the hospitality market size in 2026, making them the largest segment. Nights spent in EU hotels and similar accommodation increased by 4.7 million, or 0.9%, in Q2 2026 compared with Q2 2025. Hotels and similar accommodation accounted for 61.6% of EU tourist accommodation nights in that quarter. With most EU tourist accommodation nights concentrated in this category, even modest percentage growth generated millions of additional nights for hotels and similar accommodation to serve.
Vacation rentals are the fastest-growing segment in the hospitality market, with a projected CAGR of 6.58% over 2027-2032. Guests spent 258.8 million nights in EU short-term rentals booked through Airbnb, Booking or Expedia in Q2 2026, up 5.3% from Q2 2025. Serviced apartments attract corporate programs in Europe through professional management, consistent standards, duty of care and cost transparency, with Savills reporting increasing alignment in 2026. Luxury hospitality properties in the United States recorded 3% growth in revenue per available room (RevPAR) in 2025 as RevPAR at midscale and economy properties fell, with JLL linking premium outperformance to high-income travelers. EU platform hosts can pursue rising rental-night demand, while serviced apartments compete on corporate operating standards and luxury hotels on high-income guests' spending.



By Property Type:
Branded Networks and Independent Stay SpecializationChain and branded properties represented a 61.65% hospitality market share in 2026, making them the largest segment. Marriott's broader global lodging system, encompassing franchised, operated and licensed products, exceeded 10,000 properties at June 30, 2026. This structure lets a brand participate in accommodation supply through multiple operating arrangements, extending the network beyond properties it owns directly. Chain scale can therefore grow through owner affiliations without requiring the brand to own an equivalent number of additional assets.
Independent properties are the fastest-growing segment in the hospitality market, with a projected CAGR of 6.1% over 2027-2032. Cloudbeds recorded a 25% year-over-year increase in 7-night bookings at independent hotels in its 2025 dataset. Stays of 1 to 2 nights nevertheless accounted for more than two-thirds of bookings in that dataset. Average daily room rates in the same independent-hotel dataset fell 5.8% year over year in 2025. Weeklong stays were therefore a growing minority category within a short-stay-dominated booking mix, even as the same independent hotels faced declining average room rates.

By Booking Channel:
Direct Sales and Platform ReachDirect booking channels were the largest segment in the hospitality industry, with 42.87% of property revenue in 2026 and are forecast to be the fastest-growing segment at a CAGR of 6.2% over 2027-2032. IHG's direct digital booking channels generated 26% of its total room revenue in 2025. That company-level contribution places direct digital booking within the operating revenue model, linking the guest's reservation to accommodation sold through the group's own channel. A booking improvement on IHG's own digital channel can act on rooms already in its system, so distribution investment need not wait for new hotel openings.
Online travel agencies provide a separate route through which guests secure accommodation from property suppliers. Online travel agency platforms Airbnb, Booking and Expedia accounted for 951.6 million guest nights in EU and EFTA short-stay rentals in 2025. The scale of platform-booked rental stays makes platform access commercially relevant to rental operators serving those destinations. An operator using these routes can reach guests through an intermediary while retaining the property stay as the service it sells. For a rental host in those destinations, more platform nights improve the business only if retained income covers the cost of serving and acquiring those stays.
By Revenue Stream:
Core Room Income and Additional Service SalesRoom revenue was the largest segment in the hospitality industry, accounting for 56.49% of total property revenue in 2026. STR's global hotel RevPAR, which measures room revenue per available room, was USD 88.99 in 2025. Host Hotels & Resorts reported USD 2.13 billion in transient room revenue, USD 1.2 billion in group room revenue and USD 178 million in contract room revenue for its hotel portfolio in 2025. These categories show how the same accommodation business earns room income through several distinct customer arrangements. Host's split identifies group and contract business as additional sources of room income, giving operators alternatives to dependence on transient stays.
Wellness and recreation revenue is the fastest-growing segment in the hospitality market, with a projected CAGR of 6.65% over 2027-2032. Hotel Royal Limited reported spa revenue of SGD 553,000 (USD 423,000) in 2025, compared with SGD 444,000 (USD 332,000) in 2024, across its Singapore, Malaysia and Thailand hotel operations. That separate revenue line shows how wellness services can add to an accommodation business's sales alongside the room. Food and beverage revenue per occupied room rose 3.8% in a sample of 866 United States hotels in the first half of 2025 versus the same period of 2024. CBRE compared that increase with 3% growth in total hotel revenue for the same sample and period, showing stronger growth in the per-occupied-room food and beverage measure.
By Traveler Type:
Leisure Spending and Longer Occupancy CommitmentsLeisure travelers were the largest segment in the hospitality industry, accounting for 52.64% of property revenue in 2026. Across the broader travel and tourism sector, global leisure travel spending reached USD 6.15 trillion in 2025. In 2025, holidays were the trip purpose for 79.8% of tourists staying at least one night in Cyprus. This local mix gives accommodation operators a concrete reason to prioritize the holiday stay proposition when deciding which trip purposes a property should serve. For Cyprus operators, the broader visitor pool favors differentiating among holiday stays, because switching trip purpose would move a property's focus toward a smaller group of overnight tourists.
Long-stay and digital nomad travelers are the fastest-growing segment in the hospitality market, with a projected CAGR of 6.55% over 2027-2032. Marriott's StudioRes extended-stay brand count in the United States and Canada rose from 6 properties at March 31, 2026, to 12 at June 30, 2026. The corresponding room counts were 744 and 1,488, respectively. Marriott's brand counts included some properties expected to operate under their assigned brands after planned renovations. That parallel doubling expanded the brand's property footprint while leaving its average room count per property unchanged.
Geography Analysis
Europe Hospitality Market
Europe accounted for a 30.72% share of the hospitality market size in 2026, making it the largest region. EU tourist accommodation establishments recorded 3.1 billion nights in 2025, up 4.1% from 2024, showing substantial accommodation use within this part of Europe. Croatia added local capacity when a 65-room Curio Collection by Hilton hotel opened in Preko on Ugljan Island on June 16, 2025, marking the first Hilton-branded hotel built on a Croatian island. Hilton's first Croatian island hotel extends its coverage to a new type of destination, so European hotel growth can involve extending network coverage as well as increasing room counts.
Asia-Pacific Hospitality Market
Asia-Pacific is the fastest-growing region, with a projected CAGR of 7.3% over 2027-2032. Macao hotel establishments recorded average guest-room occupancy of 93.9% in August 2026, up 0.8 percentage points year over year. Accor reported double-digit growth in revenue per available room in the Pacific in Q4 2025, driven by both prices and occupancy. IHG opened the 225-room Hotel Indigo Auckland on April 7, 2025, marking the brand's New Zealand debut. Together, the Macao and Pacific results identify better use and pricing of existing rooms as growth mechanisms alongside new branded capacity in Auckland.
North America's domestic travel base includes Canada's 342 million resident domestic visits in 2025, covering both same-day and overnight travel. South America gained urban hotel capacity when Hilton opened the 111-suite York Medellin in Colombia on December 10, 2025. In the Middle East and Africa, Saudi Arabia's hotel room occupancy was 60.8% in Q1 2026, while serviced apartments and other hospitality facilities recorded 51.6%. Morocco added beachfront supply with the July 1, 2026 opening of Taghazout Bay Marriott Resort on its Atlantic coast, offering 250 rooms including 29 suites. Saudi hotel operators face a different utilization benchmark from serviced apartments and other facilities, so a new room's earning case depends on its format as well as its destination.
Regulatory Framework and Outlook
Selected jurisdictions are compared by the guest-selling, registration and classification requirements affecting accommodation operators. The perspective is that of a property business selling stays, including an establishment seeking an applicable accommodation grade. These frameworks place duties at different points in the transaction, from presenting a price to handling guest identity information and meeting property standards.
Regulatory Table of Hospitality Market
| Decision factor | United States | Brazil | Germany | China | South Africa |
|---|---|---|---|---|---|
| Primary authority | Federal Trade Commission | Ministry of Tourism | Registration authorities designated by state law | Shanghai Municipal Public Security Bureau | Tourism Grading Council of South Africa |
| Key instruments or direction | 16 CFR Part 464 short-term lodging total-price rules, effective May 12, 2025 | Digital National Guest Registration Form ordinance | Federal Registration Act, sections 29-30, for covered foreign guests | Shanghai lodging-registration provisions | Accommodation grading criteria revised in 2019 |
| Commercial effect | Calculable mandatory charges upfront, with conditional government, shipping and optional-charge exclusions | Digital guest registration replaces paper, with contingency exceptions | Arrival-day forms for covered foreign guests, subject to exemptions; named-guest ID checks; 1-year retention after departure then destruction within 3 months | ID verification and upload within 2 hours of registration; police or immigration verification form when valid ID is absent | Category-specific quality standards for establishments seeking grading |
| Current policy attractiveness | High | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
High attractiveness in the United States reflects pricing choice within a defined disclosure framework, with No change based on the continuing terms for presenting short-term stays. Brazil and Germany are Medium because guest-registration and record-handling duties remain operating tasks, supporting No change after Brazil's stated April 20, 2026 adoption deadline. China's Medium rating reflects Shanghai's timed data-handling requirements, with No change bounded by the provisions' validity through April 27, 2030. South Africa's Medium rating reflects the quality conditions of its grading route, with No change under criteria already covering small, boutique and apartment hotels.
Value Chain Stages
Value capture is compared across property ownership, brand affiliation, hotel software, booking distribution and the delivery of the stay. Host Hotels & Resorts owns hotel properties, with property-level operations generating room revenue. Hilton's franchise model separately earns revenue-based royalties and fees associated with hotel entry, ownership changes and contract extensions. Financial exposure therefore differs between funding a hotel and selling commercial services to its owner or operator.
Value Chain Analysis Table of Hospitality Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Property investment | Hotel property owners such as Host Hotels & Resorts | Room revenue generated by property operations | Potential site, financing and local approval constraints | Sequence capital commitments with financing and approvals |
| Brand affiliation | Hotel franchisors such as Hilton Worldwide Holdings | Royalties generally on gross room revenue; separate entry, ownership-change and extension fees | Entry and renewal fee commitments | Assess entry and extension charges alongside recurring royalties |
| Property systems deployment | Property-management software suppliers such as Oracle | Per-guest-room fees for multitenant OPERA Cloud Professional Foundation | Sequencing migration across multiple properties | Phase migrations while maintaining property service continuity |
| Reservation distribution | Online reservation platform operators such as Booking Holdings | Agency commissions when traveler payments are not facilitated | Reliance on an intermediary route for guest access | Balance intermediary bookings with property-controlled sales |
| Stay and on-site service delivery | Hotel operators such as Hilton Worldwide Holdings, through its ownership segment | Nightly room, food and beverage, and other service sales at consolidated hotels | Risk of mismatched service capacity | Align staffing and service schedules with booked demand |
| Source: Mordor Intelligence | ||||
Brand royalties, cloud-service fees and agency commissions attach to different commercial relationships, so resilience requires addressing each stage's constraint. Accor's 2025 reporting described a progressive rollout of Oracle OPERA for a shared global property management system. For providers using per-room service pricing, growth can follow adoption across existing properties, making additional earning capacity possible without the construction of new hotels.
Competitive Landscape
Market Concentration
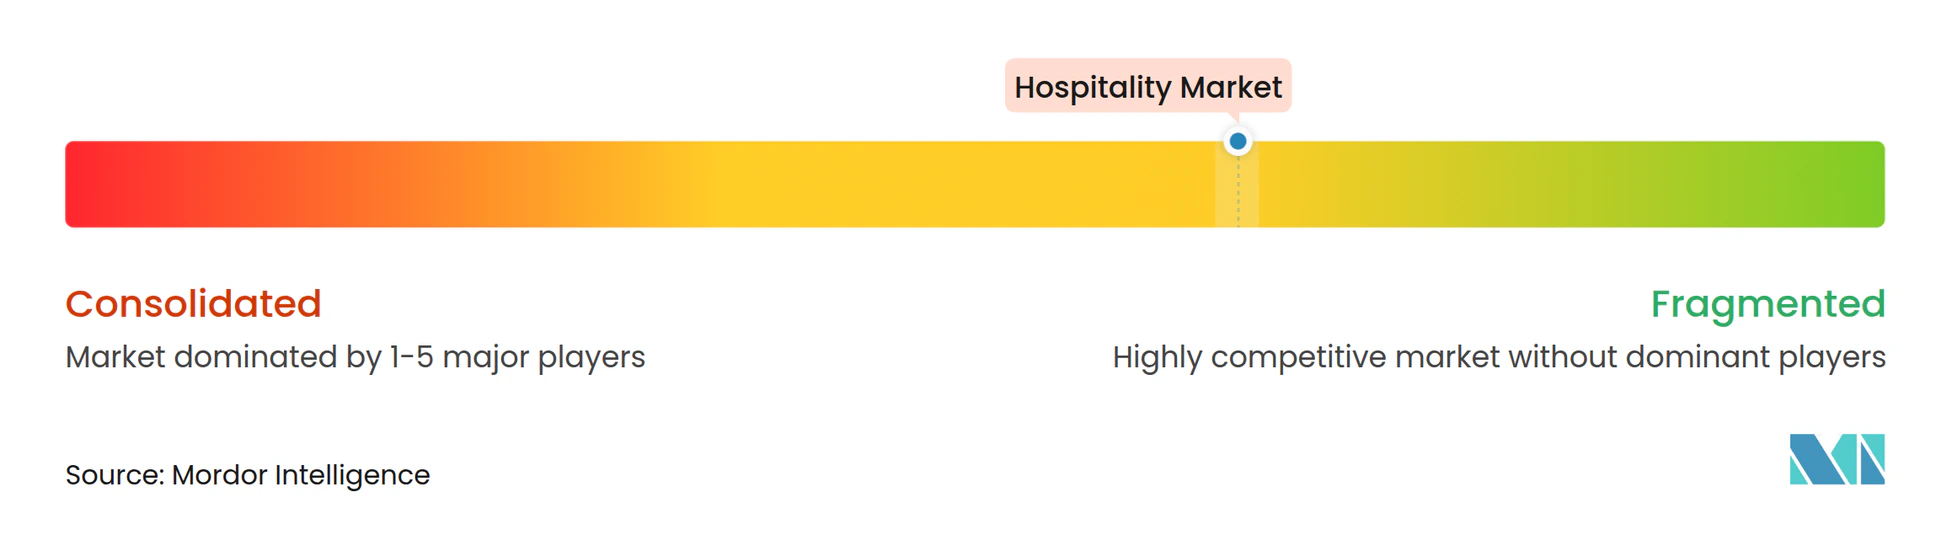
Competition is dispersed across property owners while large branded systems organize substantial accommodation networks, creating distinct layers of property and brand competition. Marriott International, Hilton Worldwide Holdings, Accor S.A., InterContinental Hotels Group (IHG) and Wyndham Hotels & Resorts compete through branded accommodation systems. Hilton opened 207 hotels with 24,100 rooms and added 21,600 net rooms in Q2 2026 across its global system of managed, franchised or licensed, and owned or leased properties. The 2,500-room gap between Hilton's gross openings and net additions distinguishes opening activity from the smaller increase in network capacity.
Acquisitions and conversions allow hotel groups to extend a branded portfolio through existing assets as well as new development. IHG reported 65,100 rooms across a record 443 hotel openings in 2025, with gross additions including Ruby acquisition rooms and NOVUM conversions. For owners, these routes make affiliation decisions relevant to an existing property's competitive position, alongside the option of building a new hotel. A competing brand can therefore challenge a network by winning an existing property's participation, making owner relationships a barrier that extends beyond physical room capacity. An acquired or converted property's integration into the brand's service proposition becomes the next competitive task after affiliation is secured.
The networks differ in both their development scale and realized expansion. As of June 30, 2026, Wyndham reported a record global development pipeline of approximately 261,000 rooms. Marriott International added roughly 17,900 net rooms worldwide in Q2 2026. At June 30, 2026, Marriott's worldwide pipeline totaled 4,186 properties with approximately 629,000 rooms, including 253 properties with over 34,000 rooms approved for development without signed contracts. Marriott's pipeline was more than twice Wyndham's, giving it a larger potential expansion base while making contract completion and openings central to realizing that competitive advantage.
Hospitality Industry Leaders
-
Marriott International
-
Hilton Worldwide Holdings
-
Accor S.A.
-
InterContinental Hotels Group (IHG)
-
Wyndham Hotels & Resorts
- *Disclaimer: Major Players sorted in no particular order
Hospitality Market Companies Covered in this Report
- Marriott International
- Hilton Worldwide Holdings
- Accor S.A.
- InterContinental Hotels Group (IHG)
- Wyndham Hotels & Resorts
- Hyatt Hotels Corporation
- Choice Hotels International
- Airbnb Inc.
- Sonder Holdings Inc.
- Extended Stay America
- OYO Rooms
- Jin Jiang International
- Meliá Hotels International
- Minor Hotels Europe & Americas (Minor International)
- Radisson Hotel Group
- Best Western Hotels & Resorts
- Louvre Hotels Group
- TUI Group
- MGM Resorts International
- Caesars Entertainment, Inc.
Key Opportunities for Market Participants
Opportunities are compared by how policy support can strengthen the accommodation offer or lower the cost of delivering it. Under June 2026 Hotel Rejuvenation Fund terms, the Singapore Tourism Board (STB) requires guest-experience enhancements, productivity solutions and sustainability initiatives within one comprehensive renovation. Applicants must be Singapore-registered businesses with a valid Hotels Licensing Board license. Applying before work, tendering, supplier payment or contracting starts makes project sequencing part of this investment decision.
Market Opportunities Table of Hospitality Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Hotel renovations for specific guest groups | Guest-experience upgrades form part of qualifying comprehensive renovations | Licensed Singapore hotels targeting families with children | Redesign the stay experience alongside the required productivity and sustainability components | Upfront funding before milestone-based reimbursement | Eligible Singapore hotel businesses |
| Hotel service redesign for productivity | Qualifying renovations must include measurable labor-hour savings | Licensed Singapore hotels redesigning service delivery | Link automation and process redesign to the guest-facing renovation | Demonstrating productivity gains while delivering all required project components | Eligible hotel owners and operators in Singapore |
| Energy efficiency at small hotels | Government-backed digital energy and carbon support for small and medium-sized hotels in England | Small and medium-sized hotels in England | Apply the free tool to hotel energy use and implement prioritized operating changes | Converting digital recommendations into sustained operating changes | Eligible small and medium-sized hotel businesses in England |
| Source: Mordor Intelligence | |||||
STB may approve fund applications by March 31, 2027, and processing may take up to 90 days after complete documents are received. Reimbursement depends on agreed milestones, deliverables and qualifying costs, with final support determined through STB evaluation. This favors owners able to finance the interval between delivery and reimbursement while coordinating guest, productivity and sustainability changes in the same renovation.
Recent Industry Developments in Hospitality Market
- Sep 2026: Hilton announced the opening of the 97-room Montara Hotel in Heredia, Costa Rica, on September 24, marking Tapestry Collection's first property in Costa Rica and Central America.
- Sep 2026: IHG announced the opening of the 685-room Crowne Plaza Manhattan Times Square in New York City on September 2. Al Rayyan Tourism Investment Company developed the hotel, and Highgate manages it.
Hospitality Market Report Scope and Research Methodology
Market Definition and Coverage
Hospitality market measures annual spending on accommodation properties worldwide. It counts property revenue from stays and related on-site services, classified by property type, booking channel, traveler type, and region.
Scope exclusions: Standalone restaurants and bars, travel agency and OTA commissions, real estate sales of accommodation properties, and standalone attractions and tour services are excluded.
Segments Covered in This Report
- By Hospitality Type
- Hotels & Resorts
- Vacation Rentals
- Serviced Apartments
- Hostels & Budget Accommodation
- Boutique & Lifestyle Hotels
- Luxury Hospitality Properties
- By Property Type
- Chain / Branded Properties
- Independent Properties
- By Booking Channel
- Direct Booking Channels
- Online Travel Agencies (OTAs)
- Corporate / Travel Management Companies
- Offline Travel Agents
- By Revenue Stream
- Room Revenue
- Food & Beverage Revenue
- Events & Conference Revenue
- Wellness & Recreation Revenue
- Other Ancillary Revenue
- By Traveler Type
- Leisure Travelers
- Business Travelers
- Bleisure Travelers
- Long-Stay / Digital Nomad Travelers
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Eurostat accommodation statistics provide nights and capacity indicators for hotels, short-stay properties, and campsites, while the World Bank's tourism-arrival series supplies a broad demand indicator. The American Hotel & Lodging Association's industry reporting helps interpret hotel wages, property costs, and guest spending, and Marriott International's annual report illustrates how filings distinguish room counts, property operations, and brand fees. These public sources help test demand, operating conditions, and revenue boundaries, such as regional accommodation nights and disclosed property activity.
Company filings, investor materials, reputable press coverage, and available tourism and accommodation datasets provide supplementary operating context and cross-checks for revenue trends and property supply. The named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include accommodation operators, brand and franchise leaders, property managers, booking-channel specialists, and finance or revenue leaders across the global field. Respondents would review secondary evidence on room revenue, on-site service income, property formats, and channel mix, and clarify how these measures are recorded in different markets. Analyst follow-up would target material gaps or conflicting definitions, then compare the resulting explanations with public filings, tourism indicators, and market estimates.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 35% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates global annual property revenue from the top down, then checks selected markets and formats with sampled room supply multiplied by occupancy and average daily room rates, plus limited on-site service revenue checks. Room supply, occupancy, average daily rates, accommodation nights, visitor flows, and on-property food, event, and wellness spending indicate how capacity, use, price, and ancillary purchases contribute to value. Segment shares are built from the same revenue evidence by hospitality format, ownership or brand status, booking route, traveler purpose, revenue stream, and region, with totals reconciled to the market estimate.
A multivariate regression can relate those indicators to annual revenue where comparable history is available, while scenario analysis adjusts the outlook for travel demand, operating costs, and market-specific constraints. Missing or inconsistent observations are cross-checked against adjacent years, regional indicators, and disclosed operator results, then documented assumptions are used only where evidence cannot resolve the gap. Interviews with relevant operating and financial roles would test whether the variable-level forecasts reflect local booking, pricing, occupancy, and service patterns before analysts reconcile them with the wider model.
Data Validation & Update Cycle
Analysts triangulate the market estimate against independent accommodation-night, room-supply, pricing, company-revenue, and tourism-demand signals, then investigate unusual movements and material differences between sources. A second analyst reviews calculations, definitions, segment totals, and source dates, with re-contact triggered by unresolved coverage questions, conflicting operator explanations, or a material change in a key input. The model is refreshed annually, updated between cycles when material market events change demand or supply, and given a fresh pre-delivery review of sources, assumptions, and totals.
Mordor Intelligence's Global Hospitality Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Hospitality market measures annual spending on accommodation properties worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression can relate those indicators to annual revenue where comparable history is available, while scenario analysis adjusts the outlook for travel demand, operating costs, and market-specific constraints.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 9.62 T (2027) | |
| Global Consultancy A | USD 927 B (2026) | At its 2026 base, this estimate is 90.4% below this report's 2027 value of USD 9.62 T, 1 year later. Its 2026 base precedes the comparison year, and its published forecast projects continued growth from that base. |
| Global Consultancy B | USD 845.7 B (2026) | At its 2026 base, this estimate is 91.2% below this report's 2027 value of USD 9.62 T, 1 year later. Its 2026 base precedes the comparison year, and its published forecast projects continued growth through 2030. |
Mordor Intelligence's analysts triangulate the market estimate against independent accommodation-night, room-supply, pricing, company-revenue, and tourism-demand signals, then investigate unusual movements and material differences between sources.
Key Questions Answered in the Report
What is the hospitality market size and growth outlook?
The size is projected at USD 9.62 trillion in 2027 and USD 12.46 trillion by 2032, with a CAGR of 5.31% over 2027-2032.
Which forces support demand for accommodation stays?
Flexible work and wellness-oriented stays are demand forces. Expedia Group's 2025 survey found 42% of adults across 11 markets planned a bleisure trip in the following 12 months.
Which accommodation type holds the largest share?
Hotels and resorts were the largest segment, with 56.33% of property revenue in 2026.
Which companies compete for accommodation business?
Major competitors include Marriott International, Hilton Worldwide Holdings, Accor S.A., InterContinental Hotels Group (IHG) and Wyndham Hotels & Resorts.
How do operating costs challenge lodging providers?
Total United States hotel labor costs rose 15% cumulatively from 2019 to 2025. That raises the revenue needed to support service delivery.
Which region leads accommodation revenue, and which is forecast to grow fastest?
Europe held 30.72% of property revenue in 2026, while Asia-Pacific is projected to grow fastest at a CAGR of 7.3% over 2027-2032.