
Luxury Hotel Market Analysis by Mordor Intelligence
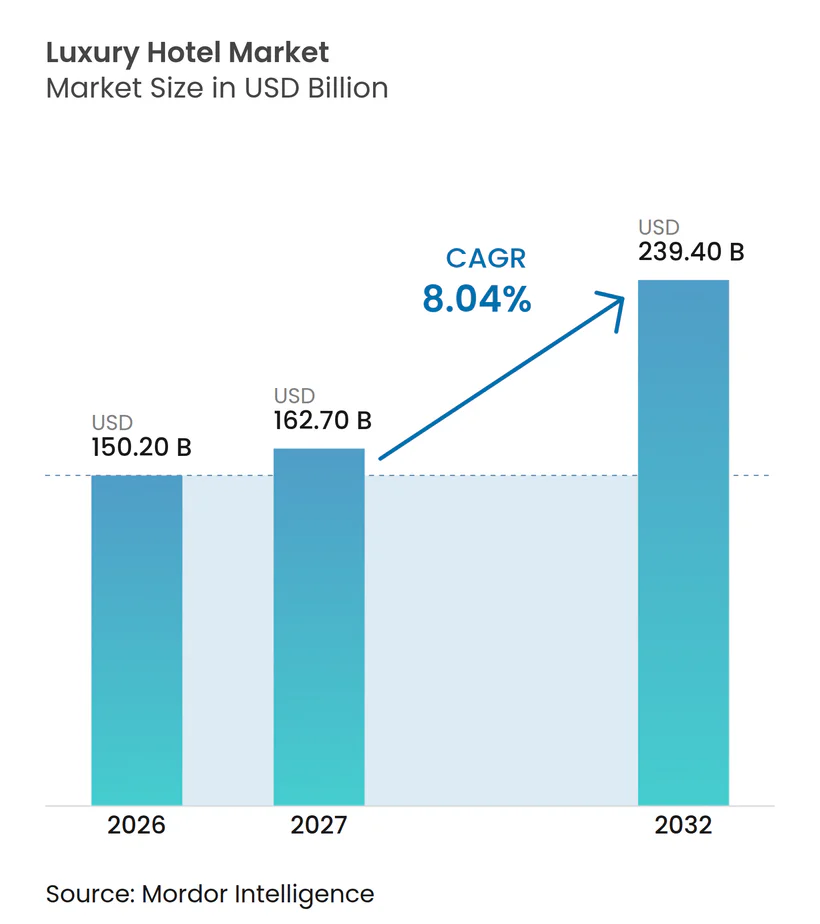
The luxury hotel market size is expected to increase from USD 150.2 billion in 2026 to USD 162.7 billion in 2027 and reach USD 239.4 billion by 2032, growing at a CAGR of 8.04% over 2027-2032.
International travel, stronger real purchasing power in China, and extended business-leisure stays support demand for premium accommodation. Operators can respond with destination-specific formats such as luxury hot-spring inns and booking routes that combine direct contact with agency distribution. High development capital requirements and the Middle East conflict that began in late February 2026 temper the conversion of travel demand into property earnings. Operators offering distinctive stays can address stronger Chinese purchasing power, while developers and Middle East properties bear financing and corridor risks that brand scale alone cannot remove.
Key Report Takeaways
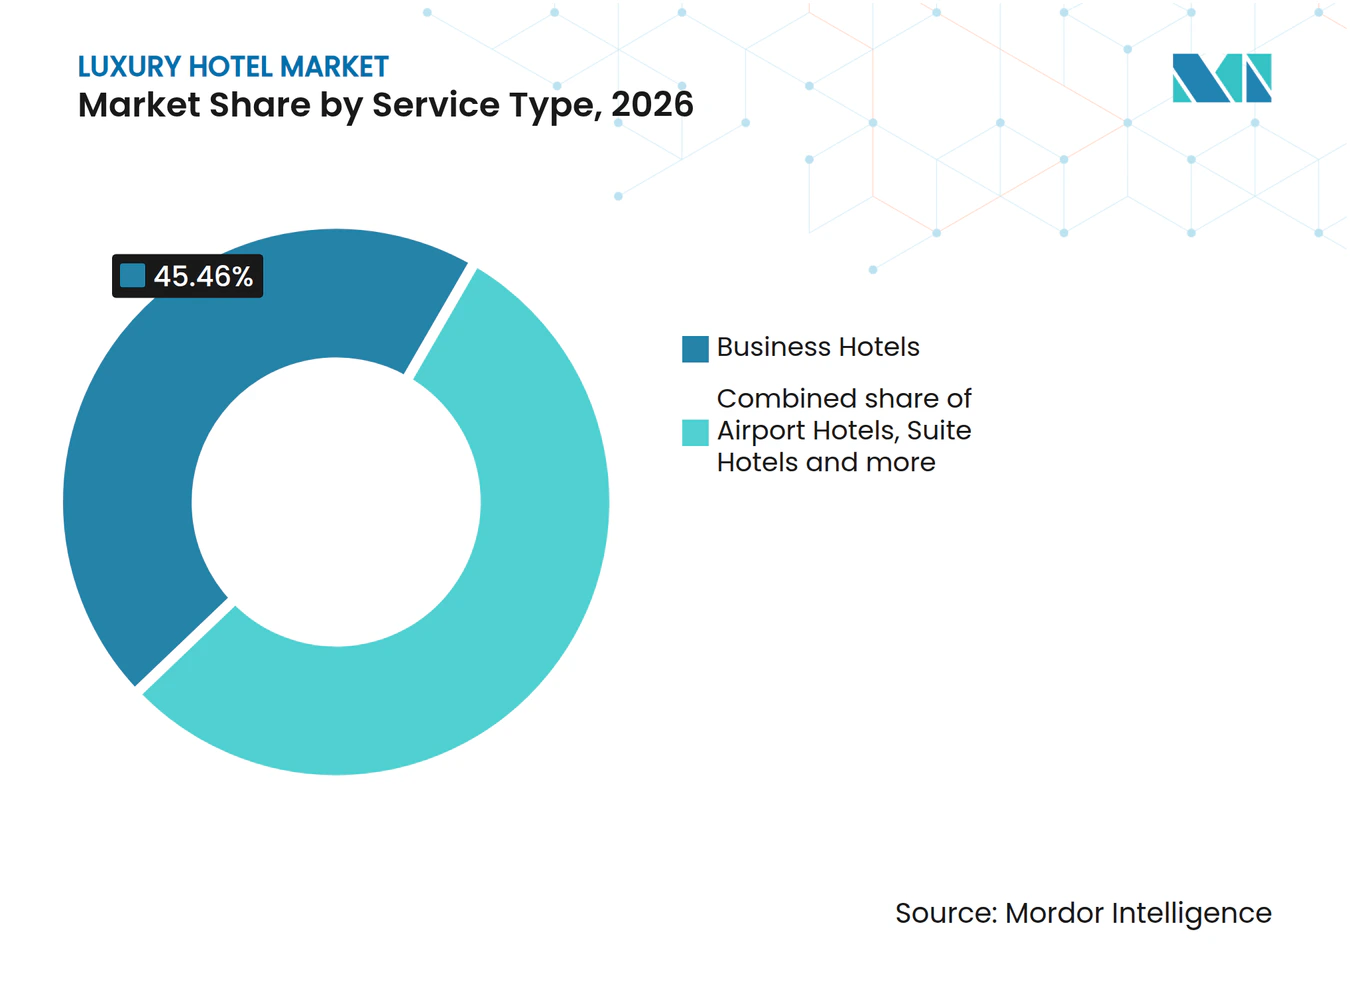
- By service type, business hotels led with a 45.46% luxury hotel market share in 2026, and resorts are forecast to be the fastest-growing segment at a 13.2% CAGR over 2027-2032.
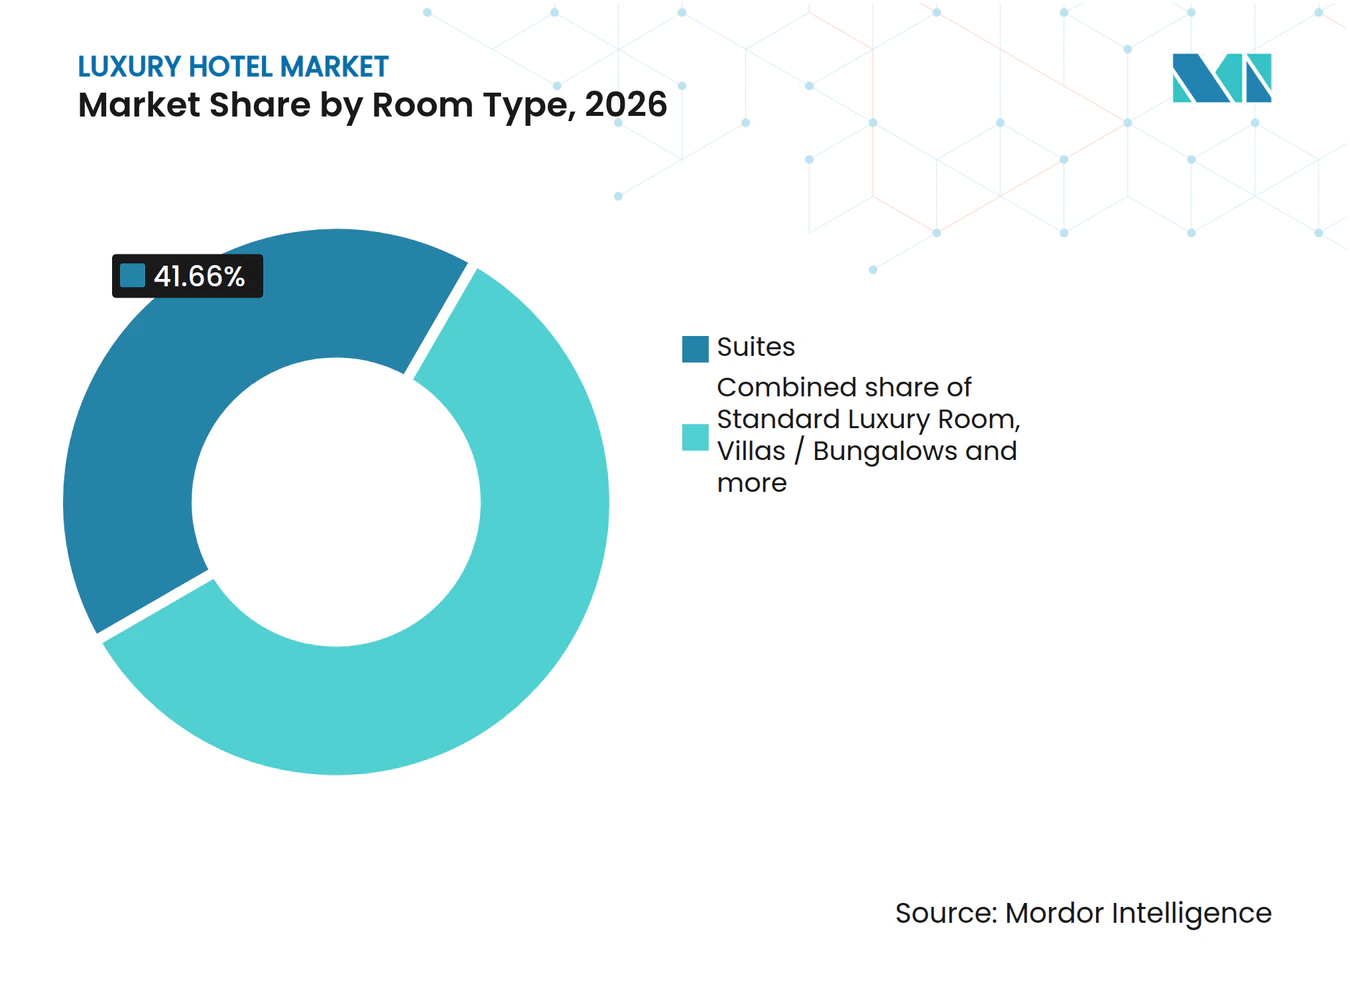
- Among room types, villas / bungalows are forecast to grow fastest at an 11.5% CAGR over 2027-2032, while suites led with a 41.66% share of the luxury hotel market size in 2026.
- Across booking channels, direct booking through brand websites and call centers led with 43.16% of market revenue in 2026, with online travel agencies forecast to be the fastest-growing segment at a 13.5% CAGR over 2027-2032.
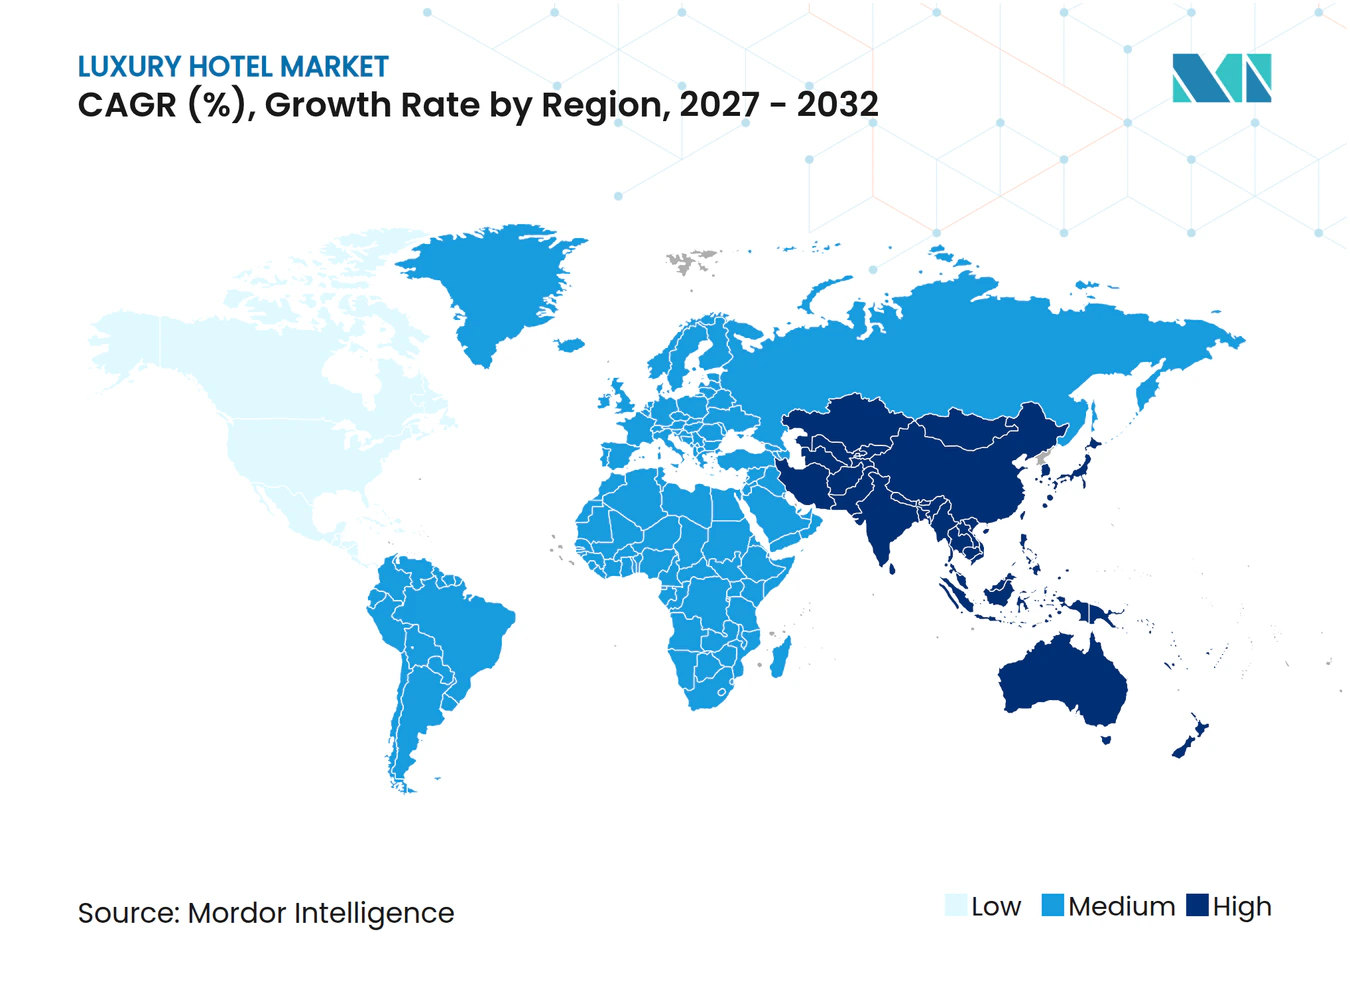
- Geographically, Europe held 37.08% of market revenue in 2026, while Asia-Pacific is forecast to be the fastest-growing region at an 11.2% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Luxury Hotel Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rebound of international tourism post-pandemic | +3% | Europe, Asia-Pacific and North America | Short term (≤ 2 years) |
| Rising disposable incomes in emerging Asian economies | +2.5% | China within Asia-Pacific | Medium term (2-4 years) |
| Expansion of branded luxury chains into tier-2 cities | +2% | India within Asia-Pacific | Long term (≥ 4 years) |
| Hybrid work trends boosting long-stay bleisure demand | +1.6% | Germany within Europe | Short term (≤ 2 years) |
| Growth of ultra-high-net-worth individuals from tech IPOs | +0.7% | The United States | Medium term (2-4 years) |
| Carbon-neutral certification premiums influencing bookings | +0.5% | Aruba in the Caribbean | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rebound of international tourism post-pandemic
Recovered inbound stays expand the accommodation demand pool for operators offering locally distinctive premium experiences. Japan Tourism Agency recorded 179.9 million foreign guest-nights across Japanese accommodation types in 2025, 9.4% above 2024 and 55.6% above 2019. Hoshino Resorts reported a 247% increase in international travelers staying at its luxury KAI onsen-ryokan brand in Japan in 2025 compared with pre-pandemic levels. The KAI result connects the recovery with a luxury format built around the Japanese hot-spring experience. International guests are the buyer pool that the KAI result demonstrates for these ryokan.
Rising disposable incomes in emerging Asian economies
Household income growth can improve the affordability of a premium stay without requiring a hotel to lower its room rate. China's nationwide per-capita disposable income rose 5% in real terms in 2025 compared with the previous year.[1] Separately, the China Hotel Association reported that luxury-hotel room-consumption heat points rose 4.6% year over year in August 2026. Its luxury category covers five-star hotels, including platinum, luxury, and ultra-luxury properties. The index tracks consumption activity using hotel room and food-and-beverage sales data. This combination supports premium-stay offers to Chinese guests, with the five-star consumption reading providing a more specific commercial signal than nationwide income alone.
Expansion of branded luxury chains into tier-2 cities
Luxury brands can widen the destinations they serve through individual property openings. Hotelivate-Savills' 2026 hospitality analysis identifies Udaipur, India, as a Tier 2 market under its sector-specific classification. Indian Hotels Company announced the opening of the 155-key Taj Lalit Bagh luxury retreat there in October 2025. Built around a century-old estate, the retreat combines local heritage with a branded luxury offer. That pairing gives the chain a way to sell Udaipur's destination character within its accommodation portfolio, supporting premium stays beyond metropolitan gateways.
Hybrid work trends boosting long-stay bleisure demand
Extending a business trip creates a lodging opportunity beyond the dates needed for work. IU International University of Applied Sciences' 2025-2026 research found that nearly half of surveyed business travelers in Germany combined work and private activities. Those travelers extended their stays by an average of 2 additional nights.[2] For luxury operators, converting an extension into continued occupancy avoids making demand depend on a second, separate trip. The commercial proposition can pair a work stay with leisure time at the same destination, provided its added cost is acceptable to the traveler. The relevant growth unit is the additional occupied night, so a longer stay can matter even when trip volumes do not change.
Restraints Impact Analysis of Luxury Hotel Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High capex & long ROI cycles | -1% | The United States | Long term (≥ 4 years) |
| Geopolitical instability on key luxury corridors | -0.8% | The Middle East | Short term (≤ 2 years) |
| Regulatory scrutiny on foreign ownership of landmark assets | -0.2% | The United States | Medium term (2-4 years) |
| Talent scarcity for bespoke service roles | -0.3% | The United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High capex & long ROI cycles
Luxury hotel owners face a financing test alongside the basic cost of development. HVS reported that median luxury-hotel development costs in the United States exceeded USD 1.6 million per room for projects proposed or under construction in 2025. For US hotel development generally, HVS reported in 2026 that lenders often required larger equity contributions and conservative underwriting, keeping otherwise feasible developments on the sidelines. At this capital intensity, a funding gap can hold back room additions before operations begin, delaying the point at which owners earn hotel revenue.
Geopolitical instability on key luxury corridors
For corridor-dependent hotels, a regional conflict can interrupt revenue growth even when a brand performs well elsewhere. The Middle East conflict began in late February 2026 and significantly affected Accor's regional activity in the first half of 2026. Accor reported that the Middle East was the only region without revenue per available room growth in its Luxury division in Q2 2026 versus Q2 2025. That contrast makes regional exposure commercially material even within a geographically diversified luxury portfolio. Accor credited geographic and segment diversification, combined with strict cost discipline, with supporting its group performance during H1 2026. An exposed property's investment case must absorb the local earnings risk even when the wider group's performance is protected.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Luxury Hotel Market Segment Analysis
By Service Type:
Business Functions Anchor Demand While Resorts Extend Destination ReachBusiness hotels accounted for a 45.46% share of the luxury hotel market size in 2026, making them the largest service-type segment. In February 2025, InterContinental Hotels & Resorts opened InterContinental Indianapolis with 170 guest rooms and suites. The luxury hotel included over 5,000 square feet of meeting and event space, a ballroom suitable for corporate events, and an executive boardroom. A ballroom and executive boardroom give the property distinct venues for larger functions and focused corporate meetings. Corporate planners can hold a function and house attendees at the same address.
Resorts are forecast to be the fastest-growing service-type segment, at a 13.2% CAGR over 2027-2032. The 188-room Hilton-managed Waldorf Astoria Costa Rica Punta Cacique opened in Guanacaste, Costa Rica, in April 2025, marking Waldorf Astoria's debut in the country. Revolution, Cacique Investors LLC and Garnier & Garnier owned the property, while Hilton provided its brand and management. Hilton's year-end report linked its regional openings with heightened traveler demand for curated, experiential stays. Managed resort capacity can extend a brand's reach into experiential destinations while separate owners provide the underlying property investment.



By Room Type:
Suites Form Core Capacity While Bungalows Differentiate the UnitSuites represented a 41.66% luxury hotel market share in 2026, making them the largest room-type segment. Following first-quarter 2025 performance, The Leading Hotels of the World reported suite-accommodation demand up 30% year over year across its portfolio. At its family-friendly coastal and lakeside locations, over half of stays were booked in suite categories. At these locations, suite availability governs the capacity to serve the predominant accommodation choice, making the room mix a constraint on that core offer.
Villas / bungalows are forecast to be the fastest-growing room-type segment, with an 11.5% CAGR over 2027-2032. Hilton announced the unveiling of 16 oceanfront bungalows at Zemi Miches Punta Cana All-Inclusive Resort in the Dominican Republic in June 2026. The announced accommodation came in studio-suite and two-bedroom-suite layouts, with private plunge pools and direct shoreline access. For operators evaluating this format, the different layouts can address different party configurations within the same coastal setting. The plunge pools and shoreline access place part of the leisure experience inside the unit itself rather than in shared resort areas.

By Booking Channel:
Direct Contact Retains Scale Alongside Agency Pricing TensionsDirect booking through brand websites and call centers accounted for 43.16% of luxury hotel revenue in 2026, making it the largest booking-channel segment. A separate 2025 study of 10 European hotel chains operating 831 hotels across 12 countries put real-time own-website bookings with availability checks at 20.1% of their bookings. Direct phone bookings represented 17.5% of bookings in the same chain sample. With phone bookings alongside real-time website reservations in the same chain sample, staff-assisted contact forms a substantial part of the own-channel mix.
Online travel agencies (OTA) are forecast to be the fastest-growing booking-channel segment, with a 13.5% CAGR over 2027-2032. Among participating hotels in 28 European countries, their share of bookings rose from 19.7% in 2013 to 29.9% in 2025. HOTREC's unweighted 2025 European survey also found that 51% of hotels reported frequent or occasional OTA rate undercutting. The channel offers a broadly used booking route while creating a practical tension over how the property's room rate is presented to the guest. Rate consistency across sales routes becomes part of the luxury property's commercial offer as agency distribution expands.
Geography Analysis
Europe Luxury Hotel Market
Europe accounted for a 37.08% share of the luxury hotel market size in 2026, making it the largest region. France's tourism development agency Atout France published a June 2026 collection of 33 exceptional five-star Palace hotels with 3-year designations, including 6 first-time recipients. The distinction recognizes outstanding locations, historical, aesthetic or heritage value, and excellence in service and amenities, giving operators complementary physical and service credentials. In Ireland, The Grace opened at Westport Estate in County Mayo in June 2026, pairing luxury lodging with regional landscape and heritage. A new brand flag cannot recreate a historic property's location or heritage, so competitive entry depends on the specific asset as well as the operator.
Asia-Pacific Luxury Hotel Market
Asia-Pacific is forecast to be the fastest-growing region, with an 11.2% CAGR over 2027-2032. JLL reported approximately USD 2.1 billion in Asia-Pacific luxury-hotel asset transactions in 2025, up 77% from 2017, and noted significant variation in performance across the region. Singapore gained a branded all-suite offer when Resorts World Sentosa and Marriott International opened The Laurus, a Luxury Collection Resort, with 183 suites in October 2025. In June 2025, Marriott's Autograph Collection debuted in Nepal at the existing Soaltee Kathmandu, with Nepalese design and luxury amenities, extending country coverage through an existing hotel rather than new rooms.
North America's US traveler pool was half Generation Z and millennials in the 2025 holiday season, creating a broad younger-adult audience for luxury operators to address. In South America, the Brazilian Luxury Travel Association's 2025 survey of 71 respondents, comprising 63 accommodation businesses and 8 travel operators, found 80% of foreign guests stayed in Brazil over 7 days, supporting itineraries. Colombia added a heritage-based option when Four Seasons opened its Cartagena hotel in restored Getsemaní buildings in April 2026. Within Middle East and Africa, the European Travel Commission linked Middle Eastern hotels' 2025 performance to expanded air connectivity and a year-round events calendar. Morocco gained its first Waldorf Astoria when Hilton opened Waldorf Astoria Rabat Salé in April 2026, extending that luxury brand's destination coverage into North Africa.
Regional Editions
All regions
Regulatory Framework and Outlook
The selected jurisdictions compare hotel access, classification, and guest-registration duties from the perspective of a luxury hotel operator seeking entry or continued operation. For hotel classifications expiring from September 1, 2026, operators in France seeking an extension must arrange the renewal inspection and notify Atout France before expiry. Operators must submit a complete renewal file within 6 months after expiry, including an inspection report less than 30 days old. Failure of either condition causes the classification to expire on its original date, making timely renewal part of the property's quality-positioning work.
Regulatory Table of Luxury Hotel Market
| Decision factor | United States | Brazil | France | China | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | US Department of Justice | Ministry of Tourism | Atout France | Local police and market-regulation authorities | Ministry of Tourism |
| Key instruments or direction | ADA Title III lodging-access rules; owner-occupied establishments renting 5 or fewer rooms excluded | Cadastur registration and mandatory FNRH Digital guest registration; adoption deadline April 20, 2026 | December 29, 2021 voluntary classification order; criteria reviewed at least every 5 years | Business license and special-industry permit before opening; guest registration and foreign-guest reporting within 24 hours | Tourism license with commercial register, municipal or housing license, Civil Defense permit, Shomoos and National Tourism Monitoring Platform linkage, facility data, and classification |
| Commercial effect | Applicable facility-date standards; readily achievable barrier removal; auxiliary-aid duties subject to undue-burden and fundamental-alteration limits | Active Cadastur registration required for FNRH access; noncompliance can bring notifications and administrative sanctions | Favorable accredited inspection every 5 years, plus mystery inspection for 4- and 5-star applications; Atout France may refuse classification | Entry licensing and check-in data-handling duties, including for foreign-invested lodging businesses | Inspection approval without observations and fee payment before licensing; trademark-use right if branded |
| Current policy attractiveness | Medium | Medium | High | Medium | Low |
| Future direction of policy attractiveness | No change | Easing | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The United States' long-term ADA review has no set rulemaking date, while China's nonbinding 2025 guidance encouraged building upgrades and permit optimization alongside licensing and guest-registration duties. France's No change assessment reflects continuing voluntary classification standards and recurring inspections, with the September 1, 2026 conditions refining the renewal procedure. Brazil's only evidenced easing signal is Senator Hiran's May 2026 suspension proposal, awaiting assignment on October 20, 2026, so FNRH Digital stays operative unless legislative adoption changes it. Saudi Arabia's No change assessment reflects continuing license prerequisites, Ministry inspection and fee payment, with penalties unchanged through June 30, 2027, and adopted amendments effective July 1, 2027, preserving entry conditions until then.
Value Chain Stages
Value capture differs across hotel asset ownership, brand operation, and booking distribution. Hilton's ownership segment earns primarily from room sales, food and beverage sales, and other services at its consolidated hotels. Marriott's management arrangements typically combine hotel-revenue base fees with profit-linked incentive fees, and their terms vary. These structures separate the return on a physical hotel asset from payments for brand and operating services.
Value Chain Analysis Table of Luxury Hotel Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Property investment and resilience | Hotel asset owners such as Host Hotels & Resorts and Hilton Worldwide | Room, food and beverage, and other service revenue at owned or leased hotels | Site-specific flood and power-outage exposure | Match physical protection and backup power to each property's exposure |
| Brand licensing and hotel operation | Hotel brand licensors and managers such as Marriott International | Application fees, typically revenue-based royalties, and variable base and incentive management fees | Different revenue and profit incentives across owner agreements | Align management incentives with property-level earnings and contract responsibilities |
| Booking and distribution | OTA groups such as Booking Holdings and Expedia Group | Platform commission income | European survey concerns over pricing and payment control | Apply channel-level pricing checks and payment reconciliation |
| Source: Mordor Intelligence | ||||
Host Hotels & Resorts installed modular flood barriers at 6 properties in 2025, including The Don CeSar and The Ritz-Carlton, Naples. This places physical resilience within the asset owner's investment decisions. Booking Holdings and Expedia Group held a combined 85.4% of the OTA share measured in HOTREC's 2025 European hotel sample, weighted by room count. Linking management fees to hotel revenue and profit does not itself protect the owner's physical asset or reduce exposure to concentrated OTA intermediaries.
Competitive Landscape
Market Concentration
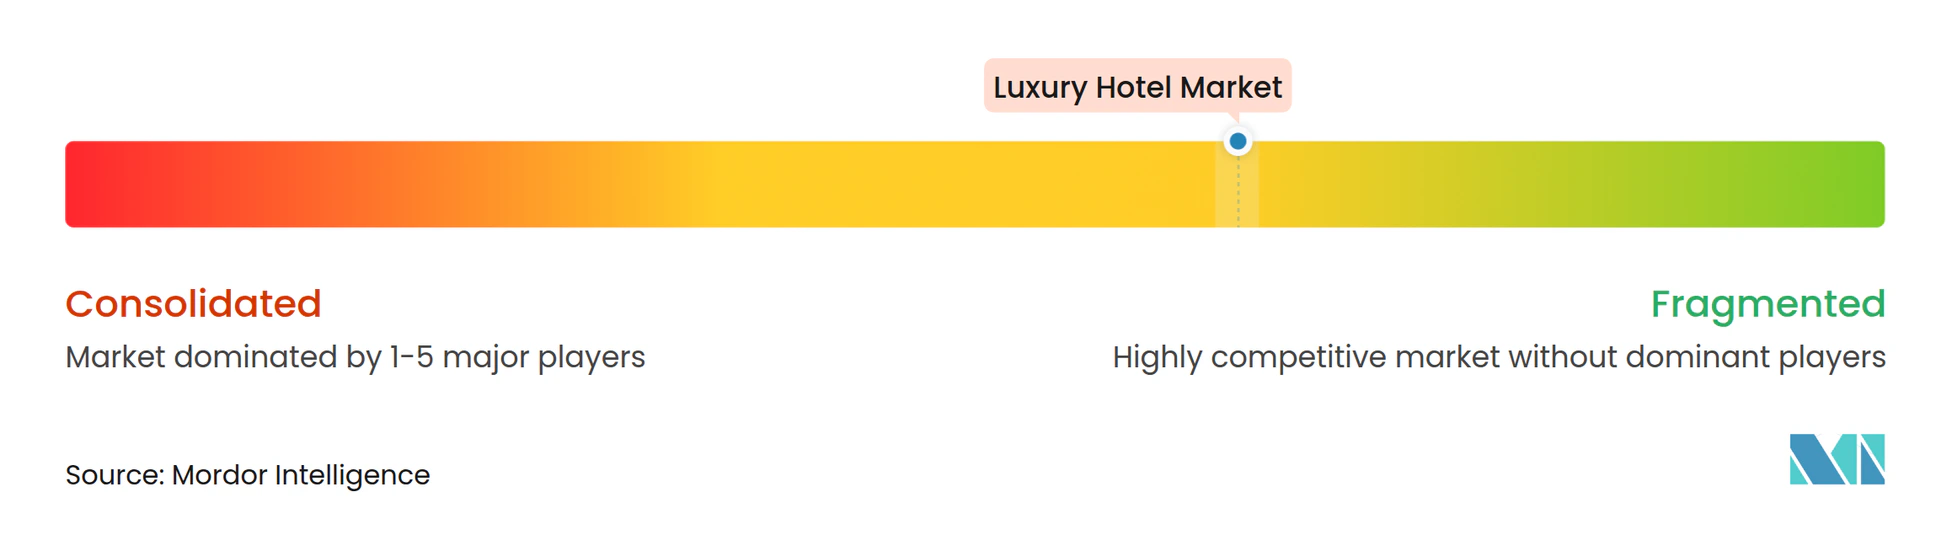
Marriott International participates through The Ritz-Carlton, whose Key Biscayne, Miami, property reopened in December 2025 after a USD 100 million transformation. Hilton Worldwide operates the Waldorf Astoria luxury brand, and Accor participates through Fairmont Hotels & Resorts. Hyatt Hotels Corporation includes Park Hyatt in its Luxury Portfolio, while Four Seasons Hotels & Resorts provides luxury hotel and resort hospitality. These roles create competition across several luxury brands and a dedicated luxury operator, so no single group's brand architecture defines the category.
Accor's Fairmont Hotels & Resorts opened Fairmont Golden Prague in April 2025 after renovation of a landmark brutalist building in the city's Old Town.[3] The property combined 320 rooms, suites, and serviced residences within Prague's UNESCO-listed Old Town. For Fairmont, renovation secures a heritage setting a new-build rival cannot reproduce, making the location part of the brand's competitive offer. In October 2025, Hilton-branded Waldorf Astoria New York opened a 22,000-square-foot Guerlain Wellness Spa with 16 treatment rooms, managed by Trilogy Spa Holdings. Because the spa is open to residents, locals, and visitors as well as guests, it can draw revenue from outside the hotel's overnight stays.
Hyatt announced Park Hyatt Tokyo's reopening in December 2025 after a 19-month restoration. In February 2026, Kenya's Environment and Land Court found statutory approvals and environmental scrutiny for Ritz-Carlton Maasai Mara Safari Camp's development, addressing conservatory orders without finally determining the underlying petition. The restoration projects at Key Biscayne, Waldorf Astoria New York and Park Hyatt Tokyo point toward competition through renewed established assets, alongside project-specific regulatory scrutiny in Kenya.
Luxury Hotel Industry Leaders
-
Marriott International (The Ritz-Carlton, St. Regis)
-
Hilton Worldwide (Waldorf Astoria, Conrad)
-
Accor (Fairmont, Raffles)
-
Hyatt Hotels Corporation (Park Hyatt, Andaz)
-
Four Seasons Hotels & Resorts
- *Disclaimer: Major Players sorted in no particular order
Luxury Hotel Market Companies Covered in this Report
- Marriott International (The Ritz-Carlton, St. Regis)
- Hilton Worldwide (Waldorf Astoria, Conrad)
- Accor (Fairmont, Raffles)
- Hyatt Hotels Corporation (Park Hyatt, Andaz)
- Four Seasons Hotels & Resorts
- InterContinental Hotels Group (Regent, InterContinental)
- Mandarin Oriental Hotel Group
- Kempinski Hotels
- Shangri-La Hotels and Resorts
- Rosewood Hotel Group
- Belmond Ltd.
- The Leading Hotels of the World
- Aman Resorts
- Six Senses Hotels Resorts Spas
- Banyan Tree Holdings
- Auberge Resorts Collection
- Dorchester Collection
- Oetker Collection
- Minor Hotels (Anantara)
- Jumeirah Group
Key Opportunities for Market Participants
The opportunities compare Reserve List site entry at River Valley Road, new hotel applications in the eligible Upper Circular Road and Beach Road street blocks, and owner-operator partnerships in Singapore. HVS reported slightly lower luxury-tier occupancy and revenue per available room in Singapore in 2025 as average daily rates rose modestly, making selective project positioning important. Singapore's Urban Redevelopment Authority (URA) earmarked the River Valley Road Reserve List site for a quality hotel, with activation dependent on developer demand and a government-acceptable minimum price. URA also agreed to consider new hotel applications in the Upper Circular Road and Beach Road street blocks received from June 5, 2026, through May 31, 2028.
Market Opportunities Table of Luxury Hotel Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Developer-led luxury hotel proposal at River Valley Road | Quality-hotel site available for Reserve List application | Hotel developers | Test a premium hotel concept against site conditions before seeking activation | Government-acceptable minimum price and tender eligibility | Hotel developers and luxury operators |
| Boutique luxury hotel applications in eligible street blocks | Temporary hotel-application route in Upper Circular Road and Beach Road | Boutique hotel operators and building owners | Prepare a site-specific hotel proposal within the application window | Application receipt by May 31, 2028 | Eligible building owners and boutique luxury operators |
| Owner-operator partnerships for a luxury hotel concept | Hotel-use applications can be considered in the eligible blocks | Property owners evaluating a hotel use | Pair site control with operator input before submitting a hotel proposal | Coordinating owner and operator commitments before the application deadline | Property owners and hotel management businesses |
| Source: Mordor Intelligence | |||||
Reserve List applicants must offer an acceptable minimum price and meet tender eligibility requirements. Following acceptance, a tender agreement and a 3% deposit capped at SGD 5 million (USD 3.9 million) are due within 2 weeks, and noncompliance causes acceptance to lapse. The street-block route makes timely submission the immediate decision, while each hotel proposal needs development approval. For luxury developers, selective site entry requires matching capital commitments to each route's decision point, since softer tier performance puts the premium concept's operating case ahead of land availability alone.
Recent Industry Developments in Luxury Hotel Market
- Jul 2026: Hilton and Reuben Brothers signed a management agreement for a Miami Beach hotel's conversion into Waldorf Astoria Miami Beach, with owner Reuben Brothers leading, Hilton managing, and a winter 2027 relaunch planned.
- Jun 2026: Marriott International completed a joint venture with the Leali family to bring the Lefay luxury wellness brand into its global portfolio. The venture owns the brand and intellectual property, while the family retains the Italian real estate and the properties operate under long-term management agreements with the venture.
- Jun 2026: Atout France unveiled its 2026 Palace collection of 33 exceptional French five-star hotels with 3-year designations, including 6 first-time recipients.
Luxury Hotel Market Report Scope and Research Methodology
Market Definition and Coverage
The global luxury hotel market measures annual spending on paid stays at luxury hotels worldwide, including room revenue and directly attributable guest services sold with the stay. It covers hotel stays across booking routes and all global regions.
Scope exclusions: Short-term rentals, airline and cruise tourism spend, and off-property luxury experiences sold separately from the lodging transaction are excluded.
Segments Covered in This Report
- By Service Type
- Business Hotels
- Airport Hotels
- Suite Hotels
- Resorts
- Other Service Types
- By Room Type
- Standard Luxury Room
- Suites
- Villas / Bungalows
- Penthouses & Presidential Suites
- By Booking Channel
- Direct Booking (Brand Website, Call Center)
- Online Travel Agencies (OTA)
- Travel Agents / Tour Operators
- Corporate Contracts
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public evidence such as the World Bank's international tourism arrivals series, the World Travel & Tourism Council's economic impact research, China's National Bureau of Statistics household income releases, and JLL's hotel investment outlook helps analysts assess travel flows, spending capacity, hotel performance and future room supply. These sources provide indicators for demand and capacity rather than direct measures of luxury hotel revenue, so annual property and market revenue must be checked against operator disclosures and the report's paid-stay boundary.
Company filings, investor materials and reputable hospitality reporting can clarify room revenues, operating models, openings, occupancy and rate trends, while independently published market estimates provide comparison points. The named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
A structured interview and survey program would seek input from hotel owners and asset managers, brand and property operators, revenue and distribution leaders, and luxury travel advisors across APAC, EMEA and the Americas. Respondents would be asked to check secondary findings on paid-stay revenue, room mix, booking routes, regional demand, pricing and planned supply, with unresolved differences returned for clarification. The analyst would triangulate comments against filings, operating indicators and market evidence, then document gaps where independent support is unavailable.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 38% |
| Mid tier: 50% | Functional/Unit leaders: 35% | EMEA: 34% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The top-down estimate starts with global paid luxury hotel stays and reconciles them to operator revenues, then selectively checks the result with sampled room-night volume multiplied by realized average daily rate and with supplier or channel roll-ups where reliable public data exist. Occupied room nights, luxury room supply, occupancy, average daily rate, and booking and room mix inform the forecast: nights and occupancy indicate sold capacity, rates convert stays to value, and mix captures differences in room formats and routes to booking. The model uses multivariate regression where these indicators have a consistent history and scenario analysis where openings, travel recovery or regional disruption make the path uncertain. Tourism arrivals, income and investment indicators frame demand and capacity, while hotel disclosures ground operating checks. Segment shares are built from evidence on revenue by service type, room type, booking channel and region, and primary respondents check whether each variable's forecast fits operating conditions. Missing series are bounded with the closest comparable indicator and recorded as a gap rather than treated as observed data.
Data Validation & Update Cycle
Analysts triangulate operator disclosures, independent tourism and hotel indicators, and market estimates, then check totals, year-on-year movements, regional shares and segment trends for anomalies or unexplained variance. A second review traces each material input to its source and checks unit, year, scope and arithmetic. Analysts resolve anomalies before sign-off and re-contact relevant respondents when definitions conflict or new information could change a major input. The evidence is refreshed annually, revisited between cycles after material travel, supply or regulatory events, and checked in a fresh pre-delivery pass.
Mordor Intelligence's Luxury Hotel Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global luxury hotel market measures annual spending on paid stays at luxury hotels worldwide, including room revenue and directly attributable guest services sold with the stay.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Tourism arrivals, income and investment indicators frame demand and capacity, while hotel disclosures ground operating checks.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 162.7 B (2027) | |
| Global Consultancy A | USD 118.4 B (2026) | At its 2026 base, this estimate is 27.2% below this report's 2027 value of USD 162.7 B, 1 year later. Its 2026 measurement year precedes the report's 2027 value. |
| Global Consultancy B | USD 137.9 B (2026) | At its 2026 base, this estimate is 15.2% below this report's 2027 value of USD 162.7 B, 1 year later. Its four-star and five-star hotel definition is narrower than the report's luxury paid-stay boundary. |
Mordor Intelligence's analysts triangulate operator disclosures, independent tourism and hotel indicators, and market estimates, then check totals, year-on-year movements, regional shares and segment trends for anomalies or unexplained variance.
Key Questions Answered in the Report
What is the luxury hotel market size and growth outlook?
The market is projected at USD 162.7 billion in 2027 and USD 239.4 billion in 2032, with an 8.04% CAGR over 2027-2032.
What is driving demand for luxury hotel stays?
China's nationwide per-capita disposable income grew 5% in real terms in 2025. In August 2026, the China Hotel Association's five-star luxury category recorded a 4.6% year-over-year increase in room-consumption heat points.
Which luxury hotel service type has the largest share?
Business hotels were the largest service-type segment, with 45.46% of market revenue in 2026.
Which companies are major luxury hotel operators?
Major participants include Marriott International, Hilton Worldwide, Accor, Hyatt Hotels Corporation, and Four Seasons Hotels & Resorts.
What limits new luxury hotel development?
HVS reported median US luxury-hotel development costs above USD 1.6 million per room for projects proposed or under construction in 2025. Its 2026 report also said lender requirements kept otherwise feasible US hotel developments on the sidelines.
Which region leads luxury hotel revenue, and which is forecast to grow fastest?
Europe led with 37.08% of market revenue in 2026. Asia-Pacific is forecast to grow fastest at an 11.2% CAGR over 2027-2032.