
Convenience Store Market Size and Share
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Market Size (2026) | USD 1.01 Trillion |
| Market Size (2031) | USD 1.35 Trillion |
| Growth Rate (2026 - 2031) | 6.02 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Low |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Convenience Store Market Analysis by Mordor Intelligence
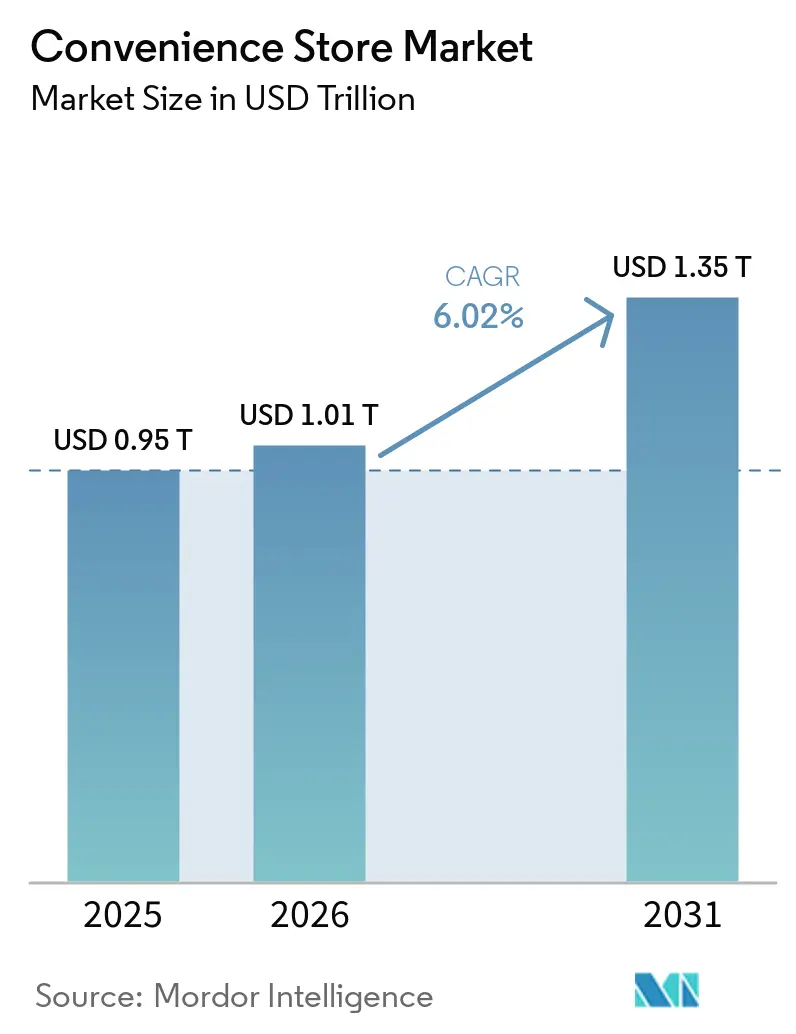
The convenience store market size was valued at USD 0.954 trillion in 2025 and estimated to grow from USD 1.01 trillion in 2026 to reach USD 1.35 trillion by 2031, at a CAGR of 6.02% during the forecast period (2026-2031). The market is evolving beyond the fuel-and-impulse model as foodservice, loyalty programs, EV charging, and local fulfillment reshape store economics. In the United States, convenience retailers generated USD 817.5 billion in sales across nearly 152,000 locations in 2025, while in-store sales reached USD 341.2 billion, marking the 23rd consecutive year of growth. Operators compete on food quality, digital engagement, and serving multiple customer needs per visit. Rising labor costs, food-promotion regulations, and modernization investments pressure margins. Larger chains use acquisitions, franchising, partnerships, and selective expansion, while smaller operators focus on assortment and operational discipline.
Key Report Takeaways
- By product category, staple products accounted for a 56.13% share of the convenience store market in 2025, while the staple products segment is projected to grow at a 7.04% CAGR through 2031.
- By store type, traditional convenience stores accounted for a 35.81% share of the convenience store market in 2025, while hyper convenience stores are projected to grow at a 9.40% CAGR through 2031.
- By ownership structure, independent stores accounted for a 56.12% share of the convenience store market in 2025, while branded stores are projected to grow at a 6.30% CAGR through 2031.
- By geography, North America accounted for a 40.54% share of the convenience store market in 2025, while Asia-Pacific is projected to grow at a 7.18% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Convenience Store Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Urban Micro-Fulfilment Demand Spike | +1.2% | Global, concentrated in dense urban areas | Medium term (2-4 years) |
| Cash-Rich Private-Equity Roll-Ups | +0.8% | North America & Europe primarily | Short term (≤ 2 years) |
| Digital Lottery & Gaming Commissions | +0.7% | North America, expanding to Asia-Pacific | Medium term (2-4 years) |
| EV-Charger Foot-Traffic Boost | +1.4% | North America & European Union leading, Asia-Pacific following | Long term (≥ 4 years) |
| Subscription-Based Meal-Kits Pick-Up | +0.6% | Urban North America & Europe | Medium term (2-4 years) |
| Real-Time Planogram Analytics | +0.8% | Global, technology-advanced markets first | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Urban Micro-Fulfilment Demand Spike
Dense city cores increasingly rely on convenience stores as last-mile hubs for two-hour and same-day delivery services, allowing operators to serve both walk-in and digital orders from the same shelf location. In 2024, Casey's completed the acquisition of a Star Food Store located in Texas, strategically enhancing its presence in delivery-friendly zones. This acquisition is expected to generate incremental revenue while maintaining minimal growth in fixed costs, reflecting a calculated approach to operational expansion and resource optimization. Wawa’s 70-store Southeast expansion follows a similar logic, ensuring enough nodes to guarantee 15-minute delivery windows. Real-time planogram tools feed demand signals directly to distribution centres, keeping high-velocity SKUs in stock and trimming spoilage. Municipal zoning rules increasingly reserve curb-space permits for companies that maintain brick-and-mortar sites, tilting competitive advantage toward established convenience brands.
Cash-Rich Private-Equity Roll-Ups
First Reserve has explored a USD 1.5 billion sale of Refuel, underscoring how financial sponsors view the category as defensive, cash-generative, and exit-ready[1]. Arko Corp.’s decision to divest its company-operated stores, valued at USD 2 billion, reflects significant opportunities for both strategic acquirers and private equity sponsors. Casey’s recent acquisition of CEFCO sites demonstrates how corporations strategically utilize debt financing to compete with private capital, achieving operational efficiencies in areas such as fuel procurement and prepared-food logistics. These developments collectively drive the professionalization of operations, enhance data standardization, and improve access to capital within the convenience store market, fostering a more competitive and streamlined industry landscape.
Digital Lottery & Gaming Commissions
Online lottery approvals in Massachusetts and self-service terminal rollouts in Canada have added high-margin fee income that requires little additional labour. Digital channels significantly enhance the accessibility and distribution of ticket sales, enabling broader audience engagement. Meanwhile, physical stores serve as strategic touchpoints by facilitating prize-redemption activities, which, in turn, drive incremental revenue through increased ancillary sales. Age-verification modules integrate with existing POS hardware, a barrier for independent bodegas but a straightforward upgrade for chain operators. As the United States seeks new tax revenue, more jurisdictions are expected to authorize digital lottery, sustaining this driver into the medium term.
EV-Charger Foot-Traffic Boost
Pilot Company, which operates a network of over 130 fast-charging stations, has reported significant growth in both customer traffic and revenue. This expansion highlights the increasing demand for electric vehicle (EV) infrastructure and its positive impact on business performance[2]. A considerable proportion of electric vehicle (EV) drivers make purchases of food or beverages during their charging sessions, which typically last several minutes. This behavior results in higher transaction values compared to visits by gasoline vehicle users. Federal tax incentives currently subsidize up to a significant portion of the installation expenses for direct-current fast chargers, thereby improving the return on investment for businesses adopting this technology. Additionally, early adopters gain a competitive advantage through locational exclusivity, as regulatory frameworks increasingly require the integration of EV infrastructure in new property developments.
Restraints Impact Analysis of Convenience Store Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Urban Lease Renewals | -0.8% | Global urban centres, particularly in North America | Short term (≤ 2 years) |
| Stricter HFSS Product Limits | -0.6% | Europe leading, expanding globally | Medium term (2-4 years) |
| Labour Shortage & Minimum-Wage Escalation | -0.7% | Developed markets globally | Short term (≤ 2 years) |
| Cyber-Security Liability for Self-Checkout | -0.4% | Technology-advanced markets | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Urban Lease Renewals
In the fourth quarter of 2024, the average rental rate for shopping centres in the United States reached USD 24.76 per square foot, reflecting the ongoing demand for retail spaces and the resilience of the commercial real estate market CBRE.COM. Cap-rate compression continues to sustain elevated property valuations, which, in turn, drive significant increases in renewal rates. This trend emerges at a time when macroeconomic challenges are exerting pressure on discretionary consumer spending. 7-Eleven shuttered 400 under-performing North American sites in late 2024, chiefly in rent-intensive metros, to recycle capital into high-return formats. Zoning laws often block relocation to cheaper districts without fuel-tank re-permitting, locking operators into escalators that compress margins.
Labour Shortage & Minimum-Wage Escalation
Casey’s trimmed labour hours for seven straight quarters, yet still faced a slight jump in same-store employee expense in fiscal 2024. Overnight shifts remain hardest to staff due to safety concerns and sparse transit options. Murphy USA has reported an increase in operating expenses, primarily driven by higher wages and maintenance costs. This trend is largely attributed to jurisdictions implementing minimum wage hikes at a rate that surpasses productivity improvements, thereby exerting upward pressure on store-level operating expenditures. Self-checkout, AI inventory, and automated fuel dispensers mitigate but do not fully offset the upward pressure, particularly for independents lacking scale to amortize technology.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Convenience Store Market Segment Analysis
By Type:
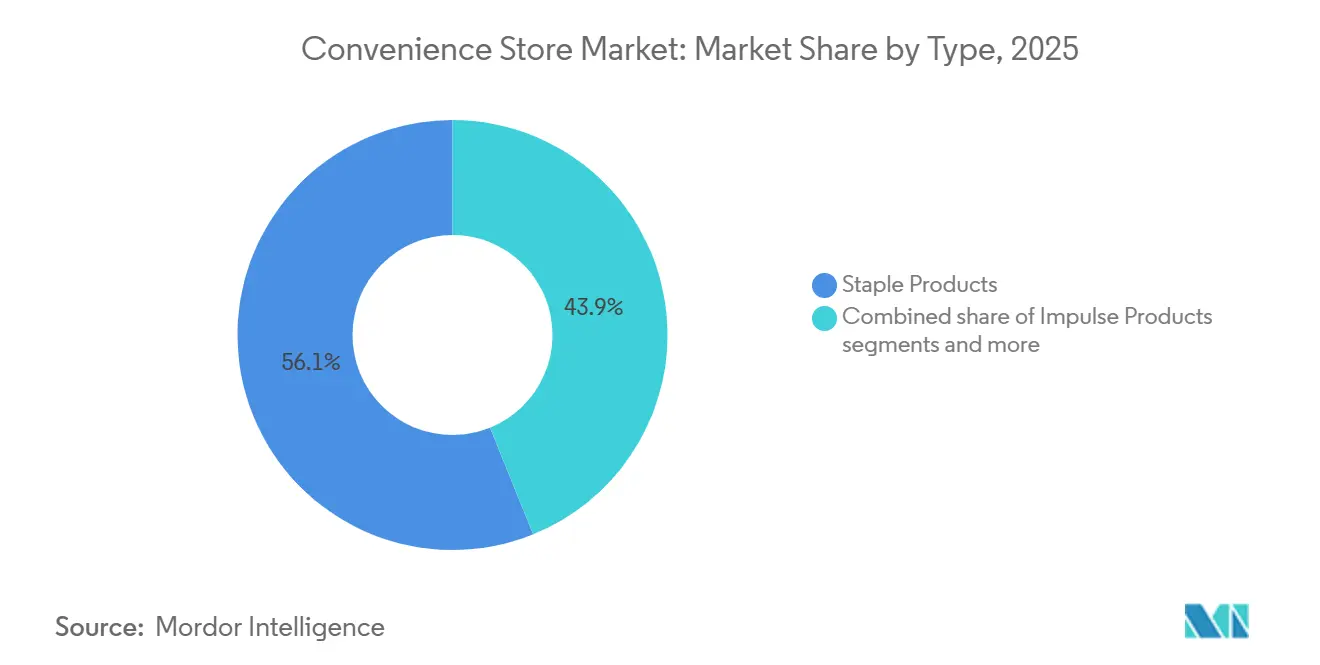
Staple Products Lead Both Revenue and GrowthStaple Products accounted for 56.13% of the global convenience stores market in 2025 and are projected to grow at a CAGR of 7.04% through 2031. This share and growth indicate that consumers increasingly use convenience stores for everyday replenishment. Food service, prepared foods, and competitive pricing enable stores to meet needs traditionally served by supermarkets. United States inside-store sales increased for the 23rd consecutive year in 2025, with foodservice and prepared foods making the largest contribution to category profits. This shift increases the need for reliable availability, fresh assortments, fast service, and disciplined daily operations.
Impulse Products increase basket values, particularly alongside ready-to-drink beverages, snacks, and lottery purchases. Emergency Products remain relevant in high-density urban areas and airport or transit locations, where immediate access provides value. Foodservice investments also blur the distinction between staple and emergency purchases as consumers buy prepared meals at store counters rather than restaurants. Casey's, which operates more than 2,900 United States locations, reported a 16% EBITDA CAGR under its previous three-year strategic plan, driven by foodservice investments. These trends support a staple-focused offering while retaining immediate-consumption categories

By Ownership Structure:
Independents Lead Revenue While Branded Networks Gain GroundIndependent stores accounted for 56.12% of revenue in 2025, while branded stores are forecast to grow at a CAGR of 6.30% through 2031. This large independent-store base reflects the historical role of family-owned and community retailers across Asia and developing markets. Branded operators provide centralized procurement, loyalty programs, digital marketing, and standardized food safety procedures. Franchise models retain local ownership participation while providing outlets with support from a larger operating platform. This structure enables branded networks to scale faster in markets where store density and logistics are important.
The branded model also improves the economics of technology adoption by enabling deployment across multiple locations. It supports standardized procedures for fresh food, promotions, compliance, and customer data management. Casey's plans to add at least 400 stores during FY2027-FY2029 through acquisitions and organic development. The company stated that acquired stores can meet its return requirements with nearly USD 1 million less capital per unit than new-build stores because conversion costs are lower. Independent stores remain important where local trust and flexible assortments matter, but branded operators have an advantage as investment requirements increase. Competition in the global convenience stores market will focus on whether scale can improve service without reducing local relevance.
By Store Type:
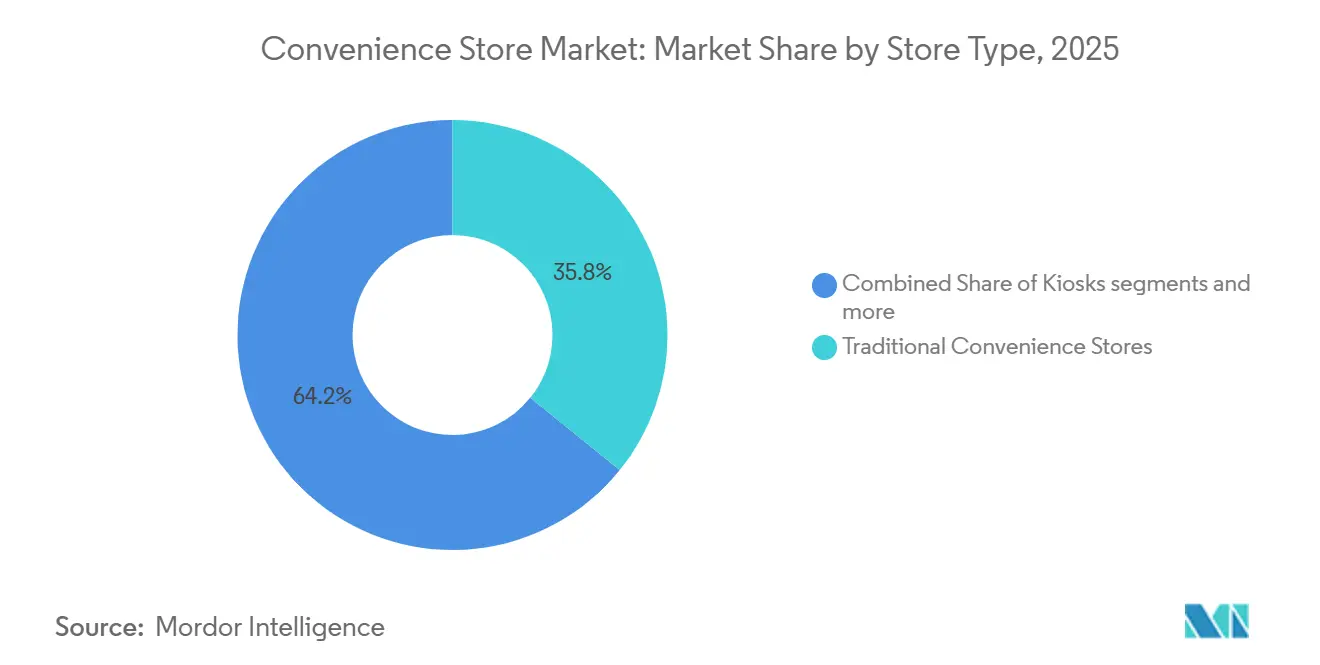
Traditional Formats Retain Scale While Hyper Stores Set the Growth PaceTraditional Convenience Stores held 35.81% of revenue in 2025, while Hyper Convenience Stores are projected to expand at a 9.40% CAGR through 2031. The traditional format benefits from its large installed base and its familiar role in local neighborhoods. Hyper formats appeal to customers seeking broader fresh food, coffee, seating, EV charging, and curated merchandise in one stop. FamilyMart opened FAMIMA PARK AZABUDAI in Tokyo in July 2026 as its first flagship under the Next FamilyMart Project. The concept shows how established operators are testing stores that move beyond a conventional convenience format. Such investments allow leading chains to address longer visits without giving up the accessibility of smaller sites.
Mini Convenience Stores and Kiosks can serve residential communities and transit-linked locations where a full staffed format may not be viable. Unmanned formats can extend access, but they require reliable payment systems, clear security controls, and customer acceptance. Expanded Convenience Stores provide a more practical upgrade path for operators that want to add foodservice without undertaking a full hyper-store conversion. The adoption of self-service formats also makes customer data protection and payment resilience more important. Store design in the global convenience stores market will therefore vary by location, local demand, and the operator's ability to support technology securely.
Geography Analysis
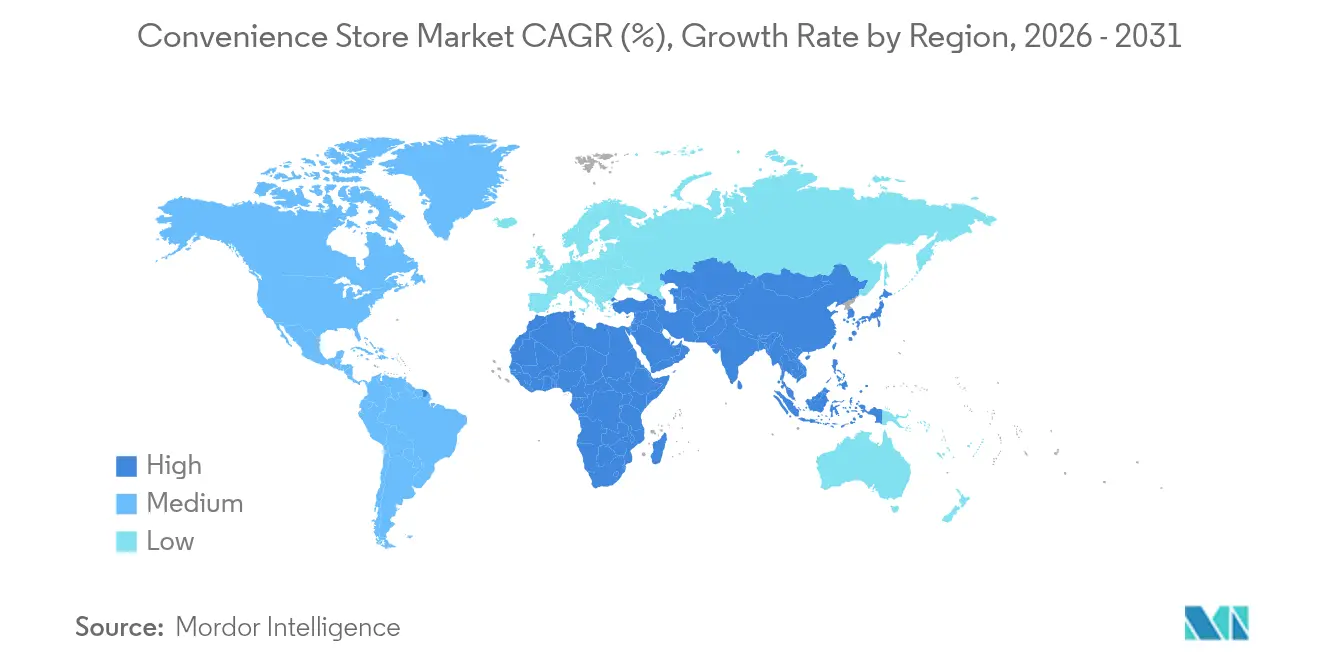
North America is projected to account for 40.54% of revenue in 2025 and grow at a 5.40% CAGR through 2031. Its dense network of fuel and retail outlets and developed foodservice offerings support its position in the global convenience store market. The United States generated USD 817.5 billion in convenience industry sales across 151,975 locations in 2025, including USD 341.2 billion in in-store sales. Foodservice, EV charging, and loyalty program monetization remain central to the region's operating model. Sunoco's acquisition of Parkland is expected to add more than 3,600 convenience and fuel sites to the combined North American network.
Asia-Pacific is forecast to grow at a 7.18% CAGR through 2031, the highest among the regions covered. Urbanization, rising incomes, and the expansion of Japanese and Korean operating models support growth. In July 2026, Seven & i Holdings secured JPY 300 billion (USD 1.92 billion) from SoftBank, PayPay, and Sumitomo Mitsui Card for digital infrastructure and store-experience upgrades. In China, the top 100 companies are projected to operate 208,000 stores in 2025 after adding a net 11,000 stores, while single-store daily revenue is expected to decline by 3.9%.
Europe is forecast to grow at a 4.90% CAGR through 2031, compared with 6.10% for South America and 6.80% for the Middle East and Africa. European operators are adapting through smaller urban formats, foodservice, and HFSS compliance. FEMSA assumed full ownership of OXXO Brazil in February 2026 following the completion of the separation of its Grupo Nós joint venture with Raízen. The company targeted approximately 100 net new OXXO Brazil stores in 2026, while management indicated that the operation would likely require around 1,000 stores to absorb its overhead costs as it scales. Growth opportunities depend on aligning store formats with local infrastructure and purchasing patterns.
Competitive Landscape
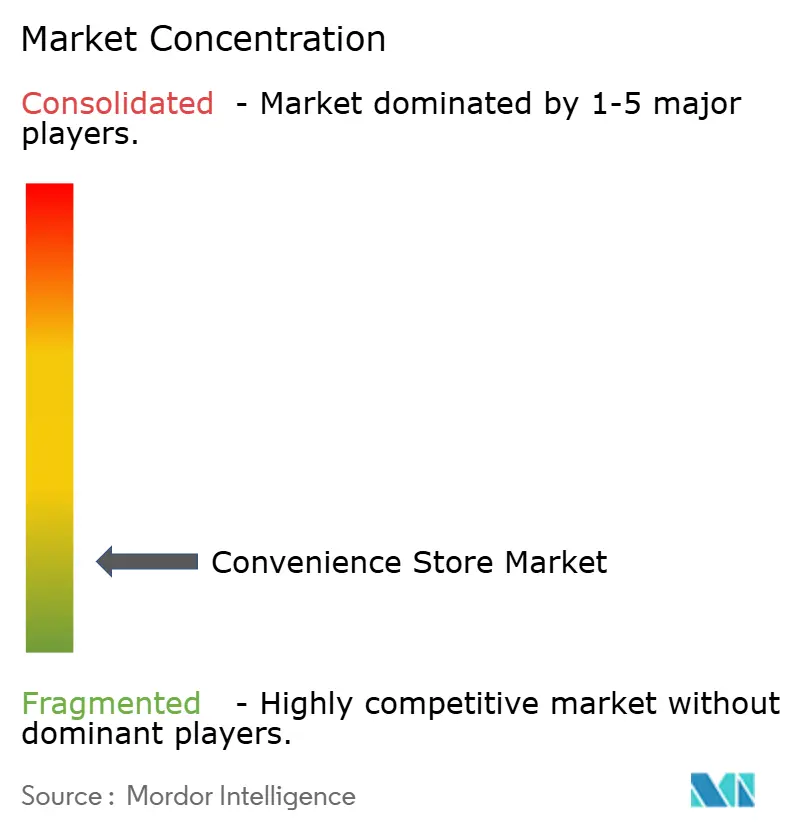
The global convenience store market is fragmented, with the top five operators accounting for no more than 30% of combined global revenue in the supplied data. Seven & i Holdings operates approximately 87,000 stores globally, while Alimentation Couche-Tard operates more than 16,800 stores across 31 countries and territories. FamilyMart reported 25,646 stores as of August 31, 2026, while Lawson reported 22,490 stores as of May 2026, including 7,782 outside Japan. These networks indicate broad international footprints but do not imply a dominant share of global revenue.
Leading operators are investing in digital loyalty, food quality, store formats, and supply-chain capabilities. Lawson's AI-backed ordering system helped reduce waste and supported higher customer traffic, contributing to the operating profit of JPY 90.4 billion (USD 0.58 billion) for March-November FY2025. Seven & i's July 2026 capital alliance also supports investment in digital retail infrastructure and customer experience. These initiatives indicate that competition extends beyond store count to loyalty, data capabilities, and digital services.
Expansion opportunities remain in lower-penetration markets, including Southeast Asia. GS25 reached 400 stores in Vietnam in November 2025, while FamilyMart expanded into Hanoi in September 2026 and targets approximately 300 Vietnam stores by fiscal 2031. Autonomous formats are also emerging, including Xpand's unmanned store in Vienna. Competitive advantage will increasingly depend on disciplined expansion, reliable operations, and effective customer-data management.
Convenience Store Industry Leaders
-
7-Eleven (Seven & i Holdings)
-
Alimentation Couche-Tard (Circle K)
-
FamilyMart Co., Ltd.
-
Lawson, Inc.
-
GS25 (GS Retail Co., Ltd.)
- *Disclaimer: Major Players sorted in no particular order
Convenience Store Market Companies Covered in this Report
- 7-Eleven
- Alimentation Couche-Tard (Circle K)
- FamilyMart
- Lawson
- GS25 (GS Retail)
- Wawa
- Casey's General Stores
- Murphy USA Inc.
- QuikTrip
- Sheetz
- EG Group
- Alfamart
- FEMSA
- Coop
- Reitangruppen (Narvesen, 7-Eleven Nordics)
- SPAR International
- Reliance Smart Point
- BGF Retail Co., Ltd.
- Indomaret
- LuLu Group International
Market Opportunities and Future Outlook
Digital integration offers a practical route to increase trip frequency and attach higher-margin services. Seven & i has pursued partnership discussions involving SoftBank and PayPay to strengthen payment infrastructure and AI capabilities, reinforcing how loyalty and payments are central to personalization, fraud control, and targeted promotions in convenience retail. FamilyMart has also expanded loyalty interoperability by integrating with the Rakuten points ecosystem, illustrating how point partnerships can broaden reach without adding physical footprint.
Store-format reinvention and new revenue pillars create whitespace in dense urban markets and along mobility corridors. FamilyMart opened its FAMIMA PARK AZABUDAI flagship (under the Next FamilyMart Project) to test experiential retail and IP-based business concepts, showing operators are prototyping higher-basket missions beyond routine top-up shopping. On the mobility side, Couche-Tard has positioned eMobility, car wash, and retail media (Full Circle Media) as targeted growth areas alongside the core store platform, while large charging networks at fuel-and-convenience sites, such as Pilot Company's fast-charging footprint, show how longer dwell time can be converted into food and beverage sales when the offer is upgraded.
Recent Industry Developments in Convenience Store Market
- July 2026: FamilyMart launched the Next FamilyMart Project and opened the FAMIMA PARK AZABUDAI flagship store in Tokyo on July 10, 2026. The experiential format expansion in urban convenience stores strengthens consumer engagement and premium basket opportunities. This marks a notable push in store-level differentiation and flagship experiential assets within a crowded regional market.
- July 2026: FamilyMart - Launched the Next FamilyMart Project and opened the FAMIMA PARK AZABUDAI flagship store in Tokyo on July 10, 2026, as part of a new convenience store experience initiative. The move positions the brand at the intersection of retail innovation and immersive consumer experiences. It broadens the attraction footprint in Tokyo and signals a strategic emphasis on experiential formats.
- July 2026: GS25 (GS Retail) - Reported a 100-fold increase in cumulative K-pop album and merchandise sales compared to 2023 levels, leveraging the Our Neighborhood GS app and store network to target foreign customers and the 10s-20s demographic. The surge in cross-category merchandise drives incremental footfall and strengthens the app driven engagement model. This development highlights the value of combining digital reach with strategic in-store activations.
Convenience Store Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market is defined as the total value of sales generated by convenience store retail formats, counted at the store level across regions, and reported in USD after consistent currency handling.
Scope exclusions: Excludes pure-play online grocery and general merchandise retail that is not operated as a convenience store format.
Segments Covered in This Report
- By Type
- Staple Products
- Impulse Products
- Emergency Products
- By Ownership Structure
- Independent Stores
- Branded
- By Store Type
- Traditional Convenience Stores
- Expanded Convenience Stores
- Limited Selection Convenience Stores
- Mini Convenience Stores
- Hyper Convenience Stores
- Kiosks
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
We first built the market boundary using widely available retail and macro datasets, and then mapped how convenience formats are counted across countries. Useful public references included sources such as the World Bank, IMF, OECD retail indicators, national statistics offices that publish retail trade indices, and customs and trade portals where packaged food and beverage flows help explain assortment shifts.
After the public baseline was set, the sizing model was supported with retailer annual reports, investor presentations, and earnings call transcripts to understand revenue mix, store expansion plans, and like-for-like sales direction. We also reviewed trade association publications and reputed press for policy changes that affect fuel retailing, tobacco rules, and food-to-go readiness. Where needed, we used paid subscriptions for company financials and news intelligence, plus patent databases to sanity-check the pace of checkout, delivery, and store automation activity. This list is illustrative, and many other sources were also used for data collection, validation, and clarification during the research process.
Primary Interviews and Surveys
To close gaps that desk research cannot answer cleanly, we conducted expert interviews and surveys with store operators, distributors, and category partners, then validated the model at a regional level. Because this is a global market, we covered demand patterns in APAC, EMEA, and the Americas so differences in fuel attachment, tobacco contribution, and food-to-go penetration were reflected in the final assumptions.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 29% | CXOs: 17% | APAC: 52% |
| Mid tier: 53% | Functional/Unit leaders: 37% | EMEA: 29% |
| Smaller Players: 18% | Managers: 46% | Americas: 19% |
Market-Sizing & Forecasting
The core build uses a top-down approach, where retail trade signals and country-level convenience channel shares are used to reconstruct total value by region, followed by conversion into a single USD series. To keep the result practical, the totals were checked using selective bottom-up approximations, such as rolling up sampled operator revenues, store counts, and an ASP-per-transaction view for in-store baskets where the data was available.
Key inputs included store count expansion and closures, same-store sales trends, fuel versus in-store sales mix (where fuel is attached to the format), the share of foodservice and prepared foods, inflation and wage pressure that shift ticket size, and urbanization and commuting patterns that influence trip frequency. When a country lacked clean channel splits, we applied proxy ratios from similar markets and then re-tested them with interview feedback before locking the assumption.
For the forecast, scenario analysis was used, anchored on consensus expectations for inflation normalization, consumer trade-down behavior, and planned store network additions. Growth was then stress-tested against macro paths and against observed convenience value growth patterns discussed by market participants, which helped us avoid overreacting to one-year price spikes.
Data Validation & Update Cycle
Before sign-off, outputs are triangulated across independent signals, including reported operator performance, retail indices, and region-level direction from primary conversations. Large variances are flagged, the drivers are re-checked (for example, a sudden jump caused by currency moves or an outlier fuel year), and only then does the model move to internal review.
Reports are refreshed annually, and interim adjustments are made when material events occur, such as major tax changes, sharp currency swings, or changes in how convenience formats are classified in key countries. Right before delivery, we perform a final pass so the published numbers reflect the most recent data points and validation feedback.
Mordor Intelligence's Global Convenience Store Market Size Compared Against Other Published Estimates
Published market values for convenience stores can look far apart, even when the titles sound similar, because the underlying counting rules are not the same. The biggest differences usually come from timing of currency conversion, how fuel and tobacco are treated inside store sales, and whether the estimate represents a channel view or a narrower store-format view.
When exchange rates are taken from a single month, or when inflation is applied as a blanket uplift without checking category mix, the final USD total can shift quickly. In our work, the refresh cadence matters because store networks and price points move during the year, and the model stays tied to operator updates and retail index direction through validation checks and consistent currency timing. This is the same 2026 baseline approach used by Mordor Intelligence, which can land away from older, less frequently refreshed snapshots.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 746.71 B (2026) | |
| Trade Journal A | USD 1000.00 B (2029) | Uses a channel-level convenience retail framing and reports a later-year threshold, which can blend broader formats and relies on a headline projection rather than a country-by-country rebuild. |
| Industry Commentary B | USD 1860.00 B (2024) | Appears to use a very broad definition and a higher total sales pool, with limited clarity on fuel inclusion, currency conversion timing, and how store-format boundaries are applied across countries. |
The spread in the table is mainly explained by scope boundaries and timing choices, followed by how pricing uplift is applied across categories that behave differently. By keeping inputs traceable to store networks, sales mix, and consistent USD conversion steps, we end up with a figure that clients can re-check and update as new country data comes in.
Key Questions Answered in the Report
What is driving growth in global convenience stores?
Foodservice, staple-product purchases, EV charging, digital loyalty, and local fulfillment are supporting growth. The sector is projected to grow at a 6.02% CAGR through 2031.
Which product category leads convenience store revenue?
Staple Products led with 56.13% of revenue in 2025 and are also forecast to grow at a 7.04% CAGR through 2031.
Which store format is growing the fastest?
Hyper Convenience Stores are forecast to grow at a 9.40% CAGR through 2031 as retailers add fresh food, coffee, seating, and charging services.
Which region will grow the fastest through 2031?
Asia-Pacific is forecast to grow at a 7.18% CAGR through 2031, supported by urbanization and the spread of established Japanese and Korean store models.
Why are convenience retailers investing in EV chargers?
EV charging increases dwell time and can raise store visits and in-store spending. Consumer Reports found fast chargers increased retail-site foot traffic by 4% and revenue by 5%.
Is the sector consolidated?
No. The supplied data indicates that the top 5 companies together hold no more than 30% of global revenue, despite large international store networks.