
Market Overview
| Study Period | 2022 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
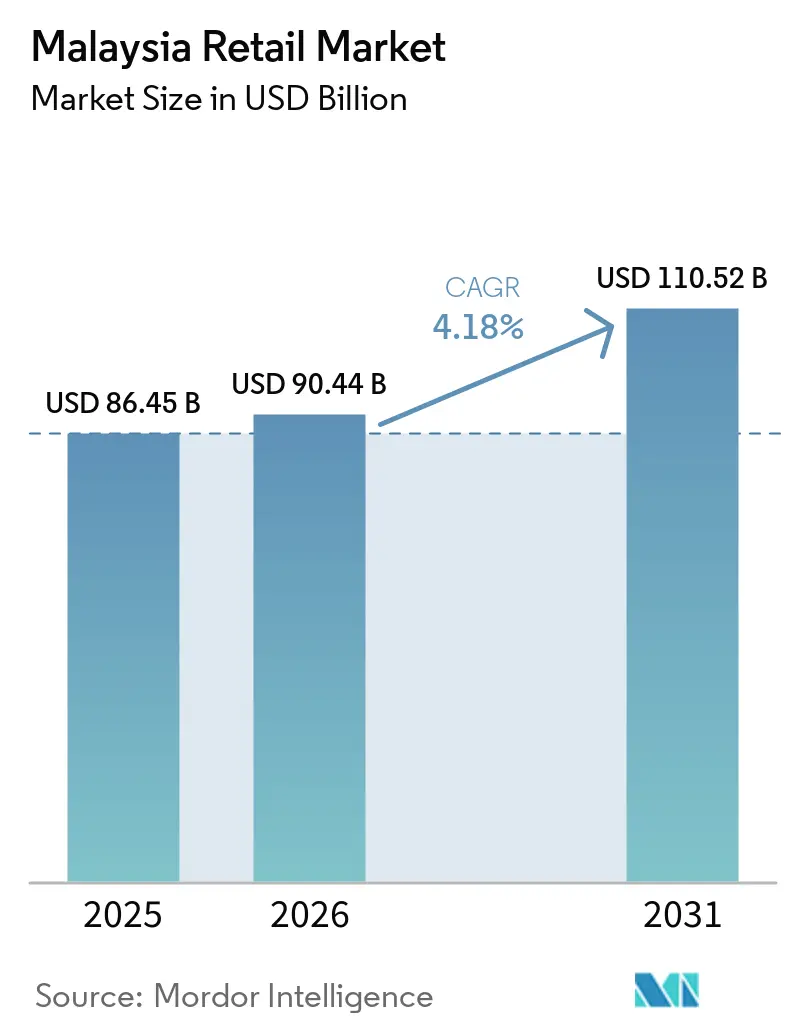
| Base Year Market Size (2025) | USD 86.45 Billion |
| Market Size (2026) | USD 90.44 Billion |
| Market Size (2031) | USD 110.52 Billion |
| Growth Rate (2026 - 2031) | 4.18 % |
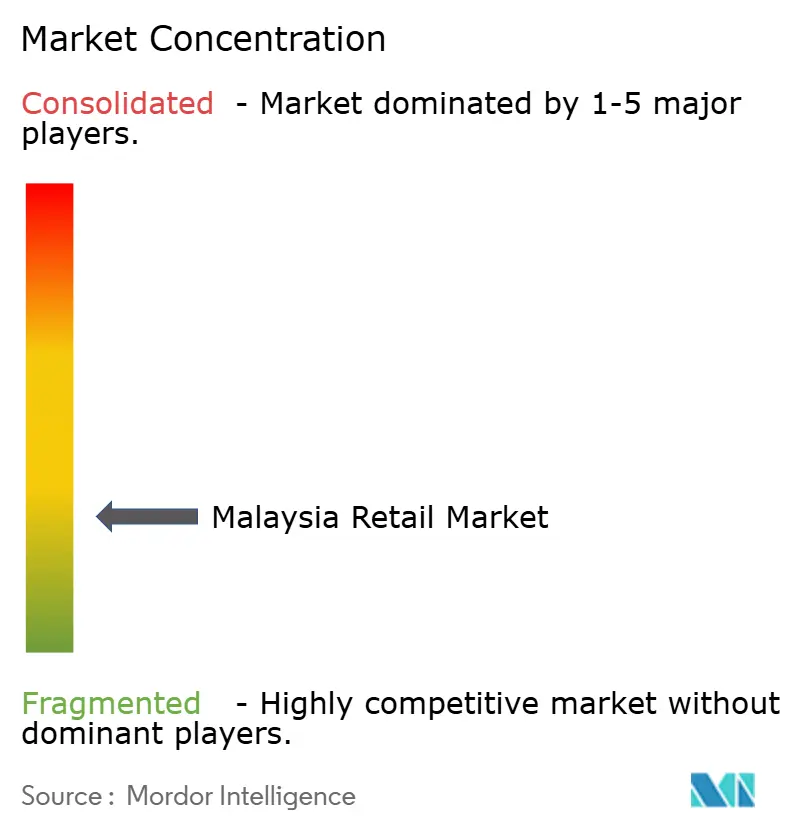
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Malaysia Retail Market Analysis by Mordor Intelligence
The Malaysian retail market size was valued at USD 86.5 billion in 2025 and is estimated to grow from USD 90.4 billion in 2026 to reach USD 110.5 billion by 2031, at a CAGR of 4.1% during the forecast period 2026-2031. Domestic demand remained an important base for the Malaysian retail market after Malaysia’s economy expanded 5.2% in 2025, supported by private consumption. Retail trade rose 6.1% in 2025, while non-specialized stores grew 7.0%, indicating continued demand for grocery, mini-market, and convenience purchases[1]. Retailers are balancing this demand against higher store costs from expanded service tax coverage, wages, electricity, and rent. Digital payments and online retail are broadening checkout options, while national chains are using distribution scale to support outlet expansion. The Malaysian retail market remains broad and fragmented overall, even though competition is more concentrated in selected formats.
Key Report Takeaways
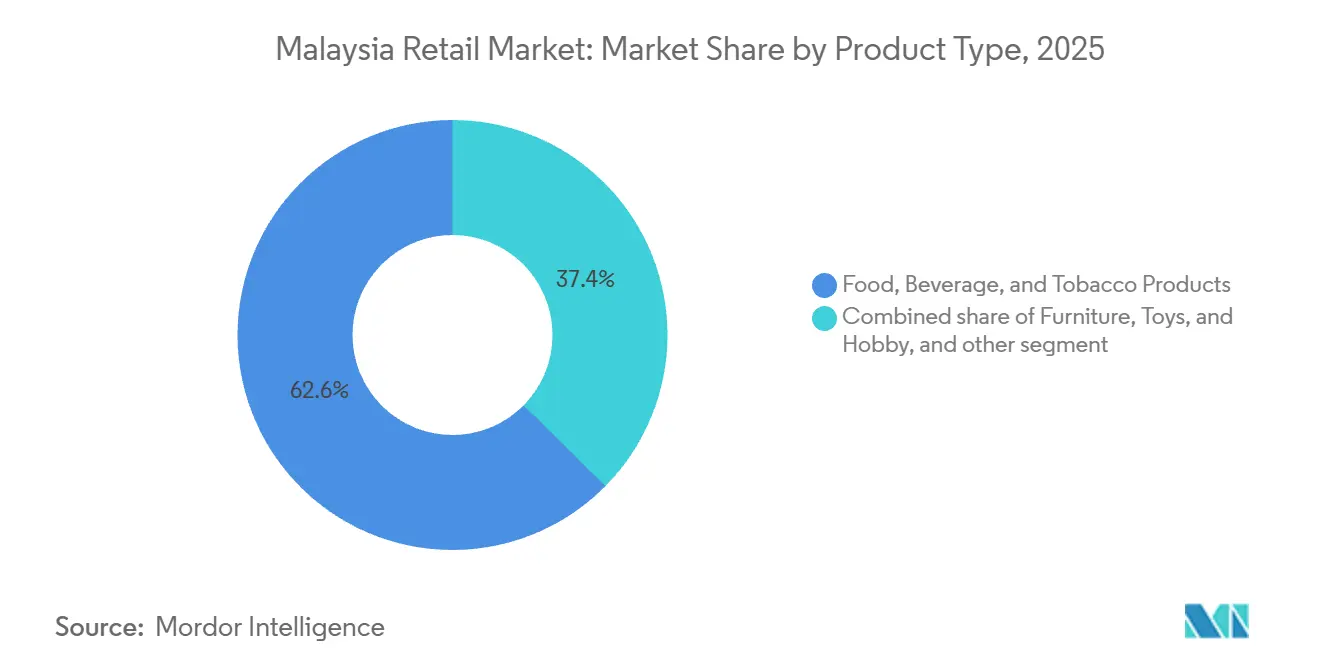
- By product type, food, beverage, and tobacco products held 62.6% of the Malaysian retail market share in 2025, while personal care and household care are forecast to expand at a 7.5% CAGR through 2031.
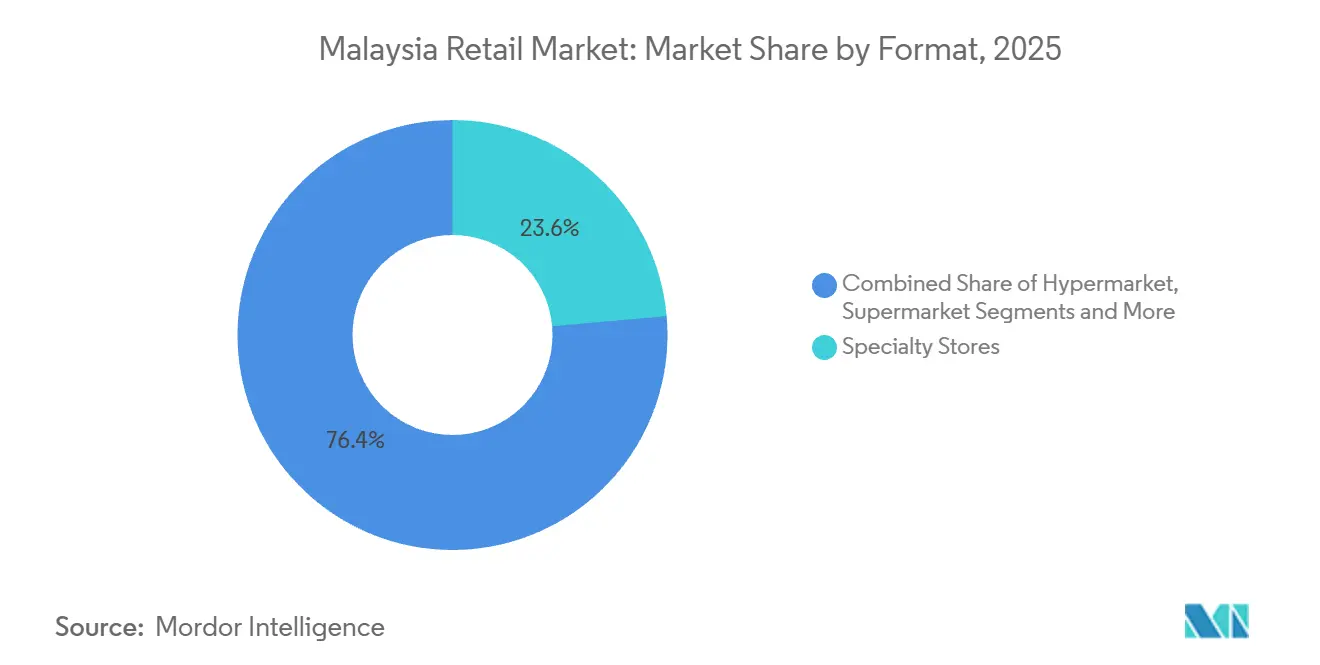
- By format, specialty stores accounted for 23.6% of the Malaysian retail market share in 2025, while e-commerce recorded the highest projected CAGR at 9.3% through 2031.
- By geography, Peninsular Malaysia held 84.1% of the Malaysian retail market share in 2025 and is forecast to grow at a 4.2% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Malaysia Retail Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| 99 Speedmart Distribution Scale and FMCG Pricing | +0.6% | National, strongest in Klang Valley, Penang, Johor, and early-stage East Malaysia | Medium term (2-4 years) |
| DuitNow QR Interoperability and Wallet Promotions | +0.5% | National, including tourist corridors and East Malaysia secondary towns | Short term (≤ 2 years) |
| Cross-Border Retail and QR Spending | +0.3% | Johor, Penang, Langkawi, coastal Sabah, and Sarawak | Medium term (2-4 years) |
| Urban Nodes Supporting Quick-Commerce Density | +0.8% | Klang Valley, Penang, and Johor Bahru | Short term (≤ 2 years) |
| Minimum-Wage and Public-Sector Pay Adjustments | +0.5% | National, especially semi-urban and suburban grocery corridors | Short term (≤ 2 years) |
| East Malaysia Network Expansion | +0.3% | Sabah and Sarawak, including Kota Kinabalu, Kuching, and Bintulu | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
99 Speedmart’s Scale-Driven Price Architecture Reshaping FMCG Retail Dynamics
99 Speedmart reported FY2025 revenue of MYR 11.4 billion (USD 2.6 billion), after 14.5% growth[2]. Its network reached 3,037 outlets by December 2025. The company has set an annual target of 250 new stores. A 63,000 sq ft Semenyih distribution center now serves 180 additional outlets. This distribution footprint allows the retailer to manage logistics as the network expands. It also strengthens its ability to negotiate bulk purchasing terms with suppliers. Large, unified orders can narrow the gap between wholesale and shelf prices across fast-moving consumer goods. That dynamic places pressure on independent supermarkets without comparable purchasing volumes. It supports frequent replenishment trips at neighborhood outlets. The Malaysian retail market, therefore, gains volume through proximity formats that serve daily household needs. The company’s planned addition of 1,000 outlets across 4 years would extend this pressure on local price competition. Smaller retailers may respond by focusing on local assortments, service, or convenience rather than direct price matching.
DuitNow QR Interoperability Broadening Retail Catchment and Digital Adoption
DuitNow QR transaction volume doubled from 1.5 billion in 2024 to 3 billion in 2025[3]. Nearly 3 million merchant touchpoints were registered nationwide in 2025. Retail e-payment value reached MYR 831 billion (USD 185.9 billion) in 2025. PayNet processed 8.44 billion digital payment transactions during the year. Cross-border QR payments reached 29.7 million transactions after growing 2.5 times. These measures show wider acceptance of digital payment tools among merchants and consumers. The zero merchant discount rate has reduced the direct acceptance cost for participating merchants. This is important for smaller retailers with limited room to absorb payment expenses. Wider QR acceptance can lower cash handling needs at checkout. The Malaysian retail market can therefore bring more small merchants into traceable digital transactions.
Klang Valley, Johor, and Penang Urban Nodes as Quick-Commerce Density Anchors
Klang Valley, Johor Bahru, and Greater Penang have the density and logistics capacity needed for quick-commerce operations. These locations combine large residential catchments with developed road networks. They also have concentrated delivery capacity and high digital payment usage. GrabMart offers grocery delivery services in Malaysia through its digital platform[4]. This operating model depends on sufficient order density within each service area. The 9.3% E-Commerce CAGR in the Malaysian retail market is therefore likely to be supported most strongly by these urban nodes. Grab Malaysia expanded its FAMA partnership in September 2025. The initiative added 18 Pasar Tani Kekal Putrajaya vendors to GrabMart. The move brought fresh produce sellers into a digital ordering channel. It also connected semi-formal retail activity with a larger online customer base. Johor Bahru adds a separate cross-border demand dimension because of its proximity to Singapore.
Minimum-Wage Uplift Expanding Essential Retail Basket Size and Frequency
Malaysia’s minimum wage increased from USD 370 to USD 419 per month in 2025. The revised wage applies from February 2025 for employers with 5 or more employees. Full implementation for all employers began in August 2025. This change increased labor costs for retail operators. It also increased income available to workers who rely on neighborhood stores for everyday purchases. The effect is most relevant for essential goods, which represent a large part of household retail spending. ses. Public assistance distribution through participating proximity retailers can reinforce this role. The Malaysian retail market benefits when these outlets remain accessible in suburban and semi-urban communities. However, wage gains and wage costs operate at the same time, so retailer outcomes depend on productivity and procurement efficiency.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Sales and Service Tax, Wage, Electricity, and Rent Costs | -0.9% | National, with high exposure in high-rent urban centers | Short term (≤ 2 years) |
| Marketplace Commission, Subsidy, and Customer-Acquisition Costs | -0.6% | National, concentrated among the Klang Valley and Penang online sellers | Medium term (2-4 years) |
| East Malaysia Last-Mile Premium and Basket-Price Disparity | -0.3% | Sabah and Sarawak, especially the interior and rural areas | Long term (≥ 4 years) |
| E-Invoicing, Data-Compliance, and Digital-Capability Burdens | -0.4% | National, particularly small retailers outside major urban centers | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
SST, Wage, Electricity, and Rent Compressing Physical Retailer Margins
Malaysia expanded the service tax scope from July 2025. The change applied an 8% service tax to rental and leasing services for operators above the USD 0.24 million annual turnover threshold. The threshold was intended to protect smaller businesses. Larger format retailers and mall operators remain more exposed to the change. Retailers with leased sites must absorb this cost alongside wage, utility, and rent pressures. These combined expenses can reduce room for price reductions or store investment. Mall-based retailers also face cost transmission through leasing structures. The Malaysian retail market may see greater pressure on mid-scale operators with limited procurement leverage. Private-label development and scale purchasing remain important responses to this margin environment.
Marketplace Commission and Customer-Acquisition-Cost Escalation Narrowing E-Commerce Profitability
Online retail growth can raise seller costs as platforms compete for customer traffic. Sellers may need to fund discounts, advertising, and promotional participation across multiple platforms. The revised Shopee fee structure from May 2026 included an 8% service tax on transaction service fees. This raises the direct cost of sales for affected sellers. Smaller merchants with undifferentiated assortments have less capacity to offset these charges. As online sales pools expand, platforms can capture more fee revenue from sellers. Larger retailers with owned logistics and private-label products can spread these costs across higher order volume. Independent sellers may face declining returns even when their gross sales increase. The need to maintain reach across several online channels can further raise customer-acquisition expenses.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Essential Goods Anchor the Base, Personal Care Products Set the Pace
Food, beverage, and tobacco products held 62.6% of the Malaysian retail market share in 2025. This category is supported by frequent daily purchases and relatively low substitution for basic food items. Mini-markets and supermarkets serve a large share of these replenishment needs. The continued addition of neighborhood outlets brings more fast-moving consumer goods into measured modern retail. Income support and wage changes also direct household spending toward essential baskets. This category, therefore, provides a stable base for the Malaysian retail market.
Personal care and household care are forecast to grow at a 7.5% CAGR through 2031. The Malaysian retail market size for this category is supported by premium skincare, male grooming, and higher household hygiene spending. Watsons and Guardian are positioned through store networks and loyalty program data. Apparel, Footwear, and Accessories remains sensitive to discretionary spending patterns. Furniture, Toys, and Hobby retail benefit from younger urban households but face online substitution in lower-priced products. Industrial and Automotive retail follows commercial vehicle and manufacturing service cycles more closely than consumer-facing categories.

By Format: Specialty Stores Command the Largest Share, E-Commerce Drives Fastest Expansion
Specialty stores held 23.6% of the Malaysian retail market share in 2025. The format includes home improvement, health and beauty, fashion, and other focused retail concepts. MR DIY reported FY2025 revenue of MYR 5.0 billion (USD 1.1 billion), after 6.5% year-on-year growth. Its store network reached 1,556 locations at the end of December 2025. These results show how scale purchasing and a broad everyday assortment can support specialty retail economics.
E-Commerce is forecast to expand at a 9.3% CAGR from 2026 to 2031. Digital ordering is extending beyond discretionary goods into grocery, household, and personal care purchases. Convenience Stores remain a high-frequency channel through 99 Speedmart and 7-Eleven Malaysia. Supermarkets and Hypermarkets face pressure as quick-commerce services compete for top-up shopping trips. Department Stores are responding to online competition through mall renewal and tenant-mix improvement. Drugstores, cash-and-carry stores, and wholesalers retain separate roles in pharmacy convenience and bulk purchasing.
Geography Analysis
Peninsular Malaysia held 84.1% of the Malaysian retail market share in 2025. Klang Valley, Johor Bahru, and Greater Penang concentrate modern trade and online fulfillment. These corridors have dense consumer catchments and developed last-mile networks. They also have high adoption of mobile banking and QR payments. This supports omnichannel retail operations across grocery, specialty, and discretionary categories. The region’s logistics depth allows retailers to test quick-commerce formats more easily.
Johor Bahru is an important cross-border retail location because of its proximity to Singapore. Participating retailers can use QR interoperability to accept payments from inbound visitors. Cross-border QR payments reached 29.7 million transactions in 2025. This payment connection can support retail spending in tourist and border zones. Penang also benefits from a large urban customer base and an established commercial infrastructure. The Malaysian retail market gains from these corridors because they combine physical shopping with digital ordering capacity.
East Malaysia covers Sabah and Sarawak and faces a different operating structure. Long delivery routes raise landed costs for goods supplied from the peninsula. National retailers must consider basket-price differences when expanding into interior locations. The broader network remains less dense than in Peninsular Malaysia. Distribution investment and better freight infrastructure can improve outlet economics over time. The Malaysian retail market can expand into these catchments when the cost of serving them becomes more manageable.
Competitive Landscape
The Malaysian retail market has a fragmented structure. This structure reflects the presence of independent stores, traditional retailers, modern trade, specialty chains, and online platforms. Competition is therefore dispersed when measured across the full scope. It becomes much tighter within specific formats. Mini-market and proximity retail show the clearest example of concentrated format competition.
99 Speedmart uses outlet density and distribution investment to improve procurement efficiency. Its FY2025 results showed revenue of MYR 11.4 billion (USD 2.6 billion) and 3,037 outlets. The Semenyih distribution center provides capacity for 180 additional outlets. MR DIY uses a value-focused assortment across more than 18,000 SKUs. It reported a 47.5% gross margin and 197.8 million transactions in FY2025. AEON has focused on private-brand expansion and mall asset optimization as it manages margin pressure.
Online platforms are competing for consumer traffic and seller activity. Physical chains are responding by strengthening their store networks, loyalty capabilities, and private-label offerings. Rural and secondary-town markets remain harder to serve with consistent availability and pricing. This is especially relevant in East Malaysia and East Coast Peninsular states. Hub-and-spoke distribution, franchise operations, and shared dark-store infrastructure are possible ways to address these catchments. The Malaysian retail market will remain diverse because no single business model can serve all locations and shopping missions.
Malaysia Retail Industry Leaders
-
Shopee Malaysia
-
99 Speedmart
-
MR D.I.Y. Group
-
Lotus's Malaysia
-
AEON Co. (M) Bhd
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- July 2026: 99 Speedmart commissioned a new 63,000 sq ft distribution center in Semenyih, with capacity to serve 180 additional outlets, reinforcing the procurement and logistics scale that underpins its shelf-price competitiveness across a planned 4,000-outlet network by 2028.
- April 2026: AEON Co. (M) Bhd and KIP REIT signed a memorandum of understanding to expand AEON Mall Kinta City in Ipoh, adding new retail lots, improved common areas, and upgraded facilities. The expansion project targets completion by 2027 and is expected to increase net lettable area materially.
- February 2026: MR DIY Group reported full-year FY2025 revenue of MYR 4.95 billion (USD 1.11 billion), and a record dividend of MYR 758 million (USD 185.5 million) with approximately 155 new store openings targeted in FY2026, sustaining the specialty retail chain’s national footprint expansion.
- November 2025: 99 Speedmart reached its 3,000-outlet milestone, opening its first Kelantan outlet in Gua Musang, establishing a presence in every Malaysian state for the first time. The network closed in December 2025 with 3,037 stores.
Malaysia Retail Market Report Scope
The retail market encompasses the sale of goods and services directly to end consumers through physical stores, online platforms, and other sales channels.The report on the Malaysian retail sector provides a comprehensive evaluation of the market, with an analysis of the segments in the market. Moreover, the report also provides the competitive profile of the key manufacturers, along with regional analysis.
Tobacco Products; Personal Care and Household Care; Apparel, Footwear, and Accessories; Furniture, Toys, and Hobby; Industrial and Automotive; Electronic and Household Appliances; Other Products), Retail Channel (Traditional Mom and Pop Retail; Modern Trade Retail; E-Commerce and Others), and Format (Hypermarkets; Supermarkets; Convenience Stores; Department Stores; Specialty Stores; Others including Drugstore, Cash & Carry, Wholesaler).
By Product Type
| Food, Beverage, and Tobacco Products |
| Personal Care and Household Care |
| Apparel, Footwear, and Accessories |
| Furniture, Toys, and Hobby |
| Industrial and Automotive |
| Electronic and Household Appliances |
| Other Products |
By Format
| Hypermarkets |
| Supermarkets |
| Convenience Stores |
| Department Stores |
| Specialty Stores |
| E-Commerce |
| Others (Drugstore, Cash & Carry, Wholesaler) |
By Geography
| Peninsular Malaysia |
| East Malaysia |
| By Product Type | Food, Beverage, and Tobacco Products |
| Personal Care and Household Care | |
| Apparel, Footwear, and Accessories | |
| Furniture, Toys, and Hobby | |
| Industrial and Automotive | |
| Electronic and Household Appliances | |
| Other Products | |
| By Format | Hypermarkets |
| Supermarkets | |
| Convenience Stores | |
| Department Stores | |
| Specialty Stores | |
| E-Commerce | |
| Others (Drugstore, Cash & Carry, Wholesaler) | |
| By Geography | Peninsular Malaysia |
| East Malaysia |
Key Questions Answered in the Report
What is the forecast growth rate for Malaysia retail through 2031?
The Malaysian retail market is forecast to grow at a 4.1% CAGR from 2026 to 2031, reaching USD 110.5 billion.
Which product category has the largest retail share in Malaysia?
Food, Beverage, and Tobacco Products held 62.6% of the value in 2025, supported by frequent essential purchases.
Which retail format is growing fastest in Malaysia?
E-Commerce is projected to grow at a 9.3% CAGR through 2031, the fastest rate among the reported formats.
What is driving digital checkout adoption among Malaysian retailers?
DuitNow QR reached 3 billion transactions and nearly 3 million merchant touchpoints in 2025.
Why is Peninsular Malaysia important for retailers?
Peninsular Malaysia held 84.1% of the value in 2025 and combines major consumer centers with strong logistics and payment infrastructure.
What cost pressures are affecting physical retailers?
The expanded service tax on qualifying rental and leasing services, wage costs, utilities, and rent is reducing margin flexibility.