
Market Overview
| Study Period | 2021 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.85 Billion |
| Market Size (2026) | USD 3 Billion |
| Market Size (2031) | USD 3.85 Billion |
| Growth Rate (2026 - 2031) | 5.12 % |
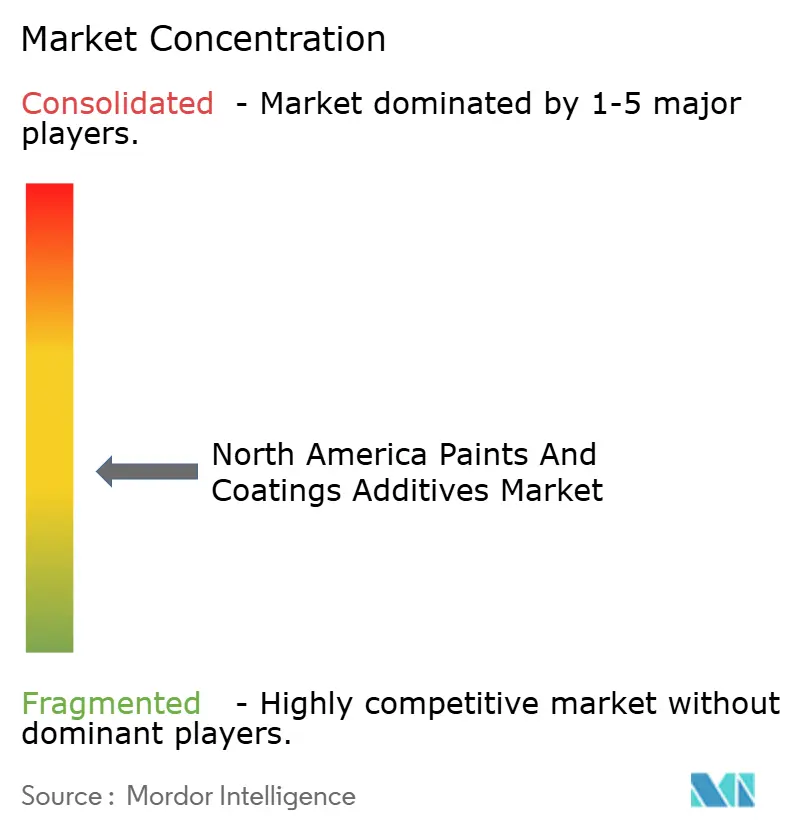
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
North America Paints and Coatings Additives Market Analysis by Mordor Intelligence
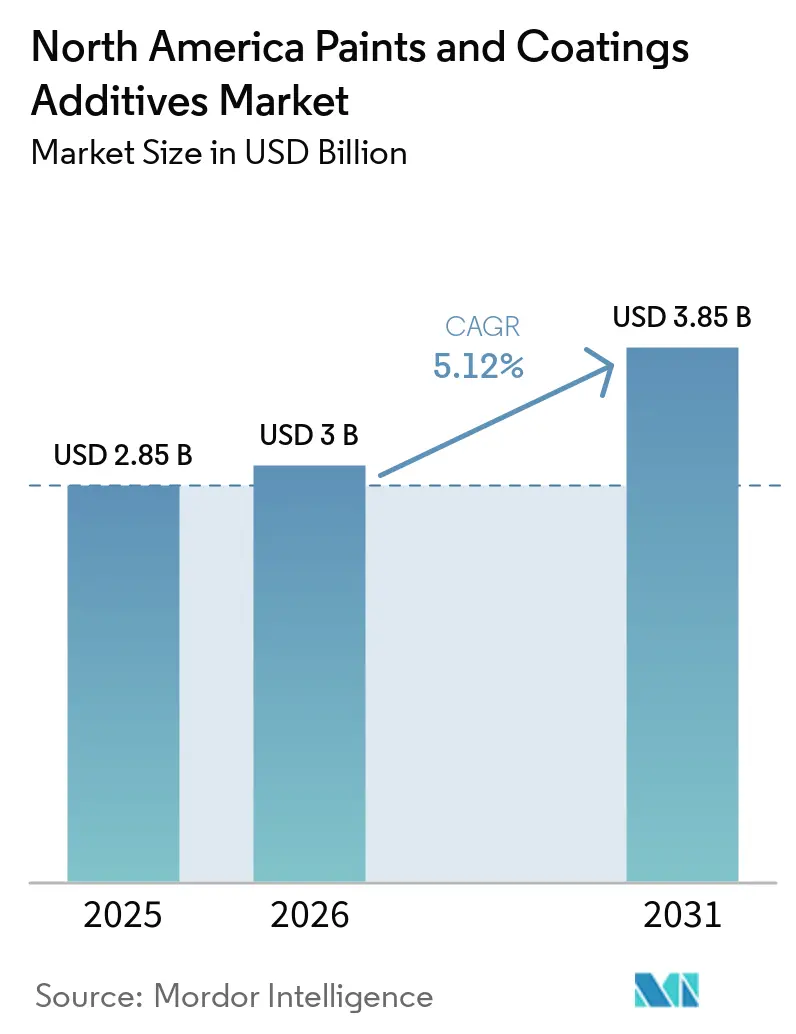
The North America Paints And Coatings Additives Market size was valued at USD 2.85 billion in 2025 and is estimated to grow from USD 3.00 billion in 2026 to reach USD 3.85 billion by 2031, at a CAGR of 5.12% during the forecast period (2026-2031). The North America paints and coatings additives market is being shaped by tighter volatile organic compound (VOC) requirements in the United States and Canada, which increases the need for formulation support in decorative and industrial paints. Waterborne systems use dispersants, defoamers, and rheology modifiers to maintain stability and application performance, so their wider use raises additive demand even where paint volumes are stable. Construction, automotive, and industrial maintenance demand give the North America paints and coatings additives market a broad customer base rather than reliance on a single end use. Suppliers are responding with multifunctional and lower-carbon materials, while their customers face more testing, documentation, and qualification work. Production investments and new product launches indicate that suppliers see the region as an important base for technology development and manufacturing.
Key Report Takeaways
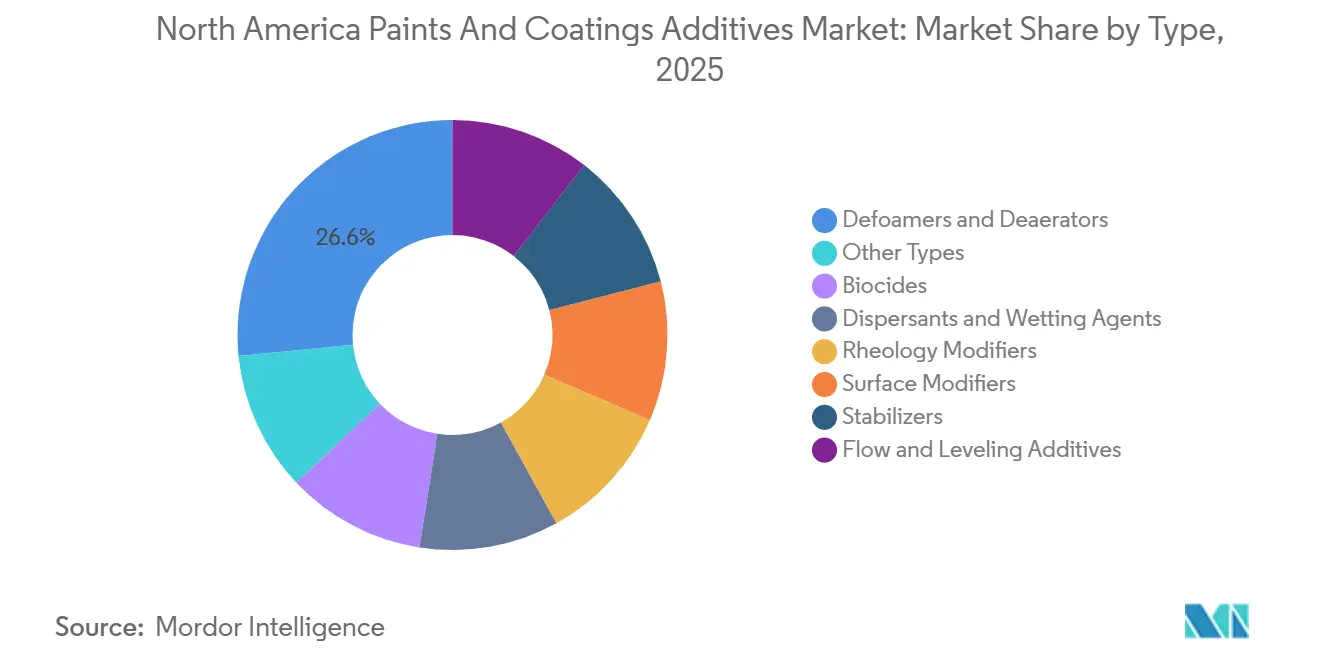
- By type, defoamers and deaerators held 26.56% of the North America paints and coatings additives market in 2025 and are projected to advance at a 5.84% CAGR through 2031.
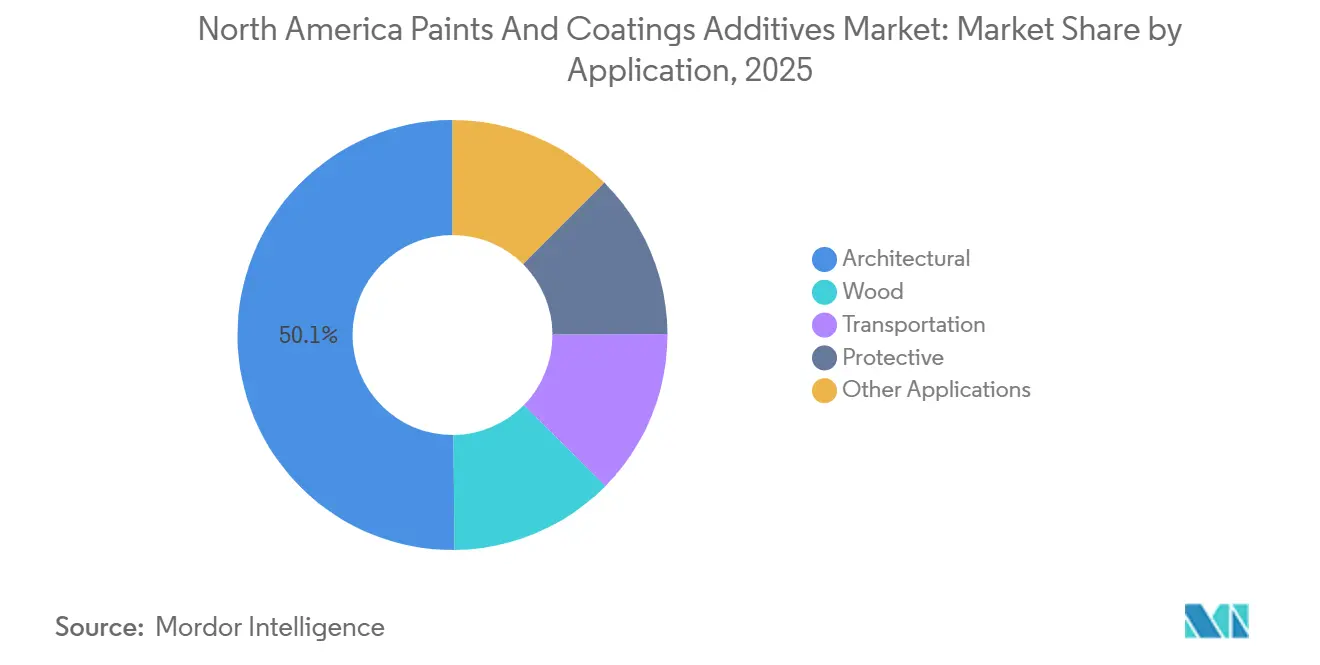
- By application, architectural held 50.14% of the North America paints and coatings additives market share in 2025, while protective is projected to advance at a 6.26% CAGR through 2031.
- By geography, the United States held 76.67% of the North America paints and coatings additives market share in 2025 and is projected to advance at a 6.02% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of North America Paints and Coatings Additives Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shift Toward Waterborne and Low-VOC Coatings | +1.7% | Global, with concentrated enforcement in US and Canada | Short term (≤ 2 years) |
| Infrastructure Renewal and Non-Residential Construction | +1.3% | North America, strongest in US Sun Belt and Midwest corridors | Medium term (2–4 years) |
| Growth in Automotive and Electric Vehicle Coatings | +1.0% | US and Canada; spillover to Mexico's OEM base | Medium term (2–4 years) |
| Demand for High-Performance and Multifunctional Additives | +0.8% | Global, with North America leading commercial adoption | Medium term (2–4 years) |
| Qualification of Bio-Based and PFAS-Free Additives in Formulations | +0.5% | Global; early adoption concentrated in US and Canada | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Shift Toward Waterborne and Low-VOC Coatings
The January 2025 update to National Volatile Organic Compound Emission Standards under 40 Code of Federal Regulations (CFR) Part 59 introduced product-weighted reactivity limits for relevant consumer and commercial products[1]. The change moved attention beyond VOC content by weight and increased the value of coalescents and defoamers that can support lower ozone-formation potential. Waterborne systems need dispersants and stabilizers because water does not dissolve resin systems in the same way as solvents. That requirement increases additive use per unit of finished paint as manufacturers move toward waterborne formulations. Professional contractors also favor low-odor, alkylphenol ethoxylate-free, and near-zero-VOC products, which adds to formulation requirements. In Canada, VOC Concentration Limits for Certain Products Regulations point in the same direction and reinforce a regional compliance focus for the North America paints and coatings additives market.
Infrastructure Renewal and Non-Residential Construction
Federal bridge data showed that many U.S. bridges still required attention, supporting demand for maintenance and recoating programs[2]. Protective systems used on bridges, highways, and water assets require performance specifications and warranty periods of 10-15 years. Those requirements increase the role of rheology modifiers, anti-settling agents, and corrosion inhibitors in coating packages. The North America paints and coatings additives market, therefore, benefits from public capital programs that follow appropriation schedules rather than household spending patterns. Premium additive packages are relevant where protective coatings must retain application consistency, corrosion resistance, and film quality over the required service period. This work offers suppliers demand visibility across several years where coating projects progress through planning, procurement, and maintenance cycles.
Growth in Automotive and Electric Vehicle Coatings
Electric vehicles require coating coverage on battery enclosures, structural underbody components, and electric axle assemblies. This creates demand for e-coat and related performance materials that are not captured by vehicle production totals alone. New paint shops associated with Ford BlueOval City, General Motors Ultium platform factories, and Tesla expansion are adopting waterborne lines with tighter performance requirements than older facilities. Domestic manufacturing incentives under the Inflation Reduction Act supported investment in new assembly capacity across the Southeast and Midwest. These sites require coating systems that meet performance and environmental requirements during vehicle finishing. Mexico's expanding original equipment manufacturer (OEM) assembly role also supports the North America paints and coatings additives market through integrated Tier-1 supply chains.
Demand for High-Performance and Multifunctional Additives
Formulators are consolidating additive bills of materials by using chemistries that address wetting, foam control, and rheological stability at the same time. This reduces the number of components in a formulation while raising the importance of each retained material. Evonik Industries AG introduced Ancamine 2875 in April 2026, a modified polyamine curing agent that combines fast curing with a moisture vapor barrier below 0.1 perms at 12-mil film thickness and contains no alkylphenol accelerators. BASF's per- and Polyfluoroalkyl Substances (PFAS)-free Efka FL 3287 and Efka FL 3782 address leveling and wetting without adding slip, reducing the need for separate surfactant and leveling ingredients. The North America paints, coatings, and additives market is also seeing interest in bio-sourced multifunctional materials because verified bio-based content can support access to federal procurement programs. USDA BioPreferred certification can support that route for suppliers able to demonstrate qualifying biosourcing.
Restraints Impact Analysis of North America Paints and Coatings Additives Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Raw Material Price Volatility | -0.9% | Global, with acute effects on US Gulf Coast additive production clusters | Short term (≤ 2 years) |
| Regulatory Testing and Product Registration Costs | -0.7% | North America and EU; early adoption costs concentrated in US | Medium term (2–4 years) |
| Long Formulation Qualification Cycles | -0.5% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Raw Material Price Volatility
Most synthetic coating additives use petrochemical-derived intermediates, leaving producers exposed to changes in raw-material availability and cost. U.S. tariff changes on some specialty chemical imports add supply-chain pressure to underlying input inflation. Titanium dioxide remains a key cost reference for pigment-related formulations, and tight ilmenite supply and higher sulfuric acid costs have affected the coatings value chain. Producers can face a 3–6-month delay before customers accept price increases, so the margin effect occurs before commercial recovery. The Toxic Substances Control Act (TSCA) premanufacture notification process can add time when producers seek to substitute raw materials in a new specialty chemical. The North America paints and coatings additives market is most exposed, where manufacturers lack the scale or approved alternatives needed to shift supply quickly.
Regulatory Testing and Product Registration Costs
The cost of qualifying new additive systems has increased as PFAS-free and bio-based claims require more analytical evidence than standard registration files. The Food and Drug Administration guidance describes full-spectrum PFAS screening for food-contact coatings, which increases the documentation needed from additive suppliers and their raw-material providers. Suppliers must provide traceability information before coating producers can make compliant claims for food-contact applications. Mexico's proposed NOM-123 and NOM-003 requirements for VOC content and product labeling have remained under approval for an extended period, allowing uncertified imports to compete with compliant products. Separate documentation is also needed for International Sustainability and Carbon Certification PLUS (ISCC PLUS), biomass-balanced claims, FDA food-contact compliance, and California VOC requirements. The resulting qualification cycles delay adoption and increase the cost of bringing new additive products into the North America paints and coatings additives market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
North America Paints and Coatings Additives Market Segment Analysis
By Type:
Defoamers and Deaerators Anchor Both Revenue and GrowthDefoamers and deaerators held 26.56% of the demand in 2025. Their role is hard to replace in architectural and industrial waterborne coatings because foam control affects mixing, application, and film quality. Aqueous media generate more foam during high-shear processing and application than solvent-borne systems. Each additional unit of waterborne paint, therefore, needs a reliable foam-control approach. Evonik Industries AG's TEGO Foamex 8051 siloxane-based defoamer concentrate received the Ringier Coating Industry Innovation Award in 2026 for its use in sustainable waterborne coatings.
Dispersants and wetting agents remain important as low-VOC coatings use higher pigment loading and need stable dispersion. Lubrizol introduced Solsperse 82510 and Solsperse 84510 in July 2026 for titanium dioxide and inorganic pigment systems. Biocides support in-can and dry-film preservation in architectural coatings, particularly in humid areas. Rheology modifiers, stabilizers, surface modifiers, and flow and leveling additives address viscosity, stability, and appearance requirements as formulations change. PFAS-free flow and leveling options are receiving attention where formulators replace fluorosurfactant-based systems.

By Application:
Architectural Anchors Revenue While Protective Gains Strategic GroundArchitectural accounted for 50.14% of the North America paints and coatings additives market share in 2025. Recurring repaint activity from the U.S. housing stock supported this position even when housing starts moderated. U.S. home-improvement and repair spending was expected to reach USD 509 billion in 2025. Nouryon introduced Alcosperse OTA 100 in April 2026 to reduce or replace glycol in water-based architectural paints, lowering VOC content while retaining compatibility with existing formulations. The product responds to contractor demand for low-odor, lower-emission interior paints.
The protective segment is projected to advance at a 6.26% CAGR through 2031. Infrastructure programs support protective systems that require anti-settling agents, rheology modifiers, and corrosion inhibitors. Wood coatings continue to use flow and leveling materials and surface modifiers for flooring, furniture, and cabinetry applications. Transportation coatings benefit from electric vehicle-related reformulation activity and higher performance requirements. Elementis PLC introduced its Colour Viscosity Stability portfolio in July 2026 to address post-tint viscosity loss in waterborne architectural systems.
Geography Analysis
Sun Belt and Midwest Paints and Coatings Additives Market
The United States held 76.67% of the market demand in 2025 and is projected to advance at a 6.02% CAGR through 2031. Its scale reflects the concentration of coating production, construction activity, automotive manufacturing, and industrial maintenance demand. The Sun Belt and Midwest concentrate housing activity, vehicle plants, and infrastructure corridors, while Gulf Coast chemical clusters provide access to inputs. BASF launched renewable-electricity-based acrylates at Freeport, Texas, in March 2026 with Avery Dennison. Lubrizol also announced a USD 209 million investment in its Ohio headquarters in January 2026, expanding innovation capability for dispersants and performance coatings.
Ontario, British Columbia and Quebec Paints and Coatings Additives Market
Canada has a high-compliance share of regional demand because provincial VOC rules can be stricter than federal requirements. Ontario Regulation 419/05 is one example of provincial air-pollution rules that shape product and plant compliance. Coastal British Columbia and the salt-belt provinces of Ontario and Quebec need protective coatings that withstand corrosion, freeze-thaw cycles, and road salt. These conditions increase the value placed on reliable corrosion protection and coating durability. Ontario vehicle assembly expansion also requires waterborne finishing systems, adding demand for associated additives across the North America paints and coatings additives market.
Mexico Paints and Coatings Additives Market
Mexico remains a developing but strategically important part of the regional supply chain. ANAFAPYT reported that its 191-member network generated annual paint-sector sales of MXN 106.232 billion (approximately USD 6.07 billion) and that the sector represented 15% of Mexico's chemical-industry gross domestic product. Mexico's role as a cost-competitive assembly location supports demand for adhesion promoters, flow agents, and anti-corrosion packages. Delays in NOM-123 and NOM-003 have allowed non-compliant imports to compete without the same quality requirements, limiting demand for premium grades.
Competitive Landscape
The North America paints and coatings additives market is moderately concentrated, with the top five players including BASF, Dow, Evonik Industries AG, Arkema, and Elementis PLC. These suppliers combine broad chemistry portfolios, proprietary molecular designs, and technical service near major paint manufacturers and OEM sites. Elementis PLC, Nouryon, Ashland, and Eastman Chemical Company compete through application knowledge in waterborne architectural and wood coatings. Their position is strongest where performance differences have commercial value and price competition is less decisive. Momentive retains a position in silicone-based defoamers and flow agents, while Solvay serves fluoropolymer-adjacent categories facing substitution pressure as PFAS review expands.
BYK, part of ALTANA AG, introduced DISPERBYK-2180 in July 2026 for inorganic pigments in aqueous systems across a wide pH range. The launch addressed a formulation need in architectural, wood, industrial, and automotive OEM coatings. BASF expanded its REDcert²-certified biomass-balanced additives portfolio for architectural coatings in July 2026. The portfolio includes dispersants, rheology modifiers, and wetting agents, linking performance requirements to supply-chain sustainability documentation. These moves show that the North America paints and coatings additives market is competing on validated product performance and traceable materials, not solely on production volume.
BASF also debuted Efka PX 4720 at the American Coatings Show 2026 for ultra-matte, solvent-free ultraviolet (UV) coatings. The dispersing agent uses Controlled Free Radical Polymerization (CFRP) technology to support viscosity reduction and matting efficiency at high silica concentrations. CLARIANT competes with food-contact-approved Licocare RBW bio-based wax additives and a PFAS-free portfolio. This pattern favors companies able to support customers with materials, test data, compliance files, and formulation assistance.
North America Paints and Coatings Additives Industry Leaders
-
BASF
-
Dow
-
Evonik Industries AG
-
Arkema
-
Elementis PLC
- *Disclaimer: Major Players sorted in no particular order
North America Paints and Coatings Additives Market Companies Covered in this Report
- Allnex GMBH
- ALTANA AG
- Arkema
- Ashland
- BASF
- Cabot Corporation
- CLARIANT
- Dow
- Eastman Chemical Company
- Elementis PLC
- Evonik Industries AG
- Lubrizol
- Momentive
- Nouryon
- Solvay
Read Analysis of North America Paints and Coatings Additives Companies
Recent Industry Developments in North America Paints and Coatings Additives Market
- July 2026: ALTANA AG, through BYK, introduced DISPERBYK-2180, a polycarboxylate-ether wetting and dispersing additive for inorganic pigments in aqueous systems, designed for high-pH stability. The launch supports the North America paints and coatings additives market by expanding additive solutions for architectural, wood, industrial, and automotive OEM coating formulations.
- May 2026: Evonik Industries AG expanded its North American distribution network for coating additives, appointing new U.S. partners and Andicor Specialty Chemicals as its exclusive distributor in Canada from May 1, 2026. The expanded distribution structure strengthens regional access to coating and ink additives and supports supply availability for paint and coatings formulators across the United States and Canada.
North America Paints and Coatings Additives Market Report Scope
Paints and coatings additives are specialized substances added to coating formulations to improve application properties, stability, appearance, and overall performance. They help optimize characteristics such as flow, dispersion, surface quality, and resistance to environmental conditions.
The North America Paints and Coatings Additives Market is segmented by type, application, and geography. By type, the market is segmented into defoamers and deaerators, biocides, dispersants and wetting agents, rheology modifiers, surface modifiers, stabilizers, flow and leveling additives, and other types. By application, the market is segmented into architectural, wood, transportation, protective, and other applications. The report also covers the market size and forecasts for paints and coatings additives in 3 countries across the region. For each segment, the market sizing and forecasts have been done on the basis of value (USD).
Segmentation Overview
By Type
| Defoamers and Deaerators |
| Biocides |
| Dispersants and Wetting Agents |
| Rheology Modifiers |
| Surface Modifiers |
| Stabilizers |
| Flow and Leveling Additives |
| Other Types |
By Application
| Architectural |
| Wood |
| Transportation |
| Protective |
| Other Applications |
By Geography
| United States |
| Canada |
| Mexico |
| By Type | Defoamers and Deaerators |
| Biocides | |
| Dispersants and Wetting Agents | |
| Rheology Modifiers | |
| Surface Modifiers | |
| Stabilizers | |
| Flow and Leveling Additives | |
| Other Types | |
| By Application | Architectural |
| Wood | |
| Transportation | |
| Protective | |
| Other Applications | |
| By Geography | United States |
| Canada | |
| Mexico |
Key Questions Answered in the Report
What is the size of the North America paints and coatings additives market?
The North America paints and coatings additives market stands at USD 3.00 billion in 2026 and is projected to reach USD 3.85 billion by 2031.
What is driving demand for paints and coatings additives in North America?
Waterborne and low-VOC coatings, infrastructure maintenance, automotive finishing, and multifunctional formulations support demand.
Which type held the largest share in 2025?
Defoamers and deaerators held 26.56% of the market share in 2025 because foam control is required in many waterborne coating systems.
Which application is projected to grow fastest through 2031?
Protective is projected to advance at a 6.26% CAGR through 2031, supported by infrastructure maintenance and long-warranty coating systems.