
Mexico Online Gambling Market Size and Share
Mexico Online Gambling Market Analysis by Mordor Intelligence
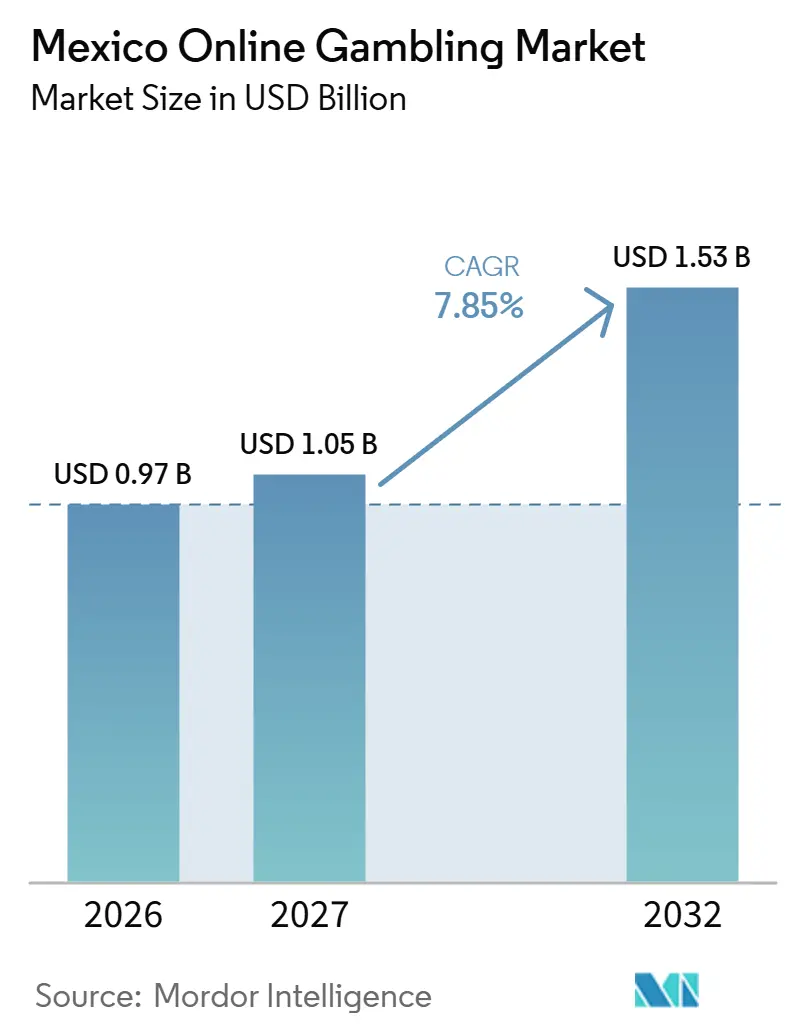
The Mexico online gambling market size is projected to expand from USD 0.97 billion in 2026 and USD 1.05 billion in 2027 to USD 1.53 billion by 2032, registering a CAGR of 7.85% between 2027 and 2032.
The 2026 FIFA World Cup in Mexico, Canada and the United States began in June 2026 and gave online operators a soccer-led setting for customer acquisition. Broader connectivity and mobile product development give operators ways to convert interest into ongoing sportsbook and casino activity. Mexico's Special Tax on Production and Services (IEPS) increase for games with bets and draws, effective January 2026, adds a fiscal burden as operators scale. Local operating relationships and content partnerships therefore shape how competitors secure customer reach through permitted local channels. Growth depends on repeat wagering activity and returns that can absorb the higher tax load.
Key Report Takeaways
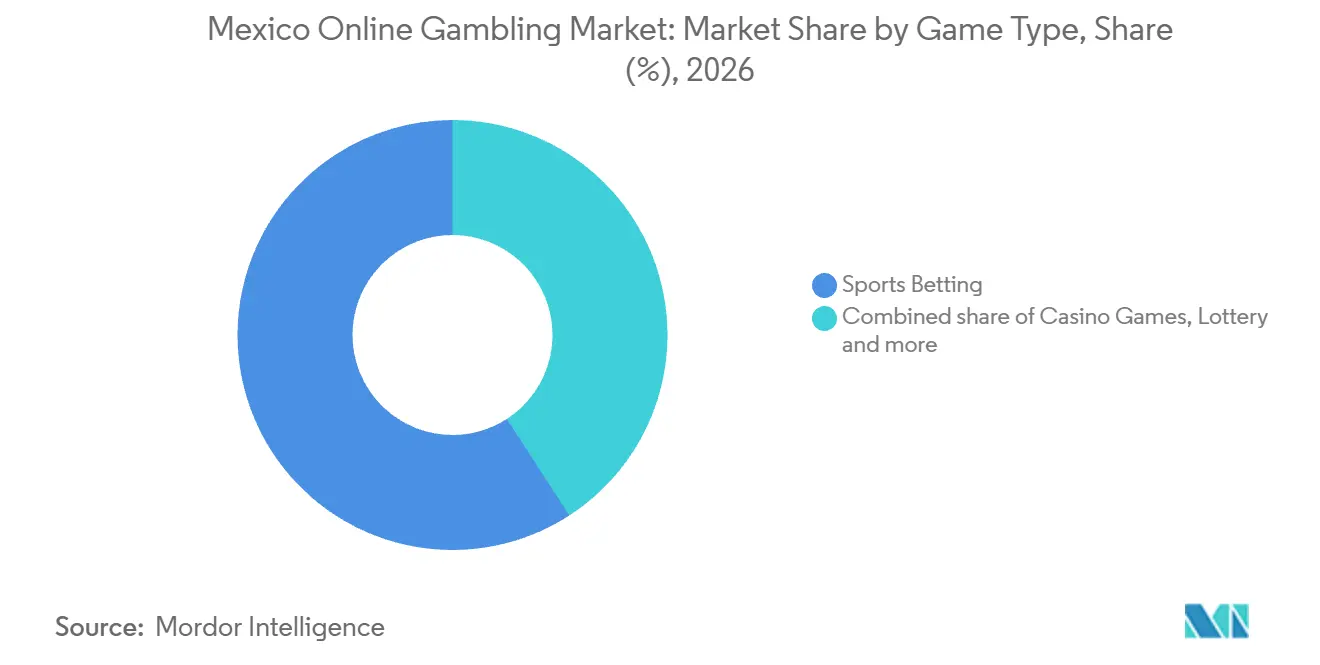
- By game type, sports betting held a 59.15% Mexico online gambling market share in 2026 and is forecast to be the fastest-growing segment, at a 17.1% CAGR between 2027 and 2032.
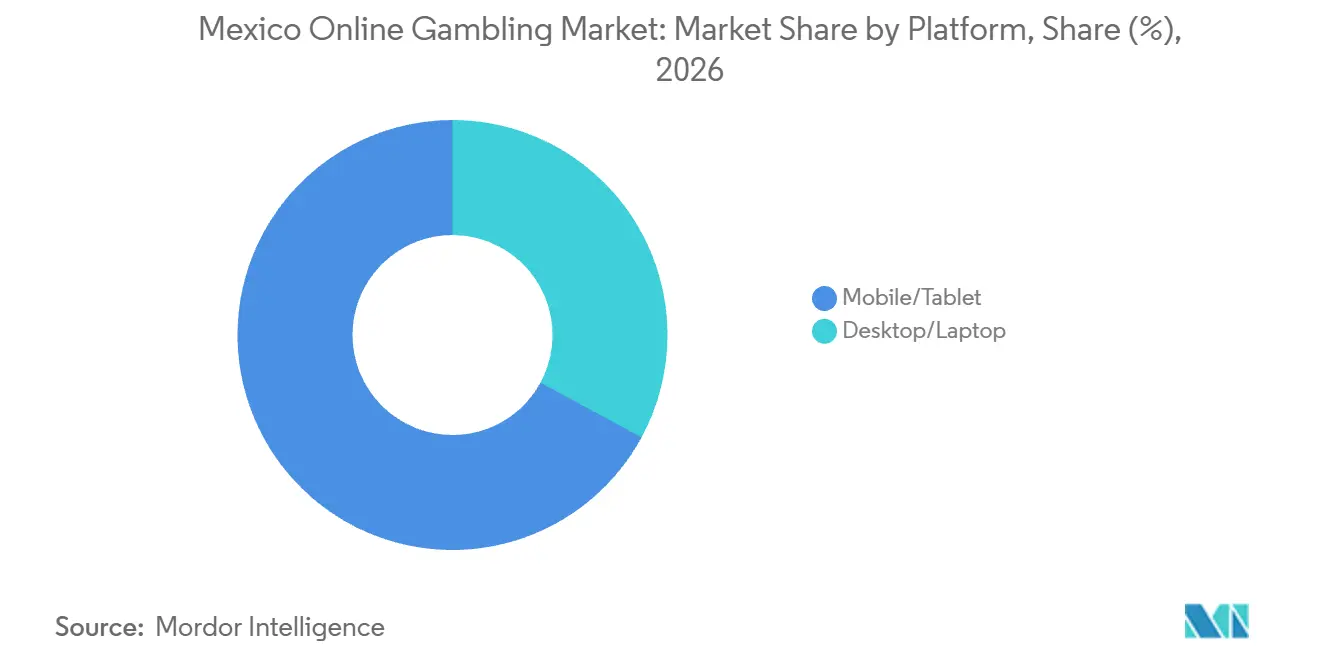
- Mobile/tablet platforms accounted for a 67.1% share of the Mexico online gambling market size in 2026, with the same platform category forecast to grow fastest at a 17.4% CAGR between 2027 and 2032.
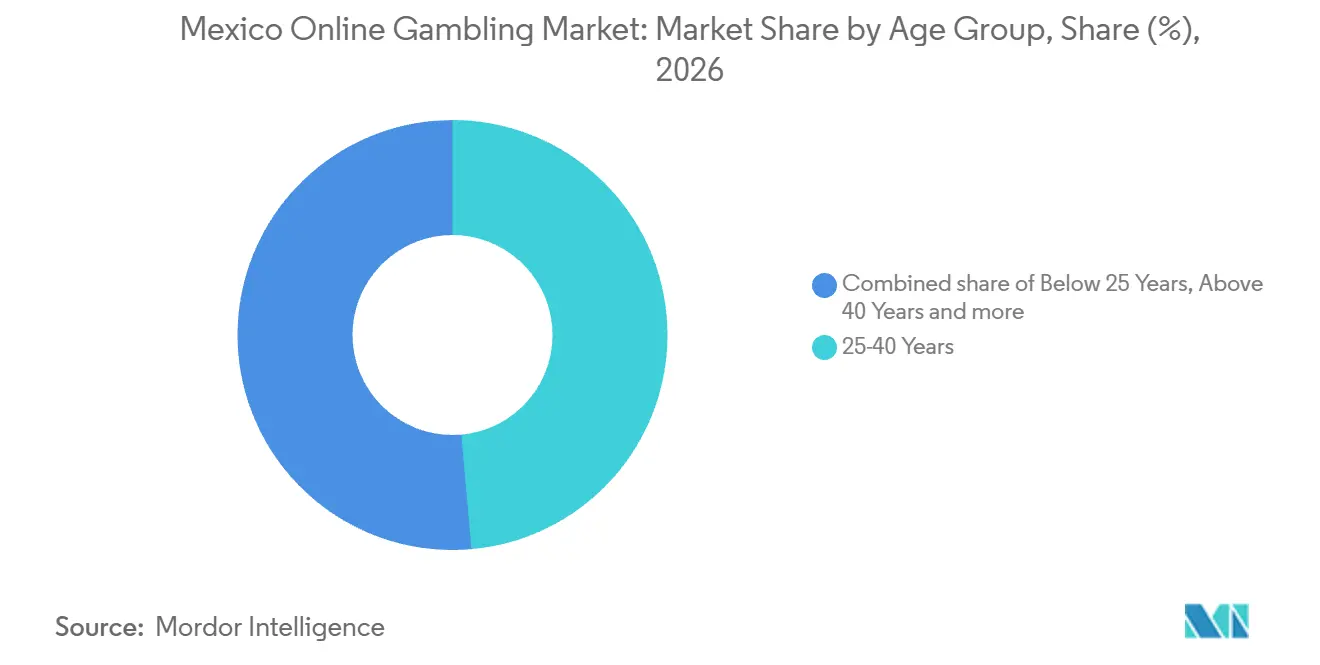
- Across age groups, people aged 25 to 40 led with 48.59% of the country's online gambling market in 2026, while eligible adults below 25 are forecast to grow fastest at a 16% CAGR between 2027 and 2032.
- Geographically, the Central region is the largest geography, with household connectivity in Mexico City providing a supportive digital distribution context.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Mexico Online Gambling Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing prevalence of gambling | +3.6% | Nationwide | Short term (≤ 2 years) |
| Enhanced internet connectivity and technology | +3.2% | Nationwide | Medium term (2-4 years) |
| Rising esports viewership drives betting adoption | +1.4% | Nationwide | Long term (≥ 4 years) |
| Spanish content and soccer themes drive millennial audience | +1.6% | Nationwide | Medium term (2-4 years) |
| Increasing popularity of sports betting | +1.2% | Nationwide | Short term (≤ 2 years) |
| Strong investment and revenue trajectory boosting market growth | +0.9% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing prevalence of gambling
Broader real-money participation creates more customer relationships through which a licensed online operator can generate wagering revenue. Codere Online reported 93,200 average monthly active players in Mexico in the first half of 2026, up 11% from 83,900 in the first half of 2025. The preliminary, unaudited figures, subject to change, measure real-money sports-betting and casino actives and exclude free bets. Because the measure averages monthly real-money actives, the increase represents a larger audience wagering in a typical month of the half. The 9,300 additional average monthly actives are real-money players, expanding the customer base from which licensed gross gaming revenue is earned.
Enhanced internet connectivity and technology
Internet access broadens the population that online gambling operators can potentially reach through digital distribution. Mexico's national statistics institute INEGI found in its survey that 86.1% of people aged 6 and older in Mexico used the internet in 2025, equivalent to 104.9 million users.[1] That proportion was 28.7 percentage points above the 2015 level, showing a longer-term expansion of connectivity. For operators serving eligible adults, the commercial task includes selecting audience groups within the broader connected population. Whether connected adults become wagering customers then rests on the quality of the first session.
Rising esports viewership drives betting adoption
Esports creates a potential demand route when an adult spectator can follow a contest closely enough to assess a wager. The service requirement is to keep the betting offer aligned with the particular game, match and settlement condition being offered. That alignment makes the selection and maintenance of competition data a distinct operating task for a sportsbook pursuing this audience. An operator can concentrate its offer on competitions it can support consistently, giving coverage depth a role in deciding how widely to expand. Game-specific data and settlement support can therefore turn specialist competition coverage into a coherent wagering service.
Spanish content and soccer themes drive millennial audience
The 2026 FIFA World Cup in Mexico, Canada and the United States began in June 2026 and gave online operators a soccer-led customer-acquisition setting. Codere Online reported approximately 75% more Mexican customers making their first deposit in June 2026 than in June 2025. A tournament co-hosted in Mexico gives operators a fixed match calendar around which to time acquisition. For an operator serving that audience, a fixed calendar means onboarding and promotional content can be prepared ahead of each fixture. For content suppliers, the practical need is modular material that operators can redeploy as fixtures change.
Restraints Impact Analysis of Mexico Online Gambling Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Regulatory uncertainty and cybersecurity threats | -1.3% | Nationwide | Medium term (2-4 years) |
| Tax regulations impact Mexican gaming market profitability | -1.9% | Nationwide | Short term (≤ 2 years) |
| Persistent gray/off-shore competition | -0.6% | Nationwide | Medium term (2-4 years) |
| Limited Spanish responsible-gambling programs | -0.2% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Regulatory uncertainty and cybersecurity threats
Unclear digital gambling rules make the timing of investment a commercial constraint for operators seeking to expand in Mexico. Miguel Ángel Ochoa, president of the Mexican gaming-industry association AIEJA, said in September 2026 that the absence of a precise framework complicated company planning and left investors awaiting a formal decision on whether to invest. This uncertainty matters before a new service earns revenue, when an operator must decide how much capital to commit. Staged commitments can limit exposure, but they also make expansion conditional on later regulatory clarity. Investment decisions can therefore trail the identification of customer demand while investors await a clearer framework.
Tax regulations impact Mexican gaming market profitability
Mexico's higher gambling tax increases the fiscal burden attached to serving online wagering demand. The IEPS rate on games with bets and draws rose from 30% to 50% on January 1, 2026.[2] The measure covers internet and electronic offerings, including those supplied by Mexican and foreign providers through digital intermediary platforms. The rate applies over the total value of bets or amounts effectively received by game and draw participants. For covered operators, the higher levy makes the relationship between wagering activity and retained earnings more demanding. Expansion therefore requires sufficient operating returns to absorb the additional tax burden before generating funds for reinvestment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Mexico Online Gambling Market Segment Analysis
By Game Type:
Sportsbook Leadership Sets Priorities While Bingo Keeps a Niche RoleSports betting accounted for a 59.15% share of the Mexico online gambling market size in 2026 and is forecast to be the fastest-growing segment, with a CAGR of 17.1% between 2027 and 2032. These combined positions make it central to decisions about which wagering services should receive product development and operating attention. A weakness in wager selection or settlement would therefore affect both the core revenue service and the leading forecast growth opportunity.
The sportsbook growth outlook leaves a portfolio question for operators serving customers with different game preferences. NEXT.io's September 2025 assessment described online bingo as a relative strength in Mexico compared with international markets and reported its declining prominence. This assessment makes locally adapted portfolio design relevant for operators deciding how to serve customers alongside their largest product line. Maintaining a smaller format can be commercially useful when it gives an operator a distinct point of engagement within the same online service. Local format relevance can therefore justify selective portfolio breadth for suppliers serving operators whose main growth opportunity lies in sports betting.



By Platform:
Mobile Leadership Follows Smartphone-First Internet AccessMobile/tablet represented a 67.1% Mexico online gambling market share in 2026 and is forecast to be the fastest-growing segment, with a CAGR of 17.4% between 2027 and 2032. The position gives mobile development a central role in how operators deliver their online offer. Codere Online Luxembourg S.A. launched its iOS poker app in Mexico on February 19, 2026, with availability in the country's Apple App Store. An iOS launch addresses a defined operating-system channel, allowing an operator to stage product distribution around the devices it chooses to support. Codere Online's poker app shows one route, a vertical-specific iOS release, by which an operator can extend its mobile offer.
The growth case also depends on the access devices through which potential customers already use a broad range of digital services. In 2025, 97.3% of internet users in Mexico connected through a smartphone, according to INEGI's survey. By comparison, 36.2% of internet users connected through a computer. For operators seeking eligible adult customers, this widespread device use makes mobile delivery a practical development priority, with service design focused on the wagering interaction inside the existing digital channel.

By Age Group:
Revenue Concentration and Cohort Renewal Require Different ApproachesPeople aged 25 to 40 made up the largest segment, accounting for a 48.59% share of the country's online gambling market in 2026. Within this cohort, 96.5% of people aged 25 to 34 in Mexico used the internet in 2025, according to INEGI's survey. That high access level gives operators a practical digital distribution route into the younger part of their largest revenue cohort. The segment's commercial attraction is its established revenue weight, making the quality of engagement within this connected adult population material to an operator's existing business.
Eligible adults below 25 are forecast to be the fastest-growing segment, with a CAGR of 16% between 2027 and 2032. The age boundary means the youngest segment must continually replenish its eligible customer pool as existing participants grow older. For an operator, ongoing recruitment of eligible adults is therefore part of sustaining this cohort's growth. Accounts kept active past the age boundary feed the 25 to 40 cohort, the segment that already carries the largest revenue weight.
Geography Analysis
Central region Online Gambling Market
The Central region is the largest geography in the Mexico online gambling market, with household connectivity providing a relevant distribution context. In 2025, 90.5% of Mexico City households had internet access, among Mexico's highest state-level rates. That household connection base gives licensed operators a substantial setting for reaching potential adult customers through online services. It makes a regional strategy built around digitally delivered wagering commercially plausible for operators selecting where to deepen their presence. Customer choice within that connected base then becomes central to converting geographic reach into repeat sportsbook and casino activity.
For operators diversifying customer acquisition, strong household connectivity can provide an expansion setting outside the leading geography. In the northern regions, Nuevo León recorded internet access in 89.9% of households in 2025, among Mexico's highest state rates, according to INEGI's survey. For an operator planning a presence beyond the leading region, this creates a separate pool of connected households to assess for adult sports betting and online casino services. A northern acquisition program can therefore diversify an operator's customer geography, reducing reliance on the leading region within the same national offer.
Lower household connectivity creates a different commercial constraint for online acquisition in some southern locations. In the south, Chiapas had internet access in 53.9% of households in 2025, the lowest state rate in INEGI's survey. The commercial constraint is reach through the household channel, which makes a population-wide acquisition effort a broader commitment than the access base supports. Selective targeting can keep spending concentrated on adults able to use the proposed channel while an operator tests the appeal of its offer. That sequencing lets operators establish reachable adult demand before committing acquisition resources across a wider southern footprint.
Regulatory Framework and Outlook
The comparison assesses selected jurisdictions through Mexico's federal gaming framework and Mexico City's local fiscal overlay. It takes the perspective of a licensed online operator assessing a local establishment that conducts covered betting games. The local column concerns the city's covered games and establishments, where operators collect a tax on participant expenditures. National authorization and obligations at a covered local establishment consequently create different commercial decisions.
Regulatory Table of Mexico Online Gambling Market
| Decision factor | Mexico, national framework | Mexico City, covered-establishment overlay |
|---|---|---|
| Primary authority | SEGOB / Dirección General de Juegos y Sorteos | Secretaría de Administración y Finanzas |
| Key instruments or direction | Federal Gaming and Sweepstakes Law; reform proposal | 2026 Fiscal Code, Articles 155 BIS 2 and 155 BIS 6 |
| Commercial effect | Federal authorization and oversight for an online operator | Register; collect 10% of covered participant expenditures upon receipt; remit by the following month's 20th; keep records and receipts |
| Current policy attractiveness | Medium | Low |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
The national Medium rating reflects an existing authorization route, while the Hardening judgment reflects the proposal's stated aims of combating money laundering and tax fraud. An October 9, 2026 report said the proposal had completed internal review and awaited Security Cabinet review before submission to Congress. Mexico City rates Low from this operator perspective because covered establishments must collect the participant-expenditure tax and maintain dedicated records and receipts. No change reflects the operative 2026 code's continuing collection and record-keeping structure, which keeps local compliance work material to the establishment's economics.
Value Chain Stages
The value chain compares the businesses that create gambling software, independently test games, and deliver the wagering service to customers. In March 2026, Codere Online announced that it had integrated RubyPlay and Koala Games casino titles into its Mexico offering. Caliente says it uses Playtech programs without alteration and that Technical Systems Testing (TST) tests its casino games monthly, issuing letters on Playtech's behalf. Codere Online illustrates the integration role, while Caliente's testing arrangement shows how independent assurance accompanies its supplied Playtech software.
Value Chain Analysis Table of Mexico Online Gambling Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Game software and content supply | Game software suppliers such as Playtech; casino content suppliers such as RubyPlay | Software and content supply income | Integrating titles from separate suppliers | Qualify integrations before customer release |
| Independent testing of Caliente casino games | Independent testing firms such as Technical Systems Testing (TST) | Testing service income | Keeping deployed software aligned with tested versions | Maintain version controls and repeat testing after relevant changes |
| Online wagering operation | Online betting and gaming operators such as Tecnología en Entretenimiento Caliplay, S.A.P.I. de C.V. | Gaming revenue from operating the wagering service | Coordinating supplied software with operator accountability | Retain clear responsibilities across technology and operating contracts |
| Source: Mordor Intelligence | ||||
Caliplay operates the Caliente brand, while Caliente Interactive is its parent and Corporación Caliente is Caliente Interactive's largest shareholder. Under an agreement effective March 31, 2025, Playtech stopped receiving an additional B2B services fee from Caliente Interactive. It instead recognized associate income and received dividends from its 30.8% equity stake, linking that income stream to ownership. Supplier exposure can therefore extend through the customer's economic performance, making ownership arrangements relevant when assessing the resilience of technology-provider earnings.
Competitive Landscape
Market Concentration
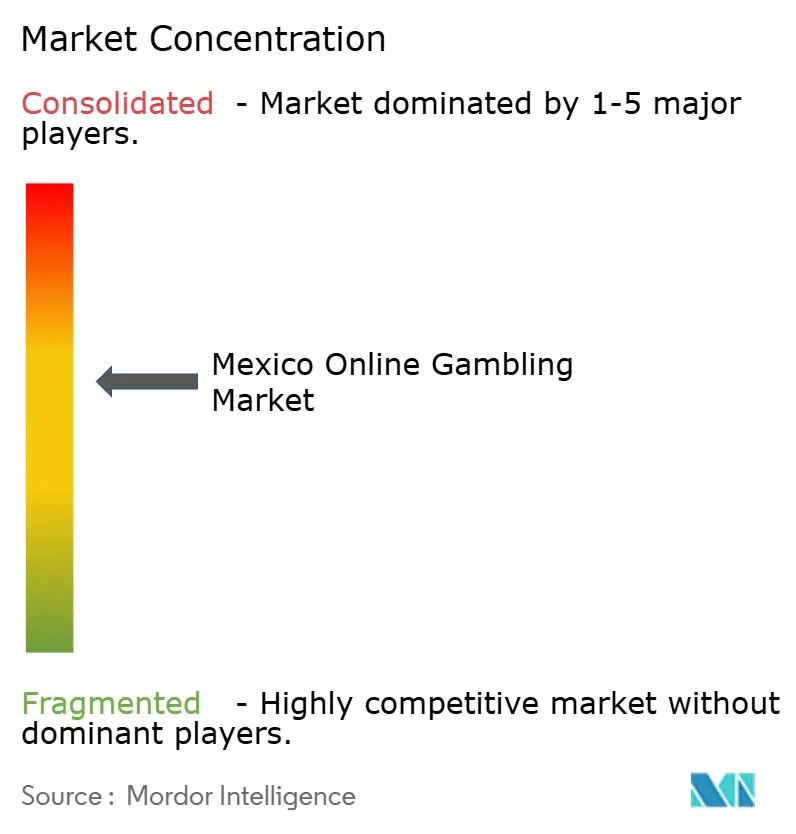
Competition combines Caliente, a Mexican gaming group, with international online operators, several of which reach customers through local permit holders or partners. Grupo Caliente (Caliente Interactive) participates through Caliente.mx, whose online operator, Tecnología en Entretenimiento Caliplay, S.A.P.I. de C.V., states that it is authorized by Mexico's Dirección General de Juegos y Sorteos. Codere Online Luxembourg S.A. and its subsidiaries provide online sports betting and casino services, complemented by the separate physical gaming presence of the wider Codere Group. Codere Online's average monthly active players in Mexico rose 38% to 88,700 in 2025 from 64,400 in 2024.
Bet365 Group Ltd is associated with the bet365 brand, while bet365.mx, linked to Grupo Salinas subsidiary Ganador Azteca, was suspended by the regulator in July 2026. Logflex MT Limited owns novibet.mx, operated in Mexico by permit holder Comercial de Juegos de la Frontera, S.A. de C.V. together with Operadora de Entretenimiento del Bajío, S.A. de C.V. as the authorized operator. Super Group (SGHC) Limited reports partnering with Espectaculos Deportivos Fronton Mexico S.A. de C.V. for access to sports betting and online casino gaming. These arrangements make control over a brand, a domain and local operating access distinct strategic assets, as the July 2026 suspension of bet365.mx shows.
Competition for recognition also extends to sponsorship of the sporting events around which betting interest forms. On January 27, 2026, Caliente.mx agreed to a multiyear sponsorship of the Concacaf Champions Cup and Concacaf W Champions Cup in Mexico.[3] The agreement covers men's and women's club competitions, with exclusivity applying to the betting sponsorship category. For challengers, that betting sponsorship category is occupied in these 2 competitions, making other sponsorships a route to audience recognition. Sponsorship visibility has commercial value for challengers only when the local domain behind it has the regulatory standing to accept wagers.
Mexico Online Gambling Industry Leaders
-
Grupo Caliente (Caliente Interactive)
-
Codere Online Luxembourg S.A.
-
Bet365 Group Ltd
-
Logflex MT Limited
-
Super Group (SGHC) Limited
- *Disclaimer: Major Players sorted in no particular order
Mexico Online Gambling Market Companies Covered in this Report
- Grupo Caliente (Caliente Interactive)
- Codere Online Luxembourg S.A.
- Bet365 Group Ltd
- Logrand Entertainment Group (Strendus)
- Rush Street Interactive Inc. (RushBet)
- Atracciones América S.A. de C.V.
- Super Group (SGHC) Limited
- Entain plc (Bwin)
- Flutter Entertainment plc (PokerStars / Betfair)
- Logflex MT Limited
- evoke plc
- TV Global Enterprises Ltd.
- Grupo Televisa
- Operadora de Espectáculos del Centro S.A. de C.V.
- Kindred Group plc (Unibet)
- Magnum Holdings Ltd.
- Lotto Direct Limited
- Betsson Group
- Bally's Corporation
- Tecnología En Entretenimiento Caliplay, SAPI DE CV
Key Opportunities for Market Participants
The opportunities compare ways to connect digital sports audiences and established poker customers with services that fit their observed channels. Comscore's 2025 Mexico report measured 26.5 million unique visitors in the Sports category, with 81% consuming sports content exclusively on mobile. For licensed sportsbooks, that audience makes the transition from reading sports coverage to using an operator's service a concrete commercial design problem. Acquisition partnerships and interface improvements address different parts of that transition.
Market Opportunities Table of Mexico Online Gambling Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Mobile sports-reader acquisition | Measured sports-content audience with extensive mobile-only consumption | Licensed sportsbooks reaching digital sports readers | Connect relevant sports coverage with clear mobile account-entry journeys | Converting content interest into voluntary betting participation | Licensed sportsbooks and sports-content publishers |
| Mobile sportsbook interface services | Mobile-only sports readership creates a defined delivery context | Operators commissioning mobile betting interfaces | Simplify navigation between event information, selection and wager confirmation | Integrating changes into the operator's transaction flow | Mobile interface developers and sportsbook operators |
| Poker retention across existing channels | An operator reports an established monthly active poker base | Casino operators serving recurring poker customers | Maintain consistent account access and poker service across supported channels | Sustaining repeat participation at an economic service cost | Poker operators such as Codere Online and service suppliers |
| Source: Mordor Intelligence | |||||
Retaining poker customers across the channels they already use gives operators a specific service opportunity. Codere Online reported more than 1,300 unique monthly active poker users in Mexico across its existing channels in February 2026. That monthly, Codere Online-specific base gives retention work a measurable customer population, making consistency across channels a concrete service objective for the operator.
Recent Industry Developments in Mexico Online Gambling Market
- Jul 2026: Mexico's Dirección General de Juegos y Sorteos suspended the bet365.mx domain, which was linked to Grupo Salinas subsidiary Ganador Azteca.
- Jun 2026: Altenar agreed to provide sportsbook technology for Logrand Entertainment Group's jubilee.mx and vivento.mx brands and Mexican casino venues. The announced deployment plan included retail integration through Calimaco's platform.
- Mar 2026: Codere Online integrated RubyPlay and Koala Games titles into its online casino offering in Mexico through a partnership with content supplier RubyPlay.
Mexico Online Gambling Market Report Scope and Research Methodology
Market Definition and Coverage
Mexico online gambling market measures annual gross gaming revenue from licensed real-money wagering offered through internet-connected platforms. The counted play is by users physically located in Mexico.
Scope exclusions: Land-based casino turnover, GGR from offshore operators without a Mexican license, free-to-play and social casino games, and separately sold gambling software and payment services are excluded.
Segments Covered in This Report
- By Game Type
- Sports Betting
- Casino Games
- Lottery
- Bingo
- By Platform
- Desktop/Laptop
- Mobile/Tablet
- By Age Group
- Below 25 Years
- 25-40 Years
- Above 40 Years
Data Sources, Market Sizing, and Validation
Desk Research
Illustrative public sources such as the World Bank's internet-use indicator, BDO Mexico's IEPS analysis, Codere Online's annual results, and Betsson AB's annual report help describe Mexico's digital access, fiscal changes, operator net gaming revenue, and financial cross-check measures. These sources help establish demand context, regulatory conditions, and the meaning of company-reported measures.
Supplementary company filings, investor materials, published operator presentations, and reputable industry reporting can check activity, product mix, customer trends, and changes in local operating conditions. These named sources are not exhaustive, and additional sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews with licensed online operators, sportsbook and casino product managers, Mexican regulatory and legal specialists, and relevant technology or payment providers would test the source-based assumptions about the licensed market. Respondents would clarify how operator GGR, game and platform attribution, and age-group evidence are recorded, with analysts documenting any unresolved gap and triangulating conflicts against independent filings, official indicators, and other Mexico-specific evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The top-down estimate begins with annual GGR from licensed online wagers by players in Mexico, counting stakes less winnings once at the operator level. Analysts use operator net gaming revenue and active-customer disclosures, Mexico internet-use and mobile-access indicators, game and device mix, fiscal and licensing changes, and the sports calendar to bound the national value. These inputs indicate reachable demand, observed monetization, product mix, and changes in operating conditions. Where disclosures include betting turnover, analysts separate wager flow from GGR using the operator's reported revenue reconciliation or a supported hold measure. Although connectivity and event calendars indicate potential demand, they do not replace the licensed-operator GGR boundary.
A multivariate regression can relate the historical GGR series to changes in connected-user reach, operator activity, product mix, and regulatory conditions, with scenario analysis for material tax or policy shifts and major sporting events. Segment shares for sports betting, casino games, lottery, and bingo, for desktop/laptop and mobile/tablet, and for the specified age groups are built from reported operator product or device revenue, customer evidence, and Mexico-specific consumer indicators, then checked against the total. Analysts use selective bottom-up checks by combining available licensed-operator net gaming revenue or sampled betting volumes with supported hold measures, rather than treating an incomplete operator sample as the whole market. Analysts document any omitted vertical or segment split, compare remaining evidence with independent market signals, and use an explicit judgment only where the gap cannot be resolved from source records. Primary respondents can challenge the drivers and variable-level forecast logic, after which unsupported inputs are revised or held out.
Data Validation & Update Cycle
Analysts triangulate the GGR model against independent operator filings, customer and connectivity indicators, tax and regulatory changes, and published market signals. They investigate outliers, reconcile differences in turnover, revenue, period, and coverage, and route corrected assumptions through analyst review before sign-off. A material source conflict or an unexplained movement triggers respondent re-contact where appropriate. The model is refreshed annually, updated between cycles when a material Mexican regulatory, tax, or market event changes its inputs, and receives a fresh source and variance review before delivery.
Mordor Intelligence's Mexico Online Gambling Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Mexico online gambling market measures annual gross gaming revenue from licensed real-money wagering offered through internet-connected platforms.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Segment shares for sports betting, casino games, lottery, and bingo, for desktop/laptop and mobile/tablet, and for the specified age groups are built from reported operator product or device revenue, customer evidence, and Mexico-specific consumer indicators, then checked against the total.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 1.05 B (2027) | |
| Industry Journal A | USD 3.2 B (2025) | At its 2025 base, this estimate is 204.8% above this report's 2027 value of USD 1.05 B, 2 years later. Its national online GGR projection covers the total online channel, including activity outside the licensed-operator boundary, which raises its reported total. |
| Global Consultancy B | USD 0.91 B (2023) | At its 2023 base, this estimate is 13.3% below this report's 2027 value of USD 1.05 B, 4 years later. Its earlier measurement year and published faster growth path place the estimate on an older market trajectory. |
Mordor Intelligence's analysts triangulate the GGR model against independent operator filings, customer and connectivity indicators, tax and regulatory changes, and published market signals.
Key Questions Answered in the Report
What is the Mexico online gambling market size and growth outlook?
It is projected to expand from USD 1.05 billion in 2027 to USD 1.53 billion by 2032, with a 7.85% CAGR between 2027 and 2032.
What is driving demand for licensed online gambling in Mexico?
Increasing real-money participation and broader internet access support demand. INEGI reported internet use among 86.1% of people aged 6 and older in Mexico in 2025.
Which game type leads online wagering in Mexico?
Sports betting held 59.15% of the country's online gambling market in 2026 and is forecast to grow fastest at a 17.1% CAGR between 2027 and 2032.
Which companies are major competitors in Mexico's online gambling industry?
Major competitors include Grupo Caliente (Caliente Interactive), Codere Online Luxembourg S.A., Bet365 Group Ltd, Logflex MT Limited and Super Group (SGHC) Limited.
What challenge weighs on licensed online operators' profitability?
Mexico's IEPS rate for games with bets and draws rose from 30% to 50% on January 1, 2026, increasing the fiscal burden on covered online offerings.
Which Mexican geography leads online gambling demand?
The Central region is the largest geography. Mexico City's 90.5% household internet-access rate in 2025 provides supportive connectivity context.