
Europe Food Cold Chain Logistics Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 74.70 Billion |
| Market Size (2026) | USD 81.29 Billion |
| Market Size (2031) | USD 124.14 Billion |
| Growth Rate (2026 - 2031) | 8.84 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Food Cold Chain Logistics Market Analysis by Mordor Intelligence
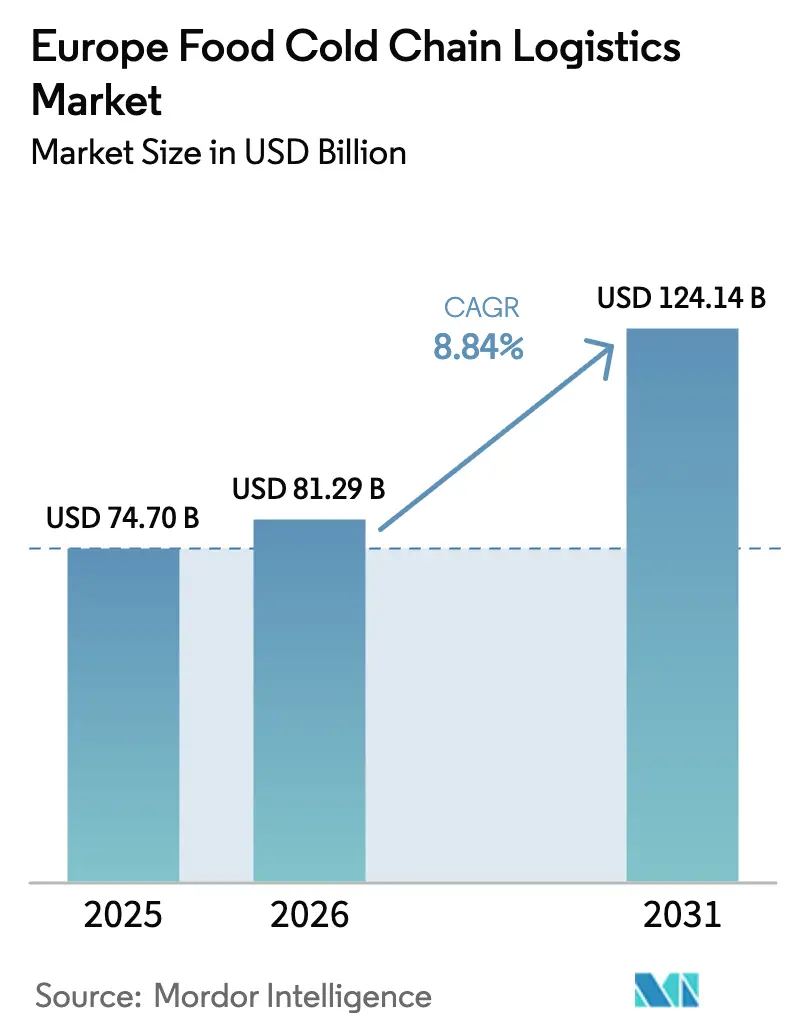
Europe Food Cold Chain Logistics Market size in 2026 is estimated at USD 81.29 billion, growing from 2025 value of USD 74.70 billion with 2031 projections showing USD 124.14 billion, growing at 8.84% CAGR over 2026-2031.
This sustained growth mirrors a region-wide overhaul of grocery fulfilment models that place temperature-controlled capacity closer to urban shoppers. Regulatory pressure from the EU Green Deal hastens the switch to natural refrigerants, raising capital needs yet lowering lifecycle emissions for compliant operators. Persistent Brexit-related customs checks create new demand for cross-docking hubs at ports such as Calais and Rotterdam, while rising e-commerce volumes compress delivery windows and favour micro-fulfilment centres with multi-temperature zones. Consolidation among pan-European specialists accelerates as private equity groups fund network build-outs, but structural driver shortages and energy price volatility inflate operating costs and test margins.
Key Report Takeaways
- By product type, Frozen Meat & Poultry led with 31.05% of the Europe food cold chain logistics market share in 2025; Ready Meals & Others is projected to expand at a 8.93% CAGR through 2031.
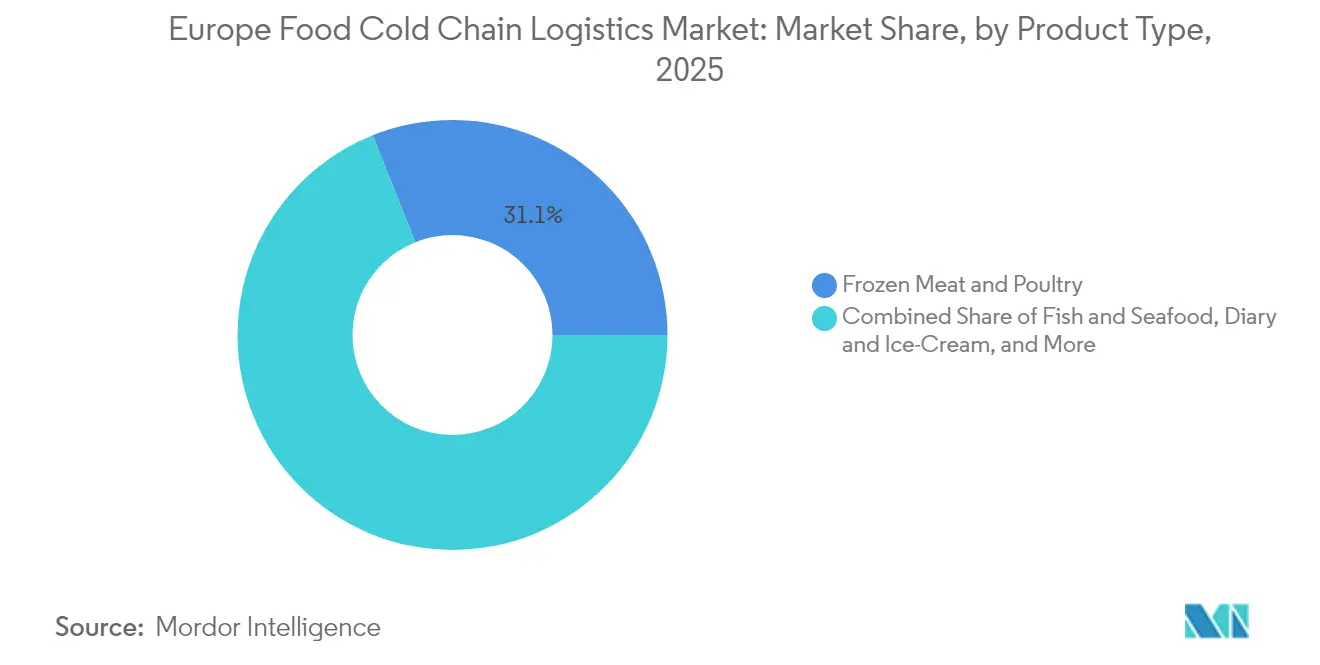
- By service type, Refrigerated Transportation held 52.60% revenue share of the Europe food cold chain logistics market in 2025, while Value-Added Services records the fastest growth at 8.72% CAGR to 2031.
- By temperature type, the Frozen category accounted for 60.10% share of the Europe food cold chain logistics market size in 2025; the Ambient category is set to rise at a 9.08% CAGR over 2026-2031.
- By geography, Germany remained the region’s primary hub in 2025, while Poland posted the strongest growth momentum among Eastern European markets.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Europe Food Cold Chain Logistics Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Europe-wide shift toward omni-channel grocery distribution networks | +2.1% | Western Europe, expanding eastward | Medium term (2-4 years) |
| Mandatory EU Green Deal targets accelerating adoption of natural refrigerants | +1.3% | EU-wide, strongest in Northern Europe | Long term (≥ 4 years) |
| Rapid capacity additions in Iberian Peninsula driven by agri-food export growth | +1.0% | Spain, Portugal | Medium term (2-4 years) |
| Surge in demand for ultra-low-temperature storage for plant-based meat analogues | +0.5% | UK, Germany, Nordics, Netherlands | Short term (≤ 2 years) |
| Post-Brexit customs friction boosting demand for cross-docking cold hubs | +0.9% | UK, France, Netherlands, Belgium | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Europe-wide Shift Toward Omni-Channel Grocery Distribution Networks
European grocers scale click-and-collect and rapid-delivery models that replace single mega-warehouses with dense clusters of micro-fulfilment hubs positioned near city centres. Operators respond by deploying modular buildings with frozen, chilled and ambient zones under one roof, supported by advanced energy-management software that balances refrigeration loads against power-price signals. Robotics adoption in Denmark illustrates the push toward automated pallet handling that compresses order-to-ship cycles without expanding headcount. Success now hinges on securing scarce urban real estate and integrating Internet-of-Things (IoT) sensors that certify temperature compliance in near real time. As these distributed networks mature, third-party logistics providers differentiate through data-driven route optimisation that protects product integrity during same-day deliveries.
Mandatory EU Green Deal Targets Accelerating Natural Refrigerant Adoption
The F-gas phasedown forces warehouse owners to retire high-GWP refrigerants and redesign systems for ammonia or CO₂. Initial capital intensity is high, yet operators report lower electricity use once regenerative heat reclaim and variable-speed compressors are in place. The ICCEE programme illustrates industry commitment by targeting 118 GWh of annual primary-energy savings and EUR 64 million of related investments. Larger companies absorb the expense by refinancing on green-bond markets, while smaller firms face merger pressure as compliance deadlines approach. A scarcity of engineers experienced with natural refrigerants adds wage inflation to project budgets but also seeds a specialised labour pool that bolsters long-run technical resilience.
Rapid Capacity Additions in Iberian Peninsula Driven by Export Growth
Spain and Portugal invest in ripening chambers and multi-temperature depots that preserve produce harvested during Northern Europe’s winter. New rail links from Almería to Rotterdam lower emissions per tonne-kilometre and tap demand from retailers seeking low-carbon supply chains. Solar-powered refrigeration arrays cut daytime grid draw and deliver operating-cost advantages against central European peers. Controlled-atmosphere rooms extend shelf life for berries and stone fruit, allowing Iberian exporters to command premium prices in Scandinavian supermarkets. These regional strengths encourage domestic third-party logistics firms to partner with multinational retailers intent on year-round assortment diversification.
Surge in Demand for Ultra-Low-Temperature Storage for Plant-Based Alternatives
Plant-based meat firms specify –23 °C to –25 °C storage, deeper than traditional frozen ranges. Beyond Burger’s life-cycle study shows refrigerated transport contributes 40% of total warming impact, spotlighting energy efficiency as a reputational risk. Operators carve out dedicated chambers within existing buildings and add doors with higher insulation values to limit thermal ingress during frequent pick-faces. Innovation extends to phase-change pallets that stabilise core temperature during cross-dock transfers and to dual-refrigerant trailers that flex between –25 °C and –18 °C routes. Analysts forecast 25 million t of plant protein demand by 2030, catalysing USD 27 billion of upstream capital projects and anchoring long-term ultra-low-temperature throughput.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Continental driver shortage inflating refrigerated road freight spot rates | −1.4% | Pan-European, most severe in Eastern Europe | Medium term (2-4 years) |
| High CAPEX for F-gas phasedown compliance across legacy facilities | −0.8% | EU-wide, highest impact in Southern Europe | Medium term (2-4 years) |
| Power-price volatility in Germany & Italy squeezing 3PL margins | −0.6% | Germany, Italy | Short term (≤ 2 years) |
| Limited availability of Class-A refrigerated warehouse sites near Tier-1 ports (Felixstowe, Antwerp, Hamburg) | −0.5% | UK, Belgium, Germany | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Continental Driver Shortage Inflating Transportation Costs
Europe faces 745,000 unfilled truck-driver slots by 2028, equal to 17% of required capacity. The talent pipeline falters as only 5% of current drivers are under 25 and cross-border routes carry extra administrative burden. IRU data notes 426,000 vacant positions already, pushing wages up and forcing shippers to book capacity weeks earlier than before. Spot-rate premiums on refrigerated lanes have widened relative to ambient lanes due to specialised licence needs and stricter rest-period rules. Modal shift to rail garners interest, yet cold-capable wagons and intermodal plugs are scarce, delaying large-scale migration and keeping road costs elevated.
High CAPEX for F-Gas Phasedown Compliance
EU Regulation 517/2014 tightens quota allocations for high-GWP refrigerants, compelling owners of ageing R-404A or R-507 systems to retrofit or rebuild. Energy now ranks as the second-largest cost item after labour, and although prices have eased since the 2022 spike they remain structurally higher than earlier in the decade. Southern European depots endure efficiency losses because high ambient temperatures erode natural-refrigerant performance, prompting investment in auxiliary adiabatic cooling and variable-speed drives. Studies show 30-40% power savings achievable through comprehensive upgrades, but payback periods stretch when electricity tariffs fluctuate. Mid-sized operators weigh phased refurbishment against outright facility replacement, with financing availability shaping long-term competitiveness.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Convenience Formats Reshape Category Priorities
The Europe food cold chain logistics market size for Frozen Meat & Poultry reached the equivalent of 31.05% share in 2025 and remains the largest revenue contributor despite slower incremental growth. Ready Meals & Others posts the highest 8.93% CAGR to 2031, propelled by dual-income households that value heat-and-eat foods compatible with shorter mealtimes. Fish & Seafood maintains resilient demand as aquaculture output scales and retailers promote omega-3 benefits, while Dairy & Ice-cream bookings continue to follow stable consumption patterns tied to established retail promotions. In fruits and vegetables, year-round supply strategies extend cold-chain penetration into previously seasonal categories, stimulating uptake of ethylene-control sachets that preserve freshness during long-haul moves.
Flash-freezing techniques in the Bakery & Confectionery segment allow centralised par-bake production shipped at −18 °C and finished on-site, shifting volume away from daily chilled deliveries. Flash-heat preservation trials for meat products indicate shelf-stable windows of up to 5 days, hinting at future attenuation of cold-chain reliance in selected cuts. Plant-based SKUs, which often blend protein isolates with functional fats, introduce atypical thermal profiles that force operators to recalibrate storage zoning within multi-use chambers. As consumer preferences evolve, agile 3PLs able to match niche temperature regimes widen their service revenue bases across converging product groups.


By Service Type: Ancillary Offerings Unlock Margin Expansion
Refrigerated Transportation represented 52.60% of total 2025 revenues in the Europe food cold chain logistics market, underpinned by dense road networks and high outbound frequency demanded by modern grocery retailers. Value-Added Services, including pick-and-pack, blast-freezing, labelling and quality control, deliver the fastest 8.72% CAGR and reposition warehouses as active fulfilment nodes rather than static holding points. Within transport, road commands a 76% modal share, but rail advances at 6.28% CAGR as green-house-gas accounting pushes shippers toward combined transport solutions. Manufacturers adopt the SWS Powerbox to energise containers on rail wagons, mitigating spoilage risk over long corridors. Airfreight retains a niche for ultra-perishable berries or premium seafood, whereas short-sea movements link Mediterranean producers to island consumers via Ro-Ro vessels fitted with plug-in reefer decks.
For operators, value-added layers defend margins against commoditised storage rates. Services such as product re-work in bonded facilities minimise duty payments on rejected imports, while light manufacturing—dicing vegetables or portioning protein—binds clients through integrated contracts. Digital portals offering real-time inventory visibility and blockchain-validated temperature logs further embed 3PLs within customers’ quality-assurance workflows, creating switching barriers and fostering multi-year engagements.
By Temperature Type: Ambient Gains Traction Yet Frozen Holds Core Volume
The frozen band (−18 °C to 0 °C) held 60.10% of the Europe food cold chain logistics market share in 2025, anchored by meat, seafood and ice-cream staples. Nevertheless, ambient solutions, powered by retort processing, aseptic filling and high-pressure pasteurisation, register a brisk 9.08% CAGR that reduces reliance on energy-heavy refrigeration. Ready-meals producers reformulate sauces and starch matrices to remain shelf-stable for nine months at 15 °C, enabling distribution through conventional dry channels and freeing consumer freezer space.
Chilled flows (0 °C to 5 °C) grow steadily as retailers expand ranges of ultra-fresh lines with premium positioning. Research shows micro-freezing extends beef freshness to 18 days compared with 4-6 days under standard chilling, prompting some processors to integrate intermittent freeze-thaw cycles that blend microbiological safety with desirable texture retention. EFSA studies on controlled ageing corroborate that microbial loads can be managed within regulatory limits, encouraging adoption of fine-tuned maturation rooms. As technology advances, product developers weigh trade-offs among shelf life, sensory appeal, energy use and packaging waste—choices that ultimately steer volume flows across the three temperature brackets.
Geography Analysis
Germany anchors the Europe food cold chain logistics market with expansive highway and rail corridors that funnel north-south citrus imports and east-west dairy exports. The country’s early embrace of natural refrigerants yields operating-cost savings that compound over time, while Lineage’s new Bremerhaven site adds 40,000 pallet positions with direct quay access that bolsters seaborne integration. Rail-connected depots around Hamburg and the Ruhr accelerate modal shift efforts and chip away at road congestion, aligning with national climate targets. German manufacturers also champion advanced warehouse-management software that synchronises inbound raw-material deliveries with just-in-time production schedules to curtail dwell time.
The United Kingdom remains pivotal despite its smaller landmass because of high grocery e-commerce penetration and elevated automation rates that compensate for post-Brexit labour gaps. Calais-linked buffer facilities manage customs clearance delays, and London-centric micro-fulfilment centres shorten delivery radii for meal-kit providers. UPS’s acquisition of Frigo-Trans and BPL reinforces healthcare cold-chain capabilities, signalling crossover between pharmaceutical and food networks that share temperature-verification standards. Duplicate regulatory frameworks raise administrative overhead, yet early adopters of blockchain traceability convert compliance into marketing claims around provenance and safety.
Southern and Eastern Europe chart divergent but complementary trajectories. France straddles Iberian produce flows to Northern consumers, pairing mature infrastructure in the north with capacity-build programmes around Marseille and Toulouse. Italy’s operators grapple with power-price volatility and therefore fast-track rooftop solar and chilled-water storage to buffer tariff swings. Spain invests heavily in multi-temperature nodes that leverage abundant solar irradiation for cost-effective cooling, providing a launchpad for winter fruit exports. Poland posts the region’s highest growth rate as EUR 252 billion (USD ) of cumulative FDI underwrites modern depots serving cross-border supermarket formats; logistics employment rose 24.6% in 2024 while national unemployment held at 3.0%, securing a robust labour pipeline.
Regulatory Landscape
Food cold chain operations in Europe are shaped by EU food hygiene and temperature-control rules that influence facility design, monitoring, and auditability across storage and transport. Regulation (EC) No 852/2004 provides the baseline for hygiene management (including cold chain integrity), while Commission Regulation (EC) No 37/2005 sets temperature-monitoring requirements for quick-frozen foodstuffs, with EN 12830, EN 13485, and EN 13486 referenced alongside the ATP Agreement, which remains a key reference for performance classes of insulated and refrigerated road equipment in international food transport.
Refrigerant and climate compliance also drives asset replacement cycles and workforce qualification needs. Commission Implementing Regulation (EU) 2024/2215 governs certification for personnel handling fluorinated gases in refrigerated transport units and trailers, reinforcing training and compliance costs alongside the EU F-gas phasedown. On trade and controls, Commission Implementing Regulation (EU) 2026/551 applies from 1 October 2026 and updates the list of animal-origin products subject to official border controls. Commission Implementing Regulation (EU) 2026/318 (February 2026) sets transitional periods for certain animal health certificate requirements, which in turn affects cold-chain documentation, inspection readiness, and cross-dock operating procedures at key gateways.
Value Chain Analysis
The European food cold chain value chain begins with producers and processors (meat, seafood, dairy, frozen and ready-meals, and fresh produce), then moves into temperature-controlled primary transport feeding regional consolidation nodes. These nodes carry out multi-vendor consolidation, inbound quality checks, and inventory holding across multiple temperature bands, including deep-freeze and chilled storage and, where applicable, controlled ambient handling, before orders enter case-pick or pallet-pick processes for retail, foodservice, and e-commerce replenishment.
Value creation is concentrated in logistics service providers and asset operators that integrate storage, handling, and distribution under audited food safety systems. Order preparation (including co-packing and light processing), blast-freeze staging, labeling, and temperature-verified cross-docking sit between refrigerated warehousing and last-mile distribution. As an example of scaled cold-chain execution in Europe, STEF operates 236 platforms and warehouses across 7 European countries and requires suppliers and subcontractors to follow structured food safety protocols, including HACCP-based controls and IFS Logistics-aligned requirements, which cascades compliance expectations across carriers, packaging partners, and subcontracted handling sites.
Competitive Landscape
The Europe food cold chain logistics market shows a barbell structure: pan-European giants on one end and local specialists on the other. DSV’s EUR 14.3 billion (approx. USD 16.55 billion) Schenker takeover pushes the Danish firm into the global top tier and is projected to unlock DKK 9.0 billion (approx. USD 1.3 billion) in annual synergies by 2028 through network rationalisation and procurement scale. EQT’s acquisition of Constellation Cold Logistics demonstrates private-equity appetite for asset-heavy platforms that offer stable cash yields and ESG-aligned upgrade potential. Kuehne + Nagel’s EUR 350 million spend in Mantova plus the purchase of Transporte y Distribución Nacional deepens its Southern and Central European footprint, signalling a pivot toward origin-country value-added services that embed the 3PL earlier in the supply chain.
Technology shapes competitive edges. Blockchain-anchored IoT ecosystems document every temperature reading, door open and location ping, reducing insurance premiums and bolstering recall readiness. Predictive maintenance software minimises compressor downtime, while AI-based slotting engines improve pick-face turnover in multi-SKU chambers. Energy-management systems that orchestrate refrigeration duty cycles against hourly grid tariffs trim utility bills by double digits and unlock value beyond simple kilowatt savings.
Regional specialists defend turf through bespoke services—such as seafood ripening in Galicia or halal meat consolidation in the Netherlands—that multinationals find hard to replicate without local talent. Yet fragmented players risk margin squeeze when negotiating power contracts or vehicle procurement, nudging them toward cooperative buying groups or eventual sale. Over the forecast window, capital-intensive sustainability mandates will likely widen capability gaps, favouring well-funded networks able to amortise large-scale upgrades across multi-country portfolios.
Europe Food Cold Chain Logistics Industry Leaders
STEF SA
Americold Logistics, LLC (AGRO Merchants Europe)
DHL Supply Chain (Deutsche Post DHL Group)
Kuehne + Nagel International AG
NewCold Advanced Cold Logistics
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Operational compliance and decarbonization requirements keep opening investable whitespace for facility upgrades, monitoring, and workforce capability. The F-gas phasedown and the personnel certification requirements for fluorinated-gas handling in refrigerated transport units (Commission Implementing Regulation (EU) 2024/2215) are lifting demand for compliant retrofit programs, natural-refrigerant engineering skills, and temperature-monitoring systems that align with quick-frozen monitoring needs under Commission Regulation (EC) No 37/2005 (EN 12830/EN 13485/EN 13486). Operators that can standardize these compliance elements across multi-country networks can also differentiate by offering auditable temperature data across both storage and transport legs.
Network densification near trade and consumption hubs remains a practical opportunity where capacity is tight near major gateways and large urban catchments. Northern Europe is a notable example, as STEF identified Belgium as a strategic focus for frozen logistics growth after its 2024 acquisition of TDL Fresh Logistics, with the Antwerp-Brussels corridor forming a targeted area for refrigerated capacity and value-added handling due to proximity to major transport infrastructure. Post-Brexit frictions also keep attention on cross-docking and documentation-ready buffer sites tied to flows through France and the Benelux, and the 1 October 2026 update to EU border-control product lists (Commission Implementing Regulation (EU) 2026/551) increases the need for inspection-ready processes and short-dwell cold handling for animal-origin products.
Recent Industry Developments
- June 2026: STEF SA - Inaugurated a major extension of its multi-temperature platform in Reichstett (near Strasbourg), adding a 65,000 cubic metre deep-freeze chamber and 15,000 pallet positions for a total capacity of 28,000 positions, in partnership with Mars Wrigley. The expansion strengthens STEF SA's temperature-controlled network in Western Europe and enhances its capacity to service large consumer brands, improving cross-border throughput and service levels in the Franco-German corridor. The project signals a step change in scale for completed capacity in the region, reinforcing STEF SA's competitive position in multi-temperature logistics and cold chain integration for confectionery and snack categories.
- May 2026: Americold Logistics LLC - Entered a long-term agreement with Jeronimo Martins to manage storage and store case pick fulfillment for approximately 12 million cases of frozen products annually, serving roughly 300 retail stores in Portugal. The deal extends Americold's footprint in Southern Europe and increases service density for a major retailer, supporting faster delivery windows and improved inventory turnover. The collaboration expands standardized cold storage and order fulfillment capabilities across a key European market, strengthening market access for Jeronimo Martins and reinforcing Americold's regional presence.
- May 2026: Americold Logistics LLC - Highlighted a centralized frozen food logistics solution for supermarket cooperative PLUS in the Netherlands, utilizing the Barneveld distribution center. The solution consolidates frozen product streams and improves slotting efficiency across multiple supermarket banners, boosting throughput and reducing handling costs. This initiative demonstrates Americold's ability to tailor multi-user cold chain platforms to complex regional networks, enhancing reliability for Dutch grocery supply chains.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market is defined as revenues earned from temperature-controlled logistics services used to move and store food across Europe, where product integrity must be maintained through chilled and frozen handling across the supply chain.
Scope exclusions: This sizing excludes non-food cold chain activity and any ambient-only food logistics that does not require controlled-temperature transport or storage.
Segmentation Overview
- By Product Type
- Frozen Meat & Poultry
- Fish & Seafood
- Dairy & Ice-cream
- Fruits & Vegetables
- Bakery & Confectionery
- Ready Meals & Others
- By Service Type
- Refrigerated Storage
- Refrigerated Transportation
- Road
- Rail
- Sea
- Air
- Value-Added Services
- By Temperature Type
- Chilled (0–5 °C)
- Frozen (-18–0 °C)
- Ambient
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Nordics
- Poland
- Rest of Europe
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with public statistics that help anchor the demand pool for refrigerated food movement and storage in Europe. We used sources such as Eurostat for trade and production series, FAOSTAT for food supply indicators, and European Commission publications for food safety and cold-chain related policy direction. Where relevant, reference points were cross-checked against national statistical offices and customs portals for major importing countries.
To convert those signals into a market model, we also reviewed annual reports and investor presentations for logistics operators, retailer disclosures that indicate cold chain intensity, and reputable trade association publications for storage capacity and handling norms. Patent databases were used selectively to understand adoption of refrigeration and monitoring technologies, and a paid subscription for company financials and intelligence supported consistent revenue classification when public reporting was limited. The desk sources listed here are illustrative only, and many other public and paid references were consulted for data collection, cross-checking, and clarification.
Primary Interviews and Surveys
Primary discussions were carried out with refrigerated transport providers, cold storage operators, freight intermediaries, and food shippers that regularly move chilled and frozen products. Inputs were used to confirm typical service mixes, contract structures, utilization swings by season, and realistic pricing movement, and then to sanity check country-level assumptions where public data is thin across Europe.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 36% | CXOs: 18% |
| Mid tier: 45% | Functional/Unit leaders: 24% |
| Smaller Players: 19% | Managers: 58% |
Market-Sizing & Forecasting
Sizing begins with a top-down build where food production, consumption, and cross-border trade flows are reconstructed into temperature-controlled handling needs, and then translated into refrigerated storage and transport revenue pools. To keep the totals realistic, selective bottom-up approximations are used as cross-checks, such as sampled price-per-pallet and price-per-kilometer ranges applied to plausible volumes, followed by supplier and operator revenue reasonableness checks.
Key inputs that shape the model include chilled versus frozen share by food type, storage capacity and utilization patterns, average length of haul for intra-Europe movement, fuel and energy cost pass-through behavior, and the share of outsourced cold chain versus in-house operations. When gaps arise, assumptions are filled using interview-led ranges and nearby country analogs, and then adjusted once the model shows outliers against known operational constraints. Forecasting is done using scenario analysis supported by variable-level expectations from market participants, so demand drivers like frozen food penetration, fresh produce import reliance, and retail cold-chain intensity can be stressed up or down without breaking the logic.
Data Validation & Update Cycle
Outputs are validated through several checks so the final totals stay aligned with real movement and storage activity. We compare implied volumes, pricing, and utilization against independent signals, and then investigate anomalies at the country and service level before sign-off. If interview feedback indicates a recent pricing reset, capacity addition, or regulatory change that materially shifts operations, assumptions are revisited and respondents may be re-contacted.
Reports are refreshed annually, and interim updates are made when a material event changes the market trajectory. Before delivery, a final pass is done to ensure the latest public releases and confirmed market signals are reflected in the model.
Mordor Intelligence's Europe Food Cold Chain Logistics Market Size Measured Against Other Published Estimates
Published market sizes for Europe food cold chain logistics often differ because the service boundary is not treated the same way, and because pricing, currency timing, and the base year can vary by publisher. The practical result is that two numbers can look far apart even when the underlying demand story is similar.
The biggest gap drivers tend to be whether value-added services are counted as part of cold chain revenue, how cross-border legs are allocated when multiple providers touch a shipment, and whether the estimate includes ambient logistics attached to food distribution. Differences also come from how price escalation is modeled (flat price, fuel-indexed pass-through, or aggressive rate growth) and how quickly assumptions are refreshed after energy cost changes or regulatory updates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 74.70 B (2025) | |
| Industry Association A | USD 68.10 B (2025) | Uses reported cold storage turnover as the main anchor and applies conservative transport attachment rates, which can undercount refrigerated road and cross-border freight mark-ups. |
| Global Consultancy B | USD 89.40 B (2025) | Broadens scope by blending some ambient food distribution and packaging-adjacent handling into cold chain totals, and applies faster rate growth without consistent checks against utilization limits. |
The table shows a spread mainly tied to what is treated as cold chain revenue versus general food logistics, and in Mordor Intelligence's model, only temperature-controlled storage, transport, and related handling for chilled and frozen food are counted once they are required to maintain the cold state. With that scope kept consistent across countries, the estimate stays traceable to clear demand signals and repeatable pricing and utilization assumptions, which helps decision-makers compare markets on like-for-like terms.


Key Questions Answered in the Report
What is the current size of the Europe food cold chain logistics market and its forecast growth?
The market is valued at USD 81.29 billion in 2026 and is projected to reach USD 124.14 billion by 2031, registering an 8.84% CAGR.
Which product segment is expanding the quickest in Europe’s food cold chain?
Ready Meals & Others leads with a 8.93% CAGR through 2031, outpacing Frozen Meat & Poultry.
How do EU Green Deal rules affect investment decisions for cold chain operators?
Mandatory natural-refrigerant adoption raises upfront capital needs but delivers long-term energy savings and compliance benefits.
What impact does the truck-driver shortage have on refrigerated transport costs?
With 745,000 positions forecast to remain unfilled by 2028, spot rates for temperature-controlled road freight continue to rise.
Why are ambient solutions gaining share against frozen storage in Europe?
Advances in aseptic processing and high-barrier packaging allow more foods to travel at room temperature, cutting energy use and costs.
Which European country is expected to post the fastest cold chain logistics growth by 2031?
Poland shows the highest momentum, supported by EUR 252 billion of cumulative FDI and expanding modern warehouse capacity.
Page last updated on:


