
Australia Beauty And Personal Care Products Market Analysis by Mordor Intelligence
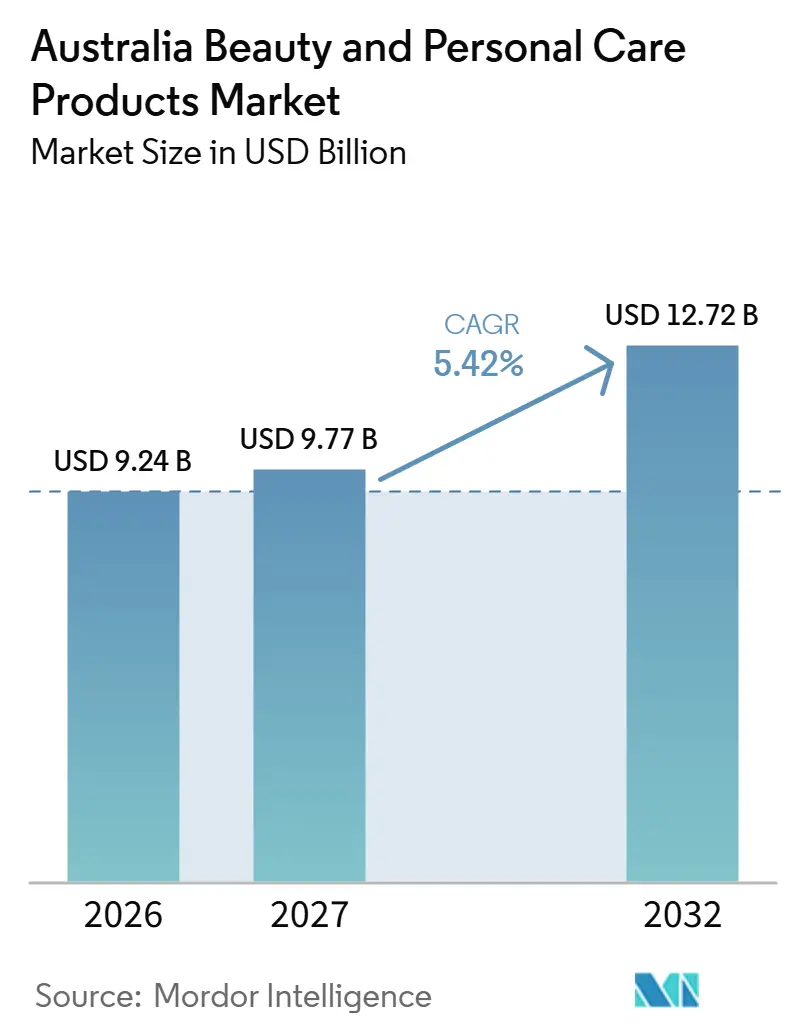
The Australia beauty and personal care products market size is expected to grow from USD 9.24 billion in 2026 to USD 9.77 billion in 2027 and is forecast to reach USD 12.72 billion by 2032 at 5.42% CAGR over 2027-2032.
Across Australia, wider skincare participation and digital research support demand for products with clearly explained functions. Online retail and specialty stores give suppliers complementary ways to connect skincare ranges with household routines. Counterfeit risk, failed sun-protection claims, and ingredient controls temper that opportunity by adding authenticity checks and formulation-assurance costs. Sunscreen and functional skincare suppliers are better placed to differentiate through substantiated claims in shoppers' comparison information than through assortment breadth alone.
Key Report Takeaways
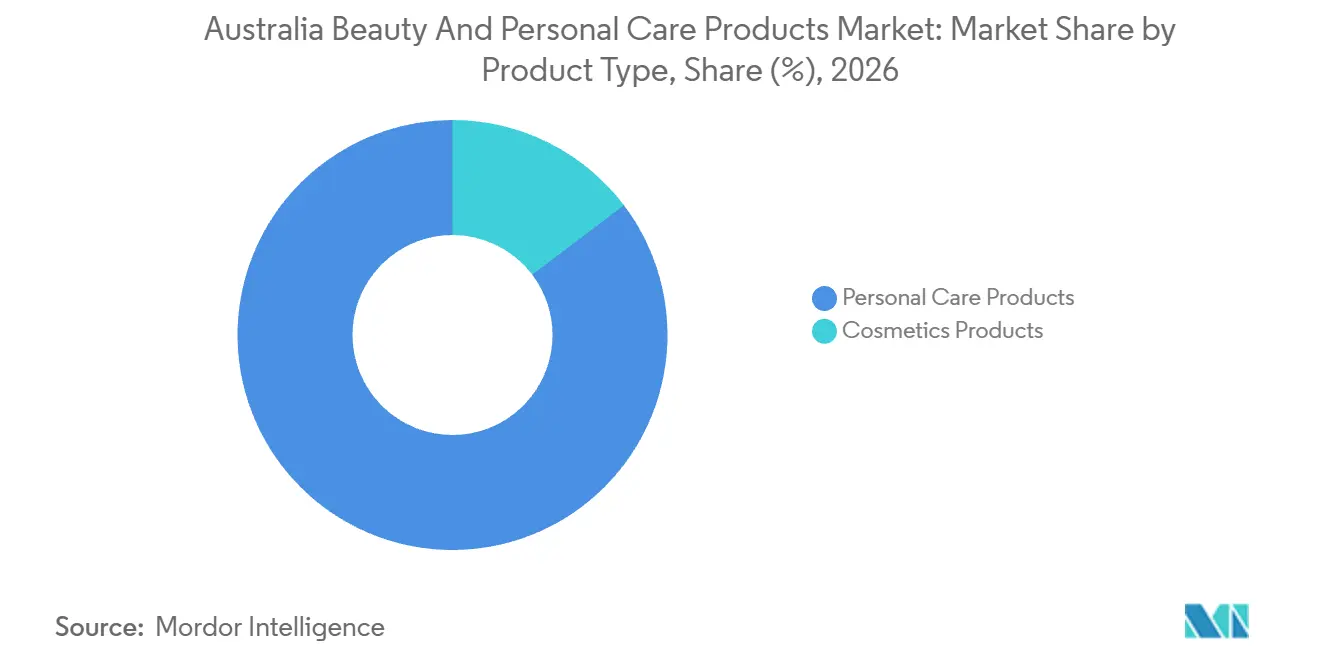
- By product type, personal care products held an 85.31% Australia beauty and personal care products market share in 2026, while cosmetics products are forecast to grow fastest at a 5.52% CAGR over 2027-2032.
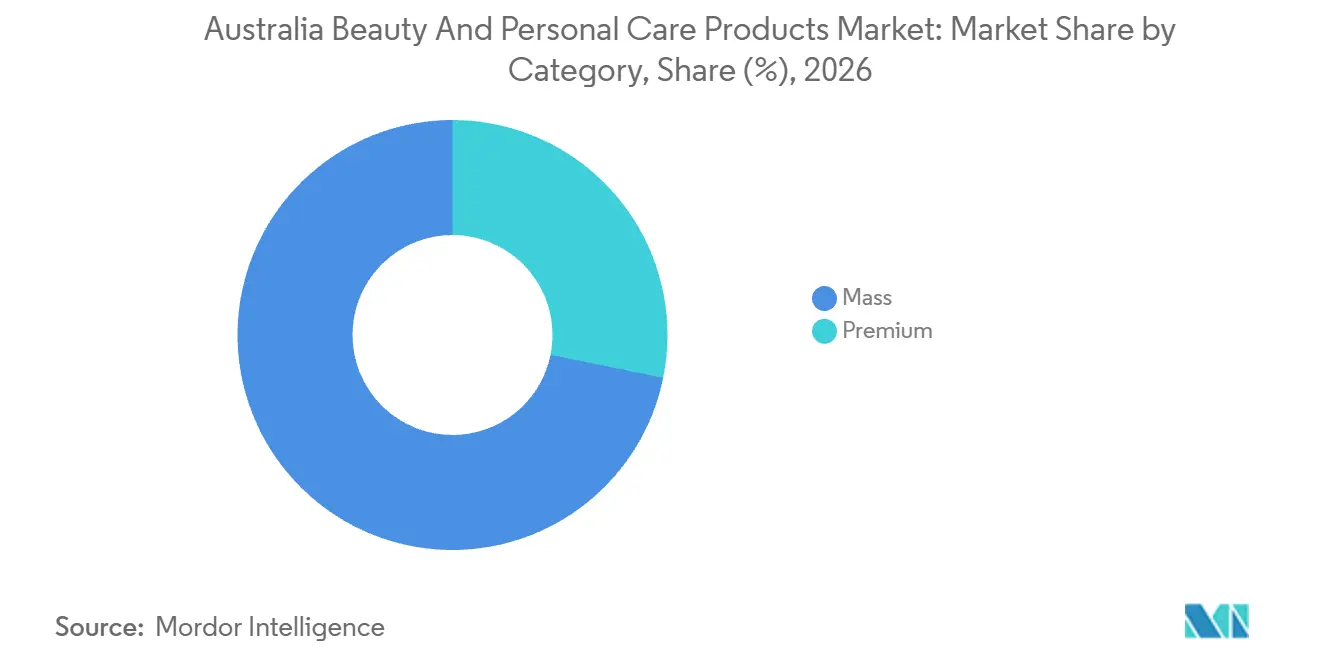
- Mass products led the category breakdown with a 71.81% share of the Australia beauty and personal care products market size in 2026, and premium products are projected to grow fastest at a 6.05% CAGR over 2027-2032.
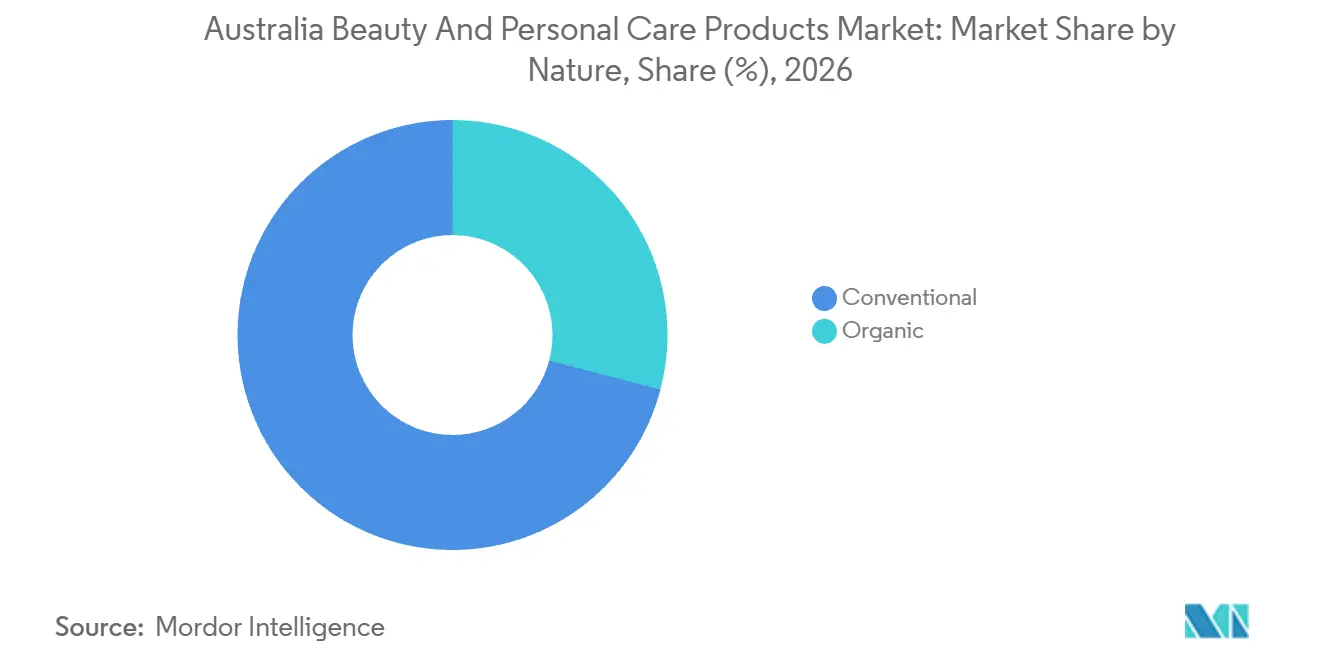
- Conventional products held 70.91% of the market by nature in 2026, whereas organic products are forecast to grow fastest at a 6.68% CAGR over 2027-2032.
- Among distribution channels, health and beauty stores held 37.88% of the market in 2026, with online retail channels forecast to grow fastest at a 6.78% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Australia Beauty And Personal Care Products Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing consumer preference for natural and organic beauty and personal care products. | +1.4% | Nationwide | Long term (≥ 4 years) |
| Increasing demand for anti-aging and age management products | +1.3% | Nationwide | Medium term (2-4 years) |
| Impact of social media and advancements in digital technology | +2% | Nationwide | Short term (≤ 2 years) |
| Rising interest in men's personal care products | +1.5% | Nationwide | Medium term (2-4 years) |
| Demand for region-specific products driven by inbound tourism | +0.5% | Nationwide | Short term (≤ 2 years) |
| Increased focus on self-care and wellness | +0.4% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing consumer preference for natural and organic beauty and personal care products.
Natural and organic positioning can create demand by making ingredient selection part of the reason to choose a skincare or cleansing product. A supplier can make that proposition more precise by explaining separately what its natural ingredient promise and its organic product promise mean. Linking those descriptions to a familiar use gives the consumer a functional basis for comparing products as well as an ingredient-based distinction. This approach can support a focused extension of a skincare range without changing the care task around which the range is organized. Such a range would compete on ingredient provenance within an existing care task, while any efficacy claim would need its own justification.
Increasing demand for anti-aging and age management products
Age-management skincare can benefit from coordinated brand communication and pharmacy distribution when the range addresses a clearly defined concern. McPherson's reported that Australian pharmacy retail sales value for its Ultra R4 skincare range rose 6.2% in FY2025, above 5.4% growth for the pharmacy category. The company described Dr. LeWinn's as a premium skincare offering addressing major aging skin concerns. McPherson's linked the range's performance to media partnerships and digital campaigns integrated with omnichannel retail activity. That 0.8 percentage point lead makes coordinated consumer-facing support part of the pharmacy supplier's competitive offer, beyond securing shelf space.
Impact of social media and advancements in digital technology
Digital product discovery makes the quality of a brand's product information commercially relevant before a shopper reaches checkout. Australia Post's 2025 survey found that 18% of consumers used AI to research beauty products online. That use gives suppliers an opportunity to explain ingredients and product functions in information that can support assisted comparison across digital interfaces. Consistent descriptions can make a range easier to interpret when the shopper's first interaction is a research query about a particular need. This shifts part of a beauty supplier's acquisition task from attracting attention to answering a specific formulation or usage question.
Rising interest in men's personal care products
Men's skincare routines can support demand for complementary facial care products. The number of Australian men reporting a skincare routine rose from 1.79 million in the year from July 2020 to June 2021 to 2.19 million in the year from July 2024 to June 2025.[1] A larger routine-user base creates more potential occasions for cleansers and moisturizers to become complementary parts of daily care. Brands can address that opportunity with clearly differentiated product functions and instructions that make a complete routine understandable. Routine participation creates a basis for complementary product sales, making a range across linked facial care tasks more relevant than repeated variations of the same item.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growth of counterfeit products | -0.5% | Nationwide | Medium term (2-4 years) |
| Increasing awareness regarding product safety and ingredient transparency | -0.6% | Nationwide | Short term (≤ 2 years) |
| Increasing adoption of do-it-yourself (DIY) approaches and minimalist trends | -0.2% | Nationwide | Medium term (2-4 years) |
| Intense competition and pricing challenges | -0.4% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Growth of counterfeit products
Counterfeit cosmetics create a commercial problem when product authenticity becomes inseparable from the credibility of the brand's safety claims. The Senate Legal and Constitutional Affairs Legislation Committee's May 2026 report on the false trade marks bill recorded evidence listing cosmetics among "high risk" counterfeit categories and noted counterfeit goods' consumer-safety risks.[2] For legitimate brand owners, this risk can make the provenance of goods part of the product proposition, especially where buyers cannot verify the formulation themselves. Retailers handling branded cosmetics consequently face a potential cost in distinguishing genuine supply from products that merely reproduce its appearance. Authentication can protect that distinction, but the remaining burden is the expense of defending trust in goods sold under the brand's identity.
Increasing awareness regarding product safety and ingredient transparency
Product claims that fail scrutiny can interrupt sales and expose the brand owner to costs beyond replacing the affected stock. In 2025, 20 sunscreens made with Wild Child Laboratories' base formulation were recalled in Australia after failing their SPF claims.[3] The shared formulation illustrates how a technical failure can affect several finished products and complicate assurance across a supplier relationship. In 2026, Advanced Skin Technology, owner of Aspect Skincare, pursued claimed losses from 2 sunscreen recalls in 2025, including lost sales, recall staff time, and reputational damage. These were claims in a Federal Court action, rather than findings of liability. Replacing stock alone would leave the claimed recall labor and reputational losses unresolved.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Product Type: Broad Personal Care Use Supports Scale
Personal care products were the largest segment, accounting for 85.31% of the market in 2026. Roy Morgan estimated that 14.4 million Australians aged 14 and older reported using skincare products in the 12 months to June 2025. That substantial user population gives suppliers an established skincare user base within the broader personal care business. A supplier can build its range around distinct care tasks, differentiating everyday maintenance products from more targeted offerings while keeping each product's intended use clear. With use up from 13 million in the 12 months to June 2021, suppliers' growth depends more on winning a place in existing skincare routines than on adding users.
Cosmetics products are forecast to be the fastest-growing segment, at a 5.52% CAGR over 2027-2032. BIG W added cosmetic brands to Australian shelves in October 2025, citing demand for affordable and accessible beauty products. That expansion gives cosmetics suppliers a concrete route to shoppers through a broader retailer assortment, with affordability and availability forming the retailer's stated commercial rationale. Manufacturers can respond with clear differences in cosmetic function and presentation, so a new item adds a reason for selection within that expanded range. BIG W's affordability-led expansion gives cosmetics suppliers broader distribution, but makes novelty alone a weak basis for seeking a price premium.

By Category: Mass Access and Premium Assortment Expansion
Mass products accounted for a 71.81% share of the Australia beauty and personal care products market size in 2026. In September 2026, Coles launched more than 100 new skincare products nationally, including Korean skincare. That supermarket expansion illustrates how the largest segment can offer greater product variety through an additional distribution setting. Suppliers can use such access to introduce a defined skincare proposition within a broad retail assortment, with the product's function carrying the explanation. A supermarket listing can put skincare trial into a shopping trip that serves other product categories, so mass skincare can be discovered during unrelated grocery trips rather than sought out.
Premium products are forecast to be the fastest-growing category segment, at a 6.05% CAGR over 2027-2032. MECCA welcomed more than 40 brands to its Australia and New Zealand portfolio in 2025, including Victoria Beckham Beauty. MECCA positions Victoria Beckham Beauty as a luxury makeup and skincare line. Winning MECCA's listing would place a premium entrant among a growing set of ranges, making retailer attention a separate commercial hurdle from gaining distribution.
By Nature: Conventional Scale and Selective Organic Expansion
Conventional products represented a 70.91% Australia beauty and personal care products market share in 2026. The largest segment's revenue base gives retailers a reason to organize conventional assortments around distinct care tasks, such as oral care, hair washing, body cleansing, and routine facial care. Suppliers can use the application as the starting point for a range brief, with separate products justified by the task they deliver and the way they are used. An unserved everyday care task would leave a conventional supplier absent from part of the largest revenue pool, making portfolio coverage a concrete competitive choice.
Organic products are forecast to be the fastest-growing segment by nature, at a 6.68% CAGR over 2027-2032. This creates an allocation decision for retailers considering how much assortment space to add for organic choices within existing personal care uses. A selective rollout can introduce organic alternatives for particular care tasks while keeping the formulation's organic classification separate from its mass or premium price position. Which care tasks earn organic lines is a shelf-space decision for retailers, not a commitment to mirror the full conventional range.
By Distribution Channel: Store Access and Digital Household Reach
Health and beauty stores were the largest distribution channel, with 37.88% of the market in 2026. MECCA reported that an average of 50,000 customers walked through its Melbourne Bourke Street flagship each week in 2025. Such concentrated foot traffic can give brands an opportunity to reach shoppers through an existing retailer relationship, without operating their own standalone physical selling location. Inside a specialty store with demonstrated foot traffic, a new brand competes for visibility before it can turn that traffic into product sales.
Online retail channels are forecast to be the fastest-growing distribution segment, at a 6.78% CAGR over 2027-2032. Australia Post reported that 3.6 million Australian households shopped online for beauty products in 2025. A direct storefront or retailer platform can aggregate consumer access without requiring a physical counter for every local shopping catchment. Other channels include pharmacies, where customers surveyed by Fonto in the June 2025 quarter listed cosmetics and personal care among items they might otherwise have bought at supermarkets. Online platforms broaden household reach for beauty shoppers, while pharmacies draw purchases that might otherwise have gone to supermarkets.
Geography Analysis
Australia Post reported that Australia's capital-city areas together generated most online beauty spending in 2025. In July 2025, W Cosmetics reported a new store in Strathfield, New South Wales, expanding its beauty retail footprint in the Sydney area. Together, digital concentration and a suburban store addition support an urban distribution strategy that combines broad online reach with physical access in a specific shopping catchment. The suburban Sydney addition gives brands a physical selling point within the capital-city catchment where online beauty spending already concentrates.
Melbourne's beauty retail development illustrates the destination-store alternative for brands seeking a concentrated physical presence. MECCA opened a 3-level flagship at 299 Bourke Street on August 8, 2025, bringing together more than 200 global beauty brands. Putting this brand breadth into one location can support cross-brand discovery and give a supplier access to an assortment-led selling environment. The format makes product presentation part of the competitive relationship between retailer and brand, because an individual range must remain distinguishable within a large selection. One destination-store relationship can offer a brand concentrated exposure, while placing its product directly alongside a large collection of beauty propositions.
The Bureau of Meteorology classifies the Red Centre mainly as desert, while coastal regions at similar latitudes are subtropical or grassland. Cancer Council Australia recommends daily sunscreen use when the UV Index is forecast to be 3 or above. Sunscreen suppliers serving either setting have a shared communication trigger in the daily UV forecast, rather than the climate-zone label.
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of cosmetic formulators and commercial importers operating in Australia. The comparison separates national chemical-introduction duties, applicable in Victoria, from the state's additional conditional permit for obtaining a particular scheduled substance for cosmetic use. Since June 27, 2026, Australian commercial importers and manufacturers have needed an AICIS assessment certificate before introducing consumer-use retinal, while retinal already in Australia may continue to be sold and used. Cosmetics industry association Accord Australasia applied on October 13, 2026, for a certificate covering participating companies, with a decision expected by late January 2027 but potentially later.
Regulatory Table
| Decision factor | Australia | Victoria |
|---|---|---|
| Primary authority | Australian Industrial Chemicals Introduction Scheme and Therapeutic Goods Administration | Department of Health Medicines and Poisons Regulation |
| Key instruments or direction | AICIS registration and retinal assessment-certificate requirements | Schedule 7 permit control for obtaining 2-nitrotoluene for cosmetic use |
| Commercial effect | Register for the registration year before chemical introduction and secure a certificate for commercial consumer-use retinal introductions | Obtain the poisons permit when acquiring the substance for cosmetic use under its Schedule 7 classification |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | No change |
| Source: Mordor Intelligence | ||
Australia's Medium rating reflects the registration and ingredient-specific certificate requirements facing formulators and commercial importers. The Hardening direction reflects the TGA's proposal for November 2026 consideration of Schedule 4 treatment above 0.05% retinol equivalents in body lotions and 0.3% in other topical vitamin A products. Victoria's Medium rating reflects the permit burden for obtaining 2-nitrotoluene for cosmetic use when it is a Schedule 7 poison. Victoria's No change direction describes only this additional permit under the October 2026 classification, while the proposed national vitamin A scheduling change would also affect Victorian formulators if adopted.
Value Chain Stages
The value chain compares the capabilities and supplier earnings associated with turning a product brief into a consumer sale. Ausmetix formulates and manufactures skincare, haircare, and bodycare for brands, while Trulux combines development with manufacturing, filling, and packaging services for small and medium-sized businesses. These capabilities allow a brand to contract for several connected activities without owning each production step. The commercial distinction is between earning from technical execution and earning from access to professional or consumer buyers.
Value Chain Analysis Table
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Product development and formulation | Formulators such as Ausmetix and Trulux | Formulation and development fees | Converting a brand brief into a reproducible formula | Resolve formula specifications before production transfer |
| Manufacturing, filling, and packaging | Contract manufacturers such as Delta Laboratories and Trulux, with filling and packaging by Trulux | Contract production, filling, and packaging revenue | Maintaining consistency across formula and finished pack | Link production specifications with filling and packaging controls |
| Professional wholesale supply | Salon-product wholesalers such as Beauty Warehouse | Wholesale product sales | Handling differing requirements across a mixed professional range | Organize fulfillment around product-specific handling needs |
| Consumer retail | Beauty retailers such as MECCA | Consumer product sales | Coordinating product information across stores and ecommerce | Maintain consistent product descriptions across selling channels |
| Source: Mordor Intelligence | ||||
The combination of technical services makes production coordination a potential source of supplier value. For small and medium-sized brands, Trulux's connected development, filling, and packaging services can reduce the number of separate production handoffs. Beauty Warehouse's professional wholesale role and MECCA's stores and ecommerce represent different routes toward buyers. A bundled production contract would concentrate technical-service earnings with the contractor, while leaving wholesale and retail sales to the businesses that organize buyer relationships.
Competitive Landscape
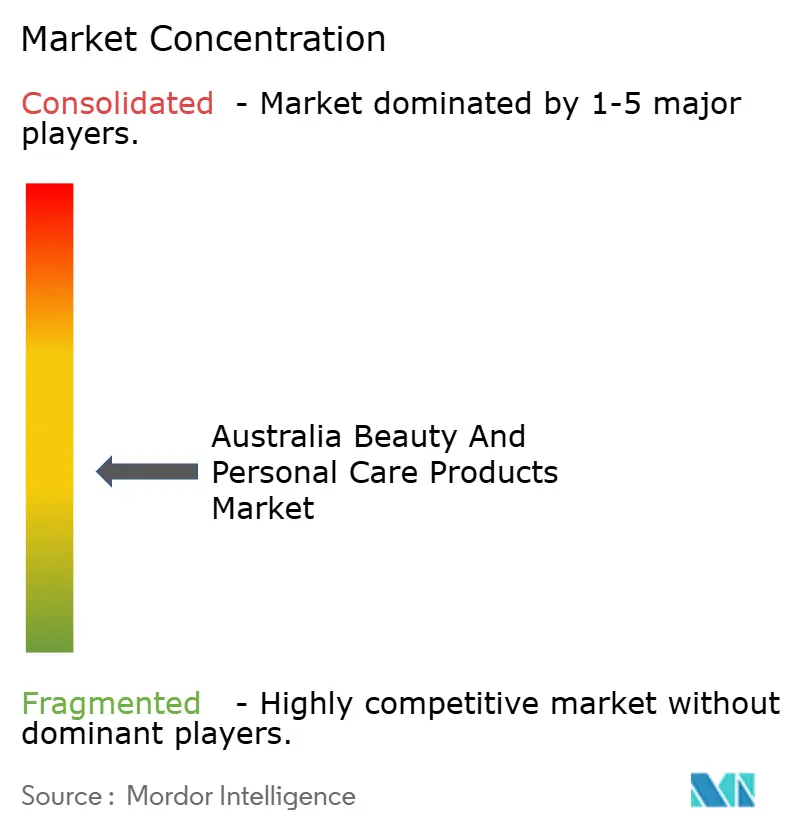
Competition is spread across major brand owners Colgate-Palmolive Co., Unilever PLC, L'Oréal S.A., Procter & Gamble Co., and Kenvue Inc. Colgate-Palmolive, an oral care and personal care producer, reported global total-company net sales of USD 20.38 billion in 2025, up 1.4% from 2024. P&G serves Australia and New Zealand with Pantene haircare, Olay skincare, and Gillette grooming products. In September 2026, Unilever Australia's Dove launched Advanced Care deodorants in aerosol and roll-on formats through Coles, Woolworths, Chemist Warehouse, and independent retailers nationwide. These portfolios make competition category-specific, since a retailer's choice of haircare or oral care products can depend on product capabilities and suitability for a particular use alongside corporate scale.
Sales in L'Oréal's global Professional Products and Dermatological Beauty divisions grew 7.5% and 5.5%, respectively, on a like-for-like basis in 2025. Both outpaced Consumer Products at 3.5% and L'Oréal Luxe at 2.8% on the same global like-for-like basis. L'Oréal also reported very strong growth in its combined Australia and New Zealand cluster in the first half of 2026. At group level, Dermatological Beauty's 5.5% like-for-like growth, ahead of L'Oréal Luxe at 2.8%, shows where the group's 2025 momentum sat in skincare.
Kenvue's Australian portfolio includes Listerine oral care and Neutrogena and Aveeno skin and beauty care. During the first quarter of 2026, the company began rolling out a new Listerine oral care range in select markets as part of a global restage of the brand. The Australian portfolio gives retailers a choice between established oral care and skin-focused brands within one supplier relationship. Commercial imports of retinal-containing skincare require an AICIS assessment certificate before introduction, while retinal already in Australia may continue to be sold and used.
Australia Beauty And Personal Care Products Industry Leaders
-
Colgate-Palmolive Co.
-
Unilever PLC
-
L'Oréal S.A.
-
Procter & Gamble Co.
-
Kenvue Inc.
- *Disclaimer: Major Players sorted in no particular order
Key Opportunities for Market Participants
The opportunities compare ways to develop beauty and personal care product sales through repeat ordering, cosmetics discovery, and store-linked fulfillment. Australian online spending on beauty products grew 15.7% year over year in 2025. Australia Post also reported that 29% of online beauty purchases were sent by same-day or next-day delivery in 2025. These channel conditions support testing product-selection services alongside faster fulfillment.
Market Opportunities Table
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Repeat ordering for familiar personal care products | Expanding online beauty spending provides a broader selling channel | Routine personal care users | Offer optional repeat orders for familiar products | Delivery cost relative to order value | Personal care brands with direct storefronts |
| Clearer cosmetics selection online | Digital beauty activity supports testing more informative product presentation | Cosmetics shoppers making a first product choice | Provide consistent shade descriptions and application guidance | Uncertainty about appearance before use | Cosmetics brands able to explain product differences |
| Store-linked express beauty fulfillment | Fast delivery formed part of beauty purchasing in 2025 | Online buyers seeking prompt product replacement | Offer a priced express service within viable store catchments | Reliable dispatch coverage | Beauty retailers able to fulfill from stores |
| Source: Mordor Intelligence | |||||
The central opening is store-linked express fulfillment, building on delivery speeds already used in online beauty purchasing. A retailer offering this service would need to match delivery promises to the stock and dispatch capacity of each participating store. Repeat ordering and clearer shade guidance are complementary service proposals, while fulfillment speed has a measured operating precedent.
Recent Industry Developments
- Oct 2026: Accord Australasia, the cosmetics industry association, lodged a group application for an AICIS retinal assessment certificate on October 13, covering participating companies if approved. A decision was expected by late January 2027 but could take longer.
- Sep 2026: Coles launched more than 100 new skincare products nationally, including Korean skincare.
Research Methodology Framework and Report Scope
Market Definition and Coverage
The Australia beauty and personal care products market measures annual retail spending on finished personal care and cosmetics products sold to consumers in Australia. It covers these products across mass and premium price tiers, organic and conventional formulations, and retail distribution channels.
Scope exclusions: Household surface and laundry cleaning products, salon and spa service fees, separately sold beauty tools and devices, and wholesale and distributor transfers before consumer retail sale are excluded.
Segmentation Overview
- By Product Type
- Personal Care Products
- Hair Care
- Shampoo
- Conditioners
- Other Products
- Skin Care
- Facial Care Products
- Body Care Products
- Lip Care Products
- Bath and Shower
- Shower Gels
- Soaps
- Other Products
- Oral Care
- Toothbrushes
- Toothpaste
- Mouthwashes and Rinses
- Other Products
- Men's Grooming Products
- Deodorants and Antiperspirants
- Hair Care
- Cosmetics Products
- Colour Cosmetics
- Facial Make-up Products
- Eye Make-up Products
- Lip and Nail Make-up Products
- Colour Cosmetics
- Personal Care Products
- By Category
- Mass
- Premium
- By Nature
- Organic
- Conventional
- By Distribution Channel
- Supermarkets/Hypermarkets
- Health and Beauty Stores
- Online Retail Channels
- Other Channels
Data Sources, Market Sizing, and Validation
Desk Research
Sources such as Australian Bureau of Statistics population estimates and retail-trade series, and Australia Post eCommerce reporting, help frame changes in the consumer base, household retail activity and online beauty purchasing. Sources such as the Senate Legal and Constitutional Affairs Legislation Committee's report on the Customs Legislation Amendment (False Trade Marks Infringement Notices) Bill 2026 inform counterfeit-goods risk context, and these sources are used to test whether reported market drivers fit Australian consumer retail conditions.
Company annual reports, Australian Securities Exchange filings, retailer announcements and reputable Australian trade coverage can supplement these public indicators with product launches, channel changes and financial context. Analysts compare those disclosures with official statistics and category evidence, and the named sources are not exhaustive, with further sources informing collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured questionnaires can include Australian manufacturers, brand owners, importers, pharmacy and beauty retailers, and ecommerce category specialists, with questions matched to the respondent's role in product sales, pricing, assortment and channel activity. Analysts use those discussions to check secondary evidence and explain gaps in product and channel splits, then triangulate any conflicting answers against company disclosures, retail indicators and other independent sources before incorporating a finding.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | |
| Mid tier: 48% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
The analyst estimates the Australian market top down from national consumer retail spending on finished personal care and cosmetics, then allocates value across product type, mass and premium category, organic and conventional nature, and distribution channel using available retail indicators, company disclosures and channel evidence. Population and household growth indicate the potential customer base, ABS retail turnover helps track retail demand, Australia Post's beauty shopping-household and online-spending measures inform channel development, and product price and mix evidence helps distinguish spending growth from changes in the assortment sold. Multivariate regression can relate these indicators to historical market value where consistent observations are available, with scenario analysis used when a structural change or short series makes a single trend unreliable. Segment shares are built from reported category sales, retailer assortment and channel evidence, and are checked for consistency with the total, and selective bottom-up checks use supplier revenue roll-ups and sampled average selling prices times estimated retail volume, with gaps reconciled against the top-down total and documented evidence. Primary respondents can test whether the selected indicators and segment assumptions reflect Australian product pricing, consumer demand and route-to-market conditions, while unresolved gaps are carried as ranges for analyst review rather than filled with unsupported precision.
Data Validation & Update Cycle
Analysts triangulate the market estimate against independent signals such as ABS retail activity, population change, company disclosures and Australia Post's online beauty measures, then investigate unusual movements and large variances between sources or adjacent periods. A second analyst reviews definitions, calculations, segment totals and source dates, after which the lead reviewer resolves documented exceptions before sign-off, and respondents are re-contacted when their answers conflict materially with public evidence or leave a decision-critical product or channel gap. The model is refreshed annually, updated between cycles when material market or regulatory events change the evidence, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Australia Beauty and Personal Care Products Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Australia beauty and personal care products market measures annual retail spending on finished personal care and cosmetics products sold to consumers in Australia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The analyst estimates the Australian market top down from national consumer retail spending on finished personal care and cosmetics, then allocates value across product type, mass and premium category, organic and conventional nature, and distribution channel using available retail indicators, company disclosures and channel evidence.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 9.77 B (2027) | |
| Global Consultancy A | USD 11.07 B (2025) | At its 2025 base, this estimate is 13.3% above this report's 2027 value of USD 9.77 B, 2 years later. The estimate includes fragrances and perfumes, which are outside this report's product boundary and can raise the reported total. |
| Regional Consultancy B | USD 8.2 B (2025) | At its 2025 base, this estimate is 16.1% below this report's 2027 value of USD 9.77 B, 2 years later. Its lower stated annual forecast rate over 2025-2030 contributes downward pressure on the 2025-to-2027 comparison, while fragrance inclusion acts in the opposite direction. |
Mordor Intelligence's analysts triangulate the market estimate against independent signals such as ABS retail activity, population change, company disclosures and Australia Post's online beauty measures, then investigate unusual movements and large variances between sources or adjacent periods.
Key Questions Answered in the Report
What is the Australia beauty and personal care products market size and growth outlook?
The market is expected to reach USD 9.77 billion in 2027 and USD 12.72 billion by 2032, with a 5.42% CAGR over 2027-2032.
What is driving demand for beauty and personal care products in Australia?
Digital research and wider participation in men's skincare routines support demand. Australia Post's 2025 survey found that 18% of consumers used AI to research beauty products online.
Which product type leads Australian beauty and personal care sales?
Personal care products held 85.31% of the market in 2026. Cosmetics products are forecast to grow fastest at a 5.52% CAGR over 2027-2032.
Which companies are major participants in Australia's beauty and personal care industry?
Major players include Colgate-Palmolive Co., Unilever PLC, L'Oréal S.A., Procter & Gamble Co., and Kenvue Inc.
What challenges affect the outlook for Australian beauty brands?
Product-claim failures can interrupt sales and add recall costs. In 2025, 20 sunscreens made with Wild Child Laboratories' base formulation were recalled after failing their SPF claims.
How does beauty retail development differ between Sydney and Melbourne?
In Sydney, W Cosmetics added a suburban Strathfield store in July 2025, while MECCA opened its 3-level Bourke Street flagship in Melbourne in August 2025.