
Pharmaceutical Manufacturing Market Size and Share
Pharmaceutical Manufacturing Market Analysis by Mordor Intelligence
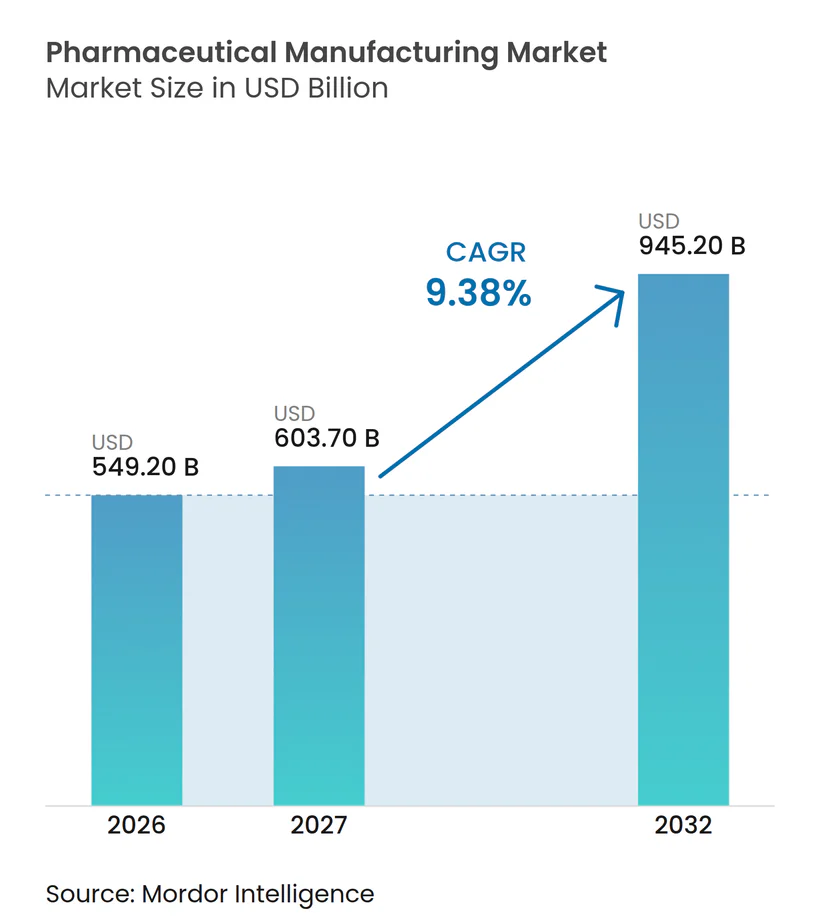
The pharmaceutical manufacturing market size is projected to expand from USD 549.2 billion in 2026 and USD 603.7 billion in 2027 to USD 945.2 billion by 2032, registering a CAGR of 9.38% between 2027 and 2032.
Research investment and biosimilar entry increase the importance of translating development work into reproducible medicines. For device-based injectable medicines, drug-substance supply must be matched to filling and delivery-device capabilities. Localization in India can widen ingredient-sourcing options, while contract manufacturing and owner-controlled sites offer different ways to coordinate the production chain. US building standards and India's pharmaceutical quality-system duties make manufacturing readiness part of the expansion decision. Producers adding injectable capacity therefore face two linked tests, securing ingredients for additional doses and earning a return under US drug-pricing pressure.
Key Report Takeaways
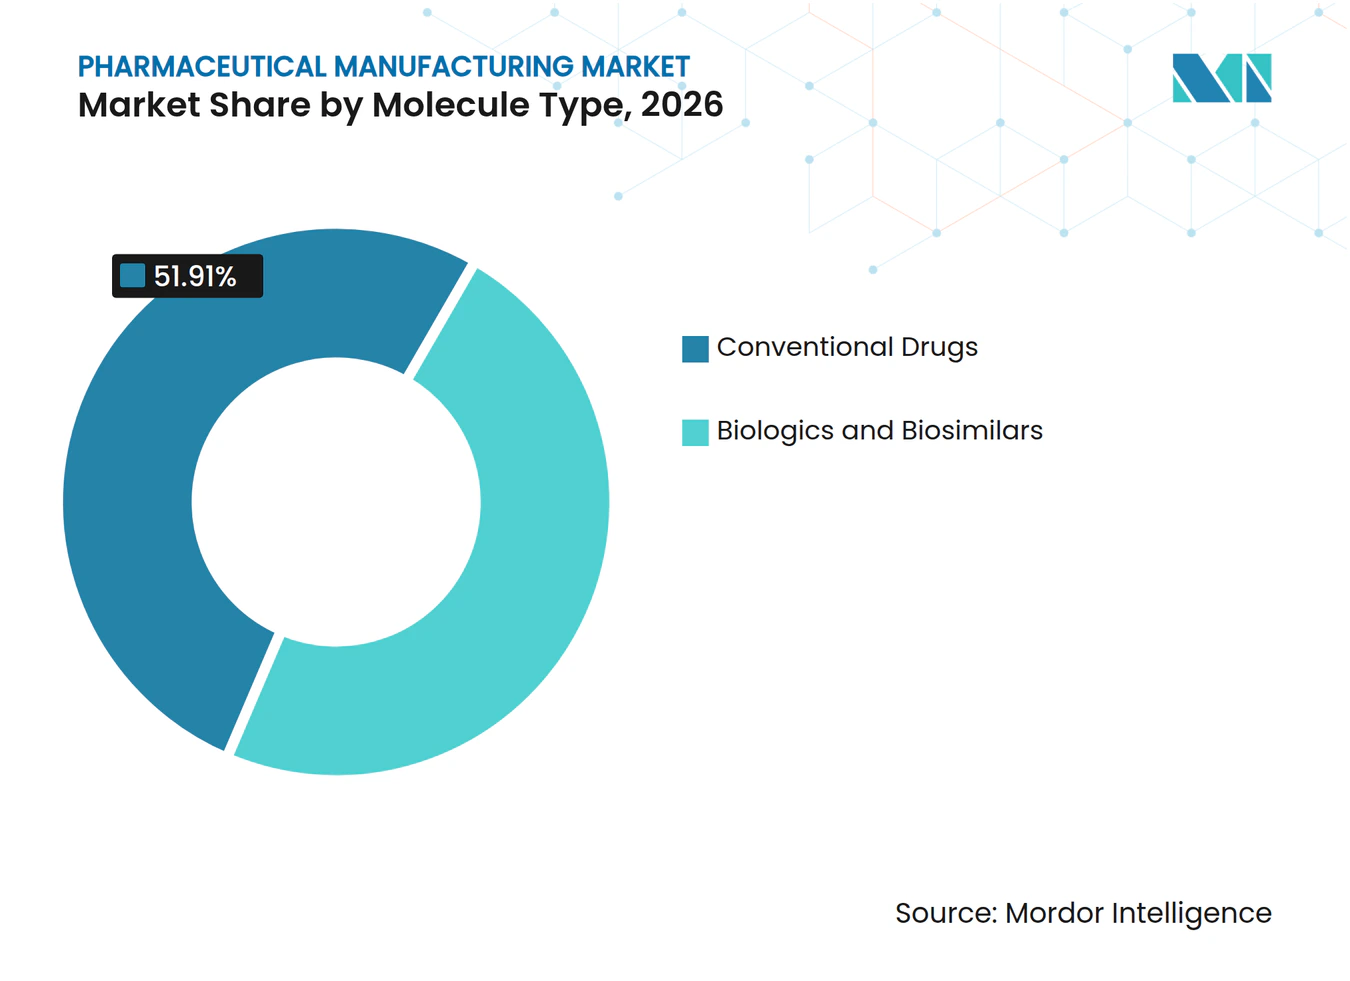
- Molecule type was led by conventional drugs, with a 51.91% pharmaceutical manufacturing market share in 2026, while biologics and biosimilars are forecast to grow fastest at a 10.08% CAGR during 2027-2032.
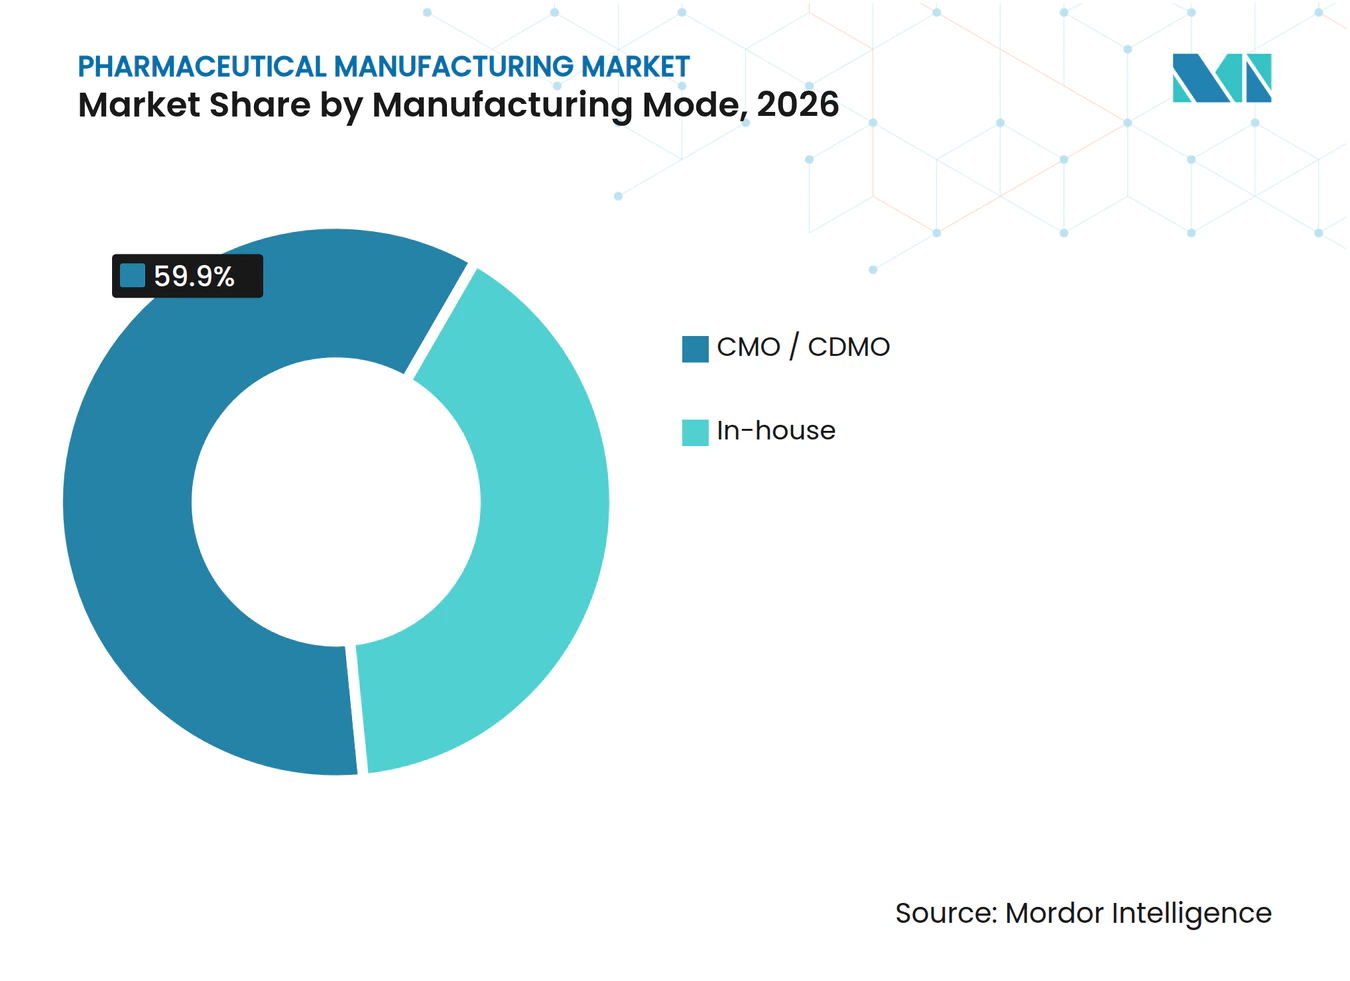
- Manufacturing mode was led by CMO / CDMO production, which held a 59.9% share of the pharmaceutical manufacturing market size in 2026 and is forecast to grow fastest at a 10.12% CAGR during 2027-2032.
- By formulation, tablets accounted for 30.88% of revenue in 2026, and injectables are forecast to grow fastest at an 11% CAGR during 2027-2032.
- Batch manufacturing led the technology breakdown with a 71.46% share in 2026, while continuous manufacturing is the fastest-growing segment, with a 10.7% CAGR forecast for 2027-2032.
- Oncology led applications with a 29.91% share in 2026 and is forecast to be the fastest-growing segment, at an 11% CAGR during 2027-2032.
- Prescription medicines led prescription type with an 85.67% share in 2026, but OTC medicines are forecast to grow fastest at a 10.9% CAGR during 2027-2032.
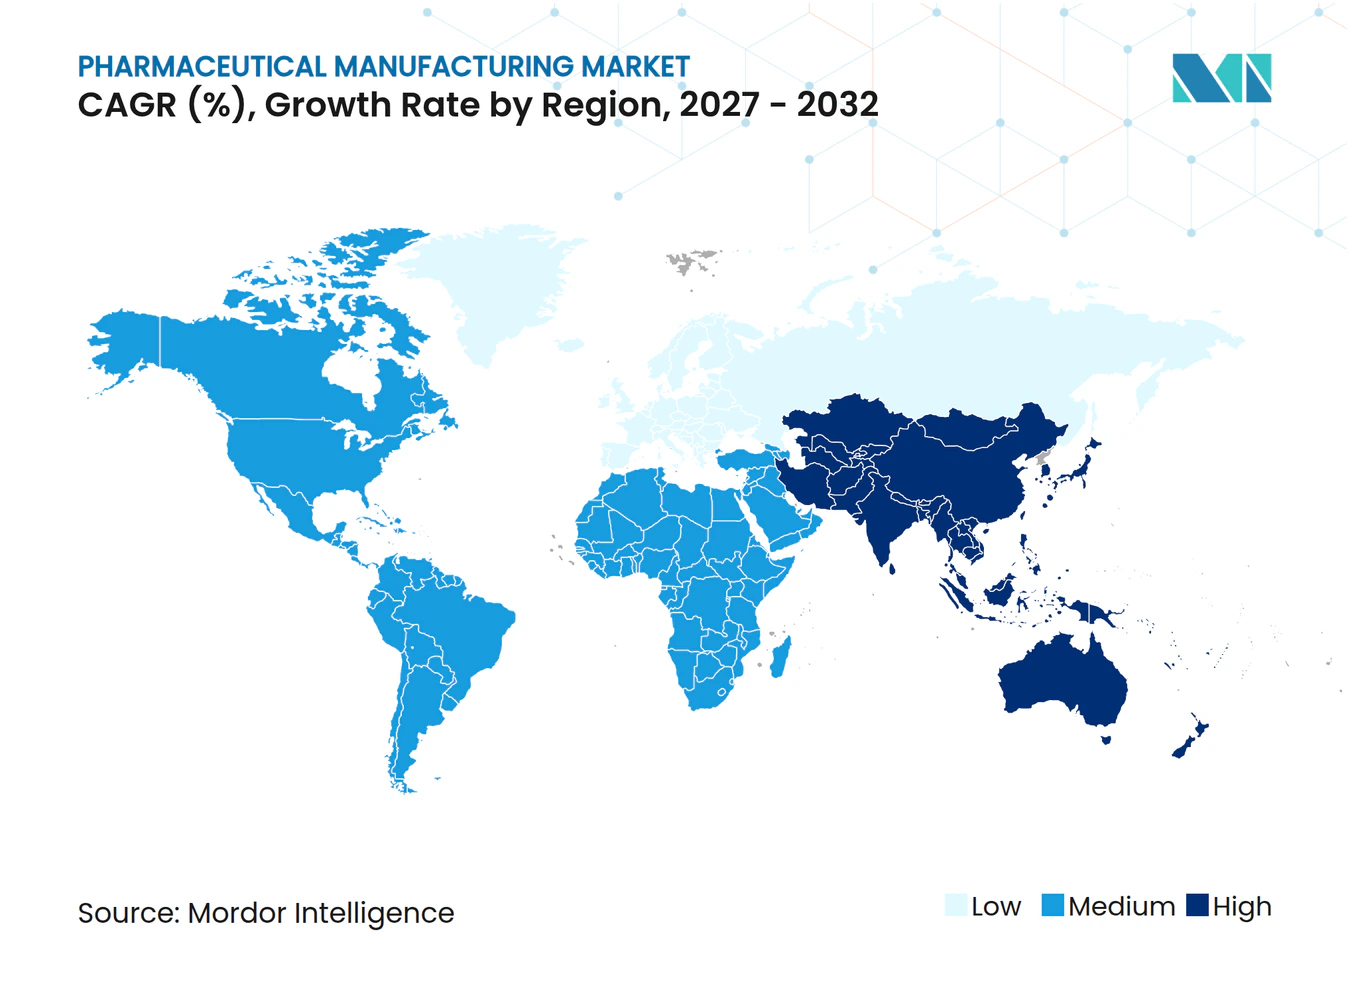
- Across geographies, North America held a 36.41% share in 2026, while Asia-Pacific is forecast to grow fastest at a 10.6% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Pharmaceutical Manufacturing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising R&D investments by Big Pharma | +3.7% | United States, Denmark, France, China and Brazil | Medium term (2-4 years) |
| Integration of AI-enabled Automation in Legacy Lines | +1.8% | North America, Europe and Asia-Pacific | Medium term (2-4 years) |
| Biosimilar surge after key patent cliffs | +3.9% | United States and European Union | Short term (≤ 2 years) |
| Reshoring & localization of API capacity | +2.4% | PLI-supported manufacturing sites in India | Medium term (2-4 years) |
| Decentralized micro-batch lines for personalized meds | +0.7% | European Union member states | Long term (≥ 4 years) |
| Heat- & solvent-free 3-D printing of tablets | +0.2% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising R&D investments by Big Pharma
Rising research budgets can increase manufacturing demand when funded medicines advance toward production. GSK plc's total research and development expense increased 18% at actual exchange rates in 2025 versus 2024, or 19% at constant exchange rates.[1] Novo Nordisk's 2025 R&D reorganization brought manufacturability and supply considerations earlier into drug development. For drug owners, earlier manufacturing input can make process requirements part of development choices instead of a later capacity decision. Bringing those decisions forward can advance demand for process-development work and capacity planning before a medicine reaches commercial production.
Integration of AI-enabled Automation in Legacy Lines
For an existing production line, the commercial test for an AI-enabled retrofit is whether it improves usable medicine output from equipment already in place. An AI-enabled retrofit adds analytics to equipment already installed, so its case rests on the extra specification-conforming output it releases from that equipment. A retrofit that increases specification-conforming output can support additional medicine supply while reducing the need for a comparable addition of physical capacity. Its contribution to manufacturing growth therefore depends on extra conforming units reaching sale. A producer facing added demand therefore measures the retrofit by the conforming units it adds to sellable supply from the existing building.
Biosimilar surge after key patent cliffs
Biosimilar manufacturing gains a concrete demand route when an authorized competitor becomes available to patients. The European Medicines Agency (EMA) reported 41 biosimilar approvals in the European Union in 2025, the highest annual number ever approved. On February 24, 2025, Biocon Biologics, a Biocon Limited subsidiary, launched YESINTEK (ustekinumab-kfce) as one of the first US Stelara biosimilar entrants. Approval activity widens the prospective product pipeline, while a launch establishes a specific medicine requiring supply beyond development work. Commercial readiness can therefore matter alongside biosimilar development progress because the competitive opening is entry into an existing treatment category with a reference medicine already established.
Reshoring & localization of API capacity
Under India's PLI Scheme for Bulk Drugs, production had commenced for 18 active pharmaceutical ingredients (APIs) by March 2026, reducing import dependence. The scheme had also created capacity for 28 APIs, key starting materials and drug intermediates, although 10 had not achieved commercial production by that date. This gap separates APIs that formulators can source from capacity projects awaiting commercial production. For drug formulators, localized production can provide an alternative source of active ingredients rather than merely another prospective plant. The demand effect therefore depends on converting investment into usable supply for finished medicines. Manufacturers able to complete that transition can compete for sourcing relationships that capacity announcements alone cannot secure.
Restraints Impact Analysis of Pharmaceutical Manufacturing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Global drug-pricing pressure & cost-containment | -1.9% | United States and China | Short term (≤ 2 years) |
| Critical-input supply-chain fragility | -0.9% | European Union member states | Medium term (2-4 years) |
| Shortage of GMP-grade recycled solvents | -0.3% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Cyber-security liability in connected plants | -0.2% | Medical-product manufacturing locations in the United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Global drug-pricing pressure & cost-containment
Drug-pricing pressure weakens the revenue available to support manufacturing even when medicines retain a treatment role. Merck & Co reported that global cost-containment efforts pressured pricing and market access in 2025, with government-mandated price reductions in several international markets.[2] Worldwide combined sales of its Januvia and Janumet fell 31% to USD 429 million in Q2 2026 versus Q2 2025. Merck & Co cited lower US demand and net pricing due to competition, alongside lower Chinese demand and generic competition in other international markets. These mechanisms affect both the value captured per sale and the volume requiring production, making additional capacity an incomplete response. For exposed manufacturers, lower net prices narrow cost recovery while weaker demand reduces the output over which production costs can be spread.
Critical-input supply-chain fragility
Concentrated input supply can constrain production even when finished-dose capacity is available. The European Commission's 2025 assessment found approximately 75% of chemical API production sites outside the EU, notably in India and China. Approximately 21% of the APIs analyzed had no EU production, limiting in-region alternatives if international supply chains are disrupted. Adding downstream capacity alone does not create an alternative source of ingredients. In the United States, Phlow and Fresenius Kabi agreed in February 2026 to supply API and finished doses, respectively, for Epinephrine Injection, USP, to US hospitals, pending approvals for possible 2027 availability. EU formulators therefore retain exposure to international input interruptions, while the conditional US timetable illustrates the lead time involved in establishing a replacement supply chain.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Pharmaceutical Manufacturing Market Segment Analysis
By Molecule Type:
Conventional Scale Meets Biologic ExpansionConventional drugs accounted for a 51.91% share of the pharmaceutical manufacturing market size in 2026. In its 2025 sustainability report, Hikma reported annual US capacity for more than 12 billion finished doses of essential medicines and a portfolio exceeding 800 products, including over 180 sterile injectable medicines. Hikma describes its US portfolio as generic medicines. This combination of dose scale and product breadth gives established manufacturers a production base serving multiple medicine requirements. Hikma's dose scale and portfolio breadth show conventional output depending on keeping many established medicines in continuous supply, which high-volume US plants make possible.
Biologics and biosimilars are the fastest-growing segment, with a projected 10.08% CAGR during 2027-2032. Complex modalities, including bi- and multispecific antibodies and antibody-drug conjugates, contributed more than half of WuXi Biologics' group revenue in H1 2026. Lonza's Integrated Biologics platform recorded 10% constant-currency sales growth in H1 2026 versus H1 2025. WuXi's revenue mix gives complex-modality expertise a direct role in serving its programs, while Lonza's sales result shows expansion in biologics development and manufacturing activity. Complex antibodies and antibody-drug conjugates need molecule-specific process capabilities, so WuXi Biologics' modality mix and Lonza's growth point to specialized suppliers rather than interchangeable capacity.



By Manufacturing Mode:
Commercial Execution Strengthens Contract ManufacturingCMO / CDMO production represented a 59.9% pharmaceutical manufacturing market share in 2026 and is the fastest-growing segment, with a 10.12% CAGR forecast during 2027-2032. WuXi Biologics' manufacturing revenue grew 26.4% in 2025 versus 2024, supported by project progression and the ramp-up of existing projects. Samsung Biologics also secured a manufacturing agreement with a European pharmaceutical company in Q4 2025. That agreement illustrates how drug owners can secure production services through a commercial relationship with a specialist provider. Providers capture the manufacturing opportunity when their capabilities remain relevant as projects move from development toward recurring production.
In-house manufacturing preserves a different form of control over linked production steps. In February 2026, Novo Nordisk reported US in-house Wegovy pill production, with active ingredients made at its Clayton, North Carolina, site and tablets made and packed at its Durham, North Carolina, site. This connects the same drug owner's upstream and finished-dose operations across separate sites. For a product owner, that arrangement can make the coordination of ingredient output, tablet manufacture and packing an internal operational decision. Manufacturing mode determines who coordinates the production chain, with in-house owners setting ingredient and tablet sequencing internally and outsourcing owners placing that coordination with providers.

By Formulation:
Tablet Capacity Supports Broader CommercializationTablets were the largest segment, accounting for a 30.88% market share in 2026. In September 2025, Biocon Generics Inc., a wholly owned Biocon Limited subsidiary, inaugurated its Cranbury, New Jersey, oral-solid-dosage facility with annual capacity for 2 billion tablets. Some products had already been commercialized from the site, with several more in the pipeline. Because products were already commercialized from the site and several more were in the pipeline, the 2 billion tablet capacity serves programs already in market and others still to launch.
Injectables are forecast to be the fastest-growing segment, with an 11% CAGR during 2027-2032. Hikma's European Injectables business grew 23% in 2025, with the company linking its regional service to local manufacturing, a short supply chain and a hospital-focused portfolio. In December 2025, the US Food and Drug Administration (FDA) approved Milestone Pharmaceuticals' CARDAMYST (etripamil) nasal spray for adult acute symptomatic paroxysmal supraventricular tachycardia (PSVT). The approval covers self-administration outside emergency departments or other health care settings. A producer choosing between hospital injectables and a self-administered nasal spray is also choosing which treatment setting its formulation can serve.
By Manufacturing Technology:
Platform Ownership Changes Production ChoicesBatch manufacturing was the largest segment, with a 71.46% market share in 2026. WuXi Biologics reported structural completion and key equipment arrival at its Chengdu microbial drug-substance and drug-product site on April 24, 2026. The site was designed for up to 110 drug-substance batches annually upon completion, with good manufacturing practice (GMP) release expected by the end of 2026. The physical milestone shows a committed buildout, while the prospective batch capacity places production scheduling at the center of the operating model. Batch operators need both the physical facility and the later release milestone to establish a customer-serving production base.
Continuous manufacturing is the fastest-growing segment, with a 10.7% CAGR forecast during 2027-2032. WuXi Biologics, a contract manufacturer, completed the first commercial process performance qualification campaign for 3 single-use bioreactors of 5,000 liters each on its Hangzhou drug-substance line in April 2025. Evotec completed the sale of its biologics site in Toulouse, France, to Sandoz and granted the buyer an indefinite license to Evotec's continuous manufacturing platform, effective December 5, 2025.[3] Combining site ownership with platform access gives a producer a way to internalize a specific manufacturing model through a completed commercial transaction. Buyers can choose between purchasing manufacturing services on a particular technology platform and owning and licensing the platform itself.
By Application:
Oncology Expansion Requires Specialized Input CapacityOncology led with a 29.91% market share in 2026 and is forecast to be the fastest-growing segment, at an 11% CAGR during 2027-2032. Lupin Manufacturing Solutions, a wholly owned Lupin Limited subsidiary and contract manufacturer, announced in November 2025 that it had commissioned a dedicated oncology high-potency API facility in Visakhapatnam, India. The upstream facility was equipped with 20 reactors and designed for batches of 1 to 35 kilograms. IQVIA reported that global oncology prescription medicine sales reached approximately USD 288 billion in 2025, measured at list prices rather than the manufacturer ex-factory net selling prices used for this report's segment values. Lupin's batch range of 1 to 35 kilograms lets the block supply high-potency oncology ingredients for client programs of different sizes, an upstream input to the finished oncology medicines the segment counts.
In diabetes, the commercial issue includes preserving affordable supply when manufacturing priorities change. The World Health Organization (WHO) reported in March 2026 that major suppliers were progressively shifting capacity from older human insulin products toward newer, more profitable treatments. Human insulin was the most affordable option in that account and was included on the WHO Model List of Essential Medicines. That creates a different investment question from adding production for newer treatments, because product availability depends on which medicines retain capacity. The manufacturing opportunity includes maintaining specific affordable insulin products alongside expanding the capabilities required for oncology's forecast growth.
By Prescription Type:
Nonprescription Access Creates Product-Specific OpeningsPrescription medicines were the largest segment, holding an 85.67% market share in 2026. In Italy, 66.9% of people assisted by the National Health Service received at least one medicine prescription in 2025, according to the Italian Medicines Agency (AIFA). IQVIA reported global prescription medicine sales of approximately USD 1.7 trillion in 2025, up 10% year on year, at list prices rather than this report's segment basis of manufacturer ex-factory net selling prices. The combination of global spending scale and broad national-system use gives established prescription producers a large supply base to serve, while nonprescription switches create a separate route to additional customers.
Over-the-counter (OTC) medicines are forecast to be the fastest-growing segment, with a 10.9% CAGR during 2027-2032. On May 22, 2026, the FDA approved Galderma's Differin Epiduo Acne Gel, containing adapalene 0.1% and benzoyl peroxide 2.5%, for US OTC use in people ages 12 and older. The prescription-to-OTC switch creates a nonprescription route for a specified formulation and age group. For manufacturers, the production opportunity centers on supplying the formulation covered by that access decision. A targeted switch can expand the accessible customer base while keeping the commercial opening tied to a precisely defined drug and label.
Geography Analysis
North America Pharmaceutical Manufacturing Market
North America held a 36.41% pharmaceutical manufacturing market share in 2026. In September 2025, FUJIFILM Biotechnologies, a contract manufacturing subsidiary of FUJIFILM Corporation, opened the first phase of its planned USD 3.2 billion commercial-scale cell-culture manufacturing site in Holly Springs, North Carolina. The opened phase included 8 mammalian cell-culture bioreactors, each 20,000 liters, with manufacturing scope spanning drug substance and drug product. The site's combination of large-scale cell culture and drug-product capability illustrates a supply base supporting North America's lead, with drug owners able to source both production stages within the region.
Asia-Pacific Pharmaceutical Manufacturing Market
Asia-Pacific is the fastest-growing geography, with a 10.6% CAGR forecast during 2027-2032. In October 2025, Lilly announced an INR 90 billion (USD 1 billion) investment to expand its contract manufacturing operations in Hyderabad, India. Duopharma Biotech increased sterile cephalosporin capacity at its Klang, Malaysia, facility from 600,000 to 800,000 vials per month starting in Q3 2025. The Indian announcement concerns contract-manufacturing expansion, while the Malaysian result shows a completed increase in capacity for a specific medicine category. Regional manufacturers face different expansion choices, with production partnerships and sterile-vial capacity offering separate paths into local manufacturing activity.
In Europe, Gedeon Richter Polska began expanding its medicine plant in Grodzisk Mazowiecki, Poland, in February 2025, estimating about 30% additional company production capacity. In the Middle East and Africa region, Jamjoom Pharma's Egypt facility produced 29 million units in 2025, up from 24.9 million in 2024. In South America, Brazil recorded 6.3 billion medicine packages sold across 14,371 presentations in 2025. Colombia's Gonher announced the opening of its Plant 3 and Plant 4 in Bogotá in June 2025. Gedeon Richter ties its Grodzisk Mazowiecki expansion to medicine security in Poland and Europe, while Brazil's broad presentation range makes supplying a varied medicine assortment a separate test for manufacturers.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of manufacturers establishing nonsterile finished-medicine capacity for local supply. Defined manufacturing-quality frameworks help investors plan while requiring substantive compliance preparation. Administrative changes can alter the route into production separately from the technical work needed to make compliant medicines.
Regulatory Table of Pharmaceutical Manufacturing Market
| Decision factor | United States | Germany | India | South Africa | Brazil |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration (FDA) | Competent state authorities | Central Drugs Standard Control Organisation (CDSCO) and State Licensing Authorities | South African Health Products Regulatory Authority (SAHPRA) | Agência Nacional de Vigilância Sanitária (Anvisa) |
| Key instruments or direction | 21 CFR Part 211; proposed Part 207 distributed-registration pathway from July 2026 | AMWHV; proposed GMP documentation, systems and AI guidance in the 2026-2028 program | Revised Schedule M GMP and pharmaceutical quality system | Act 101 of 1965, sections 22C(1)(b) and 22C(6); digital new-application route | RDC 658/2022 general medicine GMP |
| Commercial effect | Production and quality controls, excluding positron emission tomography drugs and medical gases; proposed registration consolidation for qualifying distributed arrangements | State manufacturing permit and GMP oversight; potential digital/AI preparation | Facility, plant, equipment and quality-system preparation | Manufacturing license and Authority-set quality/GMP conditions; mandatory digital new applications from September 1, 2026 | Quality system, validated critical processes, qualified personnel and records |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Easing | Hardening | No change | Easing | No change |
| Source: Mordor Intelligence | |||||
The US easing judgment reflects the July 2026 proposal to register equivalent units at multiple locations making the same drugs under one quality unit and unified pharmaceutical quality system as one establishment. Germany's hardening reflects proposed GMP documentation, computerized-system and AI guidance in the EMA's 2026-2028 program, while India's continuity reflects in-force Schedule M and the November 2025 inspection-preparation request. Brazil's nonsterile continuity rests on RDC 658/2022 general GMP, with Anvisa's sterile-rule review opened in December 2025 and its partial-impact-analysis dialogue announced September 11, 2026 for September 29. South Africa's mandatory September 1, 2026 digital application route retains fees, review and inspections, with renewals and amendments scheduled from October 1 and email submissions permitted for those applications.
Value Chain Stages
The comparison follows drug-substance production through formulation and filling to final labeling and packaging, illustrated by biologic manufacturing services. Conventional tablet production also links ingredient manufacture, dosage-form manufacture and packing, as Novo Nordisk's in-house operations demonstrate. Biocon Generics operates an oral-solid-dosage facility, while WuXi Biologics provides clinical- and commercial-scale biologic drug-substance and drug-product services. Value therefore accrues through both finished-medicine sales and contracted production work, with each operator's earnings depending on the steps it performs.
Value Chain Analysis Table of Pharmaceutical Manufacturing Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Biologic drug-substance production | Contract biologics manufacturers such as WuXi Biologics | Drug-substance manufacturing service revenue | Matching upstream scale to downstream requirements | Coordinate substance campaigns with drug-product capacity |
| Formulation and filling | Drug-product service providers such as WuXi Biologics | Formulation and filling service revenue | Aligning the fill process with the chosen container closure | Establish the product and container configuration before scheduling scale-up |
| Labeling and packaging | Pharmaceutical finishing providers such as WuXi Biologics | Labeling and packaging service revenue | Finishing schedules that lag filled-product availability | Link finishing slots to filling campaigns |
| Source: Mordor Intelligence | ||||
Integrated tablet production and contracted biologic services place successive stages under different commercial arrangements. An upstream expansion can increase the requirement for dosage-form manufacture and finishing without immediately increasing packaged-medicine output. For an integrated producer, coordinating those steps supports finished-medicine sales, while a service provider can earn additional fees by connecting its substance, filling and packaging work.
Competitive Landscape
Market Concentration
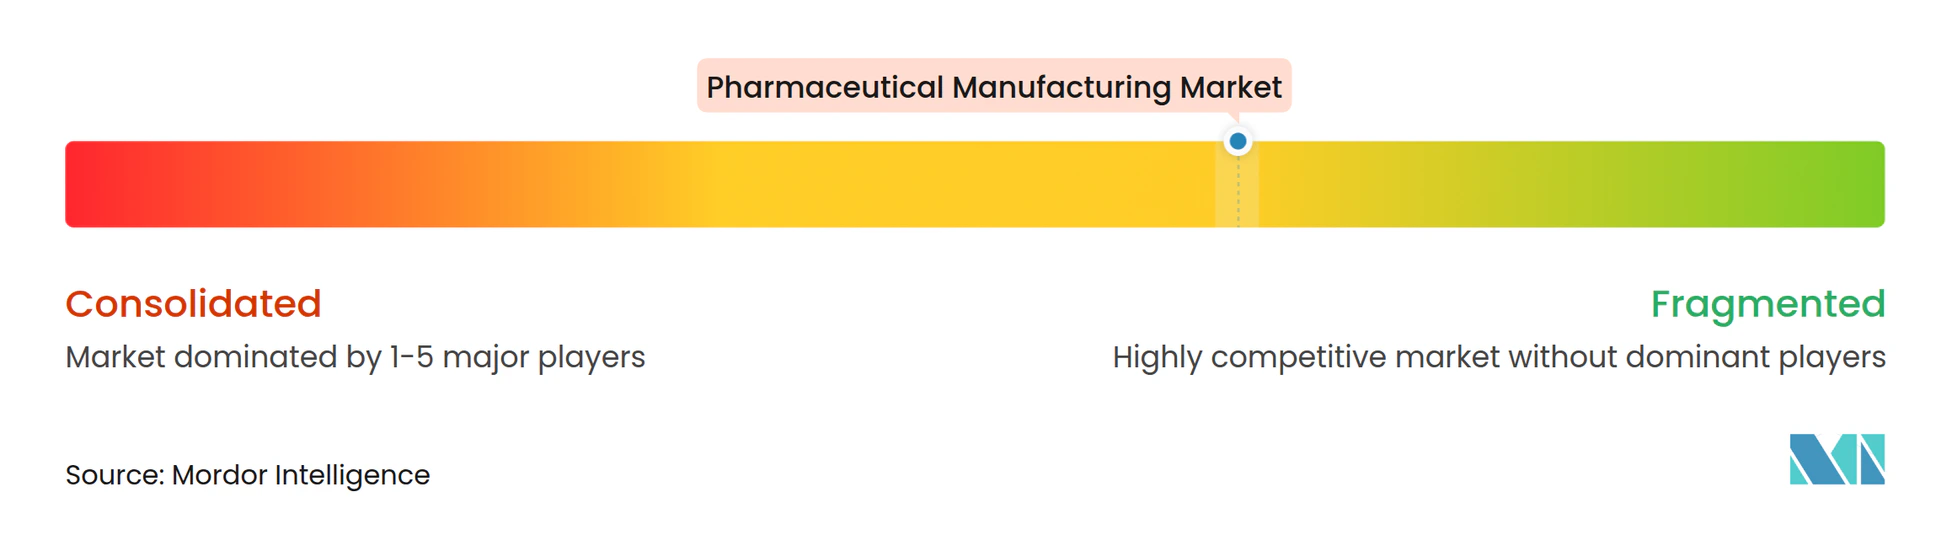
Several large integrated producers anchor competition across conventional medicines, biologics and multiple finished-dosage forms, with a wider field of manufacturers competing through distinct products and capabilities. Pfizer Inc, AstraZeneca plc, Sanofi SA, F. Hoffmann-La Roche AG and Lilly are among the principal pharmaceutical manufacturers. In its 2025 annual review, Pfizer reported about 45 billion doses of more than 500 medicines and vaccines annually for approximately 200 countries and territories. Network breadth can support multiple medicine requirements across markets, raising the commercial challenge for entrants whose manufacturing footprint and product coverage are more limited.
In July 2025, AstraZeneca announced a planned USD 50 billion US research and manufacturing program through 2030, including a proposed Virginia drug-substance facility. The facility was planned to make small molecules, peptides and oligonucleotides, spanning several molecular formats. In August 2026, Genentech, a Roche Group member, announced an approximately USD 750 million Hillsboro, Oregon, device fill-finish facility for injectable medicines and delivery devices, with operations expected in 2031. These plans address different production steps, so manufacturing differentiation can rest on molecular capability or a delivery-device process alongside the scale of investment.
In September 2026, Lilly broke ground on a planned USD 6.5 billion Houston facility for APIs for Foundayo and other small-molecule medicines and advanced therapies. Sanofi organizes chemistry, pharmaceutical and injectable sites into end-to-end clusters through regional and local industrial sites, and its dedicated Launch Sites cluster runs from API manufacturing to finished-goods packaging at Sisteron, Aramon, Ambarès and Scoppito. Under US 21 CFR 211.42(a), buildings used to manufacture, process, pack or hold a drug product must be of suitable size, construction and location to facilitate cleaning, maintenance and proper operations. That duty applies to Genentech's planned Hillsboro fill-finish facility, where operations are expected in 2031, tying future capacity to a building standard. Lilly's September 2026 Houston groundbreaking and Genentech's expected 2031 Hillsboro start represent future API and fill-finish capacity, contrasting with Sanofi's established API-to-packaging cluster.
Pharmaceutical Manufacturing Industry Leaders
-
Pfizer Inc
-
AstraZeneca plc
-
Sanofi SA
-
F. Hoffmann-La Roche AG
-
Lilly
- *Disclaimer: Major Players sorted in no particular order
Pharmaceutical Manufacturing Market Companies Covered in this Report
- Abbvie
- Amgen
- AstraZeneca
- BMS
- Boehringer Ingelheim
- Catalent
- Cipla
- GlaxoSmithKline
- Eli Lilly and Company
- Lonza Group
- Merck
- Novartis
- Novo Nordisk
- Pfizer
- Roche
- Sanofi
- Sun Pharmaceuticals Industries
- Takeda Pharmaceuticals
- Teva Pharmaceutical Industries
Key Opportunities for Market Participants
The comparison examines capital support and supply-resilience openings for finished-medicine manufacturers in the United Kingdom, European Union and United States. These openings connect manufacturing investment with funding availability, critical-medicine resilience and domestic supply development. The commercial distinction is whether an investor can use an active funding route or must develop a project around a prospective policy or supply-chain change. The value of these enablers depends on preparing compliant facilities and securing the ingredients needed for finished-medicine production.
Market Opportunities Table of Pharmaceutical Manufacturing Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| UK finished-medicine capacity investment | Life Sciences Innovative Manufacturing Fund capital grants stay open until allocation, subject to eligibility and GMP requirements | Manufacturers developing eligible UK human-medicine projects | Develop a GMP-ready finished-dose project with a qualifying capital plan | GMP preparation work and finite grant funding | Manufacturers with eligible UK finished-medicine projects |
| Resilient EU critical-medicine production | March 2025 Critical Medicines Act proposal includes prospective funding and faster procedures for designated projects | EU critical-medicine manufacturers | Prepare finished-dose projects built around resilient critical-medicine supply | Timing of legislative adoption and implementation | Manufacturers developing qualifying EU critical-medicine projects |
| Domestic US metoprolol tablet supply | API Innovation Center's March 2026 partnership expansion with its federal partner ASPR includes planned metoprolol tablets | US cardiovascular medicine supply, particularly metoprolol tablets | Pair domestic ingredient development with qualified finished-tablet manufacture | Ingredient-sourcing vulnerability reported for metoprolol in March 2026 | US finished-dose manufacturers; API Innovation Center as development participant |
| Source: Mordor Intelligence | |||||
The central opening is the conversion of supply-resilience priorities into manufacturable finished medicines. API Innovation Center identified the lack of a US-based metoprolol API source when announcing planned tablet development in March 2026. A domestic tablet project that also establishes an ingredient source would address the vulnerability where formulation capacity alone cannot.
Recent Industry Developments in Pharmaceutical Manufacturing Market
- Oct 2026: Bayer announced a planned USD 2.2 billion pharmaceutical manufacturing site in New Albany, Ohio, with expected drug-substance operations in 2031 and a planned drug-product module in 2034.
- Sep 2026: Lilly broke ground on a planned USD 6.5 billion Houston facility to make active pharmaceutical ingredients for Foundayo and other small-molecule medicines and advanced therapies.
- Aug 2026: Gilead Sciences broke ground on its planned Chess biologics facility in Foster City, California, with completion estimated by 2029.
Pharmaceutical Manufacturing Market Report Scope and Research Methodology
Market Definition and Coverage
The global pharmaceutical manufacturing market measures annual manufacturer revenue from finished pharmaceutical drug products produced in-house or by contract manufacturers worldwide. It values sales to the first independent customer at the ex-factory level.
Scope exclusions: Separately sold active pharmaceutical ingredients, excipients and other manufacturing inputs, standalone CMO/CDMO manufacturing service fees, downstream resale margins, and pharmaceutical research, development and clinical trial services are excluded.
Segments Covered in This Report
- By Molecule Type
- Biologics & Biosimilars
- Conventional Drugs
- By Manufacturing Mode
- In-house
- CMO / CDMO
- By Formulation
- Tablets
- Capsules
- Injectables
- Topical & Transdermal
- Nasal & Pulmonary Sprays
- Others
- By Manufacturing Technology
- Batch
- Continuous
- Single-Use
- By Application
- Oncology
- Diabetes
- Cardiovascular
- Neurology
- Respiratory
- Others
- By Prescription Type
- Prescription
- Over-the-Counter (OTC)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public and official sources such as the European Medicines Agency's good manufacturing practice guidance and eCFR's 21 CFR Part 211 establish regulatory requirements relevant to medicine manufacturing and finished pharmaceuticals. Anvisa's RDC 658/2022 questions and answers and the World Health Organization's World Local Production Forum publication provide regulatory and local-production context related to access to medicines. India's Press Information Bureau release on the pharmaceutical Production Linked Incentive scheme describes government incentives intended to promote domestic production and product mix, framing manufacturing policy and supply context.
Company annual reports, regulatory filings, investor presentations and reputable business press can supplement public production, revenue, capacity expansion and product-mix evidence, with each measure checked against the finished-product, first-sale boundary. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys can include pharmaceutical manufacturers, contract manufacturers, quality and operations leaders, and commercial or finance specialists with direct knowledge of finished-product sales and production economics. Respondents can test secondary estimates for market boundaries, regional mix, outsourcing and formulation patterns, while analysts resolve conflicting views against documented revenue and capacity evidence.
Where a segment or region lacks direct evidence, analysts can use public company disclosures, trade and regulatory statistics, and transparent proxies, recording assumptions for review. Interviews across manufacturers, buyers and technical functions can triangulate assumptions without relying on a single respondent type.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | APAC: 38% |
| Mid tier: 43% | Functional/Unit leaders: 35% | EMEA: 29% |
| Smaller Players: 25% | Managers: 45% | Americas: 33% |
Market-Sizing & Forecasting
The model estimates global revenue on a 2027 basis and projects annual value through 2032, using the finished-product sale at ex-factory value as its common basis. Analysts begin with a top-down estimate from pharmaceutical product revenue and manufacturing activity, then check selected totals with supplier revenue roll-ups and sampled product volume multiplied by manufacturer selling prices, excluding standalone service fees and downstream markups.
Key inputs include finished-drug revenue by molecule and formulation, manufacturer and contract-production revenue, therapy-area demand, production capacity and utilization, and regional medicine sales or export flows. These indicators help establish total value and segment shares by comparing each category's attributable finished-product revenue with the global total. Multivariate regression can relate revenue growth to medicine demand, capacity additions, outsourcing and mix shifts, with scenario analysis used when policy, patent or investment changes weaken historical relationships. Sparse supplier or country data can use disclosed regional proxies and alternative source checks. Technical, commercial and finance respondents can assess the drivers and variable-level forecasts, and disagreement can prompt review of inputs and scenario assumptions.
Data Validation & Update Cycle
Analysts triangulate the estimate against independent company revenue, regulatory and trade signals, capacity announcements and market-level sales evidence, then investigate variances in year, product boundary, currency and channel treatment. A second analyst reviews inputs and calculations, anomalies are resolved before sign-off, and respondents are re-contacted when a material boundary issue, conflicting operational signal or unexplained estimate change remains.
The model is refreshed annually, updated between cycles when material events change production or demand, and receives a fresh pre-delivery review of sources, calculations and narrative consistency.
Mordor Intelligence's Pharmaceutical Manufacturing Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global pharmaceutical manufacturing market measures annual manufacturer revenue from finished pharmaceutical drug products produced in-house or by contract manufacturers worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Key inputs include finished-drug revenue by molecule and formulation, manufacturer and contract-production revenue, therapy-area demand, production capacity and utilization, and regional medicine sales or export flows.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 603.7 B (2027) | |
| Global Consultancy A | USD 1.84 T (2025) | At its 2025 base, this estimate is 204.8% above this report's 2027 value of USD 603.7 B, 2 years later. |
| Industry Journal B | USD 1.77 T (2025) | At its 2025 base, this estimate is 193.2% above this report's 2027 value of USD 603.7 B, 2 years later. |
Mordor Intelligence's analysts triangulate the estimate against independent company revenue, regulatory and trade signals, capacity announcements and market-level sales evidence, then investigate variances in year, product boundary, currency and channel treatment.
Key Questions Answered in the Report
What is the pharmaceutical manufacturing market size outlook?
The size is projected to reach USD 945.2 billion by 2032, up from USD 603.7 billion in 2027, with a 9.38% CAGR between 2027 and 2032.
Which forces support pharmaceutical manufacturing demand?
Research investment, biosimilar entry and API localization support demand. Production had started for 18 APIs under India's bulk-drug scheme by March 2026.
Which molecule category leads pharmaceutical manufacturing revenue?
Conventional drugs led with a 51.91% share in 2026, while biologics and biosimilars are forecast to grow fastest, with a 10.08% CAGR during 2027-2032.
Which companies are major pharmaceutical manufacturers?
Major players include Pfizer Inc, AstraZeneca plc, Sanofi SA, F. Hoffmann-La Roche AG and Lilly.
What could constrain finished-medicine manufacturing growth?
Pricing pressure and concentrated inputs can constrain returns. Merck & Co reported pricing and market-access pressure from cost containment in 2025.
Which region leads pharmaceutical manufacturing, and where is growth fastest?
North America held 36.41% of the market in 2026. Asia-Pacific is the fastest-growing region, with a 10.6% CAGR forecast for 2027-2032.