
Digital Adult Content Market Size and Share
Digital Adult Content Market Analysis by Mordor Intelligence
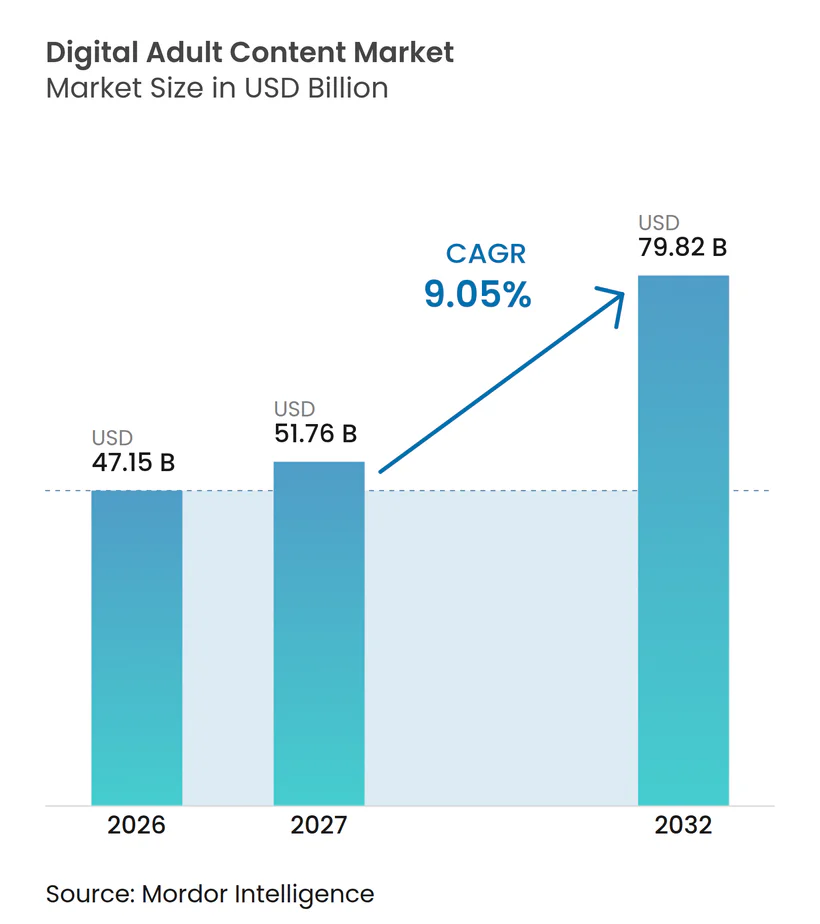
The digital adult content market size is estimated at USD 47.15 billion in 2026 and is projected to be USD 51.76 billion in 2027, reaching USD 79.82 billion by 2032, growing at a CAGR of 9.05% from 2027 to 2032.
As mobile reach expands, creator interaction gives video services a reason to charge for more than passive access. In the United Kingdom, covered publishers must apply highly effective age assurance before access unless users have already been determined adult, making access controls part of delivering paid video. Combining subscription streaming and individual purchases broadens content packaging, but age assurance and payment dependence complicate execution. Providers therefore compete on turning distinctive content into accessible paid experiences while sustaining the operating controls needed to serve adults lawfully.
Key Report Takeaways
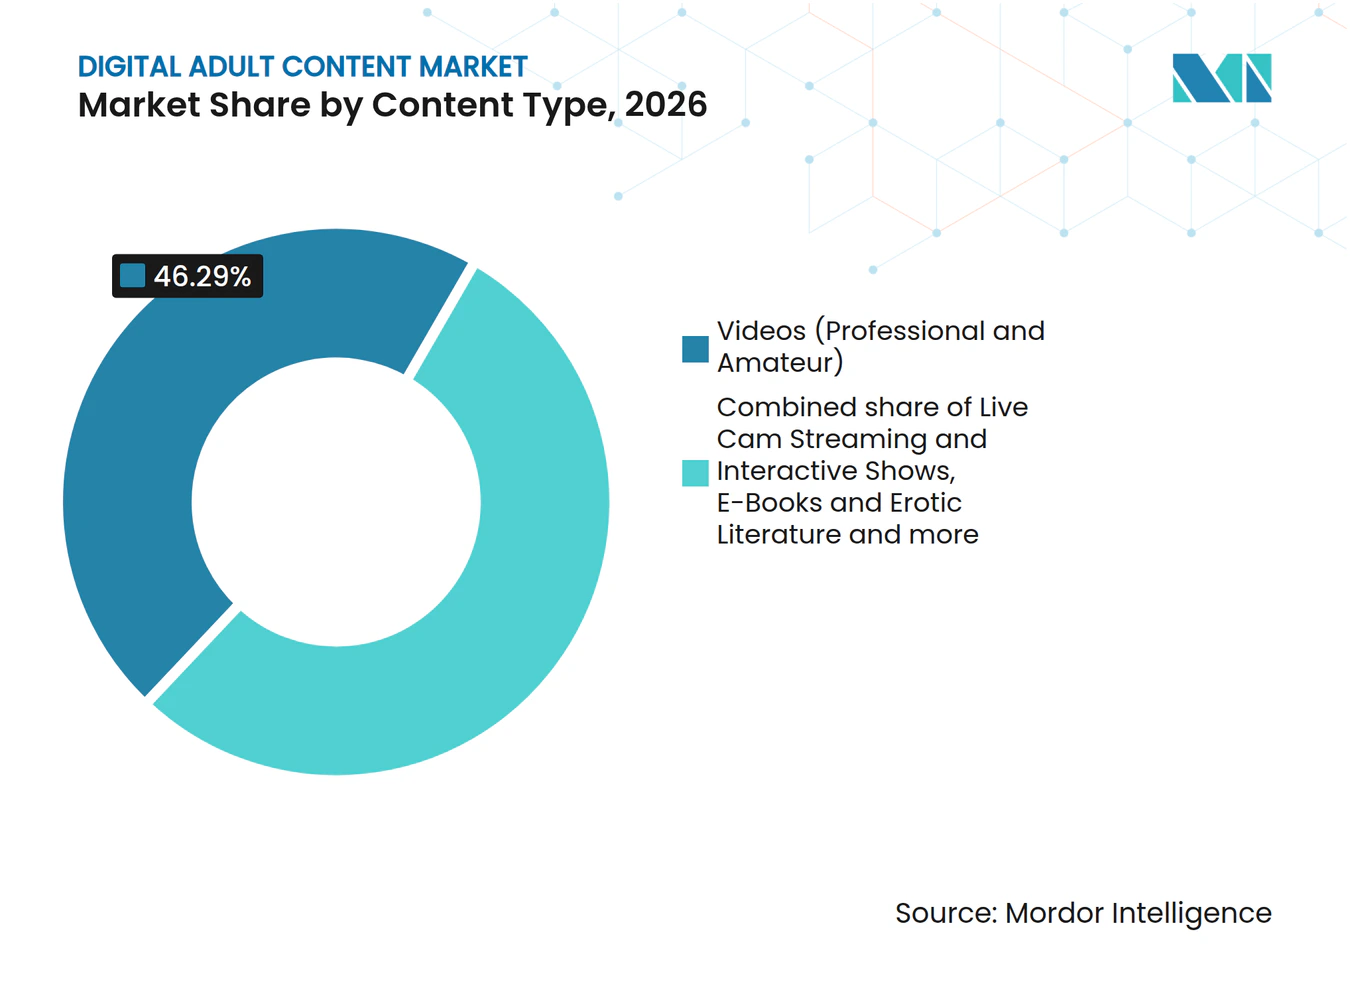
- By content type, videos (professional and amateur) held a 46.29% digital adult content market share in 2026, while virtual reality and immersive experiences are forecast to grow fastest at a CAGR of 13.2% from 2027 to 2032.
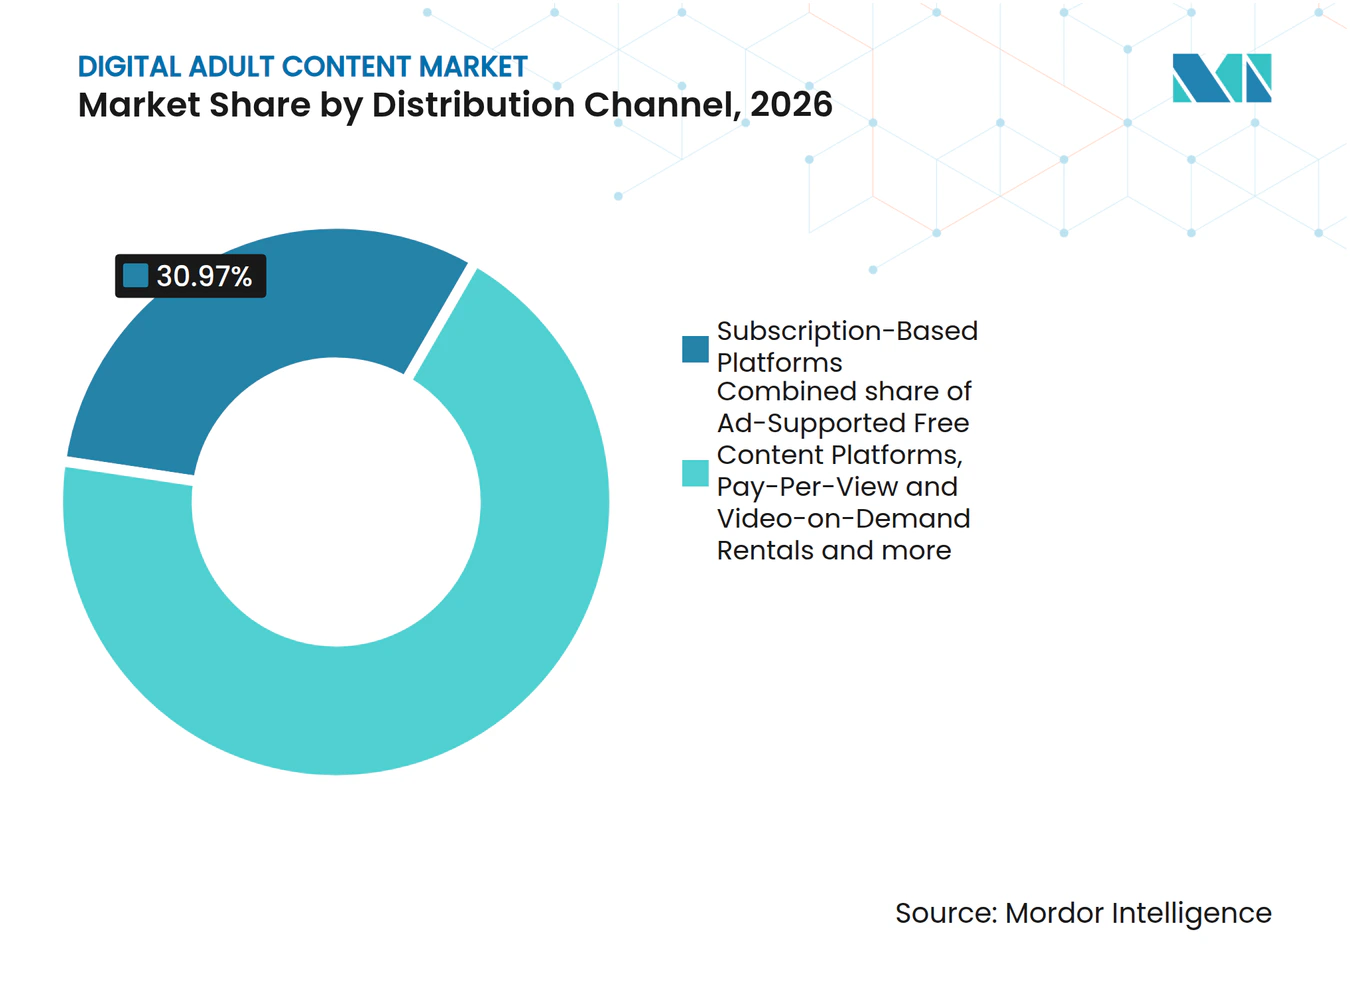
- Within distribution channels, subscription-based platforms accounted for a 30.97% share of the digital adult content market size in 2026, as direct-to-consumer creator and community platforms lead forecast growth at a CAGR of 12.9% from 2027 to 2032.
- Access devices were led by mobile smartphones with a 62.75% share in 2026, whereas gaming consoles and VR headsets are the fastest-growing segment at a forecast CAGR of 21.6% from 2027 to 2032.
- Across immersive technology levels, 2D standard content held a 79.11% share in 2026, with haptic-integrated and advanced immersive experiences forecast to grow fastest at a CAGR of 20.9% from 2027 to 2032.
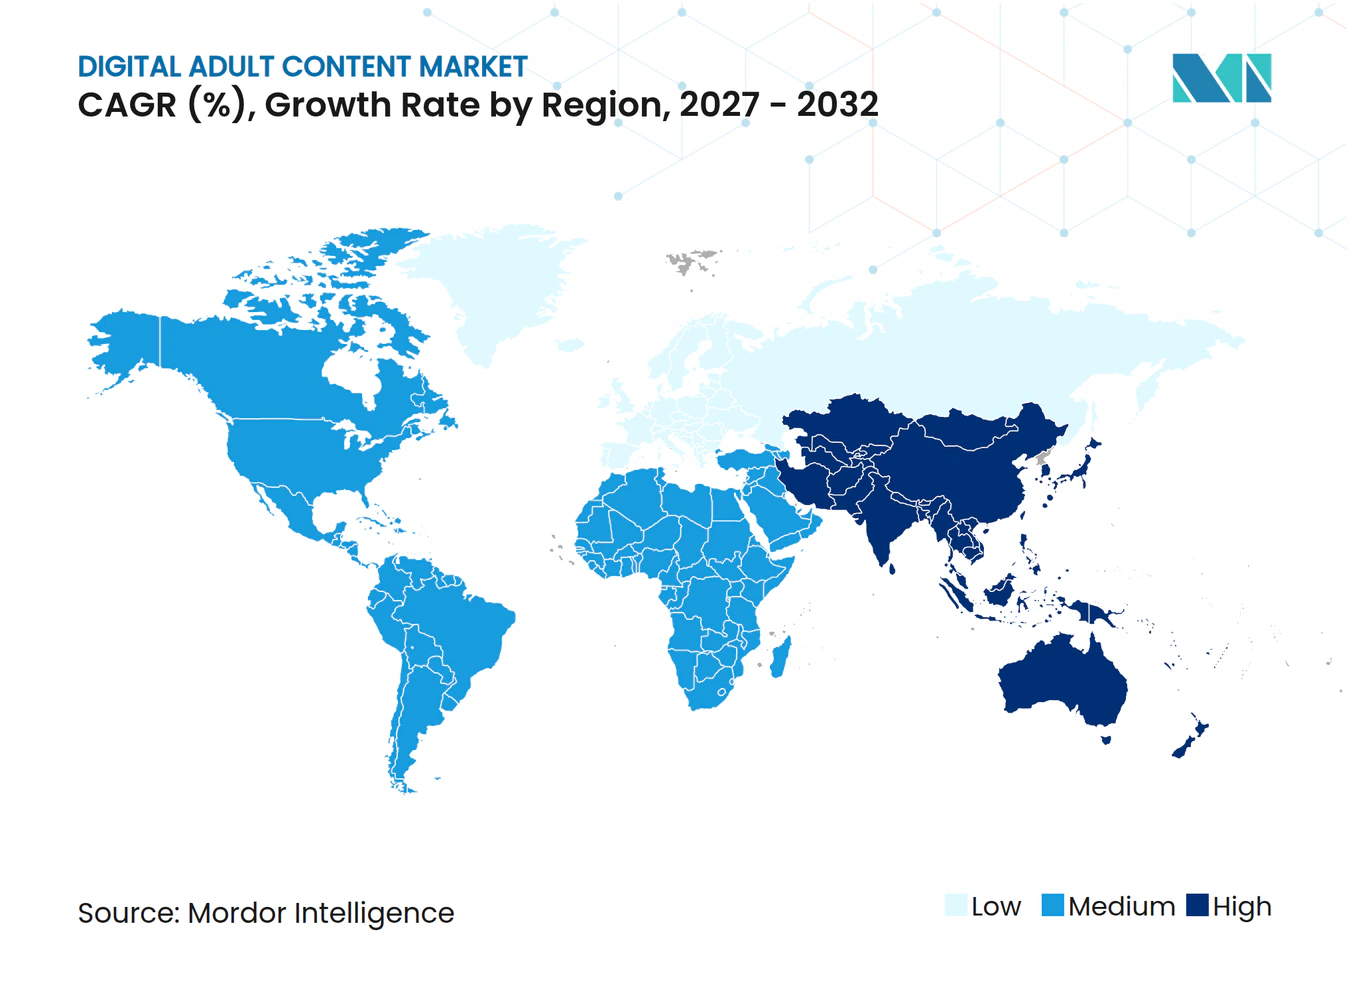
- Geographically, North America led with a 39.85% share in 2026, while Asia Pacific is forecast to grow fastest at a CAGR of 12.7% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Digital Adult Content Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Smartphone Penetration and 5G Roll-outs | +3.6% | Americas, Asia Pacific and Europe | Medium term (2-4 years) |
| Shift From Free-to-View to Paid Subscription Platforms | +3.1% | United States and Canada | Short term (≤ 2 years) |
| Surge in Immersive VR and Haptic-Enabled Experiences | +2.5% | United States of America | Long term (≥ 4 years) |
| Growing Creator-Economy Monetization Tools | +2% | United States and Canada | Medium term (2-4 years) |
| AI-Driven Personalization Boosting Engagement | +1% | Singapore and Brazil | Medium term (2-4 years) |
| Expansion of Carrier Billing and Alternative Payments | +0.9% | France, Belgium, Australia, Brazil and India | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Smartphone Penetration and 5G Roll-outs
Mobile distribution expansion has uneven commercial reach, giving adult-content providers different opportunities to monetize the same streaming proposition. 5G networks covered 55% of the global population in 2025.[1] 5G also accounted for 36% of global mobile broadband subscriptions that year. In the Americas, Asia Pacific and Europe, more than 4 in 10 mobile broadband subscriptions were 5G, compared with 2 or fewer per 100 in Africa. Network coverage creates potential reach, while subscriptions give a separate indication of uptake. The regional subscription split makes 5G-intensive adult streaming a more broadly addressable proposition in the Americas, Asia Pacific and Europe than in Africa.
Shift From Free-to-View to Paid Subscription Platforms
Paid access competes with free viewing by combining content with direct creator interaction. OnlyFans paid creators USD 6.3 billion for the year ended November 30, 2025. The platform, which hosts adult and other subscription-based content, connects creators with subscribers through livestreams, personal messages and requests for custom photos and videos. These interactions create an offer around creator-specific access, giving a consumer a reason to consider paying beyond the availability of a video library. A platform must therefore deliver renewal value, because recurring revenue depends on the relationship offered alongside the content.
Surge in Immersive VR and Haptic-Enabled Experiences
VR familiarity and adult-content viewing represent separate stages in developing demand for immersive services. Data cited by Kiiroo’s US sales manager indicated that 46.7% of US men over 18 reported having tried VR technology in 2025. About 15% of the same population reported having watched VR pornography that year. The gap points to an opportunity to bring people already familiar with VR into adult immersive viewing, rather than relying solely on new technology adoption. Content and interaction quality can therefore help develop demand among technology-familiar viewers who have yet to try adult VR.
Growing Creator-Economy Monetization Tools
Creator monetization tools can turn an audience relationship into several distinct paid content choices. By December 2025, Fansly offered tips, locked-content sales and subscription tiers, alongside tip-triggered automated media messages and configurable media permissions. A creator can automate media delivery against a defined tip and keyword, reducing the manual work attached to that transaction. Fansly also let creators make a video free for subscribers and paid for everyone else, so the same upload could serve a subscription benefit and a separate purchase. That permission structure widens the set of fans a creator can charge by accommodating viewers who want the video without committing to recurring access.
Restraints Impact Analysis of Digital Adult Content Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Intensifying Global Age-Verification Mandates | -1.6% | United Kingdom and France | Short term (≤ 2 years) |
| Payment-Processor and Banking De-Risking Policies | -1.2% | United Kingdom and United States | Short term (≤ 2 years) |
| Content Piracy and Deepfake Proliferation | -0.8% | Spain and Japan | Medium term (2-4 years) |
| Heightened Data-Privacy and Cyber-Security Risks | -0.5% | United States and Canada | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Intensifying Global Age-Verification Mandates
Age assurance places a compliance step directly between an adult-content publisher and its prospective audience. UK Part 5 services publishing regulated provider pornographic content must apply highly effective age assurance before access, unless the user has already been determined to be an adult. Providers must also retain records of their methods and consideration of privacy and data-protection laws. In July 2025, France’s Conseil d’État rejected, for lack of urgency, suspension of an age-verification order covering certain pornography services based in other EU member states.[2] That decision neither resolved the order’s legality nor treated its requirements as a prohibition on adult access. Establishing a service in another EU country therefore leaves affected publishers with the access-control work required to serve users in France.
Payment-Processor and Banking De-Risking Policies
Payment-provider withdrawal can interrupt content monetization before a platform loses the audience it serves. MintStars reported that its primary processor, Coinflow, ended their partnership on April 4, 2025, cutting off instant payouts and freezing payment processing for creators across the platform. MintStars attributed the decision to Coinflow’s banking partner, Approvely. In May 2025, SpankChain announced a pause of SpankPay, its adult crypto payment platform, and its chief of staff said the company had been kicked out of banks. Both cases locate the constraint in the financial route used to transact and settle content earnings, which a content catalog cannot replace. Restoring a reliable transaction route adds operational work and delays monetization, even when an affected platform has content ready to sell.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Digital Adult Content Market Segment Analysis
By Content Type:
Video Production Scale and Immersive Supply ExpansionVideos (professional and amateur) accounted for a 46.29% share of the digital adult content market size in 2026. In December 2025, Ellis Camino launched the production studio Pink For Ink. Nina Nova and Channy Crossfire led its first 2 releases, which were being produced for distribution on Camino’s OnlyFans page. That launch illustrates how a new production brand can enter through a creator’s distribution account, placing a distinct editorial proposition within an established platform. Because the first releases were being produced for Camino’s existing OnlyFans page, the studio launched with a distribution route already in place.
Virtual reality and immersive experiences are the fastest-growing segment, with a forecast CAGR of 13.2% from 2027 to 2032. Interactive games and adult gaming faced a distribution constraint in July 2025, when Valve confirmed that credit-card companies had pressured it to delist certain adult games from Steam. In April 2026, Stripchat’s head of brand described VR adoption on its platform as developing and reported that more VR cameras were being registered month by month. That equipment participation offers a supply-side route to broader immersive live programming, so VR platforms have a reason to develop performer participation alongside attracting viewers.



By Distribution Channel:
Paid Access and Creator RelationshipsSubscription-based platforms represented a 30.97% digital adult content market share in 2026. Across its broader platform offering adult content alongside other subscription-based material, OnlyFans had 132 million paying subscribers in 2025. The count covers paying subscribers rather than registered accounts, distinguishing an audience with paid relationships from registration reach. That paid relationship base is the commercial foundation on which subscription operators compete.
Direct-to-consumer creator and community platforms are the fastest-growing segment, with a forecast CAGR of 12.9% from 2027 to 2032. OnlyFans reported 2.5 million active creators across its broader content platform in 2025. For this channel, a large producer base makes the relationship with an individual creator a distinct organizing principle for paid content, alongside the platform’s delivery role. Aggregate creator scale describes the available supply, while each creator needs an audience willing to pay for that particular relationship. Discovery therefore has commercial value when it connects individual creator offerings with buyers across a shared distribution service.

By Access Device:
Mobile Reach and Headset Content EconomicsMobile smartphones were the largest segment, with a 62.75% share in 2026. In 2025, smartphones accounted for 87% of traffic to Pornhub, providing a platform-specific example of the concentration of adult-content viewing on mobile devices. Apple’s App Store guidelines prohibit apps containing overtly sexual or pornographic material.[3] An adult-content provider’s access to a large mobile audience is therefore separate from its eligibility for that native-app distribution channel. Browser delivery offers these providers a route to mobile viewers outside App Store admission, so native-app eligibility need not determine the entire mobile proposition.
Gaming consoles and VR headsets are the fastest-growing segment, with a forecast CAGR of 21.6% from 2027 to 2032. In May 2025, SexLikeReal and BraindanceVR released an adult VR scene using six-degrees-of-freedom technology that lets viewers move around within it as participants. A headset-focused offer can build on that spatial navigation to give viewers a role within a scene rather than a fixed viewpoint. The commercial distinction lies in what the viewer can do inside the footage, so resolution alone does not define the content proposition. Staging scenes around viewer movement becomes a content-design investment alongside filming the action.
By Immersive Technology Level:
Standard Viewing and Selective Interaction Design2D standard content held a 79.11% share in 2026, making it the largest segment. Its commercial strength rests on screen-based viewing, where a publisher can differentiate a catalog without making physical interaction part of every purchase. Editing, performer selection and release design therefore carry the differentiation, because a standard-screen title needs no spatial or haptic layer.
Haptic-integrated and advanced immersive experiences are the fastest-growing segment, with a forecast CAGR of 20.9% from 2027 to 2032. In May 2026, SexLikeReal released its adult VR scene “Harem: Maximum Bliss,” combining AI Passthrough mixed reality, frame-accurate haptic scripting for interactive devices and 8K streaming tuned for Apple Vision Pro. Frame-accurate scripting links device responses to particular points in the footage, adding a synchronization task to scene design. A producer must decide which moments warrant that response and which can remain conventionally filmed. The investment therefore covers the timing of interaction as well as the image, so the paid experience depends on coordinated content and device behavior.
Geography Analysis
North America Digital Adult Content Market
North America accounted for a 39.85% share of the digital adult content market size in 2026. Pornhub’s 2025 top-20 countries by site traffic were led by the United States and Mexico, placing 2 North American countries at the head of that platform’s audience ranking. For content providers and advertisers, those prominent national audiences can justify a regional distribution proposition that reaches beyond a single country’s viewers.
Asia Pacific Digital Adult Content Market
Asia Pacific is the fastest-growing region, with a forecast CAGR of 12.7% from 2027 to 2032. Average daily watch time among SWAG users in Japan rose by 6 minutes and 11 seconds year over year in 2025, the largest increase among its reported markets. SWAG said it believed more Japanese creators and greater diversity in creator styles drove the stronger engagement. That explanation gives platform operators a reason to consider local producer participation as part of expansion, alongside the ability to reach viewers.
In Europe, the European Commission’s March 2026 preliminary Digital Services Act findings against Pornhub, Stripchat, XNXX and XVideos concerned minors’ exposure to pornography, with the operators entitled to review files and respond. In the Middle East, UAE internet service providers must block websites and webpages containing prohibited content, including pornography and nudity, so audience availability comes before content differentiation in an adult-video provider’s entry decision. In Africa, local trackers estimated 10,000 to 14,000 active creators on platforms such as OnlyFans in South Africa in 2026. In South America, Brazil’s National Data Protection Authority (ANPD) began monitoring 18 pornographic-content and escort-service websites in June 2026, covering 98% of Brazilian traffic in that combined category. Audience access and creator supply are therefore separate entry decisions for cross-border distributors, with a different local balance between available content and regulatory exposure.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of commercial adult-video providers and their production and distribution activities. Covered US producers must maintain performer records for actual sexually explicit depictions meeting interstate or foreign commerce conditions, with inspection access at reasonable times. Production documentation and audience access controls address different activities, making the relevant operating burden depend on how a provider produces and distributes its content.
Regulatory Table of Digital Adult Content Market
| Decision factor | United States | United Kingdom | China | United Arab Emirates | South Africa | Brazil |
|---|---|---|---|---|---|---|
| Primary authority | Department of Justice | Ofcom | Cyberspace Administration of China; culture and tourism and broadcasting departments within their responsibilities | Telecommunications and Digital Government Regulatory Authority | FPB classification authority | National Data Protection Authority (ANPD) |
| Key instruments or direction | 18 U.S.C. §2257 performer records | Online Safety Act Part 5 age assurance | Online audiovisual-service provisions, Article 9 | Internet Guidelines prohibited-content categories | 2022 regulations, regulation 12 classification display | Decree No. 12.880/2026, Article 17 |
| Commercial effect | Identity checks and identifiable records for covered performers | Highly effective checks before access unless already determined adult | Covered providers and users may not produce, publish or transmit pornographic information | ISPs must block prohibited pornography and nudity | Classification labeling or display for covered commercial online distributors, as applicable | Conceal images/videos by default or age-verify unlocking for unregistered, age-unverified or minor accounts; self-declaration alone barred |
| Current policy attractiveness | Medium | Medium | Low | Low | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | Hardening | Hardening |
| Source: Mordor Intelligence | ||||||
US producer-record duties under 18 U.S.C. §2257, administered through the Department of Justice, support Medium attractiveness and continuity as a continuing production-documentation obligation. In the UK, operative Part 5 age assurance supports Medium attractiveness and No change, alongside the Government’s 2026 description of a 6-month review and the Crime and Policing Act 2026 duty for ministers to report within 12 months of Royal Assent on platforms’ verification of performers’ age and consent, with subsequent regulation-making powers. The Government also announced future priority-offence duties requiring proactive, proportionate steps to prevent UK users encountering realistic pornography depicting strangulation or suffocation, explicit penetrative sex between people appearing or pretending to be related, or explicit sexual activity apparently involving someone under 16. China’s audiovisual-service prohibition supports Low attractiveness and continuity despite the March 2026 pre-display notice duty for information potentially affecting minors, while the UAE’s TDRA Internet Guidelines maintain blocking and thus Low attractiveness and continuity, and South Africa’s classification duties and July 2025 draft video-sharing age-verification proposal and Brazil’s controlled-access duties and scheduled January 2027 enforcement support Medium ratings and Hardening.
Value Chain Stages
The value chain compares content creation, audience distribution and payment settlement according to who earns revenue and where execution can fail. Intimacy Productions, Talented Ladies LLC’s adult-content production arm, combines third-party licensing with direct distribution. That combination makes control over routes to audiences a separate commercial choice from producing the content itself. Platform monetization and settlement then determine how viewing or purchases become earnings for the businesses serving those audiences.
Value Chain Analysis Table of Digital Adult Content Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Content production and licensing | Adult-content producers such as Intimacy Productions | Licensing receipts | Dependence on routes to paying audiences | Combine third-party licensing with direct distribution |
| Platform distribution and monetization | Adult-content platform operators such as Aylo | Advertising on free Tube Sites; user fees on paid-access sites | Different conversion requirements for free and paying audiences | Manage advertising monetization and paid access separately |
| Payment processing and settlement | Adult-content payment processors such as Segpay | Percentage settlement fees when transactions settle and funds are paid out | Monthly reports including zero incidents; complaint resolution within 7 days | Keep incident records and route complaints for prompt resolution and removal |
| Source: Mordor Intelligence | ||||
Segpay’s adult-content merchants must also remove content violating its or card-brand policies immediately. Reporting and complaint handling therefore connect publishing operations directly to the conditions for payment services. Combining production with distribution can give a supplier more routes to audiences, while settlement retains an external dependency. The strategic advantage lies in controlling content access and maintaining the records needed to keep that access commercially usable.
Competitive Landscape
Market Concentration
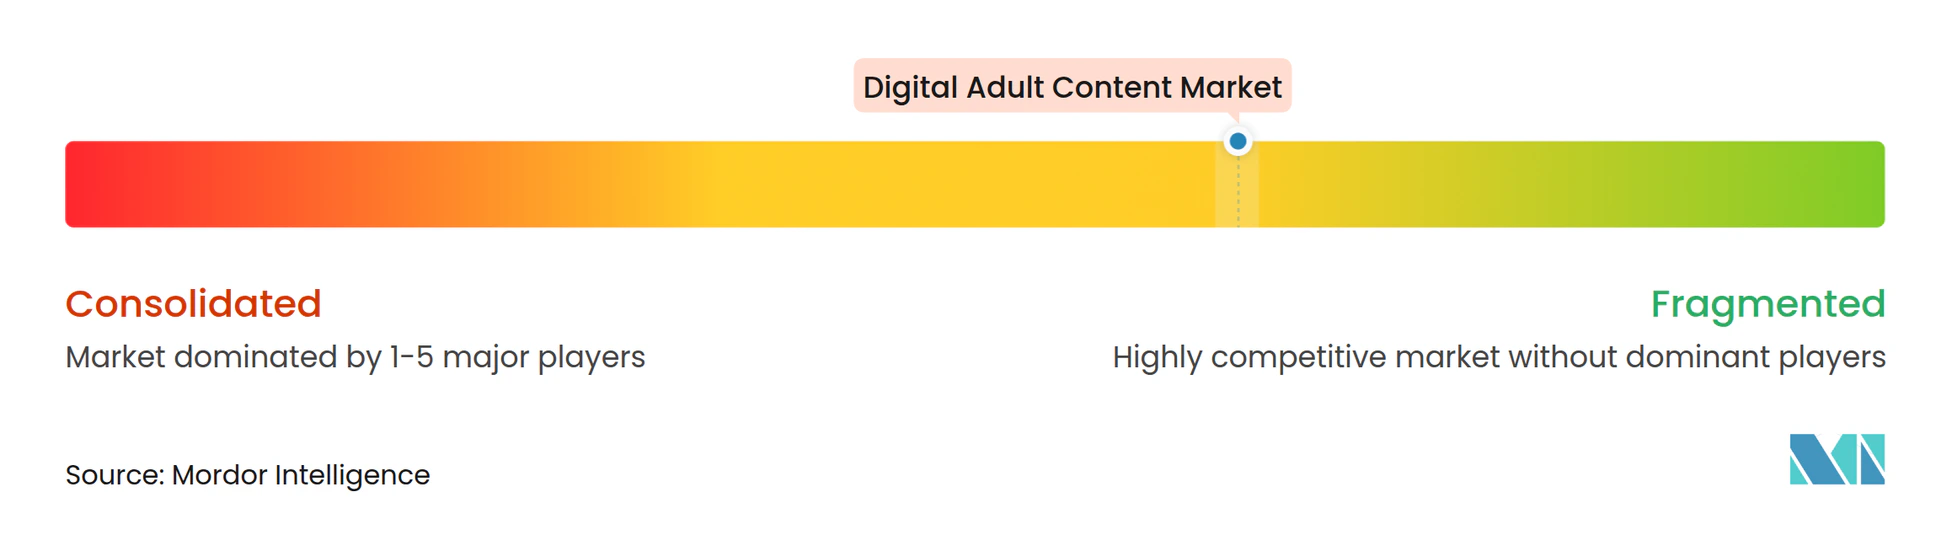
Competition is moderately fragmented across multi-brand content groups, live-cam platforms and video publishers that also offer VR. Aylo’s portfolio includes Pornhub, YouPorn and Brazzers, while Bang Bros publishes adult videos through its website. Chaturbate (Multi Media LLC) operates a live-cam platform, and Luxembourg-based Byborg Enterprises S.A., the parent of LiveJasmin, acquired 100% of Canadian adult conglomerate Gamma Entertainment in January 2025. Naughty America (La Touraine, Inc.) publishes adult video, including virtual reality experiences. The Bang Bros website footer identifies Sonesta Limited S.R.O. as trademark owner and says Aylo Premium Ltd. uses the marks under license.
Collective standard-setting offers a separate route to coordinating production expectations across studios with different brands and commercial positions. On November 10, 2025, Aylo joined the founding members of the Adult Studio Alliance, which announced a code of conduct for studio-produced adult content. Other founders included Dorcel, ERIKALUST, Gamma Entertainment, Mile High Media and Ricky’s Room, connecting several production businesses through the announced safety framework. With Aylo and Byborg-owned Gamma Entertainment among the founders, the announced code makes production governance a shared positioning issue across corporate portfolios.
Competitive direction also includes hybrid transactions that let buyers choose recurring access or an individual content purchase. On September 24, 2026, Clips4Sale rolled out C4S+, combining subscription streaming of participating creators’ content with individual clip purchases at each creator’s listed price. Because individual clips stay available at each creator’s listed price, C4S+ adds a subscription route alongside the existing per-clip purchase. On February 27, 2025, Canada’s Privacy Commissioner sought a Federal Court order requiring Aylo to obtain direct meaningful consent from everyone appearing in uploaded intimate content, with the requested order unissued and no hearing date set by October 2026. For operators pursuing UK, EU and Canadian audiences, jurisdiction-specific access and consent controls are a competitive constraint alongside the choice of payment format.
Digital Adult Content Industry Leaders
-
Aylo (Reality Kings, Brazzers)
-
Bang Bros (WGCZ Holding)
-
Chaturbate (Multi Media LLC)
-
Byborg Enterprises S.A. (Gamma Entertainment)
-
Naughty America (La Touraine, Inc.)
- *Disclaimer: Major Players sorted in no particular order
Digital Adult Content Market Companies Covered in this Report
- Byborg Enterprises S.A. (Gamma Entertainment)
- Naughty America (La Touraine, Inc.)
- Bang Bros (WGCZ Holding)
- Aylo (Reality Kings, Brazzers)
- Marc Dorcel
- Fakehub
- Soft on Demand
- Moodyz
- Digital Playground
- S1 No.1 Style
- Prestige
- DMM (Fanza)
- Stripchat
- Chaturbate (Multi Media LLC)
- Sexmex
- Hotboys Brasil
Key Opportunities for Market Participants
These opportunities compare ways to sell customized adult content, private digital interaction and discrete collections, with creators and their fans as the commercial counterparties. In September 2026, LoyalFans Creator Success Manager Anastasia Pierce said customers sought custom videos, private livestreams, direct messages and exclusive posts. Those reported preferences make the specific content or access being purchased central to offer design. Fangate’s August 2026 launch also enabled creators to sell video and photo collections through a single purchase link without requiring a user account or subscription.
Market Opportunities Table of Digital Adult Content Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Custom adult-video commissions | Reported interest in custom videos | Fans seeking personalized digital content | Sell clearly scoped custom videos with defined delivery terms | Matching delivery promises to creator capacity | Custom-content creators and LoyalFans |
| Paid private digital shows | Reported interest in private livestreams and direct messages | Fans seeking direct digital interaction | Offer time-limited paid online sessions with explicit access terms | Live delivery depends on creator availability | Live-content creators and LoyalFans |
| Individually priced content collections | Account-free collection purchases available through Fangate | Buyers of discrete video and photo collections | Package content into single-price collections for link-based sales | Establishing a clear value proposition for each collection | Independent creators and Fangate |
| Source: Mordor Intelligence | |||||
LoyalFans was expanding traffic, content-performance and purchase statistics while updating discovery in September 2026. That development can give creators a more specific basis for deciding which paid offers to emphasize. The central opening is to convert audience attention into a defined content result or digital interaction that the creator can deliver. A custom commission creates an individual production obligation, so selling more personalized work also consumes time that could serve live interaction.
Recent Industry Developments in Digital Adult Content Market
- Sep 2026: Clips4Sale launched C4S+, a subscription streaming service for participating creators’ content that also allows individual clip purchases at each creator’s listed price.
- Sep 2026: Ofcom fined Xgroovy.com’s provider for July-November 2025 age-assurance failures and an unanswered information request. The provider had added potentially highly effective age assurance and blocked UK IP addresses, with further monitoring planned.
- Aug 2026: Johnny Sins launched Fangate, enabling creators to sell content directly to fans without requiring a user account or subscription.
Digital Adult Content Market Report Scope and Research Methodology
Market Definition and Coverage
The digital adult content market measures annual revenue from digital adult content across the Global market. It includes consumer payments and advertising sales tied to monetized access to and interaction with that content.
Scope exclusions: Offline adult entertainment, separately sold access devices and equipment, non-adult digital content and general digital-media revenue, and token or NFT trading unrelated to adult content or access to it are excluded.
Segments Covered in This Report
- By Content Type
- Videos (Professional and Amateur)
- Live Cam Streaming and Interactive Shows
- E-Books and Erotic Literature
- Audio Content and Erotic Podcasts
- Interactive Games and Adult Gaming
- Virtual Reality and Immersive Experiences
- By Distribution Channel
- Subscription-Based Platforms
- Ad-Supported Free Content Platforms
- Pay-Per-View and Video-on-Demand Rentals
- Direct-to-Consumer Creator and Community Platforms
- By Access Device
- Mobile Smartphones
- Desktop and Laptop Computers
- Smart TVs and OTT Streaming Devices
- Gaming Consoles and VR Headsets
- By Immersive Technology Level
- 2D Standard Content
- 3D Stereoscopic Content
- 180° Virtual Reality
- 360° Virtual Reality
- Haptic-Integrated and Advanced Immersive Experiences
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Nordics
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
International Telecommunication Union (ITU) connectivity measures and World Bank internet-use indicators help size the addressable online audience and compare regional access, while Ofcom age-assurance reporting and European Commission Digital Services Act guidance inform regional operating conditions. These sources, such as the ITU Facts and Figures series, the World Bank World Development Indicators, Ofcom's age-assurance report and the Commission's protection-of-minors guidelines, help analysts interpret differences in audience access, mobile reach and compliance across regions.
Annual filings such as 10-Ks, investor materials and reputable press can supplement platform disclosures on subscription, advertising and transaction models, with revenue recognition and geographic reporting checked against the market boundary. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys should include senior executives, commercial and product leaders, and operating managers at global content studios, subscription and advertising platforms, live-interaction services, and creator businesses. Respondents should test the secondary-source interpretation of paid access, ad sales, creator transactions, geographic reach and content formats, and analysts should reconcile material differences against documented disclosures or seek clarification from relevant respondents. Where no reliable figure is available, the model should retain a range for scenario analysis and triangulate it with platform disclosures, audience indicators and sampled price-times-activity checks.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 50% | Functional/Unit leaders: 30% | EMEA: 32% |
| Smaller Players: 20% | Managers: 50% | Americas: 28% |
Market-Sizing & Forecasting
Analysts should estimate global annual revenue in USD first from the top down, then allocate it across content type, distribution channel, access device, immersion level and region using the market boundary and evidence on how each revenue stream is earned. Internet-user and mobile-broadband reach indicate potential audiences, paid subscriber and creator disclosures indicate recurring and direct transaction activity, advertising disclosures indicate free-content monetization, and smartphone or VR adoption helps distinguish access and format demand. Scenario analysis should project these indicators under alternative assumptions for paid conversion, advertising yield, creator monetization and immersive adoption, with public platform price and subscriber or creator disclosures used for selective price-times-activity checks. Where either input is absent, analysts should use a documented range and avoid adding overlapping platform commissions to creator sales. Primary respondents can test whether the selected drivers and regional or format allocations reflect actual commercial practice, and analysts should revise the relevant assumptions when a disclosure or interview identifies a material inconsistency.
Data Validation & Update Cycle
Platform and company disclosures should be triangulated against independent connectivity, audience, advertising and regulatory signals, followed by investigation of outliers and material variances against prior periods, nearby regions and related revenue streams before sign-off. A second analyst should review source definitions, calculations, segment shares and forecast assumptions, with re-contact triggered by conflicting respondent evidence, a material company disclosure, a regulatory change or an unexplained movement in a key indicator. When audience, sales and regulatory indicators diverge, analysts should document the cause and revisit the affected assumption before sign-off. The model should be refreshed annually, updated between cycles after material events, and checked again against the latest available evidence immediately before delivery.
Mordor Intelligence's Digital Adult Content Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The digital adult content market measures annual revenue from digital adult content across the Global market.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Scenario analysis should project these indicators under alternative assumptions for paid conversion, advertising yield, creator monetization and immersive adoption, with public platform price and subscriber or creator disclosures used for selective price-times-activity checks.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 51.76 B (2027) | |
| Global Consultancy A | USD 45.5 B (2024) | At its 2024 base, this estimate is 12.1% below this report's 2027 value of USD 51.76 B, 3 years later. Its listed estimate covers videos, images and live cam shows, a narrower digital-format pool than the report boundary. |
| Regional Consultancy B | USD 78.1 B (2026) | At its 2026 base, this estimate is 50.9% above this report's 2027 value of USD 51.76 B, 1 year later. Its defined market also includes physical publications, toys, adult novelties and disc formats sold through offline channels. |
For Mordor Intelligence, platform and company disclosures should be triangulated against independent connectivity, audience, advertising and regulatory signals, followed by investigation of outliers and material variances against prior periods, nearby regions and related revenue streams before sign-off.
Key Questions Answered in the Report
What is the digital adult content market size and growth outlook?
It is projected at USD 51.76 billion in 2027 and USD 79.82 billion by 2032, with a CAGR of 9.05% from 2027 to 2032.
What drives demand for paid adult content?
Creator interaction and mobile distribution support demand. OnlyFans paid creators USD 6.3 billion for the year ended November 30, 2025.
Which adult-content format has the largest share?
Videos (professional and amateur) held the largest share at 46.29% in 2026.
Which companies are major adult-content providers?
Major providers include Aylo, Bang Bros, Chaturbate (Multi Media LLC), Byborg Enterprises S.A. and Naughty America (La Touraine, Inc.).
What is a major operating challenge for adult-content platforms?
UK Part 5 pornography publishers must apply highly effective age assurance before access unless a user has already been determined to be an adult.
Which regions lead adult-content revenue and forecast growth?
North America held a 39.85% share in 2026, and Asia Pacific is the fastest-growing region at a forecast CAGR of 12.7% from 2027 to 2032.