
Books Market Size and Share
Books Market Analysis by Mordor Intelligence
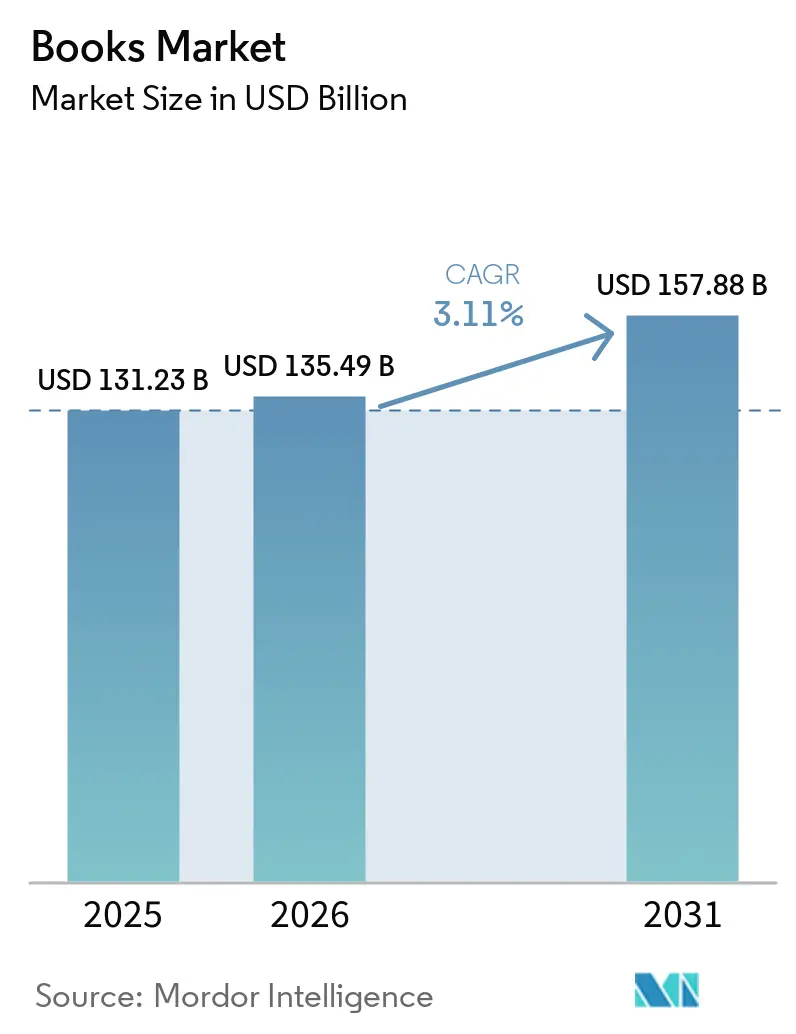
The books market size is expected to grow from USD 135.5 billion in 2026 to USD 139.7 billion in 2027 and is forecast to reach USD 161.5 billion by 2032 at 2.94% CAGR over 2027-2032.
Paid digital reading in China and grade-specific school-textbook selection in Nigeria give publishers distinct routes to reader and institutional demand. Audiobook editions and differentiated hardcovers offer different ways to turn content into a paid reading or listening experience. Acquisitions and licensing agreements broaden publishing portfolios and format permissions, increasing the commercial value of coordinating content rights across editions. E-book tax costs and reduced physical distribution constrain the revenue available from reaching readers through those routes. Revenue growth therefore depends on placing rights into premium hardcovers or recurring audio access while managing e-book tax exposure and lost mass-market paperback distribution.
Key Report Takeaways
- By format, hard copy led with a 76.05% books market share in 2026, while audiobooks lead forecast growth at an 8.25% CAGR over 2027-2032.
- In the genre breakdown, fiction led with a 33.31% share of the books market size in 2026, and comics and graphic novels are the fastest-growing genre at a 4.65% CAGR over 2027-2032.
- Across distribution channels, online retail led with a 52.18% share of the market in 2026, while the direct-to-consumer and subscriptions segment leads forecast growth at a 5.8% CAGR over 2027-2032.
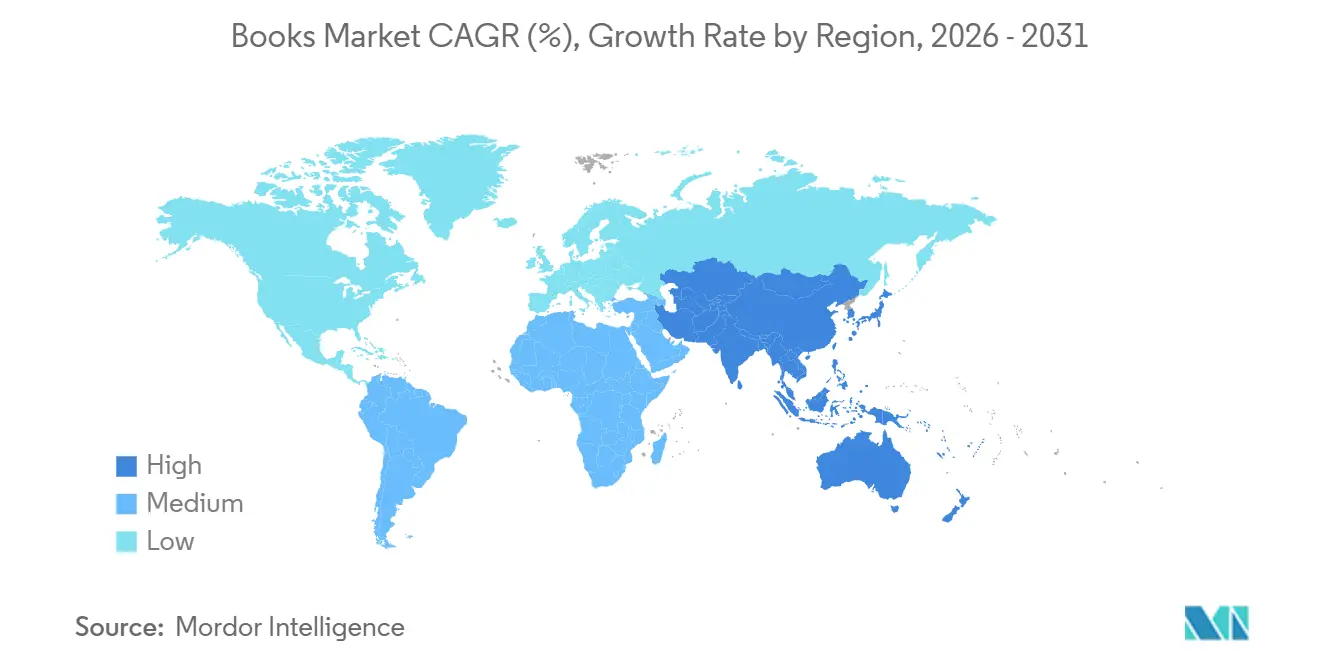
- Geographically, Asia-Pacific led with a 37.02% share of the market in 2026, and the Middle East and Africa is the fastest-growing region at a 4.6% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Books Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shift Toward Subscription-Based Reading in Asia | +1.2% | China in Asia-Pacific | Medium term (2-4 years) |
| Growing K-12 and Higher-Ed Textbook Adoption in Africa | +1% | Nigeria in Africa | Medium term (2-4 years) |
| Premiumization of Special-Interest Print in North America | +0.8% | United States of America | Short term (≤ 2 years) |
| Rapid Audiobook Uptake Among Commuters in Europe | +0.6% | Germany and Spain | Medium term (2-4 years) |
| Government-Backed Literacy Missions in South America | +0.4% | Argentina in South America | Medium term (2-4 years) |
| Copyright Reform Fueling Digital Libraries in Middle East | +0.3% | United Arab Emirates | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Shift Toward Subscription-Based Reading in Asia
Paid digital reading creates demand when access to written content offers readers enough value to justify a direct payment. In 2025, subscriptions accounted for 27.83% of revenue in China’s digital popular-reading sector.[1] Their revenue share declined in the same reporting period. South Korean reading-platform operator KT Millie Seojae, which offers e-book subscriptions, reported company-wide revenue growth of 21% in 2025. The company linked telecom partnerships to new subscriber growth and a positive contribution to its business-to-business-to-consumer channel revenue. For publishers, placing subscription content through telecom partners can connect catalog access to a demonstrated subscriber-acquisition route, making distribution partnerships a source of additional reading demand.
Growing K-12 and Higher-Ed Textbook Adoption in Africa
School-textbook demand becomes more commercially accessible when education authorities complete the selection framework that guides institutional buying. Nigeria’s Federal Ministry of Education released its ranked and approved textbook list for use in schools during 2026-2028, covering selected grades.[2] The first phase covered Primary 1, Primary 4, Junior Secondary School 1 and Senior Secondary School 1. For publishers serving these grades, inclusion provides a defined route into selection by schools, education authorities and procurement agencies. The program can direct attention toward approved editions, linking a publisher’s school offer to a specific adoption window. Within this phase, coverage of the specified class levels can matter more commercially than the breadth of a publisher’s wider school catalog.
Premiumization of Special-Interest Print in North America
By the week ended January 3, 2026, Circana BookScan recorded 1,705,655 US sales of Onyx Storm (Deluxe Limited Edition). In August 2026, Publishers Weekly reported that premium production values in middle-grade books helped justify hardcover prices. The same report said they gave booksellers another point of distinction in crowded displays. Together, edition-specific demand and retail distinction make physical presentation commercially relevant to a publisher’s release decisions. Design investment is therefore easiest to justify on titles that already draw demand, where a deluxe treatment can add price support and a point of distinction for the bookseller.
Rapid Audiobook Uptake Among Commuters in Europe
Driving and commuting create a reading occasion that does not require a screen or an open printed book. Audible’s 2025 Compass survey found that 48% of audiobook listening among listeners in Germany and Spain occurred during drives and commutes. This concentration gives publishers a commercial reason to develop audio editions around attention that visual formats cannot serve safely during driving. The same survey found commute-led listening less pronounced in Italy and France, so the commuter opening is tied to Germany and Spain rather than uniform across Europe. Audio editions timed to commuter listening therefore have the clearest footing in those two markets.
Restraints Impact Analysis of Books Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shrinking Shelf-Space in Brick-and-Mortar Retailers | -0.6% | United States of America | Medium term (2-4 years) |
| VAT on E-books in Select EU Countries | -0.4% | Denmark and France | Short term (≤ 2 years) |
| Piracy on Telegram and Discord Channels | -0.3% | Italy and Spain | Long term (≥ 4 years) |
| Supply-Chain Paper Shortage Risks | -0.2% | North America, including the United States | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shrinking Shelf-Space in Brick-and-Mortar Retailers
A smaller retail footprint constrains a book format by reducing the places where its editions can be encountered before purchase. Before ReaderLink’s February 2025 distribution announcement, Barnes & Noble had removed or downsized new mass-market paperback sections in about one-third of its US stores. ReaderLink then stopped distributing mass-market paperbacks to its accounts at the end of 2025. HarperCollins Publishers LLC said in February 2025 that it was broadening trade-paperback availability and distribution. The loss increases dependence on the remaining routes for new mass-market paperback releases, limiting the scope to recover retail visibility without changing an edition’s distribution or format.
VAT on E-books in Select EU Countries
Tax can reduce the commercial room for inexpensive digital editions even when delivery requires no printed inventory. In July 2025, Denmark applied a 25% VAT rate to e-books, equal to its standard VAT rate. For an e-book seller, that levy creates a choice between a higher tax-inclusive price and lower receipts at a fixed consumer price. An October 2026 proposal for zero VAT from July 2027 would ease the burden if enacted. Until an exemption takes effect, the tax wedge limits the revenue available from an affordable offer and makes price-led expansion harder to sustain.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Books Market Segment Analysis
By Format:
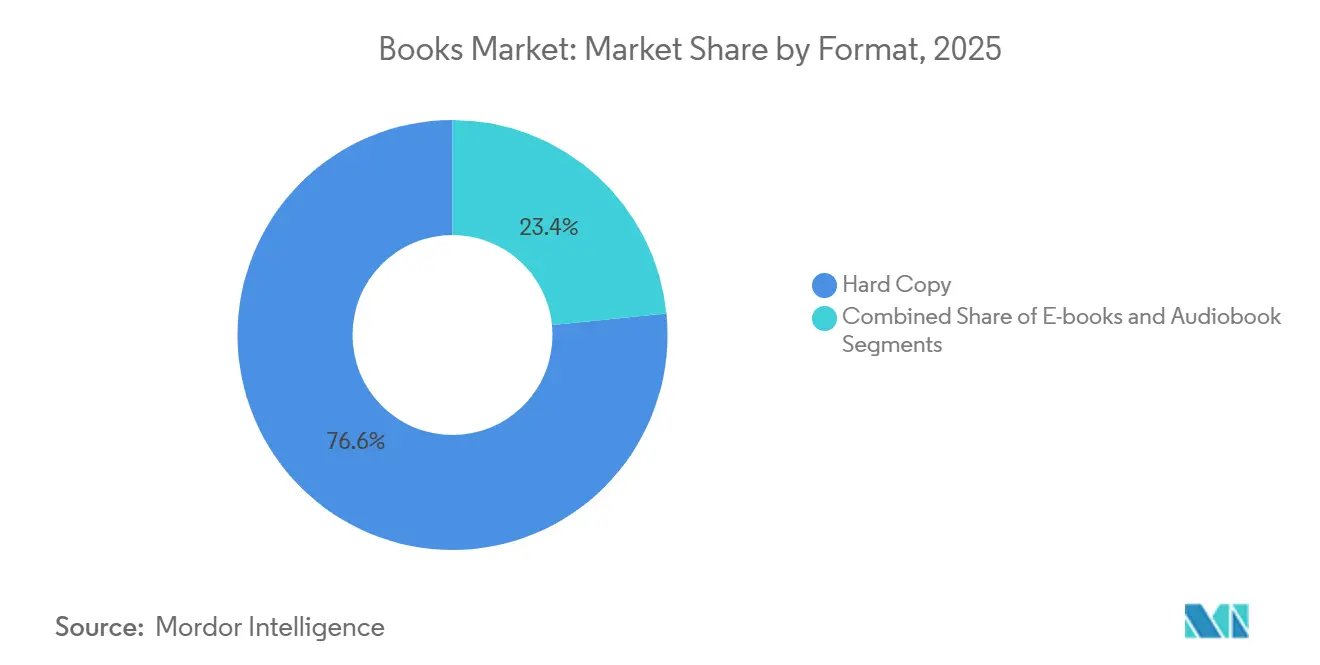
Print Scale and Audio Catalog ExpansionHard copy accounted for a 76.05% share of the books market size in 2026. Circana BookScan-tracked US outlets sold 762.4 million print books in the year ended December 27, 2025. In BookNet Canada’s January 2026 online survey of English-speaking Canadian adults who read or listened to at least part of a book in 2025, 58% preferred print. The reader sample comprised 1,005 respondents, with a margin of error of ±3 percentage points at 95% confidence. A publisher removing a print edition risks losing the version this audience wants, making format availability a demand decision alongside the practical choice of how to produce the book.
Audiobooks are the fastest-growing segment, with an 8.25% CAGR forecast over 2027-2032. US audiobook sales revenue reached USD 2.43 billion in 2025, up 9% from 2024, in the Audio Publishers Association’s Toluna-conducted sales survey. Publishers also reported more than 750,000 active US audiobook titles in 2025, 43% more than in 2024. A larger active catalog expands the range of rights that can earn audio revenue, while making the match between a title and paying listeners commercially consequential. Audio publishers therefore face an allocation decision about which additional titles can justify production alongside a rapidly expanding pool of available works.



By Genre:
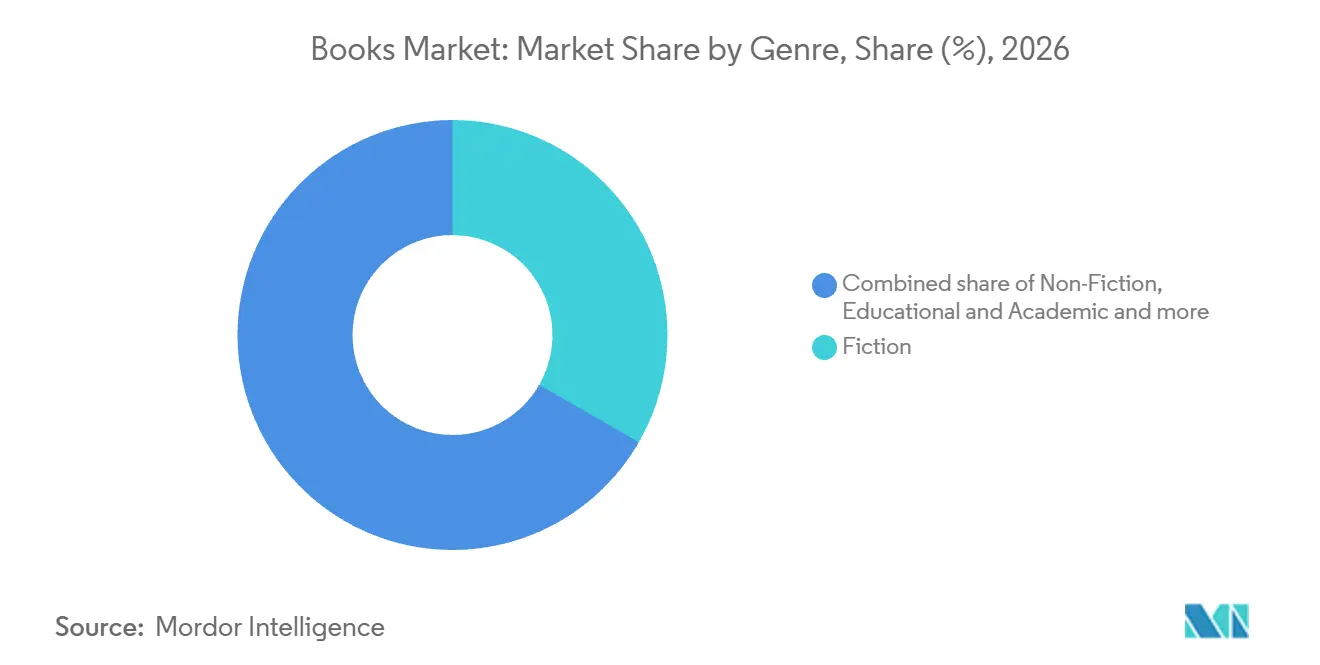
Fiction Depth and Graphic Novel Sell-ThroughFiction represented a 33.31% books market share in 2026. US adult-fiction publisher revenue grew 3.9% to USD 7.1 billion in 2025. Adult fiction also averaged more than one-third of print units sold across 19 territories analyzed by NielsenIQ BookData and GfK Entertainment in the first half of 2026, with coverage and genres varying by country. Adult fiction therefore shows scale in both US publisher revenue and print units sold across the analyzed territories.
Comics and graphic novels are the fastest-growing segment, with a 4.65% CAGR forecast over 2027-2032. US graphic-novel print unit sales at Circana BookScan-tracked outlets rose 34.9% in the nine months ended October 3, 2026, against the comparable 2025 period. The same tracked category had reached 25.9 million units in the completed 2025 year. That combination establishes a sizable physical sales base alongside a recent increase in copies bought, giving graphic-novel publishers a concrete production opportunity.

By Distribution Channel:
Online Scale and Paid Access EconomicsOnline retail was the largest distribution segment, accounting for 52.18% of the market in 2026. Estimated US publisher sales through online retail reached USD 12.3 billion in 2025 across books and course materials in print and digital formats.[3] The channel grew 3.1% year over year and was the largest category in the Association of American Publishers’ channel reporting. Its reach across print and digital books and course materials gives publishers a substantial commercial route that extends beyond one format or product type.
The direct-to-consumer and subscriptions segment is forecast to grow fastest, with a 5.8% CAGR over 2027-2032. Spotify’s May 4, 2026 distribution terms allocate a market-level subscription royalty pool to participating authors or their companies according to their share of total audiobook consumption. The model applies to authors and companies that opt into Spotify’s distribution services, and Spotify determines total consumption for the allocation. Bloomsbury Publishing PLC separately reported 57% audio revenue growth in the year ended February 28, 2025, partly driven by its new commercial relationship with Spotify. For a rights holder using pooled terms, earning revenue depends on the title’s share of listening, making sustained consumption commercially significant after access is secured.
Geography Analysis
Asia-Pacific Books Market
Asia-Pacific was the largest region, with a 37.02% books market share in 2026. Beijing OpenBook monitoring put China’s 2025 book-retail sales value at CNY 110.4 billion (USD 15.36 billion), down 2.24% year over year. China’s retail base shows the scale of paid book demand within the region even as 2025 value fell. For a publisher seeking growth in China in 2025, gaining spending share would have been necessary as the overall retail-value pool contracted.
Middle East and Africa Books Market
The Middle East and Africa is the fastest-growing region, with a 4.6% CAGR forecast over 2027-2032. NielsenIQ’s tracked South African print-book unit sales rose 4.6% in 2025 from 2024, with market and genre coverage varying by country in the underlying study. In 2025, the United Arab Emirates’ National Library and Archives signed an agreement with Naseej and Clarivate to build and catalog its collections and provide recent publications across subjects and languages. This joins a consumer sell-through signal with an institutional collection-building route, giving publishers different potential buyers within the region. For an institutional supplier, matching subject and language coverage to collection requirements can open demand separate from a single-title retail sale.
In North America, books by Canadian contributors gained a larger share of Canadian print sales in 2025 than in 2024. In South America, Colombia’s publishing-sector domestic sales increased in 2025 from 2024, underscoring a route to demand within the country. In Europe, France’s Hachette Livre announced its acquisition of LEC’s illustrated-practical publishing assets, including the Ducasse Edition cookbook imprint, in July 2025. Marketing and distribution of that catalog were planned from January 1, 2026. Canadian contributors’ larger share of print sales and Colombia’s rise in domestic sales both show home-market gains in 2025, while Hachette Livre’s LEC purchase added a French illustrated-practical catalog to a large group.
Regulatory Framework and Outlook
The selected jurisdictions are compared from the perspective of a book publisher that owns the relevant copyrights and sells print and digital editions. French print-book publishers or importers set the public price, which sellers must respect subject to an optional discount of up to 5%. Chinese marketplaces must verify distributors’ licenses, while Brazil’s contribution rules cover previously zero-rated domestic book and e-book sales listed in its 2026 tax-expenditure schedule.
Regulatory Table of Books Market
| Decision factor | United States | Brazil | France | China | United Arab Emirates |
|---|---|---|---|---|---|
| Primary authority | US Copyright Office for registration | Federal tax authorities for CBS; CGIBS for IBS | Book Mediator for conciliation; courts | National Press and Publication Administration | National Media Authority; relevant competent authorities |
| Key instruments or direction | 17 U.S.C. § 106; registration framework; January 2026 AI-training discovery proposal | Complementary Laws 214/2025 and 227/2026; 2027 tax transition | Print-book fixed-price framework; April 2026 price-code charter | Publication licensing framework; September 2026 consultation draft | Federal Decree by Law No. 55 of 2023; NMA book-circulation service |
| Commercial effect | Owner reproduction and distribution rights subject to statutory exceptions; registration or refusal before US-work litigation | Book supplies immune from the new IBS and CBS consumption taxes | Publisher-set print-book public prices; seller discounts permitted up to 5% | Wholesale, retail and online-distribution licenses; marketplace operators verify distributors’ licenses | Printed and electronic book content and age review; relevant media license; distribution through licensed commercial companies |
| Current policy attractiveness | High | Medium | High | Low | Low |
| Future direction of policy attractiveness | Easing | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
US copyright protections support High attractiveness, with potential Easing from the AI-training discovery process in H.R. 7209, introduced January 22, 2026 and pending in the House Judiciary Committee. Brazil’s Medium rating balances PIS/Pasep and Cofins at 10% of the standard-system burden on those sales since April 1, 2026 against IBS/CBS book-supply immunity through the scheduled 2027 transition. France merits High for publisher-set print pricing, with continuity under its April 2026 charter commitments on price codes rather than a statutory pricing change. China’s licensing and marketplace-verification duties and the UAE’s content review and licensed-distribution requirements support Low ratings and continuity, with China’s September 2026 revision proposed and the UAE’s December 2025 succession transferring federal functions.
Value Chain Stages
The comparison follows publishing, print production, distribution and retail sales, separating the supplier earnings available at each stage. Pearson identified long-term physical disruption risks in paper procurement, printing, logistics and distribution in its 2025 reporting. That exposure makes continuity across physical stages commercially relevant even when the content itself is ready for sale.
Value Chain Analysis Table of Books Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Publishing and edition development | Educational publishers such as Pearson PLC | Book sales | Exposure to title-level demand uncertainty | Stage edition commitments around demonstrated demand |
| Print production | Print-on-demand producers such as Ingram Publisher Services | Printing services | Exposure to physical production disruption | Qualify alternative production routes |
| Distribution and fulfillment | Publisher-service distributors such as Ingram Publisher Services and Penguin Random House Grupo Editorial | Distribution, warehousing and fulfillment services | Dependence on warehouse and shipping continuity | Maintain alternative fulfillment capacity |
| Retail sales | Mass-merchandise retailers such as Walmart and Kroger | Book sales | Dependence on wholesaler format coverage | Broaden distributor relationships for targeted editions |
| Source: Mordor Intelligence | ||||
In March 2025, Penguin Random House Grupo Editorial announced logistics services for other publishers through its Cerdanyola del Vallès center, with stated capacity of more than 40 million copies annually. Serving other publishers can create earnings alongside distribution of an operator’s own books. For a publisher buying fulfillment, that option can reduce the need to replicate a physical distribution operation. A publisher that owns a large center can fill spare capacity with other publishers’ volume, while a smaller publisher can rent that capacity rather than build its own.
Competitive Landscape
Market Concentration
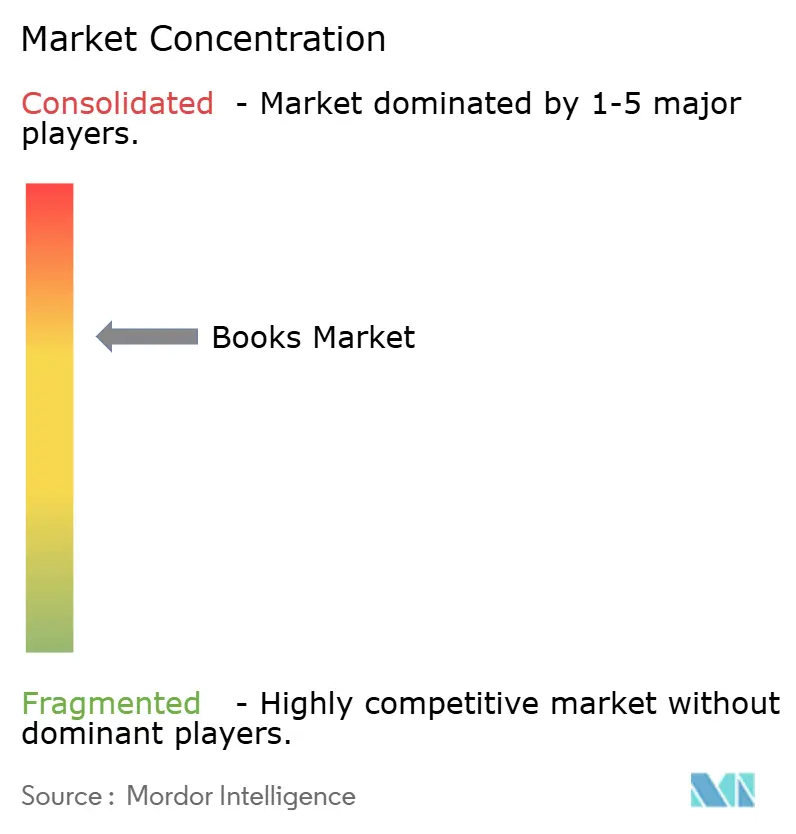
Competition combines large publishing groups and educational specialists in a moderately concentrated structure. Penguin Random House LLC is a publisher and licensee of story content, while Hachette Livre, a Lagardère SA subsidiary, publishes fiction, nonfiction, children’s books and textbooks. HarperCollins Publishers LLC completed its acquisition of Crunchyroll’s manga publishing operations in France and Germany on October 1, 2025, adding manga to its local portfolios. Pearson PLC participates in higher-education textbook publishing, while Macmillan Publishers, the US trade company within Holtzbrinck Publishing Group, publishes trade books and audio. This combination makes competitive overlap depend on the reader and edition being served, with broad consumer catalogs and specialist educational content addressing different commercial needs.
In October 2025, Macmillan Publishers announced it had acquired Sounds True’s book, e-book, audiobook and audio-original catalogs in mind, body and spirit publishing. Books and e-books were assigned to St. Martin’s Essentials, while audio content went to Macmillan Audio. Assigning the acquired formats to distinct publishing operations gives the content several routes to readers within the same group. Acquiring book, e-book, audiobook and audio-original catalogs lets Macmillan offer one mind, body and spirit list across print, e-book and audio rather than a books-only list.
Penguin Random House LLC’s expanded Disney Publishing licenses, effective May 1, 2025, covered print, e-book and audio publishing and original content. The licensed properties spanned Disney, Pixar, Marvel, Star Wars, 20th Century Studios and National Geographic. Those permissions provide a defined route for developing established properties across editions, making the scope of licensed rights part of competitive positioning. HarperCollins Publishers LLC’s acquired manga operations and Macmillan Publishers’ purchased mind, body and spirit catalogs offer a contrasting route to expanding the content a publisher controls. Because the licenses cover print, e-book and audio together, one Disney, Marvel or Star Wars property can reach a family in several formats from a single publisher.
Books Industry Leaders
-
Penguin Random House LLC
-
Hachette Livre
-
HarperCollins Publishers LLC
-
Pearson PLC
-
Macmillan Publishers
- *Disclaimer: Major Players sorted in no particular order
Books Market Companies Covered in this Report
- Penguin Random House LLC
- Hachette Livre
- HarperCollins Publishers LLC
- Pearson PLC
- Macmillan Publishers
- John Wiley & Sons, Inc.
- McGraw Hill LLC
- Scholastic Corp.
- Simon & Schuster, LLC
- Bloomsbury Publishing PLC
- Elsevier B.V.
- Springer Nature Group
- Oxford University Press
- Cambridge University Press
- Cengage Learning, Inc.
- Ingram Content Group
- Amazon Publishing
- Audible Inc.
- Kobo (Rakuten)
- Bertelsmann SE & Co. KGaA
Key Opportunities for Market Participants
The comparison evaluates school-textbook opportunities for publishers preparing content and delivery offers at different stages of institutional buying. Malaysia’s Ministry of Education tendered publishing, printing and supply of its 2027 school-curriculum textbook package for use from 2028, with bids due January 11, 2027. That package links curriculum content with the operational work of producing and supplying editions, making coordination across those activities part of the commercial offer.
Market Opportunities Table of Books Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Integrated curriculum-textbook packages | New curriculum package covers publishing, printing and supply | Malaysia’s Ministry of Education | Develop a coordinated content, production and delivery offer | Executing all parts of the package | School-textbook publishers, printers and suppliers able to meet the package requirements |
| Editions for the next textbook-ranking phase | Preparations for a second round were announced in September 2026 | Nigerian school textbooks for Primary 2, Primary 5, Junior Secondary School 2 and Senior Secondary School 2 | Prepare editions matched to the announced class levels | Coordination with the next ranking round | Publishers serving the announced grades that complete the applicable selection steps |
| Foundation Phase supply for provincial buyers | South Africa approved its catalog on September 18, 2026, and reported procurement underway the next day | South African provincial education departments | Align available editions and delivery plans with provincial procurement | Delivering before the next academic year | Foundation Phase publishers and suppliers selected through provincial procurement |
| Source: Mordor Intelligence | |||||
The opportunities call for different commitments because preparation for ranking and procurement already underway create different execution demands. A publisher preparing a future edition can stage content work, while a supplier addressing active procurement must connect its offer to deliverable books. The central opening is an integrated textbook offer that joins relevant content with a workable production and delivery plan. That combination ties revenue prospects to a defined school adoption cycle and gives institutional buyers a practical route from selection to supply.
Recent Industry Developments in Books Market
- Oct 2026: Pan Macmillan acquired a stake in UK nonfiction publisher New River Books, which was to continue publishing independently. Pan Macmillan planned to replace Hachette as its sales and distribution provider from July 2027.
- Oct 2026: Spotify announced plans to expand audiobook access from 22 to more than 180 markets by the end of 2026, with more than 350,000 titles for newly added markets.
- Sep 2026: Scholastic Corp. agreed to acquire children’s publisher Cottage Door Press for approximately USD 71 million before customary price adjustments. Luna StoryTime interactive toys were to be separated before closing and excluded from the deal. Closing was expected by the end of 2026, subject to customary conditions, required third-party consents, new license agreements and approval by one seller’s shareholders.
Books Market Report Scope and Research Methodology
Market Definition and Coverage
The global books market measures annual publisher-level revenue from new hard-copy books, e-books, and professionally produced audiobooks sold worldwide. It covers books across all genres and distribution channels, including sales to readers and institutional buyers.
Scope exclusions: Used-book resale, self-published titles without ISBN registration, and illicit digital downloads are excluded.
Segments Covered in This Report
- By Format
- Hard Copy
- E-books
- Audiobooks
- By Genre
- Fiction
- Non-Fiction
- Educational and Academic
- Children and Young Adult
- Religious / Spiritual
- Comics and Graphic Novels
- By Distribution Channel
- Online Retail
- Bookstores
- Supermarkets / Convenience Stores
- Direct-to-Consumer and Subscriptions
- Libraries and Institutional Procurement
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Association of American Publishers' StatShot, which provides estimated publisher revenue and reported unit sales by format, genre, and sales channel in the United States, and the Audio Publishers Association's sales survey, which helps assess audiobook receipts and catalog growth, anchor the format and channel estimates. The U.S. Census Bureau's retail time series can indicate shifts in bookstore activity, and reporting by Publishers Weekly offers a cross-check on industry estimates and publisher conditions.
Publisher filings, annual reports, investor materials, and reputable trade coverage can clarify the mix of consumer and institutional revenue, rights licensing, and format releases. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured surveys with publishing executives, format and rights leads, sales and distribution managers, and institutional procurement specialists would test how secondary evidence maps to publisher-recognized revenue across formats and channels. Analysts would use responses to clarify gaps in regional and segment evidence, compare reported assumptions with independent market signals, and reconcile differing estimates before incorporating supported adjustments.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
A top-down estimate would start with global publisher-level book revenue and reconcile it to the defined new-book transaction basis, with selective bottom-up checks from sampled publisher revenue and channel evidence. The model would distinguish hard-copy, e-book, and audiobook receipts, then allocate value across genre, channel, and geography using publisher reporting, trade and institutional sales indicators, format mix, and country-level market signals. Unsupported splits would be checked against available totals and carried only when evidence supports them. Historical revenue and indicators such as school procurement, household reading and listening, online retail activity, and format adoption would inform a multivariate regression or scenario analysis, with assumptions compared across regions and forecast years. Primary respondents would check whether the selected variables and resulting segment paths reflect publisher revenue recognition and current commercial practice, while analysts would investigate gaps between sampled roll-ups and the top-down total before using the evidence.
Data Validation & Update Cycle
Analysts would triangulate publisher revenue, channel and format indicators, regional signals, and comparable external estimates, then review anomalies, source-year differences, and variance from prior periods. A second analyst review would trace material adjustments to their supporting evidence, and analysts would re-contact respondents when definitions conflict or a major input changes. The model would be refreshed annually, revisited between cycles after material market events, and given a fresh pre-delivery review.
Mordor Intelligence's Books Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. It covers books across all genres and distribution channels, including sales to readers and institutional buyers.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Historical revenue and indicators such as school procurement, household reading and listening, online retail activity, and format adoption would inform a multivariate regression or scenario analysis, with assumptions compared across regions and forecast years.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 139.7 B (2027) | |
| Global Consultancy A | USD 85.9 B (2027) | At its 2027 base, this estimate is 38.5% below this report's 2027 value of USD 139.7 B. Its stated series covers physical books and e-books, excluding audiobook receipts from this all-format comparison. |
| Global Consultancy B | USD 107.6 B (2026) | At its 2026 base, this estimate is 23.0% below this report's 2027 value of USD 139.7 B, 1 year later. Its measurement year precedes the report's current year, which can contribute to a lower level. |
For Mordor Intelligence, a second analyst review would trace material adjustments to their supporting evidence, and analysts would re-contact respondents when definitions conflict or a major input changes.
Key Questions Answered in the Report
What is the books market size and growth outlook?
The size is forecast to reach USD 161.5 billion by 2032, from USD 139.7 billion in 2027, at a 2.94% CAGR over 2027-2032.
Which forces support demand for books?
Nigeria’s approved textbook list covers selected grades for use in schools during 2026-2028. Commuter audiobook listening in Germany and Spain also supports audio demand.
What is the leading book format?
Hard copy led with a 76.05% share of the market in 2026. Audiobooks are the fastest-growing format, with an 8.25% CAGR forecast over 2027-2032.
Which companies are major book publishers?
Major participants include Penguin Random House LLC, Hachette Livre, HarperCollins Publishers LLC, Pearson PLC and Macmillan Publishers.
What challenges could limit book sales growth?
ReaderLink ended mass-market paperback distribution to its accounts at the end of 2025, and Denmark applied 25% e-book VAT in July 2025. An October 2026 proposal would introduce zero e-book VAT from July 2027 if enacted.
Which regions lead book revenue and forecast growth?
Asia-Pacific held a 37.02% share of the market in 2026. The Middle East and Africa is the fastest-growing region, with a 4.6% CAGR forecast over 2027-2032.