
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 6.55 Billion |
| Market Size (2026) | USD 7.07 Billion |
| Market Size (2031) | USD 10.33 Billion |
| Growth Rate (2026 - 2031) | 7.89 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
United States Automotive Collision Avoidance Systems Market Analysis by Mordor Intelligence
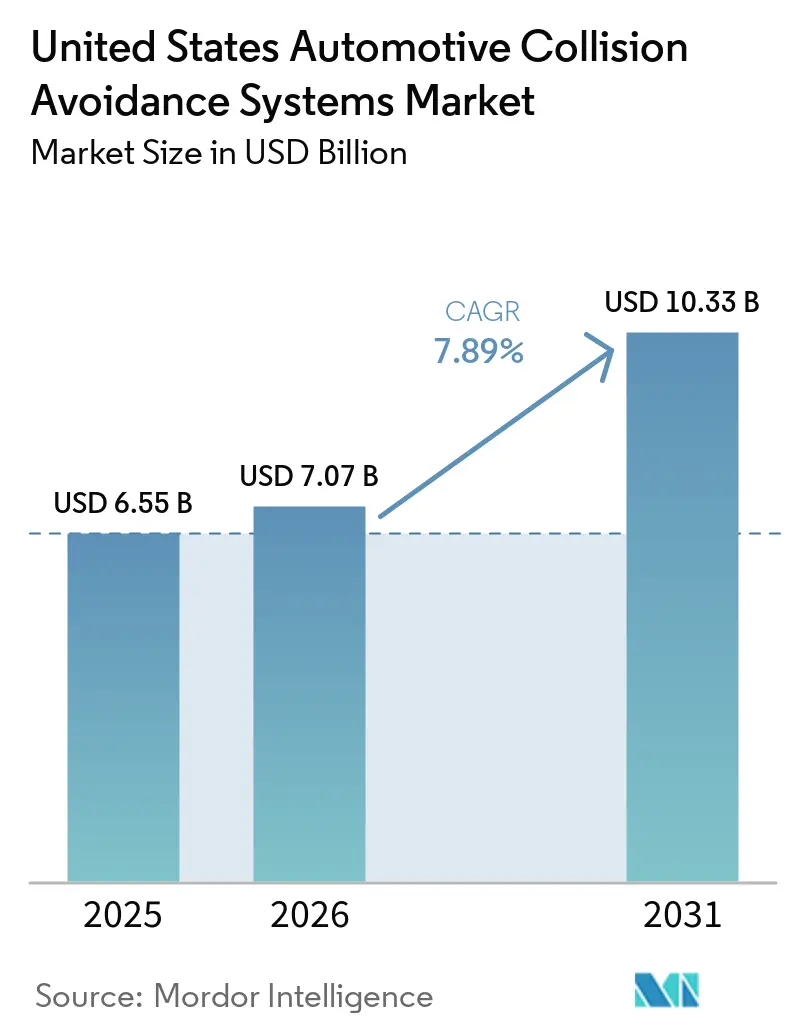
The United States automotive collision avoidance systems market was valued at USD 6.55 billion in 2025 and is estimated at USD 7.07 billion in 2026 and is projected to reach USD 10.33 billion by 2031, at a CAGR of 7.89% during the forecast period (2026-2031). Federal requirements for automatic emergency braking are moving collision avoidance equipment from optional packages into standard vehicle programs. The United States automotive collision avoidance systems market is also changing as automakers combine radar, cameras, and software in fewer electronic control units. This favors suppliers that can validate complete systems and support vehicle programs over several model years. Repair, recalibration, and semiconductor availability remain important considerations because safety features need support after sale as well as during production. The United States automotive collision avoidance systems market therefore depends on reliable sensor performance, manufacturing readiness, and clear driver communication.
Key Report Takeaways
- By function type, warning held 35.56% of the United States automotive collision avoidance systems market share in 2025, while automated is projected to grow at an 8.81% CAGR through 2031.
- By technology type, radar held a 41.11% share in 2025, while camera is projected to grow at a 15.71% CAGR through 2031.
- By vehicle type, passenger cars held an 80.29% share in 2025 and are projected to grow at an 8.29% CAGR through 2031.
- By application, adaptive cruise control held a 27.78% share in 2025, while blind spot detection is projected to grow at a 16.83% CAGR through 2031.
- By state, California held a 14.45% share in 2025, while Ohio is projected to grow at an 8.85% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
United States Automotive Collision Avoidance Systems Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Federal AEB and Pedestrian AEB Standardization | +2.1% | National; compliance investment concentrated in California, Texas, Michigan, and Florida OEM channels | Long-term (≥ 4 years) |
| OEM Standard-Fit Expansion Across Volume Vehicles | +1.8% | National; production cascades felt earliest in Michigan, California, and Texas assembly corridors | Long-term (≥ 4 years) |
| Rising Consumer and Fleet Demand for Verified Crash Avoidance | +1.4% | California, Texas, Florida, New York, Ohio | Medium-term (2–4 years) |
| Sensor Fusion and Edge-AI Cost Curve Improvement | +1.2% | Michigan, California, Texas, Ohio (primary automotive R&D hubs) | Medium-term (2–4 years) |
| Insurance and Repair-Economics Incentives for Preventive Safety | +0.9% | California, Florida, New York, Texas, Pennsylvania | Short-term (≤ 2 years) |
| United States Nighttime and Vulnerable-Road-User Performance Gap | +0.6% | Florida, Arizona, Texas, California (high-pedestrian-fatality urban arterials) | Medium-term (2–4 years) |
| Source: Mordor Intelligence | |||
Federal AEB and Pedestrian AEB Standardization
The federal automatic emergency braking rule sets a clear equipment deadline for the United States automotive collision avoidance systems market. NHTSA finalized FMVSS No. 127 in 2024 and requires automatic emergency braking, including pedestrian automatic emergency braking, on new light vehicles by September 2029[1]. The standard makes consistent detection performance a vehicle-wide design requirement rather than a feature reserved for selected trims. Automakers must evaluate sensing, braking control, software validation, and driver alerts as one safety system. It raises the value of suppliers that can support testing, production launch, updates, dependable nighttime operation, and pedestrian detection. The rule also gives manufacturers a common basis for selecting hardware and software partners while increasing the importance of avoiding unnecessary braking events.
OEM Standard-Fit Expansion Across Volume Vehicles
The shift from option packages to standard equipment increases the number of vehicles that need collision avoidance hardware. It also changes procurement because an automaker may select a platform for several vehicle lines instead of buying separate components for each feature. The United States automotive collision avoidance systems market gains when a common architecture can support entry models and higher-content vehicles without repeated redesign. Standard fitment creates longer supply commitments for sensors, compute hardware, software, and service support. It requires automakers to manage cost, reliability, wiring, packaging, and updates across several trims. Suppliers that offer scalable platforms can meet this need while preserving meaningful differences between premium and volume programs.
Rising Consumer and Fleet Demand for Verified Crash Avoidance
Fleet buyers evaluate safety equipment through vehicle downtime, claims history, repair disruption, and driver management needs. Their purchasing process differs from that of individual buyers because operating results can be reviewed across many vehicles. IIHS reported that vehicles equipped with more comprehensive driver-assistance feature bundles were associated with lower property-damage liability claim rates[2]. This supports a practical case for combining several assistance functions rather than treating each feature as a standalone add-on. The United States automotive collision-avoidance systems market can benefit as fleets specify safety capabilities in procurement requirements. It can also benefit when insurers and fleet managers use consistent evidence to compare equipment packages.
Sensor Fusion and Edge-AI Cost Curve Improvement
Sensor fusion is improving the way vehicles combine radar, camera, and ultrasonic inputs to interpret distance, movement, lanes, and nearby objects. The United States automotive collision avoidance systems market benefits when functions that once required separate electronic control units can operate through a more integrated architecture. Local processing can shorten the path between sensing and a warning or braking decision while reducing wiring and packaging demands. Bosch introduced radar system-on-chips that combine radar sensing with onboard processing for advanced driver assistance functions, which illustrates this approach. Suppliers that can align sensors, compute hardware, software, and repair procedures are better placed to support automakers seeking lower integration costs and dependable system performance.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High System Integration and Calibration Cost | -0.9% | California, Texas, New York, Pennsylvania, Ohio (dense collision-repair and OEM service markets) | Medium-term (2–4 years) |
| Semiconductor and Sensor Supply-Chain Volatility | -0.7% | National; first-order impact in Michigan, Texas, and California automotive assembly clusters | Long-term (≥ 4 years) |
| Performance Degradation in Darkness, Adverse Weather, and Complex Road Geometry | -0.5% | Illinois, Pennsylvania, New York, Ohio (snow-belt states); Arizona (sun glare conditions) | Medium-term (2–4 years) |
| Consumer Trust, False Alerts, and Liability Allocation | -0.4% | California, Texas, Florida (highest AV/ADAS litigation and incident-reporting density) | Short-term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High System Integration and Calibration Cost
Collision avoidance systems need accurate alignment after a repair affecting a windshield, bumper, grille, camera, or other sensor location. This creates a service requirement that can follow even a minor collision. Repair facilities need trained technicians, suitable work areas, tools, targets, and access to model-specific procedures. A vehicle can leave the factory with a capable system, but still create customer dissatisfaction if recalibration is difficult to arrange after damage. Consistent diagnostics and clear repair guidance can help preserve intended performance and reduce uncertainty for vehicle owners and fleets.
Semiconductor and Sensor Supply-Chain Volatility
Collision avoidance equipment depends on specialized semiconductors, sensors, power devices, and communication components. A shortage of any one input can interrupt vehicle production because these parts work within a broader electronic architecture. Automotive suppliers cannot simply substitute a new part without confirming safety, durability, hardware, and software compatibility. This makes alternative-source qualification a long-term planning task rather than a quick purchasing response. Early supplier diversification can add development work, but it can reduce disruption when a supporting component becomes unavailable.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Function Type: Automated Systems Gain Importance Alongside Warning Functions
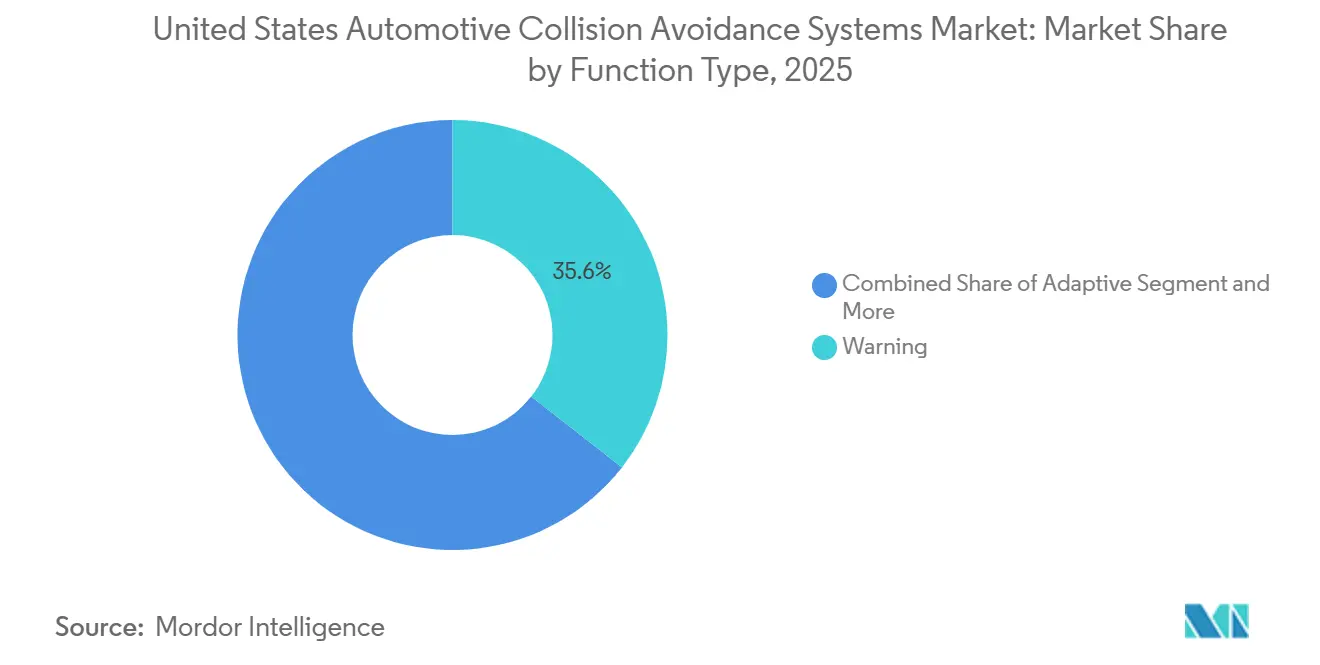
Warning functions held 35.56% of the United States automotive collision avoidance systems market share by function type in 2025. This category includes forward collision warning, lane departure alerts, blind spot alerts, and related functions that prompt drivers to respond. Its established role reflects the familiarity of alert-based assistance across many vehicle categories. Warning functions can be introduced without changing the driver’s primary responsibility for controlling the vehicle. They also provide a common foundation for safety packages that include more active forms of support.
Automated functions are projected to grow at an 8.81% CAGR through 2031. This group includes systems that can apply braking or provide steering assistance when a vehicle identifies an imminent risk. Their growth reflects the wider move toward intervention when a driver does not react in time. Monitoring functions remain relevant because information about driver attention can shape how a warning or intervention is delivered. Adaptive functions, including adaptive cruise control, continue to bridge basic alerts and more active assistance during routine driving.



By Technology Type: Radar Remains Established as Cameras Expand
Radar held 41.11% of technology revenue in 2025 within the United States automotive collision avoidance systems market. Its position reflects its ability to measure distance and relative speed across a range of driving situations. Automakers use radar to support adaptive cruise control, forward collision support, and other functions that depend on reliable range information. It can provide an important input when lighting conditions make visual sensing more difficult. Radar is increasingly combined with other technologies rather than used as a standalone solution.
Camera technology is projected to grow at a 15.71% CAGR through 2031. Cameras help the vehicle interpret lanes, road users, signs, and the broader visual context surrounding an object. This makes them important when a system needs more detailed scene understanding, including pedestrian recognition. LiDAR remains relevant for selected programs that require detailed three-dimensional perception, although its use differs by vehicle line. Ultrasonic sensors continue to support close-range functions, particularly parking and low-speed maneuvering.
By Vehicle Type: Passenger Cars Sustain the Broadest Deployment
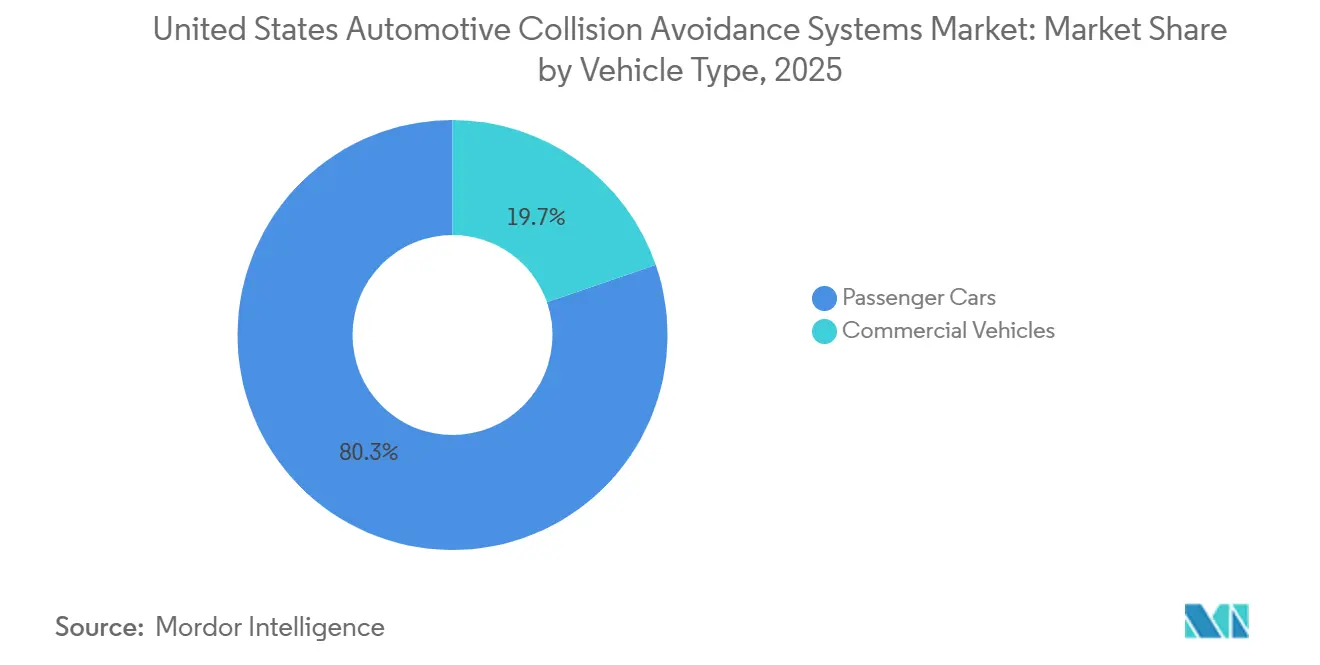
Passenger cars accounted for 80.29% of the vehicle category in 2025. Their position reflects the scale of light-vehicle production and the broad reach of consumer and fleet purchases. Automakers can standardize safety features across passenger-vehicle lines by using common electronic platforms. The segment includes privately owned vehicles as well as vehicles used for delivery, rental, and service work. This makes passenger cars important for original equipment installation and long-term repair demand.
Passenger cars are projected to grow at an 8.29% CAGR through 2031. Commercial vehicles have a different operating profile because they can require wider sensing coverage and robust support for longer use cycles. Their safety systems may also face different loading, trailer, and operating conditions. The core objective remains similar because vehicle operators need reliable warnings and appropriate intervention. The future direction of heavy-vehicle safety requirements will shape how quickly these systems are adopted across commercial platforms.

By Application: Adaptive Cruise Control Leads While Blind Spot Detection Accelerates
Adaptive cruise control held 27.78% of application revenue in 2025. It is often one of the first advanced driver assistance functions that drivers use during routine highway travel. The function manages vehicle spacing and can make longer journeys less demanding when traffic conditions are appropriate. Automakers commonly pair it with forward sensing and braking functions. This makes adaptive cruise control an important entry point for broader collision avoidance packages.
Blind spot detection is projected to grow at a 16.83% CAGR through 2031. The function assists drivers during lane changes by identifying vehicles that may not be visible in mirrors. NAIC materials identify blind spot warning as one of the driver assistance features assessed in relation to insurance claims and crash prevention. Forward collision warning, automatic emergency braking, lane departure warning, and parking assistance continue to support different stages of the driving task. A coherent set of alerts can help drivers understand how these applications operate together.
Geography Analysis
California accounted for 14.45% of the state segment in 2025. California, Texas, and Florida have strong demand conditions because of vehicle activity, dense urban routes, and high exposure to complex driving situations. California also offers a setting where manufacturers can assess systems across commuter traffic, highways, and pedestrian-heavy areas. This helps suppliers gather operational learning that can inform wider vehicle programs. The state is important not only because vehicles are sold there, but also because technology developers and automakers use it to refine safety functions. The United States automotive collision avoidance systems market benefits when lessons from these use cases can be applied to mainstream vehicle designs.
Ohio is expected to grow at an 8.85% CAGR through 2031, supported by its place in the Midwest automotive manufacturing network. Michigan, Ohio, Pennsylvania, and Illinois play a different role from high-demand coastal states because they are closely connected to engineering, sourcing, assembly, and winter-condition validation. Michigan remains important for vehicle program decisions and supplier coordination. Pennsylvania and Illinois offer cold-weather conditions that help manufacturers evaluate performance when roads, lighting, and visibility change. These locations matter as automakers prepare vehicles for broad national use rather than a single climate. The United States automotive collision avoidance systems market needs this range of testing conditions to support dependable performance.
New York, Arizona, and other states add distinct operating environments to the national picture. New York provides dense intersections, pedestrians, and frequent lane changes that can test the practical behavior of driver assistance features. Arizona offers dry, bright conditions that are useful for assessing sensor behavior in heat and strong sunlight. Other manufacturing and logistics centers can create demand through vehicle assembly, commercial transport, and fleet operations. The United States automotive collision avoidance systems market will develop differently by state because road conditions, vehicle mix, and service capacity are not the same everywhere. A national safety requirement can still produce local differences in testing, installation, calibration, and customer experience.
Competitive Landscape
Market Concentration
The United States automotive collision avoidance systems market is highly concentrated because the leading suppliers collectively account for the majority of original equipment design wins, while several specialized technology and component providers remain active. The market is led by suppliers that combine sensing, compute hardware, software, and vehicle integration support. Robert Bosch GmbH, DENSO Corporation, ZF Friedrichshafen AG, Aptiv PLC, and Mobileye Global Inc. are important participants in this supplier group. Competition centers on whether a company can support complete vehicle programs rather than simply sell an individual sensor. Automakers need systems that work with braking controls, electrical architectures, driver displays, and diagnostic tools. Suppliers also need to support validation over the life of a vehicle program. This creates an advantage for companies with broad engineering resources and established relationships with vehicle manufacturers.
Platform integration is an important competitive strategy in the United States automotive collision avoidance systems market. Leading suppliers seek to combine radar, cameras, processing, and software into a system that can be deployed across several models. This can reduce the effort needed to qualify different parts from separate vendors. It also makes software maintenance and feature updates easier for automakers to manage. Mobileye has focused on integrated perception and compute platforms for advanced driver assistance programs. Bosch has continued to develop radar-based systems that combine sensing and processing closer to the sensor. Aptiv has also advanced radar platforms for future vehicle architectures, showing that performance and scalability remain important points of competition.
The competitive field also includes semiconductor companies and service specialists that support vehicle safety systems. Infineon Technologies, NXP Semiconductors, Texas Instruments, Analog Devices, and NVIDIA provide components or computing platforms used in automotive electronics. Their role matters because system suppliers need dependable processors, power management, and signal handling to deliver finished safety functions. Calibration and repair providers are becoming more visible as the installed base of sensor-equipped vehicles expands. HARMAN's planned acquisition of ZF's ADAS business illustrates continued interest in combining automotive electronics and safety technology capabilities.
United States Automotive Collision Avoidance Systems Industry Leaders
-
Robert Bosch
-
ZF Friedrichshafen AG
-
DENSO Corporation
-
Aptiv PLC
-
Mobileye Global Inc.
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- August 2026: BMW announced plans to introduce a new set of active safety features as standard equipment as part of its transition to "Neue Klasse" vehicles. For 2026, the focus shifted toward driver monitoring (in-cabin cameras) and systems designed to prevent accidents by intervening in the vehicle in anticipation of a crash.
- June 2026: Pro-Vision, a fleet safety solutions provider, launched its Birdseye 360° AI Camera System, offering 360° vehicle coverage and real-time AI detection to improve fleet safety.
United States Automotive Collision Avoidance Systems Market Report Scope
Automotive collision avoidance systems are advanced safety technologies designed to prevent or mitigate accidents on the road. They use various sensors and communication tools to monitor the surroundings and provide warnings or automatic interventions to help drivers avoid potential collisions with other vehicles, pedestrians, or obstacles.
The United States Automotive Collision Avoidance Systems Market is segmented by function type, technology type, vehicle type, application, and state. By Function Type, the market is segmented into Adaptive, Automated, Monitoring, and Warning. By Technology Type, the market is segmented into Radar, LiDAR, Camera, and Ultrasonic. By Vehicle Type, the market is segmented into Passenger Cars and Commercial Vehicles. By Application, the market is segmented into Adaptive Cruise Control, Autonomous Emergency Braking, Forward Collision Warning, Blind Spot Detection, Lane Departure Warning, and Parking Assistance. By State, the market is segmented into California, Texas, Florida, New York, Ohio, Arizona, Pennsylvania, Illinois, and the rest of the United States. Market forecasts are provided in terms of Value (USD).
By Function Type
| Adaptive |
| Automated |
| Monitoring |
| Warning |
By Technology Type
| Radar |
| LiDAR |
| Camera |
| Ultrasonic |
By Vehicle Type
| Passenger Cars |
| Commercial Vehicles |
By Application
| Adaptive Cruise Control (ACC) |
| Autonomous Emergency Braking (AEB) |
| Forward Collision Warning (FCW) |
| Blind Spot Detection (BSD) |
| Lane Departure Warning (LDW) |
| Parking Assistance |
By State
| California |
| Texas |
| Florida |
| New York |
| Ohio |
| Arizona |
| Pennsylvania |
| Illinois |
| Rest of the United States |
| By Function Type | Adaptive |
| Automated | |
| Monitoring | |
| Warning | |
| By Technology Type | Radar |
| LiDAR | |
| Camera | |
| Ultrasonic | |
| By Vehicle Type | Passenger Cars |
| Commercial Vehicles | |
| By Application | Adaptive Cruise Control (ACC) |
| Autonomous Emergency Braking (AEB) | |
| Forward Collision Warning (FCW) | |
| Blind Spot Detection (BSD) | |
| Lane Departure Warning (LDW) | |
| Parking Assistance | |
| By State | California |
| Texas | |
| Florida | |
| New York | |
| Ohio | |
| Arizona | |
| Pennsylvania | |
| Illinois | |
| Rest of the United States |
Key Questions Answered in the Report
What is driving demand for automotive collision avoidance systems in the United States?
Federal automatic emergency braking requirements, standard-fit vehicle programs, and fleet safety needs are supporting wider adoption.
How large is the United States automotive collision avoidance systems market?
The market is estimated at USD 7.07 billion in 2026 and is forecast to reach USD 10.33 billion by 2031.
Which function type held the largest share in 2025?
Warning functions led the function type category with a 35.56% share in 2025.
Which sensing technology is growing fastest?
Camera technology is projected to grow at a 15.71% CAGR through 2031 as vehicle programs require stronger visual scene interpretation.