
UAE Contract Logistics Market Size and Share
Market Overview
| Study Period | 2021 - 2032 |
|---|---|
| Forecast Data Period | 2027 - 2032 |
| Base Year Market Size (2026) | USD 1.36 Billion |
| Market Size (2027) | USD 1.47 Billion |
| Market Size (2032) | USD 2.11 Billion |
| Growth Rate (2027 - 2032) | 7.56 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
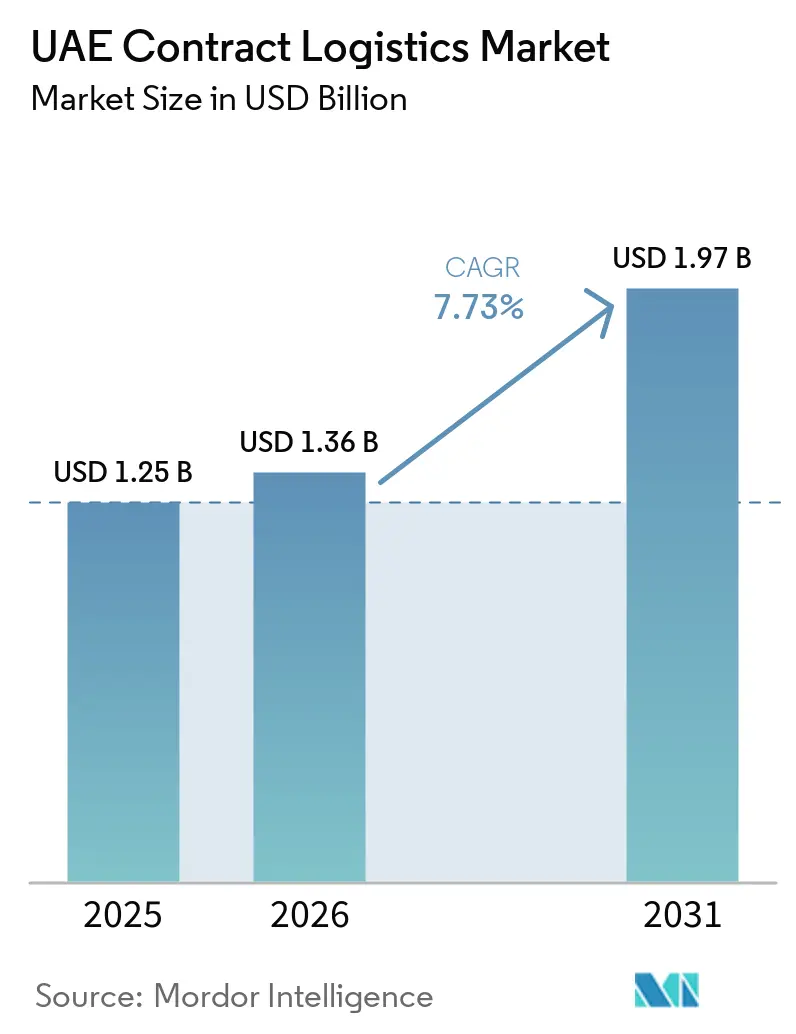
UAE Contract Logistics Market Analysis by Mordor Intelligence
The UAE contract logistics market size is valued at USD 1.36 billion in 2026 and is estimated to grow from USD 1.47 billion in 2027 and reach USD 2.11 billion by 2032 at a 7.56% CAGR over 2027-2032.
The UAE contract logistics market is moving beyond freight transit toward bonded warehousing, temperature-controlled fulfillment, and integrated supply chain management. More than 40 specialized free zones, zero import duty, and 100% foreign ownership continue to shorten location decisions for multinational shippers. Service quality in specialized verticals is becoming more important than price for longer contracts and higher revenue per square meter. Free-zone expansion, e-commerce fulfillment, and rail-linked logistics are strengthening the UAE contract logistics market, while limited Grade A capacity raises the value of well-located facilities. Large providers are responding through long leaseholds, broader networks, and regulated healthcare capability, which raises the entry threshold for smaller operators.
Key Report Takeaways
- By service type, transportation held 61.84% of the UAE contract logistics market share in 2026, while value-added services registered a 5.85% CAGR through 2032.
- By contract duration, 1-3 years held 63.55% of the UAE contract logistics market size in 2026, while above 3 years registered a 5.43% CAGR through 2032.
- By end-user industry, manufacturing and automotive held 34.22% of the UAE contract logistics market share in 2026, while retail and e-commerce registered a 6.16% CAGR through 2032.
- By geography, Dubai held 37.20% of the UAE contract logistics market size in 2026, while Abu Dhabi registered a 5.24% CAGR through 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of UAE Contract Logistics Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| E-commerce and Omnichannel Fulfillment Expansion | +1.8% | Dubai core, spill-over to Abu Dhabi and Sharjah | Short term (≤ 2 years) |
| Re-export Growth Through Free Zones and Multimodal Hubs | +1.5% | Global, anchored in Dubai and Abu Dhabi | Medium term (2-4 years) |
| Shipper Shift Toward Asset-Light, Integrated Supply Chains | +1.2% | Global, with early gains in Dubai South and JAFZA | Medium term (2-4 years) |
| Healthcare, Pharmaceutical, and Temperature-Controlled Logistics Demand | +1.4% | Dubai South, Abu Dhabi, nationwide | Long term (≥ 4 years) |
| Bonded Air-Sea-Rail Connectivity Around Dubai South and Jebel Ali | +1.0% | Dubai-Abu Dhabi-Fujairah multimodal corridor | Long term (≥ 4 years) |
| Sovereign-Backed Integration of Logistics Assets and Networks | +0.9% | National, with early concentration in Abu Dhabi and Dubai | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
E-Commerce and Omnichannel Fulfillment Expansion
E-commerce is a near-term catalyst for the UAE contract logistics market. Dubai Chamber of Commerce and Industry estimated in 2025 an increase in the need for automated distribution across several sales channels. CEVA Logistics opened a 23,000 m² e-commerce warehouse in Dubai South Free Zone in January 2026, with capacity to process more than 30,000 units daily at launch. The facility shows how operators are positioning dedicated capacity close to regional distribution routes. Demand is also favoring mid-sized facilities that can support rapid inventory changes and shared fulfillment operations. This creates an opening for providers with modular, multi-client capacity within bonded free zones.[1]
Re-export Growth Through Free Zones and Multimodal Hubs
The UAE contract logistics market benefits from free zones that serve re-export activity as well as domestic demand. JAFZA invested AED 90 million (USD 24.5 million) in Phase 2 of its Logistics Park in March 2025, adding 360,000 ft² of Grade A capacity for logistics, freight forwarding, and value-added services. Phase 1 was fully leased before completion, which points to demand for operational logistics space rather than speculative construction. Free-zone users can process, relabel, and re-export goods with limited customs friction. These activities increase demand for packaging, inventory handling, and re-export management.[2]
Shipper Shift Toward Asset-Light, Integrated Supply Chains
Manufacturers and retailers are redirecting investment away from owned logistics assets toward outsourced operations in the UAE contract logistics market. Their requirements now extend beyond storage to transportation, bonded warehousing, customs brokerage, and value-added processing under a single contract. DSV completed the integration of Schenker operations in Dubai in December 2025, doubling its warehousing footprint across JAFZA and Dubai World Central. The combined operating model brings air, sea, road, contract logistics, and customs services into one UAE structure. Larger contracts are also shifting toward hybrid terms with throughput-based components. Such terms can limit exposure to rising facility costs during longer agreements.
Healthcare, Pharmaceutical, And Temperature-Controlled Logistics Demand
Healthcare and pharmaceutical logistics is becoming a more important part of the UAE contract logistics market. Domestic healthcare demand, life sciences investment, and regional distribution activity are raising the need for controlled storage and transport. Kuehne+Nagel’s UAE facility received Emirates Drug Establishment certification in 2025 to store raw pharmaceutical materials. FedEx’s Dubai World Central hub achieved IATA CEIV Pharma certification in October 2026, confirming compliance for temperature-controlled pharmaceutical handling. These certifications can support longer contracts where compliance and service quality are central to customer selection.
Restraints Impact Analysis of UAE Contract Logistics Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Fuel, Labor, and Facility Operating Costs | -0.8% | Dubai, Abu Dhabi, prime logistics zones | Short term (≤ 2 years) |
| Customs, Licensing, and Cross-Border Compliance Complexity | -0.5% | National, with heavier burden on Northern Emirates corridors | Medium term (2-4 years) |
| Tight Modern Fulfillment Capacity in Prime Logistics Zones | -0.4% | Dubai South, JAFZA, KEZAD | Short term (≤ 2 years) |
| Geopolitical Disruption and Route-Rerouting Exposure | -0.3% | Global, with acute impact on Jebel Ali vessel traffic | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Fuel, Labor, and Facility Operating Costs
Rising operating costs challenge margins across the UAE contract logistics market. Providers face pressure from facility costs, labor availability, and fuel price changes. Fixed-price contracts signed for 1-3 years can become less attractive when operating expenses rise during the contract term. Specialized cold chain and pharmaceutical roles are particularly sensitive to labor availability because they require trained staff. Fuel variability also encourages contracts with escalation provisions or throughput-based pricing. Operators with owned sites or long leaseholds secured before recent cost increases have a clear cost position relative to new entrants.
Customs, Licensing, and Cross-Border Compliance Complexity
Different licensing frameworks across JAFZA, Dubai South, KEZAD, and Sharjah add complexity for operators building nationwide networks. Healthcare and pharmaceutical activities have further requirements under the Emirates Drug Establishment and Ministry of Health frameworks. Kuehne+Nagel’s Emirates Drug Establishment certification shows the formal approval required for handling raw pharmaceutical materials. Cross-border shipments to Saudi Arabia and Oman also need compliance with separate customs rules. These requirements add cost and administrative work for mid-sized providers. Global integrated groups can spread that work across wider regulatory and operating teams.[3]
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
UAE Contract Logistics Market Segment Analysis
By Service Type:
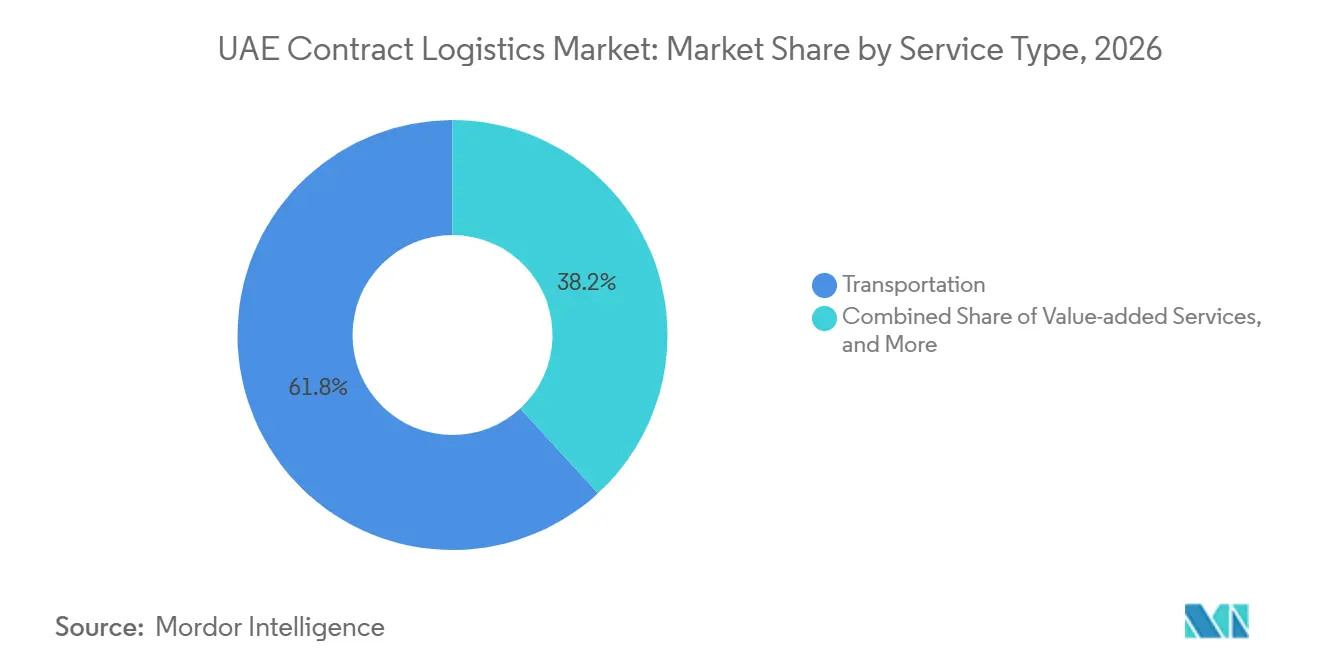
Transportation Holds the Largest Position While Value-added Services AdvanceTransportation accounted for 61.84% of the UAE contract logistics market size in 2026. Road freight supports last-mile delivery and cross-border distribution, while sea freight remains central to Jebel Ali Port activity. Air freight benefits from Dubai World Central’s pharmaceutical handling capability, while rail can gain relevance as national freight connections expand. Transportation connects these freight modes with customers’ storage and distribution requirements.[4]Warehousing and Distribution remained the second-largest service type, supported by demand for modern logistics facilities.
Value-added services are forecast to record a 5.85% CAGR from 2027 to 2032. The service category includes assembly, labeling, kitting, quality control, and inventory-related activities. JAFZA’s Phase 2 Logistics Park includes space for logistics, freight forwarding, and value-added services. This investment reflects the move toward processing and customization within free-zone facilities. Fulfillment sites are taking on work that connects storage with light production and returns handling.



By Contract Duration:
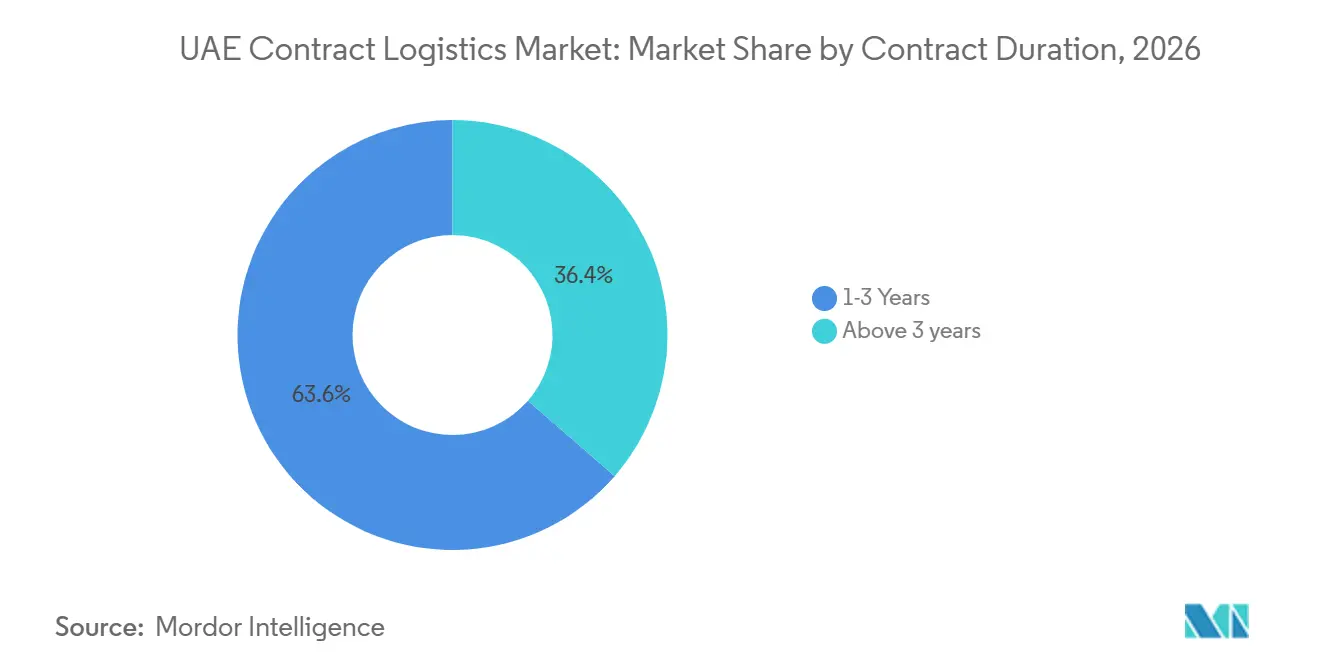
Shorter Agreements Lead While Longer Partnerships GrowThe 1-3 years category held 63.55% of the UAE contract logistics market size in 2026. Shippers use shorter agreements while they assess providers’ ability to scale bonded, temperature-controlled, and automated operations. This approach reflects the pace of new facility delivery and changing customer requirements. It also gives customers time to compare service capability across providers. Providers need to demonstrate reliable performance before customers extend commitments.
Above 3 years is projected to grow at a 5.43% CAGR from 2027 to 2032. Longer agreements are gaining ground where providers can support pharmaceutical, automotive, and other specialized operations. DHL Supply Chain signed a EUR 120 million (USD 141.15 million), 38-year leasehold agreement in Dubai South in December 2025 for a 96,000 m² land plot. The company is also planning a 55,000 m² multi-user contract logistics warehouse near Al Maktoum International Airport. The commitment supports long-term investment in dedicated assets and shared efficiency arrangements.

By End-user Industry:
Manufacturing and Automotive Leads While Retail and E-commerce Grows FastestManufacturing and automotive held 34.22% of the UAE contract logistics market share in 2026. The segment is closely linked with re-export activity through JAFZA and bonded corridors serving African and South Asian destinations. DP World expanded its vehicle storage yard at Jebel Ali Terminal 4 by 2.6 million ft² and 13,000 CEUs. The expansion shows the scale of vehicle logistics needs at the port. Food and beverage, healthcare and pharmaceuticals, and chemicals also create demand for specialized logistics services.
Retail and e-commerce is projected to grow at a 6.16% CAGR from 2027 to 2032. Cross-border purchases and the UAE’s role as a regional distribution center support this growth. RSA Global launched a 10,000 m² hub at EZDubai in May 2026, designed to process 20,000 B2C orders daily. The facility operates in a bonded, duty-free setting within Dubai South. Multi-client warehousing can serve healthcare and consumer goods customers when compliance standards allow it.
Geography Analysis
Dubai held 37.20% of the UAE contract logistics market share in 2026. JAFZA and Dubai South continue to anchor the emirate’s logistics activity. Dubai South launched multi-user facilities spanning 215,278 ft² in July 2025. Dubai South also signed a facility agreement with UPS in March 2025. DHL Supply Chain’s December 2025 leasehold agreement covers a 96,000 m² plot for a planned 55,000 m² multi-user warehouse.
Abu Dhabi is projected to grow at a 5.24% CAGR from 2027 to 2032. KEZAD and Abu Dhabi’s wider logistics network are adding capacity and attracting international operators. AD Ports Group established an inland multimodal network in May 2026 that linked cargo flows through Khalifa Port and Fujairah Terminals with rail-linked depots. The network serves customers in aluminum, steel, and industrial materials. An agreement with CMA Terminals Khalifa Port and CMA CGM Group adds support for intermodal logistics solutions across the UAE and wider region.
Sharjah and the Rest of the UAE provide alternatives for operators that do not need the most specialized bonded free-zone facilities. Fujairah and Ras Al Khaimah gain importance as east-coast connections become more integrated with inland freight routes. The bonded rail corridor supports movement between Khalifa Port and Fujairah Terminals under customs control. Noatum Logistics and Hafeet Rail signed a preliminary agreement in October 2025 for a daily service between Sohar and Abu Dhabi, projected to handle 193,200 TEUs annually.
Competitive Landscape
Market Concentration
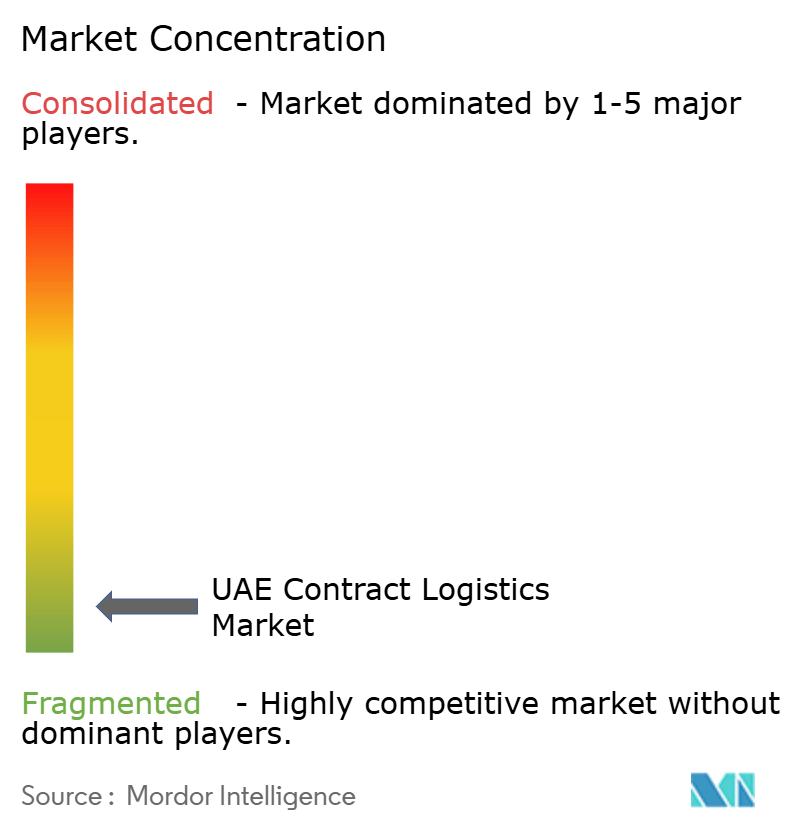
The UAE contract logistics market is moderately concentrated, with global integrated providers and sovereign-backed regional operators controlling substantial Grade A logistics capacity. Competition centers on network scale, long-term site control, integrated service coverage, and regulated healthcare capability. DSV completed the Schenker integration in Dubai in December 2025 and doubled its warehousing footprint across JAFZA and Dubai World Central. DHL Supply Chain committed EUR 120 million (USD 141.15 million) to a 38-year leasehold arrangement in Dubai South during the same month. These moves increase the capital and site-access requirements for newer providers seeking large regional contracts.
Healthcare compliance is becoming another competitive distinction. Kuehne+Nagel received Emirates Drug Establishment certification for raw pharmaceutical material storage in the UAE. FedEx’s Dubai World Central hub secured IATA CEIV Pharma certification in October 2026. RSA Cold Chain launched a 40,000-pallet-position JAFZA facility in September 2025 through a joint venture between RSA Global and Americold. Smaller specialists can stay relevant through local coverage and sector knowledge, but they are less likely to compete for broad, single-provider regional mandates.
Technology is also influencing service quality across the UAE contract logistics market. Hellmann launched robotics automated storage solutions at Dubai CommerCity in February 2025. DP World and Dubai’s Roads and Transport Authority signed an agreement in October 2025 to develop smart and integrated digital logistics solutions. Opportunities remain in Northern Emirates last-mile coverage, multi-client cold chain facilities, and bonded warehousing for smaller re-export shippers.
UAE Contract Logistics Industry Leaders
-
Aramex
-
Gulf Agency Company (GAC)
-
DHL Group
-
Kuehne+Nagel
-
CMA CGM Group (Including CEVA Logistics)
- *Disclaimer: Major Players sorted in no particular order
UAE Contract Logistics Market Companies Covered in this Report
- Aramex
- DHL Group
- FedEx
- Kuehne+Nagel
- Gulf Agency Company Limited
- CMA CGM Group (Including CEVA Logistics)
- DSV A/S
- United Parcel Service of America, Inc. (UPS)
- GEODIS
- Agility Logistics
- Al-Futtaim Logistics
- Emirates Logistics LLC
- Hellmann Worldwide Logistics
- RAK Logistics
- Tristar Transport LLC
- NYK Line (Including Yusen Logistics Co., Ltd.)
- Mohebi Logistics
- RSA Global
- DP World
- AD Ports Group
- Total Freight International LLC
- Globalink Logistics
Recent Industry Developments in UAE Contract Logistics Market
- October 2026: FedEx's hub at Dubai World Central achieved IATA CEIV Pharma certification, confirming the 57,000 m² facility's compliance with international standards for temperature-controlled pharmaceutical handling, positioning it as a qualified pharma logistics node across the Middle East, Indian Subcontinent, and Africa.
- May 2026: AD Ports Group signed an MoU with CMA Terminals Khalifa Port and CMA CGM Group to develop intermodal logistics solutions extending inland reach across the UAE through AD Ports Group's rail-linked network of dry ports and cargo depots.
- May 2026: AD Ports Group established a consolidated multimodal inland logistics network, anchoring industrial cargo flows from Emirates Global Aluminium, EMSTEEL Group, Al Ghurair Iron and Steel, and Tenaris through Khalifa Port and Fujairah Terminals, connected by rail-linked inland depots.
- May 2026: RSA Global officially launched its 10,000 m² logistics hub at EZDubai within Dubai South, designed to process 20,000 B2C orders daily as the company's primary e-commerce fulfillment center for regional and international clients.
UAE Contract Logistics Market Report Scope
Segmentation Overview
| Transportation | Road |
| Rail | |
| Air | |
| Sea | |
| Warehousing & Distribution | |
| Value-added Services (Assembly, Labelling, Kitting) |
| 1 - 3 Years |
| Above 3 years |
| Manufacturing & Automotive |
| Food & Beverage |
| Retail & E-commerce |
| Healthcare & Pharmaceuticals |
| Chemicals |
| Other Industries |
| Dubai |
| Abu Dhabi |
| Sharjah |
| Rest of UAE |
| By Service Type | Transportation | Road |
| Rail | ||
| Air | ||
| Sea | ||
| Warehousing & Distribution | ||
| Value-added Services (Assembly, Labelling, Kitting) | ||
| By Contract Duration | 1 - 3 Years | |
| Above 3 years | ||
| By End-user Industry | Manufacturing & Automotive | |
| Food & Beverage | ||
| Retail & E-commerce | ||
| Healthcare & Pharmaceuticals | ||
| Chemicals | ||
| Other Industries | ||
| By Geography | Dubai | |
| Abu Dhabi | ||
| Sharjah | ||
| Rest of UAE |
Key Questions Answered in the Report
What is the current scale and forecast of UAE contract logistics?
It is USD 1.36 billion in 2026 and is projected to reach USD 2.11 billion by 2032 at a 7.56% CAGR (2027-2032).
Which service type leads contract logistics in the UAE?
Transportation leads with 61.84% share in 2026, supported by road, sea, air, and cross-border distribution activity.
Which end-user segment is growing fastest in UAE contract logistics?
Retail and e-commerce is projected to grow at a 6.16% CAGR from 2027 to 2032, supported by cross-border purchases and regional fulfillment activity.
Which emirate has the largest contract logistics presence?
Dubai holds 37.20% share in 2026, supported by JAFZA, Dubai South, and integrated port and airport infrastructure.
Why are free zones important for UAE logistics operations?
Free zones support bonded warehousing, goods processing, relabeling, and re-export activity with limited customs friction.
How is rail changing UAE logistics networks?
The bonded rail corridor between Khalifa Port and Fujairah Terminals supports customs-controlled movement between west-coast and east-coast terminals.