
New Zealand Two-Wheeler Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
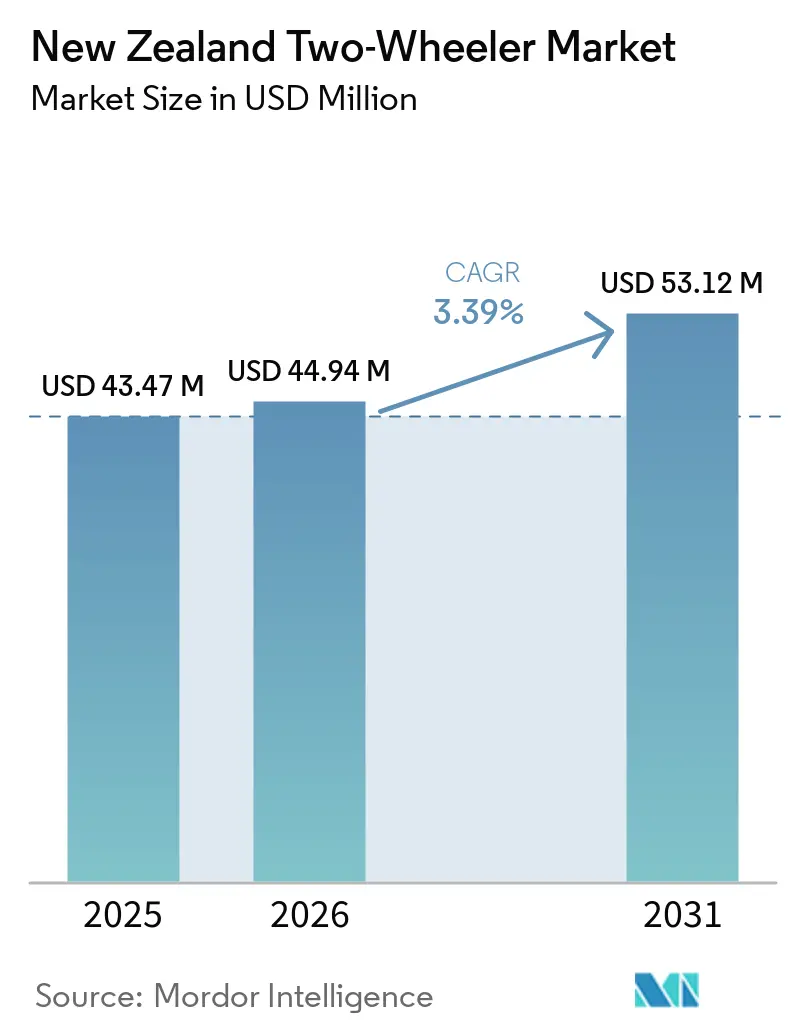
| Base Year Market Size (2025) | USD 43.47 Million |
| Market Size (2026) | USD 44.94 Million |
| Market Size (2031) | USD 53.12 Million |
| Growth Rate (2026 - 2031) | 3.39 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
New Zealand Two-Wheeler Market Analysis by Mordor Intelligence
The New Zealand two-wheeler market size was valued at USD 43.47 million in 2025 and is expected to grow from USD 44.94 million in 2026 to reach USD 53.12 million by 2031, at a 3.39% CAGR over 2026-2031. The expansion is steady rather than rapid because the market is moving from an early-growth phase to measured maturity as regulations tighten, purchase incentives recede, and buyers weigh total cost of ownership more carefully. Internal-combustion products still dominate, but the electric transition is underway as fleet buyers chase sustainability goals and as the country’s largely renewable electricity mix supports low-carbon transport. Urban congestion in Auckland and Wellington, evolving consumer lifestyles that favor compact personal mobility, and improving digital sales channels all work in tandem to keep demand on an upward trajectory. At the same time, the termination of the Clean Car Discount at the end of 2023 and the introduction of road-user charges (RUC) for higher-powered electric vehicles in April 2024 added friction to short-term electrification, while stringent graduated licensing slows first-time adoption among younger riders.
Key Report Takeaways
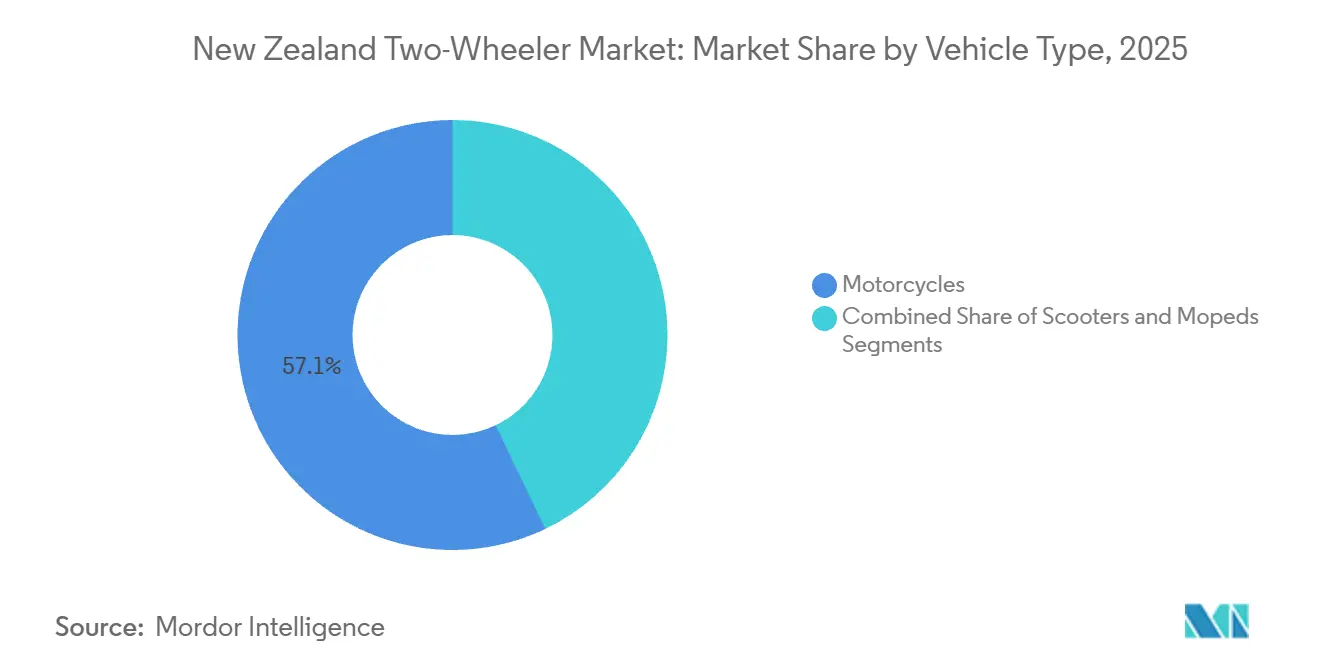
- By vehicle type, motorcycles led with a 57.13% revenue share in 2025, while scooters are projected to register the fastest 6.75% CAGR through 2031.
- By technology, internal-combustion engines accounted for 78.42% of 2025 sales, whereas electric powertrains are forecast to grow at a 11.96% CAGR to 2031.
- By transmission, manual gearboxes dominated, with a 71.87% share in 2025, but automatic/CVT units are poised for a 5.33% CAGR over the forecast window.
- By fuel type, petrol retained an 80.08% share in 2025, while electric alternatives are expected to grow at a 12.35% CAGR through 2031.
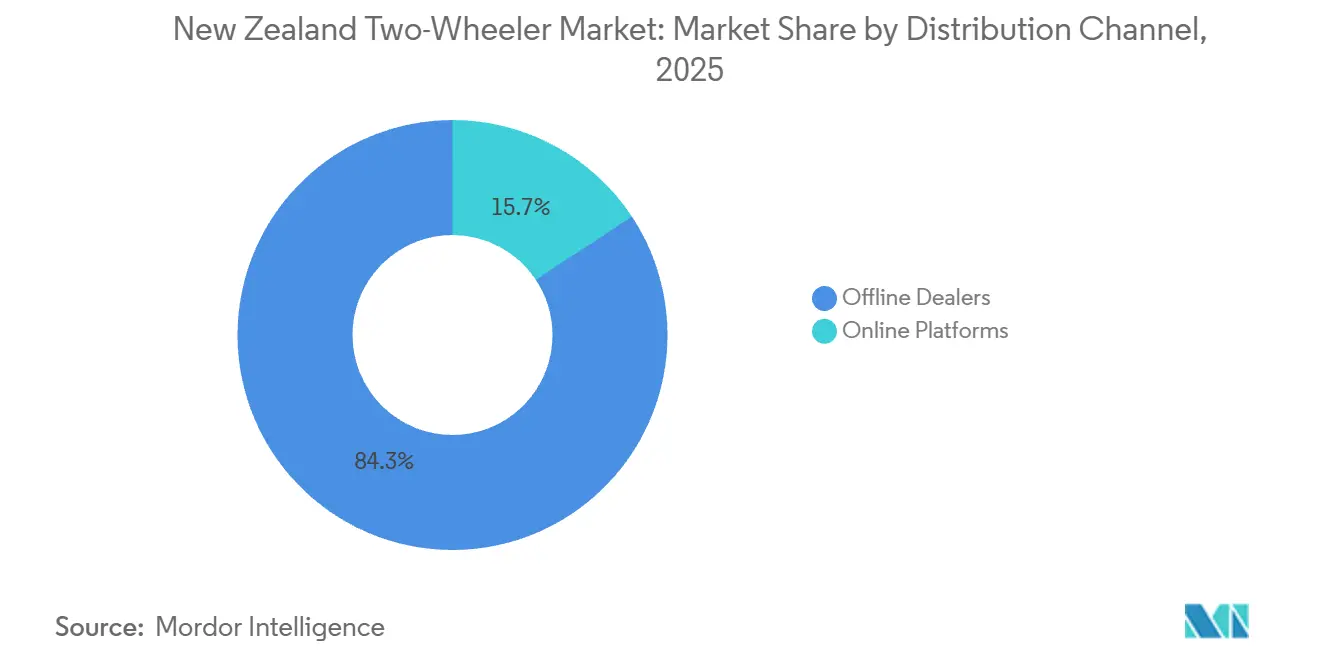
- By distribution channel, offline dealerships captured 84.31% of 2025 revenue, while online platforms are on track to grow at a 6.12% CAGR over 2026-2031.
- By end-user, personal riders accounted for 69.76% of 2025 revenue, while the commercial/fleet segment is set to expand at an 8.46% CAGR during the same period.
- By geography, the North Island held a 73.52% share in 2025, and the South Island is projected to deliver the fastest growth with a 4.58% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of New Zealand Two-Wheeler Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Urban Congestion and Parking Shortage | +0.8% | North Island, concentrated in Auckland and Wellington | Medium term (2-4 years) |
| Fuel Prices and Cost-Conscious Riders | +0.6% | National, with higher impact in urban centers | Short term (≤ 2 years) |
| Fleet Electrification by Corporates | +0.5% | National, with early adoption in major cities | Medium term (2-4 years) |
| Rise in Off-Road Riding Culture | +0.4% | South Island, with spillover to North Island | Long term (≥ 4 years) |
| Tourism in Back-Country Trails | +0.3% | South Island, concentrated in Queenstown and Central Otago | Long term (≥ 4 years) |
| Govt Rebates for E-Two-Wheelers | +0.2% | National, with early adoption in urban areas | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Surging Urban Congestion and Parking Scarcity
Auckland's traffic congestion will cost the city USD 2.6 billion annually by 2026, with residents wasting over 17 hours per year in traffic delays [1]. Private vehicles account for 90% of traffic, prompting commuters to increasingly adopt two-wheelers to mitigate economic pressures and reduce car dependency. The mayor's initiative to implement congestion charging is accelerating this shift towards motorcycles and scooters. Wellington, constrained by its geographic limitations and a concentrated government workforce, faces similar challenges. A USD 1.5 billion government reduction in public transport funding has inadvertently increased the appeal of two-wheelers, particularly as alternative transport options become more limited. Additionally, parking shortages in central business districts enhance the appeal of two-wheelers, which offer compactness, better maneuverability, and improved storage capabilities compared to traditional cars.
Escalating Petrol Prices and Cost-Sensitive Commuters
New Zealand's geographic isolation and reliance on imported petroleum significantly affect consumers as fuel costs rise. Two-wheelers, with fuel efficiency 2-3 times higher than passenger cars, offer a cost-effective alternative for price-sensitive commuters. Effective April 2024, the government implemented a road user charge of USD 76 per 1,000 kilometers on electric vehicles. This policy change may enhance the competitiveness of petrol-powered two-wheelers in specific scenarios. Notably, this adjustment coincides with electric vehicles comprising only 2% of the light-vehicle fleet, underscoring the importance of timing in incentive structures. Corporate fleet operators are increasingly adopting total cost of ownership models, which often favor two-wheelers for last-mile delivery operations. For instance, HELL Pizza's USD 160,000 investment in 45 electric bikes highlights how businesses are leveraging fuel efficiency to reduce operational costs while meeting environmental objectives.
Growing Recreational Off-Road Riding Culture
Guided motorcycle tours in the South Island, priced between USD 11,200 and USD 23,738, are contributing to the growth of the recreational two-wheeler market by attracting both international and domestic riders. The region's diverse terrain, including coastal routes, mountain passes, and backcountry trails, offers a significant value proposition for adventure motorcycles and off-road scooters. To mitigate challenges such as narrow, winding roads and left-hand traffic, tourism operators are implementing safety training programs and providing orientation on local road rules. The recreational segment benefits from New Zealand's 80% renewable electricity generation, making electric off-road vehicles more environmentally attractive [2]. UBCO's 2X2 Work Bike, despite the company's recent receivership, demonstrated market appetite for electric adventure vehicles with a 75-mile range and all-wheel-drive capability. This segment's growth trajectory remains resilient to short-term policy changes, given its discretionary-spending nature and the tourism industry's recovery momentum.
Government Rebates for E-Two-Wheelers
The Clean Car Discount scheme's termination in December 2023 eliminated direct purchase incentives for electric two-wheelers, contributing to the 55% decline in electric vehicle registrations. However, the government maintains its commitment to 10,000 public EV chargers by 2030, up from 1,378 currently, through USD 68.5 million in concessionary loans to private operators[3]. This infrastructure investment is expected to mitigate range anxiety, thereby supporting the adoption of electric two-wheelers. The exemption from road user charges for very light electric vehicles, including electric motorcycles, is expected to preserve cost advantages for these categories. Additionally, corporate fleet incentives provided through the Low Emissions Transport Fund are projected to drive the adoption of commercial electric vehicles, particularly in delivery and service applications. The policy framework indicates a focus on selective support rather than broad-based subsidies, requiring manufacturers to present clear value propositions beyond purchase-price incentives.
Restraints Impact Analysis of New Zealand Two-Wheeler Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rider Licensing and Safety Rules | -0.5% | National, with higher impact on younger demographics | Medium term (2-4 years) |
| Insurance for less than 25-Year Riders | -0.4% | National, with concentrated impact on entry-level segments | Medium term (2-4 years) |
| Battery Pack Assembly Capacity | -0.3% | National, affecting electric vehicle supply chains | Long term (≥ 4 years) |
| Competitive TCO of Micro-Cars | -0.2% | Urban areas, particularly North Island cities | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stringent Graduated Rider-Licensing and Safety Rules
New Zealand's graduated driver licensing system establishes multi-stage barriers for motorcycle adoption. Riders are required to progress through learner, restricted, and full license categories, each involving mandatory waiting periods and testing requirements. The Learner Approved Motorcycle Scheme restricts novice riders to specific vehicle models, limiting access to higher-performance segments within the market. Insurance providers impose additional excesses on riders under 25 and those with less than two years of experience, creating cost barriers for younger demographics. Government-proposed licensing reforms for 2026 primarily target car licenses, with minimal focus on motorcycle-specific improvements, indicating continued regulatory complexity. Safety concerns related to e-scooters, as evidenced by New Zealand Medical Journal studies showing crash victims requiring more surgeries than motorbike riders, contribute to regulatory caution that may extend to broader two-wheeler categories. These regulatory frameworks prioritize safety over market accessibility, constraining entry-level adoption rates within the motorcycle market.
Limited Domestic Battery-Pack Assembly Capacity
As of January 2025, UBCO's receivership led to the cessation of operations at New Zealand's primary electric two-wheeler manufacturer, significantly reducing local production capacity and increasing reliance on imports. Despite securing USD 70 million in funding and contracts with Australia Post, the company's failure highlights the challenges of scaling electric-vehicle manufacturing in smaller markets. Although UBCO has resumed operations, the impact will materialize only over the long term. Aspiring Materials operates a facility in Christchurch that produces nickel-manganese-cobalt materials for lithium-ion batteries; however, the lack of integration with local vehicle assembly operations contributes to supply chain fragmentation. This fragmentation leads to higher costs and extended lead times for electric two-wheeler manufacturers. The Clean Car Import Standard, introduced by the government, establishes emissions thresholds that favor electric vehicles but provide limited support for enhancing domestic manufacturing capabilities. Additionally, import duties and shipping costs from Asian manufacturing centers increase vehicle prices by 15-20%, placing New Zealand consumers at a disadvantage compared to those in larger markets. The absence of local assembly further restricts the ability to customize vehicles to meet New Zealand's specific regulatory requirements and operational conditions.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
New Zealand Two-Wheeler Market Segment Analysis
By Vehicle Type:
Adventure Mid-Capacity Drives Motorcycle DominanceIn 2025, motorcycles accounted for 57.13% of total revenue. However, scooters are projected to grow at a 6.75% CAGR through 2031. This trend highlights a shift in preference among urban commuters, who now prioritize ease of operation and storage over traditional performance metrics. CFMOTO's 450MT emerged as the frontrunner in 2025, dominating the mid-capacity adventure segment by offering competitive pricing and comparable off-road capabilities. Triumph is set to launch its Thruxton 400 and Tracker 400 models in 2026, targeting entry-level buyers with a focus on affordability and performance. While mopeds occupy a niche position, constrained by licensing constraints and a limited model range, they are poised for modest growth. Their appeal lies in low running costs and exemptions from higher ACC levies, making them attractive to budget-conscious urban riders.
The surge in scooter popularity can be attributed to the widespread adoption of automatic and CVT transmissions. These systems eliminate the need for clutch operation, making scooters particularly appealing to aging riders and first-time buyers. Honda's NAVi exemplifies the entry-level segment, while Yamaha's expansion of semi-automatic technology to higher-end models signals a trend of automated shifting moving upmarket. Although Piaggio's Vespa and Aprilia brands have a presence in New Zealand, the lack of disclosed local sales figures suggests modest penetration compared to established Japanese competitors. Regulatory factors also influence vehicle-type segmentation. For instance, ACC levies impose heavier penalties on higher-displacement motorcycles than on scooters or mopeds. This creates a financial incentive for urban buyers to switch from larger models to sub-300cc scooters, which offer sufficient performance for city commuting while incurring lower annual fees.



By Technology:
ICE Holds Share, Electric Grows from Minimal BaseIn 2025, internal-combustion engines accounted for 78.42% of the revenue, but electric powertrains are projected to grow at a robust 11.96% CAGR through 2031. This surge is fueled by fleet electrification mandates and RUC exemptions, which are widening the total cost-of-ownership gap. Within the ICE domain, the 126-180 cc and 181-250 cc sub-segments lead the pack. This trend mirrors New Zealand's affinity for learner-approved motorcycles and small-capacity adventure bikes, especially those priced under NZD 11,000 (approximately USD 6,800). Anchoring the LAMS category are models catering to this demand. Meanwhile, the performance niche, albeit facing rising ACC levies, is catered to by higher-displacement models. The sub-100 cc segment, primarily consisting of mopeds and entry-level scooters, remains marginal. In contrast, the 501-800 cc and 801-1600 cc brackets attract touring and cruiser enthusiasts who value highway prowess over urban maneuverability.
Electric vehicles are gaining traction, especially in the sub-4 kW and 4-7 kW segments. Here, utility bikes and off-road models are making their mark. However, the 7-15 kW and 15+ kW categories lag, hindered by a scarcity of models and steep upfront costs. Representing the spectrum are premium urban commuter models and budget-conscious off-roaders. Yet, both overlook the mass-market commuter segment, traditionally dominated by ICE scooters. The landscape of electric vehicles is further shaped by the dynamics of charging infrastructure, which serves inter-city commuters in Auckland and Wellington thanks to the dense public charging network. While electric models boasting a 150+ km range can efficiently serve inter-city commuters in Auckland and Wellington, owing to the dense public charging network, they fall short for South Island tours. This limitation persists until fast-charger networks expand beyond the primary highways.
By Transmission:
Manual Dominates, Automatic/CVT Gains Urban ShareIn 2025, manual transmissions accounted for 71.87% of the revenue, but automatic and CVT variants are projected to surge at a 5.33% CAGR through 2031. This shift is largely driven by urban commuters and older riders who favor the simplicity of operation over the traditional clutch control. Yamaha's introduction of semi-automatic technology on its models exemplifies this trend. This innovative system retains the manual gearbox while automating clutch actuation, allowing riders to enjoy the essence of traditional shifting without the strain of stop-and-go traffic. Honda, recognizing the trend, expanded its automatic technology across multiple models. This move targets riders who appreciate manual control on open roads but seek the convenience of automation in urban environments. Entry-level segments are dominated by CVT scooters, where the allure of simplicity and low maintenance costs overshadows the performance edge of manual gearboxes.
Transmission choices are also influenced by licensing stipulations. In New Zealand, the Learner Approved Motorcycle Scheme limits novice riders to bikes with power-to-weight ratios under 150 kW per metric ton. This regulation leans towards smaller-displacement manual motorcycles, which are deemed better for skill development. Yet, as the average age of new registrations has steadily risen over the last decade, there is a noticeable uptick in demand for automatic and CVT options. This is especially true among returning riders who now prioritize convenience over the traditional motorcycling experience. While motocross lineups remain firmly in the manual camp, this highlights the continued preference in the off-road and performance segments for direct mechanical control. Looking ahead, it is evident that the transmission divide will endure. Manuals will likely dominate motorcycles over 400cc, while automatic and CVT options will lead in scooter sales and bikes under 300cc.
By Fuel Type:
Petrol Leads, Electric Grows via Fleet AdoptionIn 2025, petrol accounted for 80.08% of revenue, but electric vehicles are projected to grow at a robust 12.35% CAGR through 2031. This growth mirrors technology segmentation and is propelled by similar catalysts, including fleet electrification mandates, RUC exemptions, and an expanding charging infrastructure. Meanwhile, CNG/LPG struggles to gain traction, hindered by a lack of refueling infrastructure and limited model offerings. Notably, no major OEM in New Zealand offers a factory CNG/LPG two-wheeler, and aftermarket conversions face challenges primarily due to stringent safety certification requirements. Consequently, the fuel-type segmentation narrows to a comparison between petrol and electric, with the pace of transition hinging on factors such as upfront cost parity, the density of the charging network, and regulatory incentives.
Commercial entities are leading the shift towards electrification, leveraging centralized charging and consistent duty cycles to address range anxiety that often deters retail consumers. Fleet electrification is gaining momentum beyond New Zealand's borders. However, the financial vulnerabilities faced by electric two-wheeler specialists, especially those without the scale and diversification enjoyed by established OEMs, remain a concern. On the retail front, consumers remain anchored to petrol. The sub-NZD 11,000 (approximately USD 6,800) price bracket, which dominated 2025 registrations, is largely occupied by ICE models. In contrast, electric contenders at similar price points are confined to off-road or low-speed uses. The petrol bias in fuel-type segmentation is poised to persist until mainstream OEMs unveil electric commuter models priced under NZD 15,000 (approximately USD 9,000), boasting a range of over 150 km. However, this milestone seems unlikely before 2027 to 2028.
By Distribution Channel:
Offline Dealers Retain Control, Online Gains TransparencyIn 2025, offline dealers accounted for 84.31% of total revenue. However, online platforms are projected to expand at a robust 6.12% CAGR through 2031. This growth is driven by advantages such as transparent pricing, nationwide delivery, and the ability to navigate New Zealand's fragmented dealership landscape. Smaller retailers are increasingly able to access a national audience without the overhead of maintaining multiple showrooms. Online platforms play a pivotal role in used-bike transactions where buyers prioritize affordability over warranty coverage. Physical dealers remain crucial for test rides, financing, and after-sales service. These services yield margins that are 2.3 times higher than those from vehicle sales, bolstering dealer profitability.
OEM franchise mandates also influence distribution channel segmentation. In 2025, amidst sluggish sales, some brands eased their sole-franchise constraints, allowing multi-brand showrooms to diversify. This underscores that premium brands are still investing in physical retail, even as the online trend gains momentum. While online platforms excel at price discovery and inventory aggregation, they face challenges in replicating the test-ride experience and the ease of financing offered by physical dealers. This gap is especially pronounced for first-time buyers seeking hands-on assistance. Looking ahead, the channel divide is expected to continue: online platforms are likely to increasingly dominate used-bike sales and attract budget-conscious buyers focused on price. In contrast, offline dealers are anticipated to maintain their lead in new-bike sales, exceeding NZD 15,000 (approximately USD 9,000), where services such as financing, trade-ins, and after-sales support heavily influence buyer decisions.

By End-User:
Personal Segment Contracts, Commercial/Fleet ExpandsIn 2025, personal use constituted 69.76% of total revenue. However, the commercial/fleet segment is projected to surge at an 8.46% CAGR through 2031. This growth is largely attributed to electrification mandates and the total cost-of-ownership benefits that increasingly favor centralized fleet operators over individual consumers. The transition to electric fleets has driven demand for utility-focused electric two-wheelers, with operators deploying a range of electric vehicles to enhance operational efficiency. Subscription models and swappable battery designs are being leveraged to minimize downtime and reduce operating expenses. Commercial entities are adopting electric solutions at a faster pace than retail consumers, as fleet operators benefit from multi-year contracts and centralized charging infrastructure.
On the other hand, personal-use registrations saw a significant dip year-on-year up until August 2025. This decline can be traced back to economic challenges and deferred discretionary spending, driven by high interest rates and cost-of-living pressures. The personal-use segment showcases its own nuances, with urban commuters favoring scooters and automatic/CVT models for their user-friendly operation. In contrast, adventure enthusiasts prefer mid-capacity motorcycles for their weekend getaways and off-road adventures. Rentals tied to tourism represent a specialized yet lucrative niche, although the tourism sector has not fully recovered, with international visitor numbers still trailing behind pre-pandemic levels. This shortfall has made rental businesses increasingly dependent on domestic riders, who typically opt for shorter and less profitable trips. Looking ahead, the market segmentation is expected to remain distinct. The commercial/fleet sector is anticipated to lead the shift towards electric vehicles and drive volume growth. At the same time, the personal-use segment's recovery will depend on broader economic stabilization and the availability of competitively priced electric models that match traditional internal combustion engines in both cost and range.
Geography Analysis
The North Island accounted for 73.52% of market revenue in 2025, fueled by Auckland's dense population of 1.7 million and Wellington's concentrated government workforce, both of which drive significant urban commuting demand. The region's established dealer networks, robust service infrastructure, and readily available parts bolster the market's growth across all vehicle categories. With Auckland facing a projected annual congestion cost of USD 2.6 billion by 2026, the allure of two-wheelers intensifies as commuters seek to break free from car dependency. Given Wellington's compact layout and concentration of government jobs, scooters and smaller motorcycles are favored choices for urban mobility.
Furthermore, the region's emphasis on sustainability and operational efficiency, as highlighted by NZ Post's fleet of over 400 electric delivery vehicles, underscores the corporate push towards electric-vehicle adoption. Meanwhile, the South Island is on a faster growth trajectory, boasting a 4.58% CAGR through 2031. This surge is largely attributed to a rebound in adventure tourism and a burgeoning recreational riding culture, with enthusiasts exploring everything from coastal routes to mountain passes and backcountry trails. Local tourism operators are capitalizing on this trend, offering guided motorcycle tours priced between USD 11,200 and USD 23,738, appealing to both international tourists and local aficionados.
Regions like Queenstown and Central Otago are reaping the rewards of this adventure tourism boom. Operators in these areas prioritize safety training and familiarization with local road rules, especially given the challenges posed by narrow, winding roads. The South Island's sparse population density presents unique opportunities, particularly for off-road and adventure motorcycles, which can capitalize on the region's diverse geography. While UBCO's operations in Christchurch faced recent receivership, they spotlighted the South Island's potential in electric vehicle manufacturing and innovation, even as supply chain challenges loom over immediate development prospects.
Competitive Landscape
Market Concentration
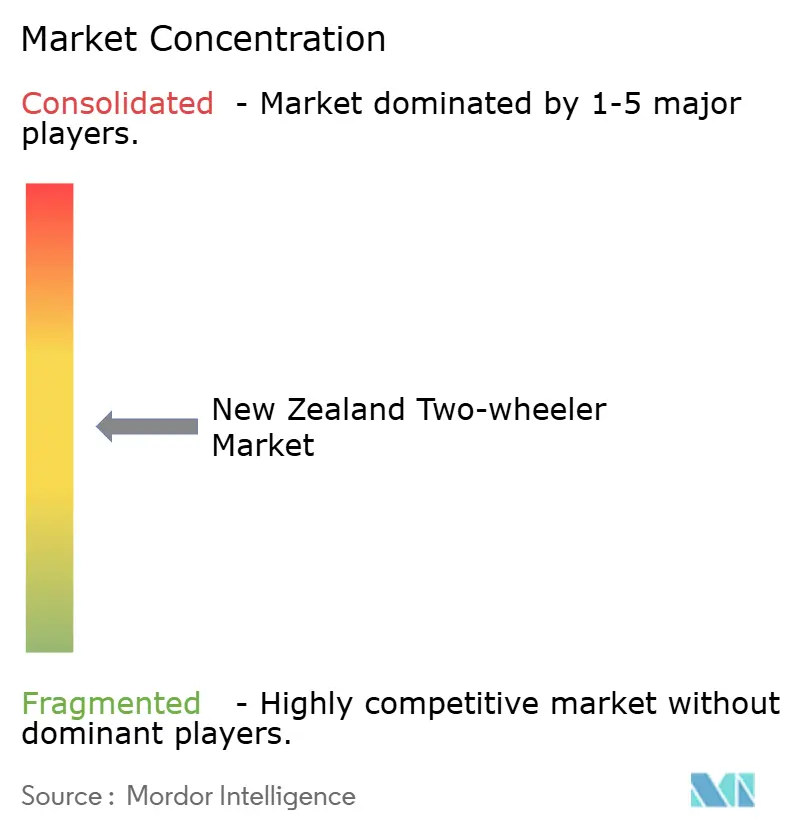
Japanese manufacturers such as Yamaha, Honda, Suzuki, and Kawasaki continued to offer a broad range of products, including scooters, learner-approved motorcycles, and premium sport bikes. Despite their extensive portfolios, these companies have not disclosed New Zealand-specific sales figures, suggesting limited market penetration compared to their global operations. European premium brands, including Triumph, KTM, BMW Motorrad, and Harley-Davidson, focused on niche segments. Triumph introduced new models and launched competitively priced entry-level options, while KTM catered to off-road enthusiasts with its motocross lineup. BMW Motorrad expanded into multi-brand showrooms, signaling a shift toward shared retail infrastructure amidst weak sales.
Opportunities in the market are emerging in the form of affordable electric commuters priced under NZD 15,000 (approximately USD 9,000) with a range exceeding 150 kilometers, as well as automated-transmission motorcycles designed for aging riders. UBCO's pivot to B2B markets in 2025 highlights the financial challenges faced by electric specialists. However, its contract with Australia Post and ongoing discussions with DX Mail demonstrate the potential for fleet electrification as a growth avenue. CFMoto's patent filings for a 550CL-C cruiser with a 526cc engine delivering 52 bhp and electric sportbike designs featuring removable batteries and innovative chassis reflect the strategic efforts of Chinese OEMs to challenge established players in both internal combustion engine and electric vehicle segments. Established manufacturers are also leveraging automation to retain aging riders. Yamaha's Y-AMT semi-automatic technology and Honda's E-Clutch, now available in multiple models including the CB1000 Hornet SP, exemplify this trend.
Regulatory compliance and licensing frameworks are shaping the competitive dynamics of the market. The implementation of Euro 4m emissions standards, mandatory from April 2025, and New Zealand's LAMS licensing framework favor OEMs with diverse product portfolios that include learner-approved, mid-capacity, and premium models. These regulations are expected to drive innovation and product development, particularly in segments serving environmentally conscious consumers and new riders. The market's fragmented nature, combined with evolving consumer preferences and regulatory requirements, presents both challenges and opportunities for OEMs. Companies that can adapt to these dynamics and offer a wide range of products are likely to strengthen their positions in the New Zealand two-wheeler market.
New Zealand Two-Wheeler Industry Leaders
-
Yamaha Motor Co., Ltd.
-
Honda Motor Co., Ltd.
-
Suzuki Motor Corporation
-
Kawasaki Motors, Ltd.
-
KTM AG
- *Disclaimer: Major Players sorted in no particular order
New Zealand Two-Wheeler Market Companies Covered in this Report
- Yamaha Motor Co., Ltd.
- Honda Motor Co., Ltd.
- Suzuki Motor Corporation
- Kawasaki Motors, Ltd.
- KTM AG
- Triumph Motorcycles Ltd
- Harley-Davidson, Inc.
- BMW Motorrad
- Piaggio & C. SpA
- Royal Enfield
- Zhejiang Chunfeng Power Co., Ltd.
- Kwang Yang Motor Co., Ltd.
- Niu Technologies
- Vmoto Limited
- UBCO Limited
- Stark Future SL
- Zero Motorcycles Inc.
- Lifan Technology (Group) Co., Ltd.
- TVS Motor Company Limited
Recent Industry Developments in New Zealand Two-Wheeler Market
- September 2026: ZXMOTO is expected to announce pricing and open pre-orders for its initial motorcycle range in Australia and New Zealand on October 8, 2026. The initial pre-order lineup will include sport, naked, and motocross motorcycles, with the 820RR, 500RR, 500F, MX250, and MX450 currently confirmed. ZXMOTO may add further models before pre-orders open and plans to announce an exclusive offering in the days leading up to the launch.
- April 2026: New Zealand-based electric motorcycle manufacturer FTN Motion introduced the Streetdog XR, a more powerful version of its original model designed for urban commuting. Hand-built at the company’s Hamilton workshop, the XR replaces the Streetdog 80 and delivers a top speed of 85 km/h, with instant torque supplied by a rear-hub motor.
New Zealand Two-Wheeler Market Report Scope
The scope includes segmentation by vehicle type (scooters, mopeds, and motorcycles), technology (internal combustion (ICE) [less than 100 cc, 100 to 125 cc, 126 to 180 cc, 181 to 250 cc, 251 to 500 cc, 501 to 800 cc, 801 to 1600 cc, and more than 1600 cc], and electric [less than 4 kW, 4 to 7 kW, 7 to 15 kW, and more than 15 kW]), transmission (manual and automatic/CVT), fuel type (petrol, electric, CNG/LPG), distribution channel (offline dealers and online platforms), and end-user (personal and commercial/fleet). The analysis also covers regional-level segmentation, including North Island and South Island. Market size and growth forecasts are presented by value in USD and volume in Units.
Segmentation Overview
| Scooters |
| Mopeds |
| Motorcycles |
| Internal Combustion (ICE) | Less than 100 cc |
| 100 to 125 cc | |
| 126 to 180 cc | |
| 181 to 250 cc | |
| 251 to 500 cc | |
| 501 to 800 cc | |
| 801 to 1600 cc | |
| More than 1600 cc | |
| Electric | Less than 4 kW |
| 4 to 7 kW | |
| 7 to 15 kW | |
| More than 15 kW |
| Manual |
| Automatic/CVT |
| Petrol |
| Electric |
| CNG/LPG |
| Offline Dealers |
| Online Platforms |
| Personal |
| Commercial/Fleet |
| North Island |
| South Island |
| By Vehicle Type | Scooters | |
| Mopeds | ||
| Motorcycles | ||
| By Technology | Internal Combustion (ICE) | Less than 100 cc |
| 100 to 125 cc | ||
| 126 to 180 cc | ||
| 181 to 250 cc | ||
| 251 to 500 cc | ||
| 501 to 800 cc | ||
| 801 to 1600 cc | ||
| More than 1600 cc | ||
| Electric | Less than 4 kW | |
| 4 to 7 kW | ||
| 7 to 15 kW | ||
| More than 15 kW | ||
| By Transmission | Manual | |
| Automatic/CVT | ||
| By Fuel Type | Petrol | |
| Electric | ||
| CNG/LPG | ||
| By Distribution Channel | Offline Dealers | |
| Online Platforms | ||
| By End-User | Personal | |
| Commercial/Fleet | ||
| By Geography | North Island | |
| South Island | ||
Key Questions Answered in the Report
What is the current value of the New Zealand two-wheeler market?
The New Zealand two-wheeler market size is USD 43.47 million in 2025.
How fast is the New Zealand two-wheeler market expected to grow?
The market is projected to expand at a 3.39% CAGR between 2026 and 2031.
Which vehicle type holds the largest share in New Zealand?
Motorcycles led with 57.13% New Zealand two-wheeler market share in 2025.
What segment is growing the quickest?
Scooters are forecast to post the fastest 6.75% CAGR through 2031.