
Indoor Plants Market Size and Share
Indoor Plants Market Analysis by Mordor Intelligence
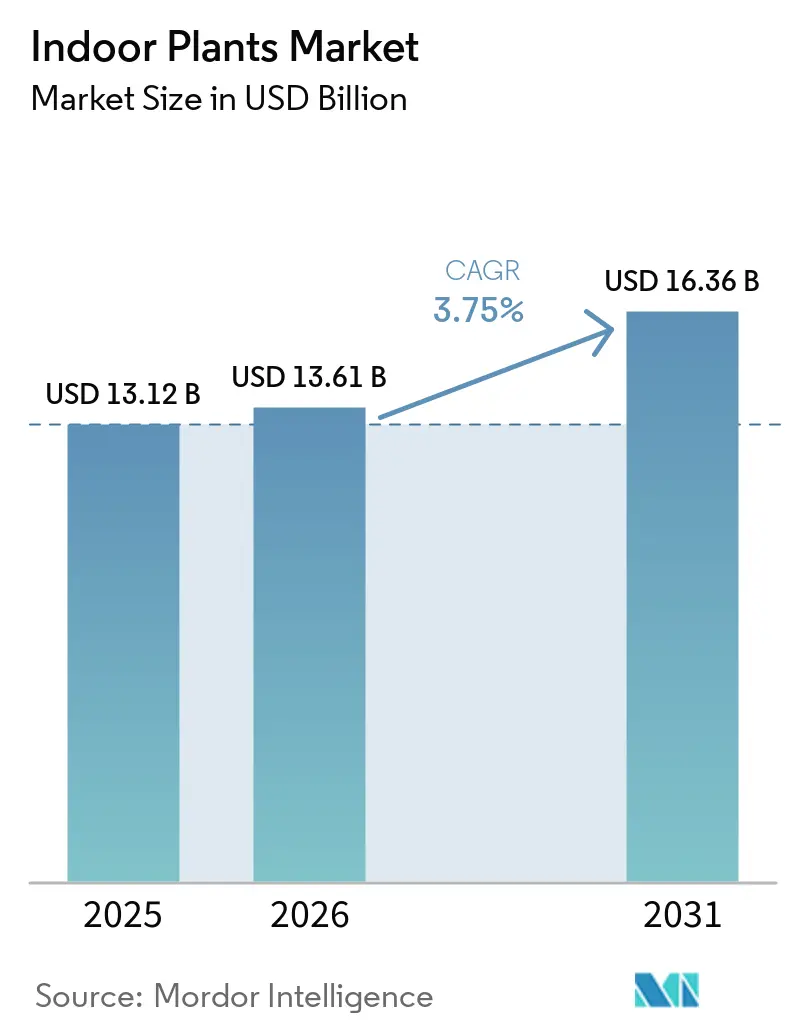
The indoor plants market size is expected to increase from USD 13.61 billion in 2026 to USD 14.12 billion in 2027 and reach USD 16.71 billion by 2032, growing at a CAGR of 3.42% over 2027-2032.
Visual appeal and perceived well-being support demand, while automated care can broaden the appeal of edible indoor growing. In the United States, sellers can connect potted-plant selection with room placement and care guidance, giving the individual specimen a clearer role within the home. Supply-led price pressure makes plant differentiation and access to buyers more important for growers. A coordinated offer can therefore tie the plant sale to the placement and care guidance that keep the plant alive after delivery.
Key Report Takeaways
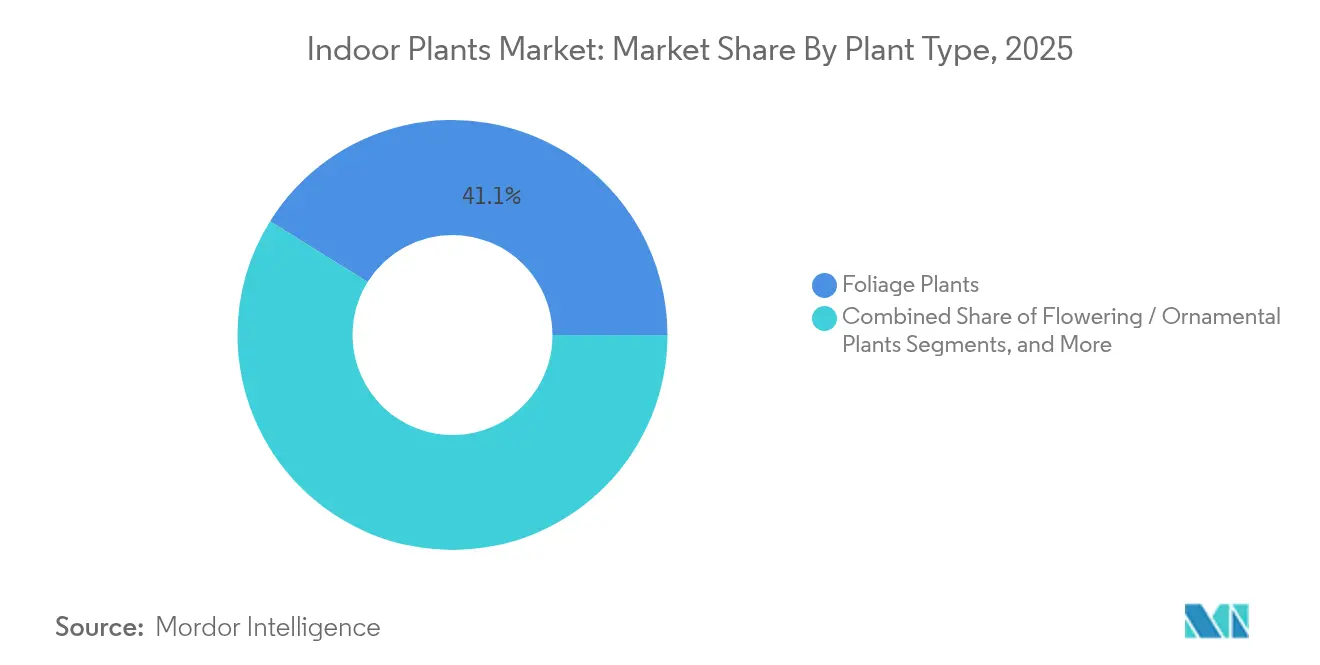
- By plant type, foliage plants held a 41.16% indoor plants market share in 2026, while succulents and cacti are forecast to grow fastest with a CAGR of 6.45% over 2027-2032.
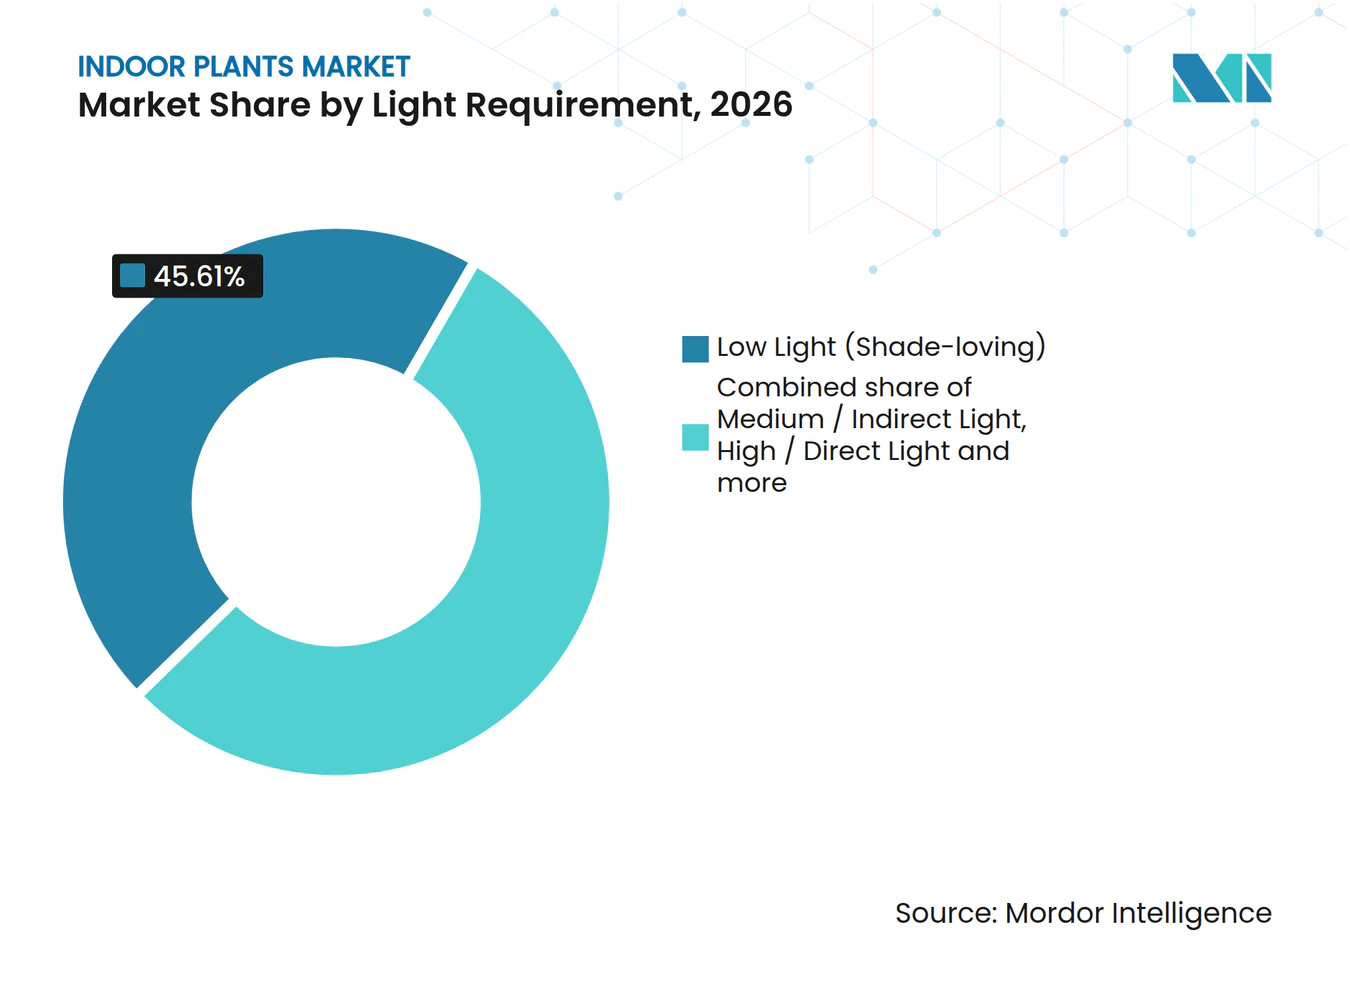
- Within light requirements, low-light (shade-loving) plants accounted for a 45.61% share of the indoor plants market size in 2026, and medium / indirect light plants are forecast to grow fastest with a CAGR of 6.15% over 2027-2032.
- In product form, potted soil-based plants led with 66.36% of revenue in 2026, while smart potted / IoT-enabled plants are forecast to grow fastest with a CAGR of 10.7% over 2027-2032.
- Home and interior decoration led application demand with 53.31% of revenue in 2026, with air purification and wellness forecast to grow fastest at a CAGR of 7.5% over 2027-2032.
- Residential buyers led end-user demand with 70.49% of revenue in 2026, whereas commercial users are forecast to grow fastest with a CAGR of 5.7% over 2027-2032.
- Across distribution channels, offline accounted for 76.31% of revenue in 2026, while online is forecast to grow fastest with a CAGR of 9.5% over 2027-2032.
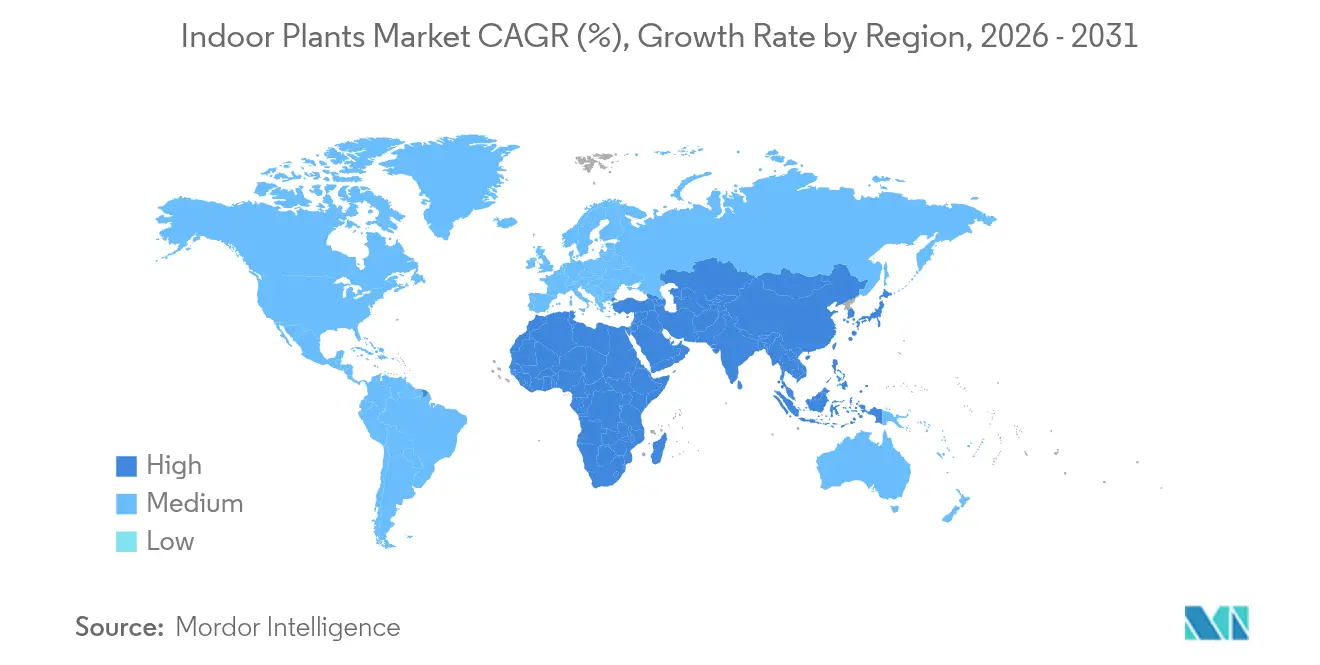
- Geographically, North America held 37.37% of revenue in 2026, and Asia-Pacific is forecast to grow fastest with a CAGR of 6.3% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Indoor Plants Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Social-media-fueled biophilic interior design trend among Millennials and Gen-Z | +1.4% | United States | Short term (≤ 2 years) |
| Corporate WELL & LEED certification push integrating greenery in workspaces | +1.2% | Poland | Medium term (2-4 years) |
| Rapid adoption of IoT self-watering and smart planter technologies | +1% | United States | Medium term (2-4 years) |
| Rising consumer focus on perceived indoor air-quality and wellness benefits of plants | +0.9% | Germany | Short term (≤ 2 years) |
| Availability of rare variegated cultivars as aspirational lifestyle assets | +0.3% | United States | Short term (≤ 2 years) |
| Declining price-points through tissue-culture mass propagation | +0.4% | France and the Netherlands | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Social-media-fueled biophilic interior design trend among Millennials and Gen-Z
Social media can connect visual plant discovery with a purchase decision among younger houseplant owners. ModMoss's September 2026 survey of 1,000 U.S. adults who owned at least one living houseplant found that 56% of Gen Z respondents said social media had influenced a plant purchase. The reported influence reaches a transaction, giving plant retailers a more concrete commercial objective than visibility alone. Plant-focused content can be designed around choosing a specimen and reaching its sales page, helping a seller connect presentation with product access. Only 12% of Baby Boomer owners in the same survey reported that influence, giving social-led merchandising a more defined audience among younger owners.
Corporate WELL & LEED certification push integrating greenery in workspaces
Workplace certification gives plant suppliers a route into office projects where greenery sits within a broader occupant-experience brief. Moderna's Warsaw office received WELL v2 Platinum certification in 2025. The office's features included live indoor plants alongside certified green cleaning products and natural materials. Cushman & Wakefield managed the certification process, while Moderna occupied the office. Because plants sit alongside materials and cleaning features in the certified workplace, suppliers can position greenery as one component of a wider fit-out brief.
Rapid adoption of IoT self-watering and smart planter technologies
Automated care changes household indoor planting from a watering task into a managed growing system. As of October 12, 2026, Gardyn reported that more than 130,000 households grew food with its indoor systems, which manage light, water, and nutrients and provide AI guidance through its app.[1] The combination addresses several interdependent growing requirements rather than treating self-watering as a standalone convenience. It can make an edible planting purchase feasible for customers who need guidance alongside the plants. Suppliers therefore have a commercial opening in coordinated plant, irrigation, and lighting performance, with software supporting the owner's decisions. Gardyn starts plants in pre-seeded yCubes, so the commercial opening depends on supplying a planting format that works within the system.
Rising consumer focus on perceived indoor air-quality and wellness benefits of plants
Perceived emotional benefits give houseplant sellers a purchase rationale beyond furnishing a room. In the Floral Marketing Fund's national study, consumers surveyed in 2025 were more likely than those surveyed in 2019 to consider houseplants appropriate get-well gifts. In that study, 96.6% of surveyed houseplant purchasers in 2025 said plants made them feel happier to some extent. Toom Baumarkt's January 2026 survey with Norstat covered 1,018 people in Germany, where 88% of indoor-plant owners said their home contributes to well-being, compared with 72% of respondents without plants. These perceptions give sellers a reason to connect household enjoyment with thoughtful gifting. Because the happiness finding concerns existing purchasers, a wellness-led assortment can address their next gifting occasion as well as their own rooms.
Restraints Impact Analysis of Indoor Plants Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Tissue-culture oversupply leading to price compression for growers | -0.8% | China and Thailand | Short term (≤ 2 years) |
| CITES and phytosanitary regulations restricting trade in exotic species | -0.5% | Great Britain and Northern Ireland | Medium term (2-4 years) |
| High e-commerce return rates due to transit damage and cold-chain gaps | -0.3% | India | Short term (≤ 2 years) |
| Transition to peat-free substrates increasing production costs | -0.2% | Scotland and England | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Tissue-culture oversupply leading to price compression for growers
Growers can face weaker revenue per plant when more suppliers bring the same varieties to market. At Qingzhou's 2026 tropical-plant exhibition, several mainstream varieties, including Monstera, showed lower prices and higher output than in 2025. Qingzhou Flower Association chair Wang Xinguo attributed the change to more companies growing and supplying tropical plants. A tropical-plant grower said in October 2025 that more growers, year-round growth and easier propagation would push prices down across Monstera, staghorn fern, begonia and caladium varieties. For Monstera producers, easier availability makes cultivar scarcity a less dependable basis for pricing. At a given sales volume, lower prices leave less revenue to cover cultivation and handling.
CITES and phytosanitary regulations restricting trade in exotic species
Cross-border sellers of protected exotic plants face an authorization sequence that can separate customer interest from a completed sale. For movements into or out of Great Britain, UK CITES guidance tells traders not to ship, pay for or contract over covered plant specimens until they receive the correct permit.[2] Traders must also check the other country's requirements, because a UK permit does not guarantee corresponding authorization there. The commercial constraint extends beyond transport paperwork, since the guidance reaches payment and contracting before dispatch. For suppliers serving collectors, permit sequencing can lengthen the interval between sourcing a covered specimen and monetizing it. A tradable plant can consequently remain commercially unavailable while the required permissions are being obtained.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Indoor Plants Market Segment Analysis
By Plant Type:
Foliage Scale Meets Specialist InterestFoliage plants accounted for a 41.16% share of the indoor plants market size in 2026. U.S. floriculture operations with at least USD 100,000 in annual sales recorded USD 974.9 million in 2025 sales of foliage plants for indoor or patio use.[3] The measure includes retail and wholesale sales, giving the largest segment an operating base across more than one selling channel. That combination makes distribution access relevant to a foliage producer's ability to turn growing activity into revenue. A foliage grower can therefore choose between direct selling and wholesale reach while serving the same indoor-or-patio plant category.
Succulents and cacti are the fastest-growing segment, with a projected CAGR of 6.45% over 2027-2032. The Sill's 2025 plant trends report said customer interest in unusual cacti and euphorbias more than doubled year over year. Cox Cactus Farm grows cacti and other succulent material for wholesale customers in Arizona. This combination of specialist supply and interest in unusual plants gives retailers a basis for developing a differentiated assortment within the category. A specialist growing route can help retailers build depth around distinctive specimens, with the commercial offer focused on unusual plants rather than treating every cactus as an interchangeable item.



By Light Requirement:
Placement Shapes the OfferLow-light (shade-loving) plants represented a 45.61% indoor plants market share in 2026. ModMoss's September 2026 survey of 1,000 U.S. adults owning at least one living houseplant found that 31% selected low-light requirements as an important choice factor. The result links plant choice to a room's lighting conditions, making placement information part of the plant's commercial proposition. Suppliers can explain where a shade-loving plant fits and set expectations for the intended indoor location. Shade-tolerance labeling on plant listings and pots therefore answers a documented selection priority for this buyer group.
Medium / indirect light plants are the fastest-growing segment, with a projected CAGR of 6.15% over 2027-2032. Meeting Green's 2025 top-selling houseplants included Calathea 'Fusion White,' Scindapsus exotica 'Silver Satin Pothos,' and Philodendron cordatum, which it describes as medium-light plants. The retailer's placement advice brings these different plants together under a common medium-light category. Its Calathea guidance calls for humidity and moisture, while Scindapsus should dry out between waterings. A shared light requirement can organize the range, but watering instructions still need to stay plant-specific.

By Product Form:
Established Pots and Connected AlternativesPotted soil-based plants were the largest segment, with 66.36% of revenue in 2026. Their commercial unit is a planted arrangement, which combines a living specimen, container and growing substrate. Bundling those elements lets a retailer offer a complete planted display in one transaction without adding the electronic functions of a smart pot. That simpler product proposition helps explain the format's broad base, while connected alternatives must earn an additional purchase rationale through their technology.
Smart potted / IoT-enabled plants are the fastest-growing segment, with a projected CAGR of 10.7% over 2027-2032. Hello Tomorrow representatives reported commercial sales of PlantPetz smart flowerpots at IFA 2025. The same representatives described pots that respond to touch, tickling, voice, music and room activity with movement and sounds. Here, electronics give the living plant an interactive household role, so the additional selling proposition is companionship rather than automated cultivation.
By Application Purpose:
Decoration and Wellness Serve Different PrioritiesHome and interior decoration was the largest segment, with 53.31% of revenue in 2026. In the September 2026 ModMoss survey, 54% of U.S. owners of living houseplants selected appearance as an important factor when choosing a plant. That preference makes the plant's visible character part of the commercial proposition, even when a purchase also serves another purpose. Retailers can organize decorative offers around the look of a specimen and its container, helping buyers translate visual preferences into a plant choice. Only 16% selected an attractive container as a choice factor, favoring specimen-led merchandising over a pot-led decorative offer.
Air purification and wellness is the fastest-growing segment, with a projected CAGR of 7.5% over 2027-2032. In September 2026, 72% of surveyed U.S. owners of living houseplants agreed that having plants in their home improves their mood. This positions wellness offers around the owner's experience of the home, giving buyers a purpose that can coexist with decoration. Suppliers can describe the intended atmosphere and interaction with the plant while keeping the offer anchored in the living product. Because these respondents already owned living plants, wellness-led merchandising has a defined audience for an additional specimen within an established household collection.
By End User:
Household Value and Project DemandResidential users were the largest end-user segment, accounting for 70.49% of total revenue in 2026. In the Floral Marketing Fund's national study, houseplant purchasers surveyed in 2025 owned more plants and reported higher spending across comparable categories than purchasers surveyed in 2019 and 2021, despite buying less frequently. Among suppliers serving this established buyer population, higher reported spending alongside fewer purchases makes the value of each transaction a relevant commercial objective. A range organized around an owner's next distinct addition can pursue that spending through assortment differentiation, keeping the offer relevant when buying occasions are less frequent.
Commercial users are the fastest-growing segment, with a projected CAGR of 5.7% over 2027-2032. In 2025, the trading floors at JPMorganChase's new headquarters in New York included live plants in their arrival areas, as documented by project architect Skidmore, Owings & Merrill. That defined space gives commercial suppliers a placement brief for a coordinated plant offer. Separately, government and public infrastructure provided an adjacent service example when Yokohama City re-let foliage-plant care for City Hall's lower floors on February 20, 2026, to a different contractor from its February 2025 award. These uses distinguish supplying a specified workplace arrangement from bidding for ongoing care outside the counted plant sale.
By Distribution Channel:
Physical Reach and Digital SpecializationOffline was the largest segment, with 76.31% of revenue in 2026. FranceAgriMer and VALHOR's 2025 consumer panel found that French households buying indoor plants favored mass retailers and florists, followed by garden centers. This pattern supports several physical routes to the same household buyer base, with plant specialists and broader retail participating. For growers, access to multiple types of stores can make distribution breadth a commercial asset within an established channel. That ordering gives mass-retail and florist accounts priority when a grower chooses its initial French household distribution partners.
Online is the fastest-growing segment, with a projected CAGR of 9.5% over 2027-2032. In 2025, Palmstreet reported that Harry Luu of PlantZaddyTherapy sold 2 rare houseplants through its live-shopping app for USD 16,000 and USD 26,000. Palmstreet described the plants as high-maintenance specimens for serious collectors. For a specialist plant seller, that format can connect a distinctive specimen with buyers beyond the immediate setting of a physical shop. These collector transactions support a specialist live-selling proposition centered on each plant's identity, rather than the breadth of an ordinary houseplant catalog.
Geography Analysis
North America Indoor Plants Market
North America accounted for a 37.37% share of the indoor plants market size in 2026. U.S. floriculture operations with at least USD 100,000 in annual sales recorded USD 1.41 billion in potted-flowering-plant sales in 2025. This broader potted category gives larger U.S. floriculture growers a substantial domestic commercial base for developing indoor offerings around plant formats they already produce and sell. For indoor-focused suppliers, the competitive task is to distinguish a home or workplace use within formats that established U.S. growers produced at commercial scale in 2025.
Asia-Pacific Indoor Plants Market
Asia-Pacific is the fastest-growing geography, with a projected CAGR of 6.3% over 2027-2032. China's potted-plant output rose in 2025, when the sector represented 30% of national flower sales and 7.6% of national flower-production area. Personal-use household consumption replaced traditional festival demand as the core support for China's potted-plant consumption in 2025. That shift gives growers and retailers a reason to design offers for ordinary household use alongside occasional celebrations. Positioning plants for household enjoyment can broaden the selling calendar for indoor-compatible varieties, linking the regional growth opportunity to everyday relevance as well as the capacity to produce potted plants.
In South America, Brazil's 2026 Mother's Day outlook highlighted potted tulips, orchids and azaleas, while 23 Hotel's June 2025 account described tropical plants in its Medellín guest rooms and common areas. In Europe, more than half of the indoor flowering plants French households bought in 2025 were gifts. In Warsaw, 4Nature System installed 2 mobile live-plant vertical gardens for Kinnarps at Lufthansa's office, alongside a stabilized-moss panel. In Middle East & Africa, Crystal Gardens designed a Nairobi corporate-office reception and lobby with low-maintenance indoor plants selected for artificial-light conditions. The French and Brazilian examples favor occasion-ready flowering displays, whereas the Warsaw and Nairobi projects make installation format and office lighting relevant to the plant offer.
Regulatory Framework and Outlook
This comparison assesses selected jurisdictions from the perspective of commercial importers of live indoor plants and propagation stock. The key commercial issue is whether an importer can preserve the intended plant format while meeting soil, certification and quarantine conditions. The ratings weigh access through those compliance routes, with country-specific controls shaping the offer that can reach buyers.
Regulatory Table of Indoor Plants Market
| Decision factor | United States | Brazil | China | France | South Africa |
|---|---|---|---|---|---|
| Primary authority | USDA APHIS | Ministry of Agriculture and Livestock (MAPA) | China Customs | DRAAF and SIVEP border-control services | National Plant Protection Organisation of South Africa (NPPOZA) |
| Key instruments or direction | 7 CFR Part 319, Section 319.37-10 | Normative Instruction MAPA No. 28 of 2020 | Customs Decree 279, effective April 1, 2026 | EU Regulations 2016/2031 and 2024/3115 | Agricultural Pests Act, 1983, and 2026 fee amendment |
| Commercial effect | Growing-media-free default for plants for planting, with specified exceptions | Import permission for regulated articles destined for quarantine | Declarations, approval documents and phytosanitary certificates for propagation material; special approval for soil | Certificates for third-country plant imports; identity and physical checks may apply | Permits unless exempt; phytosanitary duties also cover exempt goods |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The United States' 2026 7 CFR Part 319 growing-media restrictions include specified exceptions, while China's Decree 279, effective April 1, 2026, requires declarations and phytosanitary documents for imported propagation material. Brazil's Normative Instruction MAPA No. 28 of April 20, 2020, governs permission for quarantine-bound regulated articles, making quarantine entry the relevant compliance decision for that route. For France, EU Regulation 2026/1101, adopted May 22, 2026, changes minimum check frequencies rather than certificate duties, leaving importers subject to the applicable certificate and border-control framework. South Africa's Plant Health (Phytosanitary) Act 35 of 2024 was uncommenced on October 20, 2026, leaving existing permit exemptions and phytosanitary duties operative instead of the 2025 drafts' destination and quarantine proposals.
Value Chain Stages
The value chain compares cultivation and retail distribution, followed by adjacent plant-care services outside measured plant-sales revenue. Costa Farms grows most of its houseplants in Miami and also sells plants directly to consumers. That integration gives a grower access to selling revenue alongside its production activity, making the boundary between stages commercially significant.
Value Chain Analysis Table of Indoor Plants Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Plant cultivation | Houseplant growers such as Costa Farms | Plant sales | Exposure to concentrated growing locations | Qualify alternative growing sites |
| Retail distribution | Online plant retailers such as The Sill | Plant, pot and care-accessory sales | Care support must reach remote customers | Connect plant selection with targeted care resources |
| Plant care services | Plant-care contractors such as Sakata no Tane Green Service Co., Ltd. | Plant-care service contracts | Dependence on individual building awards | Develop a broader portfolio of care accounts |
| Source: Mordor Intelligence | ||||
The Sill sells indoor plants, pots, soil, care tools and grow lights through its online store. Bloomscape pairs its indoor-plant offering with plant-specific care guidance. Care guidance can support subsequent plant purchases, while accessory sales and adjacent care contracts offer separate earnings beyond the counted plant transaction.
Competitive Landscape
Market Concentration
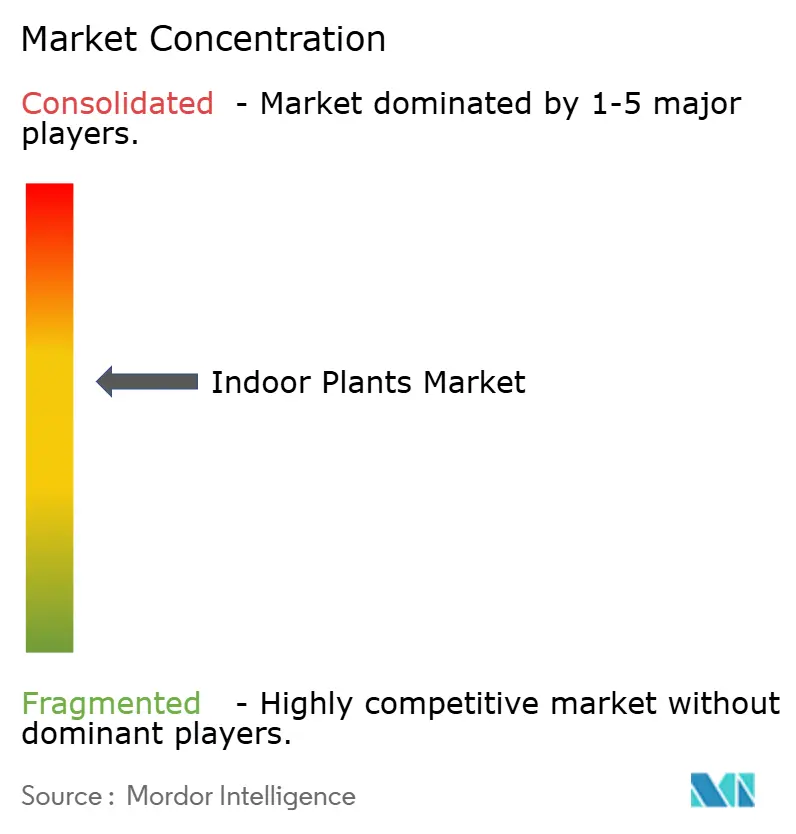
Competition is fragmented across growers, breeders, assembled plant products and retailers, with large operators specializing in different functions. Costa Farms grows more than 1,500 plant varieties on 5,200 acres across its broader operation and propagates houseplants in the United States and Dominican Republic. Dümmen Orange and Syngenta Flowers participate in ornamental breeding and propagation. LiveTrends Design Group designs and assembles plant products for retail customers, while IKEA (Indoor Greenery Line) sells live potted indoor plants in the United States. Syngenta Group reported flat Flowers sales in 2025, before agreeing to divest that business into a joint venture.
In May 2026, Syngenta Group agreed to divest its Flowers business into a joint venture with Dümmen Orange, combining ornamental breeding and propagation businesses, including annual, perennial and potted plant portfolios. Syngenta Group was to retain a significant economic interest in the venture. The announcement described combining Dümmen Orange's expertise in cut flowers with Syngenta's leadership in seed varieties, alongside annual, perennial and potted plant portfolios that both companies built over decades. The venture's indoor-plant relevance rests on potted plants within that pooled range, rather than the full breadth of the ornamental businesses.
Regulatory approval to establish the new company followed on October 1, 2026. The proposed venture would consolidate upstream portfolios while plant-product assembly and retail distribution remain separate areas of competition. Downstream, LiveTrends provides product development, merchandising and logistics for retail customers. Those capabilities address how a finished plant product reaches a store, extending beyond the choice of breeding material. The October 1 decision permits establishment of the company, making approval a step toward the proposed combination rather than completion of the joint venture.
Indoor Plants Industry Leaders
-
Costa Farms
-
Dümmen Orange
-
Syngenta Flowers
-
LiveTrends Design Group
-
IKEA (Indoor Greenery Line)
- *Disclaimer: Major Players sorted in no particular order
Indoor Plants Market Companies Covered in this Report
- Costa Farms
- Dümmen Orange
- Syngenta Flowers
- LiveTrends Design Group
- IKEA (Indoor Greenery Line)
- Bloomscape
- The Sill
- Bakker Holland
- Mother
- Leon & George
- Miracle-Gro (Scotts)
- Click & Grow
- AeroGarden
- Gardener's Supply Co.
- PlantX Life
- Beekenkamp Group
- Ball Horticultural
- Costa Group (AU)
- Dobbies Garden Centres
- Bunnings (AU)
- Patch Plants
- Green Factory
- Plantagen
- FlowerBX
Key Opportunities for Market Participants
These opportunities compare assortment expansion, first-purchase conversion and adjacent institutional plant care. An assortment offer can increase value per customer relationship, whereas a beginner offer must address concerns about keeping plants and pets. Institutional care tenders signal an adjacent service opening outside measured plant-sales revenue, with interior-plant care bundled into wider site services.
Market Opportunities Table of Indoor Plants Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Broader assortments for existing owners | Surveyed consumers in 2025 expected higher 2026 spending across all 10 categories studied | Existing houseplant purchasers | Test differentiated houseplant collections | Spending intentions may not become purchases | Houseplant growers such as Costa Farms |
| First-plant conversion | In 2025, 77% of surveyed non-purchasers would or might consider a future purchase | Prospective residential buyers | Pair pet-friendly choices with plant-specific care guidance | Pet concerns, plant survival and spending priorities | Indoor-plant retailers such as Bloomscape |
| Bundled office-plant maintenance accounts | SABC sought a 5-year garden, grounds and interior-plant maintenance service for its KwaZulu-Natal office, with bids due at noon on October 22, 2026, after a compulsory October 16 briefing | Office facilities operators | Combine indoor-plant care with landscape-service delivery | Ability to cover the wider garden and grounds scope | South African office-plant providers such as Servest |
| Source: Mordor Intelligence | |||||
The strongest consumer opening is a first-plant offer that addresses care and pet concerns together. A care guide addresses only part of that problem, because spending priorities are a separate stated obstacle among surveyed non-purchasers. A focused starter assortment can therefore combine a suitable plant, clear care instructions and a transparent entry price, making conditional interest easier to act on.
Recent Industry Developments in Indoor Plants Market
- Oct 2026: Regulatory approval was granted on October 1 to establish the proposed joint venture into which Syngenta Group agreed to divest its Flowers business with Dümmen Orange, including annual, perennial and potted plant portfolios.
- Jul 2026: The Plant Company, the licensed grower of Proven Winners leafjoy houseplants, named EHR a North American brokerage partner authorized to sell and distribute the program to independent garden centers throughout EHR's service network.
Indoor Plants Market Report Scope and Research Methodology
Market Definition and Coverage
The global indoor plants market measures annual sales value of live, rooted plants and artificial or preserved plant arrangements sold for indoor settings worldwide, including managed home, office, public, event, and research environments. Counted sales reach residential, commercial, and government buyers through offline and online channels.
Scope exclusions: Outdoor landscaping trees and plants sold for outdoor planting, cut flowers and bouquets, separately sold growing supplies and equipment, and indoor landscaping installation and maintenance services are excluded.
Segments Covered in This Report
- By Plant Type
- Foliage Plants
- Flowering / Ornamental Plants
- Succulents & Cacti
- Herbs & Edible Indoor Plants
- Aquatic Indoor Plants
- Artificial & Preserved Indoor Plants
- By Light Requirement
- Low Light (Shade-loving)
- Medium / Indirect Light
- High / Direct Light
- By Product Form
- Potted Soil-based
- Hydroponic / Water-based
- Terrariums & Miniature Landscapes
- Smart Potted / IoT-enabled
- By Application Purpose
- Air Purification & Wellness
- Home & Interior Decoration
- Commercial & Corporate Landscaping
- Gifting & Events
- Research & Biotechnology
- By End User
- Residential
- Commercial
- Offices & Co-working Spaces
- Hospitality
- Healthcare Facilities
- Educational Institutions
- Retail & Shopping Malls
- Government & Public Infrastructure
- By Distribution Channel
- Offline
- Garden Centers & Nurseries
- Home Improvement & DIY Stores
- Supermarkets / Hypermarkets
- Specialty Boutiques & Concept Stores
- Online
- E-commerce Marketplaces
- Direct-to-Consumer Brand Websites
- Subscription Services
- B2B Horticulture Platforms
- Offline
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East & Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East & Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as USDA National Agricultural Statistics Service Floriculture Crops tables help distinguish indoor-use foliage and potted flowering categories from broader floriculture sales. Eurostat crop-production metadata provides comparable European production-area and output context, while UN Comtrade records plant trade by product code and FAOSTAT documents agricultural data series and collection practices that can inform production and supply checks. Together these sources supply production, trade, and category signals that are reconciled with company-reported sales to build the end-user value estimate.
Company annual reports, investor presentations, public filings, and reputable horticulture press can clarify reported sales, channel mix, company roles, and material business changes, with each value checked for overlap against producer and trade indicators. These named sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and surveys would target commercial growers, nurseries, retailers, online sellers, distributors, and residential and institutional buyers across APAC, EMEA, and the Americas. Respondents would check secondary-source interpretations and explain gaps in prices, channel coverage, product mix, and cross-border flows, while their input would be triangulated against published company, production, trade, and consumer indicators before any forecast assumption is retained.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 30% | EMEA: 30% |
| Smaller Players: 25% | Managers: 50% | Americas: 30% |
Market-Sizing & Forecasting
The analyst would estimate global annual value from a top-down reconciliation of final sales across regions, with selective supplier roll-ups and sampled average selling price times unit volume checks used to test the total. Key indicators include floriculture sales and quantities by relevant plant category, live-plant import and export values, producer and retailer revenue trends, online versus offline channel mix, and residential and commercial demand conditions. Trade and production measures serve as supply checks and are adjusted for non-indoor uses, re-exports, and duplicate wholesale-retail transactions. Segment shares are derived from category sales where published, then cross-checked with producer assortments, retailer listings, channel information, and interviews so that each plant-type, light, product-form, application, end-user, channel, and regional split fits the corresponding total. Where direct category values are missing, the analyst uses adjacent years and comparable public indicators to bound shares, records the evidence gap, and tests the resulting estimate against the top-line total. For forecasting, multivariate regression relates historical value to demand, channel, price and product-mix indicators, while scenario analysis tests material changes in urban household demand, workplace planting, online access, and supply-led price movements. Primary respondents review the direction and relevance of each variable-level projection, and unsupported inputs are revised or excluded.
Data Validation & Update Cycle
Estimates are triangulated across company disclosures, production statistics, trade flows, and channel signals, with each series checked for geography, year, unit, product coverage, and possible overlap. Analysts investigate material variances against prior periods and independent signals, resolve anomalies through source rechecks and documented adjustments, and re-contact relevant respondents when definitions, prices, or reported activity conflict. A second analyst reviews the reconciliation before sign-off. The model is refreshed annually, revisited between cycles after material industry, regulatory, or trade events, and given a fresh source and calculation pass immediately before delivery.
Mordor Intelligence's Indoor Plants Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global indoor plants market measures annual sales value of live, rooted plants and artificial or preserved plant arrangements sold for indoor settings worldwide, including managed home, office, public, event, and research environments.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. For forecasting, multivariate regression relates historical value to demand, channel, price and product-mix indicators, while scenario analysis tests material changes in urban household demand, workplace planting, online access, and supply-led price movements.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 14.12 B (2027) | |
| Global Research Firm A | USD 19.61 B (2025) | At its 2025 base, this estimate is 38.9% above this report's 2027 value of USD 14.12 B, 2 years later. Its published forecast trajectory is faster, which reinforces the higher comparison direction. |
| Global Analytics Platform B | USD 21.75 B (2025) | At its 2025 base, this estimate is 54.0% above this report's 2027 value of USD 14.12 B, 2 years later. Its published forecast trajectory is faster, which reinforces the higher comparison direction. |
For Mordor Intelligence, estimates are triangulated across company disclosures, production statistics, trade flows, and channel signals, with each series checked for geography, year, unit, product coverage, and possible overlap.
Key Questions Answered in the Report
What is the Indoor Plants market size and expected growth?
The size is expected to grow from USD 14.12 billion in 2027 to USD 16.71 billion by 2032, at a CAGR of 3.42% over 2027-2032.
What is encouraging demand for indoor plants?
Social media, automated care, and perceived wellness support demand. ModMoss's September 2026 survey of 1,000 U.S. adults who owned at least one living houseplant found that 56% of Gen Z respondents said social media had influenced a plant purchase.
Which plant type holds the largest share?
Foliage plants led with 41.16% of revenue in 2026. Succulents and cacti are the fastest-growing segment, with a CAGR of 6.45% over 2027-2032.
Which companies compete in indoor plants?
Major participants include Costa Farms, Dümmen Orange, Syngenta Flowers, LiveTrends Design Group and IKEA (Indoor Greenery Line). Syngenta Group agreed in May 2026 to divest its Flowers business into a joint venture with Dümmen Orange.
What constrains indoor-plant suppliers' growth?
Grower price pressure and protected-species trade procedures constrain expansion. At Qingzhou's 2026 tropical-plant exhibition, several mainstream varieties showed lower prices and higher output than in 2025.
Which region leads indoor-plant sales and where is growth fastest?
North America held 37.37% of revenue in 2026, while Asia-Pacific is the fastest-growing region with a CAGR of 6.3% over 2027-2032.