
Indonesia Cloud Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 2.46 Billion |
| Market Size (2026) | USD 2.81 Billion |
| Market Size (2031) | USD 5.5 Billion |
| Growth Rate (2026 - 2031) | 14.32 % |
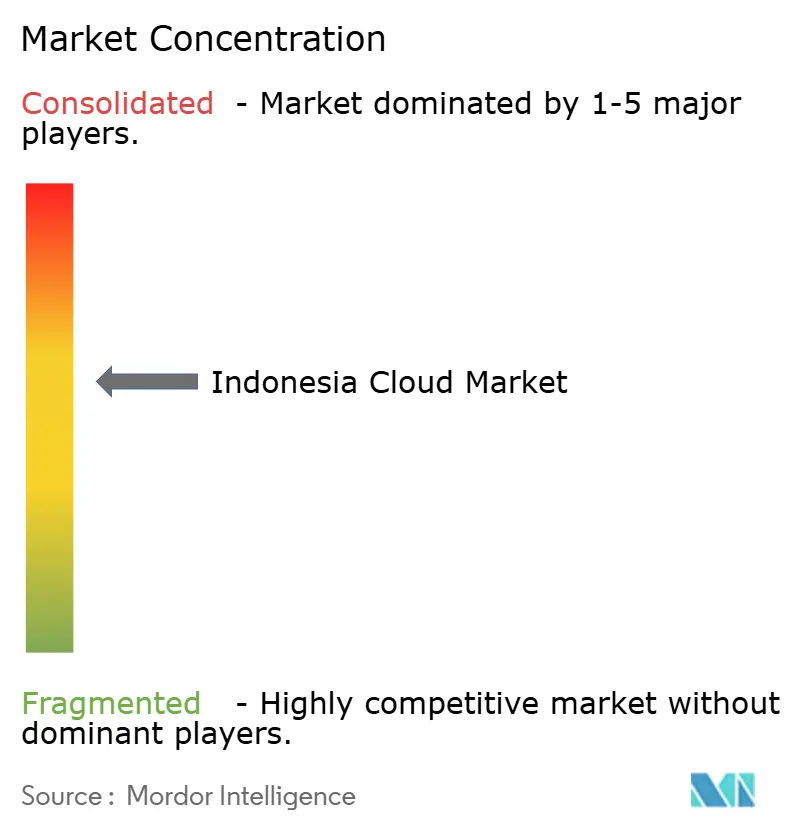
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Indonesia Cloud Market Analysis by Mordor Intelligence
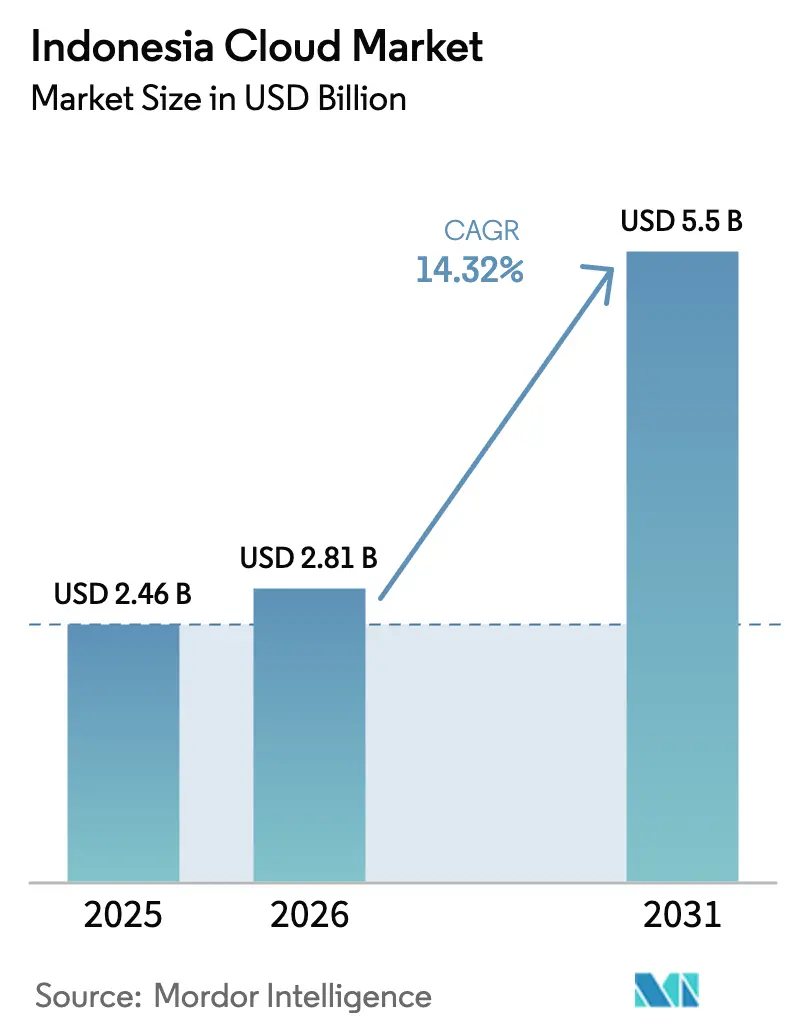
The Indonesia cloud market size is expected to grow from USD 2.46 billion in 2025 to USD 2.81 billion in 2026 and is forecast to reach USD 5.5 billion by 2031 at 14.32% CAGR over 2026-2031. This expansion is propelled by sustained enterprise digital-transformation spending, large-scale hyperscaler capital expenditure, and government mandates under the Digital Indonesia 2025 framework. Public cloud retains leadership on the back of Java-centric infrastructure density, while hybrid architectures gain momentum as regulators tighten data-sovereignty rules. Sector-specific cloud platforms that combine AI and compliance functionality differentiate providers, and rising ESG targets push demand for renewable-powered data centers. Talent scarcity and escalating cyber-attack losses temper adoption velocity, but overall growth prospects remain intact as providers embed security-by-design and training initiatives into service portfolios.
Key Report Takeaways
- By service model, Software as a Service led with 44.62% revenue share of the Indonesian cloud market in 2025, Platform as a Service is projected to expand at a 15.42% CAGR to 2031.
- By deployment model, public cloud accounted for 66.05% of the Indonesian cloud market share in 2025, while hybrid cloud recorded the highest projected CAGR at 15.21% through 2031.
- By organization size, large enterprises commanded a 72.05% share of the Indonesian cloud market size in 2025, yet the SME segment is advancing at a 15.18% CAGR through 2031.
- By end-use industry, BFSI captured 27.32% of Indonesia's cloud market revenue in 2025, whereas healthcare and life sciences posted the fastest 15.66% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Indonesia Cloud Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rapid digital-transformation spend by enterprises | +3.2% | Java-centric with spillover to Sumatra, Kalimantan | Medium term (2-4 years) |
| Hyperscaler CAPEX on Indonesian data-centre regions | +2.8% | Java, Batam, with expansion to outer islands | Long term (≥ 4 years) |
| Government "Digital Indonesia 2025" and e-Gov push | +2.1% | National, with priority focus on underserved regions | Short term (≤ 2 years) |
| Surge in e-commerce/fintech cloud workloads | +1.9% | Java dominance, expanding to tier-2 cities | Medium term (2-4 years) |
| National Data Centre (PDN) enabling sovereign cloud | +1.5% | National infrastructure with regional data centers | Long term (≥ 4 years) |
| Renewable-powered 'green-cloud' demand from ESG-focused firms | +1.1% | Java, Sumatra with geothermal/solar integration | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rapid digital-transformation spend by enterprises
Large corporations modernize core systems to defend market share against digital-native rivals. Microsoft’s USD 1.7 billion regional cloud plan and Oracle’s USD 6.5 billion Batam campus validate long-term demand. Multi-cloud adoption accelerates as GoTo partners concurrently with Alibaba Cloud and Tencent Cloud to balance pricing and resilience. [1]GoTo Group, “Alibaba and GoTo Group Announce Strategic Partnership,” gotocompany.com Telkom Indonesia’s alliance with Reka AI shows traditional firms embedding language-aware AI through Platform as a Service to improve customer interactions. Continuous innovation cycles elevate spend beyond one-off migrations, sustaining uptake of higher-margin cloud offerings. This dynamic cements SaaS leadership while igniting demand for DevOps-ready PaaS stacks.
Hyperscaler CAPEX on Indonesian data-center regions
Amazon’s USD 5 billion AI-cloud pledge, alongside Digital Realty’s USD 499 million Jakarta JV, reinforces confidence in multiyear workload growth. Investment clusters around low-latency corridors in Greater Jakarta and Batam, with renewable power procurement aligning ESG goals. Google Cloud’s BerdAIa program illustrates how regional capacity underpins ecosystem building for industry-specific AI. [2]Google Cloud, “Google Cloud Unveils Indonesia BerdAIa,” googlecloudpresscorner.com Hyperscalers accept decade-long payback profiles, signaling belief in Indonesia’s macro stability and regulatory clarity. Local colocation providers benefit via anchor-tenant demand, catalyzing secondary market development in second-tier cities.
Government Digital Indonesia 2025 and e-Gov push
Mandatory cloud-first rules for ministries plus the National Data Centre initiative spur immediate public-sector migrations. The UMKM Go Digital program, bringing 27 million SMEs online, expands downstream infrastructure consumption. Parallel grid expansions of 37 electricity projects totaling 3,222 MW improve power reliability for new data halls. Coordinated policy plus physical infrastructure raises the Indonesia cloud market growth ceiling, especially for hybrid offerings that match sovereignty needs.
Surge in e-commerce/fintech cloud workloads
Digital-economy value hit USD 90 billion in 2024 and could quadruple by 2030, multiplying compute and storage requirements. GoTo and Indosat’s generative-AI rollout underscores domain-specific model demand that favors local language processing. Crypto-tax reforms that waive VAT propel transaction volumes, further stressing fintech back-ends. E-commerce logistics firms like JNE adopt Alibaba Cloud DRaaS to assure uptime during sales peaks. Consequently, the Indonesian cloud market witnesses elevated Infrastructure as a Service usage, complemented by low-code PaaS for rapid fintech product launches.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating cybersecurity-breach costs | -1.8% | National, with highest impact on Java financial centers | Short term (≤ 2 years) |
| Complex data-localisation and sectoral compliance | -1.4% | National regulatory framework with sector-specific variations | Medium term (2-4 years) |
| Shortage of cloud-skilled talent and high wage inflation | -1.2% | Java concentration with spillover effects nationally | Medium term (2-4 years) |
| Inter-island power and fibre reliability gaps | -0.9% | Outer islands, particularly Papua, Maluku, eastern regions | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating cybersecurity-breach costs
A USD 8 million ransomware demand on the National Data Center shook enterprise confidence, pushing risk-averse sectors to delay migrations. [3]Kementerian Komunikasi dan Digital, “Komdigi Bekukan Izin Worldcoin dan WorldID,” komdigi.go.id New child online protection rules add additional security layers, increasing provider overhead. Financial institutions face punitive fines and reputational harm, tilting the market toward vendors with proven zero-trust frameworks. Heightened scrutiny may short-term curb Indonesia's cloud market uptake among late-adopting firms until providers showcase certified resilience programs.
Complex data-localization and sectoral compliance
While a 2025 trade accord softened some cross-border data rules, sector-specific regimes remain onerous. The 15% global minimum tax introduces new reporting duties for multinationals. Imminent AI regulation adds further uncertainty. Compliance cost burdens weigh heavier on niche PaaS and SaaS vendors, potentially slowing innovation and fragmenting the Indonesian cloud industry landscape.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Service Model: SaaS entrenches while PaaS accelerates
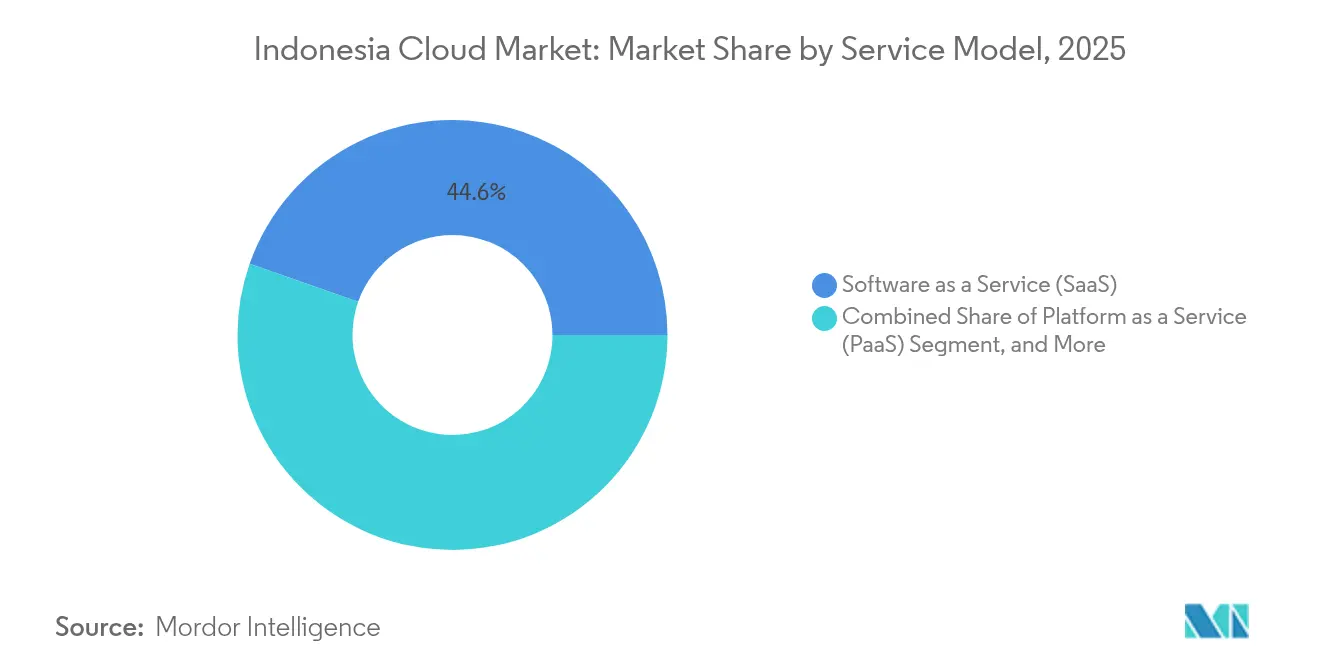
Software as a Service accounted for 44.62% of the Indonesian cloud market in 2025 as firms opted for ready-to-run business applications with predictable OPEX. PaaS follows with the fastest 15.42% CAGR, reflecting developer demand for micro-services and container orchestration. Infrastructure as a Service underpins both, supplying elastic compute that smaller SaaS players lease rather than own. Disaster Recovery as a Service uptake spikes after high-profile outages, embedding resiliency into board-level risk agendas.
The Indonesian cloud market size for SaaS will widen as compliance-ready solutions gain traction in BFSI and healthcare. PaaS vendors differentiate on domain-specific APIs, such as Telkom DWS’s multimedia CPaaS suite. Local provider Lintasarta bundles OpenShift-based PaaS with backup vaults, meeting stringent localization rules. These integrated stacks protect margins against hyperscale price cuts, stabilizing competitive equilibrium.


By Deployment Model: Hybrid strategies rise
Public deployments captured 66.05% Indonesia cloud market share in 2025 due to immediate scalability and cost visibility. Hybrid architectures, however, post a 15.21% CAGR as firms blend on-premise or colocation nodes for latency-sensitive or regulated workloads. Private clouds remain niche, reserved for ultra-regulated setups in defense or critical infrastructure.
Hybrid growth stems from GoTo’s dual-provider play and Singtel-GMI’s pooled GPU project that share capacity across borders. Rollout of Wi-Fi 6E/7 enables site-to-cloud throughput up to 46 Gbps, supporting distributed architectures. The Indonesian cloud market size for hybrid solutions is forecast to compound as regulators mandate in-country data copies while boards demand multicloud resilience.
By Organisation Size: SME momentum builds
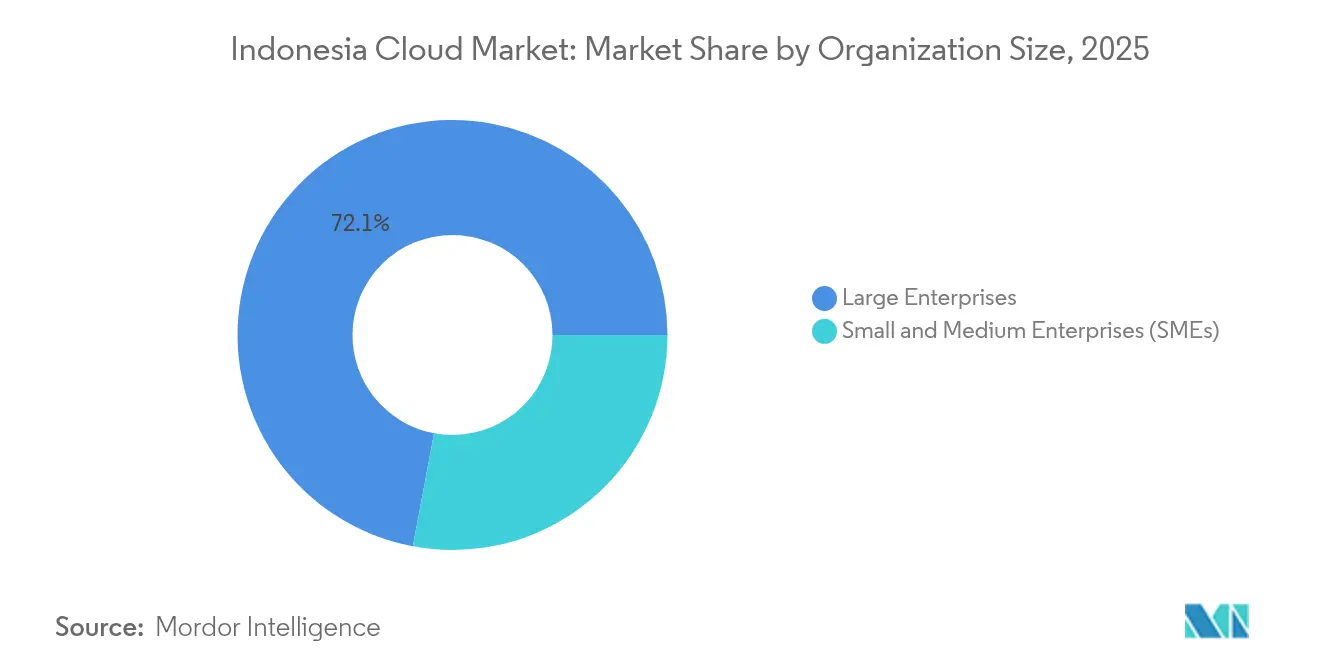
Large enterprises delivered 72.05% Indonesia cloud market revenue in 2025, leveraging scale to negotiate enterprise-grade SLAs. Yet the SME cohort charts 15.18% CAGR on the back of the UMKM Go Digital program and low-code SaaS billing models. Start-up resilience, with 65% of investors planning larger tickets through 2031, adds to SME demand trajectories.
Affordable bundles from IDCloudHost and Dewaweb target payroll, accounting, and storefront apps, removing upfront CAPEX. For providers, the long-tail SME pool diversifies revenue and dilutes concentration risk tied to a handful of conglomerates. Consequently, Indonesia's cloud market penetration deepens into rural and tier-2 cities as connectivity improves.
By End-Use Industry: Healthcare surges
BFSI preserved 27.32% share in 2025, anchored by open-banking obligations and real-time settlement rules. Yet healthcare and life sciences record a 15.66% CAGR as tele-consult platforms and electronic medical record mandates take hold. Manufacturing, retail, and transport harness supply-chain visibility apps, expanding horizontal cloud uptake.
Indonesia's cloud market size for healthcare will scale further once AI-driven diagnostics integrate with government insurance schemes. Energy utilities deploy IoT telemetry in line with the 69.5 GW renewable roadmap, feeding analytics workloads to regional data hubs. Sector diversification cushions providers against cyclicality in any single vertical, ensuring broad-based revenue streams.
Geography Analysis
Java anchors 58.7% of GDP and houses most hyperscale zones, giving it an outsized Indonesia cloud market share. Proximity to banking headquarters and fiber backbones trims latency, driving public-cloud offloads from legacy data rooms. Government electrification raised village coverage to 99.92%, extending cloud-readiness to peri-urban districts. Java’s dominance persists, but growth rates in outer islands now outpace as new zones come online.
Sumatra, Kalimantan, and Sulawesi inherit spill-over demand from mining and agribusiness digitization. Renewable build-out 76% of the 2025-34 capacity plan pitches these islands as green data-hub alternatives. Improved sea-cable redundancy narrows bandwidth gaps, allowing regional firms to adopt hybrid architectures without relocating compute to Jakarta.
Bali-Nusa Tenggara plus Papua-Maluku show niche uptake driven by tourism analytics and e-government portals. Oracle’s Batam investment illustrates how strategic free-trade zones can attract hyperscaler nodes outside Java. Continued subsidies for fiber and power back-haul remain critical to unlock full cloud potential across the archipelago, equalizing Indonesia's cloud market access.
Regulatory Landscape
Indonesia regulates cloud services mainly through the Ministry of Communication and Digital Affairs (Komdigi) framework for Electronic System Providers (ESPs/ESOs). Government Regulation No. 71 of 2019 is the foundational rulebook, and Ministerial Regulation No. 5 of 2025 sets out operational and registration obligations. Data protection requirements continue to be shaped by the Personal Data Protection Law (Law No. 27 of 2022), including ongoing work to stand up a dedicated Data Protection Authority through a presidential regulation that remained under government review as of March 2026.
Sectoral oversight adds additional compliance layers that shape deployment choices. The Financial Services Authority (OJK), in coordination with Komdigi, governs cloud use in financial services through residency and operational controls, which pushes regulated workloads toward in-country regions and well-audited operating models. For strategic electronic systems supporting public services, information-security expectations such as alignment to SNI ISO/IEC 27001 act as a practical baseline for vendors selling into government and critical-use environments.
Value Chain Analysis
Indonesia's cloud value chain starts with hyperscalers (AWS, Microsoft, Google, and other global providers) delivering core IaaS/PaaS building blocks, AI accelerators, and managed services. It then extends into local data center and interconnection capacity concentrated in Greater Jakarta and Batam-linked corridors such as the Nongsa Special Economic Zone. Under Komdigi oversight, cloud and data center operators must register as Electronic System Operators and align service offerings with applicable local business classification requirements, which can affect time-to-market for new facilities and regulated cloud services.
Downstream layers include telecom and network providers (fiber backbones, last-mile connectivity, and enterprise links), local cloud providers and integrators (migration, managed services, DRaaS, security operations), and ISVs building sector-specific SaaS on top of hyperscaler platforms. Talent and ecosystem programs also factor into the operating chain. AWS has worked with Indonesian stakeholders on digital-skills initiatives such as Terampil di Awan, and renewable-energy sourcing and utility coordination increasingly influence data center siting and operating economics for both hyperscalers and colocation partners.
Competitive Landscape
Indonesia cloud market competition blends hyperscale capital with local compliance agility. AWS, Microsoft, and Google extend regional zones and AI accelerators to capture enterprise modernization budgets. Alibaba Cloud and Tencent Cloud ride alliances with GoTo and other digital natives for traffic scale. Telkom Indonesia, Biznet Gio, DCI, and newcomer Lintasarta differentiate by local support, rupiah billing, and audited data residency.
Joint-venture models proliferate: Digital Realty pairs with Bersama Digital Infrastructure for a USD 499 million Jakarta campus, delivering neutral interconnectivity to all carriers. [4]Stock Titan, “Digital Realty Enters Indonesia…,” stocktitan.net XL Axiata-Smartfren’s USD 6.5 billion merger pools spectrum to propel 5G edge services nationwide. Indosat’s AI-RAN deployment with Nokia and NVIDIA showcases telco-cloud convergence that can offload radio workloads to regional clouds. Local specialists focus on DRaaS, GPU-as-a-Service, and sovereign PaaS niches, sustaining healthy fragmentation despite hyperscale weight.
Emerging battlegrounds center on sector-tuned SaaS, green-energy procurement, and managed security. Providers that bundle carbon reporting, threat intelligence, and compliance templates win share as tighter regulations loom. Still, the top five vendors combined control less than 60% of total revenue, leaving room for challenger entry in managed Kubernetes, edge caching, and AI model-hosting.
Indonesia Cloud Industry Leaders
Amazon Web Services, Inc.
Microsoft Corporation
Google LLC
Alibaba Cloud (Alibaba Group Holding Limited)
IBM Corporation
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Regulation-led sovereignty requirements and government demand create room for compliant, audit-ready cloud offerings that package residency controls, security baselines, and managed governance for agencies and regulated enterprises. A clear catalyst is the policy direction allowing private cloud services to store and process government data subject to data risk classification requirements, alongside Komdigi's Electronic System Provider regime, including Ministerial Regulation No. 5 of 2025. With local registration and operational controls central to vendor selection, opportunities favor providers and partners that can deliver sovereign configurations across public and hybrid architectures, particularly where procurement emphasizes verifiable controls rather than generic multi-tenant service descriptions.
AI-ready capacity and skills-building add another opportunity set anchored in hyperscaler commitments and ecosystem programs. AWS has maintained a USD 5 billion investment commitment for Indonesia spanning 2021-2036 focused on cloud and AI infrastructure and talent development, while the evidence points to major aggregate hyperscaler investment commitments into the 2026-2029 window. Cross-border operating models also gain clarity where the 2026 US-Indonesia trade agreement recognizes the United States as an adequate jurisdiction for personal data transfers, creating room for architectures that combine in-country processing for sensitive data with approved international transfers for specific workflows, provided sectoral rules such as OJK requirements for financial services are met.
Recent Industry Developments
- May 2026: Microsoft announced USD 4 billion sovereign AI cloud expansion in Indonesia, including a second Jakarta based Azure region, GPU supply, Bahasa LLM training, and a 2.5 million developer pipeline. The initiative expands local AI capacity and governance aligned cloud development.
- February 2026: Amazon Web Services Inc. confirmed continuation of its USD 5 billion, 15 year investment strategy in Indonesia aimed at cloud and AI infrastructure, targeting annual GDP contributions of USD 10.9 billion. The commitment anchors public cloud leadership and datacenter buildout, shaping market dynamics and vendor competition.
- January 2026: Amazon Web Services Inc. met with the Indonesian Ministry of Communication and Digital to discuss expanding local data center capacity to support a projected 260 percent increase in national demand. The talks align with data residency objectives and could influence hyperscaler competition and supply chains.


Research Methodology Framework and Report Scope
Market Definition and Coverage
For this report, the Indonesia cloud market is measured as revenue generated from cloud services delivered to customers in Indonesia, across public, private, and hybrid environments, and covering common cloud service types used by enterprises and public sector buyers.
Scope exclusions: Hardware-only data center equipment sales, on-premises software licenses without a cloud delivery component, and general telecom connectivity are excluded from this market value.
Segmentation Overview
- By Service Model
- Software as a Service (SaaS)
- Platform as a Service (PaaS)
- Infrastructure as a Service (IaaS)
- Disaster-Recovery as a Service (DRaaS)
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Organisation Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By End-Use Industry
- IT and Telecom
- BFSI
- Retail and Consumer Goods
- Manufacturing
- Healthcare and Life Sciences
- Government and Public Sector
- Transportation and Logistics
- Energy and Utilities
- Other End-Use Industries
- By Region
- Java
- Sumatra
- Kalimantan
- Sulawesi
- Bali and Nusa Tenggara
- Papua and Maluku
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the starting structure of the market and to anchor the model to signals from Indonesia's economy and IT spending. We reviewed public releases and statistical series that reflect digital adoption and IT investment trends, including BPS Statistics Indonesia for business and sector baselines, the Ministry of Communication and Digital Affairs for policy direction, Bank Indonesia for payments and digital activity indicators, and the World Bank for macro variables that influence enterprise spending decisions.
To translate those signals into cloud demand, we also used operator and enterprise annual reports, investor presentations, association websites, and reputable business press coverage that discusses data center build-outs and cloud program rollouts. In addition, our analysts used paid subscriptions for company financials and intelligence, news and financials, and a patent database to cross-check product focus and timing, which helped reduce guesswork where public reporting is limited. This list is illustrative, and other sources were also used for data collection, validation, and clarification during the research process.
Primary Interviews and Surveys
Primary work was used to confirm which cloud services are being purchased in Indonesia, how contracts are priced, and how workloads are shifting between public, private, and hybrid setups. We spoke with a mix of cloud service providers, system integrators, data center ecosystem participants, and enterprise buyers across regulated and non-regulated industries, so assumptions like average spend, adoption pace, and renewal patterns could be checked against buyer experience.
Inputs from these discussions were then used to adjust scenario ranges, validate the demand pool by sector, and sanity check year to year growth expectations across the country.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 28% | CXOs: 17% |
| Mid tier: 54% | Functional/Unit leaders: 37% |
| Smaller Players: 18% | Managers: 46% |
Market-Sizing & Forecasting
Market sizing starts from a top-down build where national indicators for IT and digital activity are used to reconstruct the addressable cloud spend pool in Indonesia, before it is split by deployment pattern and common cloud service types. Once that first cut is built, we corroborate totals with selective bottom-up checks, such as sampling typical contract values by customer size, mapping adoption across priority verticals, and using channel feedback to validate what is actually being consumed versus what is being marketed.
A few of the practical inputs that shape the model include enterprise digital transformation budgets, data residency driven migration activity, workload mix shifts between compute, storage, and platform services, average contract duration and renewal behavior, and the pace of new application development that tends to increase SaaS and PaaS usage. Where coverage is uneven, such as smaller buyers with limited disclosure, the model fills gaps using proxy adoption rates by industry and organization size, and then re-tests those proxies in interviews. Forecasts are produced using scenario analysis, where growth paths are tied to the expected timing of capacity additions, regulatory enforcement intensity, and macro spending conditions, and then the final curve is adjusted to reflect the expert consensus from primary checks.
Data Validation & Update Cycle
Outputs are validated through triangulation across multiple independent signals, followed by variance checks at the service type and deployment level so unusual jumps are investigated rather than averaged away. When results look inconsistent with observed demand markers, the underlying assumptions are reopened, and targeted follow-up conversations are triggered to confirm what changed in buyer behavior or pricing.
Before sign-off, the model and write-up go through multi-step internal review so calculation logic, scope, and units are consistent across the report. Reports are refreshed annually, and interim updates are made when material events occur, such as major regulatory shifts or step-changes in capacity that can affect near-term spending. Right before delivery, a final pass is done so clients receive the most current view available.
Mordor Intelligence's Indonesia Cloud Market Size Measured Against Other Published Estimates
Published market values for Indonesia cloud often do not match because different studies define the spend pool differently, use different base years, and rely on different price and adoption assumptions. Differences also come from whether figures represent customer spend in-country, provider revenue booked locally, or a broader digital infrastructure bundle.
Hardware-led data center construction and colocation revenue sit outside Mordor Intelligence's Indonesia cloud scope, which keeps the estimate focused on cloud service revenue consumed by Indonesian customers rather than the wider build-out value chain.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 2.46 B (2025) | |
| Industry Research House A | USD 4.72 B (2023) | Uses an earlier base year and may bundle adjacent items like hosting, managed infrastructure, or broader IT outsourcing, which can lift the total compared with a cloud-services-only view. |
| Specialist Research House B | USD 3.58 B (2024) | Measures a narrower sub-market labeled as cloud compute, but often applies aggressive usage and price progression assumptions across fast-growing workloads, which can inflate near-term value if not cross-checked against contract realities. |
Across the table, the spread is mainly explained by what is counted as cloud versus nearby categories, and by how fast prices and consumption are assumed to move year to year. By keeping inputs tied to observable adoption signals and re-checking assumptions with on-the-ground participants, the final number remains traceable to clear steps that can be revisited and reviewed.


Key Questions Answered in the Report
What is the forecast value of the Indonesia cloud market by 2031?
The market is projected to reach USD 5.5 billion by 2031, growing at a 14.32% CAGR.
Which cloud service model currently leads adoption in Indonesia?
Software as a Service leads with 44.62% revenue share in 2025.
Why are hybrid cloud architectures gaining momentum?
Enterprises seek to comply with data-sovereignty rules while preserving flexibility, driving hybrid deployments at a 15.21% CAGR.
Which vertical shows the fastest cloud spending growth?
Healthcare and life sciences posts the highest 15.66% CAGR through 2031 as telemedicine and digital health investments rise.
How is government policy influencing demand?
Digital Indonesia 2025 mandates cloud-first approaches and, coupled with nationwide power and connectivity upgrades, expands addressable demand.
What security challenges affect adoption?
A high-profile ransomware attack and stricter child-safety rules increase compliance costs, pushing firms toward providers with robust zero-trust frameworks.
Page last updated on:


