
India Chocolate Market Analysis by Mordor Intelligence
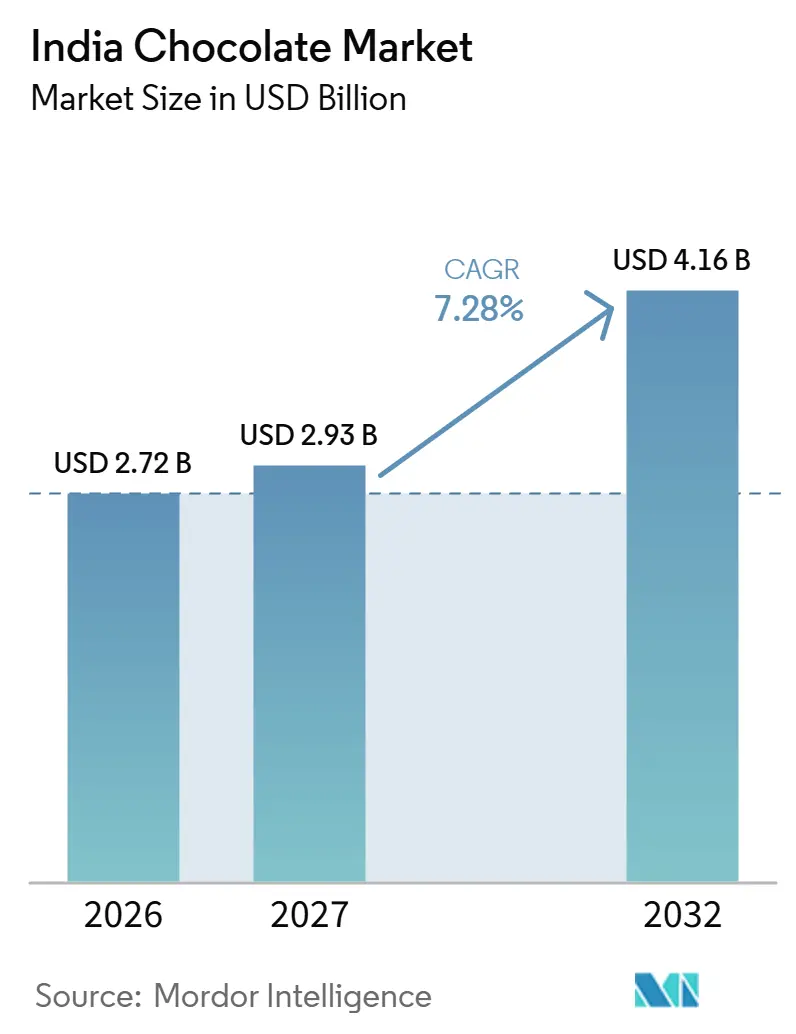
The India chocolate market size is expected to increase from USD 2.72 billion in 2026 to USD 2.93 billion in 2027 and reach USD 4.16 billion by 2032, growing at a CAGR of 7.28% over 2027-2032. The market's volume is expected to increase from 297.4 thousand tons in 2026 to 312 thousand tons in 2027 and reach 396.3 thousand tons by 2032, growing at a CAGR of 4.9% over 2027-2032.
Occasion-led gifting and recipe preferences create opportunities for chocolate sellers in India. Producers can differentiate through premium fillings and specific formulations that give gift buyers a reason to choose a premium bar. Heat-sensitive delivery can limit those opportunities, making product condition part of the online offer. Premium gift assortments can capture occasion demand, yet price-sensitive buyers and heat risk in delivery limit how far those offers can travel, so sellers need pack sizes, price points and delivery methods that suit both.
Key Report Takeaways
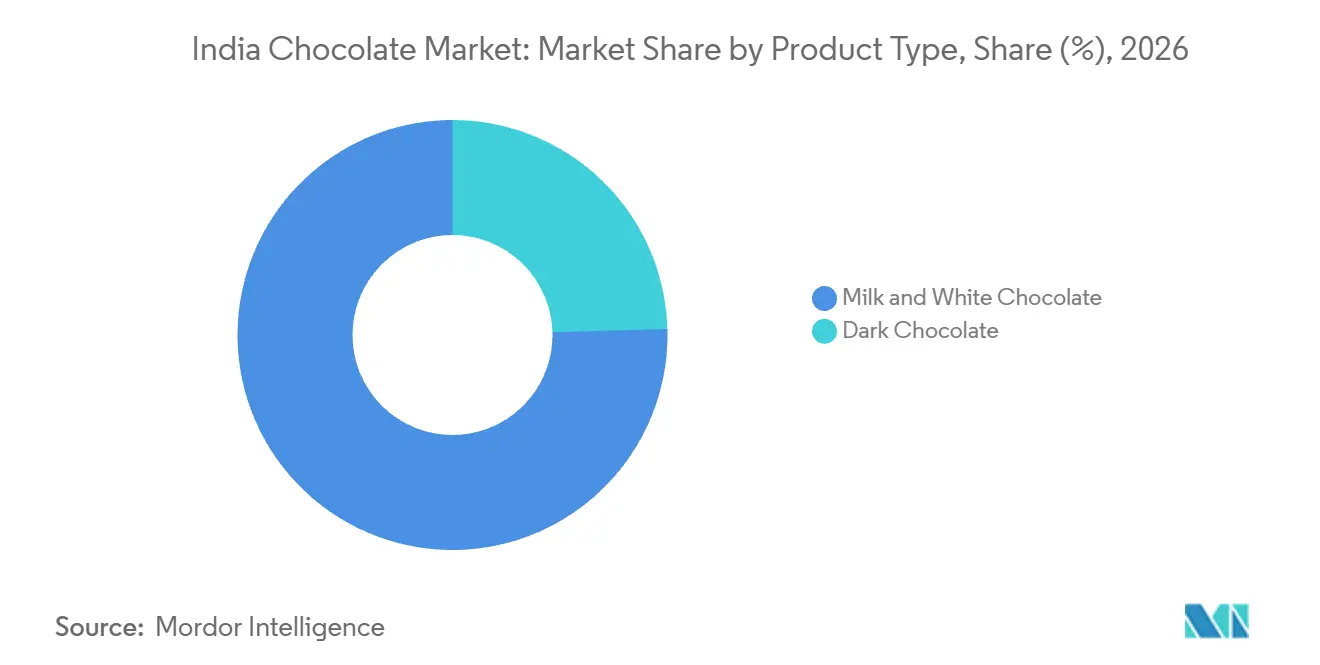
- By product type, milk and white chocolate led with a 75.45% India chocolate market share in 2026, while dark chocolate is forecast to grow fastest at a CAGR of 7.78% over 2027-2032.
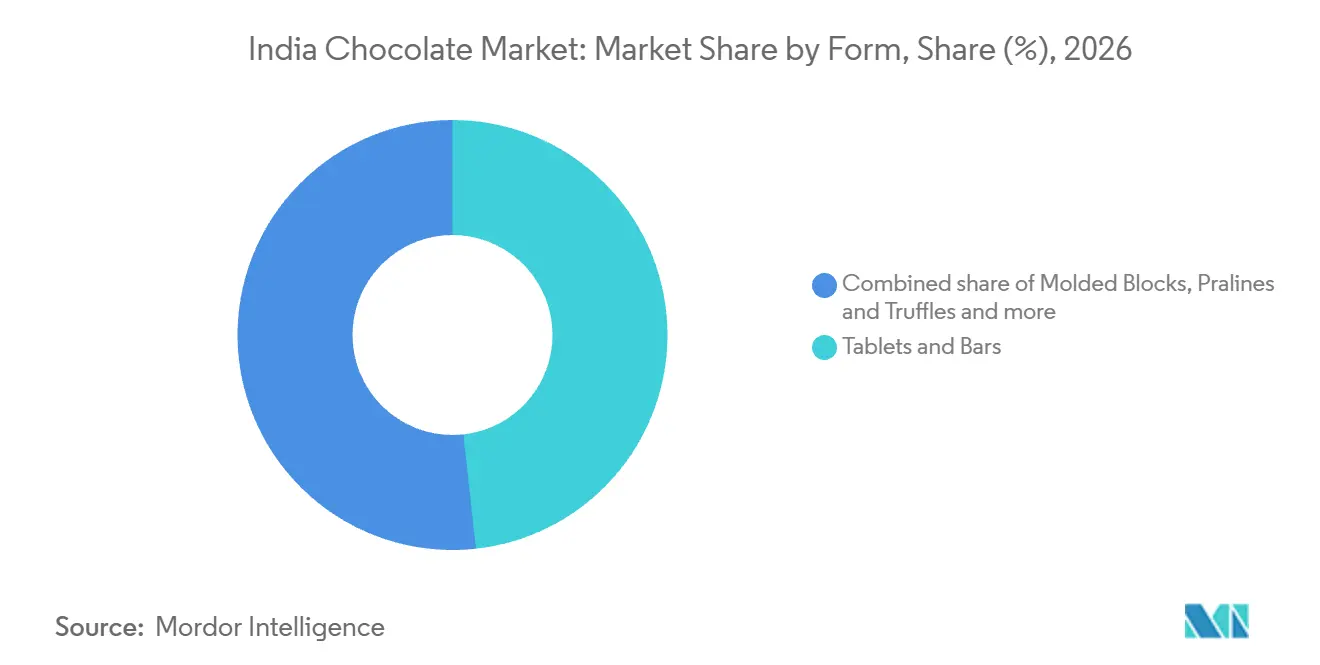
- The form breakdown was led by tablets and bars with 48.26% of chocolate retail sales value in 2026, with pralines and truffles forecast to grow fastest at a CAGR of 7.58% over 2027-2032.
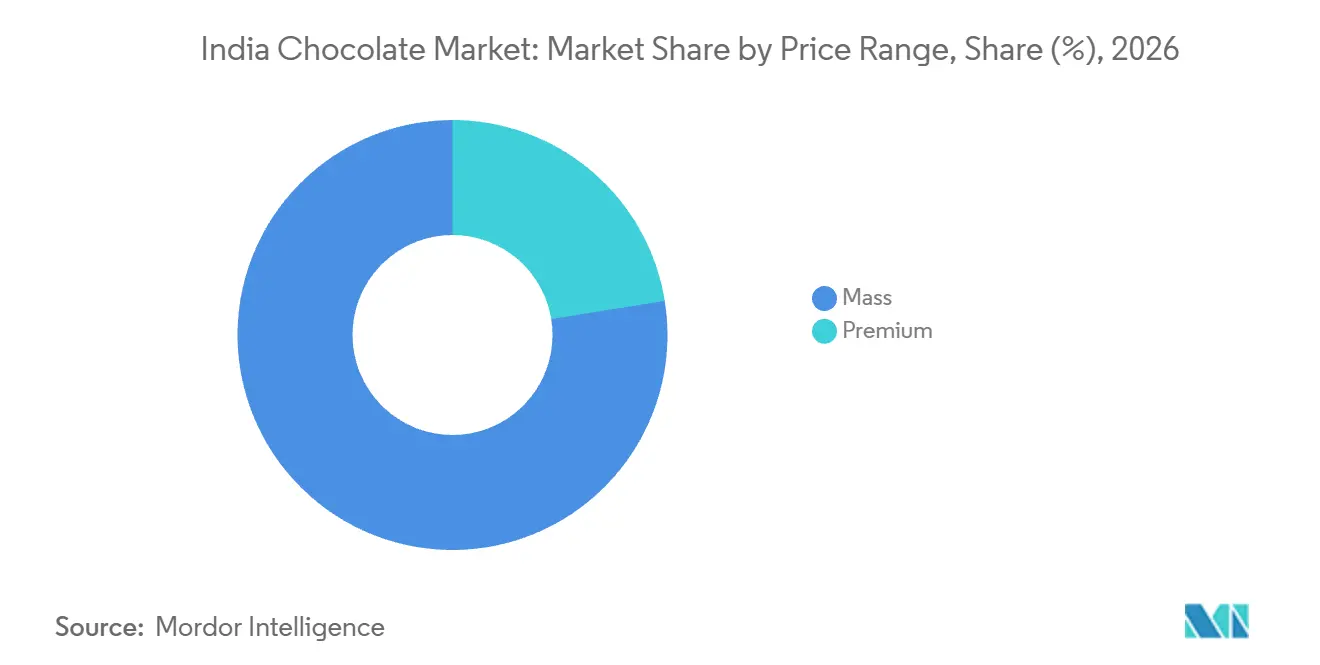
- Across price ranges, mass chocolate held a 77.54% share of the India chocolate market size in 2026, and premium chocolate is forecast to grow fastest at a CAGR of 7.83% over 2027-2032.
- Dairy-based chocolate led the ingredient-type category with 82.07% of chocolate retail sales value in 2026, whereas plant-based chocolate is forecast to grow fastest at a CAGR of 8.22% over 2027-2032.
- By distribution channel, convenience stores led with 68.98% of chocolate retail sales value in 2026, and online retail stores are forecast to grow fastest at a CAGR of 8.85% over 2027-2032.
- Geographically, Northern and Western regions account for the largest share of chocolate consumption in India, while Eastern India is smaller but steadily growing.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Chocolate Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Health and wellness trends | +2% | Nationwide | Medium term (2-4 years) |
| Strong gifting culture during festivals and occasions | +3.1% | Nationwide | Short term (≤ 2 years) |
| Product innovation and flavor experimentation | +2.3% | Nationwide | Medium term (2-4 years) |
| Sustainability and ethical sourcing narratives | +1.7% | Nationwide | Long term (≥ 4 years) |
| Strong brand marketing and emotional positioning | +1.1% | Nationwide | Short term (≤ 2 years) |
| Premiumization and indulgence seeking | +1.4% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Health and wellness trends
Health-conscious preferences create room for craft chocolate designed around buyers' priorities for ingredients, cocoa content and sugar content. In May 2025, The Economic Times described Indian craft-chocolate buyers as seeking high-cocoa chocolate, clean labels and low-sugar options. Recipe composition and clear ingredient information can connect those preferences with a chocolate choice for craft buyers limiting sugar intake. The same article contrasted mass-market chocolate at 50% to 60% sugar with craft bars that usually contain 20% to 30%. To match the craft bars' usual sugar level, the compared mass-market recipes would need reformulation, making a lower-sugar offer a product-development commitment for established brands.
Strong gifting culture during festivals and occasions
Gifting occasions can expand chocolate demand beyond individual consumption by giving buyers a specific recipient and a deadline for purchase. Amazon India reported over 1.3 times year-over-year growth in luxury chocolates and curated hampers on Amazon.in around Valentine's Day 2026.[1] Amazon India's broader gifting category recorded 1.2 times year-over-year growth for the same occasion. The contrast suggests that occasion demand can reward a premium gift proposition, making recipient suitability a relevant commercial choice for chocolate sellers. For sellers, premium chocolates and curated hampers outpacing gifting overall points to curated gift assortments as the stronger offer within the occasion.
Product innovation and flavor experimentation
Flavor experimentation can give chocolate buyers a new reason to try a familiar format without changing the underlying purchase occasion. ITC Limited's Fabelle Exquisite Chocolates launched a 3-variant Kunafa chocolate collection in India in 2025. The variants were milk pistachio kunafa, pistachio dark kunafa and pecan dark kunafa, with both dark recipes at 64% cocoa. The pecan variant was described as introducing pecans to India's kunafa chocolate trend, while crispy kunafa strands and nut ingredients added texture. Combining a dessert filling with different cocoa recipes gives the collection several ways to attract a trial purchase.
Sustainability and ethical sourcing narratives
Ethical sourcing can differentiate chocolate for buyers who value how it is produced. In May 2025, The Economic Times reported that Pascati targeted shoppers in Mumbai, Delhi and Chennai who were willing to pay more for organic, fair-trade and vegan chocolate bars. ITC's chocolate business head also reported growing consumer curiosity about cocoa origins and craft in February 2026. Cocoa Life, Mondelēz International's sustainability program, reported reaching approximately 21,400 farmers and approximately 110 communities in India by the end of 2025, using third-party data. A sourcing program provides farming context, while the willingness to pay creates a commercial reason to explain ethical product attributes. For suppliers selling to those metro buyers, documenting the sourcing behind each bar would turn broad ethical positioning into a product-specific reason to pay more.
Restraints Impact Analysis of India Chocolate Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High temperature sensitivity and climate challenges | -1.5% | Nationwide | Short term (≤ 2 years) |
| Cold chain infrastructure gaps | -1.3% | Nationwide | Short term (≤ 2 years) |
| Health concerns over high sugar and fat content | -0.7% | Schools across Maharashtra | Short term (≤ 2 years) |
| Heavy import dependency for cocoa | -0.8% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High temperature sensitivity and climate challenges
Heat sensitivity can separate an accepted chocolate order from a dependable delivery date, particularly when intact presentation matters to the purchase. Cocoacraft, an artisan single-origin chocolate seller from Kerala, says summer heat may prevent its chocolates from arriving intact. Its policy describes freezing chocolate before dispatch and using temperature-controlled boxes, yet it offers to hold an order until cooler weather. For orders handled under this policy, protective packaging does not remove the tradeoff between prompt shipment and confidence in product condition. A hold lasts until the weather cools, so a summer order may arrive well after the date the buyer wanted, which matters most for gifts bought for a fixed occasion.
Cold chain infrastructure gaps
Delivery-center coverage changes the cost and timing of supplying chocolate beyond a seller's local logistics network. Soothys charges more for thermal packaging outside its delivery-center locations. In areas without its delivery centers, delivery usually takes 2 to 3 days and may take longer depending on its delivery partner's capabilities. Savorworks Artisans prefers shipping Monday through Thursday to avoid weekend transit and warns that summer heat can melt orders despite gel packs. It also advises delivery where recipients can promptly place chocolate in appropriate temperature storage. For buyers using these services, a wider delivery reach comes with packaging charges or restricted dispatch windows, weakening the convenience of ordering chocolate for a fixed date.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Chocolate Market Segment Analysis
By Product Type:
Formulation Choices Expand Dark Chocolate's RoleMilk and white chocolate accounted for a 75.45% share of the India chocolate market size in 2026, making it the largest segment. In July 2026, Mondelēz India launched CÔTE D'OR with dark and milk chocolate variants and said the range would be available through leading quick-commerce platforms. The milk variants illustrate product renewal within the leading category, without requiring buyers to choose a different chocolate type. For a milk-chocolate supplier, a distinct branded range offers a way to compete for buyers who retain that recipe preference. The commercial test is whether the additional range earns a separate purchase occasion instead of merely dividing existing milk-chocolate purchases among more labels.
Dark chocolate is forecast to be the fastest-growing segment at a CAGR of 7.78% over 2027-2032. In July 2026, the Gujarat Co-operative Milk Marketing Federation said Amul's sugar-free dark chocolate contributed nearly 10% of Amul's total chocolate sales. That company-specific result shows how a defined formulation can earn a place within an established chocolate portfolio. For producers considering this category, a sugar-free dark recipe can address buyers seeking that particular combination of attributes. Amul was also described as India's dark-chocolate leader in July 2026, making sugar-free recipes a field where specialists would compete with an established incumbent.

By Form:
Tablets and Bars Lead While Praline Retail ExpandsTablets and bars represented a 48.26% India chocolate market share in 2026, making them the largest segment. A tablet or bar can place one recipe at the center of a tasting or sharing occasion. Buyers can compare cocoa intensity and texture within that recipe rather than choose among separately filled pralines. For a producer, this concentrates the product decision on the chocolate itself, making recipe development more consequential than the breadth of an assortment.
Pralines and truffles are forecast to be the fastest-growing segment at a CAGR of 7.58% over 2027-2032. Neuhaus opened its first Indian boutique at Navi Mumbai International Airport in 2026, extending retail access to the praline maker's Belgian-made chocolates. That expansion gives a specialist producer a direct consumer-facing setting in India, linking the format with an identifiable seller. For buyers selecting a chocolate collection, the proposition can center on the composition and presentation of the assortment. Neuhaus later reported that its first 2 boutiques in Mumbai had opened.
By Price Range:
Pack Size and Premium Distinction Shape DemandMass chocolate was the largest segment, accounting for 77.54% of chocolate retail sales value in 2026. In FY25, Indian chocolate buyers downgraded to smaller packs following cocoa-driven price increases in 2024 and early 2025, according to industry commentary reported by The Economic Times. That behavior makes the amount paid for each purchase relevant to a mass-price proposition, alongside the quantity of chocolate offered. A producer can use portion size to create a lower price per purchase while preserving the underlying chocolate recipe. Since the downgrade followed cocoa-driven price increases, a mass seller's choice of pack weight is tied to cocoa costs as much as to buyer preference.
Premium chocolate is forecast to be the fastest-growing segment at a CAGR of 7.83% over 2027-2032. In July 2026, ITC's Fabelle business head said India's luxury chocolate subset was growing nearly twice as fast as the broader chocolate market. This higher-end example places a distinct chocolate proposition at the center of the commercial offer, with luxury representing a specific part of the premium tier. With luxury growing nearly twice as fast as the broader market, a distinct origin, recipe or gift format gives premium producers more to build on than a higher-priced standard bar.
By Ingredient Type:
Recipe Identity Shapes Dairy and Plant-Based OffersDairy-based chocolate was the largest segment, holding 82.07% of chocolate retail sales value in 2026. Mondelēz India introduced Cadbury Dairy Milk MILKINIS, a chocolate product with a milk-crème-filled center, on September 15, 2025. The filled center gives the dairy formulation a role in both the chocolate and the filling.
Plant-based chocolate is forecast to be the fastest-growing segment at a CAGR of 8.22% over 2027-2032. Manam Chocolate's Diwali Edition 2025 introduced zero-sugar dark chocolate and dairy-free options made with oat milk and jaggery. For a gift buyer selecting for a dairy-free recipient, that seasonal offer brings an ingredient requirement into the festive assortment. Producers can use this approach to include those recipients in occasion gifting, giving the formulation a commercial purpose beyond everyday consumption. Single-origin chocolate offers a separate provenance proposition, illustrated by Manam Chocolate's June 25, 2025 Delhi launch featuring West Godavari chocolate in retail, pastry and beverage uses.
By Distribution Channel:
Store Access Meets Occasion-Based Online DemandConvenience stores were the largest segment, accounting for 68.98% of chocolate retail sales value in 2026. For a neighborhood shopper adding chocolate to a routine visit, the channel offers a purchase without a separate trip to a specialist outlet. That makes a readily selectable small pack more relevant than a long consultation about recipes or origins. A supplier serving this setting has to make the product and price understandable at the point of selection.
Online retail stores are forecast to be the fastest-growing segment at a CAGR of 8.85% over 2027-2032. Amazon Now said chocolate gifts were its fastest-growing category during Raksha Bandhan 2026, up 2.5 times compared with business as usual. That platform-specific result puts an online channel in the path of an occasion-led chocolate purchase, connecting digital access with a defined buying window. Retailers can build an online offer around a gift selection and its delivery service as parts of the same proposition.
Geography Analysis
Northern and Western regions Chocolate Market
Northern and Western regions account for the largest share of consumption in the India chocolate market. Lindt & Sprüngli opened its first branded retail store in India at Worldmark, Aerocity, New Delhi, on September 4, 2026. That opening placed an international chocolate maker's own retail format in Delhi-NCR, a consumption center within the leading Northern and Western regions. For a brand entering through a boutique, the commercial unit is a dedicated setting in which consumers can choose finished chocolate, giving the producer control of the offer's presentation.
Eastern India Chocolate Market
Eastern India represents a smaller but steadily growing chocolate market, offering a setting in which local retail access can matter to an occasion purchase. During Valentine's Week in February 2026, Kolkata's small pan-cigarette and stationery shops saw brisk chocolate sales. Those outlets place finished chocolate in an everyday local shopping setting, allowing a producer to serve a gifting occasion through retailers whose main identity is broader than chocolate. This makes occasion-specific selling through a neighborhood outlet a distinct regional route to demand, giving producers an alternative to dedicated chocolate retail.
Southern India and Mumbai illustrate differences between regional order concentration, production coverage and retail entry. In October 2025, nearly half of D2C orders for Kunafa, a Middle Eastern dessert marketed online as Dubai chocolate, came from Kerala, according to GoKwik. By March 2026, Manam Chocolate had entered Mumbai retail with a dedicated Galeries Lafayette destination for Indian craft chocolate. In February 2026, Bengaluru-based SMOOR said its Karnataka plant handled most of its chocolate and dessert production for Karnataka and Chennai. SMOOR's plant links production for Karnataka and Chennai, while Kerala's D2C orders and Manam's Mumbai retail entry show distinct routes to regional buyers.
Regulatory Framework and Outlook
This comparison of selected jurisdictions examines national food rules and Maharashtra's implementation for manufacturers selling finished chocolate through general retail. The Food Safety and Standards Authority of India (FSSAI) sets national chocolate standards, while Maharashtra's Food and Drug Administration implements national food-safety law in the state. Qualifying producers, importers and brand owners also face national plastic-packaging information duties, including notice to the Central Pollution Control Board (CPCB), alongside Maharashtra's packaging conditions.
Regulatory Table of India Chocolate Market
| Decision factor | India | Maharashtra |
|---|---|---|
| Primary authority | FSSAI for food standards; CPCB for packaging-information notices | Food and Drug Administration for food; Maharashtra's pollution-control authority (MPCB) for plastics |
| Key instruments or direction | Food Products Standards and Food Additives Regulations, regulation 2.7.4; plastic-waste information amendment effective July 2025; August 2026 school-food proposal | National food-safety framework; plastic-packaging information duties; 2022 state plastic amendment |
| Commercial effect | Qualifying producers, importers and brand owners provide specified information by barcode/QR, brochure or a legally issued unique number and notify CPCB | Meet food-law duties and applicable national packaging-information duties; follow the state thickness condition or its functionality exception |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
India's Medium rating reflects product standards and packaging-information duties, while FSSAI's August 2026 school-food proposal would classify solid foods with more than 3 grams of added sugar per 100 grams as high in sugar. Maharashtra's plastic packaging must exceed 50 microns, except when that thickness impairs the product's functionality.[3] On July 28, 2026, Maharashtra's Food and Drug Administration directed government, aided and private schools to enforce national school-food rules, which prohibit the sale, display and advertisement of foods high in saturated fat, trans-fat, added sugar or sodium on or within 50 meters of school campuses, and its Commissioner said chocolate should not be available at schools or within 50 meters of them. The additional packaging condition supports Maharashtra's Medium rating, while the school-specific scope of both the national proposal and state order supports a No change outlook for general-retail manufacturers in both jurisdictions.
Value Chain Stages
The comparison follows cocoa sourcing and processing, finished-chocolate manufacture and consumer selling, with supplier earnings shifting from ingredient sales to finished-product sales. In FY2025-26, Lotus Chocolate Company Ltd operated across cocoa sourcing, processing and chocolate manufacture, supplying business customers from local bakeries to multinational companies. Campco Chocolates is produced at The CAMPCO Ltd.'s Puttur factory in Karnataka, which also makes semi-finished cocoa products. Their integrated operations connect cocoa processing with finished chocolate, creating opportunities to earn from both ingredient and finished-product sales.
Value Chain Analysis Table of India Chocolate Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Cocoa sourcing and processing | Integrated cocoa processors such as Lotus Chocolate Company Ltd | Cocoa ingredient and B2B chocolate sales | Exposure to bean-input costs | Diversify qualified bean sources |
| Finished-chocolate manufacture | Chocolate manufacturers such as Campco Chocolates | Finished-chocolate product sales | Coordination between semi-finished and finished production | Schedule intermediate and finished-product runs together |
| Consumer selling and delivery | Direct chocolate sellers such as Cocoacraft | Consumer chocolate sales | Preserving product condition through delivery | Match delivery service to chocolate-handling needs |
| Source: Mordor Intelligence | ||||
Lotus supplies business customers, while Cocoacraft sells directly to consumers, so the two earn from different kinds of buyers. Cocoacraft pairs its own manufacturing with an online assortment of bars, squares, gift boxes, drinks and spreads, delivered across India. A manufacturer combining these roles can retain the retail selling relationship, but must also carry the work of fulfilling individual consumer orders.
Competitive Landscape
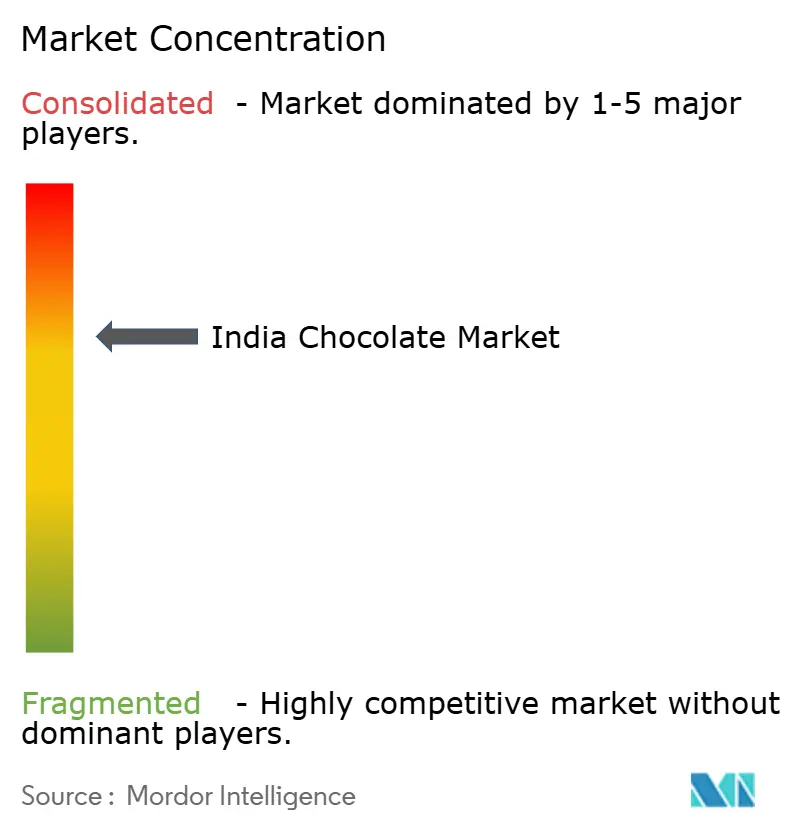
Competition has a concentrated multinational core alongside domestic chocolate producers, combining established industrial operations with focused specialist offers. The major players include Nestlé S.A., Ferrero International S.A., Mars, Incorporated, The Hershey Company and Mondelēz International, Inc. Mondelēz's investor presentation, citing Nielsen 2025 data, reported a share of more than 64% of India's chocolate category. Ferrero's broader India operation combines Baramati production with distribution across major cities, while Mondelēz India manufactures and sells chocolate within a broader manufacturing network. With one company reporting more than 64% of the category, challengers must win buyers through narrower positions rather than breadth.
On June 18, 2026, Mondelēz India launched limited-edition Cadbury Dairy Milk Silk Dubai Chocolate, available then for a limited period through quick-commerce platforms and select retail outlets nationwide. On March 19, 2026, Nestlé India reported adding a Munch wafer-chocolate production line at Sanand, Gujarat, with roughly 8,300 tons of annual capacity. In FY25, company-wide India results included a 2% sales decline for Mondelēz, flat growth for Hershey and 2% revenue growth for Mars International. Nestlé's added line gives it more annual production capacity, while Mondelēz's limited-period range has to convert a temporary availability window into purchases.
On October 8, 2026, ITC Limited unveiled Fabelle's Nav-Ras Collection of 9 handcrafted pralines at ITC Grand Central in Mumbai and said it would be available at select Fabelle boutiques and online. That defined assortment lets ITC present its luxury Fabelle brand around a collection, making the choice of pieces part of its consumer proposition. India's standard for couverture requires at least 35% total cocoa solids on a dry matter basis, including at least 31% cocoa butter and 2.5% fat-free cocoa solids. The standard sets a floor on composition and says nothing about assortment, so ITC's collection-led positioning competes on a dimension the couverture rule leaves open.
India Chocolate Industry Leaders
-
Nestlé S.A.
-
Ferrero International S.A.
-
Mars, Incorporated
-
The Hershey Company
-
Mondelēz International, Inc.
- *Disclaimer: Major Players sorted in no particular order
India Chocolate Market Companies Covered in this Report
- Mondelēz International, Inc.
- Nestlé S.A.
- Ferrero International S.A.
- Mars, Incorporated
- ITC Limited
- The Hershey Company
- Gujarat Co-operative Milk Marketing Federation (Amul)
- DS Group (Läderach)
- Reliance Consumer Products Ltd
- Surya Food & Agro Ltd (Priyagold)
- Lotus Chocolate Company Ltd
- Campco Chocolates
- Paul & Mike Craft Chocolates
- Soklet
- Pascati
- Rage Chocolate
- Choko La
- Wellversed Health Private Limited (Ketofy Keto Chocolate)
- Bean Therapy
- SMOOR Chocolates
Recent Industry Developments in India Chocolate Market
- Oct 2026: ITC Limited unveiled Fabelle's Nav-Ras Collection of 9 handcrafted pralines at ITC Grand Central in Mumbai on October 8 and said it would be available at select Fabelle boutiques and online.
- Sep 2026: Lindt & Sprüngli opened its first branded retail store in India at Worldmark, Aerocity, New Delhi, on September 4.
- Jul 2026: Mondelēz India launched CÔTE D’OR dark and milk chocolate in India and said the range would be available through leading quick-commerce platforms.
Scope and Methodology
By Product Type
| Dark Chocolate |
| Milk and White Chocolate |
By Form
| Tablets and Bars |
| Molded Blocks |
| Pralines and Truffles |
| Other Forms |
By Price Range
| Mass |
| Premium |
By Ingredient Type
| Dairy-based |
| Plant-based |
| Single Origin |
By Distribution Channel
| Supermarkets/Hypermarkets |
| Online Retail Stores |
| Convenience Stores |
| Other Distribution Channels |
| By Product Type | Dark Chocolate |
| Milk and White Chocolate | |
| By Form | Tablets and Bars |
| Molded Blocks | |
| Pralines and Truffles | |
| Other Forms | |
| By Price Range | Mass |
| Premium | |
| By Ingredient Type | Dairy-based |
| Plant-based | |
| Single Origin | |
| By Distribution Channel | Supermarkets/Hypermarkets |
| Online Retail Stores | |
| Convenience Stores | |
| Other Distribution Channels |
Market Definition
- Milk and White Chocolate - Milk chocolates is a solid chocolate made with milk (in the form of either milk powder, liquid milk, or condensed milk) and cocoa solids. White chocolate is made from cocoa butter and milk and contains no cocoa solids whatsoever. The scope includes regular chocolates, low-sugar, and sugar-free variants
- Toffees & Nougats - Toffees include hard, chewy, and small or one-bite candies marketed with labels as toffee or toffee-like confectionery. Nougat is a chewy confection with almond, sugar, and egg white as a basic ingredient; and it originated in Europe and Middle East countries.
- Cereals Bars - A snack composed of breakfast cereal that has been compressed into a bar shape and is held together with a form of edible adhesive. The scope includes snack bars made with cereals such as rice, oats, corn, etc. mixed with a binding syrup. These also include products labeled as cereal bars, cereal treat bars, or grain bars.
- Chewing Gum - This is a preparation for chewing, usually made of flavored and sweetened chicle or such substitutes as polyvinyl acetate. The types of chewing gums included in the scope are sugar-chewing gums and sugar-free chewing gums
| Keyword | Definition |
|---|---|
| Dark Chocolate | Dark chocolate is a form of chocolate containing cocoa solids and cocoa butter without the milk. |
| White Chocolate | White chocolate is the type of chocolate containing the highest percentage of milk solids, typically around or over 30 percent. |
| Milk Chocolate | Milk chocolate is made from dark chocolate that has a low cocoa solid content and higher sugar content, plus a milk product. |
| Hard Candy | A candy made of sugar and corn syrup boiled without crystallizing. |
| Toffees | A hard, chewy, often brown sweet that is made from sugar boiled with butter. |
| Nougats | A chewy or brittle candy containing almonds or other nuts and sometimes fruit. |
| Cereal bar | A cereal bar is a bar-shaped food product, made by pressing cereals and usually dried fruit or berries, which are in most cases held together by glucose syrup. |
| Protein bar | Protein bars are nutrition bars that contain a high proportion of protein to carbohydrates/fats. |
| Fruit & Nut bar | These are often based on dates with other dried fruit and nut additions and, in some cases, flavorings. |
| NCA | The National Confectioners Association is an American trade organization that promotes chocolate, candy, gum and mints, and the companies that make these treats. |
| CGMP | Current good manufacturing practices are those conforming to the guidelines recommended by relevant agencies. |
| Unstandardized foods | Unstandardized foods are those that do not have a standard of identity or that deviate from a prescribed standard in any manner. |
| GI | The glycemic index (GI) is a way of ranking carbohydrate-containing foods based on how slowly or quickly they are digested and increase blood glucose levels over a period of time |
| Skimmed milk powder | Skimmed milk powder is obtained by removing water from pasteurized skim milk by spray-drying. |
| Flavanols | Flavanols are a group of compounds found in cocoa, tea, apples, and many other plant-based foods and beverages. |
| WPC | Whey protein concentrate- the substance obtained by the removal of sufficient nonprotein constituents from pasteurized whey so that the finished dry product contains greater than 25% protein. |
| LDL | Low density Lipoprotein- the bad cholesterol |
| HDL | High density Lipoprotein- the good cholesterol |
| BHT | butylated Hydroxytoluene is a lab-made chemical that is added to foods as a preservative. |
| Carrageenan | Carrageenan is an additive used to thicken, emulsify, and preserve foods and drinks. |
| Free form | Not containing certain ingredients, such as gluten, dairy, or sugar. |
| Cocoa butter | It is a fatty substance obtained from cocoa beans, used in the manufacture of confectionery. |
| Pastellies | A type of of Brazilian candy made from sugar, eggs, and milk. |
| Draggees | Small, round candies that are coated with a hard sugar shell |
| CHOPRABISCO | Royal Belgian Association of the chocolate, pralines, biscuit, and confectionery industry- A trade association that represents the Belgian chocolate industry. |
| European Directive 2000/13 | A European Union directive that regulates the labeling of food products |
| Kakao-Verordnung | The German chocolate ordinance, a set of regulations that define what can be labeled as "chocolate" in Germany. |
| FASFC | Federal Agency for the Safety of the Food Chain |
| Pectin | A natural substance that is derived from fruits and vegetables. It is used in confectionery to create a gel-like texture. |
| Invert sugars | A type of sugar that is made up of glucose and fructose. |
| Emulsifier | A substance that helps to mix to liquids that does not mix together. |
| Anthocyanins | A type of flavonoid that is responsible for the red, purple, and blue colors of confectionery. |
| Functional Foods | Foods that have been modified to provide additional health benefits beyond basic nutrition. |
| Kosher certificate | This certification verifies that the ingredients, production process including all machinery, and/or food-service process complies with the standards of Jewish dietary law |
| Chicory root extract | A natural extract from the chicory root that is a good source of fiber, calcium, phosphorous, and folate |
| RDD | Recommended daily dose |
| Gummies | A chewy gelatin-based candy that is often flavored with fruit. |
| Nutraceuticals | Food or dietary supplements that are claimed to have health benefits. |
| Energy bars | Snack bars that are high in carbohydrates and calories are designed to provide energy on the go. |
| BFSO | Belgian Food Safety Organization for the food chain. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step 1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set, and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period for each country.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


