
India Baby Care Products Market Analysis by Mordor Intelligence
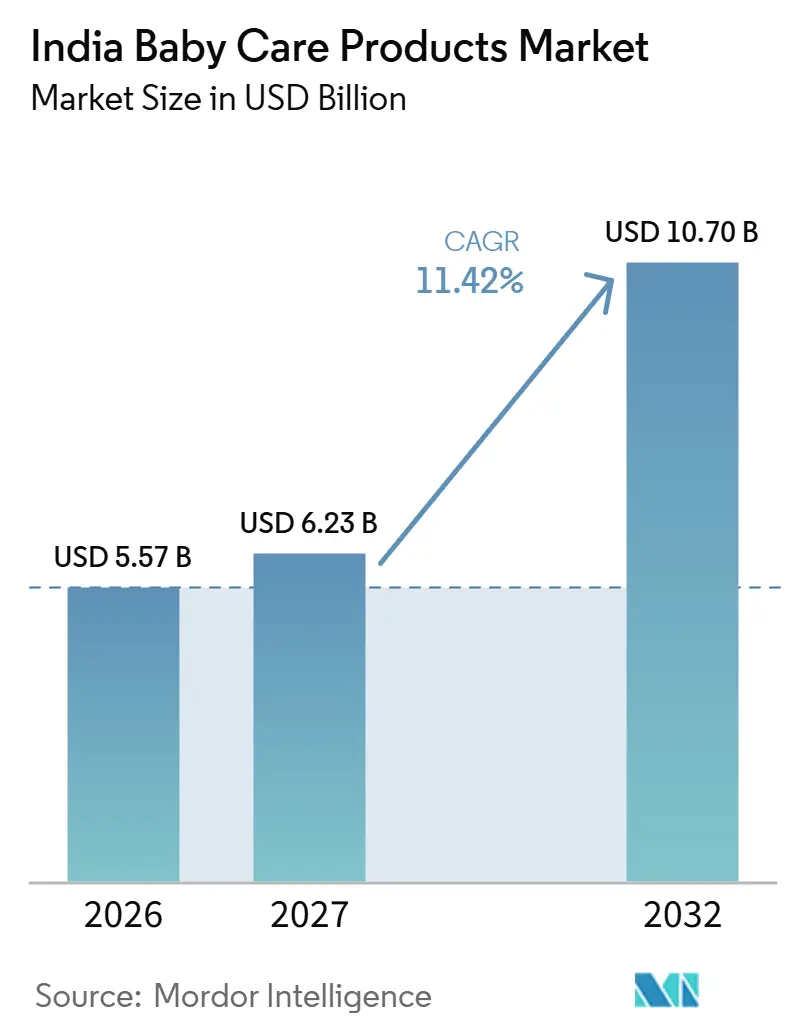
The India baby care products market size is expected to increase from USD 5.57 billion in 2026 to USD 6.23 billion in 2027 and reach USD 10.7 billion by 2032, growing at a CAGR of 11.42% over 2027-2032.
In India, caregiver learning and clinically grounded uses for emollient skin care can broaden the reasons to choose dedicated care products. Natural positioning can strengthen caregiver trust when the ingredient identity gives the care promise a recognizable basis. Competitive responses combine formulation changes with broader retail access, making product differentiation and reach complementary. Suppliers can extend a trusted care proposition across channels, but mandatory diaper certification and novel-ingredient cosmetic permissions make product-specific compliance a condition of that expansion.
Key Report Takeaways
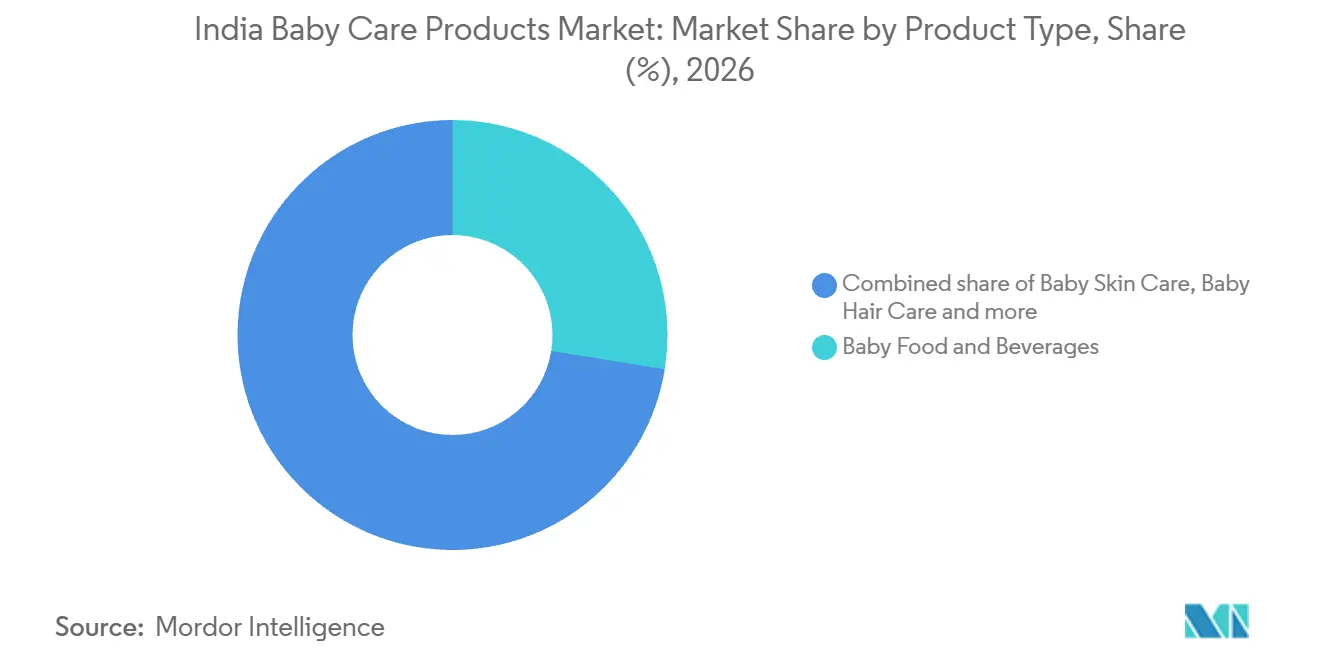
- By product type, baby food and beverages held a 27.55% India baby care products market share in 2026, while baby skin care is the fastest-growing segment at a 12.29% CAGR over 2027-2032.
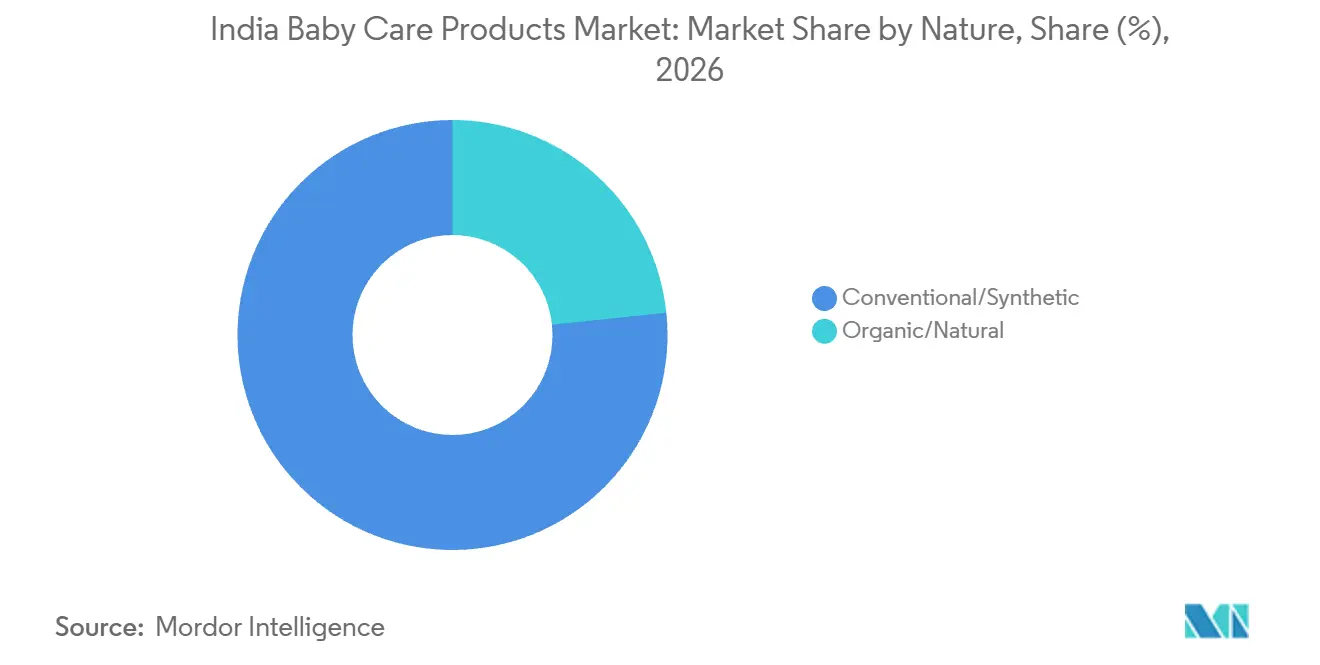
- In the nature breakdown, conventional/synthetic products accounted for a 76.65% share of the India baby care products market size in 2026, and organic/natural products are forecast to grow fastest at a 13.55% CAGR over 2027-2032.
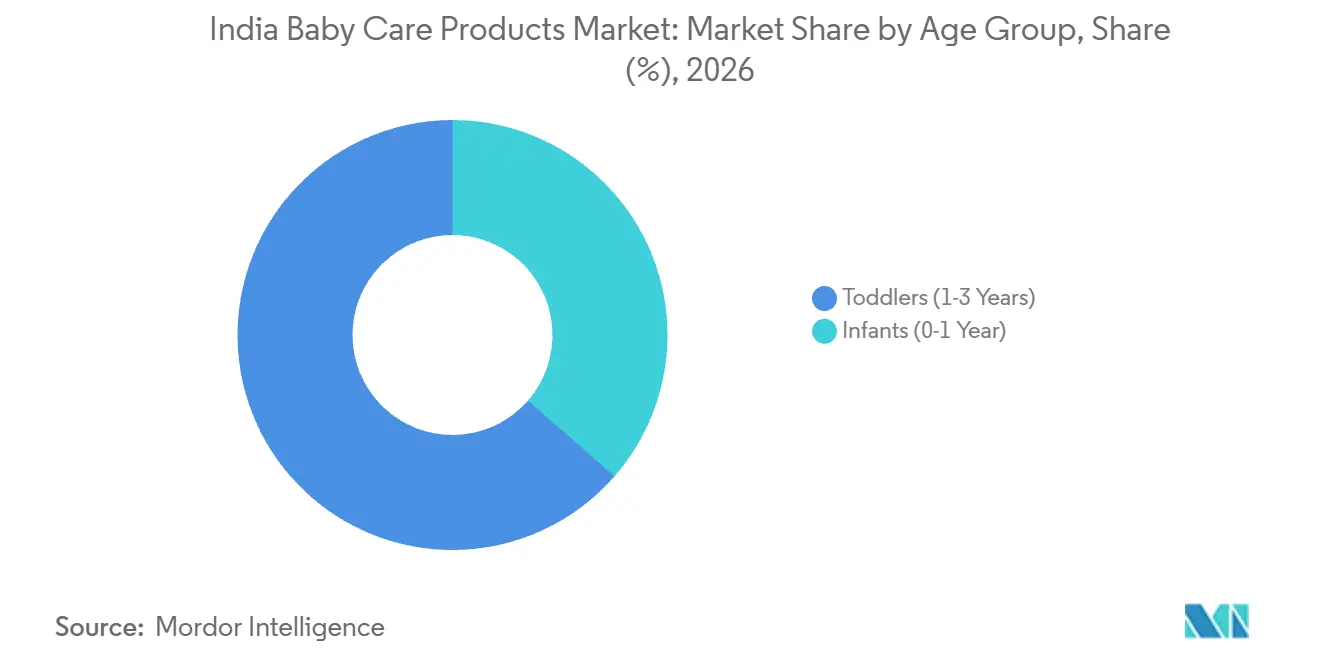
- Toddlers aged 1 to 3 years led the age-group category with 63.6% of retail value in 2026, while infants aged 0 to 1 year are forecast to grow fastest at a 12.35% CAGR over 2027-2032.
- By distribution channel, supermarkets and hypermarkets held 36.19% of retail value in 2026, with online retail stores forecast to be the fastest-growing segment at a 12.25% CAGR over 2027-2032.
- Across geographies, Tier-2 and Tier-3 cities are the fastest-growing baby-care markets.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Baby Care Products Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing awareness of infant health and hygiene | +3.8% | Himachal Pradesh newborn-care facilities | Medium term (2-4 years) |
| Shift toward organic and chemical-free products | +3.3% | Nationwide | Medium term (2-4 years) |
| Increasing awareness about product safety and certifications | +2.9% | Nationwide | Short term (≤ 2 years) |
| Technological advancements in baby care products | +2.5% | Nationwide | Long term (≥ 4 years) |
| Innovations in product offerings | +1.8% | Nationwide | Short term (≤ 2 years) |
| Rising availability of international and premium brands | +1.4% | Delhi NCR retail catchments | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing awareness of infant health and hygiene
Caregiver education can support demand for purposeful newborn-care products by making the reasoning behind daily care decisions easier to understand. The National Health Mission reported a 37% improvement in newborn-care knowledge among caregivers in special newborn care units assessed at 5 Himachal Pradesh facilities from December 2022 to March 2025.[1] The state's Care Companion Programme trained 186,878 beneficiaries and caregivers through 10,846 sessions over the same period. Learning and program reach address different parts of the demand mechanism, connecting care knowledge with a population able to apply it. The commercial relevance lies with products that match the newborn-care tasks caregivers are taught.
Shift toward organic and chemical-free products
Ingredient origin can influence baby-care choices when a caregiver associates natural formulations with gentleness. One participant in a qualitative study of 25 Indian mothers said she preferred natural ingredients because she trusted them to be gentle and safe. The mothers were primary purchasing decision makers screened for natural baby-care brand use within the 6 months before interview. This preference gives suppliers a reason to explain the ingredient choices behind a care product, so that a natural claim names the ingredients behind it. Confidence in a specific ingredient promise can support continued selection within natural care, giving formulation credibility a direct commercial role.
Increasing awareness about product safety and certifications
Product-specific certification can make safety a verifiable part of a baby-care proposition, giving caregivers a screening tool beyond an ingredient promise. India's Medical Textiles (Quality Control) Order, 2024 requires disposable baby diapers to meet IS 17509:2021 and bear the BIS Standard Mark under a BIS license. The Ministry of Textiles order names the Bureau of Indian Standards (BIS) and the Textiles Committee as certifying and enforcing authorities. India's Department of Consumer Affairs runs nationwide Jago Grahak Jago campaigns covering product quality and safety, including BIS certification and ISI marking. For caregivers applying these checks to diapers, readily verifiable conformity can favor a compliant brand at purchase.
Technological advancements in baby care products
Diaper material redesign can create a product choice around resource use while retaining a familiar baby-care format. In April 2025, Swara Baby Products Limited (formerly Swara Baby Products Private Limited) introduced a diaper technology in India that was used in Baby Hug Pro. The company said the design reduced wood-pulp usage from 100% to approximately 7%. The company presented the technology as first of its kind in India, giving the material redesign a specific competitive claim. For diaper makers, material choice becomes a purchase argument alongside the product's care function.
Restraints Impact Analysis of India Baby Care Products Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High price sensitivity and proliferation of counterfeit products | -1.9% | Thiruvallur district, Tamil Nadu | Short term (≤ 2 years) |
| Complex multi-agency regulatory approvals for baby cosmetics | -1.3% | Nationwide | Medium term (2-4 years) |
| Potential health concerns related to chemical residues | -0.6% | Nationwide | Long term (≥ 4 years) |
| Limited awareness in semi-urban/rural areas | -0.5% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High price sensitivity and proliferation of counterfeit products
Sale eligibility sets a precondition for access to baby-care products, because diapers without the required certification mark cannot be stored or offered for sale. BIS seized 286 packages of baby diapers, each containing 42 pieces, without the required BIS Standard Mark at a Flipkart India warehouse in Thiruvallur district, Tamil Nadu, on March 19, 2025. The applicable rule barred storage, sale or offer for sale without the Standard Mark under a valid BIS license. For diaper suppliers, this restriction reaches stock held for distribution as well as the retail offer. Suppliers therefore bear the compliance burden of maintaining licensed, marked diaper stock throughout distribution.
Complex multi-agency regulatory approvals for baby cosmetics
Novel-ingredient baby cosmetics face a sequential entry barrier that makes formulation choices commercially consequential. A new cosmetic contains a novel ingredient unused worldwide or unrecognized for cosmetic use in national and international literature. Applicants must seek prior central permission with safety and effectiveness data, and permission depends on the authority being satisfied about safety and effectiveness. For domestic manufacture, that permission must accompany the subsequent application to the State Licensing Authority.[2] The ingredient choice therefore determines whether a developer must complete this additional permission step before seeking manufacturing authorization. Resolving that route early becomes part of launch preparation, because a product's care proposition cannot remove the work required by the sequential applications.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Baby Care Products Market Segment Analysis
By Product Type:
Feeding Scale and Defined Skin-Care UsesBaby food and beverages accounted for a 27.55% share of the India baby care products market size in 2026. The largest segment addresses feeding across infant and toddler stages, giving suppliers a product proposition organized around the caregiver's feeding decision. For a range of baby foods and beverages, format and intended use can make the offer more specific, allowing a product to be understood as part of a defined feeding task. The commercial unit of competition is consequently the age-specific feeding proposition, even when the supplier sells a broader baby-care range.
Baby skin care is the fastest-growing segment, forecast to expand at a 12.29% CAGR over 2027-2032. An expert-panel recommendation from the Indian Academy of Pediatrics' Neonatology Chapter includes emollient use once babies adapt to transition home after neonatal intensive care. The Skin Allergy Research Society and Society for Eczema Studies guideline for atopic dermatitis in India recommends regular moisturizer use for patients with that condition, with strong, high-certainty support for regular use. These recommendations tie a commercially familiar product format to defined care settings, making the intended use more specific than a general promise of gentleness. For skin-care suppliers, transition-home care calls for emollient guidance, while atopic-dermatitis care calls for instructions that support regular moisturizer use.



By Nature:
Conventional Breadth and Natural Brand DevelopmentConventional/synthetic products represented a 76.65% India baby care products market share in 2026. In July 2026, Swara Baby Products Limited reported annual capacity to produce approximately 2.66 billion baby diapers in India, alongside capacity for adult diapers or period panties, sanitary napkins and panty liners. Capacity on that scale shows the industrial base behind mass-produced disposable baby products. That supply base supports the position of conventional disposable formats within the largest part of retail spending.
Organic/natural products are the fastest-growing segment, with a forecast 13.55% CAGR over 2027-2032. ITC Limited describes Mother Sparsh as a premium Ayurvedic and natural baby-care brand covering personal care, health and hygiene, and expert care. ITC reported that the business recorded growth during FY2025-26, which it attributed to higher brand salience and adoption. Maintaining a recognizable natural brand identity across different care needs can let suppliers broaden the offering while preserving the formulation promise that links the range.

By Age Group:
Toddler Care Breadth and Infant Feeding DecisionsToddlers aged 1 to 3 years were the largest segment, accounting for 63.6% of retail value in 2026. In July 2026, India's Ministry of Women and Child Development said Poshan 2.0 provides a normal child aged 1 to 3 with 400 kcal and 15 to 20 grams of protein through supplementary nutrition. This age-specific provision illustrates a sustained toddler feeding requirement that commercial toddler foods also address, giving suppliers a defined nutritional task alongside personal care. For commercial suppliers, the stage provides a basis for defining food formats and care propositions whose intended use is clear to caregivers. Continuity across the toddler age window gives a range a distinct competitive role, connecting its feeding purpose with the broader care offer as the child advances.
Infants aged 0 to 1 year are the fastest-growing segment, forecast to expand at a 12.35% CAGR over 2027-2032. From January to March 2025, a purposive survey covered 383 first-time mothers with infants aged 0 to 6 months at Sree Balaji Medical College and Hospital in Chennai. In that sample, 31.3% of mothers reported formula feeding. An age-bounded feeding need gives a specialist formula supplier a precise role within the infant-care basket, supporting a focused offer alongside the other care tasks.
By Distribution Channel:
Supermarket Scale and Category-Specific Online ReachSupermarkets and hypermarkets were the largest segment, accounting for 36.19% of retail value in 2026. Their commercial proposition can bring feeding, hygiene and personal-care products into one shopping setting, making a broader infant or toddler care basket easier to assemble. For a supplier, the channel's value depends on how clearly its product sits within the care task addressed by nearby categories and formats. A feeding specialist, for example, can join a combined baby-care purchase through the retailer's assortment without building its own toiletries or skin-care range.
Online retail stores are the fastest-growing segment, with a forecast 12.25% CAGR over 2027-2032. CITTA reported a current 80:20 online-to-offline baby-care sales mix in October 2026, compared with a 30:70 mix for the company overall. Mother Sparsh reported around 85% of sales online and 15% offline, with products available through e-commerce, quick commerce, pharmacy and retail channels in October 2026. The contrast within CITTA's business makes channel investment a category-level decision, so a baby-care supplier can design its digital route around the care range while maintaining a wider offline presence.
Geography Analysis
Tier-2 and Tier-3 cities Baby Care Products Market
Tier-2 and Tier-3 cities form the fastest-growing geography for baby-care products. By February 2025, Baby & Mom Retail had launched on Blinkit and Zepto, with products available in Indore and a company range spanning baby care, skincare and hygiene. This expansion route uses quick-commerce platforms, making digital access relevant to smaller-city growth alongside store-based distribution. For a multi-category supplier, baby care can share that route with adjacent personal-care products, allowing reach to expand without a separate retail format for each care task.
Rural, tribal and remote communities have a different information pathway, making community healthcare relevant to how infant skin-care choices are explained. Anganwadi centers are major healthcare-delivery sources in these communities, and their workers are crucial, sometimes sole, sources of neonatal and infant skin-care guidance. That role creates a distinction between reaching a household with products and helping a caregiver understand a care recommendation, which can affect the usefulness of a supplier's message. Community guidance can complement product-use information for rural-facing skin-care suppliers, helping caregivers connect an available product with a defined care task while retaining their role in product selection.
In hot and humid parts of the country, a condition-specific approach to skin care can make product guidance more useful. In a 2025 Indian atopic-dermatitis consensus, some panel members cautioned that coconut oil may predispose patients to miliaria in hot and humid parts of the country. An oil-based proposition can therefore need different use guidance across locations, even when its ingredient identity is unchanged. Suppliers can make that guidance specific to the intended patient and use conditions when serving caregivers managing atopic dermatitis in hot and humid areas. Local explanation then becomes part of the product proposition, tying a formulation choice to a defined care situation before it becomes a routine purchase.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions, India and Maharashtra, from the perspective of compliant suppliers of baby cosmetics. The national framework assigns cosmetic import registration to the Central Licensing Authority and domestic manufacturing licensing and inspection to state authorities. This division makes product compliance and the chosen supply route separate commercial decisions, because an importer and a domestic manufacturer engage different licensing processes.
Regulatory Table of India Baby Care Products Market
| Decision factor | India | Maharashtra |
|---|---|---|
| Primary authority | Drugs Controller General (India), acting as Central Licensing Authority | Maharashtra Food and Drug Administration |
| Key instruments or direction | Cosmetics Rules, 2020, import registration and applicable product standards | Cosmetics manufacturing licensing and inspection under the national framework |
| Commercial effect | Registration before import and compliance with applicable quality and safety standards | Manufacturing authorization and state enforcement exposure |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
India's Medium rating reflects defined entry routes alongside continuing registration and product-compliance duties. Maharashtra's Medium rating reflects licensing-backed enforcement, exemplified when its FDA sealed Sigma Lifestyle Private Limited's unlicensed Bhiwandi factory, whose seized products included baby lotions and washes, on June 18, 2026. The cosmetics amendment effective July 29, 2025, required batch and raw-material records to be retained for 3 years or 6 months after batch expiry, whichever is later. The No change direction in both jurisdictions reflects continuity of established entry and operating duties, with those record-keeping provisions already operative.
Value Chain Stages
The comparison follows category-specific packaging and manufacturing activities into distribution and consumer retail. Huhtamaki India's 2025 packaging portfolio included dry baby food, while Clarion manufactures baby shampoo, bath foam, soap, oil, cream and lotion in India. Swara Baby Products Limited manufactures baby diapers for customers and its Cuddles brand and was a Brainbees Solutions subsidiary on March 31, 2026. These capabilities make specialization and integration separate sources of supplier value, linking product-specific production work with access to families.
Value Chain Analysis Table of India Baby Care Products Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Application-specific packaging supply | Dry baby-food packaging suppliers such as Huhtamaki India Limited | Packaging sales | Matching packaging to the intended dry-food application | Qualify packaging for the specific product application |
| Baby-care manufacturing | Baby personal-care manufacturers such as Clarion Cosmetics; baby diaper manufacturers such as Swara Baby Products Limited | Manufactured-product sales | Managing formulation and diaper-production requirements | Qualify production processes by product format |
| Trade distribution | Multi-channel trade operators such as Brainbees Solutions Limited | Product distribution sales | Coordinating digital, modern-retail and general-trade ranges | Use common product and range information across channel partners |
| Consumer retail | Digital and modern-store retailers such as FirstCry (Brainbees Solutions) | Consumer product sales | Consistent execution across franchise and company stores | Apply shared product-presentation and staff-training standards |
| Source: Mordor Intelligence | ||||
Brainbees Solutions reported 1,189 modern stores in India on March 31, 2026, covering franchise-owned, franchise-operated and company-owned, company-operated formats. A producer-retailer group can connect control of diaper production with consumer access, while dry-food packaging and personal-care formulation involve different technical capabilities. Integration can therefore concentrate diaper supply and retail access within one group while category specialization preserves room for separate upstream suppliers.
Competitive Landscape
Market Concentration
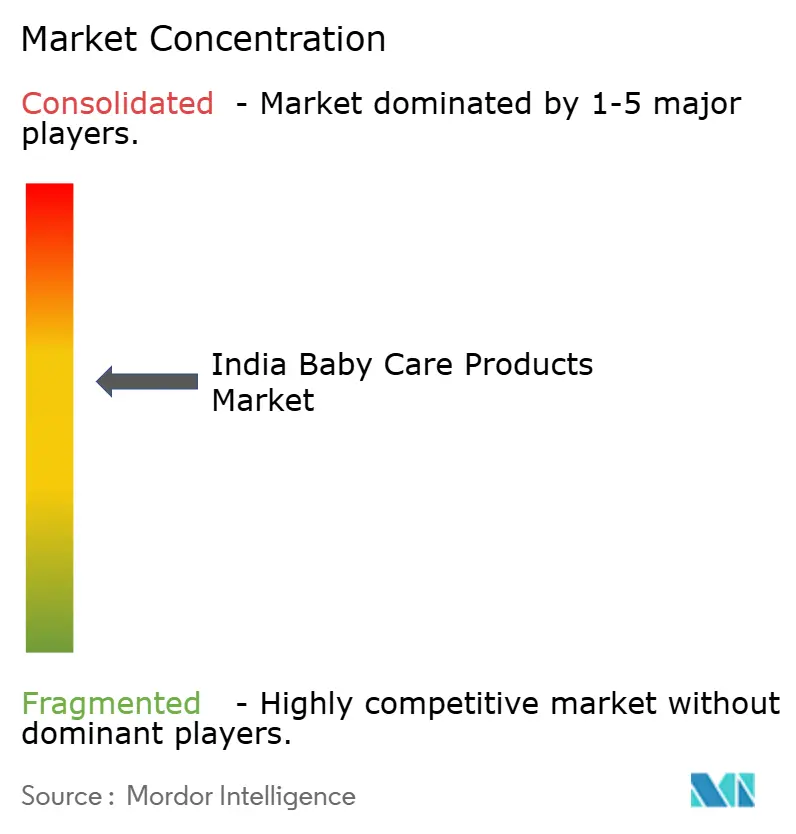
Competition is moderately concentrated around multinational groups, with Nestlé SA, Kenvue Inc., The Procter & Gamble Company, Unilever PLC and Danone SA among the major participants. Nestlé India competes in child nutrition, while Kenvue India markets Johnson's Baby products. P&G India's baby-care business includes Pampers diapers, and Danone India supplies infant and toddler nutrition. Effective September 22, 2025, Kenvue India and P&G India announced consumer pass-throughs of tax cuts on Johnson's Baby products and diapers, respectively, with the diaper Goods and Services Tax rate falling from 12% to 5%. Category-wide tax relief offers no brand-exclusive advantage, so these pass-throughs leave Johnson's Baby and Pampers needing differentiation through product-specific care functions.
In March 2025, Hindustan Unilever Limited secured Competition Commission of India approval for its proposed acquisition of 90.5% of Uprising Science, whose business included baby care. Hindustan Unilever Limited, which identified Unilever PLC as its parent in its FY2025-26 directors' report, completed the acquisition on April 21, 2025. Its subsidiary manufactures, distributes and markets Minimalist actives-led skincare and haircare products, as reported for FY2025-26. For baby-care challengers, the deal illustrates how acquisition can bring an independent producer into a multinational portfolio, making differentiation through infant-specific care more durable than independent ownership alone.
In 2025, Danone India introduced IronBiotics for infants and toddlers, which it said was designed to offer superior iron absorption. Danone linked the Dexolac range fortified with IronBiotics to an initiative engaging healthcare professionals, parents and government channels. This approach gives the product a route into discussions about infant nutrition, where the intended function can be considered alongside its formulation. India's Foods for Infant Nutrition Regulations require covered infant foods to meet composition, labeling and contaminant rules, alongside the Infant Milk Substitutes Act's advertising, marketing and promotion provisions. Within those requirements, a defensible nutrition proposition and permitted professional engagement can differentiate covered feeding ranges beyond tax-led repricing of established baby-care products.
India Baby Care Products Industry Leaders
-
Nestlé SA
-
Kenvue Inc.
-
The Procter & Gamble Company
-
Unilever PLC
-
Danone SA
- *Disclaimer: Major Players sorted in no particular order
India Baby Care Products Market Companies Covered in this Report
- Kenvue Inc.
- The Procter & Gamble Company
- Nestlé SA
- Unilever PLC
- Kimberly-Clark Corp.
- Danone SA
- Unicharm Corporation
- Himalaya Wellness Company
- Honasa Consumer Limited (Mamaearth)
- Dabur India Ltd
- Patanjali Ayurved Ltd
- Reckitt Benckiser Group plc
- ITC Limited (Mother Sparsh Baby Care Pvt Ltd)
- Emami Ltd
- Navashya Consumer Products Private Limited (SuperBottoms)
- Mee Mee (Me N Moms)
- Artsana SpA (Chicco)
- Sebapharma GmbH & Co. KG
- FirstCry (Brainbees Solutions)
- R for Rabbit Baby Products Pvt Ltd
Key Opportunities for Market Participants
The opportunities compare infant-nutrition formulation readiness, baby-care replenishment and referral-supported product sales. On October 16, 2026, the Food Safety and Standards Authority of India (FSSAI) published a draft proposing that sucrose and fructose not be added to products intended for infants up to 6 months.[3] Stakeholder comments were invited within 60 days from the date Gazette copies are made available. The proposed age limit creates a defined formulation decision for suppliers serving young infants, while leaving the outcome of the consultation open.
Market Opportunities Table of India Baby Care Products Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Infant-nutrition formulation readiness | Draft restriction on added sucrose and fructose for products intended up to 6 months | Caregivers buying nutrition products for infants up to 6 months | Prepare age-specific formulations aligned with the proposal | Final policy outcome and formulation validation | Infant-formula suppliers such as Nestlé NAN |
| Baby-care replenishment through shorter delivery routes | FirstCry Qwik's broader-assortment rollout and August 2026 expansion plan | Urban caregivers purchasing baby skin care and toiletries | Place a focused care assortment in supported delivery catchments | Coverage remains catchment-specific | Participating baby-care brands and FirstCry (Brainbees Solutions) |
| Referral-supported baby personal-care ranges | CITTA attributes baby-care revenue to parent word of mouth and, in some locations, doctor prescriptions | Caregivers choosing baby personal-care products | Supply clear product-use information to parents and local clinicians | Dependence on local recommendation networks | Baby-care brands such as CITTA |
| Source: Mordor Intelligence | |||||
FirstCry Qwik reported 125,000 shipments across its broader baby-and-kids assortment from March to June 2026 and had expanded to 12 Indian cities by the quarter ended June 30, 2026. Distribution capability can carry a focused baby-care range into covered catchments, but the more defined product decision concerns the proposed infant-nutrition composition limit. Early formulation readiness can reduce later redesign work if that draft restriction becomes binding.
Recent Industry Developments in India Baby Care Products Market
- Oct 2026: FSSAI published a draft on October 16 proposing that sucrose and fructose not be added to products intended for infants up to 6 months.
- Sep 2026: Emami Ltd announced BoroPlus FromMaa on September 8, saying the baby-care range would be available in multiple pack sizes and formats on leading e-commerce platforms across India.
- Aug 2026: Chicco opened a store in Rajouri Garden, New Delhi, bringing its Delhi NCR network to 6 stores, including 3 in Delhi.
India Baby Care Products Market Report Scope and Research Methodology
Market Definition and Coverage
The India baby care products market measures annual retail spending in India on products purchased for infant and toddler care and feeding. It counts consumer sales of baby skin care, hair care, toiletries, and food and beverages, classified by product nature, child age group, and distribution channel.
Scope exclusions: Baby durables, including strollers, car seats, and furniture, non-product services, and baby apparel and toys are excluded.
Segments Covered in This Report
- By Product Type
- Baby Skin Care
- Baby Hair Care
- Baby Toiletries
- Bath and Fragrances
- Diapers and Wipes
- Baby Food and Beverages
- By Nature
- Organic/Natural
- Conventional/Synthetic
- By Age Group
- Infants (0-1 Year)
- Toddlers (1-3 Years)
- By Distribution Channel
- Supermarkets/Hypermarkets
- Pharmacies/Drug Stores
- Online Retail Stores
- Other Distribution Channels
Data Sources, Market Sizing, and Validation
Desk Research
India-specific demand and product context can be examined through public and official sources such as the National Family Health Survey findings published by the Press Information Bureau, the peer-reviewed Frontiers study of Indian mothers' expectations for natural baby care, the Food Safety and Standards Authority of India's infant nutrition regulations, and the Bureau of Indian Standards' listing for disposable baby diapers. These sources help assess child-age context, consumer priorities, product requirements, and the regulatory conditions that shape included product categories.
Company annual reports, exchange filings, investor presentations, official product information, trade announcements, and reputable Indian business press can help cross-check brand portfolios, launches, price and product mix, and distribution activity. These sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
India-based interviews with baby-care brand and category leaders, retailers, product and regulatory specialists, and child-care professionals can test secondary evidence on category boundaries, buyer needs, prices, channel reach, and product mix. Analysts can use follow-up questions to clarify conflicting or missing inputs, then compare the resulting explanations with public filings, product information, and market indicators before using them in the estimate.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 15% | |
| Mid tier: 45% | Functional/Unit leaders: 40% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
A top-down estimate starts from total consumer retail spending on the included product families in India, then assigns that value across product type, nature, child age, and distribution channel using category sales evidence, brand portfolios, retail presence, and disclosed channel activity. Birth cohorts and the number of children in each age band inform the addressable customer base. Household income and consumption evidence inform affordability. Retail price and product-mix changes translate purchasing into value, while infant nutrition rules and product launches inform the composition of food and personal-care sales. Organized and online retail reach inform channel shares. Scenario analysis carries these drivers into the forecast period, with alternative assumptions for child cohorts, spending, price and mix, product availability, and channel expansion. The reported measure is retail value, so it does not imply a separate volume series.
Selective bottom-up checks can multiply observed retail prices by sampled product volumes or use disclosed brand and channel sales to test whether category estimates are plausible. Segment shares are supported by the relative sales and availability evidence for the defined product families, product nature, child-age groups, and channels, with category totals reconciled to the India market total. When sampled price or volume evidence is missing, analysts can triangulate from adjacent years, comparable products, and disclosed supplier or retailer information, recording the basis for any proxy. When category evidence points in different directions, India-based primary specialists can check the variable assumptions against known product, pricing, and channel conditions.
Data Validation & Update Cycle
Analysts compare the market estimate with independent signals from consumer and child-population data, product and regulatory developments, company disclosures, and retail-channel evidence, then investigate large variances between sources or periods. A second review checks boundary consistency, units, segment totals, source dates, and forecast logic. Analysts resolve anomalies or recontact relevant source respondents when definitions conflict, a material input is unsupported, or a new product or channel change could alter the estimate. The data are refreshed annually, reviewed between cycles when material events arise, and checked again in a fresh pre-delivery pass.
Mordor Intelligence's India Baby Care Products Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The India baby care products market measures annual retail spending in India on products purchased for infant and toddler care and feeding.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. When category evidence points in different directions, India-based primary specialists can check the variable assumptions against known product, pricing, and channel conditions.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 6.23 B (2027) | |
| Global Market Research Firm A | USD 4.82 B (2025) | At its 2025 base, this estimate is 22.6% below this report's 2027 value of USD 6.23 B, 2 years later. Its stated forward growth is slower, which points toward a lower later-year estimate, while its listed bottles and diaper rash ointment broaden the described products beyond the report's core product families. |
| Global Market Research Firm B | USD 4.85 B (2025) | At its 2025 base, this estimate is 22.2% below this report's 2027 value of USD 6.23 B, 2 years later. Its stated forward growth is slower, which points toward a lower later-year estimate. |
Mordor Intelligence's analysts compare the market estimate with independent signals from consumer and child-population data, product and regulatory developments, company disclosures, and retail-channel evidence, then investigate large variances between sources or periods.
Key Questions Answered in the Report
How large is the India baby care products market size in 2027, and how fast will it grow?
The size is USD 6.23 billion in 2027 and is forecast to reach USD 10.7 billion by 2032, at an 11.42% CAGR over 2027-2032.
What supports demand for baby-care products in India?
Caregiver education can support demand. The National Health Mission reported a 37% knowledge improvement among caregivers in special newborn care units at 5 Himachal Pradesh facilities from December 2022 to March 2025.
Which product category leads baby-care spending?
Baby food and beverages held the largest share at 27.55% in 2026. Baby skin care is forecast to grow fastest, at a 12.29% CAGR over 2027-2032.
Which companies are major participants in the baby-care industry?
Major participants include Nestlé SA, Kenvue Inc., The Procter & Gamble Company, Unilever PLC and Danone SA.
What could constrain baby-care sales?
For new cosmetics containing novel ingredients, India requires prior central permission before manufacturing licensing. This can add preparation work as the industry expands at a forecast 11.42% CAGR over 2027-2032.
Where is baby-care growth strongest within India?
In India, Tier-2 and Tier-3 cities are the fastest-growing geography. Rural, tribal and remote communities have a distinct care-information route through Anganwadi workers.