
Toothpaste Market Analysis by Mordor Intelligence
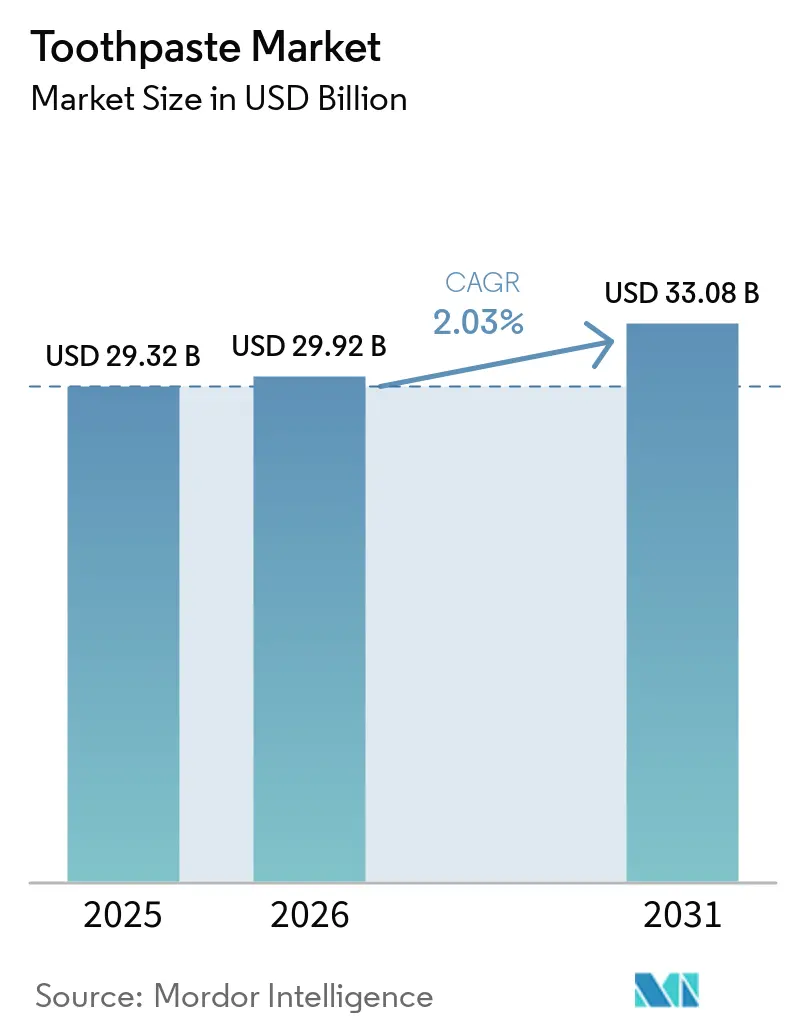
The toothpaste market size was valued at USD 29.92 billion in 2026 and estimated to grow from USD 30.53 billion in 2027 to reach USD 33.91 billion by 2032, at a CAGR of 2.12% during the forecast period (2027-2032).
Growth depends on turning specific oral-care needs into affordable daily purchases, with sensitivity relief and herbal preferences supporting different product propositions in India. Brands can respond through focused functional claims and accessible offers, while ingredient scrutiny can redirect demand toward alternative formulations. Raw and packaging cost pressure makes manufacturing efficiency matter as suppliers balance differentiated care against the cost of serving price-sensitive buyers. Since August 12, 2026, the EU Packaging and Packaging Waste Regulation has applied to packaging placed on the EU market, and the Commission's June 2026 guidance reads its recyclability requirement as covering all packaging from that date, which ties continued shelf access to the recyclability of the finished toothpaste pack.
Key Report Takeaways
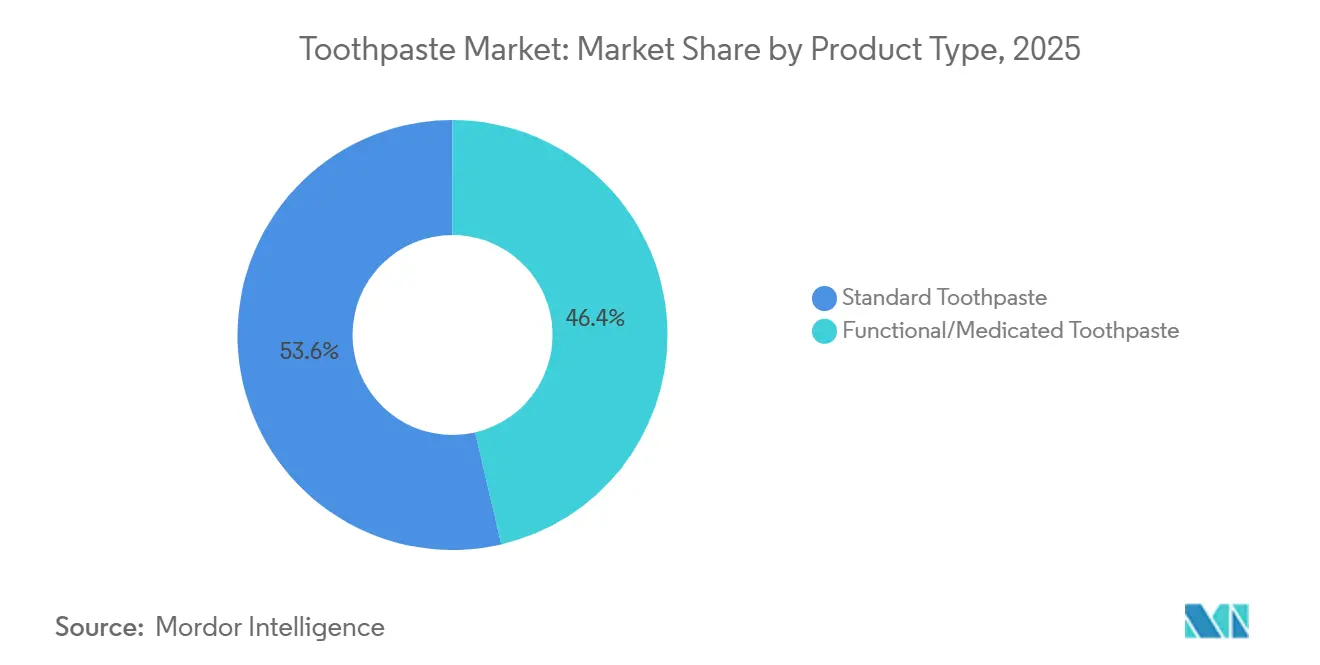
- By product type, standard toothpaste held a 53.39% toothpaste market share in 2026, while functional/medicated toothpaste is forecast to grow fastest at a 2.68% CAGR during 2027-2032.
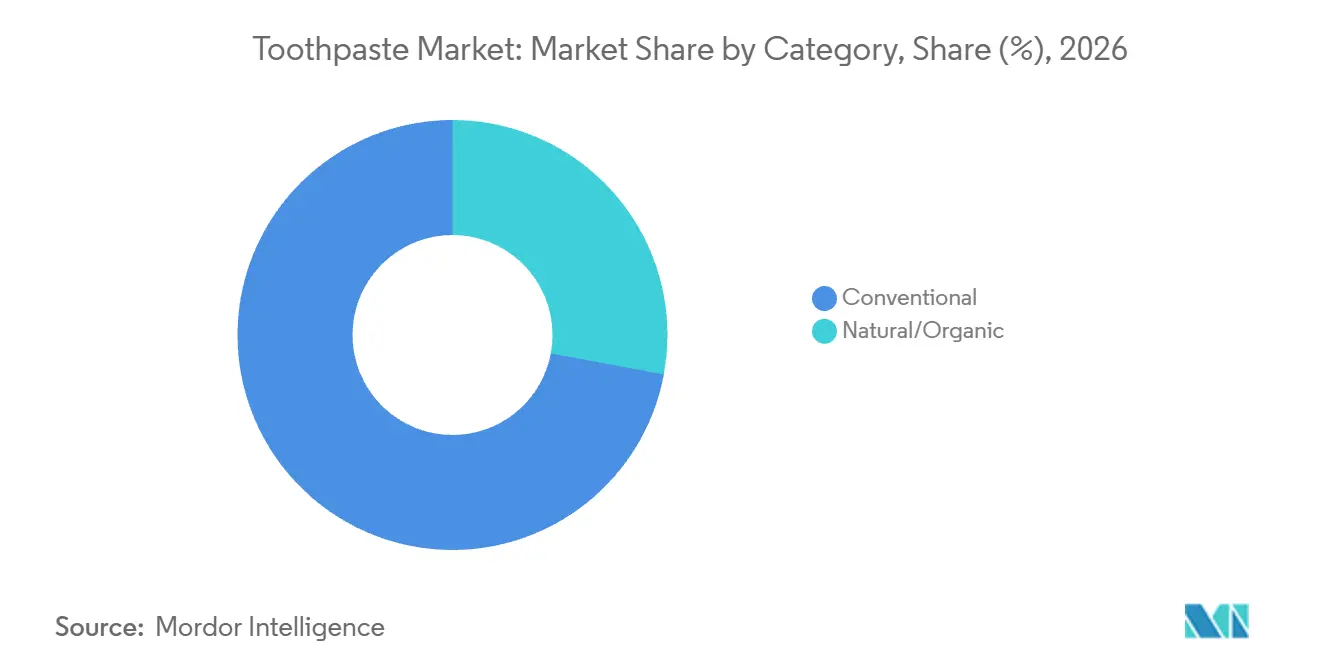
- Within the category breakdown, conventional toothpaste accounted for a 72.06% share of the toothpaste market size in 2026, and natural/organic toothpaste is projected to grow fastest at a 3.05% CAGR during 2027-2032.
- By end user, adults represented 82.54% of toothpaste spending in 2026, with kids' toothpaste forecast to grow fastest at a 3.42% CAGR during 2027-2032.
- Among distribution channels, supermarkets/hypermarkets led with 30.59% of toothpaste spending in 2026, while online retail stores are forecast to grow fastest at a 3.88% CAGR during 2027-2032.
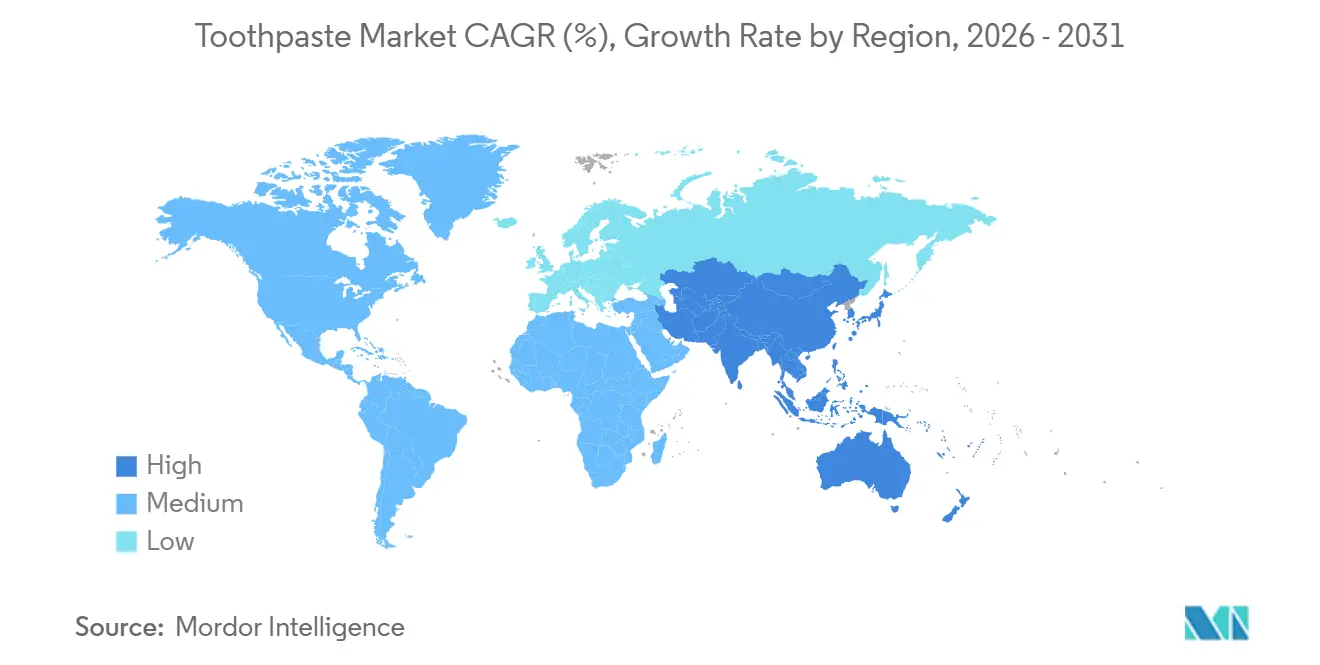
- Geographically, Asia-Pacific held 33.83% of toothpaste spending in 2026 and is projected to grow fastest at a 4.23% CAGR during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Toothpaste Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shift in consumer preference toward herbal and natural formulation-based products | +0.8% | India | Medium term (2-4 years) |
| Growing demand for toothpaste catering to sensitive teeth | +1% | India | Short term (≤ 2 years) |
| Enhanced marketing and advertising strategies by brands | +0.6% | Uttar Pradesh, Bihar, Assam, Kerala, Haryana, Maharashtra | Medium term (2-4 years) |
| Product innovation emphasizing ingredients and functionality | +0.7% | United Kingdom | Medium term (2-4 years) |
| Government initiatives supporting oral hygiene awareness | +0.3% | China and New Zealand | Long term (≥ 4 years) |
| Barriers in oral health impacting market expansion | +0.2% | Tanzania | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Shift in consumer preference toward herbal and natural formulation-based products
Herbal positioning offers toothpaste suppliers a way to combine a distinct ingredient identity with an established commercial base. In India in the quarter ended June 30, 2026, Dabur reported strengthening preferences for herbal and natural oral care, with herbal segment growth exceeding non-herbal growth by 550 basis points. Dabur also placed Dabur Red Paste in its FY2025-26 annual brand range of INR 10 billion to 15 billion (USD 113 million to 170 million). Because the 550-basis-point figure is a growth gap rather than a sales level, the segment comparison shows direction while the Red Paste brand range shows existing scale.
Growing demand for toothpaste catering to sensitive teeth
Affordable access can turn sensitivity relief into a broader source of toothpaste demand without requiring every buyer to purchase a premium pack. Haleon said affordable Sensodyne offerings helped drive double-digit growth in India during H1 2026. More than 40% of Sensodyne tubes sold in India during H1 2026 came from affordable offerings.
Enhanced marketing and advertising strategies by brands
Brand investment can develop demand through product communication and the establishment of brushing knowledge. Colgate-Palmolive (India) Limited increased company advertising spend 10% year over year in the quarter ended March 31, 2026, emphasizing premiumization and consumption.[1] Its Bright Smiles, Bright Futures program reached 11 million children in 35,000 schools across India in fiscal 2025-26. The school-based reach places education alongside paid advertising as a concrete route for making oral care familiar. That separates the task of encouraging established users to upgrade from the longer task of introducing children to preventive routines. Education can build future participation, but its commercial value depends on continued brushing rather than the number of children contacted alone.
Product innovation emphasizing ingredients and functionality
Faster sensitivity relief can give ingredient innovation a clear commercial purpose within an everyday toothpaste format. Matrix Brands launched Ozen for dentin hypersensitivity in the United Kingdom on June 8, 2026, marking the first commercial toothpaste application of Svenska Aerogel's technology. The technology supplier reported comparative testing showing relief more than 40 times faster than leading competing products.
Restraints Impact Analysis of Toothpaste Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Continued reliance on traditional tooth cleaning practices | -0.5% | Nilgiris district, Tamil Nadu | Long term (≥ 4 years) |
| Rising concerns about chemical ingredients in products | -0.4% | Denmark | Short term (≤ 2 years) |
| Instability in raw material pricing | -0.3% | Latin America | Short term (≤ 2 years) |
| Proliferation of counterfeit products in the market | -0.2% | Kaduna State | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Continued reliance on traditional tooth cleaning practices
Continued reliance on charcoal or tooth powder can constrain toothpaste demand when those materials already satisfy a household's cleaning expectations. The buyer's decision is whether a manufactured paste adds enough brushing benefit to justify a separate recurring purchase. A low-priced pack lowers that first commitment, but it does not remove the substitute from the cleaning routine. Explaining a distinct paste-based benefit may help introduce the product, although awareness alone cannot establish repeat use. Suppliers therefore face conversion spending before they can count on replenishment sales from households retaining their customary cleaning material.
Rising concerns about chemical ingredients in products
Ingredient concerns can constrain fluoride-containing toothpaste even when consumers continue buying another formulation. A 2025 Dutch dental review reported that adults often choose fluoride-free toothpaste because they consider fluoride harmful or unnecessary, prefer natural products, or avoid artificial additives.[2] A 2026 scoping review described families adopting fluoride-free alternatives while continuing oral-health prevention. This pattern makes ingredient acceptance a competitive barrier for the affected formulation within continued toothpaste use. Clear ingredient explanations may help buyers distinguish the intended product benefit from a perceived risk. Where objections persist, manufacturers face narrower demand for fluoride-containing offers and additional work to retain consumers whose oral-care routines can accommodate an alternative.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Toothpaste Market Segment Analysis
By Product Type:
Routine Cleaning Anchors Demand as Specialized Care ExpandsStandard toothpaste accounted for a 53.39% share of the toothpaste market size in 2026. In Q2 2026, Colgate-Palmolive Company said its Maximum Cavity Protection and Triple Action toothpastes were performing well in Mexico. Everyday cavity protection gives a standard paste a defined application without asking the buyer to identify a separate sensitivity or cosmetic concern. The supplier's selling task is to make that routine benefit recognizable at replenishment, rather than require a new condition-specific decision with each tube.
Functional/medicated toothpaste is forecast to be the fastest-growing segment, at a 2.68% CAGR during 2027-2032. Haleon's Oral Health review reported double-digit growth for its Sensodyne brand in H1 2026, supported by the Sensodyne Clinical platform. Haleon also said Clinical White was driving penetration gains by attracting a younger audience into the Sensodyne franchise. That combination gives targeted care a route through both a defined sensitivity need and a broader audience for the brand. The commercial implication is to extend the functional promise to additional buyers, rather than rely only on more intensive demand from existing users.



By Category:
Conventional Scale Meets Ingredient-Led DifferentiationConventional toothpaste represented a 72.06% toothpaste market share in 2026. For a conventional fluoride paste chosen for cavity prevention, the formulation decision centers on delivering that brushing function at a repeat-purchase price. The manufacturer must balance the active formulation with taste and dispensing characteristics suited to daily use. This makes the preservation of the cavity-protection proposition the central constraint on a formulation change, even when ingredient-origin positioning offers another way to distinguish the product.
Natural/organic toothpaste is forecast to be the fastest-growing segment, at a 3.05% CAGR during 2027-2032. During the quarter ended June 30, 2026, Dabur's India oral-care portfolio recorded near double-digit growth, led by its Red franchise, Meswak, and Dabur Herbal range. That result puts ingredient-led herbal brands at the front of Dabur's India oral-care growth, which gives the natural/organic category a concrete supplier example behind its faster forecast.

By End User:
Adult Value Supports Targeted Expansion Among KidsAdults were the largest segment, accounting for 82.54% of toothpaste spending in 2026. In 2025, Lion launched Dent Health Medicated Toothpaste DX Premium in Japan, its highest-priced product for self-care-focused consumers, and reported strong sales. That example shows a commercial route centered on a specific self-care proposition within the adult-oriented opportunity, rather than depending on an increase in routine brushing alone. Value is built around a clearly identified care need, so a higher price must correspond to an understandable product promise.
Kids' toothpaste is forecast to be the fastest-growing segment, at a 3.42% CAGR during 2027-2032. By September 2025, the UK government and Colgate-Palmolive had delivered more than 2 million free toothbrushes and toothpaste tubes to children in England's most deprived areas. A supplier-supported delivery model can place toothpaste within a structured brushing routine, creating an adoption pathway whose first step does not require a separate retail purchase. The introduction becomes a retail growth opportunity when families choose to continue using a children's toothpaste, extending demand beyond the free products supplied through the program.
By Distribution Channel:
Store Networks Anchor Reach as Digital Routes ExpandSupermarkets/hypermarkets were the largest segment, accounting for 30.59% of toothpaste spending in 2026. Walmart operated 3,569 U.S. Supercenters as of July 31, 2026. Walmart offered hello whipped fluoride toothpaste online and in-store in January 2026, according to Hello Products. Such a store network can provide toothpaste brands with repeated opportunities to appear within ordinary shopping trips, making geographic reach central to the channel's proposition. The scale of the store network makes retailer access a practical competitive barrier for a toothpaste brand seeking national physical distribution, even when its formulation is commercially ready.
Online retail stores are forecast to be the fastest-growing segment, at a 3.88% CAGR during 2027-2032. Colgate-Palmolive (India) Limited reported strong double-digit company e-commerce net sales growth in the year ended March 31, 2026. In 2025, Shenzhen Xiaokuo Technology ranked first among oral-care products groups in China's online toothpaste market by retail sales value, with a 9.2% share. That online position makes digital expansion a competitive task for the toothpaste producer itself, rather than simply a choice of retail platform.
Geography Analysis
Asia-Pacific Toothpaste Market
Asia-Pacific accounted for a 33.83% share of the toothpaste market size in 2026 and is forecast to be the fastest-growing region, at a 4.23% CAGR during 2027-2032. In India, Colgate-Palmolive (India) Limited reported high-single-digit toothpaste volume growth for the quarter ended June 30, 2026, led by premium offerings alongside growth in its core portfolio. On its recast geographic reporting basis, Colgate-Palmolive's combined Asia Pacific Oral, Personal and Home Care segment recorded USD 782 million in second-quarter 2026 net sales, compared with USD 746 million in second-quarter 2025. The Indian result supports core and premium offers. New Zealand's Ministry of Health reported that its Toothbrush-Toothpaste initiative had distributed more than 3 million free toothbrush and fluoride-toothpaste products to providers serving preschool-aged children since December 2021.
In North America, Guatemala's March 2026 withdrawal register marked the Colgate Total Clean Mint recall as in process and primarily linked reported adverse events to flavoring level. In 2025, 18% of U.S. adults skipped dental care because of cost, the most frequently skipped care form in the Federal Reserve's multiple-response survey. An attainable daily-use toothpaste proposition can respond to that dental-care affordability context by keeping preventive brushing within reach. Within Europe, EFSA reported in 2025 that approximately 90% of toothpastes sold in the EU contain fluoride, and its exposure assessment counted ingestion of fluoridated oral-care products rather than correct surface-only use. Instructions about swallowing therefore concern most EU toothpaste, while Denmark's 2026 consumer-council ingredient-testing update highlights a separate need to explain formulations to interested users.
In South America, Brazil shows how a tolerance concern about stannous-fluoride toothpaste can reach manufacturers through labeling guidance. On March 28, 2025, Brazil's Anvisa advised consumers to stop using stannous-fluoride toothpaste if irritation occurred and told manufacturers to label possible reactions. In Uruguay, the Ministry of Public Health ordered a preventive 180-day suspension of Colgate Total Clean Mint sales and distribution on July 23, 2025 and urged the product holder to withdraw it nationally immediately. In Middle East and Africa, WHO reported in 2025 that Mauritius had abolished toothpaste tax to improve access to fluoride toothpaste for caries prevention. Brazilian labeling guidance and Uruguay's suspension order concern product tolerance and availability, while Mauritius used tax policy to address access.
Regional Editions
Regulatory Framework and Outlook
This comparison assesses selected jurisdictions from the perspective of a toothpaste manufacturer preparing market-entry and ongoing product-compliance work. China requires overseas filing entities to designate a China-based responsible legal entity, while Brazil assigns notification for qualifying products to the responsible Brazilian company. These local accountability models make the choice of operating partner part of compliance preparation, alongside formulation and labeling decisions.
Regulatory Table of Toothpaste Market
| Decision factor | United States | Germany | China | Brazil | Nigeria |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | Competent authorities of the federal states | National Medical Products Administration (NMPA) and drug regulators at county level or higher | Anvisa | NAFDAC |
| Key instruments or direction | 21 CFR 355.10 anticaries active-ingredient and dosage-form conditions | EU cosmetics framework; packaging design acts due January 1, 2028 | SAMR Decree No. 71, effective December 1, 2023; product filing | RDC 907/2024 and RDC 814/2023 conditional authorization and notification routes | Toothpaste-specific market surveillance |
| Commercial effect | OTC anticaries sodium-fluoride gel or paste dentifrices must match the specified active and available-fluoride conditions | Toothpaste at 0.1%-0.15% fluoride requires child-use labeling unless labeled as contraindicated for children | Domestic filing with provincial regulators before marketing; imported filing with NMPA before importation; overseas filers appoint a China-based responsible legal entity | Products outside Article 34 of RDC 907/2024 and RDC 814/2023 approval lists require notification by the responsible Brazilian company | Distribution scrutiny in the reported Lagos suspected-counterfeit case |
| Current policy attractiveness | Medium | High | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change | No change |
| Source: Mordor Intelligence | |||||
U.S. OTC anticaries active-ingredient conditions and China's pre-sale filing with domestic accountability support Medium ratings and continuity, with FDA's July 2026 nonanimal-test data request seeking a possible additional procedure for fluoride dentifrices rather than changing existing duties. Brazil's Medium and No change judgments balance conditional notification against local-company responsibility, with its cosmetics filing-group transition effective April 7, 2025 preceding the forecast period. Germany's High rating favors its cosmetics advance-notification route and defined conditional fluoride labeling, but EU packaging must meet grades A, B, or C from the later of January 1, 2030 or 24 months after delegated acts take effect, subject to Article 6(10) derogations, supporting Hardening. Nigeria's Medium and No change judgments reflect registration before sale for toothpaste treated as an imported cosmetic and a December 12, 2026 guideline review that schedules review rather than changed duties, while the August 2026 Lagos suspected-counterfeit alert illustrates surveillance.
Value Chain Stages
The comparison follows ingredient and packaging supply into branded toothpaste production and sale, showing where suppliers earn revenue and where operating constraints arise. Solvay supplies precipitated silica for toothpaste formulations, illustrating the specialized input capabilities available to manufacturers. Ingredient and packaging streams converge in finished-product production, so resilience depends on qualifying both streams before scaling a formulation.
Value Chain Analysis Table of Toothpaste Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Toothpaste ingredient supply | Silica suppliers such as Solvay | Ingredient sales | Matching cleaning and abrasivity requirements to the intended formulation | Qualify grades against the formulation's intended use |
| Tube and closure production | Oral-care packaging suppliers such as Pact Group and Amcor | Packaging sales | Coordinating tube and closure specifications across pack formats | Validate packaging combinations before production commitments |
| Branded toothpaste manufacture and sale | Toothpaste manufacturers and brand owners such as Colgate-Palmolive Company and Lion Corporation | Finished-product sales | Exposure to raw and packaging material cost increases | Target production cost savings while preserving product specifications |
| Source: Mordor Intelligence | ||||
In 2025, raw and packaging costs imposed a 420-basis-point gross-margin headwind on Colgate-Palmolive's worldwide business, partly offset by 260 basis points of funding-the-growth savings.[3] That combination makes production efficiency consequential even when the product proposition is differentiated. Upstream qualification and manufacturing savings address different vulnerabilities, so resilience requires both technical fit and control of conversion economics.
Competitive Landscape
Market Concentration
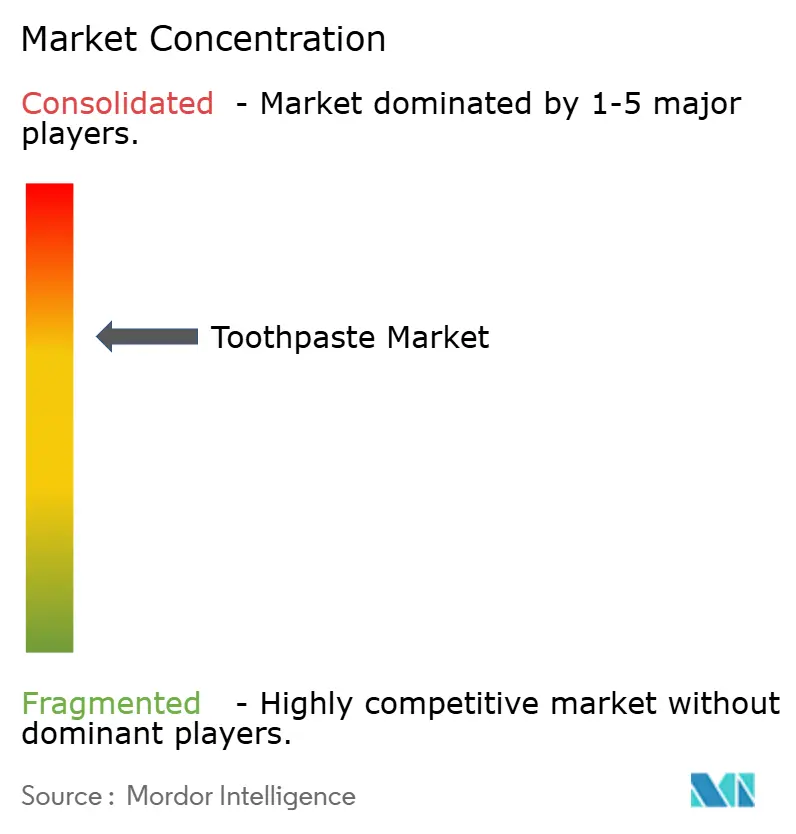
Competition is concentrated around large brand-owning groups, with differentiation spanning multiple toothpaste brands and geographically focused ranges. The Procter & Gamble Company competes in the United States through Crest toothpaste, while Unilever PLC operates an Oral Care business. Colgate-Palmolive Company sells brands including Colgate and elmex, Haleon PLC owns Sensodyne, and Lion Corporation offers toothpaste in Japan. Colgate-Palmolive reported a 20-basis-point increase in its global toothpaste value share year to date through June 2026.
Operating results show that the sources of growth differ even among large groups with established oral-care businesses. P&G reported a mid-single-digit decline in Oral Care organic sales in the fiscal year ended June 30, 2026, driven by lower volume led by North America and Greater China. Unilever reported low-single-digit Oral Care growth in H1 2026, balanced between volume and price. P&G's volume-led decline makes rebuilding demand in North America and Greater China the more direct strategic task, while Unilever's balanced growth calls for preserving both volume and price contributions.
Competitive direction in the United States includes evidence-based qualification through the American Dental Association's voluntary Seal of Acceptance. The American Dental Association's voluntary Seal of Acceptance requires applicants to submit data and publications to its Council on Scientific Affairs for a safety and efficacy determination. For fluoride toothpaste applicants, the criteria specifically address safety and efficacy in reducing tooth decay. That route offers challengers a way to structure differentiation around an evaluated dental benefit, while requiring investment in a substantiation package. The need to submit toothpaste-specific safety and efficacy evidence means that an incumbent's scale alone cannot secure the voluntary label.
Toothpaste Industry Leaders
-
The Procter & Gamble Company
-
Unilever PLC
-
Colgate-Palmolive Company
-
Haleon PLC
-
Lion Corporation
- *Disclaimer: Major Players sorted in no particular order
Toothpaste Market Companies Covered in this Report
- The Procter & Gamble Company
- Unilever PLC
- Colgate-Palmolive Company
- Haleon PLC
- Lion Corporation
- Dabur India Limited
- Church & Dwight Co., Inc.
- Sunstar Group
- Katjes International GmbH & Co. KG
- Yunnan Baiyao Group Co., Ltd.
- Vicco Laboratories Ltd
- Livionex Inc
- Perrigo Company plc
- Himalaya Global Holdings Ltd.
- Kao Corporation
- Amway Corporation (Glister)
- Patanjali Ayurved Limited
- Ludovico Martelli S.p.A. (Marvis)
- The Honest Company, Inc.
- Dr. Bronner's Magic Soaps
Key Opportunities for Market Participants
The opportunities compare immediate EU packaging compliance, preparation for later design criteria, and expansion of an operating toothpaste-refill channel in New Zealand. The European Commission's June 2026 guidance says the Packaging and Packaging Waste Regulation's all-packaging recyclability requirement applies from August 12, 2026. That creates an immediate packaging decision for toothpaste businesses placing packaged products on the EU market, while later criteria establish a separate redesign horizon.
Market Opportunities Table of Toothpaste Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| EU toothpaste offers with demonstrable packaging recyclability | Operative all-packaging recyclability duty | Toothpaste brands placing packaged products on the EU market | Offer finished toothpaste in packaging whose recyclability can be substantiated | Assessing the actual complete packaging configuration | Compliant toothpaste producers and their packaging partners |
| Toothpaste redesign for future EU criteria | Scheduled EU design-for-recycling transition | Brands developing their next packaged toothpaste range | Align the next product design with the applicable delegated criteria | Balancing dispensing function with the applicable packaging design criteria | Toothpaste brands able to coordinate product and packaging development |
| New Zealand toothpaste refill distribution | Operating refill locations and an invitation for additional stockists | Prospective stockists serving toothpaste refill customers | Add a refill offer through a Solid stockist relationship | Building repeat refill visits at each new location | Solid and participating New Zealand stockists |
| Source: Mordor Intelligence | |||||
The central opening is to preserve toothpaste market access through a package whose recyclability can be substantiated. That makes packaging a product decision for brand owners, rather than an isolated material substitution. A pack specified now has to satisfy the recyclability requirement the Commission's guidance applies from August 12, 2026 and stay adjustable to the design criteria that the delegated acts scheduled for January 1, 2028 are due to set.
Recent Industry Developments in Toothpaste Market
- Oct 2026: Lion Corporation launched Dent Health Medicated Toothpaste DX Double Anti-Inflammatory across Japan on October 7. The quasi-drug contains 2 anti-inflammatory ingredients to reduce gum inflammation and help prevent periodontitis.
- Aug 2026: NAFDAC reported suspected counterfeit ORACIRE+ toothpaste in Lagos on August 19. It said it had initiated surveillance and directed officials to investigate the product's availability and distribution.
- Jun 2026: Matrix Brands launched Ozen toothpaste for dentin hypersensitivity in the United Kingdom on June 8, using Svenska Aerogel's aerogel material.
Toothpaste Market Report Scope and Research Methodology
Market Definition and Coverage
The global toothpaste market measures annual consumer spending on finished toothpaste products sold worldwide. It covers toothpaste sales across formulation types, buyer age groups, and distribution channels.
Scope exclusions: Mouthwash, toothbrushes, floss, professional in-office prophylaxis pastes used as part of dental procedures, and toothpaste ingredients sold separately are excluded.
Segments Covered in This Report
- By Product Type
- Standard Toothpaste
- Functional/Medicated Toothpaste
- By Category
- Conventional
- Natural/Organic
- By End User
- Adult
- Kids
- By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience/Grocery Stores
- Pharmacies/Drug Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
The World Health Organization's fluoride-toothpaste affordability indicator and FDI World Dental Federation's topical-fluoride policy statement help assess access, recommended use, and the role of toothpaste in prevention, while the European Commission's cosmetics regulation informs product and labeling context. Company disclosures such as Colgate-Palmolive (India) Limited's results announcement provide operating and channel context.
Supplementary analysis can use company filings, annual reports, investor materials, and reputable press coverage to cross-check sales trends, product launches, pricing, distribution, and regional exposure. These named sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and surveys would target toothpaste manufacturers and brand owners, retailers and distributors, dental-product specialists, and oral-health professionals across APAC, EMEA, and the Americas. Respondents would check secondary evidence on purchase channels, formulation mix, pricing, use patterns, and regional demand, while unresolved gaps would be tested against independent source signals and selectively sampled retail price and availability checks.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 40% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 25% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
A top-down model estimates annual consumer spending on finished toothpaste by country and rolls the results into regional and global totals, with selective bottom-up checks using sampled retail prices and plausible purchase volumes. Population, household purchasing power, toothpaste-use and product-penetration indicators, retail prices, and product and channel mix inform the base and forecast. Segment shares are built from evidence on product propositions, intended users, and where purchases occur, then checked against the total. A multivariate regression can relate revenue to these demand and price indicators, with scenario analysis for material changes in affordability, premium mix, or access. Primary respondents would check whether the variable paths and resulting forecasts are commercially plausible. Where country or channel evidence is sparse, the analyst would use the nearest supported regional indicators, mark the assumption for review, and reconcile selective price-times-volume checks to the top-down totals rather than treating them as a complete bottom-up census.
Data Validation & Update Cycle
Analysts triangulate public health and affordability indicators, company disclosures, retail observations, and modeled demand signals, then investigate anomalies and material variance between independent estimates before sign-off. A second review checks source dates, units, country aggregation, segment totals, and forecast drivers. Analysts re-contact relevant respondents when evidence conflicts, a key input changes, or an unexplained gap remains. The model is refreshed annually, reviewed between cycles after material events, and given a fresh pre-delivery check for source currency and internal consistency.
Mordor Intelligence's Global Toothpaste Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global toothpaste market measures annual consumer spending on finished toothpaste products sold worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Population, household purchasing power, toothpaste-use and product-penetration indicators, retail prices, and product and channel mix inform the base and forecast.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 30.53 B (2027) | |
| Global Consultancy A | USD 26.6 B (2025) | At its 2025 base, this estimate is 12.9% below this report's 2027 value of USD 30.53 B, 2 years later. Its published base remains lower despite the stated positive forecast path. |
| Global Consultancy B | USD 22.3 B (2025) | At its 2025 base, this estimate is 27.0% below this report's 2027 value of USD 30.53 B, 2 years later. Its reported rise and positive forecast leave the published revenue path lower. |
Mordor Intelligence's analysts triangulate public health and affordability indicators, company disclosures, retail observations, and modeled demand signals, then investigate anomalies and material variance between independent estimates before sign-off.
Key Questions Answered in the Report
What is the toothpaste market size and growth outlook?
The market is estimated at USD 30.53 billion in 2027 and forecast to reach USD 33.91 billion by 2032, at a 2.12% CAGR during 2027-2032.
What factors support toothpaste demand?
Affordable sensitivity-care offers and herbal preferences support demand in India, while function-specific innovation adds differentiation.
Which toothpaste product type leads sales?
Standard toothpaste accounted for 53.39% of toothpaste spending in 2026.
Which companies compete in the toothpaste industry?
The Procter & Gamble Company, Unilever PLC, Colgate-Palmolive Company, Haleon PLC, and Lion Corporation are major competitors.
What challenge could limit toothpaste growth?
Ingredient concerns can redirect buyers away from fluoride-containing formulations, as described in a 2025 dental review.
Which region has the strongest toothpaste growth outlook?
Asia-Pacific is forecast to grow fastest at a 4.23% CAGR during 2027-2032 and held 33.83% of global toothpaste spending in 2026.