
Europe Space Propulsion Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 0.92 Billion |
| Market Size (2026) | USD 1.03 Billion |
| Market Size (2031) | USD 1.66 Billion |
| Growth Rate (2026 - 2031) | 10.02 % |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Europe Space Propulsion Market Analysis by Mordor Intelligence
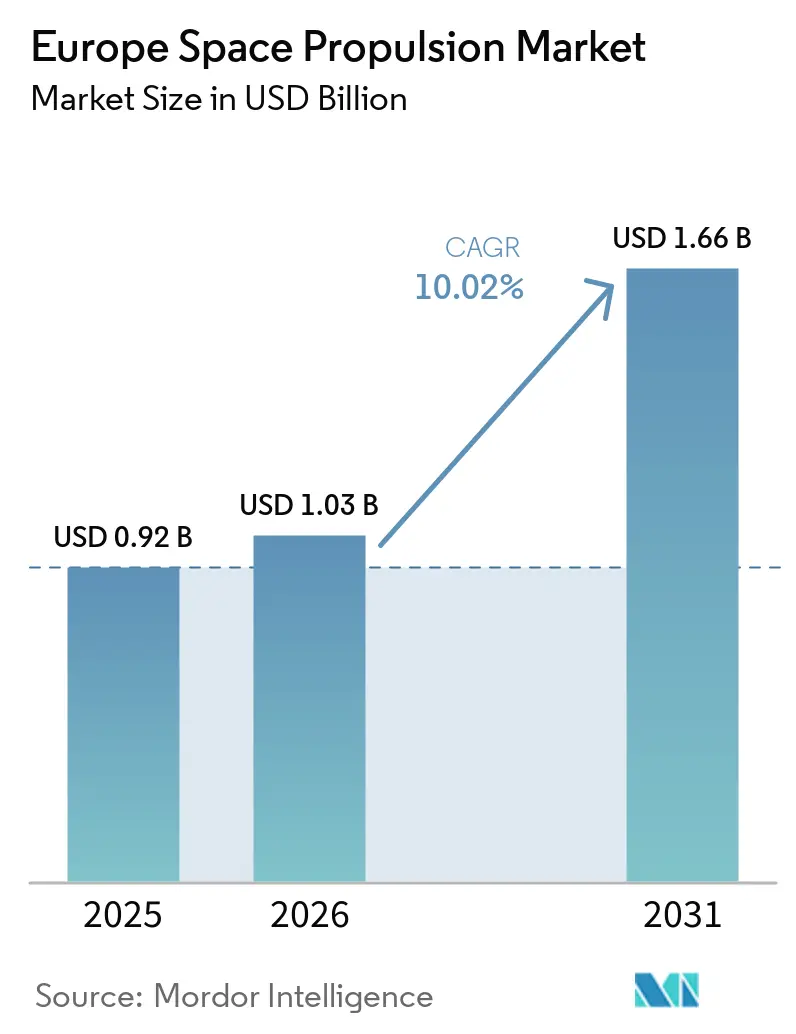
The Europe space propulsion market size was valued at USD 0.92 billion in 2025 and is forecast to grow from USD 1.03 billion in 2026 to reach USD 1.66 billion by 2031, at a 10.02% CAGR during the forecast period (2026-2031). The market is supported by institutional constellations, commercial satellite programs, and the need for European launch autonomy. Demand is moving toward repeat orders for standardized satellite propulsion units, which can provide a steadier order flow than large geostationary satellite programs. European suppliers are also expanding production capacity for electric propulsion while maintaining capabilities in liquid and solid propulsion for launch vehicles. This creates opportunities for suppliers that can meet qualification requirements, secure component supply, and demonstrate reliable performance in orbit. Production capacity for solid boosters remains important because launch availability depends on both manufacturing output and satellite demand.
Key Report Takeaways
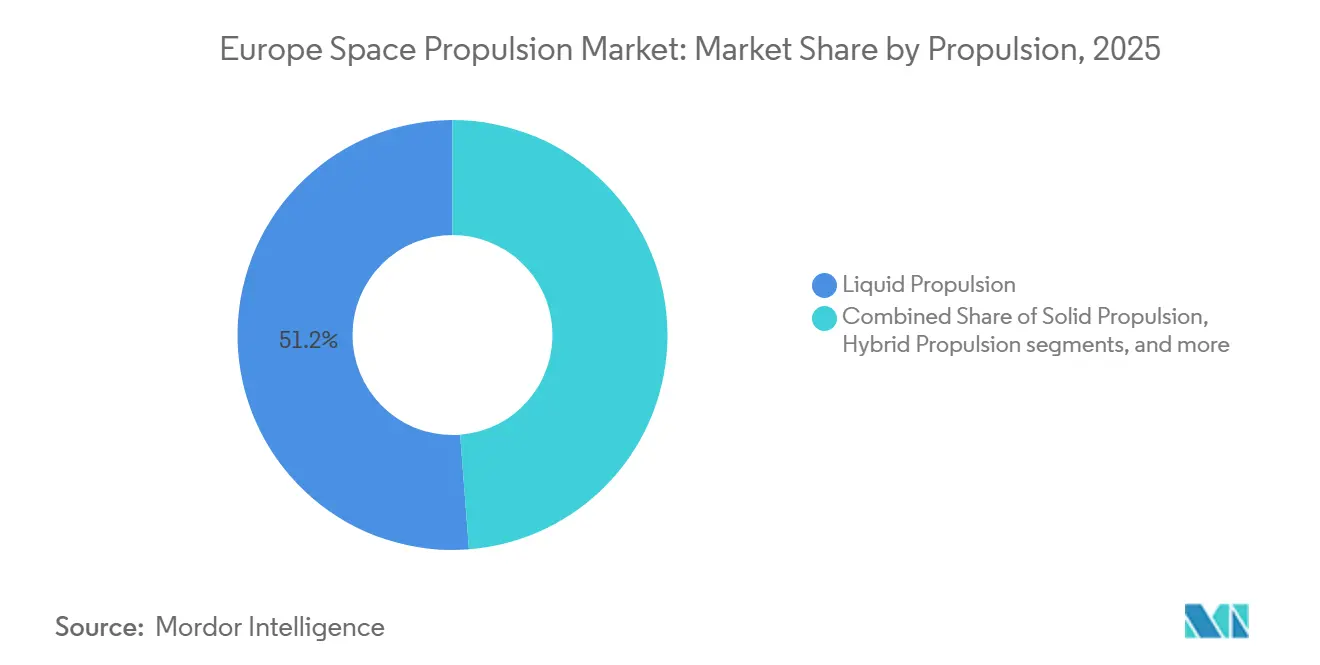
- By propulsion, liquid propulsion held 51.22% of revenue in 2025, while electric propulsion is forecast to grow at a 16.42% CAGR through 2031.
- By component, thrusters and rocket motors held 51.81% of revenue in 2025, while propellant feed systems are forecast to grow at a 14.12% CAGR through 2031.
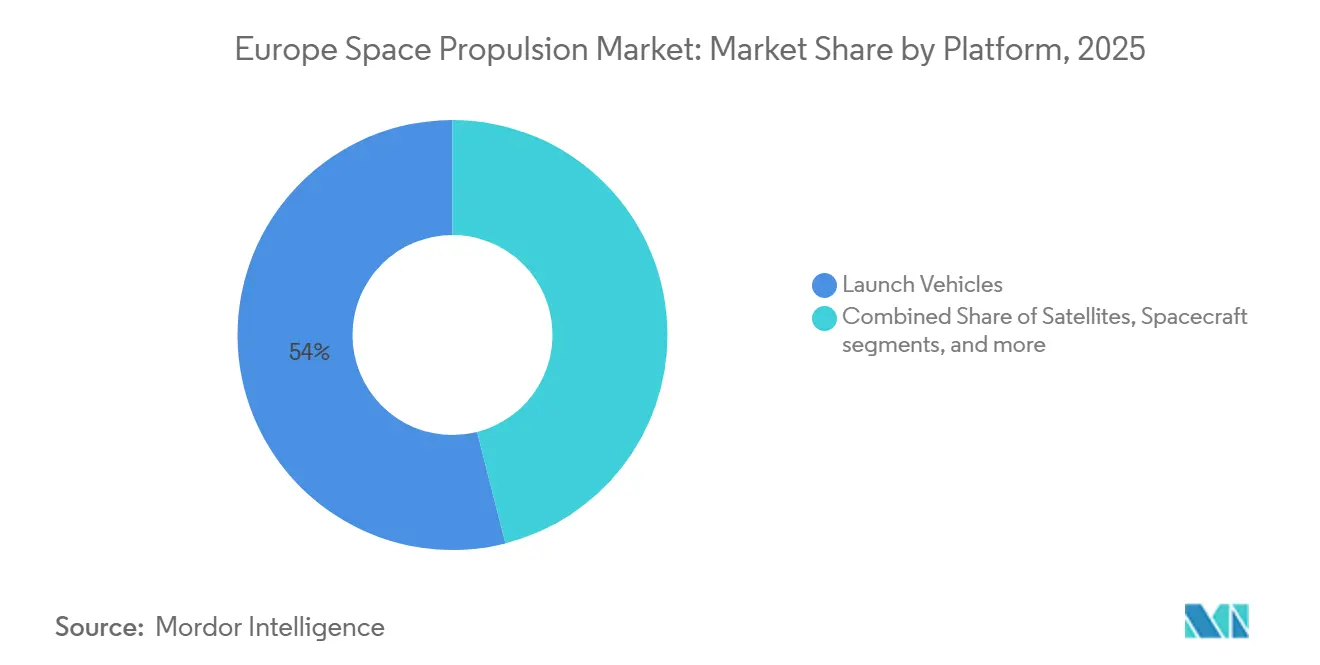
- By platform, launch vehicles held 53.96% of revenue in 2025, while satellites are forecast to grow at an 18.92% CAGR through 2031.
- By end user, commercial users held 62.63% of revenue in 2025 and are forecast to grow at a 16.52% CAGR through 2031.
- By geography, the United Kingdom held 35.17% of revenue in 2025, while France is forecast to grow at a 16.63% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Europe Space Propulsion Market*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Institutional and commercial satellite deployment | 2.90% | Europe | Medium term (2-4 years) |
| Expansion of European launch capacity | 2.30% | Western Europe (France, Italy, Germany) | Short term (≤ 2 years) |
| Electric propulsion adoption for mass and cost optimization | 2.20% | Global, European manufacturing base | Long term (≥ 4 years) |
| Growth of in-orbit mobility and end-of-life services | 1.50% | Europe, spill-over to global GEO operators | Medium term (2-4 years) |
| European industrialization of propulsion manufacturing | 0.80% | Europe (Italy, France, Germany, UK, Austria) | Medium term (2-4 years) |
| European strategic autonomy in space | 1.10% | Europe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Institutional and Commercial Satellite Deployment
The EU IRIS² program requires a multi-orbital LEO and MEO architecture, creating demand for satellites with station-keeping and deorbit capability. The program provides the Europe space propulsion market with a source of institutional demand that is less exposed to commercial pricing cycles. Renewal of the Galileo and Copernicus fleets also adds demand that is tied to public missions. Larger constellation orders favor standardized, modular propulsion units over bespoke heritage designs. This shift requires established suppliers to reduce manufacturing costs and streamline certification processes while maintaining reliability. Safran's PPS5000 Hall thruster became a European alternative after the disruption of Russian SPT-140d supply accelerated domestic qualification efforts.[1]
Expansion of European Launch Capacity
The Ariane 6 program links European launch capacity directly to demand for large solid- and liquid-propulsion systems. Ariane 6 flight VA269 demonstrated the P160C-powered Ariane 64 configuration by deploying 36 Amazon LEO satellites and setting a European payload record. The flight also demonstrated a 10-15% performance uplift for LEO missions with the new booster configuration.[2] Scaling production requires investment in propellant mixing, carbon-fiber winding, and transportation capacity. These investments have long lead times, so suppliers need sustained institutional commitments before they can increase output. ArianeGroup's CNES contract for a next-generation liquid-oxygen-and-methane engine showed that Europe is scaling up existing launch systems while developing a successor architecture.[3]
Electric Propulsion Adoption for Mass and Cost Optimization
Electric propulsion can reduce the chemical propellant mass carried by a satellite, enabling more payload mass or lower-cost launch options. This value is increasingly relevant when operators procure propulsion for large satellite groups. SITAEL opened its Smart Space Factory 4 in Pisa in July 2025, featuring ISO-8 cleanrooms and a large space simulator for serial production of Hall-effect thrusters.[4] The CHEOPS VHP BB project delivered validated building blocks for 20 kW Hall-effect thrusters in February 2026, supporting applications in deep-space exploration and in-orbit servicing. Safran's PPS5000 also received krypton qualification through the INVICTUS project, which could ease rare-gas supply constraints and reduce propellant costs. Manufacturing scale, qualification capability, and propellant flexibility therefore affect the competitive position of suppliers in the Europe space propulsion market.
Growth of In-Orbit Mobility and End-of-Life Services
In-orbit servicing missions require repeated maneuvers, docking, attitude transfer, and re-boost operations that differ from conventional station-keeping missions. ESA signed a contract with ClearSpace in September 2026 to advance the Phoenix Partnership Project for commercial geostationary satellite servicing. Thales Alenia Space coordinates the EUR 12 million (USD 13.44 million) EROSS SC contract for a European automated rendezvous and robotic docking demonstration. The planned 2030 pilot mission makes high-restart, high-delta-V propulsion an important requirement for spacecraft suppliers. European propulsion firms can use in-orbit servicing programs to demonstrate systems that address relocation, life extension, and end-of-life disposal. The related production opportunity extends beyond thruster hardware to propellant management, power processing, and thermal-control equipment.
Restraints Impact Analysis of Europe Space Propulsion Market*
| RESTRAINT | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| High capital intensity and long development cycles | -0.90% | Global | Long term (≥ 4 years) |
| High qualification and reliability requirements | -0.80% | Global | Long term (≥ 4 years) |
| Propellant, export-control, and environmental compliance constraints | -0.70% | Europe, Global | Medium term (2-4 years) |
| Limited European launch cadence and fragmented procurement | -0.60% | Europe | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High Qualification and Reliability Requirements
European propulsion systems require environmental testing, materials verification, and failure-mode analysis before flight readiness. The process can span from initial design to qualification over 5 to 8 years, delaying the supply response to new demand. The constraint is acute for electric propulsion because iodine, krypton-fed, and air-breathing concepts can change before a test program is complete. The INVICTUS project used a delta-qualification approach to extend qualified systems to krypton without a complete new cycle. High-vacuum testing capacity is concentrated at national facilities such as DLR Lampoldshausen, ESTEC, and ONERA, which can create scheduling constraints. Propellant handling, export controls, and environmental requirements add further documentation and operating requirements for the Europe space propulsion market.
High Capital Intensity and Long Development Cycles
A flight-qualified liquid engine or large solid motor can require EUR 100 million (USD 112.10 million) to EUR 300 million (USD 336.50 million) and 8-12 years of development. This level of investment limits competition in heavy-lift and primary-stage propulsion. The concentration of production can create exposure when a major engine program faces disruption. ESA and DLR agreed in October 2025 to transfer Vinci upper-stage engine assembly to Lampoldshausen, reducing single-site dependency. Smaller electric propulsion firms also face non-recurring engineering costs when individual constellation programs require different interfaces, propellants, or vibration profiles. A limited launch cadence and fragmented procurement can therefore constrain revenue scale-up, even where technical demand is present.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Europe Space Propulsion Market Segment Analysis
By Propulsion:
Electric Propulsion Is Rising While Liquid Propulsion Anchors RevenueLiquid propulsion accounted for 51.22% of the Europe space propulsion market in 2025, supported by the high value of Ariane 6 main-stage and upper-stage systems. Vulcain 2.1 and Vinci engines remain important because they support European autonomous access to space. Bipropellant systems are used in launch vehicle main stages and satellite apogee engines. Monopropellant hydrazine thrusters remain relevant for attitude control on existing and mid-life satellite platforms. Solid propulsion also remains strategically important because the P120C and P160C support Ariane 6 and Vega-C programs. ArianeGroup and Avio renewed their Europropulsion agreement in November 2025 for production through 2029. The European space propulsion market, therefore, continues to rely on established liquid and solid systems for its launch architecture. These systems require mature production lines and formal qualification procedures. Their importance limits the speed at which alternative launch propulsion suppliers can enter the field.
Electric propulsion is forecast to grow at a 16.42% CAGR through 2031 as operators adopt Hall-effect and electrospray systems for station-keeping and disposal. Its lower propellant demand can reduce spacecraft mass and support broader launch options. ION-X raised EUR 13 million (USD 14.30 million) in December 2024 to industrialize electrospray thrusters and targeted 200 units per year by 2028. Hybrid propulsion remains at an earlier stage of commercial development but attracts interest for sovereign European manufacturing. HyPrSpace raised EUR 21 million (USD 22.89 million) in 2025 through the France 2030 funding program. The segment includes different technical approaches, so qualification progress and in-orbit performance remain important selection factors. Suppliers that can match standardized spacecraft interfaces may benefit as satellite programs increase procurement volumes. The move toward repeatable modules can favor companies that show stable production quality. It can also make component availability a central part of customer selection.

By Component:
Thrusters and Rocket Motors Lead While Feed Systems Scale With Electric PropulsionThrusters and rocket motors held 51.81% of revenue in 2025 because they are the primary value-adding hardware across propulsion types. The category includes large launch engines, solid motors, Hall-effect thrusters, and discharge chambers. The ArianeGroup RIT-2X gridded-ion thruster was developed through the GIESEPP MP program as a standardized plug-and-play unit. Standardized products can reduce the custom engineering burden for satellite integrators. They can also support repeat procurement for constellation programs. Large rocket motors retain high contract value due to their role in launch-vehicle propulsion. The component mix in the European space propulsion market, therefore, reflects both launch systems and the growing satellite propulsion base. Hardware suppliers must balance the needs of high-value launch programs with those of higher-volume satellite orders. The product mix changes as satellite builders seek parts that are simpler to integrate.
Propellant feed systems are forecast to grow at a 14.12% CAGR through 2031 as electric propulsion adopts xenon, krypton, and iodine configurations. Each propellant may require different pressure-control, storage, and flow-metering designs. This increases the importance of component reliability beyond the thruster itself. Power processing units also support electric propulsion by managing the electrical supply to the thruster. Thales Belgium's Mk3 power processing unit has been integrated with Hall thruster platforms in European consortium projects. Nozzles and thermal-control equipment remain closely tied to launch vehicle production requirements. Component suppliers can benefit by supporting multiple propulsion architectures rather than a single platform design. Feed-system design becomes more important as satellite operators consider several propellant options. Common interface requirements can also make it easier for integrators to qualify a component across programs.
By Platform:
Satellites Are the Fastest-Growing Propulsion ConsumerLaunch vehicles held 53.96% of platform revenue in 2025 because each vehicle combines high-value core-stage, upper-stage, and booster propulsion systems. Ariane 6 uses the Vulcain 2.1 core-stage engine and Vinci upper-stage engine, alongside up to 4.00 P160C boosters. This results in a propulsion bill measured in tens of millions of euros per launch vehicle. The platform also requires specialized manufacturing, testing, and integration facilities. These requirements support established suppliers with long-term institutional relationships. Ariane 6 production and launch performance, therefore, remain material to the European space propulsion market. A stable launch schedule supports planning across the engine, booster, and component supply chain. Any manufacturing delay can affect several propulsion suppliers simultaneously.
Satellites are forecast to grow at an 18.92% CAGR through 2031, even though each satellite propulsion system has a lower unit value than a launch vehicle system. IRIS², Galileo renewal, and other constellation programs may require many standardized propulsion modules simultaneously. Satellite operators need systems for station-keeping, collision avoidance, orbital transfer, and disposal. Spacecraft used for in-orbit servicing increase demand for higher-performance, repeatedly restartable thrusters. ESA's work with ClearSpace and Thales Alenia Space illustrates this requirement for servicing platforms. Other platforms include hybrid and sub-orbital concepts that could move into orbital applications over time. The platform shift is expanding demand for propulsion suppliers capable of serving both satellites and mission-specific spacecraft. Servicing missions require propulsion systems capable of operating over more complex maneuver profiles. Satellite programs, by contrast, place greater weight on repeat production and modularity.
By End User:
Commercial Demand Shapes the Largest and Fastest-Growing User BaseCommercial users held 62.63% of revenue in 2025 and are forecast to expand at a 16.52% CAGR through 2031. This profile reflects LEO constellation operators that require standardized, cost-conscious propulsion for station-keeping and collision avoidance. The commercial segment places greater emphasis on production repeatability and on-orbit evidence than on a single custom mission. It also encourages suppliers to reduce delivery time and unit cost. ION-X demonstrated its electrospray thruster in orbit on a Space Inventor satellite through the SpaceX Transporter-12 mission in January 2025. Such demonstrations can help satellite operators assess performance before larger orders. Commercial procurement is therefore changing the product and delivery expectations within the Europe space propulsion market. Suppliers face greater pressure to show flight heritage before large production awards. They also need to align output capacity with the constellation operators' order cadence.
Government and civil users remain important as anchor customers for technology programs and early procurement. ESA programs can share development costs and provide a route for companies to qualify new systems. Galileo, Copernicus, and national security missions also provide demand that is not wholly tied to commercial satellite economics. Military requirements are increasingly reflected in dual-use specifications for space domain awareness platforms. European calls for on-orbit operations and services have supported the development of related technologies. Government and civil buyers can support higher reliability thresholds and long program cycles. Their continued role helps suppliers fund systems that later serve commercial customers. The end-user structure, therefore, combines public support for development with commercial demand for scaled deployment. Civil procurement can bridge the gap between early development and commercial adoption. Military and dual-use requirements can reinforce the need for reliable, resilient spacecraft systems.
Geography Analysis
United Kingdom Space Propulsion Market
The UK held 35.17% of Europe space propulsion market share in 2025, supported by major integrators and a national focus on in-space propulsion. QinetiQ, Moog, and Reaction Engines contributed to the country's established technical base. Magdrive raised EUR 9.90 million (USD 10.79 million) in February 2025 to build a high-thrust electric propulsion manufacturing facility in the UK. The investment reflected interest in satellite propulsion and in-orbit servicing applications. The country's testing capability also supports qualification work for European customers. This creates a practical barrier for programs that would otherwise need to restart qualification at a different site. The United Kingdom, therefore, combines equipment development, test infrastructure, and supplier relationships.
France and Germany Space Propulsion Market
France is forecast to grow at a 16.63% CAGR through 2031, making it the fastest-growing national segment in the Europe space propulsion market. The Île-de-France and Toulouse ecosystem includes ThrustMe, ION-X, HyPrSpace, and Exotrail. France also supports the development of heavy liquid propulsion through ArianeGroup. ArianeGroup received a CNES contract in June 2025 to develop technologies for a next-generation very-high-thrust liquid-oxygen-and-methane engine. Germany supports both upper-stage production and propulsion development. Vinci assembly moved to DLR Lampoldshausen under an October 2025 agreement. TransMIT also passed an ESA design review in 2026 for an air-breathing electric propulsion thruster for very-low Earth orbit (VLEO).
Europe Space Propulsion Market
Italy and Spain play important supply-chain roles in the Europe space propulsion market. Avio produces P120C and P160C boosters at Colleferro and supplies primary propulsion for Vega-C. SITAEL's Pisa facility added serial production capability for Hall-effect thrusters in July 2025. Pangea Aerospace raised EUR 23 million (USD 25.07 million) in March 2025 to develop methane-oxygen propulsion in Spain. Sweden supports the production of Ariane 6 turbopump components through GKN Aerospace in Trollhättan. Austria's Enpulsion is moving from supplying Field-Effect Electric Propulsion thrusters toward broader space mobility systems. These secondary markets widen the European manufacturing base and reduce dependence on a limited number of national supply chains.
Competitive Landscape
The Europe space propulsion market is moderately consolidated in launch-vehicle propulsion, with ArianeGroup, Avio, and Safran forming an institutional supply base. Long development cycles, large test requirements, and established program relationships reinforce this position. ArianeGroup and Avio renewed a multi-year Europropulsion agreement in November 2025 to produce P120C and P160C boosters through 2029. This agreement also supports the production of Vulcain turbopumps for the Ariane 6 and Vega-C programs. Safran retains a role in Hall-effect propulsion through the PPS®5000. The leading launch suppliers use long-term supply arrangements and public research programs to preserve production continuity and technology capability.
Satellite electric propulsion is more fragmented, with suppliers offering Hall-effect, gridded-ion, electrospray, and hybrid products. ION-X, ThrustMe, Enpulsion, Exotrail, and other smaller firms compete in sub-kilowatt propulsion for CubeSats and small satellites. Startups can use in-orbit demonstrations to establish reliability before pursuing larger commercial orders. The market also includes firms developing lower-toxicity chemical systems for missions requiring high delta-V performance. CORDIS projects such as F4F, GIESEPP MP, and INVICTUS connect suppliers with European research and qualification programs. Krypton qualification can be a commercial advantage when constellation operators seek alternatives to xenon. The competitive landscape, therefore, combines a concentrated launch segment with a growing set of satellite propulsion specialists.
Strategic moves have centered on capacity, technology qualification, and mission demonstrations. SITAEL opened a serial-production facility for Hall-effect thrusters in Pisa in July 2025, strengthening European manufacturing capacity for electric propulsion. ArianeGroup's agreement with DLR moved Vinci assembly to Germany, reducing the concentration of production for an important upper-stage engine. Thales Alenia Space is coordinating the EROSS SC servicing project, which broadens the addressable mission set for high-performance propulsion. ESA's Zero Debris approach also increases the value of propulsion that enables satellite disposal. Suppliers that combine qualified hardware, scalable production, and proven flight performance are better placed to compete for constellation and servicing programs.
Europe Space Propulsion Industry Leaders
-
Airbus SE
-
Safran SA
-
Thales Alenia Space
-
Avio S.p.A.
-
ArianeGroup SAS
- *Disclaimer: Major Players sorted in no particular order
Europe Space Propulsion Market Companies Covered in this Report
- Airbus SE
- ArianeGroup SAS
- Safran SA
- Avio S.p.A.
- Thales Alenia Space
- OHB SE
- Exotrail
- SITAEL S.p.A.
- Moog Inc.
- Honeywell Aerospace Inc.
- Northrop Grumman Corporation
- L3Harris Technologies, Inc.
- Space Exploration Technologies Corp.
- QinetiQ Group plc
- Reaction Engines Limited
- Pangea Aerospace, SL
- Arkadia Aerospace Propulsion & Transportation Systems SL
- ION-X SAS
- ThrustMe
- Enpulsion GmbH
- ISPTech GmbH
Recent Industry Developments in Europe Space Propulsion Market
- September 2026: ESA signed a contract with ClearSpace to advance the Phoenix Partnership Project, maturing docking and propulsion technologies for a recurring commercial in-orbit servicing capability targeting GEO satellites for station-keeping extension, relocation, and end-of-life disposal.
- June 2026: The European Commission selected Thales Alenia Space to lead the EUR 12 million (USD 13.44 million) EROSS SC contract, covering 1 of 2 spacecraft for Europe's first automated rendezvous and robotic in-orbit servicing demonstration, with integration into the ISOS 2030 pilot mission planned.
- June 2026: Ariane 6 flight VA269 deployed 36 Amazon LEO satellites using the debut P160C-powered Ariane 64, setting a European launcher payload record and validating the new booster's 10-15% performance uplift for LEO.
- February 2026: The EU-funded CHEOPS VHP BB consortium concluded its 30-month program, delivering validated building blocks for 20 kW Hall-effect thrusters for deep-space exploration and large in-orbit servicing platforms, advancing European high-power electric propulsion industrialization.
Europe Space Propulsion Market Report Scope
The Europe space propulsion market comprises the regional industry involved in the design, manufacture, integration, testing, and maintenance of systems, engines, and components that accelerate and maneuver spacecraft, satellites, and launch vehicles in outer space. The market includes all hardware, software, and support services required to generate thrust, perform orbital maneuvers, control spacecraft attitude, and execute deep-space transfers.
The Europe space propulsion market is segmented by propulsion type, component, platform, end user, and geography. By propulsion type, the market is segmented into solid propulsion, liquid propulsion, hybrid propulsion, electric propulsion, and others. By component, the market is segmented into thrusters and rocket motor, propellant feed systems, power processing units, nozzles, propulsion thermal-control systems, and others. By platform, the market is segmented into satellites, launch vehicles, spacecraft, and others. By end user, the market is segmented into commercial, government and civil, and military. The report also covers the market sizes and forecasts for the Europe space propulsion market in seven countries across the region. For each segment, the market size is provided in terms of value (USD).
Segmentation Overview
| Solid Propulsion | |
| Liquid Propulsion | Monopropellant |
| Bipropellant | |
| Hybrid Propulsion | |
| Electric Propulsion | Hall-Effect Thrusters |
| Gridded Ion Thrusters | |
| Electrospray Thrusters | |
| Pulsed Plasma Thrusters | |
| Magnetoplasmadynamic Thrusters | |
| Others |
| Thrusters and Rocket Motor |
| Propellant Feed Systems |
| Power Processing Units |
| Nozzles |
| Propulsion Thermal-Control Systems |
| Others |
| Satellites |
| Launch Vehicles |
| Spacecraft |
| Others |
| Commercial |
| Government and Civil |
| Military |
| United Kingdom |
| France |
| Germany |
| Italy |
| Spain |
| Sweden |
| Russia |
| Rest of Europe |
| By Propulsion Type | Solid Propulsion | |
| Liquid Propulsion | Monopropellant | |
| Bipropellant | ||
| Hybrid Propulsion | ||
| Electric Propulsion | Hall-Effect Thrusters | |
| Gridded Ion Thrusters | ||
| Electrospray Thrusters | ||
| Pulsed Plasma Thrusters | ||
| Magnetoplasmadynamic Thrusters | ||
| Others | ||
| By Component | Thrusters and Rocket Motor | |
| Propellant Feed Systems | ||
| Power Processing Units | ||
| Nozzles | ||
| Propulsion Thermal-Control Systems | ||
| Others | ||
| By Platform | Satellites | |
| Launch Vehicles | ||
| Spacecraft | ||
| Others | ||
| By End User | Commercial | |
| Government and Civil | ||
| Military | ||
| By Geography | United Kingdom | |
| France | ||
| Germany | ||
| Italy | ||
| Spain | ||
| Sweden | ||
| Russia | ||
| Rest of Europe | ||
Market Definition
- Application - Various applications or purposes of the satellites are classified into communication, earth observation, space observation, navigation, and others. The purposes listed are those self-reported by the satellite’s operator.
- End User - The primary users or end users of the satellite is described as civil (academic, amateur), commercial, government (meteorological, scientific, etc.), military. Satellites can be multi-use, for both commercial and military applications.
- Launch Vehicle MTOW - The launch vehicle MTOW (maximum take-off weight) means the maximum weight of the launch vehicle during take-off, including the weight of payload, equipment and fuel.
- Orbit Class - The satellite orbits are divided into three broad classes namely GEO, LEO, and MEO. Satellites in elliptical orbits have apogees and perigees that differ significantly from each other and categorized satellite orbits with eccentricity 0.14 and higher as elliptical.
- Propulsion tech - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Mass - Under this segment, different types of satellite propulsion systems have been classified as electric, liquid-fuel and gas-based propulsion systems.
- Satellite Subsystem - All the components and subsystems which includes propellants, buses, solar panels, other hardware of satellites are included under this segment.
| Keyword | Definition |
|---|---|
| Attitude Control | The orientation of the satellite relative to the Earth and the sun. |
| INTELSAT | The International Telecommunications Satellite Organization operates a network of satellites for international transmission. |
| Geostationary Earth Orbit (GEO) | Geostationary satellites in Earth orbit 35,786 km (22,282 mi) above the equator in the same direction and at the same speed as the earth rotates on its axis, making them appear fixed in the sky. |
| Low Earth Orbit (LEO) | Low Earth Orbit satellites orbit from 160-2000km above the earth, take approximately 1.5 hours for a full orbit and only cover a portion of the earth’s surface. |
| Medium Earth Orbit (MEO) | MEO satellites are located above LEO and below GEO satellites and typically travel in an elliptical orbit over the North and South Pole or in an equatorial orbit. |
| Very Small Aperture Terminal (VSAT) | Very Small Aperture Terminal is an antenna that is typically less than 3 meters in diameter |
| CubeSat | CubeSat is a class of miniature satellites based on a form factor consisting of 10 cm cubes. CubeSats weigh no more than 2 kg per unit and typically use commercially available components for their construction and electronics. |
| Small Satellite Launch Vehicles (SSLVs) | Small Satellite Launch Vehicle (SSLV) is a three-stage Launch Vehicle configured with three Solid Propulsion Stages and a liquid propulsion-based Velocity Trimming Module (VTM) as a terminal stage |
| Space Mining | Asteroid mining is the hypothesis of extracting material from asteroids and other asteroids, including near-Earth objects. |
| Nano Satellites | Nanosatellites are loosely defined as any satellite weighing less than 10 kilograms. |
| Automatic Identification System (AIS) | Automatic identification system (AIS) is an automatic tracking system used to identify and locate ships by exchanging electronic data with other nearby ships, AIS base stations, and satellites. Satellite AIS (S-AIS) is the term used to describe when a satellite is used to detect AIS signatures. |
| Reusable launch vehicles (RLVs) | Reusable launch vehicle (RLV) means a launch vehicle that is designed to return to Earth substantially intact and therefore may be launched more than one time or that contains vehicle stages that may be recovered by a launch operator for future use in the operation of a substantially similar launch vehicle. |
| Apogee | The point in an elliptical satellite orbit which is farthest from the surface of the earth. Geosynchronous satellites which maintain circular orbits around the earth are first launched into highly elliptical orbits with apogees of 22,237 miles. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. For sales conversion to volume, the average selling price (ASP) is kept constant throughout the forecast period for each country, and inflation is not a part of the pricing.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


