
Continuous Glucose Monitoring (CGM) Market Analysis by Mordor Intelligence
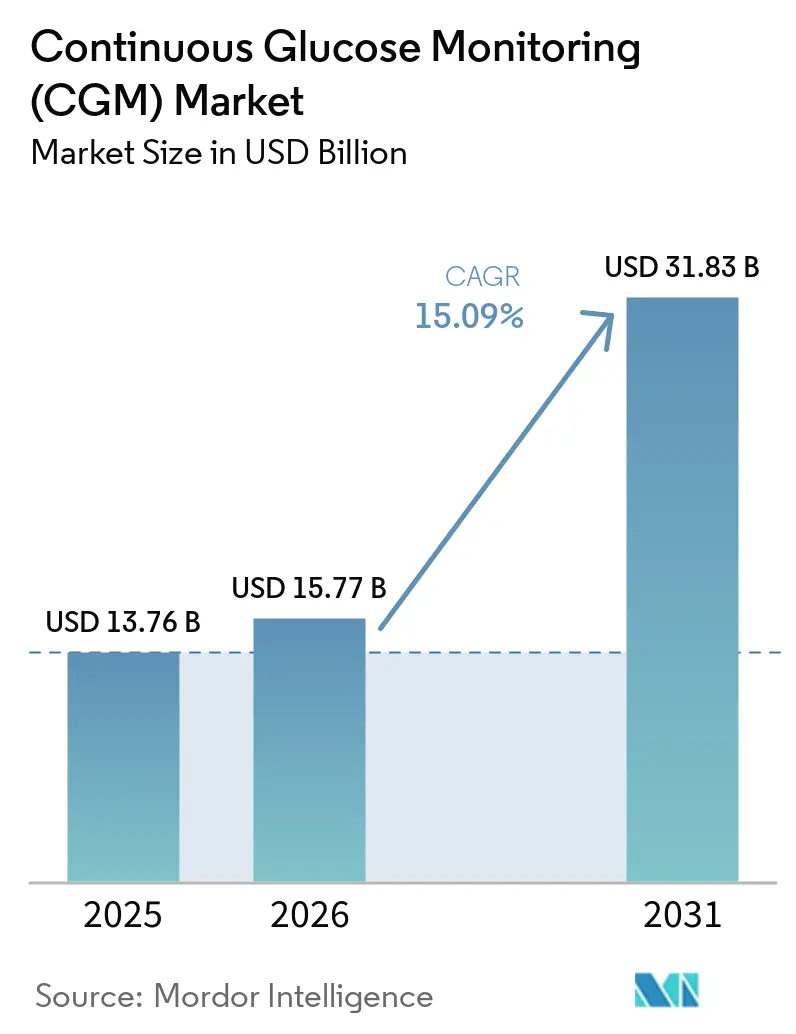
The continuous glucose monitoring (CGM) market size is estimated at USD 18.15 billion in 2026 and is projected to be USD 20.89 billion in 2027, reaching USD 42.18 billion by 2032, growing at a CAGR of 15.09% from 2027 to 2032.
Clinical guidance recommending CGM at diagnosis for people who could benefit and Medicare funding for eligible users support sensor demand in the United States. Longer wear and alternative device formats give manufacturers ways to serve personal monitoring and integrated insulin-delivery needs. Cost-related nonuse and alarm burden can prevent initiation or interrupt wear, constraining conversion of eligibility into demand. Broader access and longer wear support growth despite these barriers, but U.S. suppliers turn covered prescriptions into repeat sensor orders only through continued patient use.
Key Report Takeaways
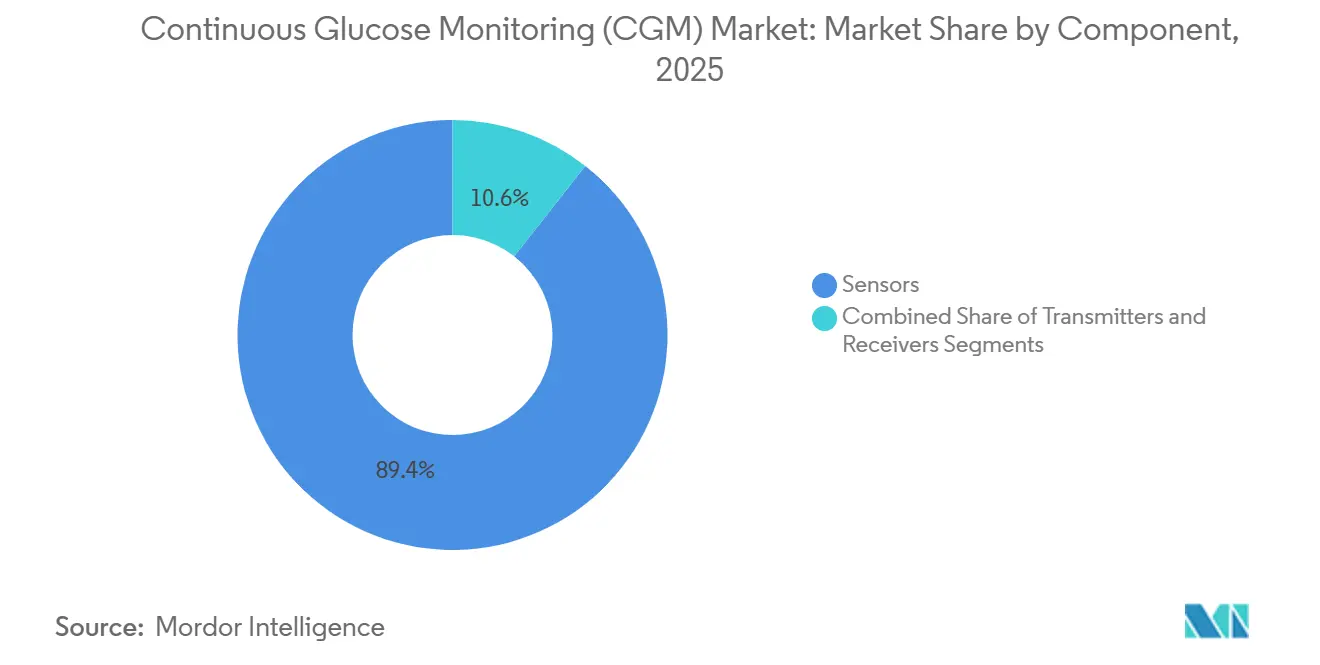
- By component, sensors led with 89.35% of revenue in 2026 and are also the fastest-growing segment, with a projected CAGR of 15.36% from 2027 to 2032.
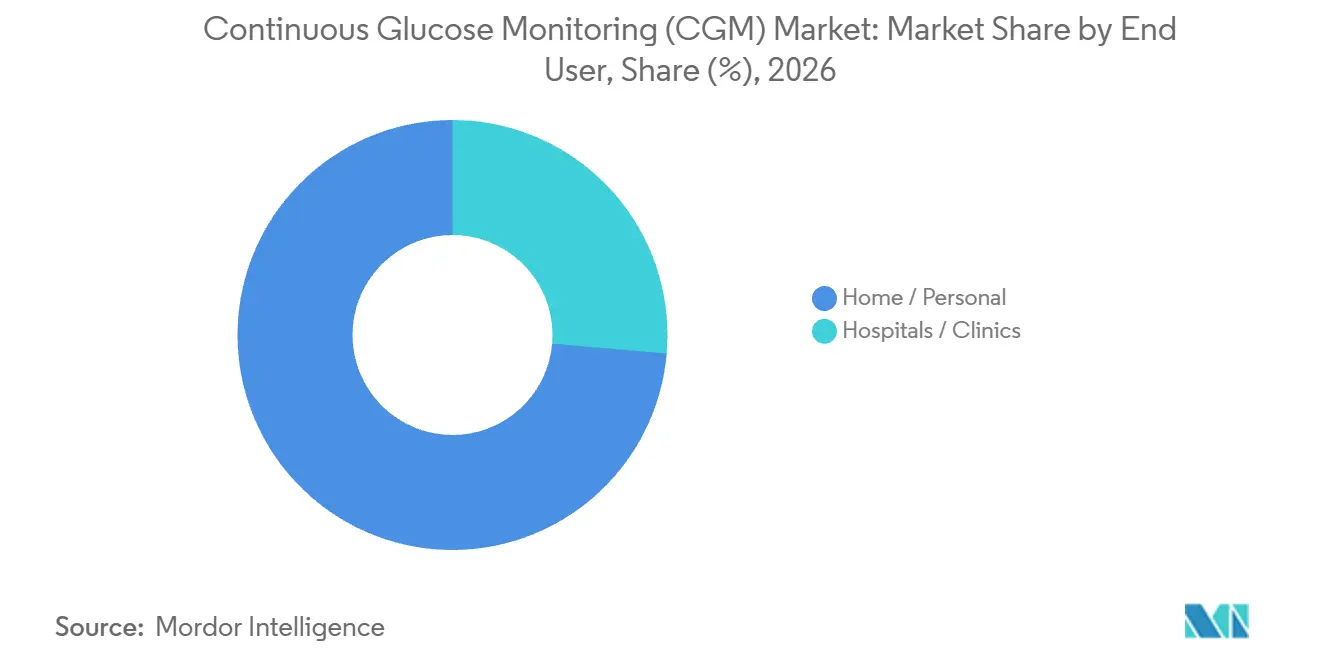
- Home and personal use led the end-user category with a 73.62% continuous glucose monitoring (CGM) market share in 2026, while hospitals and clinics are projected to grow fastest at a CAGR of 18.05% from 2027 to 2032.
- Across demographics, adults accounted for a 65.35% share of the continuous glucose monitoring (CGM) market size in 2026, while pediatric use is projected to grow fastest at a CAGR of 17.85% from 2027 to 2032.
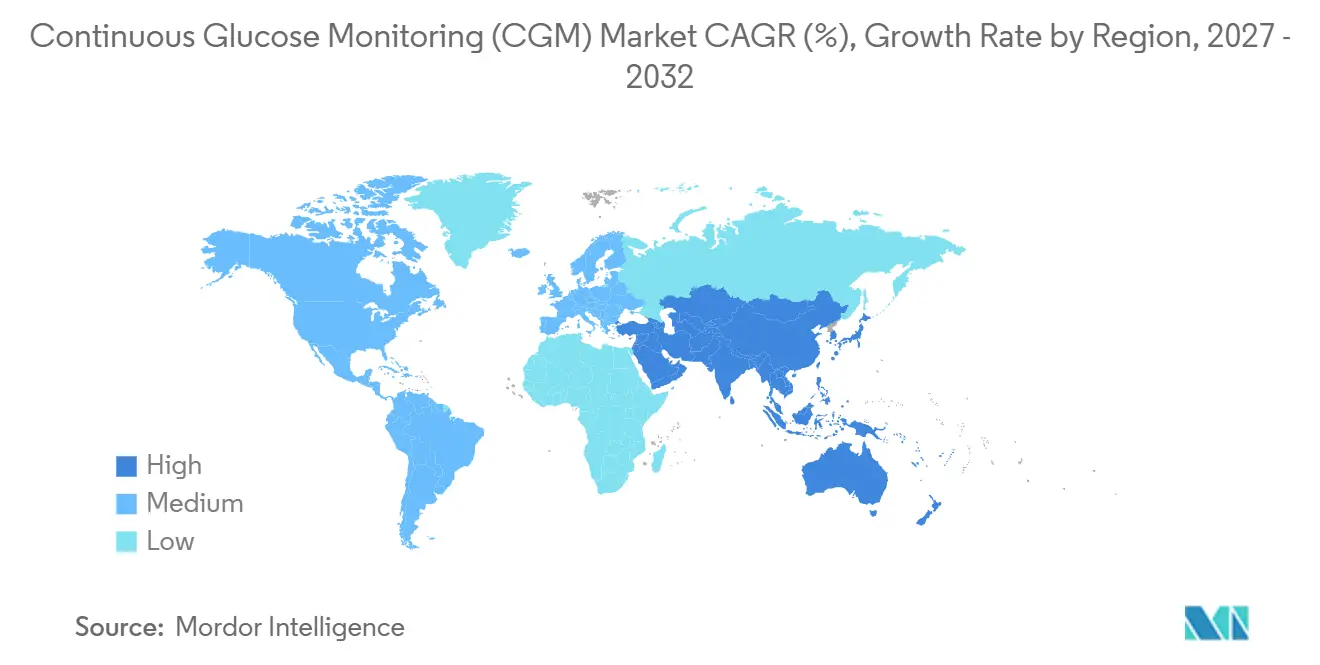
- Geographically, North America led with 50.55% of revenue in 2026, while Asia-Pacific is projected to grow fastest at a CAGR of 15.78% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Continuous Glucose Monitoring (CGM) Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Prevalence of Diabetes and Earlier Diagnosis | +6.2% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Rapid Uptake of Remote Monitoring and Tele-Health Integration | +2.5% | Across the United States | Medium term (2-4 years) |
| Sensor Miniaturization and Accuracy Breakthroughs | +4.2% | Across the United States | Short term (≤ 2 years) |
| Favorable Reimbursement Expansion in OECD & China | +5.6% | Across the United States | Medium term (2-4 years) |
| Consumer-Wellness Expansion Beyond Diagnosed Diabetes | +1% | United States and United Kingdom | Medium term (2-4 years) |
| Subscription Pricing Potentially Lowering LMIC Entry Barriers | +0.5% | Across all of India | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising Prevalence of Diabetes and Earlier Diagnosis
Diagnosis can bring CGM into the care pathway earlier when the patient has a monitoring need that the technology can address. The International Diabetes Federation projects that the global number of adults with diabetes will reach 853 million by 2050. The American Diabetes Association's 2026 Standards of Care recommend CGM at diabetes onset and thereafter for people who could benefit from it in diabetes management.[1] The projection describes a larger prospective patient pool, while the recommendation gives clinicians an entry point for monitoring within diabetes care. For clinicians following that guidance, selecting CGM can become part of the initial treatment decision for an eligible newly diagnosed patient.
Rapid Uptake of Remote Monitoring and Tele-Health Integration
Telehealth integration can support repeat CGM demand by making coverage follow-up possible without an exclusively in-person care pathway. Medicare requires the treating practitioner to conduct an in-person or Medicare-approved telehealth visit every 6 months after the initial CGM prescription to document adherence to the CGM regimen and diabetes treatment plan. The documentation requirement ties continued coverage to a clinical assessment beyond the initial prescription. A remote visit preserves that assessment while allowing the beneficiary to complete it without an office trip. A patient who cannot readily attend a clinic can therefore meet the review requirement remotely and retain a route to covered sensor refills.
Sensor Miniaturization and Accuracy Breakthroughs
Fewer sensor changes can make sustained CGM use more manageable for eligible adults, strengthening the case for adoption. In 2025, Dexcom Inc. launched G7 15 Day in the United States with a new algorithm that the company described as delivering its best sensor accuracy to date. The FDA cleared the modification on April 9, 2025, extending wear to 15 days for users aged 18 and older. Dexcom attributed fewer sensor changes to the longer wear period, giving users a practical benefit alongside the new algorithm. The 18-and-older clearance directs this usability proposition toward adult adoption, giving suppliers a defined population for the longer-wear product.
Favorable Reimbursement Expansion in OECD & China
Public reimbursement supports CGM demand by defining a patient group whose devices and continuing supplies qualify for coverage. Medicare Part B covers CGMs, sensors and transmitters when the prescription follows FDA indications and the patient uses insulin or has a history of problematic hypoglycemia. Eligibility also requires a doctor visit within 6 months of ordering to evaluate diabetes control and confirm the coverage criteria. From May 1, 2025, Saskatchewan provided full coverage of continuous and flash glucose monitors for eligible insulin-treated adults aged 18 to 25 and 65 and older. The Canadian expansion targets specified adult cohorts, while Medicare illustrates how coverage extends to continuing supplies. Converting this funding into device demand therefore starts with documenting the eligible patient and the indicated prescription.
Restraints Impact Analysis of Continuous Glucose Monitoring (CGM) Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Device and Consumable Costs for Payers And Patients | -2.3% | Across the United States | Short term (≤ 2 years) |
| Calibration / Data-Overload Usability Concerns | -1.5% | Los Angeles County, California | Short term (≤ 2 years) |
| GLP-1 Weight-Loss Drugs Potentially Reducing Glucose Testing Frequency | -0.7% | North America and Europe | Long term (≥ 4 years) |
| Cyber-Security and Data-Privacy Vulnerabilities | -0.4% | Across the United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Device and Consumable Costs for Payers And Patients
A prescription does not become a CGM purchase when coverage denial leaves the patient unable to pay. An April 2025 report by the American Diabetes Association and NORC described a U.S. Medicaid focus-group participant who could not afford a prescribed CGM after insurance denied coverage and continued traditional blood glucose monitoring. This experience places reimbursement between clinical intent and the supplier's ability to convert that intent into device demand. For patients facing the same financial constraint, a recommendation alone cannot resolve the affordability gap that prevents use. The commercial limit is therefore an unfilled prescription, with the monitoring benefit contingent on financing the patient can actually access.
Calibration / Data-Overload Usability Concerns
Excess glucose information can constrain both initial CGM acceptance and the willingness to continue wearing a device. A survey at one Los Angeles County federally qualified health center from November 2023 to February 2025 found 31.3% of 16 never-users declining clinician-recommended CGM did not want excess glucose information. Among 18 former users answering the discontinuation question, 50% cited too many alarm notifications as a reason for stopping.[2] These findings identify separate commercial losses, since reluctance can prevent a first purchase while alarm burden can interrupt continued demand. More frequent information can therefore become a usability cost that weakens the case for sustained wear among patients with these concerns.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Continuous Glucose Monitoring (CGM) Market Segment Analysis
By Component:
Funded Sensor Access Supports Recurring DemandSensors held 89.35% of revenue in 2026 and are the largest and fastest-growing segment, with a projected CAGR of 15.36% from 2027 to 2032. In January 2026, Abbott Laboratories reported public-program funding for its FreeStyle Libre 3 Plus sensor in every Canadian province, subject to eligibility and program terms.[3] This gives the sensor business a geographically broad route to publicly financed demand within Canada. The commercial mechanism depends on qualifying patients reaching the funded product through their respective programs. Abbott's public-program reach in every Canadian province gives rival sensor suppliers a reimbursement benchmark alongside device performance.
Transmitters fall within Medicare's supply allowance for adjunctive CGMs, where CMS includes sensors and transmitters and denies separate billing as unbundling. That treatment makes the supplied system's reimbursement economics more relevant than a separate transmitter billing opportunity for this patient group. Receivers have a distinct coverage role because Medicare covers the CGM supply allowance only when the beneficiary uses a durable medical equipment receiver or insulin infusion pump to display glucose data, although a non-DME device may also be used alongside it. These rules make the covered display pathway and the bundled supply allowance important to commercial participation, preserving hardware roles that a smartphone-only view of monitoring would overlook.

By End User:
Personal Scale Meets Institutional AdoptionHome and personal use accounted for a 73.62% share of the continuous glucose monitoring (CGM) market size in 2026, making it the largest segment. Separately, Abbott Laboratories reported in September 2026 that more than 8 million people across over 60 countries used its Libre portfolio. Abbott's U.S. FreeStyle Libre setup instructions say the sensor should be removed or replaced after 15 days. Each replacement cycle turns continued personal monitoring into demand for another sensor, giving the supplier an opportunity for repeat sales beyond the initial device purchase.
Hospitals and clinics form the fastest-growing segment, with a projected CAGR of 18.05% from 2027 to 2032. Spring Grove Hospital Center's May 2025 policy directed staff to use Dexcom G7 for eligible patients with diabetes and to follow manufacturer guidance and hospital protocols. It assigned supply ordering to the clinic RN manager or designee, with a purchase request submitted to the Finance Department. The policy shows one state hospital placing CGM inside a defined clinical and purchasing workflow, with named responsibility for ordering supplies.
By Demography:
Adult Scale Meets Caregiver-Supported AccessAdult users represented a 65.35% continuous glucose monitoring (CGM) market share in 2026, making adults the largest segment. The American Diabetes Association's 2026 Standards recommend CGM for older adults with type 1 diabetes and older adults with type 2 diabetes on insulin, with evidence grades A and B, respectively. The recommendation targets improved glycemic outcomes, reduced hypoglycemia and lower treatment burden, connecting monitoring to specific care needs in these older cohorts. The type 2 recommendation's insulin condition makes treatment regimen a more precise basis for targeting older adult users than age alone.
The pediatric segment is the fastest-growing segment, with a projected CAGR of 17.85% from 2027 to 2032. On June 12, 2026, the FDA cleared Dexcom's Stelo integrated CGM for over-the-counter use by people aged 2 and older who do not use insulin. Children must use it under adult caregiver supervision, and the system is not intended for people with problematic hypoglycemia or people on dialysis. Nonprescription availability changes the access route by allowing eligible families to obtain the system without a prescription. The supervising caregiver is a necessary participant for suppliers to reach, even when the child is the wearer.
Geography Analysis
North America Continuous Glucose Monitoring (CGM) Market
North America held a 50.55% continuous glucose monitoring (CGM) market share in 2026, making it the largest geography. Dexcom Inc. generated USD 3.33 billion in U.S. CGM-system revenue in 2025, with U.S. revenue growing 15% year over year. Its U.S. distributor revenue substantially exceeded its direct-channel revenue in 2025, placing intermediaries at the center of the company's sales model in the country. In the United States, this established sales base makes channel execution commercially consequential, since a large operating business already connects monitoring systems with buyers through both routes.
Asia-Pacific Continuous Glucose Monitoring (CGM) Market
Asia-Pacific is the fastest-growing geography, with a projected CAGR of 15.78% from 2027 to 2032. In 2025, MicroTech Medical reported adding registrations and market access for its LinX continuous glucose monitoring system in India. Separately, India's Central Government Health Scheme classifies 2-week CGM as a laboratory investigation in its revised rate schedule effective October 13, 2025, applying to services at empaneled providers and to reimbursement claims by eligible beneficiaries. The schedule gives eligible beneficiaries a payer pathway for provider-delivered monitoring alongside the product registrations. Device suppliers can pursue sales through added product access, while empaneled providers can earn service revenue from eligible monitoring episodes.
Europe's public-access route is illustrated by United Kingdom NHS guidance that CGM should be available to anyone with type 1 diabetes, with children usually offered real-time systems and adults a real-time or flash choice. Middle East and Africa also contains public procurement routes, illustrated by Bahrain's 2025 tender for 2-year CGM supply and installation, with 6 bids recorded at opening. In South America, Brazil's Conitec held a consultation on real-time CGM for type 1 diabetes for SUS coverage, which closed on August 17, 2026. That assessment places the public-coverage decision between clinical need and a potential purchasing route. Suppliers face different commercial tasks in these examples, serving eligible NHS users, competing for Bahrain's tender or awaiting Brazil's coverage decision.
Regulatory Framework and Outlook
This comparison of selected jurisdictions assesses policy attractiveness from the perspective of a CGM manufacturer seeking commercial market access. United States special controls for Class II integrated CGM (iCGM) systems require accuracy evidence, secure data-transmission validation and manufacturing controls that ensure performance specifications are met. The United States Quality Management System Regulation (QMSR), effective February 2, 2026, incorporates ISO 13485:2016 for covered device manufacturers. The commercial comparison therefore turns on the evidence, quality systems and authorization steps attached to the supplier's particular product.
Regulatory Table of Continuous Glucose Monitoring (CGM) Market
| Decision factor | United States | Germany | China | Saudi Arabia | Brazil |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | Federal state authorities (Landesbehörden) | National Medical Products Administration | Saudi Food and Drug Authority | Anvisa |
| Key instruments or direction | 21 CFR 862.1355; QMSR effective February 2026; proposed FY 2028-2032 review goals | EUDAMED implementation; pending December 2025 EU revision | Registration and Filing Provisions; revised GMP effective November 1, 2026 | Medical-device marketing authorization rules | RDC 751/2022; 2026-2027 regulatory agenda |
| Commercial effect | iCGM validation and production controls; applicable device quality-system duties | 4 mandatory EUDAMED modules from May 28, 2026 | National review of domestic Class III and imported Class II and III devices | Registration and authorization before commercial trade, subject to specified exceptions | Registration for devices classified in Classes III and IV |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Easing | Easing | Hardening | No change | No change |
| Source: Mordor Intelligence | |||||
United States iCGM validation and quality-system duties and the EU's mandatory EUDAMED modules, which apply in Germany, support medium ratings, while proposed FY 2028-2032 United States review goals and the EU's pending December 2025 burden-reduction proposal support easing subject to further legislation. China's registration and lifecycle quality duties underpin medium attractiveness, with strengthened medical-device good manufacturing practice (GMP) requirements effective November 1, 2026 supporting hardening. Brazil's medium rating reflects class-based registration under RDC 751/2022, and the planned 2026-2027 review of separate SaMD rules supports continuity for sensor-hardware entry because agenda work leaves that class-based route operative. Saudi Arabia's medium rating reflects a premarket gate with specified exceptions, and the SFDA's August 2026 dual glucose-ketone authorization supports continuity because the innovation pathway operates within that requirement.
Value Chain Stages
The value chain compares device manufacturing, system integration and distribution as distinct sources of supplier earnings. Abbott Laboratories manufactures Libre portfolio products in Kilkenny, Ireland. Medtronic plc, whose diabetes business is now MiniMed Group, Inc., announced a February 2026 European launch pairing Simplera sensor and InPen smart insulin pen data in one app. These roles place value in making and integrating the monitoring product, while downstream earnings depend on a functioning distribution route.
Value Chain Analysis Table of Continuous Glucose Monitoring (CGM) Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Device manufacturing | CGM product manufacturers such as Abbott Laboratories | Product sales | Maintaining consistent device output | Validate production processes before expanding output |
| System integration | Diabetes-system integrators such as Medtronic plc | Integrated-system sales | Coordinating sensor, pen and app data | Validate the combined data pathway |
| Distribution and patient supply | U.S. wholesalers such as Cencora and DME suppliers such as AdaptHealth Diabetes and Edgepark Medical Supplies | Wholesale and device-supply sales | Dependence on a functioning authorized supply route | Maintain direct and authorized wholesale routes |
| Source: Mordor Intelligence | ||||
Abbott identified contracted U.S. DME suppliers as direct purchasers in May 2026, alongside its separate authorized wholesale routes. That distinction gives distribution resilience a concrete basis, because direct supplier relationships and wholesale access offer different routes to the product. Medtronic's February 2026 announcement, for what is now MiniMed's diabetes business, specified a gradual European rollout of the combined sensor, pen and app system, so downstream sales require access to the complete configuration as it becomes available.
Competitive Landscape
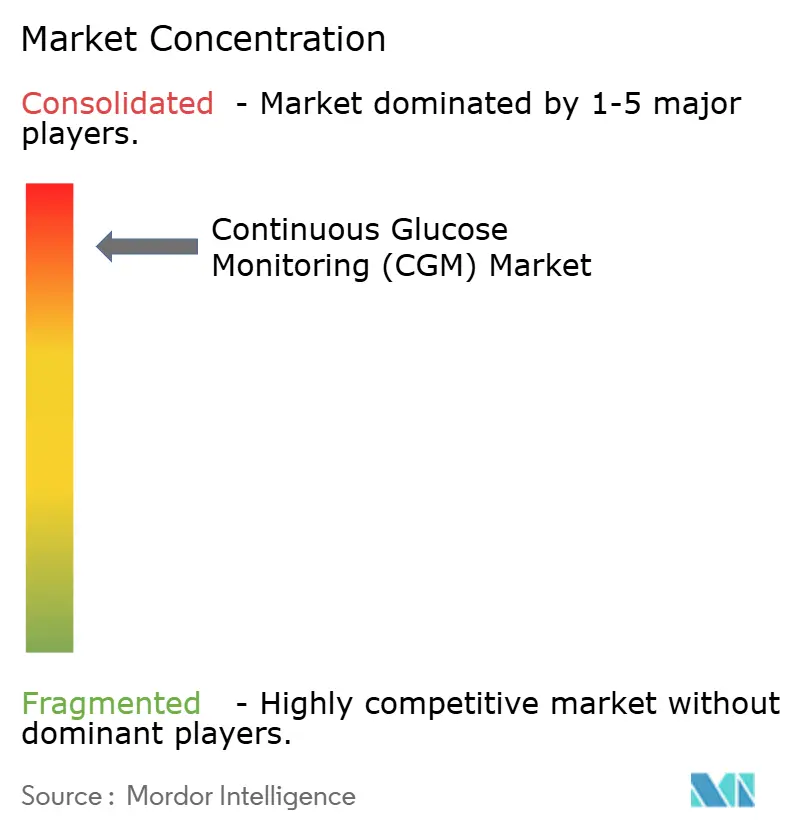
The supplier base is moderately concentrated around MiniMed Group, Inc. (the former Medtronic plc diabetes business, separated on October 15, 2026), Dexcom Inc., Abbott Laboratories, Senseonics Holdings Inc. and F. Hoffmann-La Roche Ltd. Dexcom reported company revenue of USD 4.66 billion in 2025 and approximately 3.5 million global users, excluding Stelo. Abbott participates through its Diabetes Care CGM business, while Senseonics develops, manufactures and commercializes implantable CGM systems. Senseonics reported 2025 company revenue of USD 35.3 million, up approximately 57% from 2024, so its implantable offering combines rapid company growth with a much smaller revenue base than Dexcom's.
In April 2025, Medtronic, whose diabetes business became independent as MiniMed Group, Inc., received FDA approval for Simplera Sync use with MiniMed 780G, adding a sensor option alongside Guardian 4 within that insulin-delivery system. This strategy gives MiniMed 780G users another approved sensor choice within the same insulin-delivery platform. Senseonics' implantable CGM approach offers a different format, directing competition toward how monitoring is delivered as well as the sensing technology itself. For a MiniMed 780G user, sensor choice sits within an approved insulin-delivery configuration, so the pump platform rather than the sensor alone frames the purchase.
In November 2025, Roche reported Accu-Chek SmartGuide availability in Kuwait, Qatar and Saudi Arabia, establishing commercial access in those named markets. Senseonics reported Eversense 365 availability to the first patients in Sweden in April 2026, following CE Mark approval in January. These entries show how competing formats can reach buyers through different national commercial openings. Regulatory positioning matters at the product level, while country availability determines where that positioning can become an actual buyer choice. A challenger seeking those buyers must establish local availability for its own authorized product before format differentiation can translate into sales.
Continuous Glucose Monitoring (CGM) Industry Leaders
-
Medtronic plc
-
Dexcom Inc.
-
Abbott Laboratories
-
Senseonics Holdings Inc.
-
F. Hoffmann-La Roche Ltd
- *Disclaimer: Major Players sorted in no particular order
Continuous Glucose Monitoring (CGM) Market Companies Covered in this Report
- Abbott Laboratories
- Medtronic
- Dexcom
- Senseonics
- Roche
- A. Menarini Diagnostics S.r.l.
- I-Sens
- Medtrum Technologies Inc.
- Nemaura Medical Inc.
- Zhejiang POCTech Co., Ltd.
- MicroTech Medical
Read Analysis of Continuous Glucose Monitoring (CGM) Companies
Key Opportunities for Market Participants
The opportunities compare newly covered clinical users with adults reachable through an expanded consumer app channel. Effective January 1, 2026, Maryland Medicaid expanded medically necessary CGM coverage to specified insulin-treated type 1 or type 2 patients, gestational-diabetes participants and people with problematic hypoglycemic events. Initial eligibility also requires a diagnosis, practitioner-confirmed training, an FDA-indicated prescription and the specified medical criteria. Separately, Abbott Laboratories made Lingo available on Android in the United States and United Kingdom in December 2025 for adults aged 18 and older who are not on insulin, with a non-diagnostic intended use.
Market Opportunities Table of Continuous Glucose Monitoring (CGM) Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Serve newly eligible insulin-treated participants | Expanded Maryland Medicaid coverage effective January 2026 | Qualifying participants with type 1 or type 2 diabetes | Link indicated devices to documented eligibility and training | Practitioner-confirmed training and qualification documentation | Eligible CGM suppliers and prescribing practices |
| Build a gestational-diabetes CGM care pathway | Gestational diabetes included in the 2026 Maryland expansion | Medically eligible pregnant Medicaid participants | Coordinate prescription, training and supply initiation | Establishing medical necessity and completing initial requirements | CGM suppliers and maternal diabetes care teams |
| Reach eligible Android consumer users | Lingo Android access added in December 2025 | Adults aged 18 and older, not on insulin, in the United States and United Kingdom | Develop consumer guidance within Lingo's non-diagnostic intended use | Maintaining product positioning within its intended use | Abbott Laboratories and consumer CGM channels |
| Source: Mordor Intelligence | |||||
The clinical opening turns on completing a qualified care pathway for patient groups that gained access through the Maryland expansion. Suppliers and care teams can therefore develop different onboarding approaches for insulin-treated and gestational-diabetes participants while preserving the same initial coverage requirements. The consumer opportunity requires a different proposition, since Lingo's intended use centers on eligible adults' information needs rather than diagnosis.
Recent Industry Developments in Continuous Glucose Monitoring (CGM) Market
- Oct 2026: Medtronic completed the separation of MiniMed Group, Inc., its diabetes business, which became an independent company with no Medtronic equity stake.
- Aug 2026: Abbott Laboratories received U.S. FDA authorization for Libre Duo 10 Day, a wearable that continuously monitors glucose and helps detect rising ketone levels. The system is intended for people with diabetes aged 2 and older and offers up to 10 days of wear.
- Jun 2026: The FDA cleared Dexcom Inc.'s Stelo integrated CGM for over-the-counter use by people aged 2 and older who do not use insulin. Children must use it under adult caregiver supervision, and the system is not intended for people with problematic hypoglycemia or people on dialysis.
Continuous Glucose Monitoring (CGM) Market Report Scope and Research Methodology
Market Definition and Coverage
The continuous glucose monitoring (CGM) market measures annual spending on CGM devices and device components sold globally for continuous glucose measurement and diabetes management. Sales are classified across hospitals and clinics and home or personal use, adults and children, and North America, Europe, Asia-Pacific, the Middle East and Africa, and South America.
Scope exclusions: Blood glucose meters and test strips, insulin pumps and other diabetes treatment devices, standalone CGM software, data subscriptions and telehealth services, and upstream sensor materials and manufacturing inputs are excluded.
Segments Covered in This Report
- By Component
- Sensors
- Transmitters
- Receivers
- By End User
- Hospitals / Clinics
- Home / Personal
- By Demography
- Adult
- Pediatric
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- Japan
- South Korea
- China
- India
- Australia
- Vietnam
- Malaysia
- Indonesia
- Philippines
- Thailand
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- Iran
- Egypt
- Oman
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the World Health Organization, which provides diabetes prevalence and care context for sizing the potential user base, and the U.S. Food and Drug Administration, which describes CGM device characteristics and regulatory classifications, anchor the demand side. The American Diabetes Association's Standards of Care inform clinical adoption assumptions, and Medicare's coverage rules help analysts assess reimbursement eligibility and supply demand.
Company annual reports, investor materials and reputable press coverage can cross-check reported product revenue, geographic activity, launches and supply arrangements against epidemiology, policy and regulatory evidence. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would target CGM manufacturers, distributors, diabetes care providers, reimbursement specialists and procurement leaders, with questions matched to their role in device sales, component replacement, access and use. Their input would test secondary evidence on adoption, replacement cycles, realized pricing, channel mix and regional access, and would test device-sales assumptions against adjacent diabetes spending. Analysts would reconcile conflicting responses with company disclosures, policy evidence and independent market signals, document the treatment of unresolved gaps, and triangulate each material assumption before incorporating it into the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 25% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The model estimates global annual manufacturer sales of CGM systems and separately sold replacement components, then checks the total through selected supplier revenue roll-ups and sampled average selling price times unit volume where disclosures support those checks. A top-down view starts with the addressable population and applies diagnosed diabetes prevalence, clinical eligibility and reimbursement access, CGM adoption, sensor wear and replacement frequency, and component or system pricing to estimate spending, while shipment and channel evidence tests whether the implied sales level is plausible. Analysts build component, end-user, demographic and regional shares from reported product mix, care setting, age eligibility, coverage and country-level access evidence, then reconcile those shares to the global total. Scenario analysis carries forward changes in diabetes prevalence, coverage, adoption, replacement frequency and prices, while primary-research respondents check the role and direction of these variables rather than substitute unsupported point estimates. Where supplier, price or unit evidence is incomplete, analysts use the best supported market-level indicators, retain explicit assumptions for review and avoid filling gaps with unsupported product or country detail.
Data Validation & Update Cycle
Analysts triangulate company disclosures, epidemiology, reimbursement and regulatory signals, and channel or procurement evidence, then investigate variances in growth, mix, pricing and geographic shares before sign-off. A second review checks source dates, units, boundaries, calculations and consistency across segments, with re-contact triggered when a material assumption conflicts with respondent evidence or a new filing, policy or product event changes the market signal. The model is refreshed annually, updated between cycles for material market events, and subjected to a fresh source and calculation review immediately before delivery.
Mordor Intelligence's Continuous Glucose Monitoring Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The continuous glucose monitoring (CGM) market measures annual spending on CGM devices and device components sold globally for continuous glucose measurement and diabetes management.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Scenario analysis carries forward changes in diabetes prevalence, coverage, adoption, replacement frequency and prices, while primary-research respondents check the role and direction of these variables rather than substitute unsupported point estimates.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 20.89 B (2027) | |
| Global Market Research Firm A | USD 14.3 B (2026) | At its 2026 base, this estimate is 31.5% below this report's 2027 value of USD 20.89 B, 1 year later. The published estimate is for 2026, one year before this report's current year. |
| Global Market Research Firm B | USD 15.5 B (2026) | At its 2026 base, this estimate is 25.8% below this report's 2027 value of USD 20.89 B, 1 year later. The published estimate is for 2026, one year before this report's current year. |
Mordor Intelligence's analysts triangulate company disclosures, epidemiology, reimbursement and regulatory signals, and channel or procurement evidence, then investigate variances in growth, mix, pricing and geographic shares before sign-off.
Key Questions Answered in the Report
What is the Continuous Glucose Monitoring (CGM) market size and growth outlook?
The market is projected at USD 20.89 billion in 2027 and USD 42.18 billion by 2032, growing at a CAGR of 15.09% from 2027 to 2032.
What is driving demand for CGM devices?
The 2026 American Diabetes Association recommendation of CGM at diabetes onset for people who could benefit, alongside U.S. Medicare coverage for eligible users, supports demand.
Which CGM component leads revenue?
Sensors held 89.35% of revenue in 2026 and are projected to grow at a CAGR of 15.36% from 2027 to 2032.
Which companies are prominent CGM suppliers?
Principal suppliers include MiniMed Group, Inc. (formerly the Medtronic plc diabetes business), Dexcom Inc., Abbott Laboratories, Senseonics Holdings Inc. and F. Hoffmann-La Roche Ltd.
What could limit continued CGM use?
Cost can prevent a prescribed device from reaching the patient. An April 2025 U.S. report described a Medicaid participant who could not afford a CGM after coverage was denied.
Where is CGM demand largest and fastest growing?
North America held 50.55% of revenue in 2026, while Asia-Pacific is projected to grow fastest at a CAGR of 15.78% from 2027 to 2032.