
Cloud System Management Software Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
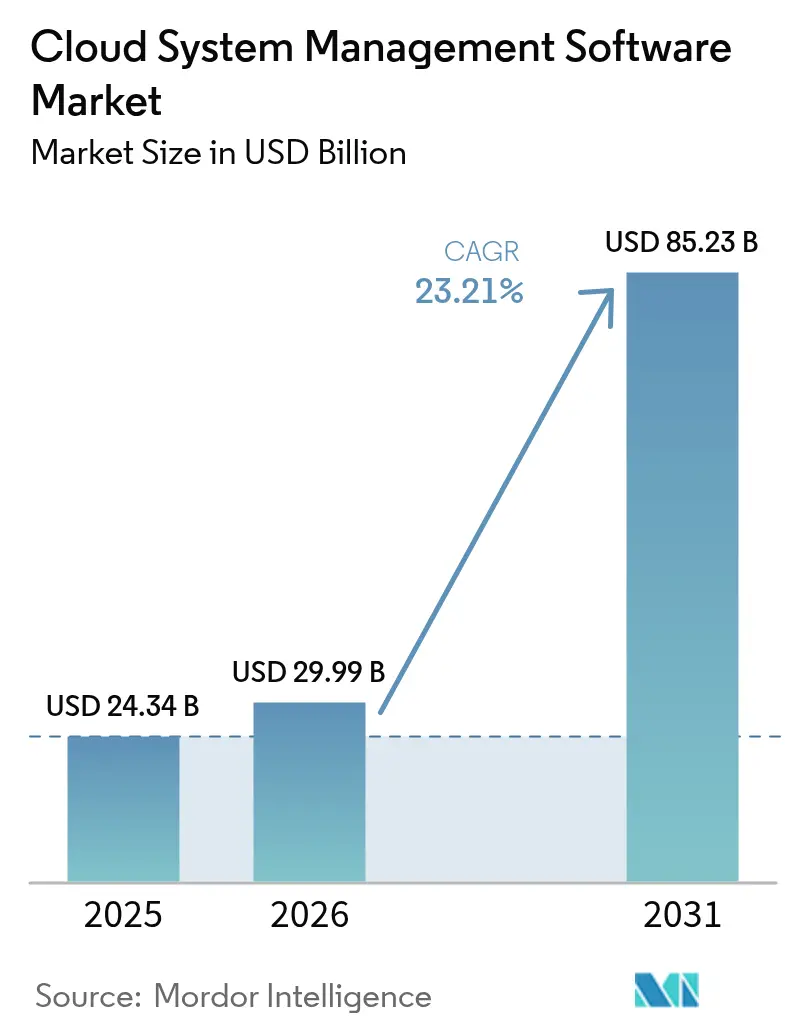
| Market Size (2026) | USD 29.99 Billion |
| Market Size (2031) | USD 85.23 Billion |
| Growth Rate (2026 - 2031) | 23.21 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Cloud System Management Software Market Analysis by Mordor Intelligence
The cloud system management software market size is expected to grow from USD 24.34 billion in 2025 to USD 29.99 billion in 2026 and is forecast to reach USD 85.23 billion by 2031 at 23.21% CAGR over 2026-2031. Demand is rising as enterprises shift from reactive monitoring toward proactive, AI-enabled orchestration across multi-cloud and hybrid estates. Consolidation such as Broadcom’s integration of VMware signals strategic scale-ups, yet the arena stays sufficiently fragmented for specialist observability and automation startups to win logos. Growth also reflects board-level cost governance, the need to manage GenAI GPU clusters, and new telemetry layers tied to Scope-3 carbon accounting and quantum-safe encryption. Vendors able to unify logs, metrics, costs, and sustainability data across clouds continue to capture premium pricing power.
Key Report Takeaways
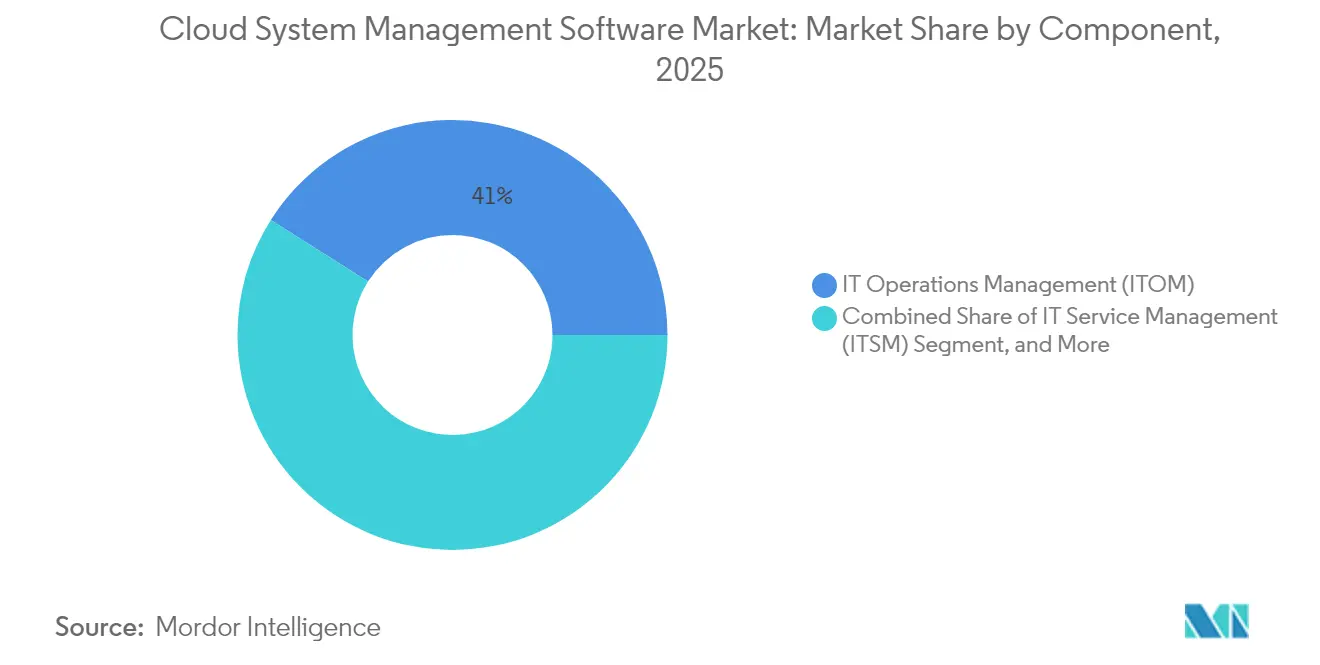
- By component, IT operations management led with 41.02% of the cloud system management software market share in 2025 while IT automation and configuration management is expanding at a 24.18% CAGR through 2031.
- By deployment model, public cloud deployments held 52.21% revenue share in 2025 in the cloud system management software market; hybrid cloud is the fastest-growing approach at a 24.42% CAGR.
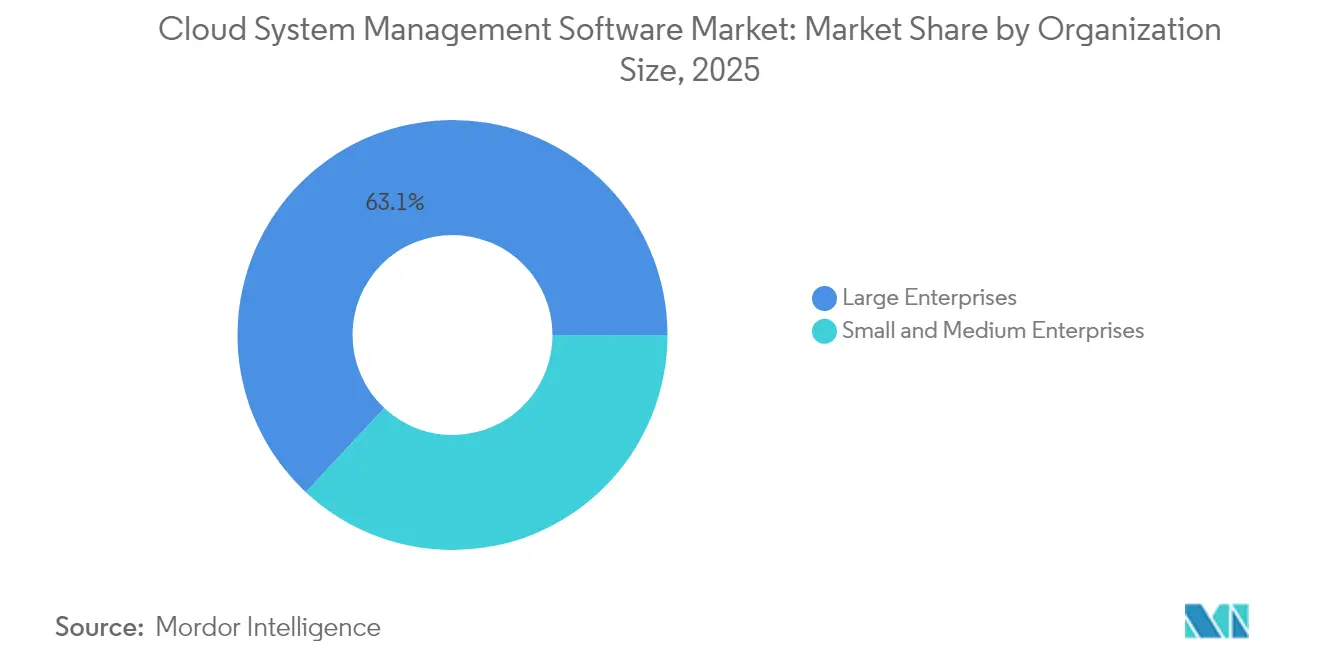
- By organization size, large enterprises accounted for 63.05% spend in 2025 in the cloud system management software market, yet small and medium enterprises are growing at a 24.58% CAGR.
- By end-user industry, IT and Telecommunications generated 29.12% of 2025 revenue in the cloud system management software market, whereas healthcare is pacing fastest at a 23.89% CAGR.
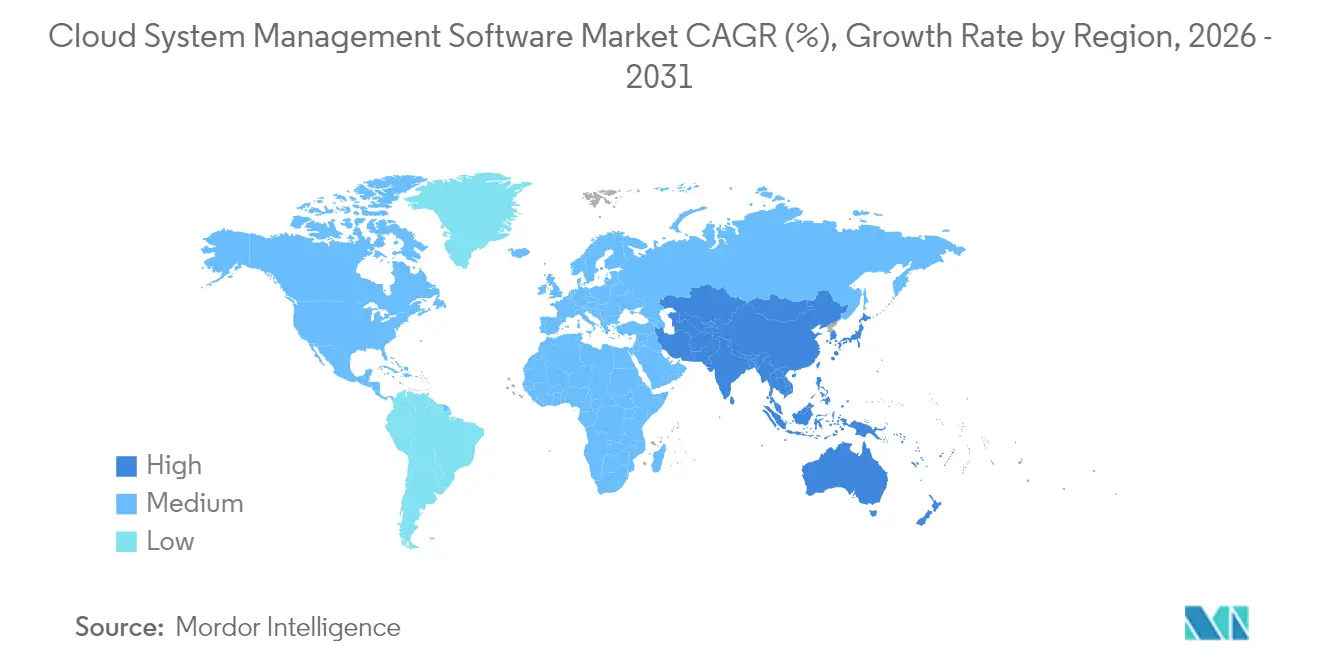
- By geography, North America contributed 38.26% of 2025 revenue in the cloud system management software market and Asia-Pacific is projected to rise at a 23.98% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Cloud System Management Software Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Explosion of multi-cloud and hybrid adoption | +5.2% | Global, with peak intensity in North America and Europe | Medium term (2-4 years) |
| Shift-left DevOps driving demand for unified observability | +4.8% | North America, Europe, Asia-Pacific urban hubs | Short term (≤ 2 years) |
| FinOps as a board-level mandate for cloud cost control | +4.3% | Global, led by North America and Europe | Short term (≤ 2 years) |
| Emergence of GenAI-ready GPU orchestration layers | +3.9% | North America, China, select Asia-Pacific markets | Medium term (2-4 years) |
| Sustainability reporting mandates (Scope-3) embedded in CMPs | +2.7% | Europe, North America, expanding to Asia-Pacific | Long term (≥ 4 years) |
| Quantum-safe crypto modules entering cloud management stacks | +1.9% | North America, Europe, government sectors globally | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Explosion of Multi-Cloud and Hybrid Adoption
Organizations ran an average of 2.6 public clouds in 2024, up from 2.2 the previous year, as visibility gaps increased with each additional provider.[1]Flexera, “2024 State of the Cloud Report,” flexera.com Platforms that normalize telemetry across AWS, Azure, and Google Cloud are displacing point tools that require manual scripting. Pre-built connectors and policy translation kits, such as Terraform providers, are speeding rollouts and boosting compliance. Enterprises now cite inconsistent tooling as the top barrier to optimization, reinforcing demand for abstraction layers that mask proprietary APIs.
Shift-Left DevOps Driving Demand for Unified Observability
DevOps teams instrument code at commit time, shrinking mean-time-to-resolution by 40% and elevating observability to a developer concern. Unified platforms correlate traces, metrics, and business KPIs, enabling engineers to identify misconfigurations before users are affected. New Relic customers who employ full-stack observability reduce alert noise by 35%. Datadog’s 2024 purchase of Bits AI pulled LLM-powered root-cause analysis into mainstream operations, turning plain-language explanations into a differentiator.
FinOps as a Board-Level Mandate for Cloud Cost Control
With cloud bills now scrutinized by CFOs, real-time budget alerts and chargeback models are shifting management suites from IT utilities to financial governance platforms. Companies adopting automated rightsizing and idle-resource reclamation have lowered waste by nearly one-third within six months according to hyperscaler case studies.[2]AWS, “Carbon-Aware Workload Placement,” aboutamazon.com Leading suites surface idle resources, reserved-instance gaps, and anomaly detection that flags spend spikes in minutes rather than weeks.
Emergence of GenAI-Ready GPU Orchestration Layers
Training and fine-tuning large language models consumes bursty GPU clusters. Cloud management platforms that schedule accelerators across on-premises and public resources now push utilization rates into the mid-80% range, up from historical baselines of around 60%. Features such as automated spot bidding and multi-region failover deliver up to 40% savings on training workloads. Enterprises therefore prize unified schedulers that pair GPU efficiency with workload-level cost attribution.
Restraints Impact Analysis of Cloud System Management Software Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating cyber-attacks on control planes | -2.8% | Global, acute in North America and Europe | Short term (≤ 2 years) |
| Persistent skills shortage in cloud operations and AIOps | -2.1% | Global, most severe in Asia-Pacific and emerging markets | Medium term (2-4 years) |
| Opaque licensing of proprietary telemetry APIs | -1.6% | Global, particularly affecting multi-cloud enterprises in North America and Europe | Medium term (2-4 years) |
| Edge-to-cloud data-sovereignty fragmentation | -1.4% | Europe, Asia-Pacific, Middle East, with regulatory spillover to other regions | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating Cyber-Attacks on Control Planes
Centralized control planes hold high-value credentials and configuration data. The 2024 Snowflake breach, traced to compromised admin accounts, exposed multi-tenant risks and drove firms to adopt hardware-backed MFA and immutable audit logs. Similar incidents at identity providers heightened scrutiny on third-party integrations. Regulatory agencies now recommend zero-trust architectures that enforce least privilege and continuous authentication. Vendors unable to demonstrate rigorous security controls often face longer procurement cycles, particularly in regulated industries.
Persistent Skills Shortage in Cloud Operations and AIOps
It is estimated that there is a global deficit of millions of persons, cloud architects, and site-reliability engineers. SMEs struggle most, lacking budgets for specialist staff capable of tuning anomaly-detection thresholds or interpreting AI-generated root-cause analyses. Vendors embed guided workflows, pre-built dashboards, and natural language queries to lower barriers. Yet, advanced users often require deeper configurability. Cloud-provider certification programs are expanding, but the talent pipeline remains at least 18–24 months behind demand.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Cloud System Management Software Market Segment Analysis
By Component:
Automation Gains as DevOps MaturesIT Automation and Configuration Management is on track to post a 24.18% CAGR, the quickest clip among components as organizations replace manual scripts with declarative infrastructure-as-code. The cloud system management software market size for IT Automation is projected to grow from USD 9.67 billion in 2025 to USD 35.45 billion by 2031. HashiCorp Terraform’s vendor-neutral language now governs thousands of resource types, reinforcing demand for tools that span public clouds and on-premises systems. IT Operations Management retained a 41.02% market share of cloud system management software in 2025, as unified observability remains foundational. Acquisitions, such as Cisco's acquisition of Splunk, fuse network telemetry with application traces to close visibility gaps.
Enterprises are increasingly seeking platforms that cover provisioning, configuration, runtime monitoring, and service management from end to end. Kubernetes-native projects, such as Argo CD and Flux, extend GitOps workflows, while ITSM suites integrate AI chat to resolve tickets more efficiently. For teams with legacy estates, agentless discovery and drift detection expedite migration roadmaps and reduce toil. The convergence of observability with automation positions vendors offering cohesive portfolios to out-execute niche point solutions.


By Deployment Model:
Hybrid Architectures Surge on Sovereignty ConcernsPublic cloud kept 52.21% revenue in 2025, yet hybrid models are expanding at a 24.42% CAGR as data-sovereignty mandates rise. The cloud system management software market size for hybrid cloud solutions is forecast to exceed USD 44.8 billion by 2031. EU rules now require providers to enable data portability without punitive fees, strengthening demand for open orchestration layers like Kubernetes that abstract workload placement. AWS Outposts, Azure Arc, and Google Anthos push public-cloud APIs into customer data centers, giving teams one control plane for disparate resources.
Private clouds remain relevant for regulated workloads but grow slower due to capital intensity. Enterprises adopt hybrid so analytics can burst to hyperscale regions while personally identifiable information stays on-premises. Unified cost allocation, security posture management, and observability across locations therefore become non-negotiable. Vendors lacking feature parity between on-premises and public endpoints risk churn as customers consolidate around consistent experiences.
By Organization Size:
SMEs Narrow the Gap with SaaS PlatformsLarge enterprises contributed 63.05% of 2025 spending thanks to sprawling multi-cloud estates that demand sophisticated governance. However, SMEs are accelerating at a 24.58% CAGR as consumption-based pricing and no-install SaaS onboarding lower barriers. The cloud system management software market size for SME buyers is set to surpass USD 23.6 billion by 2031. Vendors like Datadog and New Relic court this cohort with free or low-cost tiers and guided setups that turn value visible in hours.
Ease of use ranks higher than deep configurability for mid-market firms without dedicated SRE teams. Natural-language queries, automated baselining, and prescriptive remediation reduce the skills dependency highlighted earlier. Conversely, large enterprises continue to demand granular role-based access controls, custom integrations, and API extensibility to fit complex IT service catalogs. Modular product lines that allow each segment to adopt features at its own pace now differentiate market leaders.
By End-User Industry:
Healthcare Accelerates on EHR MigrationsIT and Telecommunications retained 29.12% of 2025 revenue as operators leverage cloud management to monetize 5G edge computing. The healthcare and Life Sciences Sectors show the fastest trajectory, advancing at a 23.89% CAGR to 2031, driven by the modernization of electronic health records and the scale-out of telemedicine. The cloud system management software market share for healthcare is forecast to climb above 12.34% by the end of the decade as HIPAA and similar rules demand audit-ready logging and encryption-key rotation.
BFSI sectors embed cost-governance dashboards directly into consoles to cap real-time spending, while manufacturing orchestrates factory IoT telemetry with ERP backends for predictive maintenance. Retail chains correlate point-of-sale feeds with inventory analytics to inform dynamic pricing, and logistics firms automate route optimization across hybrid clouds. Each vertical value unifies visibility while tailoring policies around its own compliance frameworks, making configurable reporting templates a key feature.
Geography Analysis
North America Cloud System Management Software Market
North America led the cloud system management software market in 2025 with 38.26% revenue, supported by early AIOps adoption and stringent breach-notification statutes that raise the premium on centralized security-event correlation. U.S. enterprises also benefit from the regional presence of hyperscalers and a dense ecosystem of observability startups, which accelerates innovation and partnership velocity. Consolidation moves such as Broadcom–VMware and Cisco–Splunk accentuate competition and keep spending momentum high among Fortune 500 users seeking integrated control planes.
APAC Cloud System Management Software Market
The Asia-Pacific region is projected to post the fastest growth rate of 23.98% through 2031. India’s public-sector cloud mandate requires government data to stay within national borders under the MeghRaj framework, driving hybrid architectures that blend local data centers with hyperscale capacity. China’s cybersecurity and data-security laws push critical infrastructure operators toward sovereign-cloud stacks anchored by domestic providers. Japan’s digital agency initiatives further draw enterprises into managed platforms that unify cost, sustainability, and security metrics across vendors.
EMEA and LATAM Cloud System Management Software Market
Europe sits at the center of data-sovereignty debate, with GDPR and the 2024 EU Data Act prompting enterprises to keep sensitive workloads on-premises while bursting analytics to the public cloud. Germany’s BSI promotes multi-cloud designs to mitigate vendor lock-in, spurring adoption of open orchestration layers. Middle East sovereign-wealth-fund investments in hyperscale facilities shorten latency for local enterprises, while Africa’s mobile-first economies value lightweight, API-driven suites that function over constrained bandwidth. Latin America’s GDPR-style regulations likewise accelerate adoption of management tools with granular access controls and auditability.

Regulatory Landscape
Cloud system management software is increasingly shaped by security baseline mandates and public-sector cloud-use rules that push configuration assessment, auditability, and API security into core platform requirements. In the United States, CISA Binding Operational Directive (BOD) 25-01 requires agencies and other covered tenants using finalized Secure Cloud Configuration Baselines (SCuBA) to deploy assessment tools by April 25, 2025, which is expected to raise demand for automated posture assessment, drift detection, and evidence-ready reporting within management suites.
Standards and sovereignty frameworks are also tightening across major regions. NIST updated SP 800-228 in March 2026 with guidance for API protection in cloud-native systems, reinforcing the need for API inventory, authentication/authorization controls, and continuous monitoring across multi-cloud control planes. In the EU, the European Commission adopted the Cloud and AI Development Act (CADA) proposal on June 3, 2026 to expand data center capacity and introduce a sovereignty assessment framework, while the EU Cyber Resilience Act introduces reporting obligations for products with digital elements from September 11, 2026. Australia added a public-sector anchor with its Whole-of-Government Cloud Computing Policy taking effect on July 1, 2026, making cloud-first modernization requirements a direct pull-through for compliant management tooling.
Value Chain Analysis
The value chain begins with standards and cloud primitives (compute, storage, networking, Kubernetes, identity) from hyperscalers and private-cloud stacks, then layers telemetry (logs, metrics, traces), policy, and configuration data. Cloud system management vendors normalize these inputs into workflows for ITOM, ITSM, automation/configuration management, and FinOps. Interoperability standards and reference models (for example, The Open Group IT4IT value chain operating model, DMTF cloud standards, ISO/IEC 19831:2015 for CIMI, and NIST cloud standards roadmaps) act as enabling inputs that reduce integration friction, but proprietary cloud APIs and licensing terms still create switching costs that platforms must offset through connectors and abstraction.
Channel and delivery are heavily partner-led, with global and regional SIs/MSPs packaging assessment, migration, and managed operations on top of these platforms. Marketplaces and consumption-based procurement routes also support mid-market adoption. Recent ecosystem moves point to upstream consolidation and tighter platform integration, such as IBM completing its acquisition of HashiCorp in February 2025 to integrate infrastructure automation and lifecycle management into a hybrid cloud portfolio, and Rackspace Technology signing a multi-year strategic collaboration agreement with AWS in October 2024 to expand advisory, FinOps, and migration delivery. Key bottlenecks remain skills availability for AIOps operations, data-quality and telemetry governance across environments, and the need to align procurement and billing data (chargeback/showback) with operational telemetry in a single control plane.
Competitive Landscape
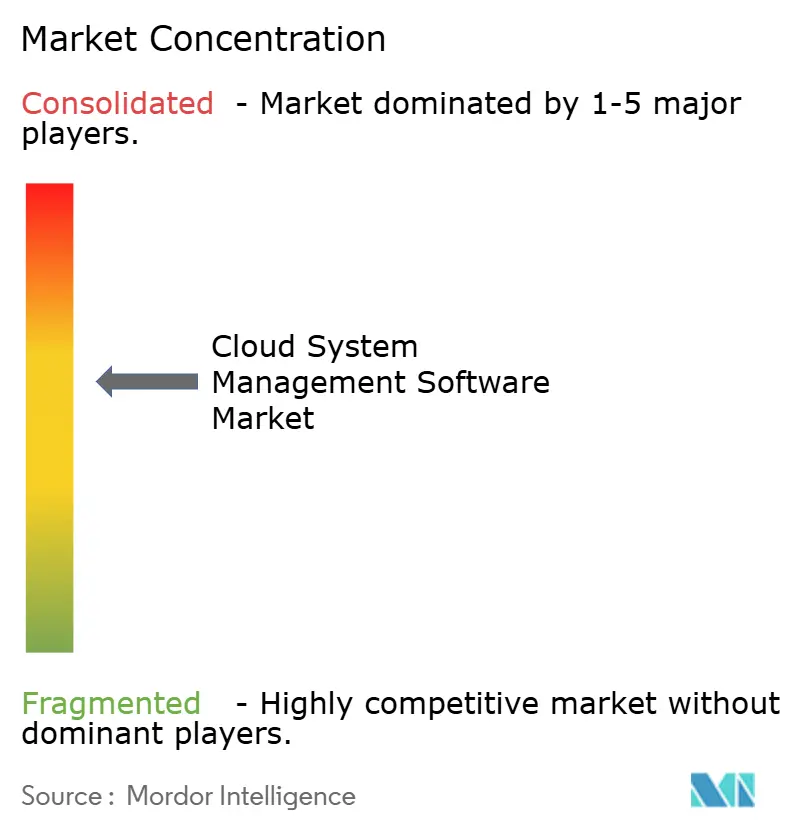
The cloud system management software industry remains moderately fragmented. The top five vendors, VMware (Broadcom), Microsoft, AWS, ServiceNow, and IBM, held an estimated 48% share in 2024, with no single firm above 15%. Broadcom’s integration of VMware tightened hybrid-cloud licensing strategies, but customer unease over pricing opens space for open-source alternatives such as Red Hat OpenShift and Terraform. IBM’s 2024 acquisition of HashiCorp strengthened its multi-cloud automation play, adding a declarative layer that spans hyperscalers.
Hyperscalers bundle native cost, security, and observability features into consumption pricing, encouraging single-vendor loyalty. Yet specialized providers thrive by tackling cross-cloud pain points, offering API-first architectures, and focusing on root-cause analysis powered by large language models. Datadog reported 32% year-on-year revenue growth in 2025 as customers sought unified monitoring for Kubernetes, serverless, and edge workloads. New Relic, Dynatrace, Harness, and CloudBolt differentiate via usage-based licensing, continuous deployment hooks, and policy-as-code frameworks.
Strategic moves emphasize AI and sustainability. IBM filed dozens of patents for predictive capacity algorithms, while Google Cloud’s intellectual-property focus lies in carbon-aware scheduling and quantum-safe key rotation. Cisco’s absorption of Splunk blends network and security telemetry into a single analytics lake. Smaller disruptors exploit hyperscaler blind spots, edge-to-cloud orchestration, multi-cloud cost attribution, and compliance for niche regulations, to win accounts resistant to vendor lock-in.
Cloud System Management Software Industry Leaders
IBM Corporation
Microsoft Corporation
Vmware Inc.
BMC Software Inc.
Cisco Systems Inc.
- *Disclaimer: Major Players sorted in no particular order
Cloud System Management Software Market Companies Covered in this Report
- VMware, Inc.
- Microsoft Corporation
- International Business Machines Corporation
- BMC Software, Inc.
- ServiceNow, Inc.
- Cisco Systems, Inc.
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Amazon Web Services, Inc.
- Google LLC
- Dynatrace, Inc.
- New Relic, Inc.
- Splunk Inc.
- Datadog, Inc.
- Flexera Software LLC
- Broadcom Inc.
- Morpheus Data LLC
- CloudBolt Software, Inc.
- Harness Inc.
- HashiCorp Inc.

Market Opportunities and Future Outlook
Sovereignty-by-design is turning into a practical buying criterion, opening whitespace for platforms that can demonstrate data residency, compliant operations, and auditable controls across hybrid estates beyond performance monitoring. Policy anchors include Australia’s Whole-of-Government Cloud Computing Policy taking effect on July 1, 2026, and enterprise-facing control requirements such as NIST SP 800-228 (March 2026 update) for API protection in cloud-native systems. Vendors that ship pre-mapped policy packs, automated evidence collection, and consistent governance across AWS, Azure, Google Cloud and on-premises stacks are positioned to translate these mandates into packaged offerings for government, regulated industries, and telco cloud modernization.
A second opportunity area is the shift from dashboard-centric operations to AI-assisted and agent-driven workflows that combine observability, automation, and security in one plane of control. In June 2026, Cisco introduced Cisco Cloud Control as a unified platform to manage, monitor, and defend IT infrastructure for both human and AI agent operation, which highlights competitive differentiation around AgenticOps-style capabilities. In parallel, confidential computing and hardware-enabled security are moving closer to mainstream requirements, supported by NIST IR 8320E (initial public draft released May 2026) focused on protecting data in cloud workloads. Platforms that orchestrate policy, identity, and workload placement while exposing verifiable controls for API security and confidential compute environments can expand beyond IT teams into finance, risk, and compliance stakeholders that influence cloud spend and operating models.
Recent Industry Developments in Cloud System Management Software Market
- July 2026: Kyndryl expanded its collaboration with Microsoft to deliver sovereignty solutioning that leverages Microsoft Sovereign Cloud capabilities. The update strengthens service-led implementations of compliant hybrid environments, bringing governance and data residency requirements closer to day-to-day cloud operations for enterprises and public-sector buyers.
- May 2026: IBM announced IBM Concert for intelligent operations and made IBM Sovereign Core generally available as part of its sovereignty-focused software portfolio. This combination links AIOps-style operations with sovereignty controls, helping enterprises manage hybrid estates with stronger compliance posture while reducing operational toil.
- April 2024: IBM announced an agreement to acquire HashiCorp to deepen its infrastructure automation and lifecycle management stack for hybrid cloud environments. The planned integration of Terraform-based workflows into a broader management portfolio highlighted the strategic value of vendor-neutral automation for multi-cloud operations and governance.


Cloud System Management Software Market Report Scope and Research Methodology
Market Definition and Coverage
For this methodology, the market covers software used to monitor, automate, configure, and govern cloud environments so IT teams can keep cloud systems stable, secure, and cost controlled across public, private, and hybrid setups.
Scope exclusions: We exclude general cloud hosting and infrastructure capacity charges, along with pure consulting, implementation labor, and managed services fees that sit outside software licensing or subscription revenue.
Segments Covered in This Report
- By Component
- IT Operations Management (ITOM)
- IT Service Management (ITSM)
- IT Automation and Configuration Management (ITACM)
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user Industry
- IT and Telecommunications
- Banking, Financial Services and Insurance (BFSI)
- Healthcare and Life Sciences
- Manufacturing
- Retail and Consumer Services
- Transport and Logistics
- Media and Entertainment
- Government and Public Sector
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to build the market frame and to gather consistent time series that can anchor software spend. We mainly relied on public, non-paywalled sources such as the US Bureau of Economic Analysis, the US Bureau of Labor Statistics, Eurostat, OECD ICT indicators, and the International Telecommunication Union for cloud and digital activity signals.
We also reviewed company annual reports, investor presentations, product documentation, and reputable tech press coverage to map how cloud management software is packaged and monetized. Where needed, paid subscriptions for company financials and intelligence, plus a patent database, supported cross-checks on revenue direction and product emphasis. The desk research sources named here are illustrative, and many other public sources were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on interviews and structured surveys with cloud operations leaders, IT service owners, platform engineers, and channel partners across major regions. Buying behavior varies meaningfully between regulated and less regulated industries, so we treated that as a segmentation check during analysis. The respondent input helped confirm adoption patterns across public, private, and hybrid deployments, and it tightened assumptions on pricing, renewal behavior, and typical module bundling, for example monitoring plus automation.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 36% | CXOs: 15% | APAC: 39% |
| Mid tier: 49% | Functional/Unit leaders: 34% | EMEA: 36% |
| Smaller Players: 15% | Managers: 51% | Americas: 25% |
Market-Sizing & Forecasting
Sizing starts with a top-down demand pool build that reconstructs cloud management software spend from enterprise cloud adoption and IT operations needs, and then it is split across key software functions that are typically purchased to run cloud estates. To keep the totals realistic, the outputs are corroborated through selective bottom-up approximations, including sampled vendor revenue splits, channel checks, and ASP estimates tied to deployments for a set of common tool categories.
In the model, a few practical inputs do most of the work, such as workload growth across public and hybrid environments, tool consolidation trends, observability coverage (logs, metrics, traces), automation and configuration intensity, and governance requirements linked to security posture and cost controls. When the forecast is built, scenario analysis is used so uncertain levers, like budget tightening or faster multi-cloud adoption, can be applied transparently, then checked against expert views. Where bottom-up roll ups have gaps, we fill them using proxy ratios from adjacent buyer groups and recheck the implied spend per organization so the outcome stays within plausible ranges.
Data Validation & Update Cycle
Model outputs are checked against independent signals, including enterprise software spend direction, cloud workload expansion indicators, and stated priorities from IT operations leaders, and then differences are investigated before sign-off. If a region or deployment type shows an unusual jump, we review the drivers, revisit inputs like pricing progression and adoption timing, and re-contact selected respondents when the variance cannot be explained.
Each report is refreshed annually, and interim updates are made when material events occur, such as major licensing changes, sharp macro shifts, or a notable jump in cloud adoption patterns. Before delivery, an analyst runs a final recency pass so the numbers and key assumptions reflect the latest available public data and validated interview feedback.
Mordor Intelligence's Cloud System Management Software Market Estimate Compared With Other Published Estimates
Published market sizes for cloud system management software can look far apart, even when they sound like they measure the same thing. The spread usually comes from differences in what gets counted as software revenue, which cloud deployment types are included, and how pricing and adoption are projected year by year.
Some estimates expand the scope to include managed services, broad IT outsourcing, or general cloud infrastructure operations spend. In Mordor Intelligence, the total is limited to software revenue tied to cloud system management functions, and it is further constrained by deployment reality checks from adoption and renewal patterns.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 24.34 B (2025) | |
| Global Consultancy A | USD 31.60 B (2025) | Uses a broader spend lens that can bundle cloud operations services and adjacent infrastructure management costs, which lifts totals beyond software-only subscriptions and licenses. |
| Trade Journal B | USD 20.10 B (2025) | Applies a narrower product cut that emphasizes monitoring and observability tools, and often undercounts automation and configuration management modules that are sold as part of suites. |
The comparison shows that the largest differences are explained by scope and by how suite modules are counted. By keeping the calculation tied to clear software functions, checking implied spend per buyer type, and revisiting pricing assumptions during updates, the final value stays traceable to inputs that can be repeated and reviewed.


Key Questions Answered in the Report
What is the current size of the Cloud system management software market?
The market is valued at USD 29.99 billion in 2026 and is forecast to reach USD 85.23 billion by 2031.
Which component is growing fastest within this space?
IT Automation and Configuration Management leads growth, expanding at a 24.18% CAGR as organizations adopt infrastructure-as-code and policy-as-code workflows.
Why are hybrid deployments outpacing public-only deployments?
Data sovereignty mandates and latency-sensitive workloads drive enterprises to blend on-premises and multiple cloud providers, producing a 24.42% CAGR for hybrid approaches.
Which industry will see the highest adoption through 2031?
Healthcare and Life Sciences, propelled by electronic health record migrations and stringent compliance needs, is anticipated to record a 23.89% CAGR.
What regions are poised for the fastest market expansion?
Asia-Pacific is projected to grow at 23.98% CAGR thanks to sovereign-cloud mandates in India and China and digital-government programs in Japan.
Page last updated on:





