
Cigar Market Size and Share
Cigar Market Analysis by Mordor Intelligence
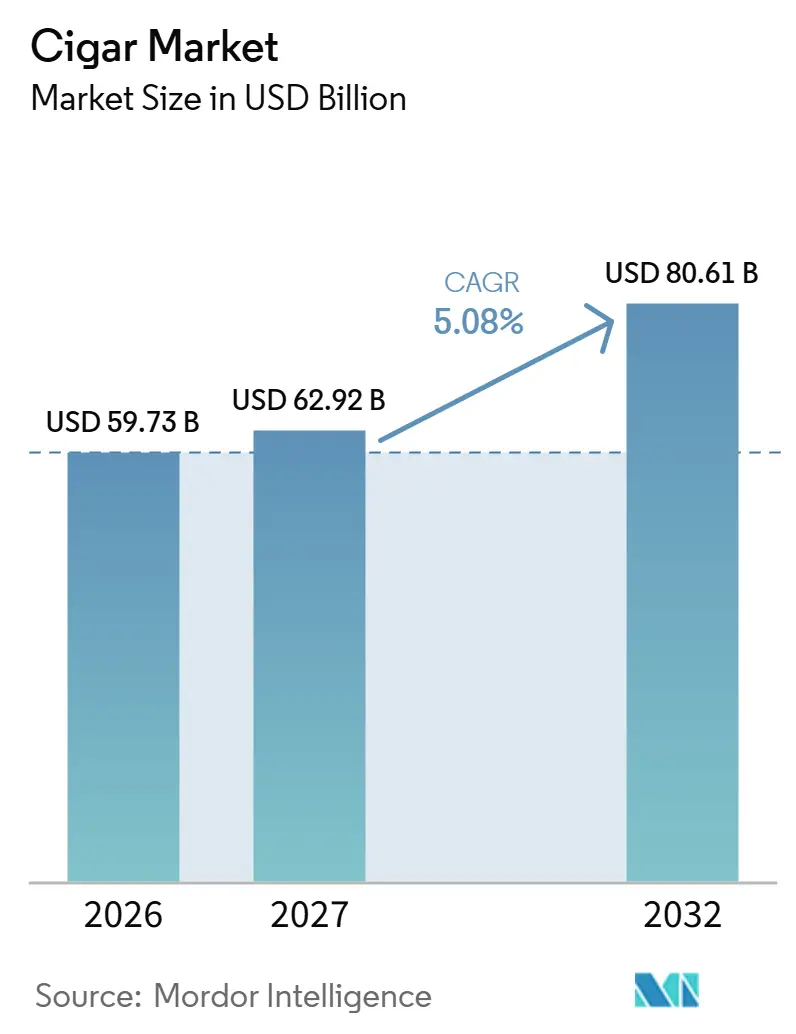
The cigar market size is estimated at USD 59.73 billion in 2026 and is projected to be USD 62.92 billion in 2027, reaching USD 80.61 billion by 2032, growing at a CAGR of 5.08% from 2027 to 2032.
Brand-specific cigar demand in the United States and the appeal of shorter cigarillo occasions give suppliers different ways to compete for adult spending. Distribution partnerships can extend that reach without requiring proportionate factory expansion, making customer access a strategic complement to production scale. Taxes and restrictions on promotion and selling channels constrain the return from reaching those buyers. Converting a distinct cigar proposition into repeat sales through lawful routes can support growth while preserving value across the production and distribution chain.
Key Report Takeaways
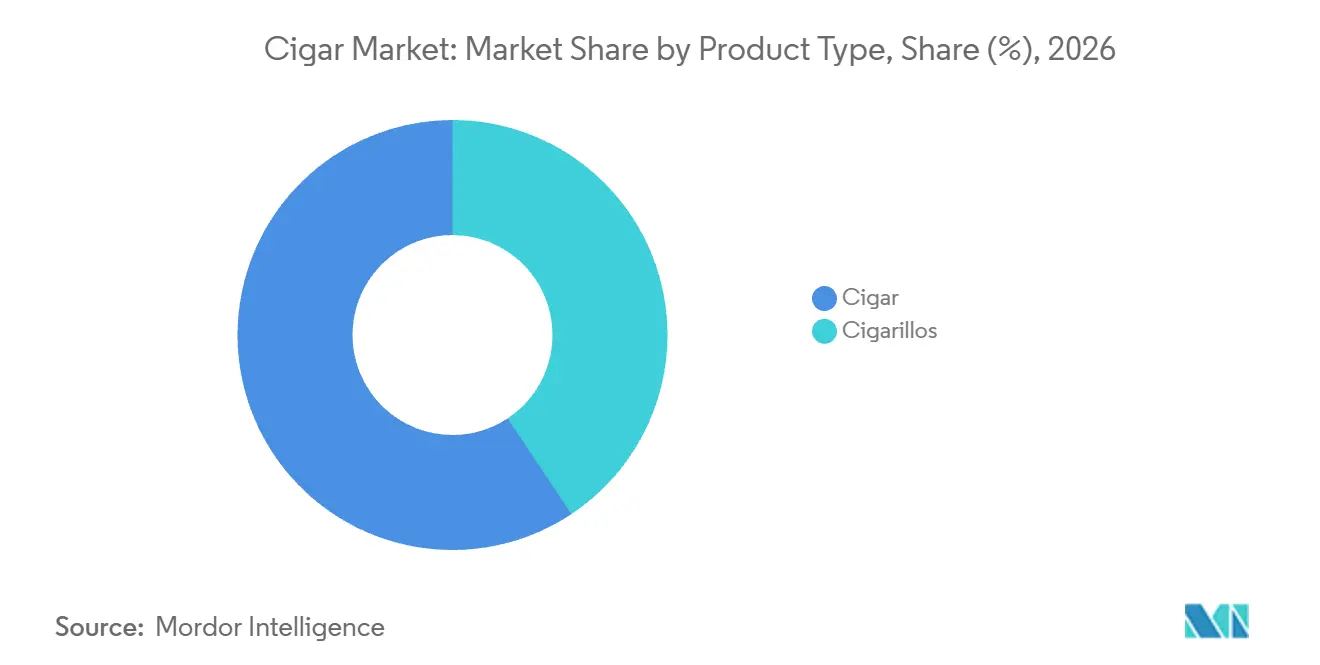
- By product type, cigars held a 59.33% cigar market share in 2026, while cigarillos are the fastest-growing segment at a projected CAGR of 5.97% from 2027 to 2032.
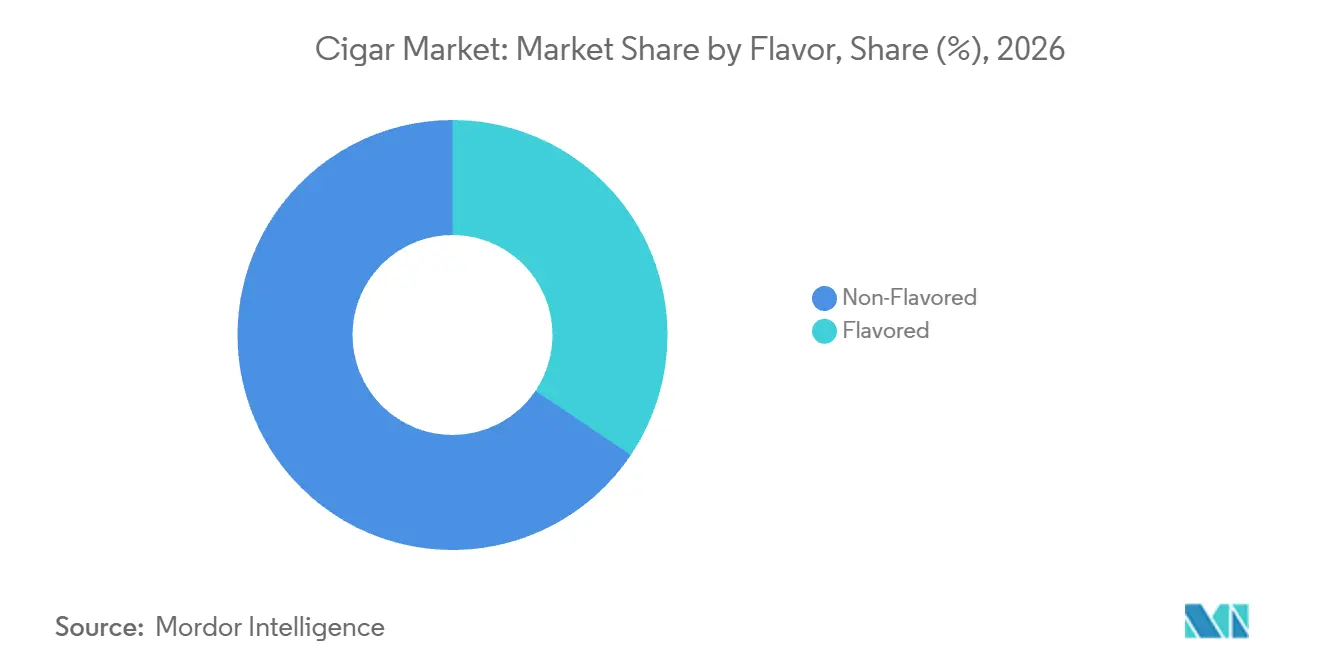
- Across flavor categories, non-flavored cigars accounted for a 65.57% share of the cigar market size in 2026, and flavored cigars are the fastest-growing segment at a projected CAGR of 6.28% from 2027 to 2032.
- By price point, mass cigars led with a 63.2% share of retail sales value in 2026, while premium cigars are the fastest-growing segment at a projected CAGR of 6.19% from 2027 to 2032.
- Among distribution channels, offline retail stores held 87.71% of retail sales value in 2026, whereas online retail stores are the fastest-growing segment at a projected CAGR of 7.13% from 2027 to 2032.
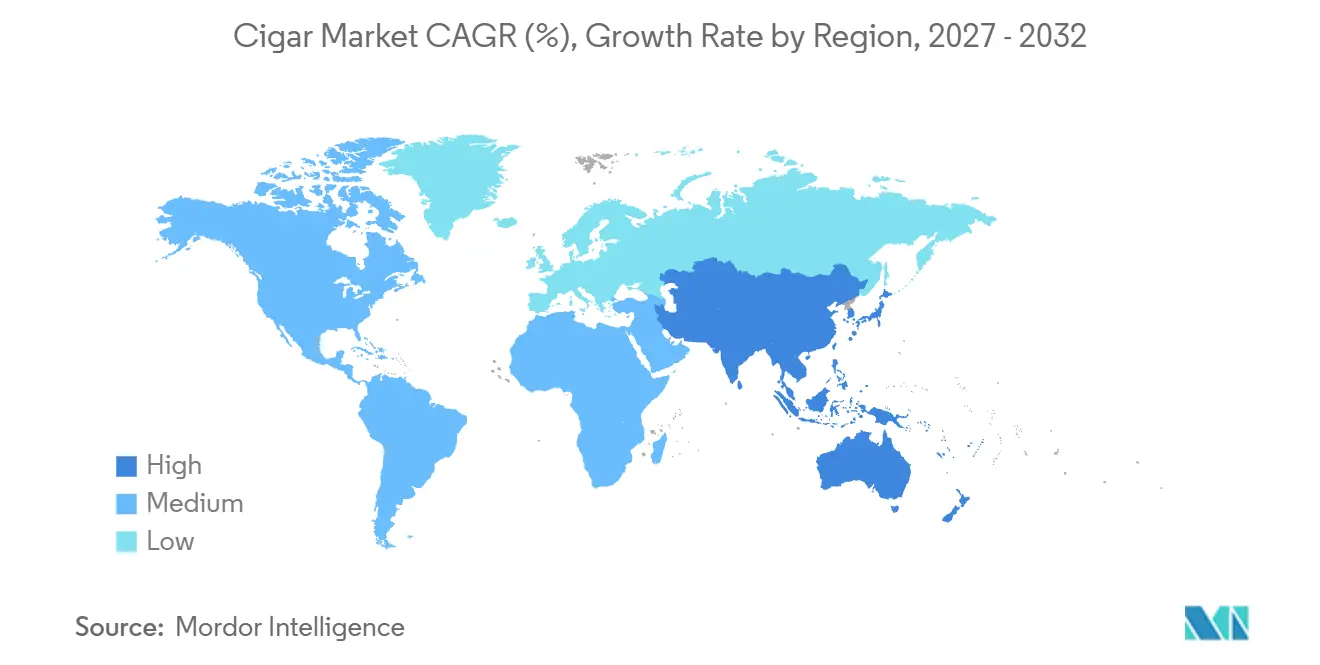
- Geographically, Asia-Pacific led with a 54.66% share of retail sales value in 2026 and is the fastest-growing region at a projected CAGR of 5.95% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Cigar Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Popularity of Premium and Hand-Rolled Cigars | +1.95% | North America (United States) | Long term (≥ 4 years) |
| Product Innovation in Cigar Blends and Packaging | +1.65% | North America (United States) | Medium term (2-4 years) |
| Rising Consumer Preference for Luxury and Status Symbol Products | +1.35% | North America (United States) | Medium term (2-4 years) |
| Growth of Boutique and Artisan Cigar Brands | +1.25% | Europe, specifically Germany | Medium term (2-4 years) |
| Increasing Adoption of Humidor Technology for Better Preservation | +0.5% | North America (United States) | Long term (≥ 4 years) |
| Expansion of Online Retail Channels for Cigars | +0.65% | Across North America | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Popularity of Premium and Hand-Rolled Cigars
Premium handmade cigars combine a substantial US import base with a store-level split between growing, flat, and declining specialist retailers. The United States imported 242.8 million premium handmade cigars through July 2026, up 0.5% from the same period in 2025.[1] In a fourth-quarter 2025 survey, 48% of Premium Cigar Association retail respondents said their store's 2025 sales had increased compared with the prior year, while 34% reported flat sales and 15% a decrease. Retailers reporting higher total-store sales offer potential distribution opportunities for premium producers, while the import reading establishes the scale of the US supply flow. Serving specialist accounts where sales are rising gives producers a route to repeat premium orders within that established business.
Product Innovation in Cigar Blends and Packaging
Innovation can raise demand by giving adult buyers a more distinctive product choice within a familiar price tier. Imperial Brands reported that its US mass-market cigar portfolio gained 35 basis points of share in FY2025. Product innovations and new flavor variants contributed to that performance. New variants offer another reason to select a brand within the mass-market range. Imperial credited the gain to variants together with brand equity investment and expanded sales coverage, making novelty one lever within a funded brand strategy.
Rising Consumer Preference for Luxury and Status Symbol Products
Prestige can give a cigar brand commercial pull even when limited production constrains the available supply. In a 2025 survey, 60% of 65 US tobacconists representing 126 stores named Fuente Fuente OpusX among the brands consumers requested most often. The finding captures retailer-reported requests for a high-priced, exclusive brand. For specialist shops, those requests provide a concrete reason to pursue access to that particular cigar rather than assume that every expensive product attracts equivalent interest. Securing an allocation can therefore matter more to the retailer's luxury proposition than simply adding another high-priced cigar to its range.
Growth of Boutique and Artisan Cigar Brands
Boutique brands can expand their addressable customer base through distribution without first becoming high-volume manufacturers. Kafie 1901 Cigars, a boutique premium cigar company, partnered with Don Stefano Zigarrenmanufaktur GmbH for German distribution in May 2025. The announcement combined that initial German distribution with a commitment to maintain limited production. For German specialist retailers, importer coverage can make a boutique range easier to access even when its supplier commits to limited production. Extending a boutique brand's commercial reach through a local distributor keeps its limited production commitment distinct from mass-volume expansion.
Restraints Impact Analysis of Cigar Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent Tobacco Regulations and Advertising Restrictions Globally | -0.95% | South America, specifically Brazil | Long term (≥ 4 years) |
| High Taxation on Tobacco Products in Many Regions | -0.8% | North America, specifically Canada | Short term (≤ 2 years) |
| Increasing Age Restrictions and Enforcement on Tobacco Sales | -0.3% | Europe, specifically United Kingdom | Long term (≥ 4 years) |
| Risks of Counterfeit and Smuggled Products Affecting Brand Trust | -0.25% | Spain and other European countries | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stringent Tobacco Regulations and Advertising Restrictions Globally
Brazil prohibits advertising of tobacco-derived smoking products except packaged displays inside retail premises, accompanied by health warnings, an under-18 sales prohibition message, and price tables.[2] It also prohibits offers and sales of tobacco-derived products over the internet nationwide. Together, these restrictions limit how a cigar supplier can turn brand awareness into legally accessible sales. A national online storefront cannot substitute for physical distribution under this framework. The display exception preserves a narrow way to present products, but it does not restore broader promotional reach. New suppliers consequently face the commercial hurdle of securing retail access before they can convert that permitted visibility into purchases.
High Taxation on Tobacco Products in Many Regions
Value-based cigar duties make product upgrading more expensive because the tax calculation rises with the assessed product value. Canada's additional cigar duty uses the greater of an applicable per-cigar minimum or 88% of the sale price for Canadian-made cigars or duty-paid value for imports. This structure places a cost hurdle between a supplier's more expensive product and the consumer revenue needed to justify carrying it. Absorbing that increment compresses the amount available to the distribution chain, while passing it through increases the buyer's expense. Moving toward higher-value cigars therefore raises the revenue Canadian importers need from each sale before the commercial return improves.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Cigar Market Segment Analysis
By Product Type:
Manufacturing Scale and Cigarillo DistributionCigars accounted for a 59.33% share of the cigar market size in 2026, making them the largest product-type segment. Oettinger Davidoff AG produced 36.6 million handmade premium cigars in 2025. The company also described recalibrating production in response to global market volatility and macroeconomic headwinds. Factory commitments and commercial conditions therefore matter more than a leading product position, which does not by itself justify additional capacity.
Cigarillos are the fastest-growing product-type segment, with a projected CAGR of 5.97% from 2027 to 2032. Scandinavian Tobacco Group UK reported in July 2026 that Signature Action cigarillo sales had increased 31% year over year in the United Kingdom. It linked that performance to improved distribution, flavor appeal, and a more affordable price point compared with some alternatives. Relative affordability gives flavor-led cigarillos a commercial role among adults balancing product preference against the cost of alternatives.

By Flavor:
Blend Identity and Additional Flavor ChoicesNon-flavored cigars represented a 65.57% cigar market share in 2026, making them the largest flavor segment. A non-flavored proposition leaves the tobacco blend and finished-cigar experience to carry differentiation without an added flavor cue. For suppliers, this creates a narrower product-development problem, since a new blend must be distinguishable within the same basic flavor promise rather than through a new flavor label. The commercial opportunity is a range whose differences adults can recognize and select repeatedly, giving the producer a reason to maintain clear blend identities instead of multiplying indistinct variations.
Flavored cigars are the fastest-growing flavor segment, with a projected CAGR of 6.28% from 2027 to 2032. Intercontinental Trading Corp. announced a February 2, 2026 Japanese release of Swisher Sweets Foil Pouch Green and Honey Banana flavored cigarillos. Both machine-made products are offered within its Japanese range following that announcement. Adding distinct flavor choices within an existing cigarillo line gives an importer a way to widen consumer selection without requiring a new product format. Japanese tobacconists face a more specific commercial choice over which flavors earn space within the same Swisher Sweets line.
By Price Point:
Volume Economics and Premium Channel ReachMass cigars were the largest price-point segment, accounting for 63.2% of cigar retail sales value in 2026. The Cigar Association of America estimated US cigar consumption at approximately 9.9 billion cigars in 2025, with mass-market products comprising most large-cigar volume. That substantial unit base gives suppliers a reason to pursue earnings across a broad flow of moderately priced cigars. A small change in the return earned on each stick can matter commercially when applied repeatedly across that flow. Production and distribution discipline therefore shape the value mass-cigar producers capture from scale as much as the number of cigars sold.
Premium cigars are the fastest-growing price-point segment, with a projected CAGR of 6.19% from 2027 to 2032. Oettinger Davidoff reported that sales of its Davidoff core brand increased 2.4% in 2025. The company linked its own-brand cigar results partly to partner-market and duty-free performance, alongside US growth. Davidoff's result makes premium brand investment sensitive to both duty-free trading and US demand, spreading its commercial exposure across different purchase occasions.
By Distribution Channel:
Store Productivity and Seasonal Online ExpansionOffline retail stores were the largest distribution segment, accounting for 87.71% of cigar retail sales value in 2026. In Cigar Insider's survey of 65 US retailers representing 126 cigar shops, 46.2% reported higher sales in 2025 than in 2024, while 30.8% reported flat sales and 23.1% reported declines. The survey's publisher read the 46.2% as a cooling from the 48.5% of retailers who reported gains over 2023 and the 69.1% who did so over 2022, after the pandemic-driven cigar boom. Maintaining sales across the stores reporting flat or declining business therefore matters to offline suppliers alongside serving retailers that are expanding.
Online retail stores are the fastest-growing distribution segment, with a projected CAGR of 7.13% from 2027 to 2032. In 2025, online and catalogue sales accounted for 88% of Scandinavian Tobacco Group's North America Online & Retail division net sales across all product categories. In Q1 2026, its online handmade-cigar sales grew more slowly than its overall handmade-cigar category, whose net sales rose 8% organically. The company characterized Q1 as typically its smallest quarter and cautioned that year-over-year comparisons could differ from underlying trends. The combined channel has substantial scale for this operator, but its slower first-quarter cigar growth does not establish an annual channel trend.
Geography Analysis
Asia-Pacific Cigar Market
Asia-Pacific held a 54.66% cigar market share in 2026 and is the fastest-growing region, with a projected CAGR of 5.95% from 2027 to 2032. China Tobacco Sichuan Industrial Co., Ltd.'s handmade cigars held a 50.77% share of China's domestic handmade-cigar market from January through September 2025, including a 69.65% share of the domestic premium handmade-cigar market. For distributors serving Chinese handmade-cigar buyers, that concentration makes producer relationships a consequential sourcing decision. China Tobacco International (HK) collaborated with China Tobacco Hubei Industrial Co., Ltd. to launch Huanghelou cigars in Hong Kong in January 2025.
In North America, Tabacalera USA's Casa de Montecristo brand added 2 licensed cigar shops in West Palm Beach, Florida, and Villa Park, Illinois, in August 2025. The licensed structure can spread a branded retail proposition across local selling areas, making partner execution part of the route to additional cigar customers. In Europe, European Union (EU) member states may use specific, ad valorem, or mixed excise structures within minimum duties covering cigars and cigarillos. A July 16, 2025 European Commission proposal would raise minimum tobacco duties, adding potential cost pressure if approved. Those national choices can produce distinct pricing conditions within the shared EU framework, so a supplier's commercial model has to accommodate the tax structure of each destination.
In Brazil, Bahia's Recôncavo is a cigar manufacturing and export area, while Menendez Amerino & Cia Ltda is based in São Gonçalo dos Campos. A supplier can seek access through local production relationships as well as finished-product distribution, creating a way to participate in the value added before retail. In the Middle East and Africa, relevant South African entities must license with the South African Revenue Service before manufacturing or dealing in tobacco products whose duty remains unpaid. Manufacturers pay excise duty on cigars consumed within the Southern African Customs Union.
Regulatory Framework and Outlook
The comparison examines selected jurisdictions from the perspective of a compliant cigar producer or importer seeking lawful retail access. It weighs entry and product-compliance obligations against restrictions that affect the ability to market finished cigars. Ratings favor jurisdictions where cigar suppliers can plan around fixed duties and eligibility rules, weighing scheduled or proposed changes by their effects on sale price, permitted buyers, and labeling.
Regulatory Table of Cigar Market
| Decision factor | Canada | United Kingdom | China | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Minister of National Revenue | Local trading standards offices in England, Wales and Scotland; local councils in Northern Ireland | National and provincial tobacco monopoly authorities | Anvisa | Minister of Health |
| Key instruments or direction | Excise Act, 2001; annual April 1 Consumer Price Index adjustment of the per-cigar duty component | Adopted Tobacco and Vapes Act 2026 | Monopoly licensing; GB 15269-2025 mandatory since March 1, 2026 | RDC 838/2023; proposed revisions to warning instructions IN 332/2024 and IN 331/2024 | Tobacco Products Control Act 83 of 1993; proposed Tobacco Products and Electronic Delivery Systems Control Bill |
| Commercial effect | Per-cigar duty component has a nominal floor | From January 1, 2027, no retail sales, including online, to anyone born on or after January 1, 2009 | Licensed supply; cigar product and packaging compliance | Warning requirements for domestic and imported tobacco-derived smoking products | No misleading packaging or labeling, including reduced-harm impressions |
| Current policy attractiveness | Low | Medium | Low | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change | Hardening |
| Source: Mordor Intelligence | |||||
Canada's Low and No change ratings reflect its value-based duty and ongoing April 1 indexation of only the per-cigar component, with a nominal floor. China's Low rating rests on monopoly licensing and its mandatory cigar standard, with No change reflecting a licensed-supplier perspective on the 2026 enforcement priority targeting illicit tobacco activity. Medium ratings in the United Kingdom and South Africa reflect retail eligibility and truthful-labeling obligations, while their scheduled January 2027 cohort restriction and August 2026 committee-stage packaging bill support Hardening. Brazil's Medium and No change judgments rest on RDC 838/2023 packaging and warnings and RDC 840/2023 advertising restrictions and online-sales bans, while the consultation opened October 9, 2026, with comments due November 23, 2026, proposes only package and display warning revisions, leaving those channel restrictions intact.
Value Chain Stages
The value chain compares cigar manufacturing, wholesale distribution, and retail selling according to who captures revenue at each stage and the constraint each stage faces. Oettinger Davidoff develops seeds, dries and ferments tobacco, rolls cigars, and delivers them to appointed merchants worldwide. Retail structures also include La Casa del Habano stores franchised by Corporación Habanos SA. Revenue capture farther downstream depends on selling finished cigars, making access to trade customers and consumers a separate commercial capability from rolling tobacco.
Value Chain Analysis Table of Cigar Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Cigar manufacturing | Cigar producers such as Oettinger Davidoff AG and Scandinavian Tobacco Group A/S | Finished-cigar sales | Execution failures interrupting consistent output | Strengthen production controls and qualify backup supply |
| Wholesale distribution | Habanos distributors such as Caribbean Cigars Corporation N.V. and Caribe Imports S.A.S. | Wholesale cigar resale revenue | Dependence on territory-specific distribution access | Develop additional trade relationships within distribution rights |
| Retail selling | Retail operators such as Scandinavian Tobacco Group A/S through its Cigars International superstores | Retail cigar sales | Dependence on individual store catchments | Broaden consumer access across multiple selling locations |
| Source: Mordor Intelligence | ||||
In 2025, Scandinavian Tobacco Group said operational errors and supply-chain issues destabilized its machine-rolled cigar business, alongside external pressures, difficult market conditions, and rising costs. These combined pressures affected its market share, volumes, and profitability. Scandinavian Tobacco Group's experience shows why tighter process control and backup supply can help preserve product flow, while added distribution reach cannot by itself correct unstable factory execution. Stabilizing output comes before expanding the downstream routes that depend on it for a producer facing these operational problems.
Competitive Landscape
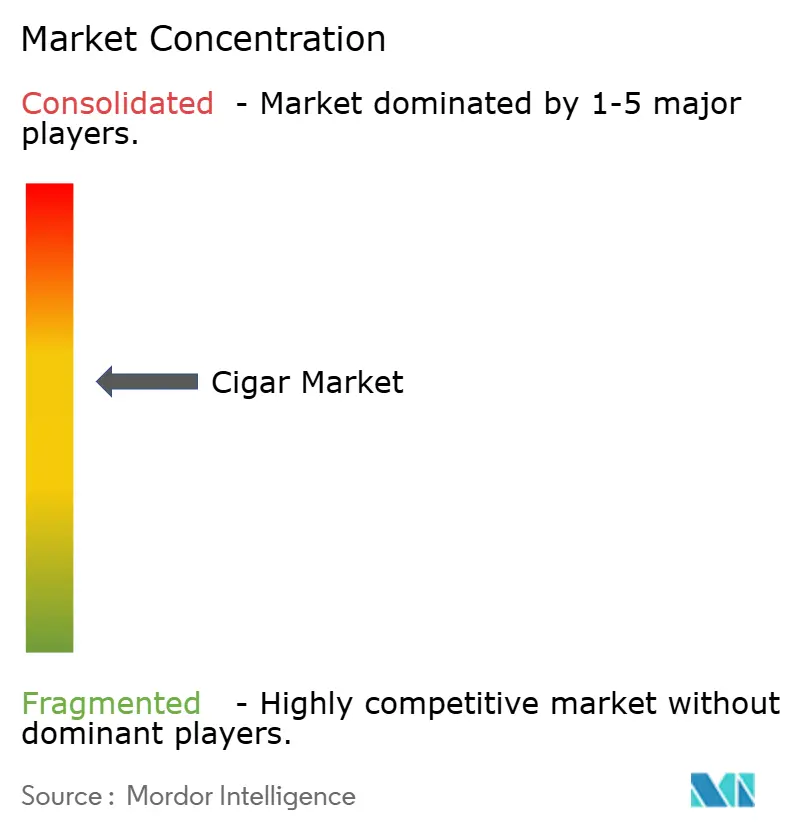
The industry has a mixed competitive structure, with several large tobacco groups competing through brand portfolios and distribution relationships. Leading participants include Scandinavian Tobacco Group A/S, Imperial Brands Plc, China National Tobacco Corp (CNTC), Altria Group Inc, and Swisher International Inc. Scandinavian Tobacco Group's US handmade cigar sales to external wholesalers and distributors rose 6% organically in 2025, with mid-single-digit volume growth and low-single-digit price/mix improvement. Swisher International Inc. manufactures Swisher Sweets Foil Pouch cigarillos, which Intercontinental Trading Corp. imports and sells in Japan. Wholesalers can gain throughput and higher-value assortments from a supplier growing both volume and price/mix, making competitive strength broader than a contest over the lowest unit price.
China Tobacco International (HK), a CNTC subsidiary, signed exclusive distribution agreements in 2025 with 4 Chinese tobacco industrial companies for international markets excluding mainland China. The agreements established a unified platform for Great Wall, Huanghelou, Taishan, and Wangguan cigars, combining several brand businesses within one international distribution framework. The subsidiary also reported substantial growth in its duty-paid cigar business during 2025. Overseas trade customers can source several Chinese brands through one distributor, while brands outside the platform need separate distribution arrangements.
In the 6 months ended March 31, 2026, Imperial Brands' mass-market cigar portfolio share in the Americas declined 39 basis points. Backwoods nevertheless gained share within the natural-leaf segment during that period. The company said Backwoods had taken price increases to offset higher tariffs, making trade-policy exposure part of its brand economics. Those divergent results favor separate investment decisions for individual brands rather than treating a broad cigar portfolio as a single competitive proposition. Recovery of tariff costs must accompany brand-specific demand if a successful cigar niche is to strengthen the wider portfolio.
Cigar Industry Leaders
-
Scandinavian Tobacco Group A/S
-
Imperial Brands Plc
-
China National Tobacco Corp (CNTC)
-
Altria Group Inc
-
Swisher International Inc.
- *Disclaimer: Major Players sorted in no particular order
Cigar Market Companies Covered in this Report
- Scandinavian Tobacco Group A/S
- Imperial Brands Plc
- China National Tobacco Corp (CNTC)
- Altria Group Inc
- Burger Holding AG
- British American Tobacco Plc
- Philip Morris International Inc
- PT Intertobacco Utama Industry
- Japan Tobacco Inc
- Villiger Söhne AG
- Arnold André GmbH
- J. Cortès Cigars NV
- Continental Tobacco Corp.
- Cia Canariense de Tabacos SA
- PT Djarum
- Tabacalera USA Inc
- Joh. Wilh. von Eicken GmbH
- Oettinger Davidoff AG
- Swisher International Inc.
- Corporación Habanos SA
Key Opportunities for Market Participants
The opportunities compare routes to specialist-store distribution with price- and occasion-focused cigarillo demand. In its Q4 2025 survey, the Premium Cigar Association found that 85% of responding retailers typically learned about new products from sales representatives or brokers.[3] A July 2026 UK trade report separately described price as a key purchase driver for adult nicotine users and linked cigarillo appeal to smaller formats and shorter smoking time. A supplier therefore faces 2 distinct commercial tasks, gaining a retailer's attention and giving an adult smoker a concrete reason to select the finished cigar.
Market Opportunities Table of Cigar Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Representative-led placement of boutique cigars | Representative-led product discovery among surveyed specialist retailers | Specialist cigar retailers | Introduce a focused range through cigar brokers | Converting introductions into retailer orders | Boutique cigar brands and specialist brokers |
| Affordable cigarillo pack choices | Price sensitivity in broader UK tobacco purchasing | Price-conscious adult cigarillo buyers in the United Kingdom | Offer clear pack-price choices for cigarillos | Preserving earnings at a lower pack outlay | Scandinavian Tobacco Group UK |
| Cigarillos for shorter smoking occasions | Smaller size and shorter smoking time support format appeal | Adult smokers seeking shorter cigarillo occasions | Build a distinct short-occasion cigarillo proposition | Substitution for existing cigarillo purchases | Scandinavian Tobacco Group UK and cigarillo retailers |
| Source: Mordor Intelligence | |||||
The central opening is to distinguish what the adult cigarillo buyer is being asked to commit before choosing the product. A lower pack outlay addresses cash commitment, while a shorter cigarillo addresses time commitment. Treating those benefits separately gives suppliers a way to test incremental demand instead of mistaking a pack change for a new consumption occasion.
Recent Industry Developments in Cigar Market
- Oct 2026: Drew Estate said its Undercrown 10 Gordo cigar was ready to ship to retailers, with the new size limited to 3,000 boxes.
- Oct 2026: Brazil's Anvisa opened consultations on revised health warnings for tobacco-derived smoking-product packages and displays, with comments due November 23, 2026.
- Jul 2026: Spain's Guardia Civil seized 33,840 counterfeit Habanos cigars in Valencia after detecting shipments from the same location to several European countries.
Cigar Market Report Scope and Research Methodology
Market Definition and Coverage
The cigar market measures annual retail spending on cigars and cigarillos sold for adult consumption in the Global market. It covers these products across flavor and price categories and sales through offline and online retail stores.
Scope exclusions: Cigarettes, e-cigarettes and heated tobacco devices, loose tobacco used for roll-your-own products, and humidors and cigar accessories sold separately are excluded.
Segments Covered in This Report
- By Product Type
- Cigarillos
- Cigar
- By Flavor
- Flavored
- Non-Flavored
- By Price Point
- Mass
- Premium
- By Distribution Channel
- Offline Retail Stores
- Online Retail Stores
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Illustrative public sources such as World Health Organization tobacco surveillance and product definitions, European Commission product regulations and excise categories, and Cigar Association of America summaries of imports and taxable releases help analysts classify products, understand tax conditions, and cross-check U.S. cigar supply signals. The Commission's product and tax material also clarifies how cigars and cigarillos are treated as manufactured tobacco categories across European Union rules.
Producer annual reports and securities filings can clarify reported cigar sales, mix, channel exposure, and price or cost changes, while reputable trade press and company investor material can date product, distribution, and regulatory developments. These sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews would draw on cigar and cigarillo producers and importers, wholesalers, retail buyers, and specialists in tobacco regulation and distribution to test how secondary sales, tax, and channel evidence should be interpreted. Analysts would reconcile differing volume, price, and product-mix reports by checking each source's geography, product coverage, and selling level, then triangulate gaps with trade statistics, taxable releases, and sampled retail price-by-volume checks.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 26% | CXOs: 20% | APAC: 45% |
| Mid tier: 54% | Functional/Unit leaders: 36% | EMEA: 30% |
| Smaller Players: 20% | Managers: 44% | Americas: 25% |
Market-Sizing & Forecasting
A top-down estimate starts with global retail value for finished cigars and cigarillos and reconciles reported market revenue with country-level supply and retail evidence. Analysts track cigar and cigarillo import flows, taxable domestic releases, producer-reported sales, retail prices and excise changes, and product, price-tier, and channel mix. Trade and release volumes indicate supply but are checked against consumer sales to account for inventory and cross-border flows. Scenario analysis carries forward adult demand, retail price and premium mix, tax changes, and offline versus online access, while selective bottom-up checks multiply sampled retail prices by supported unit volumes and compare supplier or channel roll-ups with the total. Segment shares are built from available product, flavor, price, channel, and regional sales evidence, with specialist input used to question variable-level assumptions and explain gaps. Where a country-level price or volume observation is missing, analysts use the closest documented market evidence and retain a range for review.
Data Validation & Update Cycle
Analysts triangulate market totals and segment shares against independent import, taxable-release, company-sales, pricing, and regulatory signals, then investigate material variances and anomalies before sign-off. A second review checks source dates, market boundaries, units, and calculations, with source re-contact triggered by conflicting definitions, unexplained movements, or a material change in an input. The model is refreshed annually, revisited between cycles after material policy or market events, and checked again in a fresh pre-delivery review.
Mordor Intelligence's Cigar Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The cigar market measures annual retail spending on cigars and cigarillos sold for adult consumption in the Global market.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Analysts track cigar and cigarillo import flows, taxable domestic releases, producer-reported sales, retail prices and excise changes, and product, price-tier, and channel mix.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 62.92 B (2027) | |
| Global Market Research Publisher A | USD 55 B (2025) | At its 2025 base, this estimate is 12.6% below this report's 2027 value of USD 62.92 B, 2 years later. Its published annual growth path is slower than the report's, which can contribute to a lower later-year comparison. |
| Global Market Research Publisher B | USD 31.7 B (2025) | At its 2025 base, this estimate is 49.6% below this report's 2027 value of USD 62.92 B, 2 years later. Its published growth rate is lower than the report's and the base is older, both of which point toward a lower value at the report's later measurement year. |
Mordor Intelligence's analysts triangulate market totals and segment shares against independent import, taxable-release, company-sales, pricing, and regulatory signals, then investigate material variances and anomalies before sign-off.
Key Questions Answered in the Report
What is the cigar market size and growth outlook?
The industry is projected to reach USD 62.92 billion in 2027 and USD 80.61 billion by 2032, with a CAGR of 5.08% from 2027 to 2032.
Which forces support cigar demand?
Prestige cigars and wider boutique distribution support demand. In a 2025 US survey, 60% of responding tobacconists named Fuente Fuente OpusX among the brands consumers requested most often.
Which cigar product type leads sales value?
Cigars led product types with a 59.33% share in 2026. Cigarillos are projected to grow at a CAGR of 5.97% from 2027 to 2032.
Which companies are leading cigar suppliers?
Leading participants include Scandinavian Tobacco Group A/S, Imperial Brands Plc, China National Tobacco Corp (CNTC), Altria Group Inc, and Swisher International Inc.
What is a major challenge for cigar sellers?
High taxes and sales restrictions constrain pricing and access to buyers. Canada's additional cigar duty uses the greater of a per-cigar minimum or 88% of the sale price for Canadian-made cigars or duty-paid value for imports.
Which region leads cigar spending and growth?
Asia-Pacific led with a 54.66% share in 2026 and is projected to grow at a CAGR of 5.95% from 2027 to 2032, the fastest regional rate.