
Tobacco Market Analysis by Mordor Intelligence
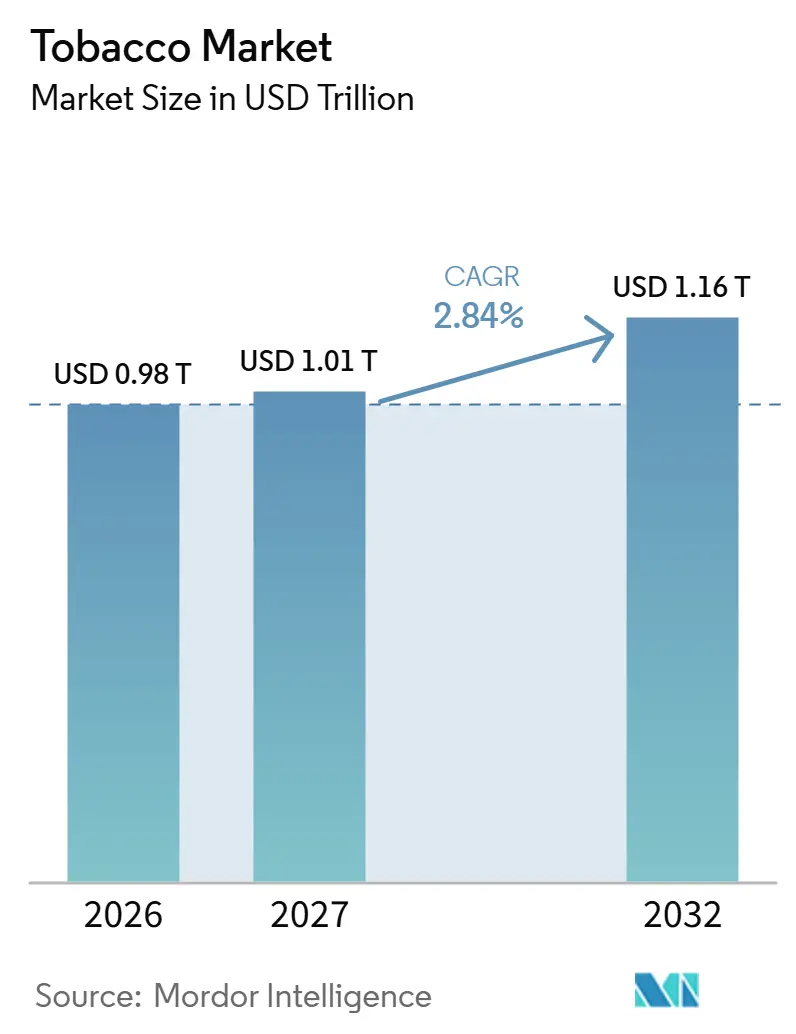
The tobacco market size was valued at USD 0.98 trillion in 2026 and estimated to grow from USD 1.01 trillion in 2027 to reach USD 1.16 trillion by 2032, at a CAGR of 2.84% during the forecast period (2027-2032).
The growth case combines recurring tobacco use with adoption of alternative nicotine formats, including vaping, while regulation shapes which products can reach buyers. Suppliers respond through broader product portfolios and country-specific market-access work. Price sensitivity in India makes tax pass-through a competing pressure on affordability and producer economics. Expansion therefore favors suppliers that can serve recurring users through lawful alternative formats.
Key Report Takeaways
- By product type, cigarettes held an 82.33% tobacco market share in 2026, while heated tobacco products are the fastest-growing segment at a forecast CAGR of 3.89% during 2027-2032.
- Across categories, mass led with an 84.14% share of the tobacco market size in 2026, and premium is the fastest-growing segment at a forecast CAGR of 4.31% during 2027-2032.
- Among end users, men held the largest share at 75.37% in 2026, while women are the fastest-growing segment at a forecast CAGR of 4.03% during 2027-2032.
- By distribution channel, convenience/grocery stores led with a 52.36% share in 2026, and online retail stores are the fastest-growing segment at a forecast CAGR of 5.08% during 2027-2032.
- Geographically, Asia-Pacific held the largest share at 45.23% in 2026 and is also the fastest-growing region, with a forecast CAGR of 4.34% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Tobacco Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Product Innovation and Alternative Nicotine Formats | +1.25% | Across the Czech Republic | Medium term (2-4 years) |
| Harm-Reduction and Reduced-Risk Product Positioning | +1.05% | Across the United States | Medium term (2-4 years) |
| Urbanization and Lifestyle Stress Factors | +0.65% | West Bank educational institutions | Long term (≥ 4 years) |
| Strong Brand Loyalty and Habit Persistence | +0.9% | Nationwide in Ireland | Long term (≥ 4 years) |
| Flavor Innovation and Sensory Differentiation | +0.5% | Japan at national level | Short term (≤ 2 years) |
| Marketing Through Packaging and Point-of-Sale Strategies | +0.4% | Across Washington, DC | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Product Innovation and Alternative Nicotine Formats
In the Czech Republic, 11.6% of people surveyed in 2025 reported using e-cigarettes at least monthly, establishing a recurring user base for an alternative format. Philip Morris ČR a.s. reported 2.3 billion smoke-free product shipments in the country in 2025 across its combined smoke-free categories. Growth in its vaping category was partly offset by lower heated-tobacco consumables, leaving a mildly positive overall volume outcome. Monthly use and substantial producer shipments give alternative formats a commercial foundation beyond the availability of new devices alone. Selective investment in vaping is therefore more defensible than assuming that every smoke-free format follows the same demand path.
Harm-Reduction and Reduced-Risk Product Positioning
Product-specific risk communication gives adult cigarette users a concrete basis for considering alternative nicotine formats. On June 30, 2026, the U.S. FDA issued modified-risk orders for 20 ZYN nicotine pouch variants, allowing PMI U.S., the U.S. business of Philip Morris International Inc. (PMI), to market a specific lower-risk claim. The permitted claim links using the authorized products instead of cigarettes to lower risks of mouth cancer, heart disease, lung cancer, stroke, emphysema and chronic bronchitis. British American Tobacco plc (BAT) added 4.7 million adult consumers across its own Smokeless brands in 2025 and estimated 35 million legal-age consumers by June 30, 2026, across vapor, heated and oral products. The communication advantage belongs to the cleared ZYN variants and their specific switching claim, so broader adoption does not give every nicotine pouch the same positioning.
Urbanization and Lifestyle Stress Factors
Occupational stress and smoking were associated within one nursing-faculty cohort, placing tobacco use in a specific working-life context. A survey conducted from December 1, 2024, to January 31, 2025, covered nursing faculty at 17 Palestinian educational institutions in the West Bank. Current smokers reported higher occupational stress than nonsmokers and former smokers, with a significant cross-sectional association between smoking status and stress levels. The comparison connects smoking status with workplace pressure among these educational professionals rather than with a particular product format. For suppliers serving this cohort, occupational circumstances provide a distinct customer context alongside product preferences.
Strong Brand Loyalty and Habit Persistence
Repeated daily use gives suppliers a recurring demand base with a different commercial value from occasional product experimentation. In Ireland, 11.7% of people aged 16 and older reported daily use of tobacco, vaping and nicotine products in 2025.[1] The comparable figure was 9.3% in 2022. The combined product group included water pipes, heated tobacco, chewing tobacco, nicotine pouches and e-cigarettes with or without nicotine. Within that pooled group, occasional use rose only from 3.2% to 3.7% over the same period, so most expansion in reported use involved a daily routine rather than occasional participation.
Restraints Impact Analysis of Tobacco Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent Tobacco Control Regulations | -0.75% | Across the United Kingdom | Short term (≤ 2 years) |
| Rising Social Stigma Around Smoking | -0.55% | North America, Europe, Asia-Pacific, South America, Middle East and Africa | Long term (≥ 4 years) |
| Supply Chain and Raw Material Constraints | -0.35% | Brazil, Bangladesh, Mexico, Pakistan, United States and India | Short term (≤ 2 years) |
| Public smoking bans and anti-smoking campaigns | -0.25% | France at national level | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Stringent Tobacco Control Regulations
Product design can determine whether a nicotine vape has a lawful route to UK buyers. Since June 1, 2025, UK businesses have been prohibited from selling or supplying single-use vapes online or in shops.[2] The restriction covers products with and without nicotine, directly including disposable nicotine vapes within its reach. Because both sales channels are covered, moving a prohibited product from a store to an online seller offers no distribution workaround. Reusable vapes remain saleable, preserving an alternative route for suppliers able to offer that format. For single-use suppliers, regaining access therefore requires a different product architecture, so a redesign must be completed before the format can re-enter the UK channel.
Rising Social Stigma Around Smoking
Social disapproval can constrain cigarette demand by reducing the situations in which a buyer is willing to smoke. The act of smoking places product use within a social setting, so the constraint attaches to consumption as well as to the purchase. A preferred brand can retain its appeal to the individual while becoming harder to use around other people. A lower price may ease the financial burden, but it does not directly resolve objections to the smoking occasion itself. For manufacturers, this separates brand retention from repeat consumption, because conventional product and pricing responses may not remove an occasion-based limit on demand.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Tobacco Market Segment Analysis
By Product Type:
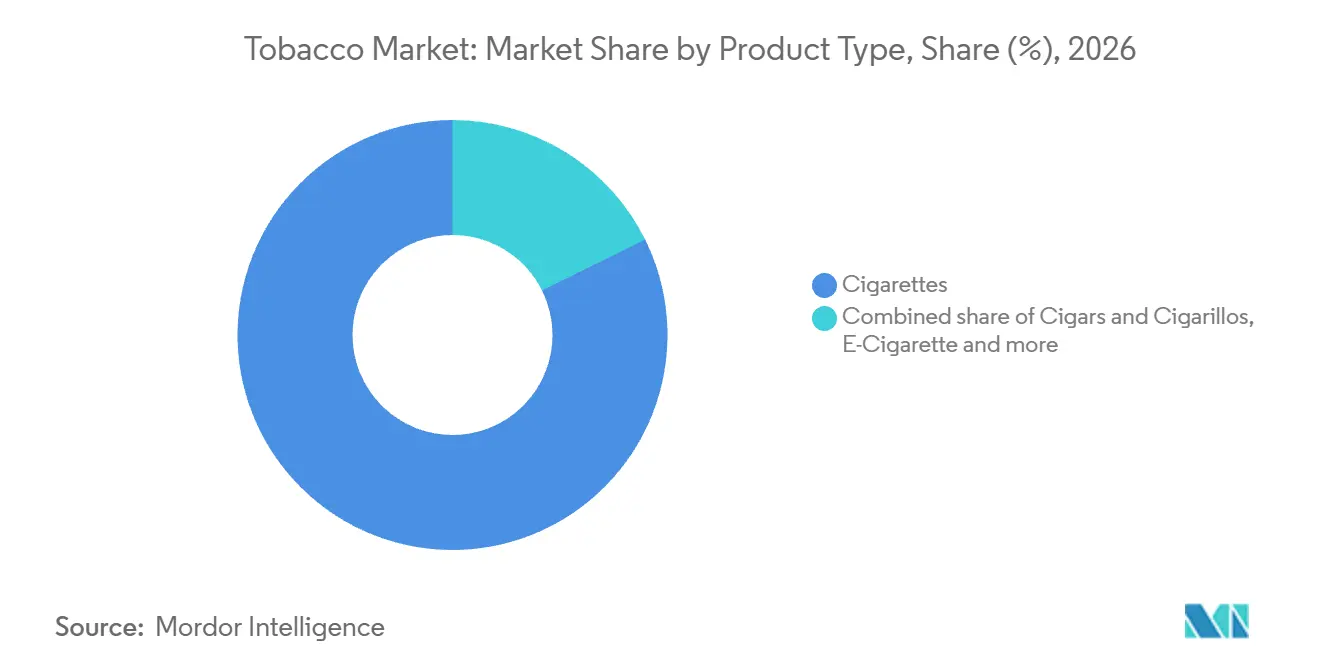
Cigarette Scale and Heated-Tobacco ExpansionCigarettes held the largest segment share at 82.33% in 2026. Philip Morris International Inc. shipped 607.4 billion cigarettes globally in 2025, illustrating the scale of one established producer’s cigarette business. British American Tobacco plc sold 465 billion cigarette sticks globally that year, down 8% from 505 billion in 2024. A 1% volume change would equal about 6.1 billion cigarettes for PMI and 4.7 billion sticks for BAT, but BAT’s 8% decline places that operating scale within its contracting cigarette business.
Heated tobacco products are the fastest-growing segment, with a forecast CAGR of 3.89% during 2027-2032. In the second quarter of 2026, PMI’s IQOS adjusted in-market sales volume grew 5.1% year over year, excluding the net impact of estimated distributor and wholesaler inventory movements. The result included expected household stock reductions and initial consumer adjustment after Japan’s April 1 excise-driven price increase, alongside Poland’s characterizing-flavor ban. These pressures connect the commercial outcome to excise and flavor policy as well as product adoption. An offer for heated-tobacco consumables has to accommodate local policy changes, which ties expansion to execution within each selling jurisdiction.

By Category:
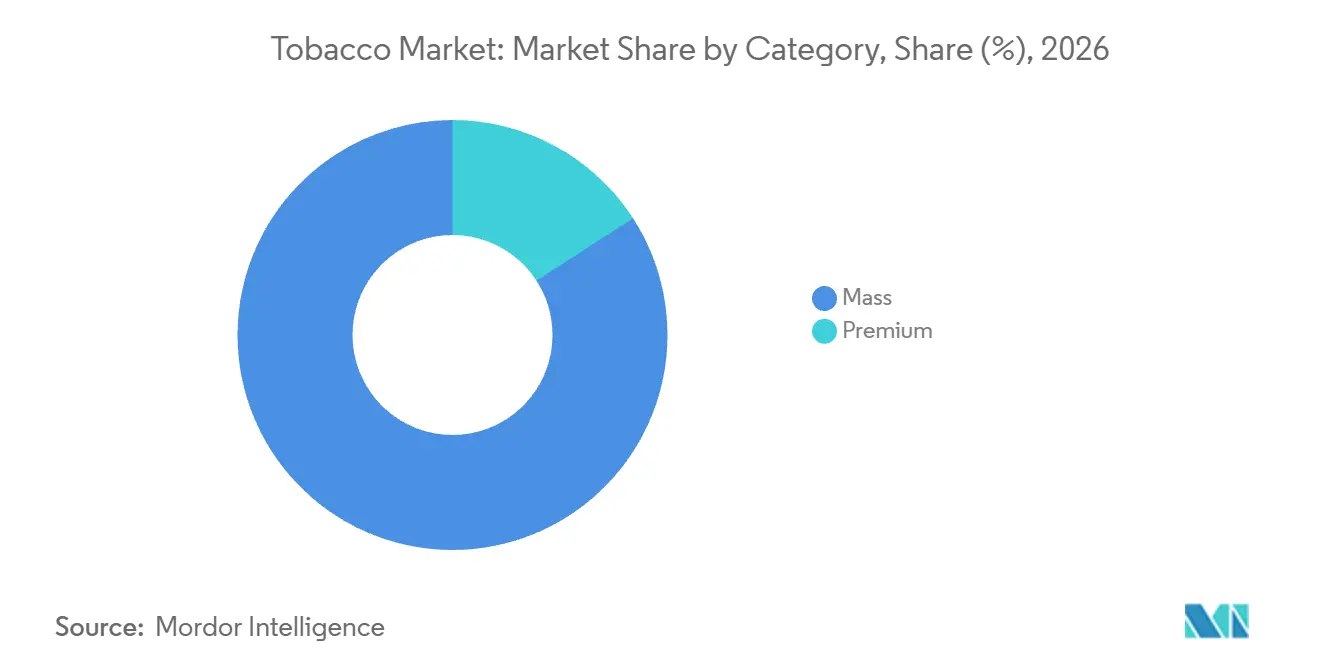
Mass Affordability and Selective Premium GrowthMass was the largest segment, with an 84.14% share in 2026. In January 2026, CRISIL Ratings classified cigarettes under 65 mm as India’s mass segment and described the category as highly price sensitive. The same assessment expected producers to absorb part of a duty increase because of that price sensitivity. That tier accounted for 40% to 45% of India’s cigarette volumes, so the cost producers absorb applies to a large part of the country’s cigarette output.
Premium is the fastest-growing segment, with a forecast CAGR of 4.31% during 2027-2032. Oettinger Davidoff reported 2025 sales growth of 2.4% for Davidoff and 16.1% for Zino within its own-brand cigar segment. Premium cigar suppliers can approach expansion through a differentiated brand portfolio, using the contrast in sales performance to identify which part of their offer is gaining commercial momentum. The opportunity is selective, because premium positioning gives access to a category but does not equalize the demand captured by individual brands within the same owner’s portfolio.
By End User:
An Established Male Base and Female Revenue ExpansionMen accounted for a 75.37% share of the tobacco market size in 2026, making them the largest segment. In the Czech Republic, 25.7% of men aged 15 and older were current smokers of tobacco products in 2025, including daily and at-least-monthly occasional smokers. The measured tobacco group covered manufactured and hand-rolled cigarettes, pipes, cigars, cigarillos and water pipes. The segment’s commercial weight therefore rests on an established smoking population that spans multiple traditional product forms rather than a single cigarette format.
Women are the fastest-growing segment, with a forecast CAGR of 4.03% during 2027-2032. In 2025, 18.6% of women aged 15 and older in the Czech Republic were current tobacco smokers. Haypp reported that cans sold to female nicotine-pouch customers on Haypp.com and Northerner.com in the United Kingdom rose 202% in 2025. This gives pouch suppliers a growth route among women on those platforms that does not depend on expanding the traditional-smoking population.
By Distribution Channel:
Convenience-Store Reach and Online TransactionsConvenience/grocery stores represented a 52.36% tobacco market share in 2026, making them the largest segment. In the United States, convenience stores handled 82.9% of cigarette sales in 2025, according to NIQ data supplied by NACS, the convenience-store association. The channel also handled 92.9% of U.S. other tobacco product sales that year. A supplier without convenience-store distribution in the United States therefore has other channels for no more than 17.1% of cigarette sales and 7.1% of other tobacco product sales.
Online retail stores are the fastest-growing segment, with a forecast CAGR of 5.08% during 2027-2032. Haypp Group recorded 1.45 million orders through its e-commerce business in the second quarter of 2026, compared with 1.17 million a year earlier. Its active-consumer count reached 667,000 in that quarter, compared with 536,000 in the second quarter of 2025. Orders and active consumers each rose by roughly a quarter, so Haypp’s transaction growth accompanied a wider customer base rather than only heavier ordering from existing buyers.
Geography Analysis
Asia-Pacific Tobacco Market
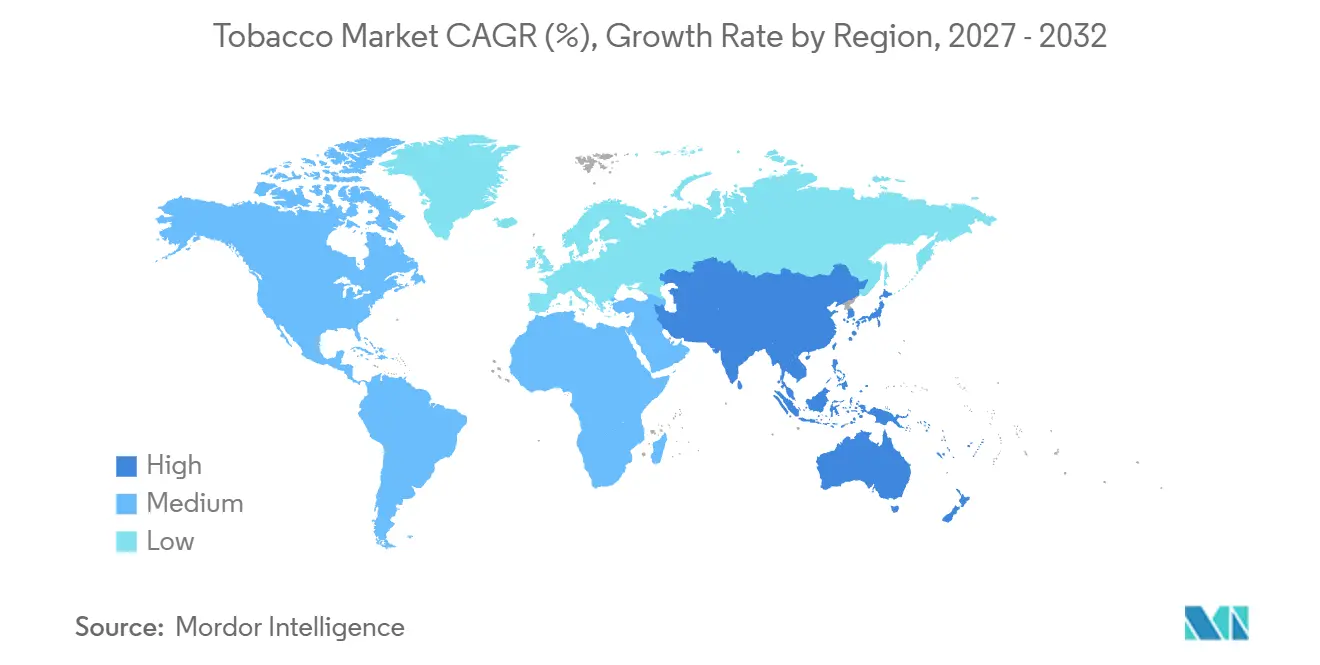
Asia-Pacific held a 45.23% tobacco market share in 2026 and was the largest and fastest-growing geography, with a forecast CAGR of 4.34% during 2027-2032. WHO estimated 364 million tobacco users aged 15 years and older in its South-East Asia Region and 431 million in its Western Pacific Region in 2024. Japan Tobacco reported 34% more Ploom users in Japan in December 2025 than in December 2024, following the Ploom AURA launch. PT HM Sampoerna Tbk. reported 79.4 billion units shipped in Indonesia in 2025, down 1.8% year over year, attributing the decline primarily to illicit erosion of legal-industry volume rather than competitive share loss. New heated-tobacco users create room for consumable sales, but illicit supply can erode the cigarette volumes supporting the established producer base.
North America presents a brand-positioning contest for cigarette producers serving established demand. British American Tobacco plc’s own cigarette value share in the United States increased by 30 basis points in 2025. Europe adds a distinct oral-tobacco business, illustrated by Philip Morris International Inc.’s 212 million cans of snus shipped in its company-defined Europe region in 2025. BAT’s U.S. value-share gain points to competition for cigarette spending, while PMI’s snus shipments fell from 236.7 million cans in 2024, making volume retention a distinct priority for its European oral-tobacco business.
South America offers scope for cigarette brand competition, with British American Tobacco plc reporting an increase in its own cigarette value share in Brazil in 2025. Winning a larger position within that country’s cigarette business is a commercial route distinct from relying on broader regional spending expansion. In the Middle East and Africa, British American Tobacco Kenya plc reported estimated illicit-cigarette prevalence of 45% in Kenya’s domestic cigarette market in 2025, up from 37% in 2024, citing third-party research. This creates a substantial competing channel outside the formal supplier’s revenue base. The 8-percentage-point increase in illicit prevalence means a larger share of Kenyan cigarette demand was served outside legal supply, so brand strength alone cannot recover lawful volume.
Regulatory Framework and Outlook
The comparison considers selected jurisdictions from the perspective of a lawful finished-product manufacturer seeking to supply domestic retail demand. China requires tobacco-product manufacturers to obtain a production-enterprise license and approval for production-capacity expansion through construction or technical upgrading. Product registration, production permission and retail buyer eligibility therefore affect different parts of the commercial decision, from committing manufacturing capacity to converting output into lawful sales.
Regulatory Table of Tobacco Market
| Decision factor | United Kingdom | China | Brazil |
|---|---|---|---|
| Primary authority | Trading Standards in England, Wales and Scotland; local councils in Northern Ireland | State Tobacco Monopoly Administration, managed by MIIT | Anvisa |
| Key instruments or direction | Under-18 tobacco-sales penalty mechanism in England and Wales from October 29 to December 31, 2026; UK tobacco-sales cutoff for people born on or after January 1, 2009, from January 1, 2027 | Tobacco Monopoly Law production licensing and capacity-expansion approval | Registration of domestic and imported tobacco-derived smoking products; annual renewal |
| Commercial effect | Retail eligibility limits shape the accessible customer base | Permission is required for manufacturing entry and capacity expansion | Sale follows publication of registration approval; renewal maintains the right to sell |
| Current policy attractiveness | Medium | Low | Medium |
| Future direction of policy attractiveness | Hardening | No change | No change |
| Source: Mordor Intelligence | |||
China’s approval requirements and its December 2025 and January 2026 enforcement priorities support continuity in the compliance framework for an already licensed manufacturer. Brazil’s annual renewal requirement underpins a continuing market-access burden, while Anvisa’s 2026-2027 regulatory agenda lists an ongoing proposal to regulate nicotine-based smoking products. In England and Wales, the scheduled UK birth-date cutoff from January 1, 2027, replaces an under-18 threshold and progressively restricts the eligible retail customer base. From 2027, the UK cutoff will prevent younger cohorts from becoming eligible tobacco buyers as they age, so manufacturing permission alone will not preserve future customer reach.
Value Chain Stages
The value chain comparison follows leaf sourcing, finished-product manufacturing and consumer sales, showing where control of specifications and routes creates earning opportunities. In 2025, Philip Morris International Inc. contracted directly with farmers in Argentina, Brazil, Italy, Pakistan and Poland, with direct sourcing representing approximately 23% of its global leaf requirements. Most of its 2025 leaf requirements therefore sat outside direct farmer contracts, so the larger share of its leaf supply was not contracted directly with growers.
Value Chain Analysis Table of Tobacco Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Leaf sourcing and processing | Leaf suppliers and processors such as Universal Leaf Tobacco | Sales of leaf processed to manufacturer specifications | Obtaining leaf that meets manufacturer specifications | Qualify alternative growing origins against the same specifications |
| Finished-product manufacturing | Tobacco and nicotine manufacturers such as Philip Morris International Inc. and British American Tobacco plc | Finished-product sales | Coordinating production across distinct product forms | Stage capacity additions by product type |
| Distribution and consumer sales | Integrated brand retailers such as Philip Morris International Inc. | Product sales through owned retail and e-commerce | Different distribution requirements across markets | Combine direct sales and intermediary routes by market |
| Source: Mordor Intelligence | ||||
Independent leaf suppliers capture value through specification matching, while direct sourcing gives manufacturers a different way to organize the grower relationship. Further downstream, a manufacturer’s own consumer channels extend its role beyond production, linking commercial returns to the ability to operate locally suitable sales routes. The structural choice is how much of that coordination to retain internally, because ownership of an additional stage brings responsibility for its distinct operating demands.
Competitive Landscape
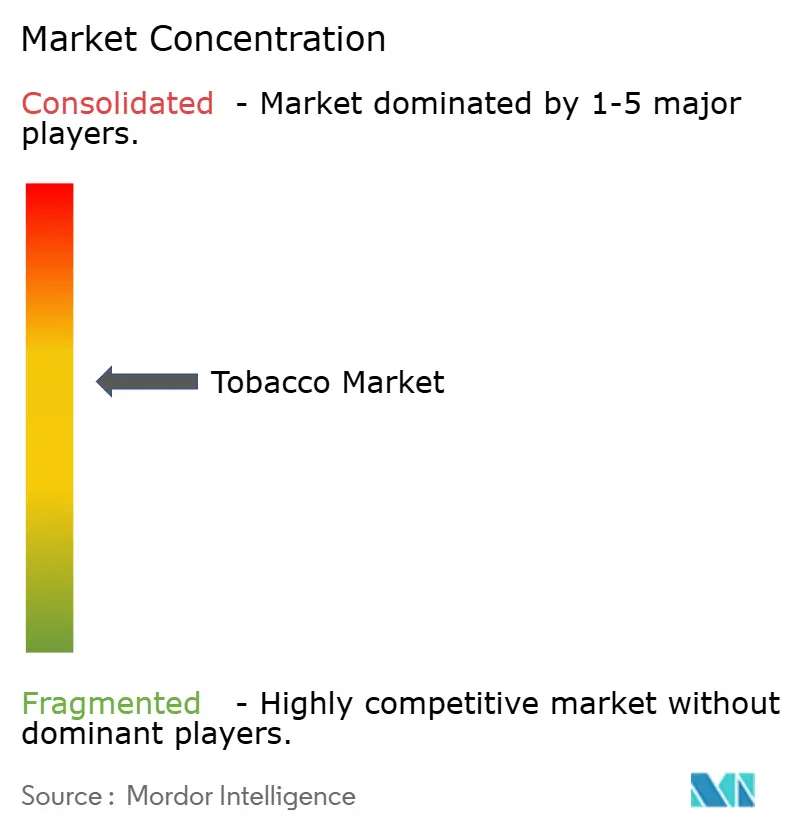
Major competitors include Philip Morris International Inc., British American Tobacco plc, Japan Tobacco Inc., Imperial Brands plc and KT&G Corporation. The industry has a concentrated multinational leadership tier, with rivalry extending across established tobacco products and alternative formats. PMI’s smoke-free business generated 41.5% of its total net revenue in 2025, giving that portfolio substantial economic weight within the company.[3] KT&G’s global cigarette business generated 54.1% of its group cigarette revenue in 2025, exceeding its domestic cigarette business for the first time. Because PMI draws substantial revenue from smoke-free products while KT&G’s cigarette revenue comes mostly from its global business, the same tax or product rule would affect their revenue bases differently.
In 2025, BAT launched Vuse Ultra, glo Hilo and Velo Shift across vapor, heated-product and modern-oral categories. Japan Tobacco reported Ploom volume growth of close to 40% in 2025 and continued share gains across its markets, including Japan. These approaches put portfolio breadth and platform execution at the center of competition, with a multi-category offer and a growing heated-product business creating different routes to adult consumers. Ploom’s volume gains make realized platform demand a stronger competitive signal than launch breadth alone.
PMI reported smoke-free products available for sale in 109 markets as of June 30, 2026. It estimated over 43 million legal-age consumers of its smoke-free products at December 31, 2025. On May 15, 2025, Imperial Brands plc met UK vaping-policy officials together with British American Tobacco plc, Japan Tobacco International and Philip Morris. The meeting addressed responses to a consultation on additional compliance measures for Vaping Products Duty. Their joint attendance places vaping-duty compliance on a shared regulatory agenda for these competing groups.
Tobacco Industry Leaders
-
Philip Morris International Inc.
-
British American Tobacco plc
-
Japan Tobacco Inc.
-
Imperial Brands plc
-
KT&G Corporation
- *Disclaimer: Major Players sorted in no particular order
Tobacco Market Companies Covered in this Report
- China National Tobacco Corporation
- Philip Morris International Inc.
- British American Tobacco plc
- Japan Tobacco Inc.
- Imperial Brands plc
- Altria Group, Inc.
- KT&G Corporation
- ITC Limited
- PT Gudang Garam Tbk
- Eastern Company SAE
- Japan Tobacco International (Logic, Ploom)
- Scandinavian Tobacco Group A/S
- Turning Point Brands, Inc.
- NTC Industries Limited
- Vector Group Ltd.
- Mac Baren Tobacco Company A/S
- PT Djarum
- Habanos S.A.
- Godfrey Phillips India Limited (Godfrey Phillips India)
- Universal Corporation
Key Opportunities for Market Participants
The opportunity comparison separates device adoption, consumable replenishment and product-range expansion for adult nicotine consumers in the United States. On August 28, 2026, the FDA authorized JUUL Labs Inc. to market the JUUL2 device and tobacco- and menthol-flavored pods in the United States. PMI U.S. began commercialization of ZYN ULTRA in June 2026 under recent FDA guidance, and PMI affiliate Swedish Match USA, Inc. makes the products. These developments create different commercial decisions around an authorized system, its continuing consumable offer and the staged development of a pouch range.
Market Opportunities Table of Tobacco Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| JUUL2 device adoption | A defined device has U.S. marketing authorization | Adult e-cigarette consumers | Develop device demand alongside the authorized pod offer | Product-specific marketing restrictions | JUUL Labs Inc. |
| JUUL2 pod replenishment | Tobacco- and menthol-flavored pods accompany the authorized device | Adult users choosing the JUUL2 system | Coordinate the device offer with compliant pod supply | Release testing before marketing covered cartridge batches | JUUL Labs Inc. |
| ZYN ULTRA range development | 11 products received U.S. authorization on August 21, 2026 | Adult nicotine-pouch consumers | Build the authorized range and stage further variants against review decisions | Additional 11 mg variants were under FDA review on August 21, 2026 | Swedish Match USA, Inc., a PMI affiliate |
| Source: Mordor Intelligence | |||||
The nearest-term opening is the JUUL2 system for adult e-cigarette consumers, with U.S. authorization covering the device and tobacco- and menthol-flavored pods. JUUL Labs must test specified nicotine, pH, endotoxin and beta-D-glucan measures in covered cartridge batches before marketing under the FDA’s JUUL2 orders. ZYN ULTRA offers a staged route, with 11 products authorized and additional 11 mg variants under FDA review on August 21, 2026, so range-extension spending should follow those decisions.
Recent Industry Developments in Tobacco Market
- Oct 2026: Scandinavian Tobacco Group A/S completed the sale of its BREAK and Moro fine-cut tobacco brands to Japan Tobacco Inc. on October 1.
- Aug 2026: The U.S. FDA authorized JUUL Labs Inc. to market the JUUL2 device and tobacco- and menthol-flavored pods in the United States on August 28.
- Aug 2026: The U.S. FDA authorized Swedish Match USA, Inc. to market 11 ZYN ULTRA nicotine pouch products in the United States on August 21.
Tobacco Market Report Scope and Research Methodology
Market Definition and Coverage
The global Tobacco Market measures annual consumer spending on finished tobacco and nicotine products sold for human consumption worldwide. It covers sales across the product, category, end-user, distribution-channel, and geographic classifications used in the report.
Scope exclusions: Raw tobacco leaf trade, vapor hardware sold without nicotine, and cannabis products are excluded.
Segments Covered in This Report
- By Product Type
- Cigarettes
- Cigars and Cigarillos
- E-Cigarette
- Heated Tobacco Products
- Smokeless Tobacco
- Other Product Types
- By Category
- Mass
- Premium
- By End User
- Men
- Women
- By Distribution Channel
- Convenience/Grocery Stores
- Specialty Stores
- Online Retail Stores
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
The World Health Organization's tobacco fact sheet and global prevalence report provide illustrative evidence on users, product families, and regional patterns, while its Global Health Observatory tax indicators and tobacco topic overview describe retail cigarette prices, affordability, and the economic context of tobacco use. National statistical releases and adult tobacco surveys can add country detail when analysts compare local prevalence and product-use trends with the global evidence.
Company annual reports and regulatory filings provide reported product sales, shipment trends, pricing, segment descriptions, and geographic exposure, while investor materials and reputable press coverage help clarify launches, tax changes, and market access developments. These sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured questionnaires would target tobacco and nicotine manufacturers, wholesalers, retail channel specialists, category analysts, and relevant regulatory or trade specialists across APAC, EMEA, and the Americas. Respondents would be asked to check the interpretation of secondary evidence, identify changes in finished-product pricing, product mix, availability, and route to market, and explain gaps where public reporting is limited. Analysts would compare these observations with company disclosures and country data, recording unresolved differences for follow-up and triangulation rather than treating a single account as market-wide evidence.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 15% | APAC: 45% |
| Mid tier: 55% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 15% | Managers: 50% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates global annual consumer spending at retail for finished products, then allocates value across the report's product, category, end-user, distribution-channel, country, and regional views. A top-down estimate starts with reported consumer sales and manufacturer or retailer revenue signals, with selective bottom-up checks using sampled retail prices times observed or reported unit volumes and supplier roll-ups. Those checks test whether country and product estimates are plausible without replacing the market-wide model. Key indicators include adult product-use prevalence and users by product, cigarette and alternative-product volumes, retail prices and tax changes, producer shipment and revenue disclosures, and channel or country sales patterns. Analysts use these indicators to estimate value and segment shares, keeping price and product mix separate from volume shifts where evidence permits, and apply scenario analysis to reflect differences in regulation, affordability, and uptake across markets. Experts would review variable-level assumptions and forecast paths against country and product evidence, while analysts investigate gaps by checking adjacent years, company disclosures, public price data, and comparable market signals before revising or documenting an assumption.
Data Validation & Update Cycle
Analysts triangulate company disclosures, country prevalence and price indicators, trade data, and channel evidence, then check for inconsistent totals, abrupt share movements, currency or unit errors, and unexplained differences from independent market signals. A second analyst reviews the calculations and source trail, and a lead reviewer resolves anomalies before sign-off. Material disagreements trigger source checks or respondent re-contact when a cited assumption, product boundary, or market event needs clarification. The model is refreshed annually, updated between cycles when material regulatory, tax, or product events change the market, and given a fresh source and calculation review before delivery.
Mordor Intelligence's Global Tobacco Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global Tobacco Market measures annual consumer spending on finished tobacco and nicotine products sold for human consumption worldwide.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Analysts use these indicators to estimate value and segment shares, keeping price and product mix separate from volume shifts where evidence permits, and apply scenario analysis to reflect differences in regulation, affordability, and uptake across markets.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 1.01 T (2027) | |
| Global Consultancy A | USD 926 B (2025) | At its 2025 base, this estimate is 8.3% below this report's 2027 value of USD 1.01 T, 2 years later. The source reports a 2025 base and projects later market growth through 2033, so the earlier measurement year contributes to a lower value than the report's 2027 estimate. |
| Global Consultancy B | USD 954.3 B (2025) | At its 2025 base, this estimate is 5.5% below this report's 2027 value of USD 1.01 T, 2 years later. The source reports a 2025 estimate and projects continued growth through 2035, so the earlier measurement year contributes to a lower value than the report's 2027 estimate. |
Mordor Intelligence's analysts triangulate company disclosures, country prevalence and price indicators, trade data, and channel evidence, then check for inconsistent totals, abrupt share movements, currency or unit errors, and unexplained differences from independent market signals.
Key Questions Answered in the Report
What is the Tobacco market size and growth outlook?
Size is estimated at USD 1.01 trillion in 2027 and forecast to reach USD 1.16 trillion by 2032, at a CAGR of 2.84% during 2027-2032.
Which forces support growth in tobacco and nicotine products?
Alternative formats and recurring use support demand. British American Tobacco plc added 4.7 million Smokeless consumers in 2025 and estimated 35 million legal-age consumers by June 30, 2026, across vapor, heated and oral products.
Which finished tobacco product type has the largest share?
Cigarettes held an 82.33% share in 2026, while heated tobacco products are forecast to grow fastest at a CAGR of 3.89% during 2027-2032.
Who are the leading tobacco and nicotine suppliers?
Major players include Philip Morris International Inc., British American Tobacco plc, Japan Tobacco Inc., Imperial Brands plc and KT&G Corporation.
Which regulatory challenge affects nicotine-product sales?
The UK ban on business sales and supply of single-use vapes, with or without nicotine, took effect on June 1, 2025, covering shops and online sales. Reusable vapes remain saleable.
Which region leads spending on finished tobacco and nicotine products?
Asia-Pacific held a 45.23% share in 2026 and is the fastest-growing region, with a forecast CAGR of 4.34% during 2027-2032.