
Wine Market Analysis by Mordor Intelligence
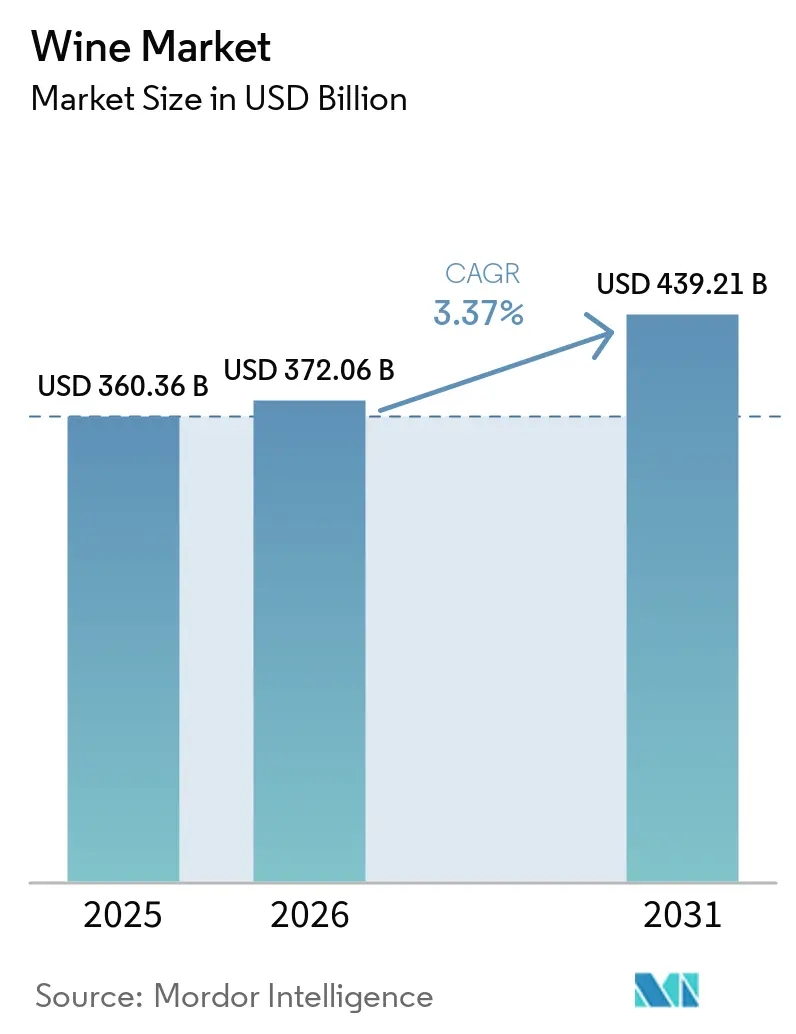
The wine market size was valued at USD 372.1 billion in 2026 and estimated to grow from USD 384.6 billion in 2027 to reach USD 447.6 billion by 2032, at a CAGR of 3.08% during the forecast period (2027-2032). The wine market volume was valued at 204.3 million Hectoliters in 2026 and estimated to grow from 205 million Hectoliters in 2027 to reach 208.6 million Hectoliters by 2032, at a CAGR of 0.35% during the forecast period (2027-2032).
Alcohol-free wine in Germany and winery visits in Spain broaden wine-buying occasions. Premium demand supports value growth, while grape costs restrict discounting flexibility. Suppliers respond by narrowing portfolios toward higher-priced brands and by relying on importers and distributors to reach trade buyers. With forecast value growth outpacing volume, premium mix and hospitality offer revenue expansion without depending on substantially more wine consumption.
Key Report Takeaways
- By product type, still wine held a 71.61% wine market share in 2026, while sparkling wine is forecast to grow fastest at a CAGR of 5.05% during 2027-2032.
- Color segmentation was led by red wine with a 48.15% share of the wine market size in 2026, and rosé wine is forecast to grow fastest at a CAGR of 3.9% during 2027-2032.
- Among end users, women accounted for 59.68% of wine sales value in 2026, while men are forecast to be the fastest-growing segment at a CAGR of 4.2% during 2027-2032.
- Distribution channels were led by off-trade with 59.51% of wine sales value in 2026, with on-trade forecast to grow fastest at a CAGR of 3.45% during 2027-2032.
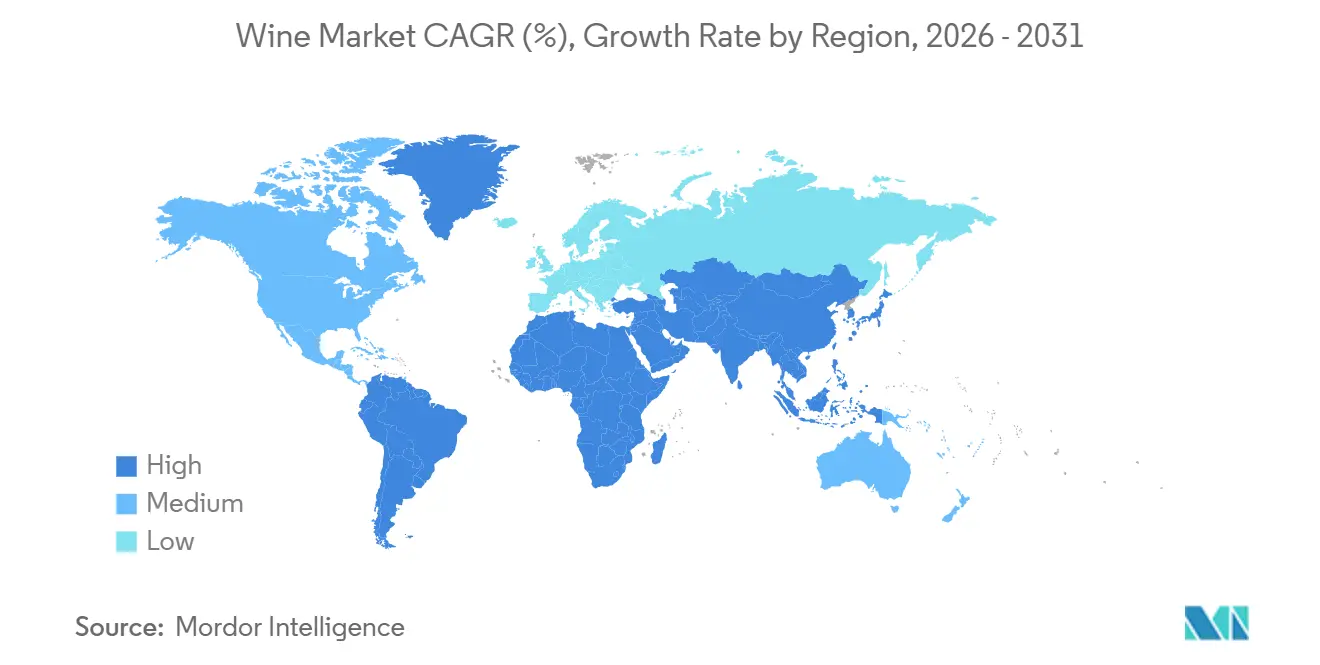
- Geographically, Europe held 45.06% of wine sales value in 2026, and Asia-Pacific is forecast to grow fastest at a CAGR of 5.2% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Wine Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing tourism and hospitality footprint | +1.1% | DOCa Rioja wine region | Short term (≤ 2 years) |
| Rising consumer preference for low-/no-alcohol wines | +0.8% | Retail markets in Germany | Short term (≤ 2 years) |
| Surge in premium and super-premium wine demand | +1.8% | United States and China | Medium term (2-4 years) |
| Climate-resilient varietal Research and Development expands viable terroirs | +0.6% | Winegrowing regions of France | Long term (≥ 4 years) |
| Blockchain-enabled provenance boosts online sales trust | +0.2% | Bolnisi winegrowing region | Medium term (2-4 years) |
| Vineyard robotics and AI analytics optimize yields | +0.3% | California Central Coast | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing tourism and hospitality footprint
Winery hospitality gives producers a direct point of contact with visitors who can become buyers of their wines. DOCa Rioja wineries in Spain received 930,364 visits in 2025, up 1.96% from 2024.[1] The designation counted 226 wineries open for wine tourism in 2025, compared with 214 in 2024. Because the number of venues grew faster than visits, regional traffic growth does not ensure higher traffic for each participating estate. Rioja estates can turn the larger hospitality footprint into wine demand through direct bottle purchases, while tasting fees alone add no wine sales.
Rising consumer preference for low-/no-alcohol wines
Alcohol-free wine gives producers a way to serve buyers for whom an alcoholic wine is unsuitable. In Germany, 44% more households bought alcohol-free wine through retail in 2025 than in 2024. German retail sales volume of alcohol-free wine rose 25% over the same period. Separately, one in 3 of the 506 wineries in the 2025 Geisenheim sales analysis reported alcohol-free wine in its assortment. Broader household reach and an established producer offering give this category a commercial basis beyond isolated product launches. The stronger expansion in household reach than in volume shifts the commercial task toward deepening purchases within that broader German retail buyer base.
Surge in premium and super-premium wine demand
Premium wine can support value growth when particular brands attract additional purchases within an otherwise stable category. Laurent-Perrier's US premium-cuvée volume increased 14% in Nielsen-tracked off-trade consumer pull-through in fiscal 2026 while the category was flat. Treasury Wine Estates' Penfolds depletions in China, measuring product moving from distributors into the market, rose 34.7% in the fiscal year ended June 30, 2026. Within Laurent-Perrier's fiscal 2026 US off-trade data, Cuvée Rosé, Blanc de Blancs Brut Nature and Grande Siècle each gained share and absolute volume. For premium suppliers, this favors backing labels with demonstrated sell-through before broadening the range, because higher-end positioning alone does not ensure category growth.
Climate-resilient varietal Research and Development expands viable terroirs
Climate-adapted varieties can protect the supply on which appellation wine sales depend. Resistant grape varieties covered 2,700 hectares in France in 2025, about 0.35% of the national vineyard area. Separately, for varieties of interest for climate adaptation, French protected-origin appellation rules cap plantings at 5% of a holding and their use at 10% of a bottle's blend. The Institut national de l'origine et de la qualité decides their status in appellation specifications after 10 years. Within those caps, growers can incorporate adaptation varieties into wines sold under established designations. Restricted blending and the lengthy review make this a gradual route to sustaining appellation wine sales, consistent with a long-term demand effect.
Restraints Impact Analysis of Wine Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent and divergent alcohol regulations | -0.6% | Retail markets in Scotland | Short term (≤ 2 years) |
| High production costs amplified by climate volatility | -0.75% | South Africa and Spain | Medium term (2-4 years) |
| Sophisticated counterfeits in e-commerce channels | -0.15% | Chianti wine production area | Medium term (2-4 years) |
| Glass and logistics bottlenecks inflate packaging costs | -0.25% | United States winery regions | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stringent and divergent alcohol regulations
Retail pricing rules can prevent wine sellers from using the full range of discounts to attract price-sensitive buyers. Scotland's minimum unit pricing law bars retailers from selling wine below the applicable legal minimum per unit of alcohol. Because the floor follows alcohol content, the constraint must be assessed against the strength and size of the wine being sold. A retailer willing to accept a thinner margin still cannot lower the shelf price of an affected bottle below the alcohol-based floor. Wines already priced above the floor may offer more promotional room, making the restriction especially relevant to offers positioned near the minimum. For the lowest-priced qualifying wines, regulatory compliance directly limits how far affordability can support additional demand.
High production costs amplified by climate volatility
Higher grape-growing costs and weather-sensitive output restrict the room wine producers have to stimulate demand through lower prices. Vinpro found that average South African wine-grape production costs rose 6.4% for the 2025 vintage compared with 2024, excluding dryland vineyards in Swartland. Separately, Spain's wine production fell 7.7% in 2025 from 2024 after a third consecutive year of drought and heatwaves contracted yields. A smaller harvest makes reliable supply harder to secure even when the commercial aim is to maintain sales. Producers absorbing higher upstream costs have less flexibility to discount, while passing costs onward risks weakening the affordability of their wines. The combined exposure constrains expansion through both supply reliability and the price needed to sustain production.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Wine Market Segment Analysis
By Product Type:
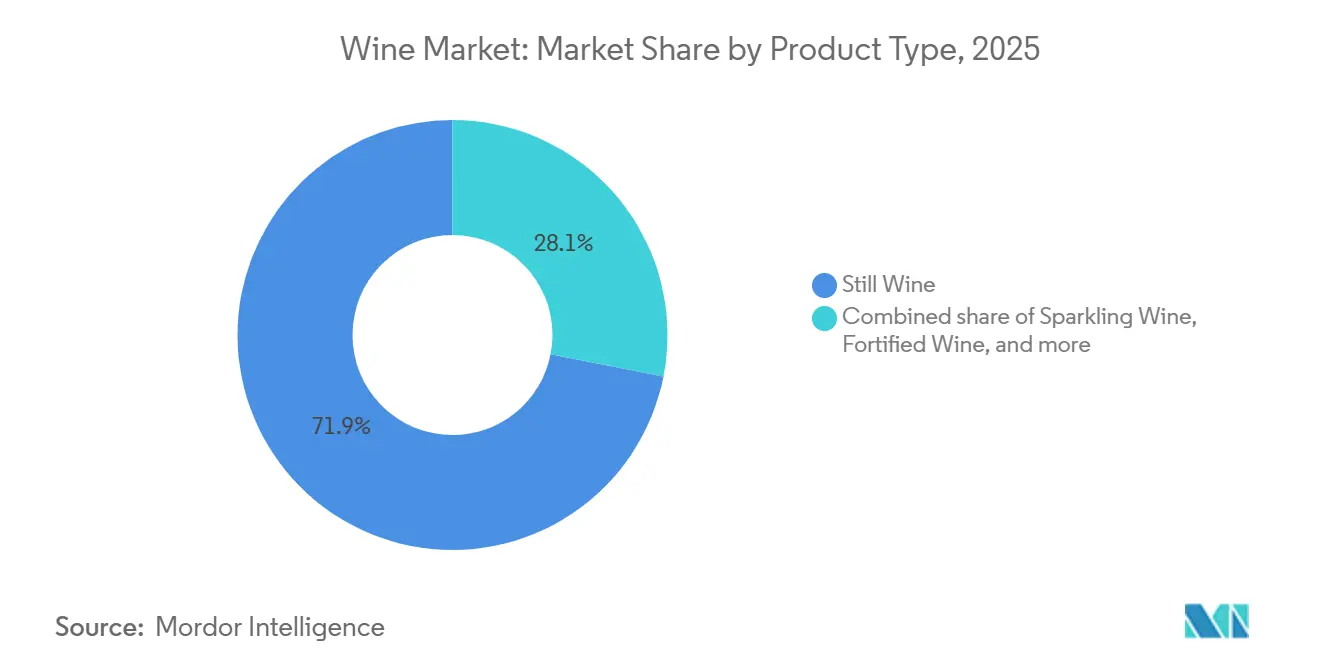
Still Wine Scale Meets Sparkling ExpansionStill wine accounted for a 71.61% share of the wine market size in 2026, making it the largest segment. Still-wine sales in France's Bourgogne-Franche-Comté totaled 1.26 million hectoliters in the 12 months through April 2026. Mass-retail weakness weighed on these regional sales, showing how channel pressure can coexist with a substantial annual still-wine sales base. Retaining mass-retail listings offers these regional producers a more direct defense of sales than adding output to a channel already losing volume.
Sparkling wine is forecast to be the fastest-growing segment, at a CAGR of 5.05% during 2027-2032. The 8 French Crémant appellations sold 122.9 million bottles in 2025 against 114.5 million in 2024, while their cellar releases rose 7.5% in 2025. Prosecco DOC bottled 667 million bottles in 2025, up 1.1% from 2024. Its US exports grew 8% in January-September 2025, when the country accounted for 23.8% of Prosecco DOC exports. Crémant sales rising alongside cellar releases show that sparkling expansion extends beyond Prosecco DOC bottling.



By Color:
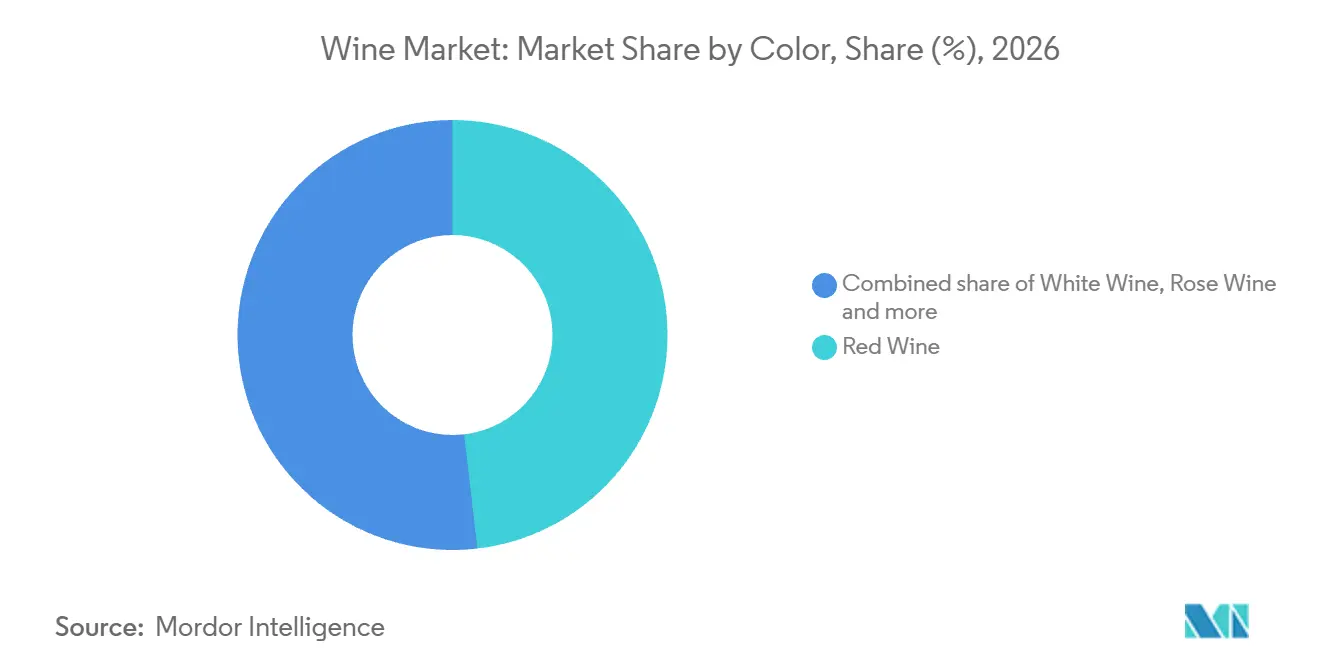
Red Wine Scale and Rosé Retail GrowthRed wine represented a 48.15% wine market share in 2026, making it the largest segment. Australian red-wine production rose 15% to 590 million liters in 2024-25 and returned to 52% of national wine output by volume after falling below white wine in 2023-24. Wine Australia's Market Insights manager, Peter Bailey, said red grapes accounted for nearly 90% of the additional grape-crush tonnage in 2025. Australian red producers have more wine to place with buyers before the output rebound can translate into higher revenue.
Rosé wine is forecast to be the fastest-growing segment, at a CAGR of 3.9% during 2027-2032. Australian retail off-trade sales of still bottled rosé rose 6% by volume in the year ended June 2026. The volume gain sat in bottled still rosé, so suppliers already holding Australian retail shelf space in that format are best placed to capture it.

By End User:
Women Anchor Demand as Men ExpandWomen were the largest end-user segment, accounting for 59.68% of wine sales value in 2026. Separately, the Wine Market Council's 2025/2026 benchmark put the US adult wine-drinker base at 79 million, of whom 54% were women. Because women make up the majority of that measured US drinker base, products and messaging aimed at them address the larger part of that US audience.
Men are forecast to be the fastest-growing end-user segment, at a CAGR of 4.2% during 2027-2032. In 2025, 70% of male US survey respondents reported buying Cabernet Sauvignon sometimes or regularly, against 57% of female respondents. In the same survey, 66% of men reported buying Pinot Noir sometimes or regularly, against 53% of women. Both red varietals attracted broader reported buying participation among men, pointing suppliers toward familiar red styles when building ranges for male US buyers.
By Distribution Channel:
Off-Trade Scale and On-Trade RecoveryOff-trade was the largest distribution segment, accounting for 59.51% of wine sales value in 2026. In the United Kingdom, off-trade represented 83.7% of total wine volume sold in the 12 months to March 2025. UK wine volume therefore reaches consumers mostly through retail, so a UK supplier's volume depends more on retailer range decisions than it does on restaurant placement.
On-trade is forecast to be the fastest-growing distribution segment, at a CAGR of 3.45% during 2027-2032. Ontario wineries' sales to restaurant licensees in Ontario rose 1.6% in value in the 12 months ending March 31, 2026, but remained below pre-pandemic levels. The opportunity for Ontario wineries is to recover restaurant business missing from that earlier sales base, so modest annual gains can support expansion before a new demand peak is reached.
Geography Analysis
Europe Wine Market
Europe accounted for 45.06% of the wine market size in 2026, making it the largest geography. European Union wine consumption totaled 100.6 million hectoliters in 2025, or 48% of world consumption, down 3.1% from 2024 and 6.9% from the previous 5-year average.[2] In 2025, Viva Wine Group integrated Netherlands-based wine importer and distributor Delta Wines, which became the foundation of its business-to-business platform outside the Nordics. For producers represented through Delta Wines, the EU contraction makes sales per listing a more relevant test of expansion than the platform's geographic reach.
Asia-Pacific Wine Market
Asia-Pacific is forecast to be the fastest-growing geography, at a CAGR of 5.2% during 2027-2032. Japan's preliminary wine consumption rose 6.8% from 2024 to 3.3 million hectoliters in 2025, in line with its 5-year average. Australian wine exports to Thailand increased 54% in value in the year ended June 2026 compared with the prior year. The Japanese rebound points to demand recovery, while the Thai export result identifies a distinct commercial route for suppliers seeking higher sales value. These different entry points favor country-specific expansion, with exporters able to pursue growing destination trade without assuming that every regional consumer base moves together.
The remaining regions combine substantial established consumption with sharply different recent demand conditions, creating different tasks for suppliers. In North America, US wine consumption was estimated at 31.9 million hectoliters in 2025, down 4.3% from 2024. In South America, Brazil was estimated to reach record consumption of 4.4 million hectoliters in 2025, up 41.9% from a low 2024 base and 19.9% above its 5-year average. Within Middle East and Africa, South Africa's estimated consumption fell 7.7% from 2024 to 4 million hectoliters in 2025 after peaking during 2022-2024. Brazil therefore offers a demand-rebuilding opening, whereas the US and South African readings put greater weight on retaining buyers within already substantial national consumption pools.
Regional Editions
All regions
Regulatory Framework and Outlook
Selected jurisdictions are compared through the labeling, registration and product-description duties that shape commercial wine operations. The perspective is that of wine producers operating in each country and serving domestic and export buyers. France's Directorate General for Competition, Consumer Affairs and Fraud Control (DGCCRF) oversees wine quality and label descriptions. Such enforcement roles make compliant presentation part of access to buyers, while different transition dates determine when producers need to adjust their wine offers.
Regulatory Table of Wine Market
| Decision factor | United States | France | China | Brazil | South Africa |
|---|---|---|---|---|---|
| Primary authority | Alcohol and Tobacco Tax and Trade Bureau | DGCCRF | State Administration for Market Regulation and local market-regulation departments | Ministry of Agriculture and Livestock (MAPA) | Minister of Agriculture's designated administering officer |
| Key instruments or direction | 27 CFR Parts 4 and 24; proposed Notices 237 and 238 for covered labels | EU ingredient and nutrition rules; export-only relief and harmonized dealcoholized terms from September 19, 2027 | Food label rules for the smallest sales unit; GB 7718-2025 and new measures from March 16, 2027 | Law 7,678/1988; Decree 12,709/2025, Article 49; standards-restoration proposal in 2026 | Liquor Products Act; 2026 label amendments; qualifying class-designation omission through December 31, 2027 |
| Commercial effect | Qualifying domestic intrastate label-approval exemptions retain Part 24 label and record duties | Electronic ingredient/nutrition details allowed, with allergens and energy on the physical label; wines produced before December 8, 2023 exempt until stocks are exhausted | From March 16, 2027, covered labels will need larger date text; tamper-evident wine boxes must display required particulars outside when bottle details cannot be read without breaking the seal | Register establishment and wine before covered operations, subject to express regulatory exceptions | Temporary class-designation omission depends on current wine-style exceptions |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Easing | Hardening | No change | Hardening |
| Source: Mordor Intelligence | |||||
US labeling and recordkeeping require routine compliance, while Notices 237 and 238 would add disclosures with a 5-year compliance period only after publication of any resulting final rule. France's physical-label duties support a moderate current rating, with electronic options and the September 19, 2027 ingredient/nutrition exemption for wine products solely intended for export easing compliance for affected producers. China's March 16, 2027 rules will raise applicable minimum date-text height from 1.8 to 3.0 millimeters for packages with maximum surface area of at least 35 square centimeters, and to 2.0 millimeters for others. Brazil's registration framework and proposed restoration of prior wine standards favor continuity, while South Africa's class-designation omission permission ends on December 31, 2027, creating a fixed transition for qualifying labels.
Value Chain Stages
The value chain compares where wine producers, packaging makers, distributors and retailers earn revenue as physical supply moves toward final wine sales. Treasury Wine Estates' group activities in the fiscal year ended June 30, 2026, included viticulture, winemaking, marketing, wine sales and distribution. O-I Glass supplied containers for wine and other beverages and sold most glass-container products directly under annual or multiyear supply agreements. Total Wine & More operated 294 US superstores across 30 states in August 2026, providing a substantial retail route to consumers.
Value Chain Analysis Table of Wine Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Integrated grape-growing and winemaking | Integrated wine producers such as Treasury Wine Estates | Wine sales | Climate exposure and grape supply-demand mismatch risk | Diversify sourcing across regions, varietals and price segments |
| Glass packaging supply | Glass-container manufacturers such as O-I Glass | Glass-container product sales | Packaging-price exposure to input-cost adjustments | Agree adjustment formulas and review points within supply terms |
| Wholesale distribution | Beverage-alcohol distributors such as Southern Glazer's Wine & Spirits | Wine distribution sales | Exposure to centralized warehouse backlogs | Establish recovery dispatch priorities after system outages |
| Retail sales | Wine retailers such as Total Wine & More | Retail wine sales | Risk that listed wines do not sell through | Adjust local assortments using observed retail demand |
| Source: Mordor Intelligence | ||||
In April 2026, Mississippi's state ABC warehouse faced delivery delays despite resolved technical issues, with more than 165,000 cases of wine and liquor held the preceding week. The state distribution center's backlog illustrates how a single hub can delay finished products reaching retail shelves. Treasury Wine Estates separately reported that diversification across regions, varietals and price segments supported management of climate-related physical risks in fiscal 2026. Where deliveries depend on a state distribution hub, upstream sourcing resilience cannot restore retail availability until that hub clears the goods for dispatch.
Competitive Landscape
Market Concentration
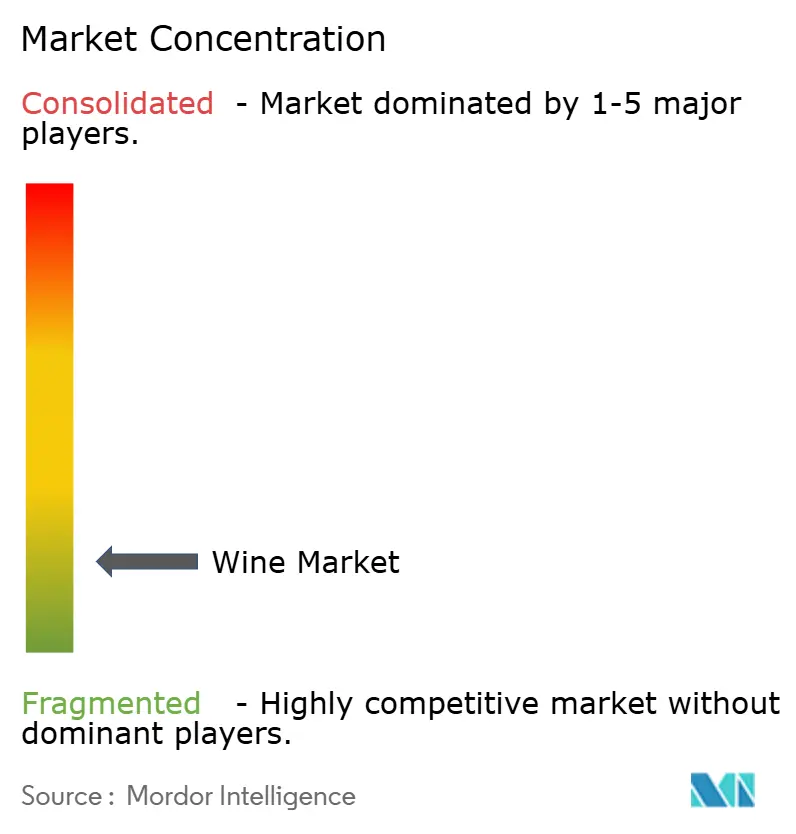
Competition combines large portfolio owners with separately positioned wine producers, creating a fragmented field with pockets of corporate scale. Major participants include Bacardi Limited with its MARTINI sparkling wines, GALLO, which reintroduced Ravenswood in March 2025 with 4 Zinfandel wines, Constellation Brands Inc., Vinarchy and Bronco Wine Company. On April 30, 2025, Pernod Ricard completed the sale of its international wine portfolio to Australian Wine Holdco, contributing to Vinarchy's creation. The transferred portfolio represented 10 million 9-liter cases annually and 7 wineries in Australia, New Zealand and Spain, with Pernod Ricard announcing continued distribution for a few months to support transition. Because the transferred platform ran from vineyard to bottle across 7 wineries, Vinarchy entered as an integrated producer, which raises the entry bar for challengers that source rather than make their wines.
On June 2, 2025, Constellation Brands Inc. completed its mainstream wine portfolio transaction with The Wine Group LLC, transferring brands, inventory, facilities and vineyards, with some trademarks exclusively licensed. Woodbridge, Meiomi, Robert Mondavi Private Selection, Cook's, SIMI and J. Rogét were among the transferred brands. Constellation's retained wines, including Robert Mondavi Winery, Schrader and The Prisoner Wine Company, were predominantly priced at USD 15 and above. The transaction separates a broader mainstream brand platform from a more focused higher-end offering, giving the buyer and seller different commercial routes to serving wine consumers.
On June 16, 2026, Bronco Wine Company announced its acquisition of Resurrection Brands, a wine sales and marketing organization representing family-owned wineries and beverage brands. Bronco presented the acquisition as expanding national representation alongside its production business, with represented wineries remaining independently owned and operated. The Federal Alcohol Administration Act's labeling rules under 27 CFR Part 4 do not apply to US wine below 7% alcohol by volume. Applicable Alcohol and Tobacco Tax and Trade Bureau rules under Parts 16 and 24 and applicable Food and Drug Administration food-labeling and packaging duties, including ingredient, nutrition and allergen disclosures, continue to apply. For domestic wine at or above 7% alcohol by volume entering interstate commerce, bottlers generally need TTB label approval before bottling, so labeling pathways differ across that threshold.
Wine Industry Leaders
-
Bacardi Limited
-
GALLO
-
Constellation Brands Inc.
-
Vinarchy
-
Bronco Wine Company
- *Disclaimer: Major Players sorted in no particular order
Wine Market Companies Covered in this Report
- GALLO
- Constellation Brands Inc.
- The Wine Group LLC
- Vinarchy
- Treasury Wine Estates
- Sula Vineyards Limited
- Bronco Wine Company
- Foley Family Wines & Spirits
- Bacardi Limited
- Symington Family Estates
- Madeira Wine Company SA
- Moët Hennessy (LVMH)
- Jackson Family Wines
- Caviro Group
- Grupo Peñaflor
- Viña Concha y Toro SA
- Familia Torres
- Changyu Pioneer Wine
- Domaines Barons de Rothschild (Lafite)
- Henkell Freixenet
- Castel Frères
Key Opportunities for Market Participants
These opportunities compare the 2027 promotion funding window for eligible French wine exporters, including suppliers targeting the United States. FranceAgriMer's 2026 call accepts applications through November 4, 2026, at noon for promotion actions running from January 1 through December 31, 2027.[3] France-based applicants need a SIRET number, an eligible professional category and wines carrying a protected designation of origin (AOP), protected geographical indication (IGP) or grape-variety indication. In August 2024-July 2025, US-bound Occitanie IGP wine exports reached 139,000 hectoliters, up 9.4% by volume and 1.8% by value, while unit prices declined.
Market Opportunities Table of Wine Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Export brands with defined origins | Preparation for supported 2027 promotion | Third-country importers of AOP wines | Connect a defined origin story to a focused wine offer | Securing repeat orders after campaign exposure | Eligible France-based AOP wine companies |
| Collective regional assortments | The 2027 promotion window includes collective applicants | Third-country importers of IGP wines | Coordinate a regional assortment around a clear commercial proposition | Aligning participating producers around one coherent offer | Eligible French collective bodies and IGP wine companies |
| Export entry through varietals | The 2027 window includes varietal-indicated wines | Third-country retail wine buyers | Introduce qualifying wines through clearly named varietals | Turning initial trial into sustained retail demand | Eligible France-based varietal-wine companies |
| Source: Mordor Intelligence | |||||
The US trade in Occitanie IGP wine provides a specific destination-product match for eligible promotion applicants. The gap between volume and value growth makes additional shipments a weaker test of success than revenue earned per unit. For these exporters, the strongest use of the funding window is to support repeat importer listings on terms that defend unit revenue, using existing commercial relationships to turn exposure into orders.
Recent Industry Developments in Wine Market
- Oct 2026: By October 15, Treasury Wine Estates had reported completing the sale of Seppelt's Great Western winery, vineyards and Drumborg vineyard in Victoria to Stonier Wines and partners, following a September announcement.
- Aug 2026: South Africa amended wine-label class-designation exceptions while retaining permission for qualifying wines to omit those designations through December 31, 2027.
- May 2026: Castoro Cellars expanded its use of ultraviolet vineyard robots with technology partner Saga Robotics to 600 acres in California after 3 years of field testing.
Wine Market Report Scope and Research Methodology
Market Definition and Coverage
The wine market measures annual spending on wine sold for consumption in the Global market. It counts sales through retail and on-premise channels across accepted product types, colors, end users and distribution channels.
Scope exclusions: Non-alcoholic grape beverages, flavored wine coolers, winemaking equipment and packaging materials, wine tourism services, and grapes sold as an agricultural input are excluded.
Segments Covered in This Report
- By Product Type
- Fortified Wine
- Still Wine
- Sparkling Wine
- Others Wine Types
- By Color
- Red Wine
- White Wine
- Rose Wine
- By End User
- Men
- Women
- By Distribution Channel
- On-Trade
- Off-Trade
- Specialty/Liquor Stores
- Other off-Trade Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Indonesia
- South Korea
- Thailand
- Singapore
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Nigeria
- Egypt
- Morocco
- Turkey
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public wine-sector evidence such as the International Organisation of Vine and Wine, Eurostat, the European Commission Wine Market Observatory, Wine Australia and the Food and Agriculture Organization supports the market baseline and its drivers. The OIV tracks global production, consumption and wine trade, while Eurostat and the Commission supply production, price, stock and trade series, and Wine Australia reports export values, volumes and unit values that help check price and mix trends.
Producer annual reports, regulatory filings, investor materials and reputable trade press can cross-check channel exposure, portfolio changes, pricing commentary and interruptions to supply, with each observation matched to its stated geography, period and transaction level. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews would be sought with winery commercial and finance leaders, distributors, importers, retail wine buyers and on-premise operators across APAC, EMEA and the Americas to test assumptions about final selling prices, channel mix, product mix and regional demand. Analysts would compare these accounts with public production, consumption and trade evidence, document disagreements by variable and country, and use targeted follow-up questions to clarify material gaps before adjusting an input or retaining a range for scenario analysis.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | APAC: 38% |
| Mid tier: 46% | Functional/Unit leaders: 35% | EMEA: 34% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
The top-down model estimates global wine spending at the final retail or on-premise price paid, then checks selected totals with sampled channel sales and supplier revenue roll-ups. Selective average selling price times volume checks test whether reported values are plausible. Separate value and hectoliter series use wine-consumption volume, producer output and harvest conditions, export and import volume and value, export unit values, and observed retail or hospitality price and mix trends. When producer output diverges from recorded consumption and trade, the model treats those supply and demand signals as constraints rather than as sales totals. A multivariate regression relates historical value and volume to these indicators, while scenario analysis adjusts for climate-sensitive harvests, trade policy, costs and premium mix when a stable historical relationship is not available. Product, color, end-user, channel and regional shares are built from published category and country evidence and channel sales information, then reconciled to the global totals. Value growth also reflects price and mix separately from physical volume. Primary experts would review the direction and plausibility of each key input and segment share. Selective bottom-up checks would be used only where sampled prices and volumes or channel and supplier data are available. Where a country lacks a consistent channel series, the analyst uses adjacent years and official regional data to bridge the gap, then tests the resulting assumption in alternative scenarios.
Data Validation & Update Cycle
Analysts triangulate the modeled totals against independent production, consumption, trade, price and channel signals, then investigate outliers, conflicting source periods and unexplained changes in value relative to volume. A second analyst reviews source definitions, calculations and segment reconciliations, and the lead reviewer resolves anomalies before sign-off. Follow-up interviews are triggered when a material input remains inconsistent or a major source changes its definition. The dataset is refreshed annually, reassessed between cycles after material harvest, policy, trade or distribution events, and receives a fresh pre-delivery review.
Mordor Intelligence's Wine Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The wine market measures annual spending on wine sold for consumption in the Global market.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. A multivariate regression relates historical value and volume to these indicators, while scenario analysis adjusts for climate-sensitive harvests, trade policy, costs and premium mix when a stable historical relationship is not available.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | Value: USD 384.6 B (2027) / Volume: 205 million Hectoliters (2027) | |
| Global Consultancy A | USD 355.6 B (2025) | Its published revenue series advances from the earlier estimate to a higher following-year value and applies a faster stated annual growth path over its forecast horizon, so its earlier measurement point is lower than this later-year comparison. |
| Global Consultancy B | USD 347.1 B (2025) | Its outlook pairs lower consumption with a projected revenue increase as buyer preferences shift toward premium wine, producing a later value path above its earlier estimate. |
Mordor Intelligence's analysts triangulate the modeled totals against independent production, consumption, trade, price and channel signals, then investigate outliers, conflicting source periods and unexplained changes in value relative to volume.
Key Questions Answered in the Report
What is the wine market size and growth outlook?
Value is forecast to rise from USD 384.6 billion in 2027 to USD 447.6 billion by 2032, at a CAGR of 3.08% during 2027-2032.
What is driving demand for wine?
Winery hospitality, premium brands and alcohol-free options support demand. German retail alcohol-free wine volume rose 25% in 2025 from 2024.
Which wine product is the largest segment?
Still wine accounted for 71.61% of wine sales value in 2026, making it the largest product segment.
Which companies are major wine industry participants?
Major participants include Bacardi Limited, GALLO, Constellation Brands Inc., Vinarchy and Bronco Wine Company.
What is a key challenge for wine producers?
Average South African wine-grape production costs rose 6.4% for the 2025 vintage compared with 2024, excluding dryland vineyards in Swartland. Higher upstream costs limit flexibility to discount.
Which regions lead wine sales and forecast growth?
Europe held 45.06% of wine sales value in 2026. Asia-Pacific is forecast to grow fastest at a CAGR of 5.2% during 2027-2032.