
United Kingdom E-commerce Market Analysis by Mordor Intelligence
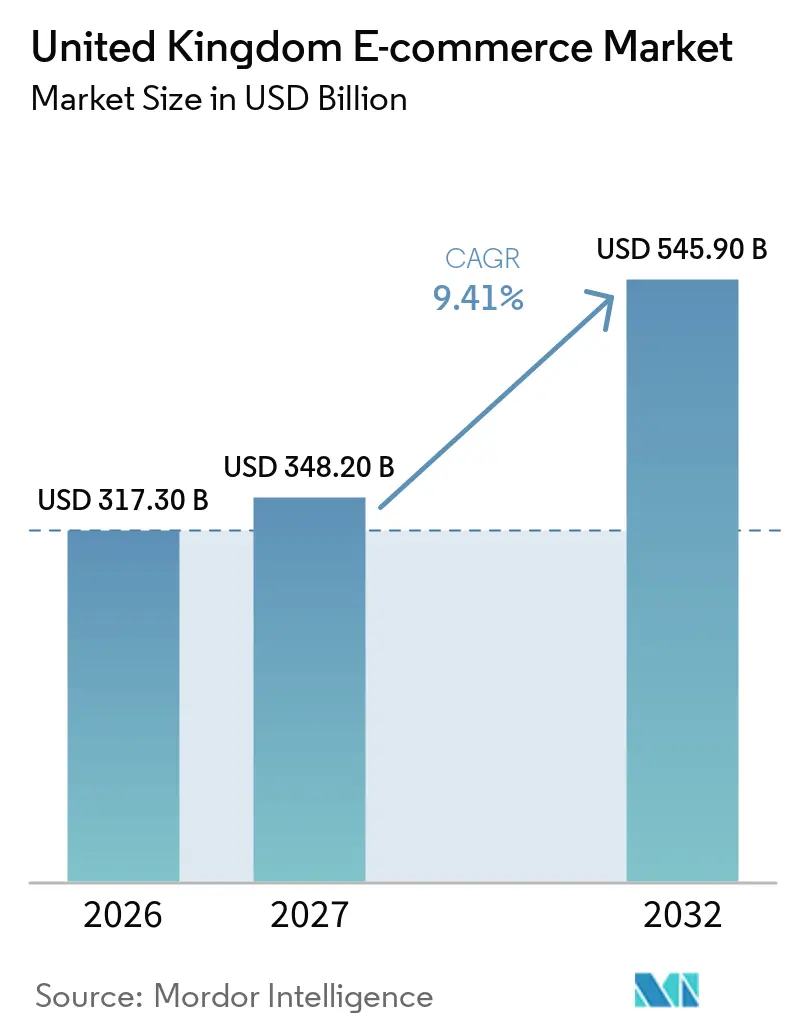
The United Kingdom e-commerce market size was valued at USD 317.3 billion in 2026 and estimated to grow from USD 348.2 billion in 2027 to reach USD 545.9 billion by 2032, at a CAGR of 9.41% during the forecast period (2027-2032).
In the United Kingdom, broader mobile connectivity and secure payments support purchases through digital storefronts. Time-sensitive essentials demand gives retailers a reason to complement next-day service with on-demand availability. Capturing those occasions makes fulfillment throughput part of the sales proposition for home-delivery operators. Competitive differentiation through loyalty and delivery therefore has to fit an operating model that price-sensitive demand can support. Privacy duties add service responsibilities for merchants acting as data controllers, making complaint handling part of the capacity needed to sustain those customer relationships.
Key Report Takeaways
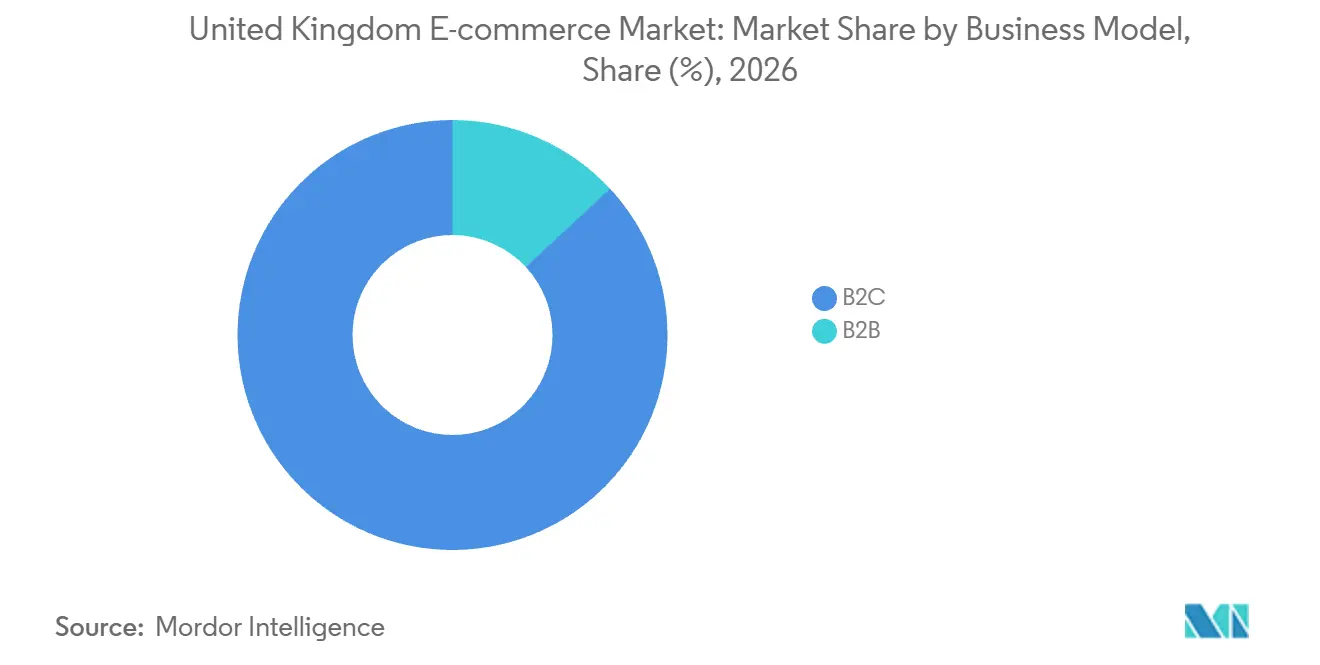
- By business model, B2C held an 86.91% share of the United Kingdom e-commerce market size in 2026, while B2B is forecast to grow fastest at a 12.15% CAGR during 2027-2032.
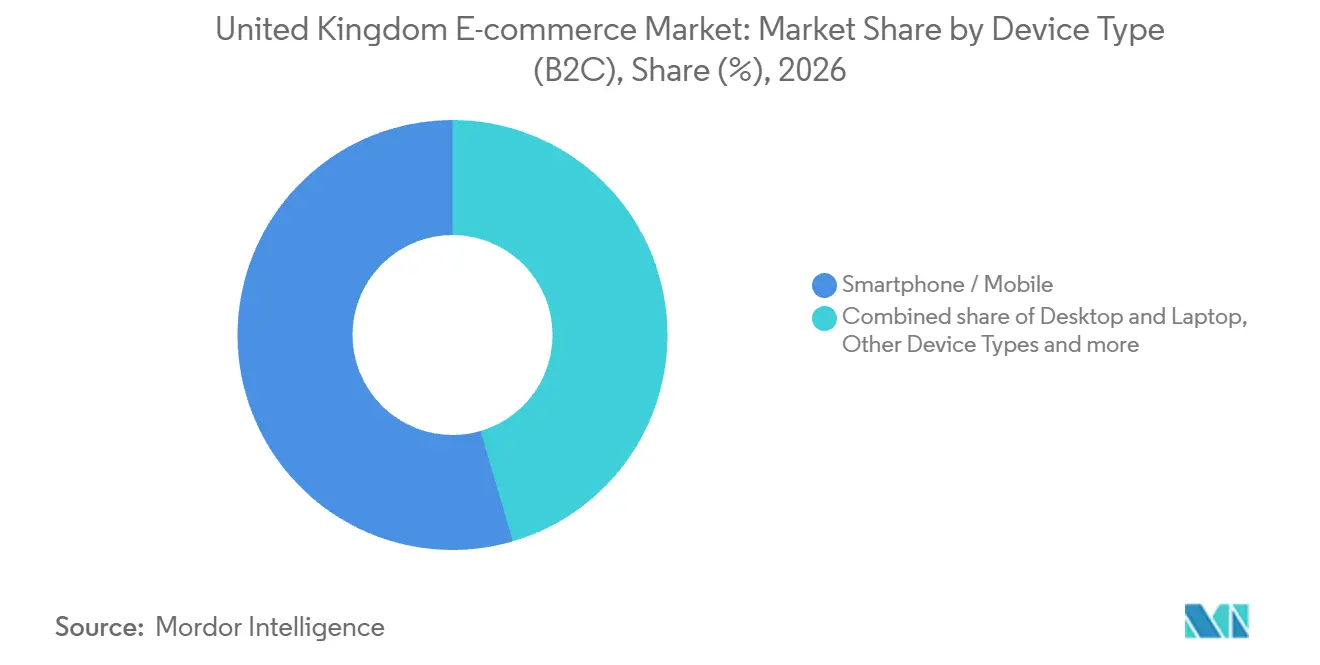
- Device demand was led by smartphone and mobile devices with 54.53% of the market in 2026, and the same segment is forecast to grow fastest at a 9.95% CAGR during 2027-2032.
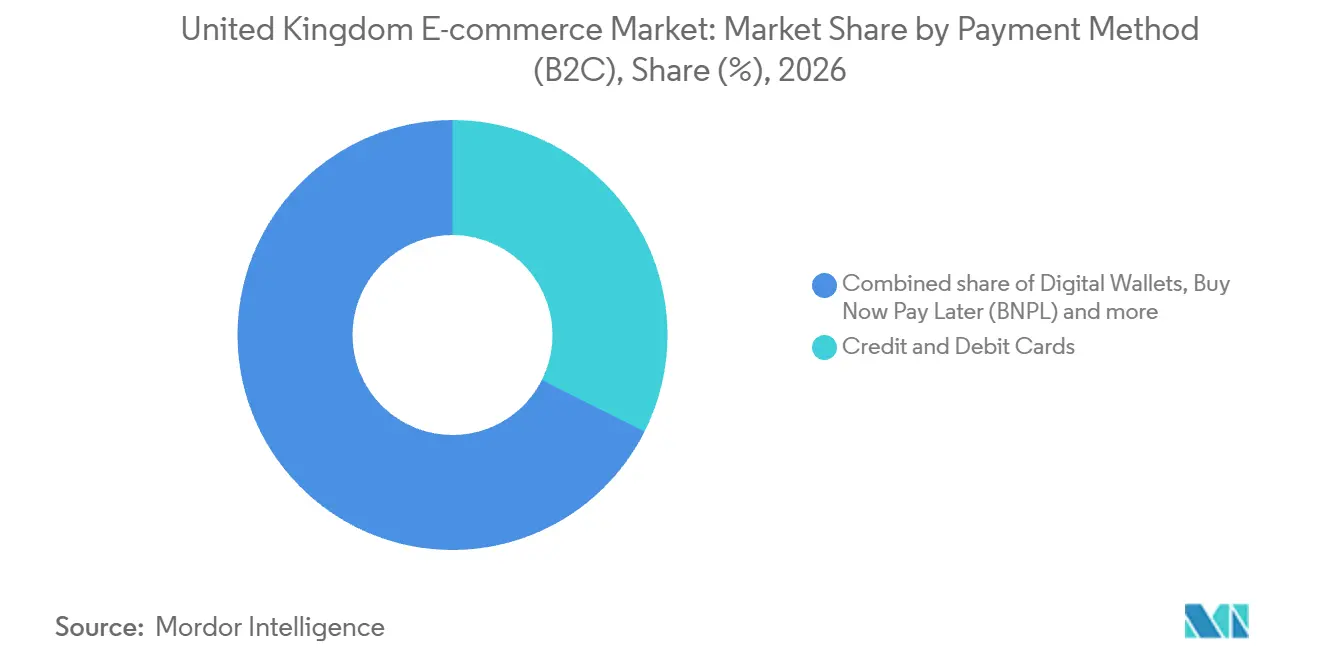
- Among payment methods, credit and debit cards led with 32.42% of the market in 2026, while buy now pay later (BNPL) is forecast to grow fastest at a 10.85% CAGR during 2027-2032.
- Across product categories, fashion and apparel led with a 29.04% United Kingdom e-commerce market share in 2026, and food and beverages are forecast to grow fastest at a 10.05% CAGR during 2027-2032.
- In geographic terms, England leads e-commerce volumes, with its large resident population underpinning the scale of the domestic opportunity.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of United Kingdom E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Widespread 5G Roll-Out | +2.6% | Nationwide | Medium term (2-4 years) |
| Proliferation of Secure Digital Payments | +3% | Nationwide | Short term (≤ 2 years) |
| Rising Mobile-Commerce Share in Retail | +3.8% | Nationwide | Short term (≤ 2 years) |
| Same-Day and Next-Day Delivery Expectations | +2.5% | Nationwide | Medium term (2-4 years) |
| Surging Adoption of Social-Commerce Live Shopping | +1.6% | Nationwide | Medium term (2-4 years) |
| Expansion of On-Graduation Student Marketplaces | +0.5% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Widespread 5G Roll-Out
Broader outdoor connectivity expands the settings in which a consumer can complete an online purchase. In the 6 months to January 2026, UK outdoor 5G coverage increased by at least 5 percentage points for each mobile network operator.[1] Ofcom's measure included standalone and non-standalone services, with individual operator coverage ranging from 76% to 94%. For retailers, that expanding reach supports shopping journeys away from a fixed connection without making universal coverage a prerequisite for mobile investment. An outdoor shopping offer needs to account for gaps on the customer's own network, because aggregate rollout cannot guarantee access across operators.
Proliferation of Secure Digital Payments
A growing digital-payment channel becomes commercially relevant to online retail when it can be implemented at checkout. Apple Pay and Google Pay do not hold funds and use tokens to link payment cards' primary account numbers to virtual cards on consumers' devices. Across UK Open Banking use cases, annual payment volume increased 45% year over year for August 2025 to July 2026. In February 2026, TrueLayer announced a partnership with eBay to introduce secure Pay by Bank checkout for UK buyers, authenticated through their own bank apps. Together, broader bank-payment growth and eBay's checkout option give online buyers another way to complete purchases, reducing dependence on manual card or account-detail entry.
Rising Mobile-Commerce Share in Retail
Peak-season consumer demand gives mobile commerce an immediate revenue role beyond product discovery. Mobile devices generated 61.5% of UK online holiday revenue in November and December 2025, compared with 56% during the same months of 2024. A shopping journey that can finish on the handset can capture that demand without making a desktop visit a condition of purchase. The handset share rose 5.5 percentage points between those holiday periods. Mobile checkout failures would therefore expose a growing share of peak-season revenue to interruption, making purchase completion on the phone a commercial priority.
Same-Day and Next-Day Delivery Expectations
Time-sensitive essentials give rapid delivery a demand case tied to when a product is needed. In ConsumerX research reported in 2025, 26.3% of UK shoppers considered next-day delivery very important. Boots Pharmacy GB's Deliveroo data covered suncare SPF items ordered from 17:00 to 21:00 BST before England games on June 17 and 23, 2026. The average was almost 200% higher than the average across 5 non-match baseline evenings. In June 2026, Boots also extended on-demand delivery hours up to midnight at 25 new UK locations via Deliveroo. Complementing next-day service with on-demand availability gives essentials retailers a way to address purchases tied to a particular evening.
Restraints Impact Analysis of United Kingdom E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Heightened Data-Privacy Regulation (Data (Use and Access) Act 2025) | -1.3% | Nationwide | Short term (≤ 2 years) |
| Intense Price Competition Compressing Margins | -2.1% | Nationwide | Short term (≤ 2 years) |
| Volatile Cross-Border VAT Reverse-Charge Rules | -0.5% | Nationwide | Medium term (2-4 years) |
| Warehousing Labor Shortages outside "Golden Triangle" | -0.7% | Outside the Golden Triangle | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Heightened Data-Privacy Regulation (Data (Use and Access) Act 2025)
For online merchants acting as data controllers, privacy compliance has a service-capacity dimension that can complicate expansion. The Data (Use and Access) Act 2025 requires data controllers to establish a process for data-protection complaints from data subjects.[2] The duty took effect on June 19, 2026. Assigning responsibility for receiving those complaints becomes part of the operating model, alongside the commercial use of customer information. Controllers must acknowledge receipt within 30 days and take appropriate steps to respond to the complaint. That deadline turns complaint handling into a standing customer-service workload, consuming staff time alongside sales activity.
Intense Price Competition Compressing Margins
Marks Electrical, a UK online retailer of domestic appliances and consumer electronics, described a highly competitive market and price-sensitive customers in FY26. Its gross product margin was stable through the year and only marginally lower than the prior year, but meaningful improvement with key brand partners proved difficult. In its core domestic-appliance category, sales orders were about 2.9% lower year over year, with reduced average order value accounting for 1.7% of the fall. The company also reported pressure on average order values across its categories alongside wider cost inflation. Lower order values constrain this retailer's room to absorb rising costs when product margins are difficult to improve.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
United Kingdom E-commerce Market Segment Analysis
By Business Model:
Consumer Scale and Wholesale Digital ExecutionB2C accounted for an 86.91% share of the United Kingdom e-commerce market size in 2026. The Office for National Statistics measured card-not-present transactions at 50.5% of UK cardholders' total card spending in September 2025, including payments to domestic and overseas merchants.[3] The same measure stood at 43.7% in September 2019. Online card payment therefore moved from a minority of cardholder spending to just over half, giving consumer-facing retailers a customer base whose card spending leans toward online purchases.
B2B is forecast to be the fastest-growing segment, at a 12.15% CAGR during 2027-2032. JJ Foodservice, which serves caterers and households, reported in October 2025 that 79% of orders were placed online, alongside increased use of its app, website, and electronic data interchange (EDI) channels. In June 2026, the wholesaler reported around 80% of transactions processed digitally across more than 4,000 product lines. Online order placement and digital transaction processing address different steps, connecting customer access with the internal work of executing wholesale trade. Linking the app, website, and EDI channels to scalable core processing gives a wholesaler a way to extend digital trading across its product catalog.

By Device Type (B2C):
Mobile Reach and Multi-Device ShoppingSmartphone and mobile devices were the largest segment with 54.53% of the market in 2026 and the fastest-growing segment, at a 9.95% CAGR during 2027-2032. Ofcom's 2025 Technology Tracker found that 66% of UK internet users shopped for items or food deliveries on a mobile phone. Those activities position the handset as a consumer interface across merchandise and food delivery, broadening the range of retailers for whom mobile access matters. A retailer serving that audience can address an established buying channel while adapting its offer to additional consumer needs within the same device environment.
ConsumerX survey data reported in 2025 showed that 90% of UK respondents used a phone to buy online always, often, or some of the time. That range of reported frequency gives mobile retailers an audience extending beyond shoppers who invariably purchase by phone. Other devices also supported online shopping, with 42% of UK internet users reporting shopping for items or food deliveries on another device in Ofcom's 2025 survey. Serving that additional device audience limits how far a merchant can concentrate its storefront investment on the handset alone.
By Payment Method (B2C):
Card Scale and Deferred-Payment ChoiceCredit and debit cards were the largest segment, accounting for 32.42% of the market in 2026. Using Visa card-payment data, ONS reported an 8.1% increase in UK cardholders' domestic online spending ratio between September 2019 and September 2025. Its online transaction definition covers card-not-present purchases made over the internet, by telephone, or through an app. For merchants taking orders through those different channels, card acceptance can provide a common payment route without requiring buyers to use a separate method for each.
Buy now pay later (BNPL) is forecast to be the fastest-growing segment, at a 10.85% CAGR during 2027-2032. Experian recorded more than 100 million BNPL transactions across 8.5 million UK customers in 2025. This usage base gives merchants a reason to consider deferred-payment choice within their consumer offer, with credit functionality as the distinguishing commercial element. Digital wallets provide a separate route to checkout, with 65% of UK adults registered for at least one mobile payment service in 2025 and online retailers and apps increasingly accepting stored credentials. Financing choice can expand alongside wallet acceptance because deferred payment and stored credentials address separate parts of the checkout decision.
By Product Category (B2C):
Apparel Value and Grocery Order GrowthFashion and apparel represented a 29.04% United Kingdom e-commerce market share in 2026, making it the largest segment. In August 2026, seasonally adjusted average weekly internet sales of textiles, clothing and footwear in Great Britain were GBP 316.4 million (USD 428.5 million). One Poll surveyed 3,000 UK consumers online for KPMG UK from March 5 to 11, 2025. Among respondents, 13% said they generally buy multiple sizes of clothes or footwear online to find the best fit, then return the rest. For retailers serving these shoppers, an online clothing sale can include a subsequent returns interaction, making post-purchase handling part of the offer.
Food and beverages are forecast to be the fastest-growing segment, at a 10.05% CAGR during 2027-2032. Tesco's UK grocery home-shopping business averaged 4.9% more orders per week in the 26 weeks ended August 29, 2026, than in the comparable prior-year period. Delivery Saver subscribers increased 6.1% year over year to 836,000 over the same period. Higher weekly order counts alongside a larger subscriber base make dependable delivery capacity central to serving grocery demand on a recurring basis.
Geography Analysis
England E-commerce Market
England leads national e-commerce volumes, making the scale of its domestic audience central to the commercial case for an extensive consumer-facing online operation. The Office for National Statistics estimated England's resident population at 58,834,800 in mid-2025. An online retailer can consequently frame an England-focused proposition around a substantial resident catchment, with the commercial goal of serving that audience more completely through its chosen format. That makes the reach of fulfillment and customer service inside England a practical determinant of domestic scale, even before expansion into additional geographic areas is considered.
Regional differences concern both seller participation and the infrastructure through which orders are processed. In Scotland, 29.6% of businesses with a presence in Scotland and 10 or more employees that had not permanently stopped trading reported online sales during August 18 to 31, 2025. Along the Midlands-Yorkshire axis, Amazon had opened a Hull fulfillment center by June 2026, creating 2,000 jobs. These examples place the regional commercial question at different points in the transaction, from business adoption of online selling to the physical capacity used to fulfill purchases. Reaching Scottish businesses through online-selling tools would require a different offer from supplying the physical order-handling operations demonstrated in Hull.
Wales illustrates a software-service role in e-commerce that reaches beyond the retailer's immediate selling location. Amazon-owned Veeqo, which produces shipping and inventory-management software, opened its Swansea headquarters on December 5, 2025. The headquarters is at 71/72 Kingsway, a scheme developed by Swansea Council and part-funded by the Swansea Bay City Deal to attract tech, digital, and creative companies. Veeqo's free software serves more than 100,000 businesses worldwide. The Kingsway scheme connects Welsh commercial-property development with a seller-technology provider, locating this example's commercial relevance in software supply.
Regulatory Framework and Outlook
The comparison covers the United Kingdom national regime and Scotland as selected jurisdictions from the perspective of a B2C online merchant offering consumer goods and subscriptions. For covered consumer distance sales, sellers must provide business, product, price, payment, delivery, contract, and cancellation information before an order in an understandable form the customer can save. The Competition and Markets Authority (CMA) has direct powers over some consumer laws, while local cancellation-notice enforcement duties also shape the Scottish commercial environment.
Regulatory Table of United Kingdom E-commerce Market
| Decision factor | United Kingdom | Scotland |
|---|---|---|
| Primary authority | Competition and Markets Authority | Local weights and measures authorities |
| Key instruments or direction | Distance-selling disclosure rules; Digital Markets, Competition and Consumers Act 2024 | 2013 consumer-contract cancellation-notice provisions; UK distance-selling disclosures |
| Commercial effect | Pre-order information in a storable form; possible CMA penalties or directions for some consumer-law breaches | Cancellation-notice enforcement within each authority's area; local business guidance in Edinburgh |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
The national Medium rating reflects standardized disclosure duties and exposure to direct CMA action for some consumer-law breaches. Scotland is also Medium because local cancellation-notice enforcement sits alongside a business-guidance route such as Edinburgh's Trading Standards service. October 2026 draft guidance proposed additional UK B2C subscription disclosures, reminders, and easy-exit duties for contracts entered from January 1, 2027. Both Hardening ratings reflect these prospective additional obligations, which depend on Parliament approving the draft regulations before they can take effect.
Value Chain Stages
The value chain compares how merchant software, marketplace access, and physical fulfillment earn revenue from online commerce. Shopify earns subscriptions for commerce software, while Amazon charges UK sellers for Individual or Professional selling plans. These activities separate control of a digital storefront from access to an intermediary's sales environment, creating different dependencies for a merchant. Amazon's Fulfilment by Amazon (FBA) service receives and stores sellers' goods, then picks, packs, and ships products and handles returns and refunds.
Value Chain Analysis Table of United Kingdom E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Storefront and order software | Commerce-platform providers such as Shopify | Merchant subscriptions | Connecting storefront orders to physical execution | Use consistent order records across sales and dispatch |
| Marketplace selling | Marketplace operators such as Amazon | Seller-plan fees and referral commissions | Commission charges include buyer-paid shipping | Cost the full commission base into the offer |
| Fulfillment and returns | Fulfillment service providers such as Amazon | Fulfillment, storage, and optional-service fees | Service costs vary with destination, speed, and unit size | Match the outsourced service to each product's economics |
| Source: Mordor Intelligence | ||||
Increasing buyer-paid shipping or gift wrapping can raise Amazon's referral commission because the fee base includes those charges alongside the item price. A per-item minimum may also apply, so the commission effect depends on whether the percentage-based charge exceeds that floor. Its FBA rate card effective July 1, 2026, separates fulfillment fees from storage and optional services, with fulfillment charges calculated by destination, shipping speed, and unit size band. A merchant's decision to outsource packing and dispatch changes both its operating responsibilities and the set of supplier charges attached to a sale.
Competitive Landscape
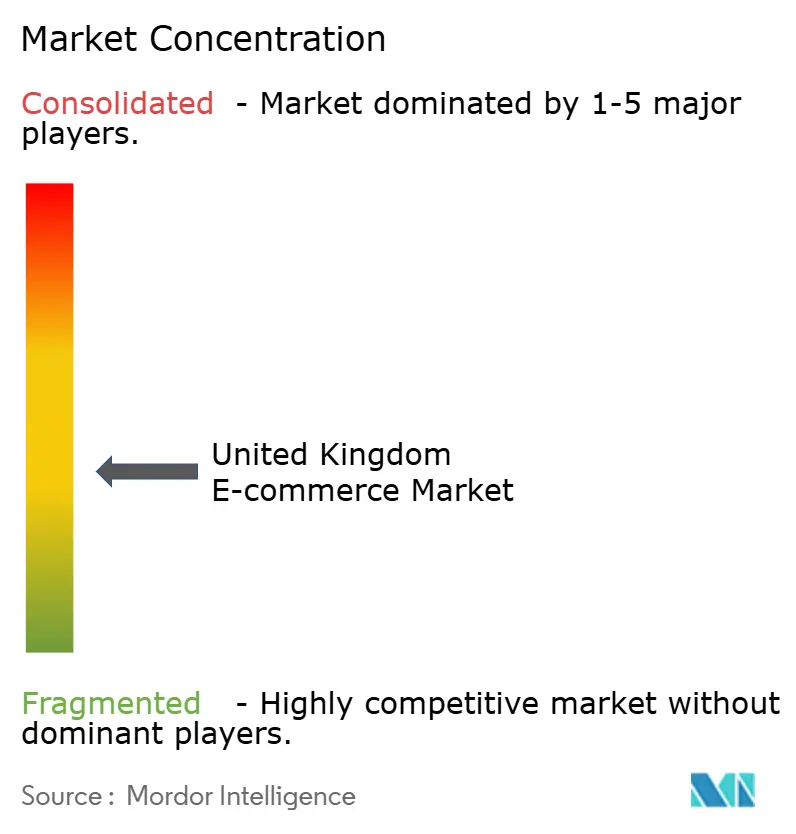
The competitive structure combines large platforms with specialist and multichannel retailers. Major participants include Amazon UK Services Ltd., eBay (UK) Ltd., online fashion retailer ASOS plc, online grocer Tesco plc (Tesco.com), and Argos Ltd., a general merchandise retailer subject to an agreed sale. On eBay, marketplace sale contracts are directly between buyer and seller, while Argos offers rapid delivery and more than 1,100 UK collection points. Amazon delivered more than 1.6 billion items to UK Prime members with same-day or next-day delivery in 2025. That service scale creates a demanding delivery benchmark for merchants competing through a narrower range or a different customer relationship.
ASOS's loyalty-program scale supports a different competitive route centered on the retailer's relationship with a defined fashion audience. In its March 25, 2026, trading update, ASOS reported approximately 3.5 million UK ASOS.World members, up from approximately 1 million at FY25 year-end. For a category specialist, the commercial value of such a program lies in giving customers a reason to continue engaging with the same fashion offer. Turning membership into a continuing fashion relationship is a different competitive task from matching a broad platform's delivery footprint, making the relevance of the customer proposition central to this strategy.
Tesco's interim results for the 26 weeks ended August 29, 2026, reported more than 1,000 Marketplace sellers, up more than 80% year over year. For business sellers, eBay's UK agreement requires them to follow applicable online-trading laws for their selling site, from acceptance for new users and August 10, 2026, for existing users. On July 31, 2026, J Sainsbury plc agreed to sell Argos Limited to Swift Whistle Midco Limited, subject to customary regulatory and other conditions, with completion expected in February 2027. The announcement said Argos and Sainsbury's would operate as before until completion. Tesco's expanding seller base increases the choice buyers can compare, while Argos's agreed sale leaves its existing customer offer unchanged until completion.
United Kingdom E-commerce Industry Leaders
-
Amazon UK Services Ltd.
-
eBay (UK) Ltd.
-
ASOS plc
-
Tesco plc (Tesco.com)
-
Argos Ltd.
- *Disclaimer: Major Players sorted in no particular order
United Kingdom E-commerce Market Companies Covered in this Report
- Amazon UK Services Ltd.
- eBay (UK) Ltd.
- ASOS plc
- Tesco plc (Tesco.com)
- Argos Ltd.
- Ocado Retail Ltd.
- Next plc
- The Very Group Ltd.
- Currys plc
- John Lewis & Partners
- Marks and Spencer Group plc
- Boohoo Group plc
- THG plc (The Hut Group)
- Dunelm Group plc
- B&Q (Kingfisher plc)
- Screwfix Direct Ltd.
- Alibaba.com UK (B2B)
- RS Components Ltd.
- Shopify UK (Merchant Base)
- Zalando SE (UK Site)
Key Opportunities for Market Participants
The opportunities compare ways sellers can use an expanding marketplace while taking responsibility for fulfillment and customer service. For the 26 weeks ended August 29, 2026, Tesco Marketplace reported unique product count growth of more than 50% since the start of 2026 and average weekly traffic growth of about 32%. In September 2026, Tesco invited seller applications and said it expects partners to share its quality, trust, and reliable customer-service values.
Market Opportunities Table of United Kingdom E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Additional home-electricals ranges | Established electrical seller channel within expanding assortment | Existing and prospective home-electricals merchants | Develop a focused electrical offer with seller-managed dispatch | Seller-side capacity to execute deliveries | Existing electrical sellers such as 3wisemonkeys |
| Specialist delivery for large items | Seller recruitment alongside marketplace expansion | Merchants offering big heavy products | Pair category applications with specialist delivery capacity | Big heavy products require specialist delivery | Large-item sellers and specialist couriers |
| Seller-operated customer service | Range expansion alongside a seller-run returns promise | Marketplace merchants and service teams | Support seller-operated contact handling and returns records | Capacity for customer contacts and reverse logistics | Marketplace merchants and returns-support providers |
| Source: Mordor Intelligence | |||||
Sellers arrange Marketplace deliveries directly by post or courier using their chosen fulfillment partners, and big heavy products require specialist delivery. Tesco's change-of-mind promise asks customers to contact the seller within 30 days for a replacement or refund when items are unused, undamaged, and in original condition, subject to product-specific exceptions. The contact period can extend seller-service work beyond dispatch, so a delivery-only offer would leave part of the customer relationship unsupported. The strongest opening is to combine additional customer reach with delivery and contact-handling capacity suited to the range Tesco Marketplace sellers are adding.
Recent Industry Developments in United Kingdom E-commerce Market
- Oct 2026: Currys launched a curated technology shop on TikTok Shop with THG Commerce, enabling customers to discover and buy products through videos, livestreams, and creator content.
- Oct 2026: THG Ingenuity was selected as UK e-commerce partner for Tata Consumer Products GB Limited's teapigs, Good Earth, and Organic India brands, with direct-to-consumer websites, fulfillment, and marketing services planned.
- Sep 2026: Tesco launched on Deliveroo across 75 UK towns and cities, making thousands of grocery and household products available for delivery in as little as 20 minutes.
United Kingdom E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The United Kingdom e-commerce market measures annual gross merchandise value of goods and services bought online by consumers and enterprises from merchants of record registered in the United Kingdom, with digital payment and fulfillment by post, courier, or click-and-collect. It covers purchases through websites, mobile apps, and social storefronts.
Scope exclusions: Sales where the merchant of record is registered outside the United Kingdom and pure digital-only media subscriptions are excluded.
Segments Covered in This Report
- By Business Model
- B2C
- B2B
- By Device Type (B2C)
- Smartphone / Mobile
- Desktop and Laptop
- Other Device Types
- By Payment Method (B2C)
- Credit and Debit Cards
- Digital Wallets
- Buy Now Pay Later (BNPL)
- Other Payment Methods
- By Product Category (B2C)
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories
Data Sources, Market Sizing, and Validation
Desk Research
The research reviews official retail and digital indicators from the Office for National Statistics, including its monthly internet sales series, and Ofcom's coverage data to assess online demand and connectivity. Sources such as the U.S. Department of Commerce country e-commerce guide and Competition and Markets Authority publications help frame digital commerce conditions and applicable consumer rules in the United Kingdom.
Company filings, investor presentations, trade reporting, and reputable press are used to cross-check retailer sales, order growth, fulfillment investment, and changes in payment or selling channels. These sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Primary research engages United Kingdom e-commerce executives, digital trading and marketplace leaders, payments specialists, and fulfillment managers who can explain demand, transaction value, and operating capacity. Their market-level perspectives are used to test secondary-source interpretations, clarify gaps in segment coverage, and triangulate estimates against company and official indicators.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 43% | Functional/Unit leaders: 36% | |
| Smaller Players: 23% | Managers: 44% |
Market-Sizing & Forecasting
The model estimates the United Kingdom total from the top down as annual online merchandise and service value transacted through qualifying UK merchants, then checks selected totals with sampled average selling prices times order volumes and retailer or marketplace disclosures. It tracks online retail value and share, order volumes and average basket value, household spending and purchasing conditions, business procurement digitization, and fulfillment capacity, using each signal to assess market scale or the pace of change. Segment shares are built by classifying the same transaction value by B2C or B2B status and, for B2C, by device, payment method, and product category, with evidence from channel data and merchant disclosures used to apportion value without double counting. A multivariate regression can relate historical market value to these demand and channel indicators, while scenario analysis adjusts the forecast for changes in household spending, digital buying, and delivery capacity through 2032. Where a bottom-up check lacks a consistent order or basket measure, the analyst records the gap, uses the nearest comparable source, and tests whether the resulting estimate remains consistent with the wider market signals. Knowledgeable market participants can review the role of each variable and the reasonableness of segment-level paths.
Data Validation & Update Cycle
Analysts triangulate official retail series, company disclosures, and independent indicators of digital access, online purchasing, and fulfillment activity, then investigate material differences in scope, timing, or measurement before resolving an anomaly. A second review checks source dates, units, market boundary, segment shares, and forecast relationships, with re-contact considered when a source is unclear, a major input changes, or independent signals remain inconsistent. The dataset is refreshed annually, updated between cycles when material market or regulatory events change the evidence, and given a fresh pre-delivery review.
Mordor Intelligence's United Kingdom Ecommerce Market Size Measured Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The United Kingdom e-commerce market measures annual gross merchandise value of goods and services bought online by consumers and enterprises from merchants of record registered in the United Kingdom, with digital payment and fulfillment by post, courier, or click-and-collect.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The model tracks online retail value and share, order volumes and average basket value, household spending and purchasing conditions, business procurement digitization, and fulfillment capacity, using each signal to assess market scale or the pace of change.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 348.2 B (2027) | |
| Global Consultancy A | USD 429.1 B (2026) | At its 2026 base, this estimate is 23.2% above this report's 2027 value of USD 348.2 B, 1 year later. |
| Regional Consultancy B | USD 167 B (2025) | At its 2025 base, this estimate is 52.0% below this report's 2027 value of USD 348.2 B, 2 years later. |
Mordor Intelligence's analysts triangulate official retail series, company disclosures, and independent indicators of digital access, online purchasing, and fulfillment activity, then investigate material differences in scope, timing, or measurement before resolving an anomaly.
Key Questions Answered in the Report
What is the United Kingdom e-commerce market size and growth outlook?
Size is estimated at USD 348.2 billion in 2027 and projected to reach USD 545.9 billion by 2032, at a 9.41% CAGR during 2027-2032.
What supports demand for UK online shopping?
Broader mobile connectivity, secure checkout, and demand-responsive delivery support growth. TrueLayer announced an eBay Pay by Bank partnership for UK buyers in February 2026, with authentication through their bank apps.
What is the leading business model in UK online commerce?
Business-to-consumer (B2C) commerce led with an 86.91% share of the market in 2026, while business-to-business (B2B) commerce is forecast to grow fastest at a 12.15% CAGR during 2027-2032.
Which companies shape competition in UK e-commerce?
Amazon UK Services Ltd., eBay (UK) Ltd., ASOS plc, Tesco plc (Tesco.com), and Argos Ltd. are major competitors.
What constrains the outlook for UK online retailers?
Marks Electrical reported price-sensitive customers and difficulty improving product margins with key brand partners in FY26. Lower order values alongside cost inflation constrained its room to absorb rising costs.
How does UK e-commerce activity vary geographically?
England leads national e-commerce volumes. Amazon-owned Veeqo opened its Swansea headquarters on December 5, 2025, illustrating Wales's role in software that helps sellers manage shipping and inventory.