
Traffic Signal Controller Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 6.44 Billion |
| Market Size (2031) | USD 11.54 Billion |
| Growth Rate (2026 - 2031) | 12.38 % |
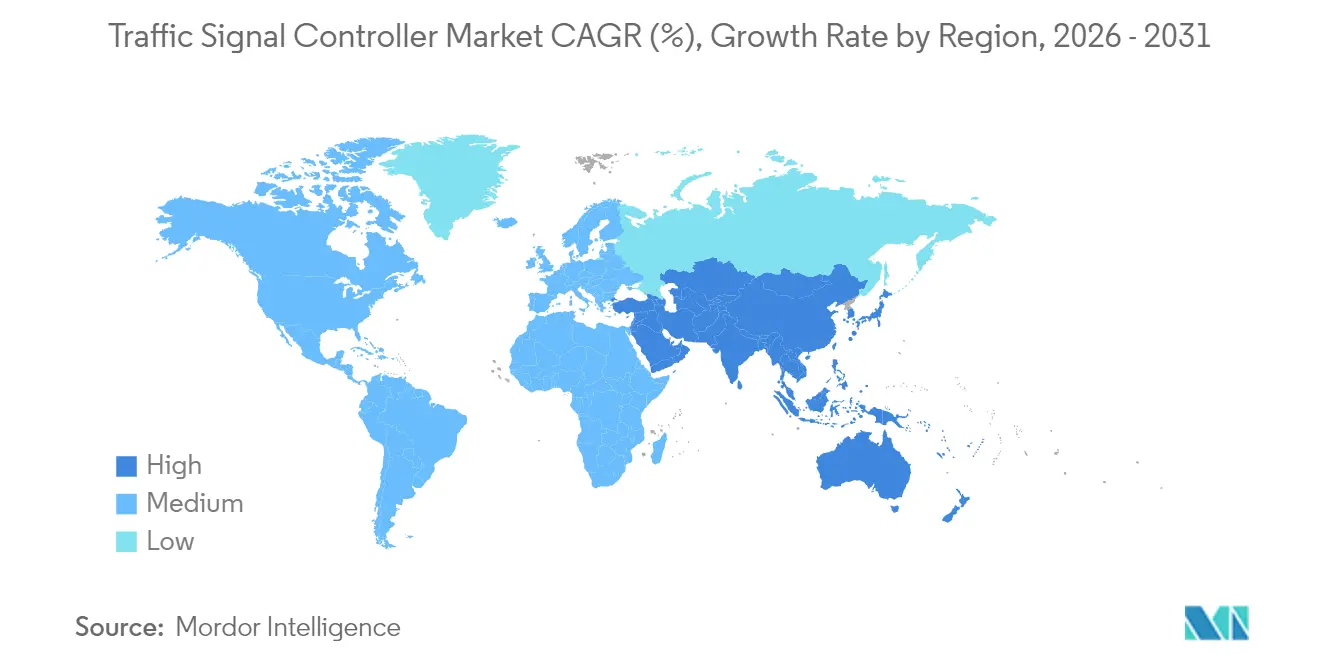
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Traffic Signal Controller Market Analysis by Mordor Intelligence
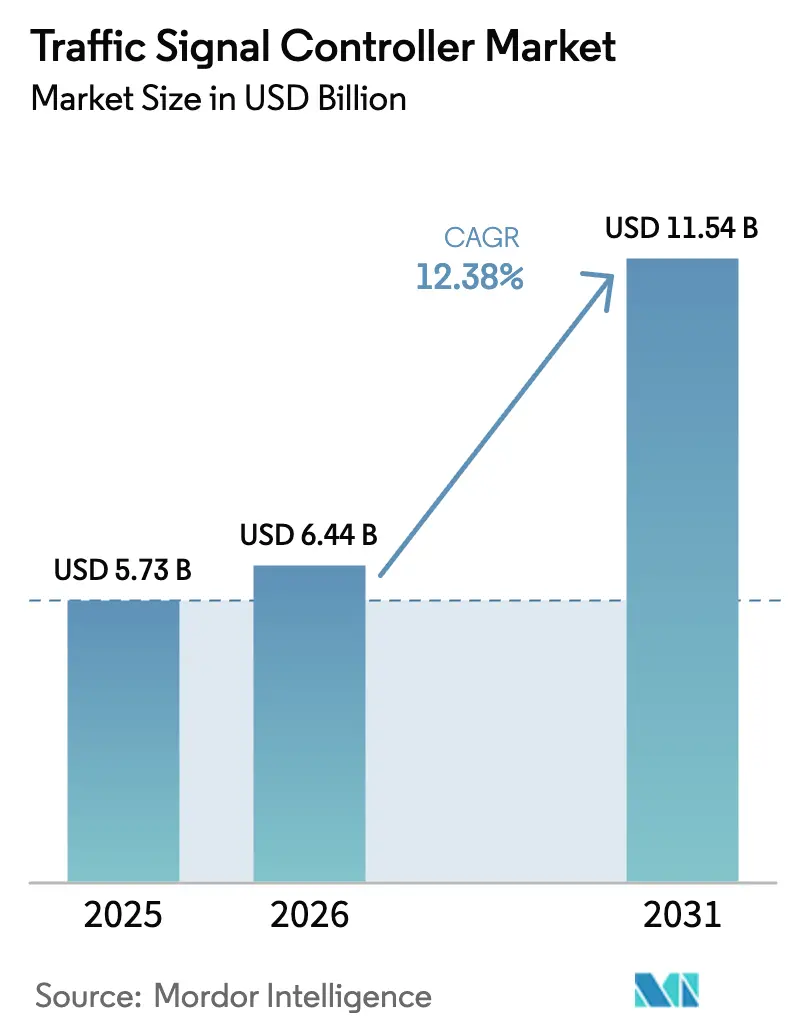
The Traffic Signal Controller Market size was valued at USD 5.73 billion in 2025 and estimated to grow from USD 6.44 billion in 2026 to reach USD 11.54 billion by 2031, at a CAGR of 12.38% during the forecast period (2026-2031). Rising urban populations, national commitments to smart-city spending, and the shift toward artificial-intelligence optimisation have moved traffic management from periodic signal timing updates to predictive control systems that adjust in real time. Federal support in the United States through the SMART Grants Program, together with Asian mega-city infrastructure programs, has created a continuous funding pipeline for new deployments.
Key Report Takeaways
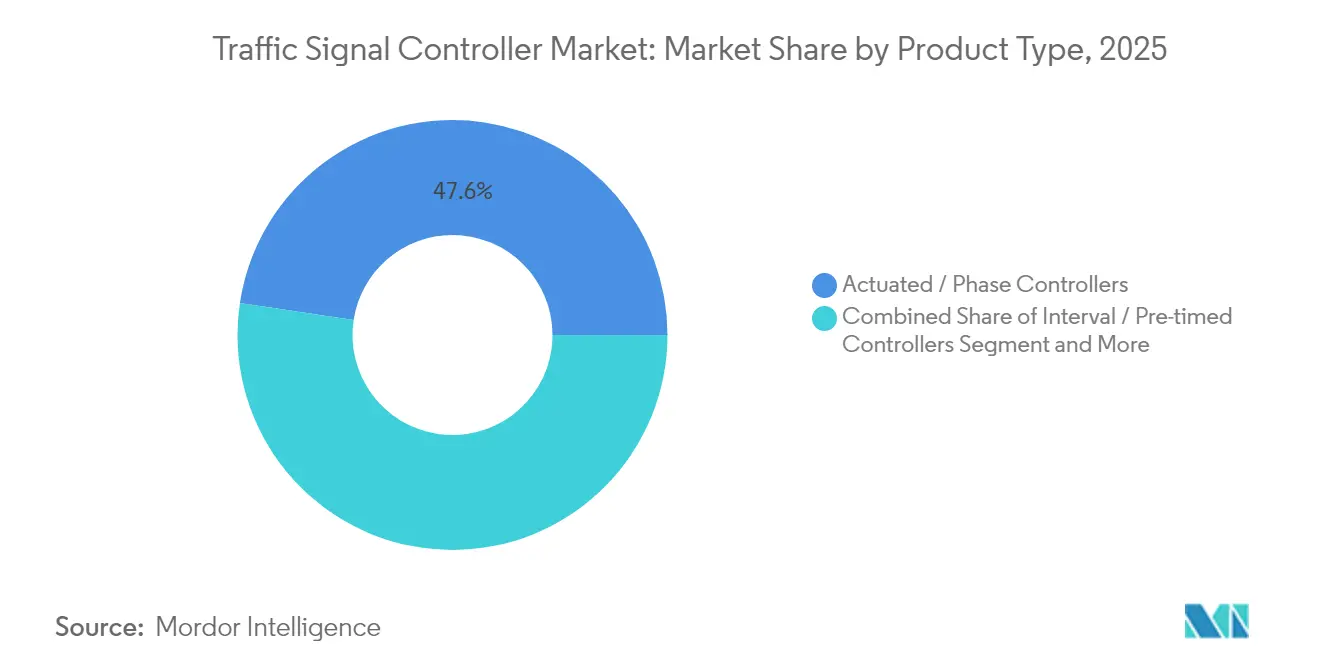
- By product type, actuated/phase controllers held 47.62% of the traffic signal controller market share in 2025, while adaptive/intelligent controllers are projected to grow at a 12.22% CAGR through 2031
- By technology, fully-actuated systems commanded 38.92% of the traffic signal controller market's market share in 2025, while AI-powered adaptive systems are advancing at 12.87% CAGR through 2031.
- By installation environment, urban intersections accounted for 57.64% of the traffic signal controller market share in 2025 and highway and expressway deployments are expanding at 11.12% CAGR to 2031.
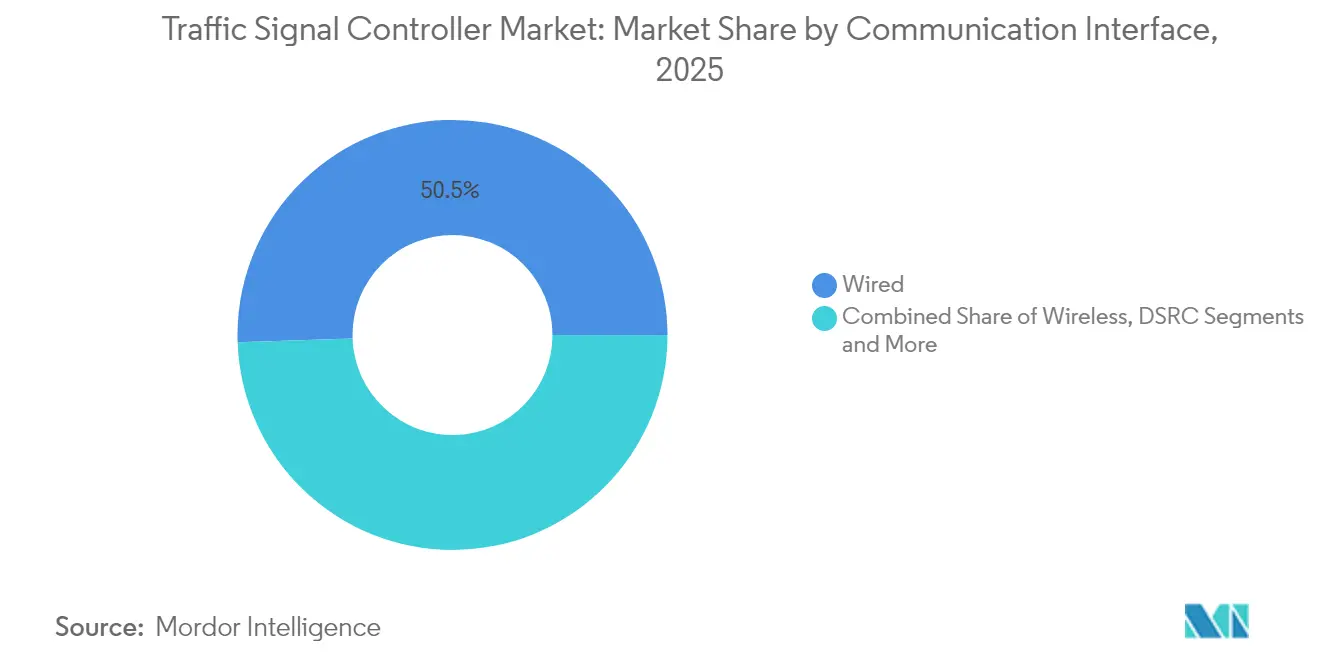
- By communication interface, wired retained 50.54% of the traffic signal controller market's market share in 2025; Cellular-V2X interfaces are growing at 12.41% CAGR through 2031.
- By end user, municipal and city traffic agencies led with 64.05% of the traffic signal controller market's revenue share in 2025; smart-city integrators are projected to expand at a 12.79% CAGR through 2031.
- By geography, North America held 36.95% share of the traffic signal controller market's market share in 2025 while Asia-Pacific is set to grow at 12.92% CAGR between 2026 and 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Traffic Signal Controller Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Urban Congestion and Smart-City Traffic Growth | +2.8% | Global, concentrated in Asia-Pacific megacities | Medium term (2-4 years) |
| Government Funding | +2.1% | North America and Europe, expanding to Asia-Pacific | Short term (≤ 2 years) |
| AI-Enabled Adaptive Traffic-Signal | +1.9% | Global, led by developed markets | Medium term (2-4 years) |
| IoT / V2X Integration | +1.6% | North America and Europe early adoption, Asia-Pacific scale | Long term (≥ 4 years) |
| Edge-Compute Decentralised Controllers | +1.4% | Global, technology-forward cities | Medium term (2-4 years) |
| Emission-Reduction Mandates | +1.2% | Europe and North America regulatory pressure | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Urban Congestion and Smart-City Traffic Growth
Traffic delays already cost Asian megacities 2-4% of GDP in lost productivity, prompting city governments to prioritise signal modernisation within broader mobility masterplans. The Asian Development Bank estimates USD 43 trillion will be spent on transport infrastructure in Asia Pacific by 2035, with 63% directed to road assets that require advanced signal control for throughput gains[1]“Meeting Asia’s Infrastructure Needs,” Asian Development Bank, adb.org . Medellín’s adaptive corridor upgrade reduced average journey times 25% and cut traffic accidents 15%, offering proof that signal retrofits deliver immediate social returns. Such performance records are convincing municipal treasurers to reallocate funds from periodic retiming exercises to capital programmes that install AI-ready controllers. The resulting demand surge ensures the traffic signal controller market remains a core component of every metropolitan digital-infrastructure roadmap.
Government Funding for Smart Transportation Infrastructure
Public financing models have evolved from mileage-based refurbishment to innovation grants that underwrite sophisticated traffic signal solutions. The United States Department of Transportation awarded USD 54 million in SMART grants across 34 projects in 2024, with eight awards earmarked for intelligent signal pilots[2]“SMART Grants Program Awards 2024,” United States Department of Transportation, transportation.gov . Europe mirrors this pattern: the United Kingdom set aside GBP 0.999 million in 2024 for adaptive pedestrian-priority trials. Dedicated programmes de-risk procurement for local agencies by absorbing upfront technology costs, and they promise recurring funds tied to performance milestones. Consequently, manufacturers experience predictable order pipelines, while integrators form consortia to satisfy increasingly complex grant-compliance specifications.
AI-Enabled Adaptive Traffic-Signal Deployment
Artificial intelligence has moved from small-scale pilots toward portfolio-wide roll-outs. Parallel research into Large Language Model agents, such as the LLMLight framework, shows these controllers better handle a typical congestion than earlier reinforcement-learning engines. The cumulative evidence positions AI adaptation not as experimental technology but as baseline functionality for the next procurement cycle, accelerating the traffic signal controller market transition toward predictive optimisation.
IoT / V2X Integration for Real-Time Optimisation
Vehicle-to-Everything standards are reshaping controller architectures. The United States Department of Transportation funded USD 60 million in 2024 for Arizona, Texas and Utah to embed V2X emergency pre-emption and transit signal priority into corridor projects. Peer-review studies confirm roughly 15% faster travel times and 8% lower fuel burn when V2X-enabled signals coordinate with connected vehicles. Cellular-V2X outperforms DSRC on coverage and mobility, while 5G slicing offers deterministic latency for safety-critical phases. As fleets and infrastructure connect over the 5.9 GHz ITS band, controllers become nodes in a cloud-edge network that optimises mobility across an entire region rather than a single junction, cementing V2X as a core determinant of traffic signal controller market growth.
Restraints Impact Analysis of Traffic Signal Controller Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shortage of Advanced Traffic-Engineering Talent | -2.3% | Global, acute in Asia-Pacific and developing markets | Long term (≥ 4 years) |
| Legacy-System Interoperability Hurdles | -2.3% | Global, concentrated in mature markets with aging infrastructure | Medium term (2-4 years) |
| High Installation and Lifecycle Costs | -1.8% | Global, acute in developing markets | Short term (≤ 2 years) |
| Cyber-Security and Data-Privacy Risks | -1.2% | Global, regulatory focus in Europe and North America | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Installation and Lifecycle Costs
Deploying adaptive controllers often requires investment far beyond cabinet replacement. Intersection surveys, fibre backhaul, detection cameras, and staff retraining can raise per-site costs from USD 10,000 to USD 120,000, depending on scope. The National Traffic Signal Report Card places ongoing US operating expenditure at USD 1.23 billion annually, which strains small municipalities with limited tax bases. Hampton Roads’ migration study showed that aligning disparate legacy cabinets onto a common platform necessitated multijurisdictional coordination, delaying procurement cycles. Developing regions face steeper challenges: currency volatility and import duties inflate hardware prices, while shortages of certified technicians extend deployment timelines. Without concessional financing or grant support, cost barriers can defer projects and temper traffic signal controller market expansion.
Cyber-Security and Data-Privacy Risks
As controllers connect to cloud management layers, their attack surfaces grow. Federal Highway Administration research identified some vulnerable traffic sensors worldwide capable of being hijacked to create stop-go waves and emergency routing chaos. Proof-of-concept hacks show that altering a few phase parameters can congest an entire network within minutes. Consequently, the ATC Cybersecurity Project is drafting hardened firmware and authentication guidelines that raise baseline capital costs. European General Data Protection Regulation rules add further complexity by classifying vehicle probe data as personal information. Agencies, therefore, demand NIST-aligned encryption, two-factor authentication, and remote kill-switch capabilities in new tenders. Vendors unable to demonstrate robust cyber controls risk exclusion from high-value procurement processes, constraining their traffic signal controller market share.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Traffic Signal Controller Market Segment Analysis
By Product Type:
Actuated Systems Lead Despite Adaptive GrowthActuated/phase-based controllers held 47.62% of the traffic signal controller market in 2025, supported by decades-long reliability and a large installed base favoring incremental upgrades. Their relatively modest price points and compatibility with inductive loop detectors align with municipality budgets pursuing gradual modernisation. In contrast, adaptive/intelligent models are forecast to record 12.22% CAGR through 2031 as city agencies prioritise dynamic optimisation that lowers delays without widening roads. Technological advancements now overlay cloud analytics onto traditional actuated hardware, extending service life while adding AI functions. Emerging controllers embed GPU modules to execute reinforcement-learning algorithms, enabling the transition from reactive phase selection to predictive split optimisation.


By Technology:
AI-Powered Systems Transform Traditional ApproachesFully actuated technology captured a 38.92% share of the traffic signal controller market in 2025, reflecting its role as the default standard for intersections equipped with vehicle detection. Pre-timed cycles continue in secondary streets, where flow remains predictable. Semi-actuated solutions handle peak-period variability for suburban arterials. AI-powered adaptive controllers, however, deliver the best growth outlook at 12.87% CAGR thanks to measurable outcomes. Taipei’s night-time optimisation yielded 35% shorter waits and TWD 1.83 million annual benefits per intersection. Edge compute allows latency-sensitive decisions to be made locally, while cloud dashboards offer macro-level coordination. These architectures enable agencies to pivot from reactive to self-learning operations, solidifying AI as the technological fulcrum of the traffic signal controller market development.
By Installation Environment:
Urban Dominance Faces Highway ChallengeUrban intersections accounted for 57.64% of the traffic signal controller market share in 2025, reflecting the sheer density of signalised junctions in metropolitan cores. Multimodal pressures—buses, cyclists, and pedestrians—drive demand for advanced phasing logic, transit priority, and pedestrian scramble capabilities. Highway and expressway corridors, though traditionally governed by ramp meters rather than full controllers, are forecast to register 11.12% CAGR as agencies adopt coordinated signal systems along suburban arterials feeding regional freeways. The USD 60 million V2X corridor grants awarded in 2024 illustrate this shift, funding Arizona and Texas projects that synchronise interchange ramps with mainline flow for smoother throughput. As inter-urban travel rebounds, coordinated highway solutions ensure that the traffic signal controller market growth expands beyond inner-city boundaries to wide-area networks.
By Communication Interface:
Wired Systems Yield to Cellular InnovationWired will still constitute 50.54% of controller communication links in 2025 because of its proven uptime and bandwidth advantages. Serial connections linger in legacy networks where capital for fibre upgrades remains scarce. The momentum, however, swings toward Cellular-V2X, forecast to post a 12.41% CAGR to 2031. Direct vehicle-infrastructure messaging eliminates the need for roadside units, reducing deployment costs and enabling speed harmonisation. Independent studies show potential 15% delay savings and 8% fuel reductions when phase selection incorporates probe vehicle data. Wi-Fi and mesh solutions serve campus and event applications requiring rapid setup. Over time, dual-mode radios capable of Ethernet backhaul plus 5G sidelink are expected to dominate new orders, ensuring the traffic signal controller market evolves in tandem with connected vehicle penetration.
By End User:
Municipal Agencies Face Smart-City Integrator CompetitionMunicipal traffic departments commanded 64.05% of 2025 revenues as they own most signalised intersections worldwide. Their procurement often follows five-year replacement cycles, tightly coupled to capital budgets. Smart-city integrators, however, are the fastest-expanding customer group at 12.79% CAGR, benefitting from design-build-operate contracts that bundle connectivity, SCADA, and urban analytics layers with signal control. The SMART grants scheme channels funds to integrators able to deliver multi-domain projects, including environmental sensors and curb-side management, alongside traditional signal hardware. Highway agencies adopt corridor solutions to meet freight-mobility targets, while private industrial parks specify bespoke control to manage shift-change peaks. This diversification redistributes bargaining power toward service-oriented firms that orchestrate complex ecosystems, reshaping value pools within the traffic signal controller industry.
Geography Analysis
North America Traffic Signal Controller Market
North America led with 36.95% of the traffic signal controller market revenue in 2025, supported by predictable federal programmes such as the USD 54 million SMART grants allocated to intelligent signal projects. Mature asset-management frameworks allow rapid disbursement, and the Biden-Harris Administration’s infrastructure law secures multiyear funding. Canadian provinces complement federal actions through regional smart-corridor schemes synchronizing cross-border freight flows. The result is continuous upgrade activity, with agencies migrating from legacy NEMA cabinets to ATC cyber-secure platforms.
APAC Traffic Signal Controller Market
Asia-Pacific is the fastest-growing region at 12.92% CAGR to 2031. The Asian Development Bank’s projection of USD 43 trillion in transport investments, of which 63% targets road networks, underscores the scale of opportunity. China’s national smart-city programme funds AI controllers across tier-two urban clusters, while India’s Smart Cities Mission accelerates tenders for adaptive signals that cut congestion without land acquisition. Japan, Singapore, and South Korea exploit domestic semiconductor capacity to pilot V2X-ready systems ahead of commercial vehicle rollouts. Collectively, these initiatives enlarge the traffic signal controller market faster than in any other geography.
Europe Traffic Signal Controller Market
Europe maintains a steady trajectory driven by climate legislation that prioritises traffic optimisation as a carbon-reduction lever. Cities deploying low-emission zones turn to adaptive phasing to prevent rerouted flows from creating new hotspots. The July 2024 acquisition of Ireland’s Elmore Group by SWARCO bolsters regional consolidation, offering agencies pan-European service coverage. The United Kingdom deploys dynamic traffic management funded by GBP 0.999 million national grants, and Nordic countries digitise arterial networks to support connected-autonomous tests. Cyber-security regulations such as NIS-2 raise procurement hurdles but also favour vendors with proven security credentials, sustaining premium pricing within the traffic signal controller market.

Regulatory Landscape
Traffic signal controller procurement is shaped by interoperability and safety standards covering cabinet hardware, communications, and software interfaces. In the United States, many municipal tenders reference NEMA TS-series requirements alongside NTCIP for management-center to controller communications, while the ATC (Advanced Transportation Controller) family of specifications, developed through bodies such as AASHTO, ITE, and NEMA, supports more open, multi-vendor deployments. At the international level, ISO 14815-1:2020 is a commonly referenced performance standard for traffic signal controllers and is used as a baseline for evaluating suppliers.
Cybersecurity and cross-border interoperability requirements are becoming more explicit in public-sector projects as signal networks connect to cloud management layers and V2X ecosystems. In Europe, the EU ITS Directive (2010/40/EU) anchors interoperability objectives for ITS deployments, shaping controller and central system interface expectations in multi-city and corridor projects. At the same time, agencies increasingly align procurement language with recognized cybersecurity frameworks (including NIST-aligned controls referenced in North American programs) as connected-controller deployments expand under public funding programs such as the US DOT SMART Grants (USD 54 million awarded across 34 projects in 2024, with multiple intelligent signal pilots).
Value Chain Analysis
The traffic signal controller value chain runs from electronics and enclosure supply through controller OEM design and firmware, and then into software platforms and field integration. Upstream inputs include semiconductors, industrial compute modules, radios, power supplies, and hardened cabinets, followed by controller manufacturing and configuration to common standards, including ATC-oriented architectures and NEMA cabinet ecosystems. Midstream, software layers such as central traffic management suites, adaptive algorithms, and cybersecurity toolsets are bundled with controller hardware and delivered by system integrators and traffic engineering firms that manage design, civil works, detection devices, communications backhaul, and commissioning.
Downstream, municipal and city traffic agencies remain the primary buyers, while highway departments and smart-city integrators increasingly procure controllers as part of corridor modernization and cloud ATMS programs. Lifecycle services (spares, patching, and maintenance SLAs) and interoperability testing capture a meaningful share of value since agencies must keep mixed fleets of legacy cabinets and newer ATC platforms operational. On the supply side, electronics availability and import duties can affect lead times and cost-to-serve, which reinforces demand for standardized, multi-vendor platforms that reduce proprietary lock-in and expand the pool of qualified maintenance providers.
Competitive Landscape
The traffic signal controller market displays moderate concentration dominated by Siemens Mobility, Yunex Traffic and SWARCO, each leveraging acquisition strategies to extend geographic reach and product breadth. Yunex, now under Atlantia, deploys the Stratos UTMC suite that Lancashire installed in December 2024 to manage citywide congestion, demonstrating the firm’s ability to integrate software with roadside hardware.
SWARCO follows an expansion pathway centred on regional bolt-ons; the July 2024 purchase of Ireland’s Elmore Group augmented its European intelligent transportation portfolio and added service capacity in Western Europe. Earlier acquisitions of McCain and Dynniq strengthened SWARCO’s foothold in North America and Benelux, evidencing a deliberate strategy to secure local maintenance bases that agencies value for uptime guarantees. Competitors such as Econolite and Trafficware focus on NEMA cabinets for the United States but increasingly partner with AI analytics start-ups to remain relevant as software differentiates bids.
Technology competition now tilts toward edge AI, V2X readiness and cyber hardening rather than metal enclosures. Vendors incorporate Trusted Platform Modules and zero-trust architectures to satisfy FHWA’s ATC Cybersecurity Project guidelines. Strategic alliances with cellular operators underpin 5G-V2X pilots, while open-API controllers invite third-party algorithm developers, creating an ecosystem play. White-space opportunities persist in emerging markets where infrastructure commitments outstrip current supplier capacity, allowing medium-sized regional firms to secure early mover status. Overall, differentiation hinges on software agility and security assurance, themes that will continue to shape future traffic signal controller market share.
Traffic Signal Controller Industry Leaders
Siemens Mobility
Econolite
SWARCO
Q-Free ASA
Sumitomo Electric Industries
- *Disclaimer: Major Players sorted in no particular order

Traffic Signal Controller Market Companies Covered in this Report
- Siemens Mobility
- Yunex Traffic
- Aldridge Traffic Controllers (ATC)
- Econolite
- Intelight
- Sumitomo Electric Industries
- SWARCO
- McCain Inc.
- JARI Electronics
- Hisense TransTech
- KYOSAN Electric Manufacturing
- FAMA Traffic
- Dynamic Traffic Systems
- Duolun Technology
- Cubic Corporation
- Trafficware
- Peek Traffic Corporation
- Q-Free ASA
- Rhythm Engineering
- Iteris

Market Opportunities and Future Outlook
The most visible opportunity is in software-defined upgrades that extend the useful life of installed controller fleets while enabling adaptive performance, V2X-readiness, and stronger cyber controls. Public programs continue to underwrite deployments that pair controller refresh with communications and analytics, including US DOT SMART Grants activity in 2024 and US corridor funding that embeds V2X emergency pre-emption and transit signal priority. For vendors, this supports portfolios that combine ATC/NTCIP-compatible hardware with cloud-based ATMS, remote configuration, and security hardening as agencies manage expanding attack surfaces and heterogeneous cabinet estates.
Geographic whitespace also shows up in how agencies extend advanced traffic management beyond city-center intersections into corridor and ramp-control applications. In the Middle East, Abu Dhabi deployed an adaptive ramp metering system (Econolite/PTV Group Umovity with ST Engineering referenced in project materials), pointing to demand for higher-end control strategies integrated with broader ITS platforms rather than standalone cabinet swaps. In the United States, state and city frameworks that standardize controller platforms, including ATC-oriented modernization approaches referenced in Virginia-related deployments, support repeatable procurement across districts and give suppliers a clearer pathway to sell controllers alongside central software, monitoring, and ongoing services.
Recent Industry Developments in Traffic Signal Controller Market
- July 2026: Parsons won a USD 33 million contract to modernize New York State DOT intelligent transportation systems using its iNET smart mobility platform, including replacement of CPU cards for more than 6,000 traffic signal controllers. The scale of controller electronics upgrades highlights how agencies are blending central platform modernization with targeted hardware refresh rather than only full cabinet replacement.
- May 2026: Miovision launched an AI-driven, end-to-end traffic signal optimization and retiming solution on the Miovision One platform, including Controller Manager for remote access to NTCIP-compliant controllers. The release continues the shift toward cloud and software layers that improve performance through ongoing tuning and remote operations across multi-vendor controller environments.
- July 2025: Q-Free and Traffic Control Products secured a statewide contract with the Kentucky Transportation Cabinet to supply 500 additional advanced transportation controllers as part of a multi-phase modernization initiative. The award reinforces standardized controller rollouts at the state level and supports demand for ATC-oriented upgrades with consistent spares, maintenance, and interoperability across districts.


Traffic Signal Controller Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers revenue earned from traffic signal controllers used to operate and coordinate signal phases at road intersections, corridors, and pedestrian crossings, including controller hardware, embedded software, and related commissioning tied to a controller sale.
Scope exclusions: We exclude stand-alone traffic sensors, cameras, V2X roadside units, and central traffic management platforms when they are sold without a traffic signal controller.
Segments Covered in This Report
- By Product Type
- Interval / Pre-timed Controllers
- Actuated / Phase Controllers
- Adaptive / Intelligent Controllers
- Centralised Cloud Controllers
- Solar-powered Controllers
- By Technology
- Pre-timed Fixed-Cycle
- Semi-actuated
- Fully-actuated
- AI-powered Adaptive
- Edge-compute Enabled
- By Installation Environment
- Urban Intersections
- Highways & Expressways
- Pedestrian Crosswalks & School Zones
- Parking Facilities & Campuses
- Public-transport Priority Corridors
- By Communication Interface
- Wired (Ethernet / Serial)
- Wireless (Wi-Fi / Cellular)
- DSRC
- Cellular-V2X
- By End User
- Municipal & City Traffic Agencies
- Highway & Transport Departments
- Smart-city Integrators & EPCs
- Private Industrial Parks & Campuses
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set the fact base for intersection counts, funding cycles, and safety-driven signal upgrades, and then to translate that into realistic replacement and expansion demand. We referenced public sources such as US Federal Highway Administration publications, US DOT program documents, NHTSA road safety statistics, US Census urbanization data, and standards bodies and procurement guidance notes used for traffic control equipment.
On the supply side, we reviewed manufacturer annual reports, investor presentations, product catalogs, and public tender notices to understand typical configurations and selling patterns, and how pricing shifts with communications interfaces and cabinet integration. Where available, paid subscriptions for company financials and patent databases were used to cross-check product focus and the pace of new controller features. The sources listed here are illustrative only, and we also reviewed other public documents and datasets to confirm and clarify assumptions.
Primary Interviews and Surveys
Primary work focused on interviews and short surveys with city and state traffic engineers, system integrators, distributor channels, and controller product specialists across major regions, so desk findings could be checked against on-the-ground buying behavior. Respondent input helped validate replacement timing, typical controller counts per intersection, the share of adaptive upgrades, and the practical split between new installs and retrofit projects.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 29% | CXOs: 17% | APAC: 46% |
| Mid tier: 50% | Functional/Unit leaders: 24% | EMEA: 31% |
| Smaller Players: 21% | Managers: 59% | Americas: 23% |
Market-Sizing & Forecasting
Sizing starts with a top down reconstruction of controller demand using intersection inventory proxies and funded signal modernization plans, which are then filtered through replacement cycles and installation mix. To keep the model practical, we used a small set of repeatable inputs such as the estimated number of signalized intersections, average controllers per intersection (including corridor coordination needs), replacement intervals by environment (urban versus rural), the share of adaptive and networked deployments, and typical price ranges by controller class and communication interface.
After that, we corroborated results using selective bottom-up checks, including sampled price x volume builds from public tenders, distributor channel checks, and supplier revenue allocation where disclosures allowed. When country data was thin, gaps were filled using analog markets with similar urban density and road spending patterns, followed by expert review to avoid over-smoothing fast-changing city-level procurement. Forecasts rely mainly on scenario analysis, where near term spending programs and procurement lead times are stress tested, and then medium term growth is aligned to expected smart corridor rollouts and safety initiatives.
Data Validation & Update Cycle
Outputs are validated through multiple checks so the totals remain tied to observable deployment signals. We compare implied controller shipments and replacement rates against tender intensity, public budget signals, and expert feedback, and then investigate any large variances before locking assumptions.
A second analyst review is completed for key inputs like replacement cycle, pricing progression, and regional weights, followed by a final consistency pass across time series so step changes have a documented reason. Reports refresh annually, and interim updates are triggered when material events affect public funding, standards, or supply availability. Before delivery, a final refresh scan is performed so clients receive the latest updated view.
Mordor Intelligence's Traffic Signal Controller Market Size Compared Against Other Published Estimates
Published market values for traffic signal controllers can look far apart even when they seem to describe the same thing, because the scope and the counting logic are not always aligned. Differences usually come from what is included around the controller, how services are treated, which year is used as the base, and how pricing is converted across regions.
Some external estimates group controllers into a wider intelligent traffic control systems spend, which can pull in sensors, connected roadside equipment, and central software. In Mordor Intelligence, the market is counted only when revenue is directly linked to the controller unit and its controller-tied software and commissioning, and adjacent ITS components sold separately are not added into the total.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 6.44 B (2026) | |
| Industry Publisher A | USD 6.36 B (2026) | Often labeled as automatic signal controllers, and the scope can include broader automation stacks or component bundles, which shifts what is counted as controller revenue across projects. |
| Market Tracker B | USD 3.20 B (2025) | Uses an earlier base year and tends to apply narrower pricing and slower replacement assumptions, which reduces the implied controller value per intersection and compresses the total market. |
Overall, the spread is explained by scope expansion into nearby traffic management items in one case and more conservative replacement and pricing inputs in the other case. By keeping the model tied to intersection controller demand, tender price signals, and validated replacement timing, the estimate stays traceable to clear variables and can be repeated as new budgets and deployments are released.


Key Questions Answered in the Report
What is the current size of the traffic signal controller market and how fast is it growing?
The market is valued at USD 6.44 billion in 2026 and is forecast to reach USD 11.54 billion by 2031, registering a 12.38% CAGR.
Which end-user segment holds the largest share?
Municipal and city traffic agencies account for 64.05% of 2025 revenue, reflecting their ownership of most signalised intersections.
Which technology segment is expanding the quickest?
AI-powered adaptive controllers are the fastest-growing technology, advancing at a 12.87% CAGR through 2031.
Which region offers the highest growth potential?
Asia-Pacific is projected to grow at 12.92% CAGR, supported by USD 43 trillion in planned transport infrastructure spending through 2035.
What are the main drivers propelling market demand?
Urban congestion, government funding programmes such as the U.S. SMART Grants, and the shift toward AI-enabled, V2X-ready systems are the primary growth catalysts.
How significant are cyber-security risks in new deployments?
Some of the vulnerable traffic sensors have been identified worldwide, prompting agencies to mandate hardened firmware and zero-trust architectures in procurement specifications.
Page last updated on:


 Your data is secure and never sold or shared.



