
Singapore Foodservice Market Size and Share
Singapore Foodservice Market Analysis by Mordor Intelligence
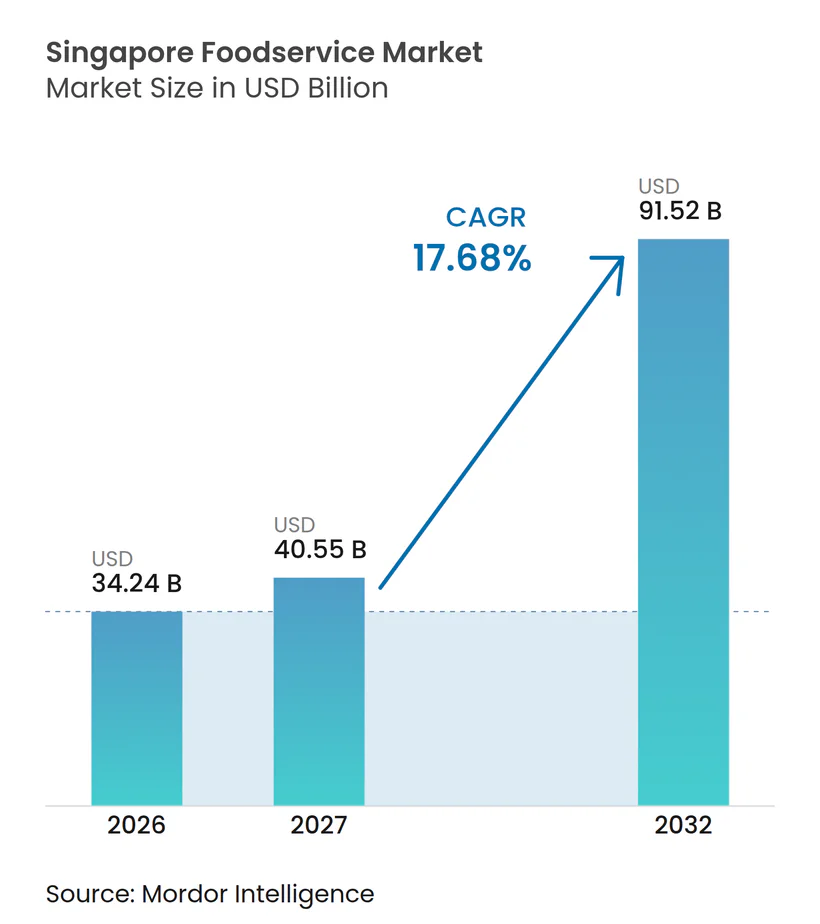
The Singapore foodservice market size was valued at USD 34.24 billion in 2026 and estimated to grow from USD 40.55 billion in 2027 to reach USD 91.52 billion by 2032, at a CAGR of 17.68% during the forecast period (2027-2032).
Singapore's beverage purchases and social dining create distinct paid occasions, favoring foodservice offers designed around how customers use a venue. Chains can replicate recognizable products, while neighborhood operators can align service with residential catchments. Digital-payment access supports transaction completion, although staffing and licensing constraints can limit the hours or timing of service. From February 2026, the Iran conflict disrupted Strait of Hormuz shipping, adding a supply-cost risk for Singapore operators. Such cost exposure favors operators whose repeat beverage visits and group meals generate enough revenue within staffing and licensing limits to absorb higher input bills.
Key Report Takeaways
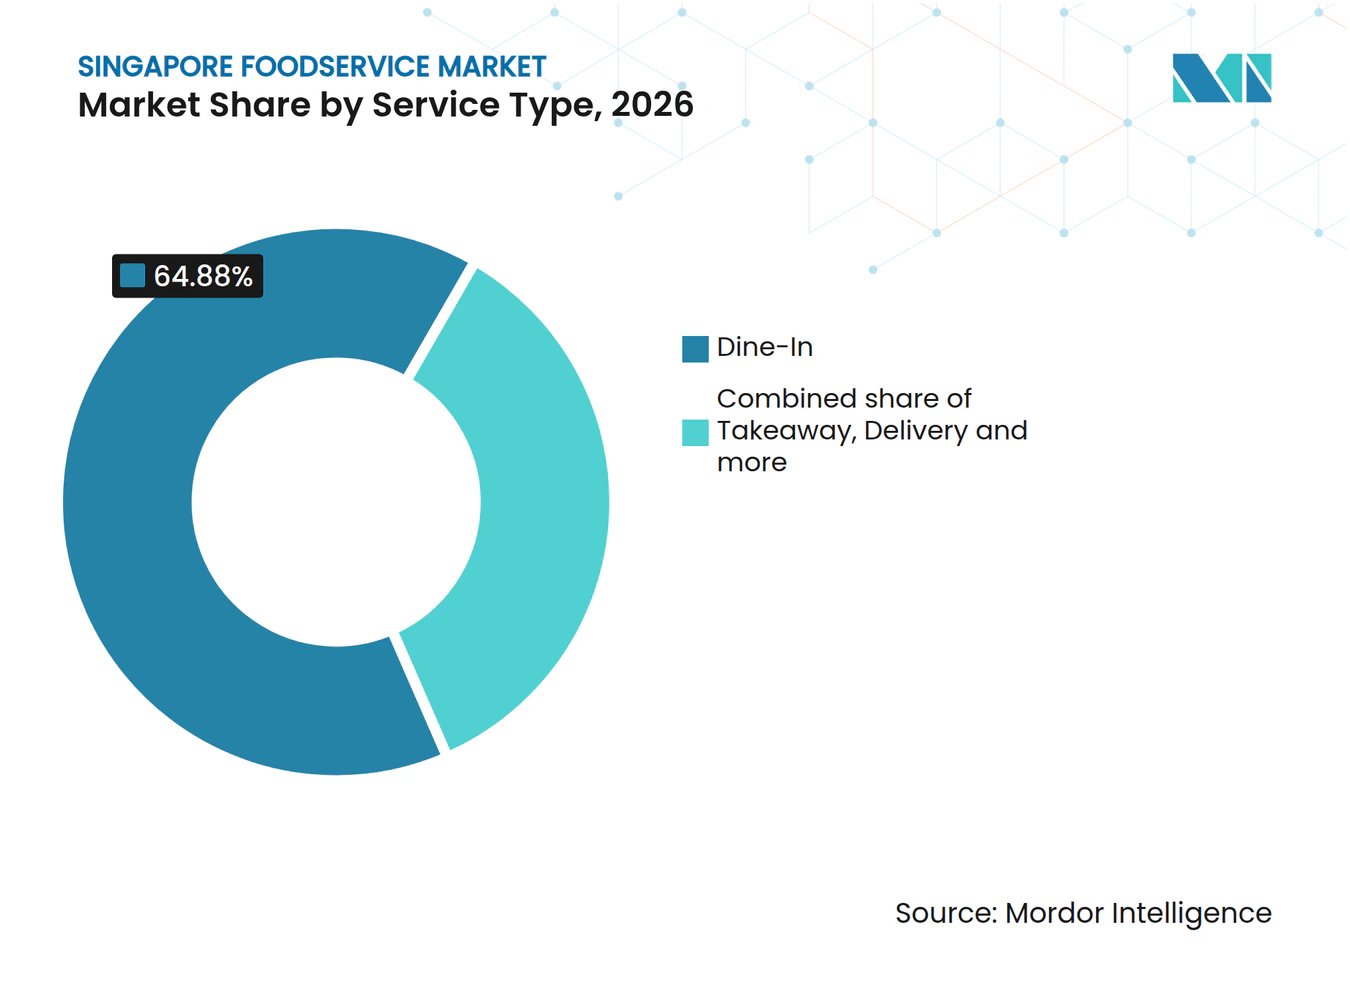
- By service type, dine-in led with a 64.88% Singapore foodservice market share in 2026, while delivery is forecast to grow fastest at a CAGR of 19.4% during 2027-2032.
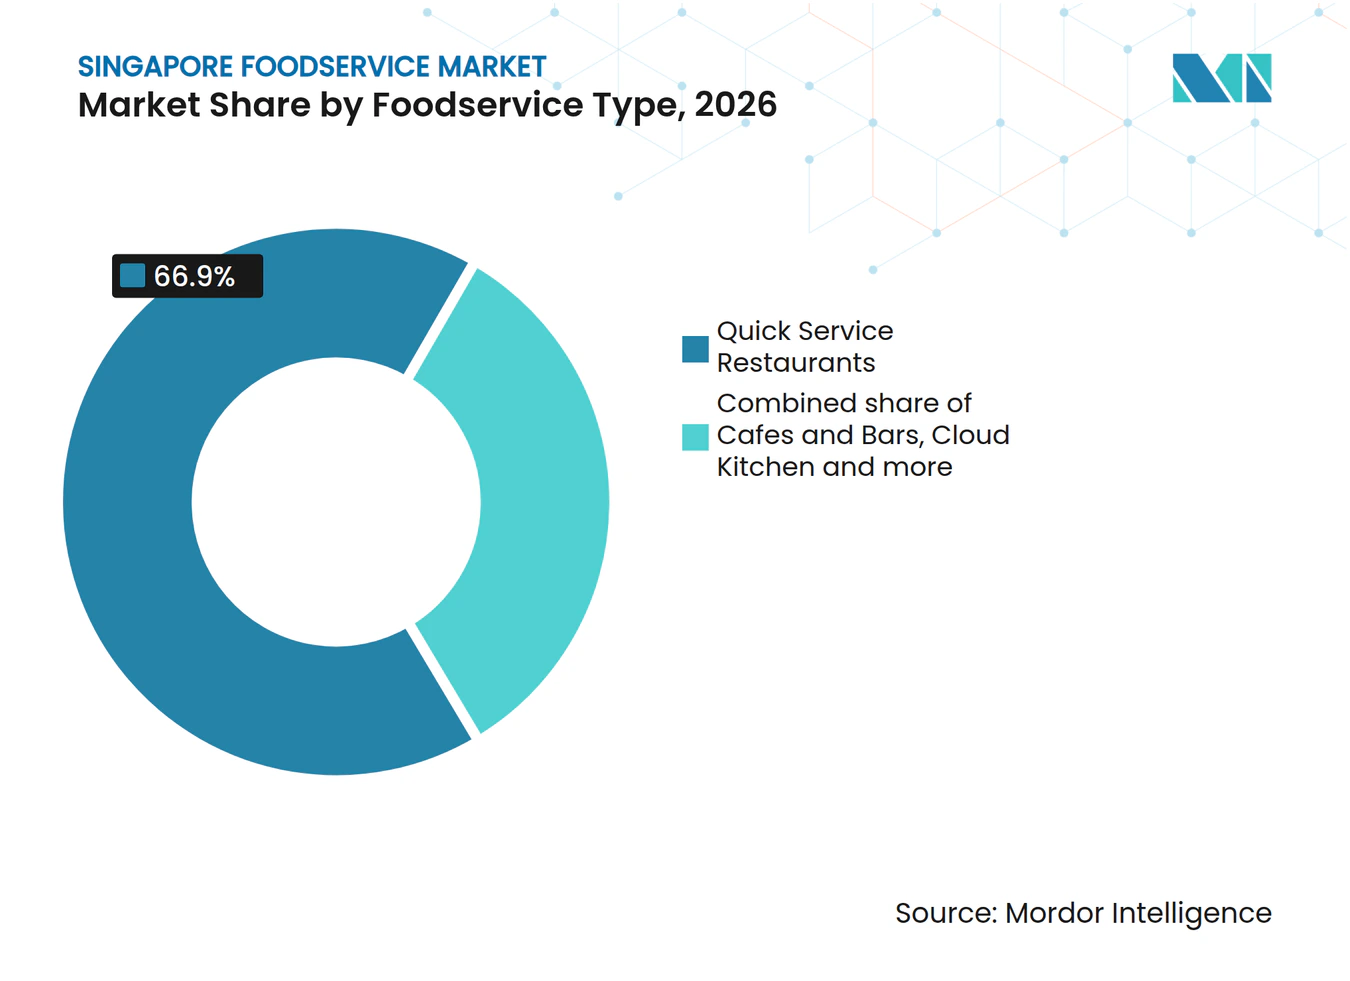
- Foodservice types were led by quick-service restaurants, with a 66.9% share of the Singapore foodservice market size in 2026, whereas cloud kitchens are forecast to grow fastest at a CAGR of 19.35% during 2027-2032.
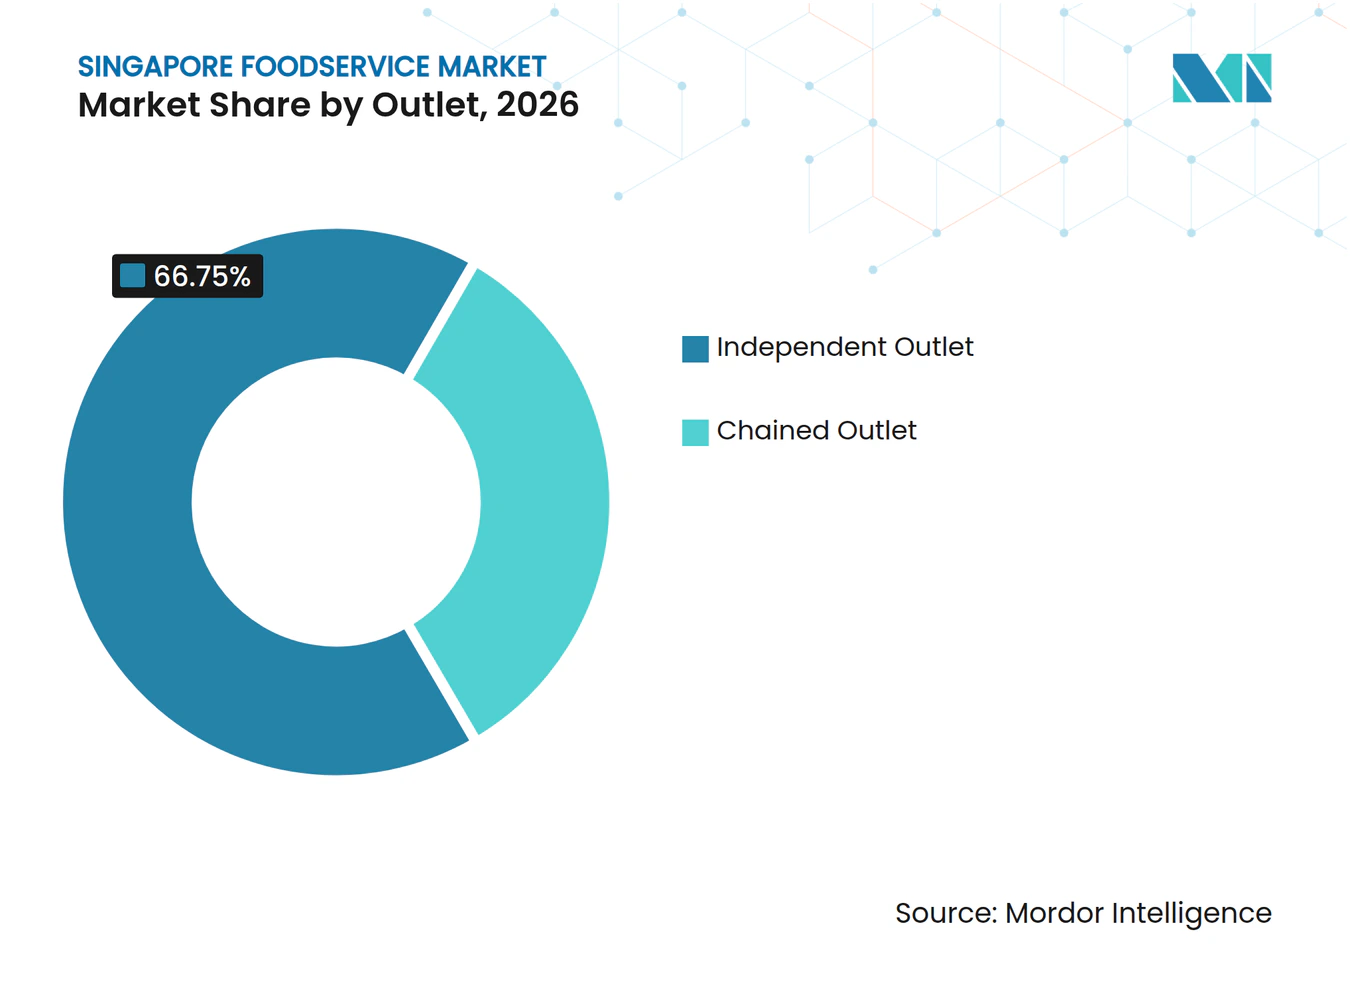
- Among outlet ownership types, independent outlets accounted for 66.75% of foodservice sales in 2026, and chained outlets are forecast to grow fastest at a CAGR of 17.95% during 2027-2032.
- Location-based sales were led by standalone venues with 76.4% of foodservice sales in 2026, while lodging is forecast to grow fastest at a CAGR of 19.4% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Singapore Foodservice Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing demand for specialty beverages and a robust coffee culture | +6% | Nationwide | Medium term (2-4 years) |
| Increasing preference for social and post-work gatherings | +4.5% | Nationwide | Medium term (2-4 years) |
| Rising use of digital payments and contactless transaction methods | +4% | Nationwide | Short term (≤ 2 years) |
| Demand for unique dining experiences and social engagement | +3.5% | Mandai Wildlife Reserve | Long term (≥ 4 years) |
| Shifting consumer preferences and expanding menu offerings | +2% | Nationwide | Medium term (2-4 years) |
| Expansion of the tourism and hospitality sector | +2.5% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Growing demand for specialty beverages and a robust coffee culture
Coffee-chain expansion can make prepared beverages a more accessible purchase and create additional occasions for foodservice spending between meals. Luckin Coffee opened 30 net new stores in Singapore during 2025. That expansion gives the operator more locations from which to compete for routine beverage purchases and build a recognizable service offer. For beverage operators, the commercial value of additional locations depends on making coffee convenient enough to become a repeat purchase. Each added store's contribution to demand depends on attracting occasions that nearby outlets were not already serving.
Increasing preference for social and post-work gatherings
A shared meal can give a social gathering a practical destination, creating foodservice demand around the group rather than an individual eating schedule. Srisun Express operator Elan Goven said in August 2026 that she thought people generally had begun making a more deliberate effort to socialize and spend time together. For restaurants, the opportunity is to accommodate that joint occasion through seating and service that let companions eat together.
Rising use of digital payments and contactless transaction methods
Digital-payment acceptance can protect foodservice demand when a customer wants a prepared meal but does not intend to pay with cash. The National Environment Agency (NEA) reported that about two-thirds of stalls at Singapore hawker centers accepted e-payment solutions as of December 31, 2025.[1] This acceptance base shows that electronic settlement is already available at about two-thirds of hawker-center stalls, without requiring a change in the meal itself. Its demand contribution comes from removing a payment barrier at the point of sale, rather than creating a new food category. Stalls without e-payment acceptance risk losing meal purchases when customers arrive without cash.
Demand for unique dining experiences and social engagement
Tung Lok Restaurants (2000) Ltd launched Cavern Restaurant at Rainforest Wild ASIA in March 2025 through a partnership with Mandai Wildlife Reserve. The operator described it as Singapore's first and only cave-themed dining destination, welcoming park and public guests for social gatherings and other outings. The theme gives diners a reason to choose a meal as part of an experience, making the setting part of the foodservice proposition. Public access gives Cavern a route to attract dedicated dining visits alongside meals associated with a park visit.
Restraints Impact Analysis of Singapore Foodservice Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Challenges in adhering to regulations and navigating licensing complexities | -1.5% | Nationwide | Medium term (2-4 years) |
| Workforce shortages and elevated employee turnover | -2% | Tras Street restaurant operations | Long term (≥ 4 years) |
| Brand cannibalization in multi-brand groups | -0.5% | Nationwide | Medium term (2-4 years) |
| Increasing raw material costs and disruptions in the supply chain | -1% | Chinatown Complex and nationwide supply chains | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Challenges in adhering to regulations and navigating licensing complexities
A food-shop opening can lose trading time when its licensing submission requires correction before approval. For food-shop license applications, the Singapore Food Agency (SFA) says rectifications or clarifications may slow processing, and incomplete applications are rejected and must be resubmitted. The distinction matters commercially because a correctable query and a rejected application create different paths to reaching the point of serving customers. Operators preparing a new outlet therefore face a sequencing risk, with the start of revenue dependent on satisfying the submission requirements. This conditional barrier can make an opening timetable less dependable and extend the period before a foodservice investment begins earning sales.
Workforce shortages and elevated employee turnover
Staffing constraints can limit foodservice sales by shortening the hours during which a restaurant can serve customers. By August 15, 2026, The Gogijip in Tras Street had begun closing from 3 a.m. to 9 a.m. on Tuesday mornings amid rising costs and manpower constraints.[2] For a restaurant built around extended opening hours, that adjustment narrows the period available to capture late-night demand. Adding dining-room space would not recover sales during those closed hours, so the binding limit is the ability to staff service. Owner Annabelle Lee said the closure gave the team time to rest and helped make operations more sustainable. The remaining trade-off is a recurring interval when the outlet cannot earn meal sales.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Singapore Foodservice Market Segment Analysis
By Service Type:
Seating Capacity and Delivery EconomicsDine-in accounted for a 64.88% share of the Singapore foodservice market size in 2026, making it the largest segment by service type. In early July 2025, Amanda Chia and Alex Ng opened Beth, a 55-seat restaurant on Casuarina Road. Later that month, CNA Lifestyle reported that customers were waiting about an hour for a table. The example highlights a capacity trade-off for dine-in operators, because a queue demonstrates interest while the number of customers served depends on how the venue uses its tables and service capacity.
Delivery is forecast to be the fastest-growing segment by service type, at a CAGR of 19.4% during 2027-2032. On April 8, 2025, Grab said GrabFood for One was available in Singapore, offering solo diners one-person meals with no small-order fees and a fixed, low delivery fee. That structure lets a customer order a solo meal without increasing the basket merely to avoid a small-order fee.

By Foodservice Type:
Restaurant Networks and Productive Kitchen SpaceQuick-service restaurants represented a 66.9% Singapore foodservice market share in 2026, making them the largest segment by foodservice type. McDonald's Singapore had more than 150 restaurants islandwide in June 2025. That network illustrates the breadth through which a standardized meal format can reach customers, giving the operator multiple points of service rather than depending on one dining destination.
Cloud kitchens are forecast to be the fastest-growing segment by foodservice type, at a CAGR of 19.35% during 2027-2032. KitchenBASE reports 10 operating commercial kitchen facilities in Singapore that it describes as meeting Food Shop License and Food Processing License needs. Turning that premises provision into a delivery business requires enough meal orders to use preparation and dispatch capacity productively.
By Outlet:
Individual Tenancies and Replicable Beverage OffersIndependent outlets were the largest segment by outlet ownership, accounting for 66.75% of foodservice sales in 2026. NEA's October 2026 tender terms normally cap individual rentals at 2 cooked-food stalls in NEA-managed hawker centers. Individual tenderers must be Singapore citizens or permanent residents aged at least 21, with qualifying undischarged bankrupts assessed case by case. This provides a route for individual participation in prepared-meal sales while constraining the scale available through that particular tenancy channel. Within the normal 2-stall limit, an individual tenant's route to higher sales is to serve more meal occasions through the permitted footprint.
Chained outlets are forecast to be the fastest-growing segment by outlet ownership, at a CAGR of 17.95% during 2027-2032. Luckin Coffee opened its 100th store in Singapore on September 28, 2026.[3] By that date, the company said its Coconut Latte and Little Butter Latte had each surpassed 2 million cups in cumulative local sales. Those cumulative sales identify the Coconut Latte and Little Butter Latte as drinks the chain can carry into each new site.
By Location:
Dedicated Sites and Hotel Dining ChoicesStandalone locations were the largest segment by location, accounting for 76.4% of foodservice sales in 2026. An operator choosing a dedicated site can shape the meal occasion around its own outlet, making access and a recognizable reason to visit central to the location proposition. That autonomy can accommodate a service format whose trading pattern does not depend on a hotel's guest schedule or a travel venue's passenger flow. However, the venue must generate sufficient meal occasions to justify the site as a foodservice destination. Site selection and customer acquisition become linked decisions because the outlet must create the meal occasion that sustains its premises.
Lodging is forecast to be the fastest-growing segment by location, at a CAGR of 19.4% during 2027-2032. Hyatt completed Grand Hyatt Singapore's transformation on August 28, 2025, with 699 rooms and 7 distinct dining venues. That configuration places several dining choices within one hotel operation, allowing the foodservice proposition to address different guest occasions instead of relying on a single restaurant offer. Hyatt described the hotel's 699 rooms and suites as one of the largest premium hotel inventories in the city, giving its dining venues a substantial potential audience among overnight guests.
Geography Analysis
Downtown's mixed land uses create a commercial case for serving more than the office lunch occasion. The Urban Redevelopment Authority (URA) describes Singapore's downtown, including the Central Business District, as a business and financial hub with mixed uses and city-living opportunities. It describes Marina Bay as an extension of the Central Business District combining offices, residences, hotels, and event facilities. For foodservice operators, that combination supports a choice between concentrating on a specific customer occasion and developing an offer that can serve several. Service hours matched to office workers, residents, hotel guests, and event visitors can use that mixed catchment beyond a single lunch sitting.
Changing residential provision in heartland estates creates a different foodservice opportunity from established commercial districts, with the timing of access becoming a central operating decision. URA's Marina South urban design guidelines envision a community-centric 10-minute district with amenities within easy reach of residents and visitors. In March 2026, the Housing & Development Board (HDB) announced that residents moving into new large-scale Build-To-Order (BTO) estates would gain access to cooked food and other amenities up to 3 months earlier than before. Earlier cooked-food access makes an outlet's opening date commercially significant, because service must coincide with residents moving in to turn planned accessibility into meal purchases.
Orchard Road, Sentosa, and the Changi region present different ways to connect a foodservice outlet with the purpose of a visit. URA describes Orchard Road as a lifestyle and retail belt with a pedestrian mall connecting developments, public spaces, and MRT stations. Indian visitors to Sentosa increased 8% year over year from April 2025 to March 2026, expanding that particular visitor audience. Coach launched Coach Restaurant, a New York-style steakhouse, at Jewel Changi Airport in the Changi region on October 31, 2025, its first restaurant in Singapore. The commercial distinction is whether an outlet must win a meal during another activity or give the customer a reason to make dining the activity.
Regulatory Framework and Outlook
Selected jurisdictions and location-specific requirements are compared from the perspective of a new food-shop operator, covering Singapore's national regime and its application in Orchard Road. SFA's Food Shop licensing requirements cover restaurants, coffee shops, food courts, and takeaway food carts, with conditions varying by outlet type. Since January 19, 2026, SFA's Safety Assurance for Food Establishments (SAFE) Phase 1 has graded covered licensed establishments preparing or processing food for public sale by safety record, inspecting poorer performers more frequently. For an entrant, the establishment's operating record and the proposed use of its premises are therefore relevant to the path from site selection to ongoing service.
Regulatory Table of Singapore Foodservice Market
| Decision factor | Singapore | Orchard Road |
|---|---|---|
| Primary authority | Singapore Food Agency | Singapore Food Agency for licensing; Urban Redevelopment Authority for site-use guidance |
| Key instruments or direction | Applicable retail food licenses, Environmental Public Health (Food Hygiene) Regulations, and SAFE Phase 1 | National food requirements plus activity-generating uses at specified first-floor frontages and basement pedestrian links |
| Commercial effect | Licensing and hygiene duties; SAFE inspection exposure varies for covered establishments | National duties plus location-specific conditions recognizing retail, food and beverage, and other active uses |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | Hardening | Hardening |
| Source: Mordor Intelligence | ||
Singapore's Medium rating balances an established licensing route with enforceable hygiene obligations and record-based inspection exposure. Orchard Road's Medium rating reflects additional planning conditions that recognize food and beverage among several activity-generating uses at specified locations. Both Hardening ratings reflect announced SAFE Phase 2 conditions for Category 1 establishments seeking grade A, requiring an Advanced Food Hygiene Officer and a certified or non-certified food-safety management system. SFA says Phase 2 implementation details are due to be announced by 2027, so the future burden relates to a defined grade objective while Phase 1 duties continue to apply.
Value Chain Stages
The value chain compares supplier earnings and operating constraints from kitchen setup through meal preparation, delivery services, and ongoing equipment care. In FY2025, Singapore Kitchen Equipment Limited reported that restaurant operators in its markets deferred new kitchens or bought secondhand equipment amid higher rental, labor, and utility costs. Those choices reduced its new installations and equipment sales, illustrating how restaurant cost pressure can change the opportunities available upstream. A supplier offering equipment rental and maintenance has an additional route to serve the existing kitchen base when new fit-outs are deferred.
Value Chain Analysis Table of Singapore Foodservice Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Kitchen setup | Equipment suppliers such as Singapore Kitchen Equipment Limited and M-Vista | Equipment sales and installation fees; equipment rental at Singapore Kitchen Equipment | Deferred fit-outs and secondhand substitution in supplier markets | Offer staged replacement or rental suited to the outlet's service needs |
| Food and ingredient distribution | Food distributors such as Bidfood Singapore and Wilmar Distribution | Ingredient and food-product sales | Exposure to delayed restaurant payments | Set customer-specific credit limits and prepayment triggers |
| Meal preparation and service | Meal-preparation operators such as Select Catering, owned by Select Group of Companies | Prepared-meal sales | Preparation capacity must fit the promised meal volume | Align batch preparation with committed meal orders |
| Delivery marketplace services | Marketplace platform operators such as Grab Singapore | Merchant service fees set by commercial terms and demand-generation or delivery mode | Merchant value must justify contracted service fees | Match the service scope and fee structure to the order channel |
| Equipment upkeep | Maintenance providers such as Singapore Kitchen Equipment Limited and M-Vista | Preventive maintenance and repair fees | Equipment failure can interrupt meal preparation | Schedule preventive care around trading hours |
| Source: Mordor Intelligence | ||||
Toh Thye San Farm said a credit sale to The Banana Leaf Apolo took about a year to settle, with the debt paid by June 30, 2025. Dessert Guru said in September 2025 that some customers took up to 120 days to pay against 30-day terms, while it paid suppliers on delivery or within a month. The mismatch between customer receipts and supplier payments can tie up a distributor's working capital after ingredients have been delivered. Credit limits and prepayment triggers can limit the unpaid balance a distributor carries while supplying restaurant customers.
Competitive Landscape
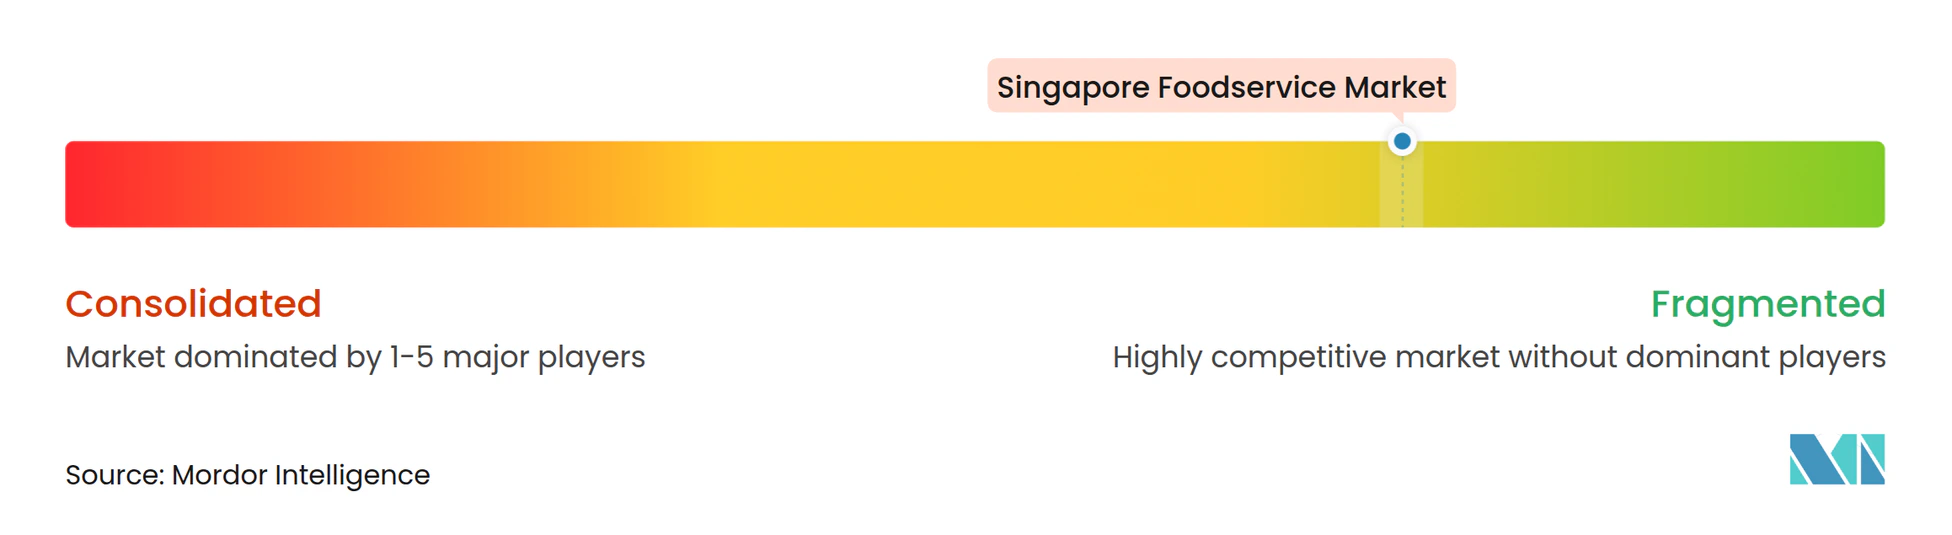
Competition combines a fragmented outlet base with branded restaurant groups and delivery platforms that organize access to customers in different ways. BreadTalk Group Pte Ltd operates bakeries, restaurants, and food atria, while Grab Holdings Limited provides platform access through GrabFood. Hanbaobao Pte Ltd (McDonald’s) and QSR Brands (M) Holdings Bhd (KFC) participate in branded quick-service competition, while Starbucks Corporation participates through its brand and a licensed operating business. McDonald’s had 8 restaurants in CapitaLand retail malls in June 2025, illustrating one chain's access to established shopping locations. The structural distinction is between operating meal formats and mediating customer access, with each route creating a different basis for competing with individual outlets.
KFC's Kallang outlet had reopened with 216 seats, up from 130, by November 24, 2025, showing how an existing address can accommodate a larger seated offer. Starbucks Singapore opened a 2-story coffeehouse in a Chinatown heritage shophouse on Smith Street on April 7, 2025, with its first dedicated retail area in Singapore. Together, these examples put part of competition into the venue itself, giving operators ways to develop an occasion through seating capacity and the use of space. Challengers can compete through a reason to visit grounded in the premises, such as added seating or a retail corner, that menu comparisons alone cannot supply.
Changes in the ownership of licensed operating businesses could alter the organization of a coffee chain without changing its brand owner. On September 30, 2026, DFI Retail Group Holdings Limited agreed to assume Maxim's interest in the licensed Starbucks business across 7 Asian markets, including Singapore. Completion was expected by the end of March 2027, subject to third-party consents, antitrust clearance, and internal separation of the licensed business. Those conditions put regulatory clearance and the separation of the licensed business ahead of any change in how Singapore outlets operate. Until completion, the licensed business stays with its existing operator, so Starbucks outlets continue to compete under the current structure.
Singapore Foodservice Industry Leaders
-
BreadTalk Group Pte Ltd
-
Grab Holdings Limited
-
Hanbaobao Pte Ltd (McDonald’s)
-
QSR Brands (M) Holdings Bhd (KFC)
-
Starbucks Corporation
- *Disclaimer: Major Players sorted in no particular order
Singapore Foodservice Market Companies Covered in this Report
- BreadTalk Group Pte Ltd
- Crystal Jade Culinary Concepts Holding
- DFI Retail Group Holdings Limited
- Doctor’s Associates LLC (Subway)
- Fidelis Express Holdings Pte. Ltd. (Pizza Express)
- Foodpanda (Delivery Hero SE)
- Grab Holdings Limited
- Hanbaobao Pte Ltd (McDonald’s)
- Jollibee Foods Corporation
- Nando’s Chickenland Singapore Pte Ltd
- Paradise Group Holdings Pte Ltd
- QSR Brands (M) Holdings Bhd (KFC)
- Restaurant Brands International Inc.
- Sakae Holdings Ltd
- No Signboard Holdings Ltd
- Starbucks Corporation
- Paradise Group
- Tung Lok Restaurants (2000) Ltd
- FairPrice Group (Kopitiam)
- 4Fingers Singapore Pte Ltd
Recent Industry Developments in Singapore Foodservice Market
- Sep 2026: DFI Retail Group Holdings Limited agreed on September 30 to assume Maxim's interest in the licensed Starbucks business across 7 Asian markets, including Singapore. Completion was expected by the end of March 2027, subject to third-party consents, antitrust clearance, and internal separation of the licensed business.
- Sep 2026: Luckin Coffee opened its 100th Singapore store on September 28, expanding its local coffee-service network.
- Jul 2026: Chick-fil-A announced its second Singapore restaurant at Millenia Walk under local Owner-Operator Deborah Ku, with an opening scheduled for July 30, 2026.
Scope and Methodology
Segmentation Overview
| Dine-In |
| Takeaway |
| Delivery |
| Cafes and Bars | By Cuisine | Bars and Pubs |
| Cafes | ||
| Juice/Smoothie/Desserts Bars | ||
| Specialist Coffee and Tea Shops | ||
| Cloud Kitchen | ||
| Full Service Restaurants | By Cuisine | Asian |
| European | ||
| Latin American | ||
| Middle Eastern | ||
| North American | ||
| Other Full Service Restaurants Cuisines | ||
| Quick Service Restaurants | By Cuisine | Bakeries |
| Burger | ||
| Ice Cream | ||
| Meat-based Cuisines | ||
| Pizza | ||
| Other Quick Service Restaurants Cuisines |
| Chained Outlet |
| Independent Outlet |
| Leisure |
| Lodging |
| Retail |
| Standalone |
| Travel |
| By Service Type | Dine-In | ||
| Takeaway | |||
| Delivery | |||
| By Foodservice Type | Cafes and Bars | By Cuisine | Bars and Pubs |
| Cafes | |||
| Juice/Smoothie/Desserts Bars | |||
| Specialist Coffee and Tea Shops | |||
| Cloud Kitchen | |||
| Full Service Restaurants | By Cuisine | Asian | |
| European | |||
| Latin American | |||
| Middle Eastern | |||
| North American | |||
| Other Full Service Restaurants Cuisines | |||
| Quick Service Restaurants | By Cuisine | Bakeries | |
| Burger | |||
| Ice Cream | |||
| Meat-based Cuisines | |||
| Pizza | |||
| Other Quick Service Restaurants Cuisines | |||
| By Outlet | Chained Outlet | ||
| Independent Outlet | |||
| By Location | Leisure | ||
| Lodging | |||
| Retail | |||
| Standalone | |||
| Travel | |||
Market Definition
- FULL-SERVICE RESTAURANTS - A foodservice establishment where customers are seated at a table, give their order to a server and are served food at a table.
- QUICK SERVICE RESTAURANTS - A foodservice establishment that provides customers convenience, speed, and food offerings at lower prices. Customers usually help themselves and carry their own food to their tables.
- CAFES & BARS - A type of foodservice business that include bars and pubs that are licensed to serve alcoholic drinks for consumption, cafes that serve refreshments and light food items, as well as specialty tea and coffee shops, dessert bars, smoothie bars, and juice bars.
- CLOUD KITCHEN - A foodservice business that utilizes a commercial kitchen for the purpose of preparing food for delivery or takeout only, with no dine-in customers.
| Keyword | Definition |
|---|---|
| Albacore Tuna | It is one of the smallest species of tuna found in the six distinct stocks known globally in the Atlantic, Pacific, and Indian oceans, as well as the Mediterranean Sea. |
| Angus beef | It is beef derived from a specific breed of cattle indigenous to Scotland. It requires certification from the American Angus Association to receive the "Certified Angus Beef" quality mark. |
| Asian cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Chinese, Indian, Korean, Japanese, Bengali, Southeast Asian, etc. |
| Average Order Value | It is the average value of all orders made by the customers at a foodservice establishment. |
| Bacon | It is salted or smoked meat that comes from the back or sides of a pig. |
| Bars & Pubs | It is a drinking establishment that is licensed to serve alcoholic drinks for consumption on the premises. |
| Black Angus | It is beef derived from a black-hided breed of cows that don't have horns. |
| BRC | British Retail Consortium |
| Burger | It is a sandwich consisting of one or more cooked beef patties, placed inside a sliced bread roll or bun roll. |
| Café | It is a foodservice establishment serving various refreshments (mainly coffee) and light meals. |
| Cafes & Bars | It is a type of foodservice business that include bars and pubs that are licensed to serve alcoholic drinks for consumption, cafes that serve refreshments and light food items, as well as specialty tea and coffee shops, dessert bars, smoothie bars, and juice bars. |
| Cappuccino | It is an Italian coffee drink that is traditionally prepared with equal parts double espresso, steamed milk, and steamed milk foam. |
| CFIA | Canadian Food Inspection Agency |
| Chained Outlet | It refers to a foodservice establishment that shares brands, operates in several locations, has central management, and standardized business practices. |
| Chicken Tender | It refers to chicken meat prepared from the pectoralis minor muscles of a chicken bird. |
| Cloud Kitchen | It is a foodservice business that utilizes a commercial kitchen for the purpose of preparing food for delivery or takeout only, with no dine-in customers. |
| Cocktail | It is an alcoholic mixed drink made with either a single spirit or a combination of spirits, mixed with other ingredients such as juices, flavored syrups, tonic water, shrubs, and bitters. |
| Edamame | It is a Japanese dish prepared with soybeans (harvested before they ripen or harden) and cooked in its pod. |
| EFSA | European Food Safety Authority |
| ERS | Economic Research Service of the USDA |
| Espresso | It is a concentrated form of coffee, served in shots. |
| European cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Italian, French, German, English, Dutch, Danish, etc. |
| FDA | Food and Drug Administration |
| Fillet Mignon | It is a cut of meat taken from the smaller end of the tenderloin. |
| Flank Steak | It is a cut of beef steak taken from the flank, which lies forward of the rear quarter of a cow. |
| Foodservice | It refers to the part of the food industry which includes businesses, institutions, and companies which prepare meals outside the home. It includes restaurants, school and hospital cafeterias, catering operations, and many other formats. |
| Franks | Also known as frankfurter or Würstchen, it is a type of highly seasoned smoked sausage popular in Austria and Germany. |
| FSANZ | Food Standards Australia New Zealand |
| FSIS | Food Safety and Inspection Service |
| FSSAI | Food Safety and Standards Authority of India |
| Full service restaurant | It refers to a foodservice establishment where customers are seated at a table, give their order to a server, and are served food at a table. |
| Ghost Kitchen | It refers to a cloud kitchen. |
| GLA | Gross Leasable Area |
| Gluten | It is a family of proteins found in grains, including wheat, rye, spelt, and barley. |
| Grain-fed beef | It is beef derived from cattle that have been fed a diet supplemented with soy and corn and other additives. Grain-fed cows can also be given antibiotics and growth hormones to fatten them up more quickly. |
| Grass-fed beef | It is beef derived from cattle that have only been fed grass as feed. |
| Ham | It refers to the pork meat taken from the leg of a pig. |
| HoReCa | Hotels, Restaurants and Cafes |
| Independent Outlet | It refers to a foodservice establishment that operates with a single outlet or is structured as a small chain with no more than three locations. |
| Juice | It is a drink made from the extraction or pressing of the natural liquid contained in fruit and vegetables. |
| Latin American | It includes full-service offerings in restaurants that serve cuisines from cultures such as Mexican, Brazilian, Argentinian, Colombian, etc. |
| Latte | It is a milk-based coffee that is made up of one or two shots of espresso, steamed milk, and a thin layer of frothed milk. |
| Leisure | It refers to foodservice offered as a part of a recreation business, such as sports arenas, zoos, movie theaters, and museums. |
| Lodging | It refers to foodservice offerings at hotels, motels, guesthouses, holiday homes, etc. |
| Macchiato | It is an espresso coffee drink with a small amount of milk, usually foamed. |
| Meat-based cuisines | This inlcudes food items like fried chicken, steak, ribs, etc. where meat is the primary ingredient for the dish. |
| Middle Eastern cuisine | It includes full-service offerings in restaurants that serve cuisines from cultures such as Arabic, Lebanese, Iranian, Israeli, etc. |
| Mocktail | It is an non-alcoholic mixed drink. |
| Mortadella | It is a large Italian sausage or luncheon meat made of finely hashed or ground heat-cured pork, which incorporates at least 15% small cubes of pork fat. |
| North American | It includes full-service offerings in restaurants that serve cuisines from cultures such as American, Canadian, Caribbean, etc. |
| Pastrami | It refers to a highly seasoned smoked beef, typically served in thin slices. |
| PDO | Protected Designation of Origin: It is the name of a geographical region or specific area that is recognized by official rules to produce certain foods with special characteristics related to location. |
| Pepperoni | It is an American variety of spicy salami made from cured meat. |
| Pizza | It is a dish made typically of flattened bread dough spread with a savory mixture usually including tomatoes and cheese and often other toppings and baked. |
| Primal cuts | It refers to the major sections of the carcass. |
| Quick service restaurant | It refers to a foodservice establishment that provides customers convenience, speed, and food offerings at lower prices. Customers usually help themselves and carry their own food to their tables. |
| Retail | It refers to a foodservice outlet inside a mall. shopping complex or a commercial real estate building, where there are other businesses operating as well. |
| Salami | It is a cured sausage consisting of fermented and air-dried meat. |
| Saturated fat | It is a type of fat in which the fatty acid chains have all single bonds. It is generally considered unhealthy. |
| Sausage | It is a meat product made of finely chopped and seasoned meat, which may be fresh, smoked, or pickled and which is then usually stuffed into a casing. |
| Scallop | It is an edible shellfish that is a mollusk with a ribbed shell in two parts. |
| Seitan | It is a plant-based meat substitute made out of wheat gluten. |
| Self-service kiosk | It refers to a self-order point-of-sale (POS) system through which customers place and pay for their own orders at kiosks, enabling totally contactless and frictionless service. |
| Smoothie | It is a beverage made by placing all the ingredients in a container and processing them together, without removing the pulp. |
| Specialty coffee & tea shops | It refers to a foodservice establishment that serves only various types of tea or coffee. |
| Standalone | It refers to a restaurants that have an independent infrastructure setup and not connected to any other business. |
| Sushi | It is a Japanese dish of prepared vinegared rice, usually with some sugar and salt, accompanied by a variety of ingredients, such as seafood—often raw—and vegetables. |
| Travel | It refers to foodservice offerings such as airplane food, dining on long-distance trains, and foodservice on cruise ships. |
| Virtual Kitchen | It refers to a cloud kitchen. |
| Wagyu Beef | It is beef derived from any of four strains of a breed of black or red Japanese cattle that are valued for their highly marbled meat. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: Identify Key Variables: In order to build a robust forecasting methodology, the variables and factors identified in Step 1 are tested against available historical market numbers. Through an iterative process, the variables required for the market forecast are set, and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market size estimations for the forecast years are in nominal terms. Inflation is considered for average order value, and it is forecasted as per predicted inflation rates in the countries.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


