
Search Engine Optimization (SEO) Services Market Size and Share
Search Engine Optimization (SEO) Services Market Analysis by Mordor Intelligence
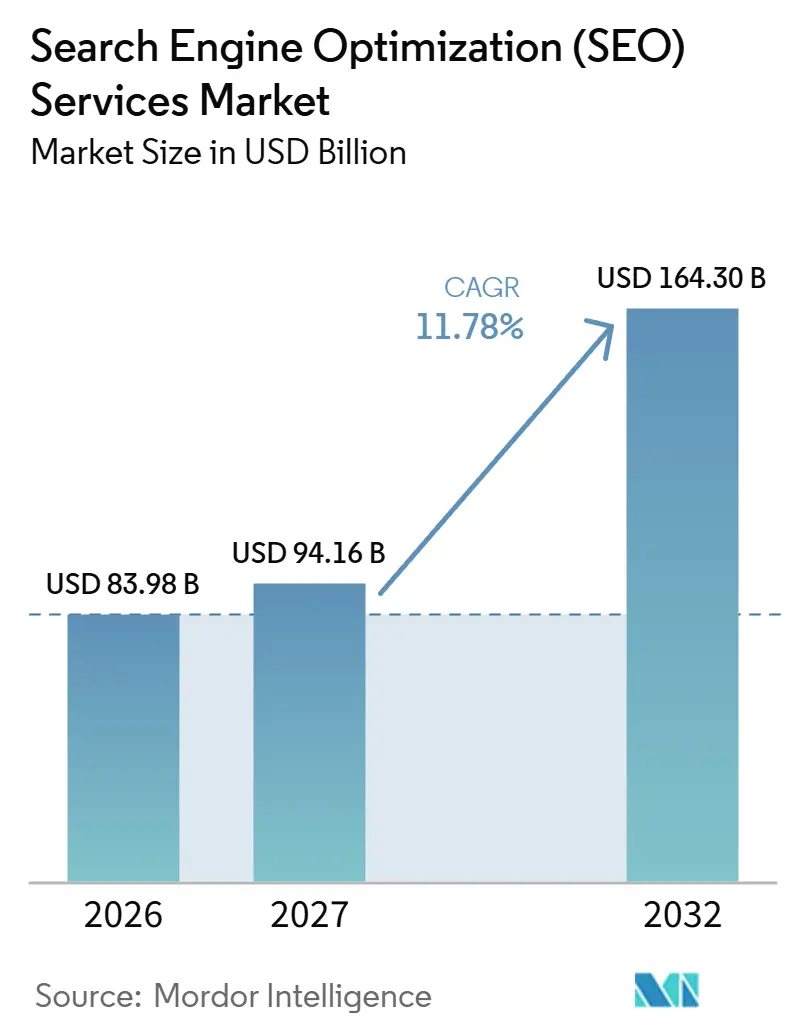
The search engine optimization (SEO) services market size was valued at USD 83.98 billion in 2026 and estimated to grow from USD 94.16 billion in 2027 to reach USD 164.3 billion by 2032, at a CAGR of 11.78% during the forecast period (2027-2032).
Online commerce in China and content-led acquisition increase the value of searchable product and service information. Mobile content parity and AI search visibility turn that demand into a mix of technical and analytical tasks. Competition brings focused search diagnostics alongside broader platform capabilities, giving buyers different ways to connect optimization with content delivery. Those choices are complicated by privacy duties and pressure on publisher click-through, which make clear measurement and delivery boundaries more valuable. Retailers can consequently prioritize technical and content work around the product information their buyers need to discover.
Key Report Takeaways
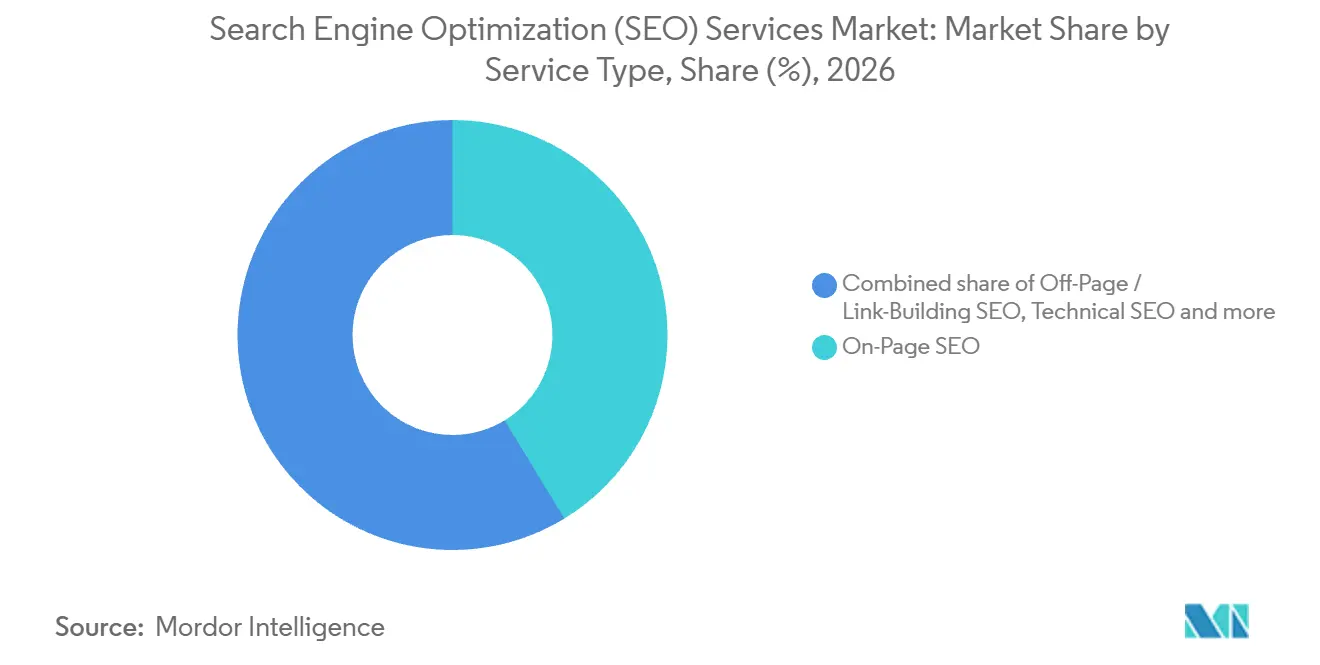
- By service type, on-page SEO led with a 41.28% search engine optimization (SEO) services market share in 2026, while voice and visual search SEO is forecast to grow fastest at a 19.7% CAGR during 2027-2032.
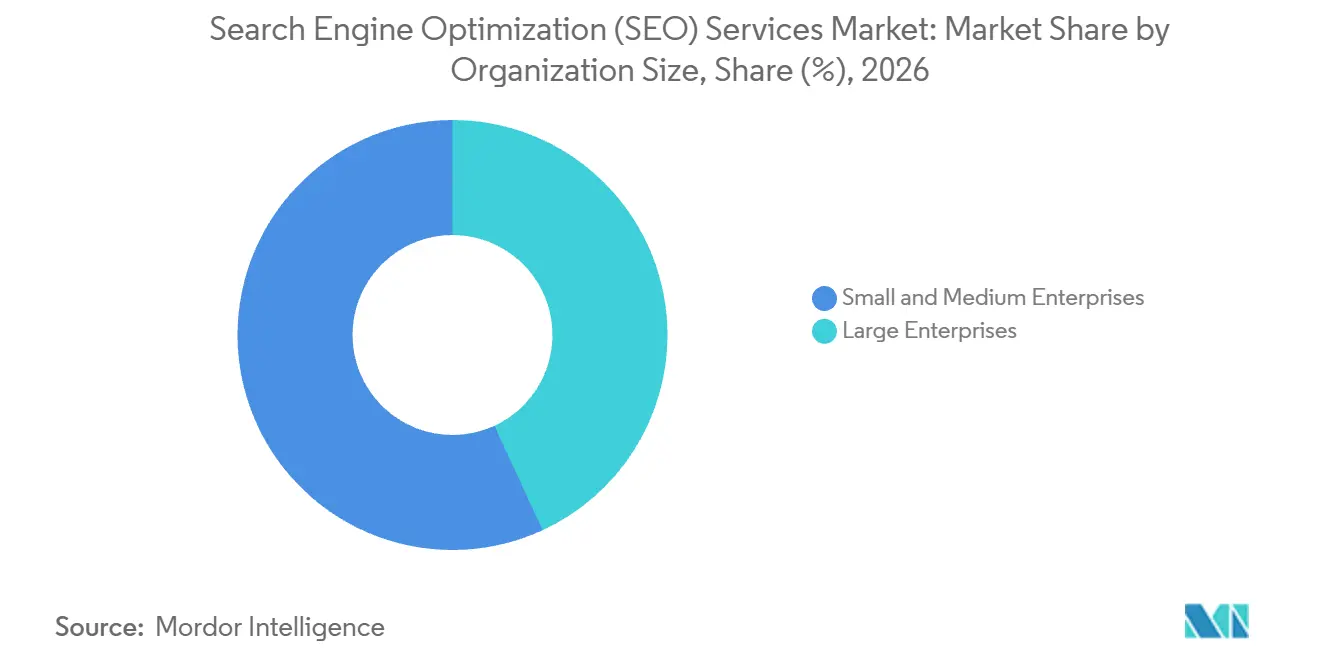
- Across organization sizes, small and medium enterprises led with a 56.88% share of the search engine optimization (SEO) services market size in 2026, whereas large enterprises are forecast to grow fastest at a 15.8% CAGR during 2027-2032.
- End-user industries were led by e-commerce and retail, with a 26.44% market share in 2026, while healthcare and life-sciences is forecast to grow fastest at a 17% CAGR during 2027-2032.
- By service model, subscription and retainer services led with a 61.46% market share in 2026, and performance / outcome-based services are forecast to record the fastest CAGR of 18% during 2027-2032.
- Among access channels, voice search is forecast to grow fastest at a 22.2% CAGR during 2027-2032, while mobile search held the largest market share at 59.74% in 2026.
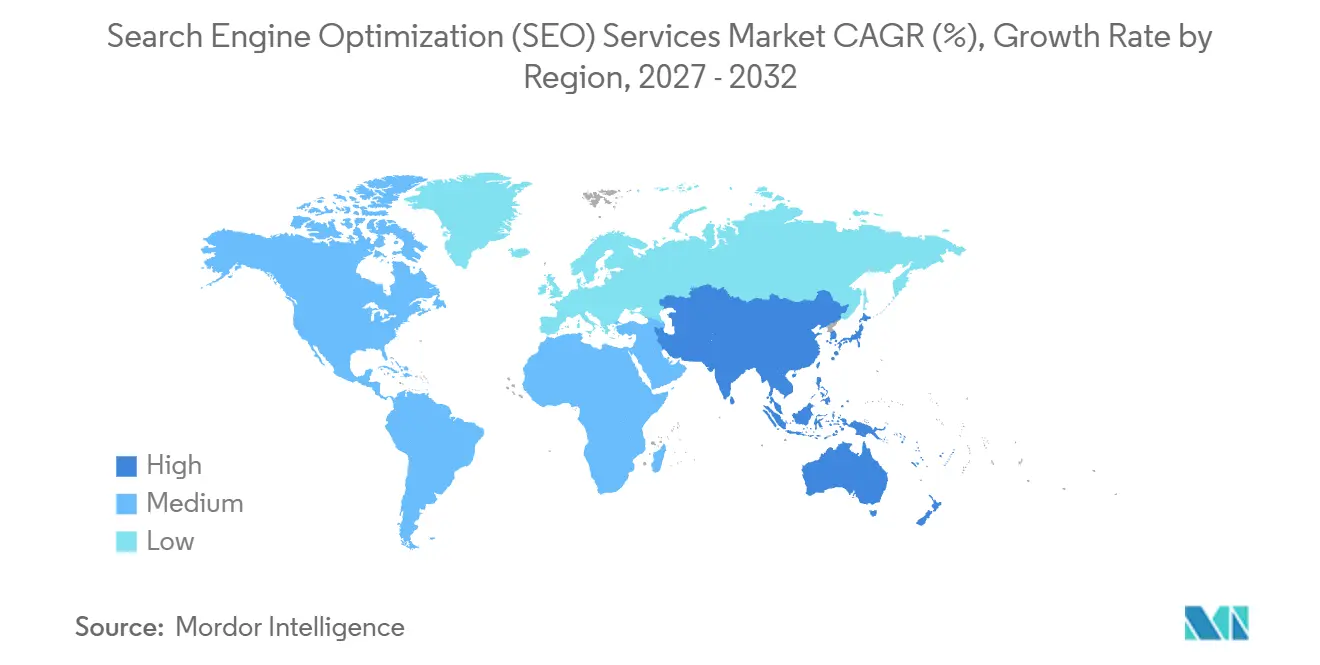
- Geographically, North America had the largest share at 33.68% in 2026, and Asia-Pacific is forecast to record the fastest CAGR of 13.3% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Search Engine Optimization (SEO) Services Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising global e-commerce and digital-ad spend | +4.8% | United States and China | Short term (≤ 2 years) |
| Growing mobile internet and smartphone use | +3.5% | North America, Europe and Asia-Pacific | Medium term (2-4 years) |
| Content-led inbound marketing adoption | +2.6% | The North American region | Medium term (2-4 years) |
| AI-driven algorithm updates raising complexity | +2.4% | North America, Europe and Asia-Pacific | Short term (≤ 2 years) |
| Surge in voice and visual search (schema-first SEO) | +1.2% | North America, Europe and Asia-Pacific | Medium term (2-4 years) |
| Third-party cookie restrictions prompting plans for higher SEO budgets | +0.3% | North America and Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising global e-commerce and digital-ad spend
Expanding online commerce increases the commercial value of making selling content discoverable before a customer reaches checkout. Across its 56-market series, Dentsu Group reported that global advertising spend grew 5.8% in 2025, mainly through digital advertising, and exceeded USD 1 trillion. China's nominal online retail sales of goods and services rose 4.4% year over year in January-September 2026 on a comparable platform basis.[1] These forces give retailers a reason to connect their promotional investment with discoverable product and service information. Because digital advertising drove the reported spending increase, agencies can offer organic page optimization alongside campaign work, creating a distinct service opportunity around the product information that retailers promote.
Growing mobile internet and smartphone use
The mobile opportunity extends from audience reach to the content that determines search visibility. By the end of 2025, 4.8 billion people used mobile internet, equal to 59% of the global population. Google uses mobile content crawled with its smartphone agent for indexing and ranking most sites. Its guidance calls for equivalent primary content, titles and meta descriptions across mobile and desktop versions. A reduced mobile page can therefore weaken the information available for indexing even when its desktop counterpart is complete. A parity audit thus targets the version Google actually evaluates, making mobile-content completeness a defined SEO service deliverable for businesses addressing that audience.
Content-led inbound marketing adoption
Content-led acquisition creates an SEO use case that extends beyond increasing page readership. In a 2025 survey of 1,015 B2B marketers, mostly from North America, 97% said their organizations had a content strategy. In the same survey, 68% of the B2B marketers cited gated assets, webinars or interactive tools for content-driven first-party data collection. These programs give search work a potential role in connecting a relevant audience with a specific content offer. Traffic alone would not capture that objective for respondents using content to collect their own audience data. For these B2B programs, SEO work becomes more commercially relevant when it connects an audience's query to the offer supporting that collection step.
AI-driven algorithm updates raising complexity
AI-generated search results broaden the monitoring task beyond a single conventional ranking. In May 2026, Google reported that AI Mode had surpassed 1 billion monthly active users globally. By August 31, 2026, Google had rolled out Search Console insights for impressions in generative AI features in Search and Discover to websites worldwide. For service providers, interpreting visibility within those distinct search experiences adds a separate layer of analysis. Buyers can therefore assess an SEO engagement partly on its ability to explain where their information appears across AI features. AI exposure can thus be reported separately from recommended content changes, distinguishing a measured impression from the agency's proposed response.
Restraints Impact Analysis of Search Engine Optimization (SEO) Services Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Frequent search-algorithm volatility | -1.4% | North America, Europe and Asia-Pacific | Short term (≤ 2 years) |
| Stricter data-privacy regulations (GDPR/CCPA etc.) | -0.8% | Country of France | Medium term (2-4 years) |
| Generative-AI answer engines cutting SERP clicks | -0.7% | The United States | Short term (≤ 2 years) |
| Marketplace ecosystems fragmenting search traffic | -0.4% | Country of Japan | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Frequent search-algorithm volatility
Uncertain timing makes a completed SEO task different from a demonstrated search result. Google says some improvements can affect Search results in a few days, while others may take several months. If no effect appears after a few months, a site may need to wait for the next core update. For an agency quoting a fixed brief, that interval can create a mismatch between completed implementation and the review effort needed to interpret results. A monitoring allowance can absorb some variability, but it cannot control the timing of any effect in Search results. The residual burden is a potentially longer evaluation period before a client can assess the effect of the commissioned search work.
Stricter data-privacy regulations (GDPR/CCPA etc.)
SEO engagements built around consent-exempt audience measurement face limits on how visitor data can be reused. In France, the data-protection authority Commission nationale de l'informatique et des libertés (CNIL) limits qualifying trackers under its Article 82 guidance to the publisher's own audience measurement and the production of anonymous statistics.[2] Those trackers must avoid cross-processing, transfers of non-anonymous data to third parties, and tracking across sites or apps. These conditions make measurement configuration and data sharing part of the agreed SEO delivery scope. An agency and its client must therefore keep an exemption-based approach consistent with those limits as reporting needs change. The remaining cost is the effort of defining and maintaining that constrained measurement scope alongside the search work.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Search Engine Optimization (SEO) Services Market Segment Analysis
By Service Type:
On-Page Execution Meets Visual Product DiscoveryOn-page SEO accounted for a 41.28% share of the search engine optimization (SEO) services market size in 2026. In a 2026 survey of 204 SEO practitioners, 117, or 57%, used AI to optimize existing content structure, headings and answer blocks. The multiple-choice survey included agency-side specialists, who accounted for 59% of respondents, while 17% worked in-house. That activity centers on revising the organization of information already available online. Because the 57% figure describes AI applied to pages that already exist, on-page work remains the layer where an agency can show a client what changed in headings, structure and answer blocks.
Voice and visual search SEO is the fastest-growing segment, with a forecast CAGR of 19.7% during 2027-2032. Google's April 2025 internal data reported more than 25 billion Lens queries per month and commercial intent in 1 in 5 Lens searches. Google's visual tools allow shoppers to begin with product photos or packaging when seeking information and comparisons. Optimization can connect the image a shopper recognizes with the product information available from that starting point. For commercially motivated Lens searches, a useful image-to-product match carries the opportunity beyond visual exposure into product comparison.

By Organization Size:
SME Funding Limits Contrast with Enterprise CoordinationSmall and medium enterprises represented a 56.88% search engine optimization (SEO) services market share in 2026. LocalImpact's September 2025 survey of 400 U.S. small-business owners and managers found that 10% said SEO received the largest share of their marketing budget. In SEO Caddy's 2025 survey of 439 UK SMEs, 67% identified budget constraints as their primary obstacle to SEO success. For agencies serving SMEs, the UK sample's budget obstacle and the U.S. finding that only 10% gave SEO the largest budget share favor scopes sized to limited budgets. Staged delivery gives a cost-constrained SME a defined group of optimization tasks to commission before funding a wider program.
Large enterprises are the fastest-growing segment, with a forecast CAGR of 15.8% during 2027-2032. In an August 2025 announcement, DAC said multinational retailer Kingfisher PLC appointed it to deliver local SEO and online reputation management for its largest retail brands in the UK and Ireland. For a multinational buyer, combining local SEO and reputation work across brands and countries creates coordination tasks alongside individual optimization assignments. The service proposition can therefore center on managing a retail portfolio's local presence within a coordinated program that preserves each brand's search requirements.
By End-User Industry:
Retail Priorities and Healthcare Communication Shape DemandE-commerce and retail accounted for 26.44% of the market in 2026, making it the largest segment. In a 2026 survey by Fachhochschule Nordwestschweiz (FHNW), 88% of 473 participating online retailers rated SEO relevant or rather relevant, and 403 were based in Switzerland. U.S. retail e-commerce sales were estimated at USD 340.2 billion in Q2 2026, seasonally adjusted but not adjusted for price changes. Retail engagements can address a buyer group that ranks SEO as its most relevant marketing instrument in the Swiss-dominated survey, while U.S. online sales volume shows a separate transaction base that search visibility can serve.
Healthcare and life-sciences is the fastest-growing segment, with a forecast CAGR of 17% during 2027-2032. In December 2025, Moorfields Eye Hospital NHS Foundation Trust awarded All Response Media Limited a media-services contract covering paid digital and offline campaigns and organic-search optimization for prospective patients and referrers. The award provided for an estimated January 19, 2026 to January 18, 2029 term, with 2 optional 12-month extensions. This supports a longer service brief in which organic discovery is coordinated with other channels while serving both patient and referrer audiences.
By Service Model:
Retainer Breadth Meets Performance CommitmentsSubscription and retainer services were the largest segment, with a 61.46% share of the market in 2026. In Neil Patel's 2025 survey of 500 U.S. full-time professionals knowledgeable about their businesses' SEO spending, monthly retainers were the most common payment method across all spending bands. That breadth shows recurring pricing was not confined to one expenditure tier in the sample, leaving room for differently sized engagements. Retainers can therefore provide a common commercial structure while workload, delivery coverage and service boundaries vary for individual clients.
Performance / outcome-based services are the fastest-growing segment, with a forecast CAGR of 18% during 2027-2032. For new or renewed agreements starting on or after January 1, 2025, 10X Digital's performance commitment covers mutually agreed keyword milestones. It targets page 1 rankings for 10% of those keywords within 4 months, 30% within 8 months and 60% within 12 months. Missing a milestone cuts that month's total SEO invoice by 50%, with full billing restored when the commitment is met. This performance commitment reallocates part of the monthly fee risk around agreed milestones without guaranteeing specific rankings.
By Access Channel:
Mobile Visibility Requires Geographic ContextMobile search was the largest segment, accounting for 59.74% of the market in 2026. Yext reported 48.7% more geographic variation in Google mobile organic results across nearby locations after mid-May 2026, using matched variation scores. Its analysis covered about 8.16 million valid location-specific organic search-result snapshots from January 1 through August 9, 2026. That variation makes an observation's location relevant to interpreting mobile visibility and limits what a single ranking snapshot can show. Agencies need observations across the client's relevant locations before treating one mobile ranking as representative of the wider service area.
Voice search is the fastest-growing segment, with a forecast CAGR of 22.2% during 2027-2032. In GatherUp's August 2025 survey of more than 1,000 U.S. consumers aged 18 to 60+, 11% reported starting local-business discovery with voice search. For a local-service buyer, the finding places voice optimization at the first stage of the consumer's search for a nearby business. Visibility at that entry point can put a provider into initial consideration, giving local SEO a role before subsequent contact or selection.
Geography Analysis
North America Search Engine Optimization (SEO) Services Market
North America accounted for 33.68% of the search engine optimization (SEO) services market size in 2026. The U.S. Department of Health and Human Services awarded Fors Marsh Group LLC an SEO-inclusive delivery order on September 18, 2026. Funded by the National Institute of Nursing Research, the order covers the institute's website maintenance, development and enhancement, search engine optimization, web security and other compliance work, with performance in Bethesda, Maryland from September 18, 2026 to September 17, 2027. For providers, combining discoverability with these technical obligations creates a route into broader public-sector website engagements where search work is part of the same award.
Asia-Pacific Search Engine Optimization (SEO) Services Market
Asia-Pacific is the fastest-growing region, with a forecast CAGR of 13.3% during 2027-2032. In Thailand, Charoen Pokphand Foods awarded InetAsia Solutions a 3-year SEO and digital consulting contract on April 5, 2025. The agreed scope combined full-spectrum SEO, analytics, performance consulting and integration across the buyer's digital ecosystem, including strategic support for Amplitude and Campaign Sherpa. InetAsia Thailand delivered a second SEO training session to the buyer's marketing team on November 24, 2025, covering advanced on-page work, keyword strategy, content optimization and tailored practical applications. Providers can package capability transfer for a buyer's own team alongside multi-year SEO consulting and integration, as this Thai buyer's contract scope and delivered training illustrate.
South America's delivery conditions include Brazil's international personal-data transfer framework, which provides routes based on adequacy recognition and qualifying controller guarantees. Europe's consumer channel base is illustrated by the EU, where 78% of internet users aged 16 to 74 bought or ordered goods or services online for private use in 2025. In the Middle East, Saudi Arabia's Personal Data Protection Law (PDPL) covers personal-data processing in the Kingdom and residents' data processed abroad, with an exception for an individual's unshared personal or family use. In Africa, Google observed search interest in “Louis Vuitton bags” rising 60% in Nigeria and “collagen induction therapy” rising 4.5 times in South Africa in the recent months preceding its July 2025 report. For cross-border agencies, Brazilian transfer requirements and Saudi data relationships shape delivery obligations, while European buying patterns and distinct Nigerian and South African queries guide the content needing visibility.
Regulatory Framework and Outlook
The table compares selected jurisdictions from the perspective of an SEO agency handling covered clients' website-visitor personal data. Ratings reflect the practical conditions for organizing that work and the near-term direction of relevant duties. On October 6, 2026, the Saudi Data and Artificial Intelligence Authority (SDAIA) opened a consultation proposing that controllers store personal data in the Kingdom, with comments closing November 5. If adopted, the amendments would take effect 60 days after Official Gazette publication, while transfers would remain possible under the PDPL and implementing rules.
Regulatory Table of Search Engine Optimization (SEO) Services Market
| Decision factor | United States | Germany | China | Brazil | Saudi Arabia | South Africa |
|---|---|---|---|---|---|---|
| Primary authority | California Privacy Protection Agency, for California | State data-protection authorities, generally for private companies, subject to exceptions | Cyberspace Administration of China for coordination; competent departments for supervision | ANPD | SDAIA | Information Regulator |
| Key instruments or direction | California CCPA service-provider rules, effective January 1, 2026 | TDDDG §25; GDPR information and valid-consent duties | Personal Information Protection Law, Articles 6 and 13 | LGPD, Articles 39 and 46 | PDPL controller privacy and security duties | POPIA, section 21 |
| Commercial effect | Specified-purpose, necessary and proportionate processing; contracts prohibit sale or sharing of contract-collected personal information | Consent for device access unless solely for transmitting a message over a public telecommunications network or strictly necessary for an expressly requested service | Lawful basis, clear and reasonable purpose, and personal-information collection limited to what is necessary | Operators follow controller instructions; controllers verify compliance; processing agents maintain technical and administrative security | Controllers vet and monitor processors, provide privacy policies to data subjects before collection and maintain safeguards | Responsible-party/operator security contracts; operators notify the responsible party immediately on reasonable grounds of unauthorized access or acquisition |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | Hardening | No change |
| Source: Mordor Intelligence | ||||||
California's purpose-bound contracts and Brazil's controller-directed processing support workable delivery with compliance overhead, while their preliminary rulemaking and September 2026 internal rights drafting, respectively, support near-term continuity. Germany's August 2026 supervisory proposal, which drew government legal concerns, and South Africa's 2026/27 amendment-submission plan leave existing consent and operator-security duties as the near-term planning basis. China's optional outbound-transfer certification route became operative January 1, 2026, requiring eligible non-critical-information-infrastructure operators meeting transfer-volume conditions to notify individuals, obtain separate consent and conduct an impact assessment before applying, so covered agencies retain ordinary lawful-basis and purpose duties while eligible agency or client applicants have a defined transfer checklist. Saudi Arabia's controller-vetting duties allow structured outsourcing, while the proposed storage amendment supports the hardening direction because it would add an implementation condition for covered controllers.
Value Chain Stages
The value chain compares diagnosis, technical repair, content delivery, off-site work and ongoing reporting. Ignite Visibility LLC examines site architecture, Core Web Vitals and crawling efficiency for AI bots in its SEO audits. WebFX Inc. and Wpromote Inc. provide technical, content and on-page services that connect assessment with implementation. These linked tasks support earnings across implementation and continuing support, illustrated by WebFX's monthly managed SEO offering.
Value Chain Analysis Table of Search Engine Optimization (SEO) Services Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Technical assessment | SEO audit agencies such as Ignite Visibility LLC and Wpromote Inc. | Assessment service fees | Competing architecture and performance repair priorities | Rank findings by affected pages and technical dependencies |
| Technical remediation | Technical SEO providers such as WebFX Inc., Wpromote Inc. and Dentsu MENA | Implementation and maintenance fees | Eligibility does not guarantee Google indexing | Validate eligibility and track indexing separately |
| Content planning and delivery | Content strategy agencies such as WebFX Inc., Wpromote Inc. and Dentsu MENA | Content planning and optimization fees | Translating keyword and intent analysis into specific page work | Assign priority topics to defined content tasks |
| Off-site optimization | Off-page SEO providers such as WebFX Inc. and Dentsu MENA | Off-page optimization fees | Incomplete control over external references | Prioritize verifiable reference repairs and review referral quality |
| Ongoing reporting | SEO reporting providers such as WebFX Inc. | Recurring monitoring and reporting fees | Connecting findings with the next delivery scope | Attach a prioritized work plan to each reporting cycle |
| Source: Mordor Intelligence | ||||
For Google Search, eligibility requires unblocked Googlebot access, an HTTP 200 response and indexable content, but meeting these conditions does not guarantee indexing.[3] That boundary makes documented corrective work and the engine's subsequent decision distinct measures of delivery. An agency can charge for diagnostic, implementation and monitoring work while treating Google indexing as an outcome outside its control.
Competitive Landscape
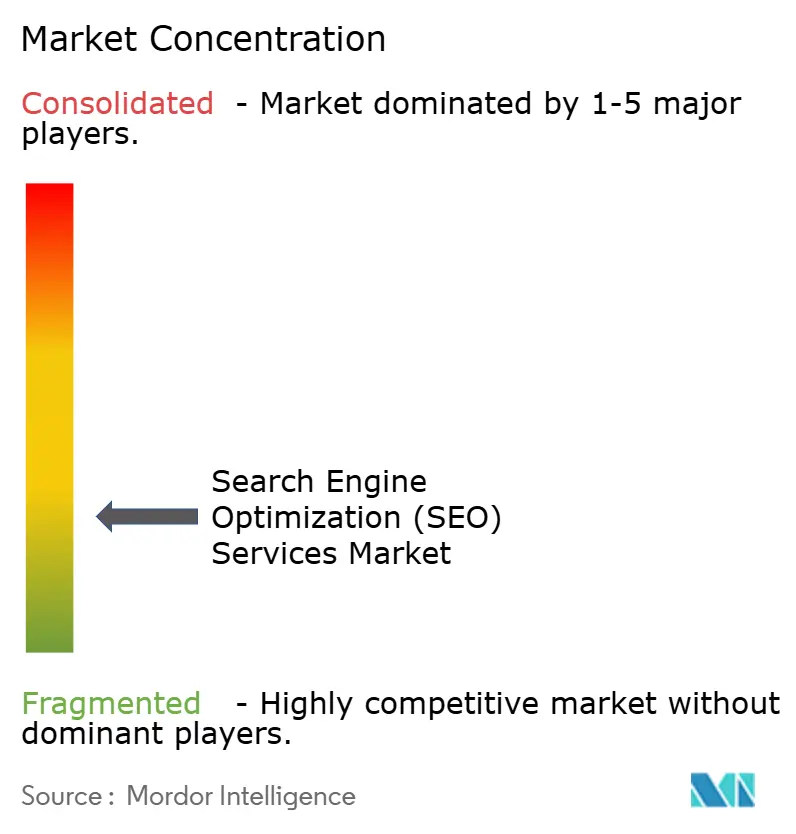
The fragmented SEO services landscape combines agencies and consultants with tool suppliers, with Ahrefs Pte Ltd, iCONQUER Ltd, Mangools s.r.o., Adobe through Semrush Holdings Inc., and Surfer Sp. z o.o. among the leading participants. Ahrefs supplies software for keyword research, link building, technical SEO, local SEO and enterprise SEO. iCONQUER provides SEO focused on Google organic rankings and ranking recovery alongside PPC management and web design, while Mangools sells keyword research, local search-result analysis, rank tracking, backlink analysis and website metrics tools. Adobe completed its Semrush acquisition on April 28, 2026, with the acquired business offering SEO, agentic search optimization, content marketing, paid media and social-strategy capabilities. Surfer provides content creation, AI visibility monitoring and SEO audit software, capabilities that agencies can use to deliver and report search work.
On September 24, 2026, Ahrefs doubled the API units included with Lite+ plans at no extra cost. For agencies using those plans, the larger data-retrieval allowance expands the work the same data-access payment can support. The announcement also made additional custom endpoints available to enterprise users, a separate option for agencies requiring tailored access to the platform's data in their daily workflows. Ahrefs framed the change as giving users more data for daily workflows, so agencies on Lite+ plans receive added retrieval capacity and tailored access has a defined enterprise route.
Surfer introduced AI Tracker on June 18, 2025, describing it as the only data-backed tool tracking AI mentions of brands, products or topics. Surfer also offers agencies separate client brand spaces and one-click reports with custom branding for their SEO and AI search work. Under agreements incorporating Semrush's July 2025 Data Processing Addendum, Semrush Inc. or the contracting affiliate acts as processor of customer personal data subject to applicable data-protection law. The customer determining the purposes and means of that processing acts as controller. An agency can package branded visibility reporting as a client deliverable while separately identifying its responsibilities for covered personal-data processing when the Semrush addendum applies.
Search Engine Optimization (SEO) Services Industry Leaders
-
Ahrefs Pte Ltd
-
iCONQUER Ltd
-
Mangools s.r.o.
-
Semrush Holdings Inc.
-
Surfer Sp. z o.o.
- *Disclaimer: Major Players sorted in no particular order
Search Engine Optimization (SEO) Services Market Companies Covered in this Report
- Semrush Holdings Inc.
- Ahrefs Pte Ltd
- SEO Moz Inc
- Screaming Frog Ltd
- Yoast BV
- Surfer Sp. z o.o.
- Webflow Inc.
- BrightEdge Technologies Inc.
- Conductor LLC
- SpyFu Inc.
- WebFX Inc.
- Ignite Visibility LLC
- iCONQUER Ltd
- Mangools s.r.o.
- Loopex Digital
- Netpeak Group
- Wpromote Inc.
- Single Grain LLC
- Deloitte Digital
- Accenture Song
- Dentsu International
- Omnicom (Resolution Media)
Read Analysis of Search Engine Optimization (SEO) Services Companies
Key Opportunities for Market Participants
These opportunities compare retail search-readiness services with an open route into public-service SEO procurement. In FHNW's 2026 survey, which primarily covered Swiss online retailers, 51% rated generative engine optimization (GEO) relevant or rather relevant. Personnel and know-how were a major or moderate challenge for 67% of participating retailers. This combination supports offers that supply a defined capability without requiring the buyer to build an entire specialist team.
Market Opportunities Table of Search Engine Optimization (SEO) Services Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| AI-search visibility diagnosis | Retailer interest in generative search in the 2026 FHNW survey | Online retailers, particularly in Switzerland | Establish a baseline and translate findings into a prioritized content brief | Limited personnel and know-how | Search visibility tool suppliers such as Ahrefs Pte Ltd, whose Brand Radar tracks ChatGPT and Perplexity mentions |
| Structured product-data discoverability | In the primarily Swiss 2026 survey, early-stage agentic commerce was not offered by 76% of participating retailers and many lacked interfaces and structured product data | Online retailers with product-data gaps | Deliver technical SEO and product-data remediation with clear acceptance criteria | Technical interfaces and organizational readiness | Technical SEO service providers |
| Public-service SEO and GEO delivery | An Post's 2026 qualification system seeks traditional and emerging search suppliers | An Post in Ireland | Qualify for advisory, optimization, technical deployment and reporting work | Uncertain flow of commissioned assignments | Qualified SEO and GEO service providers |
| Source: Mordor Intelligence | |||||
The central opening is to turn interest in AI search into a defined piece of analytical or technical work. For the surveyed retailers, personnel and know-how constraints make client-side implementation effort part of the offer's commercial design. An Post's Irish qualification route opens a different prospect for suppliers able to combine strategic advice, optimization, technical deployment and reporting for traditional SEO and GEO.
Recent Industry Developments in Search Engine Optimization (SEO) Services Market
- Oct 2026: Google announced changes to AI Mode and AI Overviews, including more prominent inline links and a planned test of a dedicated section for official websites.
- Sep 2026: Google began a global rollout of Search Console reporting for web multimodal searches, covering Lens, Circle to Search on Android, image uploads and Chrome's “Search this image” feature.
- Apr 2026: Adobe completed its acquisition of Semrush Holdings Inc., a brand visibility platform with SEO capabilities.
Search Engine Optimization (SEO) Services Market Report Scope and Research Methodology
Market Definition and Coverage
The global search engine optimization (SEO) services market measures annual client spending worldwide on fee-based services that improve a client's organic visibility on general-purpose search engines. Agencies and specialized consultants deliver this work across desktop, mobile, and voice search.
Scope exclusions: Paid search advertising, stand-alone SEO software licenses, in-house SEO labor, and standalone website design or development are excluded.
Segments Covered in This Report
- By Service Type
- On-Page SEO
- Off-Page / Link-Building SEO
- Technical SEO
- Local and Hyperlocal SEO
- E-commerce / Marketplace SEO
- Voice and Visual Search SEO
- Video and Image SEO
- By Organization Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- E-commerce and Retail
- IT and Telecom
- Hospitality and Travel
- Real Estate and Construction
- Healthcare and Life-Sciences
- BFSI
- Education
- Media and Entertainment
- Others
- By Service Model
- Subscription / Retainer
- Project-Based
- Hourly-Based
- Performance / Outcome-Based
- By Access Channel
- Desktop Search
- Mobile Search
- Voice Search
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as Google Search Central's SEO Starter Guide and Search Console guidance explain the service tasks and organic-search measures that distinguish SEO delivery from paid placement. U.S. Census Bureau retail e-commerce estimates, Eurostat's e-commerce statistics, and UN Trade and Development's Digital Economy Report provide illustrative demand and regional context for client industries and digital adoption.
Public company filings and investor materials can clarify how agencies describe services and report relevant revenue, while reputable press and company announcements can cross-check launches, contracts, and changes in delivery. These named sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
A structured interview program would include agency executives, SEO service-line leaders, client marketing and digital leaders, and channel specialists across APAC, EMEA, and the Americas. Interviews and a short survey would test secondary findings on service fees, contract models, client demand, and regional buying patterns, while clarifying whether bundled work contains a separately identifiable SEO fee. Analysts would record unresolved gaps, seek follow-up evidence from respondents when estimates conflict, and triangulate responses against public company disclosures and market indicators.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 25% | Managers: 45% | Americas: 30% |
Market-Sizing & Forecasting
The estimate would use a top-down view of global annual client fees for SEO work, expressed in USD and reported by service type, organization size, end-user industry, service model, access channel, and geography. Segment estimates would be built from evidence on client spending and provider service mix, with digital commerce activity and digital marketing budgets indicating addressable demand, mobile internet use indicating demand for mobile SEO work, and agency service revenue and contract mix checking monetized delivery. A scenario model would extend the forecast through 2032 by varying these demand indicators and the pace of adoption, with analysts checking each variable's direction and segment implications against respondent evidence. Selective bottom-up checks would compare sampled agency fee levels and engagements, or supplier revenue roll-ups where SEO service fees can be separated, with the top-down total. Bundled fees would be counted once, and gaps would be documented and reconciled against available market indicators before final estimates are set.
Data Validation & Update Cycle
Analysts would triangulate published estimates, company disclosures, market indicators, and respondent evidence, then investigate anomalies by tracing source periods, definitions, currency, and possible double counting. A second analyst review would check calculations and segment totals, with unresolved variances escalated for review and respondents re-contacted when a material input or boundary remains unclear. The estimate would be refreshed annually, reviewed between cycles after material search or market events, and checked again in a fresh pre-delivery pass.
Mordor Intelligence's Seo Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global search engine optimization (SEO) services market measures annual client spending worldwide on fee-based services that improve a client's organic visibility on general-purpose search engines.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Bundled fees would be counted once, and gaps would be documented and reconciled against available market indicators before final estimates are set.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 94.16 B (2027) | |
| Global Research Firm A | USD 85.7 B (2025) | At its 2025 base, this estimate is 9.0% below this report's 2027 value of USD 94.16 B, 2 years later. Its published 2025 base is 2 years earlier than the report's 2027 measurement. |
| Global Market Research Firm B | USD 2.6 B (2025) | At its 2025 base, this estimate is 97.2% below this report's 2027 value of USD 94.16 B, 2 years later. Its published 5.6% forecast growth is below the report's 11.78% forecast. |
Mordor Intelligence's analysts would triangulate published estimates, company disclosures, market indicators, and respondent evidence, then investigate anomalies by tracing source periods, definitions, currency, and possible double counting.
Key Questions Answered in the Report
What is the search engine optimization (SEO) services market size and growth outlook?
The size is estimated at USD 94.16 billion in 2027 and forecast to reach USD 164.3 billion by 2032, with an 11.78% CAGR during 2027-2032.
What is driving demand for SEO services?
China's online retail growth through September 2026 and active B2B content programs support demand. Google's mobile-first indexing for most sites also creates a content-parity delivery task.
Which SEO service type has the largest share?
On-page SEO led service types with a 41.28% market share in 2026.
Which companies supply tools for agency-delivered SEO work?
Ahrefs Pte Ltd and Surfer Sp. z o.o. supply SEO software that can support agencies' delivery and reporting. Adobe completed its acquisition of Semrush Holdings Inc. in April 2026.
What challenges affect the outlook for SEO providers?
France's conditions for consent-exempt audience measurement limit data reuse. The exemption requires anonymous statistics and excludes cross-site or cross-app tracking.
Which region leads SEO services, and which has the fastest growth forecast?
North America had the largest share at 33.68% in 2026, and Asia-Pacific is forecast to grow fastest at a 13.3% CAGR during 2027-2032.