
Saudi Arabia E-commerce Market Analysis by Mordor Intelligence
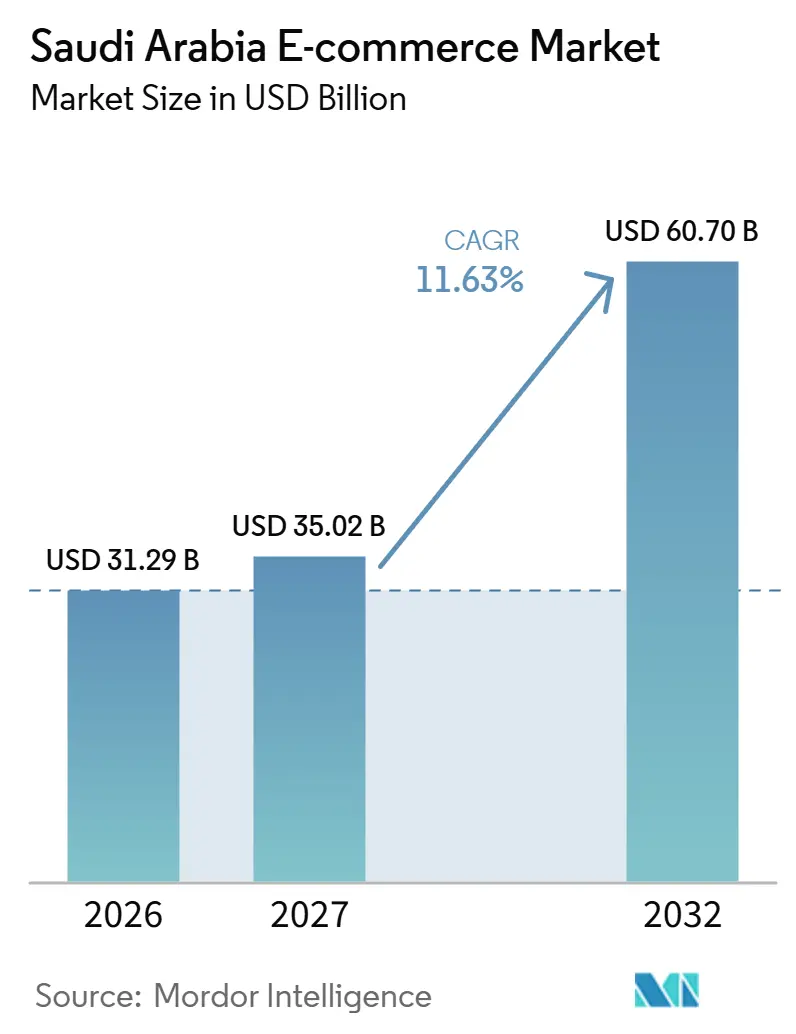
The Saudi Arabia e-commerce market size was valued at USD 31.29 billion in 2026 and estimated to grow from USD 35.02 billion in 2027 to reach USD 60.7 billion by 2032, at a CAGR of 11.63% during the forecast period (2027-2032).
In Saudi Arabia, broad internet access and established digital payments support the reach of mobile retail apps. Retailers can use that reach for grocery orders and specialist products when payment and fulfillment work together. Marketplace services and retailers' own channels offer different ways to connect sellers with customers. Long delivery routes and limited return options can reduce the appeal of extending service areas. Expansion therefore favors catchments where the operator can complete the order at a workable delivery cost.
Key Report Takeaways
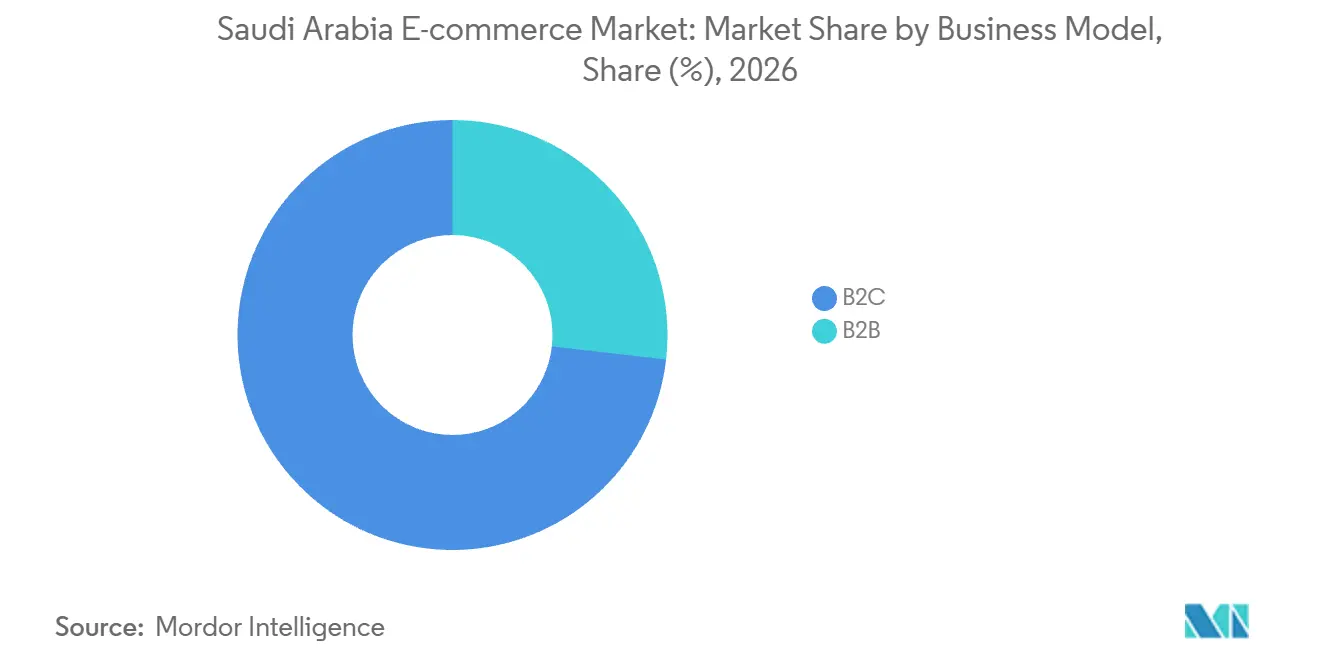
- By business model, B2C held a 73.18% Saudi Arabia e-commerce market share in 2026, while B2B is forecast to grow fastest at a CAGR of 13.15% during 2027-2032.
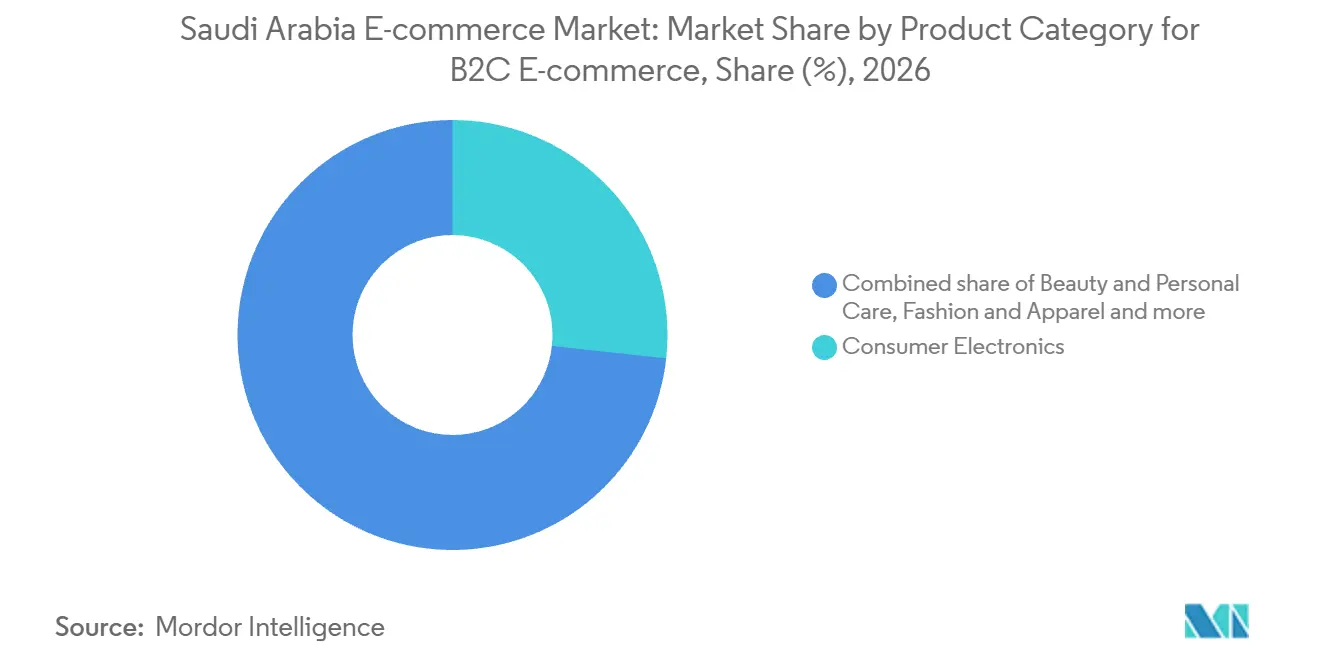
- Across B2C product categories, consumer electronics held a 26.74% share of B2C e-commerce in 2026, and the food and beverages segment is forecast to grow fastest at a CAGR of 13.42% during 2027-2032.
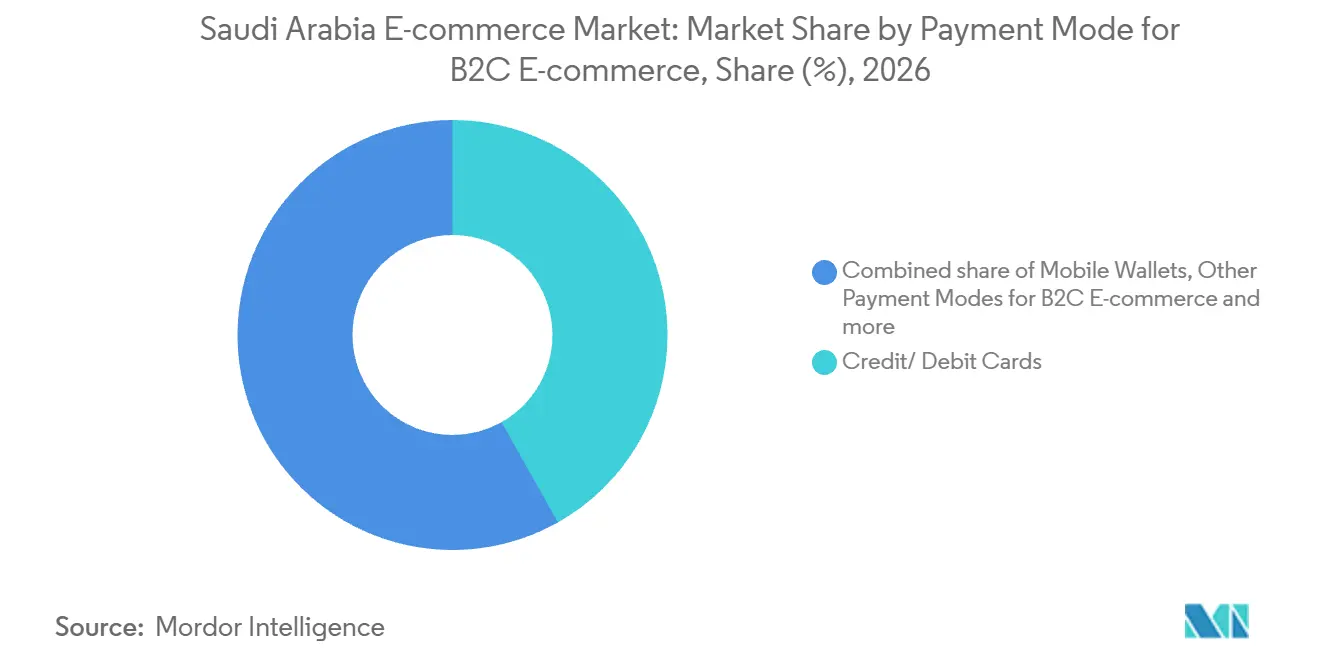
- Among B2C payment modes, credit and debit cards held a 41.84% share of B2C e-commerce in 2026, with mobile wallets forecast to grow fastest at a CAGR of 14.41% during 2027-2032.
- Smartphones held a 78.79% share of B2C e-commerce in 2026 and are forecast to be the fastest-growing segment at a CAGR of 12.77% during 2027-2032.
- Geographically, Riyadh held a 34.87% share of the Saudi Arabia e-commerce market size in 2026, and Eastern Province is forecast to grow fastest at a CAGR of 12.46% during 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Saudi Arabia E-commerce Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Expanding 5G Coverage and 99.6% Internet Penetration | +2.7% | Nationwide | Medium term (2-4 years) |
| National Payment Network (Mada)-driven cash-to-card shift | +4.2% | Nationwide | Short term (≤ 2 years) |
| Rapid grocery-delivery adoption in Tier-2 cities | +3% | Selected Jeddah and Dammam neighborhoods | Medium term (2-4 years) |
| SME onboarding via Monsha'at e-commerce enablement | +2.6% | Nationwide | Medium term (2-4 years) |
| Gen-Z social-commerce spend acceleration | +1.9% | Nationwide | Short term (≤ 2 years) |
| AI-powered fulfillment and dark-store roll-outs | +1.8% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Expanding 5G Coverage and 99.6% Internet Penetration
For an online retailer, connectivity creates a route to customers beyond the catchment of an individual physical shop. Saudi Arabia's 5G network covered 78% of the population in Q1 2025. Separately, 99.0% of individuals aged 15-74 in Saudi Arabia used the internet in 2025.[1] Where products and delivery are available, an online storefront can connect network access with an order that the merchant can fulfill. Retailers can consequently define online expansion around deliverable catchments, using connectivity to reach buyers without requiring a branch in each location.
National Payment Network (Mada)-driven cash-to-card shift
Payment-network integration can turn an established card audience into a practical source of online orders. Mada-card e-commerce transactions in Saudi Arabia reached 547 million in Q1 2026. On July 7, 2025, the Saudi Central Bank (SAMA) announced the launch of an e-commerce payments interface with standardized specifications for providers to connect with Mada and global payment networks.[2] Standardized connections can reduce the separate technical work payment providers need when serving retailers across supported networks. For smaller retailers, provider-level integration can make Mada acceptance accessible without each merchant building its own payment-network connection.
Rapid grocery-delivery adoption in Tier-2 cities
Neighborhood grocery delivery creates a route to online orders built around the household's next replenishment need. In January 2026, Meituan's Keemart grocery service was live through the Keeta app in selected neighborhoods of Jeddah and Dammam, delivering fresh produce and everyday essentials. The neighborhood format makes the service area part of the retail offer, because a shopper can order only where the operator delivers. A useful range of fresh and everyday items can support repeated shopping occasions through the same app. Adding the next neighborhood can therefore deepen the app's grocery business through another defined delivery catchment, with expansion tied to an orderable local assortment.
SME onboarding via Monsha'at e-commerce enablement
Small-store digitization can expand online purchasing when a new storefront can carry an order through payment and dispatch. In January 2025, Community Jameel Foundation, Monsha'at and Twsa'a launched an initiative helping traditional stores establish e-commerce operations. Its support included payment gateways, shipping solutions, marketing and inventory tools, training and workshops. Combining these functions can reduce the coordination burden a merchant would otherwise face when assembling the capabilities needed to sell online. Training can also help staff connect order acceptance with the operational work required to complete a sale. For traditional retailers, the value of enablement can lie in bringing payment, shipping and staff capability into the same launch decision.
Restraints Impact Analysis of Saudi Arabia E-commerce Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High last-mile costs outside metro corridors | -2% | Nationwide | Long term (≥ 4 years) |
| Cross-border return-logistics complexity | -1.3% | Nationwide | Medium term (2-4 years) |
| Low trust in BNPL among older shoppers | -0.4% | Nationwide | Medium term (2-4 years) |
| Cyber-fraud and data-sovereignty compliance burden | -0.9% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High last-mile costs outside metro corridors
Thin delivery routes can make the next online customer expensive to serve even when the storefront is already available. In December 2025, Grant Thornton identified long travel distances, low drop density, and labor-intensive delivery models as drivers of high last-mile costs in Saudi Arabia. This combination spreads transport and handling effort across fewer deliveries, increasing the amount each successful order must recover. For retailers serving scattered addresses, extending coverage can therefore raise sales while weakening the economics of small baskets. Passing the cost to shoppers can suppress order frequency, while absorbing it reduces the contribution available to fund expansion. Wider reach becomes commercially constrained wherever order density cannot support an affordable delivery charge.
Cross-border return-logistics complexity
Pecan says products sourced outside Saudi Arabia and shipped directly to customers cannot be returned or exchanged for a change of mind, citing the absence of a local Saudi warehouse. Its policy allows refunds for damaged or unusable goods and fundamental manufacturing defects. A buyer must therefore distinguish product failure from a change of preference when assessing the available remedy. For Pecan's customers, the international sourcing model makes uncertainty about personal suitability a financial consideration before placing an order. The buyer must weigh the cost of keeping a satisfactory but unwanted purchase, which can discourage a discretionary order.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Saudi Arabia E-commerce Market Segment Analysis
By Business Model:
Consumer Participation and Organizational IntegrationB2C accounted for a 73.18% share of the Saudi Arabia e-commerce market size in 2026, making it the largest segment. In 2025, 80.2% of Saudi individuals aged 15-74 purchased goods and services online. This gives consumer retailers an addressable pool of buyers with experience of placing orders through a digital channel. Winning repeat orders from Saudi consumers already shopping online can therefore sustain B2C expansion alongside the recruitment of first-time buyers.
B2B is forecast to be the fastest-growing segment at a CAGR of 13.15% during 2027-2032. In 2025, Jarir Marketing supported organizational clients by developing its Punch-out order-reception mechanism and integrating with King Fahd University of Petroleum & Minerals and Saudi Global Ports Company. Connecting order reception with named organizations makes a supplier's digital channel relevant to a defined business-buying process. For Jarir, maintaining those institutional ordering connections can support repeat business beyond the sale of an individual product.

By Product Category for B2C E-commerce:
Electronics Scale and Food Ordering MomentumConsumer electronics accounted for a 26.74% share of B2C e-commerce in 2026, making it the largest segment. Jarir Marketing reported 2025 Saudi Arabia revenue of SAR 6.37 billion (USD 1.7 billion) from smartphones, electronics and accessories across its business channels. For a retailer with that breadth, an online channel can extend customer access to a product business already generating domestic revenue. Electronics can therefore justify priority in Jarir's digital assortment investment because the retailer has substantial domestic category sales to serve through another channel.
Food and beverages form the fastest-growing segment, with a forecast CAGR of 13.42% during 2027-2032. Jahez KSA's online food-delivery orders rose 20% in Q2 2026 compared with Q1 2026. Nice One reported over 6 million customers in 2025 and linked that base to Saudi beauty and personal care e-commerce, within a business also including offline sales and marketing services. Sustaining Jahez KSA's additional orders would require delivery execution to keep pace with the ordering channel.
By Payment Mode for B2C E-commerce:
Card Scale and Wallet PreferenceCredit and debit cards accounted for a 41.84% share of B2C e-commerce in 2026, making them the largest segment. In 2025, Mada debit cards processed 1.77 billion e-commerce transactions in Saudi Arabia, covering online shopping sites, in-app purchases and e-wallets. The count provides a concrete example of debit cards carrying online purchases across several interfaces, giving retailers more than one route to accept the instrument. Consistent card acceptance across those routes can help a retailer carry the customer's chosen payment method through to a completed online order.
Mobile wallets form the fastest-growing segment, with a forecast CAGR of 14.41% during 2027-2032. Checkout.com reported in June 2026 that, over the preceding 5 years, Saudi consumers had increasingly preferred Mada or global digital wallets over cash on delivery for online shopping. That preference gives retailers a reason to make the relevant payment routes accessible within checkout. Other payment modes address flexibility, with 69.9% of respondents in Tabby's combined November 2025 Saudi Arabia and UAE survey saying they would avoid retailers without flexible options like Tabby. A retailer relying on cash on delivery can consequently lose appeal to shoppers who prefer a wallet, making wallet acceptance a practical route to new orders.
By Device Type for B2C E-commerce:
Mobile Reach and App ConversionSmartphones accounted for a 78.79% share of B2C e-commerce in 2026 and are forecast to be the fastest-growing segment at a CAGR of 12.77% during 2027-2032. In 2025, 98.4% of people aged 15-74 in Saudi Arabia used a mobile phone to access the internet. Such widespread use makes the phone a practical interface through which retailers can address potential customers. A large access base can support investment in a consistent mobile buying experience because the same interface can serve many potential buyers. That gives retailers a common access route around which to develop an online offer connecting product selection with order completion.
Retailer apps add a growth mechanism through how effectively their customer experience supports a purchase. In 2025, Jarir launched a revised app and reported a 4.8 app-store rating, doubled customer conversion rates and 60% higher downloads. Those company-wide app results covered its business in Saudi Arabia and neighboring Gulf markets. Jarir's experience makes the purchase journey an additional investment priority, since a retailer can seek more orders from app users it has already attracted.
Geography Analysis
Riyadh E-commerce Market
Riyadh accounted for a 34.87% share of the Saudi Arabia e-commerce market size in 2026, making it the largest geography. Separately, the Ministry of Commerce reported 23,061 active e-commerce commercial registrations in Riyadh Region at the end of Q3 2026. Health and wellness retailer iHerb announced the grand opening of its Riyadh fulfillment center in February 2026, with CJ Logistics as its third-party operator.[3] The fulfillment opening adds specialist retail infrastructure in the same region that led e-commerce registrations, reinforcing Riyadh's role as a base for both online commerce and its physical execution.
Eastern Province E-commerce Market
Eastern Province is the fastest-growing geography, with a forecast CAGR of 12.46% during 2027-2032. The Ministry of Commerce counted 7,792 active e-commerce commercial registrations there at the end of Q3 2026. Dell Technologies opened its first Saudi merge and fulfillment center in Dammam in February 2025, with capacity for up to 600,000 units annually across its product lines. Dell said it worked with local channel partners on product distribution. The province combines a registered e-commerce business base with investment in physical product distribution, giving expansion a foundation in both commercial participation and supply infrastructure.
In Makkah Province, Keeta's food-delivery network included Makkah city by July 2025, establishing a city-level channel within the province. Jeddah gained a platform entrant when Keeta, Meituan's international subsidiary, launched food delivery there on January 1, 2025. LuLu's March 2026 launch of its LuLu 2.0 app and website included an online product-delivery offer for Dammam customers. Within outlying regions, Keeta added Abha to its food-delivery network in July 2025. Ordering relationships can consequently develop through a delivery platform in Abha or through a retailer's own app in Dammam.
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of an online retailer managing seller and transaction disclosures. The comparison covers Saudi Arabia's national regime and its application in Riyadh. Riyadh Municipality also provides an online inquiry service for commercial-activity licenses, offering a local information channel alongside the national framework.
Regulatory Table of Saudi Arabia E-commerce Market
| Decision factor | Saudi Arabia | Riyadh |
|---|---|---|
| Primary authority | Ministry of Commerce | Ministry of Commerce for e-commerce duties |
| Key instruments or direction | E-Commerce Law, Articles 6-8 | National E-Commerce Law |
| Commercial effect | Contact and registration details if any, contract terms, total price, delivery fees if any, and itemized invoices | National disclosure duties and municipal online license inquiry |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
The national Medium rating balances defined disclosure and invoicing obligations against the ability to implement them within ordinary online order processing. Riyadh receives the same rating because national duties govern the online transaction, while its municipality provides a separate license-inquiry channel. The E-Commerce Law, Royal Decree M/126, was issued on July 10, 2019, and entered into force on October 24, 2019. Retailers must provide total prices including charges, taxes and delivery fees, if any, and issue itemized invoices after contract conclusion, so checkout and invoicing systems must carry those fields.
Value Chain Stages
The value chain compares the capabilities needed to turn a merchant's online offer into a paid, delivered order. Its structure creates distinct earnings opportunities for storefront providers, payment services and parcel operators. The commercial challenge is to coordinate these services so that work completed at one stage can be used effectively by the next.
Value Chain Analysis Table of Saudi Arabia E-commerce Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Establish the digital storefront | Commerce platform providers such as Zid | Merchant subscription fees | Configuration must fit the merchant's order workflow | Align storefront setup with payment and dispatch steps |
| Accept online payment | Payment service providers such as Zid (Zid Pay) and bank gateway providers such as Al Rajhi Bank | Zid Pay fees on successful transactions, varying by subscription package | Acceptance costs vary with package and completed transactions | Compare subscription and payment costs together |
| Deliver the order | Postal and logistics operators such as SPL | Prepaid SME shipment-package fees, with a minimum purchase of 20 packages | Handover must match the recipient's access | Offer doorstep, locker or postal-office delivery |
| Source: Mordor Intelligence | ||||
Zid's pricing links the merchant's subscription choice with payment fees, so choosing a platform package affects costs at more than one stage. That makes expected successful-payment volume relevant when comparing subscription packages. Prepaid shipment packages add a separate commitment before every package has been used. Merchants can therefore compare platform plans on their combined subscription and payment burden, then choose parcel handover around the recipients they serve.
Competitive Landscape
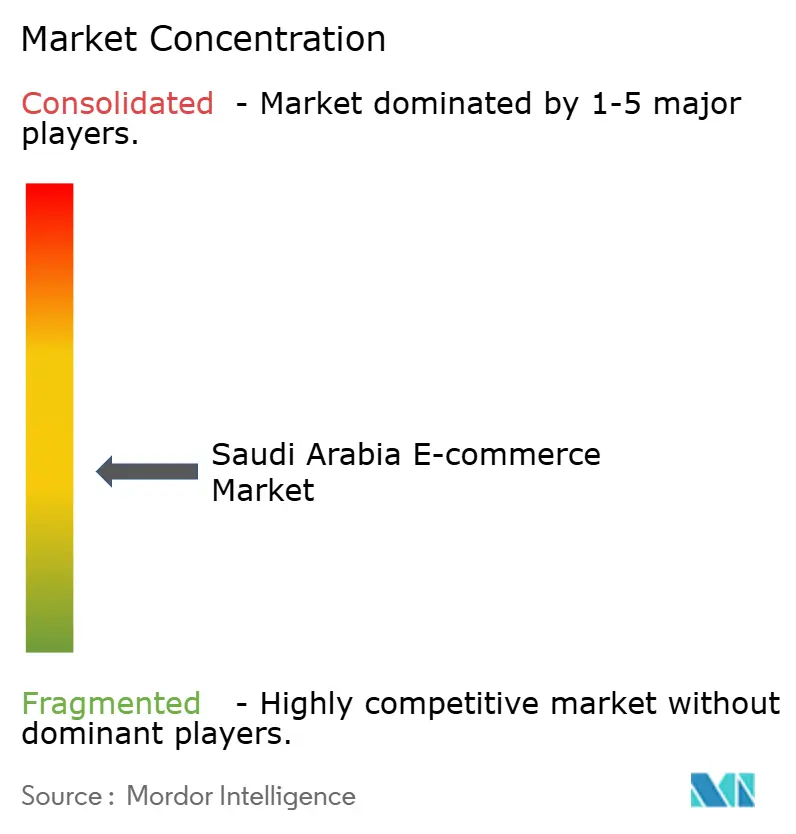
Competition has a mixed structure, with marketplace operators and established retailers developing different routes to online shoppers. Amazon Inc. (Amazon.sa), Noon AD Holdings Ltd., Jarir Marketing Co., United Electronics Co. (eXtra) and Nahdi Medical Co. are major participants. Jarir's B2C e-commerce sales grew 30% in 2025, alongside growth in customers, repeat purchases and orders received from its showrooms. Nahdi Online contributed 25.8% of Nahdi's total sales in 2025 across its Saudi Arabia and UAE business. These results show why competition includes retailers integrating digital sales into an existing business, creating alternatives to a single marketplace route for customers.
eXtra launched a marketplace in 2025, expanding product selection for customers and verified sellers across its Gulf-region business. A seller-based offer can broaden the range available through a retailer's digital channel, creating an opening for specialist merchants to reach its customers. This model makes the selection of participating sellers commercially significant because the customer encounters their products through the retailer's own platform. Its competitive promise depends on keeping that expanded offer coherent enough to shop and fulfill, making management of the seller network an additional capability alongside the retailer's direct sales operation.
In 2025, Jahez partnered with noon to add noon Minutes to its app and enable noon users to order from more than 50,000 restaurants across more than 100 Saudi cities. Such partnerships can widen an app's offer by connecting established service networks. Amazon.sa offers sellers Amazon fulfillment or self-shipping options and requires Saudi commercial registration to register and sell. That combination creates a defined entry route for smaller sellers with different logistics capabilities. Outsourced fulfillment can help smaller sellers use platform reach, while required commercial registration creates a formal entry threshold for participating businesses.
Saudi Arabia E-commerce Industry Leaders
-
Amazon Inc. (Amazon.sa)
-
Noon AD Holdings Ltd.
-
Jarir Marketing Co.
-
United Electronics Co. (eXtra)
-
Nahdi Medical Co.
- *Disclaimer: Major Players sorted in no particular order
Saudi Arabia E-commerce Market Companies Covered in this Report
- Amazon Inc. (Amazon.sa)
- Noon AD Holdings Ltd.
- Jarir Marketing Co.
- United Electronics Co. (eXtra)
- Nahdi Medical Co.
- STC Bank Co.
- Ounass (Al Tayer Insignia LLC)
- Sary Co.
- Lulu Group International
- Carrefour Saudi (Majid Al Futtaim)
- Nana Direct Co.
- Talabat (Delivery Hero SE)
- HungerStation (Delivery Hero SE)
- Haraj Co.
- Namshi Holding Limited
- Shein Group Ltd.
- eXtra Stores App (United Electronics Co.)
- CarrefourNow (Majid Al Futtaim)
- IKEA Saudi Arabia (Ghassan Ahmed Al Sulaiman Co.)
- Noon E Commerce Solutions One Person Company
Key Opportunities for Market Participants
The opportunity comparison examines where established online buying can be converted into more useful retail offers. The General Authority for Statistics (GASTAT) measured product-category purchases among online shoppers aged 15-74 in Saudi Arabia in 2025. Existing retail and ordering channels provide a practical starting point for connecting a focused assortment with a completed purchase.
Market Opportunities Table of Saudi Arabia E-commerce Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Cosmetics orders through pharmacy digital channels | In 2025, 40.2% of online shoppers aged 15-74 in Saudi Arabia bought cosmetics online | Online cosmetics buyers | Link beauty assortments with collection and delivery options | Making a focused beauty offer distinct within a broad pharmacy range | Pharmacy retailers with beauty assortments, including Nahdi Medical Co. |
| More complete online grocery baskets | In 2025, 38.5% of online shoppers aged 15-74 in Saudi Arabia bought food, groceries, or tobacco online | Households placing food and grocery orders | Build orderable grocery assortments around defined delivery areas | Coordinating basket availability with delivery execution | Supermarket merchants and order channels such as HungerStation (Delivery Hero SE) |
| Focused computer-equipment purchases | In 2025, 15.0% of online shoppers aged 15-74 in Saudi Arabia bought computer equipment or spare parts online | Computer-equipment buyers | Connect equipment and relevant accessory choices in one online basket | Accurate product and accessory matching | Computing retailers, including United Electronics Co. (eXtra) |
| Source: Mordor Intelligence | |||||
Cosmetics has the highest online purchase incidence among the 3 product groups compared here. Nahdi Medical Co. offers e-commerce, e-pharmacist and click-and-collect services, with wellness and beauty products among its broader pharmacy and healthcare offerings. A pharmacy retailer with these services can serve a beauty order through an existing ordering and collection channel. Differentiating the beauty assortment within a broad pharmacy range therefore becomes the central commercial task.
Recent Industry Developments in Saudi Arabia E-commerce Market
- Sep 2026: SNB Group and Mastercard announced an expanded merchant-solutions collaboration for Saudi Arabia, with SNB saying it would continue using Mastercard Gateway.
- Feb 2026: iHerb, an online retailer of health and wellness products, opened a fulfillment center in Riyadh, Saudi Arabia.
Saudi Arabia E-commerce Market Report Scope and Research Methodology
Market Definition and Coverage
The Saudi Arabia e-commerce market measures annual spending on goods and services ordered online by businesses and consumers in Saudi Arabia. It covers B2B and B2C transactions, with B2C sales classified by product category, payment mode and ordering device.
Scope exclusions: Offline sales of goods and services, e-commerce platform, marketplace and payment service revenues, and online sales to buyers outside Saudi Arabia are excluded.
Segments Covered in This Report
- By Business Model
- B2B
- B2C
- By Product Category for B2C E-commerce
- Beauty and Personal Care
- Consumer Electronics
- Fashion and Apparel
- Food and Beverages
- Furniture and Home
- Toys, DIY and Media
- Other Product Categories for B2C E-commerce
- By Payment Mode for B2C E-commerce
- Credit/ Debit Cards
- Mobile Wallets
- Other Payment Modes for B2C E-commerce
- By Device Type for B2C E-commerce
- Smartphone
- Desktop / Laptop
- Other Device Types for B2C E-commerce
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the General Authority for Statistics' ICT publications on households and establishments, the Communications, Space and Technology Commission's Saudi Internet Report and the Ministry of Investment's English translation of the E-Commerce Law support the work. The household publication informs purchase incidence, while the establishment publication captures business online ordering. The Saudi Internet Report provides connectivity context, and the E-Commerce Law informs seller obligations.
Company annual reports and investor materials can help cross-check reported digital-channel sales, category exposure and fulfillment changes, while reputable Saudi business press can clarify market events and reported operating developments. These examples are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include Saudi Arabia marketplace and retailer executives, e-commerce and category leaders, digital-payment and fulfillment specialists, and business buyers with online procurement responsibilities. Respondents would test secondary interpretations of transaction coverage, channel overlap, category mix and forecast drivers against their operating experience. When evidence conflicts or leaves a market input unclear, analysts would use follow-up questions and triangulation with official statistics, company disclosures and independent market signals.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | |
| Mid tier: 45% | Functional/Unit leaders: 35% | |
| Smaller Players: 25% | Managers: 45% |
Market-Sizing & Forecasting
The model estimates annual Saudi buyer spending on online orders, separating business purchases from consumer purchases and counting each qualifying order once. Consumer purchase incidence and product mix from the General Authority for Statistics, establishment online-order and internet-sales indicators, retail activity, and digital-channel revenue disclosed in company filings provide practical signals for demand, category allocation and change over time. A top-down estimate applies consumer online-purchase incidence and business ordering indicators to relevant spending pools, then allocates the value across B2B and B2C and across the defined B2C product, payment and device groups using survey mixes and seller disclosures. Selective bottom-up checks compare sampled average selling prices with order volumes and roll up seller or channel evidence, while gaps in transaction detail are bridged with observed category and company trends and reconciled to the total. Scenario analysis varies consumer ordering, business online-order penetration, basket value and category mix, with primary respondents checking the assumptions and forecast drivers at variable level.
Data Validation & Update Cycle
Analysts triangulate the estimate against household purchasing indicators, establishment online-order measures, retail activity and company-reported digital sales, then check totals and segment shares for overlap and consistency. They investigate outliers and year-to-year variances, document the evidence behind adjustments, and use a second analyst review before sign-off. Analysts re-contact sources when evidence conflicts materially with other findings or a definition, timing or channel treatment remains unclear. The dataset is refreshed annually, updated between cycles after material market events, and reviewed in a fresh pre-delivery pass.
Mordor Intelligence's Saudi Arabia Ecommerce Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Saudi Arabia e-commerce market measures annual spending on goods and services ordered online by businesses and consumers in Saudi Arabia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Consumer purchase incidence and product mix from the General Authority for Statistics, establishment online-order and internet-sales indicators, retail activity, and digital-channel revenue disclosed in company filings provide practical signals for demand, category allocation and change over time.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 35.02 B (2027) | |
| Market Data Provider A | USD 15.97 B (2026) | At its 2026 base, this estimate is 54.4% below this report's 2027 value of USD 35.02 B, 1 year later. Its estimate covers B2C physical goods and excludes B2B purchases and digitally distributed services. |
| Commercial Research Publisher B | USD 24.62 B (2025) | At its 2025 base, this estimate is 29.7% below this report's 2027 value of USD 35.02 B, 2 years later. Its earlier base year leaves forecast growth before the report's measurement year. |
Mordor Intelligence's analysts triangulate the estimate against household purchasing indicators, establishment online-order measures, retail activity and company-reported digital sales, then check totals and segment shares for overlap and consistency.
Key Questions Answered in the Report
What is the Saudi Arabia e-commerce market size and growth outlook?
The size is estimated at USD 35.02 billion in 2027 and forecast to reach USD 60.7 billion by 2032, at a CAGR of 11.63% during 2027-2032.
What supports growth in Saudi online retail orders?
Mada-card e-commerce recorded 547 million transactions in Q1 2026, and Monsha'at helped launch a traditional-store e-commerce initiative in 2025.
What business model leads Saudi online commerce?
B2C led with 73.18% of online purchase value in 2026, while B2B is forecast to grow at a CAGR of 13.15% during 2027-2032.
Which companies compete in Saudi online retail?
Major participants include Amazon Inc. (Amazon.sa), Noon AD Holdings Ltd., Jarir Marketing Co., United Electronics Co. (eXtra) and Nahdi Medical Co.
What delivery challenge constrains Saudi online retail expansion?
In December 2025, Grant Thornton identified long travel distances, low drop density and labor-intensive delivery as drivers of high Saudi last-mile costs.
Which Saudi locations lead online commerce?
Riyadh led with 34.87% of online purchase value in 2026. Eastern Province is forecast to grow fastest at a CAGR of 12.46% during 2027-2032.