
Residential Air To Water Heat Pump Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
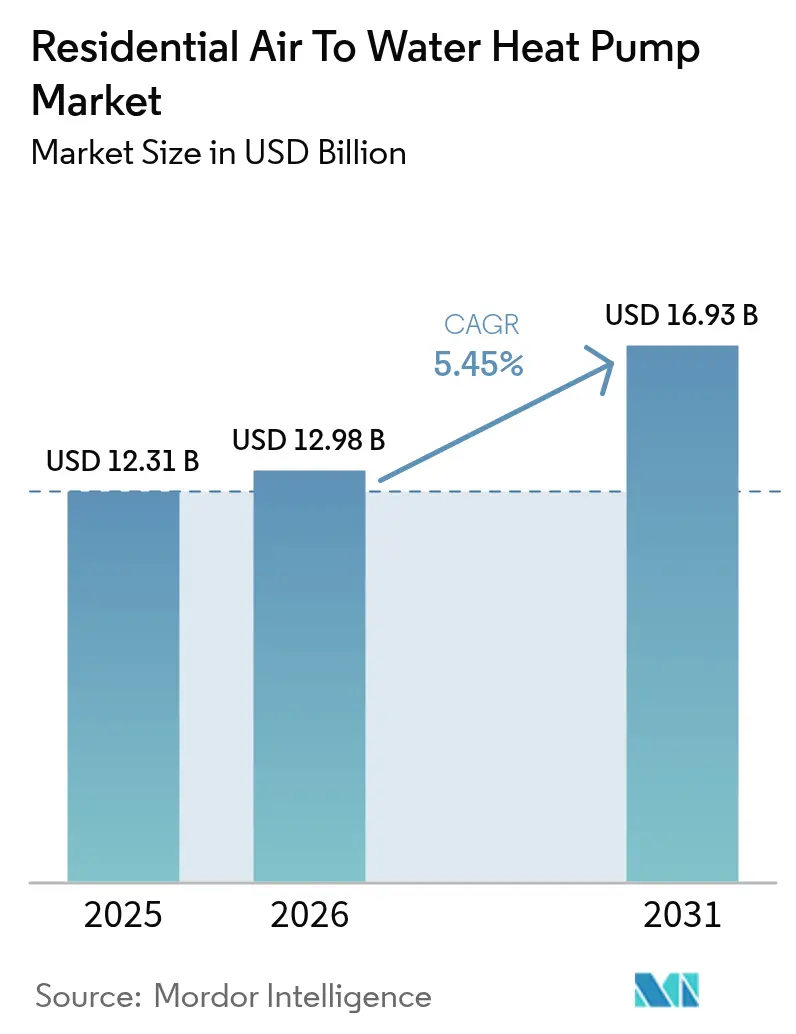
| Market Size (2026) | USD 12.98 Billion |
| Market Size (2031) | USD 16.93 Billion |
| Growth Rate (2026 - 2031) | 5.45 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players
*Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. |
|
Residential Air To Water Heat Pump Market Analysis by Mordor Intelligence
The residential air-to-water heat pump market size is expected to grow from USD 12.31 billion in 2025 to USD 12.98 billion in 2026 and is forecast to reach USD 16.93 billion by 2031 at 5.45% CAGR over 2026-2031. Rising policy pressure to decarbonize home heating, widening total cost-of-ownership advantages over gas boilers, and generous fiscal incentives are propelling this residential air-to-water heat pump market toward mainstream adoption. Manufacturers are scaling local component plants while natural-refrigerant models meet tightening F-Gas rules and improve seasonal COP. Hybrid configurations gain early favor because they reassure homeowners of fallback capacity during extreme cold, yet performance gains in inverter-driven units are narrowing that perceived reliability gap. Bottlenecks remain—grid interconnection queues in dense suburbs, installer shortages and municipal noise ordinances on outdoor units—but none appear large enough to derail the long-run trajectory of this residential air to water heat pump market.
Key Report Takeaways
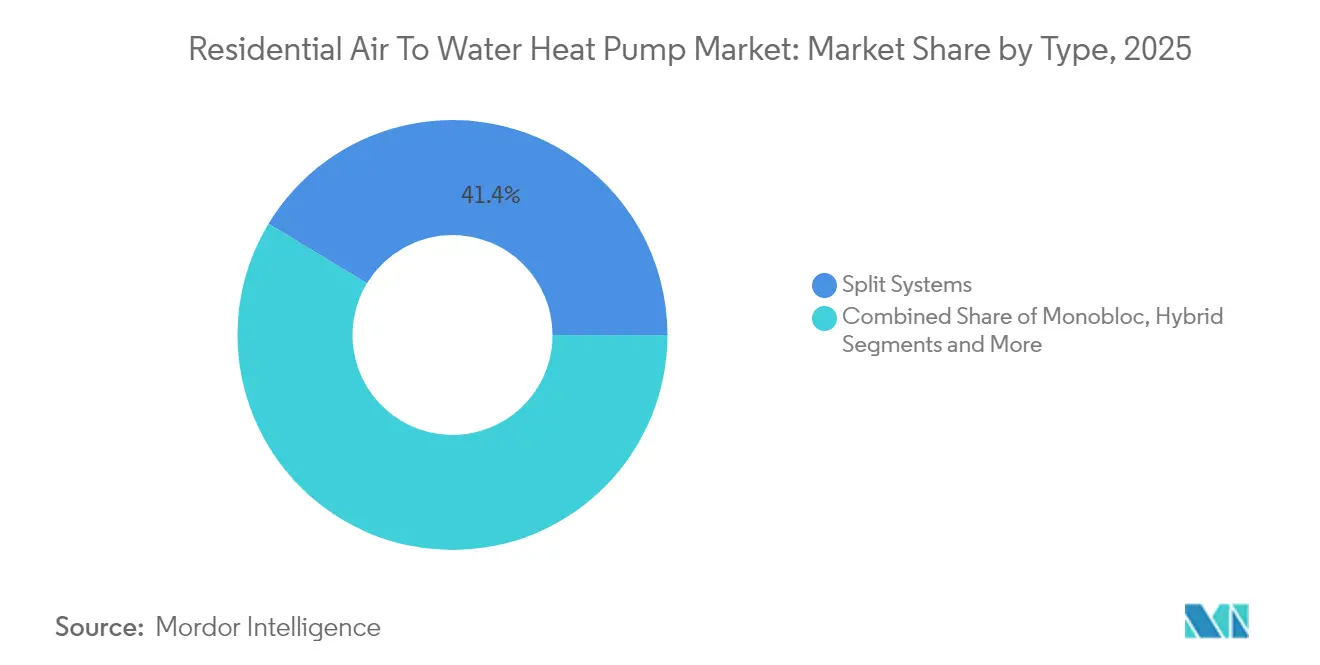
- By type, split systems led with 41.35% revenue share in 2025; hybrid combinations are projected to grow at a 8.83% CAGR through 2031.
- By capacity, < 10 kW units captured 54.30% of the residential air to water heat pump market share in 2025, while > 20 kW systems are set to expand at an 8.14% CAGR to 2031.
- By application, single-family homes accounted for 67.40% share of the residential air to water heat pump market size in 2025; multi-family residences are advancing at a 7.28% CAGR through 2031.
- By geography, Europe commanded 33.60% share in 2025; the Middle East is the fastest-growing region at 7.82% CAGR to 2031.
- Carrier’s acquisition of Viessmann Climate Solutions, Daikin, Mitsubishi Electric, Bosch and Trane collectively held about 48% of global shipments in 2024, underscoring moderate concentration in the residential air to water heat pump market.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Global Residential Air To Water Heat Pump Market Trends and Insights
Drivers Impact Analysis*
| DRIVER | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| EU-wide ban on fossil-fuel boilers accelerating heat-pump retrofits | +1.2% | Europe, with spillover to UK and Norway | Medium term (2-4 years) |
| Post-Ukraine gas-price volatility widening TCO gap in Europe | +0.8% | Europe, particularly Germany and Netherlands | Short term (≤ 2 years) |
| U.S. Inflation Reduction Act rebates for ≥15 SEER heat pumps | +0.9% | North America, primarily United States | Medium term (2-4 years) |
| Low-GWP R290 / R32 models easing F-Gas Phase-Down compliance | +0.6% | Global, with early adoption in Europe and Japan | Long term (≥ 4 years) |
| Inverter compressors lifting seasonal COP in sub-zero climates | +0.7% | Northern Europe, Canada, Northern US states | Long term (≥ 4 years) |
| Rooftop solar parity unlocking self-consumption heating in China | +0.5% | APAC core, particularly China and India | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
EU-wide ban on fossil-fuel boilers accelerating heat-pump retrofits
Mandatory phase-outs that start in 2025 for new homes and extend to replacements by 2040 remove any remaining ambiguity over the preferred hydronic heating solution. This hard deadline locks in multi-decade demand for air-to-water units able to deliver high flow temperatures via existing radiators. Subsidies covering up to 30% of installed cost in markets such as the Netherlands sweeten the economics for homeowners. Instead of sporadic incentive spikes, a predictable compliance calendar now guides OEM capacity planning and distributor stocking levels. The policy also shortens payback periods because gas-boiler replacements face higher carbon levies each year. Taken together, the measure pushes the residential air to water heat pump market toward default-technology status across Europe.[1]Bricknest, “New Rules for Heat Pumps in the Netherlands 2025-2026,” bricknest.nl
Post-Ukraine gas-price volatility widening TCO gap in Europe
Spot gas prices across northwest Europe ran three times above the pre-2022 average, tilting lifetime costs sharply in favor of heat pumps. Government analysis shows German households can cut annual heating bills by up to 60% after switching. Such savings resonate with middle-income owners who previously viewed heat pumps as a green luxury. Volatility is structural, not cyclical, because EU energy policy seeks permanent diversification away from pipeline gas. That dynamic deepens the comparative advantage of the residential air to water heat pump market every winter.
US Inflation Reduction Act rebates for ≥ 15 SEER heat pumps
Income-based rebates of up to USD 8,000 offset upfront premiums and unlock demand in states with modest heating loads where air-to-water solutions historically struggled to compete. The multiyear window gives manufacturers certainty to localize production, as shown by Mitsubishi Electric’s USD 143.5 million compressor plant in Kentucky. Aggregated rebate pipelines also create contiguous clusters of installs that cut logistics and training costs, helping the residential air to water heat pump market gain critical mass in North America.
Low-GWP R290 / R32 models easing F-Gas phase-down compliance
From January 2025, the EU bars refrigerants above 750 GWP in new hydronic systems. R290’s GWP of 20 and efficiency boost of 5-10% position adopters to capture share. Panasonic and Vaillant already sell propane-charged lines, signalling a wider portfolio migration. Early movers gain first-mover loyalty among installers, and they insulate themselves from future price shocks on legacy refrigerants. Consequently, regulatory alignment and performance gains combine to reinforce demand in the residential air to water heat pump market.
Restraints Impact Analysis*
| RESTRAINTS | (~) % IMPACT ON CAGR FORECAST | GEOGRAPHIC RELEVANCE | IMPACT TIMELINE |
|---|---|---|---|
| Grid-capacity caps delaying hook-ups in dense EU suburbs | -0.4% | Europe, particularly Germany and Netherlands | Short term (≤ 2 years) |
| Shortage of hydronic-skilled installers inflating labor cost | -0.6% | Global, most acute in North America and Europe | Medium term (2-4 years) |
| Urban noise-regulation setbacks on outdoor-unit placement | -0.2% | Global urban centers, particularly Asia-Pacific | Long term (≥ 4 years) |
| Consumer preference for gas boilers in East-Asian multi-family | -0.3% | APAC, particularly Japan and South Korea | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Grid-capacity caps delaying hook-ups in dense EU suburbs
Distribution feeders built for low electrification levels face sharp peak-load jumps as entire streets add 6-10 kW units. Germany’s 500,000-unit annual target could raise peak winter demand by 10 GW, forcing utilities to triage connections. Rural tie-in fees climb above EUR 1,200 per dwelling, while urban districts fare better. This mismatch slows early-stage volumes for the residential air to water heat pump market in grid-constrained neighbourhoods until reinforcement work catches up.[2]Clean Energy Wire, “Heat Pump Installation Plans May Overburden Germany’s Grid,” cleanenergywire.org
Shortage of hydronic-skilled installers inflating labor cost
Training throughput is rising—UK certifications grew 166% in 2024—but remains well short of policy targets. Poorly balanced loops or undersized buffer tanks cut expected COP and risk reputational damage. North American utilities sponsor six-month boot camps, yet workforce gaps linger because plumbing apprenticeships take years. Elevated labor premiums add 15-20% to final invoices, tempering the residential air to water heat pump market’s price competitiveness.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Type – Hybrid systems extend reliability perception
Split units held 41.35% of revenue in 2025 as installers value familiar component layouts that mirror legacy boiler circuits. That dominance translates into a sizeable slice of the residential air to water heat pump market. Hybrid pump-and-boiler packages, however, are racing ahead at a 8.83% CAGR as households want backup combustion during polar cold snaps. The segment’s growth reflects behavioral risk aversion more than technical necessity, because modern R290 models sustain 65 °C supply water at -20 °C ambient. Over time, as field data validates pure-pump reliability, hybrid appeal is likely to plateau. Monobloc and all-in-one variants court space-constrained retrofits, adding useful breadth to this residential air to water heat pump market.
Split offerings benefit from mass-production economics that compress hardware costs, keeping entry prices competitive. Conversely, hybrids command premium pricing but deliver perceived peace of mind, a value proposition resonating in cold continental climates. OEMs are bundling connected thermostats and intelligent switchover algorithms to optimize operating points automatically. This software layer differentiates brands and nudges the residential air to water heat pump industry toward service-centric revenue streams.


By Capacity – Large residential blocks unlock scale economies
< 10 kW units represented 54.30% of installs in 2025, a natural fit for typical detached homes. At the other end, > 20 kW machines posted the quickest 8.14% CAGR as developers of multi-dwelling blocks and luxury residences opt for central plants. That surge means the > 20 kW slice of the residential air to water heat pump market size could double by 2031. Viessmann’s 40 kW Vitocal 250-A PRO illustrates how high-output propane units tackle older buildings where radiator delta-T demands are high.
Systems in the 10-20 kW tier bridge suburban villas and small apartment houses. As carbon caps tighten, this mid-range is broadening fastest in France, Italy and parts of Canada. With flow temperatures climbing to 70 °C, the capacity brackets converge, raising questions about future segmentation relevance. Nevertheless, installer workflows, refrigerant charge limits and grid-connection forms still differ enough to keep the capacity bands meaningful within the residential air to water heat pump market.
By Installation Type – New construction dominates early roll-outs
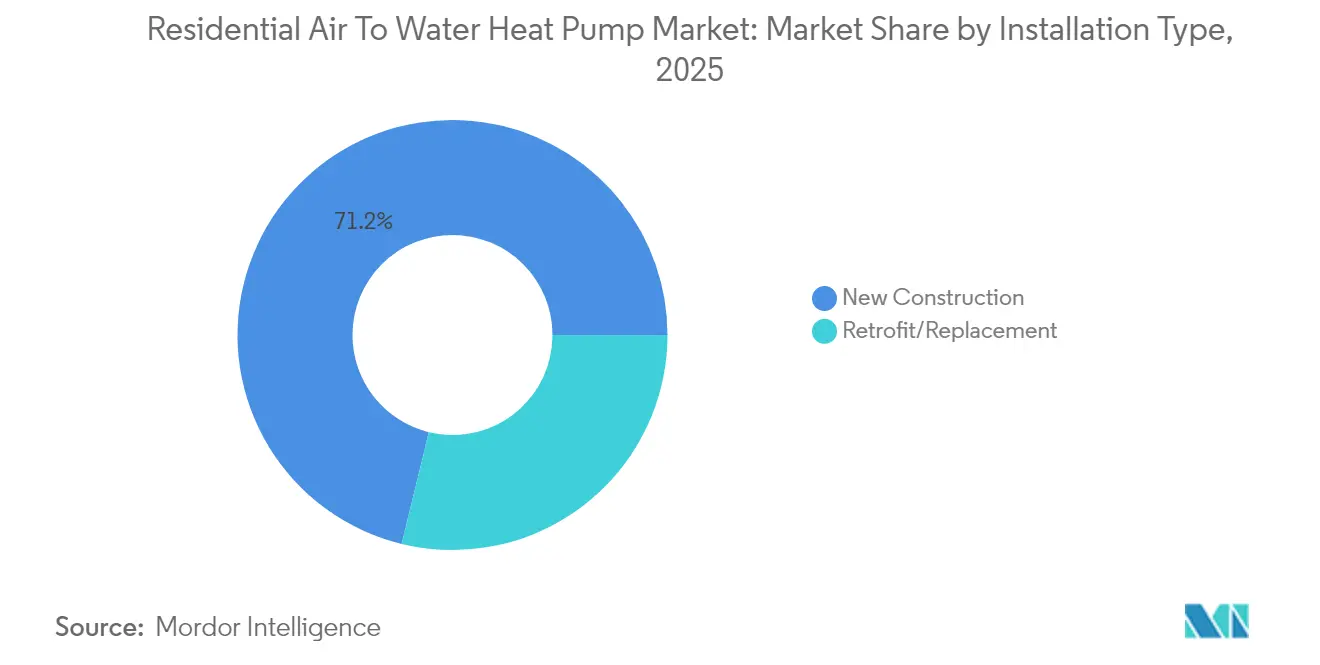
New builds accounted for 71.20% of 2025 shipments, reflecting the ease of integrating hydraulic loops and buffer tanks when architects can design around the equipment footprint at the blueprint stage. Most European building codes now require renewable primary heating; the UK’s Future Homes Standard, effective 2025, obliges heat-pump installation in every new dwelling. Forward-planning lets developers right-size emitters, minimise flow temperatures and optimise pump COP from day one, raising the share of the residential air to water heat pump market secured at the planning-permission stage.
Retrofit and replacement work makes up the remaining 28.80% but will grow faster once ageing boilers reach end-of-life and subsidy schemes sweeten paybacks. Hybrid kits and monobloc chassis simplify change-outs because installers can hook units onto existing radiator circuits without rewiring the entire home. Municipal grant programmes in Germany and France now cover up to EUR 9,000 of retrofit cost, narrowing the up-front gap with gas-boiler swaps. As component prices fall and workforce skills deepen, retrofit volume is expected to close the sales gap with new-builds after 2028, broadening the addressable residential air to water heat pump market while relieving cyclical dependence on the construction sector.
By Refrigerant – Propane (R290) leads the low-GWP shift
R410A still equips most legacy models because of supply-chain familiarity, but its >2,000 GWP rating brings phase-down risk and future servicing costs. From January 2025 the EU bans refrigerants above 750 GWP in new hydronic systems, accelerating the pivot toward R32 (GWP 675) and, more decisively, R290 with a GWP of 20. Early adopters such as Vaillant and Panasonic report 5-10% seasonal COP gains from higher latent-heat capacity in propane charge, creating both compliance and efficiency upside for the residential air to water heat pump market.
CO₂ (R744) is carving out a niche in multi-family blocks demanding 80 °C domestic-hot-water service, while next-gen magnetocaloric units in laboratory trials hint at a refrigerant-free future. Safety codes now permit up to 1 kg of propane under EN 378 when the outdoor unit sits outside the building envelope, alleviating earlier flammability concerns. Component vendors are scaling hermetically sealed compressors, and charge-reduction heat-exchanger designs keep hydrocarbon mass below critical thresholds. As a result, R290 models are forecast to lift their slice of the residential air to water heat pump market size to 46.70% by 2031, overtaking both R410A and R32 in mainstream volume sales.
Geography Analysis
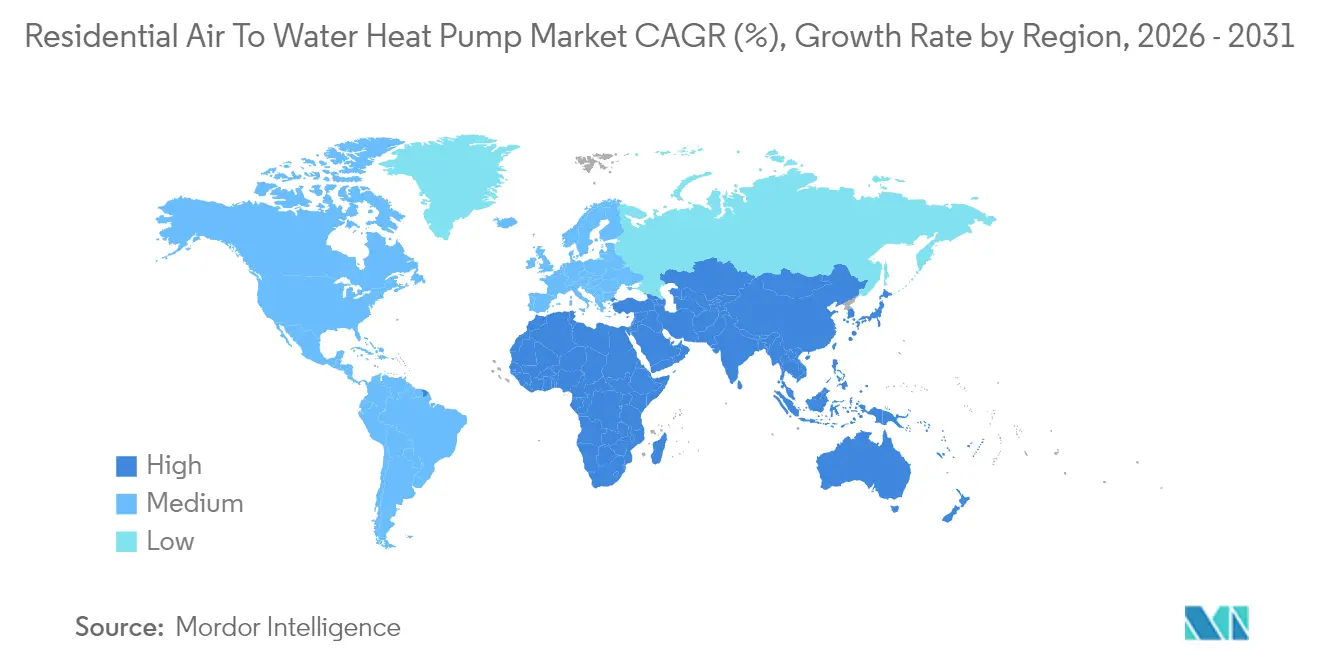
Europe retained 33.60% of global revenue in 2025 thanks to dense hydronic infrastructure and aggressive carbon policy. Nevertheless, macro headwinds and regulatory ambiguity shaved 22% off unit sales during 2024. National subsidy resets in France and Italy weighed on consumer sentiment, illustrating policy sensitivity inside the residential air to water heat pump market. Still, Brussels sees 60 million cumulative European installs as a 2030 milestone, implying a steep climb from today's base.
North America rebounded late-2024 with a 15% jump in shipments. Federal and state rebate stacks have pushed total incentives toward USD 10,000 in some ZIP codes, driving momentum in the residential air to water heat pump market. Local content rules are re-shaping supply chains; for example, the new Kentucky compressor plant will cut lead times by 30%. Canadian provinces add cold-climate tiers that spur R&D on vapor-injection compressors, raising seasonal efficiencies in frigid Prairies.
Asia-Pacific posts the fastest 7.82% CAGR led by China’s scale and rising electrification quotas. Domestic producers shipped 13% more units in 2024, even as export orders softened, highlighting robust internal momentum. The Middle East, while small today, matches that 7.82% growth rate as district-cooling operators retrofit reversible water-loop systems for winter service. Japan and South Korea remain technologically advanced but culturally attached to gas boilers in multi-family blocks, explaining a more modest uptake pace in that slice of the residential air to water heat pump market.

Regulatory Landscape
Policy and standards are tightening around two parallel compliance tracks: building decarbonization requirements and refrigerant environmental limits. In Europe, EU Regulation (EU) 2024/573 (in force since 2024) accelerates the HFC phase-down and reinforces restrictions that favor low-GWP options such as R290 and R744. The same framework also blocks the use of very high-GWP fluorinated gases (GWP >= 2,500) for heat-pump maintenance and servicing starting January 1, 2026, pushing OEM portfolios and service ecosystems further away from legacy chemistries.
In North America, codes and test-and-enforcement rules are becoming more prescriptive and measurable. California Energy Commission adopted updated Title 24 Building Energy Efficiency Standards in 2024, with the 2025 standards effective January 1, 2026, and they elevate air-to-water heat pumps as a compliance path for new and renovated buildings. At the federal level, the US Department of Energy moved central air conditioner and heat pump testing to newer metrics (including SCORE/SHORE) with mandatory testing beginning July 7, 2025, and updated enforcement provisions under 10 CFR Part 429 scheduled to take effect July 7, 2026. Program rules are also sharpening eligibility, for example New York State Clean Heat published updated whole-building air-to-water heat pump eligibility requirements in May 2026 that specify COP performance thresholds for incentives.
Value Chain Analysis
The value chain spans upstream refrigerants and metals (copper and aluminum), core electromechanical components (inverter-driven compressors, heat exchangers, pumps, valves, fans), and electronics (power modules, sensors, embedded controls), through system integration (buffer tanks, hydronic accessories, domestic hot-water modules) and downstream channels. Downstream activities include OEM and wholesaler distribution, installer networks, commissioning, and after-sales service. Differentiation and risk concentrate in compressors and inverter or power electronics, where semiconductor availability and qualification cycles can constrain output. Copper price volatility also feeds through to cost pressure and longer lead times for coils and wiring.
Recent supply-chain moves highlight localization and partnership-led component security. Copeland and Daikin expanded their cooperation for Europe in December 2025 and began operating the expanded joint-venture scope in January 2026, targeting inverter swing rotary compressors and integrated controls for the European residential heat pump market. That move supports shorter lead times and tighter hardware-software integration for cold-climate and load-shifting performance. Separately, manufacturing footprints are being adjusted in response to local-content policy signals, with reports of Samsung Electronics and LG Electronics initiating relocation of heat pump production lines from China to South Korea during March 2026, reflecting how eligibility for domestic support programs can reshape sourcing, final assembly, and logistics for residential air-to-water platforms.
Competitive Landscape
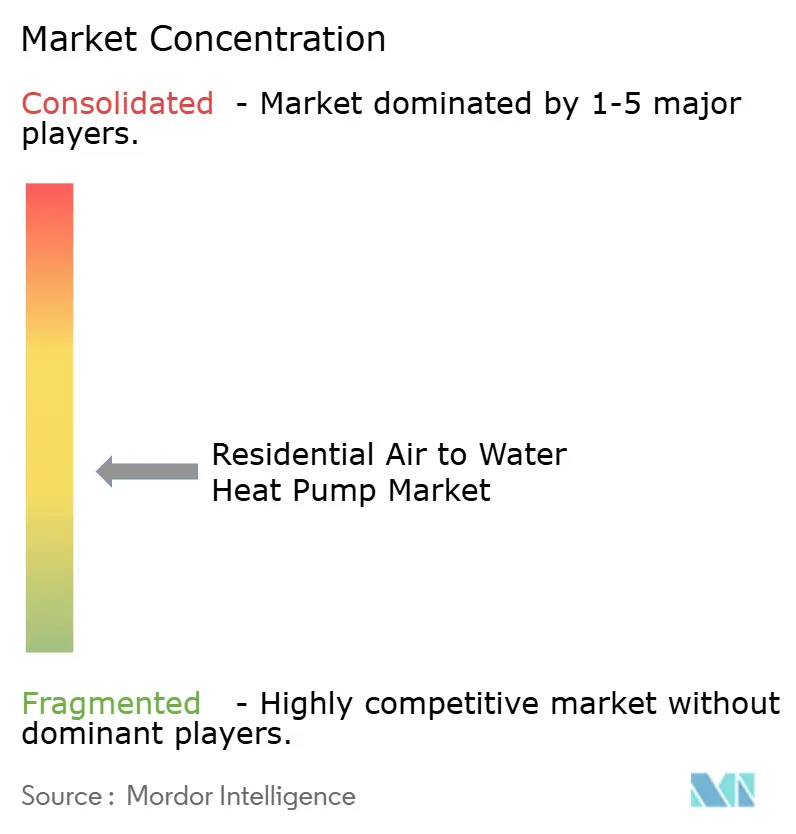
Competition is moderate: the top five vendors hold around 48% of shipments, signalling neither monopoly nor fragmentation. Carrier’s USD 13 billion Viessmann deal accelerates portfolio diversification toward hydronic solutions, while Bosch’s USD 8 billion purchase of Johnson Controls-Hitachi expands Asian reach. Daikin, long the global share leader, earmarks 30% European share by 2030 through expanded Polish and Czech plants.
Technological differentiation revolves around refrigerant choice, acoustic engineering and control ecosystems. Mitsubishi Electric leans on variable-speed compressor IP, now being localized in the United States. Trane and LG stress low-GWP credentials, securing early procurement preferences from green-mortgage lenders. Vaillant adds installer apps and predictive diagnostics, shifting value toward after-sales services within the residential air to water heat pump industry.
Strategic moves include capacity build-outs—Aira’s EUR 300 million Polish factory can output 500,000 units annually—and vertical integration into compressors and electronics to hedge component risk. Some players explore magnetocaloric prototypes that could eliminate synthetic refrigerants entirely, signalling disruptive potential beyond 2030. Private equity interest is rising in mid-tier regional assemblers, suggesting continued consolidation across the residential air to water heat pump market.
Residential Air To Water Heat Pump Industry Leaders
-
Daikin Industries Ltd
-
Mitsubishi Electric Europe B.V
-
Panasonic Corp.
-
Vaillant Group
-
NIBE Industrier AB
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
Regulatory and incentive design continues to create whitespace for products that simplify permitting, verification, and retrofit execution. California SB 282 (2025-2026 session) directs development of a standardized California Heat Pump Code Compliance Checklist for local jurisdictions by July 1, 2026, and this standardization favors OEMs and installers that can provide packaged documentation, commissioning workflows, and code-ready performance data. Incentive qualification is also getting more performance-specific, with New York State Clean Heat updated eligibility requirements for whole-building air-to-water heat pumps in 2026 that include explicit COP criteria, which raises the commercial value of verified cold-weather output and well-documented hydronic performance.
On the supply side, capacity additions and adjacent ecosystem entrants point to opportunities in higher-capacity hydronic retrofits and PV-coupled operation. Panasonic opened a dedicated production line at its Pilsen, Czech Republic factory in February 2026 for large-capacity Big Aquarea M Series air-to-water heat pumps, signaling focus on bigger residential loads and multi-dwelling applications served by hydronic distribution. In the residential energy ecosystem, GoodWe introduced PV-driven air-to-water heat pumps in June 2026, reinforcing a pathway for bundling heat pumps with inverters and home energy management. Product launches that emphasize natural refrigerants (R290 and R744) also align with the EU F-gas trajectory, which creates clearer space for installers and distributors that build competency around hydrocarbon and CO2 safety, training, and service readiness.
Recent Industry Developments
- July 2026: NIBE introduced the S2060 series of inverter-controlled monoblock air-to-water heat pumps using propane (R290) for residential and small commercial applications. The launch adds another mainstream OEM line built around natural refrigerants, supporting compliance-driven portfolio shifts and giving installers more choice in low-GWP hydronic retrofits.
- June 2026: Panasonic launched a residential CO2 (R744) air-to-water heat pump range in 4.0 kW and 6.0 kW sizes, reporting COP up to 6.1. CO2-based systems broaden the natural-refrigerant toolkit beyond propane, particularly for applications that prioritize domestic hot water performance and long-term refrigerant policy alignment.
- April 2026: Daikin launched the ALTHERMA 3 H HT air-to-water heat pump system, designed for high-temperature hydronic output and operation in cold ambient conditions. High flow-temperature capability supports boiler-replacement projects that aim to reuse existing radiators, which strengthens the retrofit value proposition for air-to-water systems.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers residential air-to-water heat pump systems sold for home space heating and domestic hot water, where outside air is used to heat water that circulates through hydronic indoor systems.
Scope exclusions: We exclude non-residential demand, and we also leave out air-to-air heat pumps and conventional boilers sold without an air-to-water heat pump unit.
Segmentation Overview
-
By Type
- Split Systems
- Monobloc Systems
- All-in-One Integrated
- Hybrid (HP + Boiler)
-
By Capacity (kW)
- Less than 10 kW
- 10 - 20 kW
- Greater than 20 kW
-
By Refrigerant
- R410A
- R32
- R290 (Propane)
- CO2 (R744)
-
By Application
- Single-Family Homes
- Multi-Family Residences
-
By Installation Type
- New Construction
- Retrofit / Replacement
-
By Geography
-
North America
- United States
- Canada
- Mexico
-
South America
- Brazil
- Argentina
- Rest of South America
-
Europe
- Germany
- France
- Italy
- United Kingdom
- Spain
- Rest of Europe
-
Middle East
- UAE
- Saudi Arabia
- Turkey
- Rest of Middle East
-
Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
-
Asia-Pacific
- China
- Japan
- South Korea
- Australia
- India
- Rest of Asia-Pacific
-
North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with building a clear demand and supply picture by country, since residential installations are shaped by policy, housing stock, and the availability of hydronic heating. We typically review public energy and heating statistics and policy trackers, using sources such as the International Energy Agency (IEA), Eurostat, the US Energy Information Administration (EIA), and national statistical offices.
To connect the market to real-world product movement, we also use trade and industry sources that discuss shipments, installed base, and efficiency standards, including customs and trade databases, heat pump association publications (for example, in Europe), and technical test and certification references. Company annual reports, investor presentations, and reputable business press are used to cross-check product mix, pricing direction, and channel strategy, and then selected paid subscriptions for company financials, patent checks, and import-export shipment-level signals help validate the direction of volumes and average selling prices. The desk research sources listed here are illustrative only, since many other public references and documents are also reviewed to collect, verify, and clarify data points.
Primary Interviews and Surveys
Primary interviews and structured surveys are used to pressure-test the desk assumptions and fill gaps that do not show up cleanly in public data, especially for residential retrofit activity and pricing by system configuration. We speak with a mix of manufacturers and component ecosystem participants, distributors, installers, and channel specialists across APAC, EMEA, and the Americas, and then reconcile differences in reported volumes, typical system sizes, and installed pricing before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 19% | APAC: 42% |
| Mid tier: 47% | Functional/Unit leaders: 33% | EMEA: 33% |
| Smaller Players: 19% | Managers: 48% | Americas: 25% |
Market-Sizing & Forecasting
For the core sizing, we reconstruct the addressable revenue pool using a top-down logic that starts from country-level residential heat pump adoption signals and then narrows it to air-to-water systems used with hydronic delivery. The totals are then corroborated using selective bottom-up checks, such as sampled ASP times unit volumes by major markets and channel checks on typical installed system value, which are used to adjust for places where published shipment signals are incomplete.
A few inputs that meaningfully move the model include the share of homes with hydronic heating, annual replacement and renovation rates, incentive coverage and eligibility rules, refrigerant transitions that affect product pricing, and the split between new-build and retrofit installs. Because heat pump demand is policy and weather sensitive, forecasting is done using scenario analysis supported by expert views, and then the chosen base case is aligned to observed program pipelines and housing activity. Where smaller markets have limited public volume visibility, gaps are handled with proxy adoption rates derived from comparable climates and building stocks, followed by an interview-led correction to avoid overstating early adoption.
Data Validation & Update Cycle
Validation is done through repeated cross-checks so that the final market value matches multiple independent signals, not just one data series. We compare implied units and pricing against installer feedback, policy uptake indicators, and the pace of residential hydronic retrofits, and then investigate outliers such as sudden price jumps or unusual country shares before sign-off.
A multi-step internal review is followed so assumptions, calculations, and scope are consistent across geographies and years. Reports are refreshed annually, and interim updates are made when major policy changes, supply disruptions, or sharp pricing shifts materially change the outlook. Before delivery, the analysis is re-checked so clients receive the most current view available at that time.
Mordor Intelligence's Residential Air to Water Heat Pump Market Size Compared Against Other Published Estimates
Published market numbers for residential air-to-water heat pumps can differ because teams pick different product boundaries, price points, and even different points in the installation value chain to count. In practice, gaps usually come from whether the estimate is equipment-only or includes installed system value, how hybrid systems are treated, and how quickly policy-driven demand changes are refreshed.
Some external figures fold in commercial air-to-water demand or count air-to-air heat pumps that are not connected to a hydronic loop. In Mordor Intelligence's model, revenues are counted only for residential air-to-water units and related system configurations, and totals are held in check using country adoption signals and interview-tested ASP progression instead of a single global average price.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 12.98 B (2026) | |
| Trade Journal A | USD 10.90 B (2026) | Often reported as equipment revenue only, with conservative ASP assumptions and limited adjustment for incentives that change mix toward higher-capacity systems. |
| Regional Consultancy B | USD 15.40 B (2026) | Commonly expands scope to include adjacent heat pump categories or partial non-residential demand, and sometimes applies uniform pricing and penetration rates across countries with different hydronic housing shares. |
The spread across the table is largely explained by what gets counted as in-scope revenue and how pricing and adoption are updated by market. When scope is kept residential and air-to-water specific, and key inputs like hydronic suitability, incentives, and ASPs are validated with field feedback, the resulting market size stays more repeatable and easier to track year to year.


Key Questions Answered in the Report
What is the current size of the residential air to water heat pump market?
The market is valued at USD 12.98 billion in 2026 and is projected to reach USD 16.93 billion by 2031.
Which region leads global demand for residential air-to-water units?
Europe holds 33.60% of global revenue, driven by mature hydronic infrastructure and strict decarbonization policy.
Why are hybrid heat pump and boiler systems growing so quickly?
They address homeowner concerns about backup heating during extreme cold and are expanding at a 8.83% CAGR through 2031.
How do government incentives affect adoption in North America?
US Inflation Reduction Act rebates of up to USD 8,000 remove upfront cost barriers, spurring a double-digit rebound in 2024 sales.
What role do natural refrigerants play in future growth?
R290 and R32 models meet upcoming F-Gas limits and improve efficiency, positioning early adopters for regulatory compliance and market share gains.
What challenges could slow near-term expansion?
Grid capacity constraints in dense suburbs and shortages of hydronic-skilled installers can delay projects and inflate costs, trimming the forecast CAGR by about 1 percentage point combined.
Page last updated on:





