
Philippines Pet Food Market Size and Share
Philippines Pet Food Market Analysis by Mordor Intelligence
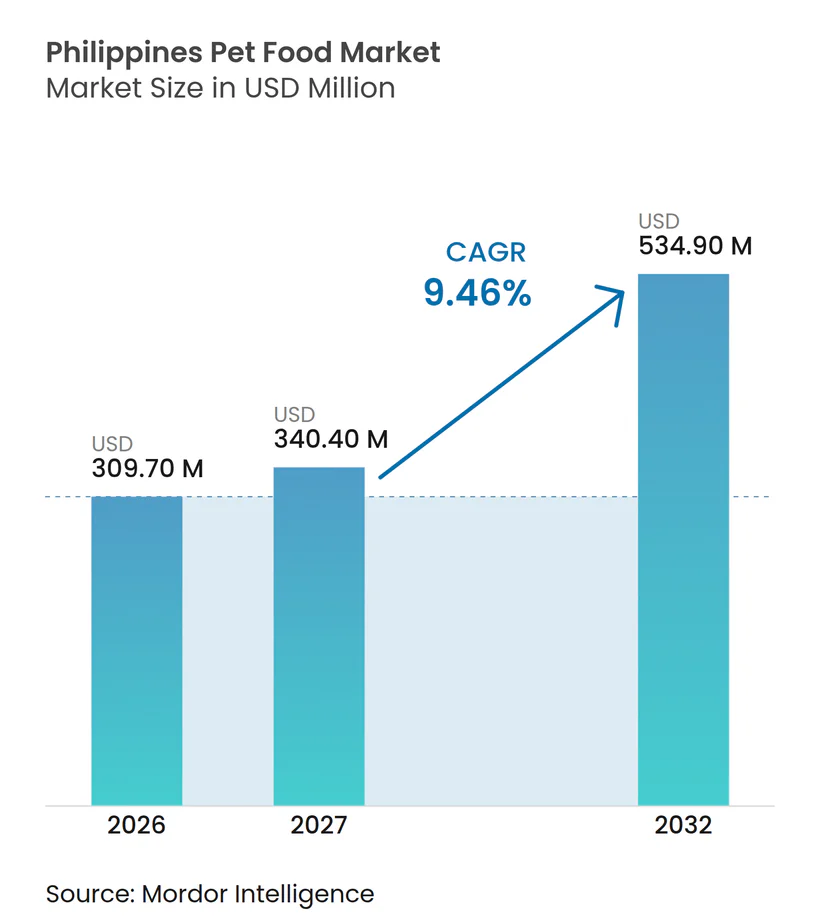
The Philippines pet food market size is projected to expand from USD 309.7 million in 2026 and USD 340.4 million in 2027 to USD 534.9 million by 2032, registering a CAGR of 9.46% between 2027 and 2032. The market volume is projected to expand from 111.5 thousand Metric Tons in 2026 and 118.6 thousand Metric Tons in 2027 to 161.7 thousand Metric Tons by 2032, registering a CAGR of 6.4% between 2027 and 2032.
Premium nutrition can raise spending per feeding occasion in the Philippines. Broader retail access gives expanding supplier portfolios another route to owners. Established groups answer with species-specific launches while newer brands offer dry-food pouches and bulk bags through regional distribution. Suppliers therefore compete for a place in daily feeding through pack-size choice and product assurance, as well as retail reach.
Key Report Takeaways
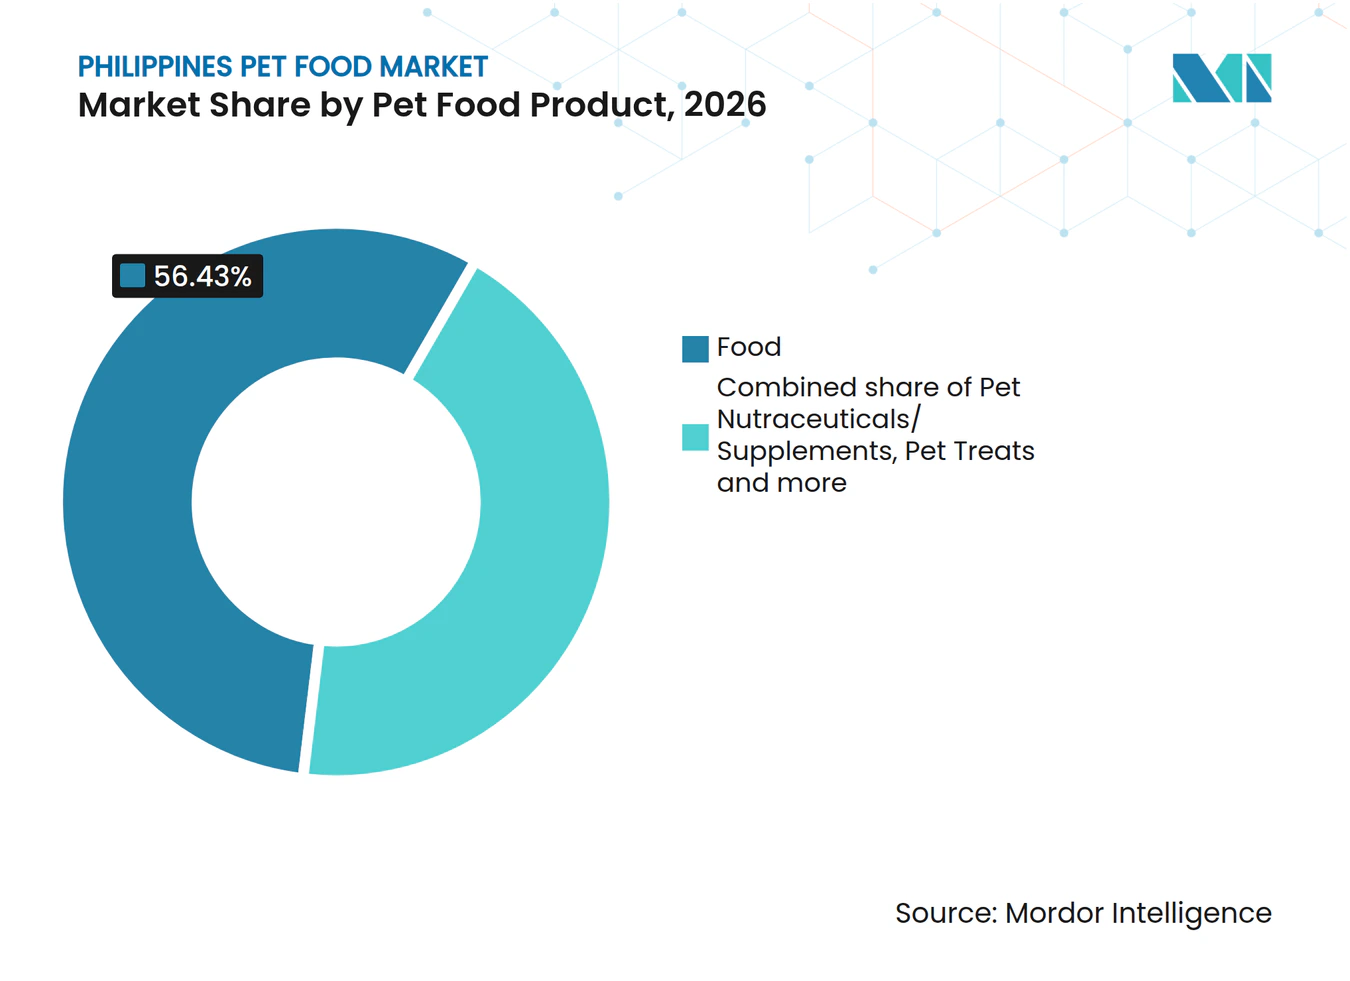
- By pet food product, food held a 56.43% Philippines pet food market share in 2026 and is forecast to be the fastest-growing segment, at a CAGR of 11.1% from 2027 to 2032.
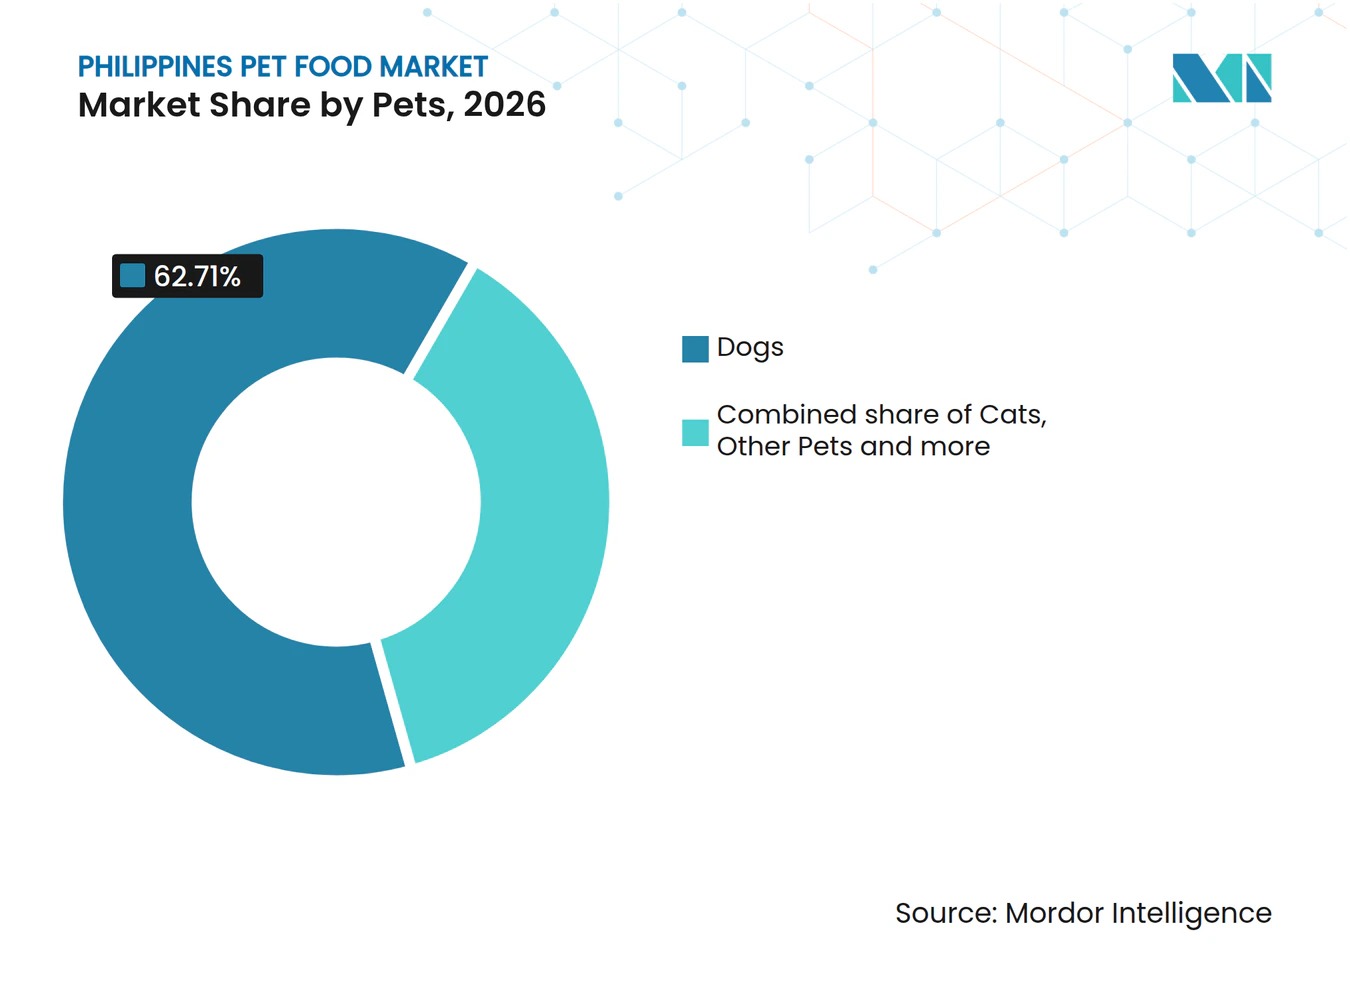
- Among pets, dogs accounted for a 62.71% share of the Philippines pet food market size in 2026 and are forecast to be the fastest-growing segment, with an 11.1% CAGR from 2027 to 2032.
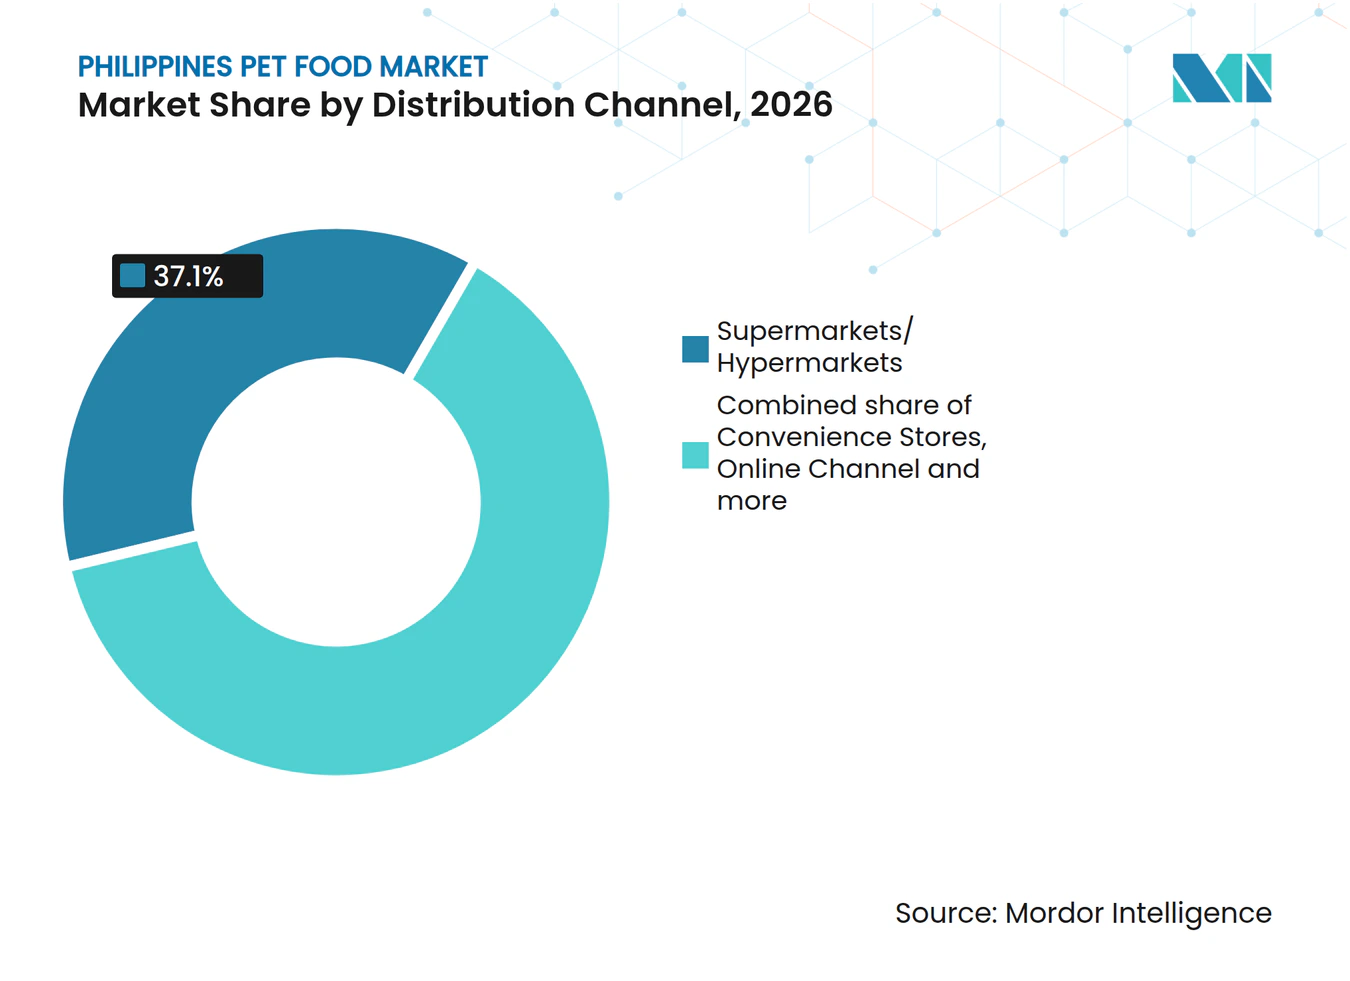
- Distribution channels were led by supermarkets/hypermarkets, with a 37.1% share of pet-food sales value in 2026, while the online channel is forecast to be the fastest-growing segment, at a CAGR of 11.1% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Philippines Pet Food Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising pet humanization and premium-nutrition spend | +4% | Nationwide | Medium term (2-4 years) |
| Expansion of modern retail and e-commerce | +3.2% | Nationwide | Short term (≤ 2 years) |
| Growing dog and cat population | +3% | Nationwide | Long term (≥ 4 years) |
| Feed-millers converting idle capacity into pet-food lines | +2.2% | Nationwide | Medium term (2-4 years) |
| Availability of veterinary tele-health and pet insurance | +0.9% | Quezon City and Metro Manila | Medium term (2-4 years) |
| Government incentive program for domestic meat by-product rendering | +0.5% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising pet humanization and premium-nutrition spend
Greater willingness to spend on pets creates an opening for nutrition suppliers beyond increasing feeding volumes. GlobalPETS reported in October 2025 that premiumization was fueling the Philippine pet industry, with more owners willing to spend on food and other essentials. For prepared-food suppliers, that willingness can support products differentiated by nutritional purpose rather than quantity alone. A higher-value food purchase can then increase supplier revenue without requiring an equivalent increase in the amount fed. Nutrition suppliers capture the uplift only when owners direct their additional pet-care spending into food.
Expansion of modern retail and e-commerce
Modern retail can give pet-food suppliers an additional route to sustained channel sales. Universal Robina Corporation reported that its pet-food sales in modern trade nearly doubled in 2025 versus 2024.[1] The result illustrates the commercial relevance of a modern-trade route for a supplier’s pet-food portfolio. An expanded route adds category demand when it brings commercial feeding to additional households or feeding occasions. Euromonitor data reported by GlobalPETS put Philippine pet-food retail e-commerce share at 7.2% in 2025, forecast from Q1, up from 5.7% in 2021. Rising online share alongside Universal Robina Corporation’s modern-trade sales result broadens the routes through which suppliers can develop prepared-food demand.
Growing dog and cat population
A larger dog and cat population expands the number of feeding occasions that prepared-food suppliers can serve. Euromonitor estimated 21.3 million dogs and 2.74 million cats in the Philippines in 2025, following population CAGRs of 4.7% and 5.2%, respectively, from 2021 to 2025. Its commercial effect depends on how many of those occasions involve purchased food, so animal numbers and packaged-food demand need not rise together. For dog- and cat-food brands, the additional feeding base creates room for entry-level products alongside more specialized diets. A food offer that becomes part of regular feeding can generate demand beyond the first trial purchase. Cat-food suppliers can address a population that grew faster in 2021 to 2025, alongside the larger potential audience for dog food.
Feed-millers converting idle capacity into pet-food lines
An integrated feed operator can extend its nutrition business into finished pet food by developing a distinct offering for pet owners. Universal Robina Corporation’s Animal Nutrition and Health segment paired its core animal-feeds business with an expanding pet-food portfolio in 2025. That diversification creates an additional commercial use for a business already active in animal nutrition. The pet-food offer must nevertheless earn its own place in the owner’s feeding choices, making consumer relevance a separate task from maintaining the broader feeds portfolio. More food options can support demand when they serve an additional feeding need.
Restraints Impact Analysis of Philippines Pet Food Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High price sensitivity and table-scrap feeding | -2.4% | Nationwide | Short term (≤ 2 years) |
| Lengthy Bureau of Animal Industry (BAI) product registration | -1.2% | Nationwide | Short term (≤ 2 years) |
| Counterfeit and gray-market products eroding trust | -0.5% | Nationwide | Medium term (2-4 years) |
| Low veterinarian density in Visayas and Mindanao | -0.3% | Visayas and Mindanao | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High price sensitivity and table-scrap feeding
Packaged pet food creates a recurring cash expense for owners choosing it as a regular diet. PSRC’s 2026 Worldviews Survey report said upper-income Philippine households chose packaged or branded food for pets, while lower-income households fed pets what was available to them. For a commercial-food supplier, that difference makes habitual use of packaged food a distinct challenge from simply reaching pet-owning households. An occasional purchase could coexist with other feeding choices, limiting the expenditure captured per pet. Premium nutrition has to earn a sufficiently important place in that routine to justify repeated spending, which makes value per meal commercially significant. A successful first trial leaves the continuing food bill to be met.
Lengthy Bureau of Animal Industry (BAI) product registration
Product-registration preparation adds technical and laboratory work to a supplier’s cost of introducing pet food. The third edition of BAI’s 2024 Citizen’s Charter requires technical product descriptions, manufacturing process flows, and certificates of analysis for locally manufactured feed products and imported feeds other than grains. Permitted analysis sources include BAI’s Veterinary Laboratory Division Chemical and Feed Analysis Section, DA regional feed chemical analysis laboratories, other government laboratories, and BAI-recognized third-party, company-owned, or in-house laboratories. A supplier proposing several products must therefore prepare the technical and analytical material for each submission. Expanding the range increases this product-level preparation burden alongside the cost of making the food.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Philippines Pet Food Market Segment Analysis
By Pet Food Product:
Core Feeding Supports ExpansionFood accounted for a 56.43% share of the Philippines pet food market size in 2026 and is forecast to be the fastest-growing segment, at a CAGR of 11.1% from 2027 to 2032. Century Pacific Food reported that its pet-food business doubled in size in 2025.[2] The company linked that result to the growing place of pets in Filipino homes. Century Pacific Food also described affordable, quality pet-food options across an expanding range for Filipino consumers. Sustaining the expansion would require its food to remain part of household meals after the first purchase.
CPPETINDO’s BOLT range in the Philippines included dry dog food and dry and wet cat food in September 2026, with retail pouches and bulk bags available. Retail-size options can let owners choose how much prepared food to commit to at once. Small pouches offer a limited initial commitment, while bulk bags accommodate a longer feeding routine. The dry and wet cat-food options also make formulation choice separate from pack quantity, giving suppliers two dimensions on which to position a daily diet. That flexibility can support adoption of a core diet without requiring a single pack format to suit every household.



By Pets:
Canine Care Creates a Broad Feeding AudienceDogs represented a 62.71% Philippines pet food market share in 2026 and are forecast to be the fastest-growing segment, at a CAGR of 11.1% from 2027 to 2032. In PSRC’s January 2026 nationwide survey, 71% of Filipino pet-owning respondents reported having a dog in their household. That widespread ownership provides a broad potential buyer base for dog-specific nutrition. For suppliers, an ownership audience identifies homes to address, while a prepared-food offer determines which of those homes’ feeding occasions can become sales. For the largest segment, suppliers can develop demand around the everyday diet of an animal already present in many pet-owning homes.
Bacolod City’s City Veterinarian’s Office vaccinated around 80,000 dogs in the city in 2025.[3] Bacolod City announced an expanded target to vaccinate at least 100,000 dogs in the city in 2026 through its public anti-rabies program. Such program scale can identify a local setting where dog-specific nutrition education may be relevant. A supplier could use canine-care education to explain feeding choices, while keeping a separately explained commercial food offer distinct from the public program’s disease-prevention purpose. Prepared-diet adoption determines how much of that canine-care audience can become commercial food demand.

By Distribution Channel:
Grocery Reach Meets Digital Product AssuranceSupermarkets/hypermarkets were the largest segment, accounting for 37.1% of pet-food sales value in 2026. On December 16, 2025, Robinsons Supermarket relaunched its Robinsons Galleria branch with an expanded pet-care zone carrying pet food, treats, grooming products, and supplies for dog and cat owners. A supermarket can place a pet-food choice within an existing grocery shopping route, giving suppliers a way to serve routine household food decisions. A dedicated pet-food offer inside a general supermarket can expand access without requiring a separate specialist-store trip.
The online channel is forecast to be the fastest-growing segment, at a CAGR of 11.1% from 2027 to 2032. Euromonitor data reported by GlobalPETS indicated that Philippine pet-food retail e-commerce share had a relative increase of about 26.3% from 2021 to 2025, with 2025 forecast from Q1. In June 2025, BAI said various pet products found on online platforms and at other pet-supply and feed establishments lacked proper certification and had unidentified suppliers. In June 2025, Petsup PH said its freeze-dried food for dogs and cats was BAI-certified and that it had posted 4 BAI feed-product registration certificates. As online adoption expands, product assurance involves connecting a registration claim with the specific food and supplier behind an offer.
Geography Analysis
Metro Manila serves as a market-entry location for imported dog and cat food. CPPETINDO’s BOLT brand entered the metropolitan market with cat and dog food products for Filipino pet owners. In September 2025, Aboitiz Foods described its portfolio, including Maxime pet food, as supplying households and retailers in Central Luzon. For a supplier, the metropolitan entry involves introducing a named pet-food range, while the Central Luzon example places pet food within a multi-category supply relationship. A pet-food entrant must therefore distinguish winning attention for an unfamiliar brand from securing a place within a retailer’s wider supplier relationships.
Visayas and Mindanao provided an earlier regional base for BOLT’s Philippine business, with CPPETINDO’s dog and cat food brand having focused on the 2 island groups for 3 years before September 2026. A.D. Gothong Manufacturing Corporation is the brand’s exclusive Philippine importer. For buyers in these island groups, an exclusive-importer arrangement makes the local intermediary’s commercial reach relevant to access alongside the overseas manufacturer’s food range. The sequence also shows why a Metro Manila launch need not be the first Philippine commercial step for an imported food range, making the prior regional route relevant when assessing a brand’s entry strategy.
Veterinary service coverage creates a different commercial consideration within the Visayas. Cebu Province reported in 2026 that only 4 of its 25 first-class municipalities had permanently hired veterinarians. It also reported consultants in 2 of the 25 first-class municipalities. For nutrition businesses whose food offers depend on professional guidance, that municipal staffing gap can constrain access to advice even when a supplier can deliver the product to a local seller. A supplier entering these municipalities would need to connect its veterinary-diet offer with a qualified referral route, making the advisory channel a separate consideration from the physical movement of food.
Regulatory Framework and Outlook
This comparison of selected jurisdictions considers domestic manufacturers of wet and dry dog and cat food under the national framework and in Cebu Province. For locally manufactured feed products, DA Regional Field Office VII requires proposed labels, samples of at least 500 grams per product for BAI analysis, and an approved establishment license. The Bureau of Agriculture and Fisheries Standards (BAFS) standard PNS/BAFS 140:2014 addresses labeling for manufactured wet and dry dog and cat food. BAFS says its standards are voluntary unless adopted into technical regulations or sanitary and phytosanitary measures, making legal adoption distinct from the existence of a labeling benchmark.
Regulatory Table of Philippines Pet Food Market
| Decision factor | Philippines | Cebu Province |
|---|---|---|
| Primary authority | Bureau of Animal Industry | Bureau of Animal Industry under the national framework |
| Key instruments or direction | Feed-product registration framework; PNS/BAFS 140:2014 labeling benchmark | National feed-product registration framework and labeling benchmark |
| Commercial effect | Prepare technical, process, analysis, label and sample materials for registration | The same national product-preparation responsibilities |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
Medium reflects the documentation and sample burden domestic manufacturers must meet under the national registration framework. Cebu Province receives the same assessment because DA Regional Field Office VII endorses initial applications to BAI and handles renewals under that shared framework. BAI administers the product-registration procedure set out in its 2024 Citizen’s Charter, and the regional service has no announced transition. Those operative responsibilities support the No change outlook for domestic product preparation in both comparison columns.
Value Chain Stages
The value chain compares how ingredient suppliers, food manufacturers, distributors, and retailers earn from different operating responsibilities. Terrafeed sources and manufactures ingredients for bird and pet food, placing a specialized supplier before the finished-food stage. Century Pacific Food’s broader manufacturing, marketing, and distribution activities include pet food, illustrating how a food company can span several responsibilities.
Value Chain Analysis Table of Philippines Pet Food Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Ingredient sourcing and preparation | Ingredient sourcers and manufacturers such as Terrafeed | Ingredient sales | Matching ingredient consistency to the intended food formula | Qualify ingredients against the formula before substitution |
| Finished-food manufacturing | Food manufacturers such as Century Pacific Food, Inc. | Finished-food sales | Reproducing formulation and batch consistency at scale | Link batch controls to the chosen recipe |
| Trade distribution | Pet-product distributors such as Pet Discount Inc. and Petwarehouse, Inc., trading as Walt & Buddy | Wholesale resale earnings | Coordinating brand supply with nationwide trade accounts | Align delivery routes with trade-customer coverage |
| Retail sale to pet owners | Specialty retailers such as Pet Express and Robinsons Retail Holdings’ franchised Pet Lovers Centre; online retailers such as Pet Warehouse | Retail resale earnings | Serving buyers through different store and delivery formats | Match the sales format and delivery offer to the service area |
| Source: Mordor Intelligence | ||||
Petwarehouse, Inc. combines trade distribution under Walt & Buddy with online food retail through Pet Warehouse. Walt & Buddy delivers to stores, retail chains, veterinarians, and groomers using its own fleet, while Pet Warehouse offers nationwide online delivery. For this operator, wholesale and retail resale earnings depend on whether the food is sold to a trade customer or directly to an owner. A brand supplied through both routes could reach owners without relying entirely on securing local specialty-store listings.
Competitive Landscape
Market Concentration
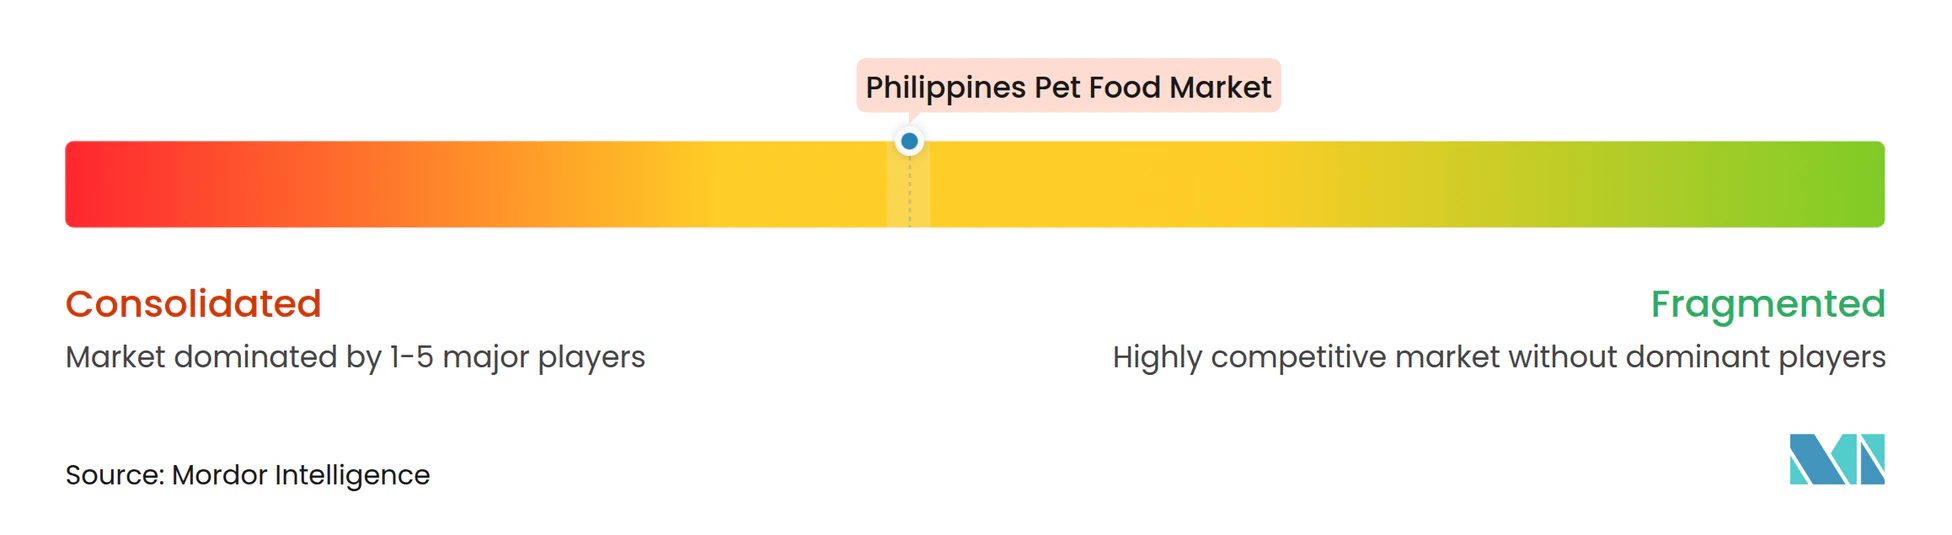
Competition is moderately concentrated around established branded groups, with major companies including Mars, Incorporated, Colgate-Palmolive Company (Hill’s Pet Nutrition, Inc.), Charoen Pokphand Group Company Limited (Perfect Companion Group Co., Ltd.), General Mills, Inc. (Blue Buffalo Pet Products, Inc.), and Nestlé Purina PetCare (Nestlé S.A.). Purina Philippines offers cat food under the FELIX, Fancy Feast, Friskies and Purina ONE brands. Mars Petcare markets Pedigree dog food in the Philippines, while Perfect Companion Philippines Corporation, a Charoen Pokphand Group affiliate, manufactures dog and cat food. These roles put a dedicated dog-food brand alongside an affiliate manufacturing for both species, giving entrants distinct established supplier models to challenge.
Globally, Hill’s Pet Nutrition reported net sales growth of 3.4% and organic sales growth of 2.1% in Q2 2026 versus Q2 2025, with higher pricing and lower reported volume. Reported volume included a positive 0.6% contribution from the Prime100 acquisition. Pricing added 3.9% while organic volume fell 1.8%, making price acceptance and the acquired contribution distinct from organic unit expansion. In the Philippines, Century Pacific Food described Goodest brand-building and pet-expo participation in November 2025 intended to generate awareness and trial as it pursued pet-food growth.
Competitive direction shows in species-specific extensions by established groups. Nestlé Purina Philippines introduced Friskies Dog dry food at a launch event held at the Glorietta Activity Center in Manila on May 16, 2026. Nestlé’s global PetCare category reported 2.7% organic growth in H1 2026, driven by continued strength in cat and improved dog performance in Q2. Dog-food challengers face Mars Petcare’s Pedigree alongside the Friskies extension, while cat-food entrants encounter Nestlé’s multibrand portfolio. BAI’s 2024 charter gives eligible license-holding feed businesses a stated 20-day product-registration process, adding a regulatory step alongside species-specific competition.
Philippines Pet Food Industry Leaders
-
Mars, Incorporated
-
Colgate-Palmolive Company (Hill’s Pet Nutrition, Inc.)
-
Charoen Pokphand Group Company Limited (Perfect Companion Group Co., Ltd.)
-
General Mills, Inc. (Blue Buffalo Pet Products, Inc.)
-
Nestlé Purina PetCare (Nestlé S.A.)
- *Disclaimer: Major Players sorted in no particular order
Philippines Pet Food Market Companies Covered in this Report
- Mars, Incorporated
- Nestlé Purina PetCare (Nestlé S.A.)
- Colgate-Palmolive Company (Hill’s Pet Nutrition, Inc.)
- Archer Daniels Midland Company
- DSM-Firmenich AG
- Zoetis Inc.
- Kemin Industries, Inc.
- Alltech, Inc.
- Virbac SA
- San Miguel Foods, Inc.
- General Mills, Inc. (Blue Buffalo Pet Products, Inc.)
- Wellness Pet Company (Clearlake Capital Group, L.P.)
- Charoen Pokphand Group Company Limited (Perfect Companion Group Co., Ltd.)
- Cargill, Incorporated
- DoggyMan H.A. Co., Ltd.
- Universal Robina Corporation (JG Summit Holdings, Inc.)
- Schell & Kampeter, Inc. (Diamond Pet Foods)
Recent Industry Developments in Philippines Pet Food Market
- Sep 2026: CPPETINDO extended BOLT’s existing Philippine presence by launching its cat and dog food products in Metro Manila on September 11.
- Jul 2026: Pet Lovers Centre opened its 12th Philippine store at Opus Mall on July 24, adding frozen pet food, premium treats, and guidance on specialized veterinary diets.
- May 2026: Nestlé Purina Philippines introduced Friskies Dog at a launch event held at the Glorietta Activity Center on May 16.
Scope and Methodology
| Food | By Sub-Product | Dry Pet Food | Kibbles |
| Other Dry Pet Food | |||
| Wet Pet Food | |||
| Pet Nutraceuticals/Supplements | By Sub-Product | Milk Bioactives | |
| Omega-3 Fatty Acids | |||
| Probiotics | |||
| Proteins and Peptides | |||
| Vitamins and Minerals | |||
| Other Nutraceuticals | |||
| Pet Treats | By Sub-Product | Crunchy Treats | |
| Dental Treats | |||
| Freeze-dried and Jerky Treats | |||
| Soft and Chewy Treats | |||
| Other Treats | |||
| Pet Veterinary Diets | By Sub-Product | Diabetes | |
| Digestive Sensitivity | |||
| Oral Care Diets | |||
| Renal | |||
| Urinary Tract Disease | |||
| Obesity Diets | |||
| Derma Diets | |||
| Other Veterinary Diets |
| Cats |
| Dogs |
| Other Pets |
| Convenience Stores |
| Online Channel |
| Specialty Stores |
| Supermarkets/Hypermarkets |
| Other Channels |
| By Pet Food Product | Food | By Sub-Product | Dry Pet Food | Kibbles |
| Other Dry Pet Food | ||||
| Wet Pet Food | ||||
| Pet Nutraceuticals/Supplements | By Sub-Product | Milk Bioactives | ||
| Omega-3 Fatty Acids | ||||
| Probiotics | ||||
| Proteins and Peptides | ||||
| Vitamins and Minerals | ||||
| Other Nutraceuticals | ||||
| Pet Treats | By Sub-Product | Crunchy Treats | ||
| Dental Treats | ||||
| Freeze-dried and Jerky Treats | ||||
| Soft and Chewy Treats | ||||
| Other Treats | ||||
| Pet Veterinary Diets | By Sub-Product | Diabetes | ||
| Digestive Sensitivity | ||||
| Oral Care Diets | ||||
| Renal | ||||
| Urinary Tract Disease | ||||
| Obesity Diets | ||||
| Derma Diets | ||||
| Other Veterinary Diets | ||||
| By Pets | Cats | |||
| Dogs | ||||
| Other Pets | ||||
| By Distribution Channel | Convenience Stores | |||
| Online Channel | ||||
| Specialty Stores | ||||
| Supermarkets/Hypermarkets | ||||
| Other Channels | ||||
Market Definition
- FUNCTIONS - Pet foods are usually intended to provide complete and balanced nutrition to the pet but are primarily used as functional products. The scope includes the food and supplements consumed by pets including veterinary diets. Supplements/nutraceuticals that are directly supplied to pets are considered within the scope.
- RESELLERS - Companies engaged in reselling of pet food without value addition have been excluded from the market scope, in order to avoid double counting.
- END CONSUMERS - Pet owners are considered to be the end-consumers in the market studied.
- DISTRIBUTION CHANNELS - Supermarkets/hypermarkets, specialty stores, convenience stores, online channels and other channels are considered within the scope. The stores which are exclusively providing pet related basic and custom products are considered within the scope of specialty stores.
| Keyword | Definition |
|---|---|
| Pet Food | The scope of pet food includes the food that is eatable by pets including food, treats, veterinary diets, and nutraceuticals/supplements. |
| Food | Food is animal feed intended for consumption by pets. It is formulated to provide essential nutrients and meet the dietary needs of various types of pets, including dogs, cats, and other animals. These are generally segmented into dry and wet pet foods. |
| Dry Pet Food | Dry pet foods may be extruded/baked (kibbles) or flaked. They have a lower moisture content, typically around 12-20%. |
| Wet Pet Food | Wet pet food, also known as canned pet food or moist pet food, generally has a higher moisture content compared to dry pet food, often ranging from 70-80%. |
| Kibbles | Kibbles are dry, processed pet food in small, bite-sized pieces or pellets. They are specifically formulated to provide balanced nutrition for various domestic animals, such as dogs, cats, and other animals. |
| Treats | Pet Treats are special food items or rewards given to pets, to show affection, and encourage good behavior. They are especially used during training. Pet treats are made from various combinations of meat or meat-derived materials with other ingredients. |
| Dental Treats | Pet dental treats are specialized treats that are formulated to promote good oral hygiene in pets. |
| Crunchy Treats | It is a type of pet treat that has a firm and crispy texture which can be a good source of nutrition for pets. |
| Soft and chewy treats | Soft and Chewy pet treats are a type of pet food product that is formulated to be easy to chewy and digest. They are usually made from soft and pliable ingredients, such as meat, poultry, or vegetables, that have been blended and formed into bite-sized pieces or strips. |
| Freeze-dried & Jerky Treats | Freeze-dried and jerky treats are snacks given to pets, that are prepared through a special preservation process, without damaging the nutritional content, resulting in long-lasting, nutrient-rich treats. |
| Urinary Tract Disease Diets | These are commercial diets that are specifically formulated to promote urinary health and reduce the risk of urinary tract infections and other urinary problems. |
| Renal Diets | These are specialized pet foods formulated to support the health of pets with kidney disease or renal insufficiency. |
| Digestive Sensitivity Diets | Digestive-sensitive diets are specially formulated to meet the nutritional needs of pets with digestive issues such as food intolerances, allergies, and sensitivities. These diets are designed to be easily digestible and to reduce the symptoms of digestive problems in pets. |
| Oral Care Diets | Oral care diets for pets are specially formulated diets produced to promote oral health and hygiene in pets. |
| Grain-Free Pet Food | Pet food that does not contain common grains like wheat, corn, or soy. Grain-free diets are often preferred by pet owners seeking alternative options or if their pets have specific dietary sensitivities. |
| Premium Pet Food | High-quality pet food formulated with superior ingredients often offers additional nutritional benefits compared to standard pet food. |
| Natural Pet Food | Pet food made from natural ingredients, with minimal processing and without artificial preservatives. |
| Organic Pet Food | Pet food is produced using organic ingredients, free from synthetic pesticides, hormones, and genetically modified organisms (GMOs). |
| Extrusion | A manufacturing process used to produce dry pet food, where ingredients are cooked, mixed, and shaped under high pressure and temperature. |
| Other Pets | Other pets include birds, fish, rabbits, hamsters, ferrets, and reptiles. |
| Palatability | The taste, texture, and aroma of pet food influence its appeal and acceptance by pets. |
| Complete and Balanced Pet Food | Pet food that provides all essential nutrients in appropriate proportions to meet the nutritional needs of pets without additional supplementation. |
| Preservatives | These are the substances that are added to pet food to extend its shelf life and prevent spoilage. |
| Nutraceuticals | Food products that offer health benefits beyond basic nutrition, often contain bioactive compounds with potential therapeutic effects. |
| Probiotics | Live beneficial bacteria that promote a healthy balance of gut flora, supporting digestive health and immune function in pets. |
| Antioxidants | Compounds that help neutralize harmful free radicals in the body, promoting cellular health and supporting the immune system in pets. |
| Shelf-Life | The duration of which pet food remains safe and nutritionally viable for consumption after its production date. |
| Prescription diet | Specialized pet food formulated to address specific medical conditions under veterinary supervision. |
| Allergen | A substance that can cause allergic reactions in some pets, leading to food allergies or sensitivities. |
| Canned food | Wet pet food that is packed in cans and contains higher moisture content than dry food. |
| Limited ingredient diet (LID) | Pet food formulated with a reduced number of ingredients to minimize potential allergens. |
| Guaranteed Analysis | The minimum or maximum levels of certain nutrients present in pet food. |
| Weight management | Pet food designed to help pets maintain a healthy weight or support weight loss efforts. |
| Other Nutraceuticals | It includes prebiotics, antioxidants, digestive fiber, enzymes, essential oils and herbs. |
| Other Veterinary Diets | It includes weight management diets, skin and coat health, cardiac care, and joint care. |
| Other Treats | It includes rawhides, mineral blocks, lickables, and catnips. |
| Other Dry Foods | It includes cereal flakes, mixers, meal toppers, freeze-dried foods, and air-dried foods. |
| Other Animals | It includes birds, fish, reptiles, and small animals (rabbits, ferrets, hamsters). |
| Other Distribution Channels | It includes veterinary clinics, local unregulated stores, and feed and farm stores. |
| Proteins and Peptides | Proteins are large molecules composed of basic units called amino acids which help in the growth and development of pets. Peptides are the short string of 2 to 50 amino acids. |
| Omega-3 fatty acids | Omega-3 fatty acids are essential polyunsaturated fats that play a crucial role in the overall health and well-being of Pets |
| Vitamins | Vitamins are the essential organic compounds that are essential for vital physiological functioning. |
| Minerals | Minerals are naturally occurring inorganic substances that are essential for various physiological functions in pets. |
| CKD | Chronic Kidney Disease |
| DHA | Docosahexaenoic Acid |
| EPA | Eicosapentaenoic Acid |
| ALA | Alpha-linolenic Acid |
| BHA | Butylated Hydroxyanisol |
| BHT | Butylated Hydroxytoluene |
| FLUTD | Feline Lower Urinary Tract Disease |
Research Methodology
Mordor Intelligence follows a four-step methodology in all our reports.
- Step-1: IDENTIFY KEY VARIABLES: In order to build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built on the basis of these variables.
- Step-2: Build a Market Model: Market-size estimations for the forecast years are in nominal terms. Inflation is not a part of the pricing, and the average selling price (ASP) is kept constant throughout the forecast period.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms


