
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 6.76 Billion |
| Market Size (2026) | USD 6.82 Billion |
| Market Size (2031) | USD 7.11 Billion |
| Growth Rate (2026 - 2031) | 0.84 % |
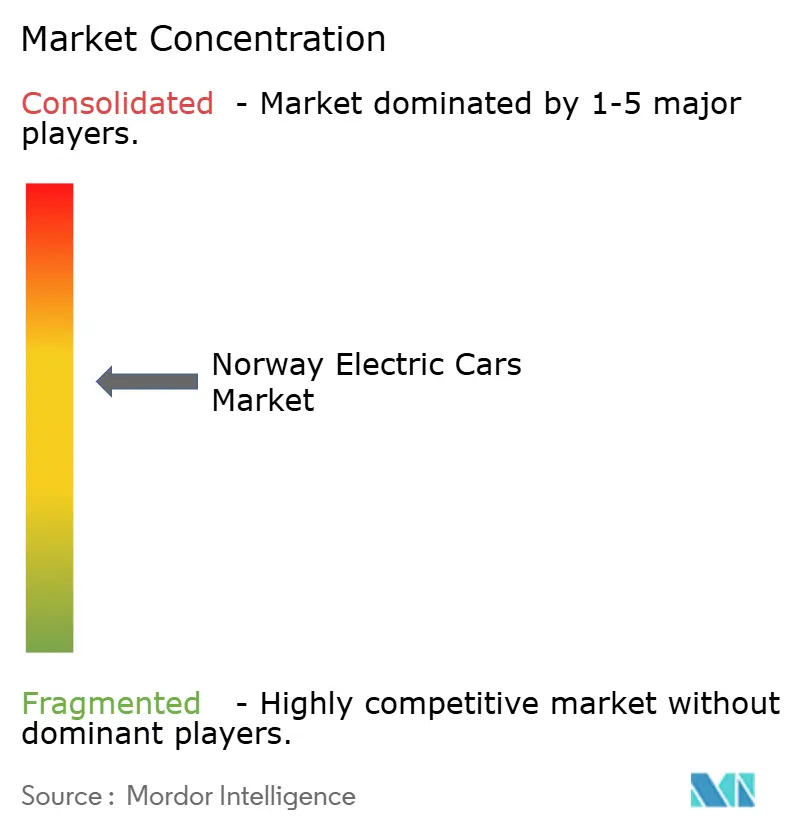
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Norway Electric Car Market Analysis by Mordor Intelligence
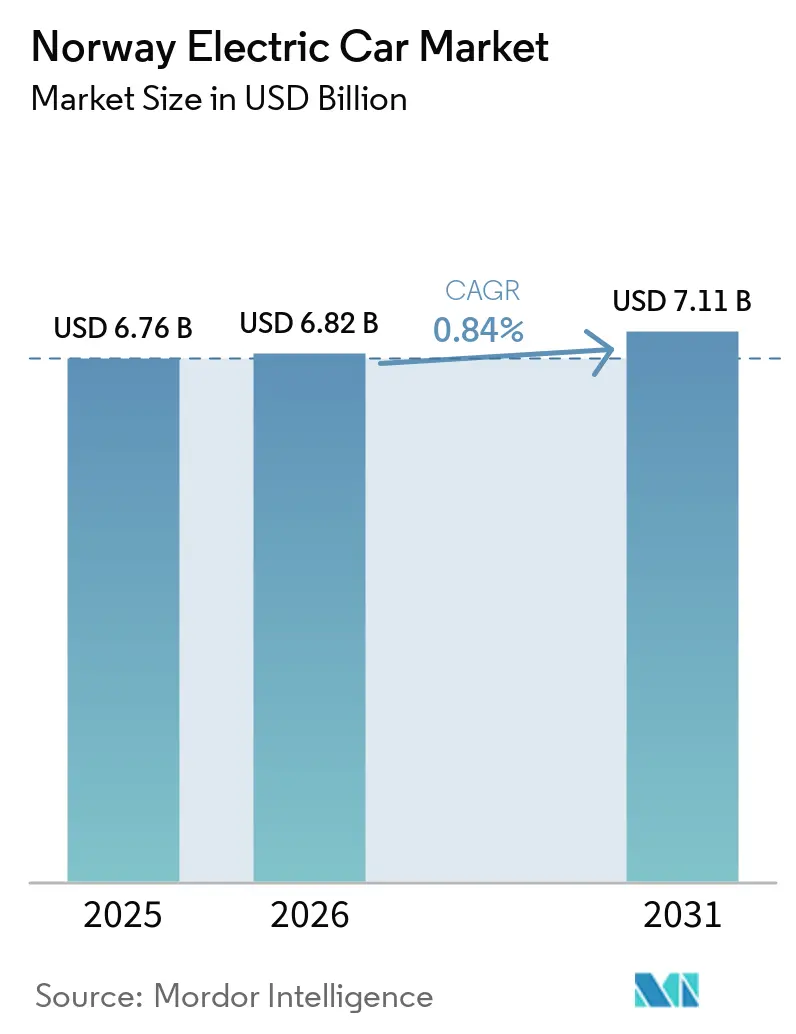
The Norway electric car market was valued at USD 6.76 billion in 2025 and is estimated to grow from USD 6.82 billion in 2026 to reach USD 7.11 billion by 2031, at a CAGR of 0.84% during the forecast period (2026-2031). The market retains a significant battery-electric vehicle share of new car sales, indicating market maturity rather than a retreat. Structural tailwinds still underpin demand, including ultra-fast-charging corridor investments, the spread of zero-emission zones, and a growing fleet ready for second-hand replacements. At the same time, the phased return of VAT on higher-priced EVs, rising insurance premiums, and grid bottlenecks in rural regions are trimming transaction values and slowing first-time adoption. Chinese brands that undercut European incumbents have injected new price competition, while domestic LFP cell production promises to localize battery supply, easing cost pressures. The strategic focus is now shifting from outright volume growth to sustaining fleet turnover, maximizing vehicle-to-grid revenues, and upgrading existing owners to longer-range or faster-charging models.
Key Report Takeaways
- By powertrain, battery electric vehicles captured 84.12% of the Norwegian electric car market share in 2025; fuel cell electric vehicles are forecast to post the fastest 4.12% CAGR through 2031.
- By vehicle type, sport-utility vehicles/crossovers led with 46.33% revenue share in 2025; the same segment is projected to advance at a 1.75% CAGR to 2031.
- By battery chemistry, Lithium Nickel Manganese Cobalt Oxide (NMC) packs accounted for 65.25% share of the Norwegian electric cars market size in 2025; lithium iron phosphate (LFP) cells are expected to grow at a 1.48% CAGR over the same horizon.
- By motor architecture, permanent-magnet synchronous motors held a 73.02% share in 2025, and they remain the fastest-expanding design with a 2.05% CAGR to 2031.
- By range, mid-range models (200–400 km) dominated with a 49.13% share in 2025, whereas the long-range cohort (400–600 km) will record a 3.45% CAGR through 2031.
- By voltage, 400-800 V platforms comprised 59.22% of 2025 sales; architectures above 800 V are set to rise at a 2.51% CAGR on the back of 600 kW charger roll-outs.
- By region, Eastern Norway led with a 38.16% share in 2025; Western Norway is the fastest-growing region with a 3.01% CAGR anticipated through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Norway Electric Car Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surge in Chinese OEM Imports | +0.4% | Rural and Northern price-sensitive areas | Short term (≤2 years) |
| Rising Grid Capacity for Corridors | +0.3% | E6, E18, E39 highway network | Medium term (2–4 years) |
| Expansion of Zero-Emission Zones | +0.2% | Oslo, Bergen, Trondheim, Stavanger | Short term (≤2 years) |
| Corporate Car-Tax Incentives | +0.2% | Major business districts | Medium term (2–4 years) |
| Vehicle-to-Grid Pilot Monetization | +0.1% | Oslo, Trondheim, Stavanger | Long term (≥4 years) |
| Lower Lifetime Toll and Ferry Fees | +0.1% | Western and Northern Norway ferry routes | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Surge in Chinese OEM Imports Lowering BEV Entry Prices
In the first half of 2025, BYD, NIO, Xpeng, and SAIC's MG brand collectively gained a notable presence in the market, driven by tariff-free access and competitive pricing strategies compared to their European counterparts. BYD's Seal offers a long-range battery pack and is positioned as a strong competitor to Tesla's Model 3, providing additional benefits such as an extended warranty to attract consumers. NIO’s battery-as-a-service lets buyers decouple battery ownership, trimming the purchase price and spreading energy costs through monthly swaps at several Nordic and continental stations. The influx is forcing incumbents to slash margins or pivot toward local LFP sourcing. Consumers benefit through broader choice and lower entry barriers, sustaining turnover even in a flatlining aggregate market.
Rising Grid Capacity for Ultra-Fast Charging Corridors
Statnett is making significant investments to enhance transmission lines along key corridors through 2035, enabling the deployment of high-capacity chargers at regular intervals and addressing rural range anxiety. In December 2025, IONITY became the first CPO to introduce 500 kW ultra-fast chargers in Norway. The company also revealed its plan to launch 600 kW units in partnership with Italian company Alpitronic, with which it has already signed an agreement. However, in areas north of the Arctic Circle, distribution grid limitations restrict the number of high-rate charging stalls per substation. As a result, automakers are prioritizing the development of vehicles with extended winter ranges until grid upgrades are completed. Strengthening the grid will not only improve its capacity but also unlock opportunities for vehicle-to-grid income generation. A pilot project has already demonstrated the potential for vehicles to contribute to the energy market while generating additional revenue. These infrastructure upgrades are essential to support ongoing replacement demand, even as overall market volumes stabilize.
Expansion of Zero-Emission Zones in Major Norwegian Cities
Oslo, Bergen, and Trondheim are implementing access restrictions that bar ICE vehicles and many plug-in hybrids from city centers during peak hours. In Oslo, BEV drivers enjoy significant toll savings, highlighting the effectiveness of these access rules in promoting the shift away from traditional vehicles. Bergen is introducing a new zone near the Bryggen waterfront, where non-compliant vans could face substantial fines. This move is accelerating the electrification of urban logistics fleets. Meanwhile, in Trondheim, where students once gravitated towards budget-friendly ICE hatchbacks, the new regulations are steering demand towards more affordable Chinese BEVs, which offer a cost advantage over their European counterparts. Additionally, these access zones are diminishing the residual values of plug-in hybrids, encouraging households to transition to longer-range BEVs instead of reverting to traditional combustion models.
Corporate Car-Tax Incentives for Electric Company Fleets
In Norway, employer-provided cars come with tax implications. Battery electric vehicles (BEVs) enjoy a tax break, with their taxable value set lower compared to gasoline vehicles. This preferential treatment continues for a few more years, but the discount will gradually decrease and eventually be phased out. As a result, leasing firms are hurrying to place orders and benefit from the more substantial relief. In major cities, corporate buyers now represent a significant portion of electric vehicle registrations, a figure expected to grow as companies refresh their car fleets. Additionally, reduced employer social charges and accelerated tax depreciation have nearly eliminated the cost disparity between BEVs and diesel sedans over a typical ownership period, even before factoring in fuel savings. Collectively, these incentives are projected to support steady fleet demand even as private sales level off.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| VAT Re-Introduction on High-Priced EVs | –0.4% | Premium segments nationwide | Short term (≤2 years) |
| Rising Insurance Premiums | –0.3% | Nationwide, heavier impact on 800 V SUVs | Short term (≤2 years) |
| Grid-Upgrade Delays in Rural Hubs | –0.2% | Finnmark, Nordland, parts of Trøndelag | Medium term (2–4 years) |
| Nickel and Cobalt Cost Volatility | –0.1% | Global input cost pass-through | Long term (≥4 years) |
| Source: Mordor Intelligence | |||
Gradual VAT Re-Introduction on High-Priced EVs Above NOK 500 K
A 25% VAT applies to the portion of an EV’s price exceeding NOK 500,000 (~USD 49,500). As of January 2026, this threshold has decreased to NOK 300,000 (~USD 25,000), increasing prices for premium vehicles and dampening demand for models such as the Tesla Model S and Mercedes-Benz EQS. As oil revenues dwindle, the treasury's gain on vehicle sales bolsters fiscal consolidation efforts. In response, Volkswagen swiftly shifted its focus to more affordable trims of its models, which have gained notable traction in the market. This strategy hastens commoditization, steering buyers towards a price range where Chinese brands demonstrate strong competitiveness.
Rising Insurance Premiums for High-Voltage Vehicles
In 2025, insurers identified battery replacements as significant loss drivers, leading to a notable increase in comprehensive premiums. Higher risk bands now encompass advanced platforms, which have further raised annual coverage costs. Meanwhile, the introduction of a new insurance tax has eliminated longstanding exemptions. Households with two cars, previously balancing an electric vehicle (EV) with an internal combustion engine (ICE), are now facing increased charges. This could potentially slow their transition to converting a second vehicle. While automakers are beginning to bundle telematics-driven policies, the range of coverage options remains limited.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Powertrain: Hydrogen’s Tiny Foothold Amid BEV Dominance
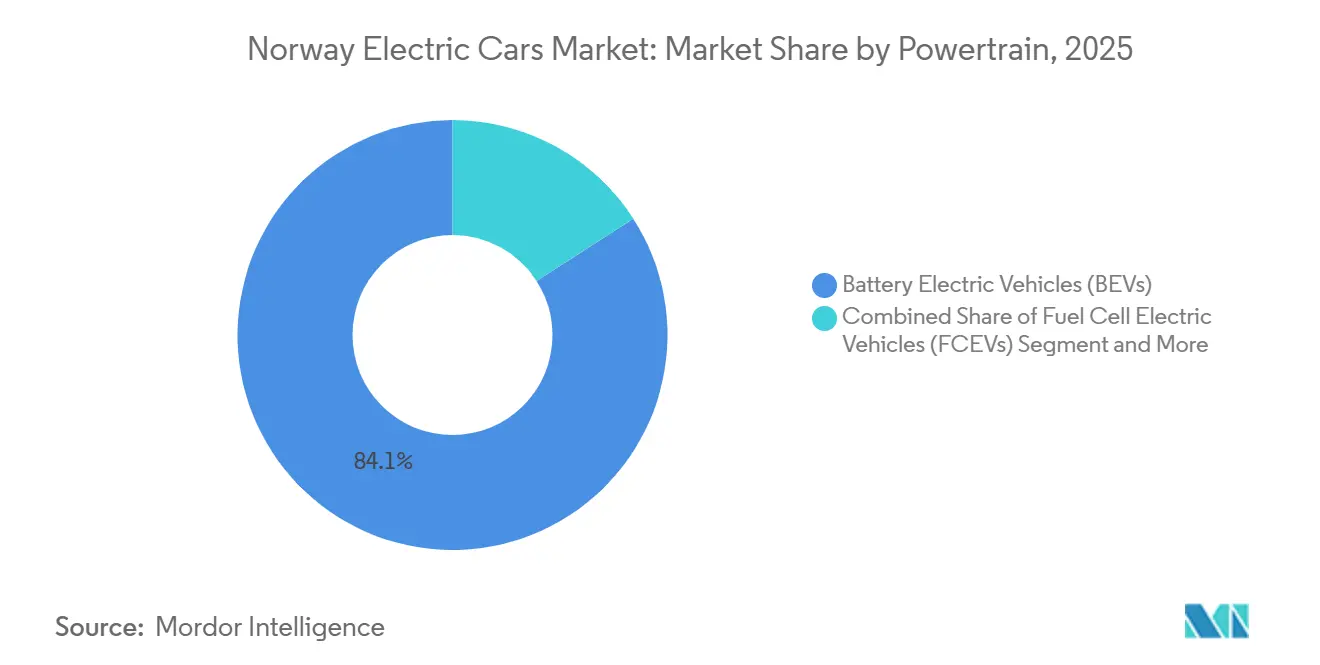
Battery electric models captured 84.12% of the Norwegian electric car market in 2025, powered by 27,000+ public chargers and near-universal home outlets. Plug-in hybrids lost tax breaks in 2025 and are fading rapidly. Hydrogen fuel-cell registrations are set for a 4.12% CAGR—the category’s quickest pace—once new stations come online.
Though the growth percentage for hydrogen is the highest, absolute uptake stays niche because only Toyota’s Mirai and Hyundai’s Nexo are on offer, both of which list above the looming VAT threshold. In contrast, BEV total cost of ownership keeps improving as LFP cell costs fall, and high-energy-density NMC packs still serve long-range niches. Accordingly, the Norwegian electric car market will rely on BEVs for the foreseeable future, while hydrogen focuses on heavy-duty use cases.

By Vehicle Type: SUVs and Crossovers Retain a Winter Edge
Sport-utility vehicles and crossovers held 46.33% of the Norwegian electric car market share in 2025, as families prefer higher ground clearance and 400+ km winter range. SUVs are expected to log a 1.75% CAGR through 2031 due to superior thermal management, with NAF tests indicating minimal range loss at cold temperatures[1]. While hatchbacks dominated from 2010 to 2018, they're now losing traction as earlier battery packs show signs of range constraints.
The Norwegian electric car market size for sedans and MPVs remains meaningful but secondary. Sedans such as the Tesla Model 3 still resonate with company-car users, while Volkswagen’s ID. Buzz proves a hit with larger households. Demand divergence underscores how winter conditions, holiday cabin trips, and multi-car ownership skew Norwegian buying toward roomy body styles.
By Battery Chemistry: Local LFP Plants Challenge NMC Supremacy
NMC technology supplied 65.25% of 2025 packs, but LFP is the fastest-growing chemistry at 1.48% CAGR through 2031 because Morrow Batteries’ Arendal plant reduces dependency on Chinese imports. The shift helps shield automakers from nickel and cobalt price swings and keeps entry-level BEVs under VAT thresholds. The Norwegian electric car market size attached to NMC will stay large, yet its share will gradually taper as cold-weather drawbacks of LFP recede thanks to pack heating and heat-pump systems.
Tesla is leading the charge, transitioning its standard-range models to LFP batteries while keeping NMC batteries exclusive to its long-range versions. Fleet operators, keen on minimizing costs per kilometer, are increasingly turning to BYD's Blade Battery, known for its impressive capacity retention even after extensive use. As the market diversifies its battery chemistry options, it strengthens the affordability of electric cars in Norway.
By Motor Architecture: PMSM Efficiency Remains Unmatched
Permanent-magnet synchronous motors (PMSM) delivered 73.02% of 2025 sales and will post a 2.05% CAGR, capitalizing on notable efficiency and robust low-temperature torque. Induction units remain Tesla’s secondary solution to reduce rare-earth reliance but consume significantly more highway energy. For Norway’s mountainous topography, PMSM regen efficiency translates into longer downhill recuperation, appealing to drivers covering Oslo–Bergen or Trondheim–Bodø routes.
Rare-earth price spikes add supply-chain risk, yet alternate topologies like switched-reluctance are not mass-ready. Hence, the Norwegian electric car market will keep revolving around PMSM for at least the next model cycle, reinforcing efficiency as a purchase priority.
By Range: Long-Range Models Capture Upgrade Demand
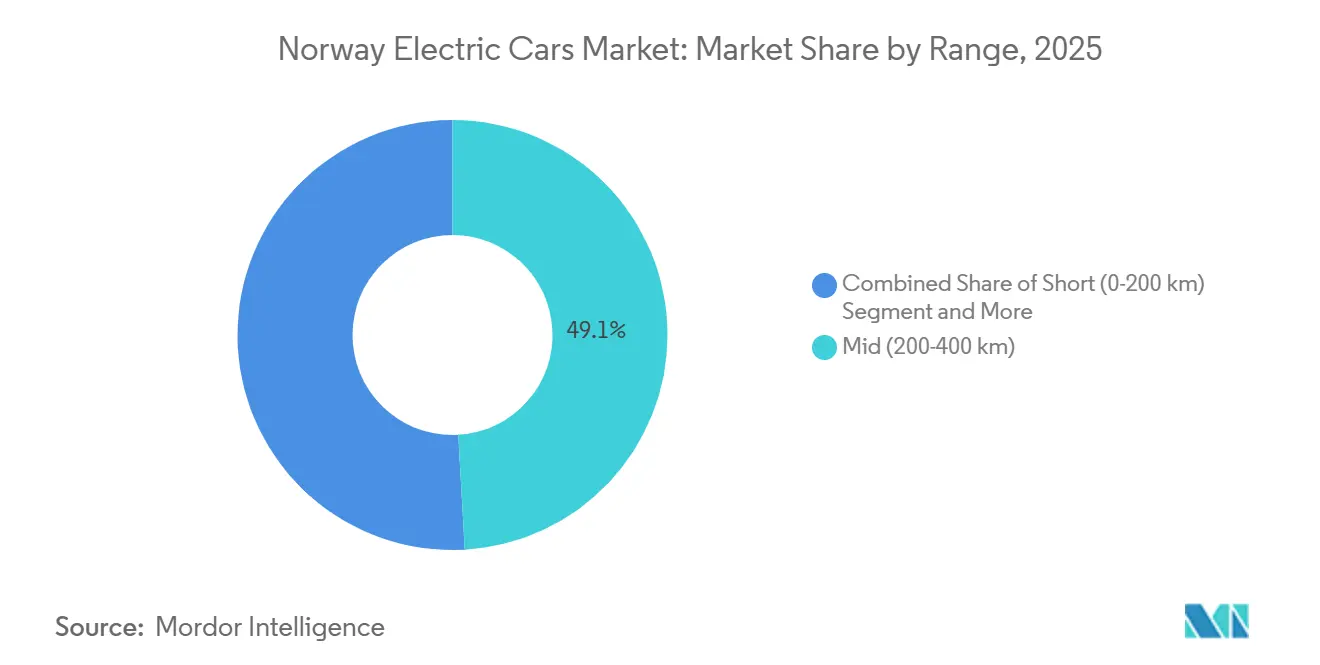
Mid-range (200–400 km) cars kept a 49.13% share in 2025, but long-range (400–600 km) variants are climbing fastest at 3.45% CAGR. Winter degradation limits mid-range usability on the Oslo–Bergen corridor. In contrast, long-range BEVs allow drivers to skip pit stops, alleviating charger congestion. As Chinese and European brands introduce more affordable long-range models, the market share for these trims in Norway's electric car sector is set to expand.
Ultra-long-range (>600 km) cars like the Mercedes EQS sit in a premium niche, partly blunted by VAT. Nevertheless, range anxiety still steers many replacement purchases, even amid dense charger coverage. Automakers combining big batteries, 800 V charging, and sub-threshold pricing will capture outsized loyalty.
By Voltage: 800 V Platforms Prepare for Megawatt Era
Cars running 400–800 V systems made up 59.22% of sales in 2025, but architectures above 800 V will grow at a 2.51% CAGR as IONITY deploys 600 kW dispensers. Hyundai, Kia, and Porsche already tout 18–22 minute 10-80% sessions, a convenience edge over 400 V rivals. When 600 kW units land, 800 V cars will add 300 km in roughly 10 minutes.
Tesla’s current 400 V suite faces either a costly redesign or a marketing pivot, because Norwegian buyers equate charging time with holiday-trip flexibility. As megawatt hardware proliferates, voltage will matter as much as battery size, reshaping competitive dynamics in the Norwegian electric cars market.
Geography Analysis
Eastern Norway retained a 38.16% share in 2025, anchored by Oslo’s significant EV penetration, vast public chargers, and notable toll savings[2]. However, growth in Eastern Norway is stabilizing as the market approaches saturation, with higher VAT influencing consumer preferences toward more affordable EV segments. Despite this, replacement demand remains strong as older EV models are phased out.
Western Norway is slated for a 3.01% CAGR to 2031, the fastest among regions. Bergen and Stavanger are expanding zero-emission zones. Multi-car households common in Vestland province typically favor one long-range SUV plus a sedan, enlarging the local Norwegian electric car market size.
Trøndelag, centered around Trondheim, has established itself as a leader in EV adoption, supported by strong environmental awareness initiatives led by local universities and early adoption of vehicle-to-grid (V2G) technology. In contrast, Northern Norway faces challenges such as limited charging infrastructure, harsh winters, and delays in grid upgrades, which have slowed EV adoption. Residents in this region tend to favor long-range SUVs capable of covering significant distances without recharging. Meanwhile, Svalbard serves more as a testing ground than a commercial market.
Competitive Landscape
Competition remains fierce. Tesla continues to lead the market, followed closely by Volkswagen Group and Volvo/Polestar. Chinese players such as BYD, NIO, Xpeng, and MG are gaining traction, leveraging cost advantages and innovative battery-swap technologies. In response, European incumbents are strengthening their positions through partnerships with IONITY and focusing on software-driven after-sales services.
The technological battleground is centered on advanced charging platforms and faster charging solutions. Hyundai’s IONIQ series has set benchmarks for rapid charging, while IONITY is working on solutions that promise significantly reduced charging times. NIO’s third-generation swap stations store 2 MWh and handle 408 swaps daily, turning batteries into a subscription commodity [3]. In Norway's electric car market, the focus has shifted from traditional specifications to a comprehensive ecosystem that includes insurance bundling, vehicle-to-grid (V2G) earnings, and over-the-air (OTA) feature unlocks.
Untapped potential exists in battery-as-a-service vans designed for zero-emission logistics, affordable models targeting rural consumers, and grid-service aggregation tailored for fleets. Brands that fail to integrate charging, software, and financing into a seamless offering risk being reduced to commodity status.
Norway Electric Car Industry Leaders
-
Tesla Inc.
-
Volkswagen AG
-
Toyota Motor Corporation
-
BYD Company Ltd.
-
Volvo Car AB
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- February 2026: Toyota Motor Corp. expanded its electric vehicle lineup in Norway as the Japanese automaker aims to become the country’s top-selling passenger car brand by 2026. The lineup included passenger car models under the main Toyota brand, including the updated Urban Cruiser and bZ4X SUVs, and the C-HR+ SUV.
- January 2026: Norway confirmed the electric vehicle value-added tax (VAT) exemption threshold at NOK 500,000 (~USD 25,000). Purchase prices above this threshold are subject to the standard 25% VAT.
Norway Electric Car Market Report Scope
The scope includes segmentation by powertrain (battery electric vehicles, plug-in hybrid electric vehicles, and fuel cell electric vehicles), vehicle type (hatchback, sedan, sport utility vehicle/crossover, and multi-purpose vehicle), battery chemistry (lithium iron phosphate, lithium nickel manganese cobalt oxide, lithium nickel cobalt aluminum oxide, and others), motor architecture (permanent magnet synchronous motors, induction motors, and others), range (short (0-200 km), mid (200-400 km), long (400-600 km), and ultra-long (above 600 km)), and voltage (low (≤200 V), mid (200-400 V), high (400-800 V), and ultra-high (above 800 V)). The analysis also covers regional-level segmentation, including Eastern Norway, Western Norway, Trøndelag, Northern Norway, Southern Norway, and Svalbard. Market size and growth forecasts are presented by value in USD and by volume in units.
By Powertrain
| Battery Electric Vehicles (BEVs) |
| Plug-in Hybrid Electric Vehicles (PHEVs) |
| Fuel Cell Electric Vehicles (FCEVs) |
By Vehicle Type
| Hatchback |
| Sedan |
| Sport Utility Vehicle (SUV)/Crossover |
| Multi-Purpose Vehicle (MPV) |
By Battery Chemistry
| Lithium Iron Phosphate (LFP) |
| Lithium Nickel Manganese Cobalt Oxide (NMC) |
| Lithium Nickel Cobalt Aluminum Oxide (NCA) |
| Others |
By Motor Architecture
| Permanent Magnet Synchronous Motors (PMSM) |
| Induction Motors (IM) |
| Others (SRM, Axial Flux, etc.) |
By Range
| Short (0-200 km) |
| Mid (200-400 km) |
| Long (400-600 km) |
| Ultra-Long (Above 600 km) |
By Voltage
| Low Voltage (≤200 V) |
| Mid Voltage (200-400 V) |
| High Voltage (400-800 V) |
| Ultra-High Voltage (Above 800 V) |
By Region
| Eastern Norway |
| Western Norway |
| Trøndelag |
| Northern Norway |
| Southern Norway |
| Svalbard |
| By Powertrain | Battery Electric Vehicles (BEVs) |
| Plug-in Hybrid Electric Vehicles (PHEVs) | |
| Fuel Cell Electric Vehicles (FCEVs) | |
| By Vehicle Type | Hatchback |
| Sedan | |
| Sport Utility Vehicle (SUV)/Crossover | |
| Multi-Purpose Vehicle (MPV) | |
| By Battery Chemistry | Lithium Iron Phosphate (LFP) |
| Lithium Nickel Manganese Cobalt Oxide (NMC) | |
| Lithium Nickel Cobalt Aluminum Oxide (NCA) | |
| Others | |
| By Motor Architecture | Permanent Magnet Synchronous Motors (PMSM) |
| Induction Motors (IM) | |
| Others (SRM, Axial Flux, etc.) | |
| By Range | Short (0-200 km) |
| Mid (200-400 km) | |
| Long (400-600 km) | |
| Ultra-Long (Above 600 km) | |
| By Voltage | Low Voltage (≤200 V) |
| Mid Voltage (200-400 V) | |
| High Voltage (400-800 V) | |
| Ultra-High Voltage (Above 800 V) | |
| By Region | Eastern Norway |
| Western Norway | |
| Trøndelag | |
| Northern Norway | |
| Southern Norway | |
| Svalbard |
Market Definition
- Vehicle Type - The category includes passenger cars.
- Vehicle Body Type - This include various body types such as Hatchbacks, Sedans, Sports Utility Vehicles, and Multi-purpose Vehicles.
- Fuel Category - The category exclusively covers electric propulsion systems, including various types such as HEV (Hybrid Electric Vehicles), PHEV (Plug-in Hybrid Electric Vehicles), BEV (Battery Electric Vehicles), and FCEV (Fuel Cell Electric Vehicles).
| Keyword | Definition |
|---|---|
| Electric Vehicle (EV) | A vehicle which uses one or more electric motors for propulsion. Includes cars, buses, and trucks. This term includes all-electric vehicles or battery electric vehicles and plug-in hybrid electric vehicles. |
| BEV | A BEV relies completely on a battery and a motor for propulsion. The battery in the vehicle must be charged by plugging it into an outlet or public charging station. BEVs do not have an ICE and hence are pollution-free. They have a low cost of operation and reduced engine noise as compared to conventional fuel engines. However, they have a shorter range and higher prices than their equivalent gasoline models. |
| PEV | A plug-in electric vehicle is an electric vehicle that can be externally charged and generally includes all-electric vehicles as well as plug-in hybrids. |
| Plug-in Hybrid EV | A vehicle that can be powered either by an ICE or an electric motor. In contrast to normal hybrid EVs, they can be charged externally. |
| Internal combustion engine | An engine in which the burning of fuels occurs in a confined space called a combustion chamber. Usually run with gasoline/petrol or diesel. |
| Hybrid EV | A vehicle powered by an ICE in combination with one or more electric motors that use energy stored in batteries. These are continually recharged with power from the ICE and regenerative braking. |
| Commercial Vehicles | Commercial vehicles are motorized road vehicles designed for transporting people or goods. The category includes light commercial vehicles (LCVs) and medium and heavy-duty vehicles (M&HCV). |
| Passenger Vehicles | Passenger cars are electric motor– or engine-driven vehicles with at least four wheels. These vehicles are used for the transport of passengers and comprise no more than eight seats in addition to the driver’s seat. |
| Light Commercial Vehicles | Commercial vehicles that weigh less than 6,000 lb (Class 1) and in the range of 6,001–10,000 lb (Class 2) are covered under this category. |
| M&HDT | Commercial vehicles that weigh in the range of 10,001–14,000 lb (Class 3), 14,001–16,000 lb (Class 4), 16,001–19,500 lb (Class 5), 19,501–26,000 lb (Class 6), 26,001–33,000 lb (Class 7) and above 33,001 lb (Class 8) are covered under this category. |
| Bus | A mode of transportation that typically refers to a large vehicle designed to carry passengers over long distances. This includes transit bus, school bus, shuttle bus, and trolleybuses. |
| Diesel | It includes vehicles that use diesel as their primary fuel. A diesel engine vehicle have a compression-ignited injection system rather than the spark-ignited system used by most gasoline vehicles. In such vehicles, fuel is injected into the combustion chamber and ignited by the high temperature achieved when gas is greatly compressed. |
| Gasoline | It includes vehicles that use gas/petrol as their primary fuel. A gasoline car typically uses a spark-ignited internal combustion engine. In such vehicles, fuel is injected into either the intake manifold or the combustion chamber, where it is combined with air, and the air/fuel mixture is ignited by the spark from a spark plug. |
| LPG | It includes vehicles that use LPG as their primary fuel. Both dedicated and bi-fuel LPG vehicles are considered under the scope of the study. |
| CNG | It includes vehicles that use CNG as their primary fuel. These are vehicles that operate like gasoline-powered vehicles with spark-ignited internal combustion engines. |
| HEV | All the electric vehicles that use batteries and an internal combustion engine (ICE) as their primary source for propulsion are considered under this category. HEVs generally use a diesel-electric powertrain and are also known as hybrid diesel-electric vehicles. An HEV converts the vehicle momentum (kinetic energy) into electricity that recharges the battery when the vehicle slows down or stops. The battery of HEV cannot be charged using plug-in devices. |
| PHEV | PHEVs are powered by a battery as well as an ICE. The battery can be charged through either regenerative breaking using the ICE or by plugging into some external charging source. PHEVs have a better range than BEVs but are comparatively less eco-friendly. |
| Hatchback | These are compact-sized cars with a hatch-type door provided at the rear end. |
| Sedan | These are usually two- or four-door passenger cars, with a separate area provided at the rear end for luggage. |
| SUV | Popularly known as SUVs, these cars come with four-wheel drive, and usually have high ground clearance. These cars can also be used as off-road vehicles. |
| MPV | These are multi-purpose vehicles (also called minivans) designed to carry a larger number of passengers. They carry between five and seven people and have room for luggage too. They are usually taller than the average family saloon car, to provide greater headroom and ease of access, and they are usually front-wheel drive. |
Research Methodology
Mordor Intelligence follows a four-step methodology in all its reports.
- Step-1: Identify Key Variables: To build a robust forecasting methodology, the variables and factors identified in Step-1 are tested against available historical market numbers. Through an iterative process, the variables required for market forecast are set and the model is built based on these variables.
- Step-2: Build a Market Model: Market-size estimations for the historical and forecast years have been provided in revenue and volume terms. Market revenue is calculated by multiplying the sales volume with their respective average selling price (ASP). While estimating ASP factors like average inflation, market demand shift, manufacturing cost, technological advancement, and varying consumer preference, among others have been taken into account.
- Step-3: Validate and Finalize: In this important step, all market numbers, variables, and analyst calls are validated through an extensive network of primary research experts from the market studied. The respondents are selected across levels and functions to generate a holistic picture of the market studied.
- Step-4: Research Outputs: Syndicated Reports, Custom Consulting Assignments, Databases & Subscription Platforms.


