
Non-Invasive Intracranial Pressure Monitoring Devices Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 389.78 Million |
| Market Size (2031) | USD 488.69 Million |
| Growth Rate (2026 - 2031) | 4.62 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Non-Invasive Intracranial Pressure Monitoring Devices Market Analysis by Mordor Intelligence
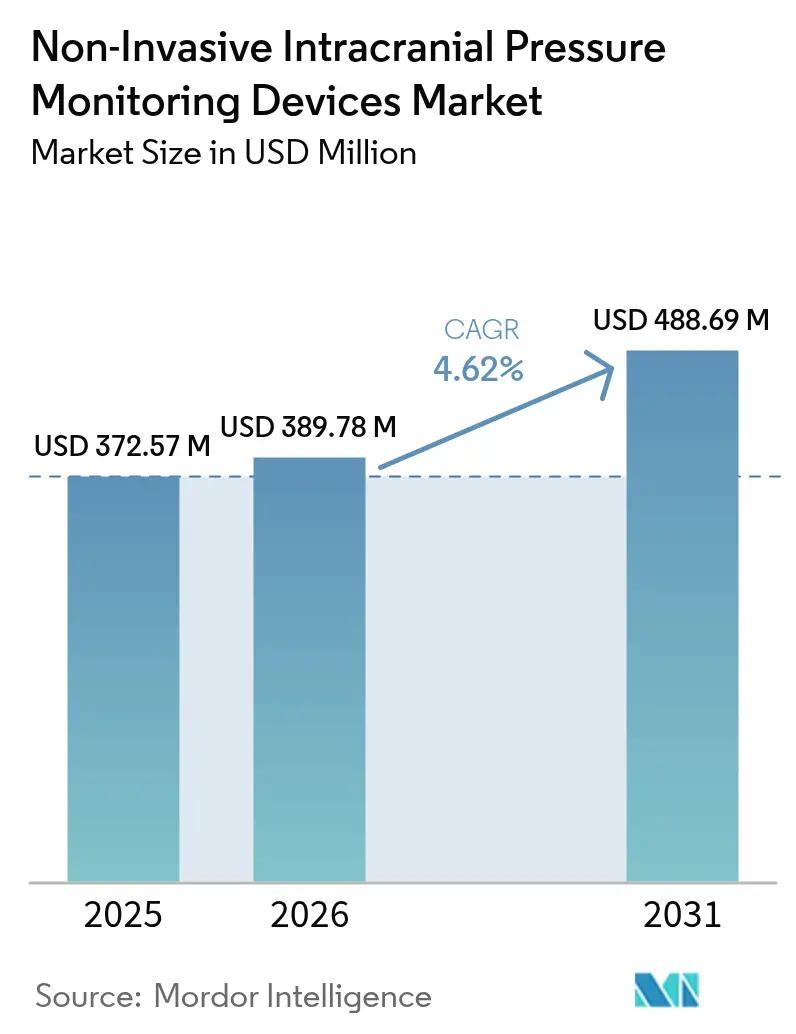
The non-invasive intracranial pressure monitoring devices market size was valued at USD 372.57 million in 2025 and estimated to grow from USD 389.78 million in 2026 to reach USD 488.69 million by 2031, at a CAGR of 4.62% during the forecast period (2026-2031). Incremental expansion reflects the shift from exploratory prototypes to clinically validated solutions that match invasive accuracy while avoiding surgical risks, lowering infection rates and shortening hospital stays. Military research grants, FDA breakthrough-device designations and expanding evidence for AI-enabled waveform analytics are accelerating clinical adoption. Hospitals remain the chief customers, yet rapid uptake in emergency departments, ambulatory centers and home-care programs signals a move toward decentralized monitoring. Asia-Pacific’s demographic pressure and infrastructure build-out underpin the fastest regional CAGR, whereas North America leverages reimbursement frameworks and defense spending to protect its leadership position.
Key Report Takeaways
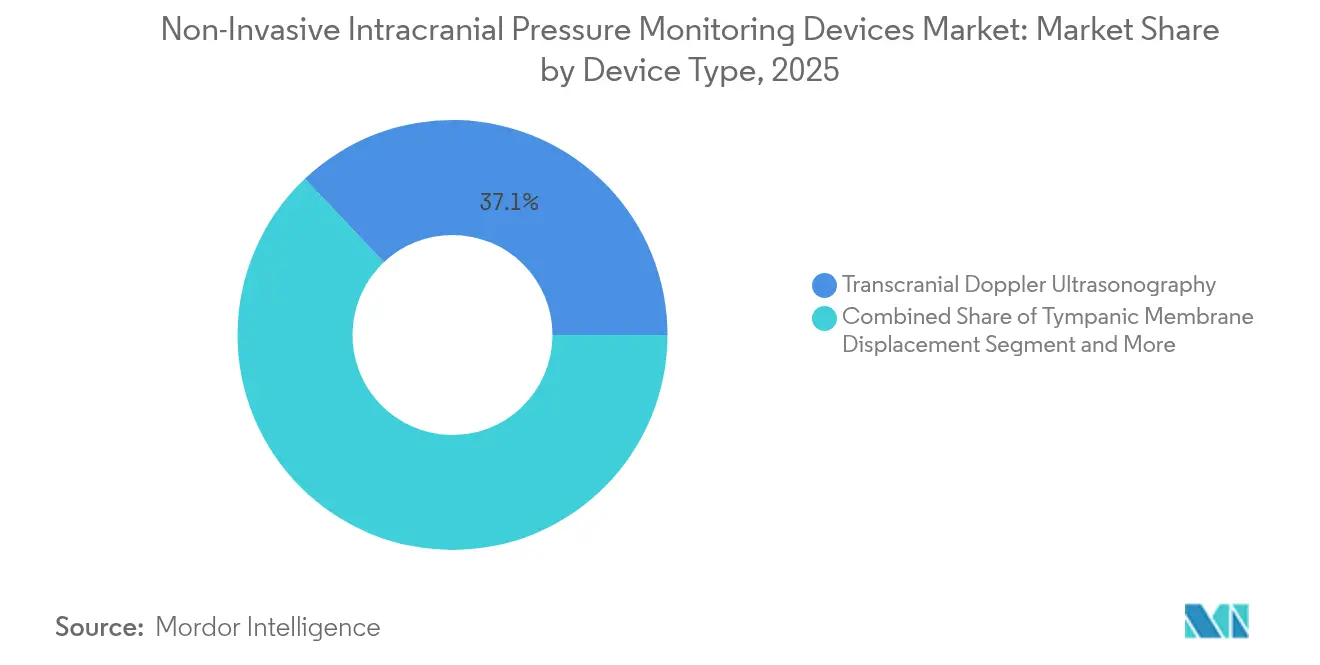
- By device type, transcranial Doppler ultrasonography led with 37.05% of the non-invasive intracranial pressure monitoring devices market share in 2025; infrared pupillometry is projected to advance at an 11.05% CAGR through 2031.
- By application, traumatic brain injury accounted for a 39.93% slice of the non-invasive intracranial pressure monitoring devices market size in 2025; stroke monitoring is expanding at a 9.37% CAGR to 2031.
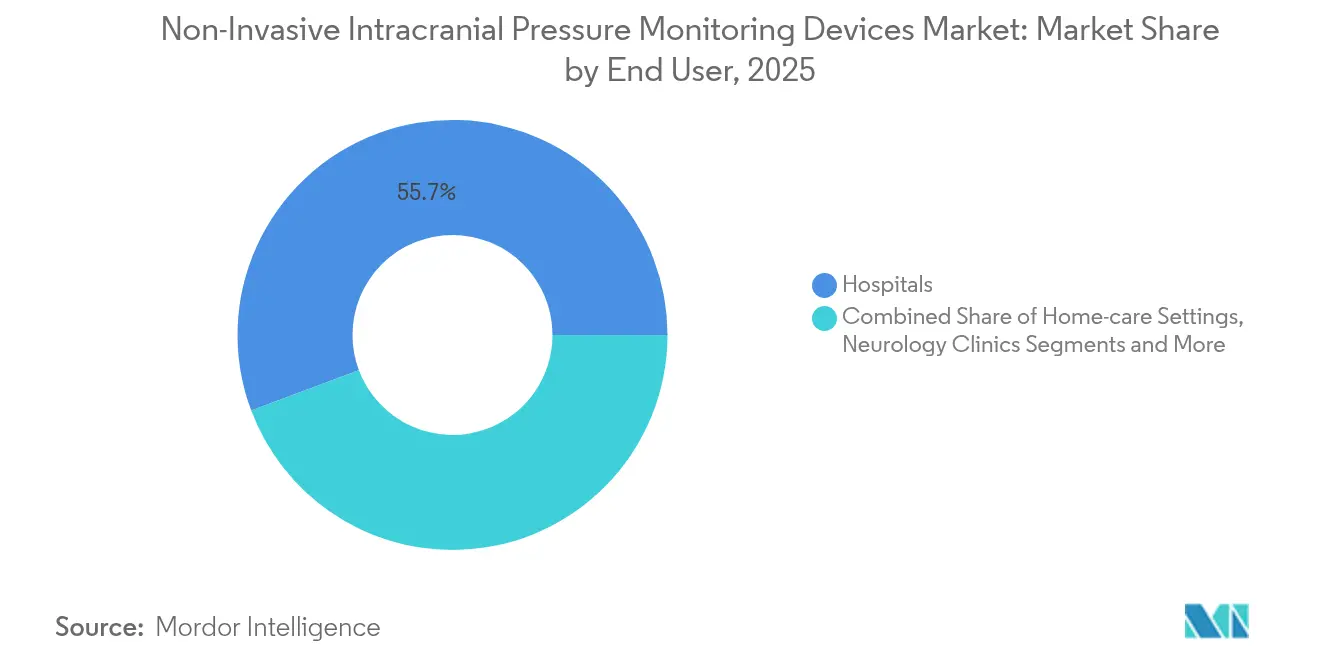
- By end user, hospitals held 55.72% revenue share in 2025, while home healthcare is set to post a 9.12% CAGR between 2026-2031.
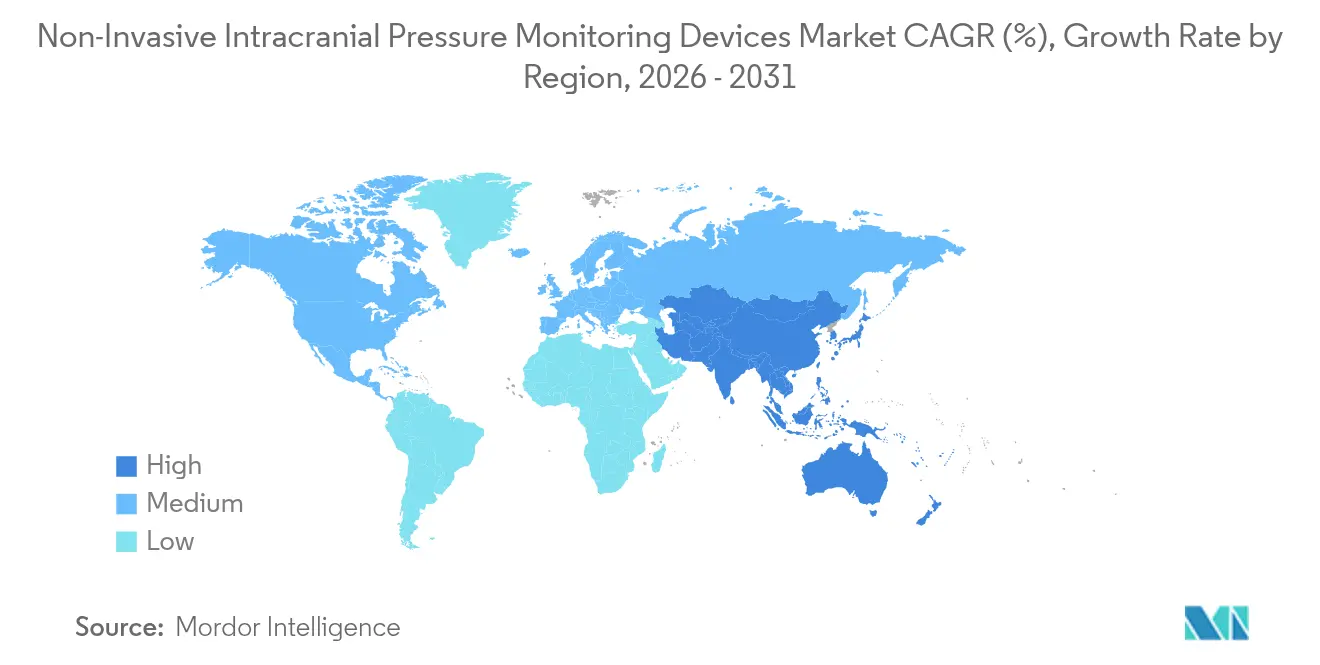
- By geography, North America controlled 37.90% of the non-invasive intracranial pressure monitoring devices market size in 2025; Asia-Pacific is the fastest-growing region with an 8.11% CAGR forecast to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Non-Invasive Intracranial Pressure Monitoring Devices Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing incidences of neurological disorders | +1.2% | Global; greatest in aging North America & Europe | Long term (≥ 4 years) |
| Preference for minimally & non-invasive procedures | +0.8% | Global; strongest in developed systems | Medium term (2-4 years) |
| Wider adoption of point-of-care ultrasound in ED/ICU | +0.6% | North America & Europe lead; Asia-Pacific rising | Short term (≤ 2 years) |
| Growing use of multimodal neuromonitoring bundles | +0.5% | Global; tertiary and trauma centers | Medium term (2-4 years) |
| AI-enabled waveform analytics | +0.7% | Tech-advanced markets first, then emerging | Medium term (2-4 years) |
| Military R&D funding for blast-TBI screening | +0.3% | United States; allies benefitting | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Increasing Incidences of Neurological Disorders
More than 70 million people experience traumatic brain injury each year, and overall stroke rates are climbing in younger cohorts, creating sustained demand for continuous, non-invasive monitoring across acute, rehabilitation and home settings[1]Center for Neuroscience and Regenerative Medicine, “Traumatic Brain Injury Statistics,” cdmrp.health.mil. Baseline cognitive testing for every new U.S. Army recruit since June 2024 highlights how military populations now require lifelong brain-health surveillance. The convergence of longer life expectancy with improved survival after severe events is enlarging the patient pool needing serial intracranial pressure checks without added surgical risk. Health systems consequently channel capital into devices that travel with patients across care environments, reinforcing volume growth for the non-invasive intracranial pressure monitoring devices market.
Rising Preference for Minimally & Non-Invasive Procedures
FDA clearance of the i-STAT TBI cartridge in 2024 exemplifies a regulatory tilt toward bedside diagnostics that bypass surgery while delivering rapid, reliable readings. Studies on Brain4care and similar platforms report mean absolute intracranial pressure errors around 3 mmHg, aligning closely with invasive probes and validating the technology in neurosurgical units. Economically, non-invasive pathways trim infection-related costs and reduce ICU length of stay, forming a persuasive value proposition for payers and clinicians alike. Patient advocacy groups amplify this momentum by challenging invasive use when harm-free substitutes exist. Collectively, these forces enlarge the non-invasive intracranial pressure monitoring devices market well beyond tertiary centers.
Wider Adoption of Point-of-Care Ultrasound in ED/ICU
Emergency physicians now deploy optic-nerve diameter and cerebral blood-flow metrics through handheld scanners, posting almost 80% agreement with in-hospital findings and cutting time to intervention. AI-integrated transducers that auto-calculate optic nerve sheath width remove operator bias, a critical gain in crowded trauma bays. Structured credentialing is closing the skills gap, enabling even junior doctors to gather accurate neurologic ultrasound data. Reduced CT usage and shorter door-to-treatment windows underpin hospital return-on-investment cases. In parallel, portable ultrasound enlarges the non-invasive intracranial pressure monitoring devices market within ambulance networks and rural clinics previously beyond reach.
AI-Enabled Waveform Analytics Improving Diagnostic Accuracy
Johns Hopkins algorithms distill arterial pressure, photoplethysmography and ECG waveforms into precise intracranial pressure estimates that match invasive catheter accuracy, all via equipment already present in standard monitors. Continuous analytics flag dangerous pressure trends sooner than manual charting, letting clinicians intervene before herniation risk spikes. Scalability permits simultaneous surveillance of multiple beds with consistent interpretation, mitigating the global neuro-sonographer shortage. Early deployment shows fewer false alarms and quicker therapy adjustments, strengthening the adoption case across high-acuity settings. These gains cement AI as a cornerstone driver for the non-invasive intracranial pressure monitoring devices market.
Restraints Impact Analysis of Non-Invasive Intracranial Pressure Monitoring Devices Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Lack of trained neuro-sonographers | -0.9% | Global; severe in emerging & rural zones | Medium term (2-4 years) |
| High device acquisition & maintenance costs | -0.7% | Mostly emerging markets | Short term (≤ 2 years) |
| Variability in non-invasive algorithm accuracy | -0.5% | Markets with strict validation rules | Medium term (2-4 years) |
| Slow reimbursement code expansion | -0.6% | United States & complex payor systems | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Lack of Trained Neuro-Sonographers
Effective transcranial Doppler demands mastery of cerebrovascular anatomy, optimal scale settings and nuanced waveform interpretation, skill sets still scarce outside academic centers. Certification pipelines remain thin, and sustained competence requires exposure to diverse pathologies. Workforce gaps translate into delayed studies, unequal access and, in turn, slower install-base growth for the non-invasive intracranial pressure monitoring devices market. Professional societies have launched standardized curricula, yet emerging economies continue to struggle with limited faculty pools and training equipment shortages[2]Journal of Neurosonology, “Transcranial Doppler Technique,” j-nn.org.
High Device Acquisition & Maintenance Costs
AI-enabled multimodal monitors command premium prices, often exceeding capital budgets in low- and middle-income facilities. Beyond purchase, calibration and software-update schedules impose recurring expenditure that strains operating funds. Administrators weigh these outlays against competing needs such as ventilators or imaging scanners. Rapid technology turnover further clouds return-on-investment calculations, prompting cautious rollouts. Consequently, price sensitivity tempers the near-term expansion of the non-invasive intracranial pressure monitoring devices market in cost-constrained health systems.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Non-Invasive Intracranial Pressure Monitoring Devices Market Segment Analysis
By Device Type:
Transcranial Doppler Leads Despite Infrared InnovationTranscranial Doppler held a 37.05% non-invasive intracranial pressure monitoring devices market share in 2025 owing to its established role in vasospasm detection, stroke risk screening and bedside cerebral hemodynamics assessment. Automated waveform storage, portable form factors and protocol standardization have kept adoption robust. The segment benefits from extensive reimbursement coverage and clinician familiarity, anchoring the non-invasive intracranial pressure monitoring devices market size on a solid installed base.
Infrared pupillometry is set for an 11.05% CAGR through 2031 as short-wave infrared cameras deliver touchless readings through closed eyelids, expanding monitoring to sedated or intubated patients. Devices that calculate the Neurological Pupil Index provide objective early warnings of intracranial hypertension, reducing reliance on subjective light-reflex checks. Tympanic membrane displacement and optic-nerve diameter tools serve niche applications where specific anatomic windows or pediatric use dictate alternate approaches. MRI/CT-based estimates remain constrained by cost, radiation exposure and limited repeatability, but may support complex cases requiring multimodal confirmation. Continuous improvements in algorithmic fusion of Doppler and pupillometry promise hybrid platforms that elevate diagnostic confidence while trimming operator training demands.


By Application:
Traumatic Brain Injury Dominance Challenged by Stroke AccelerationTraumatic brain injury represented 39.93% of the non-invasive intracranial pressure monitoring devices market in 2025, driven by defense-sector funding, sports-medicine protocols and motor-vehicle trauma prevalence. Surgeons rely on continuous pressure readings to forestall secondary injury from uncontrolled edema. Military mandates for baseline cognitive testing ensure early deployment of monitoring technology throughout active duty and veteran care pathways.
Stroke monitoring is advancing at a 9.37% CAGR as guidelines now recommend continuous intracranial pressure tracking to guide hyperosmolar therapy and blood-pressure titration in both ischemic and hemorrhagic events. Early-warning algorithms detect subtle pressure elevations that herald neurologic decline, enabling faster intervention. Intracerebral hemorrhage, meningitis and hydrocephalus collectively comprise a meaningful share, each benefitting from non-invasive options that circumvent infection risks in fragile patients. New clinical trials exploring multimodal bundles—combining intracranial pressure, cerebral perfusion and oxygenation—signal further expansion opportunities over the forecast.
By End User:
Hospital Dominance Faces Home Healthcare DisruptionHospitals controlled 55.72% of the non-invasive intracranial pressure monitoring devices market size in 2025 as neuro-ICUs standardize advanced monitoring for complex cases. Integration into electronic records and established purchasing frameworks protect incumbent sales channels. Academic centers also conduct validation studies, reinforcing hospital influence on purchasing standards and clinical protocols.
Home healthcare is forecast to register a 9.12% CAGR through 2031 due to FDA guidance that now facilitates remote neuro-monitoring platforms. Elderly and chronic-care patients benefit from wearable sensors that transmit secure data to central dashboards, curbing readmissions and enhancing quality of life. Neurology clinics and ambulatory centers occupy a middle ground, leveraging non-invasive solutions for same-day procedures and outpatient follow-up. As payors bolster reimbursement for remote physiologic monitoring, home-based deployments will chip away at hospital dominance, reshaping long-term revenue distribution within the non-invasive intracranial pressure monitoring devices market.
Geography Analysis
North America Non-Invasive Intracranial Pressure Monitoring Devices Market
North America accounted for 37.90% of the non-invasive intracranial pressure monitoring devices market in 2025 amid sizable research budgets, robust reimbursement and the Department of Defense’s USD 3.2 million grant to refine blast-TBI screening. FDA breakthrough-device pathways shorten time-to-market for innovators, while Level 1 trauma centers set clinical standards that ripple across community hospitals. Canada’s single-payer environment supports steady device procurement, and Mexico’s public-health expansions are adding advanced neuromonitoring units in select tertiary hubs.
APAC Non-Invasive Intracranial Pressure Monitoring Devices Market
Asia-Pacific is the fastest-growing region with an 8.11% CAGR to 2031, supported by rising traumatic injury rates, aging demographics and expanding critical-care capacity. China’s revision of the National Medical Products Administration (NMPA) approval process is creating clearer on-ramps for imported and locally produced monitors. Japan and South Korea drive early adoption of AI-enhanced platforms, while India demonstrates high receptivity to cost-effective handheld Doppler solutions capable of operating in resource-sparse districts. Government health-tech incentives and local manufacturing tie-ups are expected to amplify installed bases.
Europe Non-Invasive Intracranial Pressure Monitoring Devices Market
Europe maintains a steady position, anchored by rigorous evidence-based guidelines and cross-border collaboration on multicenter trials exploring multimodal neuromonitoring. Germany, the United Kingdom and France lead acquisitions, whereas Southern and Eastern European systems embrace shared-service networks to pool capital expenditure. Medical Device Regulation (MDR) compliance has lengthened certification timelines yet boosts clinician confidence once devices clear review. Constrained budgets remain a headwind, but pan-EU research grants and vendor financing schemes help sustain device turnover.

Competitive Landscape
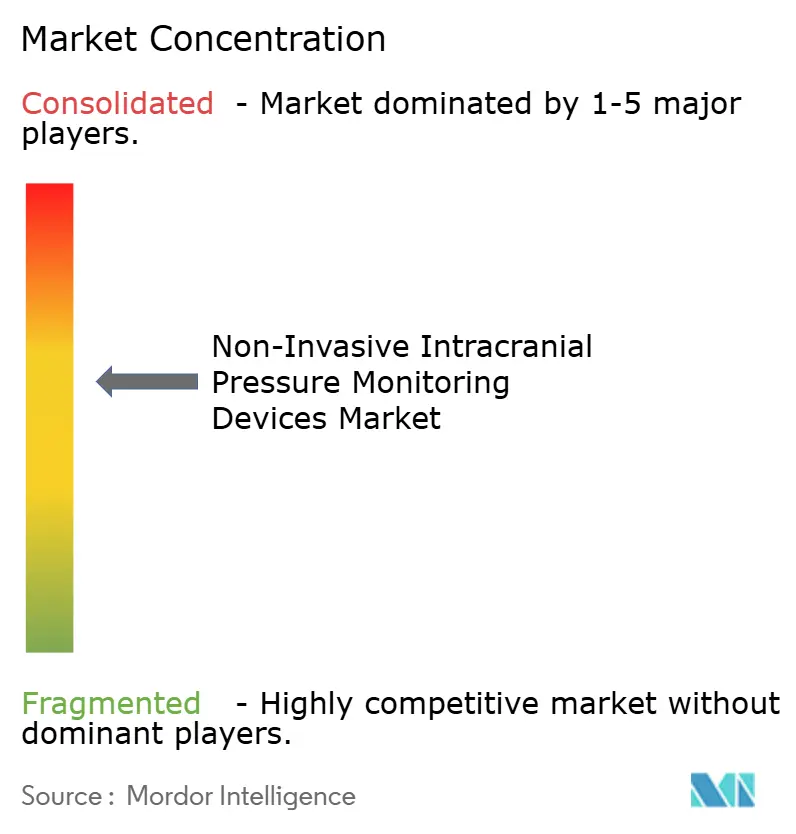
The non-invasive intracranial pressure monitoring devices market shows moderate concentration, with the top five manufacturers estimated to hold a significant share in 2025. Integra LifeSciences promotes its CereLink system while rectifying manufacturing observations cited in an FDA warning letter in December 2024. Nihon Kohden’s November 2024 purchase of a controlling stake in NeuroAdvanced expands its EEG and intracranial electrode offerings, underscoring a push toward multimodal neurological platforms.
Start-ups focus on AI algorithms that retrofit to existing bedside monitors, reducing capital hurdles for hospitals and accelerating revenue capture. Military R&D programs continue to seed early-stage ventures targeting blast-related trauma, which often migrate into civilian trauma-unit use. Device makers are also forging distribution alliances in Asia-Pacific to navigate local regulatory pathways and cut time-to-launch.
Strategically, vendors differentiate through software capabilities, cloud-integrated dashboards and training packages that counter the neuro-sonographer shortage. Subscription-based analytics models shift revenue from one-off hardware sales to recurring fees, smoothing cash flow and encouraging continual software upgrades. Litigation risk remains moderate because devices do not pierce the dura, but quality-system rigor is increasingly scrutinized: manufacturing lapses can result in stern FDA action, as evidenced in 2024. Long-term, players able to bundle intracranial pressure, EEG and cerebral oximetry within a single interface should command premium pricing.
Non-Invasive Intracranial Pressure Monitoring Devices Industry Leaders
RAUMEDIC AG
Nisonic
Natus Medical
Integra LifeSciences
Medtronic plc
- *Disclaimer: Major Players sorted in no particular order
Non-Invasive Intracranial Pressure Monitoring Devices Market Companies Covered in this Report
- Integra LifeSciences
- Medtronic
- RAUMEDIC
- Sophysa
- Spiegelberg
- Natus Medical
- Viasonix
- NovaSignal
- Nisonic
- RIMED
- Compumedics
- Dragerwerk
- Koninklijke Philips
- Nihon Kohden
- GE Healthcare
- Brain4Care
- HeadSense Medical
- Luciole Medical
- IRRAS AB
- De Cranio Solutions
Read Analysis of Non-Invasive Intracranial Pressure Monitoring Devices Companies

Market Opportunities and Future Outlook
White-space in non-invasive intracranial pressure (ICP) monitoring centers on reducing operator dependency while improving comparability to invasive reference measurements, especially in emergency and decentralized settings. Brain4Care’s FDA 510(k) clearance in March 2024 (K240821) for the B4C System (Class II intracranial pressure monitoring device) supports broader procurement beyond investigational use. The pipeline is also reflected in early feasibility work such as CoMind Technologies Limiteds CoMind One EFS (ClinicalTrials.gov NCT06368648, initiated November 2024), which focuses on model-driven, non-invasive estimation approaches, with robust head-to-head clinical validation remaining a gating item for wider protocol inclusion.
Technology roadmaps are shifting toward multimodal data fusion and AI-enabled waveform analytics that leverage routinely captured ICU signals (ECG, arterial blood pressure, photoplethysmography), rather than specialized, operator-intensive procedures. Recent 2026 publications describing passive waveform sensing and deep-learning reconstruction of ICP waveforms from standard bedside inputs reinforce the case for software-forward offerings that integrate with existing monitors and clinical dashboards, which can help address acquisition-cost and workforce constraints (including neuro-sonographer scarcity). The development split between passive wearable-style non-invasive sensors and higher-accuracy, longer-term monitoring approaches (including implantable remote monitoring research programs) also suggests differentiated use cases across traumatic brain injury, stroke monitoring, and chronic hydrocephalus follow-up. This aligns with the shift from hospital-only use toward ED, ambulatory, and home-care pathways already reflected in end-user adoption patterns.
Recent Industry Developments in Non-Invasive Intracranial Pressure Monitoring Devices Market
- June 2026: Academic researchers reported a deep learning framework to reconstruct intracranial pressure waveforms from routinely acquired ICU signals (such as ECG, arterial blood pressure, and photoplethysmography). The work supports a software-centric path to extend non-invasive ICP estimation without adding dedicated bedside hardware. It also aligns with hospital demands for scalable monitoring across more beds amid neuro-sonographer shortages.
- August 2025: Medtronic plc launched the NEUROVENT PTO intracranial pressure monitoring catheter for real-time ICP tracking. Although invasive, the launch highlights continued investment in ICP monitoring performance and workflow integration that shapes the clinical benchmarks used to validate non-invasive alternatives.
- March 2024: Brain4Care received FDA 510(k) clearance (K240821) for the B4C System, including the BcSs-PICNIW-2000 sensor model, as a Class II intracranial pressure monitoring device. Clearance improves procurement confidence and supports broader clinical deployment beyond investigational settings.


Non-Invasive Intracranial Pressure Monitoring Devices Market Report Scope and Research Methodology
Market Definition and Coverage
This market covers devices that measure or estimate intracranial pressure without an invasive catheter, and the value reflects device-level revenues captured across clinical care settings where ICP assessment is used.
Scope exclusions: We exclude invasive ICP monitors and procedure related hospital service revenues that sit outside device sales.
Segments Covered in This Report
- By Device Type
- Transcranial Doppler Ultrasonography
- Tympanic Membrane Displacement
- Optic Nerve Sheath Diameter
- MRI / CT-based Estimation
- Infrared Pupillometry
- Others
- By Application
- Traumatic Brain Injury
- Intracerebral Hemorrhage
- Meningitis
- Hydrocephalus
- Stroke
- Others
- By End User
- Hospitals
- Neurology Clinics
- Ambulatory Surgical Centers
- Home-care Settings
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research started with clarifying clinical use and device pathways so the demand pool stays tied to neurocritical care and neurology workflows. We reviewed public sources such as FDA device databases (510(k) and De Novo summaries), clinical guidance from bodies such as the Brain Trauma Foundation, and peer reviewed journals that discuss non-invasive ICP proxies and accuracy metrics.
To keep the model grounded, we also pulled supporting signals from sources such as the World Health Organization (injury burden), CDC datasets (head injury and emergency care context), and OECD health statistics (health system capacity indicators). Company annual reports, investor decks, and reputable press coverage were used to understand product launches and geographic commercialization, and paid subscriptions were used selectively for company financials and patent landscaping where disclosures were thin. The sources listed here are illustrative, and many other public documents and datasets were reviewed for data collection, cross-checks, and clarification.
Primary Interviews and Surveys
Primary work focused on pressure-monitoring decision points in hospitals and critical care, and how non-invasive tools are chosen versus invasive monitoring for different patient groups. We spoke with device side leaders, clinical users, and channel participants across major regions so pricing logic, adoption barriers, and replacement cycles could be confirmed when desk sources did not provide clean answers.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 31% | CXOs: 17% | APAC: 39% |
| Mid tier: 52% | Functional/Unit leaders: 40% | EMEA: 34% |
| Smaller Players: 17% | Managers: 43% | Americas: 27% |
Market-Sizing & Forecasting
Sizing is built by reconstructing the demand pool from clinical activity and care capacity, and then converting it into device revenues using realistic adoption and price assumptions. The top-down approach is anchored on indicators such as neuro ICU and emergency care throughput, traumatic brain injury and intracranial hemorrhage caseload direction, ICU bed availability, and the practical share of cases where non-invasive ICP assessment is used as a screening or monitoring step.
Those demand signals are translated into revenues using a small set of working inputs, such as device utilization per facility, replacement cycles, average selling price ranges by device class, and expected shifts in adoption as evidence quality improves. To keep the totals grounded, we corroborated the outputs with selective bottom-up approximations, including sampled supplier revenue disclosures, channel checks on installed base, and ASP validation from procurement style conversations. Any missing pieces were handled through conservative ranges that were tightened during expert follow-ups.
For forecasting, scenario analysis was used so changes in clinical acceptance, reimbursement direction, and hospital capital budgets can be reflected without overfitting. Assumptions for adoption lift and ASP progression were adjusted only after the primary inputs aligned with what clinicians and commercial teams see in routine purchasing cycles.
Data Validation & Update Cycle
Validation is done through stepwise checks so the final number matches independent signals and stays explainable. We review outputs against clinical volume indicators, regional health spending direction, and observable product activity, and then we flag outliers that come from unrealistic penetration, price jumps, or sudden mix changes.
Before sign-off, a second analyst reviews the model build and key assumptions, followed by targeted re-contact when a large variance cannot be explained by a clear market event. Reports are refreshed annually, and interim updates are triggered when material events occur (for example, major regulatory clearances or meaningful pricing shifts). Before delivery, a fresh review pass is completed so clients receive the most current version available.
Mordor Intelligence's Non Invasive Intracranial Pressure Monitoring Devices Market Size Compared Against Other Published Estimates
It is normal to see different published market sizes for this topic because the scope line is easy to move and the evidence base is still evolving. Differences usually come from what gets counted as non-invasive ICP monitoring, how pricing is treated across care settings, and how quickly assumptions are refreshed after new clinical results or regulatory milestones.
Some estimates broaden the market by folding in invasive ICP monitoring systems or adjacent neuromonitoring tools that do not directly estimate intracranial pressure. In the Mordor Intelligence view, revenue is counted only for non-invasive ICP monitoring devices, and related neuromonitoring categories are excluded even if they are used in the same ICU workflow.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 389.78 M (2026) | |
| Global Consultancy A | USD 482.60 M (2026) | Uses a wider device basket and applies faster adoption and price uplift assumptions, which can pull in adjacent neuromonitoring instruments and inflate the addressable revenue pool. |
| Industry Publisher B | USD 96.00 M (2024) | Tracks a narrower set of manufacturers and often emphasizes shipped volumes and average prices for a limited product subset, which can understate broader clinical usage across regions and settings. |
The spread across figures is mostly explained by category inclusions and how quickly penetration is allowed to rise in forecasts. By keeping the counted revenues tied to non-invasive ICP monitoring device sales and cross-checking with clinical activity signals and real-world pricing feedback, the estimate remains traceable to clear inputs and repeatable steps.


Key Questions Answered in the Report
How large is the non-invasive intracranial pressure monitoring devices market in 2026?
The market stands at USD 389.78 million and is projected to reach USD 488.69 million by 2031, implying a 4.62% CAGR.
Which device type currently dominates sales?
Transcranial Doppler ultrasonography leads with a 37.05% share thanks to broad clinical validation and reimbursement support.
What is the fastest-growing application segment?
Continuous stroke monitoring shows the highest forecast growth at a 9.37% CAGR through 2031.
Which region offers the highest growth potential?
Asia-Pacific is set to expand at an 8.11% CAGR due to demographic shifts and expanding critical-care capacity.
How is artificial intelligence influencing adoption?
AI-enabled waveform analytics deliver invasive-level accuracy via standard monitors, reducing operator dependency and widening clinical uptake.
What restrains faster market penetration?
A global shortage of trained neuro-sonographers and high upfront equipment costs remain primary barriers despite rising demand.
Page last updated on:





