
Military Aerospace Simulation and Training Market Size and Share
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 4.86 Billion |
| Market Size (2031) | USD 6.45 Billion |
| Growth Rate (2026 - 2031) | 5.82 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | North America |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Military Aerospace Simulation and Training Market Analysis by Mordor Intelligence
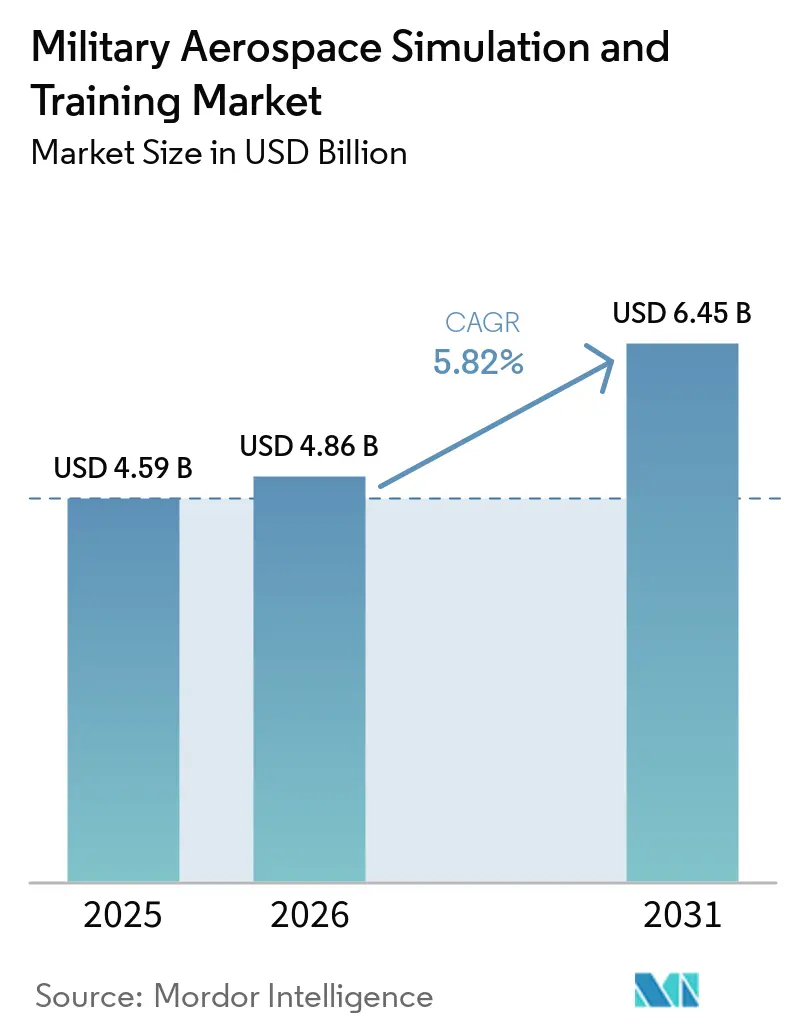
The military aerospace simulation and training market size was valued at USD 4.59 billion in 2025 and is forecast to grow from USD 4.86 billion in 2026 to USD 6.45 billion by 2031, registering a 5.82% CAGR between 2026 and 2031. Defense readiness budgets are supporting more persistent investment in synthetic training systems. The US allocated USD 159.70 billion to warfighter readiness in FY2026, positioning training within a broader readiness program rather than as a one-time procurement priority. NATO allies also committed in 2025 to a 5% of GDP defense and security spending target by 2035, which supports a longer planning horizon for training infrastructure. New-generation aircraft, pilot availability constraints, and the need to rehearse complex missions are raising demand for connected simulators. The military aerospace simulation and training market is therefore moving toward integrated training systems that combine devices, courseware, secure networks, and long-term support.
Key Report Takeaways
- By simulator type, full flight simulators held 46.95% of the military aerospace simulation and training market share in 2026, while flight training devices are projected to grow at an 8.38% CAGR through 2031.
- By aircraft type, fixed-wing aircraft accounted for 62.45% of the military aerospace simulation and training market size in 2026, while rotorcraft is forecast to expand at a 7.31% CAGR through 2031.
- In training mode, live training accounted for 49.81% of revenue in 2026, while virtual training is projected to grow at a 10.62% CAGR through 2031.
- By solution, hardware accounted for 53.59% of revenue in 2026, while services are forecast to grow at an 8.22% CAGR through 2031.
- By application, military aviation held 83.98% revenue share in 2026, while space is projected to expand at a 10.29% CAGR through 2031.
- By geography, North America accounted for 44.18% revenue share in 2026, while Asia-Pacific is forecast to grow at a 7.83% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Global Military Aerospace Simulation and Training Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising geopolitical tensions and mission complexity | +1.80% | Global, concentrated in North America, Europe, and Asia-Pacific | Short term (≤ 2 years) |
| Military fleet modernization and induction of new generation aircraft | +1.40% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Cost and safety advantages of synthetic training | +1.10% | Global | Medium term (2-4 years) |
| Expansion of Live, Virtual and Constructive (LVC) training | +0.90% | North America, Europe, and Asia-Pacific | Medium term (2-4 years) |
| Embedded digital training for software-defined aircraft | +0.70% | North America, Europe, and Türkiye | Long term (≥ 4 years) |
| Distributed training for pilot and maintainer scarcity | +0.60% | North America, Europe, and Japan | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Rising Geopolitical Tensions and Mission Complexity
Geopolitical tensions are shortening the time between a new operational requirement and the need for trained crews. NATO members agreed in 2025 to develop annual plans toward the 5% defense and security spending target. This commitment gives training programs a more durable budget setting.[1] Modern missions require aircrews to work with land, maritime, space, and cyber forces. Networked synthetic environments can combine these elements into a single training event. This expands the military aerospace simulation and training market beyond cockpit instruction into mission planning, crew coordination, and joint force rehearsal.
Military Fleet Modernization and New Generation Aircraft
New aircraft programs require training systems that reflect their sensors, software, and operating procedures. The US Air Force sought a Level D 747-8i simulator from CAE in June 2026 because it identified CAE as the only qualified manufacturer for the requirement. This example shows how qualification can limit supplier options for platform-specific devices. The F-35 Joint Simulation Environment has also been used to explore collaborative combat aircraft tactics in contested settings. Forces often need interim training support while a full synthetic system reaches operational maturity. That period creates demand for upgraded legacy devices, contractor-operated facilities, and current courseware.
Cost and Safety Advantages of Synthetic Training
Synthetic training can reduce the fuel, logistics, and maintenance burden associated with live sorties. A 2026 TERI assessment found that broader use of simulators could save the Indian Armed Forces more than INR 1,000 crore (USD 0.10 billion) annually. The assessment also linked savings to reduced ammunition use and logistics activity. Simulator availability can preserve aircraft for operational missions and reduce exposure during high-risk exercises. This benefit matters when aircraft fleets are small or maintenance capacity is constrained. The military aerospace simulation and training market benefits when procurement authorities assess training systems on readiness output and device availability.
Expansion of LVC Training
LVC training links actual aircraft with simulators and computer-generated forces. Air Education and Training Command completed its first T-7A LVC flight in September 2026. The event connected 1 airborne T-7A with 2 ground-based simulator cockpits through secure tactical data links. This model can increase scenario complexity without deploying the same number of aggressor aircraft. It also supports training against digital threats and simulated weapons effects. The military aerospace simulation and training market is gaining from related requirements for secure connectivity, scenario management, and compatible software.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High development, integration, and certification costs | -1.20% | Global, particularly emerging operators | Long term (≥ 4 years) |
| Cybersecurity exposure of connected training networks | -0.80% | North America and Europe | Short term (≤ 2 years) |
| Interoperability and open-architecture limitations | -0.60% | Multinational programs and NATO interoperability zones | Medium term (2-4 years) |
| Limited replication of physiological and psychological stress | -0.40% | Global | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
High Development, Integration, and Certification Costs
A qualified full-flight simulator requires lengthy technical validation and formal approval. The US Air Force cited schedule, life-cycle cost, and mission-training risks in its 2026 sole-source simulator notice. Such requirements favor suppliers that already hold platform knowledge and certified device designs. Smaller air forces can face high costs for audits, configuration control, and periodic updates. These costs can exceed the initial hardware expense across a device's life cycle. The resulting procurement cycle can slow the entry of newer suppliers into the military aerospace simulation and training market.
Cybersecurity Exposure of Connected Training Networks
Connected training networks can contain sensitive mission data, threat libraries, and system interfaces. A compromised environment could alter the scenarios used to train operational crews. The US Army has identified cybersecurity and interoperability as baseline needs for its persistent cyber training environment. European efforts also include the CITADEL Range program for cyber defense across connected environments. Security obligations increase integration work, compliance costs, and contract timelines. They also make trusted network design a major selection factor in the military aerospace simulation and training market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Simulator Type: Full Flight Simulators Anchor High-Fidelity Readiness
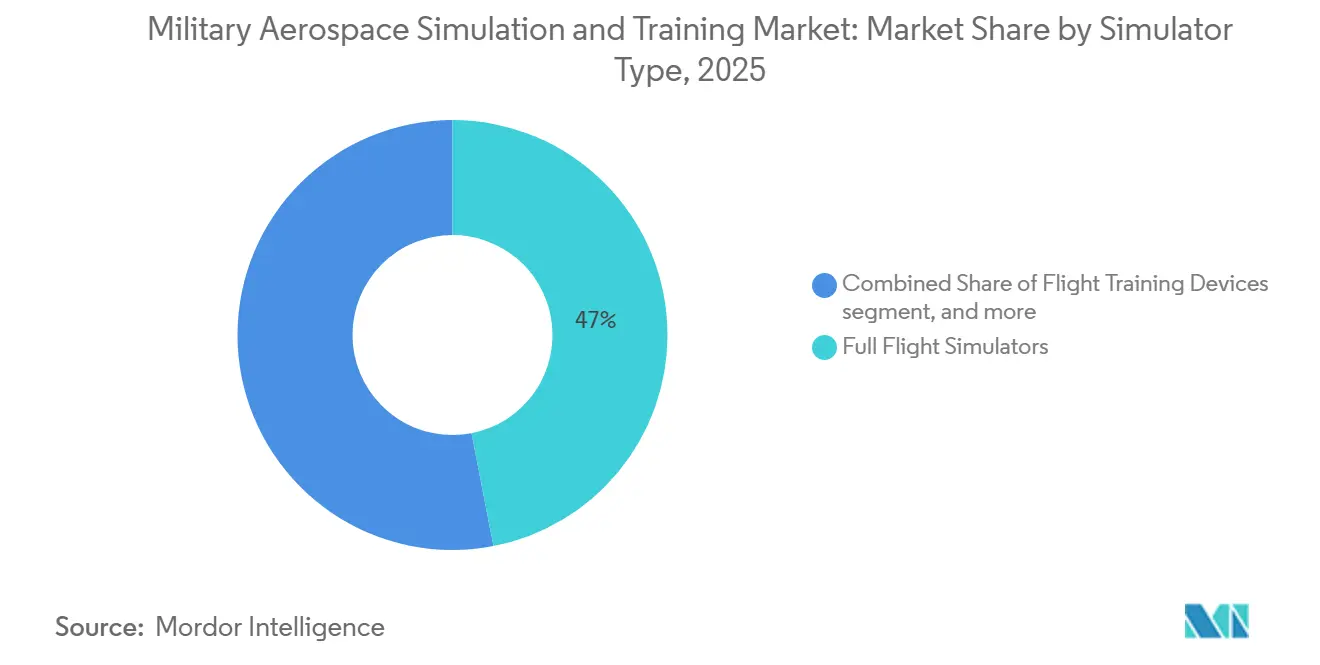
Full flight simulators (FFSs) accounted for 46.95% of the military aerospace simulation and training market in 2026. Their lead reflects the need to qualify crews on complex aircraft within a controlled setting. Full-motion devices reproduce cockpit controls, flight dynamics, visual systems, and key emergency procedures. Their procurement is commonly tied to an aircraft platform and its certification requirements. This connection supports long supplier relationships and raises switching costs. The 2026 US Air Force requirement for a Level D 747-8i simulator illustrates the importance of proven qualification capability.[2]
Flight training devices (FTDs) are forecast to expand at an 8.38% CAGR through 2031. They can support procedural and task-based training at a lower cost than full-motion devices. TRU Simulation delivered a Bell 505 FTD to the Royal Jordanian Air Force in November 2025. Part-task, maintenance, and weapons trainers also serve increasingly software-dependent aircraft systems. Portable and containerized systems extend the use of these devices to more locations. The military aerospace simulation and training market can, therefore, combine large full-flight programs with smaller systems that address specific readiness needs.

By Aircraft Type: Fixed-Wing Platforms Lead, but Rotorcraft Demand Accelerates
Fixed-wing aircraft accounted for 62.45% of the military aerospace simulation and training market size in 2026. Combat aircraft and transport fleets require extensive training pipelines and high-value mission-rehearsal systems. Fast-jet programs also depend on full mission devices that model advanced sensors and weapons employment. Boeing received a USD 880 million contract in June 2026 for P-8A aircrew and maintenance trainers, upgrades, and related services. These programs show the scale of fixed-wing training needs. They also illustrate the value of maintaining common devices across domestic and foreign military customers.
Rotorcraft is projected to grow at a 7.31% CAGR through 2031. Demand is supported by fleet modernization and new pilot-training programs. Lockheed Martin advanced to Phase III of the Flight School Next competition in February 2026. Its offering uses the Robinson R66 NxG and includes simulation, performance monitoring, and LVC capabilities. Rotorcraft training also requires work on terrain, low-level flight, and degraded visual conditions. These missions need support for specialist devices across the military aerospace simulation and training market.
By Training Mode: Virtual Training Gains Ground on Live Operations
Live training held 49.81% of 2026 revenue. Actual flight remains necessary for currency, safety, and operational proficiency. It gives crews exposure to aircraft handling, airspace conditions, and real team coordination. Many military syllabi, therefore, retain mandatory live flying requirements. The largest mode still operates alongside a growing synthetic training base. This balance means the military aerospace simulation and training market is not replacing live flying outright.
Virtual training is forecast to grow at a 10.62% CAGR through 2031. Its rise is supported by connected devices and more capable visual, sensor, and threat models. The September 2026 T-7A event demonstrated how simulator crews can participate alongside an airborne aircraft in a single exercise. Constructive tools add computer-generated forces that can represent threats difficult to field in live exercises. Embedded training is also narrowing the distinction between live and virtual activity. Lockheed Martin describes F-35 training functions that present simulated threats while the aircraft is in flight.
By Solution: Hardware Leads While Services Contracts Redefine Revenue Streams
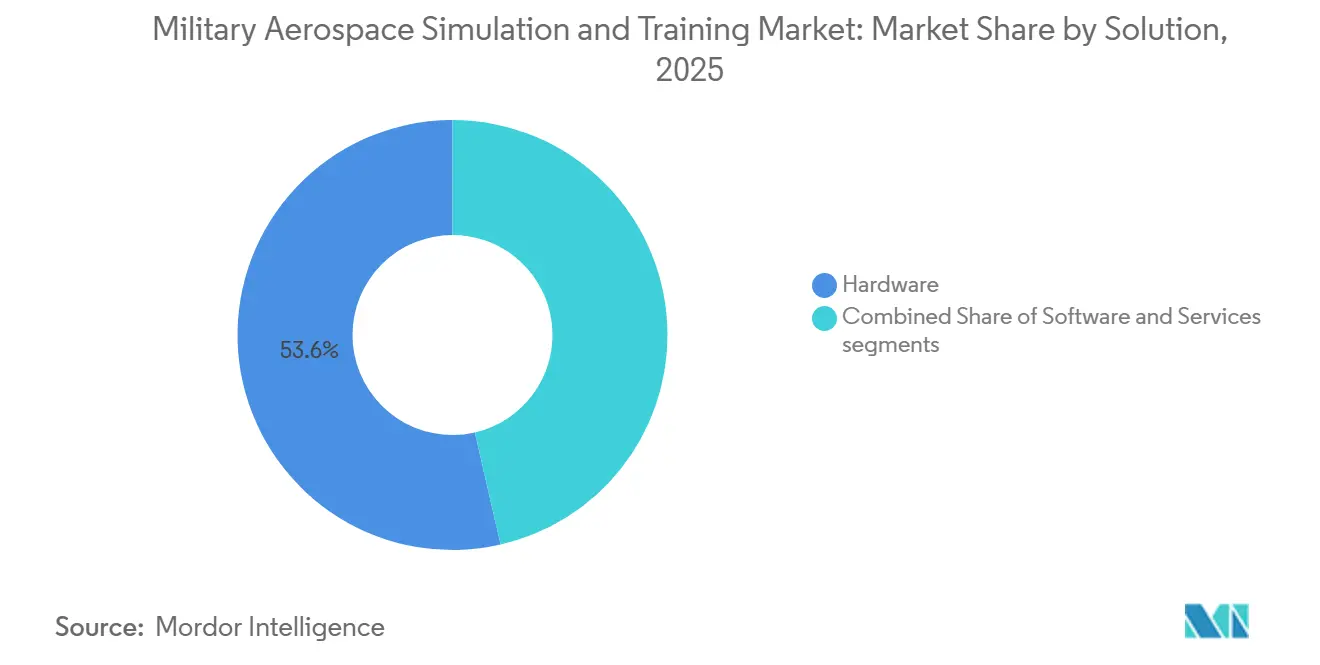
Hardware accounted for 53.59% of 2026 revenue. This segment includes cockpit replicas, visual displays, motion systems, and computing infrastructure. Full-fidelity systems require substantial capital outlays before they enter service. Device hardware also needs upgrades as aircraft software and mission systems evolve. The installed base gives suppliers recurring work in modernization and replacement. Hardware will remain central to the military aerospace simulation and training market because physical devices anchor many training programs.
Services are forecast to grow at an 8.22% CAGR through 2031. Customers increasingly seek contracts that cover instructors, technical support, software updates, and measurable availability. CAE secured a contract in July 2026 to provide Global 6500 pilot training for the US Army through March 2032. The company also received support work for the Royal Australian Navy training systems. Such arrangements shift attention from equipment delivery to training output. They offer customers more predictable support while giving providers longer revenue visibility.
By Application: Military Aviation Dominates, Space Emerges as Fastest-Growing
Military aviation held 83.98% of 2026 revenue. It includes flight instruction, mission rehearsal, combat maneuver training, and weapons qualification. These uses sit within the daily readiness cycle of air forces and naval aviation units. The Indian Air Force contracted in January 2026 for indigenous Mirage 2000 part-task combat simulators. The systems cover radar operation, target identification, weapon selection, and threat response. This application base maintains the central role of military aviation in the military aerospace simulation and training market.
Space is projected to grow at a 10.29% CAGR through 2031. Astronaut and mission operator training requires simulating rare, high-consequence situations. NASA and the Colorado Army National Guard developed flight training to prepare for Artemis landings in 2025. PaleBlue delivered a zero-G simulation engine to the European Space Agency in March 2026. These programs connect human spaceflight preparation with advanced simulation technology. They also create a smaller but increasingly relevant application area for suppliers with mission-modeling capabilities.
Geography Analysis
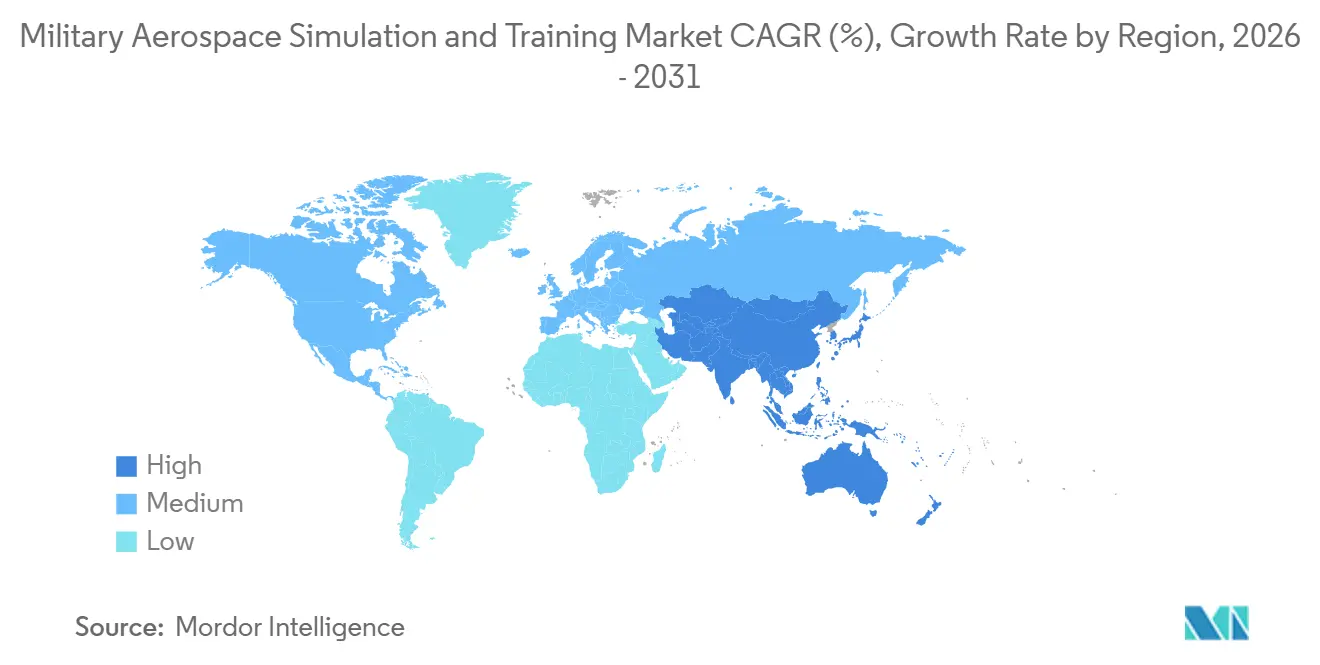
North America held 44.18% of the military aerospace simulation and training market share in 2026. The region benefits from the scale of the US readiness spending and long-running aircraft programs. The FY2026 readiness allocation included USD 45.70 billion for the Air Force and USD 51.70 billion for the Navy. Pilot shortages also increase the need to use available training capacity effectively. The Air Force aimed to graduate 1,500 new pilots in FY2026 through its revised undergraduate pilot training approach. Canada and US-based suppliers also remain important to programs serving allied operators.
Europe is driving demand through higher defense commitments, fleet replacements, and the need for coalition interoperability. NATO’s 2025 spending commitment supports a long planning cycle for readiness systems. Rheinmetall received a 2025 contract to provide C-390 simulators to the Royal Netherlands Air Force. BAE Systems, Boeing, and Saab formalized a pilot-training partnership for the United Kingdom in July 2026. European procurement increasingly weighs domestic industrial participation alongside readiness needs. Middle Eastern operators are also adding domestic training capacity through foreign military sales (FMS) and direct equipment programs.
Asia-Pacific is forecast to grow at a 7.83% CAGR through 2031. India’s FY2026-27 defense capital outlay reached INR 2.19 lakh crore (USD 25.47 billion).[3] The country is also building local simulator capacity through indigenous procurement. India’s January 2026 Mirage 2000 simulator contract reflects this direction. Japan and Australia are expanding training-system activity across air and naval domains. These programs make the Asia-Pacific region the primary growth area in the military aerospace simulation and training market.
Competitive Landscape
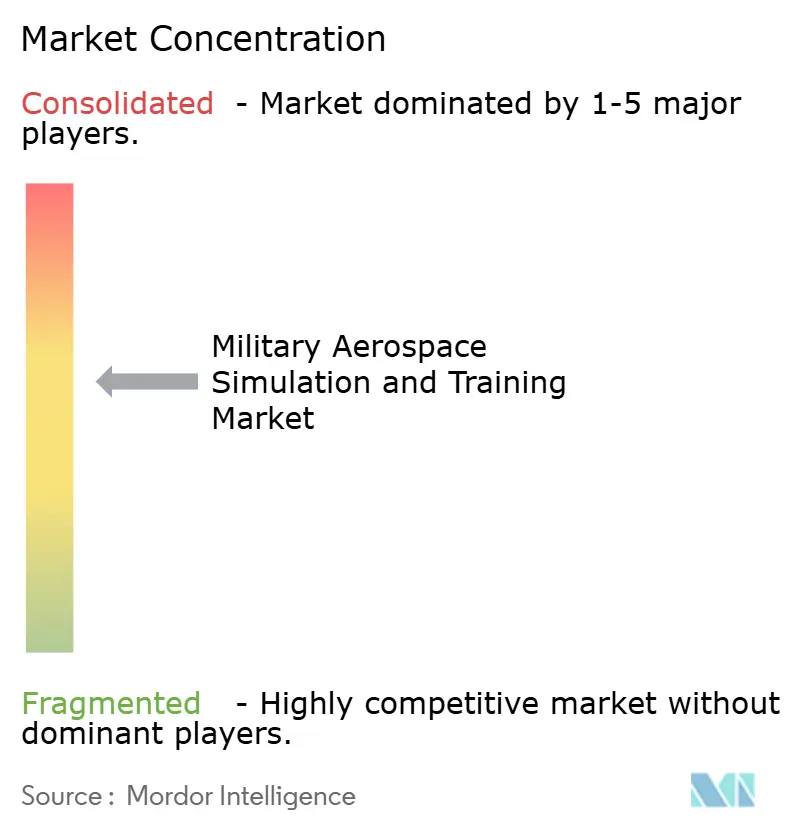
The military aerospace simulation and training market is moderately concentrated in full-flight devices. Platform knowledge, qualification standards, and long program lives favor established prime contractors. CAE Inc., The Boeing Company, Thales Group, FlightSafety International Inc., and Lockheed Martin Corporation hold important positions in high-value training programs. Boeing’s June 2026 P-8A award illustrates the advantage of an aircraft manufacturer in platform-specific training needs. CAE also benefits from qualifications in specialist device categories. This segment of the military aerospace simulation and training market has high barriers to entry.
Competition is more dispersed in courseware, part-task devices, visual systems, and networked training software. Shield AI acquired Aechelon Technology in March 2026, bringing visualization and simulation capability into its autonomous-pilot platform. That move placed simulation technology closer to the development of autonomous defense systems. Cubic received a follow-on contract in May 2026 for 140 P5 Internal Subsystems supporting F-35 Lot 21 aircraft. The systems support live training between fourth- and fifth-generation aircraft. These moves show that connected training capabilities are a competitive focus.
Providers also compete by pairing equipment with long-duration support and training delivery. CAE’s July 2026 US Army Global 6500 training contract runs through March 2032. Lockheed Martin’s Flight School Next proposal combines aircraft, simulators, monitoring, and networked training functions. Suppliers that can meet cybersecurity and interoperability requirements may gain access to more complex programs. Smaller specialists can still compete in mobile devices, visual software, and focused mission training. The competitive balance remains concentrated at the top while specialized opportunities remain open.
Military Aerospace Simulation and Training Industry Leaders
-
CAE Inc.
-
The Boeing Company
-
FlightSafety International Inc.
-
Thales Group
-
Lockheed Martin Corporation
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- September 2026: The US Air Education and Training Command conducted its first LVC flight by linking a live T-7A Red Hawk aircraft with two T-7A ground-based simulator cockpits, enabling synchronized live and synthetic training. The exercise validated secure, high-bandwidth tactical data links and a common operating picture between airborne and simulated participants, supporting the development of an integrated training architecture for future combat aviators.
- July 2026: BAE Systems, Boeing, and Saab signed a teaming agreement to develop a next-generation pilot training solution for the UK, centered on the Boeing T-7 system. The partnership also includes plans for a UK-based final assembly and integration facility to strengthen domestic capabilities in advanced military flight training systems.
Global Military Aerospace Simulation and Training Market Report Scope
The military aerospace simulation and training market encompasses solutions for military fixed-wing aircraft, rotorcraft, and space applications. It covers hardware, software, and services supporting flight, mission, tactical, combat, and weapons training, as well as space-related simulation applications.
The military aerospace simulation and training market is segmented by simulator type, aircraft type, training mode, solution, application, and geography. By simulator type, the market is segmented into full flight simulators, flight training devices, and other simulator types. By aircraft type, the market is segmented into fixed-wing aircraft and rotorcraft. By training mode, the market is segmented into live training, virtual training, and constructive training. By solution, the market is segmented into hardware, software, and services. By application, the market is segmented into military aviation and space. The report also covers the market sizes and forecasts for the military aerospace simulation and training market in major countries across different regions. For each segment, the market size is provided in terms of value (USD).
| Full Flight Simulators |
| Flight Training Devices |
| Other Simulator Types |
| Fixed-Wing Aircraft |
| Rotorcraft |
| Live Training |
| Virtual Training |
| Constructive Training |
| Hardware |
| Software |
| Services |
| Military Aviation | Flight Training |
| Mission and Tactical Training | |
| Combat Training | |
| Weapons Training | |
| Others | |
| Space |
| North America | United States | |
| Canada | ||
| Europe | United Kingdom | |
| France | ||
| Germany | ||
| Italy | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| South America | Brazil | |
| Rest of South America | ||
| Middle East and Africa | Middle East | Saudi Arabia |
| United Arab Emirates | ||
| Qatar | ||
| Rest of Middle East | ||
| Africa | South Africa | |
| Rest of Africa | ||
| By Simulator Type | Full Flight Simulators | ||
| Flight Training Devices | |||
| Other Simulator Types | |||
| By Aircraft Type | Fixed-Wing Aircraft | ||
| Rotorcraft | |||
| By Training Mode | Live Training | ||
| Virtual Training | |||
| Constructive Training | |||
| By Solution | Hardware | ||
| Software | |||
| Services | |||
| By Application | Military Aviation | Flight Training | |
| Mission and Tactical Training | |||
| Combat Training | |||
| Weapons Training | |||
| Others | |||
| Space | |||
| By Geography | North America | United States | |
| Canada | |||
| Europe | United Kingdom | ||
| France | |||
| Germany | |||
| Italy | |||
| Rest of Europe | |||
| Asia-Pacific | China | ||
| India | |||
| Japan | |||
| Australia | |||
| Rest of Asia-Pacific | |||
| South America | Brazil | ||
| Rest of South America | |||
| Middle East and Africa | Middle East | Saudi Arabia | |
| United Arab Emirates | |||
| Qatar | |||
| Rest of Middle East | |||
| Africa | South Africa | ||
| Rest of Africa | |||
Key Questions Answered in the Report
What is the projected value of military aerospace simulation and training by 2031?
The military aerospace simulation and training market is projected to reach USD 6.45 billion by 2031, growing at a 5.82% CAGR from 2026 to 2031.
Which simulator category holds the largest share?
Full flight simulators held 46.95% of revenue in 2026 because they support high-fidelity qualification on complex aircraft.
Why is virtual training growing quickly?
Virtual training is forecast to grow at a 10.62% CAGR through 2031 as LVC networks expand mission rehearsal options.
Which region is growing fastest?
Asia-Pacific is projected to grow at a 7.83% CAGR through 2031, supported by defense modernization and domestic simulator procurement.
Which application is expected to grow fastest?
Space is projected to expand at a 10.29% CAGR through 2031 as astronaut and mission operator simulation requirements increase.
How concentrated is the competitive environment?
The military aerospace simulation and training market receives a concentration score of 6 out of 10 because established primes hold strong platform-specific positions, while specialized devices, software, and services remain dispersed among many suppliers.