
Mexico Beauty And Personal Care Market Analysis by Mordor Intelligence
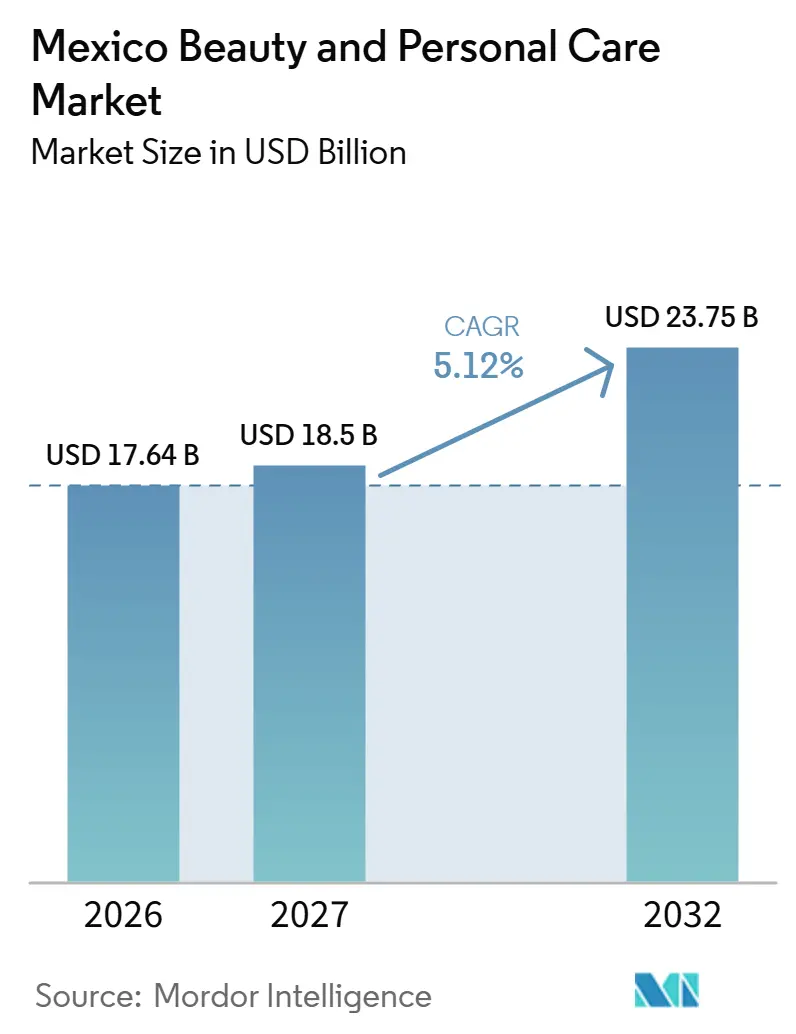
The Mexico beauty and personal care market size is projected to expand from USD 17.64 billion in 2026 and USD 18.5 billion in 2027 to USD 23.75 billion by 2032, registering a CAGR of 5.12% between 2027 and 2032.
Growth in Mexico depends on turning differentiated beauty offers into purchases through connected digital and physical retail routes. Natural-ingredient positioning and function-led skin care give suppliers distinct ways to frame their products within broader retail assortments. Production commitments offer another route to serving domestic buyers. Counterfeit exposure, input costs and currency risk increase the commercial importance of product credibility and affordability. Suppliers that substantiate authenticity and preserve accessible prices through input-cost and currency swings are better placed to retain buyers as digital and specialty retail expand product choice.
Key Report Takeaways
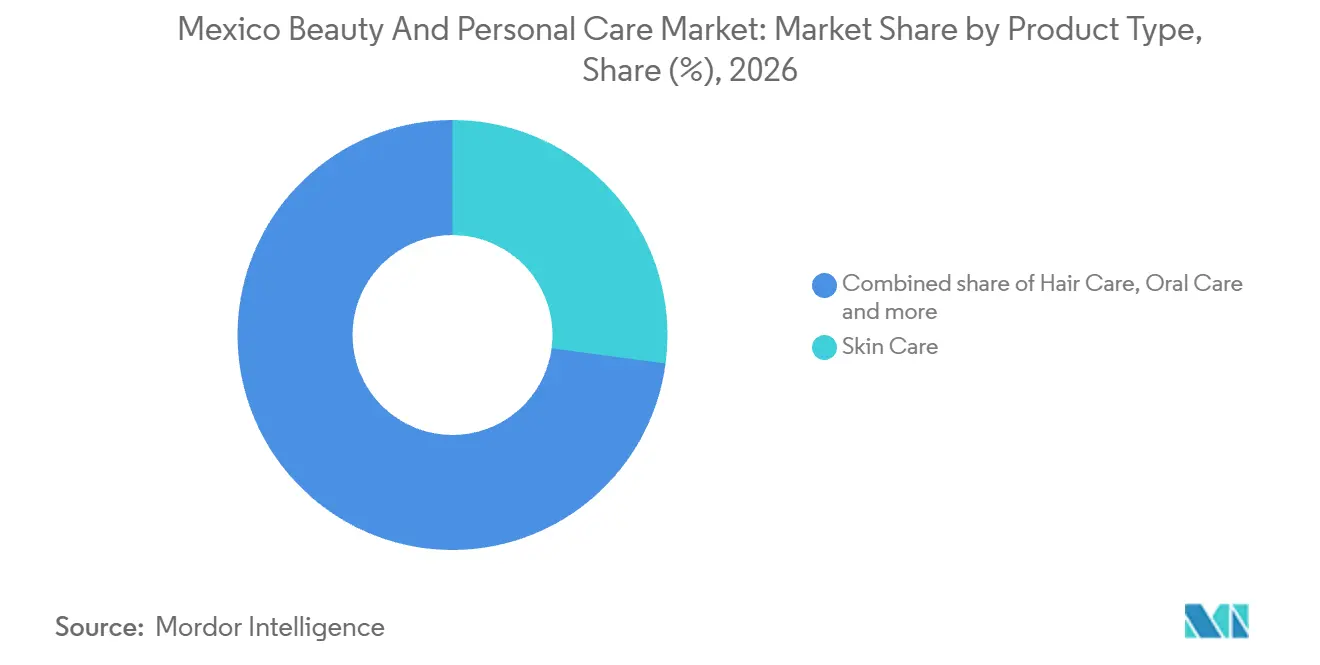
- By product type, skin care led with a 27.12% Mexico beauty and personal care market share in 2026 and is forecast to be the fastest-growing segment at a CAGR of 5.55% between 2027 and 2032.
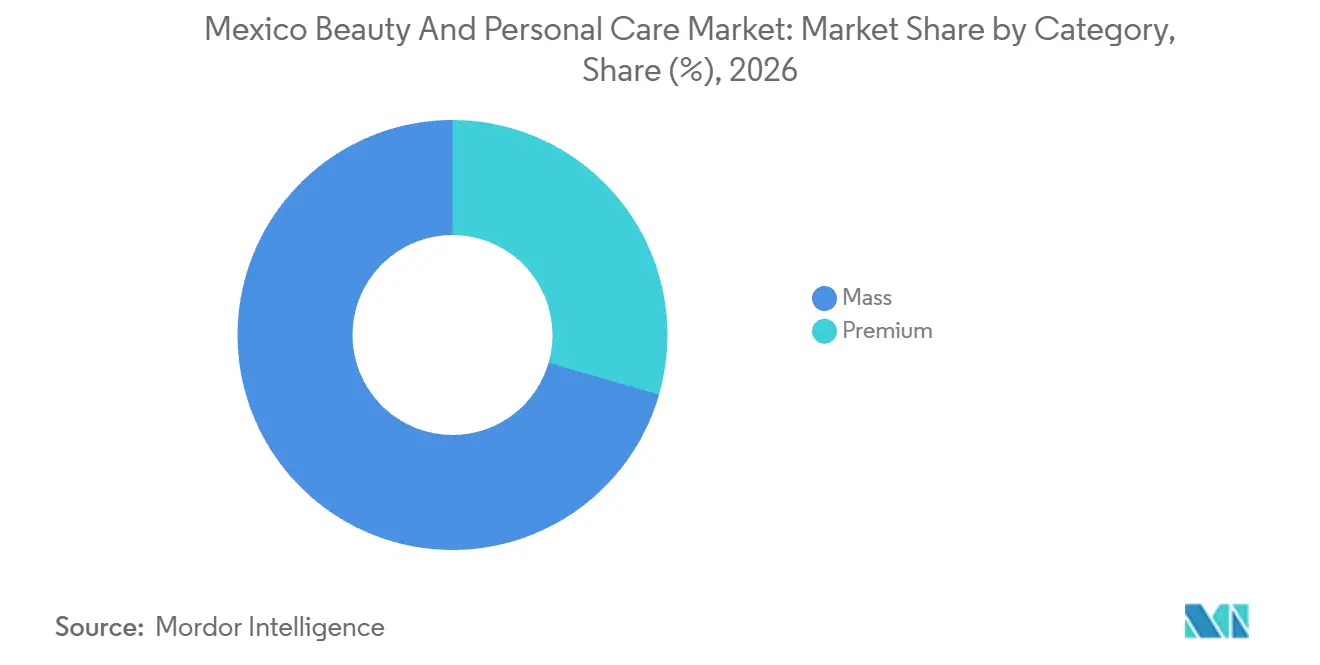
- Across price categories, mass products held a 70.53% share of the Mexico beauty and personal care market size in 2026, while premium is the fastest-growing segment with a CAGR of 5.45% between 2027 and 2032.
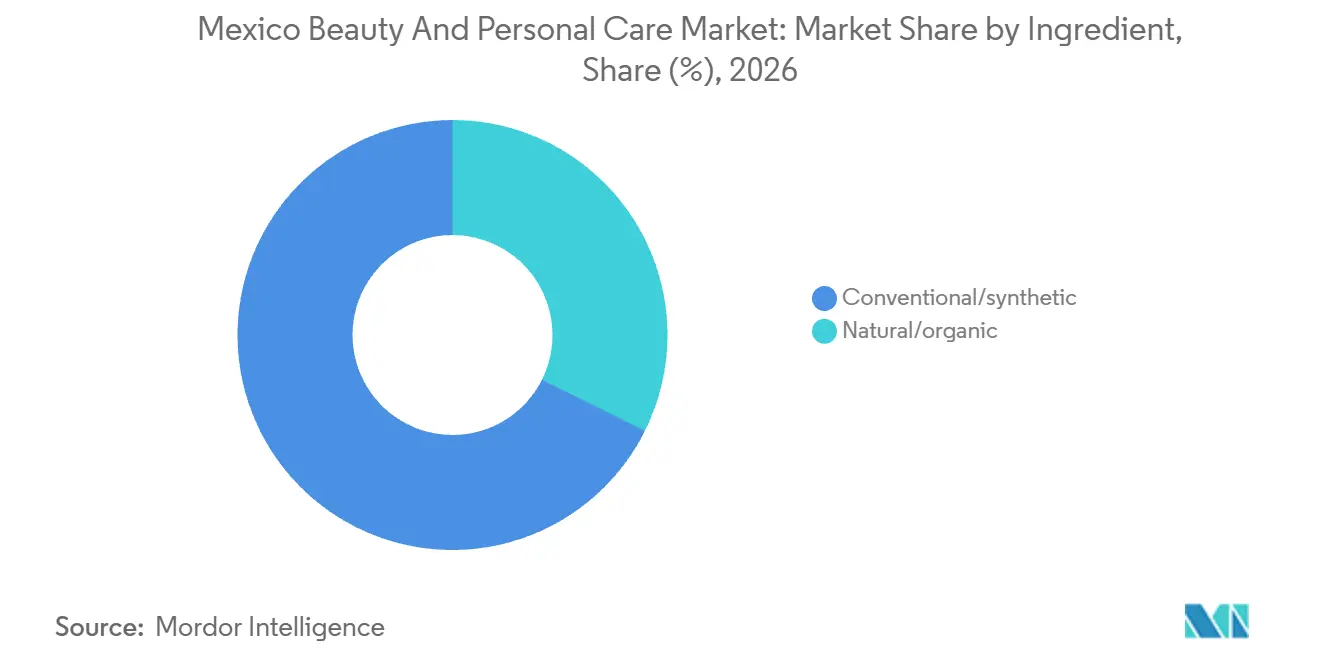
- In the ingredient mix, conventional/synthetic products held 67.64% of retail revenue in 2026, with natural/organic products forecast to grow fastest at a CAGR of 6.05% between 2027 and 2032.
- Distribution channels were led by supermarkets/hypermarkets with 34.43% of retail revenue in 2026, while online retail is the fastest-growing segment with a CAGR of 6.55% between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Mexico Beauty And Personal Care Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand for natural & organic formulations | +1.5% | Nationwide | Medium term (2-4 years) |
| E-commerce and social-commerce boom | +1.8% | Nationwide | Short term (≤ 2 years) |
| Premiumization led by higher disposable income | +1.4% | Nationwide | Medium term (2-4 years) |
| Men's grooming adoption surge | +0.9% | Nationwide | Short term (≤ 2 years) |
| Masstige hybrid brands targeting Gen Z | +0.5% | Roma neighborhood in Mexico City | Medium term (2-4 years) |
| Near-shoring incentives for cosmetic manufacturing | +0.4% | Aguascalientes and Nuevo León | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising demand for natural & organic formulations
Natural-ingredient positioning gains commercial weight when a specific formulation reaches a mainstream beauty assortment. Ulta Beauty opened its first Mexico stores with retail partner Axo in August 2025, including AloeVida in its local-brand assortment. AloeVida's body cream sold through Ulta Mexico uses organic aloe vera as its principal ingredient. The cream connects the retailer's expanded local-brand offer to an identifiable ingredient proposition rather than a general natural-brand description. Naming organic aloe vera as the principal ingredient gives the body cream a point of differentiation within the retailer's assortment and a clearer basis for comparison with other body creams.
E-commerce and social-commerce boom
The commercial value of digital selling lies in connecting beauty discovery with an immediate route to purchase. The Mexican Online Sales Association (AMVO) identified e-commerce as a principal growth engine for beauty in Mexico in 2025, alongside other consumer packaged goods categories. Mexican retail e-commerce value grew 19.2% year over year in 2025.[1] The association's 2026 study also found social commerce gaining ground, especially among Gen Z. This combination supports linking younger shoppers' social discovery to a beauty offer they can buy within the connected selling experience. Discovery-to-order conversion can become a commercial test for newer beauty brands before national shelf coverage, lowering the physical distribution hurdle to initial sales.
Premiumization led by higher disposable income
Premiumization can increase spending per beauty purchase when discretionary income allows shoppers to choose a higher-priced product. Worldpanel by Numerator's Q2 2025 Mexico household fast-moving consumer-goods findings showed premium brands increasing their spending share while mainstream brands continued to lead. This points to premium demand strengthening without replacing mainstream purchasing. For beauty suppliers, a higher-priced offer therefore needs a distinct product proposition that gives the shopper a reason to spend more on that purchase. Because mainstream brands still lead, a premium offer is weighed against the mainstream item already in the basket, so the price gap is what the supplier has to justify.
Men's grooming adoption surge
Men's grooming offers suppliers both functional and personal-image propositions, with fragrances providing a measurable example of demand. The cosmetics industry chamber CANIPEC reported that men's-fragrance sales in Mexico grew 5.2% in 2025. CANIPEC also said consumers view men's fragrances as expressions of identity, confidence and well-being and as an accessible luxury. CANIPEC's broader male-care assessment also described continued consumer investment in products offering functional benefits, efficacy and alignment with personal image. These observations support differentiated fragrance offers while preserving functional credibility across the wider grooming range. Accessible luxury sets a boundary for fragrance positioning, because an identity-led offer must preserve the affordability implicit in that consumer role.
Restraints Impact Analysis of Mexico Beauty And Personal Care Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Counterfeiting & grey-market imports | -0.6% | Nationwide | Long term (≥ 4 years) |
| Raw-material cost volatility & FX risk | -0.4% | Nationwide | Short term (≤ 2 years) |
| Cross-border customs rules for e-commerce | -0.3% | Nationwide | Short term (≤ 2 years) |
| Water-scarcity sustainability compliance costs | -0.2% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Counterfeiting & grey-market imports
Counterfeiting makes product authenticity an additional purchase decision for consumers and an additional selling burden for legitimate suppliers. Mexico's industrial property institute IMPI identified cosmetics among common counterfeit-product categories in its study of notable piracy markets in Mexico City. Its identification of a market did not mean that all its goods or vendors were involved in piracy. Separately, an August 2025 risk notice from Mexico's sanitary regulator COFEPRIS said many skin-lightening products entered Mexico through illegal channels. An authorized seller therefore has a commercial reason to make the product's supply route verifiable, since a product claim alone does not establish authenticity. The remaining constraint is the effort required to establish trust before a shopper can confidently compare offers and complete a purchase.
Raw-material cost volatility & FX risk
Input inflation and currency exposure can constrain beauty demand through the cost of maintaining an affordable finished product. JAFRA, BeFra's beauty and personal-care business, saw raw-material costs increase 6% in 2025 versus 2024 across its Mexico and U.S. operations.[2] BeFra's filing for 2025 also identified approximately 30% of JAFRA's raw materials as U.S. dollar-priced, creating exchange-rate risk. Foreign-exchange losses on inventory purchases were among several contributors to higher cost of sales that year. These exposures leave an affected producer sensitive to both the supplier's price and the currency used to settle the purchase. Absorbing the burden reduces funds available for expansion, while passing it through raises the price consumers must pay.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Mexico Beauty And Personal Care Market Segment Analysis
By Product Type:
Skin Care Combines Scale With Application-Led GrowthSkin care accounted for a 27.12% share of the Mexico beauty and personal care market size in 2026 and is the largest and fastest-growing segment, with a 5.55% CAGR forecast for 2027 to 2032. CANIPEC reported that sunscreen purchases in Mexico rose 13.1% during 2025.[3] An already substantial revenue base makes the growth opportunity relevant both to established ranges and to more focused product offers. The sunscreen example makes sun protection a concrete product-development priority within that broader opportunity, with the commercial decision centered on an identifiable skin-care application.
CANIPEC's director general described a youth skin-care routine of cleansing, hydration and sunscreen, recommending morning and night use. That recommended sequence offers a basis for organizing a skin-care range around complementary uses, with each product serving a defined part of the offer. Fragrances and color cosmetics featured in Worldpanel's Q2 2025 Mexico findings, which reported 20% personal-care ticket growth as shoppers added products per trip. The basket expansion creates a separate opportunity to widen a personal-care purchase beyond one functional product. These are different assortment decisions, with routine-led development deepening skin-care coverage and adjacent product choices extending the shopping basket.



By Category:
Mass Scale Coexists With Premium Assortment ExpansionMass products represented a 70.53% Mexico beauty and personal care market share in 2026, making them the largest segment. In 2025, brands across several Mexican consumer-goods categories, including personal hygiene, used smaller packages or reformulations to maintain prices and retain consumers amid inflation and higher raw-material costs. For a mass-tier hygiene supplier, that response makes the affordable purchase price a concrete constraint on product redesign. A smaller pack can preserve the price paid at checkout while supplying less product, so defending access for price-sensitive buyers requires a separate decision about the quantity offered.
Premium is the fastest-growing segment, with a forecast CAGR of 5.45% between 2027 and 2032. Sephora Mexico added Make Up by Mario, Charlotte Tilbury and Patrick Ta to its assortment in 2025, with Charlotte Tilbury identified as a luxury brand. The additions give suppliers access to consumers through Sephora's branded assortment, bringing different product propositions into the same retail setting. Charlotte Tilbury's explicit luxury positioning makes the upgrade proposition brand-specific, so suppliers need a premium rationale beyond sharing shelf space with newly added names.

By Ingredient:
Formulation Scale Meets Natural-Ingredient Retail EntryConventional/synthetic products held 67.64% of retail revenue in 2026 and were the largest segment. For Mexican shoppers, the segment's proposition combines proven performance with lower cost across skin care, hair care, oral care and the other product types. Keeping those benefits together matters for repeat use, because an ingredient change has to preserve the function buyers are paying for. Suppliers need to defend this proposition application by application, with hair-dye color performance and deodorant odor control giving distinct reasons to retain an established formulation.
Natural/organic products are the fastest-growing segment, with a forecast CAGR of 6.05% between 2027 and 2032. Nopalera uses oils extracted from nopal cactus seeds and natural butters in its body-care products. In September 2025, Ulta Beauty named Nopalera among Latin-founded brands it planned to sell in Mexico under its Proudly Latino banner. The combination links an identifiable formulation approach with a route into a named beauty retailer, making channel selection central to commercialization. The banner groups Nopalera by founder origin rather than ingredient, leaving its nopal-based formulation to distinguish the body-care offer within that grouping.
By Distribution Channel:
Store Networks Anchor Reach As Digital Selling ExpandsSupermarkets/hypermarkets held 34.43% of retail revenue in 2026, making them the largest segment. The ANTAD retail trade association's 2025 annual report recorded 22 member self-service chains with 3,683 stores and 8.91 million square meters of sales floor. That network gives a packaged-product supplier a substantial physical channel through which to place an affordable or differentiated beauty offer. A relationship with an established self-service chain can provide a supplier multiple selling locations, a wider physical route than a single branded outlet offers.
Online retail is the fastest-growing segment, with a forecast CAGR of 6.55% between 2027 and 2032. By May 2026, Amazon México accounted for more than 30% of total sales for some Estée Lauder Companies brands launched on its Mexico store. Mercado Libre recorded 2 million sunscreen searches, 616,000 facial-serum searches and 2 million matte-lipstick searches in Mexico in 2025. Converting product-specific searches into orders is the commercial task online, and Amazon's result shows the channel's potential importance to some brands' sales. Specialty stores added physical access in parallel, with Sephora opening its 52nd Mexico store in Villahermosa as its final opening of 2025.
Geography Analysis
The manufacturing locations in San Luis Potosí and Mexico City give suppliers a reason to distinguish production geography from the geography of consumer purchases. L'Oréal México operates plants in San Luis Potosí and Xochimilco, Mexico City, making dermatological products, personal hygiene products and hair dyes for more than 15 company brands. For an industrial supplier, this footprint identifies places where a multi-brand beauty producer operates, making local manufacturing requirements relevant to the commercial offer. A consumer-sales strategy and a manufacturing-supply strategy therefore need different geographic priorities, even when both address products that eventually enter the same national retail category.
Querétaro illustrates a different change, with specialty retail adding a consumer-facing route for several packaged beauty categories within a single operating store. Ulta Beauty opened at Puerta La Victoria on August 22, 2026, as its 13th Mexico store, offering makeup, skin care, hair care and fragrances. For packaged-beauty sellers, the opening adds a physical location at which a multi-category offer can be presented to consumers in that city. The opening extended Ulta's physical network into a new city, adding geographic coverage rather than another outlet in a city it already served.
Aguascalientes and Monterrey illustrate different kinds of footprint change, with manufacturing consolidation in one location and an additional consumer-facing store in the other. The Aguascalientes governor inaugurated Edgewell's new personal-care plant in October 2025, which consolidated Edgewell's existing operations from Obregón and Mexico City. Sephora opened its fourth Monterrey store at Esfera Monterrey in 2025, bringing its nationwide total to 49 locations at that time. The plant brought existing domestic activity to a new site, while the store added another selling location within Sephora's retail network. In Aguascalientes, supplier outreach can focus on relocated production requirements, while Monterrey offers another consumer selling point within an established urban network.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions, Mexico's national regime and Mexico City, from the perspective of a seller preparing labels for prepackaged cosmetics. NOM-141 requires the specified consumer information in Spanish, with Spanish characters at least as large as those used for other languages. A nationally specified label gives the seller a common product-compliance task across these sales locations, while requiring preparation of the information before the product is offered to consumers.
Regulatory Table of Mexico Beauty And Personal Care Market
| Decision factor | Mexico | Mexico City |
|---|---|---|
| Primary authority | COFEPRIS and PROFECO, within their respective competencies | COFEPRIS and PROFECO under the nationally applicable standard, within their respective competencies |
| Key instruments or direction | NOM-141-SSA1-SCFI-2012 for prepackaged cosmetics intended for final consumers | The same national NOM-141 labeling requirements apply to final-consumer prepackaged cosmetics |
| Commercial effect | Prepare the specified Spanish-language product information | Apply the national Spanish-language labeling specification to cosmetics sold locally |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
Mexico's Medium rating reflects the required label-preparation work alongside the commercial benefit of a defined national specification. Mexico City's Medium rating follows the same product-label duty, allowing the seller to use a common core label for both sales locations. Both No change judgments reflect continuity in that specification, supported by its operative status and the economy ministry's February 2024 confirmation review.
Value Chain Stages
The comparison follows material distribution, packaging production and finished-product manufacturing, showing where each supplier earns revenue. Grupo Pochteca's subsidiaries distribute raw materials to personal-care and home-care customers in Mexico and other countries. That upstream role makes material qualification commercially significant because a substitute must suit the product that the downstream manufacturer is commissioned to make.
Value Chain Analysis Table of Mexico Beauty And Personal Care Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Raw-material distribution | Industrial raw-material distributors such as Grupo Pochteca subsidiaries | Raw-material sales | Qualification of substitute ingredients | Qualify alternative sources against formulation specifications |
| Cosmetic packaging production | Cosmetic packaging manufacturers such as Shyahsin Packaging México | Packaging-component sales | Package changes requiring component validation | Validate alternative packaging before changing supply |
| Finished-product manufacturing | Personal-care and cosmetics contract manufacturers such as Absara | Contract-manufactured product sales | Coordination of materials and packaging specifications | Agree specifications before commissioning production runs |
| Source: Mordor Intelligence | ||||
Shyahsin Packaging México manufactures plastic packaging for mascara, lipstick, concealer and bottles, while Absara contract-manufactures personal-care products and cosmetics in Mexico. Their separate roles show why a brand's manufacturing decision also requires a packaging decision, even when the finished product comes from a contract producer. Packaging-component sales and contract-manufactured product sales are distinct sources of supplier value in this arrangement. Qualifying alternative materials and packaging against common product specifications connects the resilience response to both stages and gives the brand a basis for coordinating substitution decisions.
Competitive Landscape
Market Concentration
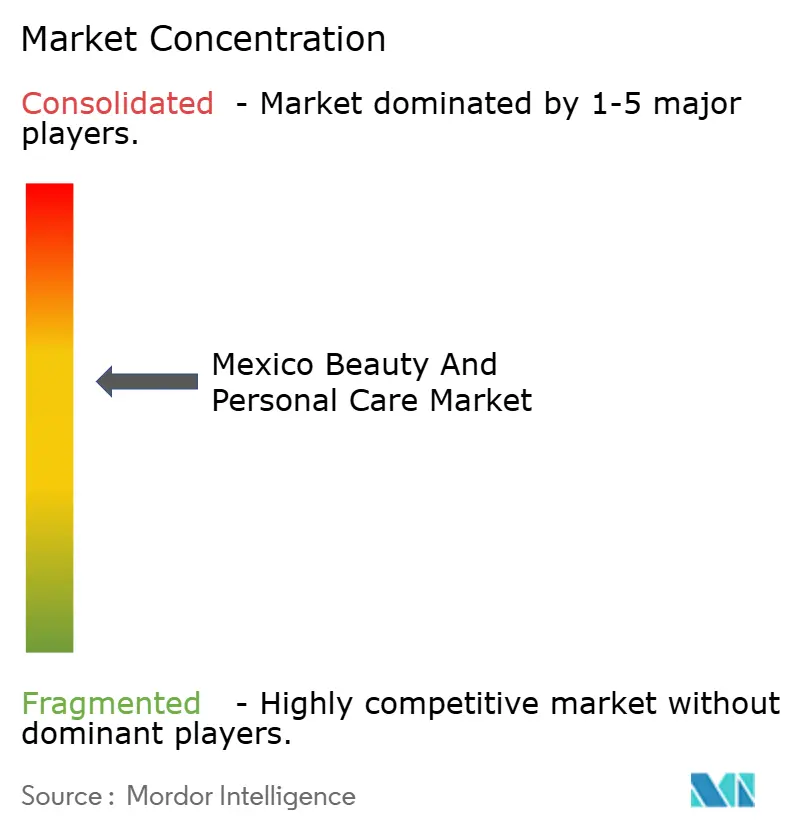
Competition combines suppliers working through retailers with Natura's stores, online sales and direct-selling consultants. Major participants include Unilever PLC, Procter & Gamble Co., Colgate-Palmolive Co., Natura Cosméticos S.A. and L'Oréal SA. In May 2025, Natura reached Mexican buyers through stores, online sales and more than 500,000 beauty consultants. P&G Mexico reported high-single-digit organic sales growth and a value-share gain of more than one percentage point across its portfolio in fiscal 2026, alongside longer-term joint business planning with retailers. Retailer coordination and consultant reach offer different ways to secure consumer access, making a supplier's route to buyers a competitive asset alongside its product portfolio.
In May 2025, Unilever announced a Mexico investment program of MXN 30 billion (approximately USD 1.53 billion) for 2025 to 2028. The program covered manufacturing capacity, production lines, logistics and brands across Mexico, including a Nuevo León factory intended for beauty and daily-care products. Natura opened its first Mexican franchise in Morelia in late August 2025, extending its consumer-facing retail presence. Natura's franchise added a point of sale in 2025, whereas the supply benefit of Unilever's 2025 to 2028 plan depends on bringing the announced manufacturing capacity into production.
Colgate-Palmolive reported high-single-digit Mexico organic sales growth in Q4 2025 and described its Luminous White Color Correct toothpaste launch as performing well in Mexico and Brazil. L'Oréal reported 8.3% like-for-like Latin America sales growth in 2025, naming Mexico and Brazil among particularly strong performers. Colgate-Palmolive's launch illustrates an established competitor using a named product benefit, while L'Oréal's regional results show incumbent momentum. For prepackaged cosmetics, the NOM-141 cosmetics labeling standard requires verifiable consumer information and prohibits claims attributing drug actions to the product. Challengers face a differentiated cosmetic promise bounded by the requirement to substantiate it and to keep medicinal actions out of cosmetic claims.
Mexico Beauty And Personal Care Industry Leaders
-
Unilever PLC
-
Procter & Gamble Co.
-
Colgate-Palmolive Co.
-
Natura Cosméticos S.A.
-
L'Oréal SA
- *Disclaimer: Major Players sorted in no particular order
Mexico Beauty And Personal Care Market Companies Covered in this Report
- L'Oréal SA
- Unilever PLC
- Procter & Gamble Co.
- Colgate-Palmolive Co.
- Natura Cosméticos S.A.
- Beiersdorf AG
- Kenvue Inc.
- Estée Lauder Inc.
- Mary Kay Inc.
- Tío Nacho Mexican Herbs
- Haleon Plc
- Kimberly-Clark de México
- Genomma Lab Internacional
- LVMH (Louis Vuitton Moët Hennessy)
- Lunalabs
- Kao Corp.
- Coty Inc.
- Revlon Inc.
- Shiseido Inc
- Laboratorios Avant SA
Key Opportunities for Market Participants
The comparison separates opportunities in locally manufactured products, branded retail access and specialty-store assortments. Natura's August 2026 production and retail targets connect a prospective increase in domestic supply with a wider consumer-facing network. These involve distinct commercial decisions, including the producer's choice of product supply and retailers' selection of the branded ranges that receive assortment access.
Market Opportunities Table of Mexico Beauty And Personal Care Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Locally manufactured packaged beauty ranges | In August 2026, Natura targeted domestic production of 60% of its branded products consumed in Mexico in 2027, versus 30%, through Celaya expansion and supplier development | Natura-brand product shoppers | Prioritize finished products suited to domestic production | Completing capacity expansion and qualifying supply | Natura Cosméticos S.A. and its packaged-product customers |
| Beauty purchases through branded stores | In August 2026, Natura targeted 50 Mexico stores in 2027, after expecting 24 at the end of 2026 | Shoppers using Natura's retail network | Match packaged assortments to new retail locations | Converting outlet expansion into product purchases | Natura Cosméticos S.A. and retail operators |
| Packaged cosmetics for specialty retail | Sephora opened its first Durango store at Paseos Durango on October 9, 2026, as its 57th Mexico location | Specialty-store cosmetics shoppers | Seek assortment access through the specialty channel | Securing retailer selection for the proposed range | Sephora and prospective packaged-beauty brands |
| Source: Mordor Intelligence | |||||
Natura's two targets create a practical opening in matching the domestic product range to an expanding branded retail network. In August 2026, Natura said 30% of its branded products consumed in Mexico were manufactured domestically and targeted 60% in 2027. Its planned Celaya expansion and domestic supplier development create potential supply work for Mexican component and ingredient producers. Reaching the 60% domestic-production target depends on the planned Celaya expansion and domestic supplier development, which would determine how quickly locally made ranges could serve the larger store network.
Recent Industry Developments in Mexico Beauty And Personal Care Market
- Oct 2026: Sephora México opened its first Durango store at Paseos Durango on October 9, as its 57th Mexico location, offering makeup, skin care, hair care and fragrances.
- Aug 2026: Natura Mexico said it was expanding its Celaya plant and developing domestic suppliers to raise local production from 30% to 60% of Natura-brand products consumed in Mexico in 2027.
- Aug 2026: Ulta Beauty opened its Puerta La Victoria store in Querétaro on August 22, as its 13th Mexico location, offering makeup, skin care, hair care and fragrances.
Mexico Beauty And Personal Care Market Report Scope and Research Methodology
Market Definition and Coverage
Mexico beauty and personal care market measures annual retail spending on packaged beauty and personal care products in Mexico. Sales are classified by product type, price tier, formulation, and retail channel.
Scope exclusions: Professional-only salon and clinic services, medical procedures, separately sold cosmetic and personal care raw materials, and separately sold beauty and personal care appliances and devices are excluded.
Segments Covered in This Report
- By Product Type
- Skin Care
- Facial Care
- Body Care
- Lip Care
- Hair Care
- Shampoo
- Conditioner & Masks
- Styling Products
- Other hair care products
- Oral Care
- Bath & Shower
- Deodorants
- Fragrances & Perfumes
- Color Cosmetics
- Facial Cosmetics
- Eye Make Up
- Lip & Nail Make Up
- Skin Care
- By Category
- Mass
- Premium
- By Ingredient
- Conventional/synthetic
- Natural/organic
- By Distribution Channel
- Supermarkets/ Hypermarkets
- Specialty Stores
- Drugstores/pharmacies
- Online Retail
- Others
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as CANIPEC's 2024 annual report and industry statistics, the Mexican Online Sales Association's annual ecommerce study, and Data México's trade data can inform category context, retail activity, channel development, and cross-border product flows. These sources describe different parts of the market and should be matched to the packaged-product retail boundary before use.
Company filings, investor materials, annual reports, and reputable Mexican business press can supplement those sources by clarifying product portfolios, manufacturing activity, channel access, and reported sales trends. The named sources are illustrative and not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and surveys can include Mexican beauty and personal care manufacturers, distributors, retailers, and category specialists, with participants familiar with product sales, pricing, formulation, and channel movements. Their input can test the interpretation of secondary indicators, clarify gaps in category coverage, and be compared across company, retail, and public data before estimates are incorporated.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | |
| Mid tier: 42% | Functional/Unit leaders: 35% | |
| Smaller Players: 24% | Managers: 45% |
Market-Sizing & Forecasting
The estimate starts with a top-down view of annual consumer retail spending in Mexico on the accepted packaged product groups, then checks selected totals through supplier roll-ups and sampled retail price times units sold. Category shares are built by comparing product revenue across skin care, hair care, oral care, bath and shower, deodorants, fragrances, and color cosmetics, while price tier, ingredient type, and channel shares classify the same sales rather than add revenue. Retail revenue, average selling prices, household purchasing power, category-specific demand, and the balance between physical and online retail provide indicators for the historical estimate and outlook. A multivariate regression can relate these demand and price indicators to annual market revenue, with scenario analysis used where available series are short or a structural change such as channel expansion shifts the relationship. Missing values can be bounded from adjacent years, category trends, and comparable retail indicators, with assumptions checked against Mexican respondent evidence and selective channel or supplier estimates before inclusion.
Data Validation & Update Cycle
Analysts triangulate category sales, retail indicators, trade context, and company disclosures, checking that each signal reflects consumer purchases rather than production or an intermediate sale. They investigate unusual year-to-year movements and material differences between independent sources, document the explanation, and re-contact relevant respondents when definitions, timing, or reported values remain unclear. A second analyst reviews the boundary, calculations, source treatment, and forecast logic before sign-off. The evidence is refreshed annually, revisited sooner after material market or regulatory events, and checked again in a fresh pre-delivery review.
Mordor Intelligence's Mexico Beauty and Personal Care Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. Mexico beauty and personal care market measures annual retail spending on packaged beauty and personal care products in Mexico.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Retail revenue, average selling prices, household purchasing power, category-specific demand, and the balance between physical and online retail provide indicators for the historical estimate and outlook.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 18.5 B (2027) | |
| Global Consultancy A | USD 11.17 B (2025) | At its 2025 base, this estimate is 39.6% below this report's 2027 value of USD 18.5 B, 2 years later. |
| Regional Consultancy B | USD 10.76 B (2024) | At its 2024 base, this estimate is 41.8% below this report's 2027 value of USD 18.5 B, 3 years later. |
Mordor Intelligence's analysts triangulate category sales, retail indicators, trade context, and company disclosures, checking that each signal reflects consumer purchases rather than production or an intermediate sale.
Key Questions Answered in the Report
What is the Mexico beauty and personal care market size and growth outlook?
The size is projected at USD 18.5 billion in 2027 and USD 23.75 billion by 2032, with a CAGR of 5.12% between 2027 and 2032.
Which forces are increasing demand for beauty and personal-care products?
Digital retail and men's grooming support demand. CANIPEC reported 5.2% growth in men's-fragrance sales in Mexico in 2025, while AMVO identified digital selling as a beauty growth engine.
Which product category leads beauty and personal-care sales?
Skin care was the largest segment, with 27.12% of retail revenue in 2026. It is forecast to grow at a CAGR of 5.55% between 2027 and 2032.
Which companies are major competitors in packaged beauty and personal care?
Major competitors include Unilever PLC, Procter & Gamble Co., Colgate-Palmolive Co., Natura Cosméticos S.A. and L'Oréal SA.
What challenge could constrain beauty and personal-care expansion?
Raw-material and currency exposure can pressure affordability. JAFRA's raw-material costs rose 6% in 2025 versus 2024 across its Mexico and U.S. operations.
Where are packaged-beauty manufacturing and retail activities developing in Mexico?
Manufacturing and retail investment create different local roles. Edgewell's Aguascalientes plant opened in October 2025, while Ulta Beauty opened its 13th Mexico store at Puerta La Victoria in Querétaro on August 22, 2026.