
Malaysia Plastics Market Analysis by Mordor Intelligence
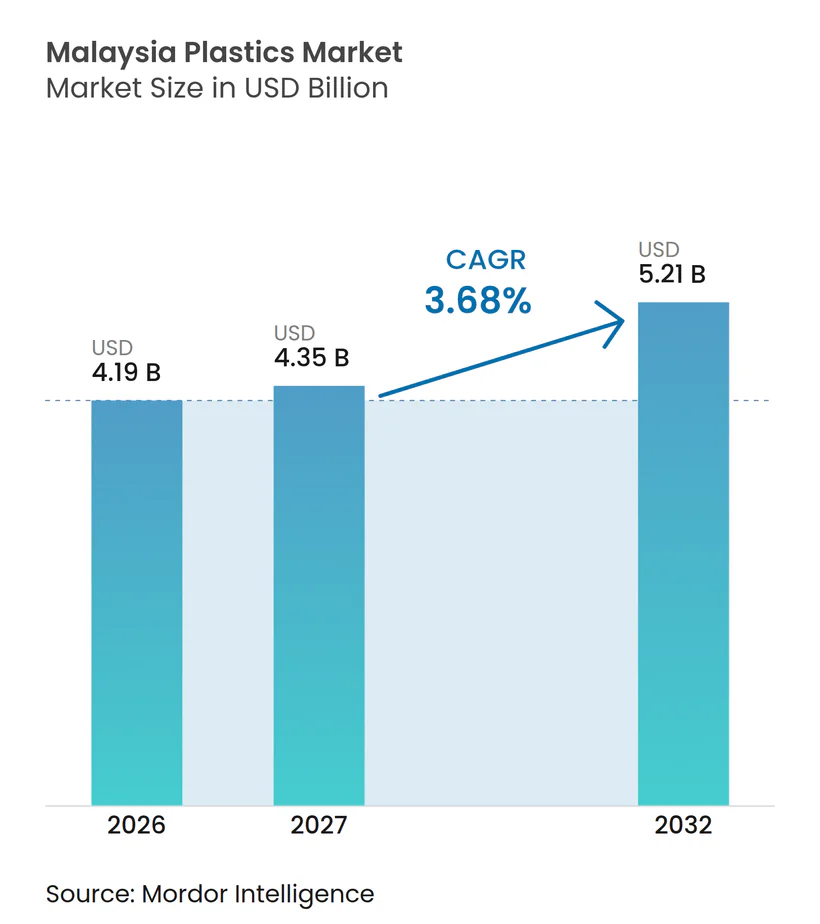
The Malaysia plastics market size is projected to expand from USD 4.19 billion in 2026 and USD 4.35 billion in 2027 to USD 5.21 billion by 2032, registering a CAGR of 3.68% between 2027 and 2032.
Food production and electronics manufacturing support material demand in Malaysia, while brand circularity programs favor recycled-content packaging. The West Asia conflict disrupted feedstock flows through the Strait of Hormuz from March 2026, increasing converters' cost exposure. Tax incentives can support qualifying resin investment, but restrictions on selected single-use formats make application choice commercially important. Broader rigid- and flexible-packaging capabilities offer converters a way to address demand across formats. Suppliers able to qualify recycled-content grades for food and beverage packaging can pursue brand demand while reducing reliance on carry-bag outlets affected by restrictions.
Key Report Takeaways
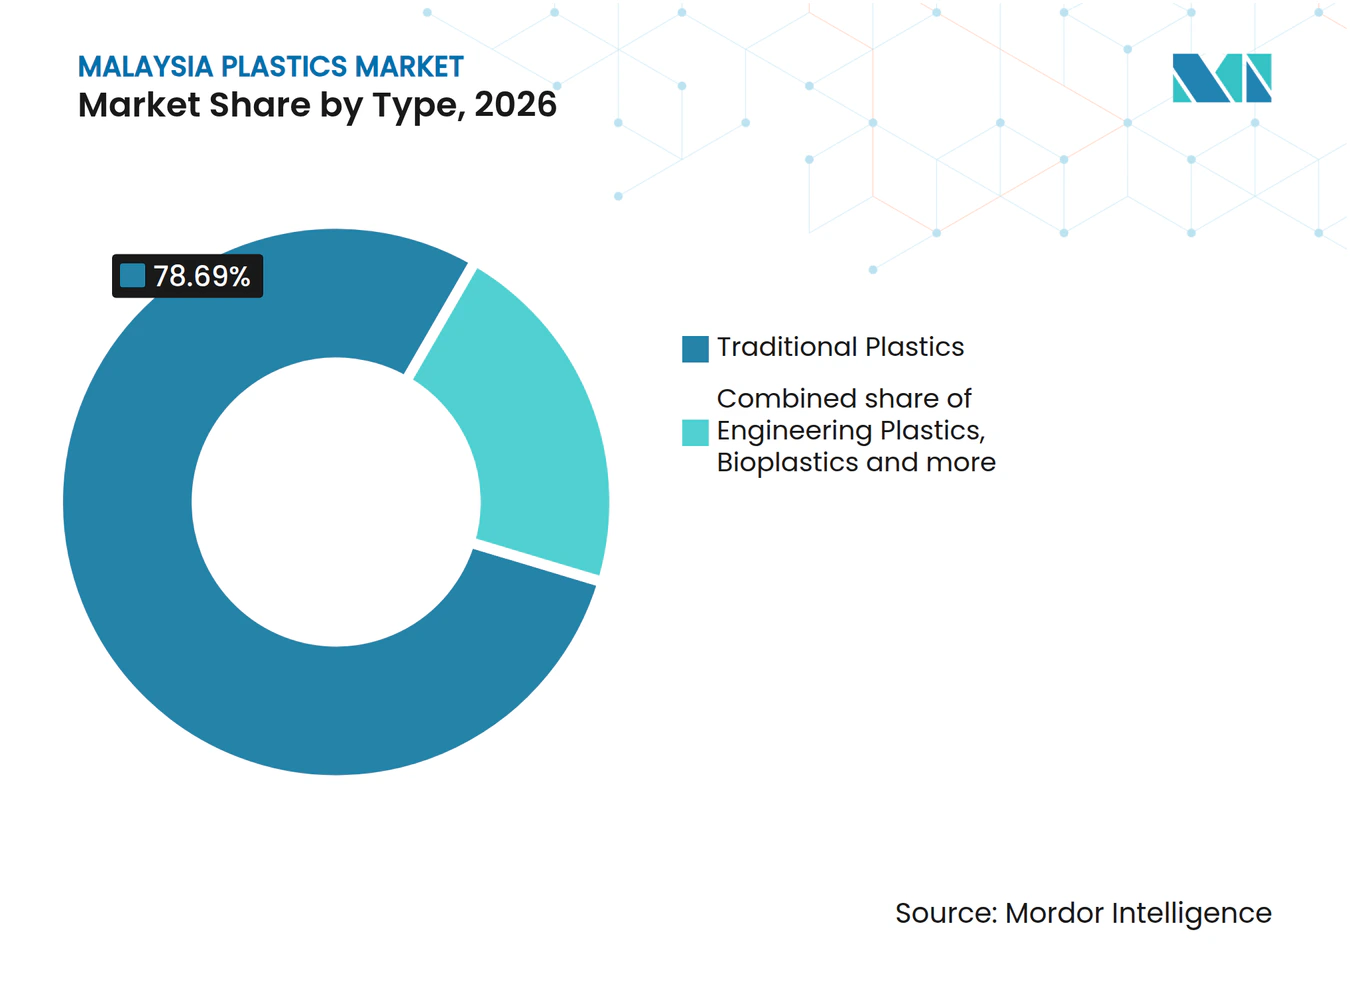
- By type, traditional plastics held a 78.69% Malaysia plastics market share in 2026, while bioplastics are forecast to grow fastest at a CAGR of 4.66% between 2027 and 2032.
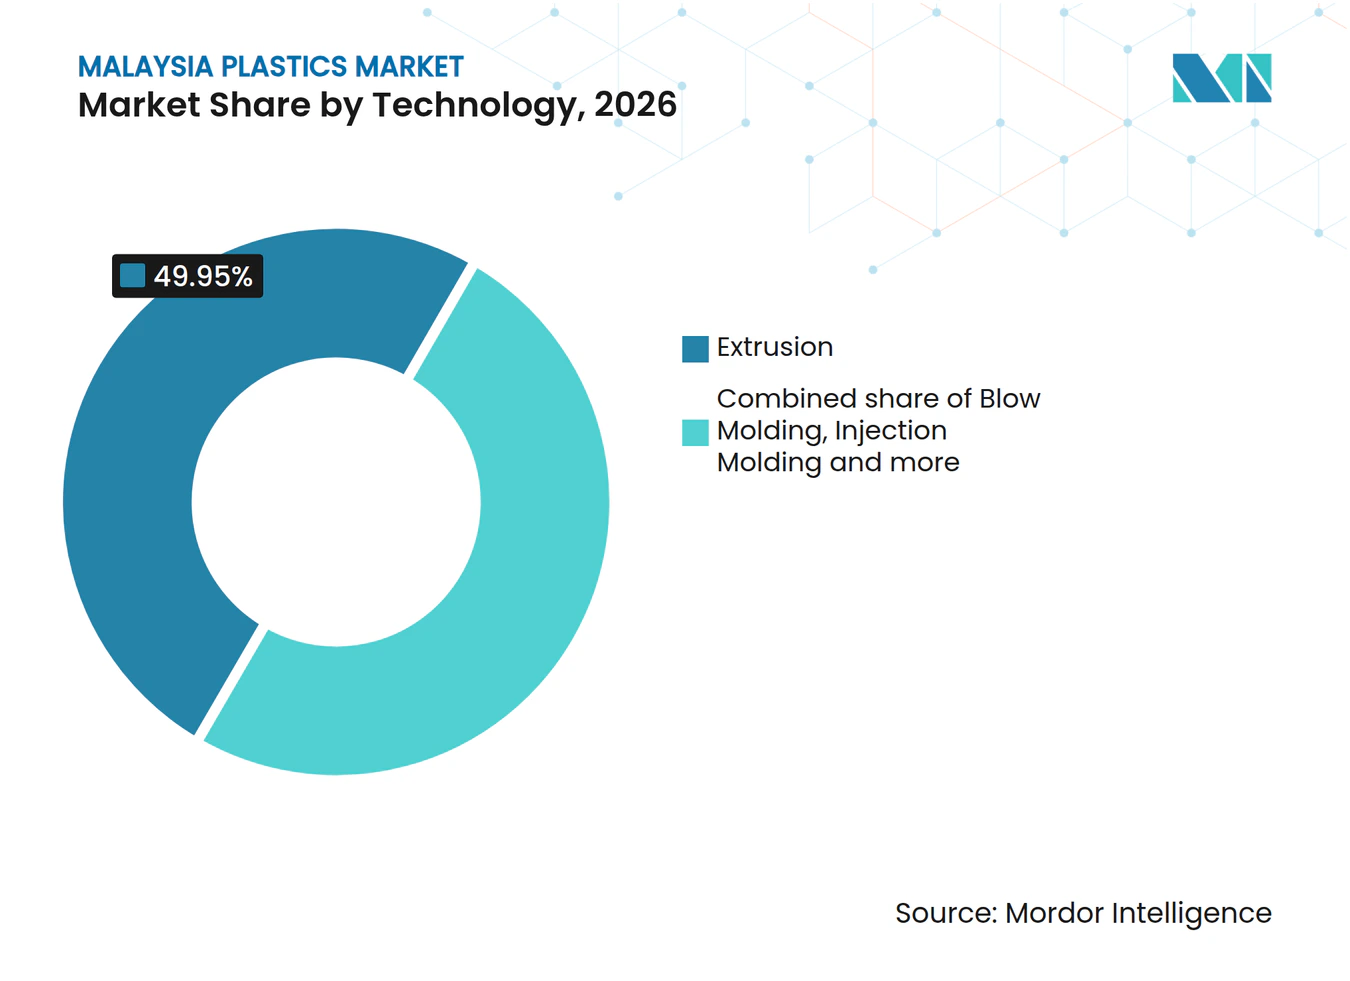
- Among processing technologies, extrusion accounted for a 49.95% share of the Malaysia plastics market size in 2026, with blow molding forecast to grow fastest at a CAGR of 3.8% between 2027 and 2032.
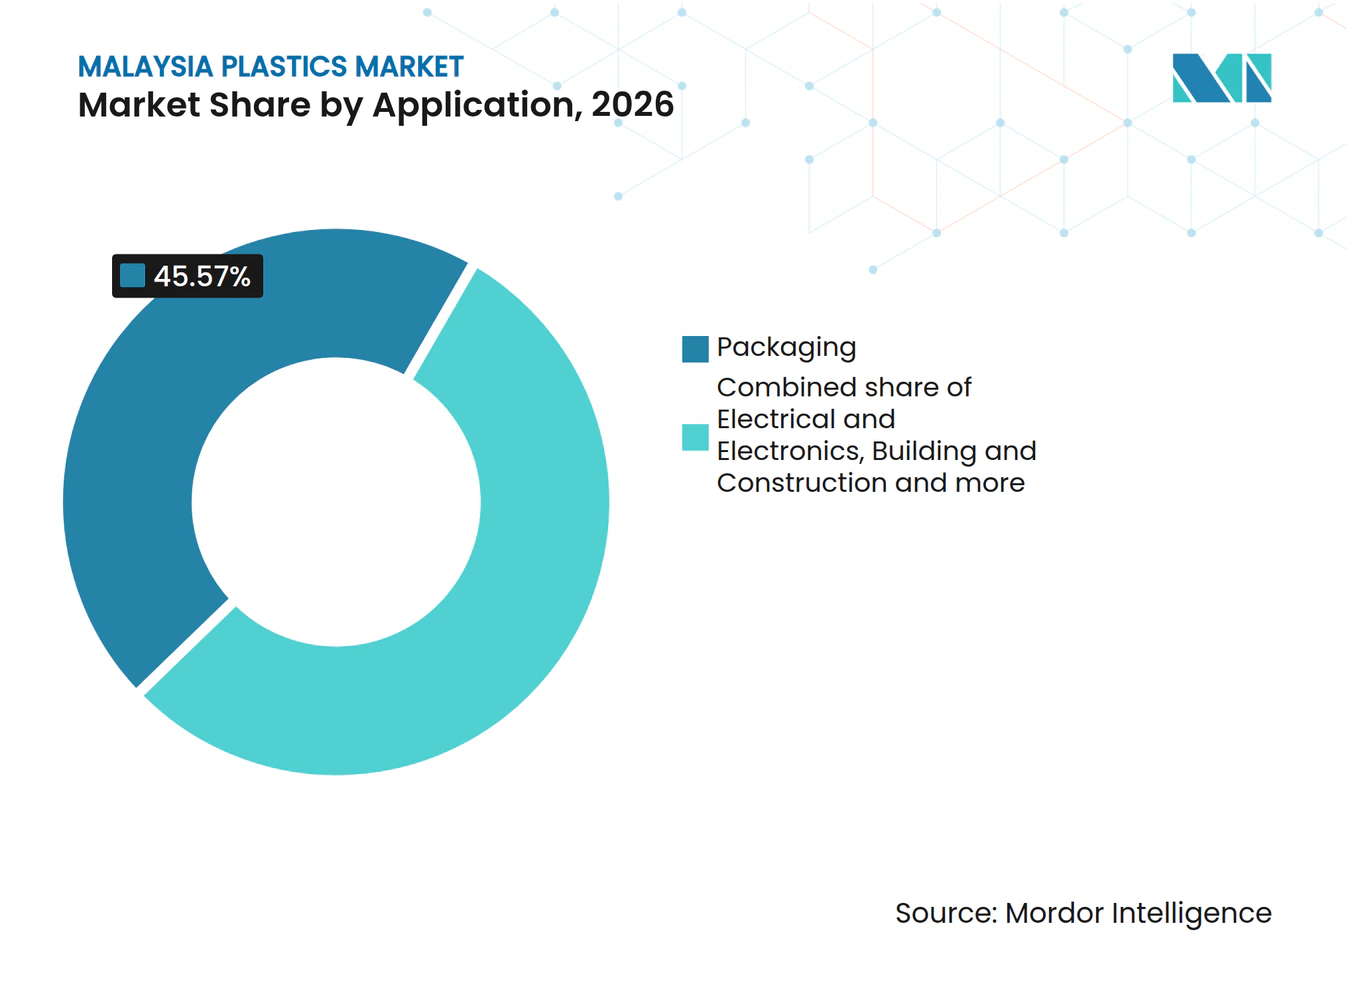
- Packaging led applications with a 45.57% share of domestic plastic-material spending in 2026, and the electrical and electronics segment is forecast to grow fastest at a CAGR of 3.9% between 2027 and 2032.
- Geographically, Selangor leads through its widest converter base.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Malaysia Plastics Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising demand from food and beverage packaging | +2% | Nationwide | Short term (≤ 2 years) |
| Growth of electronics manufacturing ecosystem | +1.2% | Nationwide, including Johor Bahru | Medium term (2-4 years) |
| Government incentives for downstream petrochemicals | +1% | Nationwide | Medium term (2-4 years) |
| Circular-economy commitments by global brands | +0.8% | Nationwide | Medium term (2-4 years) |
| Expansion of medical-device clusters | +0.4% | Penang's medical-device manufacturing cluster | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Rising demand from food and beverage packaging
Pack-size changes give material suppliers another source of opportunity besides growth in food producers' sales. Malaysia's domestic-oriented food-processing industry recorded provisional year-on-year sales-value growth of 6.9% in August 2026, following 9.6% in July.[1] Fraser & Neave Holdings Bhd launched a new 380-milliliter pack for selected F&N SEASONS beverages in FY2025 to meet growing demand for upsized, value-focused options. An upsized value-focused format shifts the buyer's commercial problem toward delivering more beverage per pack at an acceptable packaging cost. Because the August reading eased from July, the more durable opening for converters lies in the formats and prices food producers choose, such as upsized value packs, rather than in food producers' sales growth alone.
Growth of electronics manufacturing ecosystem
Malaysia approved 245 electrical and electronics manufacturing projects in 2025, up from 153 in 2024.[2] Its plastics industry supplies precision components to global electronics and electric-vehicle supply chains, with electronics the industry's main export contributor. In September 2025, Scanfil inaugurated an expansion of its Johor Bahru electronics and complex box-build facility, increasing production area by nearly 50%. The facility is part of SRXGlobal, which Scanfil acquired in October 2024. The approval pipeline and completed expansion indicate demand potential across different stages of industrial investment, with implementation determining when additional manufacturing activity develops. Resin suppliers serving precision-component producers can diversify their demand exposure through electronics, connecting material supply to industrial production rather than relying entirely on consumer packaging.
Government incentives for downstream petrochemicals
Tax incentives can improve the economics of qualifying petrochemical investment before additional material reaches converters. Malaysia's New Incentive Framework accepts manufacturing applications from March 1, 2026, including petroleum products and petrochemicals.[3] Eligible applicants select either a special tax rate or an investment tax allowance, with the mutually exclusive choice subject to criteria and outcome assessment. For a qualifying resin project, the potential benefit can make investment more attractive without requiring higher material prices to justify the expenditure. Executed resin projects can turn the tax benefit into additional material supply for converters, making the incentive commercially relevant through production and sales.
Circular-economy commitments by global brands
Brand circularity programs can redirect material demand toward recycled resin rather than simply increase total polymer consumption. Nestlé Malaysia reported collecting more than 15,000 metric tons of materials through voluntary extended producer responsibility initiatives in 2025, including more than 11,000 metric tons of plastic. Coca-Cola Malaysia offers 3 beverage variants in 500-milliliter bottles made with 100% recycled plastic, excluding caps and labels. Together, recovery activity and a defined recycled-content packaging application give material suppliers separate commercial entry points, from recovered feedstock to replacement resin. The opportunity depends on converting recovery into material suitable for the intended package, making usable resin output more commercially significant than collection tonnage alone.
Restraints Impact Analysis of Malaysia Plastics Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Environmental concerns and single-use bans | -0.6% | Perak's affected permanent premises | Medium term (2-4 years) |
| Feedstock price volatility | -0.9% | Nationwide | Short term (≤ 2 years) |
| Skills gap in advanced polymer processing | -0.3% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Environmental concerns and single-use bans
Restrictions on retail carry bags can remove a specific material outlet even while other packaging applications expand. Perak prohibited affected permanent premises, including supermarkets and pharmacies, from providing or using single-use carry bags from September 1, 2026. On October 17, 2026, local authorities were still focusing on education and public awareness before more serious enforcement. For suppliers serving those premises, a prohibition changes the long-term usefulness of carry-bag capacity even when implementation initially emphasizes awareness. The adjustment therefore depends on the converter's exposure to the restricted format, making a mixed product portfolio less vulnerable than one concentrated in those bags. Education-led implementation can soften the immediate adjustment, but affected suppliers face the commercial cost of replacing a restricted outlet.
Feedstock price volatility
The West Asia conflict disrupted crude oil and petrochemical feedstock flows through the Strait of Hormuz from March 2026. By April 17, 2026, Malaysian Plastics Manufacturers Association (MPMA) president Cheah Chee Chon reported that Malaysian manufacturers faced resin prices above USD 1,500 per metric ton, compared with approximately USD 800 to USD 900 previously. He also reported supplier surcharges of up to USD 250 per metric ton. Such increases can raise the cash required for an unchanged material volume, making higher spending a poor guide to stronger consumption. For converters, the commercial exposure therefore extends beyond the quoted resin price to the additional surcharge on supply. Until those costs can be recovered, maintaining production volumes can require more working capital without a corresponding improvement in earnings.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Malaysia Plastics Market Segment Analysis
By Type:
Conventional Scale And Specialized Material GrowthTraditional plastics accounted for a 78.69% share of the Malaysia plastics market size in 2026. LOTTE Chemical Titan's Malaysian polyethylene plants have nominal annual capacities of 220,000 metric tons at PE1, 230,000 metric tons at PE2 and 115,000 metric tons at PE3. PE1 and PE3 produce high-density polyethylene, while PE2 produces low-density polyethylene. These facilities show the scale of established polyethylene supply, placing smaller material categories alongside a substantial installed base.
Bioplastics are the fastest-growing segment, forecast to register a CAGR of 4.66% between 2027 and 2032. Zantat Holdings Berhad reported higher revenue from its Bioplastic segment in the first half of 2026 than in the first half of 2025. Zantat's subsidiary Zaneco launched its Earthya compostable bag in Malaysia in August 2025, offered through Shopee and Health Lane Family Pharmacies nationwide, giving that product a consumer retail route. Engineering plastics serve another industrial route, with Malaysia's automotive sector increasingly using lightweight grades in local vehicle production. Growth across these specialized materials can change suppliers' product mix well before it displaces the production scale underpinning traditional resins.



By Technology:
Film-Conversion Scale And Container ExpansionExtrusion represented a 49.95% Malaysia plastics market share in 2026. BP Plastics reports aggregate monthly capacity of 8,500 metric tons across 2 facilities in Sri Gading Industrial Estate, Johor, with cast stretch-film and blown-film co-extrusion capabilities. That footprint illustrates how a film converter can support substantial material throughput across related processing routes rather than rely on a single narrow application. The largest segment's commercial weight therefore rests on material use within established converting operations, where line capability and the mix of film requirements shape opportunities for suppliers serving that industrial base.
Blow molding is the fastest-growing segment, with a forecast CAGR of 3.8% between 2027 and 2032. In 2025, Ansoon Superior relocated to Pusing, Perak, increasing floor space from 38,781 to 91,864 square feet and more than doubling its extrusion blow-molding capacity. That completed expansion links growth potential to additional bottle-and-jar manufacturing capability. Injection molding has a separate role in industrial, med-tech and consumer-goods components, illustrated by Ge-Shen Corporation Berhad subsidiary Polyplas' Penang plant launch on November 21, 2025. Material suppliers consequently face different commercial tasks in hollow-container expansion and precision-component production, making process-specific applications more useful than a uniform technology strategy.

By Application:
Packaging Breadth And Electronics MomentumPackaging was the largest segment by application, holding a 45.57% share of domestic plastic-material spending in 2026. Food and beverages, fast-moving consumer goods and e-commerce support demand in Malaysia's downstream plastic-packaging industry. The Malaysian Investment Development Authority (MIDA) also identifies packaging as one of the sectors driving exports from Malaysia's plastics industry. Resin suppliers serving packaging converters can consequently reach several buyer channels and gain indirect exposure to overseas demand, making local consumer spending only one influence on those customers' needs.
Electrical and electronics is the fastest-growing segment by application, with a forecast CAGR of 3.9% between 2027 and 2032. Malaysia's electrical and electronics equipment subsector recorded provisional year-on-year sales-value growth of 22.6% in August 2026, compared with 17.8% in July. DOSM also listed electrical and electronics products at 17.0% among the subsectors contributing to Malaysia's manufacturing output increase in August 2026, adding a production-side reading. Building and construction supply a separate route through PVC piping and cable insulation, for which MIDA identifies steady demand in Malaysia. Suppliers can pair electronics grades with grades for PVC piping and cable insulation, combining strong August electronics sales growth and steady construction demand to reduce reliance on one buyer cycle.
Geography Analysis
Selangor Plastics Market
Selangor leads the geographic market through the breadth of its converter base. In July 2026, Ekonusa said its existing Shah Alam facilities, including its warehouse, were fully utilized. The company produces plastic bottles and pails for industrial and consumer goods, including fertilizer and shampoo packaging. That mix gives material suppliers exposure to industrial and household-product demand through a converter serving distinct packaging uses. Full utilization also means incremental material demand from that operating base depends on added capacity or a changed product mix, separating an established customer base from immediate volume headroom.
Outside the leading state, regional differences arise from the types of converting customers that a resin supplier can reach. Formula Lab (M) Sdn Bhd manufactures bottles, caps and closures in Johor Bahru for pharmaceutical, lubricant, chemical, cosmetics, food and drinks industries. In Sarawak, Hwa Khoon Plastic Industries Sdn Bhd produces industrial packaging at its Kuching facility, including stretch film, shrink film and heavy-duty bags. The Johor example spans consumer and industrial containers, while the Sarawak example centers on industrial films, creating different material-supply opportunities within the same broad packaging application.
Terengganu adds industrial-component manufacturing, with DD Plastic Sdn Bhd making polyethylene heavy-duty film and injection-molded components in Kemaman for oil and gas, electrical, medical and automotive uses. In Melaka, Packerman uses extrusion and thermoforming to produce cups, lids, containers and trays. Kuala Lumpur has a polymer-distribution function through Sumikeng (M) Sdn Bhd, which has a sales office there and acts as agent and distributor for regional producers. These roles separate manufacturing locations from the commercial channels through which converters obtain grades. A resin supplier can therefore develop regional reach through distribution relationships while locating technical support around the specific component and packaging operations that consume its materials.
Regulatory Framework and Outlook
The table compares selected jurisdictions from the perspective of resin suppliers serving single-use carry-bag converters. In February 2026, the Ministry of Natural Resources and Environmental Sustainability (NRES) reported state-dependent carry-bag restrictions, making local implementation central to the commercial effect. Selangor's March 2025 administrative instruction concerns government premises, while the Penang comparison focuses on the announced restriction in Seberang Perai. This perspective places the greatest weight on continued access to specific carry-bag outlets, rather than general manufacturing attractiveness.
Regulatory Table of Malaysia Plastics Market
| Decision factor | Malaysia | Selangor | Penang |
|---|---|---|---|
| Primary authority | NRES and state governments | State Secretary's office and local authorities | Seberang Perai City Council |
| Key instruments or direction | Carry-bag agreement for a January 2026 start, subject to state adoption | March 2025 government-premises instruction; September 2026 draft retail-charge by-laws | Announced carry-bag ban from September 2026; enforcement scheduled from October 2026 |
| Commercial effect | Locally determined access to carry-bag end uses | State bodies directed to avoid single-use plastics at government premises; proposed retail-charge enforcement | Announced restriction on free and paid bag supply at listed Seberang Perai premises |
| Current policy attractiveness | Medium | Medium | Low |
| Future direction of policy attractiveness | Hardening | Hardening | Hardening |
| Source: Mordor Intelligence | |||
The national Medium rating and Hardening direction reflect the April 2025 council agreement to begin carry-bag bans from January 1, 2026, subject to state adoption and methods. Selangor's Medium rating reflects the government-premises scope, while the September 2026 draft retail-enforcement by-laws support Hardening if approved. Penang's Low rating reflects the announced Seberang Perai prohibition, whose notice scheduled enforcement from October 1, 2026. Penang's framework consultations on June 9 and July 21, 2026, add a broader policy-design process to that local enforcement step, strengthening the Hardening judgment.
Value Chain Stages
The value chain compares virgin-resin production, film conversion and recycled-material regeneration in Malaysia. LOTTE Chemical Titan produces high-density, low-density and linear low-density polyethylene, establishing a domestic production base across these resin families. Resin suppliers earn from material sales, while converters capture a separate manufacturing return by turning material into application-specific products. Recycling returns waste-based material to the supply stage, creating another point at which processing capability can earn a material-sales return.
Value Chain Analysis Table of Malaysia Plastics Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Virgin-resin production | Polyethylene producers such as LOTTE Chemical Titan | Resin sales | Matching resin grade to conversion requirements | Qualify suitable grades for the intended process |
| Film conversion | Polyethylene film converters such as BP Plastics Holding Bhd | Customized film sales | Meeting application-specific film requirements | Agree specifications before scaling production |
| Recycled-material regeneration | Recycled-resin manufacturers such as MJ MATERIAL | Recycled-material sales | Consistency of recovered-material quality | Apply sorting and polymer-processing controls |
| Source: Mordor Intelligence | ||||
BP Plastics' Blown PE Film Division produces customized films for industrial packaging, illustrating how conversion earns value through application fit. MJ MATERIAL develops and manufactures recycled plastic materials in Malaysia using waste plastics, giving recovered inputs a route back into material supply. Konica Minolta reported in February 2026 that rising recycled-plastics demand had destabilized waste-plastic procurement and raised prices, making feedstock security a constraint on extending recycled-material sales.
Competitive Landscape
Market Concentration
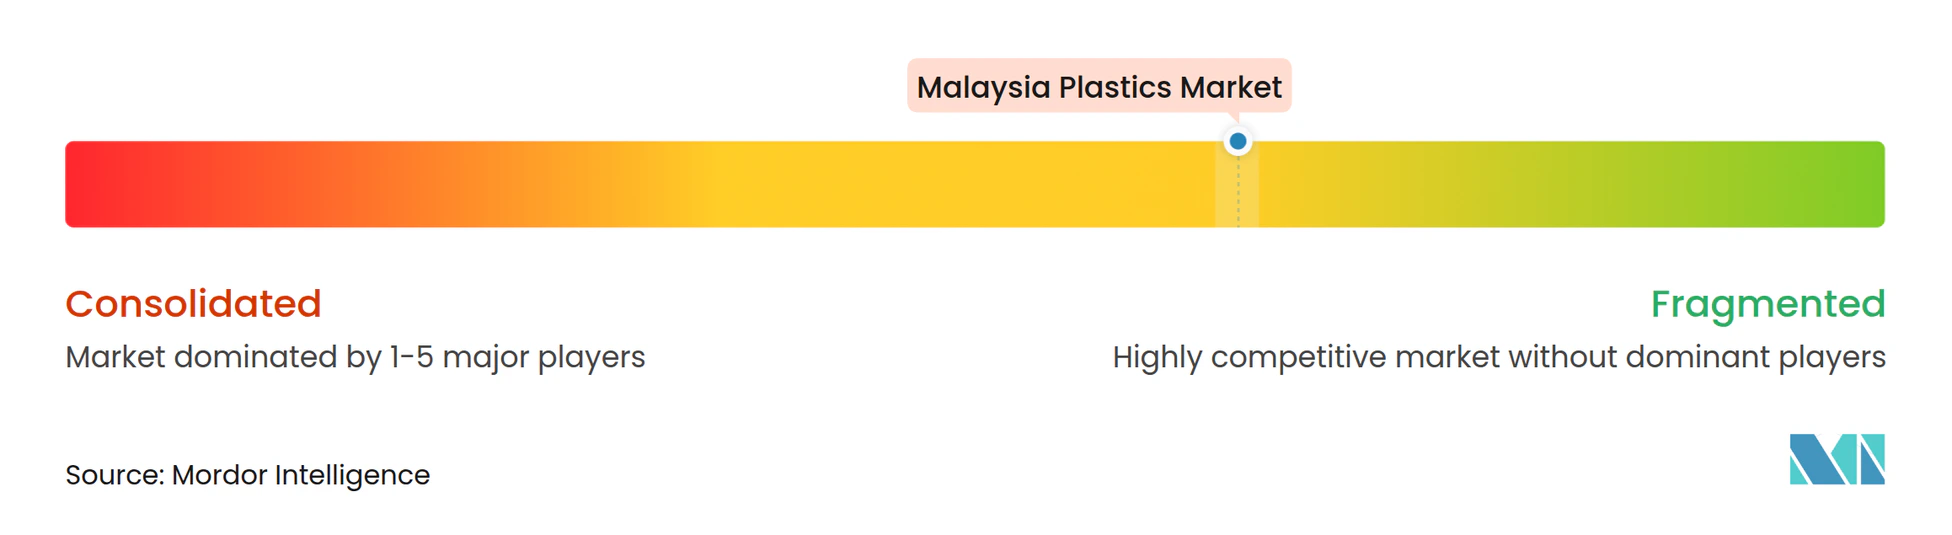
Competition is moderately fragmented across material production and specialized packaging conversion, with different business models shaping how companies serve the plastics industry. Major participants include BP Plastics Holding Bhd, LOTTE CHEMICAL TITAN HOLDING BERHAD, Daicel Corporation following the transfer of Polyplastics Co., Ltd.'s business, Scientex Berhad and SLP RESOURCES BERHAD. That transfer took effect on April 1, 2026, and Daicel's group includes Polyplastics Asia Pacific Sdn Bhd in Malaysia. BP Plastics' operating business makes flexible packaging, while LOTTE Chemical Titan produces olefins and polyolefins, placing these companies on different sides of material consumption and giving their competitive influence distinct commercial foundations.
In FY2025, Scientex Packaging increased its stake in Hiro Food Packages Manufacturing from 30% to 70%, strengthening Scientex Berhad's complementary rigid-packaging capability alongside flexible packaging. For customers using both formats, that combination can broaden the packaging requirements addressed by one corporate group, making portfolio coverage a source of differentiation. SLP RESOURCES BERHAD is a holding company whose group operations use extrusion to produce customized plastic bags, sheeting and films. Together, broader format coverage and application-specific conversion show how these businesses can compete through the scope of their customer solutions, alongside the scale of the material-production businesses serving them.
SLP Resources Berhad's group obtained ISCC certification in 2025. That credential sits alongside customized packaging activities, bringing assurance and conversion capability into the same supplier comparison. In a written parliamentary reply reported on October 9, 2026, Malaysia's Ministry of Housing and Local Government said packaging-waste extended producer responsibility (EPR) was being developed for voluntary implementation in 2026. Mandatory implementation was targeted for 2030 subject to related legislation, with producer responsibility encompassing collection, recovery and recycling. This direction gives converters a reason to develop recovery-focused packaging proposals, connecting their customized production capabilities to producers' future waste-management responsibilities.
Malaysia Plastics Industry Leaders
-
BP Plastics Holding Bhd
-
LOTTE CHEMICAL TITAN HOLDING BERHAD
-
Polyplastics Co., Ltd.
-
Scientex Berhad
-
SLP RESOURCES BERHAD
- *Disclaimer: Major Players sorted in no particular order
Malaysia Plastics Market Companies Covered in this Report
- Behn Meyer
- BP Plastics Holding Bhd
- Commercial Plastic Industries Sdn Bhd
- CYL Corporation
- Ee-Lian Enterprise (M) Sdn. Bhd.
- Fu Fong Plastic Industries Sdn Bhd
- Guppy Group
- HICOM-Teck See
- Lam Seng Plastics Industries Sdn Bhd
- LOTTE CHEMICAL TITAN HOLDING BERHAD
- Malayan Electro-Chemical Industry Co. Sdn Bhd
- Meditop International
- Megafoam Containers Enterprise Sdn Bhd (MEGAFOAM)
- Metro Plastic Manufacturer Sdn. Bhd.
- Polyplastics Co., Ltd.
- Sanko Plastics (M) Sdn Bhd
- Scientex Berhad
- SLP RESOURCES BERHAD
- Teck See Plastic Sdn Bhd (TSP)
- TORAY INDUSTRIES, INC.
Key Opportunities for Market Participants
The opportunities compare material-supply plays for packaging and industrial converters in Malaysia. MIDA reported 115 approved plastic-products projects in 2025, identifying a potential downstream buyer base for resin and plastic materials. The manufacturing incentive framework's emphasis on domestic supply-chain linkages and sustainability adds a 2026 policy reason to develop local material capabilities. These premises favor application-led proposals, with commercialization depending on actual converter requirements as projects and material supply develop.
Market Opportunities Table of Malaysia Plastics Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Food-grade recycled PET materials | Melaka facility reported under development on May 20, 2026, with stated annual capacity of 50,000 metric tons | Food and beverage packaging converters | Qualify resin for selected packaging applications | Meeting package-specific material requirements | FE Green PET (M) Sdn Bhd, part of Far Eastern New Century |
| Locally compounded engineering materials | 2026 domestic-linkage incentives and reliance on imported high-performance engineering plastics | Electronics, automotive and electrical converters | Develop compounds matched to defined end-use requirements | High-performance material qualification | Colour Image Plastic Compound Sdn Bhd |
| Process-matched polyethylene supply | 2025 plastic-products approvals and 2026 domestic supply-chain incentives | Polyethylene converters | Match domestic resin grades to converting processes | Project implementation and grade fit | LOTTE Chemical Titan |
| Source: Mordor Intelligence | |||||
The central opening is application-specific material localization in an industry that MIDA describes as reliant on imported high-performance engineering plastics. Colour Image Plastic Compound manufactures engineering-plastic compounds for electronics, automotive, electrical and construction industries, providing a local formulation capability. Compounding can capture application-specific material value without requiring the same company to reproduce every stage of base-polymer manufacturing.
Recent Industry Developments in Malaysia Plastics Market
- Sep 2026: Perak's prohibition on providing and using single-use carry bags at affected permanent premises, including supermarkets and pharmacies, took effect on September 1. On October 17, local authorities were focusing on education before more serious enforcement.
- Jul 2026: Malaysia's National Economic Action Council directed the Ministry of Investment, Trade and Industry and the Economy Ministry to examine Malaysian Plastics Manufacturers Association proposals on downstream manufacturers' structural costs and competitiveness, including raw-material cost differences with competing countries. The review was to consider the wider industrial chain, fiscal balance and long-term national economic competitiveness.
- May 2026: Invest Melaka reported that FE Green PET (M) Sdn. Bhd., a Far Eastern New Century Group subsidiary, was developing a food-grade recycled PET facility in Melaka with a stated annual capacity of 50,000 metric tons.
Malaysia Plastics Market Report Scope and Research Methodology
Market Definition and Coverage
The Malaysia plastics market measures annual spending on plastic polymer resins and plastic materials consumed in Malaysia. It values material supplied to converters and direct end users, with imports added and exports deducted.
Scope exclusions: Standalone recycled plastic scrap trading, upstream petrochemical feedstocks, finished converted plastic articles, finished non-plastic goods where plastic is only a minor component, and resin or plastic material exported from Malaysia or sold for consumption outside Malaysia are excluded.
Segments Covered in This Report
- By Type
- Traditional Plastics
- Engineering Plastics
- Bioplastics
- By Technology
- Blow Molding
- Extrusion
- Injection Molding
- Other Technologies
- By Application
- Packaging
- Electrical and Electronics
- Building and Construction
- Automotive and Transportation
- Houseware
- Furniture and Bedding
- Other Applications
Data Sources, Market Sizing, and Validation
Desk Research
Illustrative public sources such as Department of Statistics Malaysia manufacturing releases help track industrial activity, the U.S. Department of Commerce's Malaysia Plastics Industry profile informs downstream applications, and the Malaysian Petrochemicals Association's Malaysia Petrochemical Country Report supports analysis of resin supply, trade and production. The World Bank's Malaysia plastics circularity study adds evidence on recycled materials and value-chain conditions, while customs and trade statistics help reconcile domestic supply with imports and exports.
Company annual reports, regulatory notices, investor materials and reputable Malaysian business reporting provide supplementary evidence on capacity, product mix, investment and demand conditions. These sources are illustrative rather than exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Structured interviews with Malaysian resin producers, compounders, distributors, converters and material buyers clarify transaction prices, material flows, end-use demand and the treatment of recycled-content grades. Interviews with commercial, procurement and operations leaders test secondary findings and identify gaps in supply, trade and application data, with conflicting or missing inputs checked against independent sources and followed up with relevant respondents.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | |
| Mid tier: 48% | Functional/Unit leaders: 35% | |
| Smaller Players: 20% | Managers: 45% |
Market-Sizing & Forecasting
Malaysia's annual material spending is estimated from domestic resin and plastic-material supply, adding imports and deducting exports, then checked against the value of material bought by converters and direct users. The main indicators are domestic resin and material output, import and export flows, polymer prices, and production trends in packaging, electrical and electronics, construction, and automotive manufacturing. These indicate available material, net domestic supply, unit values and end-use demand. Material spending is allocated across type, processing technology and application using reported product mix, converter activity and end-use evidence, with shares reconciled to the total. Where historical observations are sufficient, multivariate regression relates spending to these supply, price and demand indicators. Scenario analysis is used when data gaps or policy and feedstock changes make a single trend unreliable. Selective bottom-up checks, including supplier roll-ups and sampled material volume multiplied by average selling price, test the top-down estimate, and any missing supplier or channel inputs are bounded with trade data and comparable local operating evidence. Malaysian industry experts can review the direction and relevance of each forecast driver, while analyst review resolves differences before a forecast is carried into the market total.
Data Validation & Update Cycle
Analysts triangulate production, trade, price and downstream demand signals, then investigate unusual changes and material differences between independent estimates before sign-off. A second analyst reviews source fit, calculations and segment reconciliation. Respondents are re-contacted when reported prices, volumes or timing conflict with documentary evidence or a material forecast assumption changes. The series is refreshed annually, reviewed between cycles after material market or policy events, and checked again in a fresh pre-delivery pass.
Mordor Intelligence's Malaysia Plastics Market Sizing Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Malaysia plastics market measures annual spending on plastic polymer resins and plastic materials consumed in Malaysia.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The main indicators are domestic resin and material output, import and export flows, polymer prices, and production trends in packaging, electrical and electronics, construction, and automotive manufacturing.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 4.35 B (2027) | |
| Global Consultancy A | USD 3.73 B (2024) | At its 2024 base, this estimate is 14.3% below this report's 2027 value of USD 4.35 B, 3 years later. Its older base year and stated 2.43% forecast pace leave its published estimate below the later comparison. |
| Regional Consultancy B | USD 3.9 B (2024) | At its 2024 base, this estimate is 10.3% below this report's 2027 value of USD 4.35 B, 3 years later. Its five-year historical estimate predates the comparison year, while its page cites rising demand in packaging, automotive and construction. |
Mordor Intelligence's analysts triangulate production, trade, price and downstream demand signals, then investigate unusual changes and material differences between independent estimates before sign-off.
Key Questions Answered in the Report
What is the Malaysia plastics market size and growth outlook?
It is projected to expand from USD 4.35 billion in 2027 to USD 5.21 billion by 2032, at a CAGR of 3.68% between 2027 and 2032.
What drives demand for plastic materials in Malaysia?
Food production and electronics manufacturing support demand. Malaysia approved 245 electrical and electronics manufacturing projects in 2025.
Which plastic type holds the largest share in Malaysia?
Traditional plastics held a 78.69% share of domestic plastic-material spending in 2026.
Which companies shape the Malaysian plastics industry?
Major participants include BP Plastics Holding Bhd, LOTTE CHEMICAL TITAN HOLDING BERHAD, Daicel Corporation, Scientex Berhad and SLP RESOURCES BERHAD.
What is a major cost challenge for Malaysian plastics processors?
By April 17, 2026, Malaysian Plastics Manufacturers Association president Cheah Chee Chon reported that Malaysian manufacturers faced resin prices above USD 1,500 per metric ton, plus surcharges of up to USD 250 per metric ton.
Which location leads Malaysia's plastics converter base?
Selangor leads through its widest converter base. Ekonusa reported fully utilized Shah Alam facilities in July 2026.