
Luxury Car Market Analysis by Mordor Intelligence
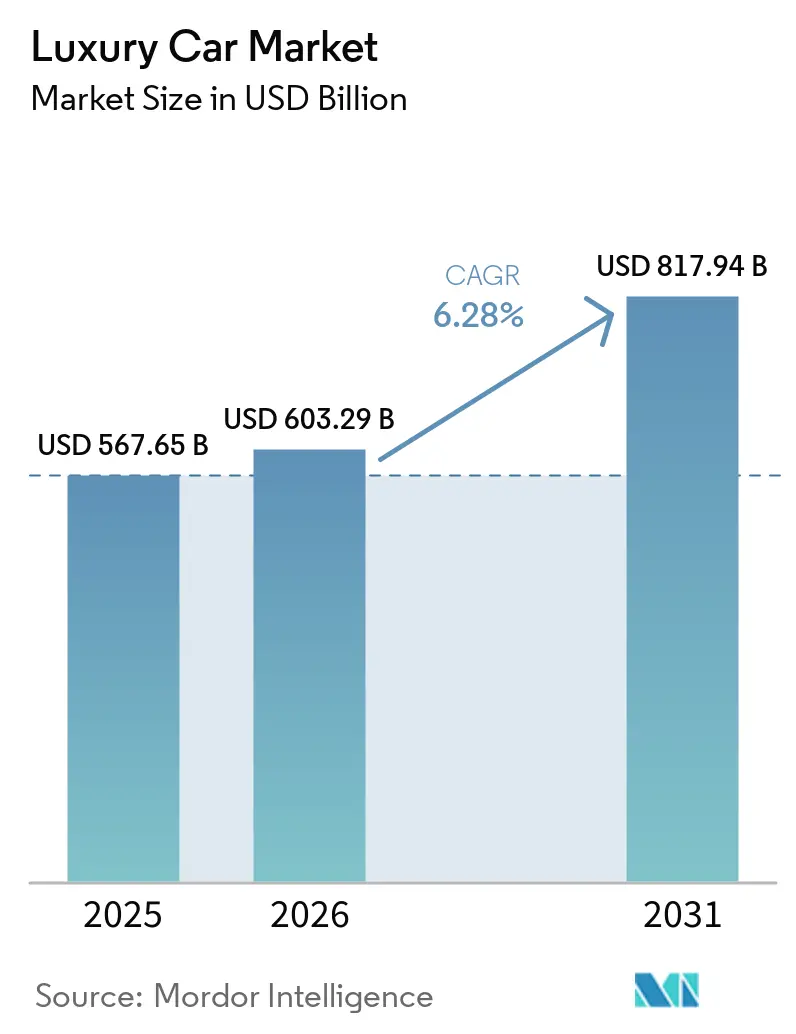
The luxury car market size is expected to increase from USD 603.3 billion in 2026 to USD 641.2 billion in 2027 and reach USD 852.4 billion by 2032, growing at a CAGR of 5.86% over 2027-2032.
Electric-car demand in Europe and sports utility vehicle (SUV) demand in the United States favor adaptable vehicle programs. Asia-Pacific's expanding high-net-worth population broadens potential demand, while price competition in China challenges the premium buyers will accept. The Nexperia chip disruption began in Europe in October 2025 after Dutch government and court measures and Chinese export controls, exposing the risk from slow component replacement. Flexible production and country-specific commercialization of new capabilities become practical competitive responses. Growth favors producers able to shift output between powertrains and qualify alternative components quickly, while China's price competition limits what premium positioning alone can earn.
Key Report Takeaways
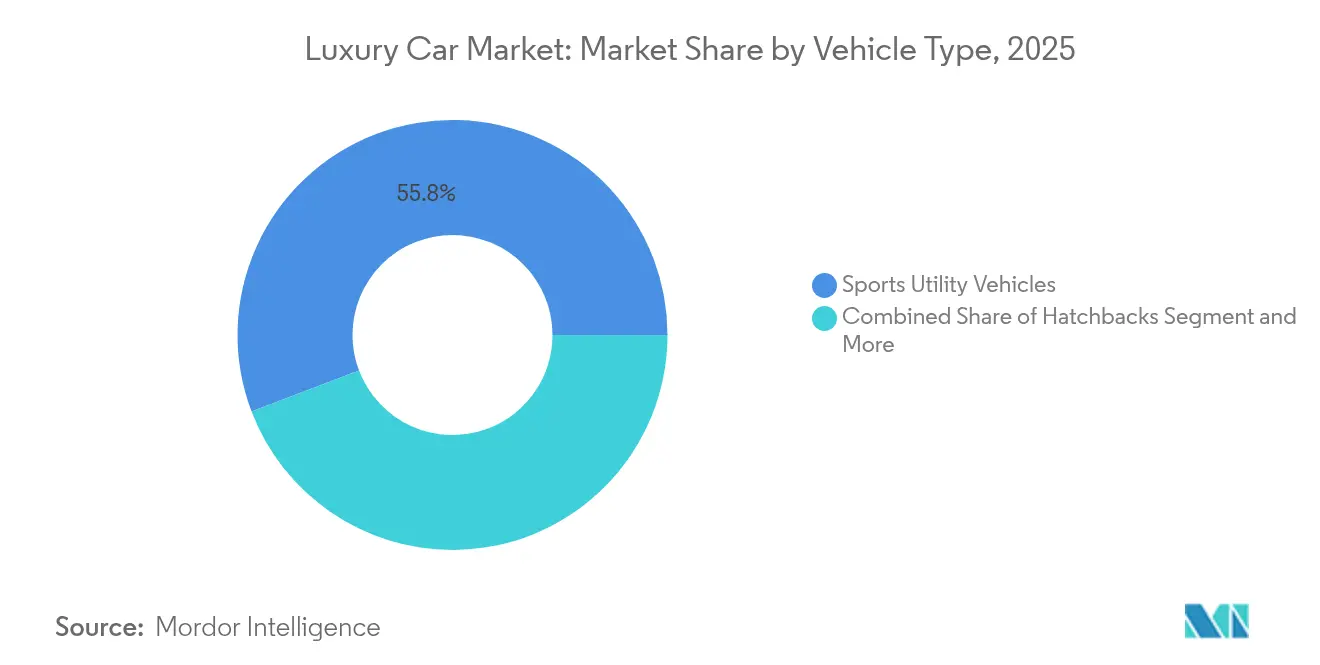
- By vehicle type, SUVs held a 56.28% luxury car market share in 2026 and are forecast to be the fastest-growing segment, with a CAGR of 7.3% over 2027-2032.
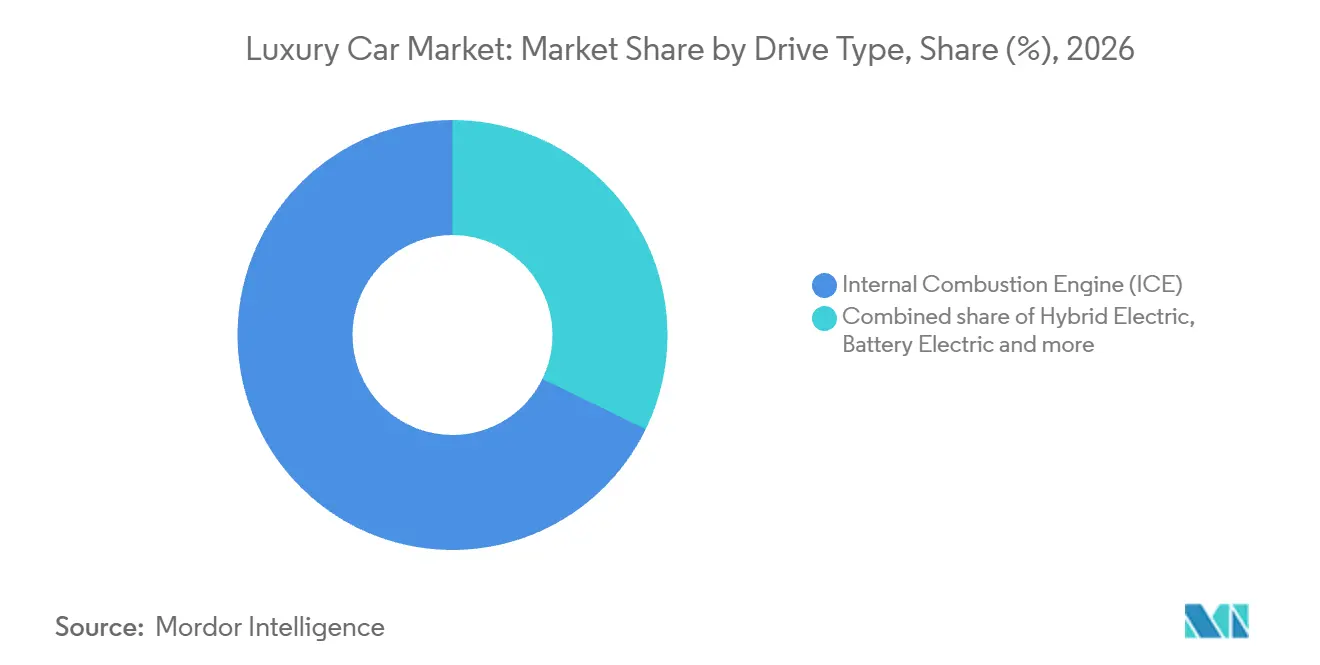
- Across drive types, internal combustion engine (ICE) vehicles accounted for a 67.78% share of the luxury car market size in 2026, while battery electric vehicles are forecast to grow fastest at a CAGR of 8.4% over 2027-2032.
- The vehicle-class breakdown was led by mid-level luxury with 44.78% of the market in 2026, whereas ultra-luxury and exotic vehicles are forecast to be the fastest-growing segment at a CAGR of 7.5% over 2027-2032.
- Among sales channels, authorized dealerships held 89.38% of the market in 2026, and direct-to-consumer and online sales are forecast to be the fastest-growing segment with a CAGR of 8.3% over 2027-2032.
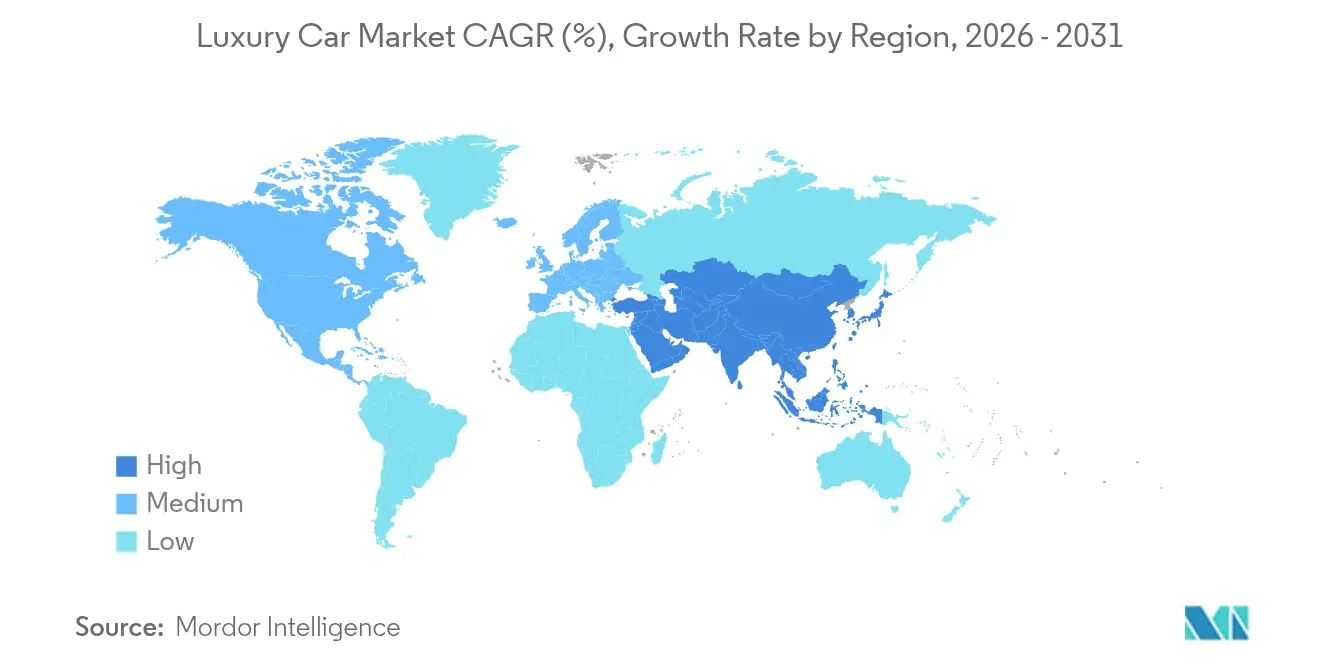
- Geographically, Asia-Pacific represented 43.07% of the market in 2026, while Middle-East and Africa is forecast to grow fastest at a CAGR of 7.5% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Luxury Car Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Luxury-SUV Demand Boom | +2.2% | The United States | Medium term (2-4 years) |
| Rapid Electrification of Premium Models | +2% | Europe and international markets | Medium term (2-4 years) |
| Rising HNWI Population in Asia and Middle East | +1.4% | The Asia-Pacific region | Long term (≥ 4 years) |
| Enhanced ADAS and Safety Expectations | +1.1% | The United Kingdom | Short term (≤ 2 years) |
| Online/Direct-To-Consumer Retail Shift | +0.7% | Across North America | Medium term (2-4 years) |
| Mass-Customization and Bespoke Options | +0.5% | China and Crewe | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Luxury-SUV Demand Boom
Demand for an established luxury SUV can support a vehicle program and the regional retail business that brings it to buyers. Mercedes-Benz USA, the brand's US distributor, reported that preliminary US GLE SUV retail sales rose 14% in 2025, the model's best year ever. The preliminary figures also showed 12% year-over-year GLE retail sales growth in Q4 2025. Growth in both periods, with the fourth-quarter gain below the full-year gain, indicates demand for the Alabama-built GLE held through year-end.
Rapid Electrification of Premium Models
Customer demand is turning electrification into an operating-capacity issue for premium manufacturers. BMW Group reported provisional worldwide deliveries of 110,257 fully electric vehicles in Q3 2026, up 7.2% year over year.[1] In its Q3 update, Mercedes-Benz said its battery-electric GLC, CLA, GLB, and GLA variants were sold out in Europe for the rest of 2026, with order books extending well into 2027. Its Bremen, Rastatt, and Kecskemét plants operated on 3-shift schedules to meet demand for these models. Because these electric variants were sold out in Europe for the rest of 2026 and the plants already ran 3 shifts, fulfilling committed European orders depends on added output.
Rising HNWI Population in Asia and Middle East
An expanding investable-wealth population can increase the pool of potential luxury-car buyers in Asia-Pacific. Capgemini reported 9.4% growth in the region's high-net-worth individual population in 2025. It defined these individuals as having at least USD 1 million in investable assets, excluding their primary residence, collectibles, consumables, and consumer durables. Because the USD 1 million threshold excludes the primary residence and consumer durables, the measure captures investable resources potentially available for discretionary purchases such as luxury cars.
Enhanced ADAS and Safety Expectations
Driver assistance can add practical value to a luxury vehicle when customers use it in everyday driving. By June 2026, BMW customers had driven more than 200 million kilometers hands-free with Highway Assistant. BMW said the function was used daily across several model ranges, including the 5 Series, 7 Series, X5, X6, X7, and XM. Daily use gives BMW a concrete function to emphasize when differentiating its vehicles, beyond the presence of an assistance-system label. Its spread across sedan and SUV ranges lets the same hands-free proposition address several luxury-vehicle buyer groups.
Restraints Impact Analysis of Luxury Car Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High Purchase and Ownership Cost | -0.8% | China's national market | Medium term (2-4 years) |
| Semiconductor and Component Shortages | -0.6% | Europe and China | Short term (≤ 2 years) |
| Macroeconomic Demand Volatility | -0.4% | China's national market | Short term (≤ 2 years) |
| Anti-SUV Climate Regulation Pressure | -0.2% | France's national market | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High Purchase and Ownership Cost
High purchase prices can expose foreign luxury brands to competition from cheaper Chinese models. Those alternatives catered to buyer preferences for comfort and electronics, increasing the challenge of defending a premium through cabin features alone. Premium cars' share of total car sales in China fell to 13% in the first nine months of 2025 from 14% in 2024. For the foreign manufacturer, the constraint reaches both access to price-sensitive customers and the revenue attached to each vehicle transaction. A lower price can improve affordability while reducing the amount collected per sale, leaving a trade-off between retaining the buyer and defending the premium.
Semiconductor and Component Shortages
The Nexperia supply disruption began in October 2025 after Dutch government and court measures were followed by Chinese export controls. Those controls blocked chips packaged in China after European front-end production from returning to the European Union (EU). On October 16, 2025, the European Automobile Manufacturers' Association (ACEA) warned that European vehicle production was at risk because qualifying replacement suppliers and building up their production would take months, while stocks were expected to last only weeks. In June 2026, the European Commission reported resumed shipments after restrictions eased in early November 2025, but warned that dwindling stocks could cause further automotive production disruptions. For luxury-car assemblers, this mismatch turns supplier qualification time into a potential bottleneck for completed vehicle sales. Resumed chip shipments address immediate supply, but replacement qualification leaves assemblers exposed to a separate delay before another supplier can support vehicle output.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Luxury Car Market Segment Analysis
By Vehicle Type:
SUV Scale Supports Powertrain ExpansionSports utility vehicles (SUVs) accounted for a 56.28% share of the luxury car market size in 2026, making them the largest segment, and are forecast to be the fastest-growing segment, with a CAGR of 7.3% over 2027-2032. Porsche AG delivered 59,586 Cayenne vehicles worldwide in January-September 2026, its strongest model line despite a 2% year-over-year decline. Porsche's total deliveries fell 16% to 178,532 in the same period, so Cayenne's smaller decline shows that the SUV line held up better than the rest of the range.
The all-electric Cayenne adds a different route to serve SUV demand within the same model family. Porsche AG delivered 7,002 all-electric Cayennes worldwide from the model's summer 2026 launch through September 2026. By February 2, 2026, Cayenne Electric production had begun in Bratislava on a line shared with combustion and hybrid Cayenne models.[2] Porsche said this flexible setup enables rapid response to changes in demand. Sharing assembly across electric, combustion, and hybrid Cayennes lets Porsche adapt output to demand without committing the entire line to electric vehicles.

By Drive Type:
Combustion Scale Coexists With Electric AdoptionInternal combustion engine (ICE) vehicles represented a 67.78% luxury car market share in 2026, making them the largest segment. Porsche AG Group delivered 38,961 combustion-engined Macans worldwide in 2025, when the model was offered in most countries outside the European Union. Porsche AG delivered 27,996 combustion-engined Macans worldwide in January-September 2026. Production of the combustion-engined variant ended in summer 2026. The earlier non-EU footprint shows the geographic reach behind this combustion franchise, while its withdrawal demonstrates that delivery scale alone does not secure a variant's place in Porsche's portfolio.
Battery electric vehicles are forecast to be the fastest-growing segment, with a CAGR of 8.4% over 2027-2032. Porsche AG delivered 23,029 fully electric Macan vehicles worldwide in January-September 2026. Hybrid electric vehicles provide a separate choice, with BMW Group's FY2025 portfolio placing plug-in hybrids alongside combustion and battery-electric drivetrains to meet varied global customer needs.
By Vehicle Class:
Volume Franchises and Allocated ExclusivityMid-level luxury was the largest segment, accounting for 44.78% of the market in 2026. FAW-Audi reported 172,000 Audi A6L sales in China in 2025, with the model retaining its lead in the country's luxury C-segment sedan category. Audi introduced its next-generation A6L combustion sedan in China at the end of March 2026 as part of its Premium Platform Combustion (PPC) model renewal. The renewal gives Audi a way to pursue the next sales cycle through a sedan franchise that already had substantial national scale, linking growth potential to the next generation of an established vehicle business.
Ultra-luxury and exotic vehicles are forecast to be the fastest-growing segment, with a CAGR of 7.5% over 2027-2032. Ferrari NV reported in its July 30, 2026, results that its 12Cilindri Manuale Special Series was already fully allocated when revealed in the preceding months. Entry-level luxury serves a different route, with nearly half of demand for BMW's entry-level electric SUV in India through September 2025 coming from first-time luxury owners. Ferrari's allocated special series calls for fulfilling existing commitments, whereas BMW's Indian example makes first-time ownership a distinct source of entry-level demand.
By Sales Channel:
Dealer Scale Meets Flexible Digital OrderingAuthorized dealerships were the largest segment, accounting for 89.38% of the market in 2026. Penske Automotive Group operated 365 retail automotive franchised dealerships company-wide at December 31, 2025, including 148 in the United States and 217 elsewhere, principally in the United Kingdom. Premium brands, including Audi, BMW, and Lexus, generated 71% of Penske's retail automotive franchised dealership revenue in 2025. Premium-focused retail groups concentrate sales execution for rival luxury brands within the same dealer business, tying several manufacturers to a shared route to customers.
Direct-to-consumer and online sales are forecast to be the fastest-growing segment, with a CAGR of 8.3% over 2027-2032. Lucid Group's FY2025 annual report described a digital path that allows customers to configure vehicles and place orders online through its direct-to-consumer model. Customers could also schedule a test drive, contact sales, or visit physical Studios. This combination lets a product choice begin digitally while retaining personal contact where the buyer chooses it. For Lucid, digital ordering and optional physical contact support one producer-led customer relationship, making the handoff between those steps central to the direct channel.
Geography Analysis
Asia-Pacific Luxury Car Market
Asia-Pacific held a 43.07% share of the luxury car market size in 2026, making it the largest geography. Audi delivered 617,514 vehicles in China, including Hong Kong, in 2025, down 5% from 2024. A substantial delivery base can coexist with pressure on an individual brand, so Asia-Pacific's commercial scale does not imply uninterrupted growth for Audi.
Middle-East and Africa Luxury Car Market
Middle-East and Africa is forecast to be the fastest-growing geography, with a CAGR of 7.5% over 2027-2032. Lexus sold 45,645 vehicles in the Middle East in 2025, equal to 101.4% of its 2024 volume, and 1,485 in Africa, equal to 118.8% of its 2024 volume. BMW importer Al-Uroush Automotive opened a 1,200-square-meter BMW and MINI showroom in Sulaymaniyah, Iraq, on October 9, 2025, with display capacity for up to 10 vehicles. The additional retail point creates local display and customer access through an official importer. Lexus's higher relative gain in Africa came from a much smaller sales base, while the Iraqi showroom adds a local route to buyers in the Middle East.
North America offers substantial brand-level demand, illustrated by Lexus's record 370,260 US vehicle sales in 2025, up 7.1% on a volume basis. South America has a distinct country-level growth example in Brazil, where K.Lume Consultoria reported 54,564 luxury-car registrations in 2025, up 6.6% from 2024. Europe presents a drivetrain-mix consideration, with battery-electric and plug-in hybrid vehicles comprising 40% of BMW Group deliveries there in 2025. In the first half of 2026, Canada's luxury sector faced cost and trade pressures, while BMW reported a preliminary Mexican premium-market contraction and Argentine premium-segment growth in 2025. Lexus's US gains and rising Brazilian registrations contrast with Canada's weaker luxury share and Mexico's preliminary premium-market contraction, while BMW's European delivery mix shows electrification coexisting with a larger base using other powertrains.
Regulatory Framework and Outlook
The comparison examines selected vehicle-compliance frameworks from the perspective of a manufacturer or importer selling mixed-powertrain luxury passenger cars. Fleet-emission targets, credit requirements, and registration conditions affect the commercial preparation of those vehicle programs. The US Environmental Protection Agency repealed federal greenhouse-gas standards for light-, medium-, and heavy-duty vehicles and engines, effective April 20, 2026.[3]
Regulatory Table of Luxury Car Market
| Decision factor | United States | Brazil | Germany | China | United Arab Emirates |
|---|---|---|---|---|---|
| Primary authority | Environmental Protection Agency | Ministry of Development, Industry, Trade and Services | European Commission for the EU fleet framework | Ministry of Industry and Information Technology | GCC Standardization Organization (GSO) for certification; Ministry of Industry and Advanced Technology (MoIAT) for the compliance data link |
| Key instruments or direction | Federal vehicle greenhouse-gas repeal | MOVER new-vehicle requirements | Regulation (EU) 2019/631 | New-energy vehicle (NEV) credit-ratio notice for 2026 and 2027 | GSO vehicle certification and vehicle identification number (VIN) reporting |
| Commercial effect | Lower federal greenhouse-gas obligations | Sales and imports conditioned on efficiency, recyclability, safety, and labeling | Manufacturer-specific fleet CO2 targets and premiums for exceeding them | Credit-ratio requirements shape vehicle-program planning | GSO certification and VIN reporting are prerequisites for registration |
| Current policy attractiveness | High | Medium | Low | Medium | Medium |
| Future direction of policy attractiveness | Easing | Hardening | Hardening | Hardening | Hardening |
| Source: Mordor Intelligence | |||||
Germany's rating rests on EU fleet-average new-car CO2 reductions that deepen from 15% for 2025-2029 to 55% for 2030-2034 against 2021 levels, with premiums for manufacturers exceeding their specific targets. The Commission's December 16, 2025, proposal to relax the 2035 tailpipe target and allow 2030-2032 banking and borrowing is pending, so the 2030 step supports a Hardening direction. China's medium rating reflects credit-based planning as NEV credit ratios rise from 48% for 2026 to 58% for 2027, whereas Brazil's conditional market access is scheduled to add product-carbon-footprint requirements on January 1, 2027. The UAE's medium rating reflects certification and VIN-linked registration, with scheduled Euro 6d compliance expanding from new type approvals for model year 2030 to all new vehicles registered from January 1, 2031. Mixed-powertrain producers gain US federal greenhouse-gas relief, but must prepare for China's higher 2027 credit ratio and Brazil's scheduled carbon-footprint requirements when deploying the same lineup.
Value Chain Stages
The value chain compares mobility-component supply, vehicle manufacturing, and luxury-brand retail and aftersales as distinct earnings positions. Bosch produces mobility electronics, while Porsche AG and its subsidiary Porsche Leipzig GmbH operate vehicle-production plants. Component supply and completed-vehicle production therefore expose suppliers to different points of interruption before a customer receives a car. Retail adds earnings from vehicle transactions, parts, service, and finance and insurance products, extending the commercial relationship beyond delivery.
Value Chain Analysis Table of Luxury Car Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Electronic component supply | Mobility-electronics suppliers such as Bosch | Component sales | Dependence on timely availability of electronic inputs | Prepare alternative component sourcing before disruption |
| Vehicle manufacturing | Vehicle producers such as Porsche AG and its subsidiary Porsche Leipzig GmbH | Completed-vehicle sales | Production and information technology (IT) interruptions affecting vehicle availability | Separate critical systems and rehearse plant recovery |
| Authorized retail and aftersales | Franchised automotive retailers such as AutoNation and Penske Automotive Group | Retail vehicle sales, parts, service, and finance and insurance products | Manufacturer-driven delays in vehicles and parts | Maintain parts contingencies and protect workshop throughput |
| Source: Mordor Intelligence | ||||
Service and parts generated the largest part of Penske Automotive Group's retail automotive gross profit in 2025. On September 2, 2025, Jaguar Land Rover disclosed a cybersecurity incident that temporarily shut certain production facilities and IT systems, delaying vehicle deliveries and interrupting parts supply. These earnings and disruption exposures favor protecting repair capability alongside restoring the flow of completed vehicles. Repair continuity consequently has a commercial purpose beyond the initial luxury-car sale, because it protects a dealer earnings activity that also depends on manufacturer supply.
Competitive Landscape
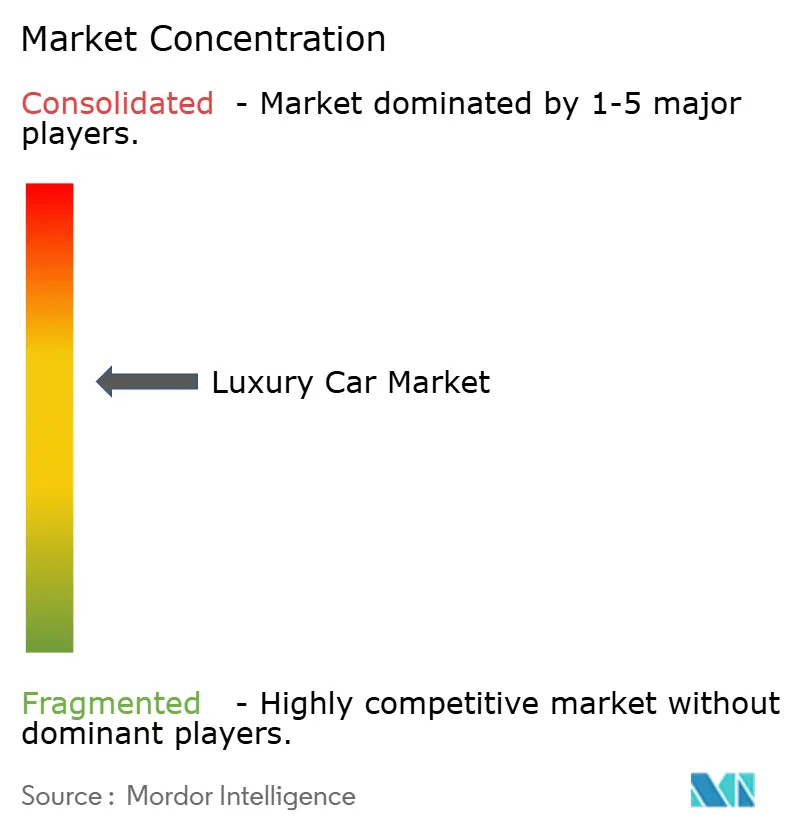
Competition is moderately concentrated around large vehicle groups and distinct luxury brands, led by Volkswagen Group, Tesla Inc., Mercedes-Benz Group AG, BMW AG, and Toyota Motor Corporation (Lexus). Lexus global sales reached a record 882,231 vehicles in 2025, equal to 104% of its 2024 volume. Volkswagen Group's Sport Luxury brand group delivered 279,400 Porsche vehicles globally in 2025, down 10.1% from 2024. Porsche's decline alongside Lexus's record sales shows that group scale can coexist with sharply different brand-level demand trajectories.
Manufacturers can distinguish their offer through a recognizable vehicle franchise or through approval for a buyer-facing technology. Mercedes-Benz reported record G-Class deliveries of 49,700 vehicles in 2025, up 23%, while BMW M GmbH delivered a record 213,457 vehicles in 2025, up 3.3%. On October 30, 2025, BMW Group announced that it had received UN Regulation No. 171 approval for driver-assistance systems for the new BMW iX3. BMW said the approval enabled future Level 2 hands-off motorway assistance in additional models and countries, with the driver remaining involved and country-specific availability and system limits. The commercial advantage depends on translating that permission into an available vehicle feature with clearly defined conditions for its buyer.
Competitive direction also depends on which vehicle programs a manufacturer keeps in production. Tesla completed production of the Model S sedan and Model X SUV at its Fremont, California, line in May 2026. BMW Deutschland handed the first BMW iX3 vehicles to customers in Germany at BMW Welt in Munich on January 27, 2026. Tesla's change affects both a sedan and an SUV, whereas BMW's handovers broaden its electric-SUV offer in Germany. These moves show that a year of new premium electric-vehicle deliveries can also include withdrawals of established model programs.
Luxury Car Industry Leaders
-
Volkswagen Group
-
Tesla Inc.
-
Mercedes-Benz Group AG
-
BMW AG
-
Toyota Motor Corporation (Lexus)
- *Disclaimer: Major Players sorted in no particular order
Luxury Car Market Companies Covered in this Report
- Mercedes-Benz Group AG
- BMW AG
- Volkswagen Group
- Toyota Motor Corporation (Lexus)
- Jaguar Land Rover Automotive PLC
- Stellantis NV (Maserati, Alfa Romeo)
- Tesla Inc.
- Volvo Car Group
- Hyundai Motor Group (Genesis)
- Nissan Motor Co. (Infiniti)
- Geely Holding (Lotus, Zeekr)
- FAW Group (Hongqi)
- SAIC Motor (IM, Roewe)
- BYD Co. (Yangwang)
- Lucid Group
- Rivian Automotive
- Ferrari NV
- Aston Martin Lagonda
- Rolls-Royce Motor Cars
- McLaren Automotive
Key Opportunities for Market Participants
The comparison examines vehicle-buyer and retailer opportunities created by US luxury electric-SUV programs at different commercial stages. On September 2, 2026, Jaguar Land Rover Automotive PLC opened US orders for the Range Rover Electric, with a starting manufacturer's suggested retail price (MSRP) of USD 138,000. On May 6, 2026, Toyota Motor Corporation announced that the three-row all-electric Lexus TZ was expected to go on sale in the United States in late 2026 from USD 64,050, including delivery, processing, and handling. An orderable vehicle and an expected launch create different opportunities for converting a product choice into a completed purchase.
Market Opportunities Table of Luxury Car Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Upper-tier electric-SUV orders | Range Rover Electric has an established US order channel | US luxury-SUV purchasers considering electric propulsion | Connect vehicle specification with retailer-assisted order placement | High starting MSRP | Jaguar Land Rover Automotive PLC and Range Rover retailers |
| Three-row luxury electrification | Lexus TZ sale was expected in late 2026 | US three-row luxury-SUV buyers | Prepare consultations around seating needs and the announced price basis | Purchase availability depends on expected sale timing | Toyota Motor Corporation through Lexus |
| Retailer support for electric-SUV transactions | Range Rover retailers accept and support orders | Luxury-vehicle retailers | Coordinate configuration, order follow-through, and handover preparation | High vehicle purchase commitment | Range Rover retailers and Jaguar Land Rover Automotive PLC |
| Source: Mordor Intelligence | |||||
The central opening is to carry a high-value electric-SUV buyer through an existing retailer relationship to an order. Retailers can direct immediate selling resources toward orderable vehicles while using expected launches for preparation. The pricing and readiness gap separates an immediate upper-tier order opportunity from preparation for a lower-priced three-row offering.
Recent Industry Developments in Luxury Car Market
- Sep 2026: Mercedes-Benz Group AG began series production of the new GLA at Rastatt. In its October 7 release, the company reported initial customer orders for the entry-level model.
- Sep 2026: Jaguar Land Rover Automotive PLC opened US orders for the Range Rover Electric, with a starting MSRP of USD 138,000.
- Jul 2026: BMW Group began production of the new 7 Series sedan at Plant Dingolfing, bringing Neue Klasse innovations into an established production model.
Luxury Car Market Report Scope and Research Methodology
Market Definition and Coverage
The luxury car market measures annual value of luxury passenger cars sold globally. It covers vehicles positioned and priced above mass-market cars, with value recorded at the vehicle sale price across dealer and direct-to-consumer channels.
Scope exclusions: Mass-market passenger cars, including those with premium trims or high-end features, commercial vehicles, and two-wheelers are excluded.
Segments Covered in This Report
- By Vehicle Type
- Hatchbacks
- Sedans
- Sports Utility Vehicles (SUVs)
- Multi-purpose Vehicles (MPVs)
- Sports / Exotic
- By Drive Type
- Internal Combustion Engine (ICE)
- Hybrid Electric
- Battery Electric
- By Vehicle Class
- Entry-level Luxury
- Mid-level Luxury
- Ultra-luxury / Exotic
- By Sales Channel
- Authorized Dealership
- Direct-to-Consumer / Online
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Desk research draws on public and official sources such as OICA production tables, ACEA registration data, Capgemini Research Institute wealth data and European Commission vehicle-emissions rules, which give supply context, passenger-car volumes and powertrain mix, regional demand indicators and changes in model economics. These sources provide complementary production, registration, buyer-capacity, and regulatory evidence for a global luxury-car assessment.
Company annual reports, investor presentations, regulatory filings, and reputable automotive press can then cross-check reported deliveries, pricing and model launches, capacity changes, channel developments, and supply constraints. These sources are illustrative rather than exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would include luxury vehicle manufacturers, authorized retailers, and market specialists, with executives and functional leaders addressing sales, product planning, channel mix, and regional demand. Their evidence would test secondary-source assumptions about transaction values, powertrain and vehicle-class mix, and regional variation, and would help resolve conflicting definitions or missing observations. Where a source gap remains, analysts would compare respondent evidence with public delivery, registration, pricing, and filing indicators, retain only supportable estimates, and document the uncertainty for internal review.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 50% | Functional/Unit leaders: 35% | EMEA: 35% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
The model estimates global annual luxury passenger-car sales value from a top-down market series, then checks selected totals with sampled vehicle deliveries or registrations multiplied by average transaction prices across vehicle class and powertrain. Key inputs include passenger-car registrations and manufacturer deliveries for unit direction, observed luxury-car prices and model mix for value per vehicle, and regional wealth and income indicators for buyer capacity. Powertrain availability and emissions rules inform the shift among ICE, hybrid, and battery-electric sales. Historical value and unit trends can be projected with a multivariate regression using these indicators, with scenario analysis for regulatory, affordability, and supply shocks. Segment shares are built from observed registration and delivery mix, price differences, model offerings, and regional evidence, then checked to sum to the market total. Analysts would use manufacturer and retailer interviews to challenge variable-level assumptions and forecast paths, while gaps in sampled bottom-up checks would be bounded with nearby public registration, delivery, and price evidence rather than filled with unsupported detail.
Data Validation & Update Cycle
Analysts triangulate the top-down value series against independent registration, delivery, pricing, and public filing signals, then check totals, units, segment shares, and year-to-year changes for anomalies and unexplained variance. Review proceeds from source verification to model and arithmetic review and then senior analyst review. Anomalies are investigated before sign-off, and respondents or source owners are re-contacted when definitions conflict, a major observation changes, or an unexplained gap persists. Estimates are refreshed annually, revised between cycles when material market events alter sales, pricing, regulation, or supply, and subjected to a fresh source and calculation pass immediately before delivery.
Mordor Intelligence's Luxury Car Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The luxury car market measures annual value of luxury passenger cars sold globally.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Historical value and unit trends can be projected with a multivariate regression using these indicators, with scenario analysis for regulatory, affordability, and supply shocks.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 641.2 B (2027) | |
| Global Consultancy A | USD 593.8 B (2025) | At its 2025 base, this estimate is 7.4% below this report's 2027 value of USD 641.2 B, 2 years later. The older base year precedes the comparison year, and the source projects continued market growth over its subsequent forecast period. |
| Regional Consultancy B | USD 551.14 B (2025) | At its 2025 base, this estimate is 14.0% below this report's 2027 value of USD 641.2 B, 2 years later. The older base year precedes the comparison year, and the source projects continued market growth over its subsequent forecast period. |
Mordor Intelligence's analysts triangulate the top-down value series against independent registration, delivery, pricing, and public filing signals, then check totals, units, segment shares, and year-to-year changes for anomalies and unexplained variance.
Key Questions Answered in the Report
What is the luxury car market size and growth outlook?
The market is expected to reach USD 641.2 billion in 2027 and USD 852.4 billion by 2032, growing at a CAGR of 5.86% over 2027-2032.
What is driving demand for luxury cars?
Mercedes-Benz USA reported preliminary US GLE SUV retail growth of 14% in 2025 and 12% in Q4 2025, while BMW Group's provisional worldwide electric-vehicle deliveries reached 110,257 in Q3 2026. These results point to demand for luxury SUVs and for electric models.
Which luxury-car body type leads sales value?
SUVs held 56.28% of the market in 2026, making them the largest vehicle-type segment.
Which companies compete in the luxury-car industry?
Leading participants include Volkswagen Group, Tesla Inc., Mercedes-Benz Group AG, BMW AG, and Toyota Motor Corporation (Lexus).
What limits luxury-car purchases and deliveries?
Purchase-price pressure in China and component qualification delays can constrain buying and deliveries. China's premium cars accounted for 13% of total car sales in the first nine months of 2025.
Which region leads luxury-car sales value, and which is forecast to grow fastest?
Asia-Pacific held 43.07% of the market in 2026, while Middle-East and Africa is forecast to grow fastest at a CAGR of 7.5% over 2027-2032.