
Landscaping And Gardening Service Market Size and Share
Landscaping And Gardening Service Market Analysis by Mordor Intelligence
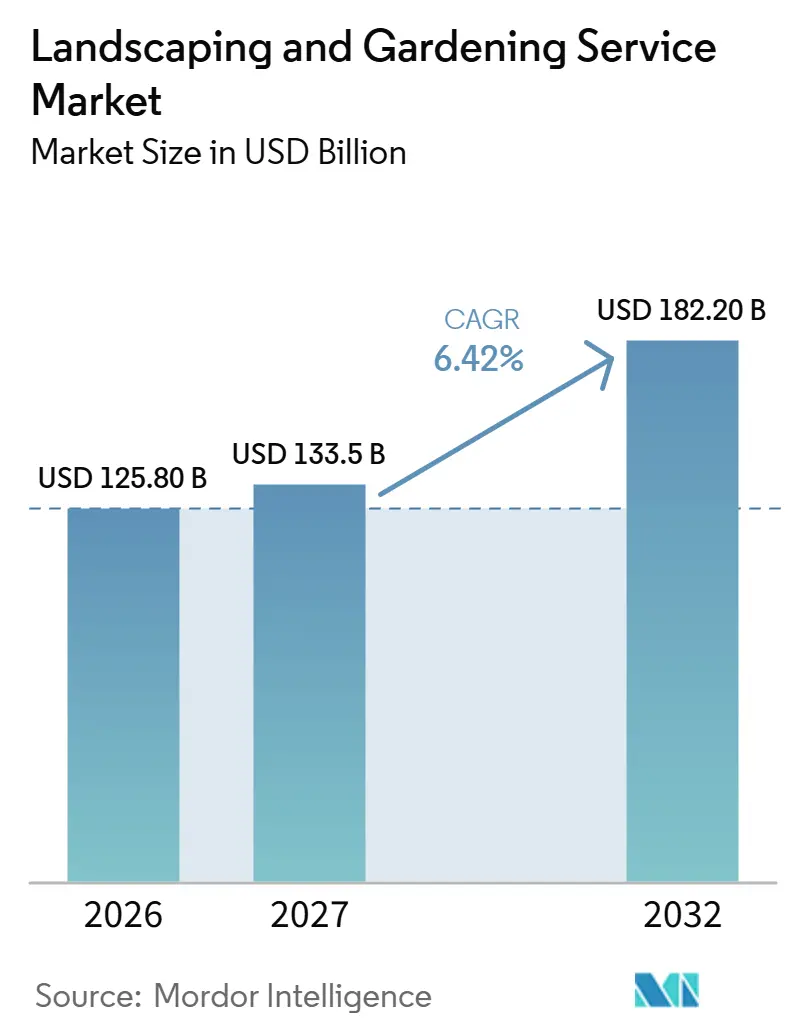
The landscaping and gardening service market size is expected to increase from USD 125.8 billion in 2026 to USD 133.5 billion in 2027 and reach USD 182.2 billion by 2032, growing at a CAGR of 6.42% over 2027-2032.
Paid yard assistance and campus landscaping that serves sustainability goals create service opportunities spanning individual gardens and corporate grounds. Urban planting assignments broaden that opportunity, while acquisitions connect local service operations to larger commercial platforms. In the United States, severe drought in Denver Water's Colorado service area and severe to exceptional drought in its collection watersheds prompted a March 2026 declaration and subsequent grass-watering limits. Skilled-labor shortages and rising input costs make crew capability, delivery within watering limits, and recovery of job expenses central to commercial returns.
Key Report Takeaways
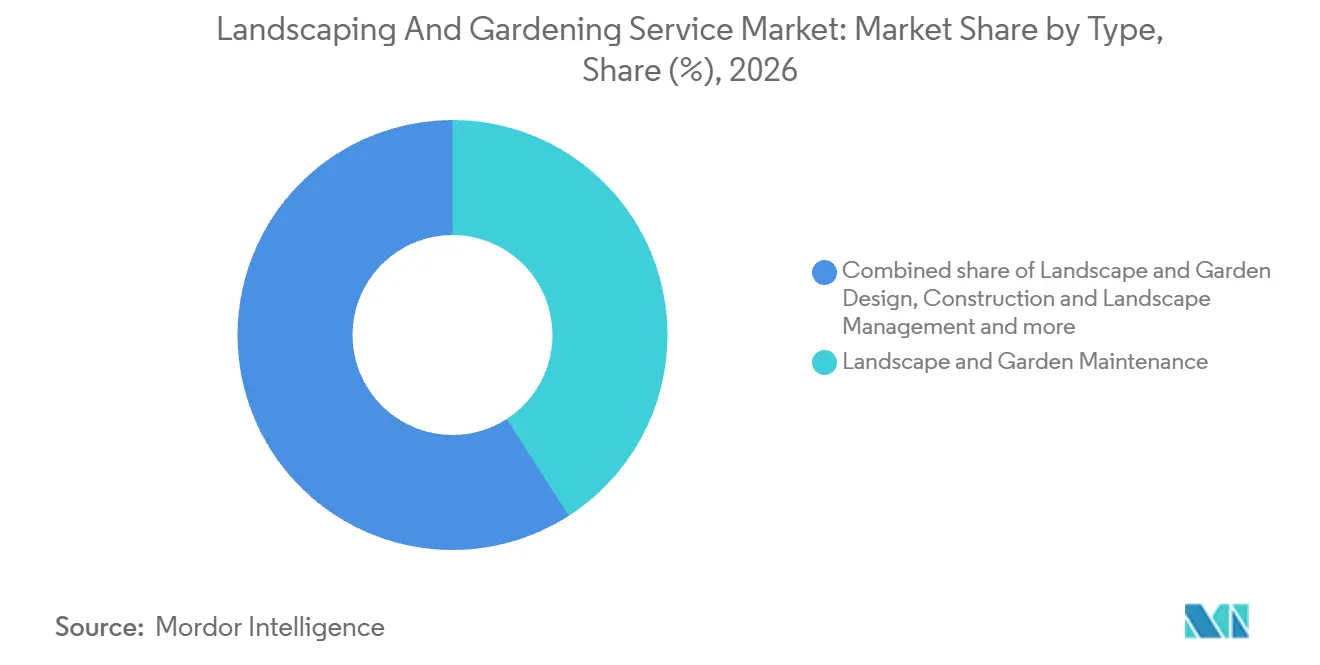
- By type, landscape and garden maintenance held a 40.89% landscaping and gardening service market share in 2026, while landscape and garden enhancements are forecast to grow fastest at a CAGR of 8.55% over 2027-2032.
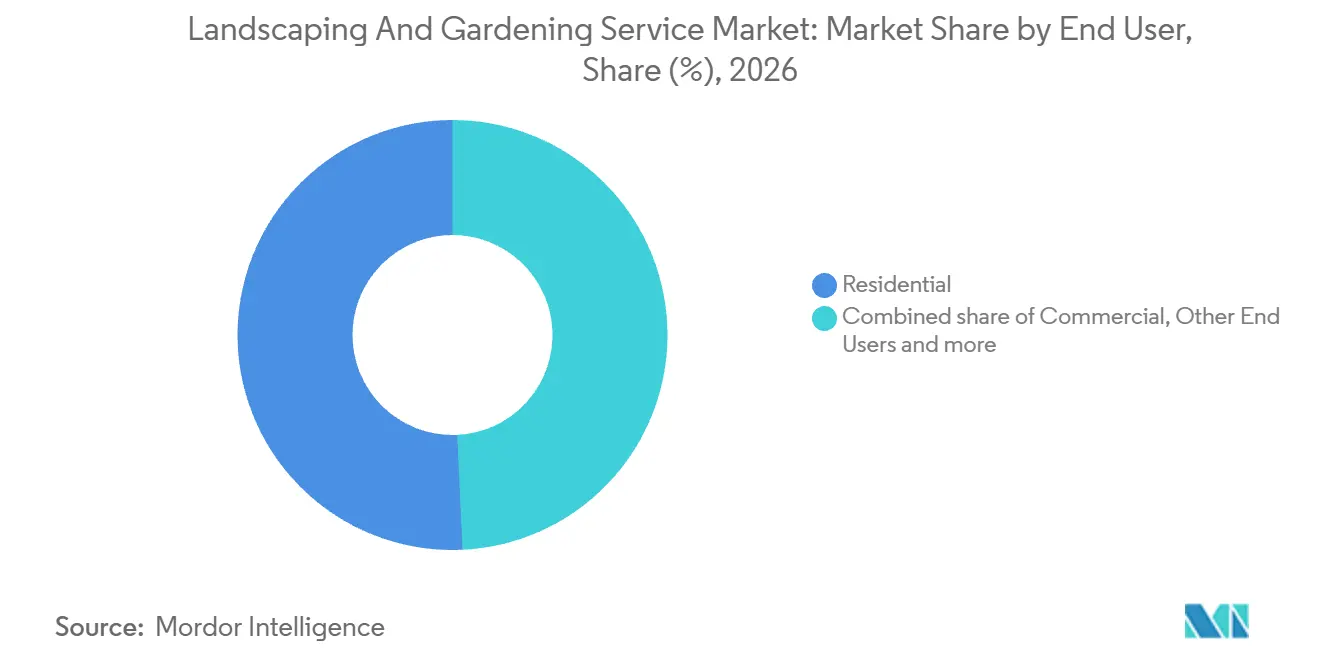
- Among end users, residential customers accounted for a 50.75% share of the landscaping and gardening service market size in 2026, and commercial customers are projected to grow fastest at a CAGR of 7.85% over 2027-2032.
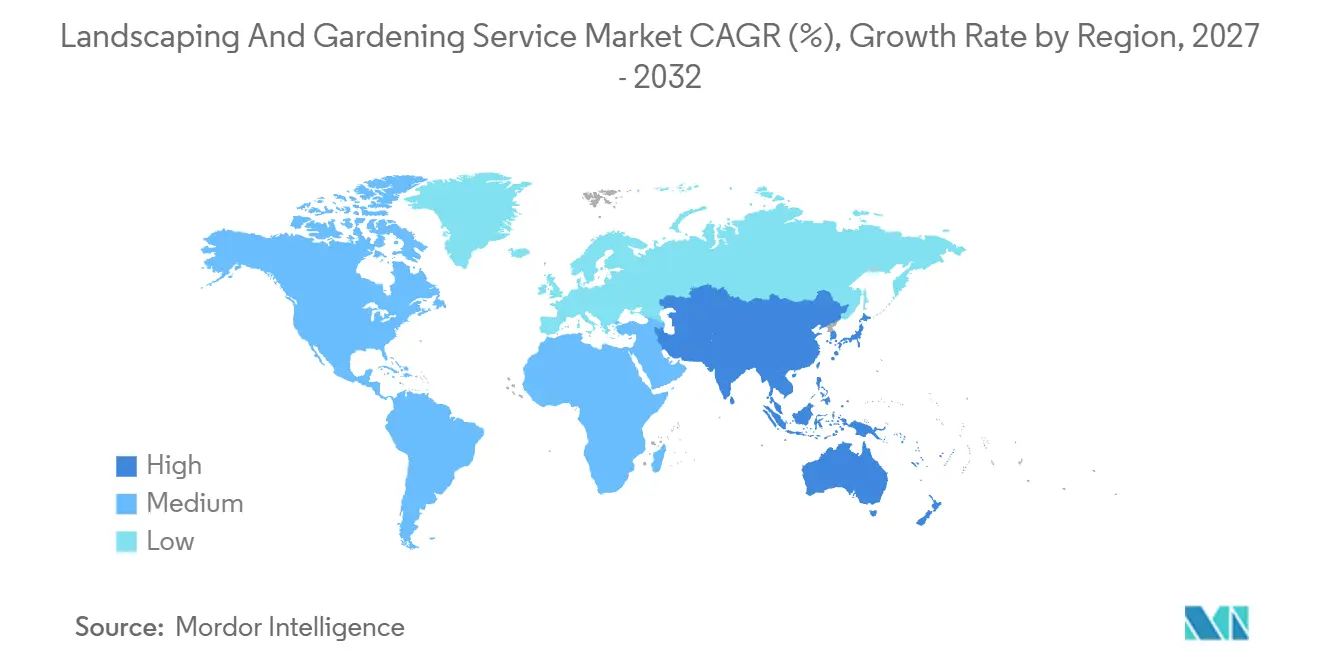
- Across geographies, North America led with 39.31% of global landscaping and gardening service revenue in 2026, while Asia-Pacific is forecast to grow fastest at a CAGR of 7.6% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Landscaping And Gardening Service Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Aging-in-place demand boosts residential landscaping | +1.3% | The United States | Long term (≥ 4 years) |
| Corporate net-zero commitments spur green campuses | +1.5% | The United States | Medium term (2-4 years) |
| Increasing demand for outdoor aesthetics and recreational spaces | +3% | North America, Europe and Asia-Pacific | Medium term (2-4 years) |
| Rising urbanization and infrastructure development | +2.8% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Growing environmental awareness and sustainability trends | +0.8% | The United States | Medium term (2-4 years) |
| AI-enabled robotic mowers cut labor costs and spur adoption | +0.5% | Countries across Europe | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Aging-in-place demand boosts residential landscaping
Keeping a home's outdoor spaces usable can require paid assistance when older residents do not perform yard work themselves. In a 2025 US survey, 34% of 250 adults aged 50 or older who self-identified as solo-agers reported paid assistance with lawn and yard care. The unweighted sample was a younger and wealthier subset of the wider solo-ager population. That buyer profile points providers toward paid yard-care services for solo-ager households already able to afford practical help with their residence.
Corporate net-zero commitments spur green campuses
A corporate campus can turn a sustainability objective into a landscape assignment spanning several parts of the site. BrightView installed green roof systems, irrigation infrastructure, sod, mulch, and thousands of plants at Ford Motor Company's headquarters campus in Dearborn, Michigan. The headquarters opened in November 2025. The campus plan called for 12 acres of greenspace, with broader work scheduled through 2027. The sustainability emphasis in the campus design thus reached the landscape provider as a multi-component installation covering roofs, irrigation, turf, and plantings.
Increasing demand for outdoor aesthetics and recreational spaces
Buyers seeking recreational outdoor space can commission a landscape around a specific use, making the design brief commercially consequential. In Houzz's 2026 US survey, the share of renovating homeowners hiring landscape contractors rose 5 percentage points to 26% compared with 2024. The survey covered 1,191 US Houzz users planning, undertaking, or recently completing outdoor renovations and ran from April 25 to May 6, 2026. A service proposal can connect the desired appearance with decisions about planting, circulation, and the area reserved for activity. With more surveyed homeowners hiring landscape contractors, translating a recreational brief into a buildable layout offers a concrete route to winning that work.
Rising urbanization and infrastructure development
Urban growth creates demand for landscape work when public buyers translate green-space needs into commissioned planting. The United Nations estimated that cities held 45% of the world's population in 2025, up from 20% in 1950.[1] Its city definition requires at least 50,000 residents and 1,500 people per square kilometer. In December 2025, Chicago Park District commissioners authorized districtwide planting and landscaping services from Christy Webber & Company, with work subject to written contract execution. The authorization provided an initial 2-year term from execution and 3 optional one-year extensions. For urban landscape providers, the opportunity is converting a public-space network into defined planting assignments that can be delivered across multiple sites.
Restraints Impact Analysis of Landscaping And Gardening Service Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Acute shortage of skilled horticultural labor | -1.4% | Australia and United Kingdom | Long term (≥ 4 years) |
| High installation and maintenance costs | -1.1% | Regions across the United States | Short term (≤ 2 years) |
| Seasonal and weather-dependent nature of services | -0.6% | Seasonal regions of United States | Short term (≤ 2 years) |
| Water-use restrictions in drought-prone regions | -0.4% | Denver Water service area | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Acute shortage of skilled horticultural labor
A shortage of trained entrants limits how quickly landscape contractors can add crews for work requiring horticultural judgment. An interim Australian landscaping review reported that consultations from October 2025 to April 2026 identified skills shortages, including insufficient entrants and career-pathway problems.[2] The Landscape Institute's 2026 research also attributed 4 in 5 hard-to-fill vacancies in the wider UK landscape sector to skills shortages. For service operators, adding headcount cannot fully resolve a gap in the skills needed to direct and complete landscape work. An inexperienced crew may require supervision from the same limited pool of qualified staff needed on other assignments. This creates a capacity constraint that can lengthen delivery schedules even when customers are ready to commission work.
High installation and maintenance costs
Material-intensive installation exposes landscape contractors to costs that must be recovered through the service invoice. In its July 2026 survey, Aspire found rising material and equipment costs among US commercial landscape businesses.[3] For installation providers, absorbing those expenses can weaken the return from accepting work, while passing them through can make a proposed landscape more expensive for the customer. Maintenance providers face the same cost-recovery decision where their work requires equipment or replacement materials. Direct purchasing from suppliers, which Aspire said more landscape businesses were adopting, may limit exposure to price volatility, but leaves contractors carrying the material and equipment costs of each assignment.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Landscaping And Gardening Service Market Segment Analysis
By Type:
Maintenance Leads as Enhancements Extend Contractor WorkLandscape and garden maintenance accounted for a 40.89% share of the landscaping and gardening service market size in 2026. BrightView's US commercial landscape maintenance revenue reached USD 1.22 billion in the 9 months ended June 30, 2026. That was up 1.3% from USD 1.2 billion in the same 2025 period. For a provider, routine care generates successive assignments from an existing landscape, so maintenance revenue continues without a new installation to win each time.
Landscape and garden enhancements represent the fastest-growing segment, with a forecast CAGR of 8.55% over 2027-2032. The Home Improvement Research Institute found that contractors alone completed 66% of US mid-to-large yard, garden, and outdoor projects in 2025, while 21% combined contractor and do-it-yourself work. The surveyed households spent more than USD 5,000 on their projects. Such projects give an enhancement contractor a way to sell coordination and execution as part of the improvement, alongside the physical landscape work. Mixed contractor and do-it-yourself delivery creates a reason to define a professional work package that fits within the homeowner's wider project.



By End User:
Household Customization and Commercial Contract GrowthResidential customers represented a 50.75% landscaping and gardening service market share in 2026. A homeowner can commission a job at the level of a single garden, allowing the provider to define responsibilities around that property's boundaries and intended use. An offer can then be tailored to a particular balance of retained planting, changes in layout, and the care needed after the work is finished. In Houzz's 2026 US survey of Houzz users planning, undertaking, or recently completing outdoor renovations, 71% hired a professional, up from 65% in 2024. Rising professional involvement in household outdoor renovations puts a contractor's ability to scope work around a single property at the center of residential demand.
Commercial customers form the fastest-growing segment, with a forecast CAGR of 7.85% over 2027-2032. BrightView's US commercial landscaping revenue in its Maintenance Services segment rose 2.3%, or USD 11.7 million, in the quarter ended June 30, 2026, versus the corresponding 2025 quarter. The company attributed the increase to contract revenue and, to a lesser extent, ancillary services. Contract revenue creates a different growth channel from an isolated installation project, because an account can support landscape services over a defined service period.

Geography Analysis
North America Landscaping And Gardening Service Market
North America held a 39.31% share of the landscaping and gardening service market size in 2026, making it the largest geography. United Land Services, backed by Centre Partners and LP First Capital, completed 4 US acquisitions of landscaping and related service businesses in 2025. H&O Grounds added United Land Services' first Louisiana branch, while Wrightsville Beach Landscaping supplemented the platform's North Carolina presence. The commercial value lies in connecting a larger ownership platform with local field delivery, because the acquired landscape operations give the buyer established branch capacity through which to extend service coverage.
Asia-Pacific Landscaping And Gardening Service Market
Asia-Pacific is the fastest-growing geography, with a forecast CAGR of 7.6% over 2027-2032. Singapore's National Parks Board awarded integrated landscape services for Changi, the Tourist Corridor, and Katong, with a service period from July 1, 2026, to June 30, 2029. The 3-year agreement includes an option to extend for up to 3 years. A contract spanning several zones and multiple years creates an opening for providers that can coordinate landscape work across a public buyer's service area. The award creates a defined initial service horizon, while the optional extension leaves further participation dependent on the public buyer's decision.
In South America, Brazil's Saquarema contracted RPX Comercial e Serviços Ltda. on July 8, 2025, for 12 months of urban landscaping, garden maintenance, supplies, and planting seedlings. Europe's policy framework includes European Union member-state duties for no net loss in total national urban green space and tree canopy by 2030, followed by increases. In the Middle East, Riyadh Municipality in Saudi Arabia opened 87 parks during the 3 years to March 15, 2025, taking the capital's total above 700. In Africa, Cape Town's tender closing February 23, 2026, sought gardening and cleaning for community and health facilities and owned or leased public spaces, with functions determined by site need. Brazil's contract, the EU member-state duty, Riyadh's park estate, and Cape Town's site-specific tender point to local scoping rather than one service template for suppliers.
Regulatory Framework and Outlook
The comparison covers selected jurisdictions from the perspective of landscape service contractors undertaking the regulated activity in each country. Pesticide application, urban landscape construction, and irrigation face different qualification, documentation, and water-access obligations. Adding pesticide application brings certification or supervised-use conditions for restricted-use ornamental and turf pesticides in the United States and professional-use pesticides in the United Kingdom. Brazilian companies applying pesticides for third parties must keep training and application records, while Saudi Arabia's updated rule classifies non-efficient urban irrigation as a violation from March 21, 2027.
Regulatory Table of Landscaping And Gardening Service Market
| Decision factor | United States | Brazil | United Kingdom | China | Saudi Arabia | Egypt |
|---|---|---|---|---|---|---|
| Primary authority | Environmental Protection Agency; approved state, tribal, and federal certifiers | State and Federal District inspection authorities | Health and Safety Executive | Local housing and landscaping authorities | Ministry of Environment, Water and Agriculture; National Center for Water Efficiency and Conservation | Ministry of Water Resources and Irrigation, Groundwater Sector |
| Key instruments or direction | Federal certification standards for restricted-use ornamental and turf pesticides | Law 14.785/2023, Articles 9 and 25 | Professional-pesticide certification; planned Codes of Practice update | 2017 cancellation of urban-landscaping enterprise qualification approvals | Water Sources and Uses Code; urban irrigation compliance regulation from March 21, 2027 | Well licensing and technical studies; non-agricultural well-water fee decree planned by July 2027 |
| Commercial effect | Certified application or directly supervised personnel meeting qualifying conditions | Third-party application providers keep training, product-use, prescription, and application-guide records | Accredited certificate or direct supervision by a certificate holder | Authorities cannot require the specified enterprise credentials for landscaping construction | Traditional-source water barred for gardens and green spaces when a nontraditional source is available | Well users need licensing and technical studies |
| Current policy attractiveness | Medium | Medium | Medium | High | Medium | Medium |
| Future direction of policy attractiveness | No change | No change | No change | No change | No change | Hardening |
| Source: Mordor Intelligence | ||||||
US and UK pesticide qualifications support Medium and No change, with the planned UK code update reflecting existing standards, while Egypt's well licensing supports Medium and its non-agricultural well-water fee decree scheduled for issuance by July 2027 supports Hardening. China's High and No change reflect the April 2017 abolition of enterprise qualification approvals alongside contractor capability requirements and acceptance supervised by local greening authorities or their delegates under separate construction rules. Brazil's Medium and No change reflect Law 14.785's training and application records for third-party pesticide applicators and the Ministry of Agriculture's guidance that Decree 4,074/2002 applies where compatible until the law is regulated. Saudi Arabia's Medium and No change reflect its Water Sources and Uses Code (effective May 23, 2025) and updated water-efficiency regulation (published August 14, 2026, effective March 21, 2027), which retains the 2025 violation for non-efficient urban irrigation.
Value Chain Stages
The value chain compares how design, plant supply, installation, maintenance, and subsequent improvements contribute to a landscape service job. Valley Growers Nursery & Landscape, Inc. combines a Pacific Northwest native wholesale nursery with landscape contracting in Oregon and Washington, illustrating that supply and service roles can sit within one business. The Davey Nursery supplies specimen trees through wholesale and retail channels, alongside The Davey Tree Expert Company's separate commercial grounds-service activities. These structures create opportunities to coordinate successive stages while retaining distinct sources of supplier earnings.
Value Chain Analysis Table of Landscaping And Gardening Service Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Landscape design | Integrated landscape design providers such as Chapel Valley Landscape Company, Inc. | Design and planning fees | Translating site needs into an executable landscape | Resolve planting and construction interfaces before installation |
| Plant supply | Nursery suppliers such as Valley Growers Nursery & Landscape, Inc. and The Davey Nursery | Plant sales | Matching specified plants with available stock | Agree acceptable plant substitutions before ordering |
| Landscape installation | Landscape installers such as Chapel Valley Landscape Company, Inc. and The Davey Tree Expert Company | Installation project fees | Coordinating successive landscape activities | Sequence crews under a shared installation plan |
| Grounds maintenance | Grounds-service providers such as Chapel Valley Landscape Company, Inc. and The Davey Tree Expert Company | Maintenance service fees | Preserving continuity across repeated site visits | Define recurring tasks and responsibility for handovers |
| Landscape enhancements | Landscape enhancement providers such as The Davey Tree Expert Company | Renovation and enhancement project fees | Integrating improvements with maintained areas | Phase additions around ongoing grounds work |
| Source: Mordor Intelligence | ||||
Recurring grounds work and later enhancements offer separate earnings opportunities after the initial installation. Combining them gives a service provider a way to extend its commercial role through an existing site's life, while a nursery supplier earns from the plants supplied to that work. In its fiscal 2025 annual report, BrightView described recurring annual landscape maintenance contracts typically lasting 1 to 3 years and generally cancellable by customers on 30 to 90 days' notice. A provider capturing the maintenance handover earns continuing fees only while it retains the account.
Competitive Landscape
Market Concentration
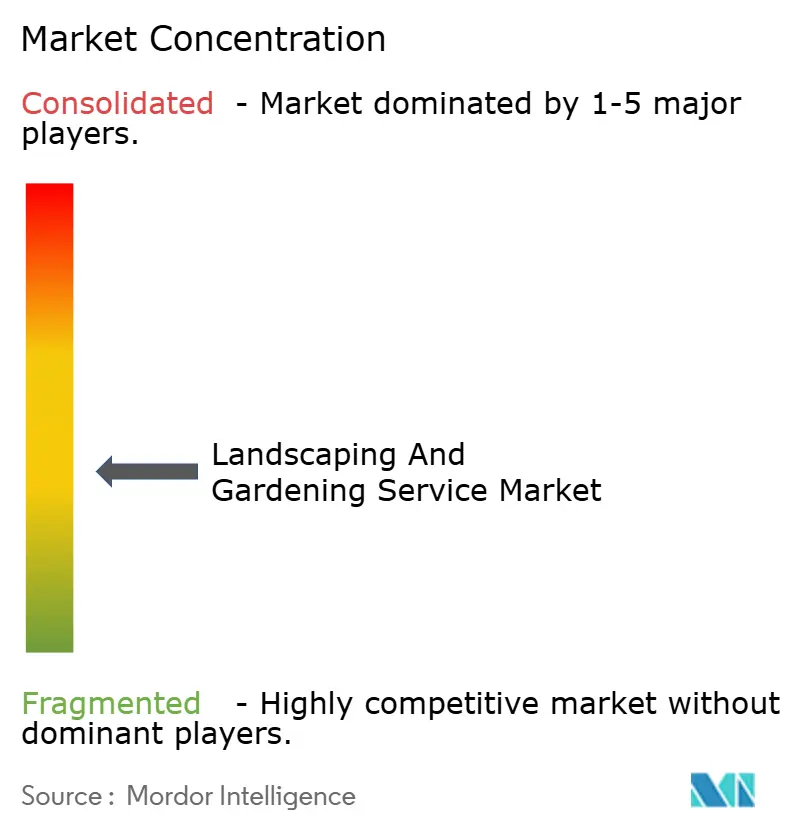
Competition combines large service groups with local operators, creating a fragmented delivery landscape even as ownership platforms expand through acquisitions. The major providers are BrightView Holdings, Inc., The Davey Tree Expert Company, TruGreen Limited Partnership, Yellowstone Landscape Group, Inc., and Ruppert Landscape, LLC. Davey's Residential/Commercial segment revenue increased by USD 57.2 million, or 7%, in 2025, driven by Commercial Landscape Services. The result illustrates the competitive weight of commercial landscape work inside a group serving multiple buyer categories, making business-property accounts relevant to the performance of a broader operating portfolio.
Geographic expansion through an acquired operator can give a commercial platform an established service presence without requiring a new location to be built from the start. In June 2026, Osprey Landscape Group, a Southfield Capital portfolio company, completed its acquisition of LandGraphics, establishing its California presence through a Southern California provider. In April 2026, Ruppert Landscape, LLC announced its acquisition of Five Seasons Landscape Management, a commercial landscaping and snow-removal provider in Columbus, Ohio. The Davey Tree Expert Company acquired LandStudies and Natural Directions in 2025 to broaden its services and expertise. Territory and capability are therefore separate routes to commercial accounts, allowing an acquirer to target either where it competes or the range of work it can undertake.
Acquisitions also let platforms add local density in metro areas where established commercial landscape companies already operate. In August 2026, Charter Vista Holdings announced it had acquired Visionscapes, an Atlanta-area operator specializing in large-scale commercial landscape installation and maintenance. Yellowstone Landscape Group, Inc. provides commercial installation and maintenance across greater Atlanta, placing a similar service proposition in the same local operating area. Matching service scopes leave an enlarged Charter Vista competing for the same installation and maintenance assignments as established Atlanta operators such as Yellowstone.
Landscaping And Gardening Service Industry Leaders
-
BrightView Holdings, Inc.
-
The Davey Tree Expert Company
-
TruGreen Limited Partnership
-
Yellowstone Landscape Group, Inc.
-
Ruppert Landscape, LLC
- *Disclaimer: Major Players sorted in no particular order
Landscaping And Gardening Service Market Companies Covered in this Report
- BrightView Holdings, Inc.
- idverde Group
- The Davey Tree Expert Company
- TruGreen Limited Partnership
- Yellowstone Landscape Group, Inc.
- Park West Companies, Inc
- Ruppert Landscape, LLC
- Gothic Landscape, Inc.
- LandCare USA, LLC
- Juniper Landscaping of Florida, LLC
- Pacific Landscape Management, LLC
- Denison Landscaping, Inc.
- Chapel Valley Landscape Company, Inc.
- The F.A. Bartlett Tree Expert Company
- Asia Flora & Landscape Sdn Bhd
Read Analysis of Landscaping And Gardening Service Companies
Key Opportunities for Market Participants
The opportunities compare 3 dated US municipal solicitations for planter services, public works landscaping, and landscape architecture within an engineering assignment. Their defined service scopes give providers specific assignments against which to assess existing delivery capacity. Providers with these capabilities can choose between delivering a defined landscape service and joining a broader design team, with the commercial proposition depending on the work each city is buying.
Market Opportunities Table of Landscaping And Gardening Service Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Roadway planter services | Philadelphia opened its Roadway Planter Program solicitation on October 9, 2026, with bids due November 10, 2026 | Municipal roadway landscape buyers | Offer a service package focused on planter care | Organizing service delivery around roadway access | Landscape service operators, including BrightView |
| Public works landscape services | Chandler listed a landscape-services proposal with submissions due November 12, 2026 | Municipal public works buyers | Match field teams and supervision to the landscape assignment | Mobilizing sufficient service capacity | Grounds-maintenance providers, including BrightView |
| Integrated landscape design assignments | Charleston's open Eastern Peninsula RFP combines civil engineering and landscape architecture, with proposals due November 2, 2026 | Municipal infrastructure and landscape-design buyers | Pair landscape design capability with civil engineering expertise | Coordinating the engineering and landscape interfaces | Landscape-design teams, including BrightView |
| Source: Mordor Intelligence | |||||
Municipal procurement of landscape work with a bounded scope is the central opening illustrated by these notices. Responding requires enough delivery capacity and coordination to take on the specified assignment within the procurement timetable. With the 3 submissions falling due between November 2 and November 12, 2026, the opening favors operators whose crews, supervision, or design resources are already organized.
Recent Industry Developments in Landscaping And Gardening Service Market
- Aug 2026: Charter Vista Holdings announced it had acquired Visionscapes, a large-scale commercial landscape installation and maintenance company serving the Atlanta area.
- Jun 2026: Osprey Landscape Group, a Southfield Capital portfolio company, completed its acquisition of LandGraphics, a commercial landscape services provider serving Southern California, including San Diego and Orange County.
- Apr 2026: Ruppert Landscape, LLC announced its acquisition of Five Seasons Landscape Management, a commercial landscaping and snow-removal provider in Columbus, Ohio.
Landscaping And Gardening Service Market Report Scope and Research Methodology
Market Definition and Coverage
The global landscaping and gardening service market measures annual spending on paid services to design, construct, manage, maintain, and enhance outdoor landscapes and gardens. It covers provider revenue from work delivered worldwide to residential, commercial, and other end users.
Scope exclusions: Landscaping tools and equipment, plants, fertilizers, and other retail products sold separately are excluded.
Segments Covered in This Report
- By Type
- Landscape and Garden Design
- Construction and Landscape Management
- Landscape and Garden Maintenance
- Landscape and Garden Enhancements
- Other Types
- By End User
- Commercial
- Residential
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Denmark
- Rest of Europe
- Asia-Pacific
- China
- India
- Australia
- Malaysia
- South Korea
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the U.S. Census Bureau's NAICS manual define service classifications that help distinguish landscape care, installation, design-linked work, and standalone landscape architecture, while its Service Annual Survey provides a revenue series for U.S. service industries. UN DESA's World Urbanization Prospects supplies settlement and population context for regional demand analysis, and Aspire's public commercial landscape industry survey describes material and equipment cost pressures reported by U.S. contractors.
Company filings, including 10-Ks, annual reports, and investor materials, can be checked for service revenue, contract activity, acquisitions, and regional operations, with reputable business press providing dated context for major projects and ownership changes. These named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
The primary research program includes executives, functional leaders, and managers at large, mid-sized, and smaller landscape service providers, alongside commercial, residential, and public buyers who specify or purchase the work. Their input tests the interpretation of secondary evidence on service boundaries, pricing, contract renewal, crew capacity, and regional demand, while company filings and public procurement records provide independent checks. Where a market or segment input remains unreported, analysts document the gap, use comparable service and buyer evidence to bound it, and triangulate the resulting estimate before including it.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 30% | CXOs: 20% | APAC: 40% |
| Mid tier: 50% | Functional/Unit leaders: 35% | EMEA: 35% |
| Smaller Players: 20% | Managers: 45% | Americas: 25% |
Market-Sizing & Forecasting
A top-down estimate starts with worldwide customer spending on paid landscape and garden services, then estimates annual value by region in USD and reconciles regional totals to the global market. A multivariate regression can relate historical service revenue to urban population and development, residential and commercial property activity, public landscape procurement, labor availability and wage costs, and water restrictions. Each variable represents a distinct source of service demand or delivery capacity, while scenario analysis tests alternative paths for construction activity and input costs. Historical revenue and service mix evidence from public surveys, provider filings, contract notices, and interviews support regional and service-type shares, with buyer evidence separating residential, commercial, and other demand. Selective bottom-up checks can roll up disclosed provider revenue and sampled project or contract values, and analysts investigate missing company coverage, avoid double-counting work spanning service types, and use regional or peer evidence to bound gaps rather than treating the checks as a complete census. Interviews with provider and buyer specialists can challenge the direction and practical size of forecast variables, while source-backed trends and sensitivity cases determine whether a forecast needs adjustment.
Data Validation & Update Cycle
Analysts triangulate the market total and segment shares against independent government series, company disclosures, procurement activity, and customer-side signals, then investigate differences in service boundary, timing, and unit. They check unusual year-over-year movements, compare regional and segment totals with the global result, and resolve outliers through source review or re-contact with relevant provider or buyer respondents before multi-step analyst review and sign-off. The dataset is refreshed annually, reviewed sooner after material events such as major regulatory changes or large acquisitions, and given a fresh source and variance check immediately before delivery. Re-contact is triggered when a new disclosure conflicts with a prior response or changes a material model input.
Mordor Intelligence's Landscaping and Gardening Service Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global landscaping and gardening service market measures annual spending on paid services to design, construct, manage, maintain, and enhance outdoor landscapes and gardens.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Interviews with provider and buyer specialists can challenge the direction and practical size of forecast variables, while source-backed trends and sensitivity cases determine whether a forecast needs adjustment.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 133.5 B (2027) | |
| Global Research Publisher A | USD 156.2 B (2026) | At its 2026 base, this estimate is 17.0% above this report's 2027 value of USD 133.5 B, 1 year later. The listed service scope adds snow and ice management to landscape work, extending the counted service bundle. |
| Global Research Publisher B | USD 109.4 B (2025) | At its 2025 base, this estimate is 18.0% below this report's 2027 value of USD 133.5 B, 2 years later. Its earlier base year and published positive market growth can place the estimate below a later-year value. |
Mordor Intelligence's analysts triangulate the market total and segment shares against independent government series, company disclosures, procurement activity, and customer-side signals, then investigate differences in service boundary, timing, and unit.
Key Questions Answered in the Report
What is the landscaping and gardening service market size and growth outlook?
The market is expected to reach USD 133.5 billion in 2027 and USD 182.2 billion by 2032, growing at a CAGR of 6.42% over 2027-2032.
What drives demand for paid landscape and garden services?
Paid yard assistance and green campuses support demand. An unweighted 2025 survey of 250 self-identified US solo-agers aged 50 or older, a younger and wealthier subset, found 34% using paid lawn and yard care.
Which type of paid landscaping service is largest?
Landscape and garden maintenance led with 40.89% of total service revenue in 2026.
Which companies are major providers of landscape and garden services?
Major providers include BrightView Holdings, Inc., The Davey Tree Expert Company, TruGreen Limited Partnership, Yellowstone Landscape Group, Inc., and Ruppert Landscape, LLC.
What limits landscaping contractors' growth?
Skilled-labor shortages and input costs constrain delivery. An interim Australian review of landscaping consultations from October 2025 to April 2026 identified shortages of skills and new entrants.
Which regions lead landscape and garden services?
North America led with 39.31% of service revenue in 2026. Asia-Pacific is forecast to grow fastest at a CAGR of 7.6% over 2027-2032.