
Japan Automotive Engine Oils Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Base Year For Estimation | 2025 |
| Forecast Data Period | 2026 - 2031 |
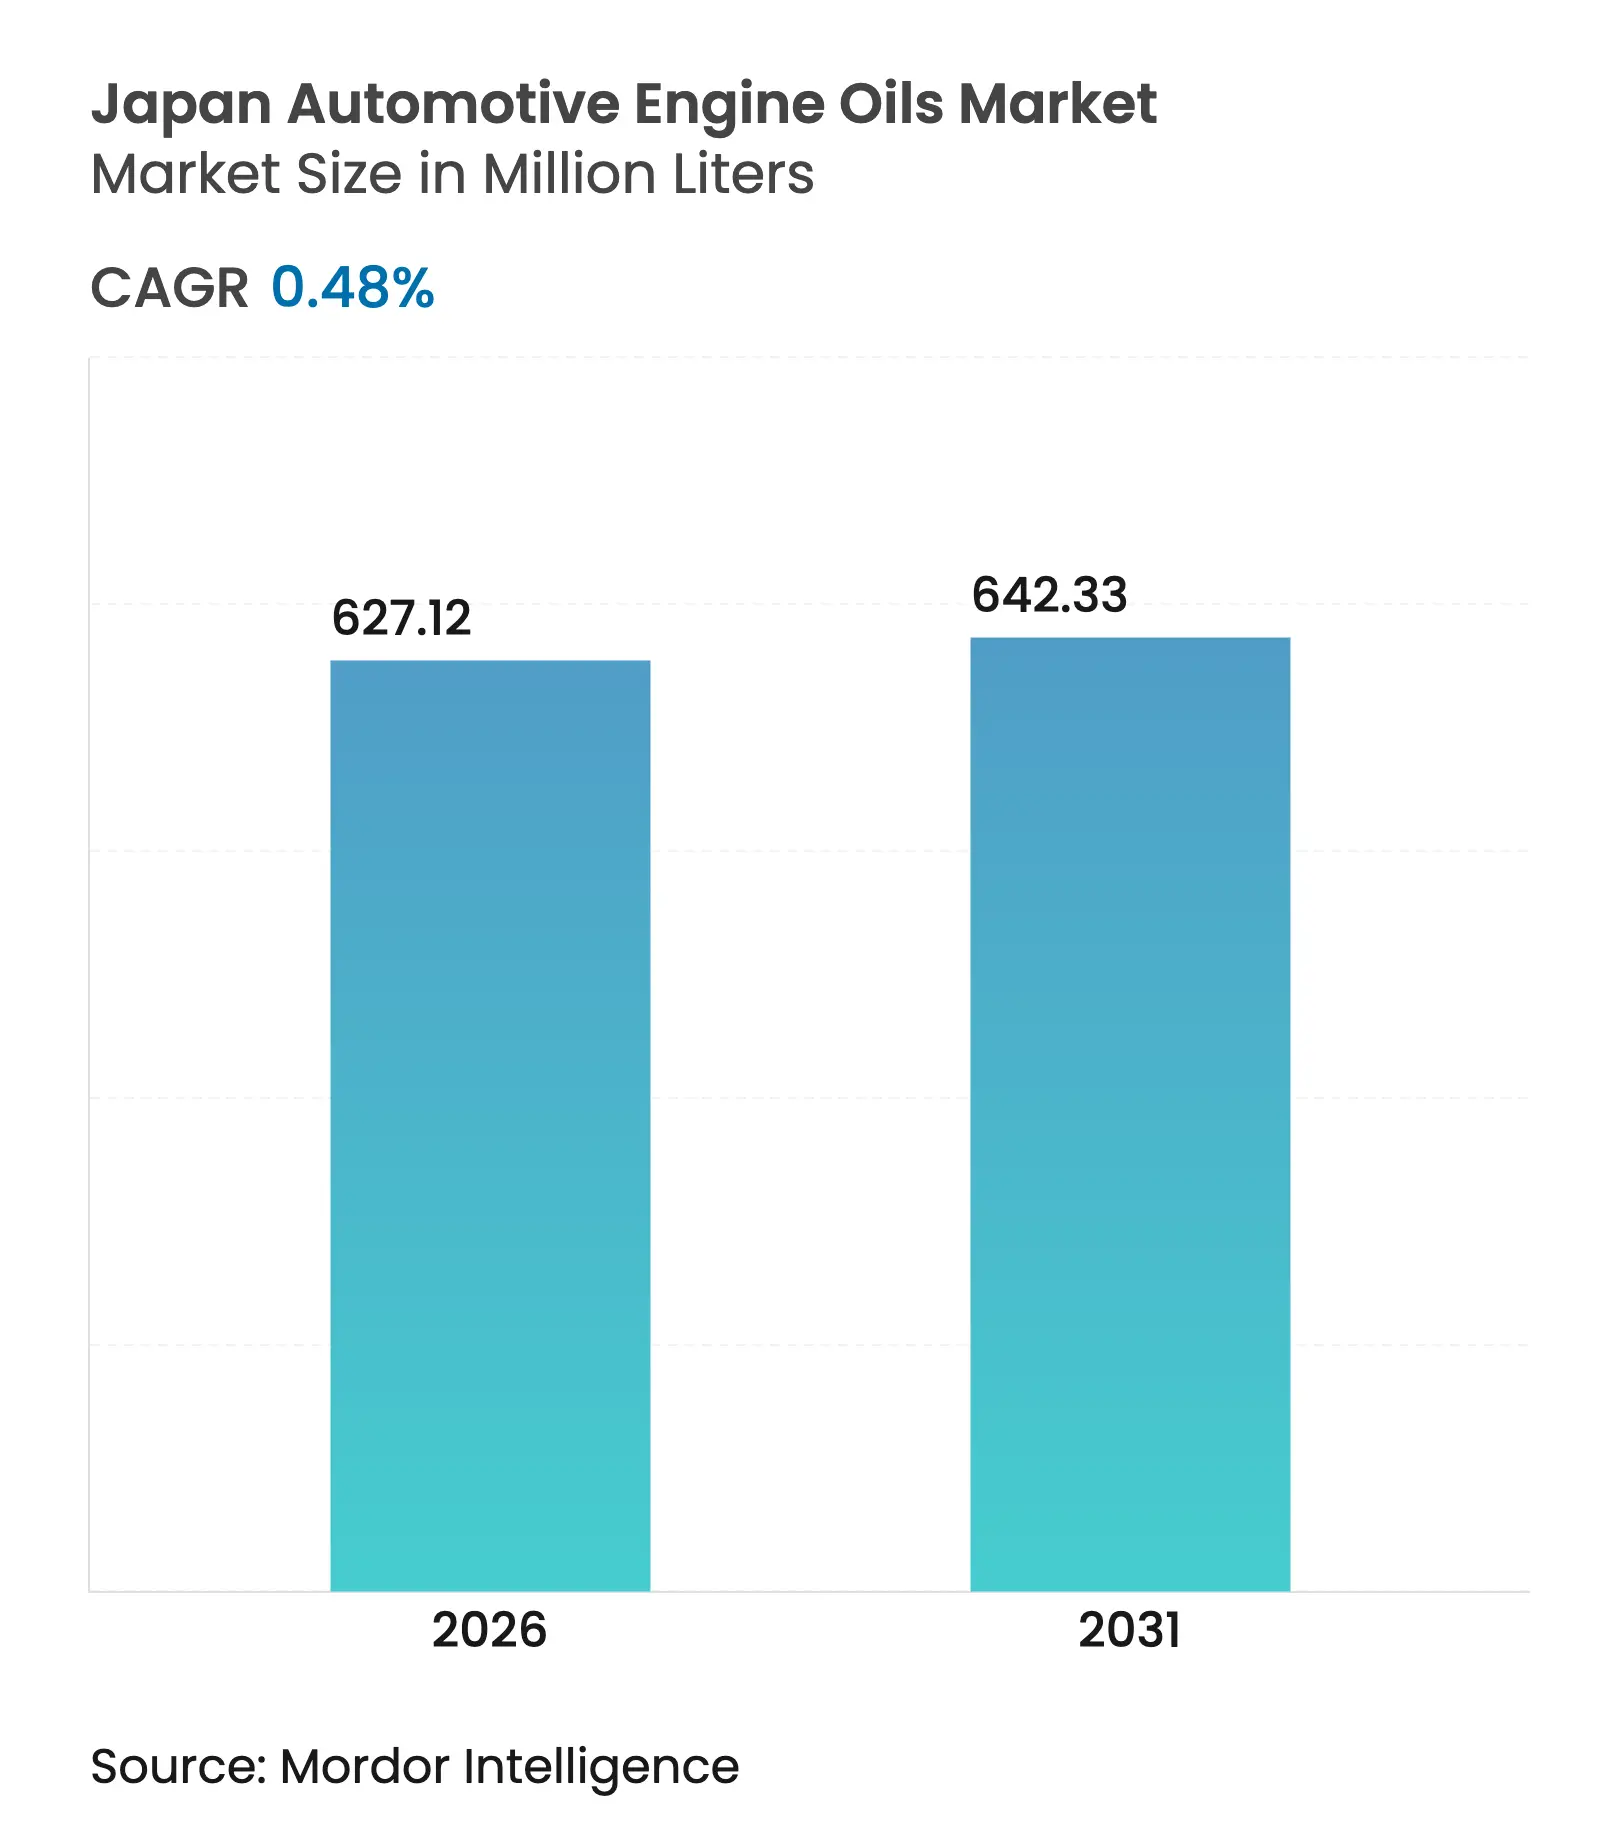
| Market Volume (2026) | 627.12 Million liters |
| Market Volume (2031) | 642.33 Million liters |
| CAGR | 0.48 % |
| Market Concentration | High |
Major Players *Disclaimer: Major Players sorted in no particular order. Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. |

Japan Automotive Engine Oils Market Analysis by Mordor Intelligence
The Japan Automotive Engine Oils Market size was valued at 624.12 Million liters in 2025 and estimated to grow from 627.12 Million liters in 2026 to reach 642.33 Million liters by 2031, at a CAGR of 0.48% during the forecast period (2026-2031). This modest trajectory reflects a mature vehicle parc, rapid electrification, and the industry’s accelerating pivot toward extended-drain synthetic formulations. Ultra-low-viscosity oils (0W-20 and below) account for an estimated 89-95% of factory fills as OEMs chase stringent corporate average fuel-economy targets. Mandatory nationwide “Shaken” inspections create predictable service intervals that partly cushion volume erosion, while start-stop-ready synthetics gain traction alongside Japan’s world-leading hybrid penetration. OEM-branded lubricants dominate replacement demand because factory-fill partnerships embed long-term brand loyalty inside dealer networks.
Key Report Takeaways
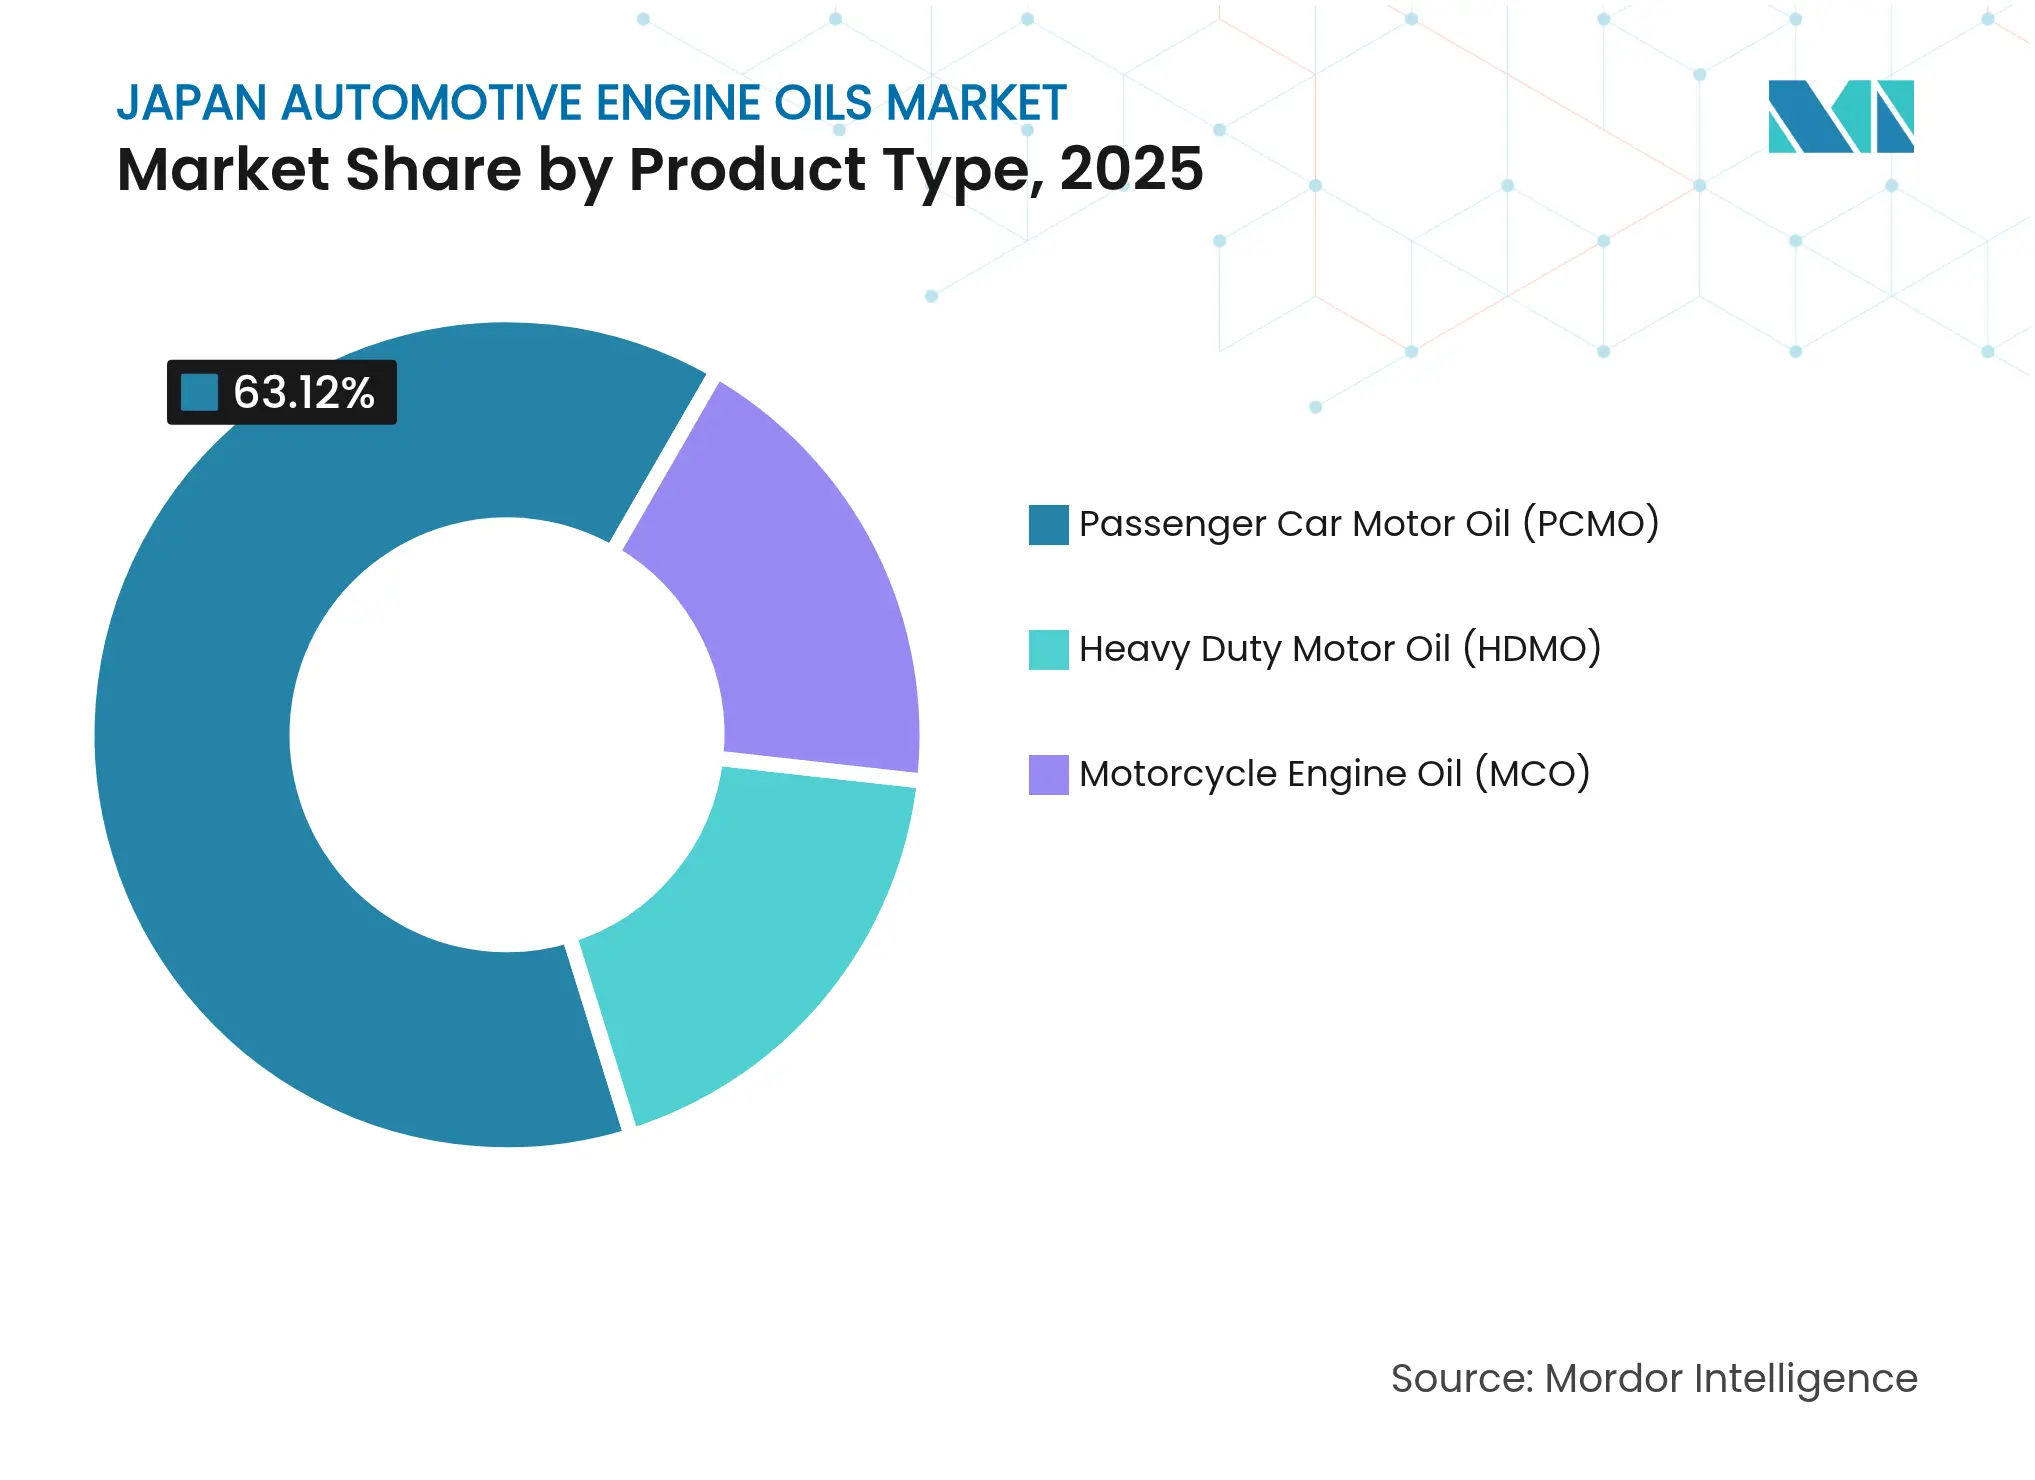
- By product type, Passenger Car Motor Oil led with 63.12% of the Japan automotive engine oil market share in 2025, while motorcycle Engine Oil is projected to post the fastest 0.74% CAGR through 2031.
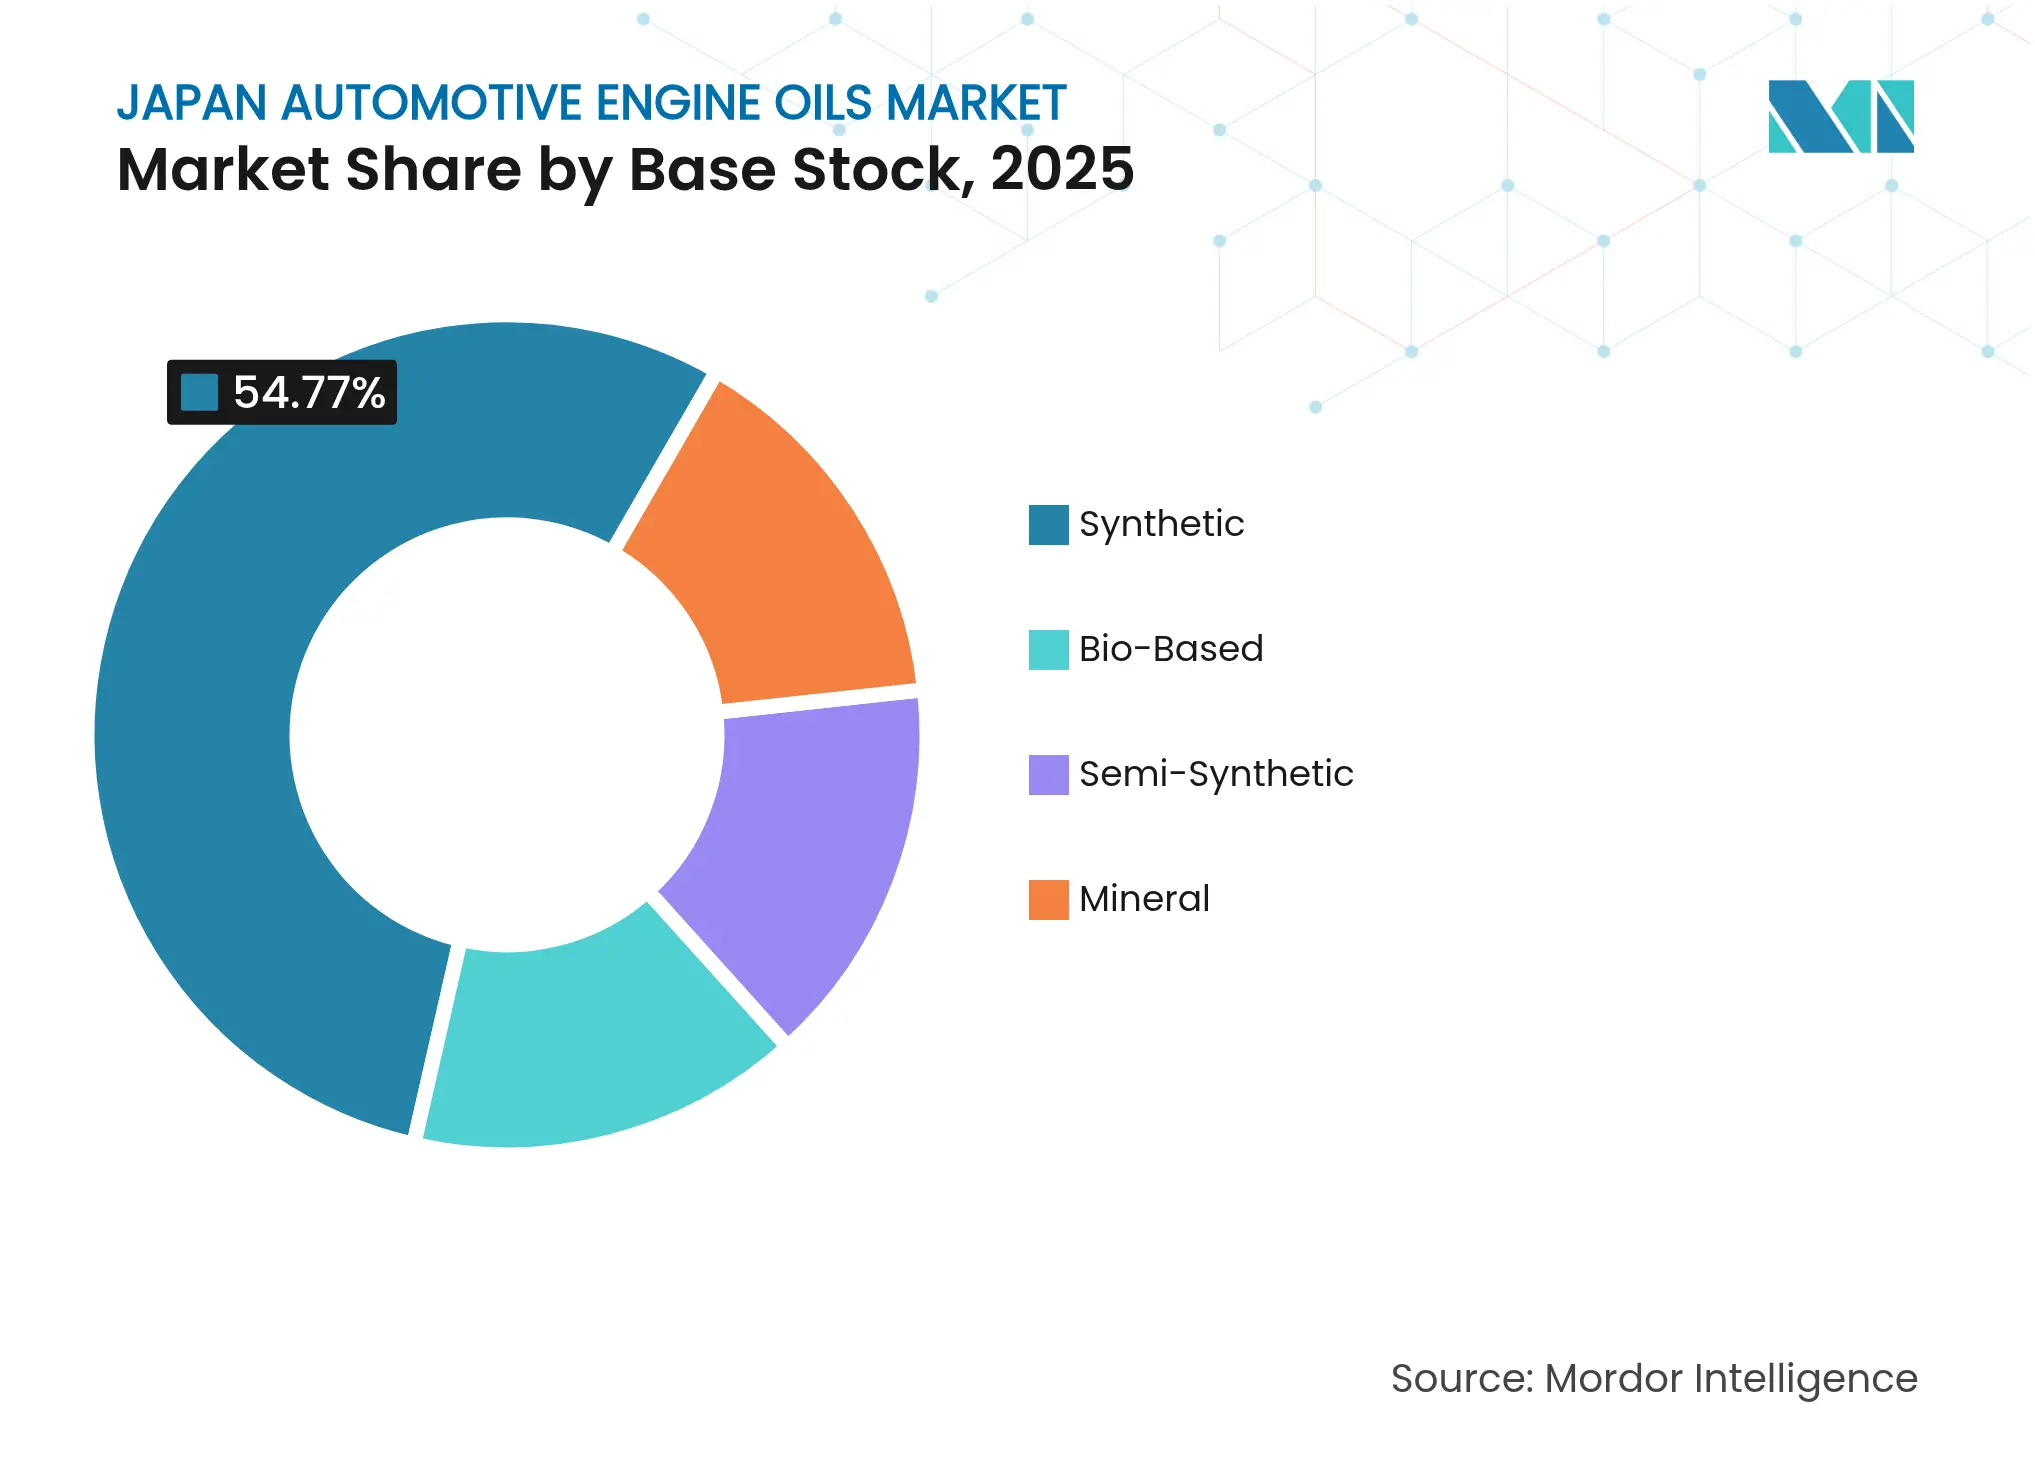
- By base stock, synthetic grades commanded 54.77% share of the Japan automotive engine oil market size in 2025, while bio-based oils are forecast to expand at a 0.61% CAGR between 2026-2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence's proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Japan Automotive Engine Oils Market*
| Drivers | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
Stricter CAFE-equivalent fuel-economy norms
|
+0.3%
|
Nationwide, early adoption in Tokyo and Osaka
|
Medium term (2-4 years)
|
Hybrid-fleet expansion requiring start-stop-ready
synthetics
| +0.2% | Urban centers countrywide | Long term (≥ 4 years) |
Mandatory “Shaken” inspections sustaining oil-change
volumes
| +0.1% | Nationwide | Long term (≥ 4 years) |
OEM factory-fill partnerships locking in branded sales
| +0.2% | Assembly hubs in Aichi, Kanagawa and others | Medium term (2-4 years) |
Quick-lube and e-commerce channels widening premium-oil
access
| +0.1% | Major cities, spreading to suburbs | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Stricter CAFE-Equivalent Fuel-Economy Norms Drive Ultra-Low-Viscosity Adoption
Japan targets a fleet average of 25.4 km per liter by 2030, a 32% jump over 2016 levels[1]. Achieving this goal hinges on 0W-16 and 0W-8 formulations that reduce pumping losses without sacrificing wear protection. The Ministry of Land, Infrastructure, and Transport and METI use a corporate-average compliance framework that pressures every OEM to spec friction-modified synthetics across model ranges. Toyota and ENEOS jointly advanced the new JASO GLV-2 standard, enabling ultra-high-viscosity-index oils suited to electrified drivetrains. As Japanese hybrids operate engines at lower temperatures, lubricant chemistries must balance very-low-temperature fluidity with adequate high-temperature shear stability to preserve catalytic-converter durability.
Hybrid-Fleet Expansion Demanding Start-Stop-Capable Synthetics
Hybrids captured 18% of Japan’s new light-duty sales in 2019, the highest share among major economies. Start-stop events can exceed 500,000 cycles over a vehicle life, making film retention and additive robustness critical. ENEOS and Idemitsu validated new Group III+ basestock blends that retain viscosity after repeated micro-oxidation episodes during regenerative-braking shutdowns. Dealer workshops report rising demand for SP-rated synthetics labeled “Hybrid-Approved,” indicating consumer acceptance of premium price points in exchange for warranty adherence and fuel-economy retention.
Mandatory “Shaken” Inspections Sustaining Regular Oil-Change Volumes
Every passenger vehicle undergoes a mandatory Shaken test at year three and every two years thereafter. The program enforces OEM-recommended maintenance and emission checks, effectively anchoring oil changes at roughly 12- to 18-month intervals even as drain limits lengthen. Service operators align promotional bundles around inspection windows, keeping volume attrition below the pace implied by synthetic adoption. Inspection documentation requirements also encourage continued use of OEM labels because such proof simplifies resale and insurance procedures.
OEM Factory-Fill Partnerships Locking in Branded Oil Sales
OEM genuine oils supply 75% of Japan’s passenger-car lubricant demand, dwarfing the 10-15% penetration in China and India. Factory-fill contracts embed brand preference at purchase, while dealer loyalty programs reinforce repeat sales. ENEOS supplies Toyota, Nissan, and Mazda; Idemitsu services Honda, Subaru, and Daihatsu, and both firms maintain in-house additive development to meet proprietary engine tests. Global brands face protracted approval cycles and high localization hurdles, constraining new entrants despite attractive margins on synthetics.
Restraints Impact Analysis of Japan Automotive Engine Oils Market*
| Restraints | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
EV penetration eroding long-term ICE-oil demand
|
-0.4%
|
Nationwide, fastest in megacities
|
Long term (≥ 4 years)
|
Wide price gap between premium synthetics and mineral oils
| -0.2% | Price-sensitive consumer segments | Short term (≤ 2 years) |
Longer drain-interval technology lowering liters per
vehicle
| -0.1% | Premium-vehicle segments | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
EV Penetration Eroding Long-Term ICE-Oil Demand
Government subsidies, toll exemptions, and a growing public-charging network lifted battery-electric registrations 72% year on year in 2024. Full EVs eliminate engine oil use, while range-extender hybrids halve consumption. The Petroleum Association of Japan projects lubricant production sliding to 2.3 million kiloliters by 2030, versus 2.6 million kiloliters in 2023, mirroring falling gasoline throughput. Industry leaders therefore diversify into e-fluids, thermal-management coolants and hydrogen fuel partnerships to hedge revenue risk.
Wide Price Gap Between Premium Synthetics and Mineral Oils
Fully synthetic 4-liter packs retail at JPY 5,800 (USD 37.6) versus JPY 1,900 (USD 12.3) for mineral equivalents at mass-merchandise outlets. The 200-300% differential discourages cost-conscious owners who perceive oil as a commodity, especially in rural prefectures where annual mileage is low. Education programs from JASO and OEM dealers stress total-cost-of-ownership benefits, but price sensitivity remains a headwind while wage growth stagnates.
Japan Automotive Engine Oils Market Segment Analysis
By Product Type: Passenger Car Motor Oil (PCMO) Dominates While MCO Accelerates
PCMO generated 63.12% of 2025 volume, underpinning the Japan automotive engine oil market through the country’s 61 million-unit passenger-car fleet. Nearly all new car models specify 0W-20 or thinner, cementing demand for Group III synthetics that deliver fuel-economy gains without warranty risk. The segment also benefits from high loyalty to OEM-genuine labels, reinforcing stable premium pricing.
Motorcycle Engine Oil records the fastest 0.74% CAGR as two-wheel registrations rose to 376,720 units in 2023 and micro-mobility trends expand scooter use in crowded urban corridors. JASO MA2 specifications for wet-clutch performance differentiate premium offerings, and Japanese riders show strong brand affinity toward domestic suppliers. Heavy-duty motor oil faces stagnation because electrified logistics pilots and hydrogen fuel-cell trucks gain government support, though construction and marine niches provide resilience.
Note: Segment shares of all individual segments available upon report purchase
By Base Stock: Synthetic Oils Lead, Bio-Based Formulations Emerge
Synthetic grades captured 54.77% of 2025 consumption as OEM drain intervals extended beyond 10,000 km and ultra-low viscosities required higher VI base oils. Blenders favor hydrocracked Group III+ stocks, while a small share of Group IV PAOs targets high-performance and motorsport niches. The Japan automotive engine oil market size for synthetic products is forecast to add 8.9 million liters by 2031 despite flat overall demand, reflecting continued mineral-to-synthetic conversion.
Bio-based oils posted the quickest 0.61% CAGR on the back of Idemitsu’s IFG Plantech Racing launch in 2024, the first API SP product with over 80% plant-derived content. Government net-zero ambitions foster pilot programs for re-refining waste oils and integrating esterified vegetable bases. Semi-synthetics retain relevance among cost-sensitive drivers seeking partial fuel-economy benefits without the full synthetic price premium, whereas conventional mineral oils gradually lose share outside legacy fleets.
Note: Segment shares of all individual segments available upon report purchase
Geography Analysis
Kanto, Chubu and Kansai Automotive Engine Oils Market
Japan’s archipelagic layout concentrates 68% of the population in three major metropolitan areas—Kanto, Chubu, and Kansai—driving premium lubricant demand in dense dealer networks. Tokyo alone accounts for roughly 17% of national PCMO volume due to high passenger-car density, stringent emission controls, and affluent consumers who favor OEM service packages.
Regional Japan Automotive Engine Oils Market
Regional production clusters around Aichi Prefecture (Toyota), Kanagawa Prefecture (Nissan), and Hiroshima Prefecture (Mazda) tether factory-fill demand to nearby blending plants. These industrial zones benefit from just-in-time logistics and captive service channels that reinforce OEM-genuine brand dominance. Rural prefectures such as Hokkaido and Tohoku display a higher HDMO mix because of commercial agriculture and snow-removal fleets requiring higher-viscosity multigrades.
Nationwide Japan Automotive Engine Oils Market
Japan relies on imports for 94.7% of its crude supply, mostly from the Middle East, making exchange-rate swings and maritime freight costs key input risks. Nineteen refineries provide sufficient base-oil output, yet declining transport-fuel throughput forces continuous capacity optimization. Consolidation reduced the national service-station count to 27,414 in March 2024 from 60,421 in 1995, prompting lubricant marketers to pivot toward e-commerce, quick-lube chains and dealer-installed “subscription” oil programs.
Reports are available across multiple geographies.
Gain in-depth market insights across regions to support informed decisions.
Competitive Landscape
Market Concentration
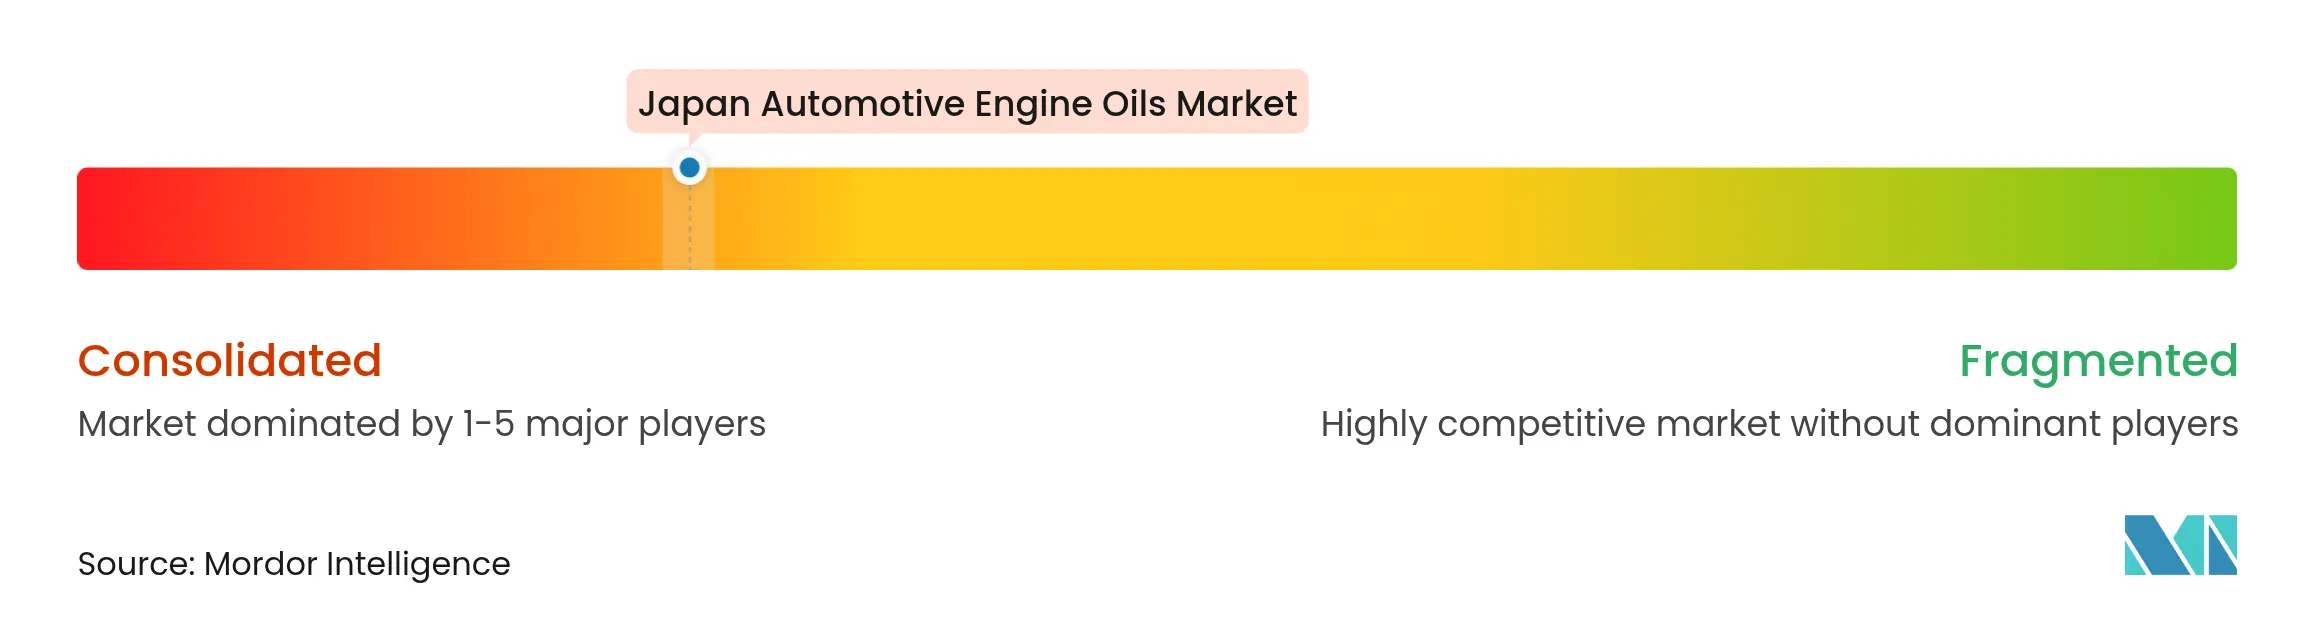
The market is consolidated in nature. Recent diversification includes a USD 97 million stake in Danish e-methanol producer C2X and joint ventures for synthetic rubber, signaling hedging against flattening lubricant demand. ExxonMobil and TotalEnergies remain active in premium segments but struggle to breach entrenched OEM partnerships. High JASO certification costs, language-specific marketing, and strict end-user loyalty raise market-entry barriers, leaving collaborative research and development with domestic assemblers as the most viable route for newcomers.
Japan Automotive Engine Oils Industry Leaders
*Disclaimer: Major Players sorted in no particular order
Japan Automotive Engine Oils Market Companies Covered in this Report
- AKT Japan Co. Ltd (TAKUMI Motor Oil)
- BP p.l.c.
- Chevron Japan (Caltex Havoline)
- Cosmo Energy Holdings Co. td
- ENEOS Corporation
- Exxon Mobil Corporation
- FUCHS
- Honda Motor Co. Ltd (Honda Genuine Oil)
- Idemitsu Kosan Co. Ltd
- Japan Sun Oil Company Ltd (SUNOCO Inc.)
- Motul
- NAKAJIMA.B.C Co.,Ltd.
- Saudi Arabian Oil Co.
- Shell plc
- Suzuki Motor Corporation
- Wako Chemical Co. Ltd
Recent Industry Developments in Japan Automotive Engine Oils Market
- April 2025: Toyota and ENEOS co-published research outlining the new JASO GLV-2 ultra-high-VI gasoline engine-oil standard establishing new industry standards for carbon neutrality and fuel economy optimization in both new and existing vehicles.
- December 2024: Idemitsu introduced IFG Plantech Racing, the world’s first API SP motor oil formulated with over 80% plant-based feedstock.
Table of Contents for Japan Automotive Engine Oils Industry Report
1. Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2. Research Methodology
3. Executive Summary
4. Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter CAFE-equivalent fuel-economy norms (0W-16/0W-8 push)
- 4.2.2 Hybrid-fleet expansion demanding start-stop-capable synthetics
- 4.2.3 Mandatory “Shaken” inspections sustaining regular oil-change volumes
- 4.2.4 OEM factory-fill partnerships locking in branded oil sales
- 4.2.5 Quick-lube and e-commerce channels widening premium-oil access
- 4.3 Market Restraints
- 4.3.1 EV penetration eroding long-term ICE-oil demand
- 4.3.2 Wide price gap between premium synthetics and mineral oils
- 4.3.3 Longer drain-interval technology lowering litres/vehicle
- 4.4 Value Chain and Distribution Channel Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
- 4.6 Regulatory Framework
- 4.7 Automotive Industry Trends
5. Market Size and Growth Forecasts (Volume)
- 5.1 By Resin Type
- 5.1.1 Passenger Car Motor Oil (PCMO)
- 5.1.1.1 0W-XX
- 5.1.1.2 5W-XX
- 5.1.1.3 10W-XX
- 5.1.1.4 15W-XX
- 5.1.1.5 Monogrades
- 5.1.1.6 Other Grades
- 5.1.2 Heavy Duty Motor Oil (HDMO)
- 5.1.2.1 0W-XX
- 5.1.2.2 5W-XX
- 5.1.2.3 10W-XX
- 5.1.2.4 15W-XX
- 5.1.2.5 Monogrades
- 5.1.2.6 Other Grades
- 5.1.3 Motorcycle Engine Oil (MCO)
- 5.1.3.1 0W-XX
- 5.1.3.2 5W-XX
- 5.1.3.3 10W-XX
- 5.1.3.4 15W-XX
- 5.1.3.5 Monogrades
- 5.1.3.6 Other Grades
- 5.2 By Base Stock
- 5.2.1 Mineral
- 5.2.2 Synthetic
- 5.2.3 Semi-Synthetic
- 5.2.4 Bio-Based
6. Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Production Capacity, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AKT Japan Co. Ltd (TAKUMI Motor Oil)
- 6.4.2 BP p.l.c.
- 6.4.3 Chevron Japan (Caltex Havoline)
- 6.4.4 Cosmo Energy Holdings Co. td
- 6.4.5 ENEOS Corporation
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 FUCHS
- 6.4.8 Honda Motor Co. Ltd (Honda Genuine Oil)
- 6.4.9 Idemitsu Kosan Co. Ltd
- 6.4.10 Japan Sun Oil Company Ltd (SUNOCO Inc.)
- 6.4.11 Motul
- 6.4.12 NAKAJIMA.B.C Co.,Ltd.
- 6.4.13 Saudi Arabian Oil Co.
- 6.4.14 Shell plc
- 6.4.15 Suzuki Motor Corporation
- 6.4.16 Wako Chemical Co. Ltd
7. Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
8. Key Strategic Questions for CEOs
Japan Automotive Engine Oils Market Report Scope
Segmentation Overview
| By Resin Type | Passenger Car Motor Oil (PCMO) | 0W-XX |
| 5W-XX | ||
| 10W-XX | ||
| 15W-XX | ||
| Monogrades | ||
| Other Grades | ||
| Heavy Duty Motor Oil (HDMO) | 0W-XX | |
| 5W-XX | ||
| 10W-XX | ||
| 15W-XX | ||
| Monogrades | ||
| Other Grades | ||
| Motorcycle Engine Oil (MCO) | 0W-XX | |
| 5W-XX | ||
| 10W-XX | ||
| 15W-XX | ||
| Monogrades | ||
| Other Grades | ||
| By Base Stock | Mineral | |
| Synthetic | ||
| Semi-Synthetic | ||
| Bio-Based | ||
