
Influencer Marketing Market Size and Share
Influencer Marketing Market Analysis by Mordor Intelligence
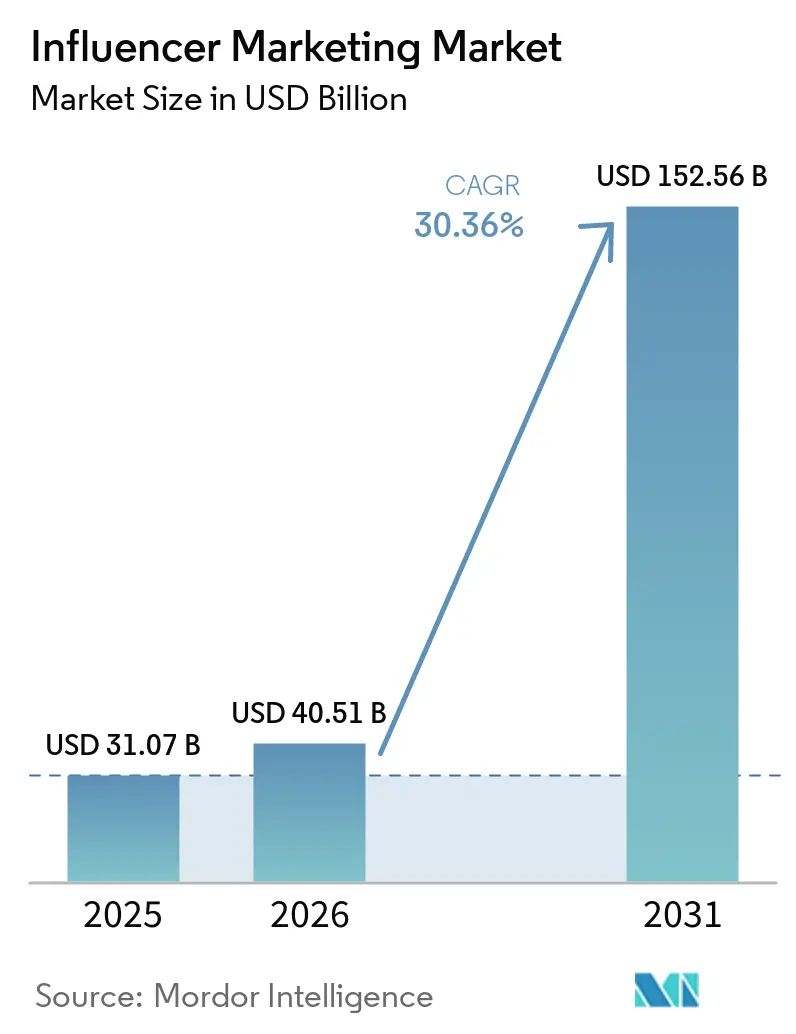
The influencer marketing market size is expected to increase from USD 40.51 billion in 2026 to USD 52.81 billion in 2027 and reach USD 193.9 billion by 2032, growing at a CAGR of 29.71% over 2027-2032.
Short-form video activity and sales attribution give advertisers stronger reasons to connect creator campaigns with commercial outcomes. In India, demand for regional creator partnerships adds a need for coordinated delivery, while audience-quality concerns raise the cost of verifying campaign value. Software and managed-service providers can respond through AI-assisted selection, coordinated execution, and reporting, with content screening informing talent decisions. The ability to expand such services efficiently depends on limiting the manual reconciliation burden that fragmented measurement adds as creator programs scale.
Key Report Takeaways
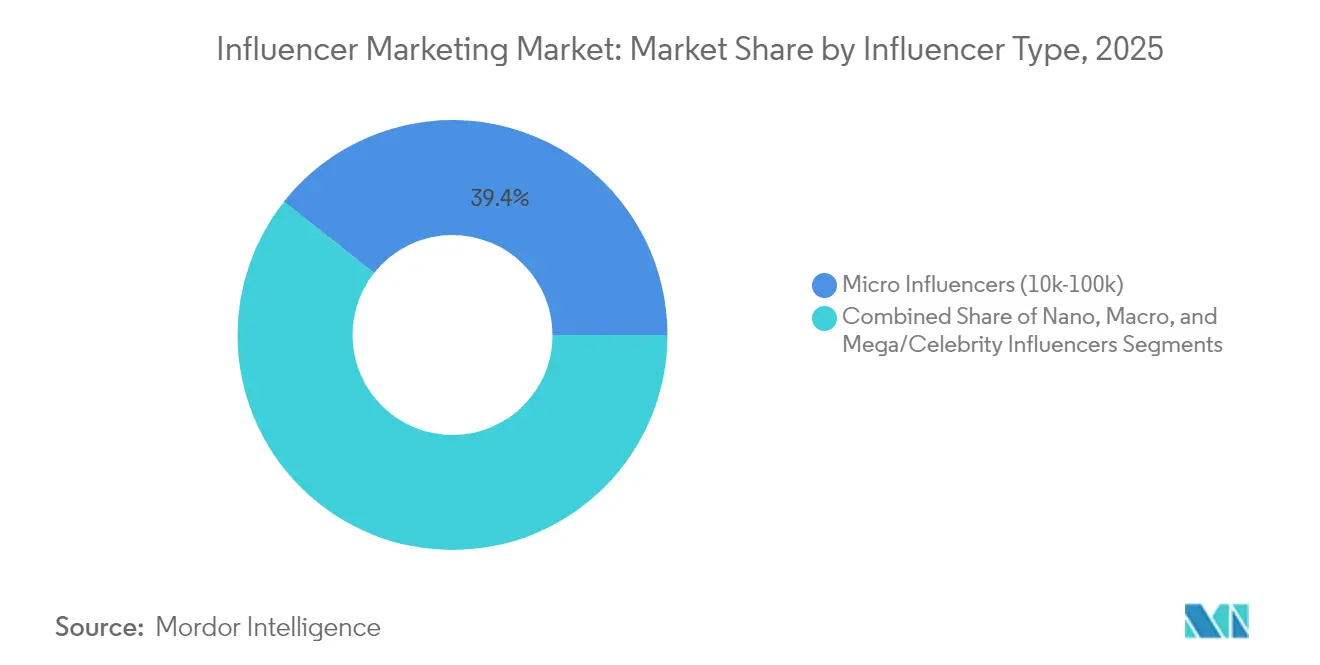
- By influencer type, micro influencers held a 39.52% influencer marketing market share in 2026, while nano influencers are forecast to grow fastest at a CAGR of 34.4% over 2027-2032.
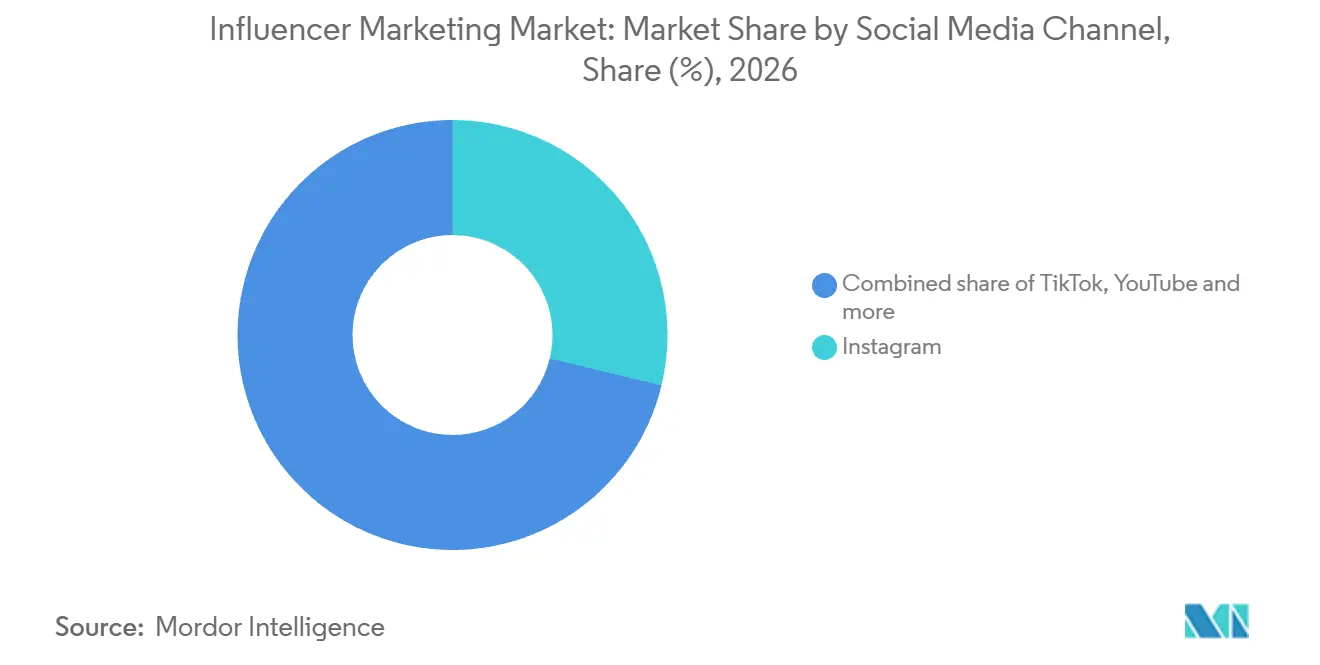
- Among social media channels, Instagram accounted for a 28.77% share of the influencer marketing market size in 2026, with TikTok forecast to grow fastest at a CAGR of 36.2% over 2027-2032.
- For applications, campaign management led with a 33.82% share in 2026, while the compliance and fraud detection segment is forecast to grow fastest at a CAGR of 33.2% over 2027-2032.
- Across end users, retail and e-commerce held the largest share at 27.36% in 2026, and the gaming and entertainment segment is forecast to grow fastest at a CAGR of 32.1% over 2027-2032.
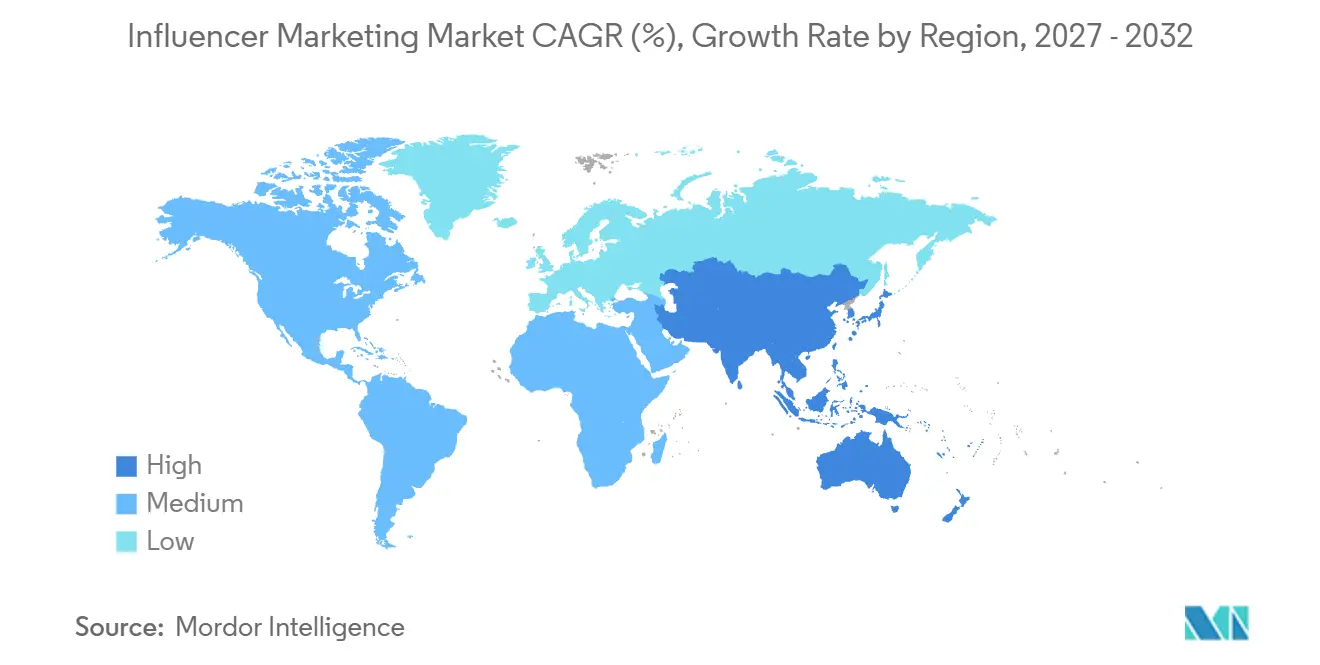
- Geographically, North America led with a 34.1% share in 2026, while Asia-Pacific is forecast to grow fastest at a CAGR of 33.3% over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Influencer Marketing Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing Dominance of Short-Form Video Platforms (TikTok, Reels) in Brand Budgets (North America and Asia) | +9.1% | North America and Asia | Short term (≤ 2 years) |
| Adoption of AI-Driven Creator Matching and Dynamic Pricing Engines by SaaS Platforms (US, EU) | +7.4% | United States and European Union | Medium term (2-4 years) |
| Integration of Social Commerce APIs Driving Attribution-Linked Spend (SEA and MENA) | +6% | Southeast Asia and MENA | Medium term (2-4 years) |
| Rise of Nano/Micro Influencer Networks for Hyper-local Campaigns (India, Brazil, Africa) | +6.3% | India, Brazil and Africa | Short term (≤ 2 years) |
| Regulatory Push for Transparent Ad and Brand Safety Tools (EU, US) | +3.5% | European Union and United States | Short term (≤ 2 years) |
| Shift Toward Outcome-based Pay-per-Campaign Pricing among DTC Brands | +2% | North America, particularly the United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Growing Dominance of Short-Form Video Platforms (TikTok, Reels) in Brand Budgets (North America and Asia)
Campaign concentration gives short-form execution a commercial advantage over a service offer spread evenly across social channels. In 2025, TikTok accounted for 61.3% of influencer-marketing campaign usage in Indonesia on AnyTag, compared with 37.6% for Instagram. For each campaign, a brand's platform choice narrows the pool of relevant creators and the setting for content coordination. Together the 2 channels carried almost 99% of AnyTag's Indonesian campaign usage in 2025, so brands running local campaigns there generate demand for creator selection and coordination built around TikTok and Instagram first.
Adoption of AI-Driven Creator Matching and Dynamic Pricing Engines by SaaS Platforms (US, EU)
Creator selection is an entry point for AI because it connects the advertiser's brief with the choice of who receives paid campaign work. In IAB's July-August 2025 survey in the United States, 35% of brand and agency buyers reported using AI for creator selection at the survey date. Because the recommendation precedes commissioning, selection software can influence which creator receives the assignment and how the brief is tailored. For software suppliers, explaining the fit between each recommendation and the advertiser's criteria offers a way to differentiate AI matching tools.
Integration of Social Commerce APIs Driving Attribution-Linked Spend (SEA and MENA)
Sales attribution strengthens demand for campaign services by connecting creator activity with a commercially relevant outcome beyond audience reach. From April 2026, TikTok Shop's Thailand sales reporting added seller-versus-affiliate-creator order attribution across Shop Analytics, Partner Center, and Open API. That separation provides a way to assess creator-associated orders apart from the seller's own activity within the same shop. For suppliers serving paid creator campaigns, API access offers a basis for incorporating this distinction into advertiser reporting. Order-source attribution gives sellers and their partners a more specific measure of creator-associated orders than total shop revenue, supporting performance-oriented creator campaign reporting.
Rise of Nano/Micro Influencer Networks for Hyper-local Campaigns (India, Brazil, Africa)
Kofluence's 2025 India report linked preference for micro-influencers with 10,000 to 100,000 followers to regional, hyper-local campaigns. In July 2025, PitchOnNet reported that Indian brands were increasingly using vernacular influencers to build trust in Tier 2 to Tier 4 markets. For Indian campaign providers, follower range and language relevance answer different parts of the brief. A network provider can coordinate those assignments while keeping vernacular communication relevant to each campaign's intended audience. A regional roster therefore needs selection criteria for audience scale and language fit, giving providers a more specific task than assembling creators by follower count alone.
Restraints Impact Analysis of Influencer Marketing Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Creator Fraud and Bot Engagement Eroding ROI in Emerging Markets | -2% | Asia-Pacific, particularly India | Short term (≤ 2 years) |
| Third-Party Cookie Restrictions Delaying Cross-Channel Attribution | -1.2% | Europe's national advertising markets | Medium term (2-4 years) |
| Fragmented Data Standards Limiting Inter-platform Benchmarking | -0.9% | North America, Europe and Asia-Pacific | Long term (≥ 4 years) |
| Intense Price Competition from Point-Solution Start-ups | -0.5% | North America and Europe | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Creator Fraud and Bot Engagement Eroding ROI in Emerging Markets
Suspicious audiences weaken the connection between a creator's apparent reach and the attention an advertiser can use commercially. In June 2025, Astatine.ai reported that suspicious or inactive audiences impaired campaign performance and complicated ROI measurement for Indian brands. For campaign buyers, paying against audience counts therefore carries a verification burden before those counts can justify further investment. Dabur India Ltd added engagement rate, cost per engagement, and cost per view to all major influencer campaigns, according to June 2025 reporting. More detailed performance reporting cannot by itself establish audience authenticity, leaving verification as a separate campaign cost.
Third-Party Cookie Restrictions Delaying Cross-Channel Attribution
Cross-channel attribution becomes harder to use as a campaign investment test when signals for connecting exposure and response are limited. In IAB Europe's August-September 2025 survey of European digital-advertising organizations, 53% identified attribution without cookies as a measurement challenge. In the same survey, 48% identified signal loss from cookie deprecation as an addressability challenge. For advertisers assessing creator work alongside their wider digital advertising, those limitations weaken the basis for connecting exposure on one channel with response on another. Program expansion consequently carries the extra burden of substantiating creator contributions when the wider advertising measurement environment offers incomplete attribution.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Influencer Marketing Market Segment Analysis
By Influencer Type:
Buyer Trade-offs Favor Smaller Creator AssignmentsMicro influencers accounted for a 39.52% share of the influencer marketing market size in 2026, making them the largest segment. In IAB's July-August 2025 survey in the United States, 55% of 453 creator-ad-spend decision-makers reported brand partnerships with creators having 10,000 to 50,000 followers. For that narrower follower range, IAB suggested adoption likely reflected a balance of reach, content quality, and affordability. Suppliers serving this tier therefore have to show that reach and content quality justify the fee, given IAB's suggested role for affordability in adoption.
Nano influencers (1k-10k) are forecast to be the fastest-growing segment, with a CAGR of 34.4% over 2027-2032. In Cheerful's campaign negotiation data measured September 16, 2026, brands offered a median USD 150 per deliverable to creators with 1,000 to 10,000 followers. The dataset is skewed toward direct-to-consumer campaigns. At that proposed fee level, coordination overhead must stay proportionate to the value of a single assignment. Standardized briefs and repeatable approvals can limit the work attached to each proposed deliverable, favoring streamlined coordination over bespoke account management.

By Social Media Channel:
Audience Scale and Paid Participation Shape DemandInstagram represented a 28.77% influencer marketing market share in 2026, making it the largest segment. Meta reported 3 billion Instagram monthly active users in September 2025. Meta CEO Mark Zuckerberg said Instagram reached 2 billion daily active users in Q2 2026. These distinct measures establish broad participation and frequent use, giving creator partnerships a substantial setting for potential repeated exposure. Instagram-focused discovery and execution tools therefore address the largest channel segment, making support for that platform a consequential product priority for campaign suppliers.
TikTok is forecast to be the fastest-growing segment, with a CAGR of 36.2% over 2027-2032. From August 2025 to July 2026, 93% of CreatorIQ customers used TikTok for creator marketing. TikTok reported that the number of creators receiving TikTok One rewards globally rose 90% between June 2025 and May 2026. Customer use provides a buyer-side signal, while rewarded participation shows expansion in the pool taking part in compensated collaborations. Supplier differentiation can center on matching paid TikTok creators to specific briefs, since access alone does not resolve which collaborator fits an advertiser's assignment.
By Application:
Execution Scale Creates Demand for Embedded ScreeningCampaign management was the largest segment, with a 33.82% share in 2026. CreatorIQ, a creator-marketing software provider, said its customers ran more than 44,000 campaigns across 170 countries in 2025, up 70% from 2024.[1] In 2025, CreatorIQ powered its largest single customer deployment by campaign count, with more than 1,350 active campaigns globally, 9,000+ unique creators, and 320+ monthly active users. The deployment combines coordination inside the customer's team with activation of a much larger creator roster. For enterprise advertisers, campaign-management software therefore has value as an operating framework for concurrent work, giving execution capacity a role beyond the initial choice of creator.
Compliance and fraud detection is forecast to be the fastest-growing segment, at a CAGR of 33.2% over 2027-2032. SafeIQ, CreatorIQ's brand-safety and suitability tool, analyzed more than 2.3 billion frames of creator video in the year preceding October 13, 2026. In October 2026, Collab by ZDX reported that SafeIQ informed partnership decisions and helped put brand-aligned talent before its clients. The agency account places suitability review before talent recommendations, where a creator's fit with a client's brand matters to the selection. Agencies can pair automated video screening with their own client-specific judgment, keeping the final talent recommendation tied to the advertiser's brand.
By End User:
Retail Reach and Creator-Led Launch Campaigns Create Different BriefsRetail and e-commerce was the largest end-user segment, accounting for 27.36% in 2026. Among German retail companies with at least 10 employees already using influencers, Bitkom's 2025 survey found an average 7% of advertising budgets allocated to influencer marketing. In that survey, 88% of retailers with influencer experience reported reaching new target audiences through influencer advertising.[2] That reported reach supplies a buyer-side reason for considering creator activity alongside other advertising channels. Retail demand therefore supports services that connect a creator's audience with an advertiser's intended target group, making audience relevance a commercial test for the paid assignment.
Gaming and entertainment is forecast to be the fastest-growing segment, at a CAGR of 32.1% over 2027-2032. In 2025, game publisher 2K partnered with agency QYOU on a creator-led Borderlands 4 launch campaign, for which QYOU reported 32 million video views. QYOU activated cosplay, maker, and comedy creators around the game's humor and art style. That approach makes the choice of creator community and the coordination of its creative brief central to what the publisher purchases. A game launch can therefore generate assignments built around a title's humor and art style, extending demand to creators from communities such as cosplay, maker, and comedy.
Geography Analysis
North America Influencer Marketing Market
North America accounted for a 34.1% influencer marketing market share in 2026, making it the largest region. In IAB's July-August 2025 survey in the United States, 43% of brand respondents reported using creator platforms independent of social media for sponsored-content work. That adoption gives independent campaign infrastructure a defined buyer base, creating room for suppliers to organize sponsored work alongside the social networks that distribute it. Because a majority of surveyed U.S. brands did not report independent-platform use, suppliers serving North America face an adoption task as well as competition for established platform buyers.
Asia-Pacific Influencer Marketing Market
Asia-Pacific is forecast to be the fastest-growing region, with a CAGR of 33.3% over 2027-2032. Across AnyMind Group's 10 Asia-Pacific markets, performance-driven campaigns represented 42.47% of tracked influencer-marketing activity in 2025, up from 30.67% in 2024 and 28.24% in 2023.[3] Awareness-focused campaigns nevertheless remained the majority of tracked activity in 2025. Suppliers therefore face a dual task of preserving broad exposure while attaching more campaigns to defined business outcomes along the consumer decision journey. Providers that combine execution and measurement can address both objectives within one advertiser relationship, extending the creator program beyond a single awareness placement.
In South America, 72% of Brazilian creator followers surveyed in August 2026 preferred brands working with several smaller creators over one celebrity. In Europe, 84% of French national advertisers using influencer marketing prioritized financial creator remuneration in 2025. Within Middle East and Africa, Humanz's 2026 South African survey found that about one in 5 creator respondents had ever received cash for brand work. Consumer preferences inform the composition of a creator brief, while the remuneration findings affect how compensated partnerships can be organized. Suppliers can prioritize multi-creator rosters in Brazil, administer financial remuneration for France's national advertisers, and establish cash or product compensation terms with South African creators.
Regulatory Framework and Outlook
The comparison assesses selected jurisdictions from the perspective of advertisers commissioning paid creator campaigns. These frameworks place different operational tasks around commercial influence, hidden advertising, livestream review, and creator eligibility. For an advertiser, attractiveness depends on the clarity of those tasks and the coordination needed to commission compliant work. Brazil's framework covers third-party-content providers offering advertising or paid boosting to Brazilian consumers, including foreign providers, and advertising-content suppliers.
Regulatory Table of Influencer Marketing Market
| Decision factor | United States | Brazil | United Kingdom | China | United Arab Emirates |
|---|---|---|---|---|---|
| Primary authority | Federal Trade Commission | SENACON, SEDIGI and SPDIGI | Competition and Markets Authority, Trading Standards Services | State Administration for Market Regulation, Cyberspace Administration of China | National Media Authority |
| Key instruments or direction | Consumer Reviews and Testimonials Rule, effective October 21, 2024 | Joint Order No. 3 of September 2026, with 30-day and 90-day phases after publication | Digital Markets, Competition and Consumers Act 2024, Part 4, effective April 6, 2025 | Livestream-commerce measures, effective February 1, 2026 | Individual advertising and media-content permit, paid or unpaid |
| Commercial effect | Prohibits buying fake indicators to misrepresent commercial influence | After the 90-day phase, covered platforms provide tools for content suppliers to disclose material connections in context | Unfair-commercial-practices responsibilities cover brands, creators, intermediaries and platforms | Room operators review displayed and spoken content before broadcasts and verify marketer identities | Applicants meet commercial-licensing, conduct, content-standard and authority-training requirements |
| Current policy attractiveness | High | Medium | Medium | Low | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The prohibition in the United States on buying fake indicators to misrepresent commercial influence offers a targeted safeguard, while the United Kingdom's advertising-chain responsibilities create a broader continuing workload. Brazil's hardening direction reflects its September 2026 order's 30-day general phase and 90-day disclosure-tool phase after publication, with marketplaces, editorially controlled providers, and certain previously licensed copyrighted content excluded. China's already operative pre-broadcast review and identity checks weigh on livestream campaign execution, so its low attractiveness reflects work required within the existing regime. The UAE's defined permit route combines commercial licensing, conduct and content standards, and training, supporting medium attractiveness and continuity of that administrative path.
Value Chain Stages
The value chain compares campaign planning, onboarding, content coordination, and measurement as linked activities with different supplier responsibilities. Later offers an influencer-marketing platform plan and a platform-plus-services plan. Impact.com contracts specify platform and product subscription charges and may include service fees. The commercial distinction is whether an advertiser buys access to operating tools or assigns coordination work to a supplier.
Value Chain Analysis Table of Influencer Marketing Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Program design and creator selection | Campaign strategy and creator-selection agencies such as Later and IZEA Worldwide Inc. | Campaign strategy revenue within service plans | Aligning the brief with creator selection | Agree selection criteria before recruitment |
| Creator onboarding and contract administration | Campaign-workflow software providers such as CreatorIQ and Impact.com | Platform and product subscription fees | Coordinating contracts, onboarding and payments | Assign ownership and preserve agreed campaign terms |
| Content coordination and publication oversight | Creator-content coordinators such as Later and IZEA Worldwide Inc. | Service-plan fees covering campaign coordination | Connecting creator submissions with brand review | Use agreed content briefs and named review owners |
| Measurement and campaign review | Campaign-reporting service providers such as Later and IZEA Worldwide Inc. | Campaign-service fees covering reporting | Matching reported results to the campaign objective | Agree measures when setting the campaign brief |
| Source: Mordor Intelligence | ||||
Full-service providers can span these stages, while workflow suppliers support the teams performing the same activities. Bundled fees reward responsibility across the campaign, and subscriptions reward continued access to its operating tools. Resilience comes from preserving decision ownership and campaign records at each handoff, allowing a combined platform and service offer to stay coherent as participants change.
Competitive Landscape
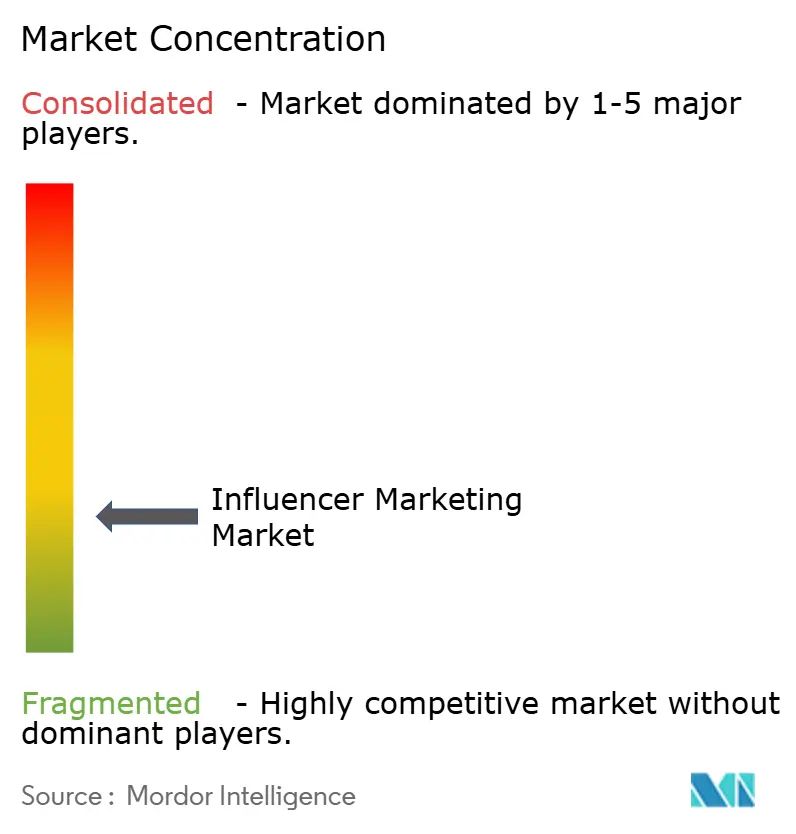
Competition is fragmented across specialist software and managed-service providers, with Upfluence, Aspire.io, Later, NeoReach, and Traackr, Inc. among the major participants. Aspire.io combines creator discovery, campaign management, and measurement, while NeoReach supplies both influencer-marketing services and technology. In September 2026, Later integrated the acquired creator-affiliate platform Mavely into its business, giving creators access to enterprise brand partners while direct campaign applications were described as planned. Specialist software and managed-service firms can serve different stages of the same paid campaign, creating competition among supplier models as well as individual platforms.
First-party YouTube reporting makes the distinction between organic exposure and paid amplification a concrete competitive feature. On September 24, 2026, Later announced a YouTube Creator Partnerships API integration that it said was already live across more than 300 campaigns and 70 brands. It combined creator discovery, channel insights, automated campaign-video matching, and organic-versus-paid reporting for YouTube campaigns. Matching videos to deliverables can make performance records part of campaign execution, reducing reliance on manually assembled evidence. With first-party channel data and separate organic and paid views, advertisers can assess a sponsored video's organic response separately from views generated through paid amplification.
In October 2025, Upfluence introduced Creator Marketplace, where brands publish campaigns, AI identifies and invites creators, and brands manage collaborations centrally. Creators apply directly to campaigns. That application model makes the relevance of the AI invitations a competitive test, since participation alone does not establish fit with the brand's criteria. Brazil's September 2026 joint order assigns covered third-party-content platforms offering ads or paid boosting an in-context material-connection disclosure-tool duty, effective 90 days after publication. Campaign providers serving those advertisers can align approved briefs with platform disclosure tools, while the legal responsibility for providing those tools rests with covered platforms.
Influencer Marketing Industry Leaders
-
Upfluence
-
Aspire.io
-
Later
-
NeoReach
-
Traackr, Inc.
- *Disclaimer: Major Players sorted in no particular order
Influencer Marketing Market Companies Covered in this Report
- Upfluence
- Aspire.io
- Later
- NeoReach
- Traackr, Inc.
- Webfluential.com
- Hypetap
- IZEA Worldwide Inc.
- Meltwater
- CreatorIQ
- Klear
- Sprout Social
- Impact.com
- Captiv8
- HypeAuditor
- Influence.co
- Julius Influencer Marketing
- Brandwatch
- Grapevine
- Linqia
- Post for Rent
- CreatorStack
- Modash
- Lumanu
- Grin
Key Opportunities for Market Participants
The opportunities compare creator-data integration, internal campaign coordination, and managed execution as different ways to address advertiser operating problems. In CreatorIQ's global 2026 survey, brand respondents identified integration and cross-team coordination as execution roadblocks. Suppliers can address these reported roadblocks through clearly scoped responsibility for campaign records and decisions.
Market Opportunities Table of Influencer Marketing Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Creator-data integration | 27% of brand respondents in CreatorIQ's global 2026 survey cited integration difficulties | Brands connecting creator records with marketing systems | Define data handoffs and connect agreed campaign records | Usable data handoffs across existing systems | CreatorIQ |
| In-house campaign coordination | 26% of brand respondents cited cross-team coordination roadblocks in the 2026 survey | Brands retaining internal creator-program teams | Establish shared approvals, decision owners and campaign records | Agreement across teams on responsibilities | CreatorIQ |
| Managed creator-program execution | Brand coordination roadblocks reported in 2026 | Brands seeking external campaign coordination | Bundle creator selection, activation and reporting under one service owner | Assigning execution responsibility between brand and provider | Later |
| Source: Mordor Intelligence | |||||
Integration support is the clearest opening, with difficulty connecting creator data and workflows across marketing systems the more frequently cited of these 2 roadblocks in CreatorIQ's global 2026 brand survey. Keeping execution in-house leaves coordination with brand teams, while managed execution transfers that work to a provider. Integration support can fit either arrangement because its assignment concerns creator records crossing marketing systems, allowing a supplier to define specific data handoffs without taking responsibility for the entire campaign.
Recent Industry Developments in Influencer Marketing Market
- Oct 2026: CreatorIQ made MeasureIQ and enhanced SafeIQ available for enterprise creator marketing, including the first deployment of Q, its enterprise agentic AI system, in MeasureIQ. Full Q capabilities were planned for early 2027.
- Sep 2026: Later completed Mavely's integration into its creator-marketing and social-commerce platform, giving creators access to enterprise brand partners. Direct applications to campaign opportunities were planned at the September announcement.
Influencer Marketing Market Report Scope and Research Methodology
Market Definition and Coverage
The influencer marketing market measures annual advertiser spending globally on creator-led sponsored campaigns and the software and managed services used to plan, place, measure, and govern them. It includes creator compensation and campaign-related platform or agency fees, with sales classified by creator, social channel, application, buyer industry, and region.
Scope exclusions: Pure affiliate-only tools, employee advocacy suites, and B2B word-of-mouth referral programs are excluded.
Segments Covered in This Report
- By Influencer Type
- Nano Influencers (1k-10k)
- Micro Influencers (10k-100k)
- Macro Influencers (100k-1M)
- Mega/Celebrity Influencers (>1M)
- By Social Media Channel
- TikTok
- YouTube
- Others (Snap, Pinterest, Twitch)
- By Application
- Campaign Management
- Search and Discovery
- Analytics and Reporting
- Product Seeding
- Compliance and Fraud Detection
- Others
- By End User
- Retail and E-commerce
- Fashion and Lifestyle
- Travel and Hospitality
- Food and Beverage
- Gaming and Entertainment
- Health and Fitness
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Interactive Advertising Bureau's creator advertising research help assess advertiser spending and budget intentions, while DataReportal's global digital reports provide comparable context on social platform reach and use. Federal Trade Commission endorsement guidance informs treatment of disclosure and fraud-control activity, and Meta's creator marketplace announcements illustrate changes in discovery and campaign workflows.
Company filings, investor materials, platform announcements, and reputable press coverage can cross-check supplier offerings, financial context, product launches, and changes in campaign execution. These sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys would cover advertisers and agencies that commission creator campaigns, platform and software providers, and managed-service firms, with functional leaders and managers able to explain budgets, campaign operations, and fee structures. Respondents would be asked to check secondary-source interpretations, variable assumptions, and segment boundaries, while unanswered gaps would be recorded and tested against independent company, platform, and advertising signals. Conflicting evidence would be reconciled by checking definitions, periods, and transaction coverage before it informs the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 38% |
| Mid tier: 40% | Functional/Unit leaders: 35% | EMEA: 30% |
| Smaller Players: 25% | Managers: 45% | Americas: 32% |
Market-Sizing & Forecasting
A top-down estimate would start with global advertiser spending on creator campaigns, then add only campaign software and managed-service fees that fall within the market boundary, counting pass-through payments once at the advertiser-paid amount. The main indicators would be digital advertising budgets and creator allocations, social platform reach and usage, campaign activity and creator compensation, adoption and revenue of campaign software, and managed-service fees. Each indicator helps explain the addressable spending pool, its activity level, or its average cost. Historical relationships among advertising budgets, platform use, campaign activity, and service revenue would inform a multivariate regression, with scenario analysis testing changes in social commerce, platform policies, and disclosure requirements. Segment shares by creator tier, channel, application, buyer industry, and region would be built from published spending splits and campaign evidence, then checked for consistency with total spending. Selective bottom-up checks would multiply sampled campaign volumes by observed compensation or fees and roll up disclosed supplier revenue where coverage is clear. Where a sampled price, volume, or supplier figure is missing, the analyst would use a documented comparable indicator, test a range, and retain only estimates consistent with the top-down total. Respondent evidence would test variable-level assumptions and explain material departures without substituting for recorded market evidence.
Data Validation & Update Cycle
Analysts would triangulate the model against independent advertising-spend, platform-use, campaign-volume, and supplier-revenue signals, checking that each measure matches the market boundary and year. Outliers and variances would be traced to source definitions, currency, timing, and possible double counting, then reviewed by a second analyst before sign-off. Respondents would be re-contacted when an answer is material, ambiguous, or inconsistent with other evidence. The model would be refreshed annually, updated between cycles for material platform, regulatory, or economic events, and given a fresh source and calculation review immediately before delivery.
Mordor Intelligence's Influencer Marketing Market Size Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The influencer marketing market measures annual advertiser spending globally on creator-led sponsored campaigns and the software and managed services used to plan, place, measure, and govern them.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The main indicators would be digital advertising budgets and creator allocations, social platform reach and usage, campaign activity and creator compensation, adoption and revenue of campaign software, and managed-service fees.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 52.81 B (2027) | |
| Global Data Publisher A | USD 33 B (2025) | At its 2025 base, this estimate is 37.5% below this report's 2027 value of USD 52.81 B, 2 years later. Its stated measure centers on creator placements and endorsements, while the report also counts qualifying campaign software and managed-service fees. |
| Global Market Research Firm B | USD 34.2 B (2025) | At its 2025 base, this estimate is 35.2% below this report's 2027 value of USD 52.81 B, 2 years later. Its estimate captures revenue from influencer marketing platform tools, while the report also counts creator compensation and qualifying managed-service fees. |
Mordor Intelligence's analysts would triangulate the model against independent advertising-spend, platform-use, campaign-volume, and supplier-revenue signals, checking that each measure matches the market boundary and year.
Key Questions Answered in the Report
What is the influencer marketing market size and growth outlook?
The market is expected to reach USD 52.81 billion in 2027 and USD 193.9 billion by 2032, with a CAGR of 29.71% over 2027-2032.
What supports spending on paid creator campaigns?
Short-form activity, AI-assisted creator selection, and regional campaigns support demand. IAB's 2025 survey in the United States found that 35% of brand and agency buyers reported using AI for creator selection.
Which creator tier leads influencer-campaign spending?
Micro influencers held 39.52% of spending in 2026. Nano influencers are forecast to grow fastest at a CAGR of 34.4% over 2027-2032.
Which companies supply influencer-campaign technology and services?
The sector includes Upfluence, Aspire.io, Later, NeoReach, and Traackr, Inc. as major suppliers.
What can constrain returns from influencer campaigns?
Astatine.ai reported in June 2025 that suspicious or inactive audiences impaired campaign performance and complicated ROI measurement for Indian brands. Better performance reporting does not by itself verify audience authenticity.
Which regions lead influencer-campaign spending and forecast growth?
North America led with 34.1% of spending in 2026. Asia-Pacific is forecast to grow fastest at a CAGR of 33.3% over 2027-2032.