
India Pet Food Market Analysis by Mordor Intelligence
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
India Pet Food Market Trends and Insights
Drivers Impact Analysis of India Pet Food Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Urban pet ownership upsurge | +4.3% | Chennai urban area | Medium term (2-4 years) |
| Pet care spending surges amid rising incomes and humanization trends | +3.5% | Nationwide | Medium term (2-4 years) |
| Expansion of e-commerce and quick-commerce delivery | +3.2% | Nationwide | Short term (≤ 2 years) |
| Domestic extrusion capacity expansion lowers prices | +2.8% | Zaheerabad in Telangana | Medium term (2-4 years) |
| Pet-insurance rollout lifts premium-diet spending | +0.4% | Nationwide | Long term (≥ 4 years) |
| Functional ingredients sourced from food waste cut formulation cost | +0.3% | Nationwide | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Urban pet ownership upsurge
An urban pet base gives suppliers a pool of animals around which to build local distribution and feeding propositions. As of July 6, 2026, Greater Chennai Corporation's website contained records for 126,781 pets in Chennai. The corporation introduced online pet licensing in August 2023 and launched an enhanced portal in October 2025 that required anti-rabies vaccination and microchipping to obtain a license. To convert that presence into product demand, a supplier must offer a feeding proposition that works for the owners it can reach. Pet registration tied to vaccination and identification creates an organized local pet-care setting around which retailers and food brands can build feeding outreach.
Pet care spending surges amid rising incomes and humanization trends
Higher nutrition spending can support domestic producers when local supply does not meet the range of products buyers seek. Retail value sales of premium dry dog food in India rose from USD 51.2 million in 2020 to USD 99 million in 2025, a 14.1% CAGR over 2020-2025. India's retail dog and cat food imports grew 16.2% annually from 2020 to 2025. Agriculture and Agri-Food Canada said the 2025 trade deficit suggested domestic demand outpaced local production capacity, particularly in premium and expanding segments. Premium dry dog food offers a defined category in which rising retail spending and the broader import-reliance signal intersect. For a domestic premium dry recipe, that overlap makes overseas brands the competitive reference for winning existing packaged-food spending.
Expansion of e-commerce and quick-commerce delivery
Rapid delivery can make packaged food accessible when an owner needs supplies before a planned store visit. Agriculture and Agri-Food Canada reported that Blinkit, Instamart and Zepto were gaining momentum by offering rapid delivery of pet essentials, including food. Equirus reported that the combined dark-store network of Blinkit, Instamart and Zepto expanded to 5,026 locations in May 2026, up from 3,405 a year earlier.[1] That wider infrastructure gives pet-food suppliers a potential route to serve short-notice demand beyond dedicated retail visits. For participating brands, the commercial value of delivery speed depends on local diet availability, making the neighborhood assortment a practical limit on the demand this channel can capture.
Domestic extrusion capacity expansion lowers prices
Domestic extrusion investment can make price competition more feasible by supporting repeatable production of finished pet food within India. In October 2025, Allana Group reported capacity of 10 tons per hour at its Zaheerabad facility, programmable logic controller automation, a dry-food and treat focus, and investment in extrusion technology. That combination provides a technical route to local supply at scale, with the commercial benefit depending on how effectively the operation is used. If unit costs fall, manufacturers can apply the savings to a more accessible feeding proposition while maintaining a separate role for premium recipes. The demand benefit emerges when production economics translate into finished-food prices that cost-sensitive owners can sustain.
Restraints Impact Analysis of India Pet Food Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High price sensitivity in Tier 2/3 cities | -1.4% | Nationwide | Medium term (2-4 years) |
| Low packaged-food penetration vs homemade diets | -1.2% | Nationwide | Long term (≥ 4 years) |
| Dependence on imported wet food and specialty ingredients | -0.7% | Nationwide | Short term (≤ 2 years) |
| Fragmented regulatory oversight slows feed-standard rollout | -0.4% | Nationwide | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
High price sensitivity in Tier 2/3 cities
For a price-sensitive household in a Tier 2/3 city, the cost of regular commercial feeding matters beyond the price of an initial trial pack. A product that fits an occasional purchase can be difficult to fund as the principal meal over repeated feeding occasions. For suppliers, this makes the affordable daily ration a more demanding price target than the smallest pack's entry cost. Smaller entry packs can make trial more accessible, but the commercial feeding proposition must also work at the cost of regular use. The supplier's constraint is the price tier that can support daily feeding, which limits premium positioning even when an entry pack is affordable.
Low packaged-food penetration vs homemade diets
A survey of 91 adult pet dogs in Central Kashmir found that about 63% were reared on homemade diets and about 5% were exclusively fed commercial dog feeds. A supplier addressing such owners competes with an established meal routine, rather than simply another packaged brand. Distribution can put a product within reach without changing who prepares the dog's daily food. The survey therefore locates the conversion opportunity in predominantly homemade-fed dogs, where habitual meal preparation can delay packaged-food volume beyond the work of adding retail outlets.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Pet Food Product: Core Meals Anchor Revenue and Format Competition
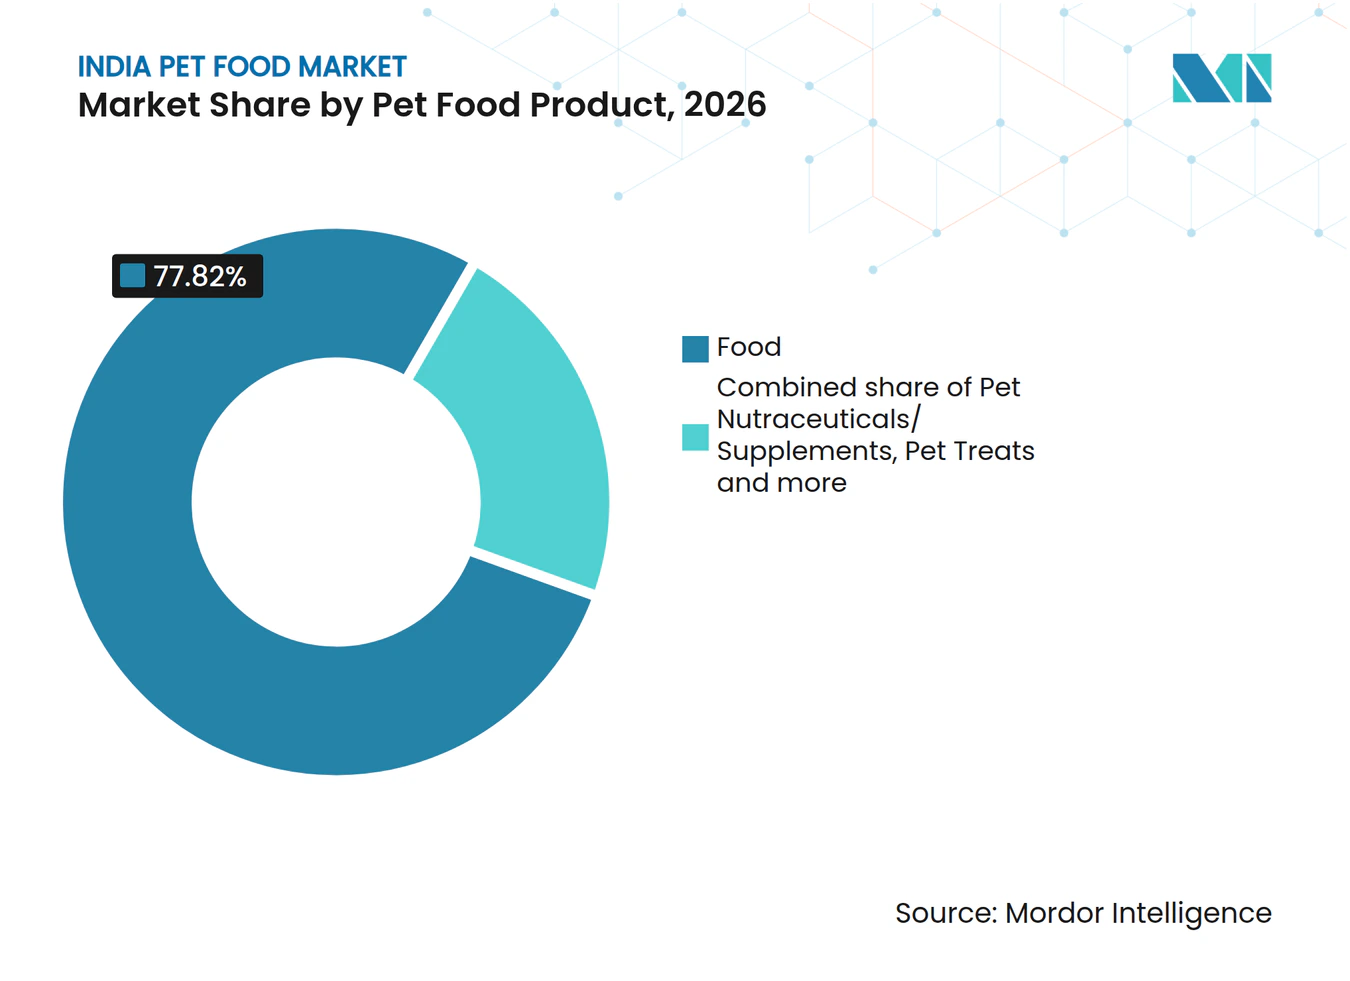
Food accounted for a 77.82% share of the India pet food market size in 2026 and is forecast to be the fastest-growing segment, with a CAGR of 11.2% over 2027-2032. The scale of this segment makes core meals central to the commercial opportunity for food producers. For FY2024-25, Drools Pet Food Pvt. Ltd. told the Delhi High Court that kibble products under its DROOLS mark contributed around 70% to 75% of its annual revenue. Most of Drools's revenue therefore depends on core kibble demand.
Food manufacturers can broaden the feeding choices they address by pairing meal formats with a defined regional distribution route. On September 8, 2026, Godrej Pet Care, a subsidiary of Godrej Consumer Products Ltd., debuted Godrej Ninja cat food in Tamil Nadu, where dry and wet formats were available through local pet retailers. The range covered kittens and adult cats, combining life-stage coverage with different meal formats. Availability through local pet retailers in Tamil Nadu made the range's reach dependent on that state's pet-store network.


Note: Segment shares of all individual segments available upon report purchase
By Pets: Dog Nutrition Sets the Main Portfolio Priorities
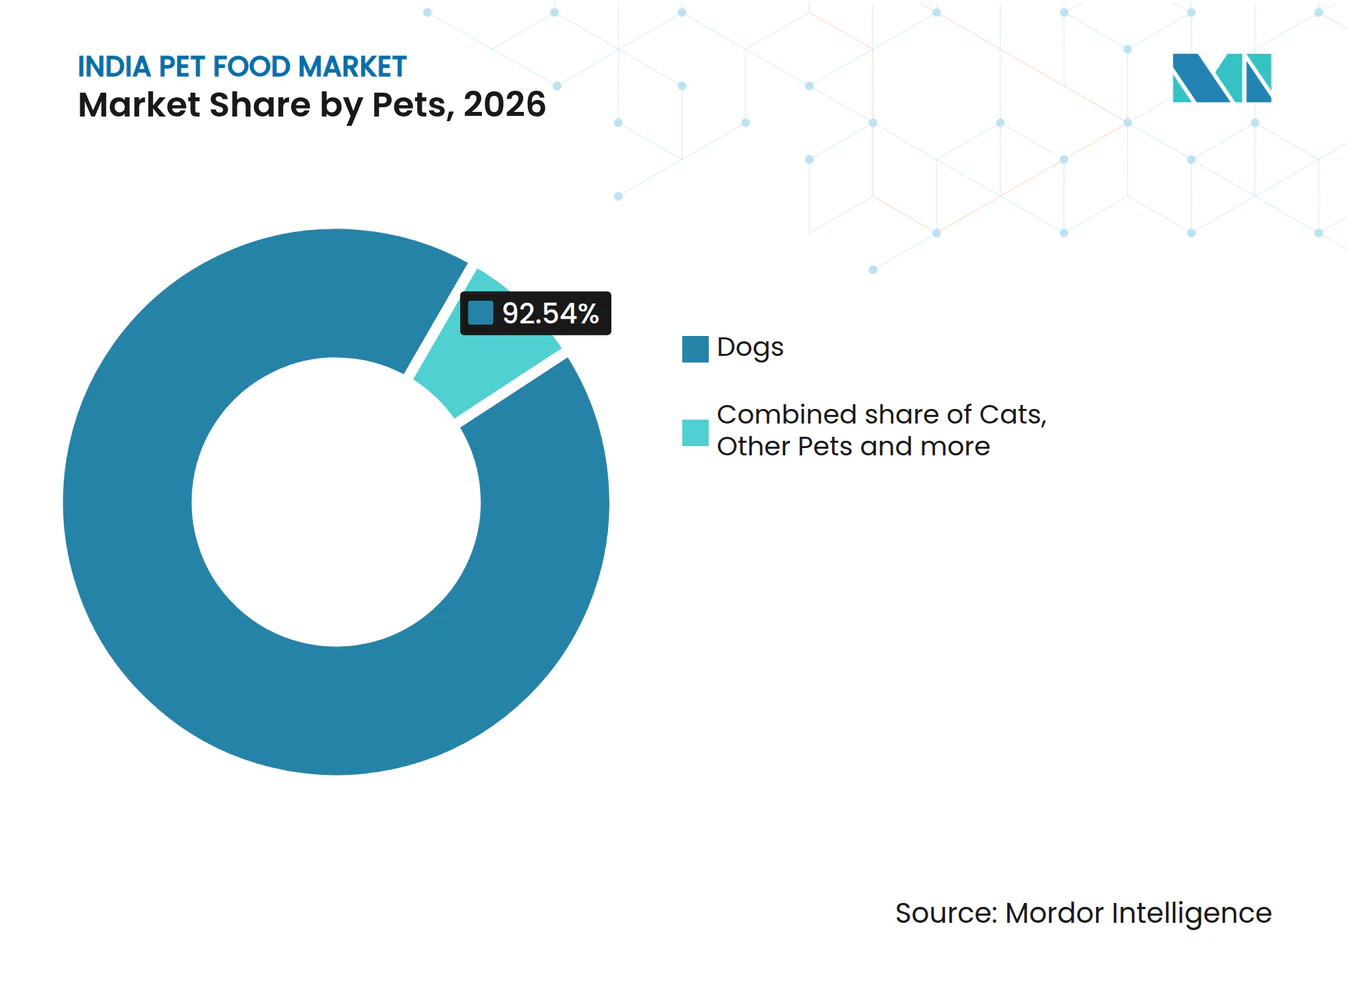
Dogs represented a 92.54% India pet food market share in 2026 and are forecast to be the fastest-growing segment, with a CAGR of 11% over 2027-2032. That share makes dog-oriented products central to the revenue exposure of a supplier seeking broad participation in the industry. Separately, India's dog-food retail sales were USD 540.1 million in 2025, up from USD 292.7 million in 2020. Expanding into another species can diversify a portfolio, but it addresses a much smaller portion of the existing commercial base than improving the main dog offering. The principal portfolio decision is therefore how to differentiate within dog nutrition, where a change in product relevance can affect a larger pool of existing spending.
For dog-food suppliers, a diet sold for renal or digestive needs creates a different commercial proposition from a treat used occasionally. India had 33.4 million dogs in 2025. For dog owners choosing a diet for a defined feeding purpose, relevance rests on that particular need, while a treat addresses an additional feeding occasion. A dog-focused portfolio can serve both decisions without treating the products as substitutes for each other. The population scale leaves room for differentiated feeding uses, so extending a range within dogs need not depend on one uniform formulation or price position.

Note: Segment shares of all individual segments available upon report purchase
By Distribution Channel: Specialty Stores Combine Physical Reach With Fulfillment
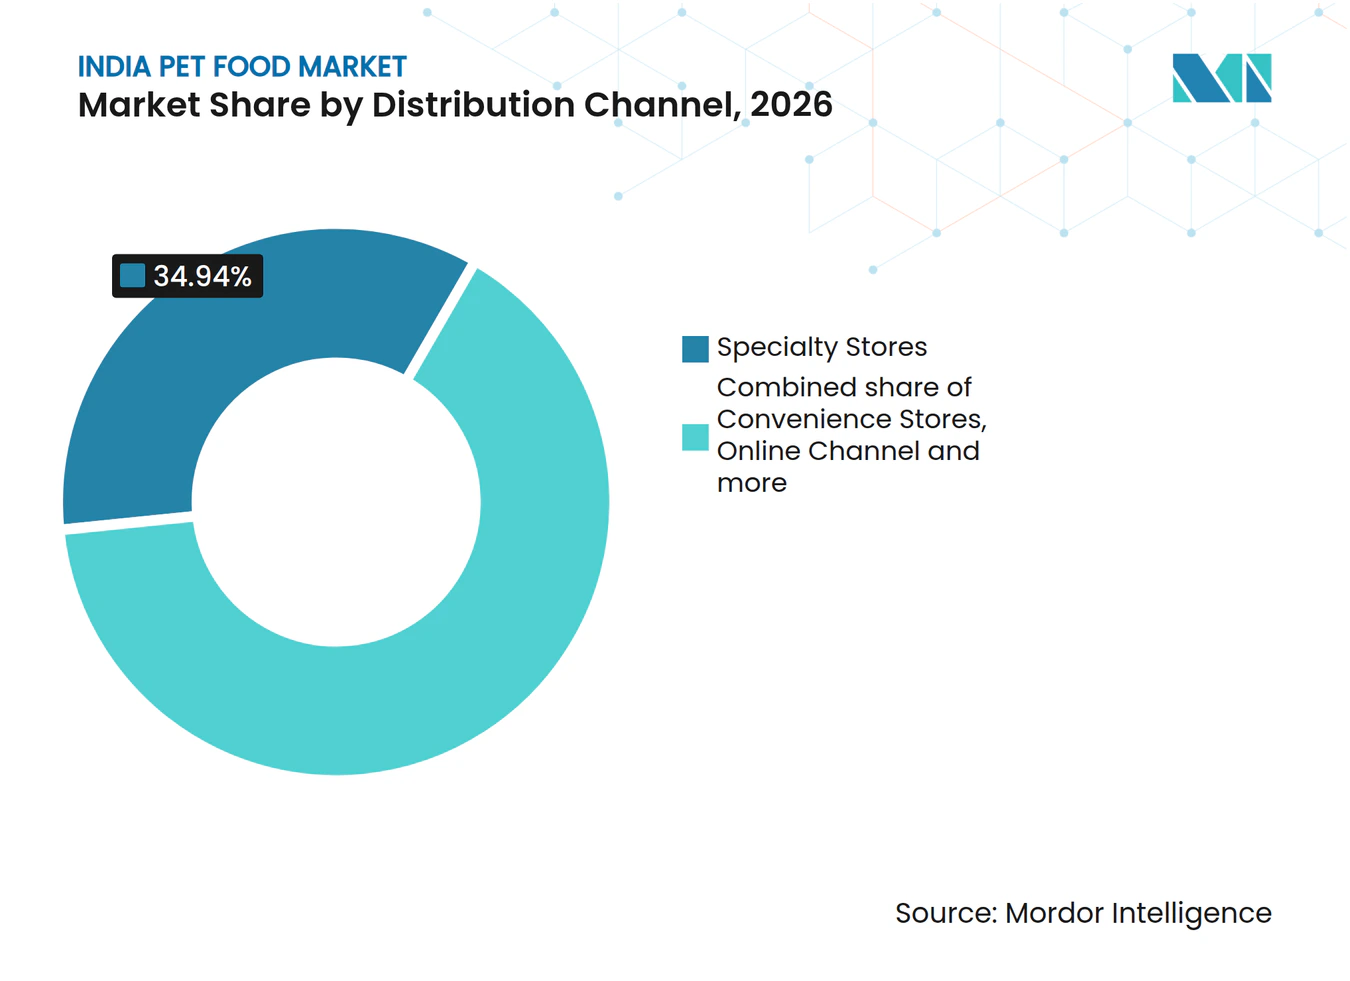
Specialty stores held the largest segment share at 34.94% in 2026 and are forecast to be the fastest-growing segment, with a CAGR of 13.5% over 2027-2032. In March 2026, Heads Up For Tails opened its 110th pet store and full-service spa in Hyderabad and reported more than 110 stores nationwide. The combined retail and service format puts food within a broader pet-care visit, creating a potential selling occasion beyond a trip dedicated solely to feeding supplies. The spa can keep an outlet relevant between food purchases, adding a service-based reason for owners to maintain contact with the retailer.
The store network can also support fulfillment for customers who order remotely, extending the use of an existing retail location. In June 2026, Heads Up For Tails reported HUFT Express live across Bengaluru, with nearby stores fulfilling same-day orders from an assortment of more than 3,000 pet-care products, including food. Food shared this delivery assortment with treats, litter and healthcare products, allowing owners to combine feeding and other care needs in one order. Because every order was filled from the nearest HUFT store, the June service's geographic reach depended on the retailer's local store footprint.
Note: Segment shares of all individual segments available upon report purchase
Geography Analysis
West India Pet Food Market
West India leads the regional market, making access to its pet-owning customers an important commercial priority for suppliers. In July 2025, Zigly, Cosmo First Limited's pet-care division, announced its acquisition of Mumbai's established Small Animal Clinic & Surgical Centre and its conversion into a Zigly pet-care center. The acquired Khar West center had an existing customer base of more than 25,000 pet parents. The converted center offered veterinary services alongside products, pharmacy and grooming, so a food brand could reach owners through a clinic visit as well as a retail trip.
Within Mumbai, the species mix of online demand can create a more specific route to market than a regional presence alone. An Instamart analysis of orders across more than 130 Indian cities from June 2025 to June 2026 ranked Mumbai first among cities for cat-food orders. For a cat-food supplier seeking that platform's buyers, the city therefore offers a specific species-and-channel combination around which to shape a local proposition. Concentrating on that combination can make the entry decision more precise, directing attention to cat-food availability through a defined delivery channel and the feeding occasions it can serve.
Lucknow illustrates a different route to market, where a mobile operation can bring a fresh-meal proposition directly to pet owners. HobbsGo launched its HobbsGo On Wheels pet-food truck in Lucknow on April 4, 2026, with fresh pet meals and real-time app tracking. The app can connect an owner to the truck's location before a fresh-meal purchase. Mobility also gives a fresh-food seller a way to test local selling locations without opening a permanent outlet in each neighborhood. Because the truck serves Lucknow communities and takes fresh-meal orders through Swiggy in selected areas, its reach follows a mobile route rather than a fixed store.
Regulatory Framework and Outlook
This comparison of selected jurisdictions considers India's published dog-and-cat food specification and Maharashtra's packaging enforcement from a domestic packaged-food manufacturer's perspective. On October 8, 2026, India's Department of Consumer Affairs directed State and Union Territory Legal Metrology officers to enforce imported pre-packaged commodity declarations before clearance for home consumption. Its amendment adopted on April 27, 2026 requires e-commerce entities offering imported products to provide a searchable and sortable country-of-origin filter from July 1, 2027. Those product and operator distinctions matter when judging the outlook for a manufacturer of domestically produced food.
Regulatory Table of India Pet Food Market
| Decision factor | India | Maharashtra |
|---|---|---|
| Primary authority | Bureau of Indian Standards | Maharashtra Legal Metrology Organization |
| Key instruments or direction | Published IS 11968:2019 specification for dog and cat food | Mandatory packaged-commodity declarations |
| Commercial effect | Technical product reference for dog and cat food | Manufacturer/packer/importer name and address, generic name, net quantity, manufacture/packing/import month and year, and tax-inclusive retail-price declarations |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | No change |
| Source: Mordor Intelligence | ||
India's Medium rating balances a defined product specification with the revision BIS listed among finalized drafts for printing. Maharashtra's Medium rating reflects mandatory package declarations and inspections of weights, measures and net contents, making compliance operationally significant for finished-food suppliers. For domestic manufacturers, No change follows from the existing product and declaration framework, while the specified new measures address import handling and import-selling platforms.
Value Chain Stages
The value chain compares how brand development, manufacturing and retail turn a formulated feeding proposition into a finished product sale. Wipro Consumer Care and Lighting launched Snuggles dry dog food in India in August 2026.[2] Allana Consumer Products Ltd. makes Bowlers pet food at its Zaheerabad plant. Wipro's launch and marketing role and Allana's owned manufacturing capacity illustrate distinct capabilities through which suppliers earn from finished-food sales.
Value Chain Analysis Table of India Pet Food Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Brand development and marketing | Pet-food brand marketers such as Wipro Consumer Care and Lighting | Branded-product sales | Translating a feeding proposition into repeatable product specifications | Define specifications and verification responsibilities before scaling |
| Finished-food manufacturing | Domestic pet-food manufacturers such as Allana Consumer Products Ltd. | Manufactured-food sales | Maintaining consistent execution across production batches | Validate batches against agreed specifications |
| Retail sale | Specialty retailers such as Heads Up For Tails and online retailers such as Supertails | Retail product sales | Matching local availability to the required product | Coordinate assortment and replenishment with suppliers |
| Source: Mordor Intelligence | ||||
Value is captured through branded-product and manufactured-food sales before retail resale brings food to owners. Heads Up For Tails sells pet food and treats through its stores across more than 20 Indian cities. Supertails sells dog and cat food, treats, supplements and prescription diets through its online store in India. For a producer with Allana's reported October 2025 dry-food and treat focus, shelf or listing access can set expansion's pace without requiring production of Supertails's supplements and prescription diets.
Competitive Landscape
Market Concentration
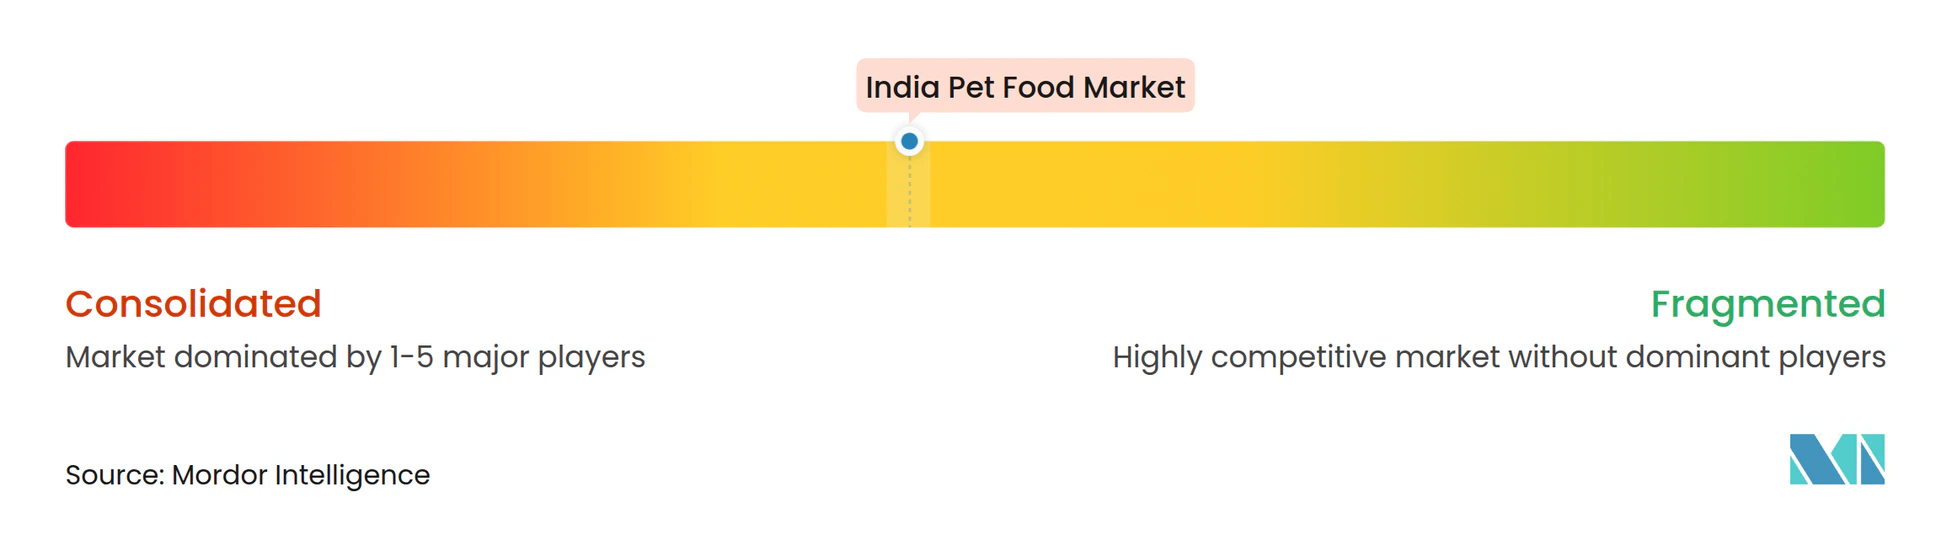
Competition is moderately concentrated around an established leadership group, with domestic investment and new formats providing additional ways to differentiate. The major players are Mars, Incorporated, Drools Pet Food Pvt. Ltd., Charoen Pokphand Group, Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.) and Nestlé (Purina). In March 2025, Mars Petcare said it had invested in expanding its Telangana factory and expected to double capacity by the end of 2025. A Mars Petcare executive tied the spending to having run out of capacity during COVID-19, which made production headroom the constraint the company chose to address.
An international supplier can participate in Indian pet nutrition through its own brand and an equity stake in a domestic producer. In May 2025, Nestlé S.A. acquired a minority stake in Drools, which continued to operate with strategic and operational independence.[3] For buyers, Purina and Drools represented separate commercial offers within the leading supplier group, making the operating business the relevant level for comparing their propositions.
Packaging-based product design provides another route to differentiation by changing how a fresh-food offer can be presented and distributed. In April 2026, Drools introduced 4 chicken-based fresh dog-food variations in Tetra Recart packaging with Tetra Pak as its packaging collaborator. GlobalPETS described this as the first introduction of fresh pet food in Tetra Recart by an Asian pet-food brand. On October 7, 2026, a Bureau of Indian Standards (BIS) deputy director said the agency had prioritized revising IS 11968:2019, the dog-and-cat food specification. Nutrition, ingredients and microbiological safety are within the developing revision's scope, making Drools's claim of 90% real meat and vegetables with no added preservatives relevant to product positioning.
India Pet Food Industry Leaders
-
Mars, Incorporated
-
Drools Pet Food Pvt. Ltd.
-
Charoen Pokphand Group
-
Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.)
-
Nestlé (Purina)
- *Disclaimer: Major Players sorted in no particular order
Recent Industry Developments
- Sep 2026: Godrej Pet Care, a subsidiary of Godrej Consumer Products Ltd., debuted Godrej Ninja cat food in Tamil Nadu, with dry and wet formats available through local pet retailers.
- Aug 2026: Wipro Consumer Care and Lighting launched Snuggles dry dog food in India, combining kibble with freeze-dried chicken chunks.
- Jun 2026: Heads Up For Tails reported HUFT Express live across Bengaluru, with nearby stores fulfilling same-day orders for more than 3,000 pet-care products, including food.
Mordor Intelligence follows a four-step methodology in all our reports.
Key Questions Answered in the Report
What is the India pet food market size and growth outlook?
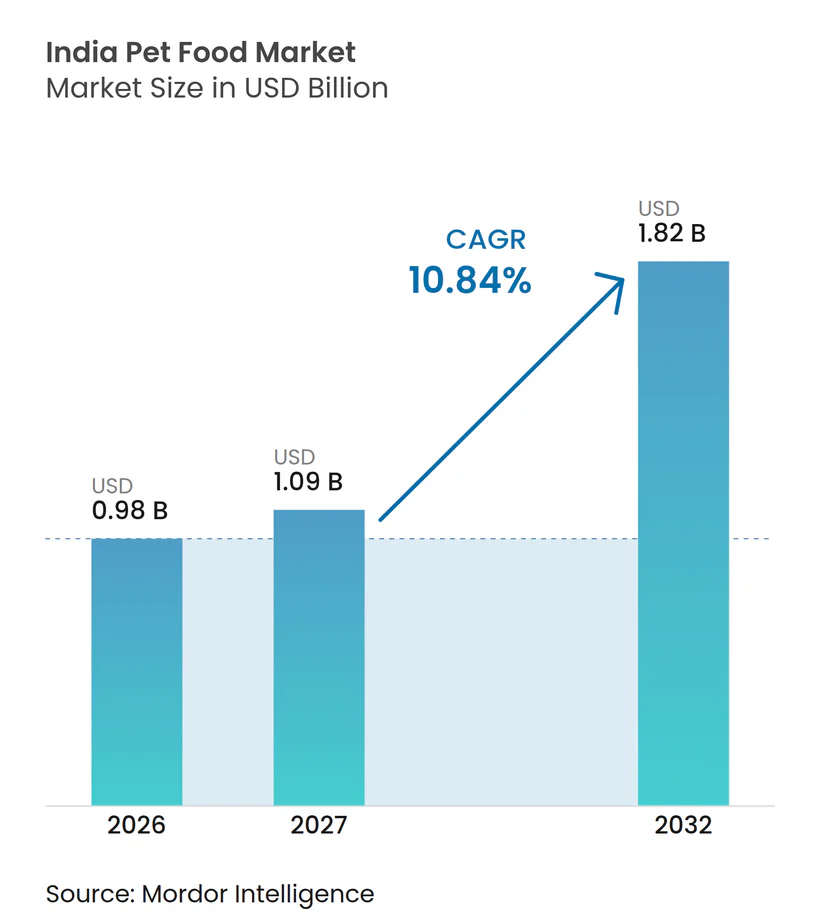
The market is projected at USD 1.09 billion in 2027 and USD 1.82 billion by 2032, with a 10.84% CAGR over 2027-2032.
What supports demand for commercial pet food?
Urban pet bases and rapid delivery support the opportunity, including access through Blinkit, Instamart and Zepto.
Which pet-food product segment leads sales?
Food led with a 77.82% share in 2026 and is forecast to grow fastest, with an 11.2% CAGR over 2027-2032.
Which companies lead the pet-food industry?
The major players are Mars, Incorporated, Drools Pet Food Pvt. Ltd., Charoen Pokphand Group, Colgate-Palmolive Company (Hill's Pet Nutrition, Inc.) and Nestlé (Purina).
What can slow the shift to packaged pet food?
Price sensitivity in Tier 2 and Tier 3 cities and homemade feeding constrain regular packaged-food use. Godrej Pet Care's Tamil Nadu pilot saw slow early adoption as owners shifted from home-cooked meals, before demand gathered momentum.
Which Indian region leads the pet-food sector?
West India leads the regional market. Mumbai ranked first for cat-food orders among more than 130 cities in Instamart's June 2025-June 2026 analysis.