
India Combine Harvester Market Analysis by Mordor Intelligence
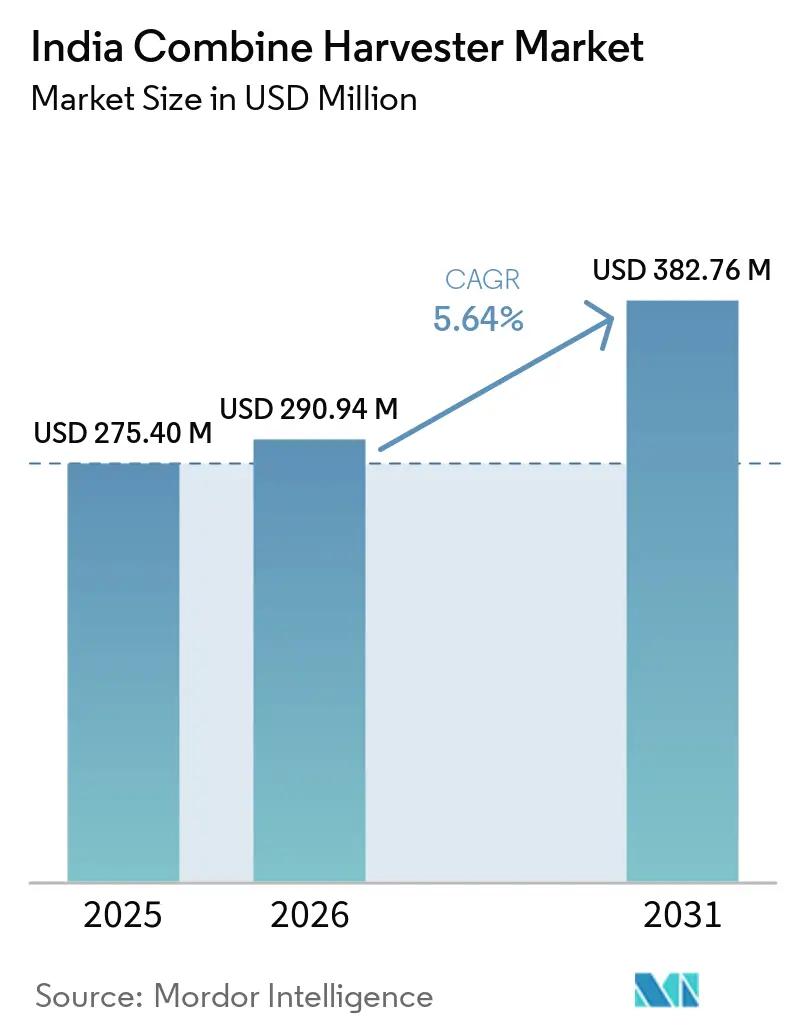
The India combine harvester market size is expected to increase from USD 290.9 million in 2026 to USD 307.4 million in 2027 and reach USD 408.8 million by 2032, growing at a CAGR of 5.87% over 2027-2032.
Expanding grain acreage and higher harvesting labor costs strengthen demand for timely machine access in India, increasing the value of completing grain harvesting on schedule. Smallholding economics favor shared fleets for complete-machine investment, while public mechanization support can reinforce this channel by directing expensive machines toward shared-use organizations. Suppliers can respond through crop-specific machines and dealer-supported delivery that connects manufacturing capacity with local rice-harvesting operators. Local service and spare-parts access can then help a hiring center keep machines working where paddy harvesting leaves a short interval before sowing. Shared-use organizations therefore offer a route to machine orders by pooling harvest work that fragmented individual holdings cannot economically support.
Key Report Takeaways
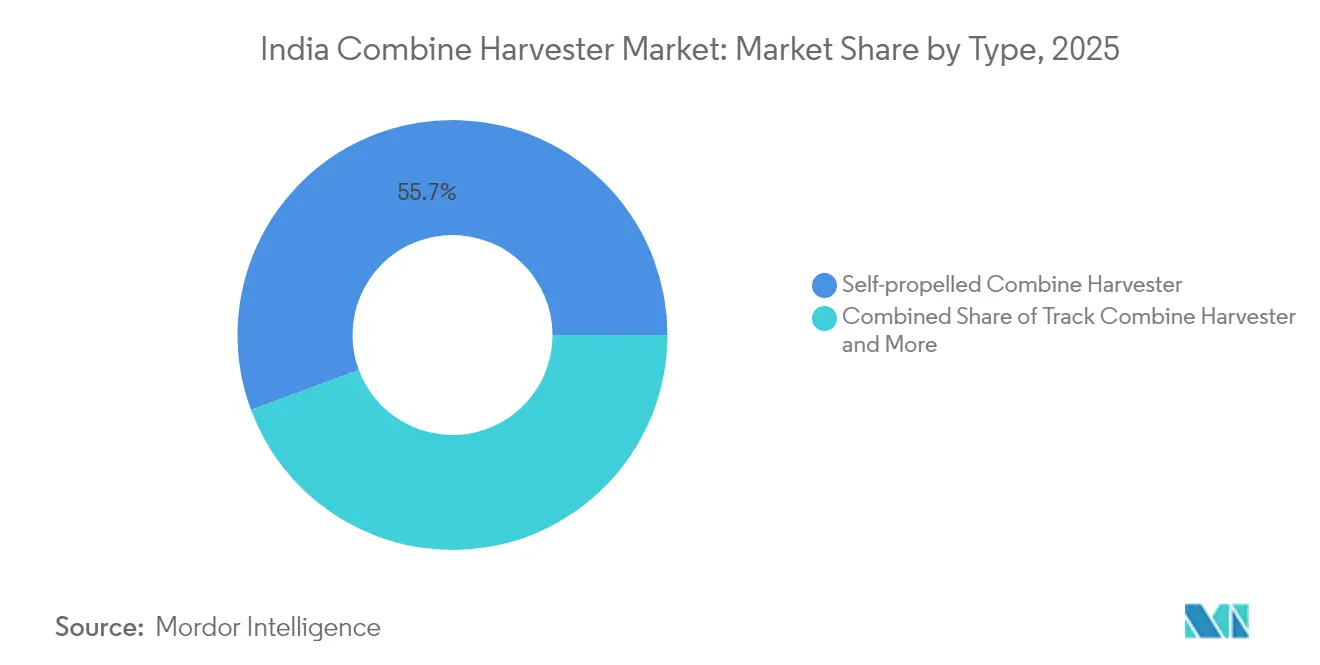
- By type, self-propelled combine harvesters held a 56.34% India combine harvester market share in 2026 and are forecast to grow fastest at a 7.12% CAGR over 2027-2032.
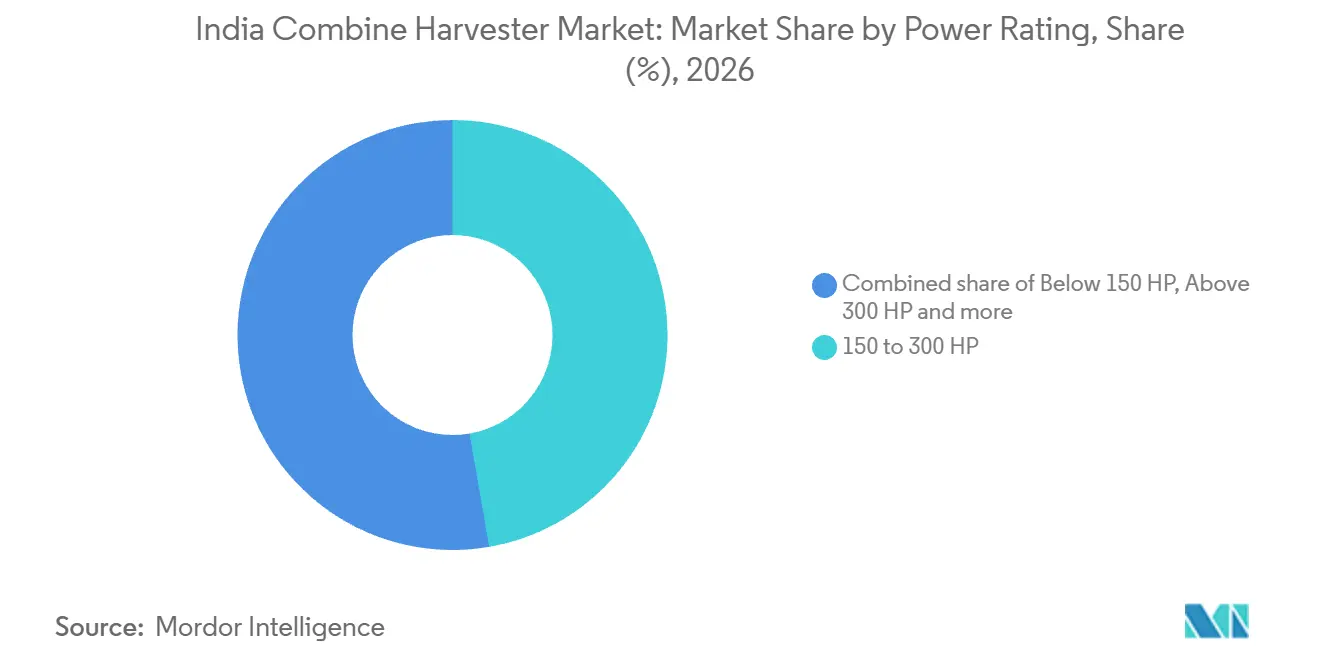
- The power-rating category was led by 150 to 300 HP machines with a 47.27% share of the India combine harvester market size in 2026, while machines above 300 HP are forecast to grow fastest at a 7.45% CAGR over 2027-2032.
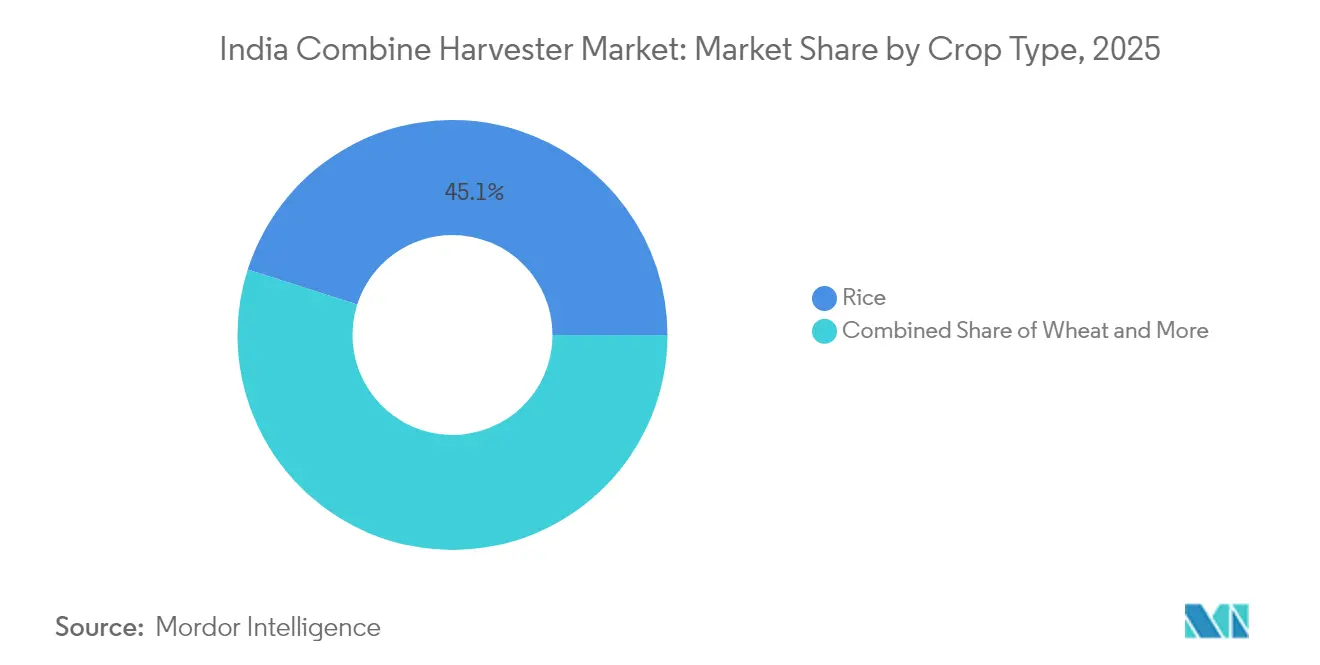
- Across crop types, rice held the largest share at 45.06% of market value in 2026, with corn forecast to grow fastest at a 6.95% CAGR over 2027-2032.
- By drive mechanism, wheel-drive combines led with 59.22% of market value in 2026, while track-drive combines are forecast to grow fastest at an 8.2% CAGR over 2027-2032.
- Geographically, Central India leads the 5-year growth outlook.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of India Combine Harvester Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising area under grain crops | +2.2% | Nationwide | Medium term (2-4 years) |
| Escalating farm labor costs | +2.3% | Nationwide | Short term (≤ 2 years) |
| Government subsidies for mechanization | +1.9% | Punjab, Haryana, Uttar Pradesh, Madhya Pradesh, Delhi | Short term (≤ 2 years) |
| Growth of custom-hiring centers | +1.6% | Nationwide | Medium term (2-4 years) |
| Precision-ag retrofit kits for aging fleets | +0.4% | Nationwide | Long term (≥ 4 years) |
| Growing availability of harvester-as-a-service models | +0.6% | Sahari, Gurdaspur district, Punjab | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising area under grain crops
India's gross foodgrain area, including cereals and pulses, rose from 132.1 million hectares in 2023-24 to a provisional 137.6 million hectares in 2024-25.[1] The increase enlarges the potential field area over which harvesting equipment can provide commercially useful work. A 2025 Rajya Sabha committee report covering the National Capital Region and adjoining areas identified a short interval between paddy harvest and the next crop's sowing, linking it to stubble burning. Where additional grain acreage meets such cropping constraints, the demand mechanism is more work that must be completed within a limited interval. For combine suppliers, the opening is harvesting capacity that can convert expanded crop coverage into timely field completion.
Escalating farm labor costs
Higher harvesting wages strengthen the economic case for replacing labor-intensive field work with mechanized capacity. All-India nominal annual average daily wages for harvesting, winnowing, and threshing workers rose for men and women between July 2023-June 2024 and July 2024-June 2025. The rates express cash-equivalent compensation, with wages paid in kind converted at local retail prices. Higher daily rates increase the expense of a given labor requirement, making the amount of work a combine can replace more consequential to its economic value. Manufacturers and harvesting operators can therefore compete on the labor displaced per completed harvest, with wage pressure strengthening the value of machine use wherever that substitution is feasible.
Government subsidies for mechanization
Public assistance can lower the cost of combine-mounted equipment, while purchase assistance under the Sub-Mission on Agricultural Mechanization (SMAM) covers part of a combine's price. A February 2026 government answer described 50% assistance for individually purchased Super Straw Management Systems (Super SMS) attached to combines in Punjab, Haryana, Uttar Pradesh, Madhya Pradesh, and Delhi. For eligible farmers, that support reduces the attachment component of a mechanized harvesting investment. Separately, central assistance under SMAM supported cumulative distribution of 2.16 million agricultural machines to individual farmers from 2014-15 through 2025-26. That cumulative total covers agricultural machinery generally, giving suppliers a broad public-program channel alongside combine-specific support. The attachment-cost advantage is therefore geographically concentrated, so eligibility depends on where the farmer invests as well as which equipment is purchased.
Growth of custom-hiring centers
Custom-hiring centers give machinery suppliers an institutional route to farmers who need equipment access through rental services. India's Sub-Mission on Agricultural Mechanization established 27,554 such centers cumulatively from 2014-15 through 2025-26, as reported on March 20, 2026. For combine manufacturers, this network creates potential buyers able to serve several farms through a single equipment investment. Its commercial value depends on centers adding harvesting capacity where aggregated service demand can sustain machine ownership, making the operator's workload more consequential than the number of individual farm customers. Additional rental activity supports new-machine demand when it triggers fleet purchases, so the growth channel runs through investment by equipment-owning centers.
Restraints Impact Analysis of India Combine Harvester Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| High upfront cost of machines | -1.5% | Nationwide | Short term (≤ 2 years) |
| Fragmented and small land holdings | -1% | Across Uttar Pradesh | Long term (≥ 4 years) |
| Expensive after-sales maintenance | -0.4% | Nationwide | Medium term (2-4 years) |
| Slow rural credit disbursement to small farmers | -0.3% | Nationwide | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
High upfront cost of machines
The purchase price can prevent a smallholder's need for harvesting from becoming a direct machine order. In its 2026 extension material, the National Institute of Agricultural Extension Management (MANAGE) described tractors or harvesters as too costly for small and marginal farmers to buy and identified combines among rental-center harvesting machines. For manufacturers, this separates demand for harvesting work from the purchasing capacity of the farm receiving that work. A complete combine must earn enough over its working life to justify the initial commitment, so smallholder access alone offers a weak basis for projecting direct ownership. Small and marginal growers can consequently remain customers for harvesting services, with the machine purchase held back by the initial capital requirement.
Fragmented and small land holdings
Fragmented holdings constrain the amount of farm work available to justify an individual equipment investment. The World Bank's December 2025 assessment identified fragmented land holdings as making individual agricultural-equipment ownership economically unviable and hindering mechanization across India.[2] For a prospective combine owner, the question is whether the work under that owner's control can support a complete machine. A lower acquisition price may ease entry, but it does not by itself enlarge the agricultural workload over which ownership costs must be recovered. This limits direct sales to small landholders whose own harvesting requirements cannot sustain the investment, leaving insufficient ownership scale as a continuing commercial constraint.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
India Combine Harvester Market Segment Analysis
By Type:
Self-Propelled Combines Link Scale With Purchase AssistanceSelf-propelled combine harvesters accounted for a 56.34% share of the India combine harvester market size in 2026, making them the largest segment and the fastest-growing segment at a forecast 7.12% CAGR over 2027-2032. The August 2026 SMAM schedule provides 50% assistance, capped at INR 960,000 [USD 10.06 thousand], for Scheduled Caste, Scheduled Tribe, small and marginal farmer, women, and northeastern-state beneficiaries. Other beneficiaries qualify for 40% assistance, capped at INR 768,000 [USD 8.05 thousand]. Assistance is the lower of the state price-discovered cost percentage or the per-machine ceiling, which includes goods and services tax. The guidelines direct promotion through Custom Hiring Centers and Farm Machinery Banks and discourage individual ownership, with expensive-machine distribution, if necessary, capped at 25% of its earmarked individual-ownership budget.
Punjab's combine industry produced around 8,000 self-propelled harvesters annually, according to a July 2025 account. A manufacturing cluster of that scale can supply harvesting territories beyond its home state. The same July account reported that 85% of harvesters built in Punjab went to other states, with 15% used locally. That distribution makes access to buyers outside Punjab consequential to the cluster's manufacturing opportunity. Interstate distribution is consequently a separate growth requirement for self-propelled suppliers expanding from this manufacturing base.



By Power Rating:
Midrange Leadership and High-Power GrowthMachines rated 150 to 300 HP held 47.27% of market value in 2026, making them the largest segment by power rating. For a custom-hiring center building a repeatable fleet, this band presents a specification decision rather than a reason to maximize horsepower. Selecting a common machine configuration within the band could simplify operator familiarization and replacement support across repeated purchases. The commercial case centers on how consistently one configuration can serve the center's crop mix, making fleet standardization a distinct reason to select midrange equipment.
Machines above 300 HP are the fastest-growing segment by power rating, with a forecast 7.45% CAGR over 2027-2032. For a contract-harvesting fleet, concentrating work in a high-power unit also concentrates exposure to that unit's downtime. The decision should therefore include whether a repair or replacement arrangement can protect the promised harvesting schedule. A supplier's service commitment can distinguish otherwise comparable high-power offers when the buyer cannot readily substitute another machine.

By Crop Type:
Rice Scale Meets Corn Fleet InvestmentRice represented a 45.06% India combine harvester market share in 2026, making it the largest segment by crop type. India's Ministry of Agriculture and Farmers Welfare estimated 2025-26 rice production at 154.024 million metric tons, against 120.657 million metric tons for wheat, in its third advance estimates. Rice's lead in machine value therefore aligns with the largest crop volume among rice, wheat, and maize in those estimates.
Corn is the fastest-growing segment by crop type, with a forecast 6.95% CAGR over 2027-2032. India's August 2026 SMAM schedule provides maximum 50% assistance for Scheduled Caste, Scheduled Tribe, small and marginal farmer, women, and northeastern-state beneficiaries, and 40% for other beneficiaries for self-propelled maize combines. State and Union Territory governments implement this national assistance schedule. The maize-combine entry is marked for promotion through Custom Hiring Centers and Farm Machinery Banks. The terms a maize-combine buyer meets therefore depend on the jurisdiction where the custom hiring center applies for support.
By Drive Mechanism:
Wheel Scale Meets Track AccessWheel-drive combines held 59.22% of market value in 2026, making them the largest segment by drive mechanism. The Indian Express reported in April 2025 that the annual Indian market for self-propelled wheel-moving combines was about 8,000 units. That recurring machine category gives suppliers a substantial commercial base for complete machines serving operators that use wheeled self-propelled equipment.
Track-drive combines are the fastest-growing segment by drive mechanism, with a forecast 8.2% CAGR over 2027-2032. In October 2026, farmers in Jalbera, Ambala district, Haryana, used hired tracked combines to harvest waterlogged paddy fields where ordinary combines could not operate. The commercial distinction was access to harvesting work under difficult field conditions, making the tracked machine a service-capacity choice in that location. For a harvesting operator, this use case can open paid work that an ordinary machine cannot perform in the affected fields. The hire arrangement makes the harvesting-service operator the customer for a supplier addressing this field-access problem.
Geography Analysis
Central India Combine Harvester Market
Central India has the highest 5-year growth in the geographic outlook, making operator preparation part of the timetable for deploying additional machines. The Madhya Pradesh government's Directorate of Agricultural Engineering offers free combine-harvester operator training lasting 390 hours, up to 60 days, at Bhopal, Jabalpur, Gwalior, and Satna centers. Free access lowers the course-fee barrier for prospective operators, while the defined training duration means preparation carries a meaningful commitment of time. For a fleet entering this part of Central India, operator preparation should precede machine commissioning so the training period fits the deployment schedule.
In Punjab, the Sahari Custom Hiring Centre in Gurdaspur delivers residue management through a farmer producer organization's machinery service. The center expanded its residue-management coverage from 500 acres in 2019 to 1,500 acres in 2025. The group built a mixed fleet of more than 50 implements, including Super SMS units for combines, with an 80% government Crop Residue Management Scheme machinery subsidy. This combination connects combine equipment with a broader residue-management service, making the investment decision larger than an isolated harvesting-machine purchase. At Sahari, the Super SMS units connect combines to the center's residue-management workload.
Uttar Pradesh illustrates a distribution route centered on farmer recipients across a wide district footprint. In June 2025, the state government said it had facilitated distribution of 450 combine harvesters to farmers across 62 districts. That geographic spread makes access across the served districts part of the distribution channel's task. For potential suppliers, serving a dispersed group of farmer recipients calls for district-level access rather than relying solely on a single large fleet customer. The state's distinctive commercial signal is the breadth of publicly facilitated farmer access, which can widen the set of locations where a supplier needs a practical route to end users.
Regulatory Framework and Outlook
This comparison covers selected jurisdictions, pairing India's national scheme with conditions in Punjab that apply only within Rupnagar district. Ratings assess policy attractiveness for combine suppliers serving fleet operators. India's August 2026 SMAM guidelines require combine-harvester manufacturers and suppliers to have their machines tested through specified institutions for supply under the scheme.[3]
Regulatory Table of India Combine Harvester Market
| Decision factor | India | Punjab |
|---|---|---|
| Primary authority | Department of Agriculture and Farmers Welfare | Rupnagar District Magistrate, for the district order |
| Key instruments or direction | August 2026 SMAM supplier-testing conditions | Rupnagar paddy order, September 18-November 17, 2026; 10:00 a.m. to 6:00 p.m. harvesting; Bureau of Indian Standards conformity and Super SMS equipment |
| Commercial effect | Combine supply under the scheme requires qualifying machine testing | District operators must match equipment and work schedules to seasonal duties |
| Current policy attractiveness | Medium | Medium |
| Future direction of policy attractiveness | No change | Easing |
| Source: Mordor Intelligence | ||
National attractiveness balances access to scheme demand against product qualification, with continuity favored by the operative August 2026 testing framework. Suppliers pursuing that channel need to incorporate qualifying testing into their route to supported equipment sales. The Punjab column's Medium assessment is confined to Rupnagar district, where harvesting outside permitted hours carries 7-day impoundment during the order period. The No change judgment reflects recurring 10:00 a.m. to 6:00 p.m. paddy-combine hours for September 13-November 14, 2025, and September 18-November 17, 2026, making seasonal compliance a recurring fleet requirement.
Value Chain Stages
The value chain comparison follows complete-machine manufacturing, distribution, and support, where different capabilities generate supplier earnings. Kartar Agro Industries Private Limited manufactures combines in Punjab and supports dealer sales, service, and spare-parts access, while Erisha Agritech manufactures, sells, and services combines through Indian distribution channels. These linked roles make coordination between machine configuration and local support a source of commercial value beyond assembly alone.
Value Chain Analysis Table of India Combine Harvester Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Machine manufacturing | Combine manufacturers such as Kartar Agro Industries Private Limited and Erisha Agritech | Complete-machine sales | Coordinating production across combine configurations | Sequence assembly around configuration-specific demand |
| Dealer distribution | Dealer-network operators such as Preet Agro Industries (P) Limited and Erisha Agritech | Equipment distribution and resale earnings | Matching the supplied machine to the buyer's crop and operating requirements | Carry configuration information through the dealer handoff |
| After-sales support | Manufacturers supporting service networks such as Kartar Agro Industries Private Limited and Erisha Agritech | Spare-parts sales and service fees | Aligning replacement support with the machines placed in service | Link parts stocking and service preparation to installed configurations |
| Source: Mordor Intelligence | ||||
Preet Agro Industries (P) Limited combines manufacturing with a dealer-finding channel, illustrating the connection between production and customer access. As suppliers serve different configurations, the commercial task is to carry machine-specific knowledge through distribution into replacement support. Dealer and service feedback can help wheel- and track-combine manufacturers choose a production mix that their channels can support through replacement parts and field service.
Competitive Landscape
Market Concentration
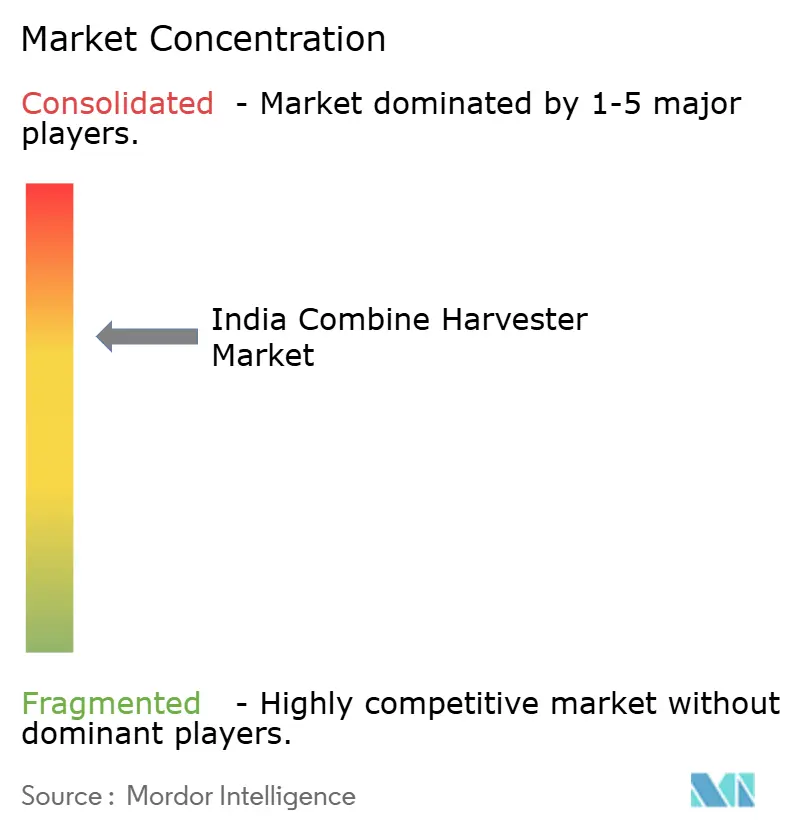
The fragmented supplier base includes Punjab-based combine makers such as Kartar and Preet alongside diversified agricultural-machinery groups. Major competitors include Kartar Agro Industries Private Limited, Preet Agro Industries (P) Limited, Mahindra & Mahindra Ltd., Deere & Company, and Escorts Kubota Limited. The Preet Group, comprising Preet Tractors Private Limited and Preet Agro Industries (P) Limited, sold 1,826 harvesters in FY2025, up from 751 in FY2024. Preet Group deliveries more than doubled in a single year, showing that competitive position in this fragmented field can shift quickly with delivered volume.
In FY26, Mahindra & Mahindra Ltd.'s Farm Machinery business reported its highest-ever volumes for wheeled and crawler harvesters and upgraded the Swaraj 8200 Wheel Harvester. Kartar's combine portfolio spans wheeled and tracked machines as well as multicrop and maize models, while Preet manufactures combine harvesters alongside agricultural tractors and farm implements. These portfolios can address operators with different crop and machine-configuration requirements, so each supplier's growth opportunity depends on the harvesting work its machines can serve. Tracked combines consequently form a point of competitive overlap for Mahindra, Kartar, and Escorts Kubota, despite the differences in their wider portfolios.
Competition also turns on how combines handle wet fields and recover straw for further use. Escorts Kubota Limited introduced the PRO588i-G in Punjab and Haryana on September 17, 2025. The machine weighs 2,700 kilograms versus conventional models at around 9,000 kilograms and uses crawler tracks for wet fields. It cuts stalks near ground level, allowing full-length straw collection for cattle feed or biomass plants. That links the harvester choice to the intended outlet for straw, giving feed and biomass requirements a role in machine selection.
India Combine Harvester Industry Leaders
-
Kartar Agro Industries Private Limited
-
Preet Agro Industries (P) Limited
-
Mahindra & Mahindra Ltd.
-
Deere & Company
-
Escorts Kubota Limited
- *Disclaimer: Major Players sorted in no particular order
India Combine Harvester Market Companies Covered in this Report
- Mahindra & Mahindra Ltd.
- Deere & Company
- Preet Agro Industries (P) Limited
- Tractors and Farm Equipment Limited
- Kartar Agro Industries Private Limited
- Dasmesh Mechanical Works Pvt. Ltd.
- International Tractors Limited (Sonalika)
- Indo Farm Equipment Limited
- Yanmar Agricultural Machinery India Private Limited
- CNH Industrial N.V.
- Escorts Kubota Limited
- Tirth Agro Technology Private Limited
- KS Agrotech PVT. LTD.
Key Opportunities for Market Participants
These opportunities compare shared-fleet expansion with crop-specific complete-machine investment under India's mechanization support framework. The August 2026 SMAM assistance schedule includes self-propelled maize combines and tractor-operated combines for potato, groundnut, and other tuber crops. Bihar's agriculture portal opened general SMAM individual-farmer, Custom Hiring Center, and Farm Machinery Bank applications for October 1-31, 2026. Commercial execution requires matching the machine and buyer with the applicable state funding and application conditions.
Market Opportunities Table of India Combine Harvester Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Additional shared-fleet combine capacity | Shared-use promotion in the August 2026 framework | Eligible custom-hiring centers and farm machinery banks | Build complete-machine offers around aggregated harvesting work | Sustaining enough paid machine time | Shared-fleet operators and combine suppliers |
| Specialized maize-harvesting fleets | Maize-combine category in the national assistance schedule | Maize-focused shared-equipment operators | Concentrate new-machine capacity around a defined maize service territory | Concentration of crop-specific harvesting work | Maize-harvesting operators and specialized machinery suppliers |
| Crop-specific tractor-operated combines | Named potato, groundnut, and tuber-crop equipment category | Shared-equipment organizations serving the specified crops | Develop complete-machine proposals for distinct crop-service workloads | Balancing specialized equipment with sufficient annual service work | Crop-service operators and crop-specific combine suppliers |
| Source: Mordor Intelligence | |||||
Crop-focused shared fleets are the central opening because the program's access channels and machinery categories can be addressed together. A maize combine and a tractor-operated tuber-crop combine require distinct service propositions even when their buyers use the same shared-equipment channel. State application windows determine when these crop-specific investments can enter the support process, making local program timing a constraint on turning fleet needs into orders.
Recent Industry Developments in India Combine Harvester Market
- Sep 2026: Rupnagar's District Magistrate set paddy-combine harvesting hours at 10:00 a.m. to 6:00 p.m. for September 18-November 17, 2026, with 7-day impoundment for violations, and required Bureau of Indian Standards conformity and Super SMS equipment within the district.
- Aug 2026: India's Department of Agriculture and Farmers Welfare issued revised SMAM guidelines requiring qualifying machine testing for scheme suppliers and directing combine-harvester promotion through Custom Hiring Centers and Farm Machinery Banks.
India Combine Harvester Market Report Scope and Research Methodology
Market Definition and Coverage
The India combine harvester market covers the annual value of new combine harvester sales to end users in India for harvesting crops. It measures end-user spending on complete machines, including units imported and sold in India.
Scope exclusions: Used-machine resales between farmers, standalone headers, spare parts, and routine service revenue are excluded.
Segments Covered in This Report
- By Type
- Self-propelled Combine Harvester
- Track Combine Harvester
- Tractor-powered Combine Harvester
- By Power Rating
- Below 150 HP
- 150 to 300 HP
- Above 300 HP
- By Crop Type
- Wheat
- Rice
- Corn
- Other Crops
- By Drive Mechanism
- Wheel Drive
- Track Drive
Data Sources, Market Sizing, and Validation
Desk Research
Public sources such as the Economic Survey 2025-26, the Ministry of Agriculture and Farmers Welfare's crop estimates, and the Press Information Bureau's farm-mechanization release and SMAM program note frame crop production, fragmented holdings, mechanization conditions, scheme-supported machine access, custom-hiring centers, equipment distribution, and public testing requirements that shape machine demand in India.
Company filings, annual reports, investor materials, and reputable Indian press coverage can supplement public sector evidence on manufacturer sales, product portfolios, dealer reach, prices, and registration trends, with conflicting definitions reconciled against the complete-machine end-user boundary. These sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Structured interviews and a focused survey would cover India-based combine manufacturers and importers, agricultural machinery dealers, custom-hiring center operators, harvesting contractors, and farm machinery specialists. Responses would check machine price and configuration assumptions, channel movement, and use by crop and power class against desk evidence, with gaps followed up through targeted re-contact and reconciled across respondent roles and independent records.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 18% | |
| Mid tier: 42% | Functional/Unit leaders: 36% | |
| Smaller Players: 24% | Managers: 46% |
Market-Sizing & Forecasting
The model starts with the annual India market value of new complete combines sold to agricultural end users, using a top-down estimate of machine demand and realized transaction prices, then checking selected totals through supplier or dealer roll-ups and sampled average selling price multiplied by unit volume. Crop production and harvested area indicate workload by wheat, rice, corn, and other crops. SMAM support and custom-hiring center growth indicate access to shared machines. Registrations, supplier deliveries, and import flows inform unit demand, while prices by power rating, type, and drive configuration inform value and mix. Scenario analysis carries these indicators through 2032, with replacement demand, labor availability, financing conditions, and crop-specific machine use shaping alternative paths. Segment shares follow the available product mix, registrations, operator use, and channel evidence across machine type, power, crop, and drive. Primary respondents would test the direction and plausibility of each variable forecast, while gaps in selective volume or price checks would be filled with comparable Indian channel observations and reconciled to the national total before use.
Data Validation & Update Cycle
Analysts triangulate machine registrations, supplier and dealer signals, public scheme data, crop conditions, and respondent evidence, then check totals and segment shares for unexplained changes or inconsistencies. A second review traces material variances to source definition, timing, price mix, or coverage, resolves anomalies before sign-off, and triggers re-contact when a key input conflicts across sources or a material channel change is unclear. The dataset is refreshed annually, reviewed between cycles when a material policy, supply, or crop event changes the outlook, and given a fresh source and calculation pass before delivery.
Mordor Intelligence's India Combine Harvester Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The India combine harvester market covers the annual value of new combine harvester sales to end users in India for harvesting crops.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Primary respondents would test the direction and plausibility of each variable forecast, while gaps in selective volume or price checks would be filled with comparable Indian channel observations and reconciled to the national total before use.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 307.4 M (2027) | |
| Commercial Research Publisher A | USD 246.4 M (2024) | At its 2024 base, this estimate is 19.8% below this report's 2027 value of USD 307.4 M, 3 years later. Its page uses a 2024 measurement year and forecasts positive market growth through 2034, placing the published value before the current-year comparison. |
| Commercial Research Publisher B | USD 238.8 M (2024) | At its 2024 base, this estimate is 22.3% below this report's 2027 value of USD 307.4 M, 3 years later. Its page uses a 2024 base and forecasts positive market growth through 2031, so the estimate precedes the current-year comparison. |
Mordor Intelligence's analysts triangulate machine registrations, supplier and dealer signals, public scheme data, crop conditions, and respondent evidence, then check totals and segment shares for unexplained changes or inconsistencies.
Key Questions Answered in the Report
What is the India combine harvester market size and growth outlook?
The size is projected at USD 307.4 million in 2027 and USD 408.8 million by 2032, with a 5.87% CAGR over 2027-2032.
What drives demand for combine harvesters in India?
Grain acreage expansion, higher harvesting wages, and shared-machine access support demand. SMAM established 27,554 custom-hiring centers cumulatively from 2014-15 through 2025-26, as reported on March 20, 2026.
Which combine type leads sales value in India?
Self-propelled combines held 56.34% of market value in 2026 and are forecast to grow fastest at a 7.12% CAGR over 2027-2032.
Which companies compete in India's combine-harvester industry?
Major competitors include Kartar Agro Industries Private Limited, Preet Agro Industries (P) Limited, Mahindra & Mahindra Ltd., Deere & Company, and Escorts Kubota Limited.
What limits wider combine ownership among Indian farmers?
High purchase costs and fragmented holdings constrain individual equipment ownership. MANAGE's 2026 extension material identified machinery cost as a barrier for small and marginal farmers.
Which Indian region has the strongest combine growth outlook?
Central India has the highest 5-year growth outlook. Madhya Pradesh offers free 390-hour combine-operator training, lasting up to 60 days, at Bhopal, Jabalpur, Gwalior, and Satna.