
Germany Data Center Rack Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Forecast Data Period | 2026 - 2031 |
| Base Year Market Size (2025) | USD 115.6 Million |
| Market Size (2026) | USD 131.62 Million |
| Market Size (2031) | USD 251.75 Million |
| Growth Rate (2026 - 2031) | 13.86 % |
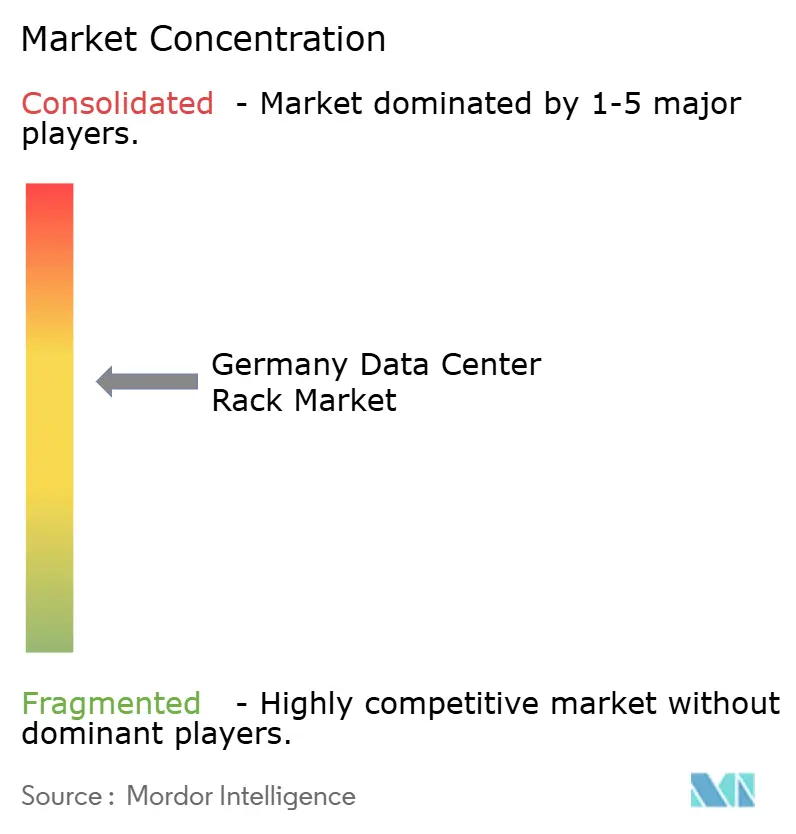
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Germany Data Center Rack Market Analysis by Mordor Intelligence
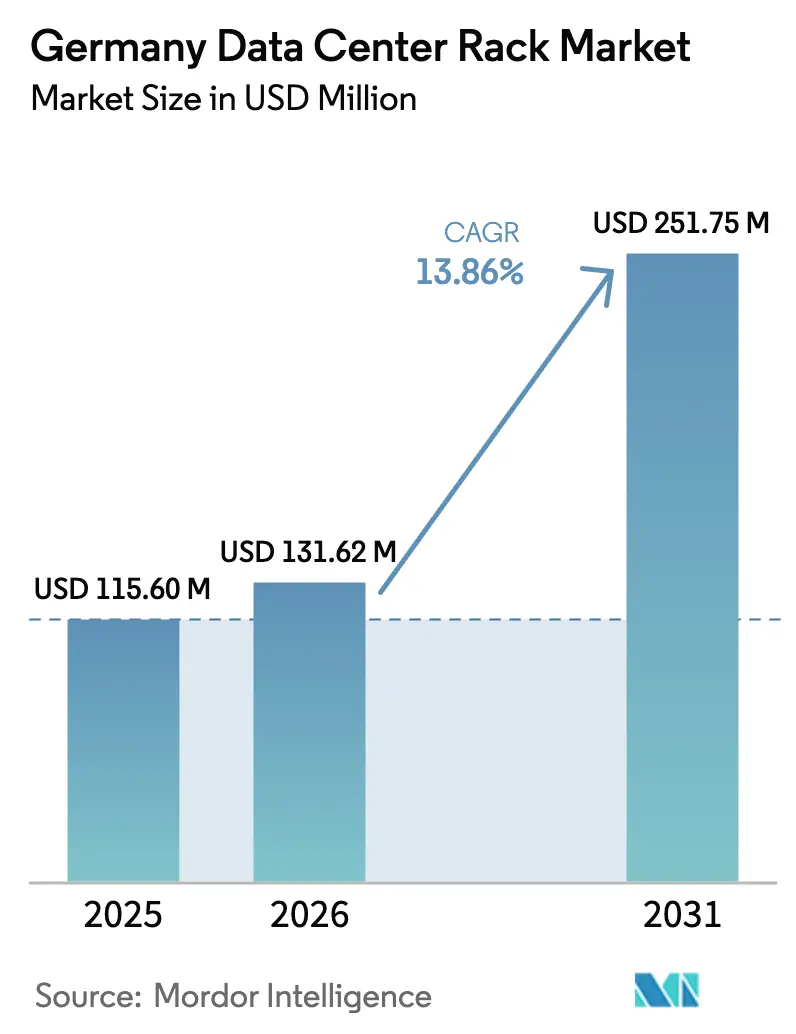
Germany data center rack market size in 2026 is estimated at USD 131.62 million, growing from 2025 value of USD 115.6 million with 2031 projections showing USD 251.75 million, growing at 13.86% CAGR over 2026-2031. Sustained capital expenditure by hyperscale cloud operators in Frankfurt, the national roll-out of 5G edge nodes by telecom firms, and the federal GAIA-X data-sovereignty agenda underpin this vigorous trajectory. Liquid-cooling-ready cabinets are moving from proof of concept to mainstream as artificial intelligence (AI) servers double average rack power densities, while the Energy Efficiency Act (EnEfG) steers buyers toward integrated cooling and monitoring solutions that can help future sites reach a 1.2 PUE target. Cabinet-type enclosures hold a structural advantage because German insurers, financial regulators, and GDPR auditors all demand high levels of physical security, driving continuous refresh cycles. Finally, brownfield conversions of idle industrial buildings into micro facilities are spreading demand toward secondary locations and opening fresh revenue streams for German rack suppliers that can offer modular, pre-certified solutions.
Key Report Takeaways
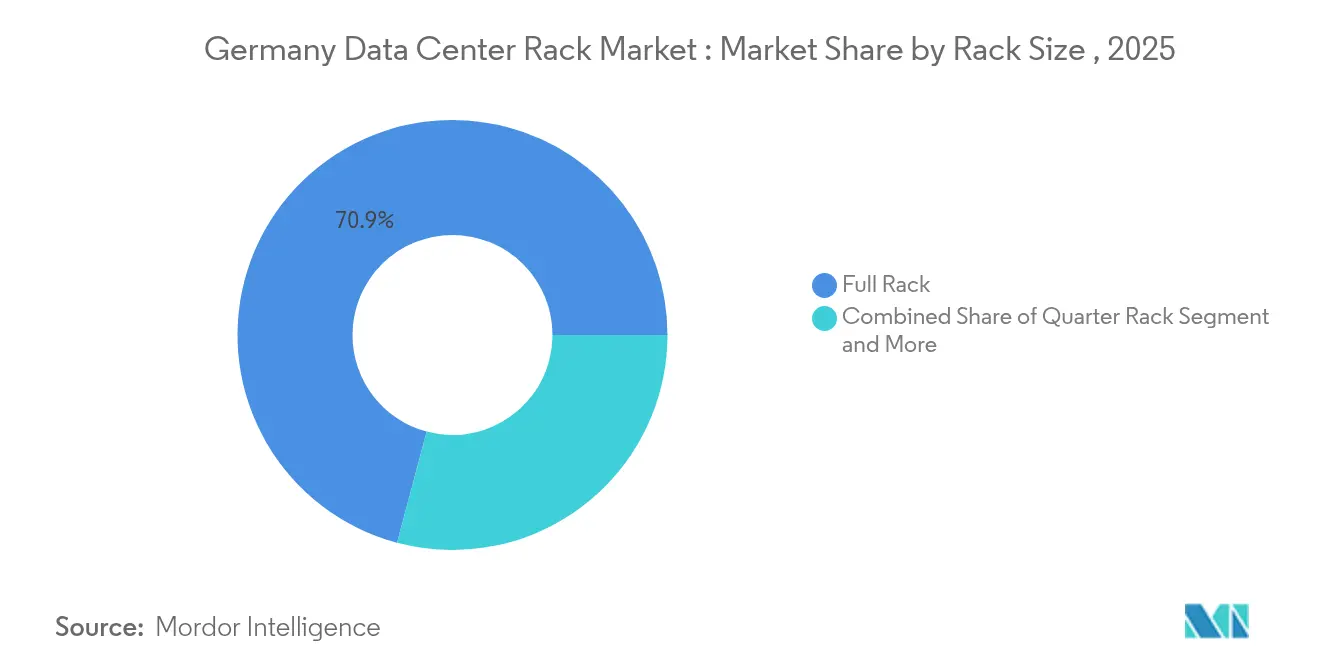
- By rack size: Full racks led with 70.85% of Germany data center rack market share in 2025, while the same category expands at 15.91% CAGR through 2031.
- By rack height: 42U racks held 55.12% share of the Germany data center rack market size in 2025; 48U racks post the fastest 17.08% CAGR to 2031.
- By rack type: Cabinet (closed) solutions captured 74.68% revenue share in 2025 and progress at 15.64% CAGR through 2031.
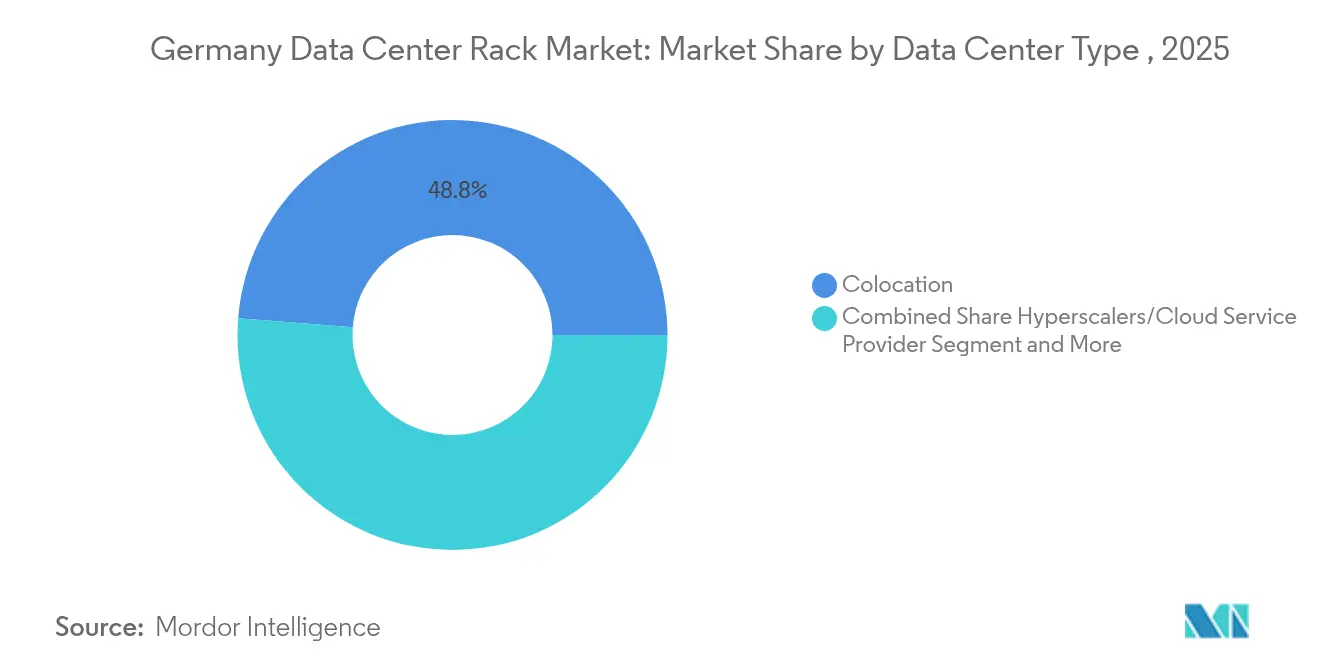
- By data center type: Colocation facilities represented 48.75% of the Germany data center rack market size in 2025, whereas hyperscale and cloud sites record the highest 18.12% CAGR to 2031.
- By material: Steel frames retained 81.47% share in 2025; aluminum racks advance at 16.98% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Germany Data Center Rack Market Trends and Insights
Drivers Impact Analysis*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Surging hyperscale cloud investments in Frankfurt region | +3.2% | Frankfurt metropolitan area, spillover to Rhine-Main | Medium term (2-4 years) |
| Rapid growth in edge computing deployments by telecom operators | +2.8% | National, early gains in Berlin, Munich, Hamburg | Short term (≤2 years) |
| Government support for digitalization (GAIA-X initiative) | +2.1% | National, concentrated in major urban centers | Long term (≥4 years) |
| Adoption of high-density servers and liquid cooling drives rack refresh cycles | +3.5% | Frankfurt, Berlin, secondary markets | Medium term (2-4 years) |
| Demand for seismic-rated racks to meet German insurance standards | +1.2% | National, industrial zones | Long term (≥4 years) |
| Retrofit of brownfield industrial sites into micro data centers | +1.0% | Regional, former industrial areas | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Surging Hyperscale Cloud Investments in Frankfurt Region
Frankfurt’s role as Europe’s main interconnection hub fuels an aggressive build-out that commits more than EUR24 billion in capacity between 2024 and 2029. [1]German Datacenter Association, “Market Study 2024,” germandatacenterassociation.orgMicrosoft has pledged EUR3.2 billion and Amazon Web Services EUR16.6 billion to enlarge regional footprints, pulling the Germany data center rack market toward taller 48U cabinets that can host AI GPU sleds. Digital Realty’s FRA18 site, installed inside a listed building, shows how land scarcity pushes innovative layouts that still require full-depth, liquid-ready racks datacenterknowledge.com. Seismic-rated frames also see greater adoption because German insurers link lower premiums to robust cabinet construction. Overall, hyperscale capex concentrates demand, shortens replacement cycles, and locks in volume contracts that favor suppliers with local assembly plants and fast lead times.
Rapid Growth in Edge Computing Deployments by Telecom Operators
Telecom carriers introduce distributed mini-hubs to support 5G network slicing and low-latency industrial IoT, which broadens the geographic spread of the Germany data center rack market. Deutsche Telekom’s involvement in the EU-funded AI Gigafactory positions dozens of micro installations across manufacturing corridors, creating steady orders for quarter- and half-racks that can be installed by a two-person crew. Cisco’s reference design for telco edge nodes calls for unified, remotely managed, standards-based cabinets that simplify unmanned site operations. Edge nodes stimulate incremental demand because every 5G region needs its own micro-facility, yet operators insist on TÜV-certified frames that meet German safety codes, allowing local vendors such as Rittal to capitalize on proximity and fast service response.
Government Support for Digitalization (GAIA-X Initiative)
GAIA-X strengthens the national requirement for sovereign data processing and accelerates workload migration from non-European clouds to domestic infrastructure. More than 300 stakeholder firms, among them Deutsche Telekom, shape a reference architecture that standardizes compliance, security, and interoperability. Because GAIA-X prescribes where data can reside, customers prefer in-country, colocation suites and request racks with built-in access logs and environmental sensors that satisfy GDPR audits. The policy outlook ensures consistent demand for compliant cabinets and gives German manufacturers an edge over offshore rivals that lack local certification credentials.
Adoption of High-Density Servers and Liquid Cooling Drives Rack Refresh Cycles
AI training clusters now exceed 30 kW per rack in Frankfurt’s latest halls, double the 2017 average, forcing a transition toward rear-door heat exchangers, direct-to-chip cold plates, and immersion options. Rittal’s 400 kW prototype, unveiled at the 2024 OCP Global Summit, demonstrates how the supply chain redesigns frameworks to host manifolds, pumps, and quick-disconnect fittings. Liquid-ready products command premium prices yet also shorten deployment because the cooling lines arrive pre-integrated. Operators appreciate the operational resilience and the ability to comply with the EnEfG 1.2 PUE mandate from July 2026, thereby ensuring a sustained refresh opportunity for the Germany data center rack market.
Restraints Impact Analysis*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating land and power costs in major colo clusters | -2.8% | Frankfurt, Berlin | Short term (≤2 years) |
| Data security breaches and compliance cost escalation | -1.5% | National, financial hubs | Medium term (2-4 years) |
| Lengthy permitting under Federal Immission Control Act | -2.1% | National, urban areas | Medium term (2-4 years) |
| Shortage of TÜV-certified installers for advanced containment | -1.3% | National, secondary markets | Short term (≤2 years) |
| Source: Mordor Intelligence | |||
Lengthy Permitting Under Federal Immission Control Act
Projects that install more than 2 MW of diesel backup must obtain a Federal Immission Control Act license, lengthening timelines by 12-18 months because of public consultations and environmental reviews. Each new requirement—waste-heat capture plans, energy-management audits, biodiversity reports—adds engineering scope, which then delays the rack procurement stage. International entrants without established local partners struggle to navigate separate city and state approval layers, occasionally abandoning purchase intentions or shifting capacity to the Netherlands. For the Germany data center rack market, the biggest impact is a stop-start order pattern that complicates factory planning and inventory management for domestic suppliers.
Escalating Land and Power Costs in Major Colo Clusters
Construction prices averaged USD9.1 million per megawatt in Frankfurt during 2024, up 6.5% year-on-year, eroding headroom for equipment budgets and slowing purchase orders for new cabinets.
[2]Savills, “Frankfurt Data Center Construction Cost Tracker 2024,” savills.de Grid bottlenecks mean certain projects wait up to two years for transformer slots, pushing operators to enter capacity-swap deals and secondary locations. Rising electricity tariffs, along with the 100% renewable energy requirement by 2027, oblige operators to co-invest in solar and battery assets, leaving fewer funds for discretionary rack upgrades. Smaller colocation firms that compete on price have postponed non-critical refresh programs, translating into a near-term drag on Germany data center rack market expansion.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Segment Analysis
By Rack Size: Full Racks Dominate Enterprise Deployments
Full racks held 70.85% of Germany data center rack market share in 2025, progressing at a 15.91% CAGR through 2031 as hyperscale halls standardize on 42U and taller footprints for GPU clusters. This dominance reflects economies of scale, uniform cable management layouts, and easier hot-aisle containment integration. Quarter racks and half racks serve niche edge locations or retrofitted office basements where depth or ceiling limits prevail, but their combined revenue remains below one-third of the Germany data center rack market size. The preference for full racks also aligns with the EnEfG waste-heat clause, because contiguous rows improve airflow modeling and enable rear-door exchanger retrofits that capture thermal output for district heating loops. As more AI inference nodes migrate to factories and logistics warehouses, compact variants will grow, yet standardized full racks should retain the top position given hyperscalers’ sizeable forward purchase contracts.
German engineering groups have responded by developing prefabricated modules where full racks leave the factory pre-wired, reducing site work from weeks to days. Siemens and Cadolto promote an ISO-container design that includes twelve 42U enclosures, in-line cooling, and a dedicated battery pod, lowering total installed cost for multiregional edge fleets. Local fabricators also secure a logistics edge; proximity to Frankfurt permits next-day delivery of spare parts, which remains a critical factor for colocation tenants bound by stringent service-level agreements. As Germany data center rack market demand broadens to secondary cities, flexible service coverage and rapid replacement options will strengthen full-rack adoption further.


By Rack Height: 48U Configurations Lead Innovation
42U frameworks, the global benchmark, retained 55.12% share of the Germany data center rack market size in 2025. Operators nonetheless upgrade to taller 48U units to squeeze additional servers into unchanged footprints, achieving up to 14% space savings on a per-rack basis. This trend produces the segment’s highest 17.08% CAGR through 2031. Taller layouts offer the headroom to mount liquid distribution manifolds above the server area, which keeps servicing clear of live power rails. They also allow operators to install two cable trays—one for fiber, one for power—improving fault isolation.
A smaller yet visible share of buyers select 45U or 52U custom heights for research labs and automotive test cells that host experimental compute clusters. Rittal’s 400 kW specimen, effectively a custom 52U chassis with reinforced uprights, demonstrates how design boundaries are being pushed to accommodate AI accelerators that draw more than 130 kW per cabinet. Ceiling clearance in urban Frankfurt remains the practical governor; most new builds retain a 3.6 m raised-floor height, which imposes a physical cap on rack height. Consequently, the Germany data center rack market will continue to record a migration from 42U toward 48U without fully displacing the legacy form factor.
By Rack Type: Cabinet Solutions Ensure Security Compliance
Cabinet enclosures secured 74.68% share in 2025 and keep a 15.64% CAGR outlook, driven by data-sovereignty guidelines, insurer requirements, and the practical need to segregate colocation tenants. Cabinet models arrive with lockable front and rear doors, adjustable side panels, and integrated access logs that interface with building management systems, all of which streamline ISO27001 audits. Open-frame racks cater mainly to hyperscale interiors where each hall is already a restricted zone, but their open sides complicate hot-aisle containment retrofits, delaying the move to liquid cooling.
Wall-mount and micro variants serve small telecom huts and campus facilities where floor space is scarce. German operators value TÜV certification, so suppliers must provide documentation on load ratings, corrosion resistance, and seismic scores. Cabinet solutions therefore remain the default across financial services, public sector hosting, and cloud regions that require per-tenant security fencing. As liquid cooling adoption accelerates, cabinet doors with 70% perforation or rear-door heat exchangers will reinforce the cabinet model’s continued primacy within the Germany data center rack market.
By Data Center Type: Hyperscalers Drive Infrastructure Transformation
Colocation providers accounted for 48.75% of the Germany data center rack market share in 2025 as landlords spread fixed infrastructure costs over multiple tenants. Nevertheless, hyperscale and cloud sites post the highest 18.12% CAGR because AI investments require enormous power densities that in-house data centers cannot accommodate. Cloud builders negotiate multi-year volume agreements that bundle racks, power rails, and hot-aisle containment into a single invoice, therefore exerting price pressure yet offering predictable revenue flow to suppliers.
Enterprises are right-sizing on-premise footprints and moving non-core loads to hosted clouds, which releases capital but also shifts procurement timing. Edge deployments rise within manufacturing and automotive verticals where latency targets fall below 10 milliseconds. Every automated factory or smart logistics hub thus orders between two and eight cabinets, providing a different sales rhythm—small batches on fast turnaround. Overall, the Germany data center rack market size tilts toward hyperscale buyers, yet growth potential remains diversified across the deployment continuum.
By Material: Steel Dominance Faces Aluminum Challenge
Steel frames captured 81.47% of revenue in 2025 because they offer robust load capacity, vibration resistance, and cost advantages. The Germany data center rack market gradually adopts aluminum at a 16.98% CAGR through 2031 as operators factor weight restrictions in multi-storey halls and seismic requirements mandated by insurers. Aluminum dissipates heat faster than steel, making it a suitable pick for liquid-cooling backbones, and it eases manual handling during on-site assembly. Vendors combat steel’s weight disadvantage by offering pre-galvanized sheets with thinner gauges while retaining the 1 500 kg load rating typical for Frankfurt hyperscale rooms.
Composite and hybrid alloys remain niche and often appear in research institutes or military sites that demand electromagnetic shielding. Certification efforts add cost, thereby limiting broader uptake. The EnEfG waste-heat rule, however, introduces higher permissible operating temperatures, so materials that maintain structural integrity at 45 °C will gain relevance. Local firms already integrate recycled aluminum in new models, aligning with European Union circular-economy targets and adding an eco-label that resonates with sustainability-driven colocation tenants.
Geography Analysis
Germany hosts 522 operational data centers, making it the second-largest global market behind the United States and the largest national network in Europe. Frankfurt leads with 745 MW of live IT capacity and the DE-CIX internet exchange, concentrating more than one-third of the Germany data center rack market size within a 25 km radius. Land scarcity and grid congestion, however, are redirecting expansion to adjacent Rhine-Main towns, which draw incremental rack demand as hyperscalers adopt a campus model that spans ten or more buildings.
Berlin has transitioned from an emerging node into a strong alternate hub. Google and NTT each secured multi-hectare parcels, and new halls will support over 200 MW of additional load by 2030 cushmanwakefield.com. The capital’s lower land values and access to renewable power attract AI and high-performance computing tenants who prefer the region’s technology talent pool. Munich follows with fresh activity, including Portus and PGIM Real Estate projects that anchor 5.5 MW and 30 MVA phases respectively, broadening the Germany data center rack market toward southern Bavaria. Consistent with EnEfG policy, Munich utilities promote waste-heat capture, spurring rack redesigns that integrate rear-door exchangers compatible with district heating circuits.
Secondary cities such as Hamburg, Düsseldorf, and Stuttgart escalate appeal because local governments offer streamlined permits and renewable energy credits. Edge deployments further diffused demand to industrial towns where automotive factories and chemical plants require sub-10 ms latency links to cloud workloads. Brownfield conversions of disused steel mills and paper plants in the Ruhr Valley demonstrate that rack suppliers able to furnish modular, corrosion-resistant enclosures can secure high-margin projects. Consequently, while Frankfurt remains the focal point, a distributed build-out narrative now shapes the geography of the Germany data center rack market and reinforces the need for a national service footprint.
Regulatory Landscape
Germany's operating requirements for data center infrastructure increasingly tie rack selection to measured energy and sustainability performance, data protection, and safety compliance. A key near-term anchor is the Energy Efficiency Act (EnEfG), which links to a 1.2 PUE target for new sites from July 2026, pushing buyers toward racks that can support integrated monitoring, containment, and liquid-cooling-ready layouts. In March 2026, the German Federal Government adopted a National Data Centre Strategy via the Federal Ministry for Digital Affairs and State Modernisation (BMDS), explicitly framing energy, location, and technology sovereignty as priorities for new capacity. This reinforces demand for standardized, auditable rack platforms in colocation and public-sector-adjacent deployments.
At the EU level, the European Commission in March 2026 advanced a draft Delegated Regulation for a common EU rating scheme for data centers using PUE and WUE metrics, increasing the value of rack-level instrumentation and metering that can feed facility reporting. For network and grid-related interfaces, national and local processes, including permitting pathways and grid connection procedures overseen across transmission and distribution operators, affect build timelines, and that in turn shapes rack and power distribution procurement cadence. Together, these frameworks elevate the role of certified, documented cabinet systems aligned to GDPR audit practices and energy reporting expectations, particularly in Germany's regulated industries and colocation environments.
Value Chain Analysis
The Germany data center rack value chain runs from metal fabrication and frame manufacturing (steel and aluminum) through enclosure engineering (doors, side panels, seismic-rated uprights) and accessories (cable management, rails, blanks). An increasingly important layer is thermal and power integration for high-density AI deployments. Major OEMs and system vendors such as Rittal, Schneider Electric, Eaton, Vertiv, Legrand, and nVent (Schroff) supply standardized rack families and options for containment and rear-door cooling. They then rely on local distributors, systems integrators, and EPC partners to package racks with PDUs, busways, and monitoring into deployable rows and suites. Downstream, hyperscale and colocation operators in Frankfurt and emerging campuses in Berlin and other metros drive volume buys, while telecom operators and industrial edge sites pull smaller form factors that emphasize rapid installation and remote manageability.
Integration is shifting upstream toward modular, factory-prepared building blocks that reduce onsite labor constraints and commissioning time. A March 2026 example is the Siemens Smart Infrastructure and Rittal partnership, which centers on standardized, modular infrastructure and dedicated power-rack concepts for AI-grade power densities. It aligns rack demand with low-voltage distribution, power electronics, and monitoring as a combined specification rather than a standalone cabinet purchase. Policy-led coordination, highlighted by the BMDS National Data Centre Strategy adopted in March 2026, further connects industry stakeholders around sovereign infrastructure goals, strengthening the pull for locally certified products and documented supply chains that can satisfy energy, safety, and security requirements.
Competitive Landscape
The Germany data center rack market displays moderate concentration. Rittal, Schneider Electric, and Eaton combine strong domestic production with global service networks, while Vertiv uses its thermal management leadership to cross-sell integrated racks plus rear-door coolers. Local champions differentiate through compliance documentation, TÜV stamps, and proximity, which cut delivery lead times to less than one week for standard SKUs. Global entrants, including Legrand and Huawei Digital Power, seek footholds through partnerships with German engineering, procurement, and construction contractors who can navigate municipal zoning and federal emission laws.
Technological differentiation tilts toward platform bundles. Schneider Electric’s EcoStruxure IT Gateway update in 2025 added multivendor device mapping, meeting a market request for unified monitoring across mixed asset fleets. Siemens advanced a turnkey concept with Cadolto and Legrand that pairs prefabricated rooms with factory-installed 42U racks, thus trimming on-site fit-out by 40% and responding to tight edge deployment schedules. Northern Data Group signals a new buyer persona: AI-focused infrastructure operators that demand 48U liquid-ready frames, high copper weight load ratings, and extensive sensor arrays for machine-learning power optimization.
Mergers and long-term supply agreements intensify competition. Rittal signed a five-year framework with two hyperscale landlords that locks a baseline of 100 000 cabinets across European sites. Vertiv countered by aligning with a German colocation provider to integrate its CoolLoop rear-door heat exchangers as a standard option. New entrants chase sustainability differentiation by marketing aluminum frames with a 70% recycled content claim, targeting customers that disclose cradle-to-grave carbon assessments to investors. The evolving competitive chessboard thus combines engineering capability, regulatory fluency, and green credentials as the key winning vectors in the Germany data center rack market.
Germany Data Center Rack Industry Leaders
Eaton Corporation
Rittal GMBH & Co.KG
Schneider Electric SE
Vertiv Holdings Co
nVent Electric plc (incl. Schroff)
- *Disclaimer: Major Players sorted in no particular order

Market Opportunities and Future Outlook
National policy and hyperscale-style campus expansion are creating whitespace for rack vendors that can deliver standardized, energy-reportable, AI-ready cabinet platforms. The BMDS National Data Centre Strategy adopted in March 2026 sets out targets to double total national data center capacity and to quadruple AI and high-performance computing capacity by 2030. It organizes measures across energy and sustainability, location and space, and technology and sovereignty. This agenda increases the addressable need for higher-density rack configurations, including 48U and liquid-ready frames, and for rack-level sensors and metering that support PUE and WUE reporting, particularly as the European Commission advances a common EU rating scheme using these metrics.
A second opportunity area is the spread of new large campuses and the relocation of capacity to secondary corridors, where permitting and grid access shape deployment designs. For example, Virtus has announced a 204 MW campus in Wustermark (outside Berlin) with multiyear phased build-out, which points to sustained demand for repeatable rack SKUs, staged delivery programs, and service coverage beyond Frankfurt. The strategy focus on waste-heat utilization in regions around Berlin, including Havelland and Potsdam, also favors rack architectures compatible with rear-door heat exchangers and integrated coolant distribution in high-density halls. At the same time, industry moves toward standardized AI infrastructure, such as the March 2026 Siemens-Rittal collaboration on modular power and rack concepts, widen the commercial space for bundled rack-plus-power-plus-thermal offerings that shorten lead times for new builds and for brownfield conversions.
Recent Industry Developments
- June 2026: Vertiv co-hosted the Next Level Data Center event at the House of Logistics and Mobility (HOLM) in Frankfurt am Main to promote scalable AI infrastructure. The gathering highlights demand for modular edge and AI ready racks in Germany. It strengthens Vertiv's role in enabling scalable AI deployments across regional data centers.
- May 2026: Vertiv announced European availability of Vertiv CoolChip CDU 2300 and fluid network row manifolds for high density AI rack cooling. The launch targets rising density requirements in German racks and edge facilities. It broadens Vertiv's footprint in European markets and supports AI workloads with advanced cooling.
- April 2026: Vertiv deployed PowerIT switched rPDUs across data centers and core network sites in Germany for rack level real-time monitoring. The deployment improves power, capacity, and temperature visibility in German data center racks. It boosts operational intelligence and reliability for AI and edge deployments in the region.


Research Methodology Framework and Report Scope
Market Definition and Coverage
This market covers revenue generated from physical data center racks sold and installed in Germany, including cabinet and open-frame rack structures used to mount servers, storage, and networking equipment in data halls and edge rooms.
Scope exclusions: Services, power and cooling equipment, rack PDUs, KVMs, and IT hardware are excluded from this market sizing.
Segmentation Overview
- By Rack Size
- Quarter Rack
- Half Rack
- Full Rack
- By Rack Height
- 42U
- 45U
- 48U
- Other Heights (52U and Custom)
- By Rack Type
- Cabinet (Closed) Racks
- Open-Frame Racks
- Wall-Mount Racks
- By Data Center Type
- Colocation Facilities
- Hyperscale and Cloud Service Provider DCs
- Enterprise and Edge
- By Material
- Steel
- Aluminum
- Other Alloys and Composites
Data Sources, Market Sizing, and Validation
Desk Research
Desk research was used to set market boundaries and build a cleaner demand view before modeling. We reviewed public data and reference materials such as Germany energy and digital infrastructure releases (including the Federal Network Agency), Destatis macro series, and Eurostat trade and industrial indicators, plus European Commission policy notes that shape data center build activity and energy efficiency compliance.
To translate macro signals into rack demand, we also checked data center and internet ecosystem publications and datasets, including materials from the German Datacenter Association, DE-CIX traffic updates, and public construction and permitting commentary in reputable press outlets. Company filings, product catalogs, and investor presentations were used to validate typical rack formats, cabinet features, and price ranges. Where needed, a paid subscription for company financials and a patent database were used selectively to cross-check supplier activity and product change cycles. The sources listed here are illustrative and not exhaustive, and additional public materials were also used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work focused on aligning the model with what is actually being installed across German colocation, hyperscale, and enterprise sites, and how buying differs between new halls and retrofit upgrades. We spoke with rack suppliers and channel partners, data center operators, systems integrators, and facility teams. These discussions were then used to confirm rack mix, typical cabinet specifications for higher-density loads, lead times, and the timing of projects across major hubs (especially Frankfurt) and secondary cities.
Distribution of primary research fieldwork respondents
| Company type | Respondent position |
|---|---|
| Top tier: 36% | CXOs: 17% |
| Mid tier: 46% | Functional/Unit leaders: 38% |
| Smaller Players: 18% | Managers: 45% |
Market-Sizing & Forecasting
Sizing starts with a top-down demand pool reconstructed from Germany data center build activity, site expansions, and creation of rackable space. That pool is then translated into annual rack unit additions and replacement cycles. To keep totals realistic, we corroborated results with selective bottom-up checks, including sampled pricing used to estimate cabinet volumes by rack type, plus channel feedback on shipment pacing and backlog, and then adjusted the model when gaps appeared.
Key inputs include the pace of new data hall commissioning, retrofit intensity driven by higher rack power densities, cabinet versus open-frame preference in audited environments, typical rack heights and usable U space, average selling price movement linked to steel and feature content, and the share of edge deployments versus large campus installs. Forecasting uses scenario analysis supported by expert views on hyperscale rollouts, colocation pre-lease momentum, and energy efficiency compliance timelines. A short ARIMA-style time series check is applied to smooth year-on-year installation swings. When supplier volume data is incomplete, missing portions are filled using conservative adoption ratios and then re-tested with operator-side purchase patterns so the final numbers stay traceable.
Data Validation & Update Cycle
Model outputs are checked against independent signals like data center capacity additions, public project pipelines, and procurement lead-time direction, and then variances are flagged for review. Anomaly checks are run by year and by rack category, so sudden jumps can be tied to a specific driver such as a large campus phase going live or a retrofit wave.
Before sign-off, the work is reviewed in steps, starting with assumption screening, then cross-checks against interview notes, and ending with an internal consistency pass across related infrastructure markets. The report is refreshed annually, with interim updates when material events occur, such as major capacity announcements or policy shifts that affect deployment timing. Right before delivery, a fresh scan of recent public releases is completed so clients receive the latest updated view.
Mordor Intelligence's Germany Data Center Rack Market Size Versus Other Published Estimates
Published market values can vary because teams do not always define what counts as a rack sale in the same way, and the year and pricing basis can also differ. Here, the sizing logic stays tied to physical rack revenues in Germany, and then install activity and replacement cycles are used so one-time project spikes do not inflate the total.
Rack PDUs and rack-level monitoring add-ons sit outside the Mordor Intelligence scope, which is a practical reason some broader figures read higher when they bundle adjacent enclosure accessories into the same number. Another common driver is how fast average selling prices are assumed to rise for liquid-cooling-ready cabinets, since some estimates apply a faster uplift without checking what portion of sites are actually buying those configurations in the near term.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 115.60 M (2025) | |
| Industry Research House A | USD 271.52 M (2025) | May include a wider basket that blends rack cabinets with related rack systems and add-ons, and it can also apply higher blended pricing across cabinet types without separating retrofit refresh from new hall installs. |
| Industry Research House B | USD 153.65 M (2020) | Uses a different comparison year and may lean more on smooth long-range extrapolation, which can underweight step-changes from large campus phases and over-simplify years where commissioning is uneven. |
The table shows that differences usually come back to scope items included with the rack, the comparison year chosen, and how price progression is handled when high-density cabinets grow faster than standard racks. By keeping the estimate traceable to rack unit demand signals, realistic pricing checks, and repeatable review steps, the result stays easier to reconcile with real procurement patterns in Germany.


Key Questions Answered in the Report
What is the current size of the Germany data center rack market?
The market generated USD 131.62 million in 2026 and is forecast to reach USD 251.75 million by 2031.
Which rack type leads in Germany
Cabinet (closed) racks command 74.68% revenue share, driven by GDPR security and cooling efficiency requirements.
Why are 48U racks gaining popularity?
48U frames allow operators to host more servers in the same footprint and provide space for liquid-cooling manifolds, supporting a 17.08% CAGR through 2031.
How do energy regulations influence rack design?
The Energy Efficiency Act mandates a 1.2 PUE for new sites from July 2026, prompting buyers to adopt racks with integrated cooling and monitoring.
Page last updated on:
- UK Data Center Rack Market
- Spain Data Center Rack Market
- Europe Data Center Rack Market
- Middle East Data Center Rack Market
- Data Center Rack Market
- Singapore Data Center Rack Market
- India Data Center Rack Market
- Vietnam Data Center Rack Market
- US Data Center Rack Market
- Poland Data Center Rack Market
- Artificial Intelligence (AI) Data Center Market AI facilities across all regions, split by facility type, component and tier.
- Data Center Server Market Servers across the global market, covering tier, facility size and facility type.
- Data Center Construction Market Global construction demand, split by tier, facility size and facility type.
- Spain Data Center Power Market Power systems demand across Spain, covering component, facility type and facility size.





