
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market Size and Share
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market Analysis by Mordor Intelligence
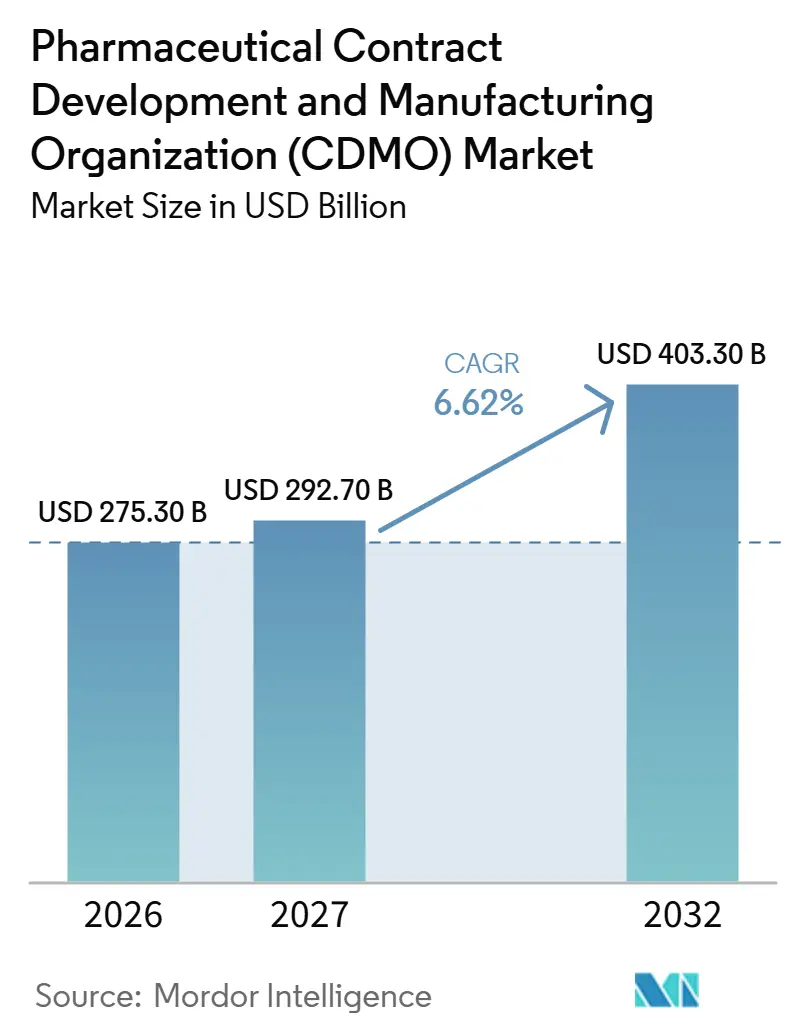
The pharmaceutical contract development and manufacturing organization (CDMO) market size is projected to expand from USD 275.3 billion in 2026 and USD 292.7 billion in 2027 to USD 403.3 billion by 2032, registering a CAGR of 6.62% between 2027 and 2032.
Commercial outsourcing in the United States and complex-therapy development are expanding the opportunity for suppliers that combine production assets with specialized services. Sterile injectables make the connection between technology transfer, manufacturing execution, and product approval commercially important. Broader service combinations can capture more of that work, while limited production headroom and destination-market enforcement can constrain conversion into dependable supply. Multiyear supply commitments make the handover from technology transfer to approved production a point where headroom and destination-market standing shape a supplier’s ability to retain a program.
Key Report Takeaways
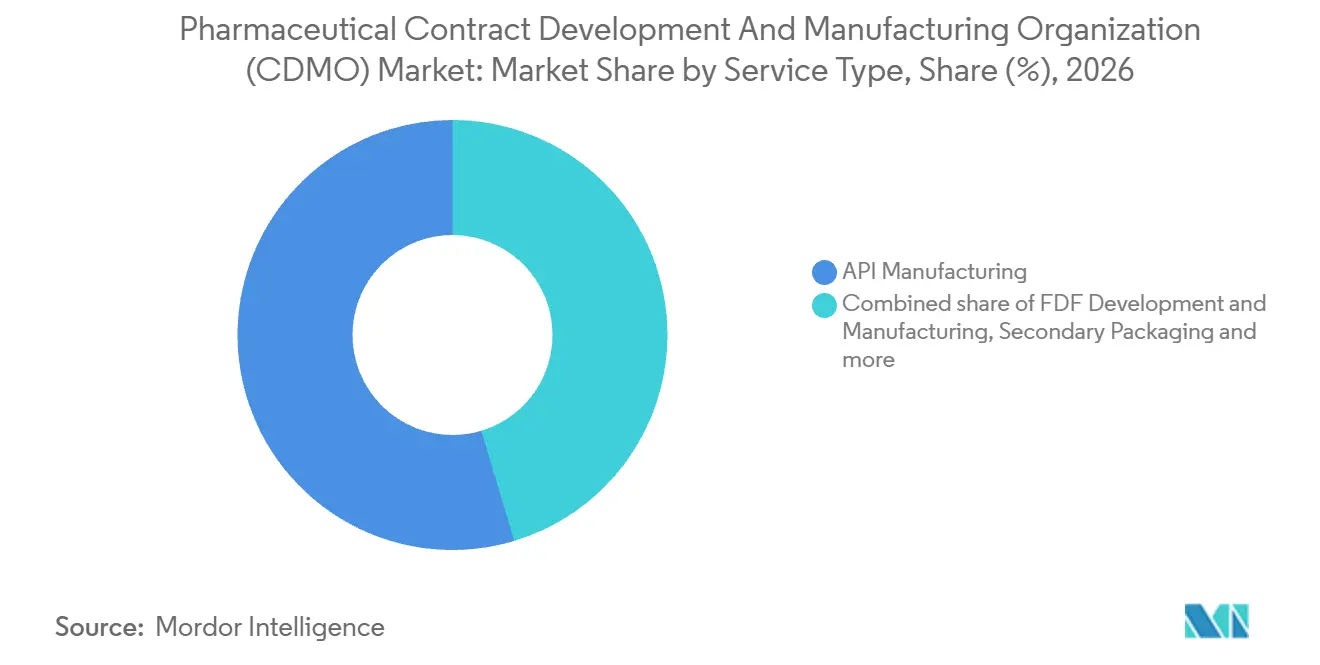
- By service type, API manufacturing held a 54.64% pharmaceutical contract development and manufacturing organization (CDMO) market share in 2026, while FDF development and manufacturing is forecast to achieve the fastest CAGR of 7.45% between 2027 and 2032.
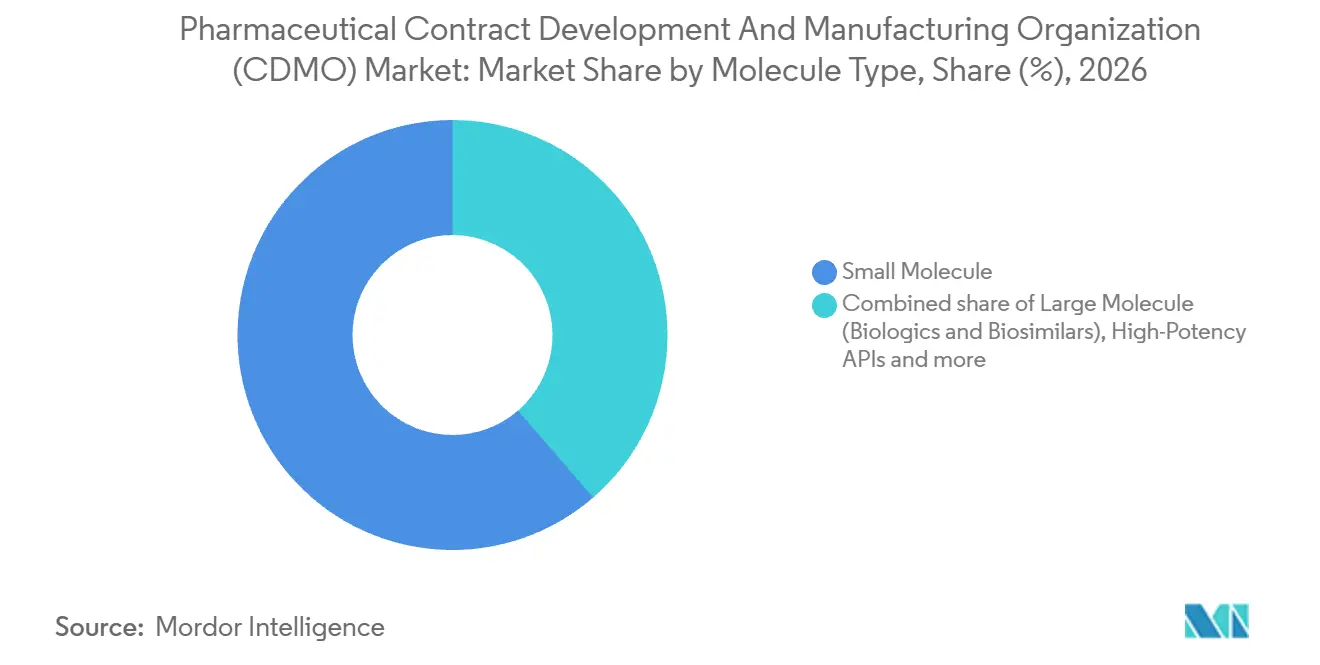
- Among molecule types, small molecules accounted for a 61.35% share of the pharmaceutical contract development and manufacturing organization (CDMO) market size in 2026, and high-potency APIs are forecast to grow fastest at a CAGR of 8.35% between 2027 and 2032.
- By dosage form, solid oral products led with 39.2% of CDMO revenue in 2026, whereas sterile injectables are expected to register the fastest CAGR of 9.3% between 2027 and 2032.
- Across therapeutic areas, oncology held 32.24% of CDMO revenue in 2026, with infectious diseases and vaccines forecast to record the fastest CAGR of 8.4% between 2027 and 2032.
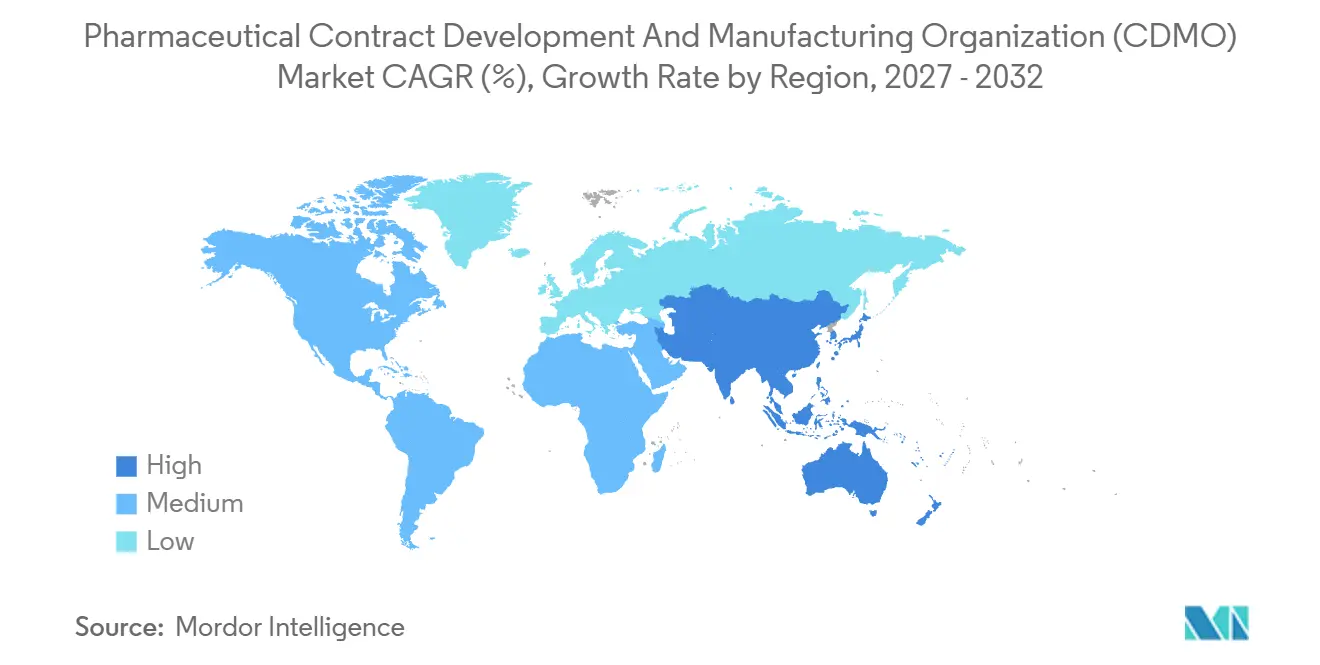
- Geographically, North America accounted for 37.88% of CDMO revenue in 2026, while Asia-Pacific is forecast to register the fastest CAGR of 7.6% between 2027 and 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Increasing outsourcing volume by large pharmaceutical companies | +2.8% | United States and Canada | Medium term (2-4 years) |
| Surge in biologics and complex-molecule pipelines | +2.5% | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Long term (≥ 4 years) |
| Cost- and speed-advantage of manufacturing in emerging markets | +1% | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Medium term (2-4 years) |
| Consolidation toward end-to-end one-stop CDMOs | +1.3% | United States and China | Short term (≤ 2 years) |
| AI-enabled rapid process-development platforms | +0.5% | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Medium term (2-4 years) |
| GLP-1 and peptide HPAPI capacity build-outs | +0.8% | China and United States | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Increasing outsourcing volume by large pharmaceutical companies
Large pharmaceutical sponsors expand access to commercial production through long-duration commitments to external manufacturing networks. In April 2025, Regeneron agreed to have FUJIFILM Biotechnologies (formerly FUJIFILM Diosynth Biotechnologies) manufacture bulk drug product for its commercial biologic medicines in Holly Springs, North Carolina, under a 10-year agreement.[1] The arrangement was expected to nearly double Regeneron’s US large-scale manufacturing capacity. In February 2026, GSK renewed a 5-year manufacturing partnership with Bora Pharmaceuticals that expanded access to multiple Bora sites. GSK is the largest pharmaceutical partner at Bora’s Mississauga facility, where Bora provides end-to-end manufacturing for more than 20 commercial product lines. Together, these commitments show how outsourcing can anchor recurring commercial workloads, giving CDMOs a reason to organize capacity around sustained product supply instead of relying exclusively on development batches.
Surge in biologics and complex-molecule pipelines
Complex-therapy pipeline growth expands the potential customer base for specialized development services before programs reach commercial manufacturing. The ISCT/Citeline global cell and gene therapy pipeline contained 383 active clinical trials in its 2026 edition, compared with 322 in the 2025 edition. Phase I and II studies represented 95% of that 2026 clinical-trial pipeline. This concentration makes progression through clinical development a central condition for translating the larger trial population into commercial supply requirements. Development-stage sponsors offer the nearer service opportunity, because the trial mix supports clinical-development work before it supports commitments to commercial manufacturing suites.
Cost- and speed-advantage of manufacturing in emerging markets
For a pharmaceutical sponsor sourcing small-molecule generic tablets, an emerging-market CDMO’s potential advantage depends on the local cost of the required production standard. An Indian supplier would be cheaper if lower local labor and facility costs reduced the cost of an otherwise equivalent manufacturing assignment. Any saving would need to survive the buyer’s destination-market validation and release obligations. A speed advantage would likewise require the supplier to complete those obligations sooner, without treating a less demanding specification as an equivalent service. Price-sensitive generic assignments would favor suppliers that could preserve their local cost advantage after meeting the destination’s requirements.
Consolidation toward end-to-end one-stop CDMOs
Combining complementary capabilities can reduce organizational handoffs for sponsors seeking external support across several development and manufacturing stages. In September 2026, Kincell Bio and Cellipont Bioservices completed their merger to form Kincellis Advanced Therapies, a US CDMO spanning cell-therapy development through commercial supply.[2] The combination joined immune-cell expertise with stem-cell and other advanced-modality capabilities. CordenPharma completed its AmbioPharm acquisition in August 2026, strengthening an offering extending from peptide drug substance to sterile injectable and oral solid drug products. Its announcement described integration of the acquired US and Chinese sites as planned over the following months. A peptide or cell-therapy program can stay with one organization from development through supply, with CordenPharma’s version depending on the announced integration of its acquired sites.
Restraints Impact Analysis of Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Stringent multi-region regulatory requirements | -0.9% | India and United States | Short term (≤ 2 years) |
| Capacity-utilization and lead-time risk | -0.7% | People’s Republic of China | Short term (≤ 2 years) |
| High capex for sterile biologics suites | -0.4% | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Long term (≥ 4 years) |
| Scarcity of skilled aseptic-manufacturing talent | -0.3% | North America, Europe, Asia-Pacific, Middle East and Africa, South America | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Stringent multi-region regulatory requirements
US-bound pharmaceutical batches can face import detention after manufacturing is completed. On February 12, 2025, FDA added India-based contract manufacturer Zenzi Pharmaceutical Industries Private Limited to Import Alert 66-79 for all drugs and drug products from the listed establishment. Zenzi remained on the Red List in the September 23, 2026 edition. The alert covers foreign establishments refusing FDA inspection or a mandatory remote regulatory assessment, and FDA divisions may detain covered shipments without physical examination. Release may be considered after case-by-case evaluation of evidence when shipments are detained. Export manufacturers with a listing like this face US entry as the point where an otherwise completed batch can stall, adding release-review delay after production.
Capacity-utilization and lead-time risk
Growing peptide programs can require additional manufacturing headroom as they advance. Medtide Inc., a peptide contract research, development, and manufacturing organization, reported high utilization across its production lines during the first 5 months of 2025. Its key lines comprised high-capacity synthesis lines and large-diameter purification lines, linking the constraint to specific production steps. In its June 2025 prospectus, the supplier warned that excessively high utilization risked losing potential orders because customers preferred sufficient buffered capacity.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market Segment Analysis
By Service Type:
Manufacturing Scale Meets Late-Stage Oral SupplyAPI manufacturing accounted for a 54.64% share of the pharmaceutical contract development and manufacturing organization (CDMO) market size in 2026. Cambrex Corporation’s Charles City, Iowa, site manufactures active pharmaceutical ingredients (APIs) and intermediates, including highly potent molecules and controlled substances. In October 2025, the company announced a planned USD 120 million investment to increase the site’s large-scale API manufacturing capacity by 40%, to nearly 1 million liters. In March 2026, Cambrex completed initial engineering studies for the new large-scale API plant at the site, progress toward the previously announced USD 120 million investment.
Finished dosage form (FDF) development and manufacturing is forecast to be the fastest-growing service segment, with a CAGR of 7.45% between 2027 and 2032. Ardena completed its acquisition of Catalent’s Somerset, New Jersey, facility in February 2025, adding late-stage and small-scale commercial oral drug manufacturing capabilities. A newer patient-oriented dosage-form assignment connects outsourced production directly to a planned product introduction. In August 2026, Cycle Pharmaceuticals agreed to have Forma Life Sciences manufacture FDA-approved CAVHANZA (nilotinib) orally disintegrating tablets in Irvine, California, to establish US commercial supply ahead of Cycle’s introduction. Product-specific supply preparation extends the FDF assignment from developing a dosage form to establishing a commercial manufacturing route for an approved therapy.



By Molecule Type:
Commercial Breadth Meets High-Potency SpecializationSmall molecules represented a 61.35% pharmaceutical contract development and manufacturing organization (CDMO) market share in 2026. Lonza Group reported more than 135 commercial small molecules in its 2025 Advanced Synthesis portfolio, covering APIs, highly potent APIs, dosage forms and delivery systems, and particle engineering. It also signed a large multiyear commercial small-molecule drug-substance supply agreement in 2025.
High-potency APIs are forecast to be the fastest-growing molecule segment, with a CAGR of 8.35% between 2027 and 2032. Aragen Life Sciences began operating its OneHP high-potency development and manufacturing platform at Nacharam in Hyderabad, India, on October 6, 2026. The platform operates one manufacturing line designed for annual API capacity of 500 to 600 kilograms and supports highly potent compounds, including cytotoxic molecules. It connects milligram-scale discovery with process development and multi-kilogram manufacturing under current good manufacturing practice (cGMP). Keeping those stages on one campus makes early process development part of the manufacturing relationship before a potent compound reaches larger batch requirements.

By Dosage Form:
Dedicated Oral Suites Accompany Sterile ExpansionSolid oral products formed the largest dosage-form segment, accounting for 39.2% of CDMO revenue in 2026. In August 2025, Piramal Pharma Solutions, part of Piramal Pharma Ltd., opened a dedicated oral-solid-dose suite at Sellersville, Pennsylvania, for NewAmsterdam Pharma. Reconfigured existing space housed a suite designed for multilayer tablet production, with granulation, compression, tableting, and coating capabilities. It was intended to provide commercial capacity for NewAmsterdam’s investigational fixed-dose combination, with patient delivery conditional on approval. Piramal’s dedicated multilayer suite ties the manufacturing assignment to NewAmsterdam’s defined tablet configuration, extending the service proposition beyond access to general-purpose equipment.
Sterile injectables are forecast to be the fastest-growing dosage-form segment, with a CAGR of 9.3% between 2027 and 2032. In September 2026, CordenPharma projected capacity of up to 500 million injectable units annually at Caponago, Italy, serving programs from early-phase projects through large-scale commercial production. CordenPharma frames its planned Caponago capacity as serving injectable programs from early-phase projects through large-scale commercial production, so a program could scale within one supplier as volumes grow. Topicals and transdermals have a commercial-transfer role, illustrated by MedPharm’s October 2026 agreement with an unnamed global pharmaceutical company for a specialty topical product in Durham, North Carolina. Novel and specialty forms create formulation-development assignments, illustrated by InnoCore’s March 2026 collaboration with an unnamed US pharmaceutical company on a long-acting injectable small molecule for depression.
By Therapeutic Area:
Oncology Scale Depends on Dedicated CapabilitiesOncology was the largest therapeutic-area segment, accounting for 32.24% of CDMO revenue in 2026. Lupin Manufacturing Solutions, a wholly owned subsidiary of Lupin Limited, commissioned a dedicated oncology API CDMO block at Vizag, India, in November 2025.[3] The high-containment unit was designed to support oncology programs from preclinical research through commercial manufacturing, with a batch range of 1 to 35 kilograms. At commissioning, the unit had 20 reactors and more than 20 isolators, with containment systems designed for exposure levels of ≤0.05 µg/m³. Batch sizes of 1 to 35 kilograms inside a unit built to contain highly potent API production suit programs that move from preclinical to commercial batches.
Infectious diseases and vaccines are forecast to be the fastest-growing therapeutic-area segment, with a CAGR of 8.4% between 2027 and 2032. In March 2026, SK bioscience contracted IDT Biologika for drug-product development and manufacturing for MSD’s existing Zaire Ebola vaccine with an updated process. SK bioscience will produce the drug substance, and the updated process, developed with MSD and Hilleman Laboratories, aims to raise manufacturing yield and improve thermostability. AGC Biologics had separately agreed in July 2025 to supply drug substance from Heidelberg, Germany, for Phase II studies of Valneva’s investigational tetravalent Shigella bioconjugate vaccine. Vaccine assignments in this group range from re-engineering an existing product’s supply process to supplying clinical-candidate material.
Geography Analysis
North America Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
North America accounted for a 37.88% share of the pharmaceutical contract development and manufacturing organization (CDMO) market size in 2026. FUJIFILM Biotechnologies’ Holly Springs site in North Carolina, United States, launched cGMP production in 2025 with 8 bioreactors of 20,000 liters each. One of North America’s largest end-to-end cell-culture facilities, it gives sponsors an external manufacturing option linked to substantial production assets within the region.
Asia-Pacific Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
Asia-Pacific is forecast to be the fastest-growing geography, with a CAGR of 7.6% between 2027 and 2032. Aragen’s installed small-molecule capacity across Hyderabad and Visakhapatnam in India stood at 364,000 liters on March 31, 2026. In July 2026, AGC Biologics, an AGC Inc. subsidiary, entered a long-term agreement to provide commercial manufacturing at Yokohama, Japan, for multiple products of an unnamed global biopharmaceutical customer. At the announcement, the site was under development, with GMP-compliant services planned for 2027. The Japanese agreement illustrates a route to expansion in which a future service launch is backed by a customer commitment, rather than capacity construction alone.
Within Europe, the EU’s GMP guidance requires a written contract between the contract giver and contract acceptor for outsourced pharmaceutical activities. Aenova provides drug-product development, manufacturing, and packaging at sites in Germany, Switzerland, Italy, Ireland, and Romania. In the Middle East and Africa, Egypt’s SEDICO and Sandoz Global agreed in March 2025 to technology transfer for local manufacture of 5 essential oncology products. Porton Advanced Solutions and EVA Pharma signed a June 2025 memorandum of understanding to develop CAR-T manufacturing capabilities, with hubs planned in Egypt and Saudi Arabia. In South America, Anvisa’s August 2025 certification of Akums’ Haridwar, India, sterile facility authorized manufacture and export to Brazil, opening a route through qualified overseas production.
Regulatory Framework and Outlook
Selected jurisdictions are compared by the approvals, quality controls, and announced policy changes affecting pharmaceutical contract manufacturers. The perspective is a CDMO operating an affiliated network of equivalent units making the same drugs under one quality unit and a unified pharmaceutical quality system while serving pharmaceutical sponsors. FDA’s framework for finished pharmaceuticals gives quality-control units approval or rejection authority over components, packaging materials, labeling, and drugs. China’s National Medical Products Administration (NMPA) contract-manufacturing notice keeps marketing authorization holder (MAH) and manufacturer obligations distinct, making oversight allocation another part of the compliance task.
Regulatory Table of Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
| Decision factor | United States | Germany | China | Brazil |
|---|---|---|---|---|
| Primary authority | FDA | Competent state authorities | NMPA and provincial drug regulators | Anvisa |
| Key instruments or direction | 21 CFR Parts 210 and 211; July 2026 distributed-manufacturing registration proposal | Manufacturing authorization and GMP inspection framework; proposed EU documentation, computerized-systems, and AI guidance | Announcement No. 134 of 2025, effective December 30, 2025, for marketed-drug contract manufacturing; earlier accepted applications retain original requirements | RDC 658/2022, amended by RDC 972/2025 |
| Commercial effect | Covered foreign establishments must register and list US-bound drugs even when further processed at another foreign establishment | Manufacturing authorization is required; GMP inspections are generally conducted by the relevant state authority | Evaluate MAHs, product risk, technical transfer, and shared-line feasibility before accepting work; provincial enforcement can restrict activities after regulator-set remediation deadlines are missed | Maintain a documented, monitored, resourced GMP and quality-risk system; technically justified, adequate risk-based alternatives may replace online packaging control |
| Current policy attractiveness | Medium | Medium | Low | Medium |
| Future direction of policy attractiveness | Easing | Hardening | Hardening | No change |
| Source: Mordor Intelligence | ||||
FDA’s July 13, 2026 proposal would simplify registration for this affiliated network, excluding separately hired unaffiliated contract manufacturers, but remained proposed on October 20, 2026 after comments closed on September 11, 2026. The European Commission’s documentation, computerized-system, and AI GMP drafts (July to October 2025 consultation) were unadopted on October 20, 2026 without implementation dates, suggesting heavier validation alongside Germany’s state-level authorization and GMP inspection. China’s enforcement schedule generally allows one year from December 30, 2025, for remediation, with reasons and completion deadlines required for longer items and consequences where regulator-set time limits are missed. Brazil’s quality-system duties under RDC 658/2022 continue, and conditional risk-based packaging flexibility took effect April 23, 2025, supporting continuity because Anvisa’s September 2026 sterile-GMP review announcement sets no revised text or effective date.
Value Chain Stages
Value capture differs across drug-substance production, sterile finished-dose manufacturing, and packaging and clinical-supply services. Cambrex Corporation provides drug-substance development, manufacturing, analytical, and investigational new drug application support services to pharmaceutical clients. Thermo Fisher Scientific Inc. (Patheon) develops and commercially manufactures sterile liquid and lyophilized products at Swindon in the United Kingdom. Across these stages, the purchased service changes from ingredient development to finished-dose execution and trial-supply preparation.
Value Chain Analysis Table of Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Drug-substance development and manufacturing | Drug-substance CDMOs such as Cambrex Corporation | Development, analytical, and manufacturing service fees | Matching process readiness with manufacturing scale | Link process-transfer milestones to production campaigns |
| Sterile finished-dose manufacturing | Sterile-product CDMOs such as Thermo Fisher Scientific Inc. (Patheon) at Swindon | Development and fill-finish service fees | Handover from product development to commercial sterile production | Keep development and manufacturing execution closely integrated |
| Secondary packaging and clinical supply | Commercial packagers such as PCI Pharma Services; clinical-supply providers such as Thermo Fisher Scientific Inc. (Patheon) | Packaging, assembly, labeling, and distribution service fees | Matching packaging configurations to clinical-distribution needs | Coordinate packaging specifications with trial-supply releases |
| Source: Mordor Intelligence | ||||
Patheon’s clinical-supply services connect drug manufacturing with packaging, labeling, and distribution for biotech and biopharma sponsors. Combining those assignments can reduce the handover work between a manufactured batch and trial supplies ready for distribution, extending the provider’s fee opportunity to packaging, labeling, and distribution. Execution responsibility broadens with fee capture, since the provider takes on packaging and distribution deliverables alongside the clinical batch.
Competitive Landscape
Market Concentration
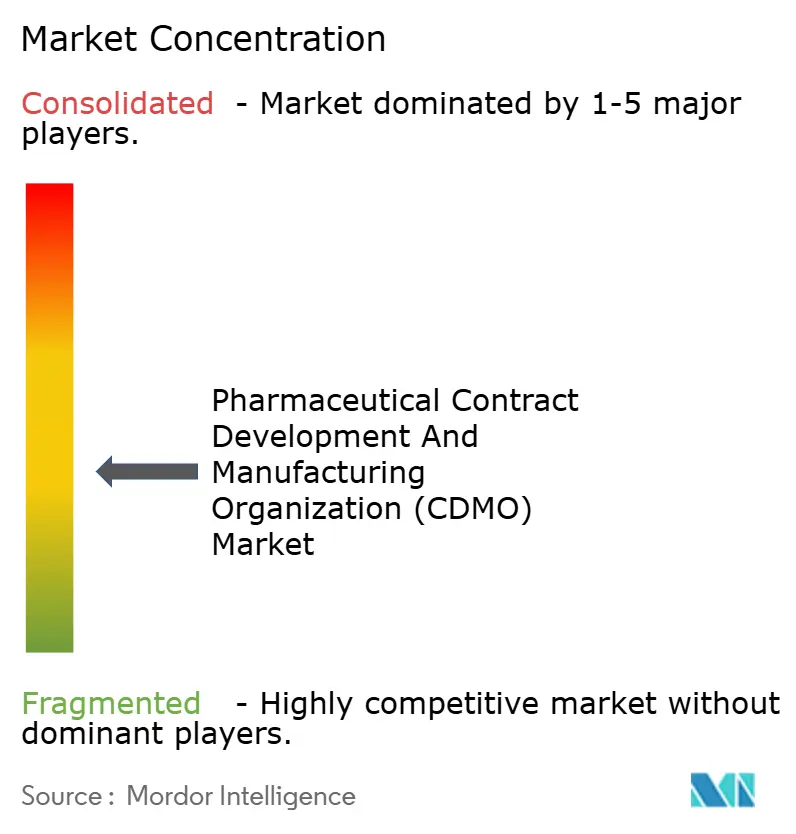
The industry is moderately fragmented across broad networks and specialized manufacturers, including Catalent Inc.’s oral drug-product and spray-drying services. In July 2025, Catalent completed a Boston spray-drying upgrade that added amorphous spray-dried dispersion manufacturing for late-stage clinical supply through commercialization. Recipharm AB provides product development and GMP pilot-scale manufacturing in Germany, while Jubilant Pharmova Ltd. competes through its sterile injectables CDMO business. Thermo Fisher Scientific Inc. (Patheon) offers end-to-end CDMO services for small and large molecules across drug-development stages. Boehringer Ingelheim Group manufactured biopharmaceuticals for third-party global industrial customers and its own products through Human Pharma’s BioXcellence division in 2025, making integrated drugmakers part of the competitive supplier base.
Boehringer Ingelheim Biopharmaceuticals (China) operates a Shanghai Zhangjiang biologics CDMO serving global and Chinese innovators. On September 23, 2026, Boehringer Ingelheim (China) Investment, wholly owned by Boehringer Ingelheim Auslandsbeteiligungs GmbH, agreed to sell 100% of that subsidiary to Shanghai RAAS, subject to foreign antitrust approval, with closing due by December 31, 2027. The seller said its parent’s Greater China strategic adjustment prompted a planned focus on other China businesses, while Shanghai RAAS said the purchase would internalize its existing outsourced collaboration with the target. Captive use could follow after closing if the buyer’s innovative drugs successfully complete clinical development and commercialize, the condition Shanghai RAAS gave for placing its own products on the site’s capacity.
Competitive direction in sterile manufacturing turns on moving from technology-transfer batches into commercial manufacturing after product approval. By October 2025, Jubilant Pharmova had launched its third sterile fill-and-finish line in Spokane, Washington, with a USD 132 million investment. At that point, it was running transfer programs for 5 to 6 products across multiple vial sizes, and its inaugural batch initiated revenue generation from technology-transfer programs. In its October 2025 update, the company expected commercial batch production from fiscal 2027 after FDA product approvals. For challengers, winning transfer work can provide an entry route, but commercial manufacturing income depends on the product’s approval path as well as installed equipment.
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Industry Leaders
-
Catalent Inc.
-
Recipharm AB
-
Jubilant Pharmova Ltd.
-
Thermo Fisher Scientific Inc. (Patheon)
-
Boehringer Ingelheim Group
- *Disclaimer: Major Players sorted in no particular order
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market Companies Covered in this Report
- Thermo Fisher Scientific Inc. (Patheon)
- Lonza Group
- Catalent Inc.
- Samsung Biologics Co. Ltd.
- WuXi AppTec Inc.
- Recipharm AB
- Jubilant Pharmova Ltd.
- Boehringer Ingelheim Group
- Pfizer CentreOne
- Aenova Holding GmbH
- Fujifilm Biotechnologies
- Simtra BioPharma Solutions
- Corden Pharma GmbH
- AbbVie Contract Manufacturing
- Cambrex Corporation
- Syneos Health Inc.
- IQVIA Holdings Inc.
- Fortrea
- PAREXEL International Corporation
- ICON PLC
- Charles River Laboratories International Inc.
- Eurofins Scientific SE
- SGS Life Science Services SA
- CMIC Holdings Co. Ltd
- Novotech Pty Ltd
- Hangzhou Tigermed Consulting Co. Ltd
- Samsung Bioepis Co. Ltd
- Labtec GmbH (AdhexPharma S.A.S.)
- Tapemark
- Famar SA
Key Opportunities for Market Participants
Supplier opportunities depend on whether the buyer needs a facility operator, an improved manufacturing process, or additional productive capacity. BRIC-THSTI’s Faridabad mandate in India requires proven CAR-T experience and obliges the partner to procure and qualify additional equipment. Planned EU support targets eligible critical medicines with a demonstrated supply vulnerability and viable long-term supply to the Union market. The commercial distinction is between winning a manufacturing assignment and funding the capabilities needed to pursue subsequent customer work.
Market Opportunities Table of Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Joint operation of CAR-T and lentiviral-vector manufacturing capacity | October 9, 2026 expression of interest; submissions due November 10, 2026 | BRIC-THSTI, Faridabad, India | Propose a manufacturing-operation team and equipment-procurement and qualification plan | Validated commercial-grade cell-therapy ecosystem, CDSCO-approved CAR-T production history, and at least 3 years of cGMP CAR-T manufacturing experience | Qualified Indian CAR-T manufacturing operators |
| Sustainable medicines-manufacturing process development | Innovate UK competition opened October 5, 2026; applications due December 2, 2026 | UK medicines-manufacturing businesses and collaborative projects | Build a sustainability-focused project with a UK-registered SME claiming funding | Competitive selection; UK execution and intended UK exploitation; start at technology readiness level 6 or above and advance at least 2 levels | UK CDMOs such as OXB in qualifying consortia |
| Additional EU critical-medicine and API manufacturing capacity | October 19, 2026 work program indicated a planned Q4 2026 call | EU enterprises manufacturing Union-listed critical medicines or their active substances | Propose net capacity creation, expansion, or modernization rather than relocation within the Union | Union-listed products, demonstrated supply vulnerability, viable long-term Union supply, and competitive selection | Recipharm AB and Aenova Holding GmbH for qualifying EU projects |
| Source: Mordor Intelligence | |||||
Faridabad is the only one of these openings that procures an operator for an existing facility. The UK competition and planned EU call instead fund projects that applicants must design and win through competitive selection. An operator’s documented CAR-T production history and equipment-qualification plan determine whether its bid addresses the Faridabad facility’s execution requirements.
Recent Industry Developments in Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market
- Oct 2026: Aragen Life Sciences began operating its OneHP high-potency development and manufacturing platform at its Nacharam campus in Hyderabad, India.
- Sep 2026: ESTEVE CDMO approved an additional USD 17.5 million expansion of small-molecule API capacity and containment capabilities at Morton Grove, Illinois.
- Sep 2026: Hovione opened 89 Twin Rivers, a 31,000-square-foot facility in East Windsor, New Jersey, expanding US spray-drying capacity for spray-dried amorphous solid dispersions.
Pharmaceutical Contract Development And Manufacturing Organization (CDMO) Market Report Scope and Research Methodology
Market Definition and Coverage
The pharmaceutical contract development and manufacturing organization (CDMO) market measures annual global spending on outsourced pharmaceutical development, manufacturing, and secondary packaging services performed by CDMOs for pharmaceutical and biotechnology sponsors. It covers contracted work across active pharmaceutical ingredients and finished dosage forms.
Scope exclusions: In-house pharmaceutical or biotechnology development and manufacturing, finished pharmaceutical product and vaccine sales, separately sold pharmaceutical manufacturing inputs and materials, and separately sold manufacturing equipment and facility construction are excluded.
Segments Covered in This Report
- By Service Type
- API Manufacturing
- Small Molecule
- Large Molecule
- High-Potency (HPAPI)
- FDF Development and Manufacturing
- Solid Dose
- Liquid Dose
- Injectable Dose
- Secondary Packaging
- API Manufacturing
- By Molecule Type
- Small Molecule
- Large Molecule (Biologics and Biosimilars)
- High-Potency APIs
- By Dosage Form
- Solid Oral
- Sterile Injectables
- Topicals and Transdermals
- Specialty/Novel (e.g., ODT, Long-acting)
- By Therapeutic Area
- Oncology
- Metabolic and Endocrine
- Cardiovascular
- CNS and Psychiatry
- Infectious Diseases and Vaccines
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public references such as the World Health Organization's landscape report on pharmaceutical production and technology transfer, its global vaccine manufacturing and procurement analysis, and its Kenya health-products manufacturing strategy provide context on regional production capability, capacity expansion, and technology transfer. European Medicines Agency guidance on outsourced activities and ICH Q7 explains contract responsibilities and controls for outsourced API work. How these sources describe manufacturing stages, outsourced obligations, and regional capacity is used to interpret the market boundary and select indicators, rather than treating them as direct estimates of total CDMO contract revenue.
Which companies disclose CDMO revenue, service mix, facility investment, customer commitments, site launches, or capacity changes is checked through annual reports, regulatory filings, investor presentations, and reputable industry and financial press. Analysts compare those disclosures with public manufacturing and regulatory information and investigate differences in reporting periods or business definitions before using them as corroboration. These named sources are not exhaustive, and further sources inform collection, validation, and clarification.
Primary Interviews and Surveys
Interviews and structured questionnaires would be directed to CDMO executives, commercial and site leaders, and sponsor-side procurement, technical operations, and supply-chain managers across APAC, EMEA, and the Americas. Respondents would review secondary-source interpretations of outsourced scope, service-line demand, regional capacity, and forecast drivers, while questions would target gaps in contract structure, utilization, pricing, and pipeline conversion. Analysts would compare responses with company disclosures and regulatory or capacity signals, record unresolved differences, and seek follow-up clarification where a material input remains inconsistent.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 32% | CXOs: 20% | APAC: 40% |
| Mid tier: 43% | Functional/Unit leaders: 38% | EMEA: 27% |
| Smaller Players: 25% | Managers: 42% | Americas: 33% |
Market-Sizing & Forecasting
The model estimates annual global CDMO contract and service revenue in USD, counting a bundled end-to-end assignment once and classifying it across service, molecule, dosage form, therapeutic area, and geography. A top-down estimate begins with pharmaceutical sponsors' external development and production activity and the share handled by specialist providers, then tests the resulting total against selective supplier revenue roll-ups and sampled service revenue estimates. Relevant indicators include sponsor outsourcing commitments, clinical pipeline activity as a leading signal for development work, disclosed CDMO revenue and service mix, announced site capacity and utilization changes, and regional manufacturing and regulatory activity. Each indicates demand, conversion timing, provider supply, or geographic availability rather than market value by itself. Segment shares are built from reported supplier service mix, contract and site capabilities, sponsor program profiles, and regional footprints, with classifications applied consistently so the same contract revenue is not added twice. Scenario analysis carries these indicators into 2027-2032 forecasts by service, molecule, dosage form, therapeutic area, and region, while sponsor-side and CDMO-side respondents can check the assumptions behind each input and the timing of pipeline conversion. Where supplier roll-ups or sampled price-times-volume checks lack coverage, analysts retain their observed range as a cross-check and reconcile it with disclosed revenue and market-level demand evidence before setting the estimate.
Data Validation & Update Cycle
Analysts triangulate the modeled total and segment views against supplier filings, sponsor outsourcing announcements, regulatory and capacity signals, and relevant production indicators. They investigate anomalies such as abrupt share shifts, inconsistent units, duplicate end-to-end revenue, and differences between recognized revenue and announced capacity, then document and resolve variances through a second analyst review before sign-off. Follow-up with relevant respondent types is triggered when a material input conflicts with new filings, site changes, or another independent signal. The model is refreshed annually, revised between cycles after material events, and given a fresh pre-delivery review.
Mordor Intelligence's Pharmaceutical Contract Development and Manufacturing Organization Cdmo Market Estimate Compared With Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The pharmaceutical contract development and manufacturing organization (CDMO) market measures annual global spending on outsourced pharmaceutical development, manufacturing, and secondary packaging services performed by CDMOs for pharmaceutical and biotechnology sponsors.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The model estimates annual global CDMO contract and service revenue in USD, counting a bundled end-to-end assignment once and classifying it across service, molecule, dosage form, therapeutic area, and geography.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 292.7 B (2027) | |
| Global Consultancy A | USD 166 B (2025) | At its 2025 base, this estimate is 43.3% below this report's 2027 value of USD 292.7 B, 2 years later. Its published 2025 base predates the report's 2027 comparison year and does not include the intervening years of market growth. |
| Global Consultancy B | USD 173.7 B (2025) | At its 2025 base, this estimate is 40.7% below this report's 2027 value of USD 292.7 B, 2 years later. Its published 2025 base predates the report's 2027 comparison year. Its additional regulatory and related technical services would broaden coverage, so that scope difference does not account for its lower value. |
Mordor Intelligence's analysts triangulate the modeled total and segment views against supplier filings, sponsor outsourcing announcements, regulatory and capacity signals, and relevant production indicators.
Key Questions Answered in the Report
What is the pharmaceutical contract development and manufacturing organization (CDMO) market size and growth outlook?
The size is projected at USD 292.7 billion in 2027 and USD 403.3 billion by 2032, registering a CAGR of 6.62% between 2027 and 2032.
What drives demand for outsourced pharmaceutical manufacturing?
Long-term commercial outsourcing and complex-therapy development support demand. GSK renewed its 5-year Bora Pharmaceuticals manufacturing partnership in February 2026.
Which service segment leads pharmaceutical contract manufacturing?
API manufacturing led with 54.64% of pharmaceutical CDMO revenue in 2026. FDF development and manufacturing has the fastest forecast CAGR of 7.45% between 2027 and 2032.
Which companies compete in pharmaceutical development and manufacturing services?
Major providers include Catalent Inc., Recipharm AB, Jubilant Pharmova Ltd., Thermo Fisher Scientific Inc. (Patheon), and Boehringer Ingelheim Group.
What can constrain fulfillment in outsourced pharmaceutical manufacturing?
US import detention and limited production headroom can constrain outsourced supply. Zenzi’s Indian establishment remained on FDA’s inspection-refusal Import Alert 66-79 in September 2026.
Which regions lead pharmaceutical contract manufacturing?
North America led with 37.88% of pharmaceutical CDMO revenue in 2026. Asia-Pacific is forecast to register the fastest regional CAGR of 7.6% between 2027 and 2032.