
Market Overview
| Study Period | 2019 - 2031 |
|---|---|
| Market Size (2026) | USD 10.65 Billion |
| Market Size (2031) | USD 15.16 Billion |
| Growth Rate (2026 - 2031) | 7.32 % |
| Fastest Growing Market | Asia-Pacific |
| Largest Market | Asia-Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Electric Motors For Electric Vehicles Market Analysis by Mordor Intelligence
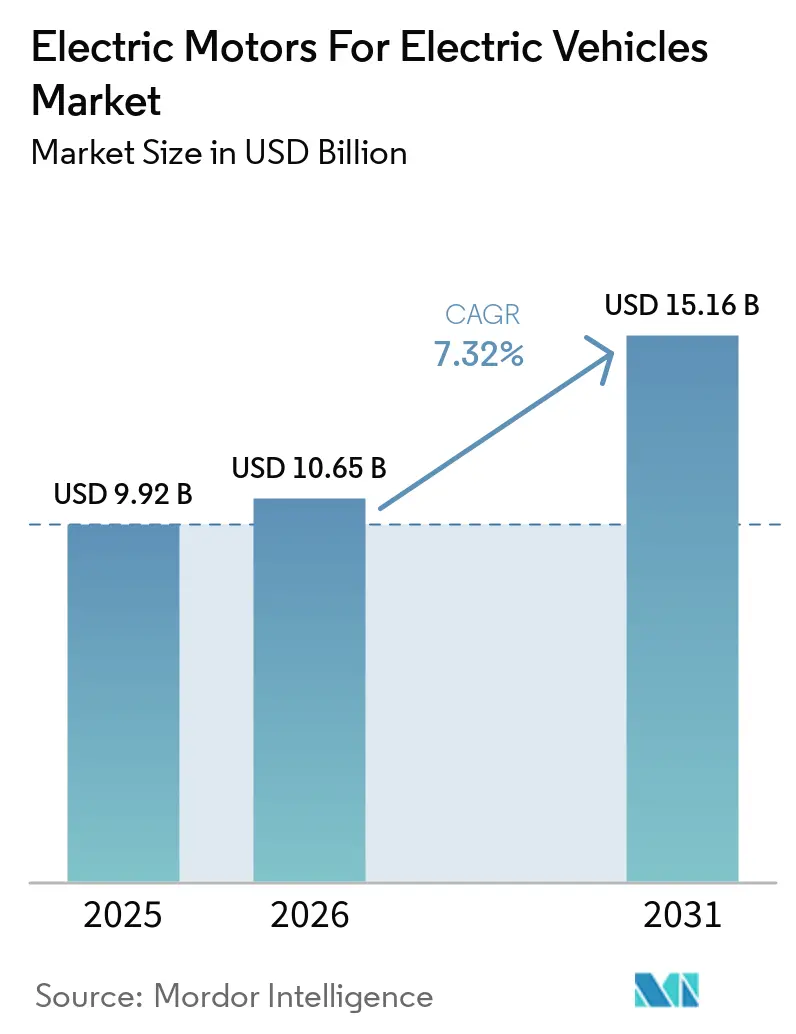
The electric motors for electric vehicles market size was valued at USD 9.92 billion in 2025, is estimated at USD 10.65 billion in 2026, and is projected to reach USD 15.16 billion by 2031, growing at a CAGR of 7.32% from 2026 to 2031. Permanent magnet synchronous motors remain central to passenger vehicle programs because automakers value power density and thermal efficiency. At the same time, rare-earth supply disruption is making motor sourcing, magnet access, and localized production more important in supplier selection. The move toward 800V vehicles and integrated e-axles favors suppliers that can combine motors, inverters, gearboxes, cooling, and calibration work. Battery electric vehicles remain the main source of demand, while policy flexibility has preserved a role for plug-in hybrid designs. The EV motors market is therefore shaped by vehicle production growth, evolving propulsion choices, and suppliers' ability to manage material risk without sacrificing system performance.
Key Report Takeaways
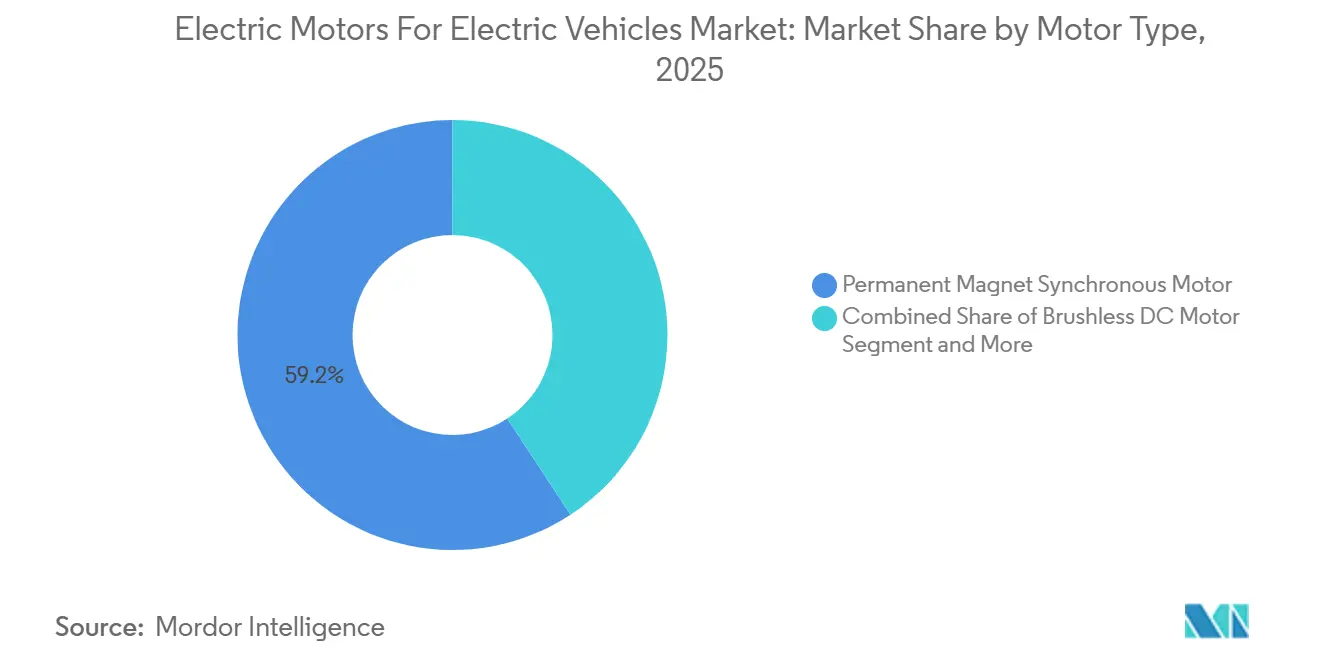
- By motor type, permanent magnet synchronous motors held 59.24% of the EV motors market share in 2025, while AC induction motors are forecast to grow at a 9.92% CAGR through 2031.
- By vehicle class, passenger cars accounted for 51.12% of the EV motors market share in 2025, while two-wheelers are forecast to grow at a 15.22% CAGR through 2031.
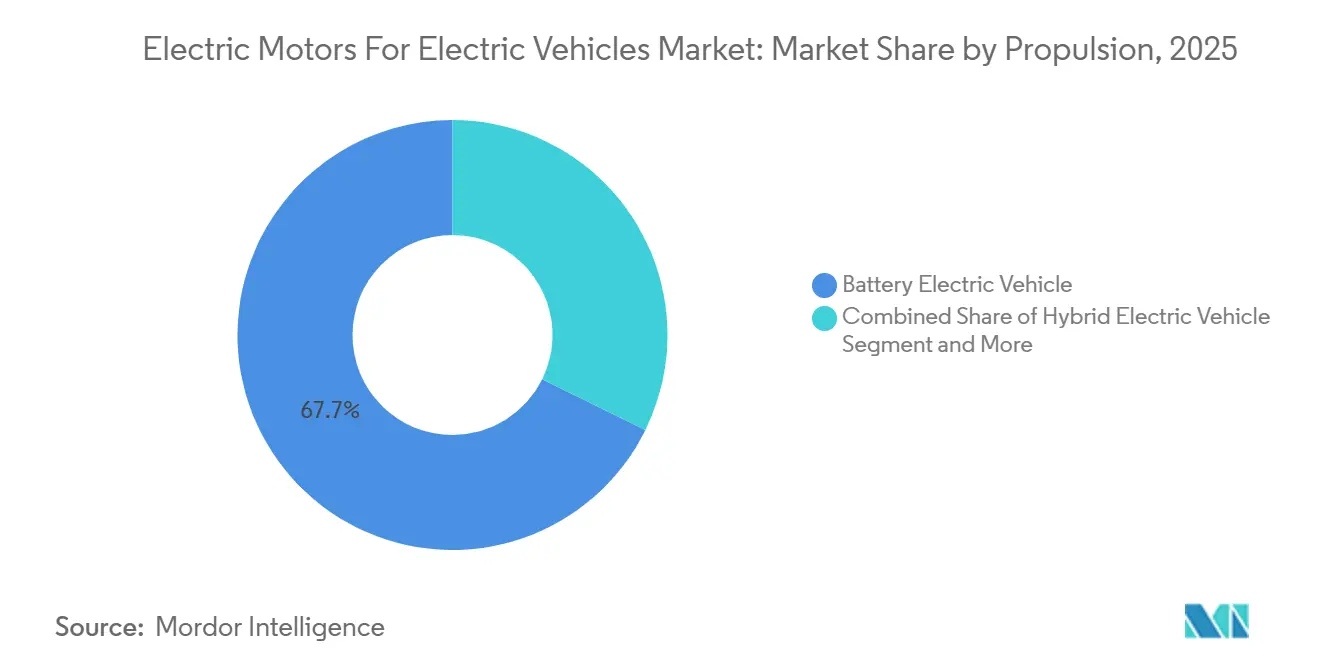
- By propulsion, battery electric vehicles held 67.72% of the EV motors market share in 2025, while plug-in hybrid electric vehicles are forecast to grow at an 8.81% CAGR through 2031.
- By power output, the 200–400 kW range accounted for 56.83% of the EV motors market share in 2025, while motors above 400 kW are forecast to grow at a 10.62% CAGR through 2031.
- By geography, Asia-Pacific held 52.53% of the EV motors market share in 2025 and is forecast to grow at a 9.11% CAGR through 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of January 2026.
Market Trends and Insights
Drivers Impact Analysis of Electric Motors For Electric Vehicles Market*
| Driver | (~) % Impact on CAGR Forecast | Geography Relevance | Impact Timeline |
|---|---|---|---|
| Rising EV Production and Sales | +2.1% | Global | Short term (≤ 2 years) |
| Tightening Emissions Regulations and Electrification Incentives | +1.3% | EU, China, US, South Korea | Medium term (2-4 years) |
| Demand for Higher Efficiency, Power Density, and Vehicle Range | +0.9% | Asia-Pacific core, EU, North America | Medium term (2-4 years) |
| Growth of Integrated E-Axles and Multi-Motor Platforms | +0.7% | Asia-Pacific, EU, North America | Medium term (2-4 years) |
| Rare-Earth-Reduced Motor Design and Localized Supply Chains | +0.6% | North America, EU, India, Asia-Pacific demand-side | Long term (≥ 4 years) |
| Commercial EV Duty-Cycle Electrification | +0.5% | Asia-Pacific core, China, EU | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Ramping Electric Vehicle Sales and Regional Policies
Global electric vehicle sales exceeded 20 million units in 2025 and represented 20% of new passenger car sales, according to the International Energy Agency [1]. China accounted for more than 55% of global EV sales, giving the country the largest pool of motor purchasing demand. The EV motors market also has a separate source of demand in India and Southeast Asia, where two-wheelers and three-wheelers use lower-power motor systems. This demand does not follow the same product requirements as European passenger car programs. India’s electric two-wheeler retail sales surpassed 1.4 million units in FY2026, supported by FAME III and PM E-Drive measures. Suppliers, therefore, need portfolios that cover both hub motors below 5 kW and high-power commercial e-axle systems above 400 kW.
Tightening Emissions Regulations and Electrification Incentives
EU regulations establish fleet-average emissions targets for new passenger cars over the near and longer term. Under the EU climate framework, regulations require complete emissions reductions for new passenger cars [2]. China’s Dual Credit Policy links new energy vehicle credits to internal-combustion vehicle production rights, supporting EV production volumes. A planned EU revision would allow limited flexibility in meeting future emissions targets through low-carbon fuels, thereby preserving a commercial role for PHEV drivetrains in the near term. This policy environment supports compact motor configurations and aligns with the projected growth of PHEVs. Established Tier-1 suppliers also benefit, as functional safety requirements increase the engineering threshold for motor control systems.
Demand for Higher Efficiency, Power Density, and Vehicle Range
Passenger and commercial vehicle buyers increasingly prioritize driving range and sustained high-power performance. BMW has begun series production of its next-generation motors at Plant Steyr, using high-voltage architecture and silicon carbide power electronics. Compared with its previous-generation system, BMW reported lower energy losses and costs, while Neue Klasse models are designed to deliver an extended WLTP range. Higher-voltage motors require advanced insulation materials, such as PEEK or PAI, increasing material and manufacturing requirements. MAHLE introduced its MCT motor for heavy trucks, which delivers high peak output and high efficiency under the VECTO cycle. The design also reduces the use of rare-earth magnets and system weight, demonstrating that manufacturers can improve efficiency while reducing material exposure.
Growth of Integrated E-Axles and Multi-Motor Platforms
Integrated e-axles combine the motor, inverter, gearbox, and thermal system into a single assembly. This approach changes the EV motors market because system capability matters more than a motor sold as a standalone component. Nidec began mass production of its third-generation 7-in-1 e-axle in 2025, according to the supplied research. Turntide Technologies presented a commercially validated axial-flux electric drive unit at CONEXPO-CON/AGG in February 2026. The assembly combines a motor, gearbox, and inverter, thereby shortening OEM validation work. Multi-motor vehicles also increase motor content per vehicle, as illustrated by the three axial-flux motors used in the supplied example of the all-electric Mercedes-AMG CLA 45.
Restraints Impact Analysis of Electric Motors For Electric Vehicles Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rare-Earth Magnet Price and Supply Volatility | -1.6% | Global, acute in EU, US, India | Short term (≤ 2 years) |
| High Capital Intensity for Precision Motor Manufacturing | -1.4% | Global, with acute impact on North America, EU, India new entrants | Long term (≥ 4 years) |
| NVH, Thermal-Derating, and Durability Trade-Offs at High Power | -0.8% | Asia-Pacific core, EU premium segment | Medium term (2-4 years) |
| Platform Integration and Interoperability Constraints | -0.5% | North America, EU | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rare-Earth Magnet Price and Supply Volatility Constraining PMSM Scale
China’s export controls on key rare-earth materials disrupted supplies of high-temperature PMSM magnets. Chinese magnet exports subsequently declined significantly, affecting production at Ford, BMW, Suzuki, and Stellantis. China dominates global sintered permanent magnet production, while rare-earth-containing designs account for the majority of global EV motors. Buyers sourcing magnets outside China faced premiums above Chinese benchmark prices, and NdPr oxide prices increased substantially in some cases. Energy Fuels validated U.S.-mined NdPr oxide for use in high-temperature EV drivetrain magnets; however, downstream processing and sintering capacity remain concentrated in China.
High Capital Intensity Limiting Competitive Entry in Precision Motor Segments
Precision motor production requires specialized winding lines, stator impregnation equipment, automated assembly systems, and rigorous quality-control processes. OEM-grade production lines require substantial capital investment. Manufacturers also need to meet extensive qualification requirements before generating significant customer revenue. IATF quality requirements and ISO functional safety processes further increase costs and favor established manufacturers.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Electric Motors For Electric Vehicles Market Segment Analysis
By Motor Type:
PMSM Leadership Faces a Supply-Chain ShiftPermanent magnet synchronous motors held 59.24% of the EV motors market share in 2025. Their lead reflects high power density and strong efficiency in passenger car applications. Brushless DC motors are used in many two-wheeler and auxiliary-system applications. They use simpler control electronics and retain a cost advantage below 10 kW. Switched reluctance motors and other types remain smaller categories. Torque ripple and acoustic concerns have limited their use in premium passenger cabins.
AC induction motors are the fastest-growing motor type, with a projected 9.92% CAGR through 2031. Export controls have prompted OEMs and Tier-1 suppliers to reassess motor designs that rely on NdFeB magnets. Induction motors eliminate direct dependence on these magnets, although they may deliver lower efficiency under partial-load conditions. Magnet-free motor technologies offer an alternative for heavy-duty applications. Rare-earth-free drive designs can also support cost-effective electrification. Consequently, the EV motors market may see more magnet-free platform awards, particularly in commercial vehicles and emerging markets.

By Vehicle Class:
Two-Wheelers Reflect Distinct Mobility EconomicsPassenger cars held 51.12% of the EV motor market share in 2025. Their motor choices generally prioritize performance, range, and efficient operation. Two-wheelers are the fastest-growing vehicle class at a 15.22% CAGR through 2031. India, Vietnam, and Indonesia are the leading sources of this demand in the supplied research. In the sub-5 kW range, EV ownership costs can undercut comparable internal-combustion models. Commercial vehicles are also becoming more important as fleet buyers move to electric buses and trucks.
EU regulations support the transition of city buses toward zero-emission operation. Three-wheelers are in high demand in South Asia and Southeast Asia, where policy support promotes commercial electric vehicles. Hub motors are widely used in two-wheelers because they eliminate the mechanical transmission and reduce overall system weight. They also enable the retrofit electrification of internal-combustion-engine two-wheelers. Off-road and specialty vehicles provide suppliers with an additional application area for high-torque commercial motor designs. The EV motors industry requires dedicated hub-motor engineering, as these requirements do not readily carry over from passenger-car e-axle programs.
By Propulsion:
BEVs Remain the Structural MajorityBattery electric vehicles accounted for 67.72% of the EV motor market share in 2025. Their position reflects mature long-range vehicle architectures in China and a broader model range in Europe. Plug-in hybrid electric vehicles are projected to grow fastest, at an 8.81% CAGR through 2031. Regulatory revisions reinforced the continued role of PHEVs. PHEV platforms require compact, high-power-density motors that fit within limited packaging space, sustaining demand for P2 and P4 motor placements.
BorgWarner secured a P2 eMotor award from a Chinese OEM for global PHEV platforms. The program incorporates S-winding technology and is scheduled to begin production. Hybrid electric vehicles continue to generate meaningful demand in Japan and Southeast Asia as a lower-cost transition option. Fuel-cell electric vehicles remain a small segment, primarily serving heavy-duty vehicles and transit buses in Japan, South Korea, and China. BEVs are expected to maintain their lead. However, suppliers with hybrid motor capabilities may benefit from faster growth in PHEV platforms than suppliers focused exclusively on BEVs.
By Power Output:
Mid-Range Motors Lead, While Heavy-Duty Demand BuildsThe 200–400 kW range accounted for 56.83% of the EV motors market share in 2025. This power band serves mainstream passenger cars and light commercial vehicles. It balances power, thermal management requirements, and system cost. The 100–200 kW range serves mid-range passenger cars and urban delivery fleets. Motors below 100 kW cover two-wheelers, three-wheelers, and light utility vehicles. These smaller systems generate lower revenue per unit but substantial volume in India and China.
Motors above 400 kW are projected to record a 10.62% CAGR through 2031. Electric buses, long-haul trucks, and high-performance vehicles are the primary sources of demand. These applications require sustained power output, thermal endurance, and robust regenerative braking capability. Specialized electric motor systems incorporate advanced cooling technologies to support the demanding duty cycles of buses, trucks, and intercity coaches. Higher revenue per unit than in the mainstream passenger vehicle segment supports the EV motors market for high-power applications.
Geography Analysis
APAC Electric Motors for Electric Vehicles Market
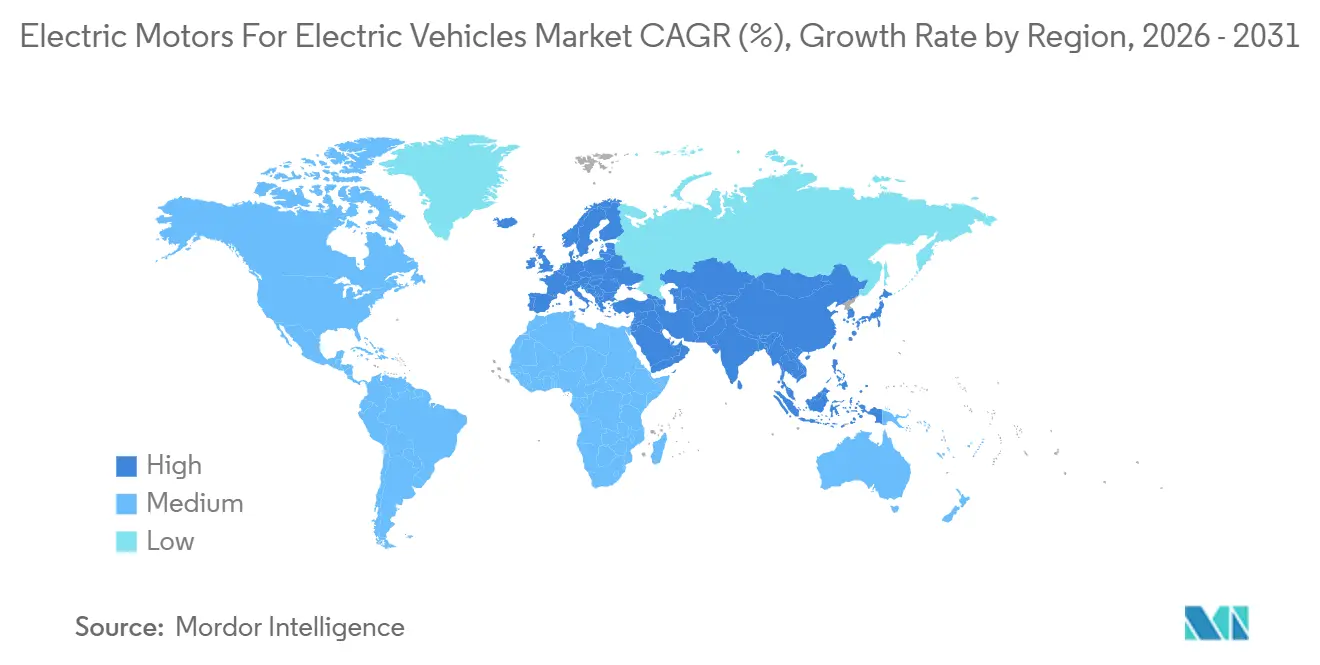
Asia-Pacific held 52.53% of the EV motors market share in 2025 and is projected to grow at a 9.11% CAGR through 2031. China serves as both a major consumption center and a key supplier of rare-earth materials and permanent magnets. Its export policies can affect the costs and availability of permanent magnet synchronous motors (PMSMs) across the EV motor market. China also leads global sales of electric medium- and heavy-duty trucks. India represents an important secondary growth center, supported by the expansion of its two- and three-wheeler segments and localized manufacturing programs.
Europe Electric Motors for Electric Vehicles Market
Nidec has established its Orchard Hub campus in Hubli. India has extended the PM E-Drive program and relaxed traction motor localization timelines in response to a magnet shortage. Japan and South Korea support demand for premium vehicles and advanced motor technologies. BorgWarner has received a stator assembly award for a South Korean B-segment SUV. Europe follows a more regulation-driven demand pattern, as EU CO2 regulations require OEMs to expand their BEV and PHEV offerings, thereby supporting sustained motor procurement.
The Americas and EMEA Electric Motors for Electric Vehicles Market
BMW’s Steyr facility has become a high-voltage supply hub following the start of Gen6 motor production. YASA has opened an upgraded facility in Yarnton, expanding its production capacity. North America is expanding commercial EV motor production capacity and developing domestic rare-earth supply capabilities. BorgWarner has secured an award for an integrated drive module for REEV trucks and large SUVs. South America, the Middle East, and Africa remain early-stage markets. These regions primarily source imported motor assemblies and remain price-sensitive, while Brazil demonstrates interest in PHEVs, and Middle Eastern fleet programs generate initial demand from the logistics sector.
Competitive Landscape
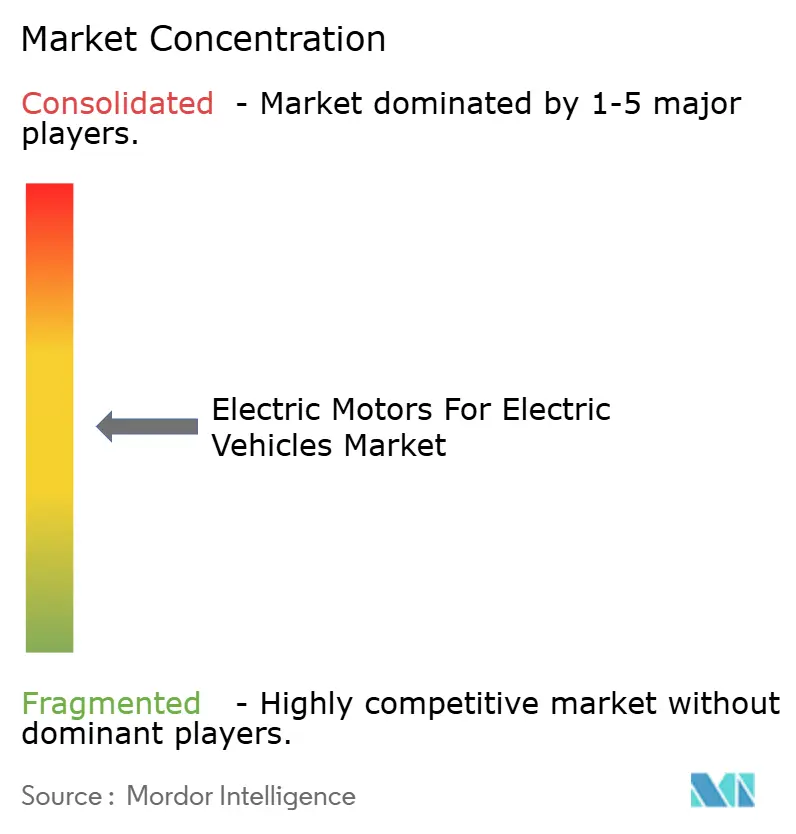
The EV motors market is moderately concentrated at the Tier-1 systems level. Nidec, BorgWarner, ZF Friedrichshafen, Magna International, Robert Bosch, AISIN, Schaeffler, and Valeo are leading suppliers. Tesla and BYD vertically integrate traction motor production, reducing opportunities for independent suppliers. Chinese suppliers, including Jing-Jin Electric Technologies, Shenzhen Inovance, and Shanghai Edrive, compete on cost advantages and local-content capabilities. Western suppliers differentiate through integrated e-axles, high-voltage power electronics, and validated systems engineering. Chinese suppliers have significantly reduced new-model-to-production cycles.
Competitive activity increasingly focuses on hairpin winding, direct oil cooling, and silicon carbide inverter integration. BorgWarner’s S-winding technology and ZF’s AxTrax architecture position both companies strongly in these areas. Magna supplies an eDrive system for Chery from its Wuhu facility. This development highlights the importance of localized production in competing for Chinese OEM programs. Nidec’s China-sourced e-axle for a Toyota electric vehicle platform similarly demonstrates how sourcing decisions influence platform awards. BorgWarner’s awards across China, South Korea, and North America illustrate its focus on regional programs and integrated modules.
Potential opportunities remain in rare-earth-free high-power motors, in-wheel motor systems, and cost-focused integrated drives for small mobility applications. MAHLE positions its MCT platform for rare-earth-free heavy-duty applications. YASA has developed a high-power in-wheel prototype. Protean Electric also competes in the hub motor technology space [3]. Equipmake and Turntide Technologies are pursuing axial-flux opportunities in commercial and off-highway applications. The EV motors market rewards suppliers that combine credible motor designs with capabilities in cooling, inverters, gearboxes, manufacturing, and local sourcing.
Electric Motors For Electric Vehicles Industry Leaders
-
NIDEC CORPORATION
-
BorgWarner Inc.
-
ZF Friedrichshafen AG
-
Magna International Inc.
-
Robert Bosch GmbH
- *Disclaimer: Major Players sorted in no particular order
Electric Motors For Electric Vehicles Market Companies Covered in this Report
- NIDEC CORPORATION
- BorgWarner Inc.
- ZF Friedrichshafen AG
- Magna International Inc.
- Robert Bosch GmbH
- BYD Company Limited
- DENSO CORPORATION
- AISIN CORPORATION
- Schaeffler AG
- Valeo
- Continental AG
- Hitachi Astemo, Ltd.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- Johnson Electric Holdings Limited
- Magna Powertrain
- MAHLE GmbH
- Jing-Jin Electric Technologies Co., Ltd.
- Shenzhen Inovance Technology Co., Ltd.
- Shanghai Edrive Co., Ltd.
- Tesla, Inc.
- YASA Limited
- Equipmake Ltd.
- Protean Electric Limited
Recent Industry Developments in Electric Motors For Electric Vehicles Market
- September 2026: MAHLE premiered the MCT permanent-magnet-free electric motor at IAA Transportation 2026 in Hanover, delivering 370 kW peak output and 95% VECTO-cycle efficiency for heavy commercial vehicles. The design eliminates up to 3 kg of rare-earth magnets per vehicle and reduces complete drive system weight by up to 10 kg versus a comparable PMSM. It directly addresses critical-mineral supply risk for fleet operators.
- August 2026: BorgWarner secured a next-generation integrated drive module contract with a global OEM, with production beginning in 2027. The system features the GenIV Viper D power switch, a next-generation coaxial gearbox, and an oil-cooled motor targeting demanding performance requirements at high power density.
Global Electric Motors For Electric Vehicles Market Report Scope
The Electric Motor for Electric Vehicle Market Report is segmented by motor type, including BLDC, PMSM, AC induction, SRM, and other motors; vehicle class, including 2-wheelers, 3-wheelers, passenger cars, commercial vehicles, and other vehicles; propulsion, including BEV, HEV, PHEV, and FCEV; power output, including less than 100 kW, 100–200 kW, 200–400 kW, and above 400 kW; and geography, including North America, South America, Europe, Asia-Pacific, the Middle East, and Africa. Forecasts are presented in value and volume.
Segmentation Overview
By Motor Type
| Brushless DC Motor |
| Permanent Magnet Synchronous Motor |
| AC Induction Motor |
| Switched Reluctance Motor |
| Other Motor Types |
By Vehicle Class
| Two-Wheelers |
| Three-Wheelers |
| Passenger Cars |
| Commercial Vehicles |
| Off Road and Others |
By Propulsion
| Battery Electric Vehicle |
| Hybrid Electric Vehicle |
| Plug-In Hybrid Electric Vehicle |
| Fuel-Cell Electric Vehicle |
By Power Output
| Less Than 100 kW |
| 100 kW to 200 kW |
| 200 kW to 400 kW |
| Above 400 kW |
By Geography
| North America | United States |
| Canada | |
| Mexico | |
| Rest of North America | |
| South America | Brazil |
| Rest of South America | |
| Europe | Germany |
| United Kingdom | |
| France | |
| Italy | |
| Russia | |
| Rest of Europe | |
| Asia-Pacific | China |
| India | |
| Japan | |
| South Korea | |
| Australia | |
| Rest of Asia-Pacific | |
| Middle East and Africa | South Africa |
| Saudi Arabia | |
| United Arab Emirates | |
| Rest of Middle East and Africa |
| By Motor Type | Brushless DC Motor | |
| Permanent Magnet Synchronous Motor | ||
| AC Induction Motor | ||
| Switched Reluctance Motor | ||
| Other Motor Types | ||
| By Vehicle Class | Two-Wheelers | |
| Three-Wheelers | ||
| Passenger Cars | ||
| Commercial Vehicles | ||
| Off Road and Others | ||
| By Propulsion | Battery Electric Vehicle | |
| Hybrid Electric Vehicle | ||
| Plug-In Hybrid Electric Vehicle | ||
| Fuel-Cell Electric Vehicle | ||
| By Power Output | Less Than 100 kW | |
| 100 kW to 200 kW | ||
| 200 kW to 400 kW | ||
| Above 400 kW | ||
| By Geography | North America | United States |
| Canada | ||
| Mexico | ||
| Rest of North America | ||
| South America | Brazil | |
| Rest of South America | ||
| Europe | Germany | |
| United Kingdom | ||
| France | ||
| Italy | ||
| Russia | ||
| Rest of Europe | ||
| Asia-Pacific | China | |
| India | ||
| Japan | ||
| South Korea | ||
| Australia | ||
| Rest of Asia-Pacific | ||
| Middle East and Africa | South Africa | |
| Saudi Arabia | ||
| United Arab Emirates | ||
| Rest of Middle East and Africa | ||
Key Questions Answered in the Report
What is driving demand for EV motors?
Growth in EV production, emissions rules, and demand for efficient electric drivetrains are the main factors supporting demand through 2031.
Which motor type leads electric vehicle applications?
Permanent magnet synchronous motors held 59.24% share in 2025 because they offer strong power density and efficiency for passenger vehicles.
Why are AC induction motors gaining attention?
AC induction motors are projected to grow at a 9.92% CAGR through 2031 because they avoid rare-earth magnet dependence.
Which vehicle category is growing fastest?
Two-wheelers are forecast to grow at a 15.22% CAGR through 2031, led by demand in India and Southeast Asia.
What role do 800V systems play in electric drivetrains?
800V systems support high-power operation, improved efficiency, and integrated e-axle designs, but they require more demanding insulation and power electronics.