
Active Pharmaceutical Ingredients (API) Market Analysis by Mordor Intelligence
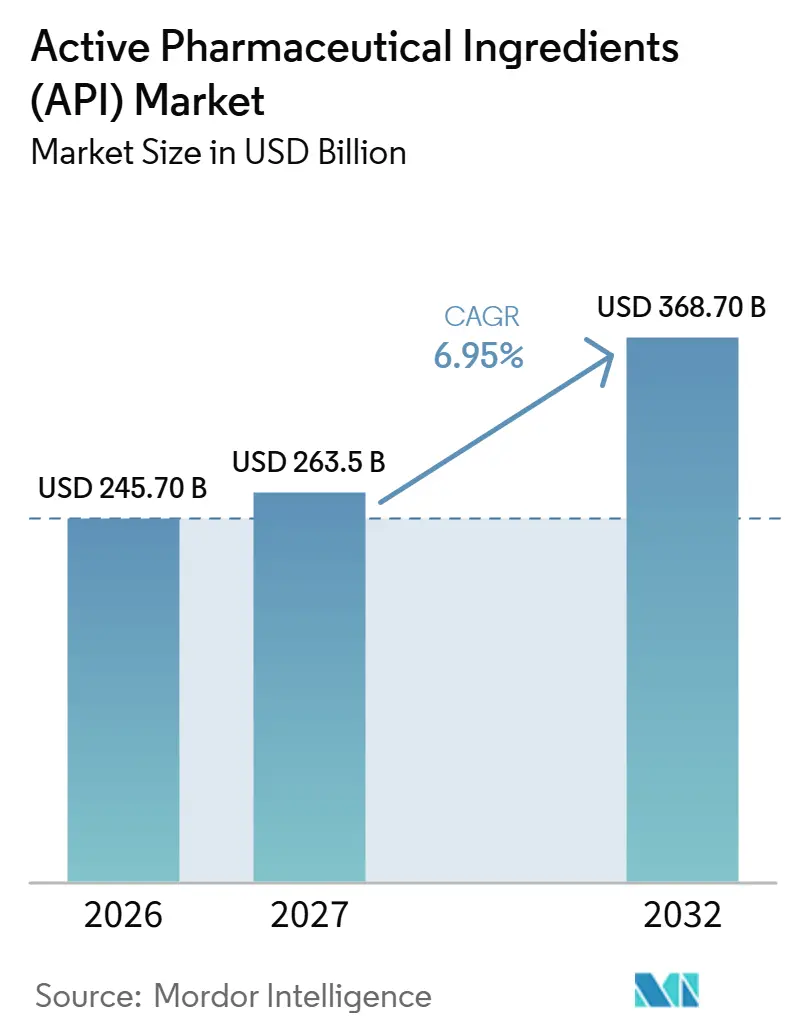
The active pharmaceutical ingredients (API) market size is expected to grow from USD 245.7 billion in 2026 to USD 263.5 billion in 2027 and is forecast to reach USD 368.7 billion by 2032 at 6.95% CAGR over 2027-2032.
The need for chronic-disease medicines and targeted cancer therapies supports ingredient supply, while planned small-molecule investment in the United States could broaden future manufacturing options. External production offers cost-control opportunities, but supplier competition can limit the prices earned on mature APIs. Suppliers can therefore compete through complex chemistry and integrated development, manufacturing and testing to meet commercial medicine programs' technical requirements. EU nitrosamine controls for chemically synthesized APIs reinforce the commercial value of that technical breadth by connecting ingredient specifications with the finished medicine's requirements.
Key Report Takeaways
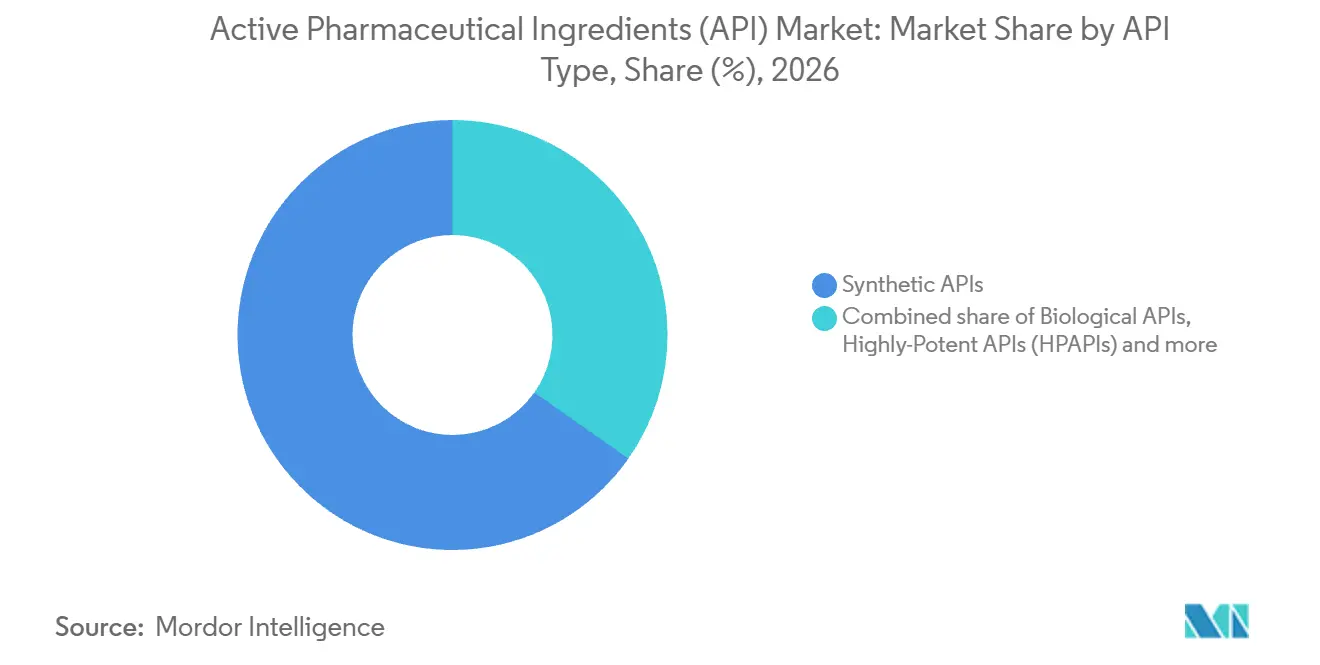
- By API type, synthetic APIs led with a 65.25% active pharmaceutical ingredients (API) market share in 2026, while biological APIs are forecast to grow fastest at 8.92% CAGR over 2027-2032.
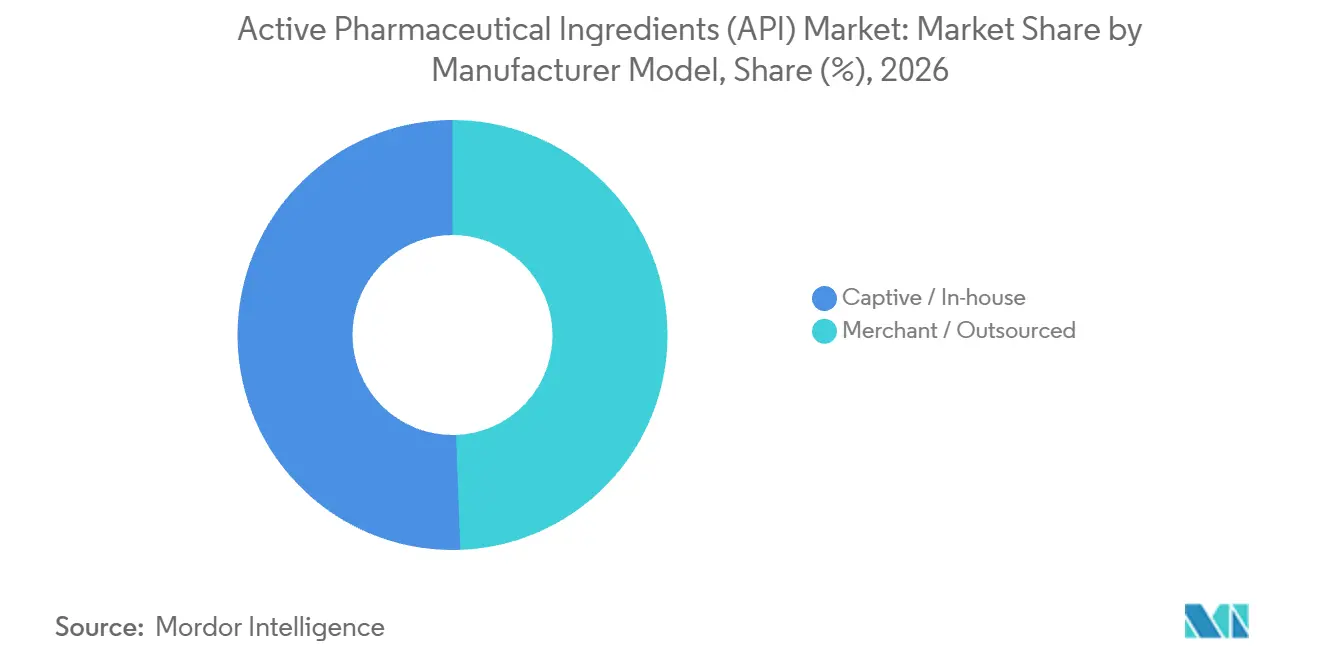
- Within manufacturer models, captive and in-house production led with a 50.58% share of the active pharmaceutical ingredients (API) market size in 2026, and merchant and outsourced manufacturing is forecast to grow fastest at 9.5% CAGR over 2027-2032.
- For molecule size, small molecules led with 56.84% of the market in 2026, and large-molecule and biologic APIs are forecast to grow fastest at 7.8% CAGR over 2027-2032.
- By therapeutic area, cardiovascular applications held the largest share at 27.75% of the market in 2026, while oncology is forecast to grow fastest at 10.3% CAGR over 2027-2032.
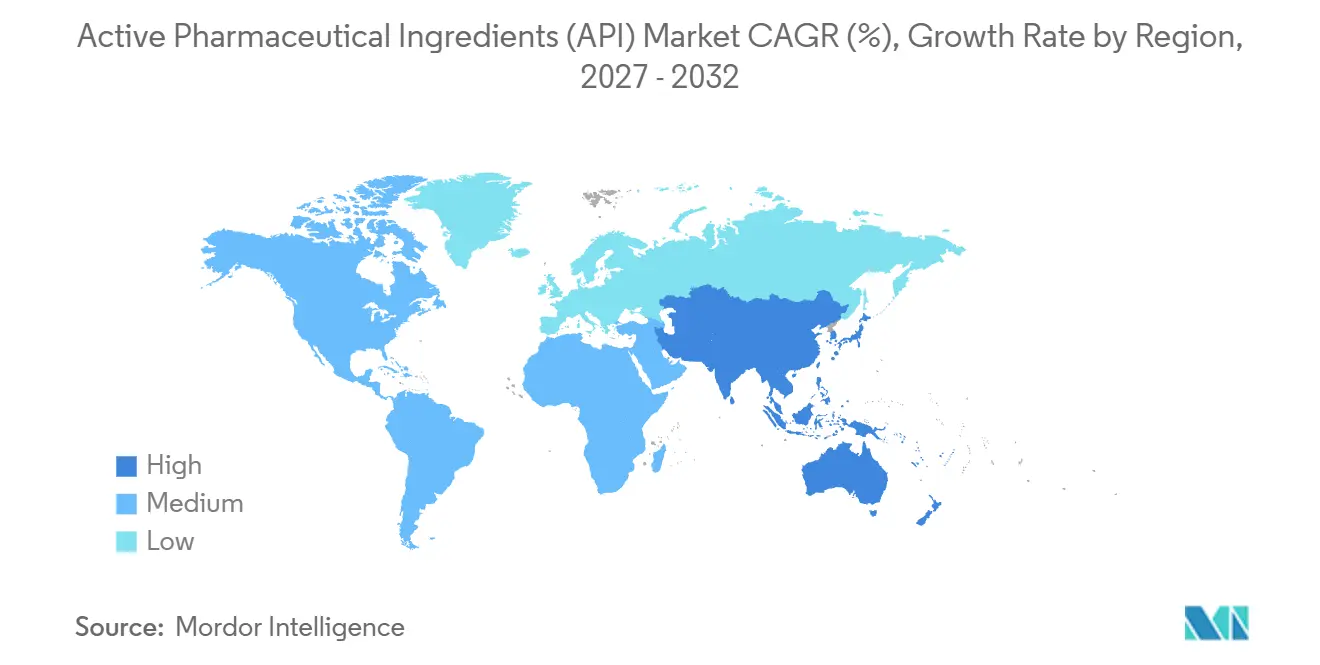
- Geographically, North America led with 39.28% of the market in 2026, and Asia-Pacific is forecast to grow fastest at 10% CAGR over 2027-2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Active Pharmaceutical Ingredients (API) Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Escalating Chronic-Disease Drug Demand | +3% | North America, specifically United States | Short term (≤ 2 years) |
| Biologics & Targeted-Therapy Pipeline Expansion | +2.5% | North America, specifically United States | Medium term (2-4 years) |
| Outsourced Manufacturing Cost Advantages | +1.75% | Asia and European Union | Short term (≤ 2 years) |
| Continuous-Flow & Mini-Plant Technologies Gain Traction | +1.25% | Europe, specifically Belgium | Medium term (2-4 years) |
| Government PLI/On-Shoring Incentives Reshape Clusters | +0.75% | Asia-Pacific, specifically India | Medium term (2-4 years) |
| AI-Enabled Retrosynthesis Cuts Development Cycles | +0.25% | Europe, specifically Switzerland | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Escalating Chronic-Disease Drug Demand
Large treated populations make chronic-disease medicines a substantial source of recurring requirements for their active ingredients. Novo Nordisk reached 42 million people with its diabetes portfolio in 2025, delivering 4% sales growth at constant exchange rates for that portfolio.[1] WHO's 2025 Model Lists added treatments for various cancers and diabetes with associated comorbidities, and the lists serve as a basis for public procurement in over 150 countries. Inclusion can widen the institutional route to treatment, although national procurement decisions determine whether that route becomes additional medicine supply across the API Market. Novo Nordisk recorded DKK 88.47 billion (USD 13.36 billion) in 2025 US sales of Ozempic, its type 2 diabetes medicine, illustrating the commercial scale a single chronic-disease franchise can support for ingredient suppliers.
Biologics & Targeted-Therapy Pipeline Expansion
New treatment indications can extend demand across several active ingredients within a single approved regimen. The FDA approved epcoritamab with rituximab and lenalidomide for relapsed or refractory follicular lymphoma on November 18, 2025, following an international phase 3 trial. Epcoritamab is a T-cell-engaging bispecific antibody. Using the approved combination requires supply of all 3 active ingredients for patients receiving that regimen, creating coordinated sourcing requirements across the API Market. If more eligible patients with relapsed or refractory follicular lymphoma receive the regimen, commercial ingredient demand can increase for the antibody and both companion agents together.
Outsourced Manufacturing Cost Advantages
Supplier competition gives pharmaceutical companies a cost-control mechanism when they place API production with external manufacturers. In its 2025 report, EUROAPI said pharmaceutical companies gain better control over production costs through contracts and competition between API suppliers. The European Commission's 2025 analysis said lower costs for APIs sourced in Asia could help explain generic API production shifting outside the EU. For buyers, contracts can therefore combine supplier comparison with access to a geographically different cost base. Where buyers use external contracts to access that lower cost base, sourcing shifts can channel API orders to Asian merchant producers, influencing supplier competition in the API Market.
Continuous-Flow & Mini-Plant Technologies Gain Traction
Commercial operation makes continuous flow relevant to API supply decisions beyond laboratory route development. Ajinomoto Bio-Pharma Services' Wetteren, Belgium platform has over 15 years of commercial operation across good manufacturing practice (GMP) and non-GMP environments, spanning development through multi-ton commercial supply. Pharmaron offers flow techniques at scales from multiple kilograms to multiple metric tons, including photochemistry, electrochemistry, ozonolysis, and continuous extraction, separation, and distillation for small-molecule drug substances. Wetteren's development-to-commercial operation gives developers a flow route for progressing projects into material supply. As suitable projects enter commercial production, placing their API lots with flow-capable producers can turn development work into recurring manufacturing demand.
Restraints Impact Analysis of Active Pharmaceutical Ingredients (API) Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Rising Global GMP & Nitrosamine-Control Compliance Costs | -1% | European Union member states | Short term (≤ 2 years) |
| Generic-Price Compression Squeezing API Margins | -0.75% | Europe and Asia | Short term (≤ 2 years) |
| Supply-Chain Opacity Fueling Quality-Risk Perception | -0.5% | European Union member states | Short term (≤ 2 years) |
| Complex Global Regulatory Harmonization for Biotech APIs | -0.25% | European Union member states | Medium term (2-4 years) |
| Source: Mordor Intelligence | |||
Rising Global GMP & Nitrosamine-Control Compliance Costs
Nitrosamine control can make the commercial quality requirement for an API depend on its customer's finished medicine. EMA's October 2025 Q&A requires marketing-authorization holders and applicants to ensure robust evaluations by relevant manufacturing authorization holders and API manufacturers for EU human medicines containing chemically synthesized APIs. A given finished product may need additional API tests or tighter limits than the pharmacopeial monograph to control nitrosamine impurities. The Active Pharmaceutical Ingredients Committee's 2025 guidance reported that some API companies faced customer requests to verify very low amine content against historical impurity limits, without a settled convention for reasonable levels. Suppliers can consequently face product-specific verification work beyond a standard ingredient specification, adding a customer-dependent burden to compliant production.
Generic-Price Compression Squeezing API Margins
Mature-API producers face a constraint when competition weakens the price available for each unit of supply. In its 2025 business review, EUROAPI said intensifying competition from Asian manufacturers was increasing price pressure on mature APIs for European producers.[2] Such pressure can limit revenue expansion even when a supplier retains production work, making commercial volume a less reliable guide to earnings potential. In 2026, EUROAPI announced a stronger focus on high-margin complex molecules, with commoditized products to be deprioritized if necessary. For European producers retaining mature APIs, price pressure does not remove the cost of meeting obligations such as EU nitrosamine risk evaluations.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Active Pharmaceutical Ingredients (API) Market Segment Analysis
By API Type:
Scale and Chemistry Expertise Support Synthetic ProductionSynthetic APIs accounted for a 65.25% share of the active pharmaceutical ingredients (API) market size in 2026. WuXi AppTec reported that its small-molecule API reactor volume exceeded 4,000 kiloliters at the end of 2025. Cambrex reported in 2026 that 80% of its customer molecules require advanced chemical expertise. Within the largest segment, production scale and expertise in complex synthesis address different parts of a pharmaceutical developer's needs, connecting manufacturing infrastructure with the chemistry required for its specific molecule. For a producer serving a portfolio like Cambrex's, reactor expansion alone would not resolve the chemistry work required to convert customer projects into manufacturing business.
Biological APIs are forecast to grow at 8.92% CAGR over 2027-2032, making them the fastest-growing segment. As of June 30, 2026, WuXi Biologics' Chengdu commercial drug-substance and drug-product site had reached structural completion and received key equipment. Its microbial-biologics design included a 15,000-liter fermenter and capacity for up to 110 drug-substance batches annually, with GMP release expected by the end of 2026. The stated annual capacity is a ceiling rather than realized output, so its contribution to biological API supply depends on achieving GMP release and then using that capacity.



By Manufacturer Model:
Internal Demand Anchors Captive ProductionCaptive and in-house production represented a 50.58% active pharmaceutical ingredients (API) market share in 2026. In FY2025, Aurobindo Pharma met 52% of its own API requirements internally for finished dosage form manufacturing. The company identifies subsidiary Apitoria Pharma as leading its API business. Within this largest segment, internal ingredient manufacturing connects with the same group's downstream medicine requirements, giving production assets a use tied to finished dosage forms. Captive manufacturing can therefore underpin a formulation business without making the pharmaceutical group fully self-sufficient in its ingredient requirements.
Merchant and outsourced manufacturing is forecast to grow at 9.5% CAGR over 2027-2032, making it the fastest-growing segment. William Blair analysts found that contract development and manufacturing organizations (CDMOs) produced APIs for 73% of drugs approved by the US FDA in 2025. Among small-molecule drugs approved that year, 89% used outsourced API manufacturing. External manufacturing was consequently embedded in many newly approved products, linking contract suppliers with the commercialization pathway for medicines developed by other companies. This creates a growth route through participation in approved therapies, allowing a manufacturing business to gain work as its customers bring medicines through regulatory review and into commercial supply.

By Molecule Size:
Commercial Scale and Project Maturation Shape SupplySmall molecules were the largest segment, accounting for 56.84% of the market in 2026. In March 2026, Wilmington PharmaTech announced a Delaware expansion expected to more than double its API reactor capacity. The plan included 2 new 10,000-liter reactor suites for small-molecule API and peptide production, expected online in Q3 2027. The announced reactor capacity would add to commercial supply only after the planned suites come online. How the suites are deployed between small-molecule and peptide programs will determine the manufacturing work supported by this shared infrastructure.
Large-molecule and biologic APIs are forecast to grow at 7.8% CAGR over 2027-2032, making them the fastest-growing segment. Lonza's Integrated Biologics platform recorded 10% constant-currency sales growth in H1 2026 versus H1 2025. Lonza attributed the platform's performance to maturing growth projects and robust base-business growth. Samsung Biologics' revenue rose 30% in Q2 2026 versus Q2 2025, supported by full utilization of Plants 1 through 4 and favorable exchange rates. An established biologics operation can contribute to revenue growth alongside maturing projects, giving suppliers a commercial growth route before another facility is built.
By Therapeutic Area:
Cardiovascular Scale Meets Oncology ExpansionCardiovascular applications were the largest segment, accounting for 27.75% of the market in 2026. Pfizer reported USD 7.96 billion in worldwide 2025 ELIQUIS (apixaban) revenue. In some regions of Bangladesh, hypertension control improved through 2025 as treatment joined essential health services and screening and follow-up care strengthened. Bangladesh Hypertension Control Initiative facilities procure non-communicable disease medicines through a public fund and systematically refill community-clinic supplies. Systematic refills can sustain recurring ingredient requirements through medicine manufacturers supplying public care, giving cardiovascular API producers a route to demand alongside branded medicine franchises.
Oncology is forecast to grow at 10.3% CAGR over 2027-2032, making it the fastest-growing segment. Johnson & Johnson reported worldwide Q3 2026 DARZALEX (daratumumab) net trade sales of USD 4.24 billion, including its subcutaneous product. On January 27, 2026, the FDA approved DARZALEX FASPRO with bortezomib, lenalidomide and dexamethasone for newly diagnosed adults with multiple myeloma ineligible for autologous stem cell transplant. Medicine revenue establishes a substantial commercial base, while the new indication changes the patient group that can receive a particular regimen. Broader approved use of an existing oncology franchise can consequently create additional manufacturing opportunities around a molecule already linked to commercial medicine supply.
Geography Analysis
North America Active Pharmaceutical Ingredients (API) Market
North America accounted for 39.28% of the active pharmaceutical ingredients (API) market size in 2026. On August 13, 2026, the International Finance Corporation (IFC) signed financing for Neolpharma's Mexico expansion, including acquisition, refurbishment and reactivation of an API plant in Morelos. The broader project also included a third-party injectables facility in Toluca and upgrades at existing sites, with disbursement pending at the August 16 status update. The API component gives the regional manufacturing base an expansion route through asset refurbishment, alongside investment in finished-product services. Commercial value depends on turning the agreed project scope into operating ingredient capacity, so the manufacturing contribution follows execution of the reactivation work.
Asia-Pacific Active Pharmaceutical Ingredients (API) Market
Asia-Pacific is forecast to grow at 10% CAGR over 2027-2032, making it the fastest-growing geography. In 2026, BioDuro's joint venture with Taiwan-based Cenra added 10 GMP API production lines and more than 350,000 liters of reactor capacity to BioDuro's network. The collaboration connects process development with clinical and commercial-scale manufacturing, bringing an established Taiwanese API producer together with a contract research, development and manufacturing business. The added lines let BioDuro pursue later-stage API orders as development projects mature, creating a route for customer relationships to generate additional clinical and commercial manufacturing work in Taiwan.
Within Europe, the Commission's 2025 analysis of the European Directorate for the Quality of Medicines & HealthCare certification database showed EU reliance on external chemical API production sites. In the Middle East & Africa, CAD Middle East Pharmaceutical Industries manufactures APIs in Riyadh, Saudi Arabia. Egypt's Arab API laid a January 2026 foundation stone for an Ain Sokhna factory planned to supply active and inactive ingredients and related materials for local pharmaceutical manufacturing and regional exports. In South America, BNDES approved financing in September 2026 for CYG Biotech, a Grupo Blanver company, to expand API capacity through a planned Indaiatuba, Brazil, unit. The commercial distinction is whether a supplier serves established cross-border production networks or develops local ingredient capacity whose contribution depends on completing planned facilities.
Regional Editions
All regions
Regulatory Framework and Outlook
Selected jurisdictions are compared through manufacturing controls, documentation and market-entry conditions affecting API supply. API batch-record guidance in Germany and Brazil's scoped CADIFA approval requirement create different commercial gates. Ratings assess operating attractiveness for an established API manufacturer supplying human-medicine companies. Manufacturing readiness and the approval pathway can therefore affect different parts of a supplier's route to commercial medicine production.
Regulatory Table of Active Pharmaceutical Ingredients (API) Market
| Decision factor | United States | Germany | India | South Africa | Brazil |
|---|---|---|---|---|---|
| Primary authority | FDA | Competent state authorities | CDSCO and state drug regulators | SAHPRA | ANVISA |
| Key instruments or direction | Drug cGMP baseline under 21 CFR 210.1 | EU GMP Part II; proposed AI Annex 22 | Revised Schedule M API provisions | SAHPRA API Q7 guide adopting ICH Q7 | RDC 359/2020 CADIFA for synthetic and semisynthetic APIs in new, innovator, generic and similar medicines |
| Commercial effect | Manufacturing methods, facilities and controls to assure safety, identity, strength, quality and purity | Batch production records should document production and control of each API batch | Stage-dependent GMP through manufacturing, purification and packaging; appropriately qualified personnel | Medicines-sector manufacturer licensing and ability to comply with applicable GMP | Valid CADIFA for associated medicine-registration or post-approval-change approval; qualifying legacy API registrations continue until expiry or cancellation |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Hardening | No change | No change | No change |
| Source: Mordor Intelligence | |||||
The United States' Medium and No change judgments reflect baseline cGMP, while FDA's June 2026 PreCheck cohort offered voluntary early engagement for selected new pharmaceutical facilities. India's stage-specific GMP and staffing duties and South Africa's licensing and Q7 framework support Medium and No change judgments for these established operating requirements. Germany's Medium rating reflects batch-record guidance, while draft AI Annex 22, consulted on from July to October 2025 and without an announced adoption date, supports prospective Hardening through model selection, training and validation controls for manufacturers that use AI. Brazil's CADIFA gate supports Medium and No change judgments, while ANVISA's planned November 2026 seminar session on revising RDC 359/2020 and updating the CADIFA manual, and the EMA/PIC/S draft Annex 15 consultation scheduled for December 2026, concern policy development rather than new commercial-entry duties.
Value Chain Stages
Value capture is compared across intermediate supply, process development and commercial API production, where different activities support different supplier revenues. BASF supplies chemical intermediates used in pharmaceutical API synthesis. Hikal manufactures APIs and intermediates and provides contract development and manufacturing services to global pharmaceutical partners.[3] EUROAPI combines API sales with services for customer-owned API intellectual property, making the distinction between product earnings and contracted development work commercially relevant.
Value Chain Analysis Table of Active Pharmaceutical Ingredients (API) Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Supply chemical intermediates | Intermediates suppliers such as BASF | Intermediate sales | Intermediate suitability for the intended API synthesis route | Specify route-specific input criteria and qualify alternative sources |
| Develop and scale API processes | API development and manufacturing providers such as Hikal and EUROAPI | Contract development and scale-up services | Scale transition from development to commercial API production | Pair development work with the intended commercial manufacturing process |
| Manufacture and release commercial APIs | API manufacturers such as Hikal and EUROAPI | API sales and contracted manufacturing services | Quality-unit API release responsibility | Coordinate testing evidence with the responsible quality unit |
| Source: Mordor Intelligence | ||||
Integrating development and production can keep scale-up connected to commercial manufacture, where a supplier earns from API sales or contracted services. ICH Q7 assigns API release responsibility and oversight of testing and results to the quality unit, without prescribing who performs the testing. Moving testing work to another party therefore changes the operating arrangement while leaving the producer's release oversight intact.
Competitive Landscape
Market Concentration
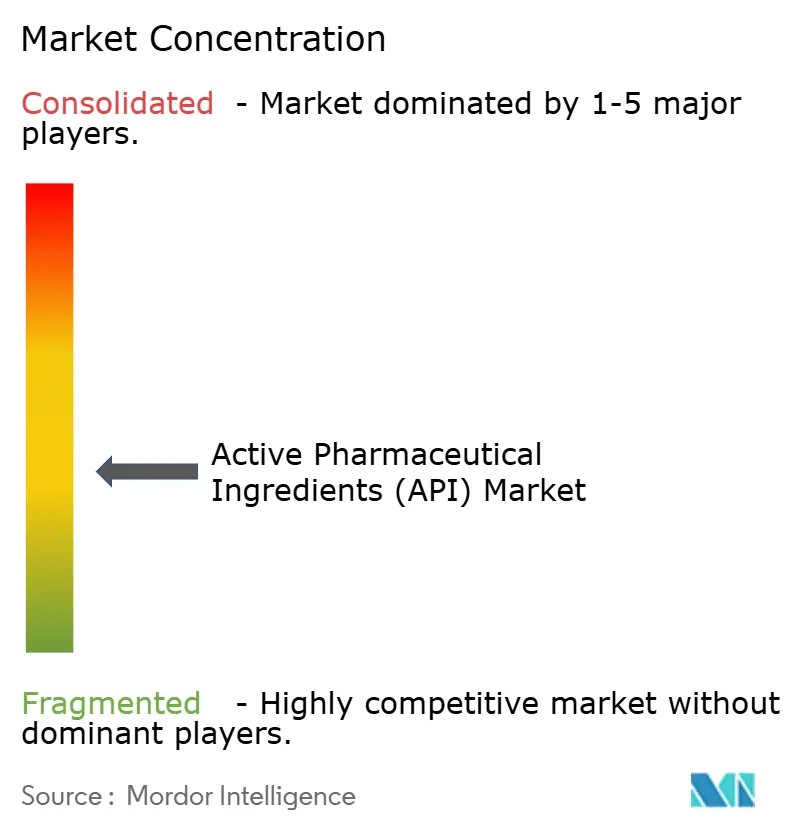
Competition is moderately fragmented across integrated drugmakers, specialized contract manufacturers and producers of selected APIs, with capabilities differing by molecule and service scope. Teva Pharmaceutical Industries reported USD 118 million in third-party API sales in Q2 2026, down 12% from Q2 2025 in both US dollars and local currency. Pfizer CentreOne, Pfizer's CDMO brand with API manufacturing at Kalamazoo, and Merck KGaA, through its Life Science Services unit, compete as contract providers to outside drugmakers. BASF SE supplies APIs including ibuprofen and omega-3 fatty acids, while AbbVie Inc. represents the integrated-drugmaker model. Teva attributed the decline to lower demand from market dynamics and price reductions and reported a July 2026 API-business sales process with no assurance of completion, leaving performance and ownership as open competitive questions.
In March 2026, BASF Pharma Solutions announced a global increase of up to 20% for selected APIs and excipients, effective immediately or as existing contracts allow. In linking the adjustment to rising global energy and raw-material costs, BASF presented it as supporting reliable supply across its portfolio. Such contract conditions can stagger the commercial effect of an adjustment, while the selected-product scope allows variation within a supplier's business. Pricing signals for buyers diverged by supplier in 2026, with Teva's Q2 report citing reductions on third-party APIs alongside BASF's announced increase.
Captive investment and contract services address different buyers and capacity horizons. In February 2026, AbbVie announced USD 380 million for 2 North Chicago API facilities for neuroscience and obesity medicines, with full operation then expected in 2029. Merck KGaA's Life Science Services unit manufactures high-potency APIs through integrated development, manufacturing and testing services from preclinical stages to commercialization. ICH Q7 recommends a risk-based approach for highly active or toxic materials, considering dedicated areas unless validated inactivation or cleaning procedures are established and maintained. Outside drugmakers have a contract route for high-potency APIs through Merck KGaA, while AbbVie's announced expansion addresses its own medicines on a 2029 horizon.
Active Pharmaceutical Ingredients (API) Industry Leaders
-
Teva Pharmaceutical Industries
-
Pfizer CentreOne
-
Merck KGaA
-
BASF SE
-
AbbVie Inc.
- *Disclaimer: Major Players sorted in no particular order
Active Pharmaceutical Ingredients (API) Market Companies Covered in this Report
- Abbvie
- Aurobindo Pharma
- BASF
- Boehringer Ingelheim
- Cambrex
- Catalent
- Cipla
- Dr. Reddy’s Laboratories
- GlaxoSmithKline
- Lonza Group
- Merck
- Novartis
- Pfizer CentreOne
- Piramal Group
- Recipharm
- Samsung Group
- Siegfried AG
- Sun Pharmaceuticals Industries
- Teva Pharmaceutical Industries
- WuXi App Tec
Read Analysis of Active Pharmaceutical Ingredients (API) Companies
Key Opportunities for Market Participants
The opportunities compare commercial API sourcing, manufacturing-equipment renewal and prospective critical-ingredient supply, with different routes to revenue. In July 2026, Evonik announced a 5-year USD 100 million modernization of its multi-customer Tippecanoe small-molecule drug-substance CDMO site in Indiana. The European Commission proposed strategic-project designations and public procurement measures for critical medicines and their ingredients under the Critical Medicines Act in March 2025. Council and Parliament negotiators reached a provisional agreement on May 12, 2026, subsequently approved by Coreper and Parliament's Public Health Committee, with formal adoption by both institutions still required.
Market Opportunities Table of Active Pharmaceutical Ingredients (API) Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| US-based small-molecule contract supply | Planned modernization at an established multi-customer drug-substance site | Pharmaceutical developers seeking external US manufacturing | Qualify existing capabilities and phase any upgrade-dependent supply commitments | Upgrade execution extends over 5 years | Drug-substance CDMOs such as Evonik |
| Equipment and automation integration | Announced renewal of reactors and other critical site systems | Operators of commercial drug-substance facilities | Offer staged equipment and automation integration for operating plants | Coordinating implementation with multi-customer manufacturing | Pharmaceutical equipment and automation providers |
| Resilient EU critical-ingredient supply | Proposed strategic-project and procurement mechanisms | Producers supplying critical-medicine manufacturers | Prepare ingredient projects and supply offers around resilience requirements | Dependence on enactment and implementation of the proposed framework | EU API producers serving critical medicines |
| Source: Mordor Intelligence | |||||
The strongest near-term opening is participation in an established manufacturing operation's renewal, where supply services and equipment work address different commercial needs. A modernization program can create work for both the CDMO and its industrial suppliers as existing production systems are renewed. The EU opportunity has a longer policy dependency because the provisionally agreed strategic-project designations and procurement measures must be formally adopted and implemented before they can underpin awards. Commercial positioning therefore turns on whether the buyer needs execution around an existing plant or preparation for a prospective policy framework.
Recent Industry Developments in Active Pharmaceutical Ingredients (API) Market
- Sep 2026: Eli Lilly and Company broke ground on its USD 6.5 billion Houston site, intended to manufacture Foundayo (orforglipron), other small-molecule medicines and advanced therapeutics, including domestic API production.
- Aug 2026: IFC signed financing for Neolpharma's Mexico expansion, covering Morelos API plant acquisition, refurbishment and reactivation, a planned third-party injectables facility in Toluca and existing-site upgrades. Disbursement was pending on August 16.
- Jul 2026: Evonik announced a 5-year USD 100 million equipment-modernization investment at Tippecanoe Laboratories in Lafayette, Indiana, which manufactures pharmaceutical intermediates, APIs and excipients.
Active Pharmaceutical Ingredients (API) Market Report Scope and Research Methodology
Market Definition and Coverage
The Active Pharmaceutical Ingredients (API) Market measures the annual value of active drug substances produced for human medicines by pharmaceutical manufacturers, including captive production valued at the API production stage. It covers this activity globally.
Scope exclusions: Excipients, finished dosage forms, veterinary APIs, diagnostic reagents, and in-process intermediates are excluded.
Segments Covered in This Report
- By API Type
- Synthetic APIs
- Biological APIs
- Highly-Potent APIs (HPAPIs)
- Natural / Phytochemical APIs
- By Manufacturer Model
- Captive / In-house
- Merchant / Outsourced
- By Molecule Size
- Small Molecule
- Large Molecule / Biologics
- By Therapeutic Area
- Oncology
- Cardiovascular
- Infectious Diseases
- Metabolic Disorders
- CNS & Neurology
- Other Therapeutic Area
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Data Sources, Market Sizing, and Validation
Desk Research
WHO's API prequalification page and prequalified list, EMA's nitrosamine questions and answers, and ICH Q7 provide examples of how supplier quality, GMP status, manufacturing-site requirements, and regulatory documentation can be assessed. These sources also help distinguish active substances and their production controls from finished medicine requirements.
Company annual reports and filings, investor presentations, and reputable industry and financial press can add evidence on capacity, sourcing, investment, pricing, and production plans, which can be checked against public regulatory and company disclosures. These named sources are illustrative and not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Interviews and structured surveys with API manufacturers, contract development and manufacturing providers, pharmaceutical sourcing and technical operations leaders, and regulatory or quality specialists can clarify production values, captive transfer values, and changes in supplier or product mix. Analysts can use respondent evidence to check secondary-source assumptions at the variable and segment level, revisit gaps where definitions or production status are unclear, and triangulate reported capacity or demand signals against public disclosures without treating a single account as a market total.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 35% | CXOs: 20% | APAC: 40% |
| Mid tier: 45% | Functional/Unit leaders: 35% | EMEA: 32% |
| Smaller Players: 20% | Managers: 45% | Americas: 28% |
Market-Sizing & Forecasting
A top-down model estimates global API production value at the ex-factory API stage, then allocates value across API type, manufacturer model, molecule size, therapeutic area, and geography using reported market splits and production evidence. Relevant indicators include pharmaceutical demand by therapy, drug approvals and pipeline activity for biologics and oncology, announced API capacity and utilization, outsourcing activity, and regional production or trade signals. These inform demand, supplier output, and changes in product and regional mix. Segment shares are built from published splits and company production disclosures, with cross-checks against sampled supplier revenue or capacity roll-ups and, where usable, price times volume estimates for selected product groups. Forecasts use the variables' historical movement and stated forward drivers in scenario analysis, with market and segment values kept internally consistent. Analysts review variable-level forecasts with primary respondents to question assumptions and resolve unsupported jumps. Gaps in selective supplier checks are recorded and bounded against company disclosures and regional totals, and are not extrapolated as a complete bottom-up market estimate.
Data Validation & Update Cycle
Analysts triangulate regulatory, company, trade, and market evidence against independent signals such as capacity announcements, filings, and therapeutic demand, then investigate outliers, inconsistent definitions, and material variances between sources before sign-off. A second review checks source dates, units, API-stage treatment, and segment totals. Analysts re-contact relevant respondents when an answer conflicts with a documented source or leaves a material gap. The model is refreshed annually, reviewed between cycles after material regulatory, capacity, or supply events, and given a fresh source and calculation pass before delivery.
Mordor Intelligence's Global Active Pharmaceutical Ingredients API Market Size Compared Against Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The Active Pharmaceutical Ingredients (API) Market measures the annual value of active drug substances produced for human medicines by pharmaceutical manufacturers, including captive production valued at the API production stage.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. Forecasts use the variables' historical movement and stated forward drivers in scenario analysis, with market and segment values kept internally consistent.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 263.5 B (2027) | |
| Global Consultancy A | USD 149.02 B (2026) | At its 2026 base, this estimate is 43.4% below this report's 2027 value of USD 263.5 B, 1 year later. The estimate uses a 2026 base and projects growth through 2031, so its earlier measurement point precedes this report's 2027 value. |
| Global Consultancy B | USD 190.87 B (2026) | At its 2026 base, this estimate is 27.6% below this report's 2027 value of USD 263.5 B, 1 year later. The estimate uses a 2026 base and projects growth through 2032, so its earlier measurement point precedes this report's 2027 value. |
Mordor Intelligence's analysts triangulate regulatory, company, trade, and market evidence against independent signals such as capacity announcements, filings, and therapeutic demand, then investigate outliers, inconsistent definitions, and material variances between sources before sign-off.
Key Questions Answered in the Report
What is the active pharmaceutical ingredients (API) market size and growth outlook?
The market is expected to reach USD 263.5 billion in 2027 and USD 368.7 billion by 2032, with 6.95% CAGR over 2027-2032.
What drives demand for pharmaceutical active ingredients?
Demand is supported by diabetes treatment and targeted cancer therapies. Novo Nordisk reached 42 million people with its diabetes portfolio in 2025, while the FDA approved epcoritamab with rituximab and lenalidomide for relapsed or refractory follicular lymphoma that year.
Which API type holds the largest share?
Synthetic APIs had the largest share at 65.25% in 2026. Biological APIs are forecast to grow fastest at 8.92% CAGR over 2027-2032.
Which companies compete in API production and contract manufacturing?
Teva Pharmaceutical Industries sells third-party APIs, and Pfizer CentreOne provides contract manufacturing. Merck KGaA, BASF SE and AbbVie Inc. contribute specialized services, selected APIs and planned captive investment, respectively.
What challenges can affect API supplier profitability?
EUROAPI reported price pressure on mature APIs for European producers in its 2025 review. Product-specific EU nitrosamine controls can add verification work for chemically synthesized ingredients.
Which regions lead API revenue and forecast growth?
North America led with a 39.28% share in 2026. Asia-Pacific is forecast to grow fastest at 10% CAGR over 2027-2032.