
Elastic Bonding Adhesive And Sealant Market Size and Share
Market Overview
| Study Period | 2020 - 2031 |
|---|---|
| Market Size (2026) | USD 23.29 Billion |
| Market Size (2031) | USD 30.04 Billion |
| Growth Rate (2026 - 2031) | 5.21 % |
| Fastest Growing Market | Asia Pacific |
| Largest Market | Asia Pacific |
| Market Concentration | Medium |
Major Players *Disclaimer: Major Players sorted in no particular order Image © Mordor Intelligence. Reuse requires attribution under CC BY 4.0. | |
Elastic Bonding Adhesive And Sealant Market Analysis by Mordor Intelligence
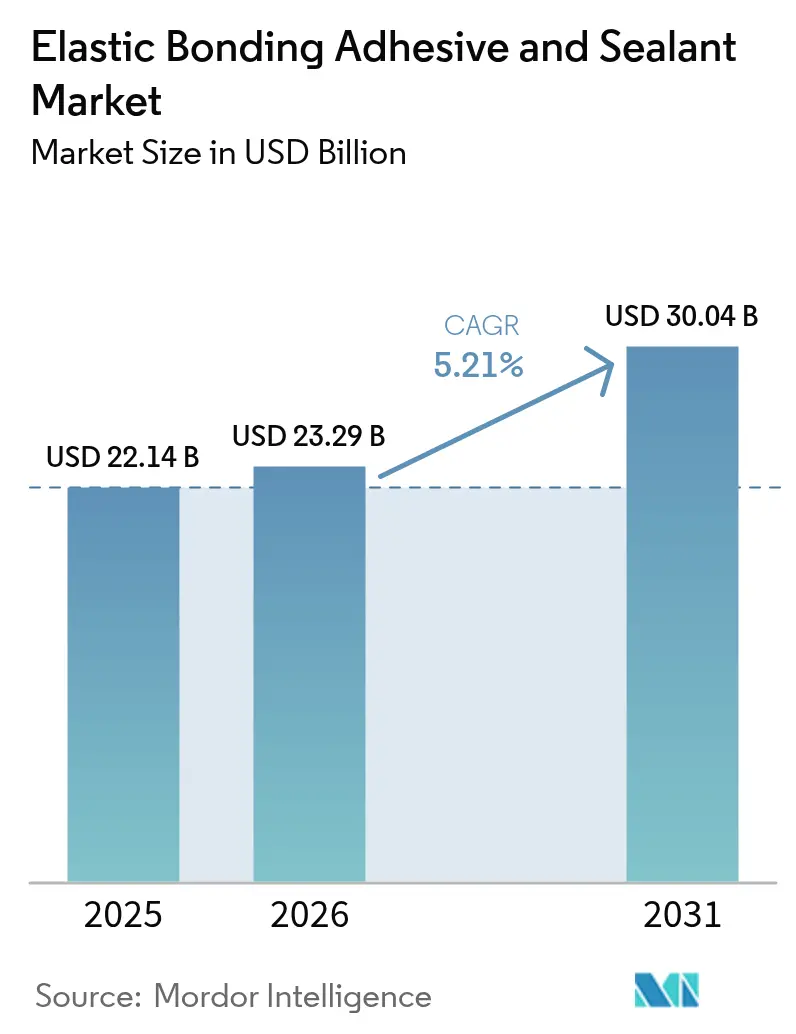
The Elastic Bonding Adhesive And Sealant market size is expected to grow from USD 22.14 billion in 2025 to USD 23.29 billion in 2026 and is forecast to reach USD 30.04 billion by 2031 at 5.21% CAGR over 2026-2031. Growing reliance on lightweight multi-material assemblies, tighter environmental rules, and demand for faster manufacturing cycles continue to steer this growth. Within automotive production, modern vehicles incorporate more than 400 linear feet of adhesive, displacing mechanical fasteners and driving repeat orders from global OEM lines. Construction firms are also shifting toward curtain walls and modular façades that need weather-resistant bonding systems able to tolerate thermal stress and UV exposure. Polyurethane grades remain the most widely specified chemistry, yet silyl-modified hybrids are rising quickly on class-leading VOC performance. Regionally, Asia-Pacific anchors supply chains, attracts fresh capacity for electric-vehicle (EV) battery pack assembly, and delivers the fastest incremental demand for the Elastic Bonding Adhesive and Sealant market. Consolidation among tier-one manufacturers persists, but scores of regional specialists still compete on niche chemistries and custom packaging formats.
Key Report Takeaways
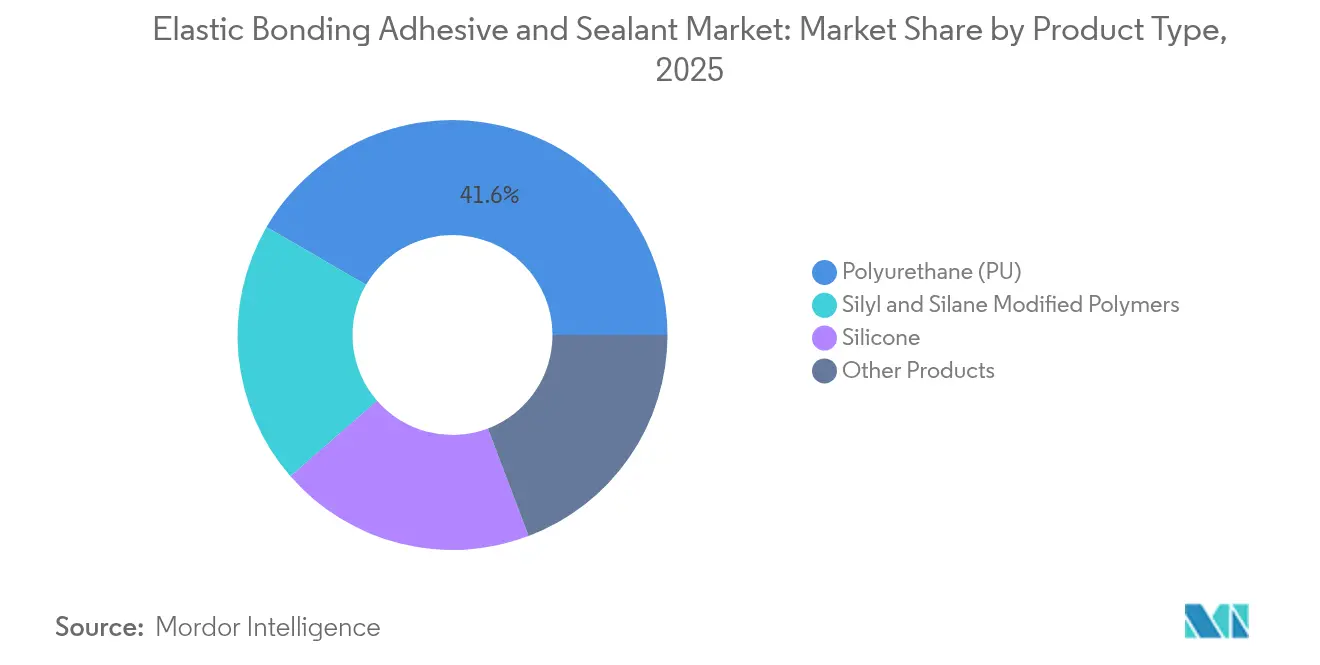
- By product type, polyurethane held 41.63% of the Elastic Bonding Adhesive and Sealant market share in 2025 while silyl and silane-modified polymers are projected to register a 7.01% CAGR to 2031.
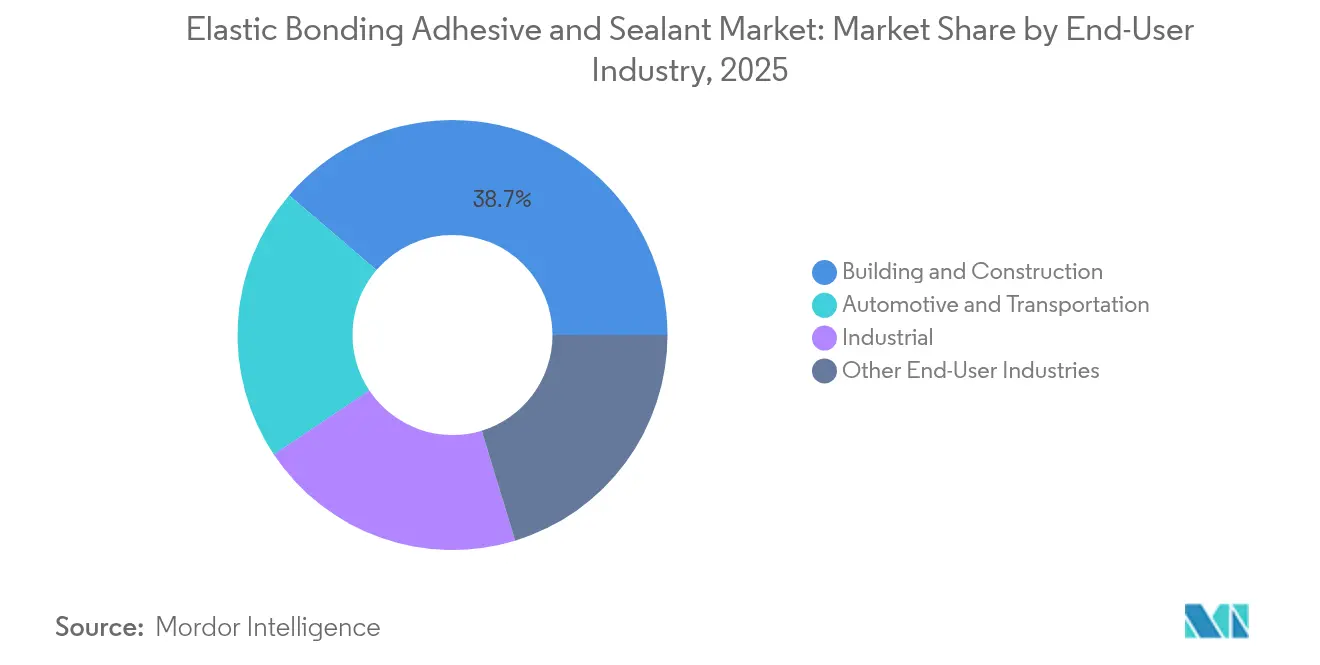
- By end-user industry, building and construction accounted for 38.74% of the Elastic Bonding Adhesive and Sealant market size in 2025 while automotive and transportation is forecast to expand at a 6.44% CAGR through 2031.
- By geography, Asia-Pacific commanded 42.88% revenue in 2025, while also advancing at a 6.67% CAGR to 2031.
Note: Market size and forecast figures in this report are generated using Mordor Intelligence’s proprietary estimation framework, updated with the latest available data and insights as of 2026.
Market Trends and Insights
Drivers Impact Analysis of Elastic Bonding Adhesive And Sealant Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Shift to lightweight multi-material vehicle structures | +1.2% | Global, with concentration in APAC and Europe | Medium term (2-4 years) |
| Rising adoption of modular façade and curtain wall systems | +0.8% | North America and EU, expanding to APAC | Long term (≥ 4 years) |
| Stricter VOC regulations driving solvent-free chemistries | +0.6% | Global, led by California and EU regulations | Short term (≤ 2 years) |
| Wind-turbine blade fatigue mitigation needs | +0.4% | Global, concentrated in offshore wind markets | Medium term (2-4 years) |
| EV battery pack gap-filling for thermal shock control | +0.3% | APAC core, spill-over to North America and EU | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Shift to Lightweight Multi-Material Vehicle Structures
Automakers are replacing welds and rivets with high-strength bonding to shave vehicle weight, meet CO₂ targets, and improve NVH. Mixed-material bodies that combine steel, aluminum, CFRP, and bio-composites demand adhesives able to bridge wide differences in thermal expansion. Adoption grew from 30 linear feet of adhesive per car in 2001 to more than 400 feet in current models. Battery-electric vehicles deepen this dependence because cell-to-pack designs require structural bonding that also channels heat away from cells. Suppliers such as Parker LORD have released acrylic and epoxy grades tuned for peel resistance and crash energy absorption. As every tenth of a kilogram saved translates into longer driving range, the Elastic Bonding Adhesive and Sealant market captures recurring volume per new vehicle platform.
Rising Adoption of Modular Façade and Curtain Wall Systems
Architects favor prefabricated façade units to accelerate schedules, lower labor risk, and achieve sleek glass exteriors. These systems rely on structural silicone glazing that must resist hurricane-force winds, seismic sway, and UV degradation for 30 years or more. Momentive UltraGlaze sealants are already specified on landmark towers from Shanghai to Chicago[1]Momentive Performance Materials, “UltraGlaze™ Structural Silicone Glazing,” momentive.com . Ködiglaze hybrids from H.B. Fuller let designers slim frame profiles, enlarge pane area, and integrate IoT sensors without drilling hardware through the envelope. As green-building codes tighten air-leakage rates, builders opt for continuous bead bonding, which raises unit demand for the Elastic Bonding Adhesive and Sealant market.
Stricter VOC Regulations Driving Solvent-Free Chemistries
California’s Air Resources Board targets a 21-ton-per-day cut in VOC emissions from consumer and industrial sealants, forcing global adoption of solvent-free and water-borne systems. Henkel launched Loctite Liofol LA 7837/LA 6265 in July 2025 as a zero-solvent laminate adhesive that eliminates drying ovens and associated CO₂. Hybrid silyl technologies comply with EU REACH limits on diisocyanates above 0.1%, allowing applicators to avoid costly training mandates. Manufacturers racing to certify low-VOC products unlock premium pricing and higher tender eligibility, reinforcing revenue momentum across the Elastic Bonding Adhesive and Sealant market.
Wind-Turbine Blade Fatigue Mitigation Needs
Average rotor diameter already exceeds 150 meters offshore, magnifying cyclic shear on trailing-edge bonds. Delft University observed that damping in adhesive joints can rise 45% before failure, providing predictive maintenance windows. Epoxy formulations enriched with toughening agents now dominate root-joint bonding, while urethane-acrylic hybrids fill spars and shear webs to stall crack propagation. Blade makers turn to bondline-thickness optimization via FEA, spurring consultancy demand and additional liters per blade. Larger nacelle factories in China, Denmark, and the United States therefore elevate regional consumption in the Elastic Bonding Adhesive and Sealant market.
Restraints Impact Analysis of Elastic Bonding Adhesive And Sealant Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Raw-material price volatility (isocyanates, silicone) | -0.7% | Global, with acute impact in Asia-Pacific | Short term (≤ 2 years) |
| Limited durability data for new hybrid chemistries | -0.5% | Global, affecting premium applications | Medium term (2-4 years) |
| Smart mechanical fasteners as substitute solutions | -0.3% | North America and EU, early adoption markets | Long term (≥ 4 years) |
| Source: Mordor Intelligence | |||
Raw-Material Price Volatility (Isocyanates, Silicone)
Isocyanate costs surged in early 2025 after refinery outages in East Asia forced force-majeure at MDI suppliers. Silicone feedstock values swung week-to-week due to quartz shortages and freight spikes. Epoxy supply rebounded in Europe when construction demand softened, but the lack of long-term price visibility squeezes formulators’ margins. Such unpredictability delays product launches and prompts converters to carry higher inventory, weighing on near-term growth for the Elastic Bonding Adhesive and Sealant market.
Limited Durability Data for New Hybrid Chemistries
Silane-terminated polyether blends promise VOC-free curing and primer-less adhesion, yet field exposure data beyond five years remains limited. Certification bodies in façade engineering still favor legacy polyurethane or structural silicone systems because failure risk carries large liability. Universities accelerate weather-ing cycles with UV-humidity chambers, but real-world acid-rain and freeze-thaw patterns differ. Until long-term datasets mature, conservative specifiers slow mass adoption, capping highest-value gains for the Elastic Bonding Adhesive and Sealant market.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Elastic Bonding Adhesive And Sealant Market Segment Analysis
By Product Type:
Polyurethane Dominance Faces Chemistry EvolutionPolyurethane commanded 41.63% of Elastic Bonding Adhesive and Sealant market share in 2025, underlining its versatility in vehicle bodies, window frames, and wind blades. Toughness, low-temperature cure, and broad substrate compatibility keep polyurethane entrenched, yet regulatory scrutiny of free isocyanate levels creates reformulation urgency. Silyl-modified polymer demand is climbing at a 7.01% CAGR as processors seek VOC-free dispensing without secondary moisture-barrier paints. Hybrid grades blend polyurethane backbone strength with silane end-groups, extending shelf life and ensuring bubble-free cures even in humid climates. Henkel, Sika, and Bostik now supply pre-polymer blends shipped in foil packs that cut packaging waste and aid robotic application. Silicone and epoxy chemistries still serve aerospace interiors, electronics potting, and high-temperature gasketing where heat resistance above 180 °C is critical. Within these niche use-cases, premium pricing and lower volume still lift revenue per kilogram, cushioning margin pressure across the Elastic Bonding Adhesive and Sealant market.
Second-generation bio-based polyurethane pulls polyols from soybean oil and castor beans, lowering CO₂-equivalent by up to 40% against petroleum analogues. Pilot housing projects in Germany report primer-less adhesion to cross-laminated timber, opening fresh volumes in mass-timber construction. Nanotube-reinforced epoxies deliver 30% higher fracture toughness, appealing to wind-blade makers fighting edge erosion. As product portfolios diversify, distributors carry smaller lot sizes but wider SKU counts, fostering bespoke selection and advisory services that strengthen the Elastic Bonding Adhesive and Sealant market.


By End-User Industry:
Construction Leadership Challenged by Automotive AccelerationBuilding and construction contributed 38.74% of Elastic Bonding Adhesive and Sealant market size in 2025. Curtain wall contractors, window fabricators, and flooring installers all depend on structural bonding that resists moisture, UV, and cyclic wind load. Infrastructure stimulus packages in India and the United States fund bridge bearing pads, expansion joint sealing, and precast panel assembly that leverage high-elongation grades. Yet automotive and transportation is growing faster, with a 6.44% CAGR projected through 2031. Electric-vehicle makers bond aluminum roof panels, carbon-fiber spoilers, and battery housings in single pass robotic cells, raising unit adhesive consumption per car. Tier-1 suppliers are qualifying flame-retardant epoxies that meet UN 38.3 battery shipping rules, expanding procurement budgets. Rail carriage producers in China and Europe adopt flexible silane systems to cut vibration, reduce noise, and speed final assembly, redirecting spend toward the Elastic Bonding Adhesive and Sealant market.
Industrial machinery, marine vessel, and electronics segments offer steady baseline demand. Food-grade silicone sealants keep conveyors hygienic, while two-part acrylics bond composite boat hulls and withstand salt-spray fatigue. These applications need niche certifications, allowing formulators to defend premium margins even as mainstream prices align with lower-cost Asian imports. Cross-sector synergies- such as the same toughened epoxy serving both rotor blade spars and high-speed rail noses- highlight how innovations cascade across segments, bolstering resilience of the Elastic Bonding Adhesive and Sealant market.
Geography Analysis
APAC Elastic Bonding Adhesive and Sealant Market
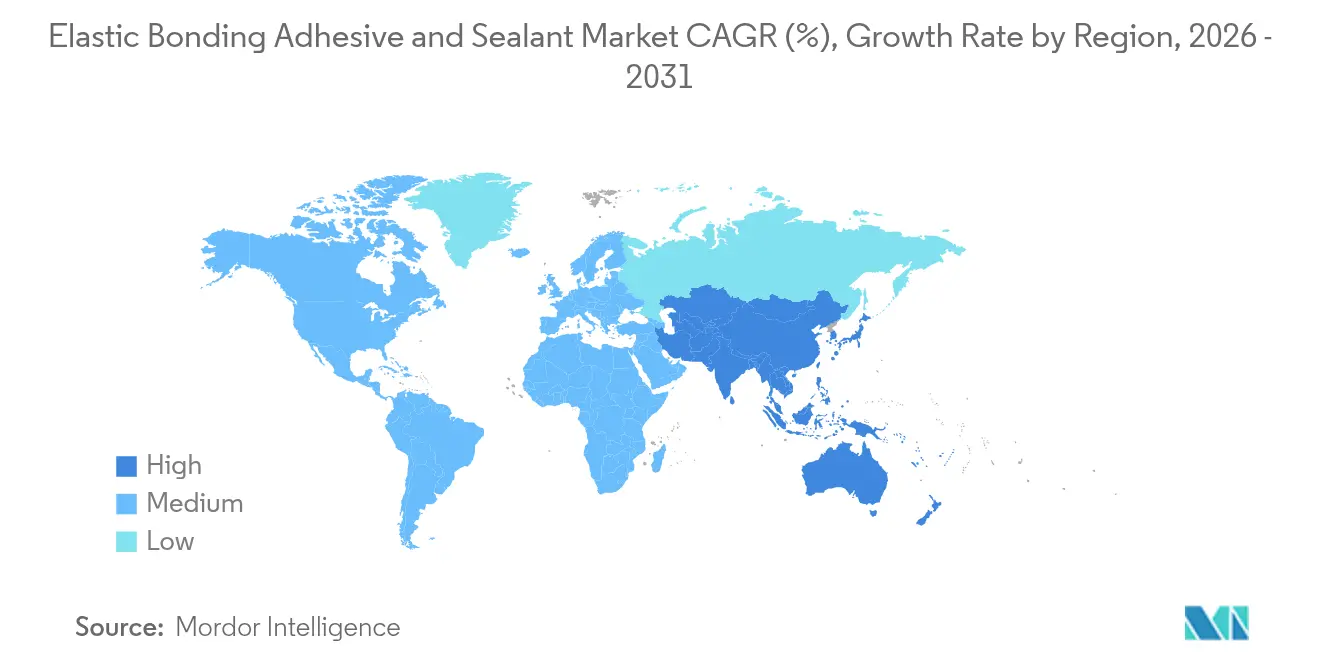
Asia-Pacific generated 42.88% of global revenue in 2025 and is projected to post a 6.67% CAGR to 2031, the highest regional pace. China’s dominant battery supply chain pulls in thermally conductive gap fillers and polyurethane gasketing at double-digit growth. India’s adhesive demand surges on public-sector housing and the Make-in-India automotive push, reinforced by Henkel’s LEED-Gold Kurkumbh facility ramp-up, which shortens lead times and trims imports. Japan and South Korea focus on precision electronics and next-generation mobility, requiring ultra-low outgassing formulas for camera modules and ADAS sensors. ASEAN economies invest in mass-rapid-transit lines and data centers, both reliant on fire-retardant sealants, therefore extending the regional pull on the Elastic Bonding Adhesive and Sealant market.
North America Elastic Bonding Adhesive and Sealant Market
North America remains the second-largest market. California’s VOC cap accelerates zero-solvent adoption, while the Inflation Reduction Act channels billions into wind-power and EV factories, each consuming kilogram-scale adhesive lines. Aerospace primes in Washington and Quebec specify high-temperature bismaleimide pastes for composite nacelles. Mexico’s export-oriented auto clusters integrate robotic bead systems that improve cycle-time predictability and cut rework, contributing new demand nodes to the Elastic Bonding Adhesive and Sealant market.
EMEA and South America Elastic Bonding Adhesive and Sealant Market
Europe blends mature demand with regulatory leadership. The August 2023 REACH limit on diisocyanates above 0.1% spurs accelerated substitution toward hybrids, pushing R&D centers in Germany, Austria, and Italy to pilot catalyst-free cure routes. Automotive assembly plants in Central Europe hunger for bonding that tolerates e-coat ovens and provides crash energy absorption. Offshore wind farms in the North Sea rely on fatigue-resistant epoxies for blade bonding, safeguarding replacement intervals. South America and the Middle East and Africa collectively hold smaller shares, yet infrastructure builds such as Brazil’s BR-163 upgrades and Saudi giga-projects open localized production incentives, pointing to future participation in the Elastic Bonding Adhesive and Sealant market.

Regulatory Landscape
Regulation is tightening around solvent and hazardous-substance content in elastic bonding adhesive and sealant formulations, accelerating shifts toward solvent-free and lower-hazard chemistries across major regions. In the United States, the US Environmental Protection Agency (EPA) issued a final TSCA rule in December 2024 that prohibits industrial and commercial use of trichloroethylene (TCE) in adhesives and sealants, which requires solvent audits and substitution planning for producers serving industrial maintenance and manufacturing applications.
In Europe, CLP and REACH-related compliance requirements continue to influence labeling, training, and product selection for polyurethane, silicone, and hybrid systems. Regulation (EU) 2024/2865 updated label formatting requirements for mixtures, and Regulation (EU) 2025/2439 extended the transition timeline so mandatory compliance runs to December 31, 2026, easing near-term relabeling pressure while still requiring documentation readiness. Policy work to streamline chemical procedures is also visible through EU discussions such as the Chemical Omnibus VI initiative under regulations including (EC) No 1272/2008, reinforcing the need for manufacturers to manage dossiers, labels, and safety communication at scale.
Value Chain Analysis
The value chain covers (1) chemical acquisition of feedstocks (isocyanates, silicones, epoxies, silanes, plasticizers, catalysts), (2) additive production (fillers, tackifiers, rheology modifiers), (3) formulation and manufacturing (1K and 2K systems, cartridges/sausages/pails/drums), (4) channel distribution and application equipment (dispensing, mixing, metering, robotic bead systems), and (5) end-use application and maintenance in construction, automotive and transportation, industrial assembly, and energy. Trade-association mapping from the Adhesive and Sealant Council (ASC) highlights the role of upstream chemical availability and downstream application practices in shaping performance, waste, and compliance across the lifecycle.
Vertical integration is a competitive lever when feedstock security supports more stable supply of formulated products, particularly in silicone and silane-modified platforms; integrated players such as Dow and Wacker Chemie AG anchor parts of this chain through feedstock-to-formulation capabilities. Additives such as rheology modifiers are important for sag control, storage stability, and extrusion behavior, which elevates the influence of additive suppliers and compounders during OEM qualification. Distribution density and technical service (on-site trials, specification support, and equipment integration) also capture value, particularly for construction networks and OEM-certified durability requirements in automotive, rail, and heavy equipment assembly.
Competitive Landscape
Market leadership is shared among global multinationals distinguished by R&D scale, application engineering teams, and vertically integrated raw-material chains. Sika posted CHF 11.24 billion sales in 2023, using profits to expand admixture-ready silane lines[2]Sika AG, “Annual Report 2024,” sika.com . Henkel’s Adhesive Technologies logged EUR 5.475 billion in H1 2024 and recently agreed to co-develop CO₂-based methanol routes with Celanese, targeting cradle-to-gate carbon cuts. 3M continues to restructure toward higher-growth safety and industrial businesses and authorized a USD 7.5 billion share buyback in February 2025, signaling balance-sheet strength.
Saint-Gobain’s USD 1.025 billion purchase of FOSROC in July 2024 extends reach in Middle Eastern construction bonding. Parker Hannifin scales CoolTherm production at its Ohio plant, supplying EV battery customers in the United States and Korea. Regional specialists, such as Wacker and Shin-Etsu, defend silicone niches through backward-integrated monomer capacity. Despite moderate concentration, new entrants supplying bio-based chemistries and nano-reinforced hybrids keep pricing competitive, capping gross margins at midsized formulators. Technical service, digital dispensing analytics, and in-line visualization of cure profiles become differentiators rather than mere product specification, shaping competitive tactics within the Elastic Bonding Adhesive and Sealant market.
Elastic Bonding Adhesive And Sealant Industry Leaders
Henkel AG & CO. KGaA
Sika AG
3M
H.B. Fuller Company
Arkema (Bostik)
- *Disclaimer: Major Players sorted in no particular order
Elastic Bonding Adhesive And Sealant Market Companies Covered in this Report
- 3M
- Arkema (Bostik)
- Cemedine Co., Ltd.
- Dow
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Huntsman International LLC
- Jowat SE
- MAPEI S.p.A.
- Permabond LLC
- PPG Industries, Inc.
- RPM International Inc.
- Sika AG
- ThreeBond Holdings Co. Ltd
- Wacker Chemie AG
Read Analysis of Elastic Bonding Adhesive And Sealant Companies

Market Opportunities and Future Outlook
A clear whitespace is developing for product systems that simplify compliance and documentation while maintaining high-elongation performance, particularly where end users need standardized environmental reporting. In construction, industry alignment on environmental declarations is tightening: in June 2025 the Adhesive and Sealant Council (ASC) partnered with Smart EPD to update Product Category Rules (PCRs) for adhesives and sealants used in construction, and Green Seal published Edition 2.2 of the GS-36 Standard for Commercial Adhesives in September 2025. These efforts expand the addressable space for manufacturers that can provide verified, low-VOC formulations and credible lifecycle documentation for building and infrastructure bids.
Capacity and portfolio actions in 2025-2026 also point to opportunity in localized supply for transportation and industrial assembly, where lead times and consistent quality influence supplier selection. QEP unveiled a next-generation Roberts adhesive manufacturing plant in Dalton, Georgia in July 2025 that doubles production capacity, improving supply responsiveness for flooring and building-related adhesive demand. Strategic consolidation and feedstock security actions further support elastic bonding platforms: Sika announced an agreement in February 2026 to acquire Akkim (Turkey-based adhesives and sealants manufacturer), and Covestro completed acquisitions of two former Vencorex sites for HDI derivatives in Thailand and Texas on July 1, 2026, reinforcing access to polyurethane-related intermediates for elastic systems. Taken together, these moves reflect active investment in both formulated output and key inputs, creating room for suppliers that can combine local manufacturing with application engineering for EV assembly, rail interiors/exteriors, heavy equipment sealing, and modular facade bonding.
Recent Industry Developments in Elastic Bonding Adhesive And Sealant Market
- May 2026: Henkel introduced the Teroson EP 52 Series, a heat-curing one-component structural adhesive designed for automotive body-in-white production with integrated vibration damping. The launch targets faster, more automated assembly while helping OEMs manage noise and durability requirements in lightweight multi-material structures.
- August 2025: Bostik (an Arkema company) launched VSR 400A, a silyl-modified polymer conductive seam sealant aimed at heavy-duty truck manufacturing. Conductive seam sealing supports corrosion protection and assembly integrity on metal-intensive platforms, expanding SMP adoption into higher-spec transportation sealing points.
- April 2024: MAPEI introduced Mapeflex MS 55, a hybrid elastic adhesive and sealant combining silicone and polyurethane system attributes for professional and domestic use. Its positioning for damp or wet surfaces and durable elastic performance broadens hybrid chemistry penetration in repair, renovation, and general construction bonding.


Elastic Bonding Adhesive And Sealant Market Report Scope and Research Methodology
Market Definition and Coverage
For this study, the market covers elastic bonding adhesives and elastomeric sealants sold for flexible bonding and sealing in building, transportation, and industrial use, where joint movement and vibration resistance matter. Values are captured as revenue at the point of sale for these materials across major regions.
Scope exclusions: Excluded from this sizing are non-elastic or rigid structural adhesives, tapes, mechanical fasteners, and generic caulks not positioned for elastic bonding performance.
Segments Covered in This Report
- By Product Type
- Polyurethane (PU)
- Silyl and Silane Modified Polymers
- Silicone
- Other Products
- By End-User Industry
- Building and Construction
- Automotive and Transportation
- Industrial
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle East and Africa
- Asia-Pacific
Data Sources, Market Sizing, and Validation
Desk Research
Desk research starts with mapping the demand pool that actually consumes elastic bonding adhesives and sealants, and then connecting it to supply availability and trade movement. We rely on public sources such as US Census construction spending series, Eurostat construction indicators, UN Comtrade trade statistics for relevant chemical categories, and the International Energy Agency for EV production direction and material shifts that affect bonding choices.
To keep assumptions realistic, we also review items like company annual reports and investor presentations, technical papers in peer reviewed polymer and coatings journals, and product certification or standard references that indicate where elastic chemistries are typically specified. Patent databases are used to spot formulation focus and likely substitution patterns between PU, silicone, and silyl-modified systems. A few paid subscriptions are used only for company financials and news, and for shipment-level import and export checks where needed. These examples are not exhaustive, and many other public references were used for data collection, validation, and clarification.
Primary Interviews and Surveys
Primary work is used to confirm what portion of adhesive and sealant demand is truly elastic bonding grade, and how mix shifts by end use affect average selling prices. We speak with formulators, distributors, applicators, and procurement or engineering contacts across APAC, EMEA, and the Americas, and the discussions are used to validate penetration, replacement cycles, and realistic growth cases before finalizing the model.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 16% | APAC: 46% |
| Mid tier: 50% | Functional/Unit leaders: 28% | EMEA: 31% |
| Smaller Players: 16% | Managers: 56% | Americas: 23% |
Market-Sizing & Forecasting
Sizing is built using top-down logic where construction activity, vehicle output, and industrial production indicators are translated into an addressable consumption pool for elastic bonding and sealing materials, and then converted to value using price bands reported by the market. The totals are then corroborated with selective bottom-up approximations, such as sampling a set of suppliers by region and applying observed product mix and channel splits, followed by checks against trade flows where the product mapping is clean.
Key model inputs include new construction and renovation activity (because elastic joints move over time), vehicle production and lightweight material adoption (which changes bonding content per vehicle), EV assembly intensity in areas like battery pack sealing, waterproofing and facade installation trends, and region-level price progression for PU, silicone, and silyl-modified systems. Where bottom-up visibility is limited, gaps are handled by using verified penetration ranges from interviews and by aligning volumes with independent macro indicators so the final number does not drift.
For forecasting, scenario analysis is used with a main case anchored to consensus expectations from industry experts, and with sensitivity around construction cycle shifts, automotive output changes, and formulation cost pass-through. Growth rates are applied by end use and then rolled up, so the final forecast reflects mix changes rather than a single uniform CAGR.
Data Validation & Update Cycle
Validation is done through repeated cross-checks between the model and outside signals, so unusual jumps in volume, pricing, or mix are easy to spot. Our team compares outputs against construction and manufacturing indicators, trade direction, and interview feedback, and then re-checks any region or end use that shows an unexpected variance before sign-off.
Each report is refreshed annually, and interim updates are triggered when material events occur, such as major regulatory shifts, demand shocks in construction, or sharp feedstock movements that change pricing. Before delivery, analysts do a fresh pass on key assumptions and recent public data, which helps ensure clients receive the latest updated view.
Mordor Intelligence's Elastic Bonding Adhesive and Sealant Market Size Versus Other Published Estimates
Published market values for elastic bonding adhesives and sealants often differ because each publisher defines what qualifies as elastic bonding grade, and because the years, currencies, and pricing logic are not always handled the same way. Differences also show up when one estimate leans more on long-range projections, while another is more tied to near-term construction and manufacturing indicators.
Non-elastic, rigid structural adhesive families are kept outside Mordor Intelligence's scope for this market, which can materially change the total when other estimates group broader adhesives under a similar title. Gaps also come from how PU versus silicone versus silyl-modified systems are counted by end use, whether distribution margins are included, and how pricing is updated when feedstock costs and construction demand move quickly.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 23.29 B (2026) | |
| Industry Publisher A | USD 3.29 B (2025) | Uses a narrower value capture that appears to focus on select elastic bonding sealants, and it applies a longer forecast window with lower near-term pricing refresh, which can keep the starting value smaller. |
| Industry Publisher B | USD 12.50 B (2024) | Leans on a different base year and a broader application narrative without clearly separating elastic bonding grades from adjacent sealant and adhesive categories, which shifts what is counted in the total. |
Looking across the table, the spread is mostly explained by product-category cutoffs, base-year alignment, and whether pricing and channel markups are treated consistently. By keeping the addressable demand pool tied to construction, transportation, and industrial consumption signals and then validating mix and price bands through interviews, our estimate stays traceable to simple inputs that can be rechecked as the market evolves.


Key Questions Answered in the Report
What is the current value of the Elastic Bonding Adhesive and Sealant market?
The Elastic Bonding Adhesive and Sealant market size reached USD 23.29 billion in 2026.
Which region leads demand for elastic bonding products?
Asia-Pacific holds the largest revenue share at 42.88% thanks to strong automotive, construction, and battery manufacturing bases.
Which end-user segment is growing the fastest?
Automotive and transportation is expanding at a 6.44% CAGR through 2031 as EV production accelerates.
Why are silyl-modified polymers gaining popularity?
They cure without emitting VOCs and avoid diisocyanate restrictions, resulting in a projected 7.01% CAGR to 2031.
How do VOC regulations affect adhesive formulation?
Stricter limits in California and the EU push formulators toward solvent-free systems, boosting demand for hybrid chemistries.
Page last updated on:


 Your data is secure and never sold or shared.



