
Condom Market Size and Share
Condom Market Analysis by Mordor Intelligence
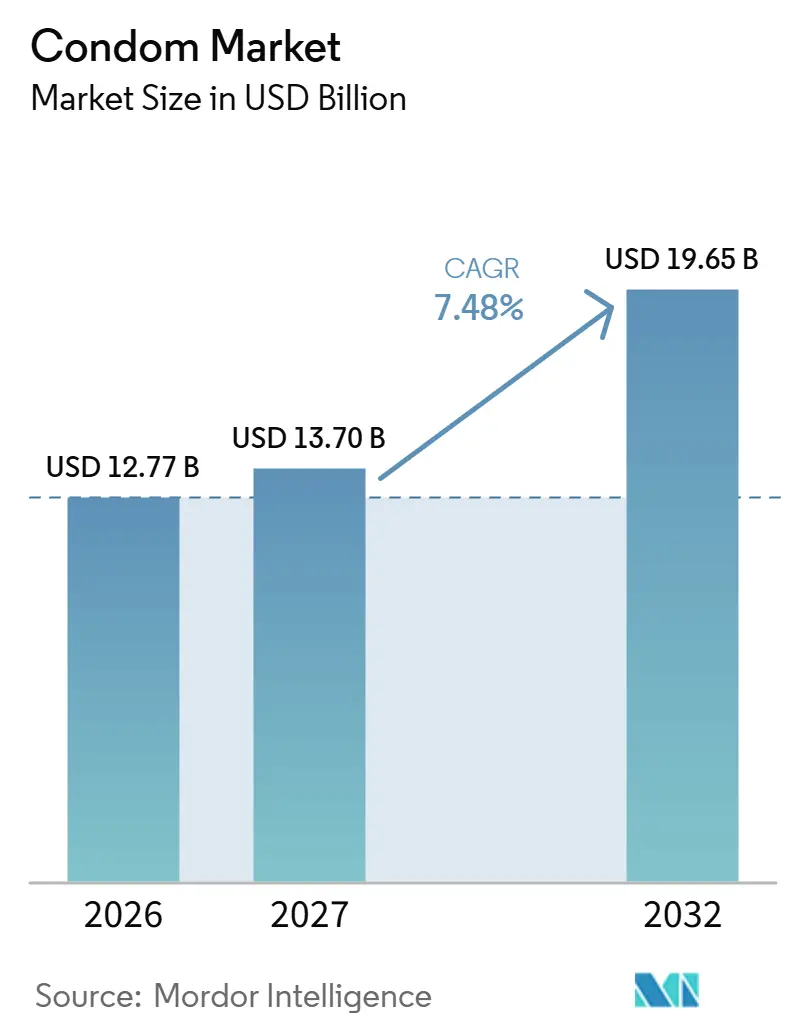
The condom market size is estimated at USD 12.77 billion in 2026 and is projected to be USD 13.7 billion in 2027, reaching USD 19.65 billion by 2032, growing at a CAGR of 7.48% from 2027 to 2032.
Institutional prevention programs and product development expand commercial routes for condoms, while social stigma and doubts about protection can constrain conversion into use. India’s public procurement activity creates a manufacturer-facing demand route, as latex-free innovation gives brands a way to broaden their offer. The commercial response combines qualified product offers with distribution through retail outlets and public health services. This favors suppliers able to join product differentiation with the practical requirements of public programs, retail channels and product-specific authorization in each jurisdiction.
Key Report Takeaways
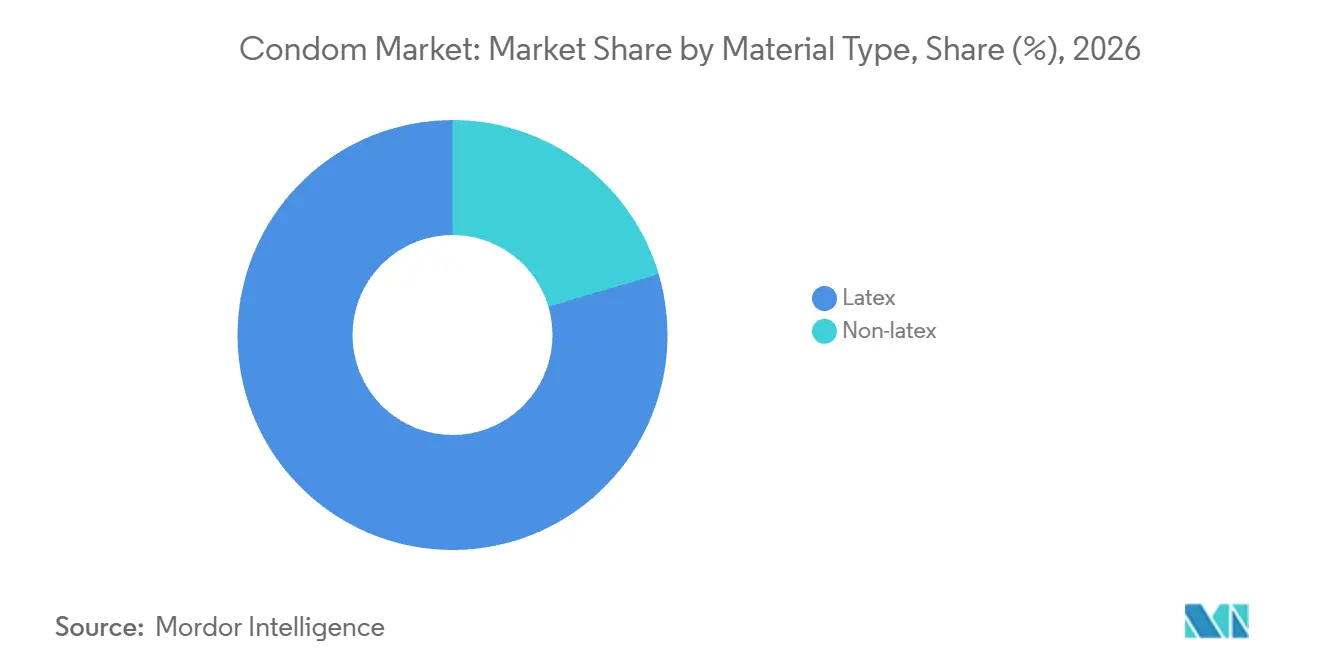
- By material type, latex led with a 79.57% condom market share in 2026, while non-latex is forecast to grow fastest at a CAGR of 10.14% from 2027 to 2032.
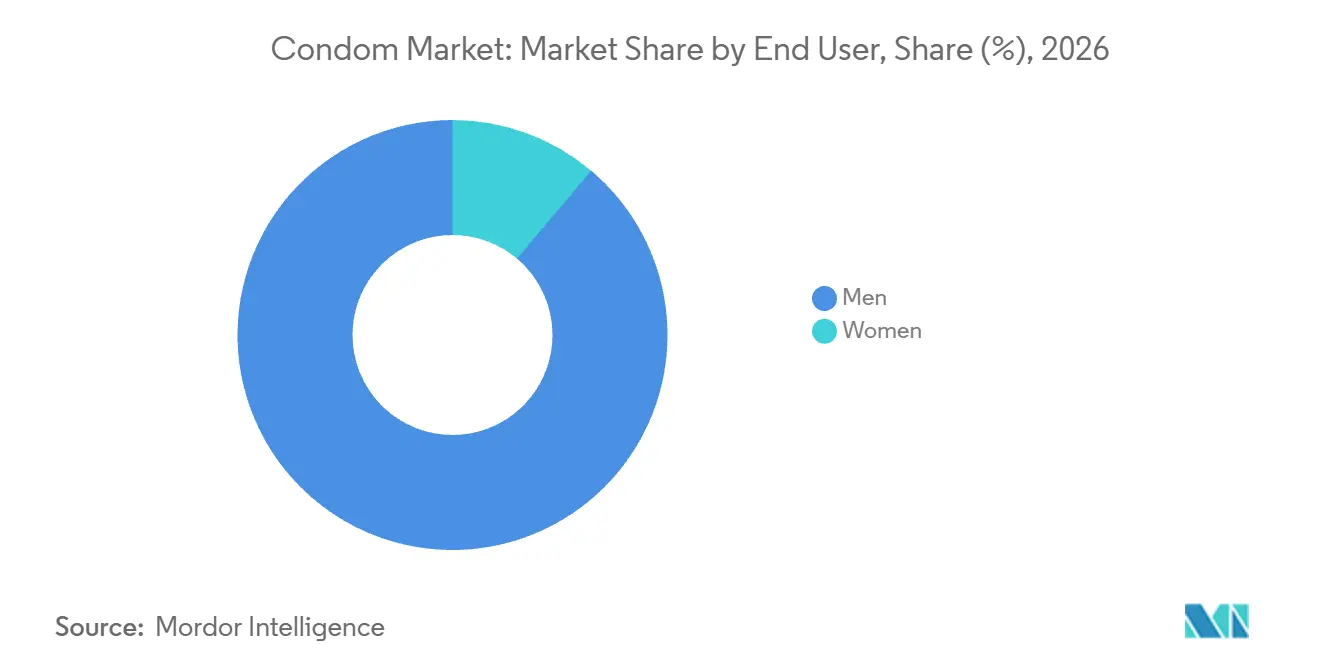
- Among end users, men held an 88.84% share of the condom market size in 2026, and women are projected to grow fastest at a CAGR of 9.55% from 2027 to 2032.
- Distribution was led by pharmacies and drug stores with a 44.8% share of the market in 2026, as online retail stores are forecast to be the fastest-growing channel at a CAGR of 10.4% from 2027 to 2032.
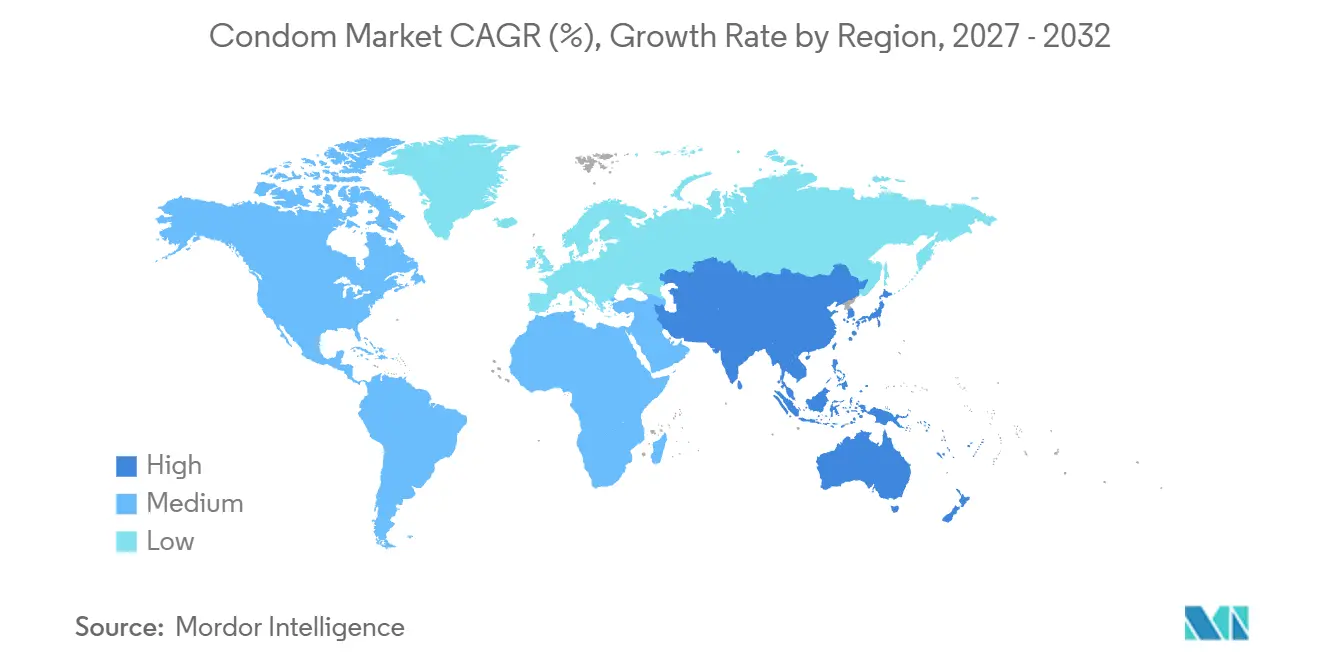
- Geographically, North America led with a 34.85% share of the market in 2026, with Asia-Pacific expected to grow fastest at a CAGR of 10.42% from 2027 to 2032.
Note: Market numbers in this report are based on Mordor Intelligence's proprietary estimation framework, which combines nine months of actuals with Q4 projections for base year 2026.
Market Trends and Insights
Drivers Impact Analysis of Condom Market*
| Driver | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Growing awareness about sexually transmitted infections (STIs) | +2.4% | Republic of Ireland | Medium term (2-4 years) |
| Sex education initiatives in schools and communities | +1.9% | Hard-to-reach areas of South Sudan | Long term (≥ 4 years) |
| Rise in government and public health campaigns | +2.8% | Brazil and UNFPA recipient countries | Short term (≤ 2 years) |
| Innovation in latex-free condoms | +1.7% | Europe and the United States | Medium term (2-4 years) |
| Growing adoption of female condoms | +0.8% | Across South Africa | Long term (≥ 4 years) |
| Rising acceptance of casual relationships and dating apps | +0.6% | Across the United Kingdom | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Growing awareness about sexually transmitted infections (STIs)
Awareness gives suppliers a recognized prevention rationale, while sustained use determines how fully that recognition can become demand. The HSE commissioned Ipsos B&A to survey 1,134 Republic of Ireland residents aged 18 to 30 online in January 2025, with results weighted to 806,000 adults in that age group. When prompted with multiple possible prevention methods, 89% selected condoms as effective against STI transmission, excluding HIV. Separately, 79% reported having had intercourse without a condom at some point in their lives. For suppliers serving Irish young adults, awareness can support additional unit demand when that recognized prevention rationale leads to condom use on occasions that would otherwise be unprotected.
Sex education initiatives in schools and communities
Education initiatives can strengthen demand by making prevention knowledge teachable before potential users face a purchasing decision. In March 2026, WHO reported that a small but growing number of countries were improving comprehensive sexuality education content and delivery in and outside schools.[1] In 2025, UNESCO’s O3 Programme supported training for 305 teachers in 23 primary and 13 secondary schools in South Sudan, including hard-to-reach and vulnerable communities. Preparing teachers gives education providers a way to embed prevention knowledge in repeated instruction across participating schools. The opportunity for suppliers is a broader base of informed potential users, with its reach constrained by the uneven educational access identified by WHO.
Rise in government and public health campaigns
Public-health programs can support condom demand through physical provision as well as messages directed at potential users. Brazil’s Ministry of Health completed its 2025 Carnival STI-prevention campaign, promoting condom use alongside other prevention methods and including condom distribution. Separately, UNFPA provided 1.09 billion male condoms worldwide in 2025 through its programs. For manufacturers, these activities establish a commercial route through organized provision, where serving program requirements can matter alongside winning individual retail purchases. The connection between communication and accessible supply is the central opportunity, because a campaign that puts products into users’ hands can address the immediate means of prevention as well as its rationale.
Innovation in latex-free condoms
Latex-free innovation creates demand opportunities through product-specific paths to regulatory access and distribution. On February 28, 2025, the FDA found RB Health (US) LLC’s Durex Polyisoprene Condom substantially equivalent to predicate devices. The decision allowed marketing subject to general controls for contraception and to help reduce pregnancy and STI transmission risks. Separately, Reckitt reported an ongoing global rollout and range extensions for Durex Intensity in H1 2026. For Durex, the US polyisoprene marketing basis and Intensity’s continuing rollout make product-specific authorization and distribution complementary requirements for extending its latex-free offer.
Restraints Impact Analysis of Condom Market*
| Restraint | (~) % Impact on CAGR Forecast | Geographic Relevance | Impact Timeline |
|---|---|---|---|
| Cultural and religious stigma | -1% | Burauen study area in Leyte | Long term (≥ 4 years) |
| Misconceptions about condom efficacy | -0.8% | South African study communities | Medium term (2-4 years) |
| Accessibility issues in rural and remote areas | -0.6% | Moretele study area | Medium term (2-4 years) |
| Competition from alternative contraception | -0.3% | Republic of Ireland | Short term (≤ 2 years) |
| Source: Mordor Intelligence | |||
Cultural and religious stigma
Stigma can constrain access through the social exposure attached to both buying condoms and requesting them at a service point. A 2025 qualitative study of young cisgender adults in Poblacion District 4, Burauen, Leyte, Philippines, found that social judgment and gender expectations made women feel ashamed when purchasing condoms. One participant also described embarrassment about asking for condoms at a barangay office because people might talk about them. Moving distribution from a shop to a local office could therefore leave the barrier intact if obtaining supplies still requires a visible request. For services addressing these needs, the remaining constraint is the perceived social cost of being seen seeking protection.
Misconceptions about condom efficacy
Perceived failure risk can constrain demand even when users understand what condoms are intended to do. Interviews conducted from November 2023 to March 2024 with adolescent girls and young women in a South African school-based HIV prevention program captured fear that condoms could burst and were unsafe. Researchers described that fear as partly a misconception and as a reason participants chose to use pre-exposure prophylaxis (PrEP). For condom suppliers, the barrier is confidence in protection at the moment of use, which additional awareness alone would not necessarily resolve. Rebuilding trust therefore adds a communication burden before this audience can be expected to choose the product confidently.
*Our forecasts treat driver/restraint impacts as directional, not additive. The impact forecasts reflect baseline growth, mix effects, and variable interactions.
Condom Market Segment Analysis
By Material Type:
Latex Infrastructure Supports Scale as Synthetic Products DifferentiateLatex accounted for a 79.57% share of the condom market size in 2026, making it the largest segment. Tianjin Human-Care Latex Co., Ltd., a wholly owned subsidiary of Lifestyles Health Industry Co., Ltd., operates 5 natural-latex condom production lines in Tianjin, China. Cupid Limited reported for FY2025-26 that its natural-rubber-latex female condom held WHO/UNFPA prequalification and was supplied to more than 50 countries. For suppliers, specialized production infrastructure and qualified products with international reach give latex a commercial foundation across different condom formats and routes to buyers.
Non-latex is forecast to be the fastest-growing segment, at a CAGR of 10.14% from 2027 to 2032. Reckitt reported that its nitrile male condom Durex Intensity became one of its best-selling portfolio products after launching in Europe in early 2025. The company linked nitrile to body-heat transfer and enhanced sensation without compromising protection. That product result connects a material choice with the experience offered to buyers, giving suppliers a specific basis for differentiation.



By End User:
Program Requirements Sustain Men’s Scale and Women’s Procurement RoutesMen represented an 88.84% condom market share in 2026 and formed the largest end-user segment. For its November 1, 2025, to October 31, 2030, state contract, South Africa’s National Treasury estimated annual requirements of 800 million male condoms and 200 million male youth condoms. The separate youth category creates another defined buyer requirement within the male-condom business. Estimated annual requirements give suppliers a scale for planning production, while the categories define the offers public buyers seek. This gives manufacturers a product-specific route into institutional supply alongside consumer-facing brand competition.
Women are forecast to be the fastest-growing segment, at a CAGR of 9.55% from 2027 to 2032. On July 1, 2025, UNFPA recorded an award covering female condoms alongside male latex condoms and personal lubricants for multiple countries and territories. In May 2026, UNDP invited bids for multiple non-exclusive global long-term agreements covering WHO/UNFPA-prequalified female condoms, male condoms and lubricants, with submissions due June 8, 2026. That requirement makes prequalification commercially significant for manufacturers seeking institutional female-condom business. The opening is qualified participation in multi-product prevention procurement, giving suppliers a buyer route beyond establishing a standalone consumer brand.

By Distribution Channel:
Pharmacy Access and Digital Selling Serve Different NeedsPharmacies and drug stores held the largest segment share, at 44.8% in 2026. Haringey’s 2025 pharmaceutical needs assessment recorded 23 pharmacies in the English borough registered to provide free condoms through Come Correct for young people under 25. The local network gives the pharmacy channel a defined service setting in which access is organized around an eligible group. For suppliers addressing that setting, participating outlets provide an identifiable route for reaching the program’s intended users. Pharmacy participation can consequently serve a prevention program as well as individual product purchases.
Online retail stores are forecast to be the fastest-growing segment, at a CAGR of 10.4% from 2027 to 2032. In 2025, Reckitt said Durex livestreaming and social commerce in China drove higher full-price sell-through and more efficient recruitment. Condom brands can therefore treat livestream selling as an acquisition tool that does not depend on discounting.
Geography Analysis
North America Condom Market
North America held a 34.85% condom market share in 2026, making it the largest regional market. On February 3, 2026, New York City’s Department of Citywide Administrative Services awarded Global Protection Corp. a 5-year requirements contract valued at USD 6.11 million for condoms and lubricant packets for the city’s Condom Availability Program. An April 2026 NYC Health announcement confirmed the renewed 5-year partnership with ONE Condoms, the brand owned by Global Protection Corp., with supply through January 2031. By packaging condoms with lubricant, the procurement creates a supplier opportunity around a complete prevention offer, making the ability to serve the combined requirement part of the commercial case.
Asia-Pacific Condom Market
Asia-Pacific is forecast to be the fastest-growing region, at a CAGR of 10.42% from 2027 to 2032. Thailand’s Thai Nippon Rubber Industry Public Company Limited implemented one concentrated-natural-latex condom production machine in the second quarter of 2026. Its project plan aimed to improve revenue-generating capability and gross profit margin through advanced production technology. For Thai Nippon, the commercial test is whether the implemented natural-latex technology supports both revenue generation and gross margin, rather than equipment installation alone.
In Europe, England’s provisional 2025 official statistics in development showed reported condom use at last sex with a partner of another sex in 19.8% of women’s and 16.4% of men’s face-to-face sexual-health-service attendances. This English country case concerns use within a clinical service setting, where product provision can be paired with prevention communication. Brazil’s Unified Health System offers a South American example, providing external and internal condoms, including textured and sensitive varieties, through primary care and specialized STI services on individual demand without registration or quantity limits. South Africa’s national example within Middle East and Africa is a state contract covering male and female condoms and lubricant. For suppliers, these examples suggest service-linked communication in England, public-health distribution in Brazil and combined condom-and-lubricant offers for South Africa’s state buyer.
Regulatory Framework and Outlook
Selected jurisdictions are compared from the perspective of a condom manufacturer seeking commercial market entry. Product material and device class shape the documentation and technical work required for an offer. Natural-rubber-latex male condoms have specific technical or labeling requirements in the United States and Argentina, while China’s scheduled unique device identification requirement applies to Class II devices manufactured from June 1, 2027. These distinctions make the choice of product and entry route commercially significant alongside the selection of a destination country.
Regulatory Table of Condom Market
| Decision factor | United States | Germany | China | Argentina | Saudi Arabia |
|---|---|---|---|---|---|
| Primary authority | Food and Drug Administration | Federal state authorities, Landesbehörden | National Medical Products Administration and provincial drug regulators | ANMAT | Saudi Food and Drug Authority |
| Key instruments or direction | 21 CFR 884.5300 Class II controls; 510(k) pathway; part 820 quality systems | EU MDR conformity and Rule 15 classification; MPDG language requirements | Registration dossier requirements; scheduled Class II unique device identification, UDI | Disposición 2337/2002 for latex male condoms; Disposición 236/2026 for eligible imports | Class C guidance with a separate spermicide-product rule; registration and medical-device marketing authorization |
| Commercial effect | Premarket notification, latex labeling controls and applicable quality-system obligations | Conformity and CE marking; German user/patient information; justified English or another understandable language permitted; German or English conformity declarations | Multiple single-use devices of the same model and batch may omit individual UDI if the minimum sales pack has UDI | National technical compliance and manufacturer and applicable importer package identification; prior notification for qualifying Class I/II imports with required documentation | Technical documentation, ISO 13485:2016 quality system and premarketing inspection report |
| Current policy attractiveness | Medium | Medium | Medium | Medium | Medium |
| Future direction of policy attractiveness | No change | Easing | Hardening | Easing | No change |
| Source: Mordor Intelligence | |||||
US Class II controls and Saudi Arabia’s authorization and premarketing quality-inspection requirements justify medium ratings, with continuity supported by the completed US quality transition and maintained Saudi oversight framework. Germany’s medium rating reflects conformity and language duties, while the December 2025 proposal for narrower non-implantable Class IIb documentation assessment, pending in October 2026 with additional review for concerns, supports easing subject to adoption. China’s medium rating weighs registration work against the conditional multipack exception, with hardening for remaining Class II products manufactured from June 1, 2027, when the scheduled UDI requirement applies. Argentina’s medium rating retains latex-male-condom technical duties, while the March 19, 2026, notification procedure supports easing for eligible Class I/II imports with required documentation and continuing national technical compliance.
Value Chain Stages
The value chain compares contract manufacturing, branded commercialization and downstream distribution as different sources of supplier earnings. In FY2025, commercial-market sales were Karex’s largest revenue contributor across its business, covering original equipment and original design manufacturing for brands and private labels. Its subsidiaries’ manufacturing roles, proprietary brands and US distribution subsidiary show how successive activities can sit within one group. Vertical integration can therefore expose a supplier to more sales interfaces, while each activity requires its own operating capability.
Value Chain Analysis Table of Condom Market
| Primary activity | Key participants | Value capture | Bottleneck | Resilience response |
|---|---|---|---|---|
| Condom manufacturing | Condom manufacturers such as Karex Berhad and HLL Lifecare Limited | Contract production and finished-product sales | Prequalification when seeking UNFPA contracts | Prepare supplier qualification and product specifications before contracting |
| Brand development and commercialization | Brand owners such as Reckitt Benckiser Group PLC and Karex Berhad | Branded-product sales | Translating changing consumer preferences into a branded offer | Use direct consumer engagement to guide product choices |
| Packaging and distribution | Condom distributors such as Global Protection Corp., a Karex subsidiary | Distribution and packaged-product sales | Order fulfillment during facility transitions | Stage transfers and preserve dispatch capacity |
| Source: Mordor Intelligence | ||||
In FY2025, Karex’s US subsidiary Global Protection Corp. completed a facility relocation that temporarily disrupted order fulfillment.[2] Its warehousing and distribution capacity reached 3 times the previous level. For integrated suppliers, the commercial benefit of a larger distribution footprint depends on managing the transfer of operations while preserving the order fulfillment that customers rely on.
Competitive Landscape
Market Concentration
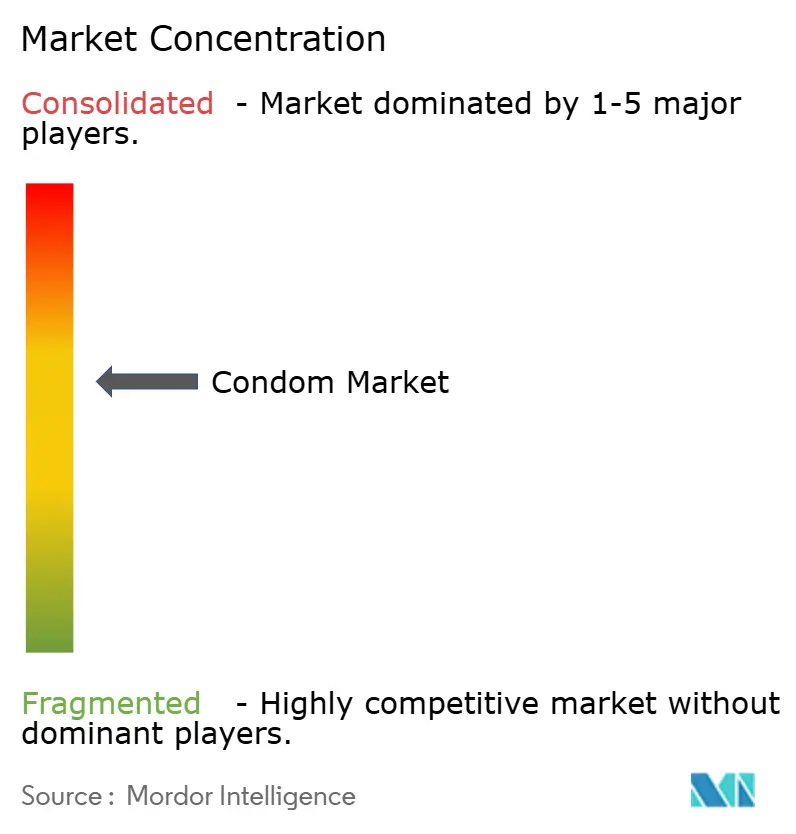
A moderately concentrated competitive structure combines international consumer brands with manufacturers serving branded and institutional channels, with material development and access to buyers shaping competition. Reckitt Benckiser Group PLC reported broadly flat Durex like-for-like net revenue in H1 2026, with strong Latin American and Indian performance and double-digit European Durex Intensity net revenue growth offset by China’s condom VAT. Church & Dwight Co., Inc. operates the TROJAN condom brand, including its non-latex G.O.A.T. product. Brand positioning therefore depends on how product differences meet local conditions, because strong performance in some destinations can be offset elsewhere.
In FY2025, Karex Berhad’s Europe-region sales across its business rose by more than 34% year over year, boosted by initial synthetic-condom deliveries to 15 launch countries. Karex explained that synthetic condoms require a dedicated manufacturing process and entirely new production lines. LifeStyles Healthcare Pte. Ltd. manufactures, markets and sells condoms through retail outlets and also supplies public tenders and third-party branded businesses. Okamoto Industries, Inc. sells condoms in Japan and overseas markets, including China. For a manufacturer, buyer access can therefore be built through existing brands or public supply arrangements as well as entry into additional national markets.
In August 2026, Okamoto reported that 2 Japan-market condom models had entered France through unofficial channels and were recalled after French authorities found they lacked required CE marking. The company stated that its authorized-channel products supplied to France were approved as CE-marked Class IIb medical devices. This makes channel control part of competitive positioning, because a product designed for one market can face different requirements elsewhere. Suppliers seeking European buyers need commercial arrangements that preserve the relevant local product status. Product differentiation becomes usable for buyers only when its supply route supports the conditions under which the product may be sold.
Condom Industry Leaders
-
Reckitt Benckiser Group PLC
-
Church & Dwight Co., Inc.
-
Karex Berhad
-
LifeStyles Healthcare Pte. Ltd.
-
Okamoto Industries, Inc.
- *Disclaimer: Major Players sorted in no particular order
Condom Market Companies Covered in this Report
- Reckitt Benckiser Group PLC
- LifeStyles Healthcare Pte. Ltd.
- Church & Dwight Co., Inc.
- Karex Berhad
- Fuji Latex Co., Ltd.
- Cupid Limited
- Okamoto Industries, Inc.
- Veru Inc.
- Mankind Pharma Limited
- Mayer Laboratories, Inc.
- Ansell Limited
- Thai Nippon Rubber Industry Public Company Limited
- HLL Lifecare Limited
- Global Protection Corp.
- Australian Therapeutic Supplies PTY Ltd.
- Richter Rubber Technology Sdn. Bhd.
- Ritex GmbH
- RFSU AB
- Unique Condom Corp.
- Caution Wear Corp.
Key Opportunities for Market Participants
Institutional purchasing offers different openings for eligible local manufacturers and suppliers preparing for separately planned male- and female-condom procurements. On October 1, 2026, India’s Central Medical Services Society invited Class I and Class II local-supplier manufacturers to bid for 2 NACO condom schedules totaling a tentative 115.5 million pieces.[3] Bids are due October 29, 2026, with 1-year rate contracts beginning on award. South Africa’s Health procurement plan separately scheduled male- and female-condom processes to begin November 12 and 13, 2026.
Market Opportunities Table of Condom Market
| Opportunity | Why now | Buyer / lead segment | Recommended play | Main barrier | Likely beneficiaries |
|---|---|---|---|---|---|
| Supply India’s free-condom program | October 2026 invitation under 1-year rate contracts | NACO through Central Medical Services Society | Pursue the appropriate schedule after confirming local-manufacturer eligibility | Participation restricted to Class I and Class II local-supplier manufacturers | Qualifying Indian condom manufacturers |
| Prepare for South African male-condom purchasing | Procurement-plan start scheduled for November 2026 | South Africa Health, male condoms | Prepare manufacturing and submission capacity for the planned process | Execution risk before a planned procurement becomes a tender | Male-condom manufacturers able to meet the eventual requirements |
| Prepare for South African female-condom purchasing | Separate female-condom procurement planned for November 2026 | South Africa Health, female condoms | Build a product-specific supply proposal when tender requirements emerge | Planned process offers no committed order | Female-condom manufacturers able to meet the eventual requirements |
| Source: Mordor Intelligence | |||||
The Indian invitation gives qualifying manufacturers a defined submission window, making eligibility the first commercial screening decision. South Africa’s separate planned processes justify product-specific preparation, while their planning status makes an order commitment premature. The strongest near-term opening is converting manufacturing capability into an eligible institutional offer, with preparation scaled to how far each purchasing process has progressed.
Recent Industry Developments in Condom Market
- Oct 2026: India’s Central Medical Services Society invited Class I and Class II local-supplier manufacturers to bid for 2 NACO condom schedules totaling a tentative 115.5 million pieces, with bids due October 29, 2026.
- Aug 2026: Okamoto Industries, Inc. reported that 2 Japan-market condom models entered France through unofficial channels and were recalled after French authorities found they lacked required CE marking.
- Apr 2026: The NYC Health Department announced a renewed 5-year contract with ONE Condoms, a brand of Global Protection Corp., to supply free external condoms and lubricant across New York City through January 2031.
Condom Market Report Scope and Research Methodology
Market Definition and Coverage
The global condom market measures annual retail and institutional point-of-sale spending on male and female condoms. Sales are classified by material, end user, distribution channel and region across all countries.
Scope exclusions: Other contraceptive products, broader sexual wellness products, separately sold condom manufacturing inputs and equipment, and separately sold condom accessories are excluded.
Segments Covered in This Report
- By Material Type
- Latex
- Non-latex
- By End User
- Men
- Women
- By Distribution Channel
- Hypermarkets/Supermarkets
- Convenience Stores
- Pharmacies and Drug Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Spain
- United Kingdom
- Germany
- Russia
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- Rest of Middle East and Africa
- North America
Data Sources, Market Sizing, and Validation
Desk Research
Public and official sources such as the World Health Organization's condom guidance inform product definitions, use patterns and standards, while UNFPA supplier and supply-chain materials help frame prequalification, procurement and institutional distribution. UNAIDS reporting adds context on global procurement and program distribution, and U.S. Food and Drug Administration records illustrate how product authorization and device classification can be checked.
Company annual reports, regulatory filings, investor materials and reputable business press can supplement public market evidence by checking product portfolios, capacity, channel activity and material changes in supply. Researchers reconcile source definitions, units and timing before using these materials. The named sources are not exhaustive, and further sources inform collection, validation and clarification.
Primary Interviews and Surveys
Primary interviews target condom manufacturers, brand owners, retail and online distributors, institutional procurement specialists and sexual-health program representatives across APAC, EMEA and the Americas. Questions test secondary estimates of channel coverage, product mix, price realization, procurement volumes and regional demand, while resolving gaps in reported institutional and online sales. Analysts compare responses with independent company, retail and procurement evidence and revisit a respondent when definitions, timing or reported ranges conflict.
Distribution of primary research fieldwork respondents
| Company type | Respondent position | Region |
|---|---|---|
| Top tier: 34% | CXOs: 20% | APAC: 40% |
| Mid tier: 43% | Functional/Unit leaders: 37% | EMEA: 32% |
| Smaller Players: 23% | Managers: 43% | Americas: 28% |
Market-Sizing & Forecasting
The model starts with a top-down estimate of global annual point-of-sale condom revenue, then allocates value across material, end user, channel and region using reported sales mixes, retailer and institutional channel evidence, and country-level demand indicators. Key inputs include relevant population and condom-use measures to assess demand, procurement quantities and award prices to anchor institutional value, and retail channel revenue and product price trends to track consumer sales and price mix. Analysts use multivariate regression for the relationships among demand, income, channel reach and product mix, then apply scenario analysis when policy, access or product changes alter the outlook. Primary specialists check the variable assumptions and the resulting segment shares. Selective supplier roll-ups and sampled average selling price times volume checks test the top-down totals, with gaps in supplier or channel detail bounded using observed mix ranges and independent procurement or retail signals rather than treated as observed sales.
Data Validation & Update Cycle
Analysts triangulate market totals against independent retail, supplier and institutional procurement signals, then check segment shares and forecast inputs for unit, currency, timing and boundary consistency. Outliers and material variances are reviewed against source records before sign-off, with re-contact triggered when a definition or reported range remains unclear. A full refresh occurs annually, a targeted update follows a material market event, and analysts complete a fresh source and calculation review before delivery.
Mordor Intelligence's Condom Market Size Versus Other Published Estimates
Published estimates can differ in the transactions and products they count and the inputs used to model demand. The global condom market measures annual retail and institutional point-of-sale spending on male and female condoms.
Key Gap Drivers include the study's defined coverage and market-specific modeling choices. The model starts with a top-down estimate of global annual point-of-sale condom revenue, then allocates value across material, end user, channel and region using reported sales mixes, retailer and institutional channel evidence, and country-level demand indicators.
Benchmark comparison
| Source | Market Size | Gaps in Research Methodology |
|---|---|---|
| Mordor Intelligence | USD 13.7 B (2027) | |
| Global Consultancy A | USD 8.9 B (2025) | At its 2025 base, this estimate is 35.0% below this report's 2027 value of USD 13.7 B, 2 years later. The earlier measurement year and its published growing forecast explain the lower amount, while its faster forward growth rate partly offsets that timing effect. |
| Global Consultancy B | USD 8.44 B (2026) | At its 2026 base, this estimate is 38.4% below this report's 2027 value of USD 13.7 B, 1 year later. Its published estimate is for the year before this report's current year, and the source projects continued market growth. |
Mordor Intelligence's analysts triangulate market totals against independent retail, supplier and institutional procurement signals, then check segment shares and forecast inputs for unit, currency, timing and boundary consistency.
Key Questions Answered in the Report
What is the condom market size and growth outlook?
The market is projected at USD 13.7 billion in 2027 and USD 19.65 billion by 2032, with a CAGR of 7.48% from 2027 to 2032.
What supports demand for condoms?
Public-health provision and education support potential demand. UNFPA provided 1.09 billion male condoms in 2025, while WHO reported improving sexuality-education delivery in a small but growing number of countries in March 2026.
Which condom material has the largest share?
Latex held the largest share, at 79.57% in 2026.
Which companies compete in the condom industry?
Key competitors include Reckitt Benckiser Group PLC, Church & Dwight Co., Inc., Karex Berhad, LifeStyles Healthcare Pte. Ltd., and Okamoto Industries, Inc.
What can limit the wider use of condoms?
Social judgment can complicate access. In a 2025 qualitative study, young cisgender adults in Burauen’s Poblacion District 4, Leyte, Philippines, described shame associated with women buying condoms.
Which regions lead the condom industry in share and growth?
North America led with a 34.85% share in 2026, and Asia-Pacific is forecast to grow fastest at a CAGR of 10.42% from 2027 to 2032.